KALYANKJIL
Equity Metrics
November 18, 2026
Kalyan Jewellers India Limited
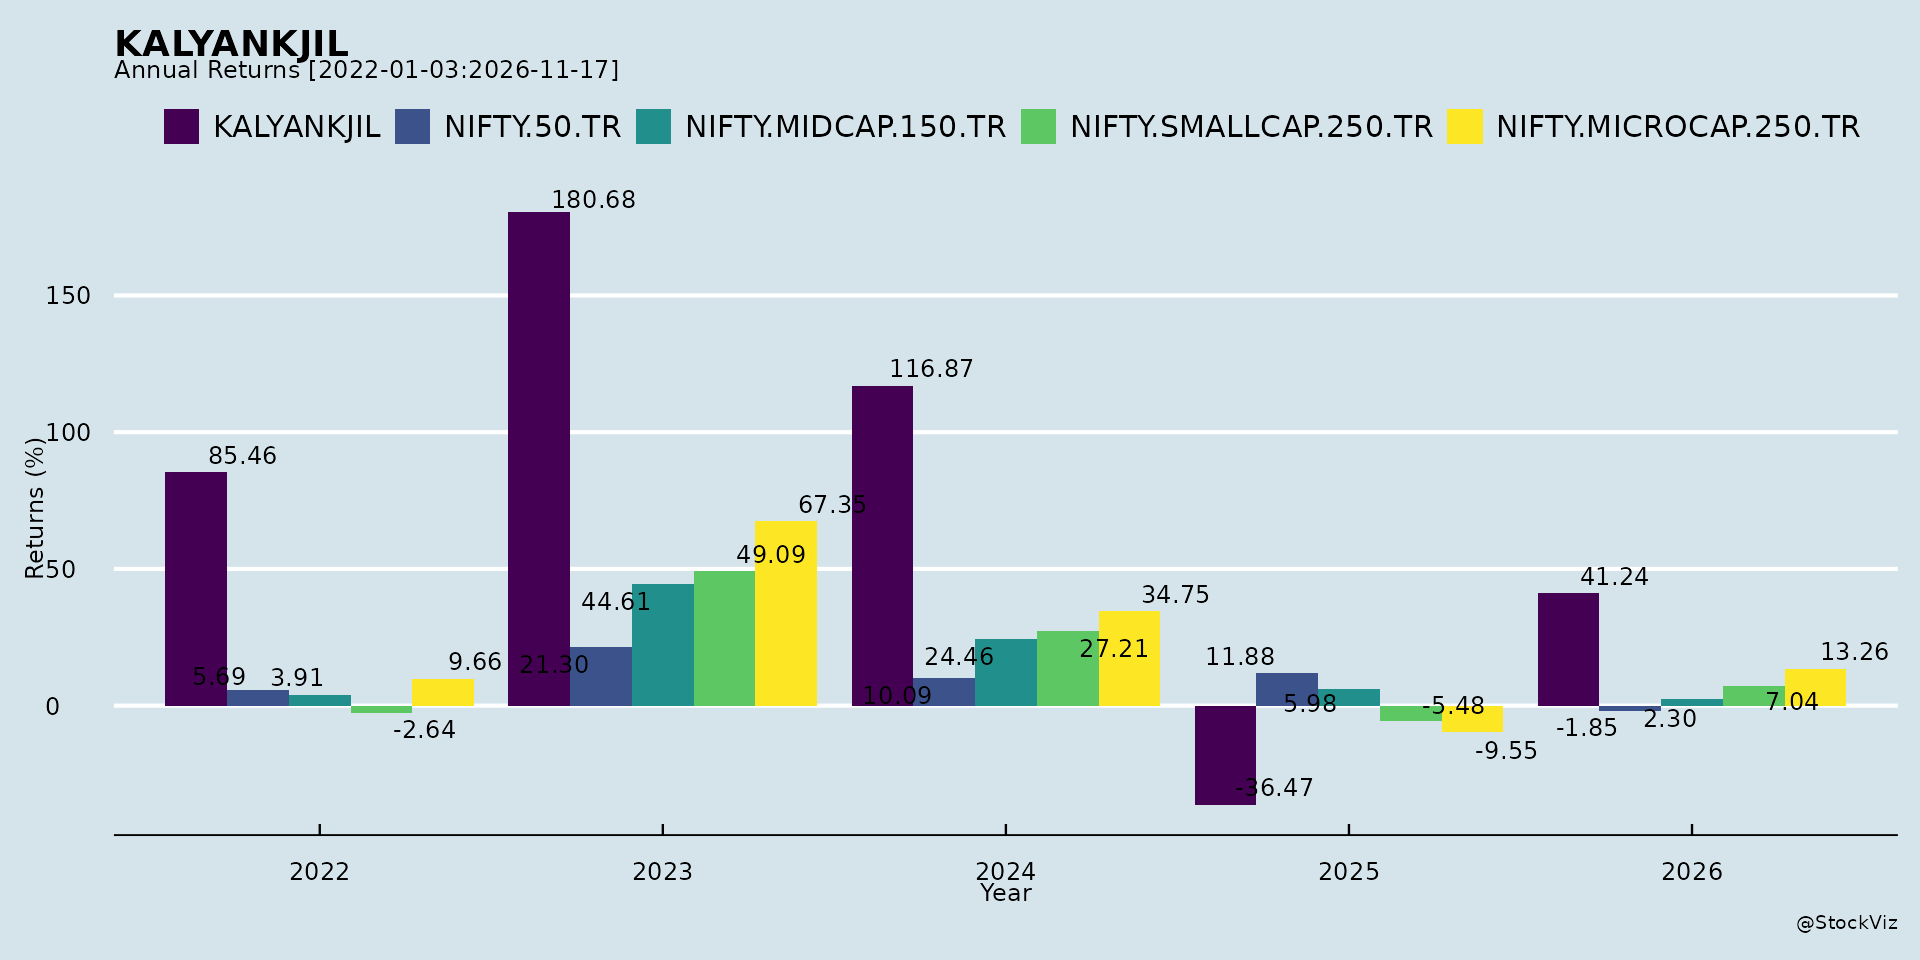
Annual Returns
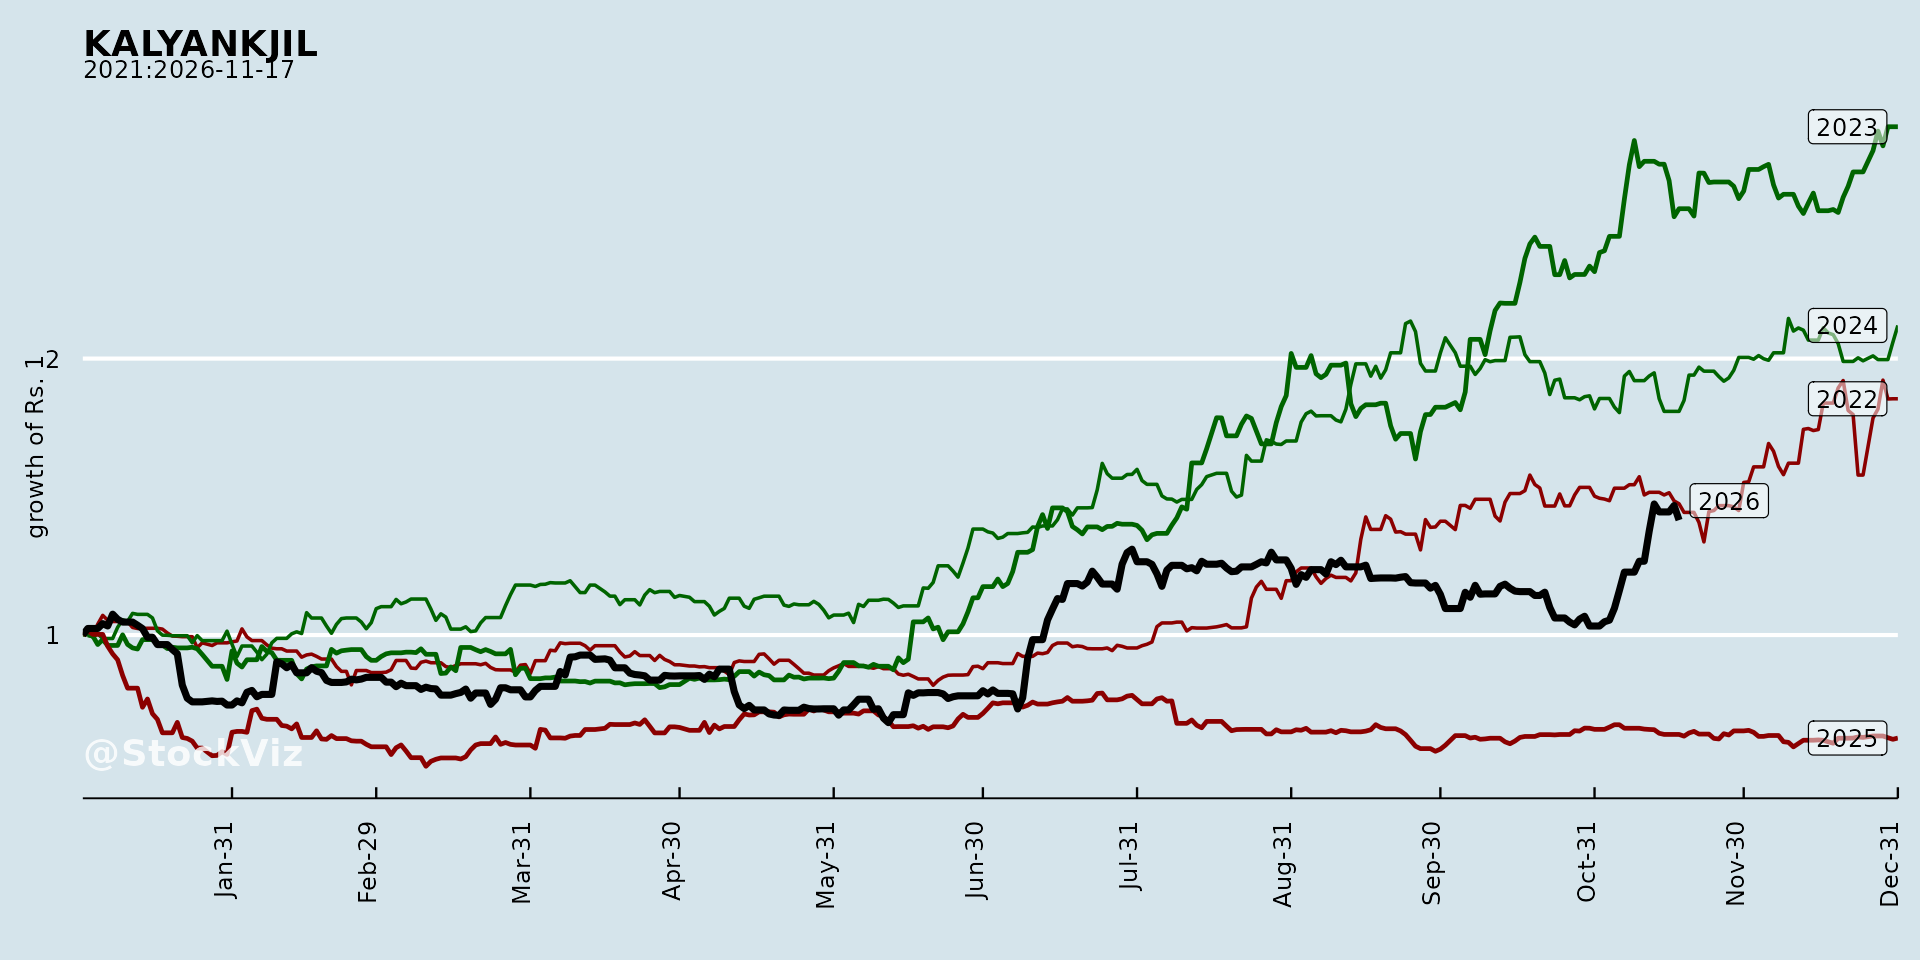
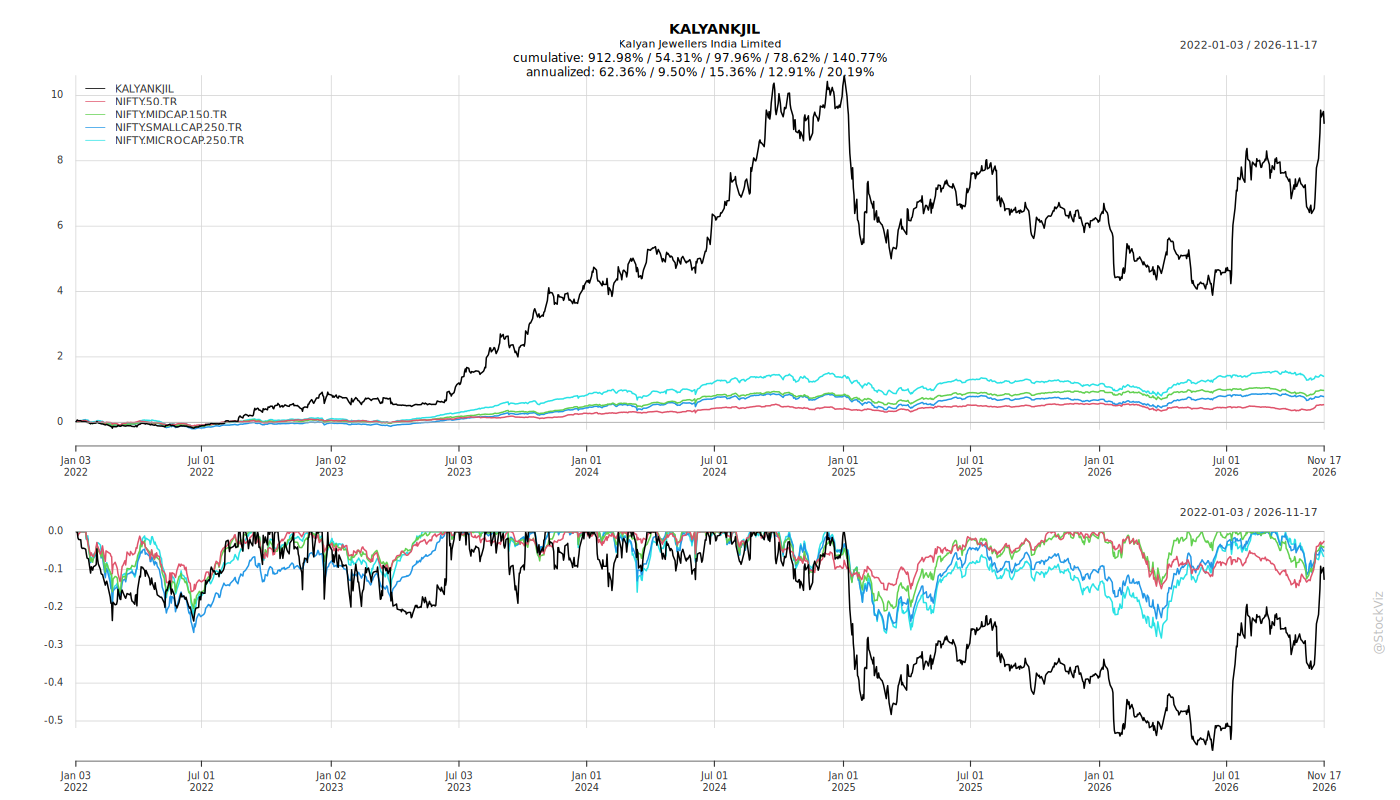
Cumulative Returns and Drawdowns
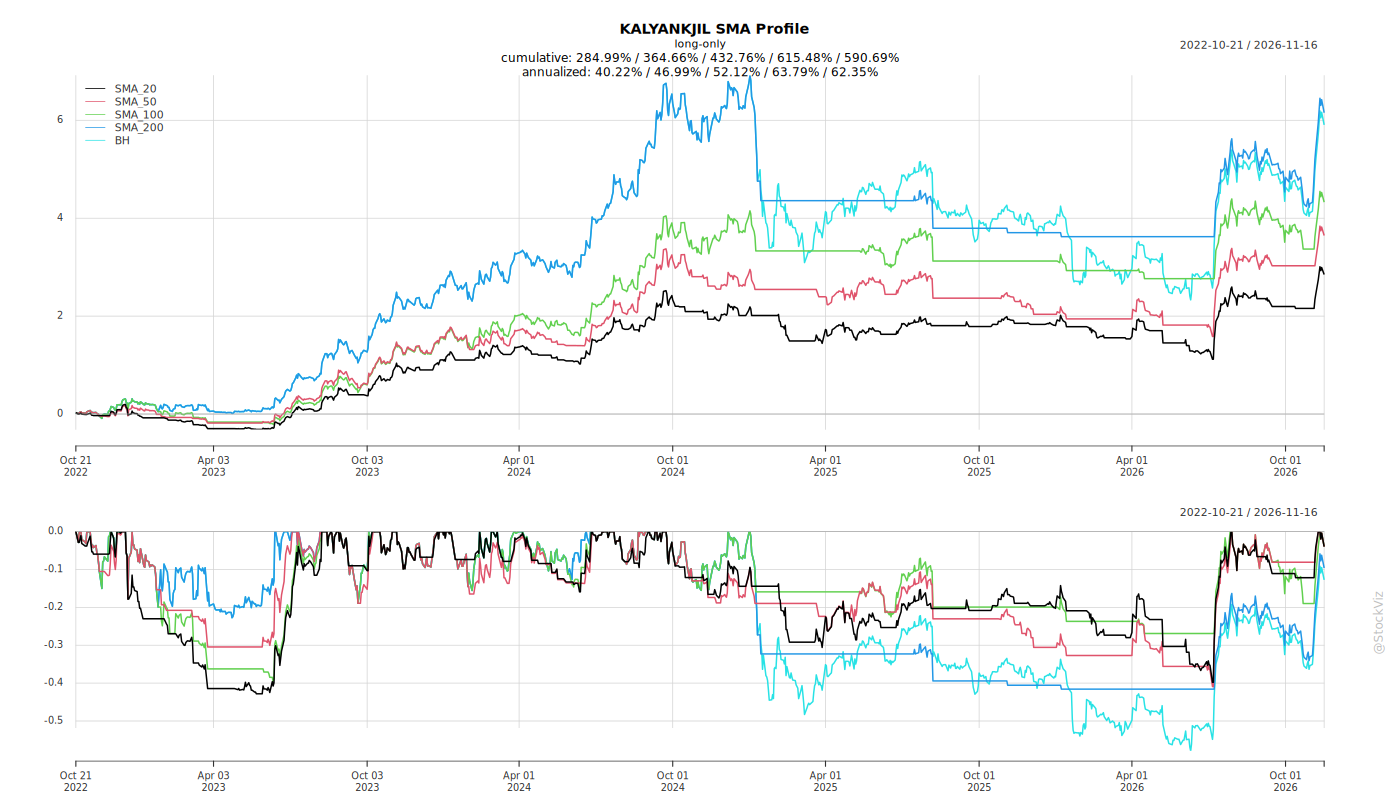
Fundamentals
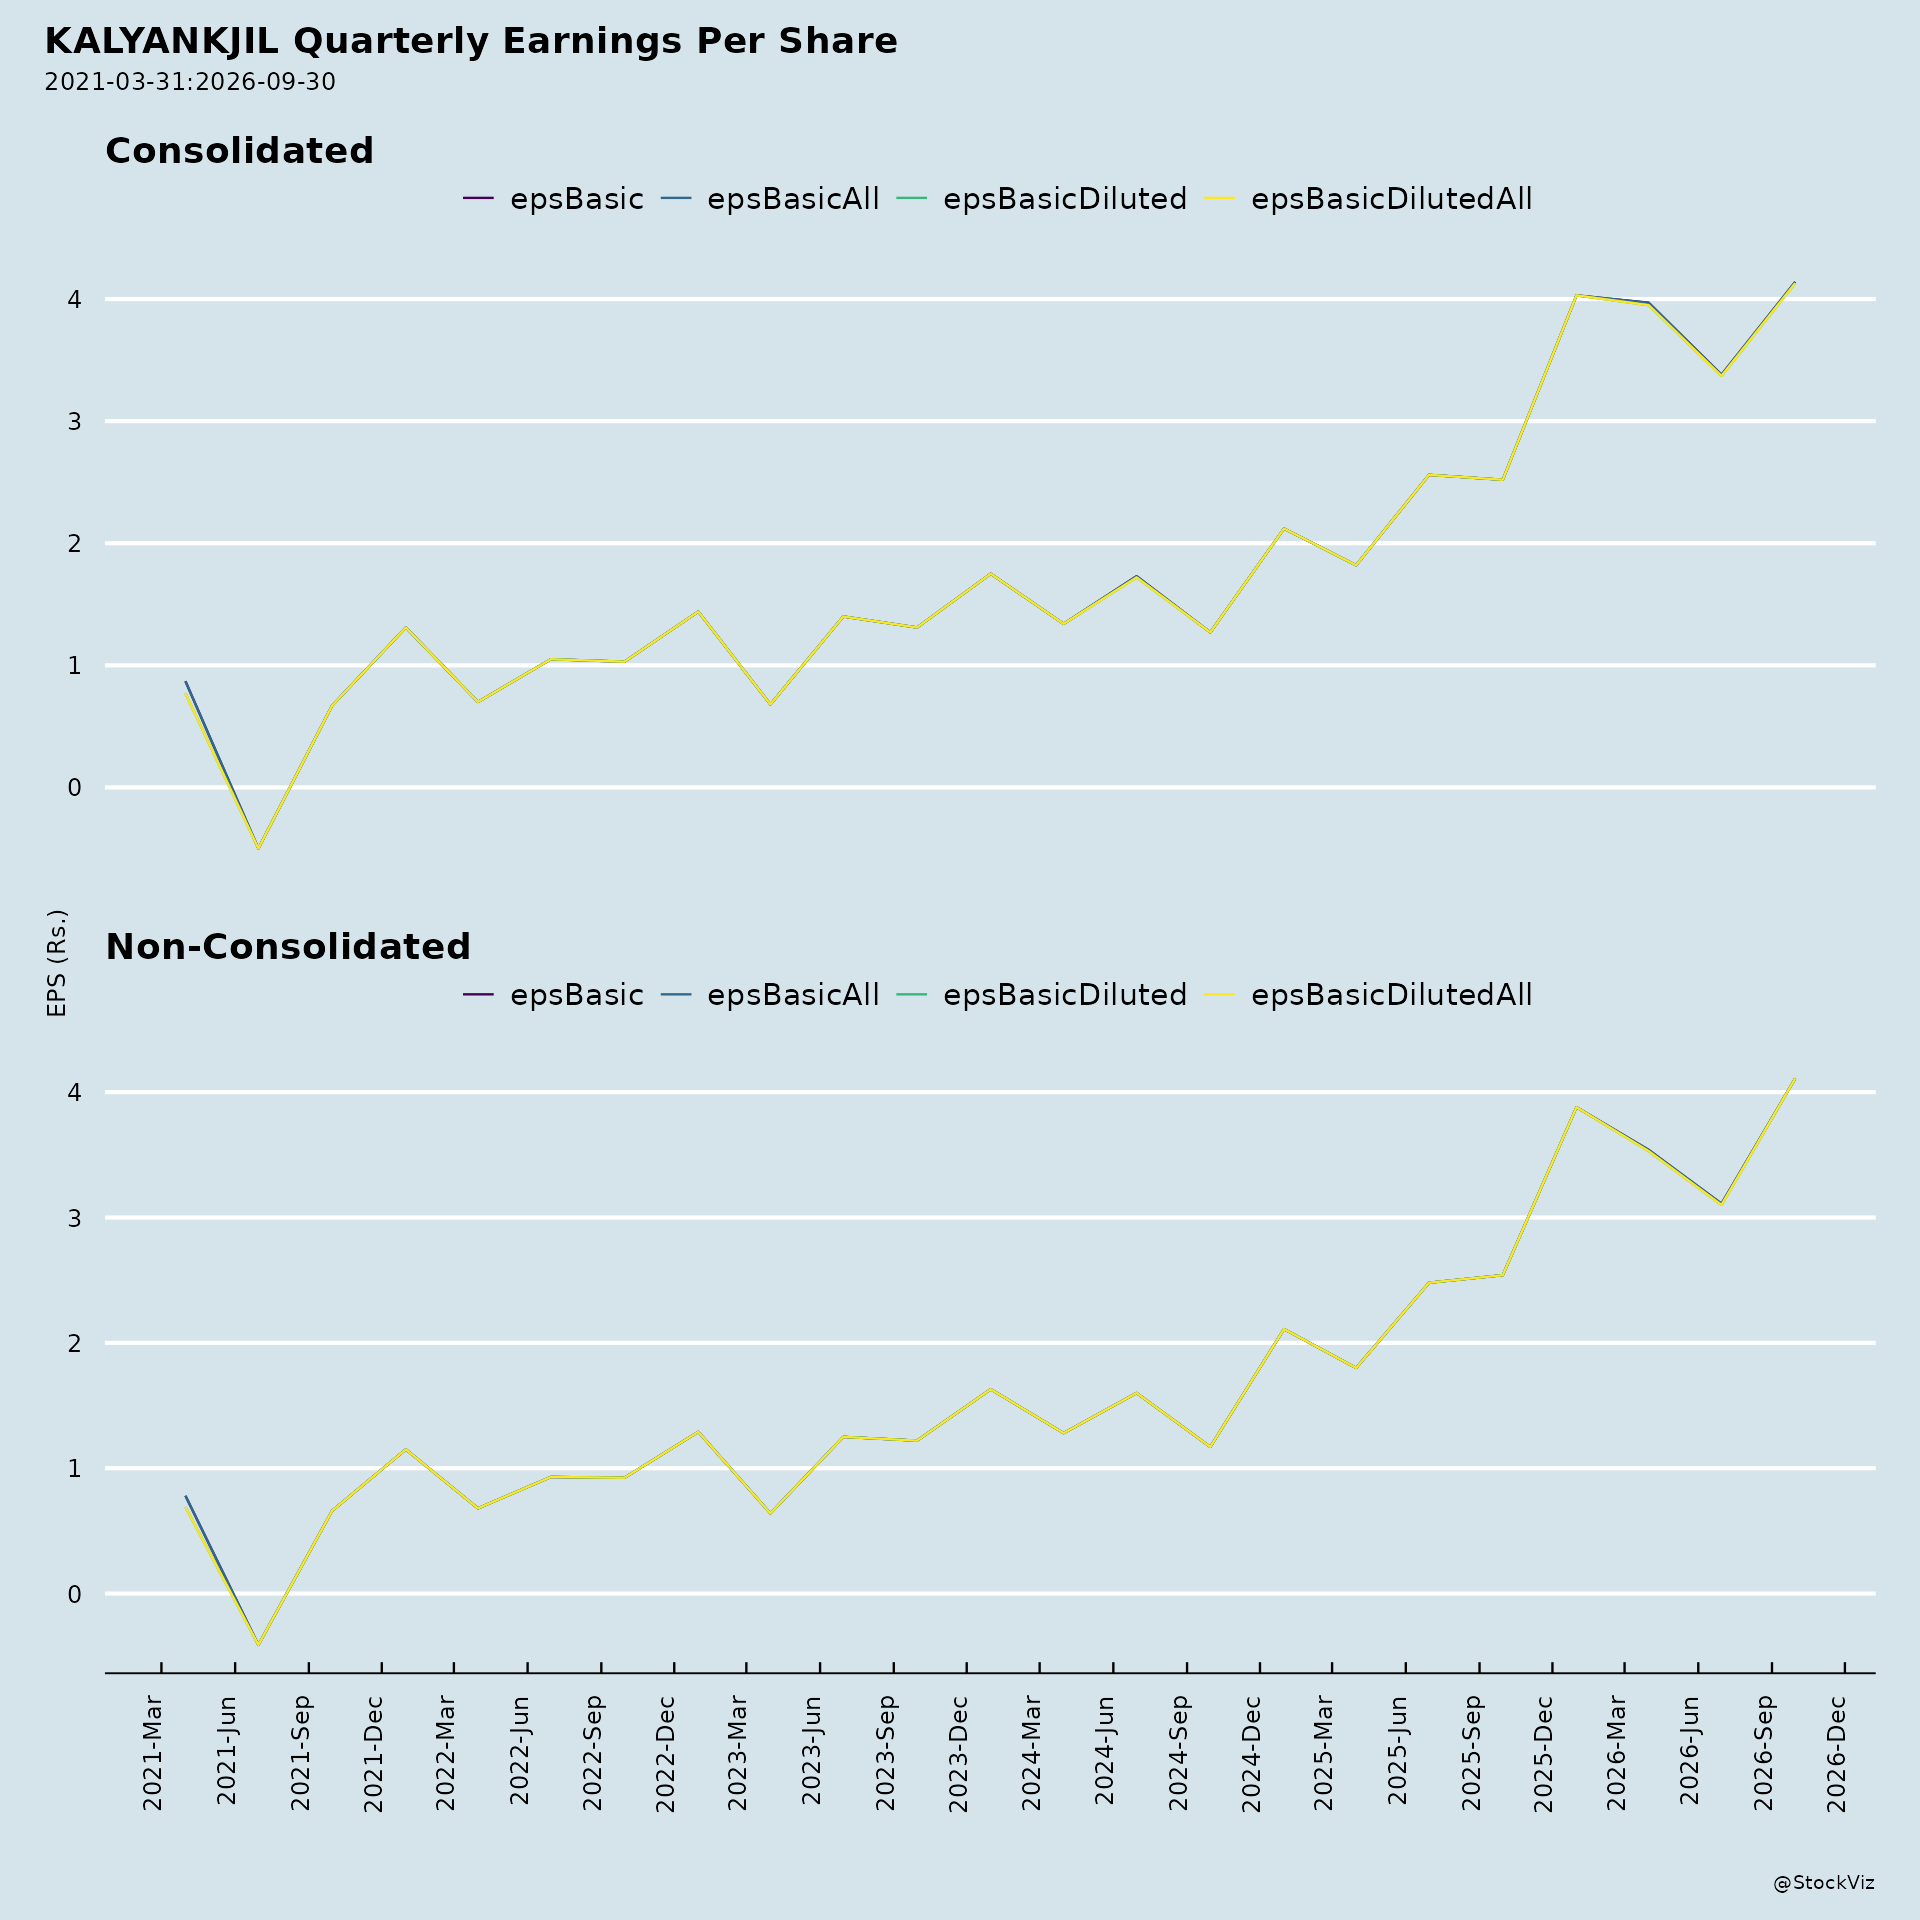
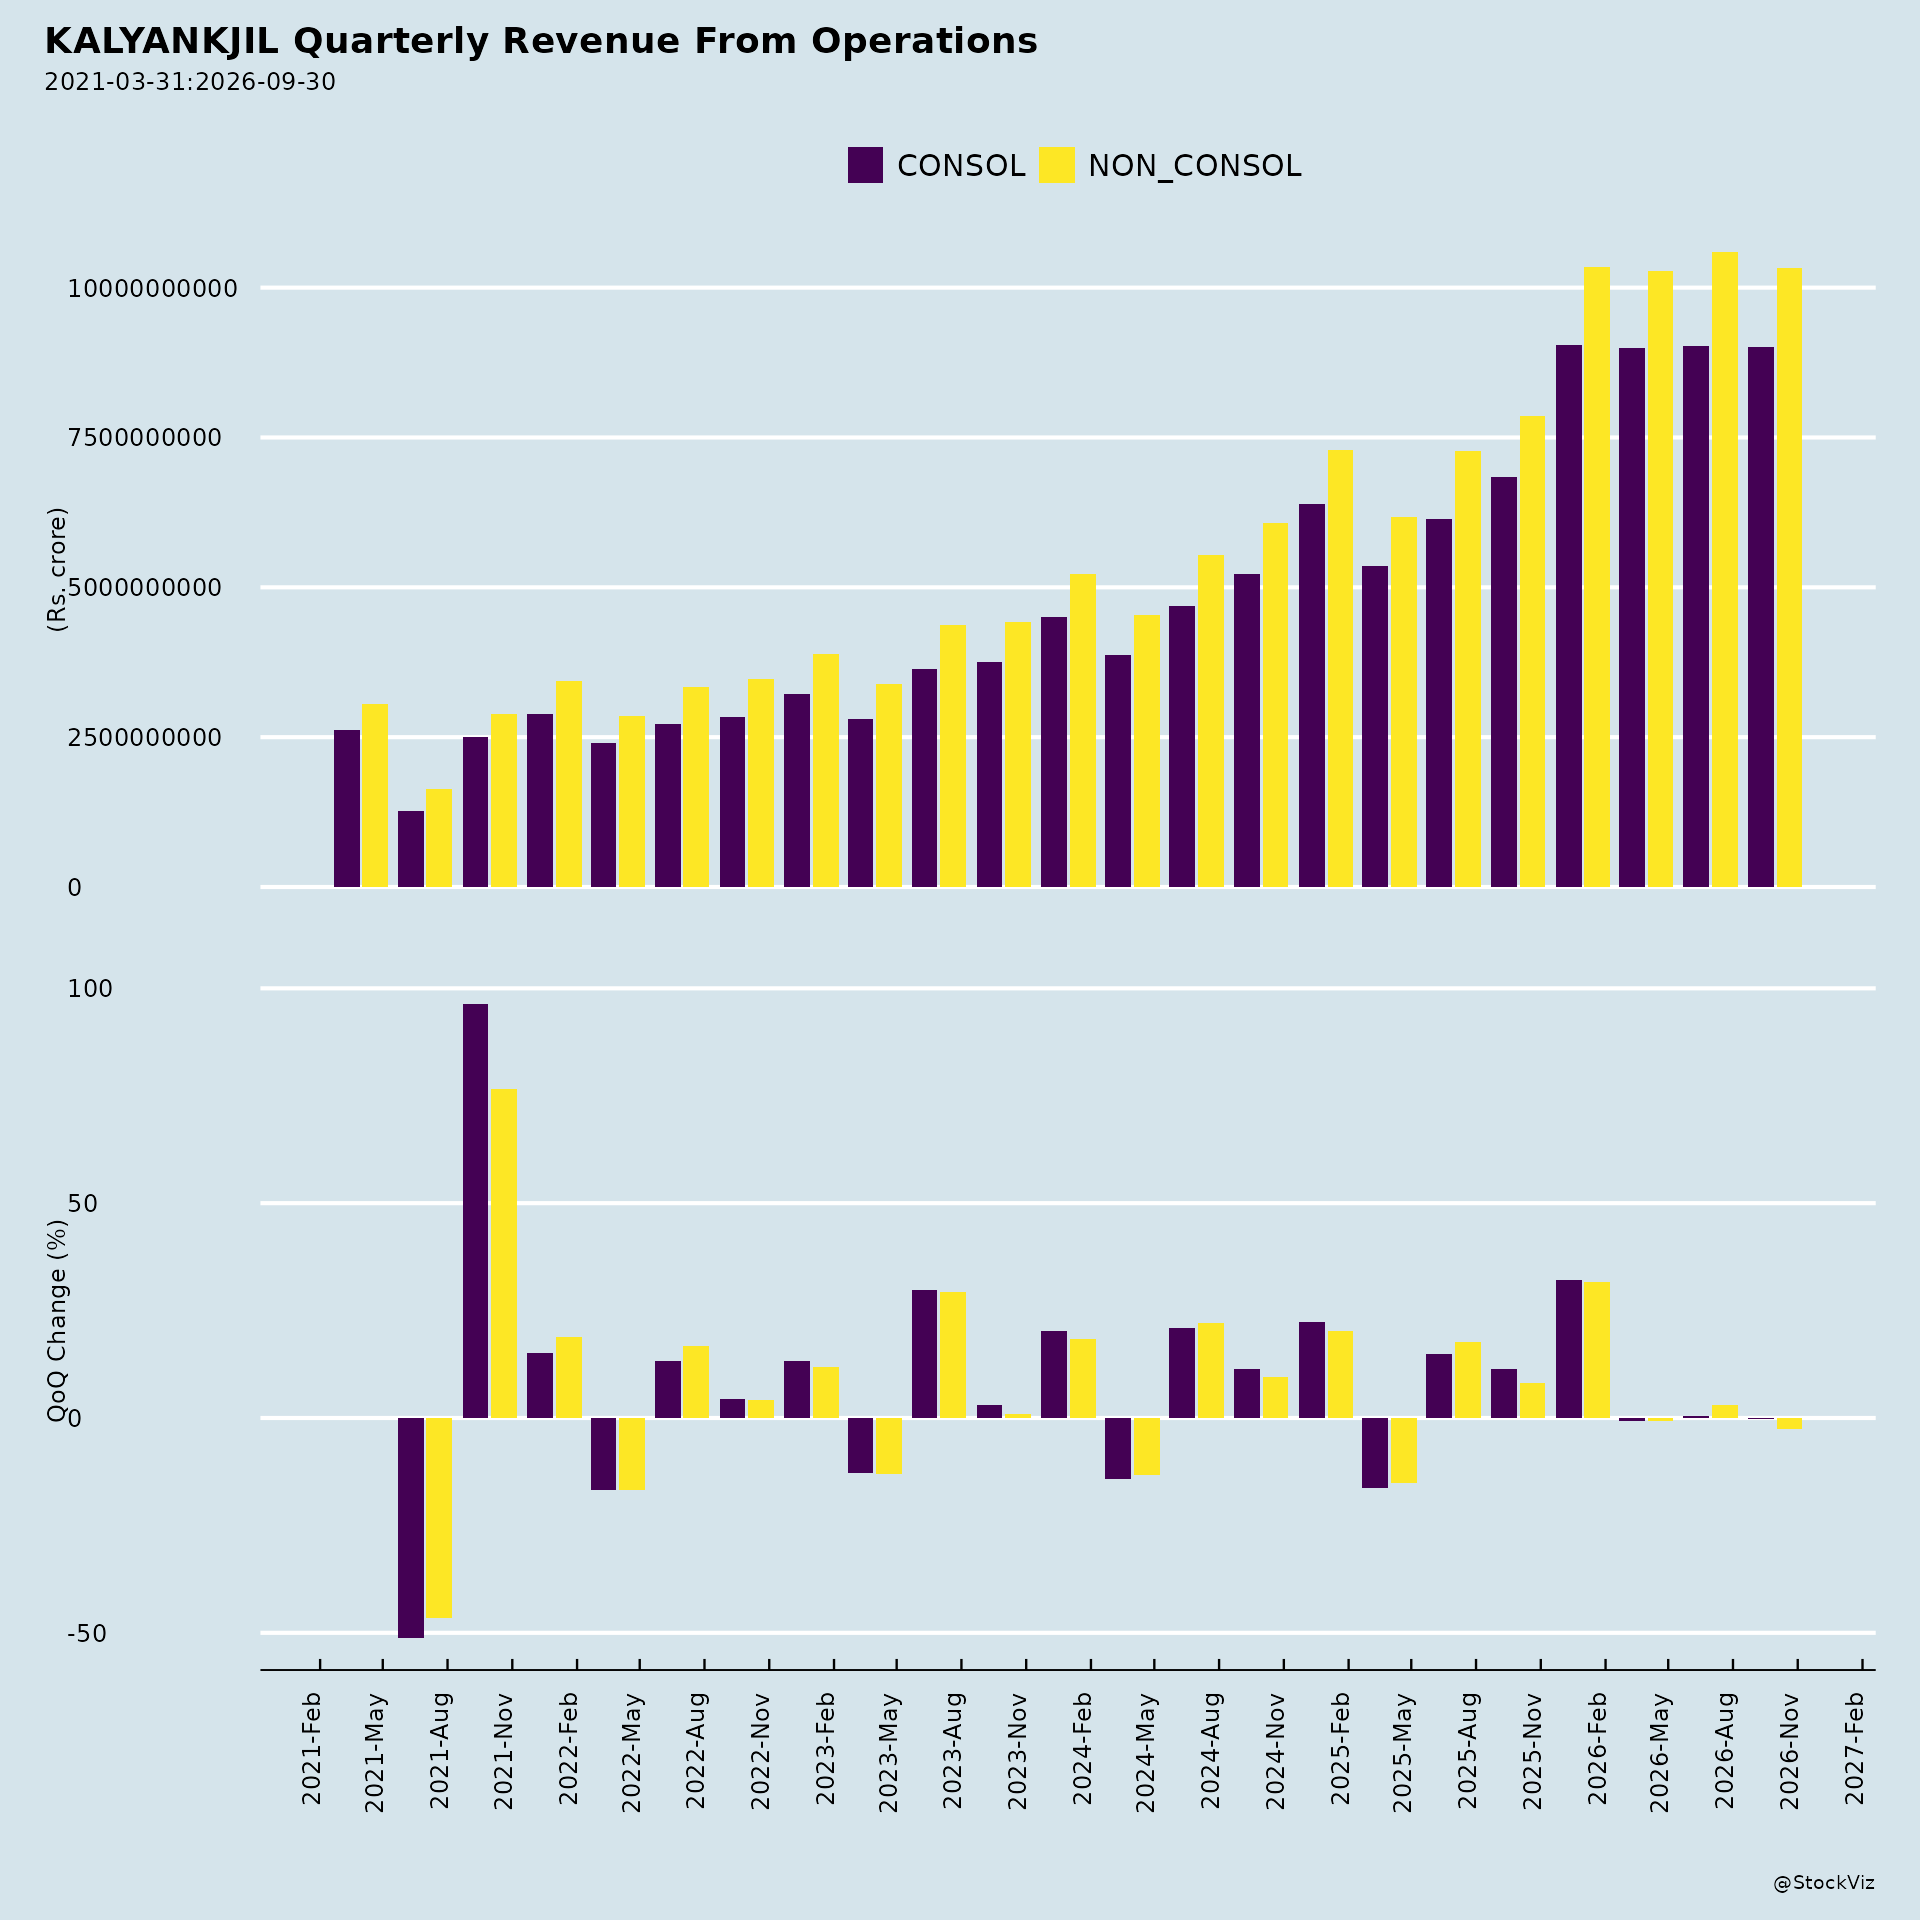
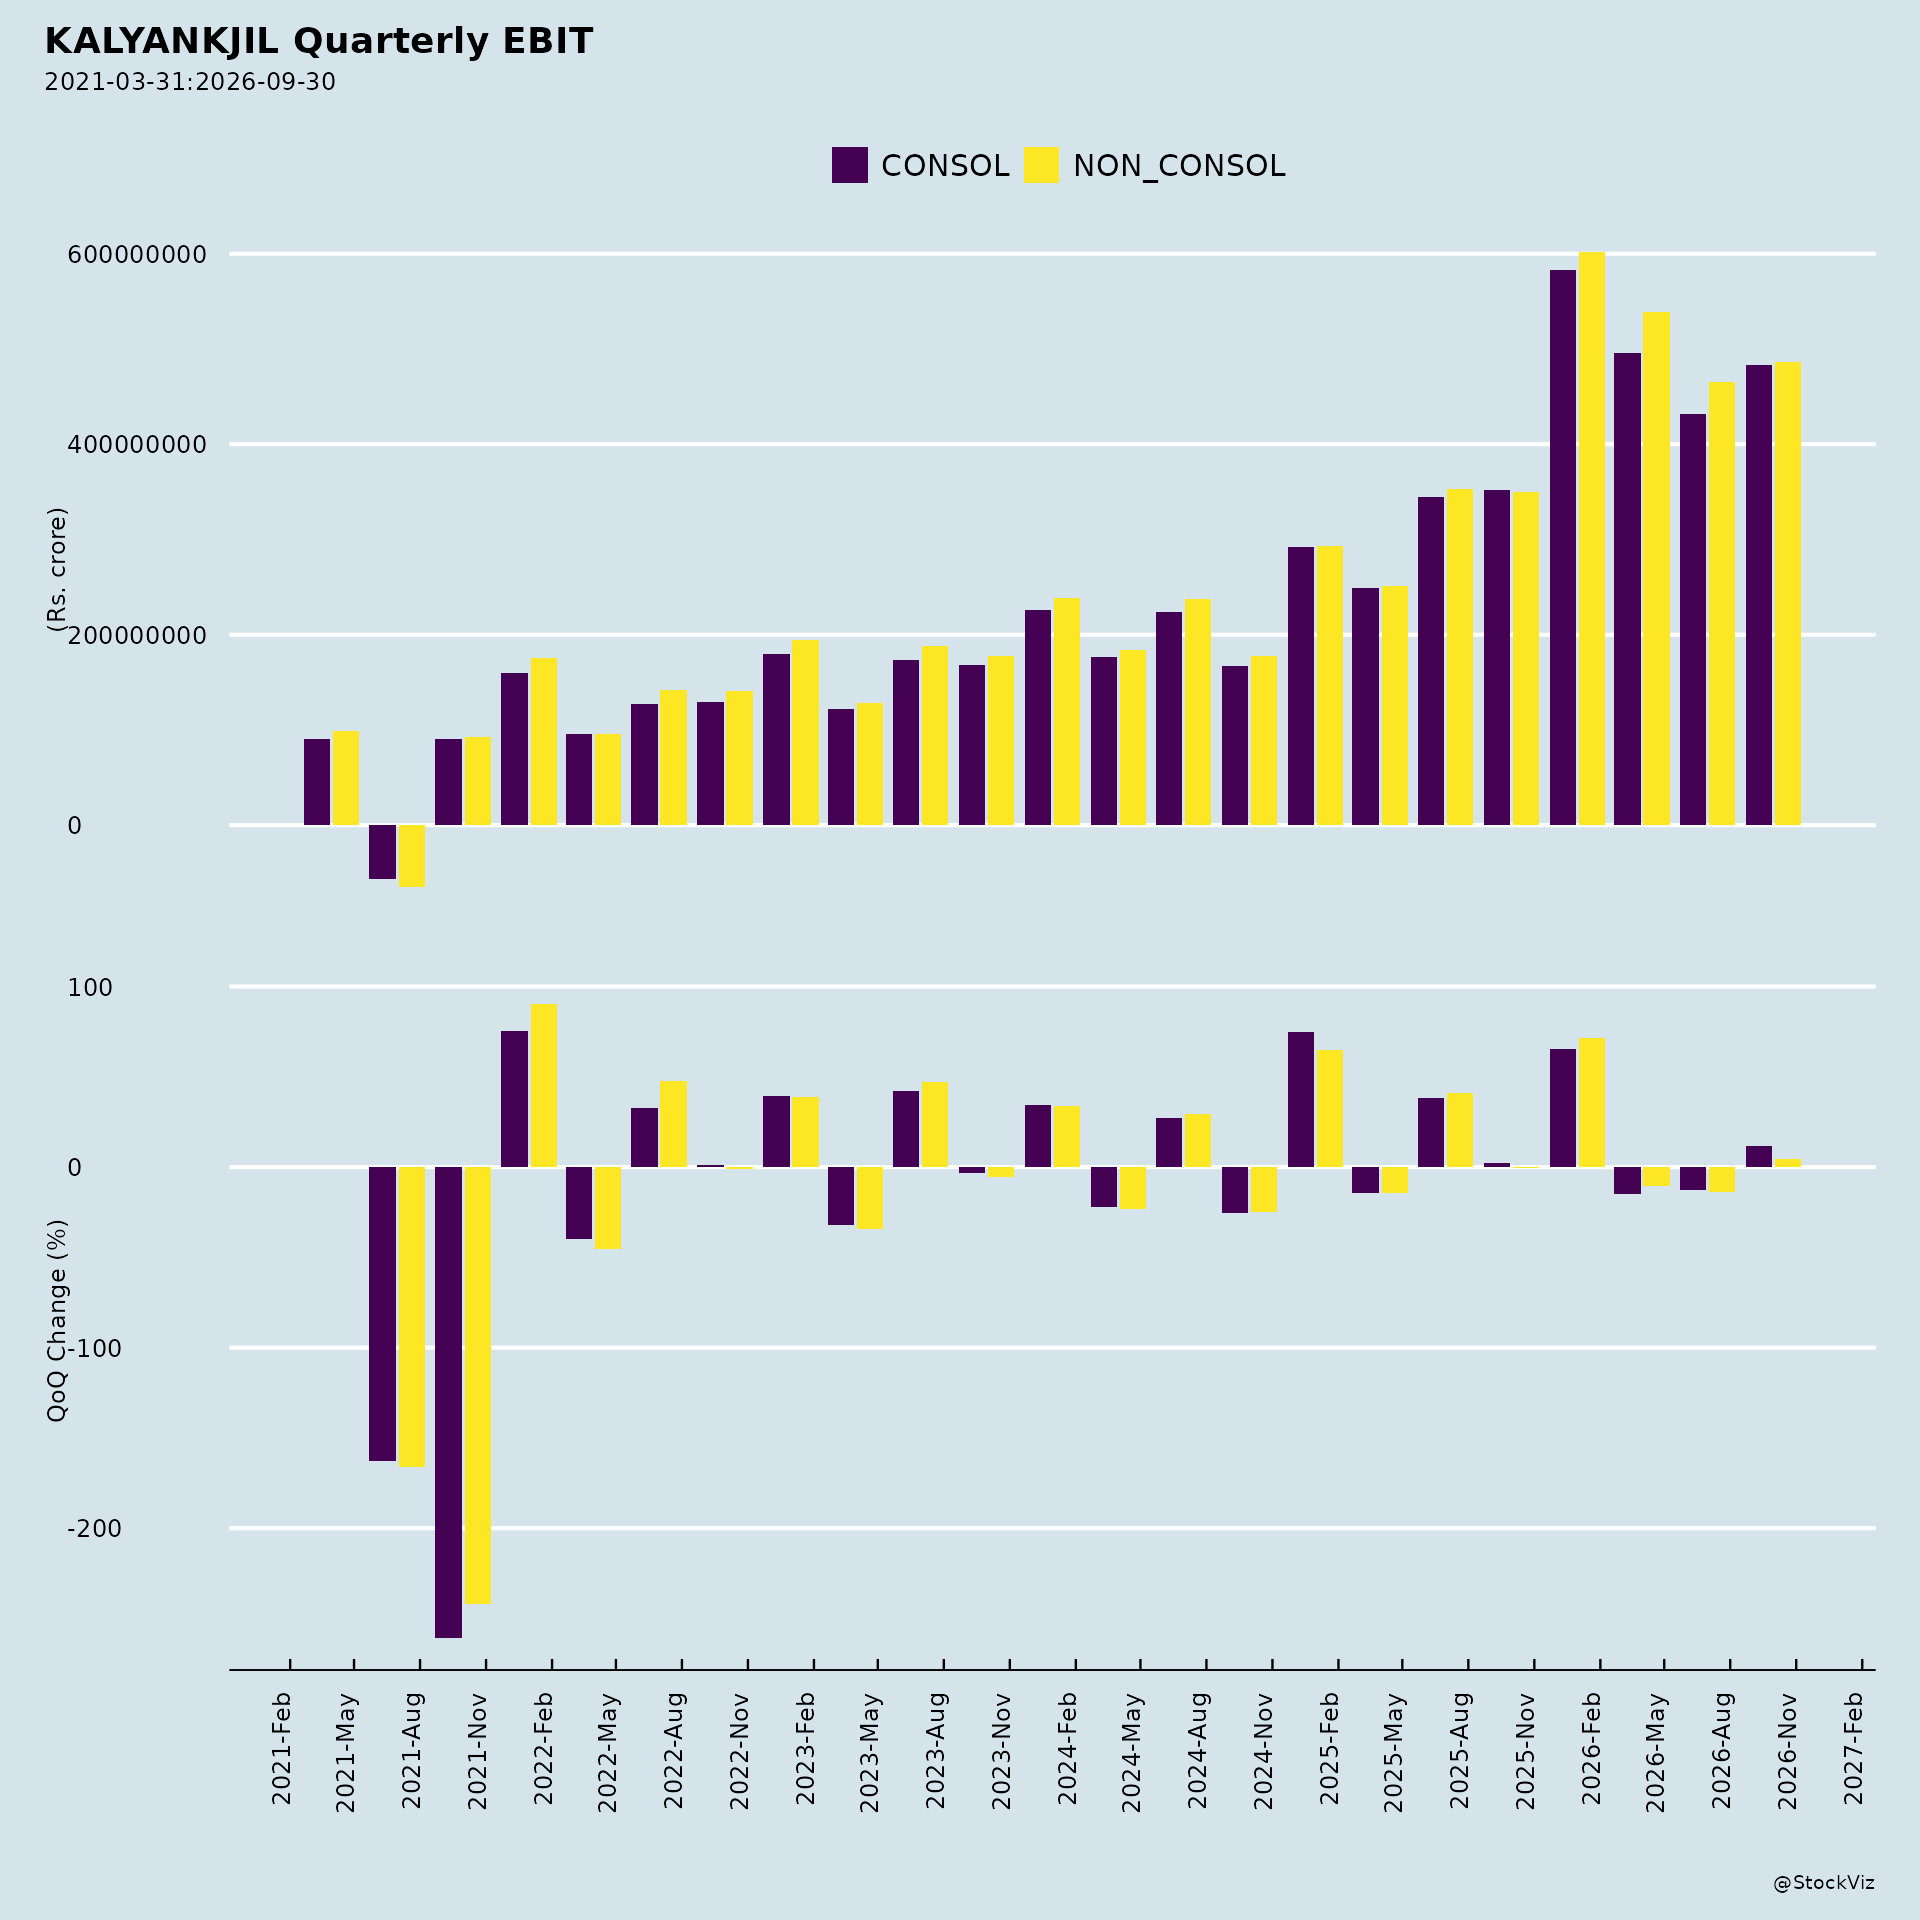
Ownership
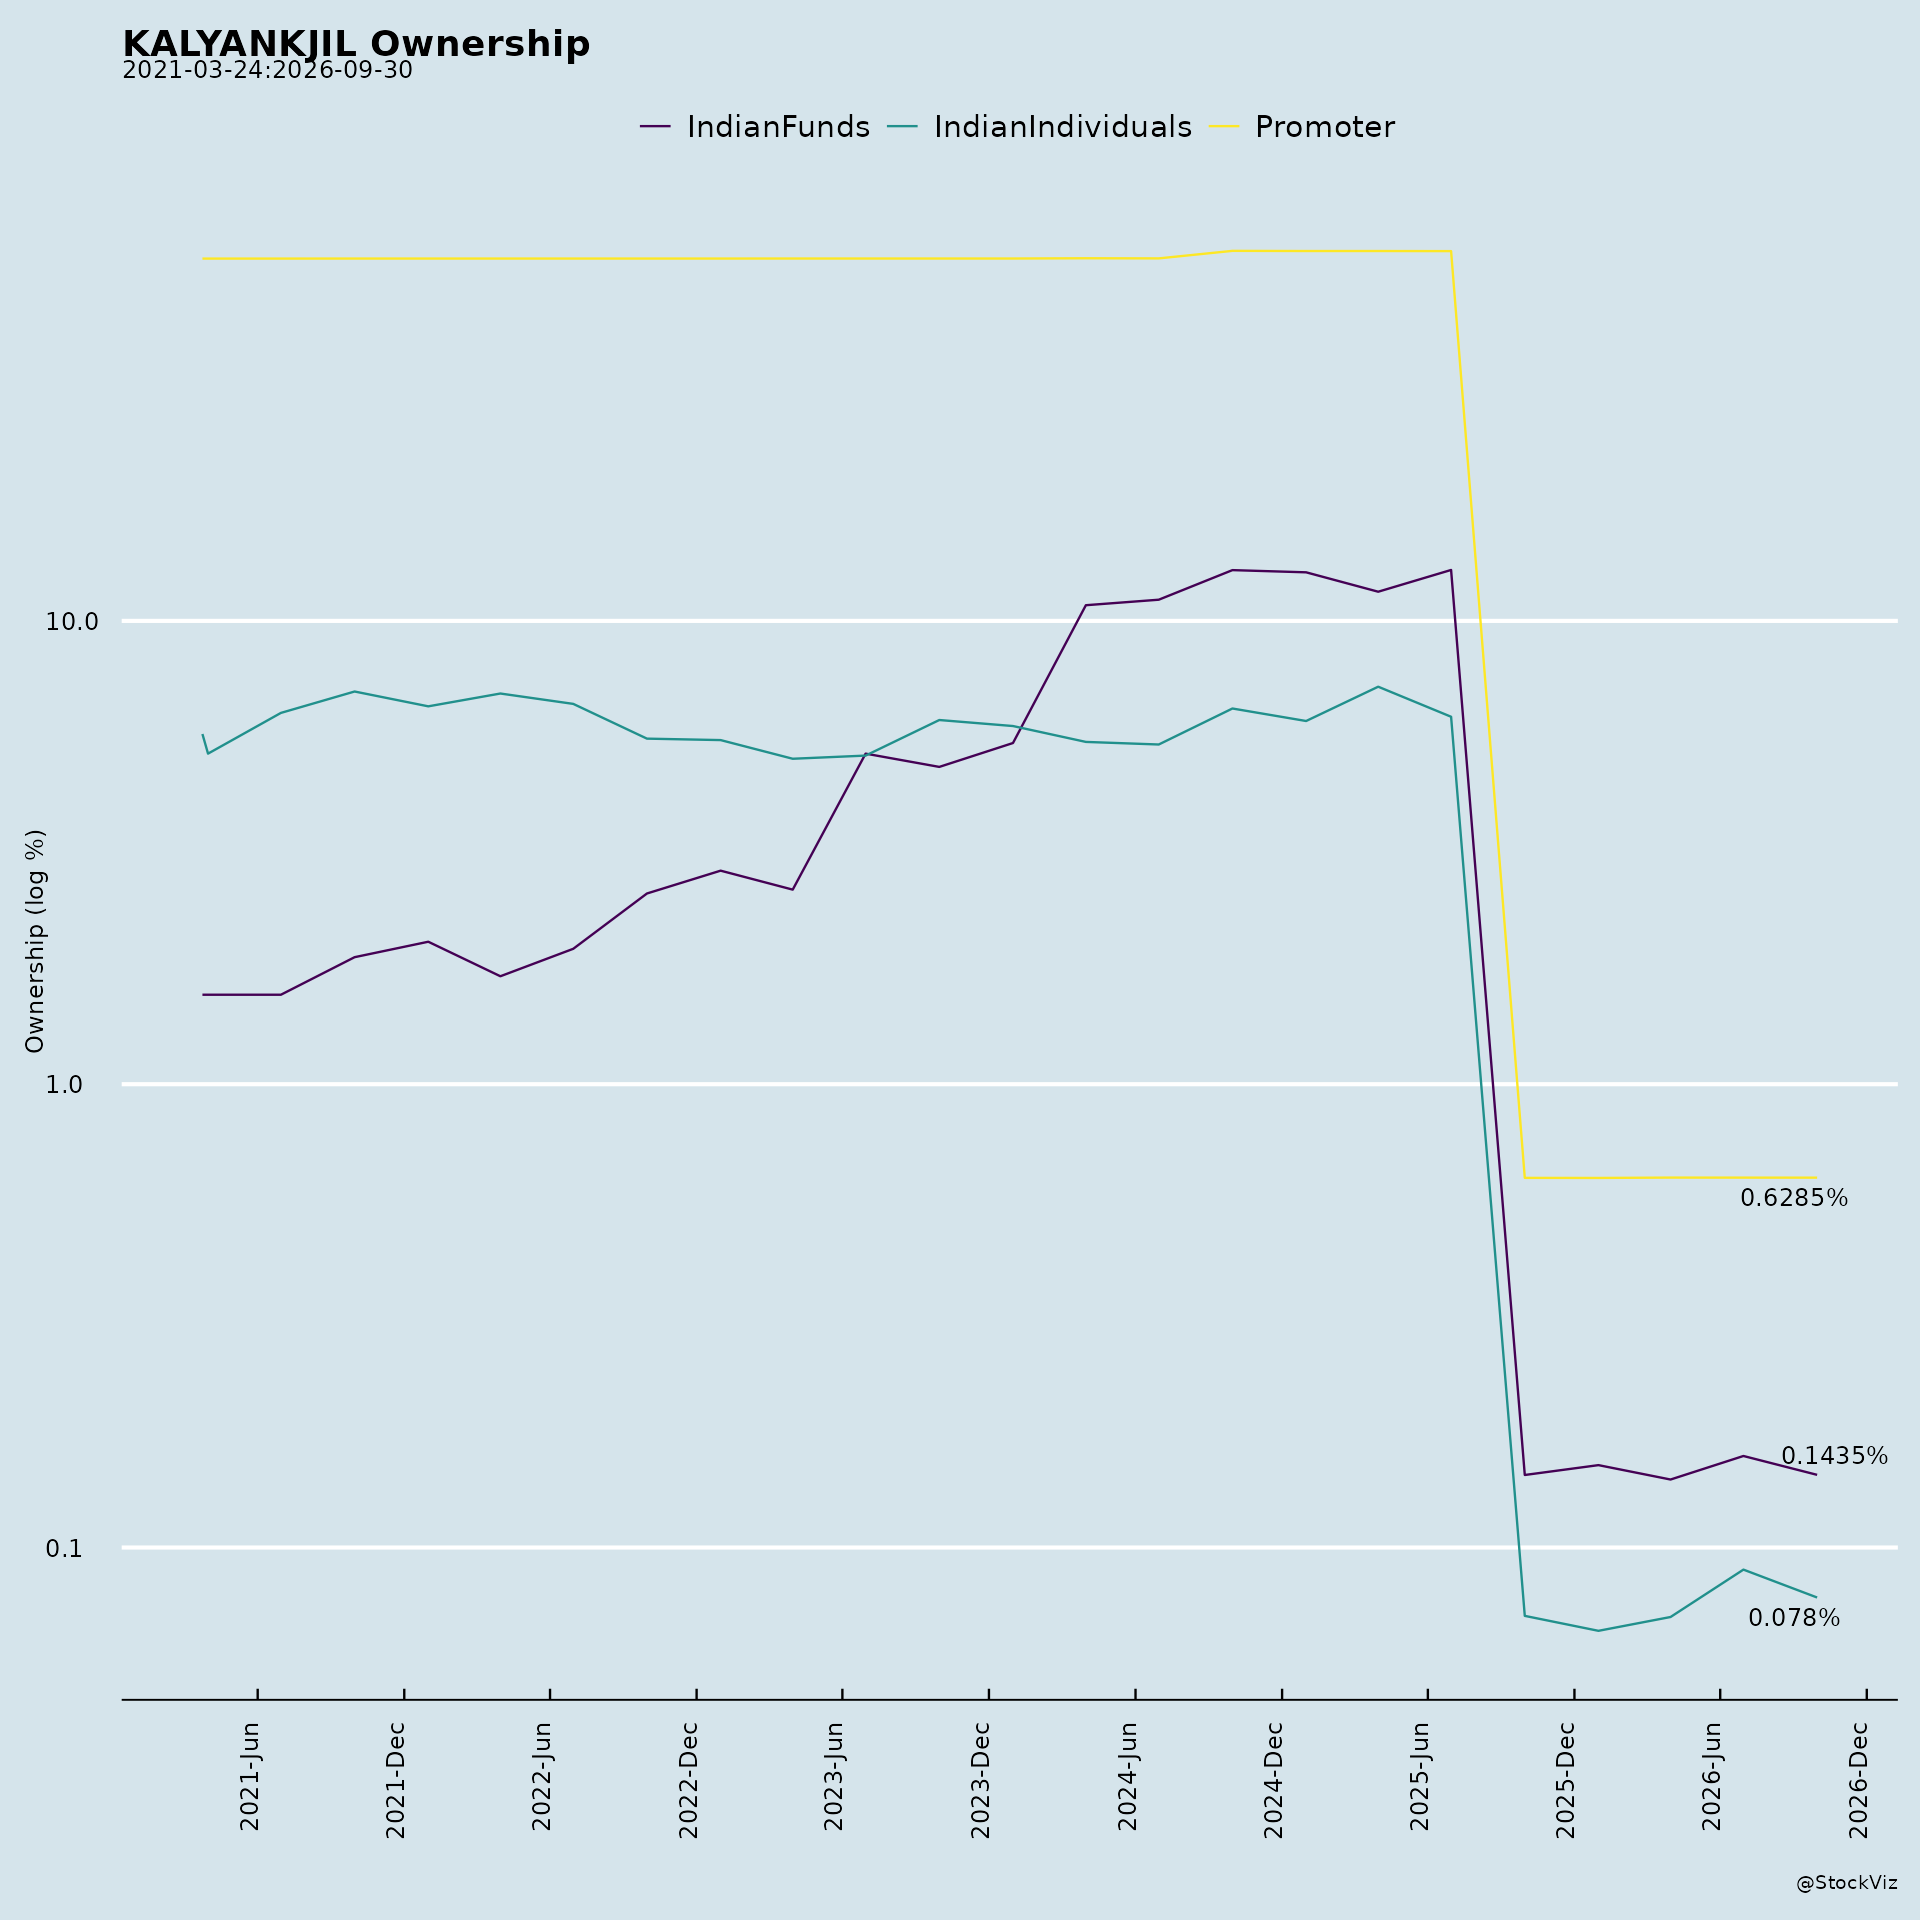
Margined
AI Summary
asof: 2026-09-16
Headwinds and Challenges
- Gross margin pressure in India. In Q1FY27, India gross margin was impacted by a higher proportion of exchanged gold, promotional offers as part of the exchange campaign, and a one-off gain in platinum and silver sale during the base quarter (Q1FY26). Consolidated gross margin fell to 11.9% in Q1FY27 from 13.9% in Q1FY26, and India gross margin declined to 11.2% from 13.6% year-on-year.
- Higher share of recycled/exchanged gold. The share of recycled gold during Q1FY27 stood at 46%, which weighed on margins.
- Studded mix dilution. India studded share was 29.7% in Q1FY27, marginally lower than 30.3% YoY; Middle East studded share was 16.3% versus 18.3% YoY.
- Middle East profitability pressure. Middle East EBITDA declined 4% YoY in Q1FY27 (₹899 Mn vs ₹728 Mn base comparison as presented), with EBITDA margin at 6.8% versus 7.1%, and PAT down 14% YoY. Showroom walk-ins only returned to normal from end-April.
- Margin compression across key lines. India EBITDA margin fell to 5.5% in Q1FY27 from 7.1% in Q1FY26; consolidated EBITDA margin fell to 6.0% from 7.0%; consolidated PAT margin fell to 3.3% from 3.6%.
- QoQ softness. Consolidated revenue grew 3% QoQ but EBITDA fell 14% QoQ and PAT fell 15% QoQ in Q1FY27 versus Q4FY26.
- One-time exceptional item. A ₹415 Mn exceptional impact was recognised due to changes in employee benefit provisions arising from the New Labour Codes.
- Regulatory/compliance obligations. The company is seeking shareholder approval to accept public deposits under Sections 73/76 of the Companies Act, 2013, and a special resolution for remuneration to the Non-Executive Chairman exceeding 50% of aggregate Non-Executive Director remuneration for FY2026-27 under Regulation 17(6)(ca) of SEBI LODR.
- Tax withholding complexity for shareholders. TDS at 10% (valid PAN) or 20% (invalid/no PAN) applies to the final dividend, with documentation deadlines of 12 September 2026.
Tailwinds and Growth Prospects
- Strong Q1FY27 revenue growth. Consolidated revenue rose 46% YoY to ₹1,05,889 Mn; India revenue rose 38% to ₹85,033 Mn; Middle East revenue rose 29% to ₹13,201 Mn.
- Healthy same-store-sales growth. India SSSG was 28% in Q1FY27 (South ~30%, Non-South ~27%); Middle East SSSG was ~25%.
- New customer additions. Share of new customers in India remained above 36% in Q1FY27.
- Franchise (FOCO) model scaling. India franchised showroom revenue share was ~57% in Q1FY27 (30% in Q1FY26; 31% in Q4FY26). As of 30 June 2026, there were 234 FOCO Kalyan showrooms in India, 73 FOCO Candere showrooms, and 1 Kalyan FOCO in the UK.
- Capital-light expansion plans. FY27 plans include 84 Kalyan showrooms in India (all FOCO), 6 international showrooms, and 50 Candere showrooms via a mix of COCO and FOCO. Discussions are underway with potential investors in the Middle East for a larger FOCO partnership, and work is ongoing to convert more Middle East showrooms to FOCO.
- New regional brand. Akshaya Thanga Maligai (ATM), exclusively curated for Tamil Nadu, was scheduled to launch its first showroom on 21 August in Chennai. The first regional brand under the FY27 roadmap is to be launched in FY27.
- Candere expansion. Candere had 129 showrooms (73 FOCO) as of 30 June 2026, with TTM revenue of ₹5,581 Mn; Shah Rukh Khan was onboarded as brand ambassador in FY26.
- Balance sheet deleveraging. Standalone non-GML debt fell to ₹3,168 Mn as of 30 June 2026 from ₹8,808 Mn a year earlier; non-GML debt is targeted to be fully repaid in FY27. Total standalone debt was ₹16,001 Mn (GML ₹12,833 Mn).
- Return profile improvement. ROCE improved to 30.3% (TTM) from 28.8% (FY26) and 19.8% (FY25); ROE improved to 25.8% (TTM) from 24.3% (FY26) and 15.9% (FY25).
- Credit rating upgrade. Rating enhanced from A+ (Positive) to AA- (Stable), with further enhancement expected.
- Non-core asset divestiture. Agreement signed to sell first set of non-core real estate assets worth ₹102 Cr; additional real estate collateral release worth ₹2,000 Mn expected during FY2027.
- Shareholder returns. FY26 dividend of ₹2,582 Mn (payout ~20%) to be paid during FY27; ₹1,525 Mn dividend paid during FY26. Final dividend of ₹2.50 per equity share (25%) recommended for FY2025-26.
- Industry structural drivers. Shift from unorganised to organised retail (organised share rising from 32% in 2000 to 40% in 2025 per Technopak), GST compliance, mandatory PAN for transactions above ₹2,00,000, compulsory hallmarking from 2021, and rural policy push.
- My Kalyan network. 1,157 grassroots stores, 4,723 employees, ~21% contribution to India revenue, ~31% of purchase advance scheme enrolments in India, and ~10 Mn customer connects annually.
- International footprint. 41 Kalyan showrooms internationally (38 Middle East, 2 USA, 1 UK) as of 30 June 2026.
Key Risks
- Margin sustainability. Gross and EBITDA margins declined YoY in Q1FY27 across India, Middle East, and consolidated segments, driven by exchange gold mix, promotions, and base-quarter one-offs.
- Gold price and inventory risk. The business hedges gold inventory against price fluctuations; GML stood at ₹12,833 Mn standalone as of 30 June 2026.
- Execution risk on expansion. FY27 plans include 84 Kalyan India showrooms, 6 international showrooms, 50 Candere showrooms, and 5 new regional brand showrooms; conversion of Middle East showrooms to FOCO is under discussion.
- Geographic concentration. South India contributed 43% of India revenue in Q1FY27 (₹41,879 Mn of ₹85,033 Mn); non-south contributed ~57%.
- Regulatory and tax compliance. Public deposit acceptance requires shareholder approval and compliance with Sections 73/76 and the Companies (Acceptance of Deposits) Rules, 2014. Dividend TDS documentation must be submitted by 12 September 2026.
- Governance-related approvals. Special resolution sought for Non-Executive Chairman remuneration exceeding 50% of aggregate Non-Executive Director remuneration for FY2026-27.
- Forward-looking statement risk. The presentation notes risks including Indian and global economic performance, industry performance, competition, strategy implementation, growth and expansion levels, technological changes, revenue/income/cash flow changes, market preferences, and market risk exposure.
Management Guidance vs. Observed Performance
- Non-GML debt repayment. Management targets complete repayment of non-GML debt in FY27. Observed: standalone non-GML debt reduced to ₹3,168 Mn as of 30 June 2026 from ₹8,808 Mn as of 31 March 2025; ₹10,073 Mn non-GML loans repaid in India from 1 April 2023 to 31 March 2026; ₹5,640 Mn non-GML reduction in India during FY26.
- Capital-light expansion. Management targets expansion largely via FOCO. Observed: 234 FOCO Kalyan India showrooms and 73 FOCO Candere showrooms as of 30 June 2026; FY26 network expansion largely through FOCO showrooms; India franchised revenue share at ~57% in Q1FY27.
- ROCE improvement. Management targets meaningful improvement. Observed: ROCE improved to 30.3% (TTM) from 28.8% (FY26), 19.8% (FY25), and 17.4% (FY23).
- Dividend policy. Management indicates 40–50% of profits to be used for debt repayment, new strategic initiatives, and rewarding shareholders. Observed: ₹1,525 Mn dividend paid during FY26; FY26 dividend of ₹2,582 Mn (~20% payout) to be paid during FY27; ₹2.50 per share final dividend recommended for FY2025-26.
- FY27 showroom targets. Management targets 84 Kalyan India showrooms (all FOCO), 6 international showrooms, 50 Candere showrooms, and 5 new regional brand showrooms. Observed: 12 new India showrooms added in Q1FY27; ATM first showroom scheduled for 21 August in Chennai.
- Middle East FOCO partnership. Management states discussions are underway with potential investors for a larger FOCO partnership. Observed: Middle East showroom count at 38 as of Q1FY27 versus 36 in Q1FY26; 1 FOCO showroom internationally as of 30 June 2026.
- Credit rating. Management expects further enhancement. Observed: rating enhanced from A+ (Positive) to AA- (Stable).
- Non-core asset divestiture. Management targets divestiture of select non-core assets. Observed: agreement signed to sell first set of non-core real estate assets worth ₹102 Cr; additional real estate collateral release worth ₹2,000 Mn expected during FY2027.
- Same-store-sales growth. Management targets mid-to-high single digits. Observed: India SSSG of 28% and Middle East SSSG of ~25% in Q1FY27, above the stated target range.
- Investor engagement. The company is scheduled to participate in the Jefferies India Forum 2026 on 17 September 2026 via in-person meeting; meeting dates are subject to change in case of exigencies, and only information already in the public domain will be shared.
Broker Narrative
The core thesis persisted end-to-end — asset-light FOCO expansion, strong consolidated revenue/SSSG, and balance-sheet repair (the early deleveraging roadmap of divesting land and a private aircraft matured into ‘full repayment of non-GML debt in India and real estate monetization’) — so the call stayed Buy/Add almost throughout. What rotated was the risk map: the first report feared gold-price volatility crushing sentiment/demand, Candere e-commerce -18% YoY, cost pressure (ads +24%, employee +27.1%), a ₹330M one-time write-off and inventory days stretching 175 to 182, whereas the last report drops Candere/write-off and instead flags higher Middle East finance costs, one-off inventory losses on silver/platinum open positions hitting gross margins, and a high 4Q base. Realized returns stayed strongly positive overall, with only two DISAPPOINTMENTs (2024-09-04 Hold; 2025-03-20 Add, actual -17.9%).
Fears that came true
- The early fear that a ‘sharp rise and volatility in gold prices’ would hit ‘consumer sentiment and overall demand’ is the one risk mapping to the book’s only negative actual return (-17.9% on 2025-03-20, an Add call logged DISAPPOINTMENT), and precious-metal volatility later re-emerged concretely as ‘one-off inventory losses due to open positions in silver and platinum’ that left gross margins ‘impacted.’
Optimism that failed
- The early deleveraging tailwind of debt reduction ‘freeing capital and lowering interest expenses’ did not fully deliver on the cost side — the last report still flags ‘higher finance costs in the Middle East business’ even after India non-GML debt was repaid.
- The ‘higher studded mix & margin expansion’ driver (studded +37%, gross margin +20 bps to 15.8%) was not sustained, as the last report shows ‘gross margins impacted by one-off inventory losses due to open positions in silver and platinum.’
Broker Timeline
24 broker calls · 2023-05-15 to 2026-11-11
CNBC-TV18: ratings, targets and commentary
Extracted from CNBC-TV18 posts; ratings and targets are as published, not current consensus. OCR may contain errors. Speaker attribution is retained; not all speakers are brokers. These statements are separate from the Broker Narrative and Broker Timeline and have no calculated performance or outcomes.
Ratings and targets
| Published / source (IST) | Speaker / affiliation | Rating / target | Commentary |
|---|---|---|---|
| 2026-11-11 |
UBS
|
—
Target: INR 900
|
UBS sees Kalyan Jewellers stock at ₹900 |
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.