JIOFIN
Equity Metrics
September 24, 2026
Jio Financial Services Limited
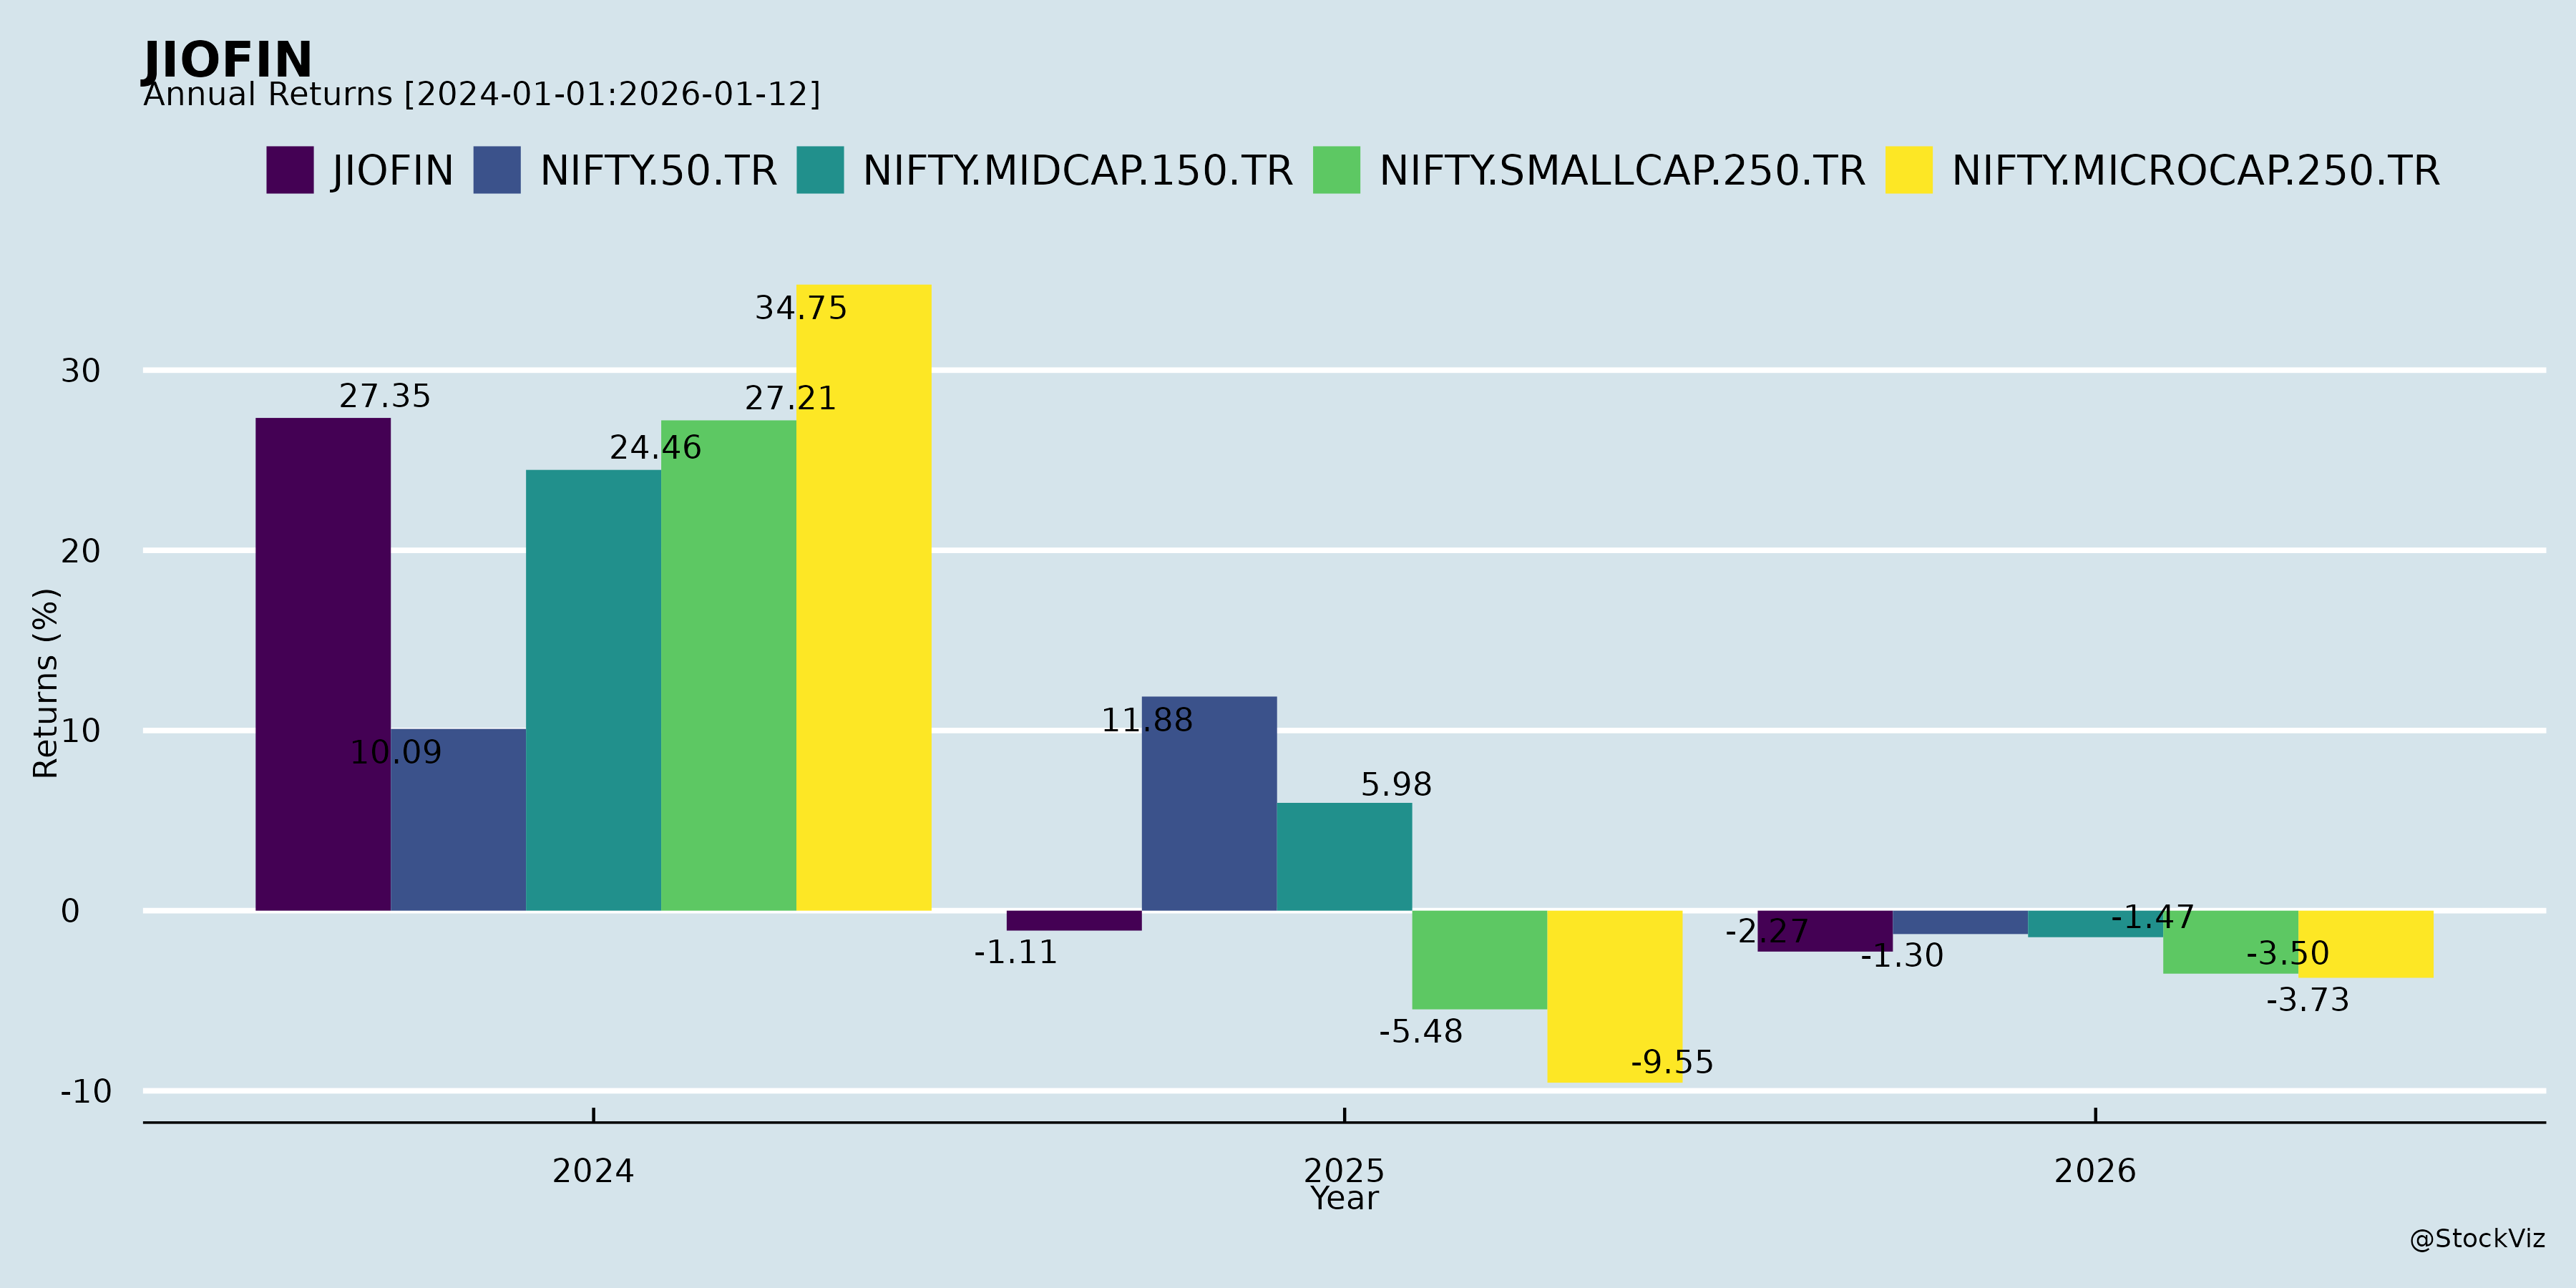
Annual Returns

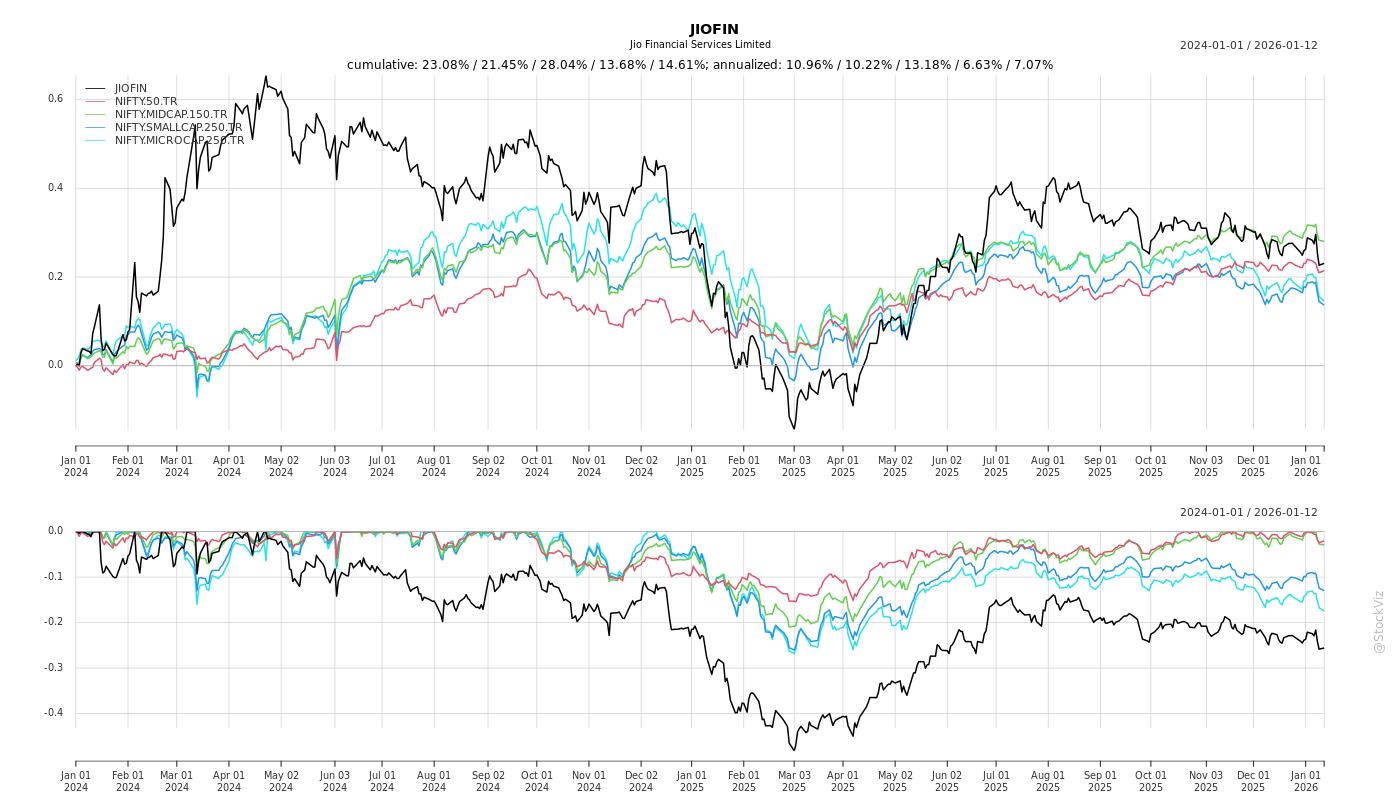
Cumulative Returns and Drawdowns
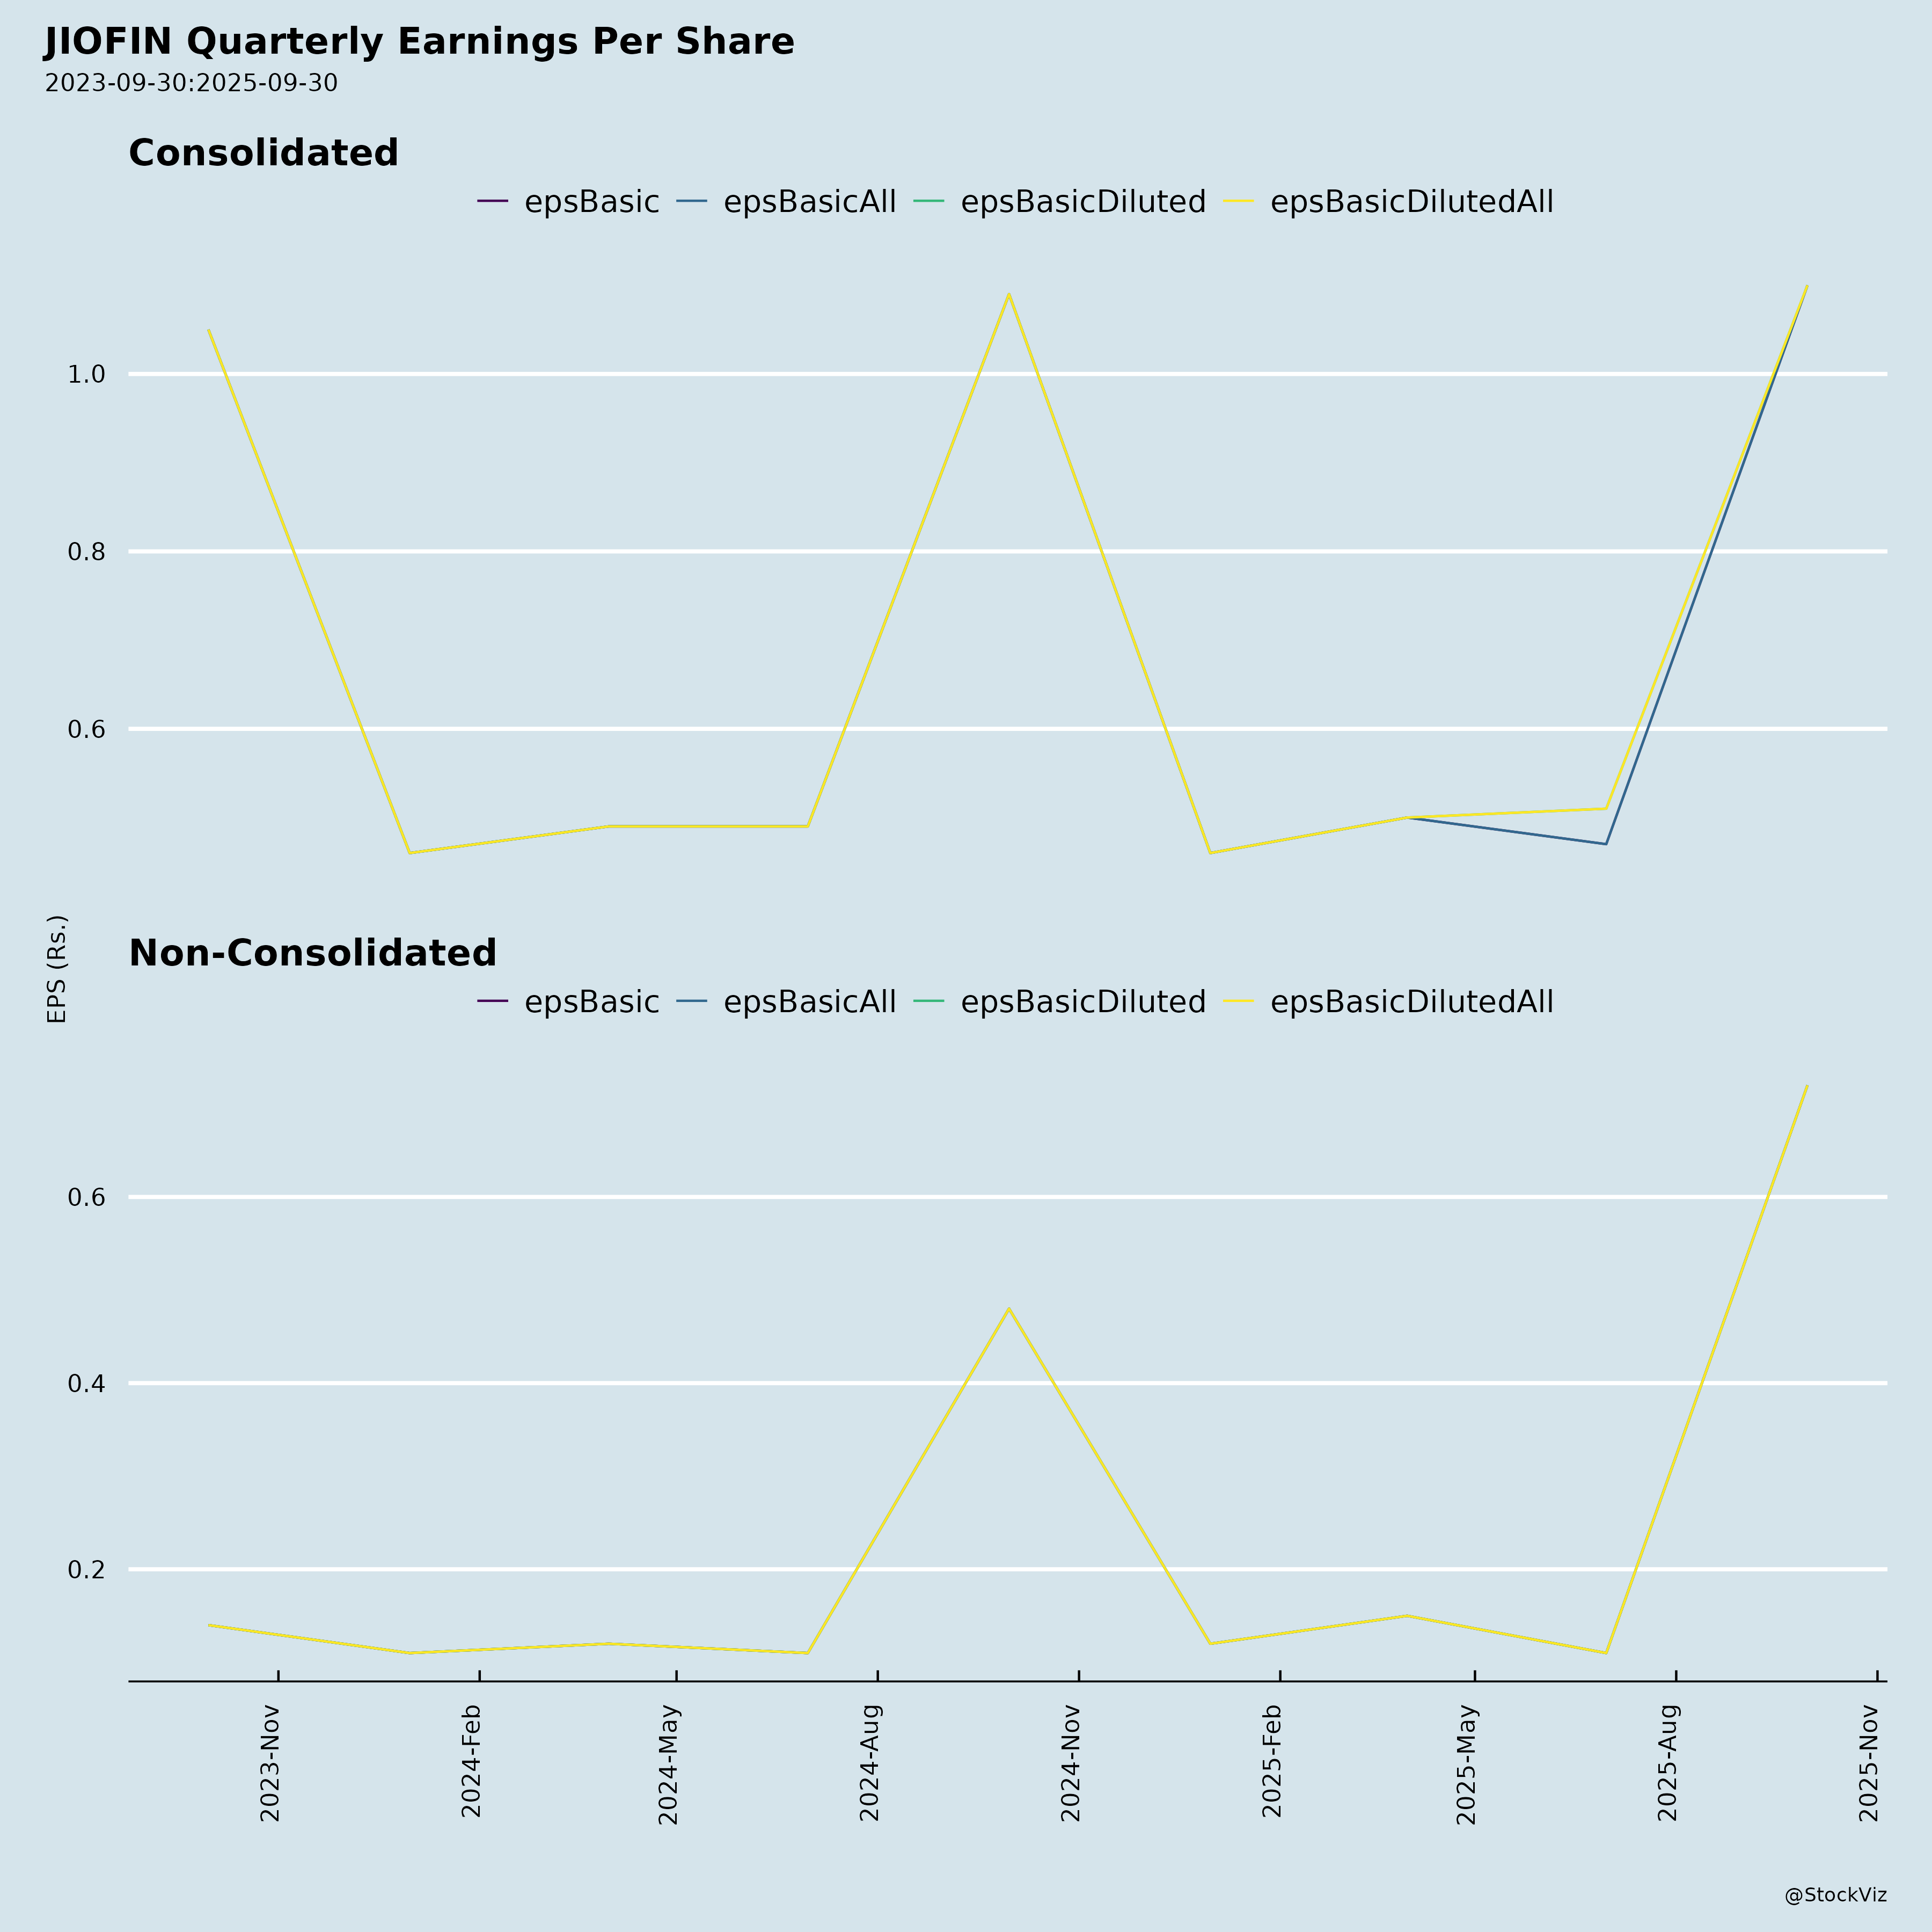
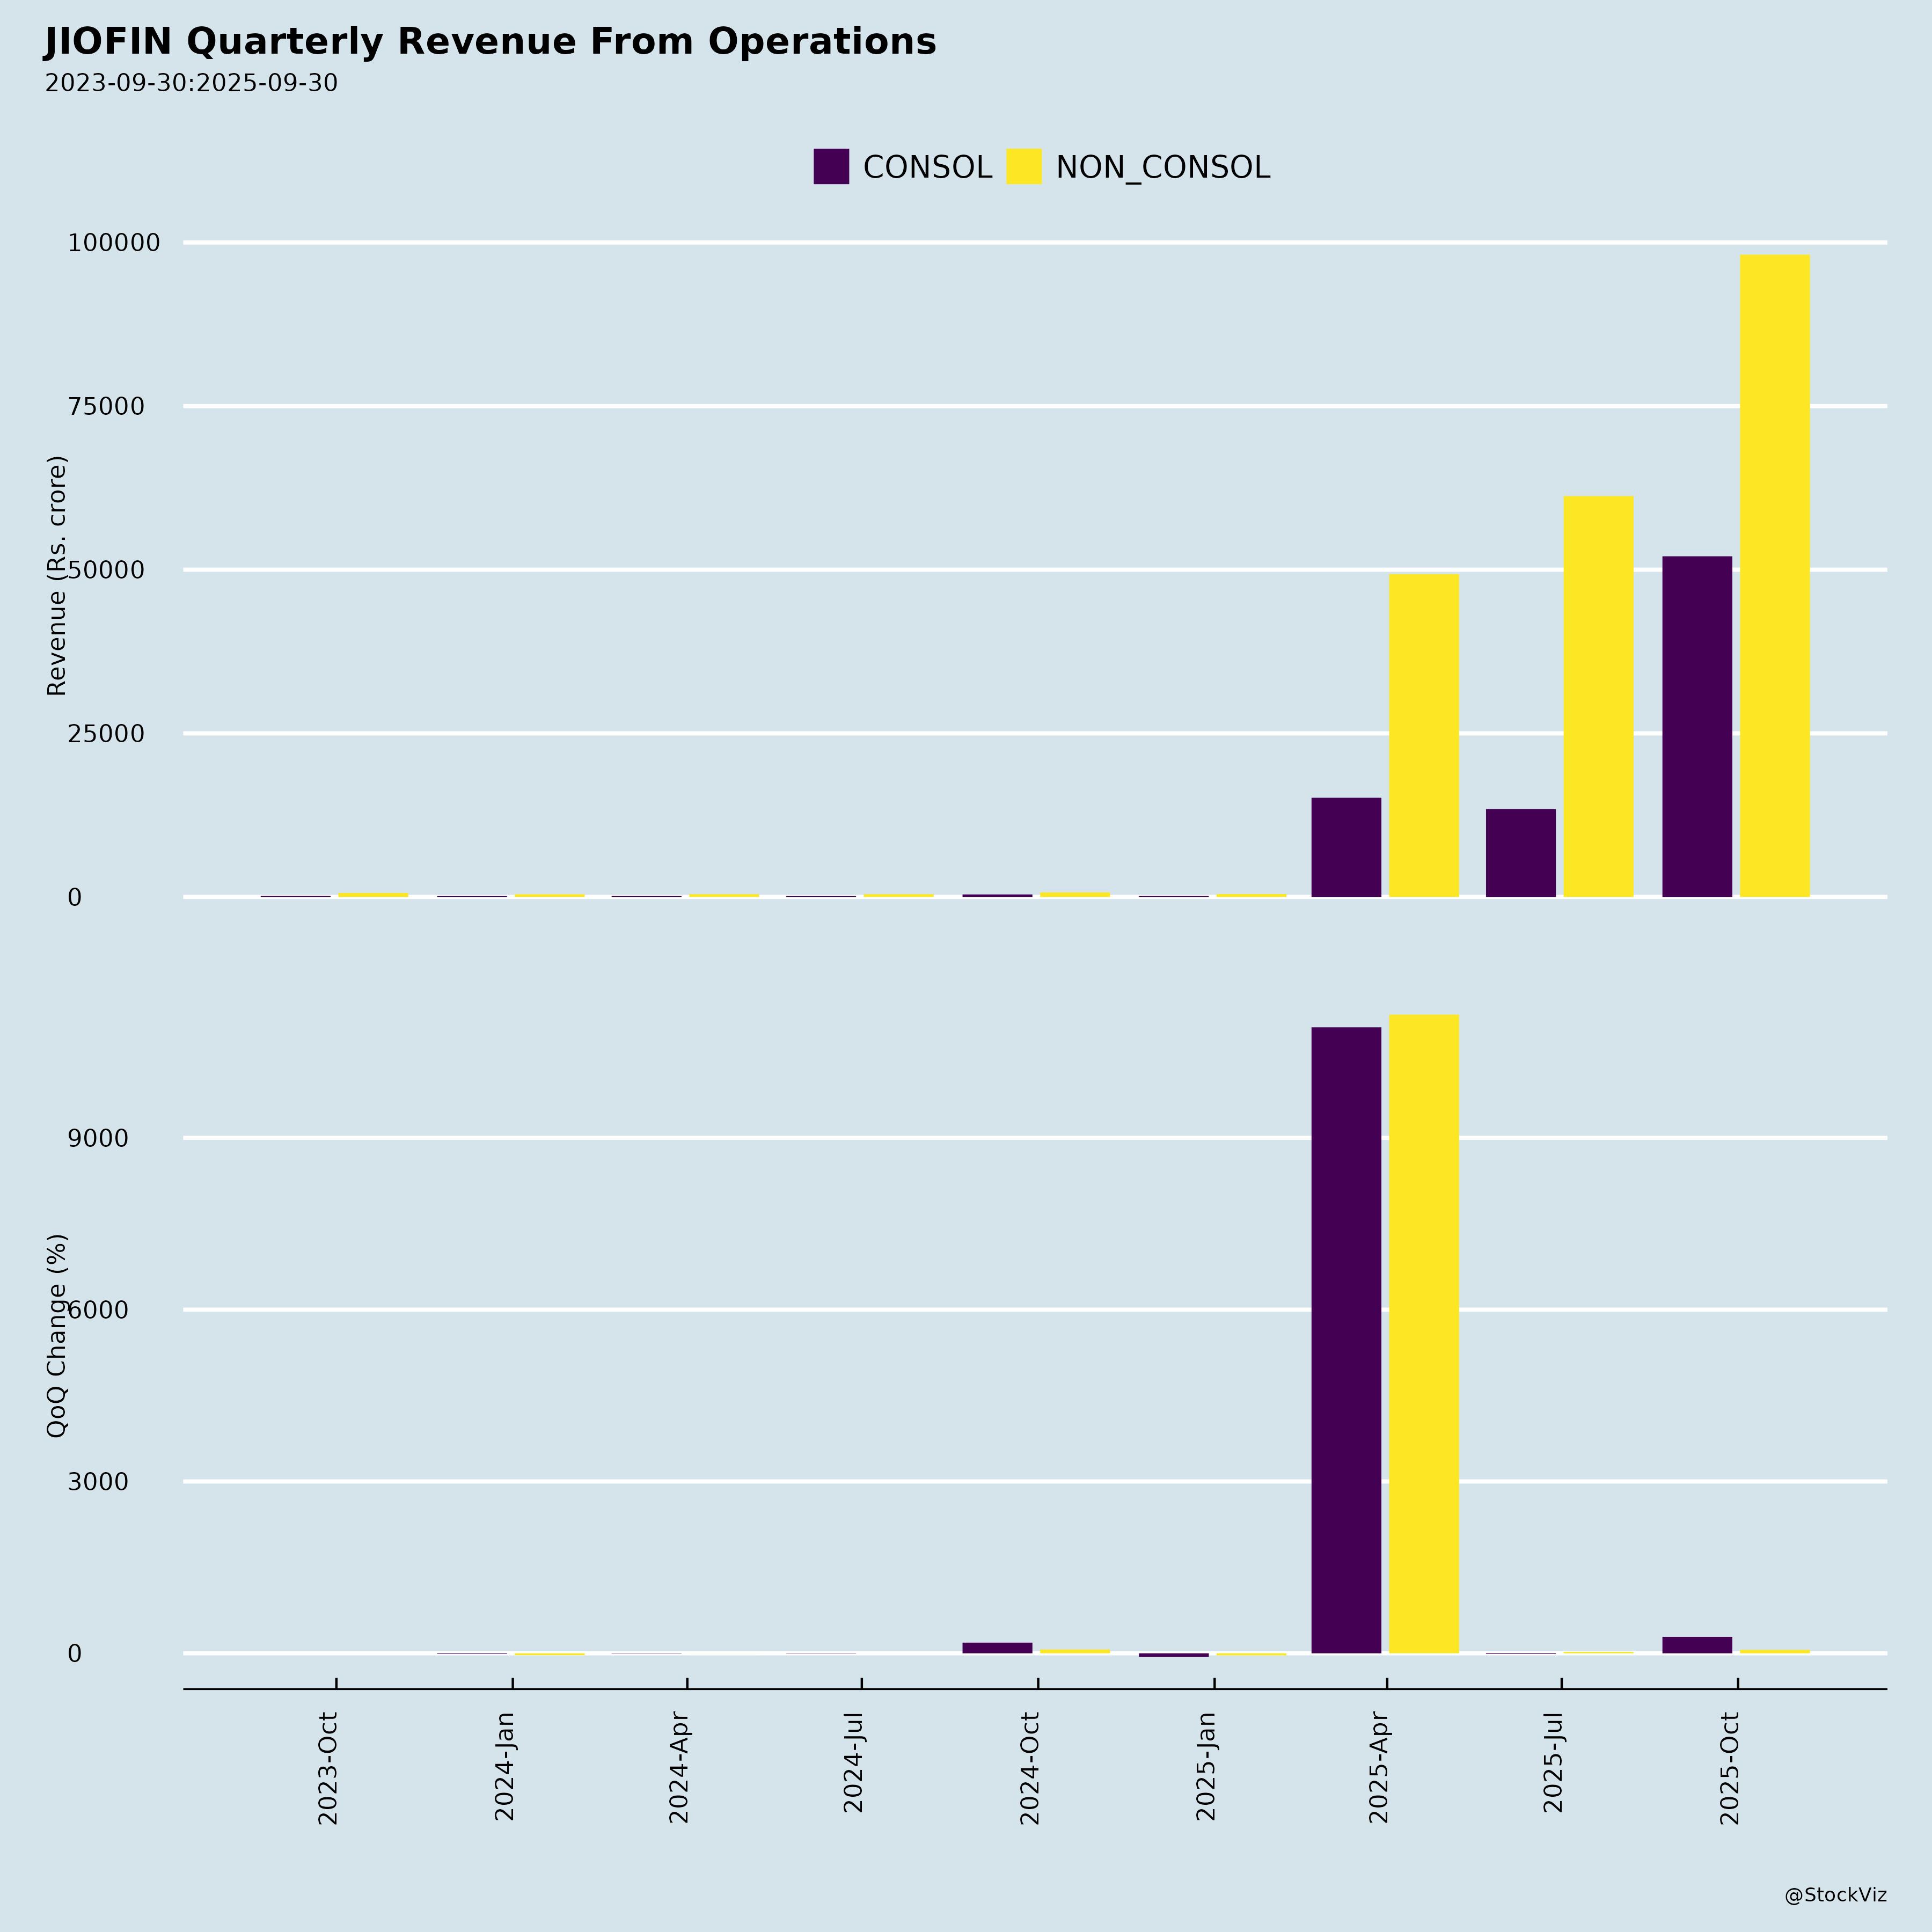
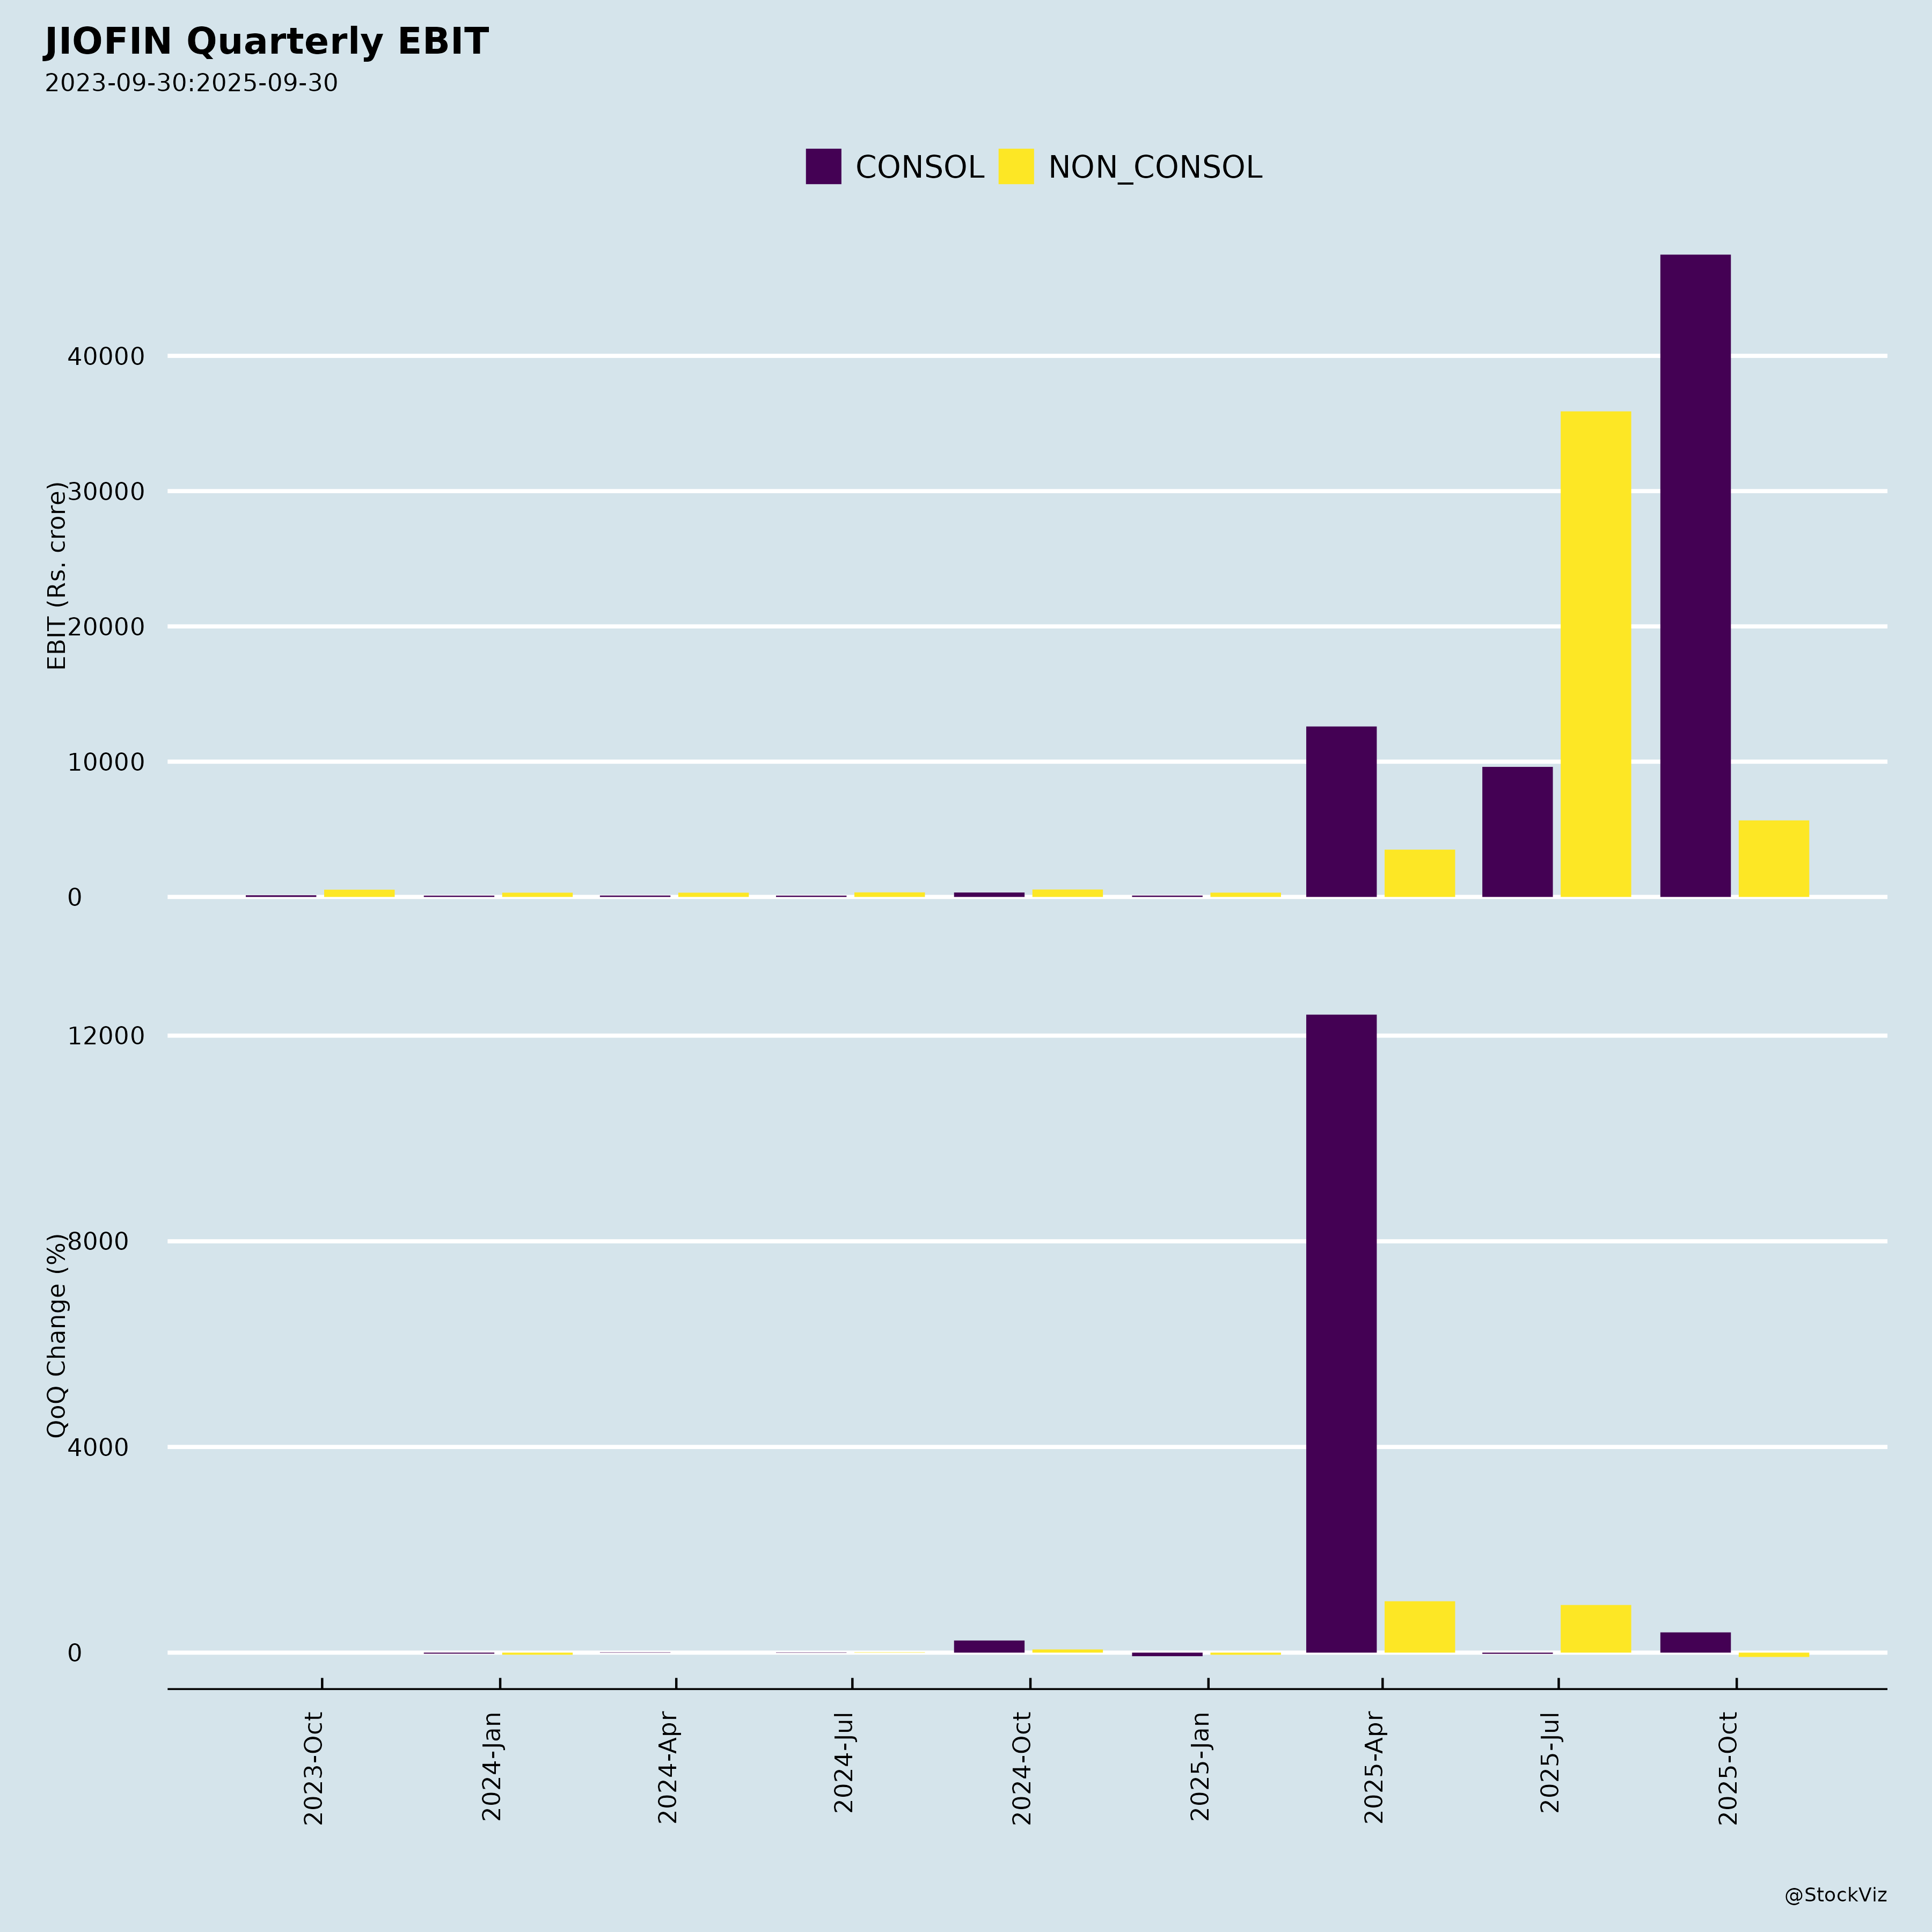
Fundamentals
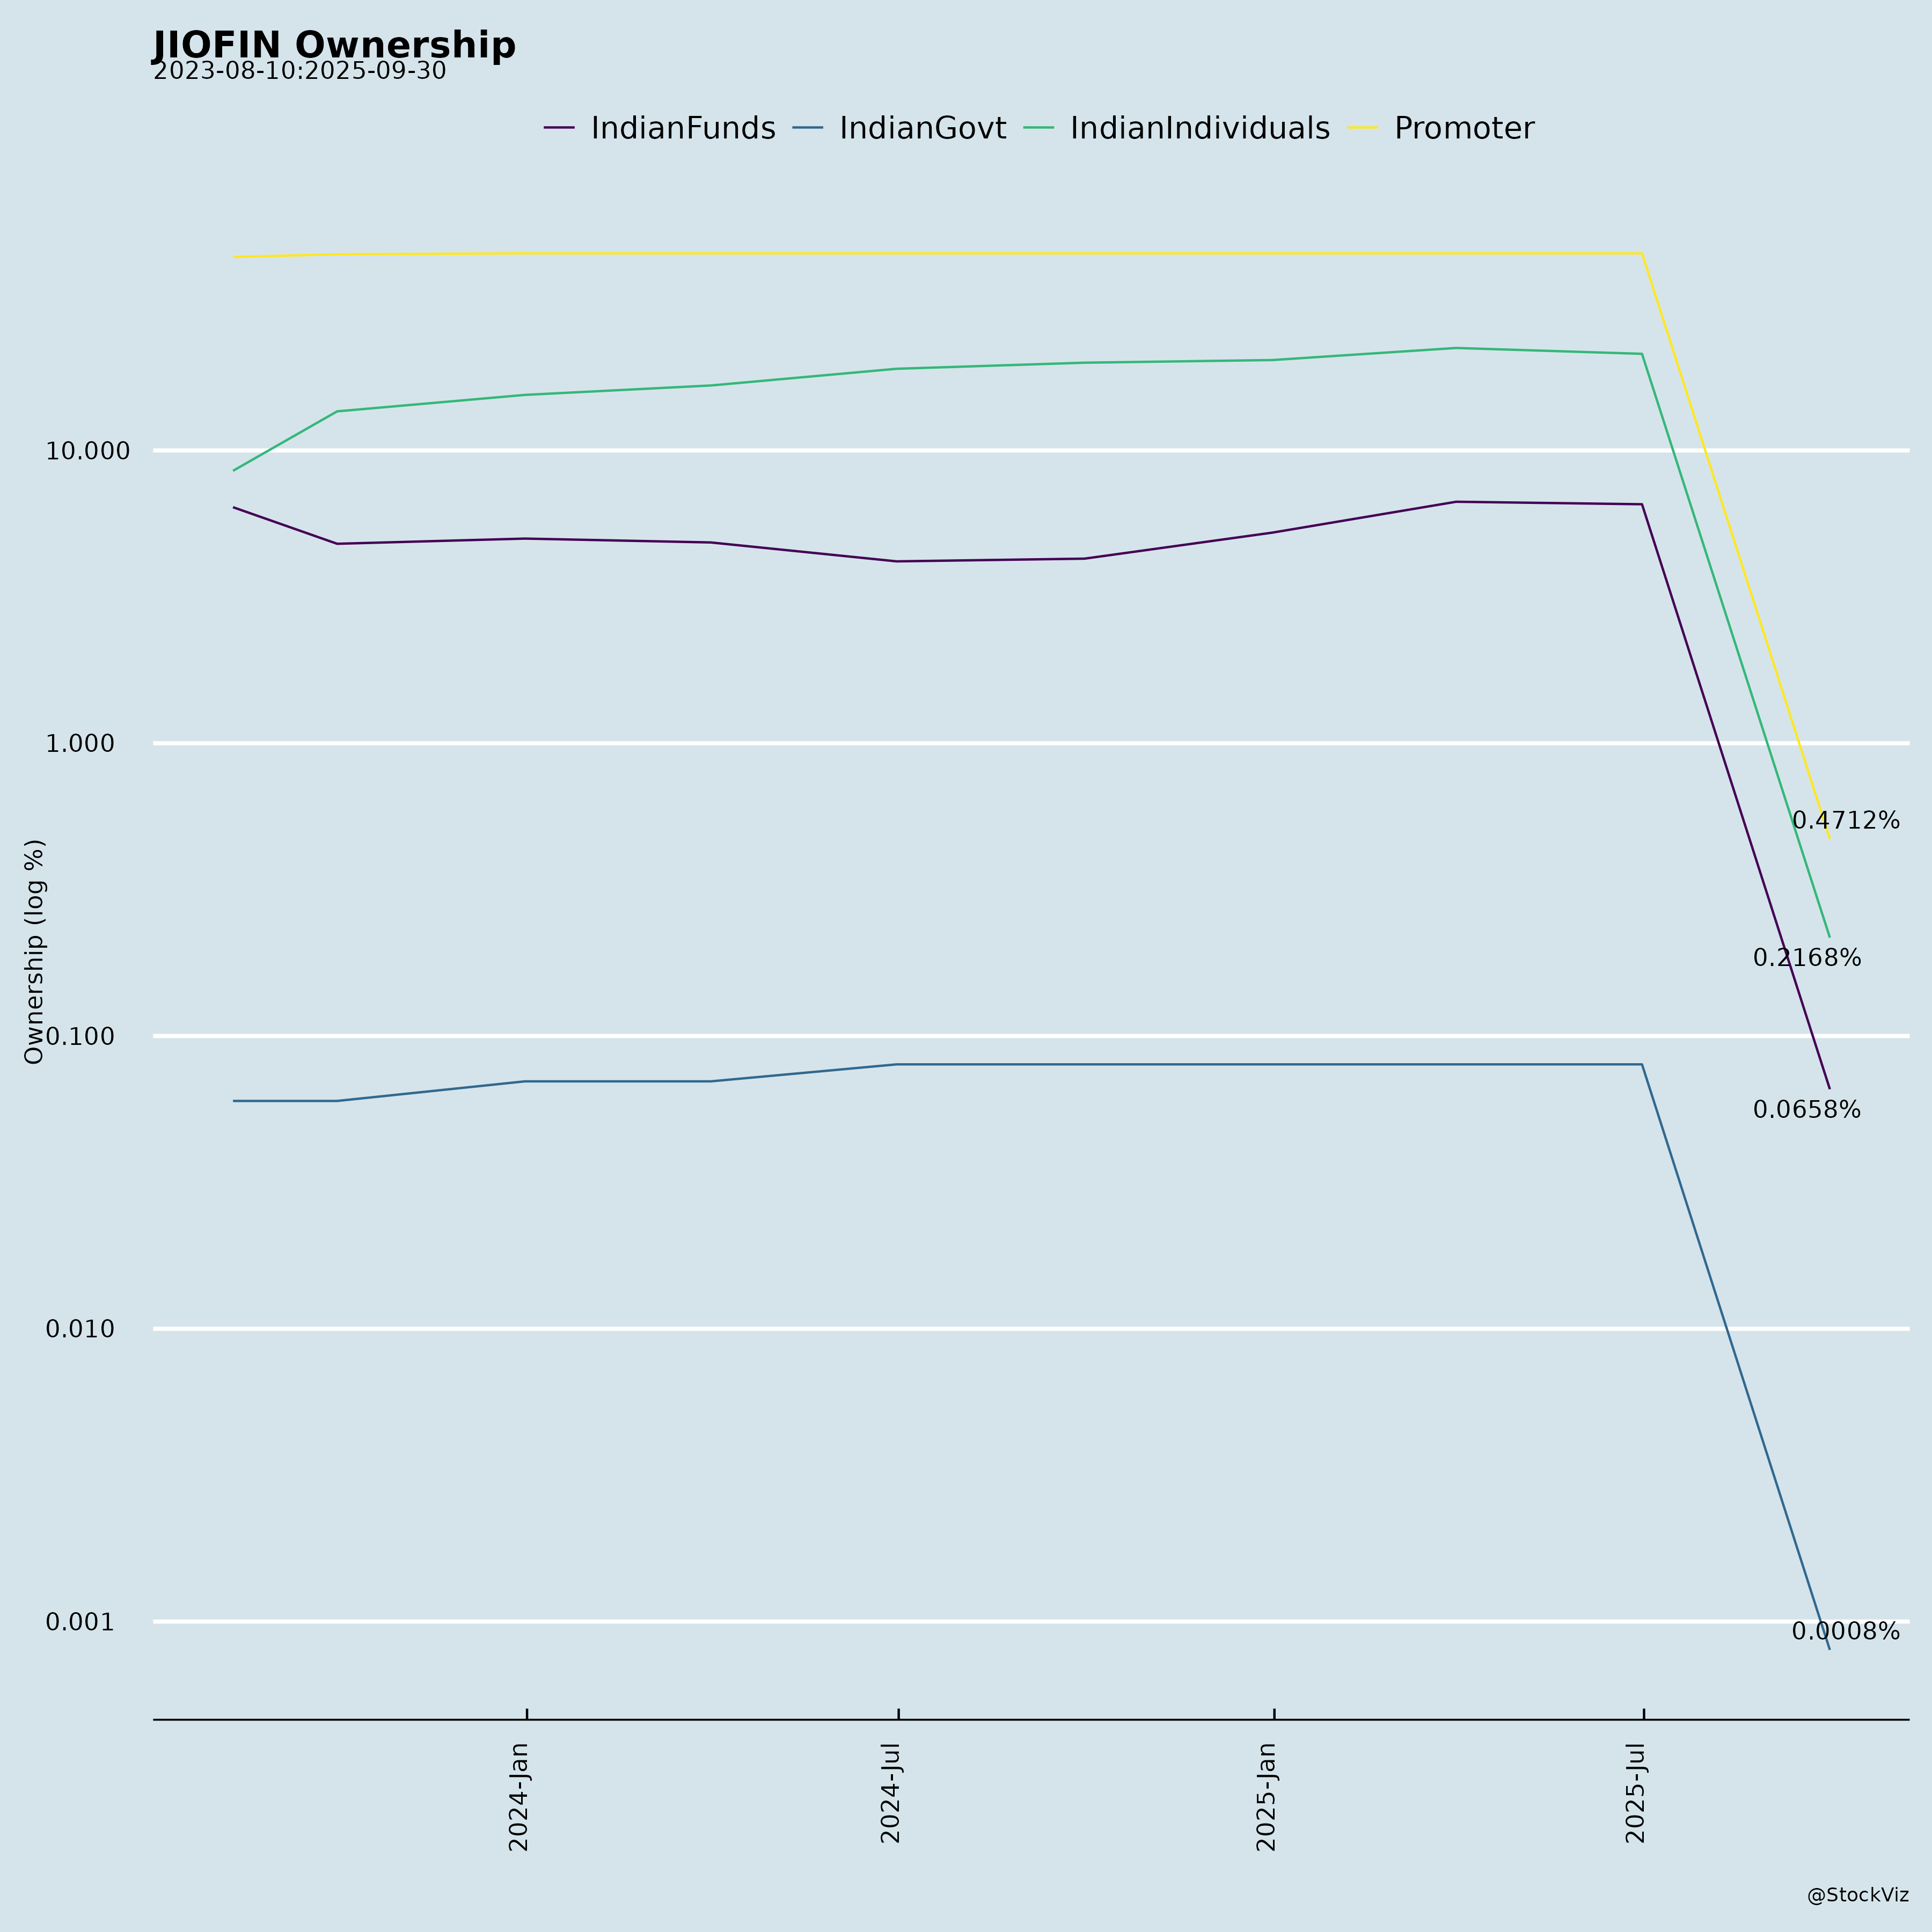
Ownership
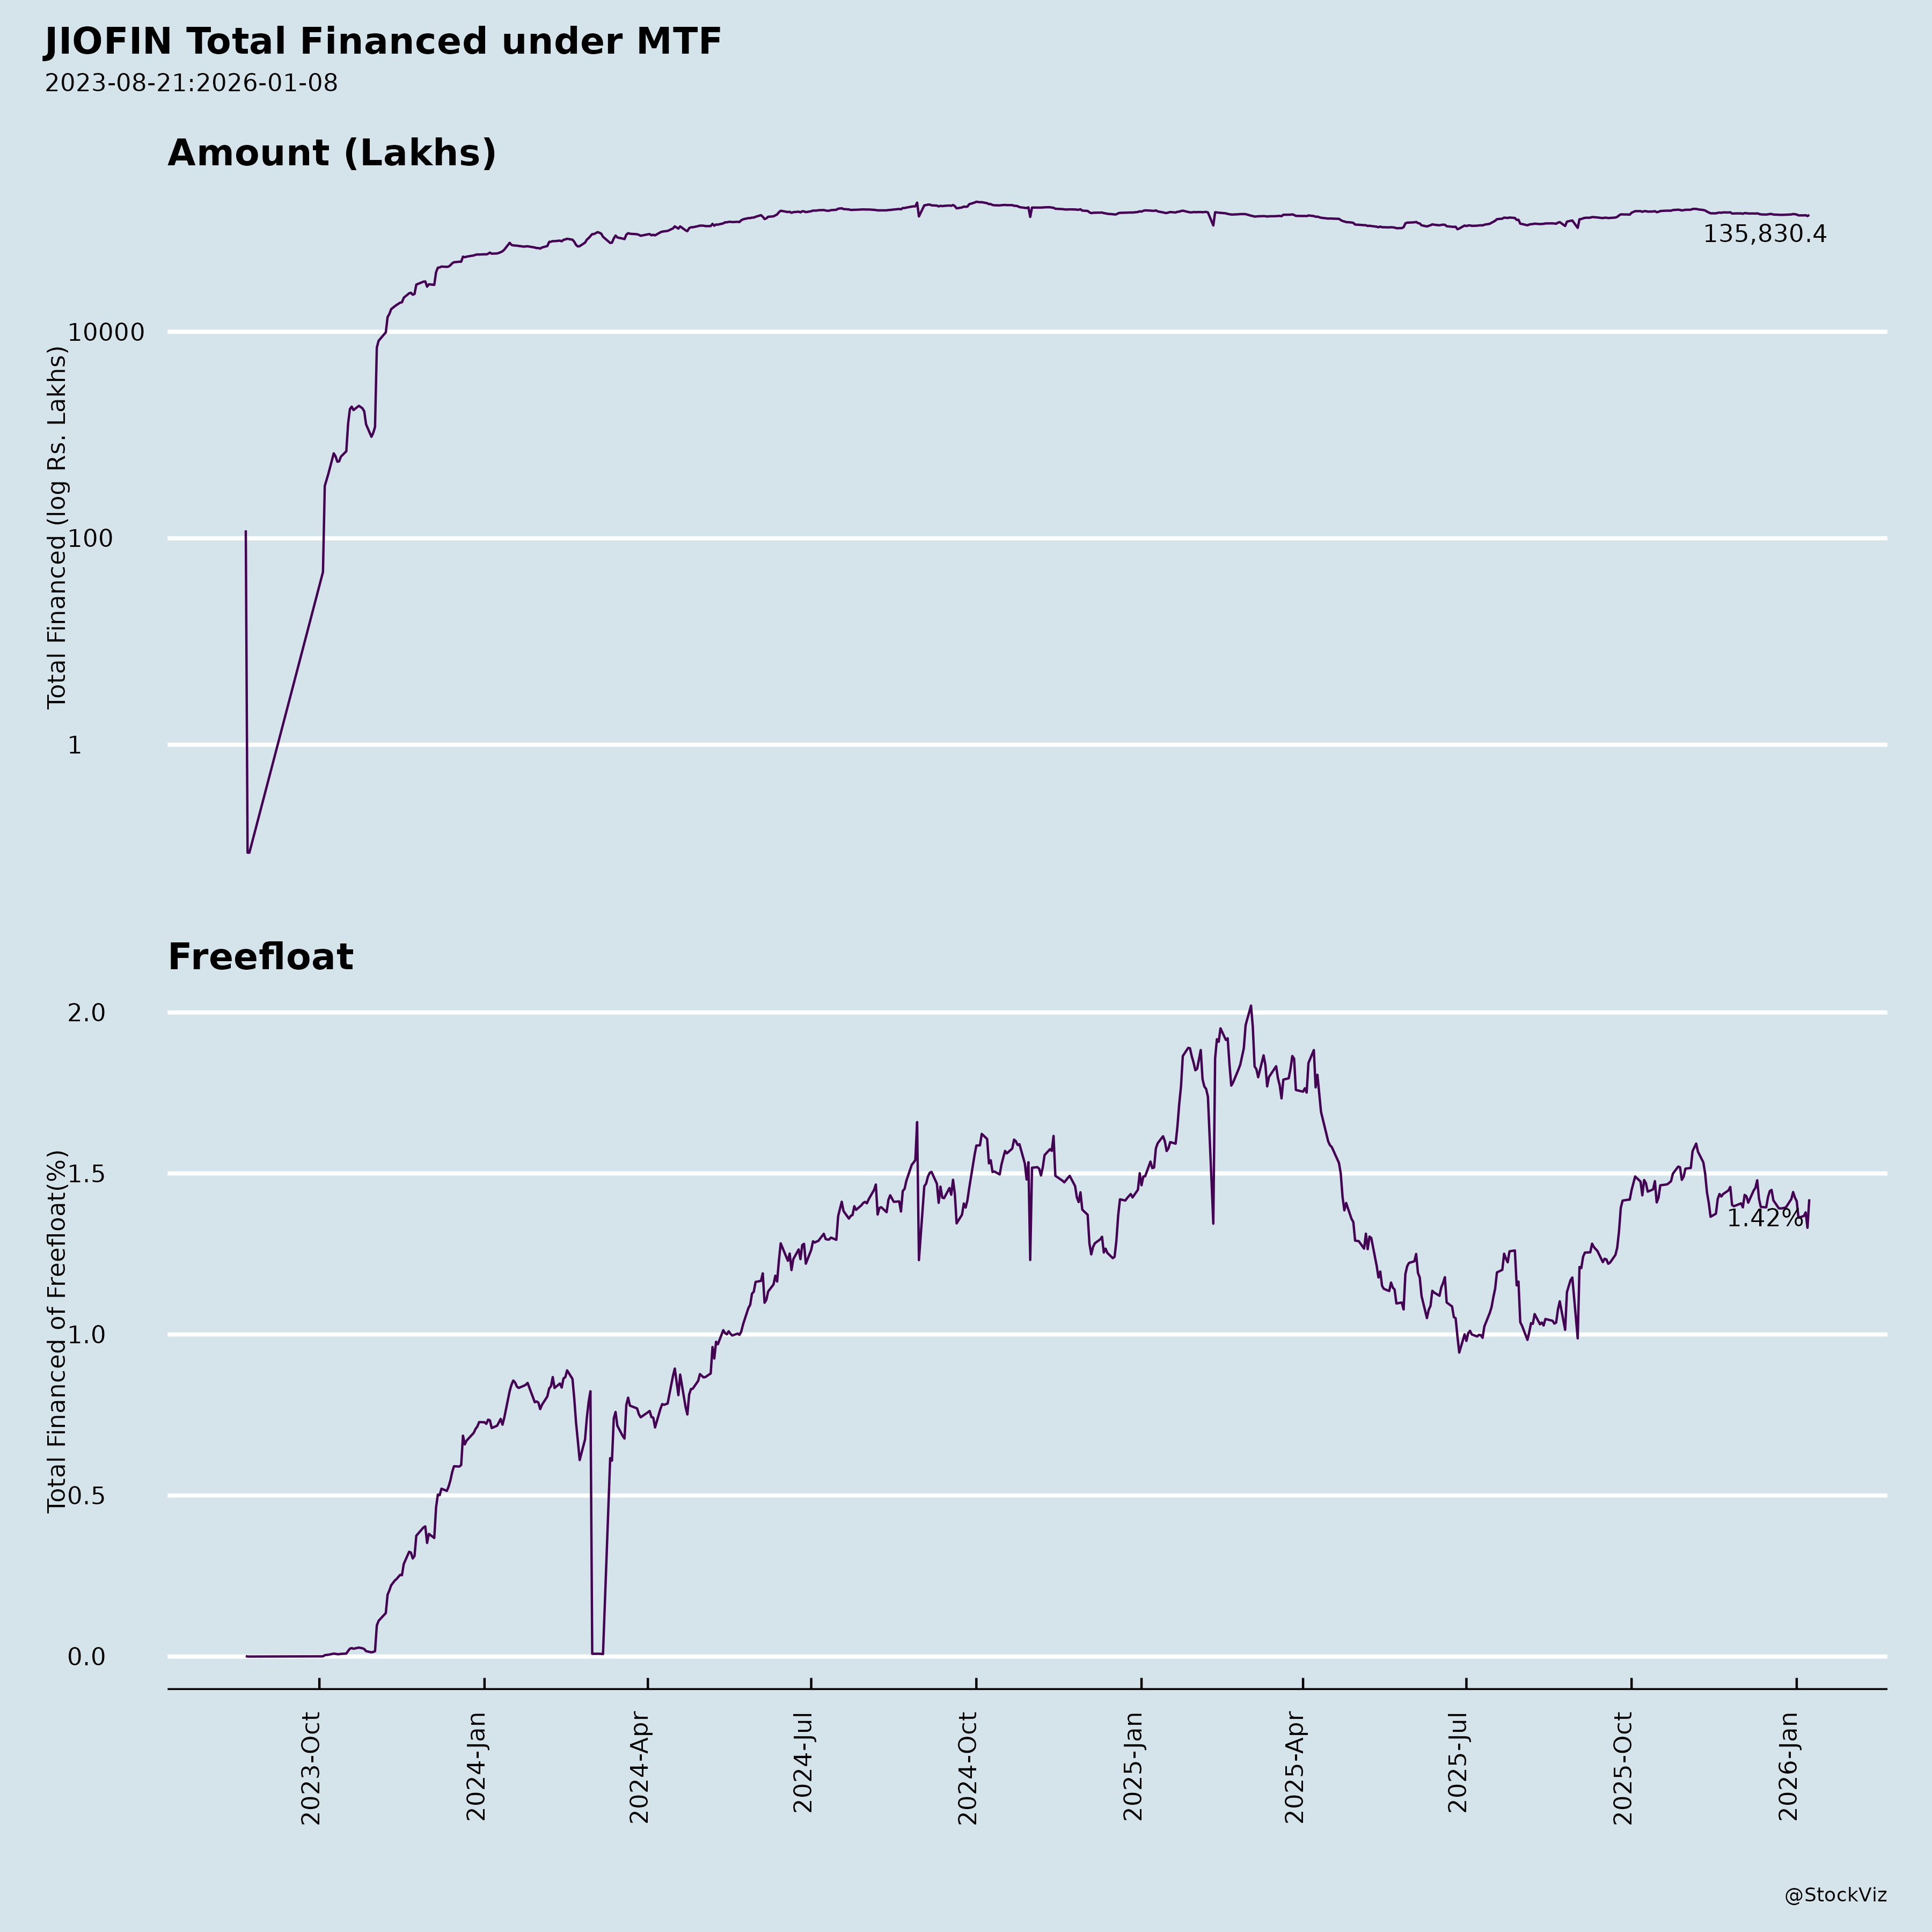
Margined
AI Summary
asof: 2026-09-14
Jio Financial Services (JIOFIN) – Recent Corporate Announcements
1. Headwinds and Challenges
- Regulatory and statutory approval dependency: The Bank of America investment into Jio Credit Limited (JCL) is subject to statutory and regulatory approvals. The transaction is not yet consummated and remains contingent on clearances.
- Loss-making joint ventures and nascent businesses: The consolidated results show a share of loss in associates and joint ventures of ₹(19.05) crore in Q1 FY27, compared with a profit of ₹38.83 crore in Q4 FY26 and ₹31.45 crore in Q1 FY25. The “Others” segment reported a loss after tax of ₹(36.09) crore in Q1 FY27, versus a profit of ₹31.11 crore in Q1 FY25.
- Rising cost base: Total consolidated expenses rose to ₹1,015.81 crore in Q1 FY27 from ₹260.51 crore in Q1 FY25, with finance costs up to ₹418.33 crore from ₹98.80 crore, employee benefits up to ₹151.95 crore from ₹63.68 crore, and other expenses up to ₹411.45 crore from ₹84.93 crore.
- Negative other comprehensive income: Other comprehensive loss for Q1 FY27 was ₹(3,402.80) crore, driven by equity instruments through OCI of ₹(6,771.41) crore, partly offset by tax and share of OCI in associates and joint ventures. Total comprehensive loss for the period was ₹(2,572.55) crore.
- Continued investment drag from scaling businesses: Management noted it “maintained targeted investments to scale growth-stage and incubate nascent businesses,” and the MD & CEO stated the company is “accelerating our investments towards some of our newer businesses including our JVs with BlackRock and Allianz,” which “will yield significant benefits over a period of time.”
- Regulatory clearances pending for new ventures: Jio Allianz General Insurance Limited has been incorporated but statutory and regulatory clearance processes are “currently underway.” The BlackRock broking venture is still at beta-launch stage (scheduled for Q2 FY27).
- Forward-looking statement risk: Both JFSL and BofA caution that actual results could differ materially from projections, and that assumptions underlying forward-looking statements may not be accurate or realised.
2. Tailwinds and Growth Prospects
- Bank of America joint venture: On August 12, 2026, the Board approved execution of a Share Subscription Agreement and Shareholders’ Agreement for an investment of up to ₹18,268.22 crore by NB Holdings Corporation (wholly owned subsidiary of Bank of America Corporation) in Jio Credit Limited. This comprises up to 4,29,29,760 equity shares (26.50% of post-issue paid-up equity) for up to ₹6,612.90 crore, and up to 7,56,64,248 warrants for up to ₹11,655.32 crore, each convertible within 18 months into one equity share. Post-conversion, NB Holdings USA will hold 49.90% of JCL. The venture combines JFSL’s digital reach and Indian market knowledge with BofA’s global financial services expertise, governance, risk management, and technology.
- NBFC scale-up: JCL’s gross AUM reached ₹30,667 crore as of June 30, 2026, a 2.6x YoY growth, with quarterly gross disbursements of ₹11,252 crore (up 2.7x YoY). JCL’s PAT rose 113% YoY to ₹96 crore and NII rose 118% YoY to ₹257 crore. JCL has expanded to 25 offices across 18 cities.
- Payments turnaround: Jio Payments Bank and Jio Payment Solutions achieved operational turnaround in Q1 FY27. JPBL total income grew 7.7x YoY to ₹83 crore; deposits rose 72% YoY to ₹617 crore; BC network expanded to 527,037 touchpoints from 50,192 in Q1 FY26. JPSL TPV reached ₹19,208 crore (up 2.5x YoY), with net processing margin of 12 bps and cross-border collection services launched.
- Asset management momentum: BlackRock JV closing AUM reached ₹18,412 crore, up 21% QoQ; Liquid Funds AUM crossed ₹10,000 crore in April 2026; Prism SIF Hybrid Long-Short NFO raised over ₹150 crore; IFSCA final approval received to set up retail Fund Management Entity in GIFT City.
- Insurance and reinsurance: Allianz Jio Reinsurance underwrote ₹266 crore gross written premium in its first full quarter. Jio Insurance Broking facilitated premium of ₹238 crore (up 1.6x YoY) with fee and commission income up 131% YoY to ₹61 crore.
- Digital engagement: JioFinance app has 25 million+ unique users, ~9 million average MAU in Q1 FY27, ~34,000 product purchases per day in June 2026, and 204 million+ JioPoints issued to 5.7 million enrolled customers.
- Capital strength: Total consolidated shareholders’ equity stood at ₹1.37 lakh crore as of June 30, 2026. The company received the second tranche of ₹5,934 crore from the Promoter Group, taking cumulative capital infusion to ₹9,890 crore. JCL’s capital adequacy ratio was 22.35% with an average cost of borrowing of 7.07%.
- Macro opportunity: The media release cites India as the world’s fastest growing major economy at double the global growth rate, with an expanding financial sector.
3. Key Risks
- Execution and integration risk: The BofA joint venture requires equal board representation and continued consolidation of JCL as a subsidiary in JFSL’s financial reporting; the existing management team continues to drive strategy and operations.
- Warrant conversion uncertainty: The BofA warrants are convertible within 18 months from allotment, with 25% payable at subscription and the balance at conversion. Full subscription is not guaranteed, and the eventual 49.90% stake depends on exercise.
- Regulatory risk: The transaction and the new insurance ventures remain subject to statutory and regulatory approvals. JAGIL’s clearances are still in process.
- Market and credit risk: JCL’s lending book spans mortgages, loans against securities, and corporate/SME loans; the presentation notes “stringent credit guardrails” and “advanced risk frameworks,” but credit and market risks remain inherent.
- OCI volatility: Large swings in equity instruments through OCI (₹(6,771.41) crore in Q1 FY27 versus ₹11,212.21 crore in Q1 FY25) introduce significant volatility to total comprehensive income.
- Dependence on JV performance: Share of associates and JVs swung to a loss of ₹(19.05) crore in Q1 FY27, and the “Others” segment posted a loss, indicating that newer businesses are not yet consistently profitable.
- Forward-looking statement risk: Both companies disclaim guarantees that assumptions will be accurate or realised, and note actual results could differ materially.
4. Management Guidance Versus Observed Business Performance
- Guidance on growth investments: Management stated it “maintained targeted investments to scale growth-stage and incubate nascent businesses” and is “accelerating our investments towards some of our newer businesses including our JVs with BlackRock and Allianz… which will yield significant benefits over a period of time.” Observed performance: the “Others” segment posted a loss after tax of ₹(36.09) crore in Q1 FY27, and share of associates/JVs was a loss of ₹(19.05) crore, consistent with investment-phase drag.
- Guidance on operational turnaround: The presentation and media release state JPBL and JPSL “achieved operational turnaround in Q1 FY27.” Observed performance: JPBL total income grew 7.7x YoY to ₹83 crore; JPSL net fee and commission income rose 3.4x YoY to ₹24 crore with 12 bps net processing margin, supporting the turnaround claim.
- Guidance on lending growth: JCL is described as having “ambitions to responsibly continue its growth trajectory by providing borrowing opportunities across existing and new products within India.” Observed performance: AUM grew 2.6x YoY to ₹30,667 crore, disbursements rose 2.7x YoY to ₹11,252 crore, and PAT rose 113% YoY to ₹96 crore.
- Guidance on broking: The BlackRock JV “proposes to offer broking services” with a “Beta-launch scheduled for Q2 FY27.” No observed launch has yet occurred in the supplied material.
- Guidance on insurance: JAGIL was incorporated and “necessary applications have been made”; regulatory approvals remain “in process.” No premium or operational figures for JAGIL are reported.
- Guidance on capital deployment: The BofA investment is intended to provide “further capital to support its growth in India” and “long-term capital for sustainable loan growth.” Observed performance: JCL’s capital adequacy ratio stood at 22.35%, and the transaction had not yet closed as of the announcement date.
- Guidance on digital engagement: The JioFinance app is positioned as an “AI-native and conversational Neural Agentic Marketplace.” Observed performance: 25 million+ unique users, ~9 million average MAU, and ~34,000 daily product purchases in June 2026.
- AGM outcome: The Third Annual General Meeting held on August 26, 2026 passed all seven resolutions, including adoption of financial statements, declaration of a dividend, re-appointment of Shri Hitesh Kumar Sethia as MD and CEO, appointment of joint statutory auditors, and approval of material related party transactions.
- Investor engagement: Company executives will participate in the Ashwamedh – Elara India Dialogue 2026 on September 01, 2026, in Mumbai, with no unpublished price sensitive information proposed to be shared.
Broker Narrative
Initially, the broker’s report was a sector-wide telecom review covering Bharti, RJio, VIL, and Tata Communications, with concerns over currency devaluation, ARPU caps, subscriber losses, and opex inflation, while highlighting ARPU growth and subscriber acceleration as drivers. By the final report, the narrative had pivoted entirely to JIOFIN’s own fintech operations, focusing on lending AUM growth, payments profitability, AMC traction, and AI, with new concerns about opex overruns and credit costs. The only persistent theme was cost pressure, though it evolved from network opex in telecom to aggressive business incubation costs at JIOFIN.
Broker Timeline
16 broker calls · 2023-11-06 to 2026-07-17
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.