ITC
Equity Metrics
October 23, 2026
ITC Limited
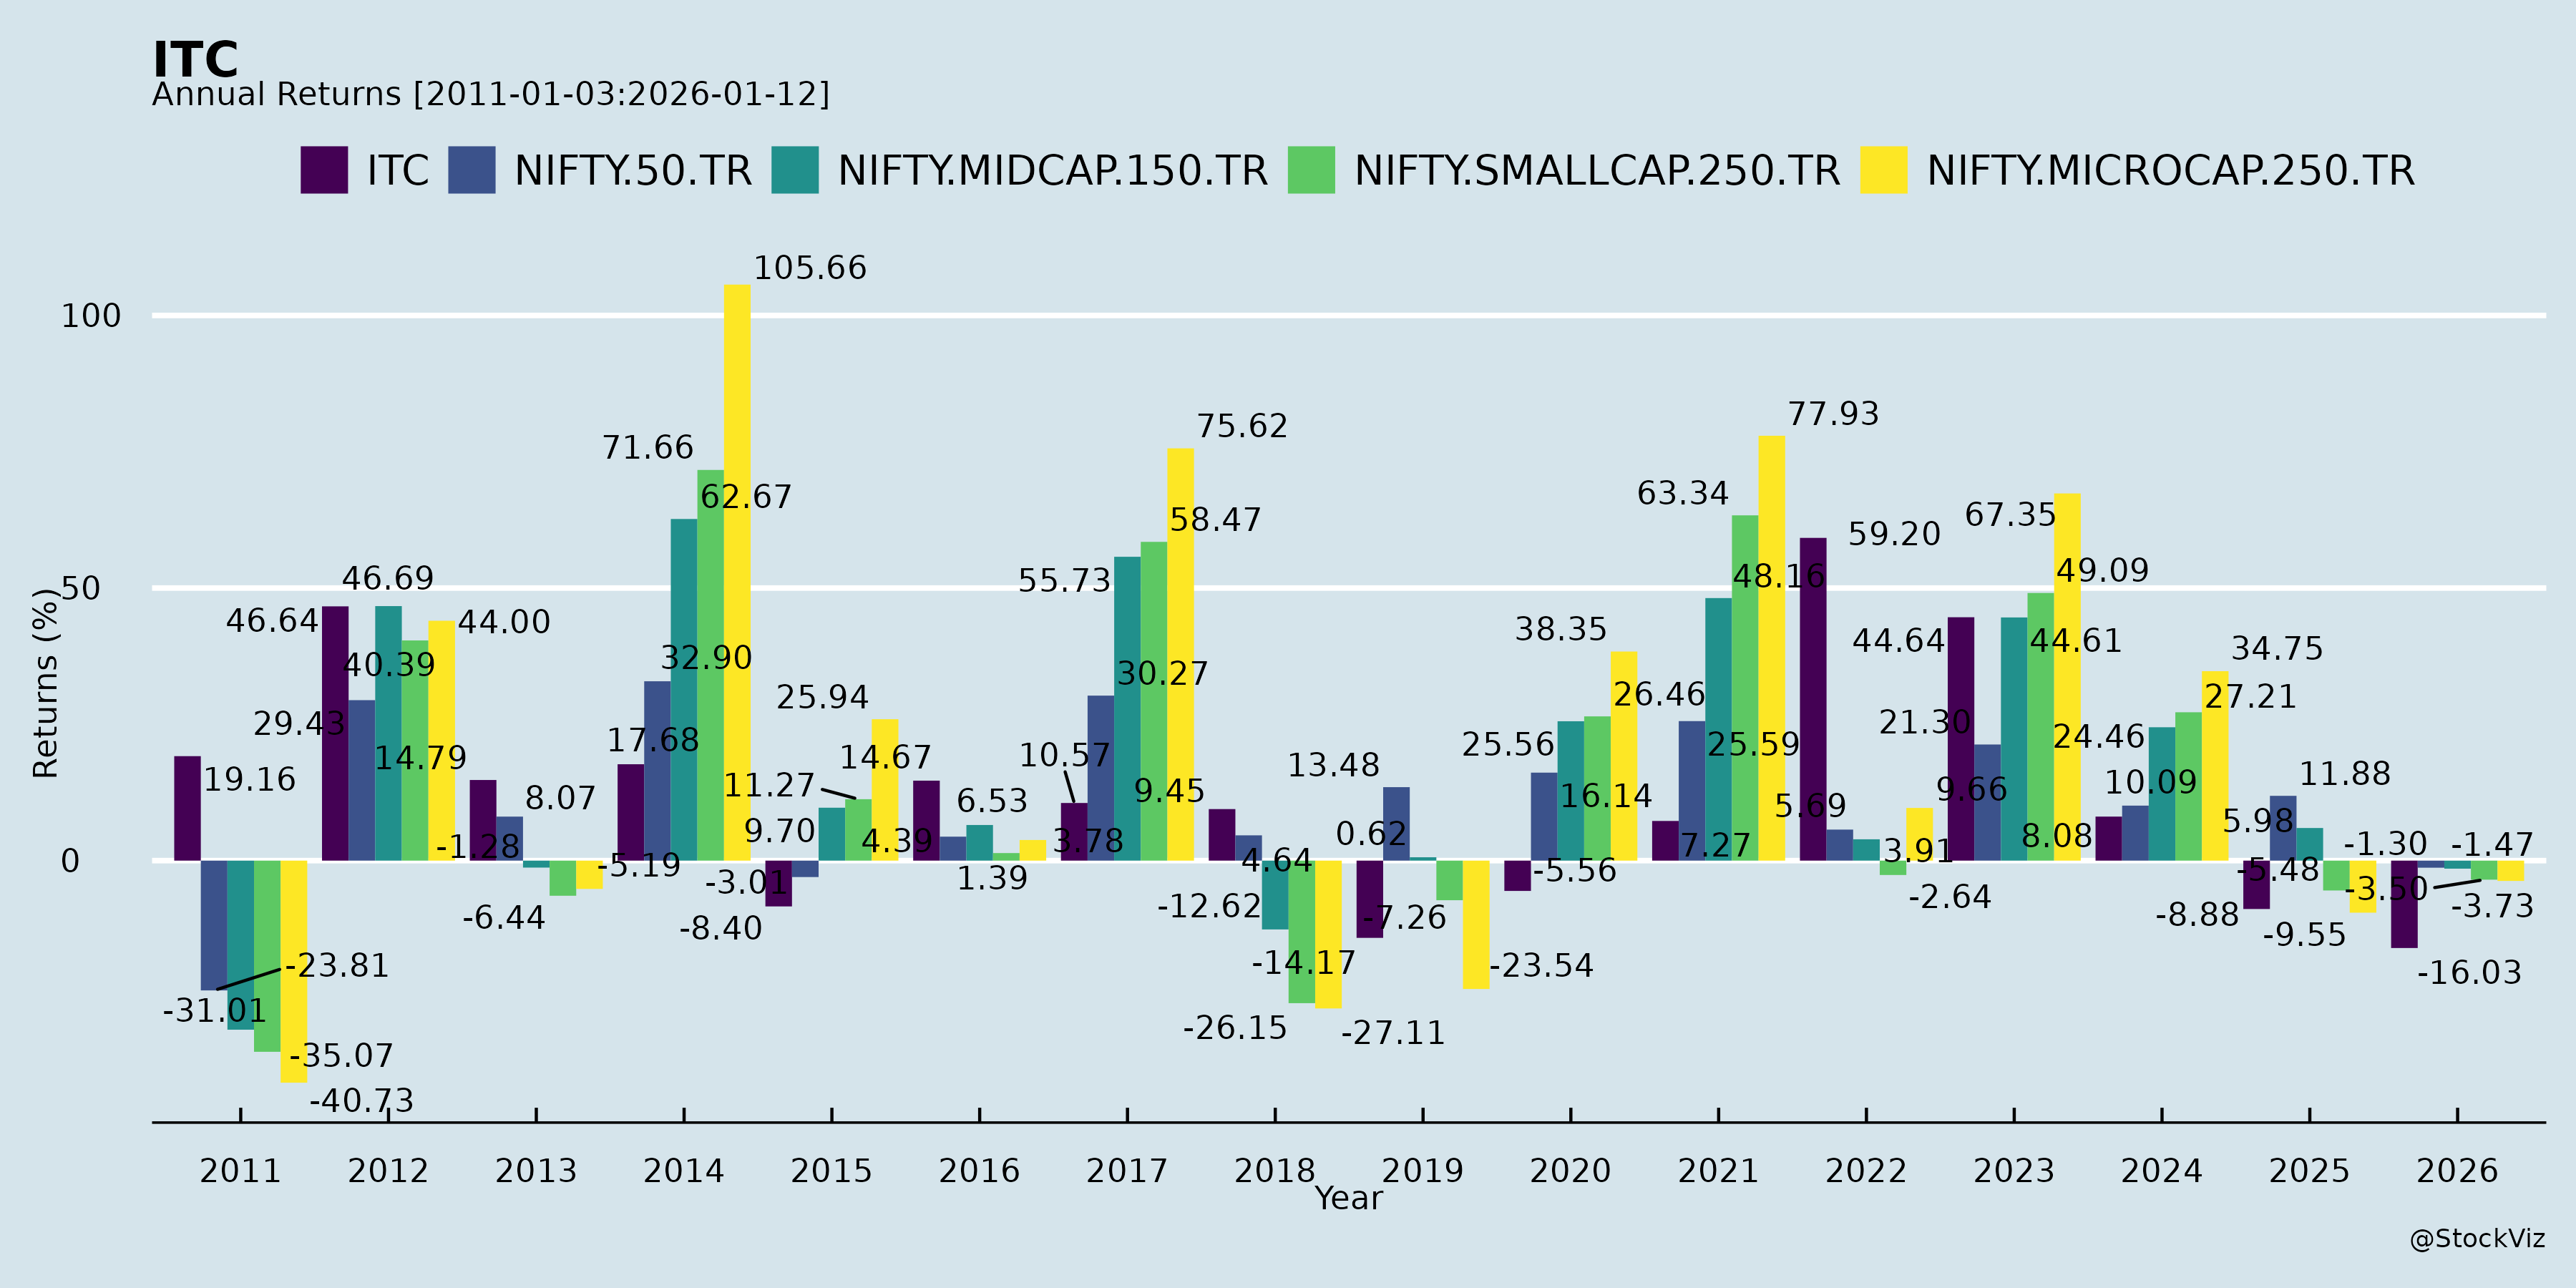
Annual Returns
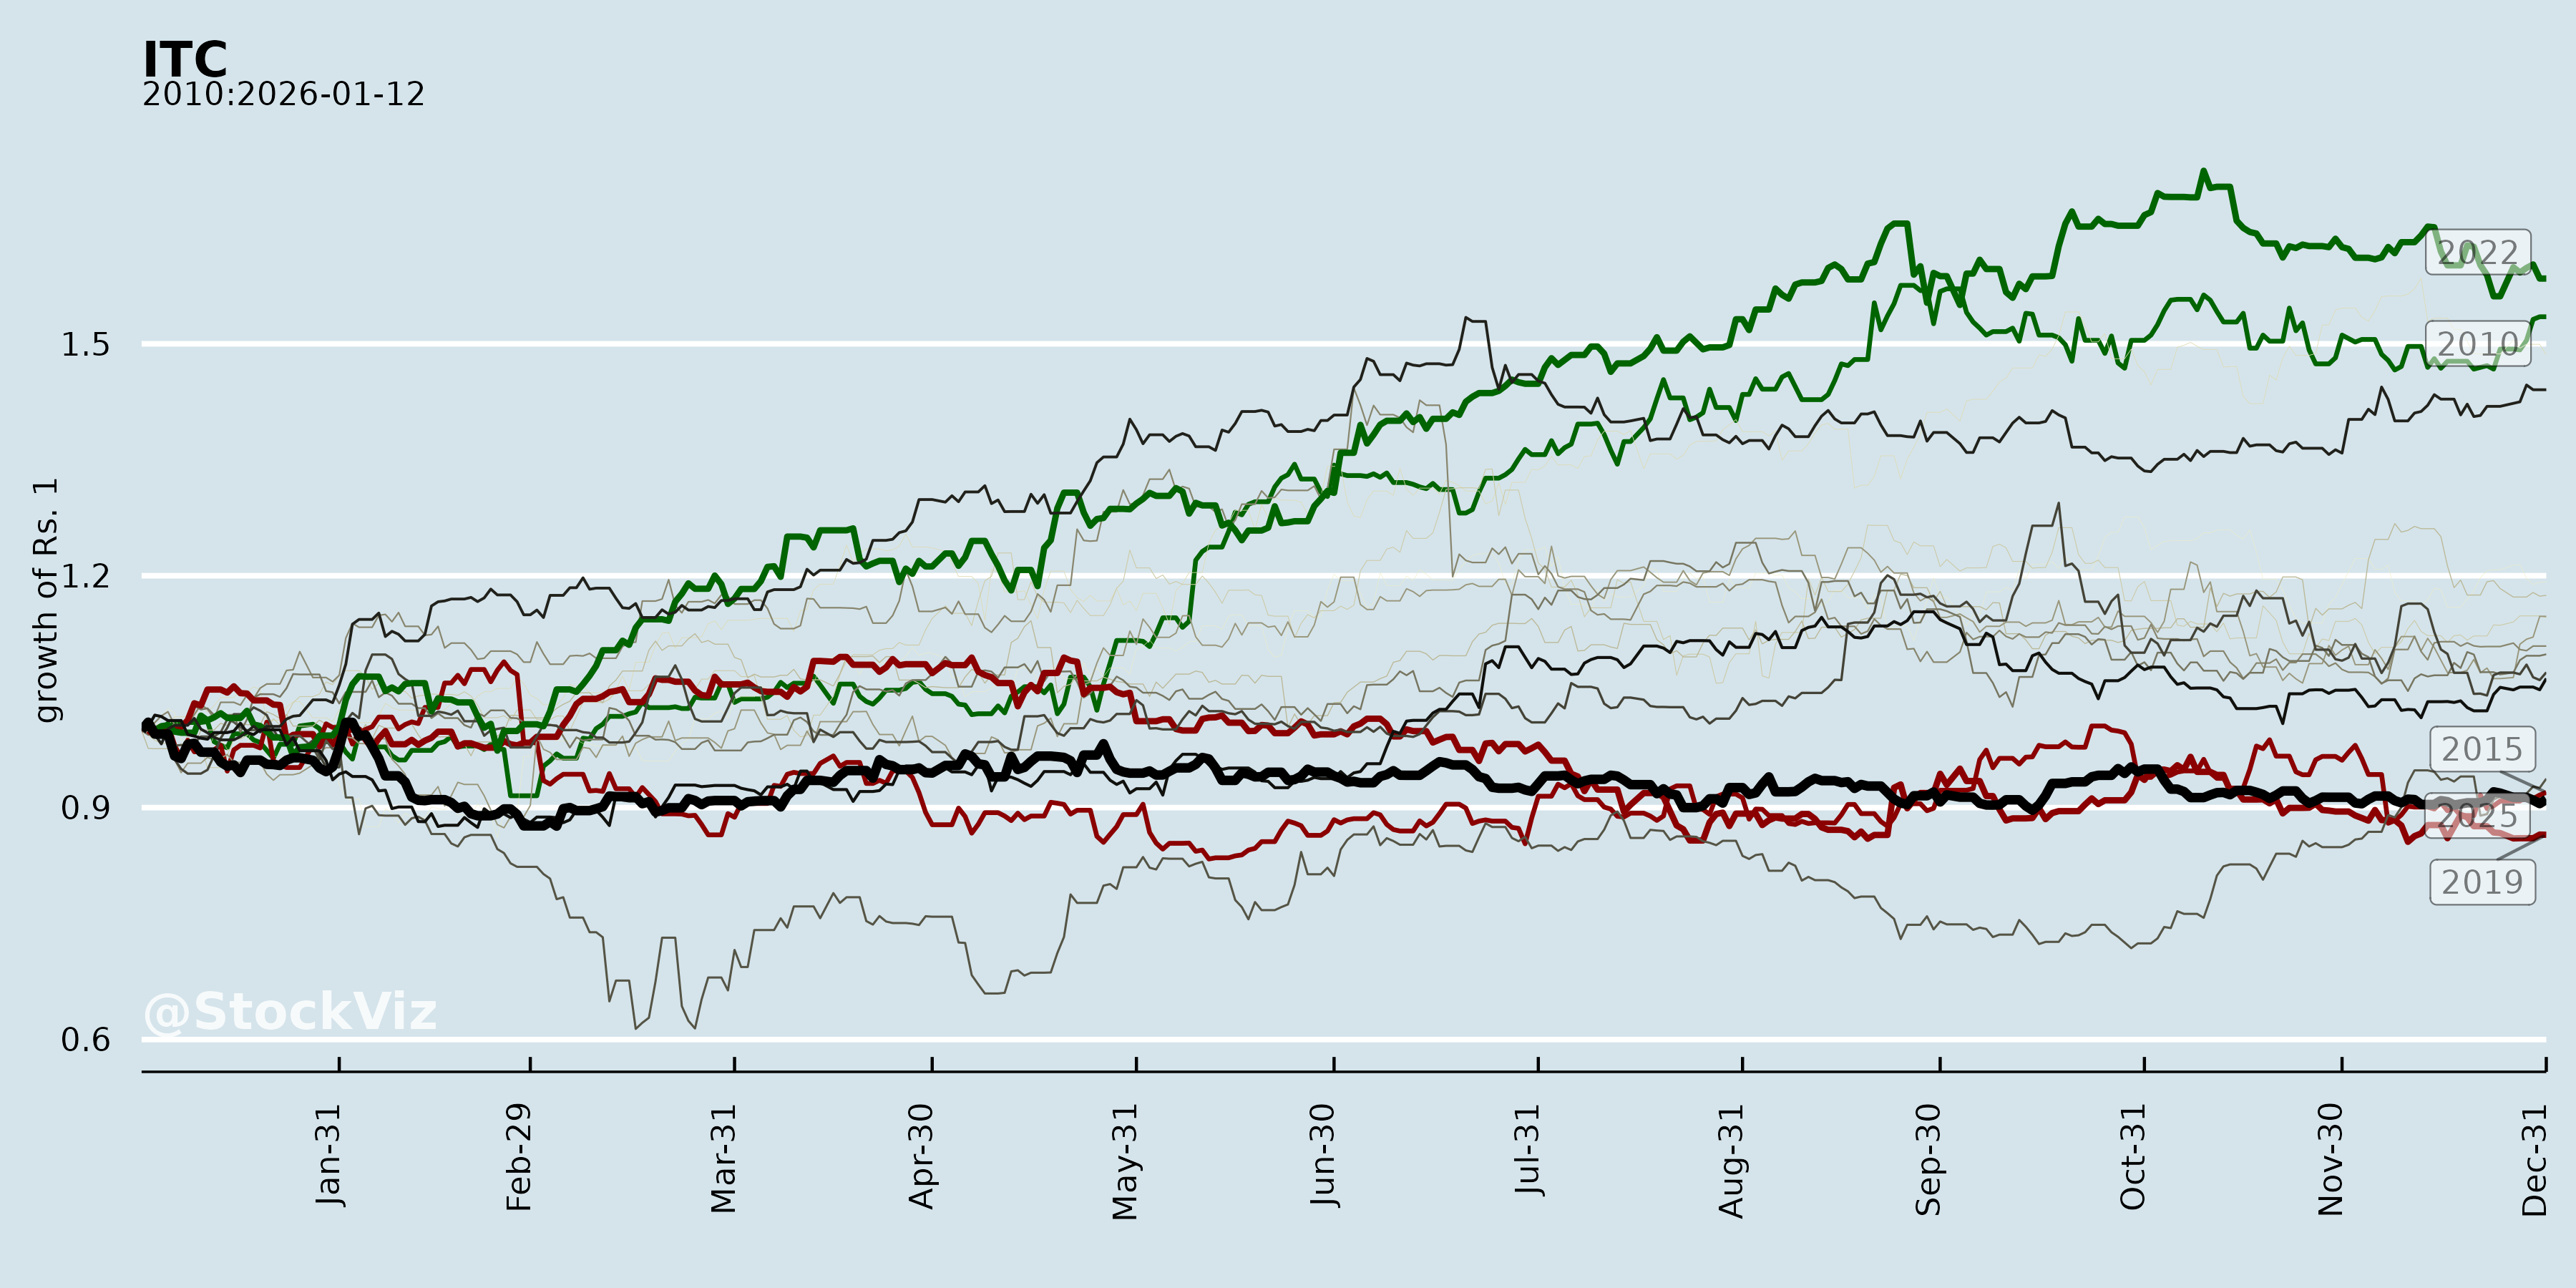
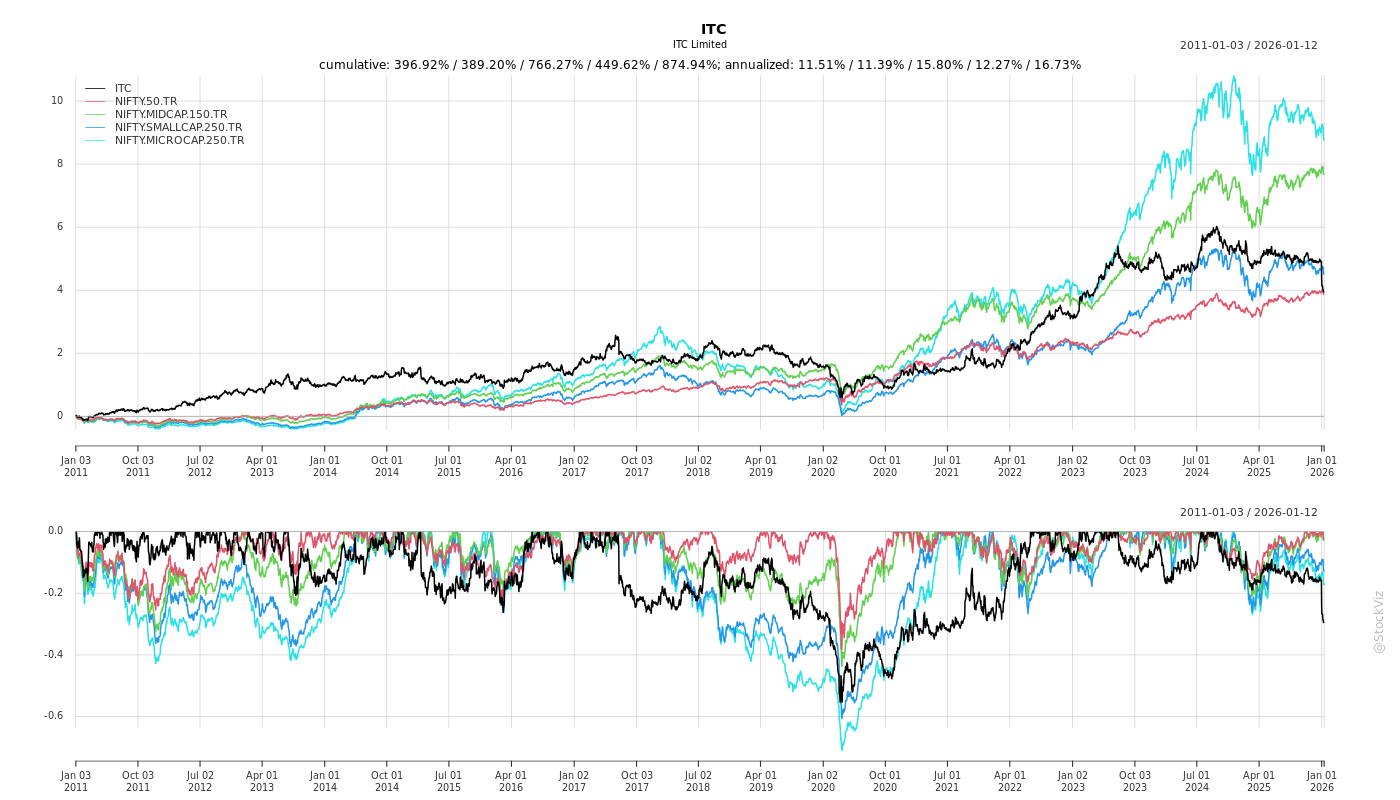
Cumulative Returns and Drawdowns
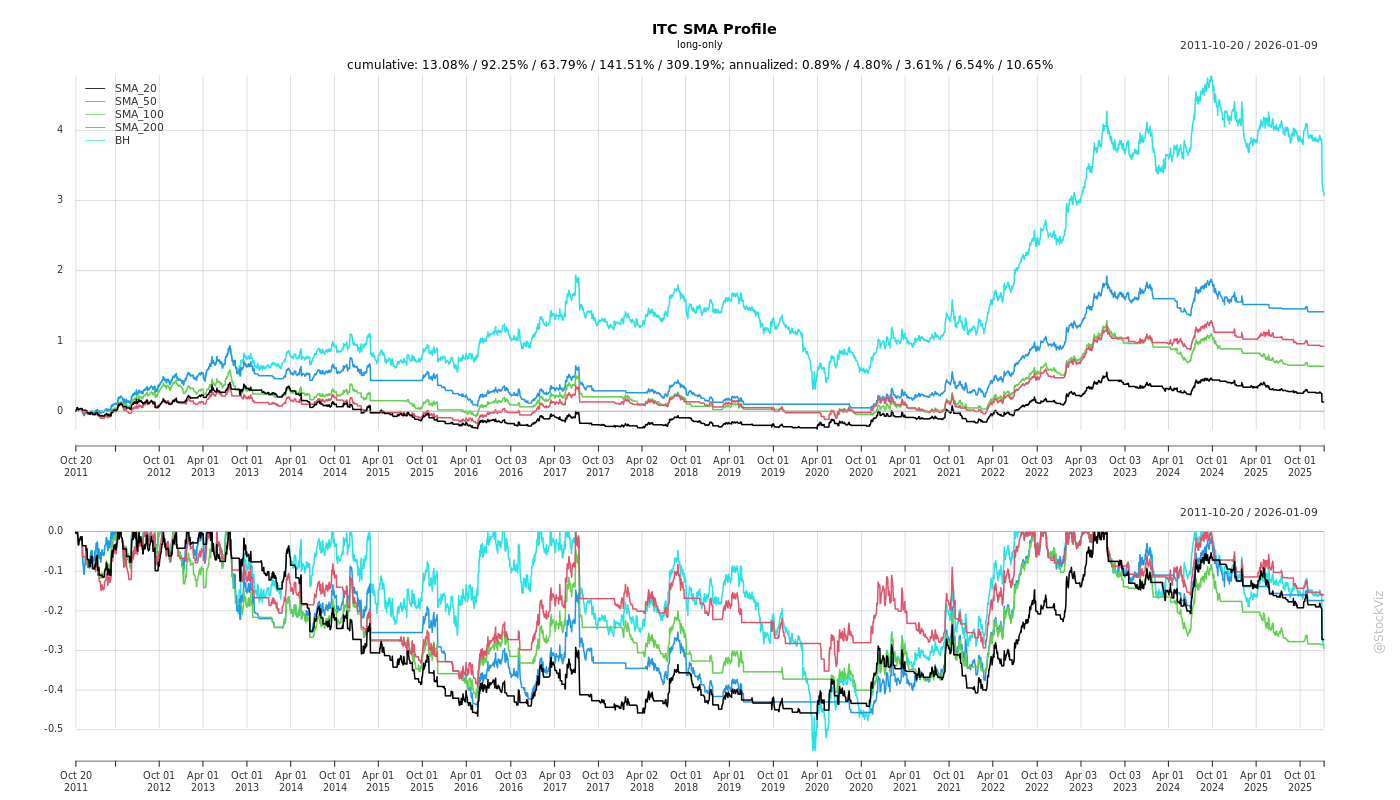
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-14
Headwinds and Challenges
- Sharp excise duty increase on cigarettes: Consequent to the expiry of the GST Compensation Cess, the Government of India increased GST and Central Excise duty on cigarettes with effect from 1st February, 2026. Because excise duty is not excluded from gross revenue (unlike GST and GST Compensation Cess), reported gross revenue and excise duty for the quarters ended 30th June, 2026 and 31st March, 2026 reflect this sharp increase and are not strictly comparable with previous periods.
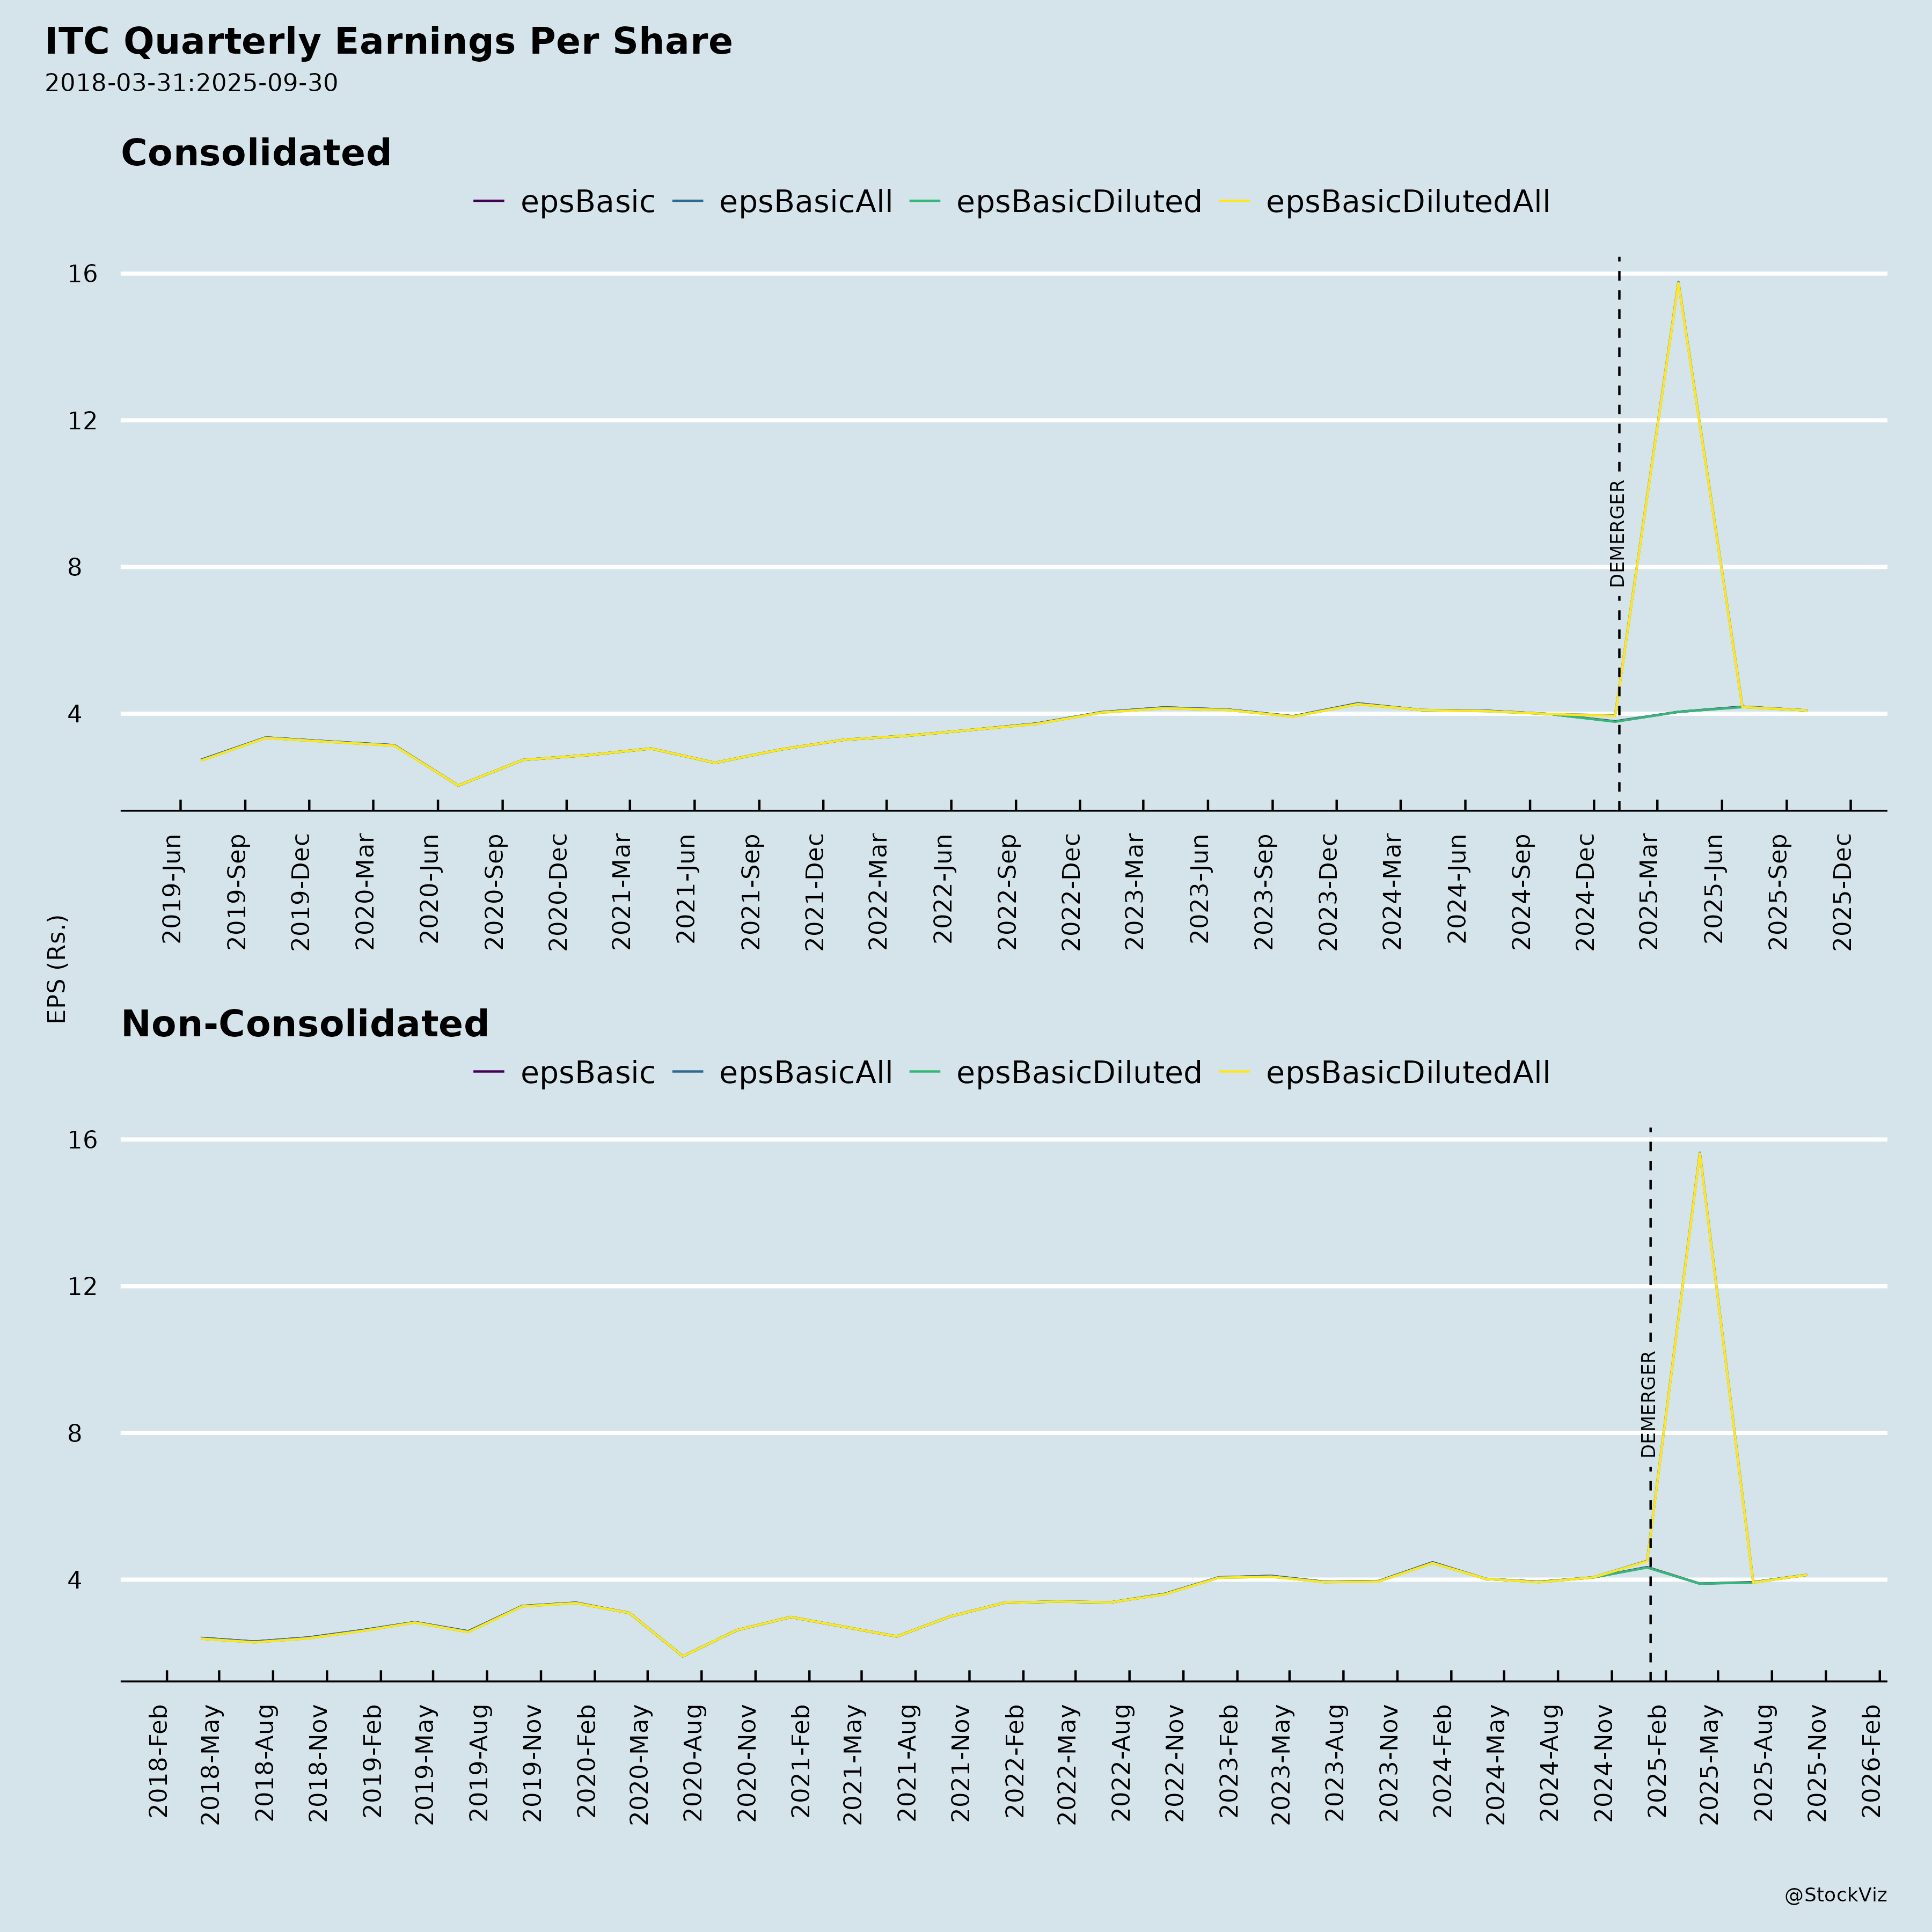
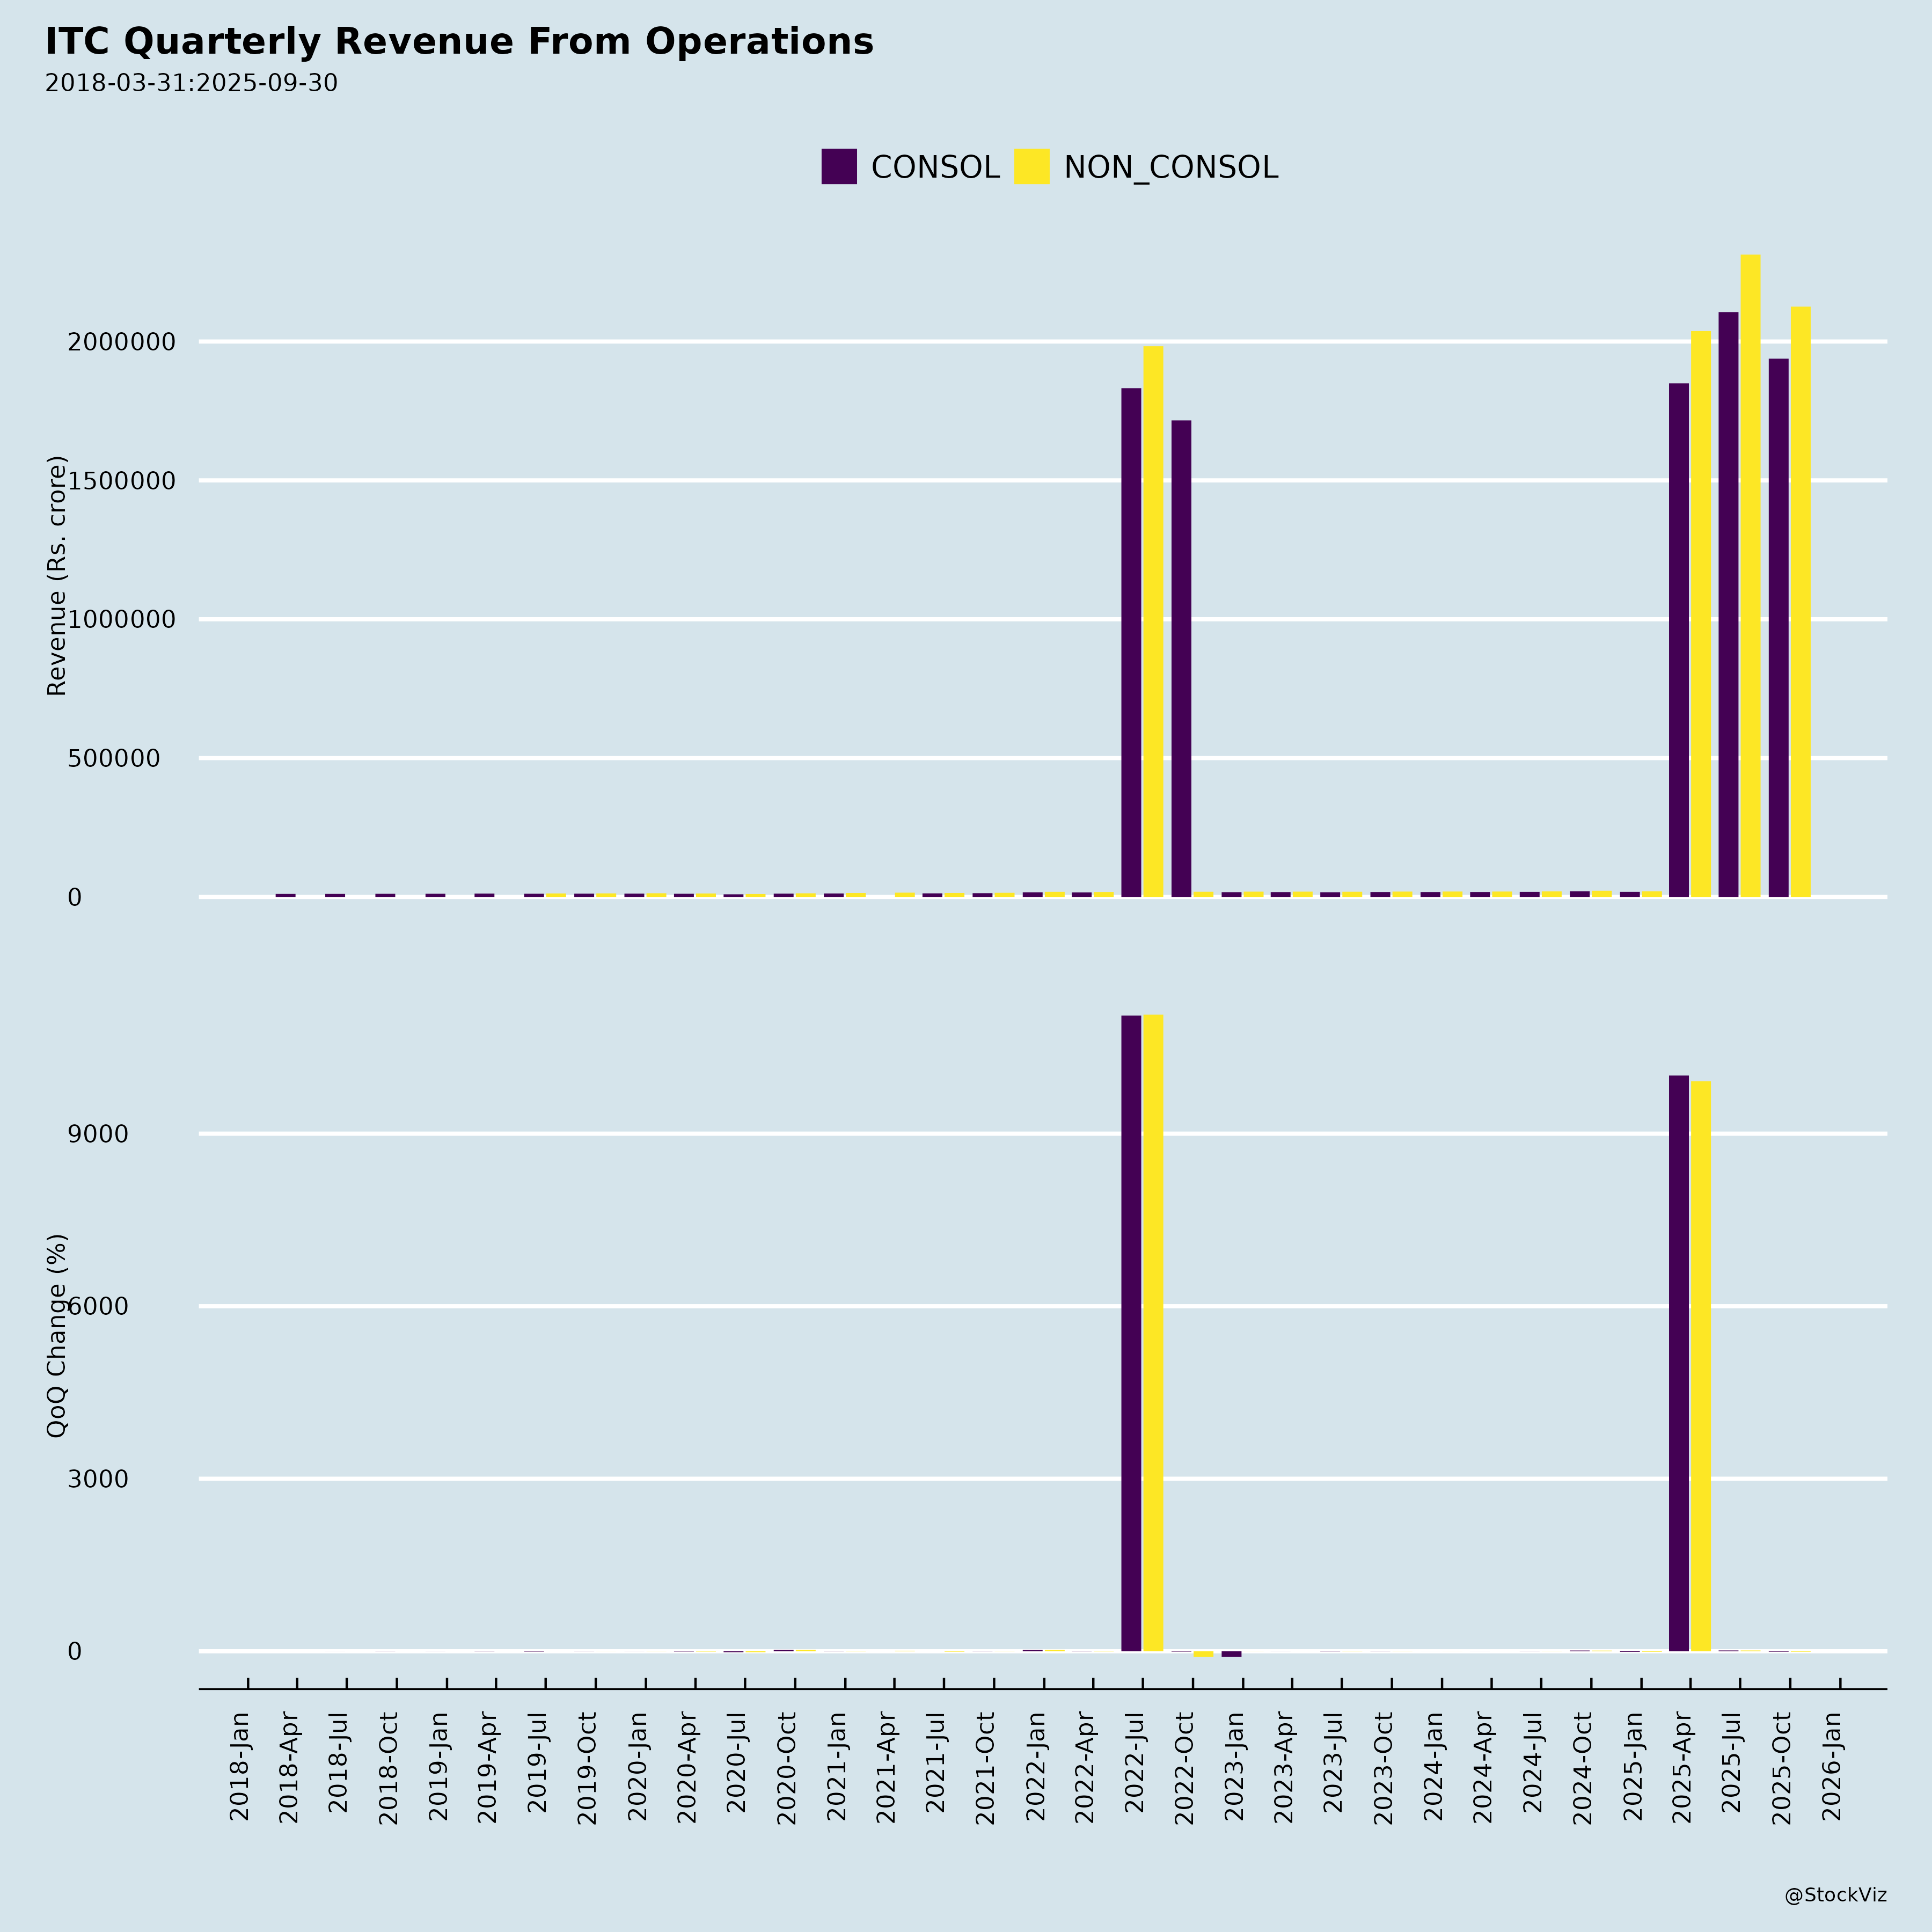
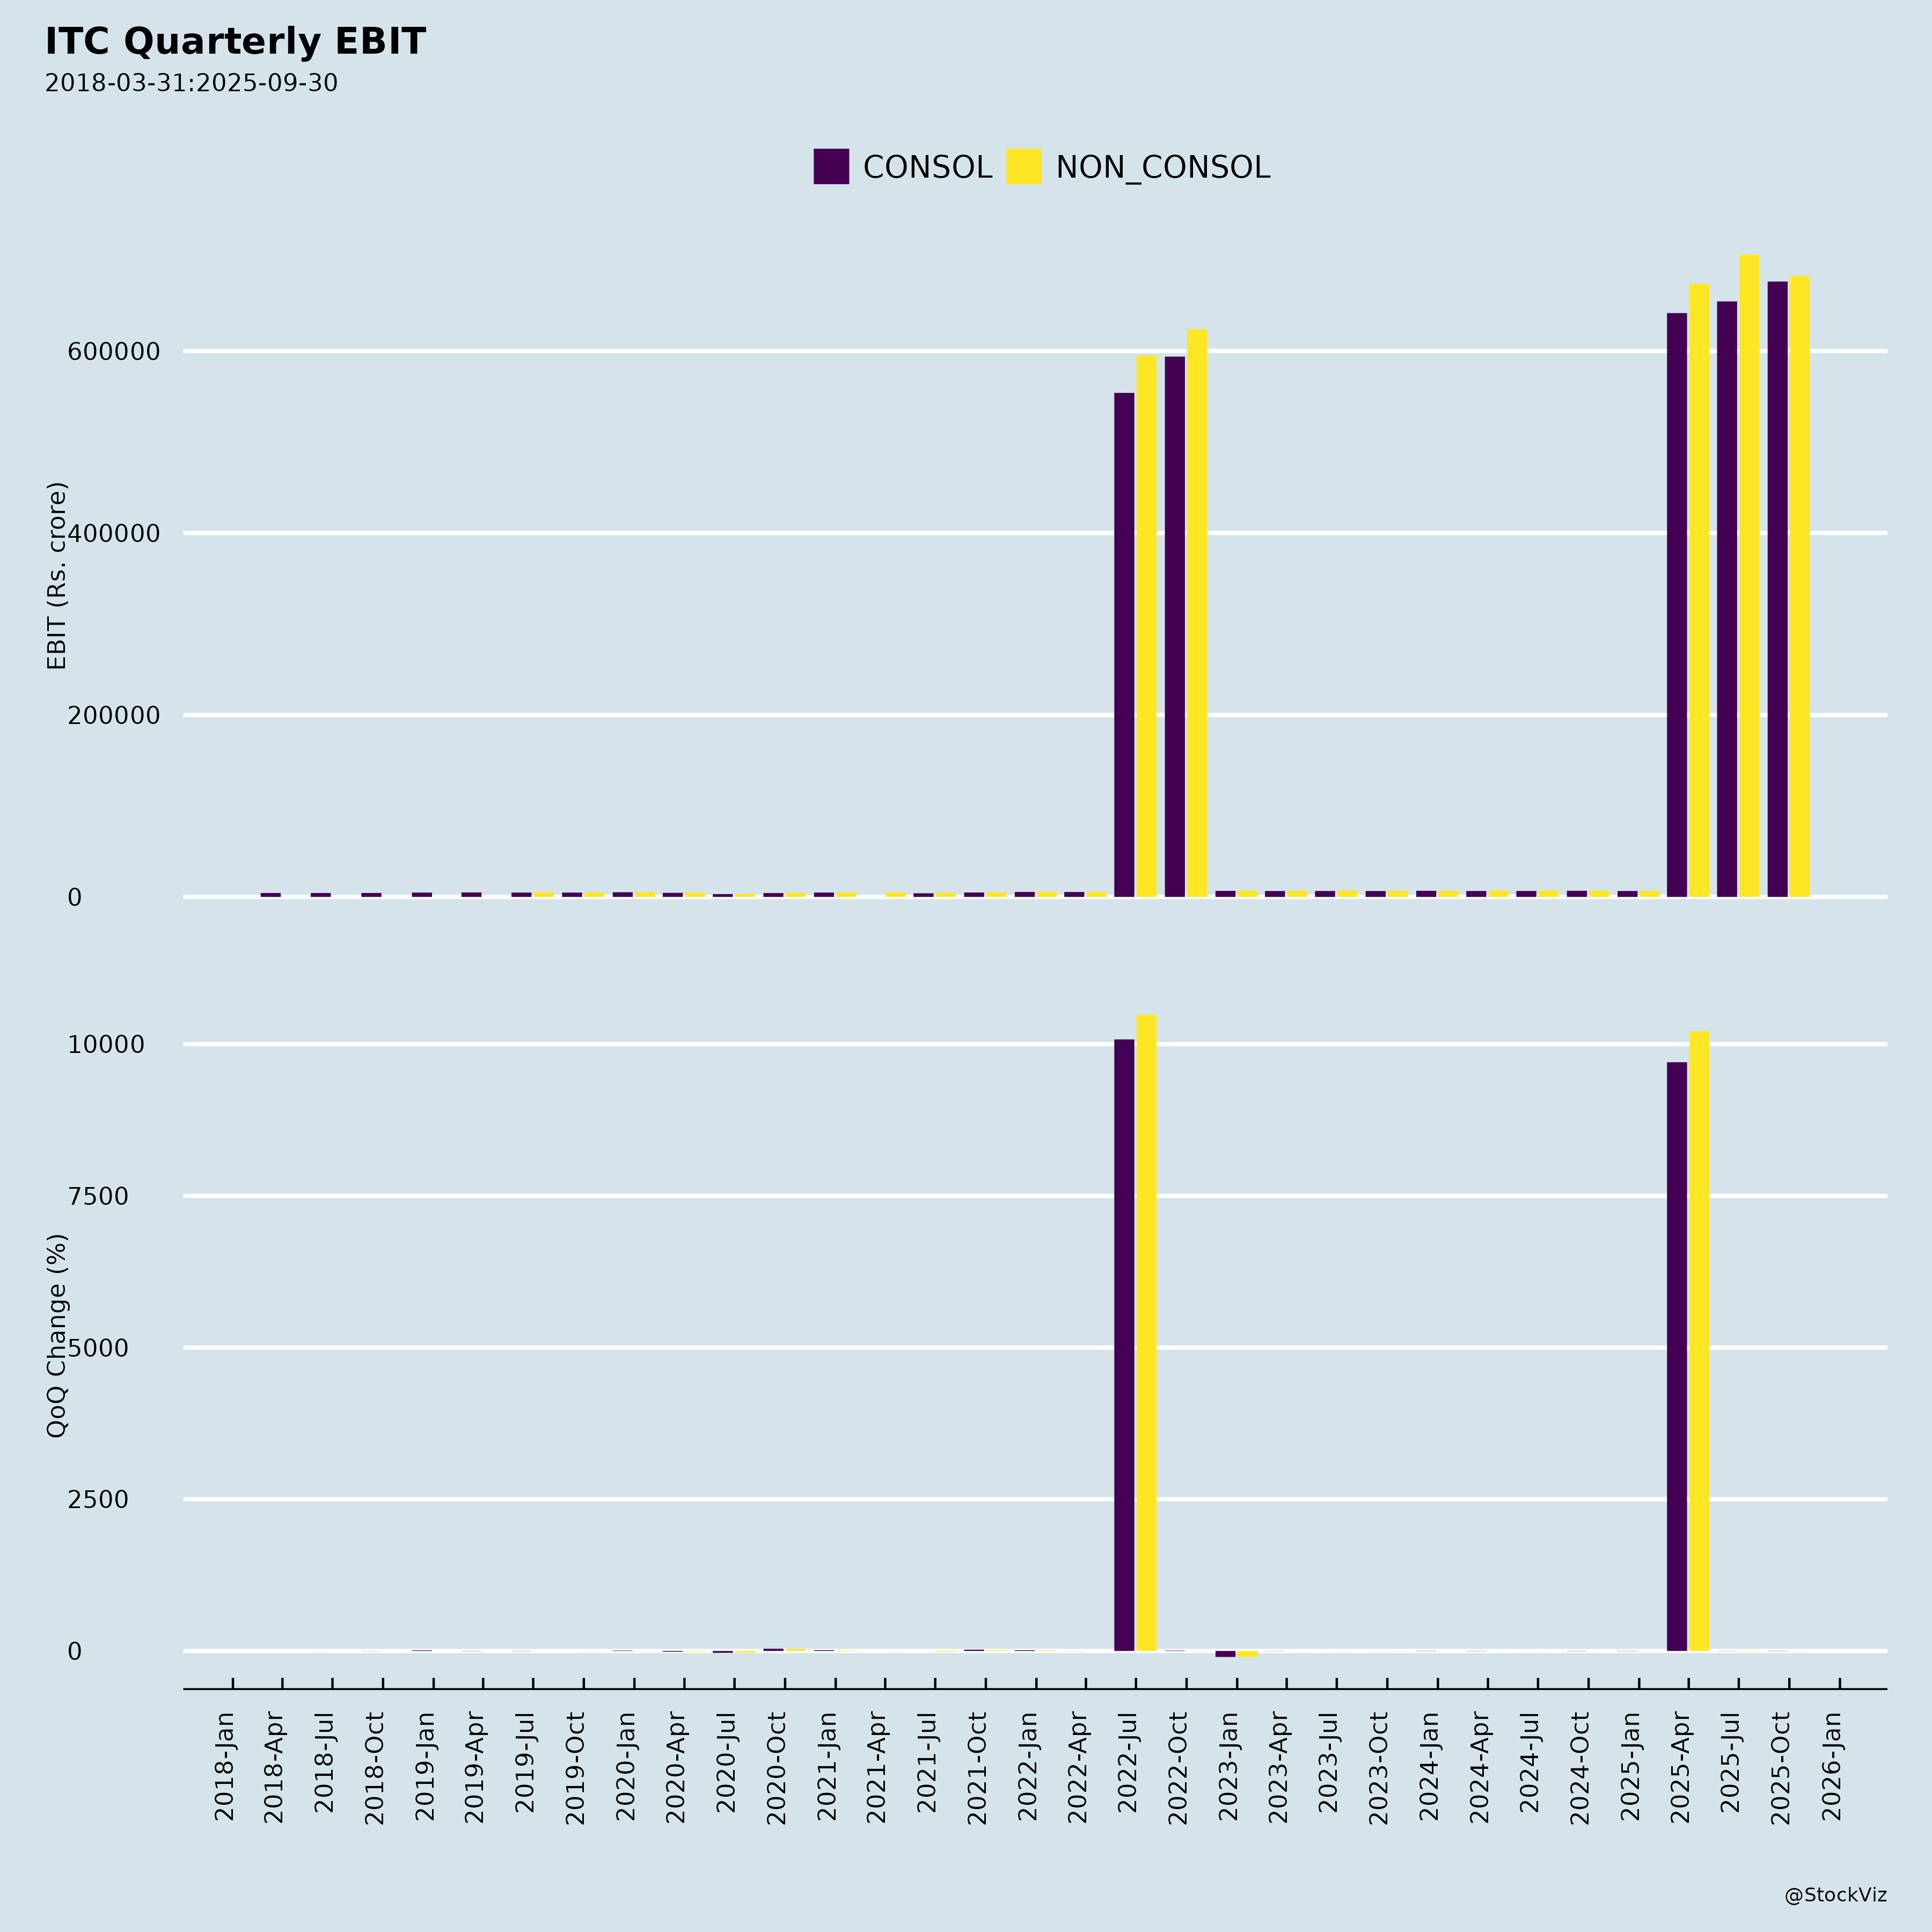
- Subdued profitability despite higher revenue: On a standalone basis, revenue from operations rose to ₹26,943.23 crores for the quarter ended 30th June, 2026 from ₹21,069.81 crores a year earlier, but profit before exceptional items and tax fell to ₹4,759.41 crores from ₹6,543.48 crores, and profit for the period fell to ₹3,578.82 crores from ₹4,910.73 crores. Standalone basic earnings per share declined to ₹2.86 from ₹3.93.
- Cigarettes segment result decline: Standalone FMCG-Cigarettes segment results fell to ₹3,341.23 crores for the quarter ended 30th June, 2026 from ₹5,145.28 crores in the corresponding quarter, even as segment revenue rose to ₹15,383.55 crores from ₹8,520.04 crores.
- Agri Business weakness: Standalone Agri Business revenue declined to ₹8,082.06 crores from ₹9,685.03 crores, and segment results fell to ₹353.79 crores from ₹439.67 crores (consolidated: revenue ₹8,137.81 crores versus ₹9,723.84 crores; results ₹359.54 crores versus ₹434.67 crores).
- Continued brand-building and gestation costs: Significant brand building costs across personal care and branded packaged food products continue to be reflected in ‘Other expenses’ and in FMCG-Others segment results, alongside business development and gestation costs.
- Consolidated profit decline: Consolidated profit for the quarter fell to ₹4,508.79 crores from ₹5,343.41 crores, with profit attributable to owners of the parent at ₹4,394.13 crores versus ₹5,244.20 crores. Consolidated basic EPS declined to ₹3.51 from ₹4.19.
- Governance dissent at the AGM: At the 115th AGM held on 23rd July, 2026, the special resolution re-appointing Mr. Hemant Bhargava as an Independent Director for five years from 20th December, 2026 passed with 94.1815% votes in favour and 5.8185% against; public institutions recorded 94.1508% in favour and 5.8492% against.
Tailwinds and Growth Prospects
- FMCG-Others growth: Standalone FMCG-Others revenue rose to ₹6,481.95 crores from ₹5,787.34 crores, with segment results improving to ₹478.61 crores from ₹396.02 crores. FMCG-Others EBITDA for the quarter was ₹631.06 crores versus ₹544.65 crores a year earlier.
- Paperboards, Paper & Packaging improvement: Standalone segment revenue rose to ₹2,307.24 crores from ₹2,115.76 crores, with results at ₹224.22 crores versus ₹162.62 crores (consolidated results ₹216.81 crores versus ₹151.40 crores).
- Sproutlife acquisition: Sproutlife Foods Private Limited became a subsidiary with effect from 1st April, 2026, following acquisition of the right to nominate a majority of Directors on its Board. Its results are included in the Group and FMCG-Others segment from that date. The Group recognised a remeasurement gain of ₹405.88 crores as an exceptional item under Ind AS 103.
- Mother Sparsh stake increase: On 19th May, 2026, the Company acquired 1,681 equity shares of Mother Sparsh Baby Care Private Limited, taking its shareholding to 49.32% of share capital on a fully diluted basis.
- Portfolio and structure: The corporate strategy aims at creating multiple drivers of growth anchored on core competencies across three business groups: FMCG, Paperboards, Paper & Packaging, and Agri Business.
- ITC Infotech consolidation: Blazeclan Technologies Private Limited and Cloudlytics Technologies Private Limited amalgamated with ITC Infotech India Limited, effective 1st September, 2026, and dissolved without winding up.
- Investor engagement: ITC representatives are attending the Jefferies 5th India Forum 2026 in Gurugram on 18th September, 2026, and the 11th Annual J.P. Morgan India Conference 2026 in Mumbai on 21st September, 2026.
- Shareholder returns: The 115th AGM confirmed an interim dividend of ₹6.50 per ordinary share and declared a final dividend of ₹8.00 per ordinary share for the financial year ended 31st March, 2026.
Key Risks
- Tax and regulatory risk: The excise duty increase on cigarettes from 1st February, 2026 affects reported revenue and comparability, and the cigarette segment result declined year on year.
- Earnings pressure: Lower profit before tax, profit for the period, and earnings per share on both standalone and consolidated bases indicate pressure on profitability.
- Segment concentration and volatility: Cigarettes remain the largest standalone segment by revenue and results, and its results declined sharply year on year; Agri Business also weakened.
- Cost inflation in operations: Cost of materials consumed rose to ₹6,826.87 crores from ₹6,178.11 crores (standalone), and employee benefits expense rose to ₹978.63 crores from ₹916.69 crores; finance costs rose to ₹33.78 crores from ₹13.40 crores.
- Integration and acquisition accounting risk: The fair values of Sproutlife’s assets and liabilities were provisionally determined under Ind AS 103, and its results are not comparable with previous periods.
- Shareholder dissent: The special resolution on Mr. Hemant Bhargava’s re-appointment as Independent Director saw 5.8185% of votes polled against, with public institutions at 5.8492% against.
Management Guidance Versus Observed Business Performance
- The documents do not contain explicit management guidance or forward-looking financial projections. The available forward-looking elements are event-based: ITC representatives are attending the Jefferies 5th India Forum 2026 in Gurugram on 18th September, 2026, and the 11th Annual J.P. Morgan India Conference 2026 in Mumbai on 21st September, 2026.
- Observed performance against the stated strategic aim of creating multiple drivers of growth is mixed: FMCG-Others and Paperboards, Paper & Packaging improved, while Cigarettes and Agri Business segment results declined, and overall standalone and consolidated profit fell year on year.
- The stated focus on three business groups (FMCG, Paperboards, Paper & Packaging, and Agri Business) is reflected in the segment reporting, with FMCG-Others continuing to absorb significant brand building and gestation costs.
- The Company’s corporate strategy aims at creating multiple drivers of growth anchored on core competencies, and the organisational structure is designed to support effective management of multiple businesses while retaining focus on each one of them.
Broker Narrative
The broker narrative evolved from 2022 concerns over digital liquidity, venture-funding droughts and unit economics to 2026 focus on cigarette excise duties, agri-export disruptions and input-cost inflation. Inflation persisted as the one consistent macro headwind across both periods. The early optimism around digital adoption and niche consumer demand matured into tangible FMCG digital-first brands (ARR ~₹1,500 crore) and value-added agri growth, but was eclipsed by the structural drag from cigarette volume declines and tax hikes.
Fears that came true
- “Higher inflation impacting unit economics” flagged in 2022 materialized as sustained input-cost inflation and West Asia/monsoon-driven cost pressures in the last report, correlating with repeated DISAPPOINTMENT outcomes from 2023–2025.
Broker Timeline
93 broker calls · 2022-06-09 to 2026-08-04
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.