IOC
Equity Metrics
September 24, 2026
Indian Oil Corporation Limited
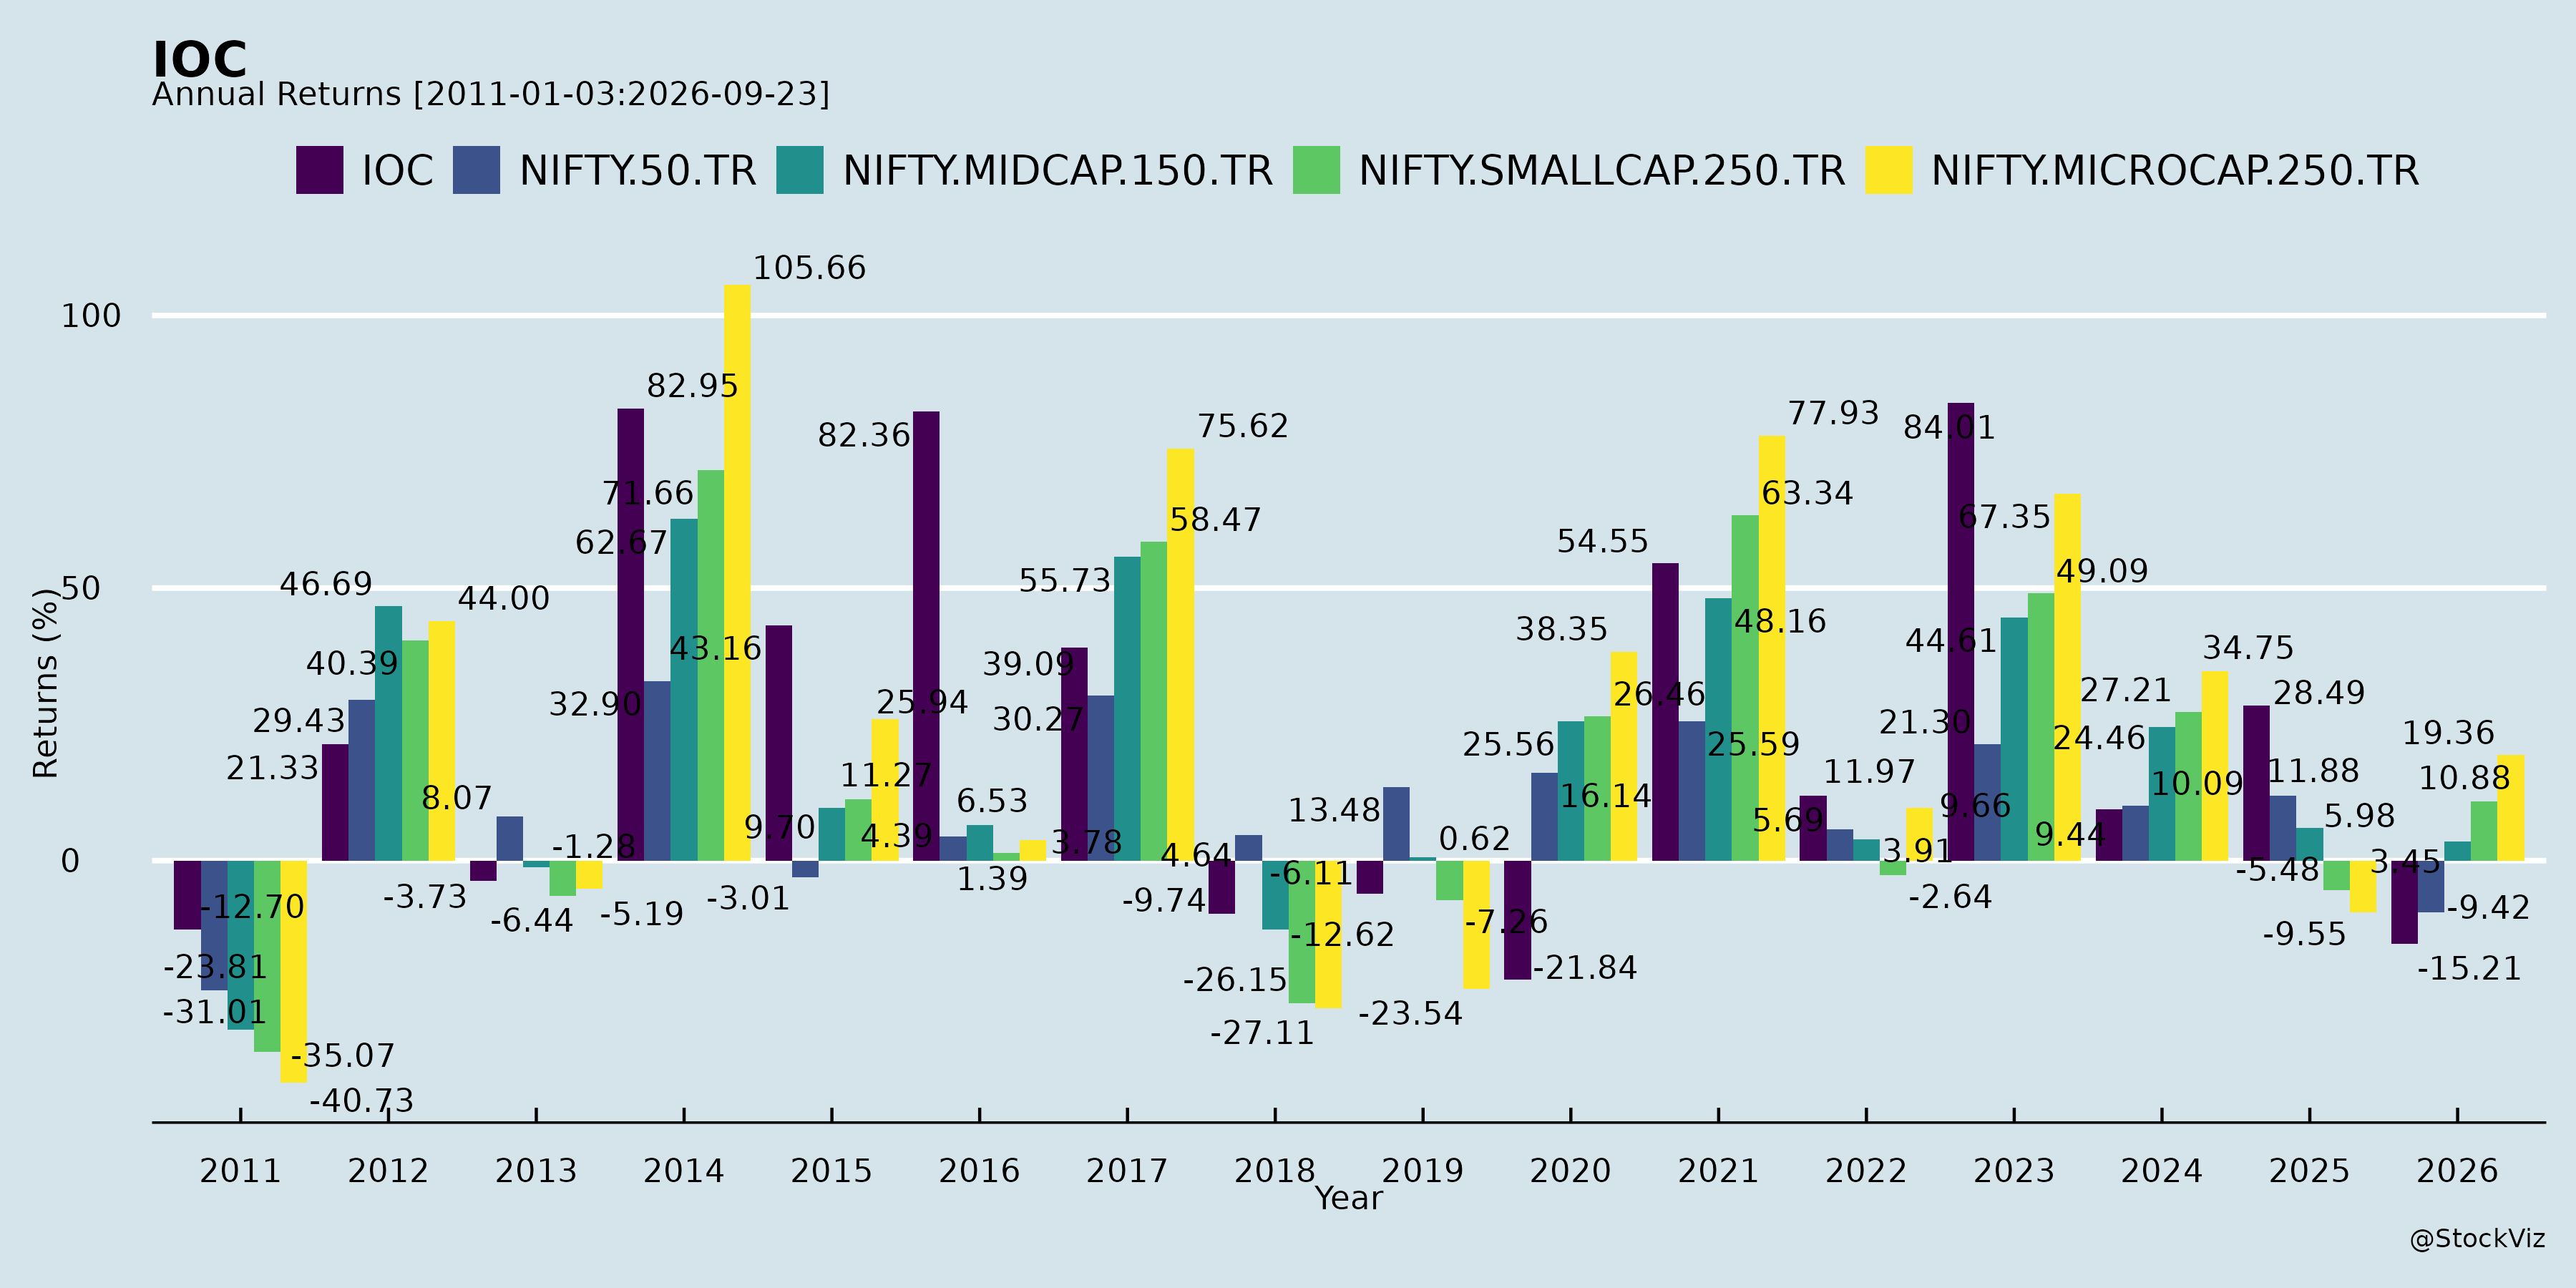
Annual Returns
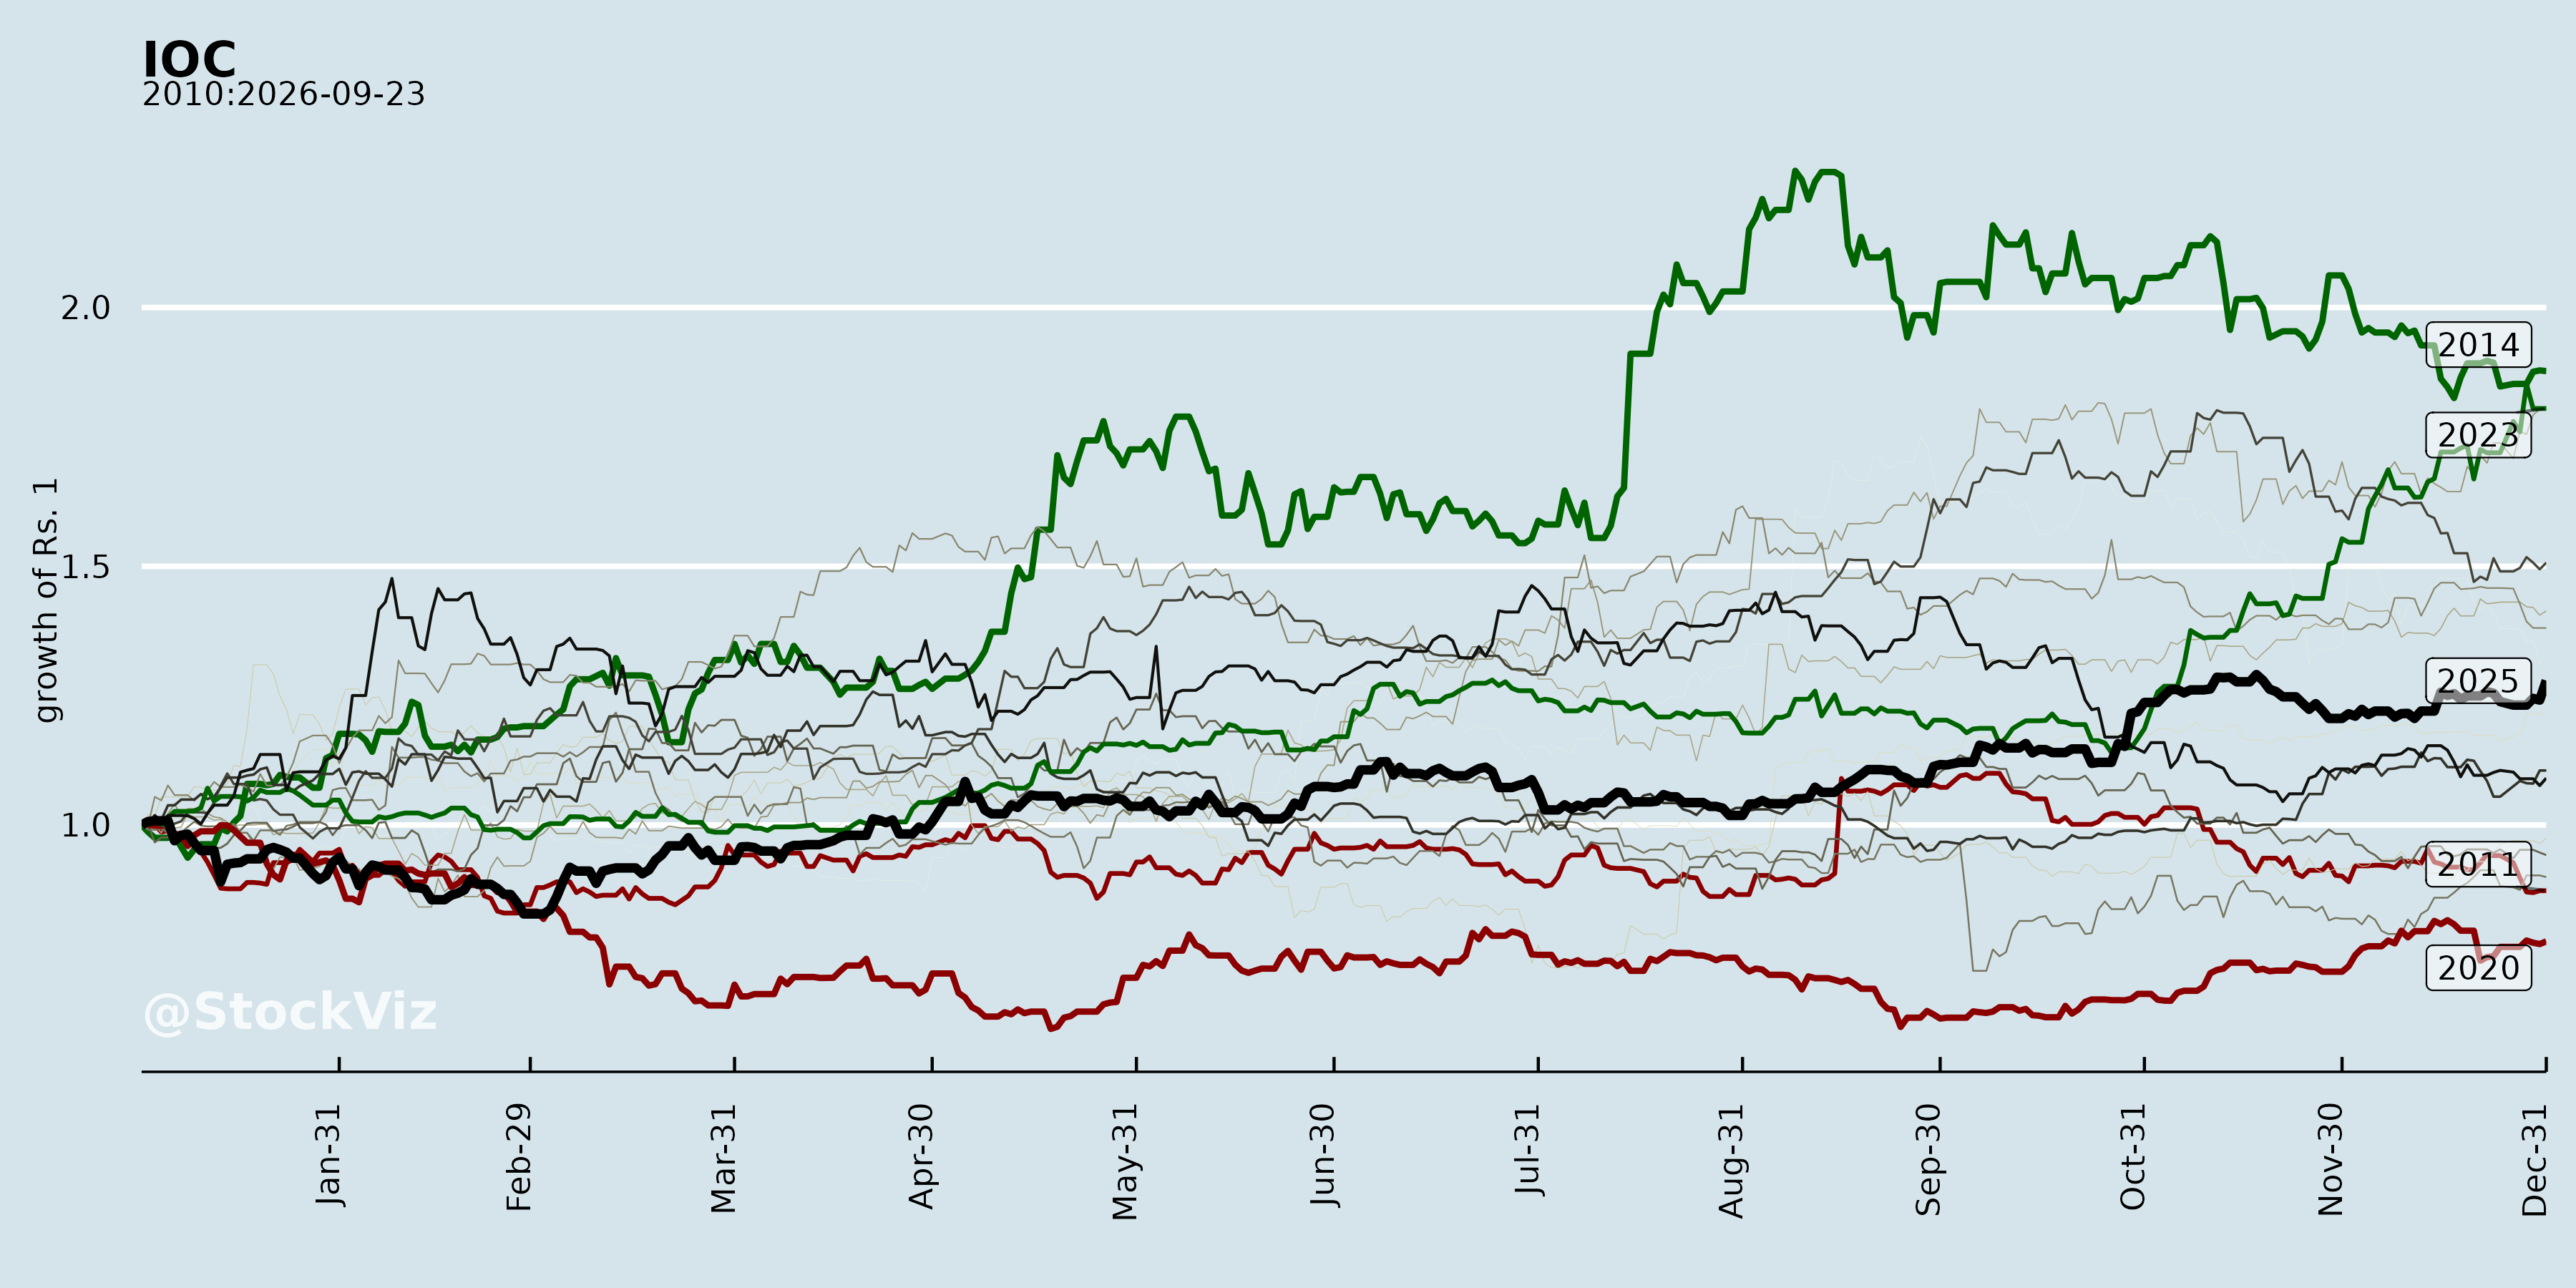
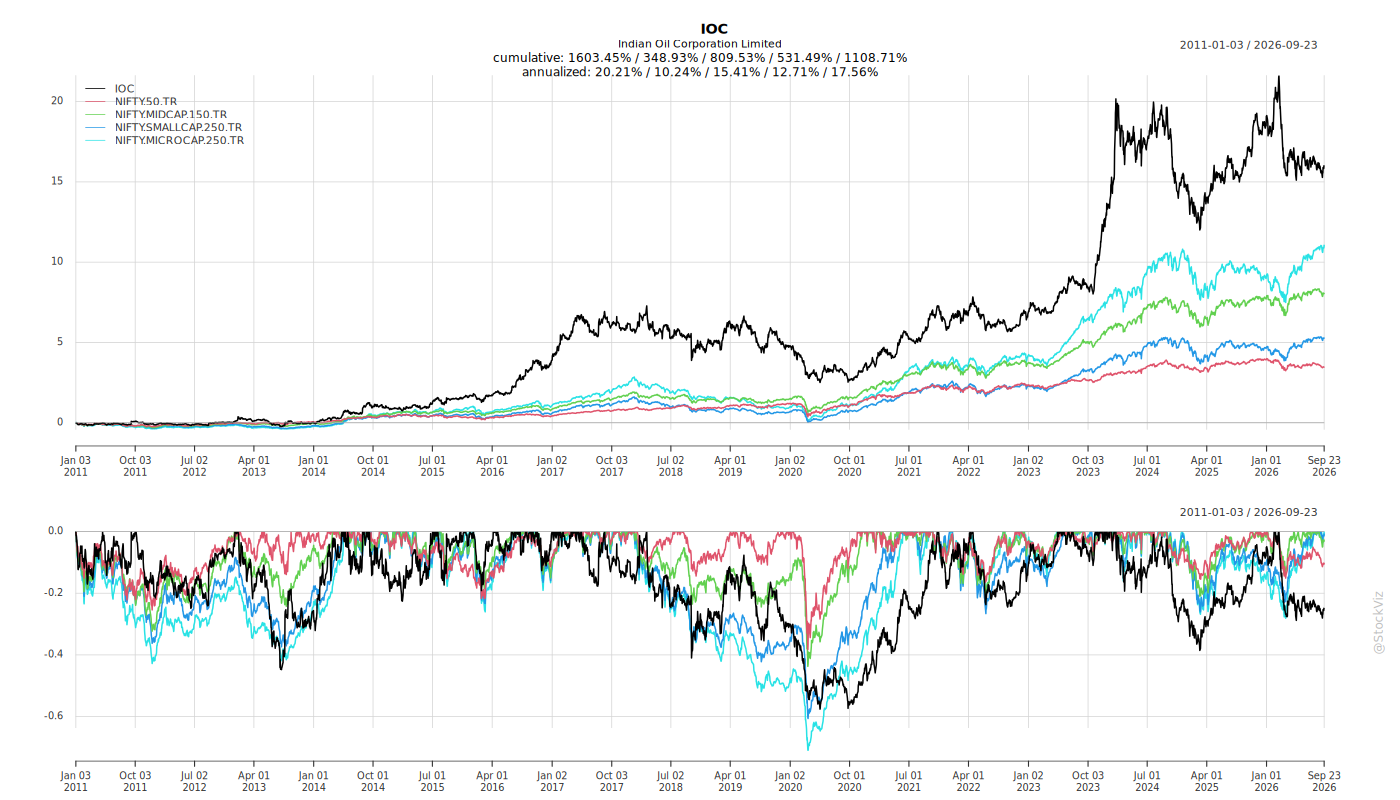
Cumulative Returns and Drawdowns
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-14
IndianOil Q1 FY2026-27: Headwinds, Growth Prospects, Risks and Guidance
1. Headwinds and Challenges
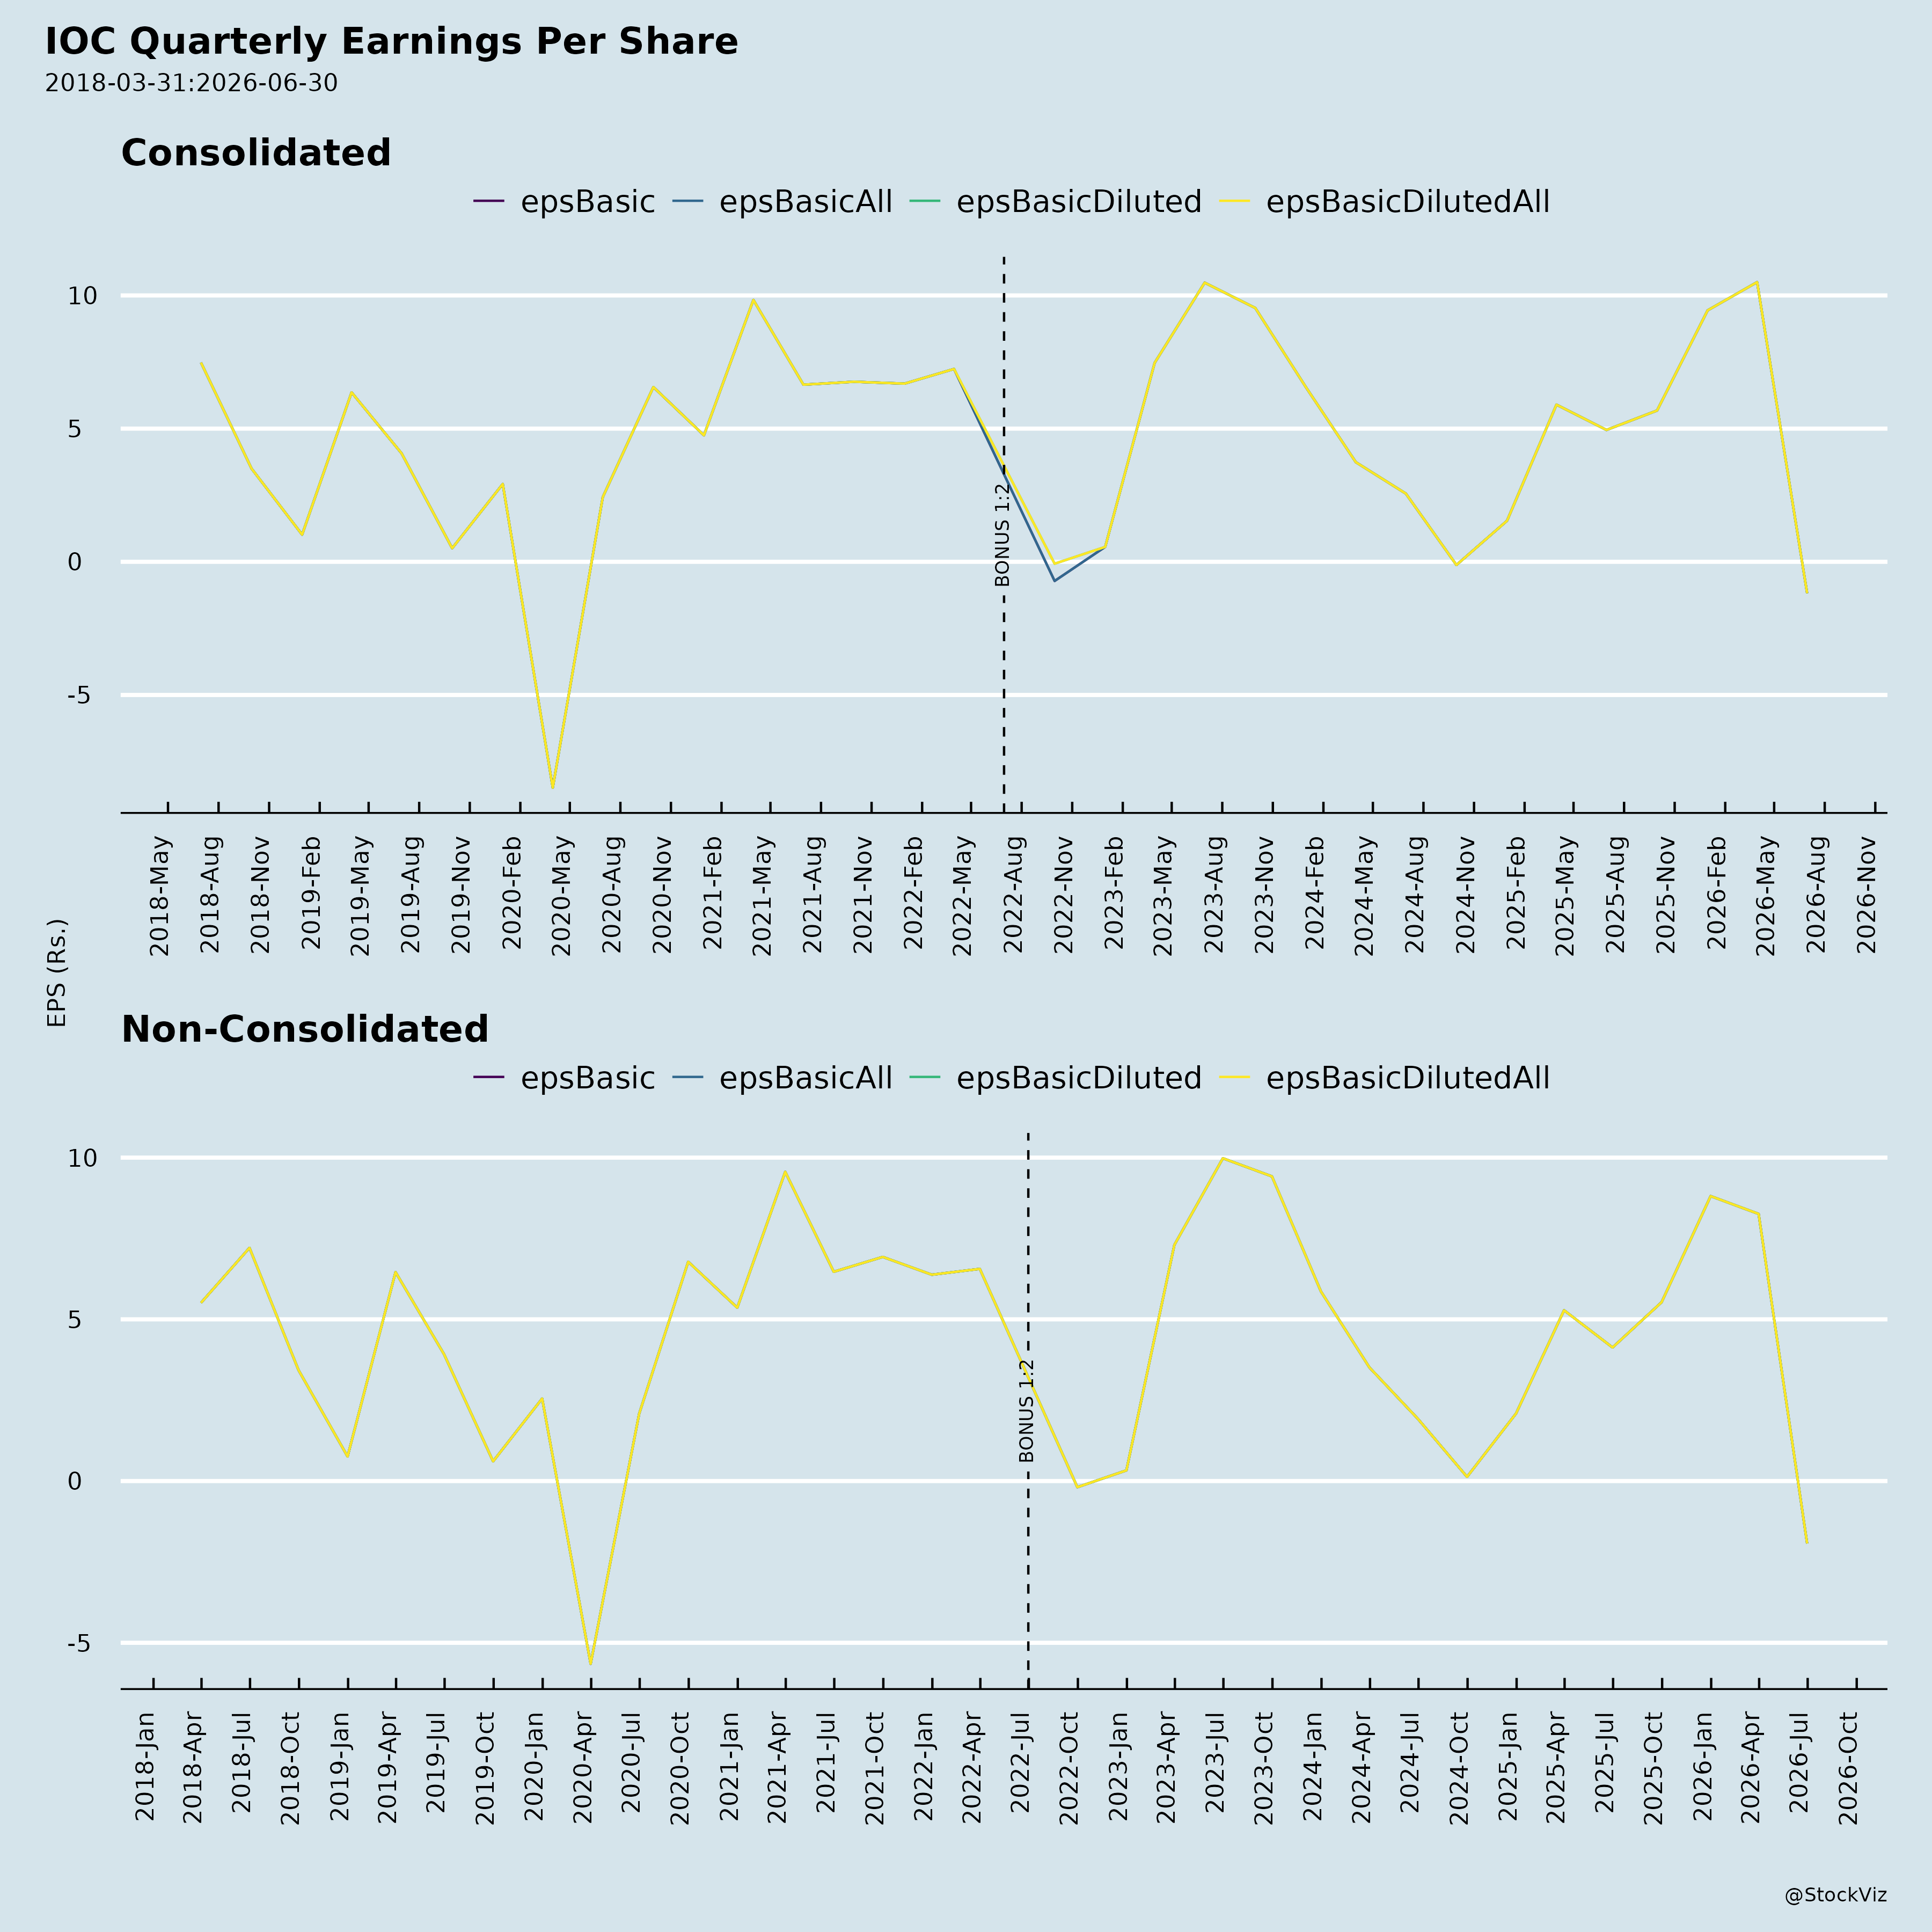
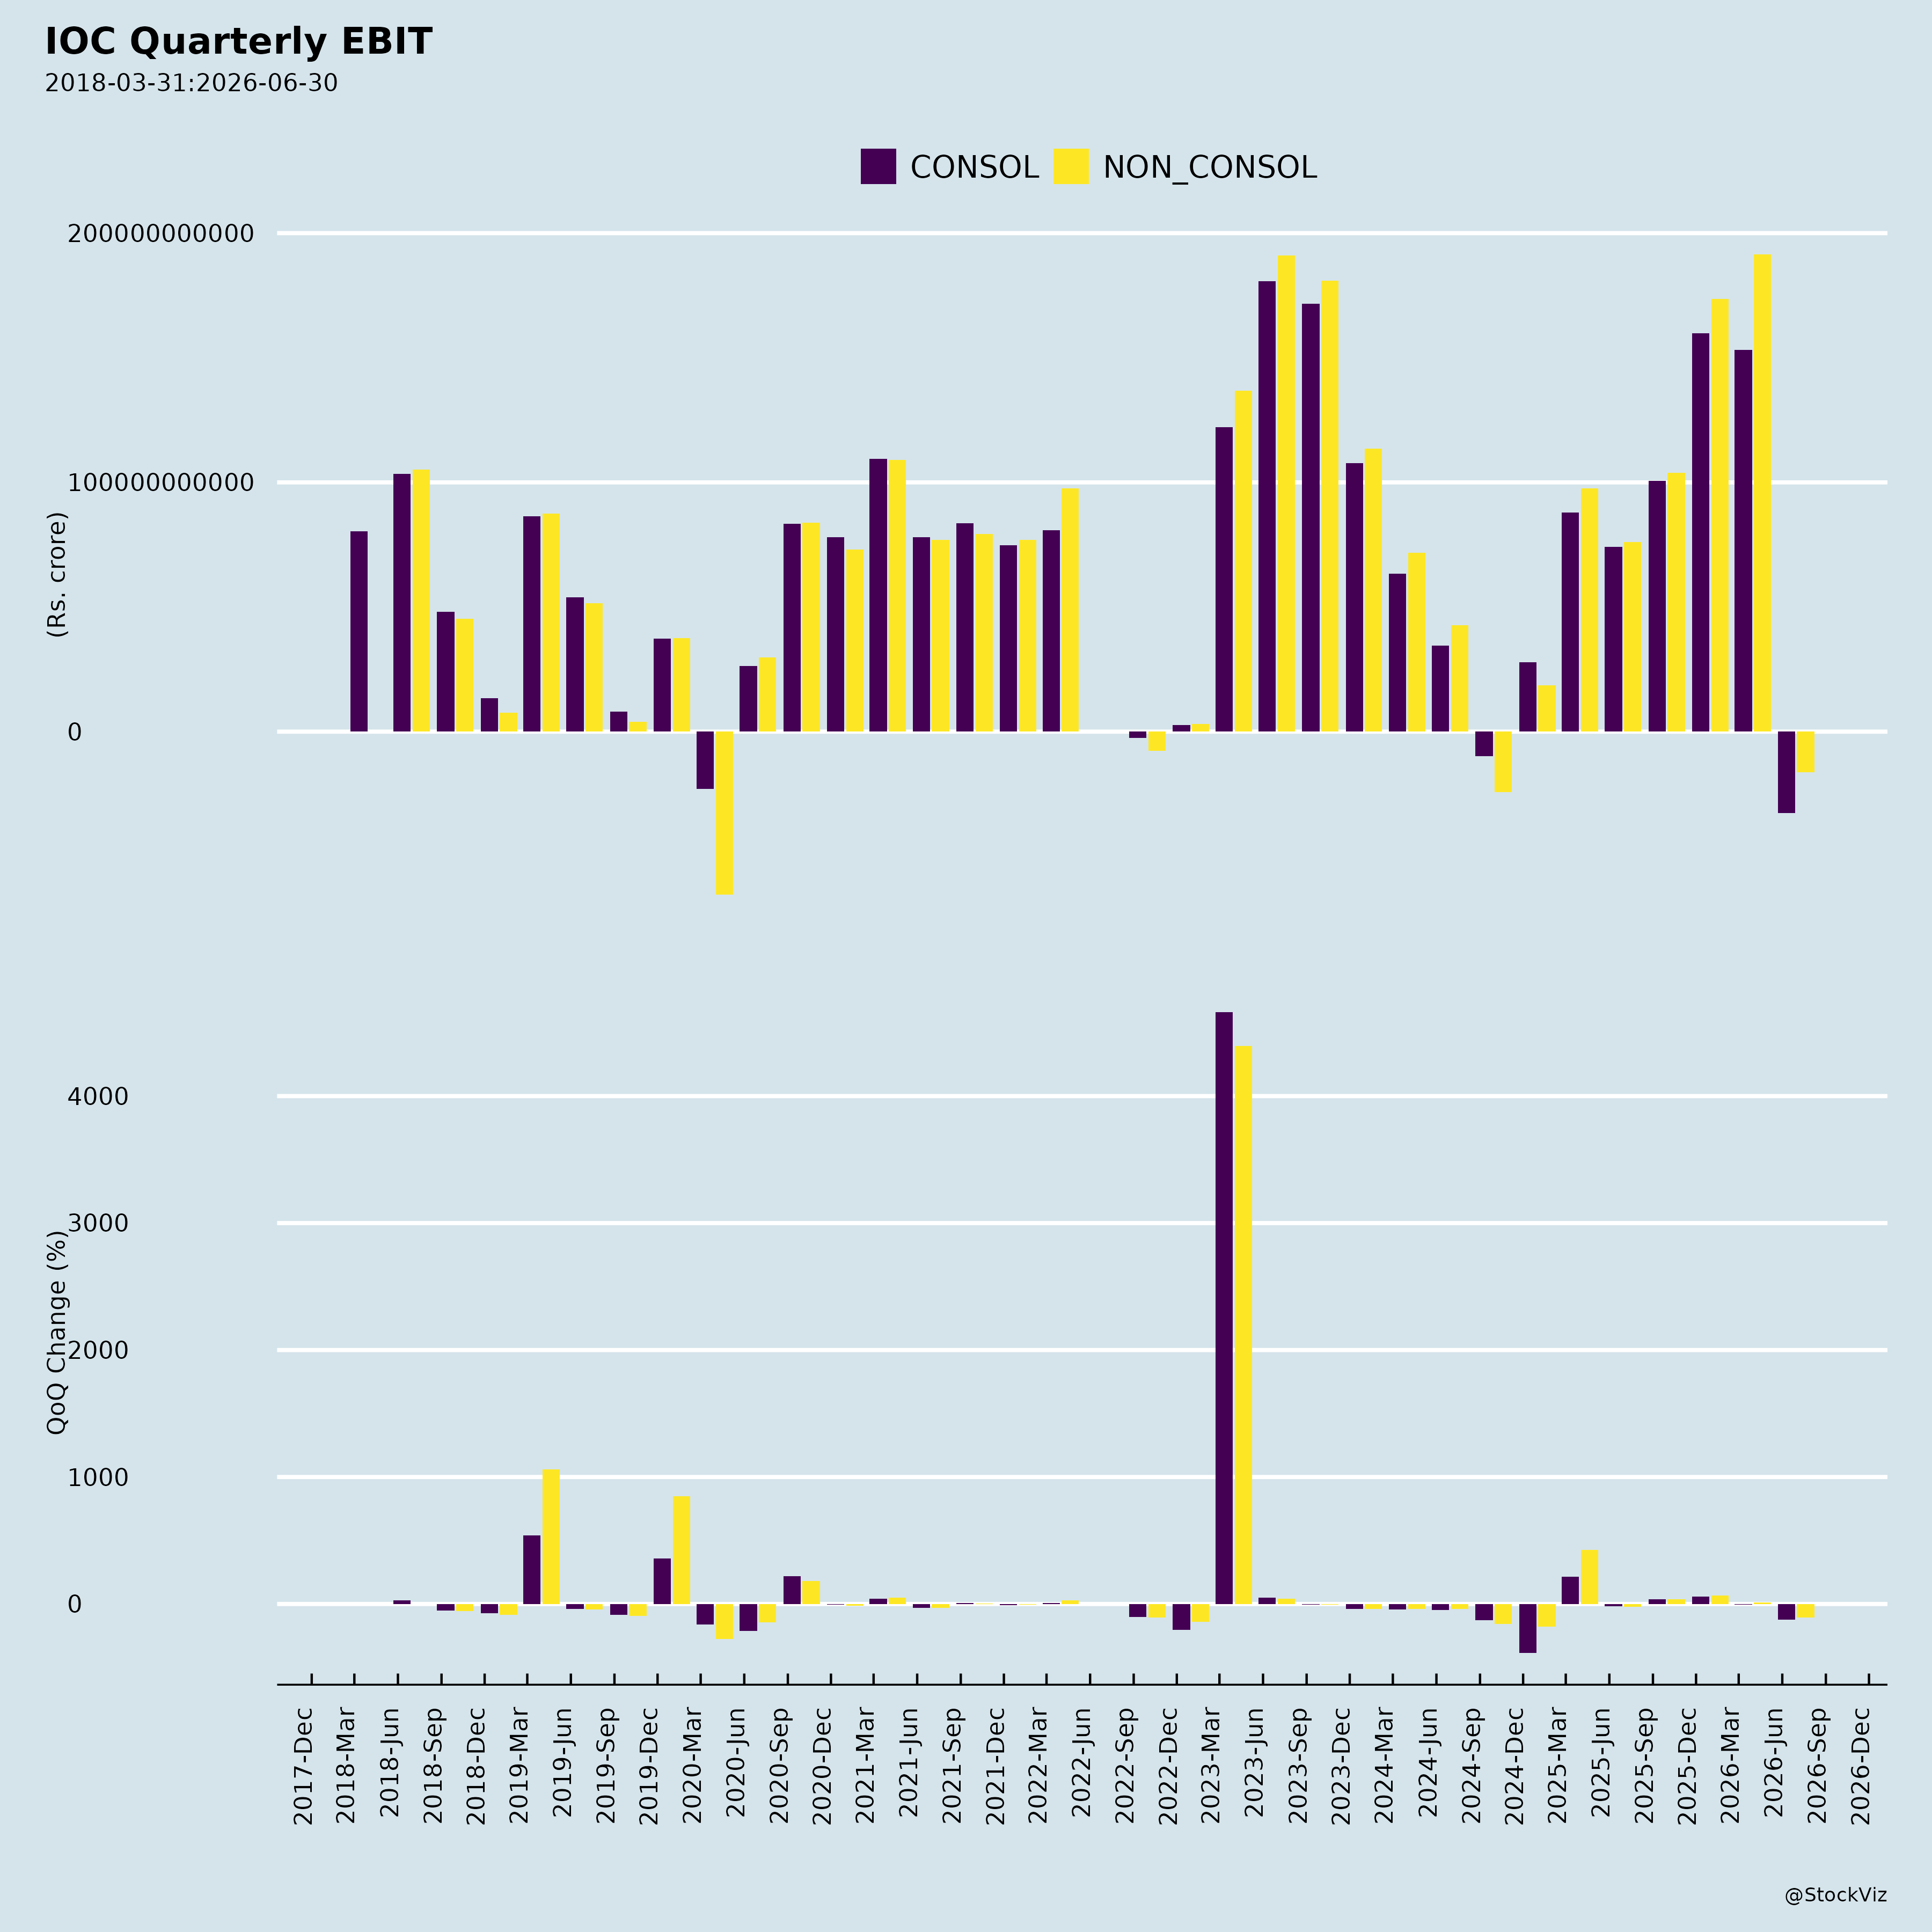
Loss-making quarter. For the quarter ended 30 June 2026, IndianOil reported a standalone loss before tax of ₹3,274.30 crore and a net loss of ₹2,662.37 crore, compared with a profit before tax of ₹7,404.91 crore and net profit of ₹5,688.60 crore in the quarter ended 30 June 2025. On a consolidated basis, the loss before tax was ₹932.59 crore and the net loss attributable to equity holders of the parent was ₹1,630.74 crore, against a consolidated profit before tax of ₹8,750.48 crore a year earlier.
Petroleum Products segment swung into loss. The standalone Petroleum Products segment recorded a loss before tax, interest income, finance costs and dividend of ₹2,872.56 crore for the quarter, versus a profit of ₹9,137.96 crore in the same quarter of the previous year. On a consolidated basis, the same segment recorded a loss of ₹1,705.02 crore against a profit of ₹9,070.29 crore a year earlier.
LPG under-recovery buffer remains deeply negative. As on 30 June 2026, the company had a cumulative net negative buffer of ₹29,729.95 crore under the MoPNG mechanism of 30 April 2020, under which oil marketing companies retain the difference between the market determined price and the effective cost to customer in a separate buffer account for future adjustment.
Sharp deterioration in coverage and margin ratios. Standalone interest service coverage fell to 1.23 times in Q1 FY2026-27 from 5.64 times in Q1 FY2025-26 and 10.33 times in Q4 FY2025-26. Debt service coverage fell to 0.62 times from 2.06 times a year earlier. Operating margin turned negative at (0.74%) against 4.01% a year earlier, and net profit margin was (0.96%) against 2.60%. Consolidated interest service coverage was 2.59 times against 6.16 times, and consolidated operating margin was 0.12% against 4.61%.
Higher leverage. Standalone debt-equity rose to 0.71 times as on 30 June 2026 from 0.66 times as on 30 June 2025 and 0.54 times as on 31 March 2026. Total debts to total assets rose to 0.27 times from 0.25 times a year earlier. Consolidated debt-equity was 0.69 times against 0.65 times.
Board and committee non-compliance. The company did not have the minimum number of Independent Directors (including one Woman Independent Director) and Non-Executive Director required under the Companies Act and SEBI LODR throughout the reporting period. Due to the non-availability of any Independent Director with effect from 28 March 2026, the Audit Committee, the Nomination & Remuneration Committee, the CSR Committee and other relevant committees were discontinued and had not been reconstituted as of the date of reporting. The auditors noted that their conclusion is not modified in respect of these matters.
Lower physical volumes. Standalone domestic product sales were 25.252 MMT in Q1 FY2026-27 against 26.065 MMT in Q4 FY2025-26 and 24.973 MMT in Q1 FY2025-26. Export sales fell to 0.959 MMT from 1.278 MMT and 1.355 MMT respectively. Refineries throughput was 19.165 MMT against 19.732 MMT and 18.683 MMT. Pipelines throughput was 28.548 MMT against 27.656 MMT and 26.256 MMT.
Working capital position. The standalone current ratio was 0.72 times and the consolidated current ratio 0.76 times as on 30 June 2026, indicating current liabilities exceed current assets.
2. Tailwinds and Growth Prospects
Government compensation for LPG under-recoveries. MoPNG letters dated 3 and 24 October 2025 conveyed approval for compensation of ₹14,486 crore towards under-recoveries on domestic LPG sales up to 31 March 2025 and likely to be incurred up to 31 March 2026, disbursable in 12 equal monthly instalments accruing monthly from November 2025. Instalments for April to June 2026 aggregating ₹3,621.51 crore were recognised as Revenue from Operations, reducing the cumulative net negative buffer to that extent.
Paradip Refinery investment programme. IndianOil has made a cumulative investment of approximately ₹43,359 crore at Paradip, comprising refinery units (₹34,555 crore), a polypropylene plant (₹3,150 crore) and a mono ethylene glycol plant (₹5,654 crore), sustaining over 12,500 livelihoods. A further ₹13,805 crore is being invested in the ongoing Paraxylene-Purified Terephthalic Acid (PX-PTA) project. About ₹4,382 crore is planned for the Bhadrak Textile Park Project through a joint venture with MCPI Private Limited, and ₹1,064 crore is planned for a Hydroprocessed Esters and Fatty Acids (HEFA) based Sustainable Aviation Fuel project through a joint venture with M11 Energy Transition Pvt. Ltd.
Paradip operational milestones. During FY2025-26, Paradip Refinery recorded its highest-ever crude processing of 16.35 MMT and commissioned the Standby Sulphur Recovery Unit-III and the New Hydrogen Generation Unit. The 1.2 MMTPA Purified Terephthalic Acid unit under the PX-PTA project is nearing completion.
Petrochemicals and Gas segment performance. Standalone Petrochemicals segment revenue rose to ₹9,516.94 crore in Q1 FY2026-27 from ₹6,764.10 crore a year earlier, with segment profit before tax of ₹216.85 crore against a loss of ₹1.02 crore. Gas segment revenue rose to ₹14,481.49 crore from ₹10,309.28 crore, with segment profit of ₹526.05 crore against ₹50.41 crore.
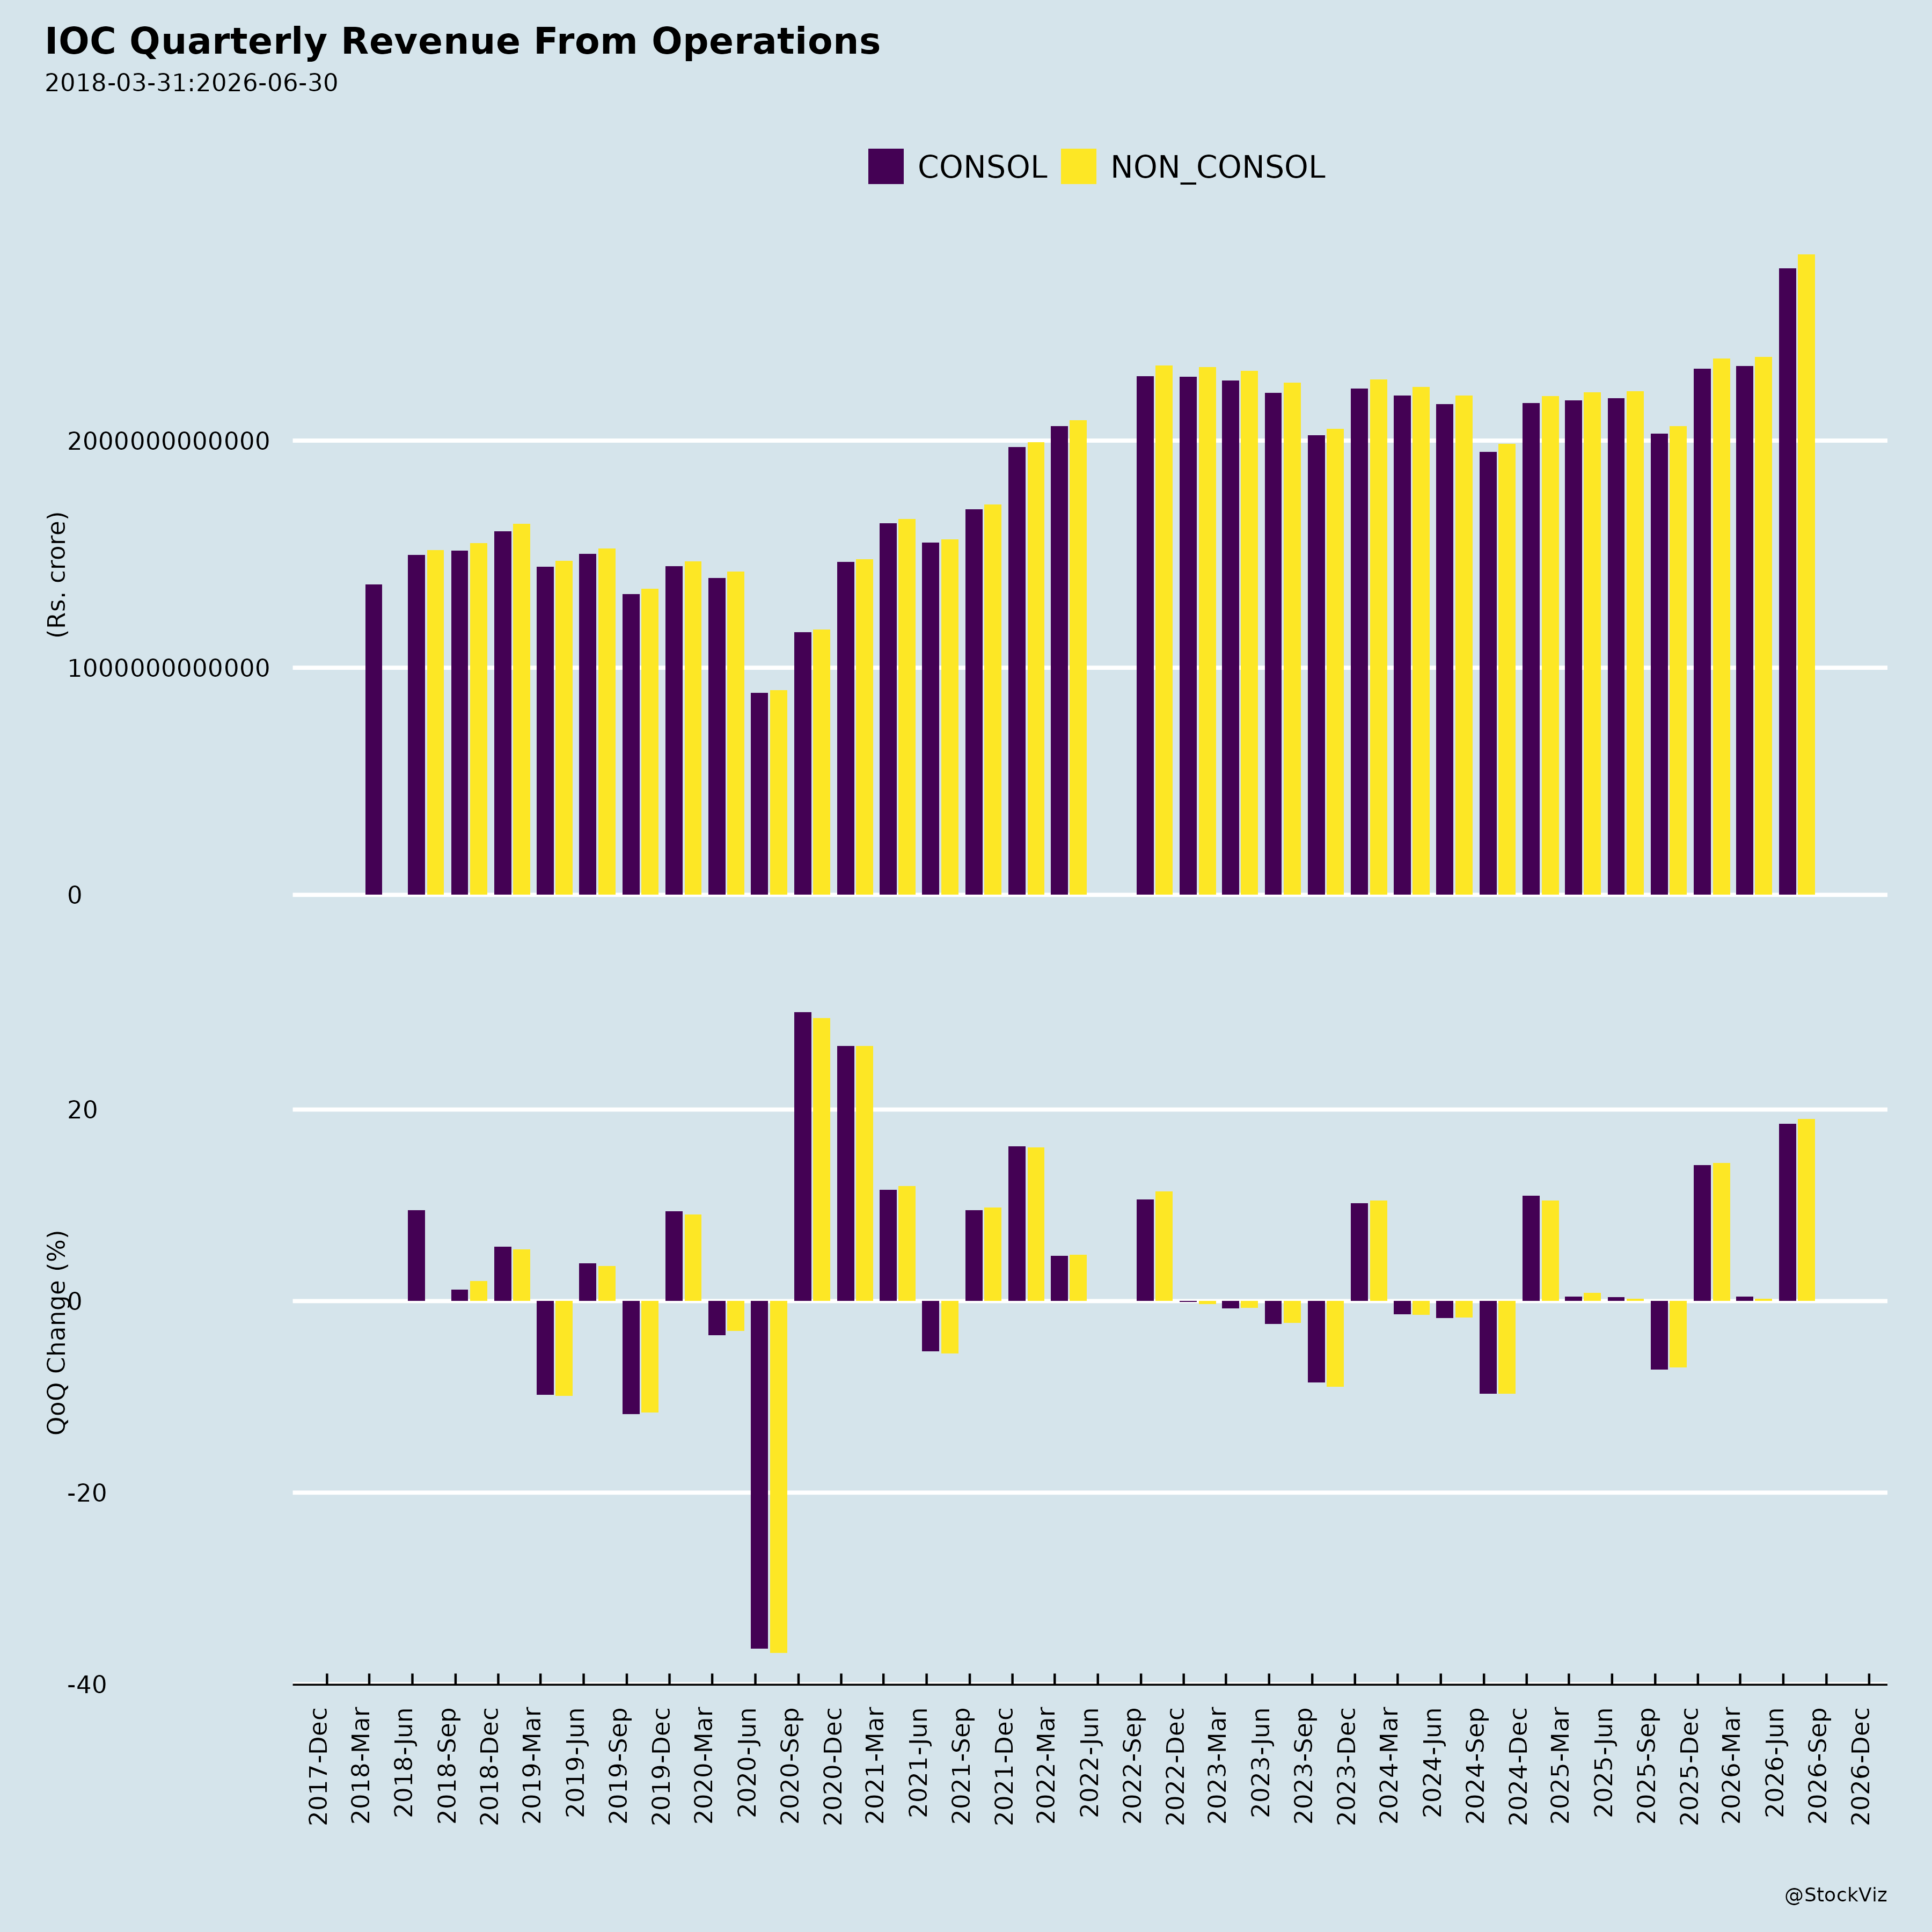
Revenue growth. Standalone revenue from operations rose to ₹275,971.77 crore in Q1 FY2026-27 from ₹218,607.70 crore a year earlier. Consolidated revenue rose to ₹281,933.07 crore from ₹221,849.02 crore.
Paradip contribution to exchequer and CSR. During FY2025-26, Paradip Refinery contributed over ₹30,392 crore to the state and central exchequer. IndianOil Paradip Refinery spent ₹56.71 crore on CSR and Corporate Environment Responsibility initiatives from FY2014-15 to FY2025-26.
Awards. Paradip Refinery received the Kalinga Safety Excellence Award, Kalinga Environment Excellence Award, National Safety Council of India Safety Award and Green Champions Award during FY2025-26.
No deviation in debenture proceeds. The statement of deviation or variation confirmed no deviation in the use of proceeds of listed non-convertible unsecured debentures, with ₹17,000 crore outstanding as on 30 June 2026 fully utilised for refinancing existing borrowings and/or funding capital expenditure. There was no default in payment of outstanding loans, revolving facilities or unlisted debt securities.
3. Key Risks
- Sustained negative LPG buffer: The cumulative net negative buffer of ₹29,729.95 crore as on 30 June 2026 represents a continuing exposure to the difference between market determined price and effective cost to customer, subject to future adjustment.
- Earnings volatility: The swing from profit to loss between Q1 FY2025-26 and Q1 FY2026-27, and the negative operating and net profit margins, indicate sensitivity of results to pricing and cost movements.
- Governance and compliance: The absence of the requisite number of Independent Directors and Non-Executive Directors, and the discontinuation of the Audit Committee and other committees from 28 March 2026, represent an ongoing compliance gap noted by the statutory auditors.
- Leverage and coverage: Rising debt-equity and sharply lower interest and debt service coverage ratios reduce financial headroom.
- Volume dependence: Lower domestic and export product sales and lower refinery throughput in the quarter affect scale economics.
- Working capital: Current ratios below one on both standalone and consolidated bases indicate a tight liquidity position.
- Project execution: The PX-PTA project, Bhadrak Textile Park and HEFA-SAF projects are ongoing or planned investments whose benefits depend on completion and commissioning.
- Unreviewed components: The standalone results include 24 joint operations where the company is not an operator (8 blocks relinquished), reflecting revenues of ₹872.46 crore and net profit before tax of ₹344.42 crore not reviewed by their auditors. The consolidated results include one subsidiary with total income of ₹29,376.45 crore and net profit of ₹1,031.35 crore reviewed by other auditors, and 10 subsidiaries with total income of ₹5,301.30 crore and net profit of ₹335.26 crore not reviewed by their auditors. Four joint ventures and one associate were not considered due to liquidation, closure or unavailability of financials.
4. Management Guidance Versus Observed Business Performance
LPG compensation guidance. MoPNG’s October 2025 letters approved ₹14,486 crore of compensation to be disbursed in 12 equal monthly instalments accruing monthly from November 2025. Observed performance: instalments for April to June 2026 aggregating ₹3,621.51 crore were recognised as Revenue from Operations, and the cumulative net negative buffer was reduced to that extent. The buffer nevertheless remained at a net negative ₹29,729.95 crore as on 30 June 2026.
Paradip PX-PTA project guidance. The press release states the 1.2 MMTPA PTA unit under the PX-PTA project is nearing completion. Observed performance: the project remains under execution, with ₹13,805 crore being invested, and no commissioning date is disclosed in the material.
Paradip investment guidance. The press release sets out planned investments of about ₹4,382 crore in the Bhadrak Textile Park Project and ₹1,064 crore in the HEFA-based SAF project. Observed performance: these are described as planned investments through joint ventures, with no completion or operational data provided.
Financial reporting guidance. The company’s 31 July 2026 filing confirmed the board meeting commenced at 03:00 PM and concluded at 05:40 PM, with results approved by the Board. Observed performance: the results were reviewed by the statutory auditors, but the Audit Committee had been discontinued from 28 March 2026, so the results were reviewed and approved by the Board instead of the Audit Committee.
Analyst call guidance. The company’s 7 August 2026 letter referred to a conference call with analysts held on 1 August 2026 to discuss Q1 FY2026-27 performance, with transcripts made available on the company website. No forward-looking statements from that call are contained in the supplied material.
Dividend and AGM. The company held its 67th Annual General Meeting on 31 August 2026, where all 9 proposed resolutions were passed with the requisite majority, including declaration of a final dividend of ₹1.25 per equity share for the year 2025-26, approval of financial statements, director appointments, and material related party transactions.
Broker Narrative
The narrative shifted from a bullish Accumulate thesis in 2023—anchored on supernormal marketing margins, strong GRMs, and volume growth—to a cautious Overweight in 2026 where the same structural themes inverted: crude price volatility became the US-Iran conflict, supernormal marketing margins turned into severe under-recoveries, and strong GRMs were suppressed by government RTP caps and SAED duties. Persistent fears around crude sensitivity and marketing margin vulnerability ultimately dominated, while early tailwinds like petrochemical recovery and volume-driven growth faded entirely from the later narrative.
Fears that came true
- Higher crude oil prices/volatility risk materialized as the US-Iran conflict severely impacted OMC profitability, driving an expected net sector loss of INR72.9bn in Q1FY27, correlating with DISAPPOINTMENT outcomes in mid-2024 and early 2026.
- Marketing margin moderation fears fully materialized—SAED export duties, RTP caps, and massive MS/HSD/LPG under-recoveries wiped out OMC marketing margins, causing expected EBITDA losses of INR200bn for IOCL alone amid sector-wide distress.
- Inventory loss concerns flagged in Q4FY23 (US$4.4/bbl product and US$4.8/bbl crude losses) persisted, with the last report confirming inventory losses expected to weigh on refining earnings.
- Delayed Barauni (3 MMTPA) and Koyali (4.3 MMTPA) capacity additions did not contribute to growth as hoped, with no mention of refining capacity expansion benefiting earnings by the last report.
Optimism that failed
- Supernormal near-term marketing margins on diesel (Rs 14.8/lt) and petrol (Rs 13.0/lt) expected to drive EBITDA growth were completely wiped out by MS/HSD under-recoveries and SAED export duties.
- Strong GRMs of US$15.3/bbl (core US$20.0/bbl) compressed drastically as GoI capped domestic RTP and SAED prevented refiners from benefiting from elevated global cracks (BPCL GRM fell from US$18.0/bbl to US$7.7/bbl QoQ).
- Petrochemical recovery (volumes up 81% QoQ, EBIT margin turning positive to US$53/ton) did not sustain; the last report makes no mention of petrochem tailwinds amid sector-wide losses.
- Volume growth and market share expansion (petrol +350 bps, diesel +540 bps YoY) were overshadowed by massive sector EBITDA losses, with OMCs collectively expected to lose over INR500bn in Q1FY27.
Broker Timeline
30 broker calls · 2023-05-16 to 2026-07-08
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.