INNOVACAP
Equity Metrics
November 16, 2026
Innova Captab Limited
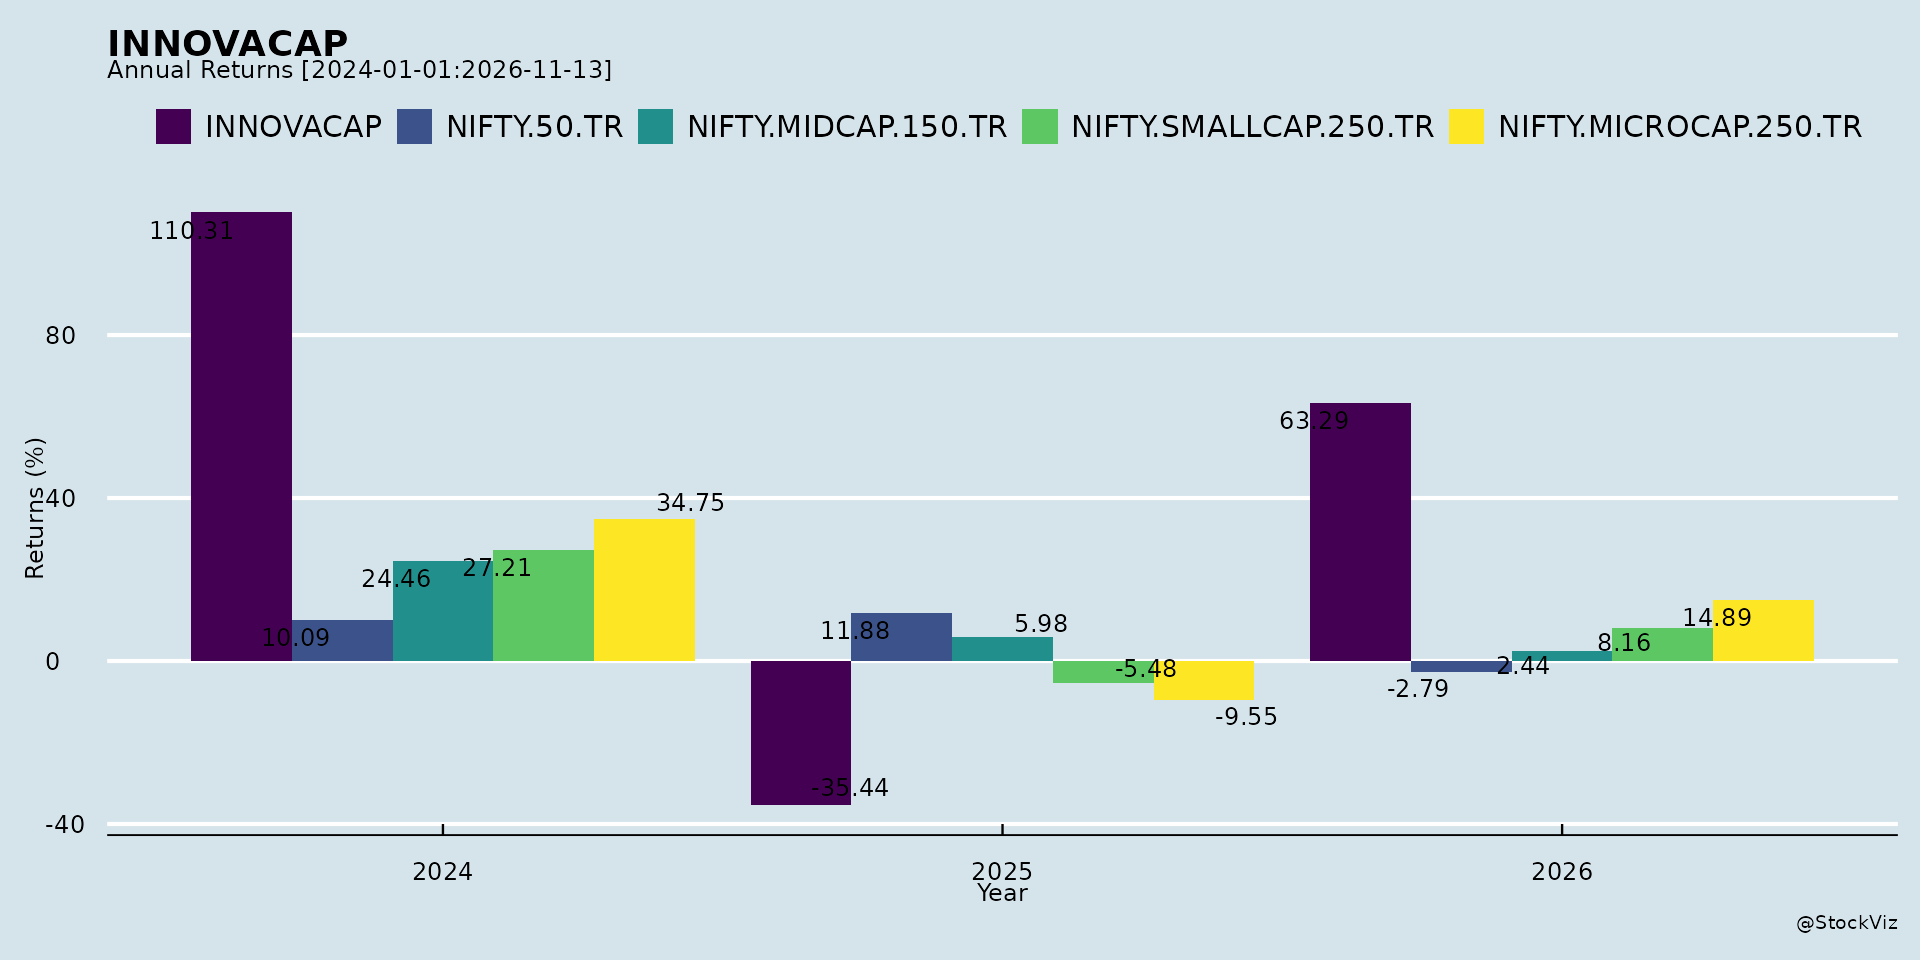
Annual Returns
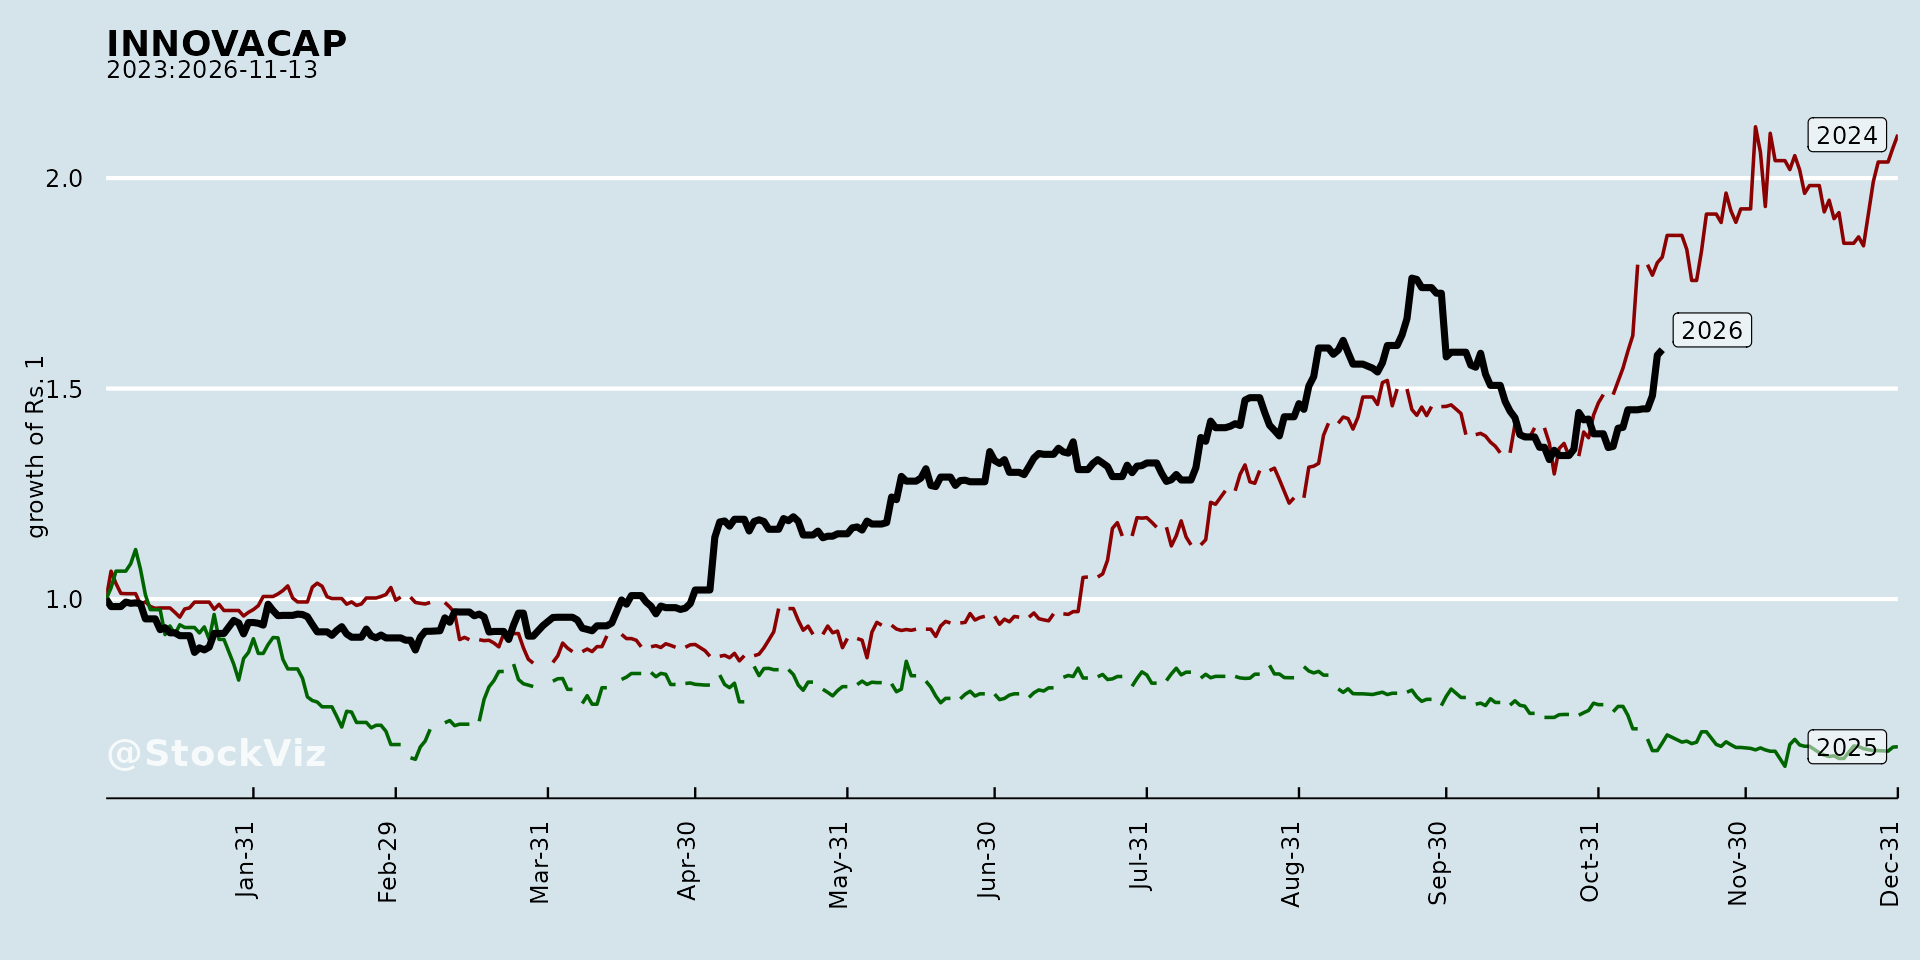
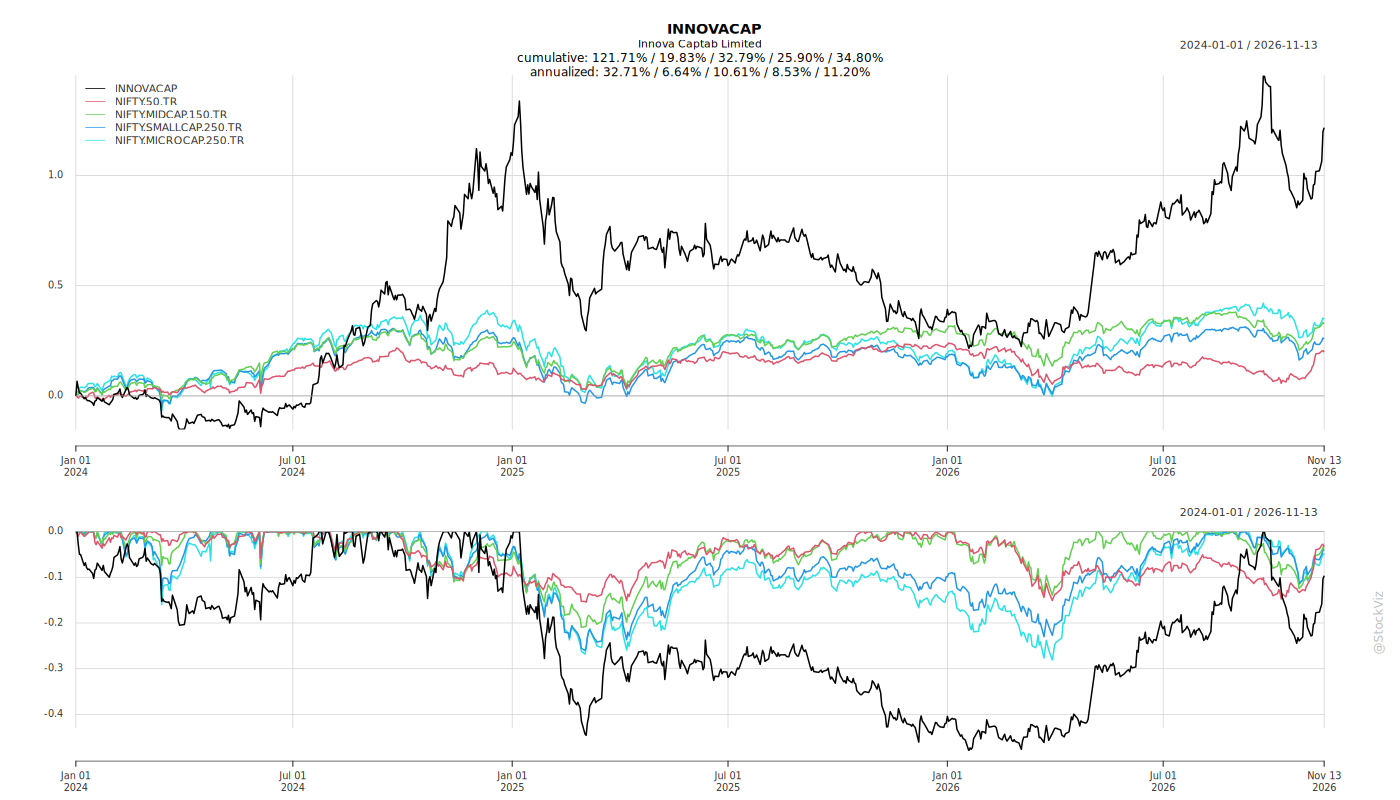
Cumulative Returns and Drawdowns
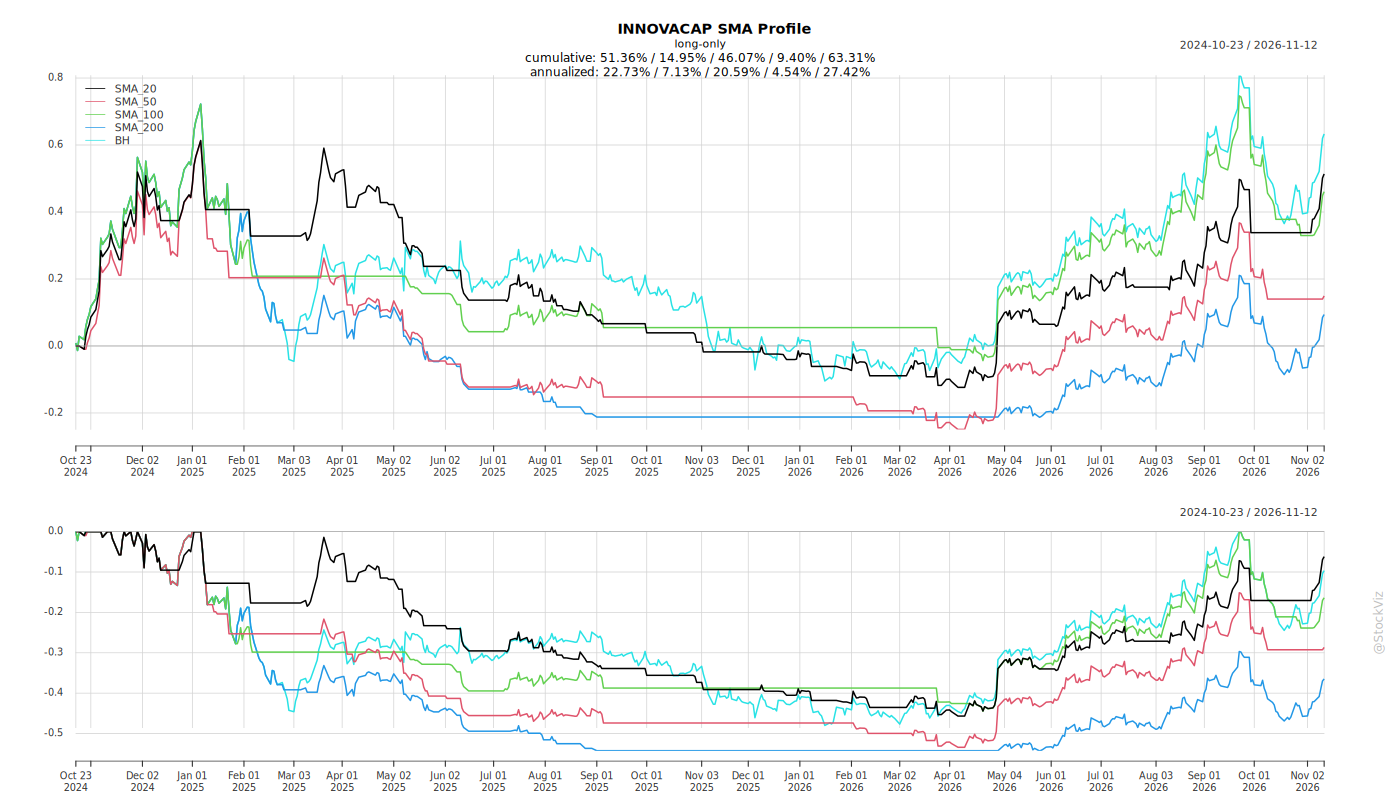
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-17
Innova Captab Limited — Recent Corporate Developments
Headwinds and Challenges
The company operates in a pharmaceutical landscape marked by pricing pressures and dynamic regulatory shifts. Trade policy volatility and fiscal and financial vulnerabilities across major economies add further uncertainty. Geopolitical tensions, including those involving Iran and the US, are cited as sources of commodity price volatility and supply chain disruption. The business also carries reliance on key raw material suppliers and exposure to raw material price fluctuations, alongside compliance and regulatory risk, legal and litigation risk, and operational risks tied to maintaining product quality and safety. Cyber security and data privacy threats, as well as environmental impact and climate change risks, are also identified.
On the earnings side, risks include fluctuations in earnings, the ability to manage growth, domestic and international competition, economic growth conditions in India and abroad, the ability to attract and retain highly skilled professionals, time and cost overruns on contracts, the ability to manage international operations, government policies and regulatory actions, and interest and other fiscal costs.
Tailwinds and Growth Prospects
The company points to strong macroeconomic resilience and high GDP growth in India, rising domestic healthcare needs and disease burden, and increasing global preference for outsourcing contract manufacturing. The global CDMO market is projected to reach USD 580.72 billion by CY 2034, and the Indian CDMO market is projected to reach USD 71.14 billion by CY 2035. Patent expiries of major drugs, such as GLP-1 drugs like semaglutide and liraglutide, are cited as opportunities. Supportive government policies include the New Central Sector Scheme providing GST-linked incentives and capital interest subventions.
Operationally, growth is supported by a portfolio of over 4,200 products, CDMO customers across the globe, a network of 2,50,000+ touchpoints in India, a presence across 60+ countries, and the commercialization of the manufacturing facility in Kathua, Jammu, alongside strategic expansion and capital allocation. The company operates a dual-engine model spanning CDMO services and branded generics across 9 manufacturing blocks and 5 units, serving 350+ customers across 60+ countries.
Key Risks
The identified risks span pricing and regulatory shifts, trade policy volatility, macroeconomic fiscal and financial vulnerabilities, geopolitical tensions affecting commodities and supply chains, raw material supplier reliance and price fluctuations, compliance and regulatory exposure, legal and litigation exposure, operational risks around product quality and safety, cyber security and data privacy threats, and environmental and climate-related risks. Additional risks include earnings fluctuations, growth management, competition both domestic and international, dependence on economic conditions in India and abroad, retention of skilled professionals, contract time and cost overruns, international operations management, government policy and regulatory actions, and interest and other fiscal costs.
Management Guidance Versus Observed Performance
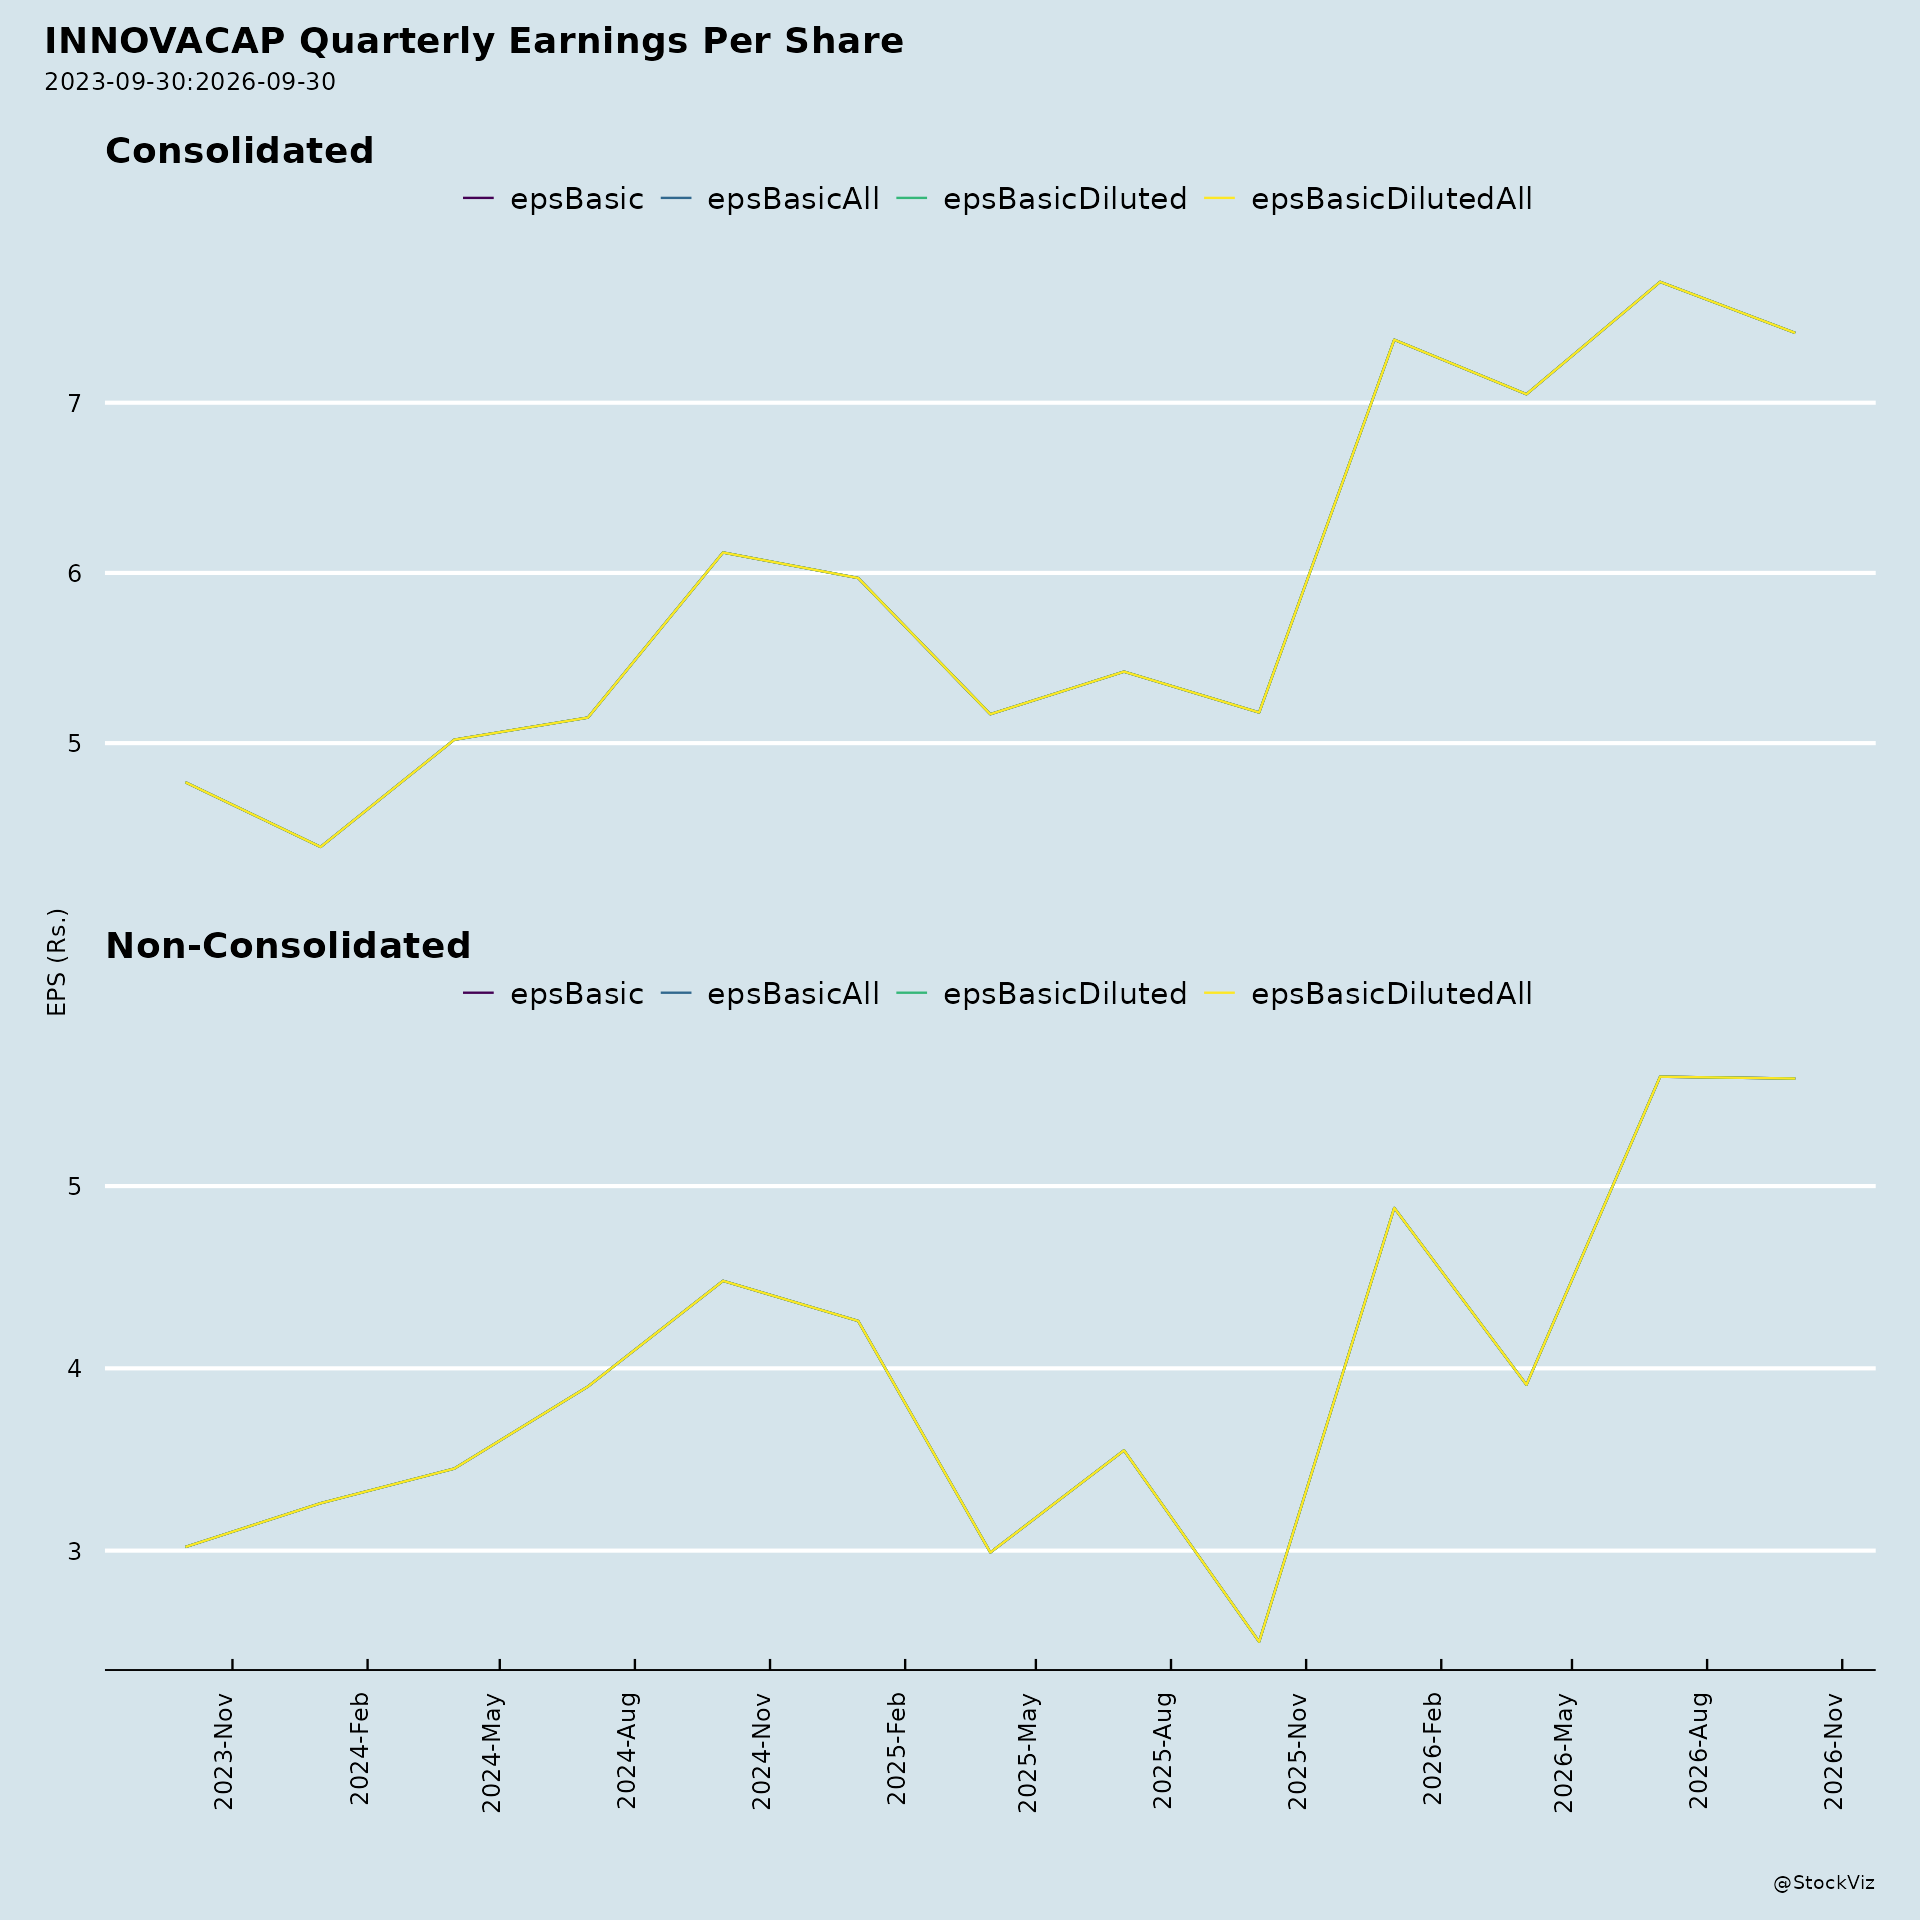
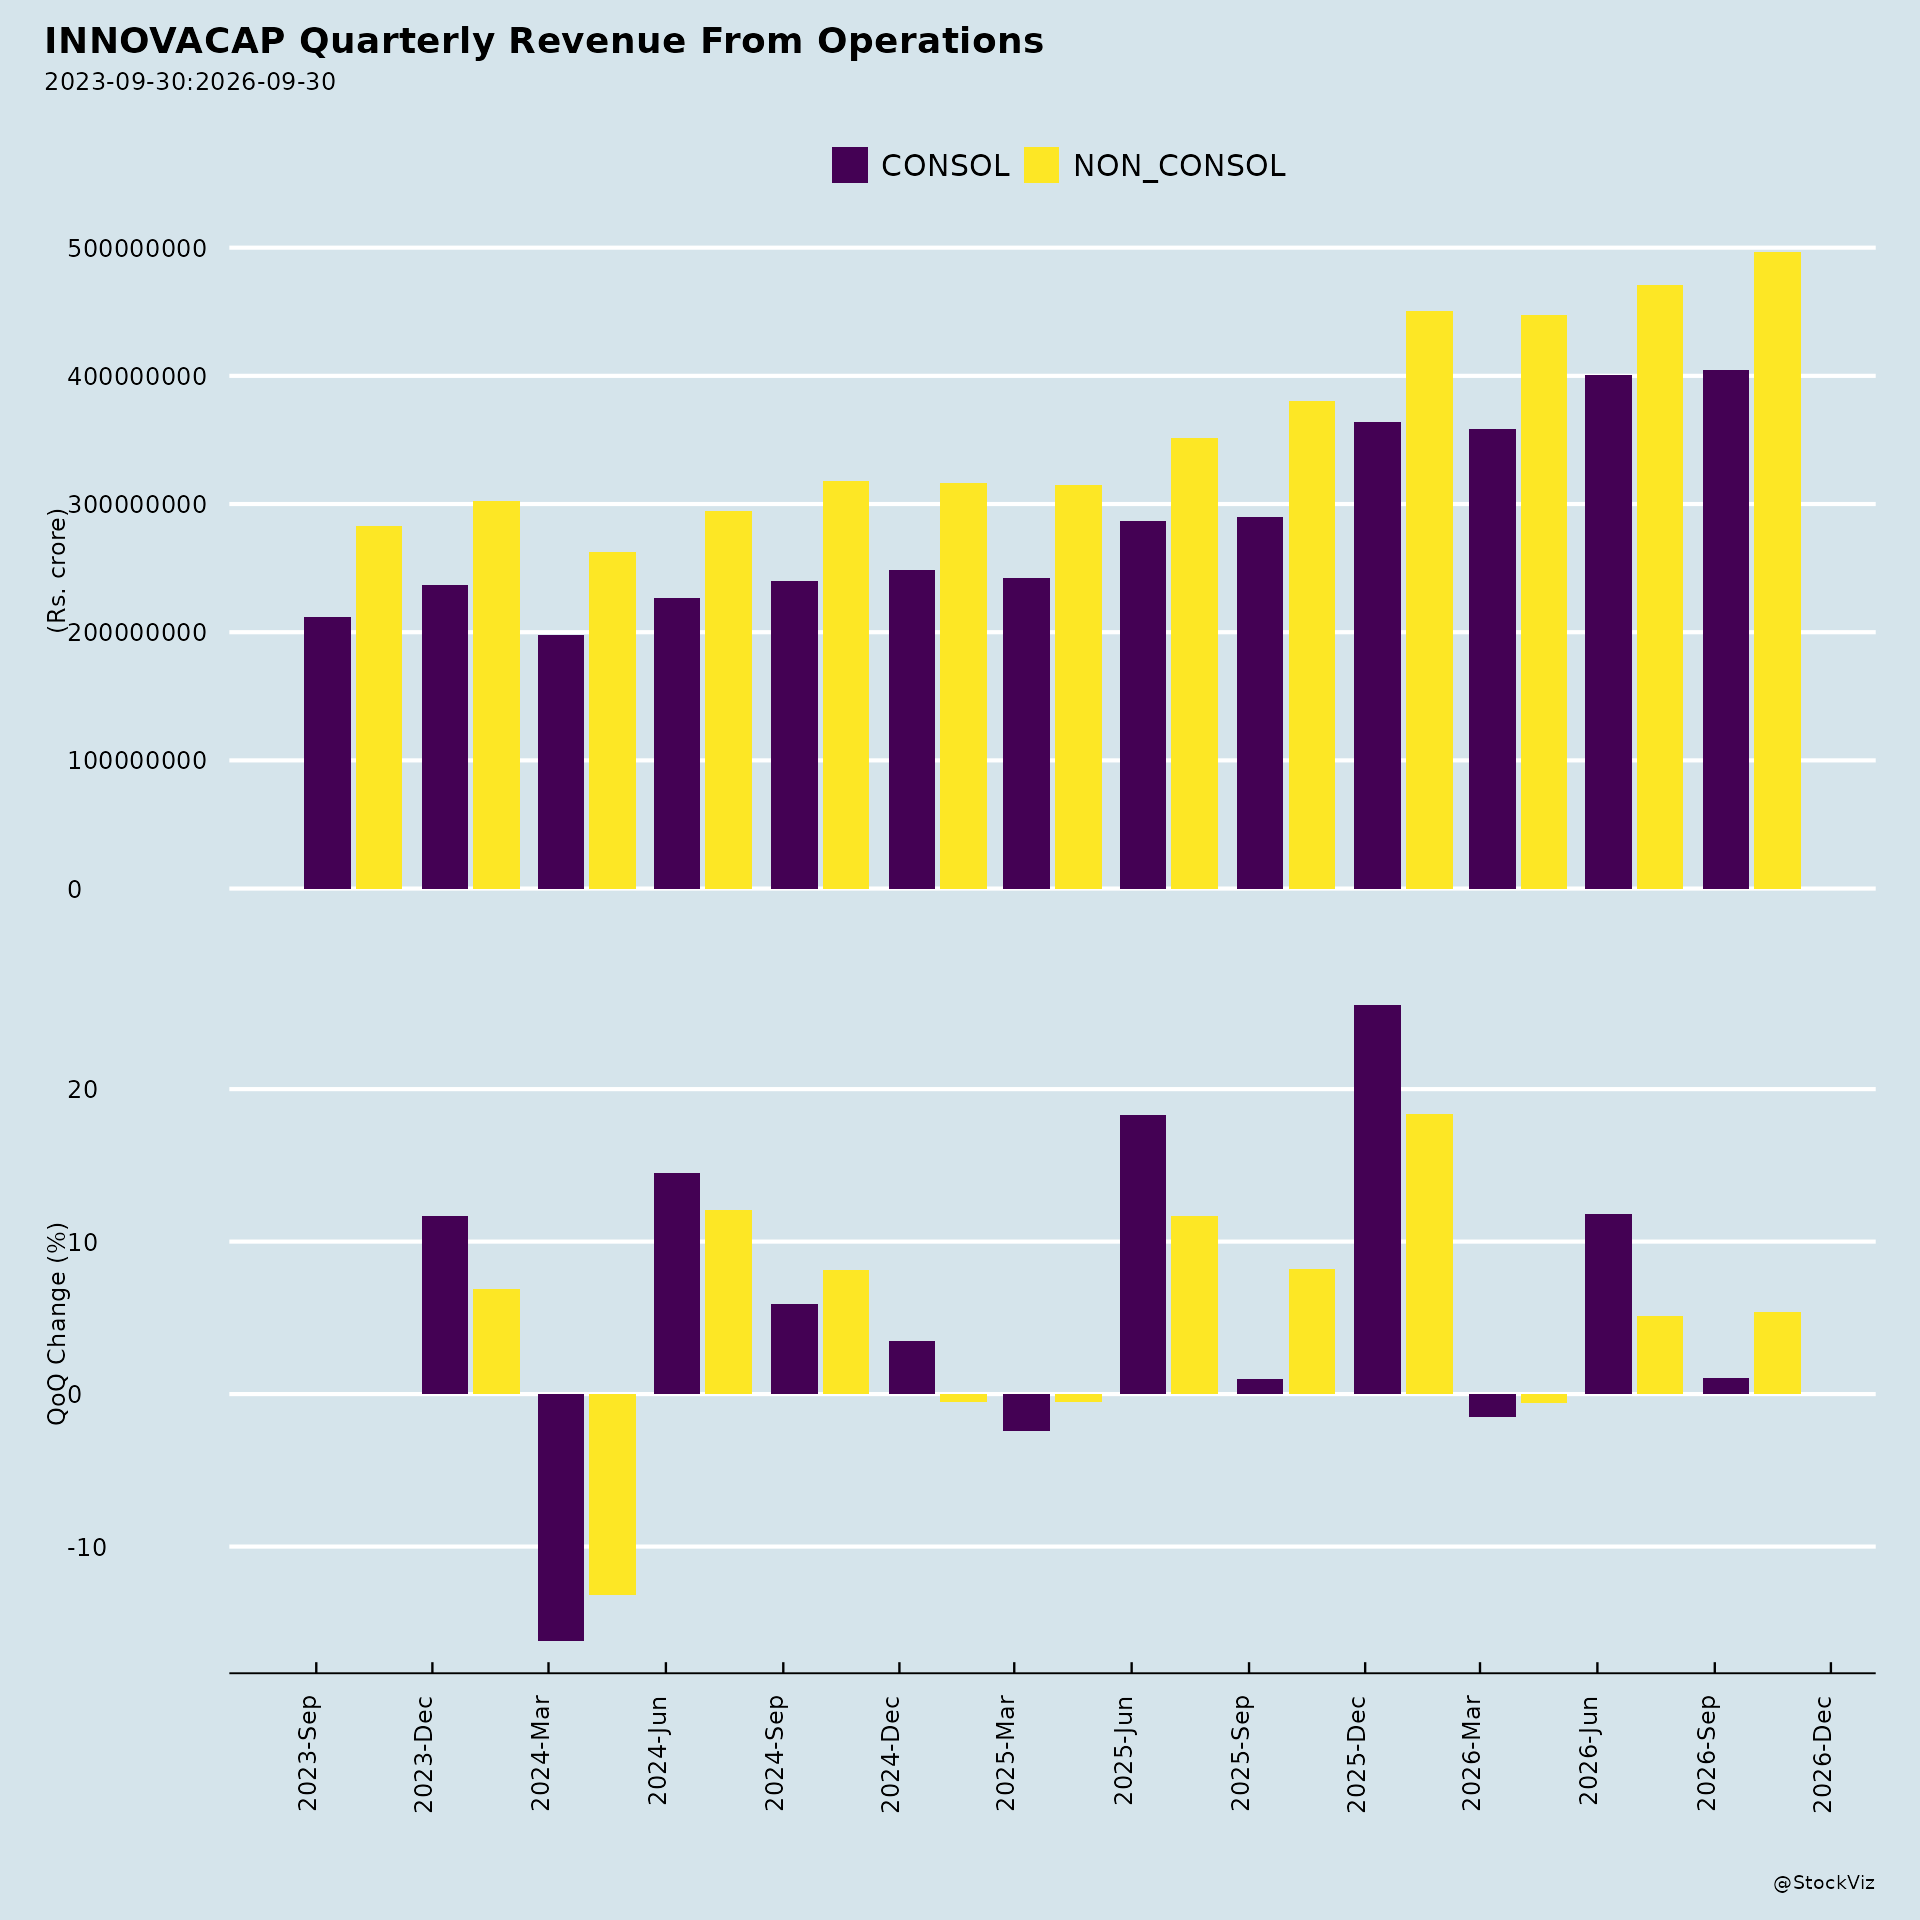
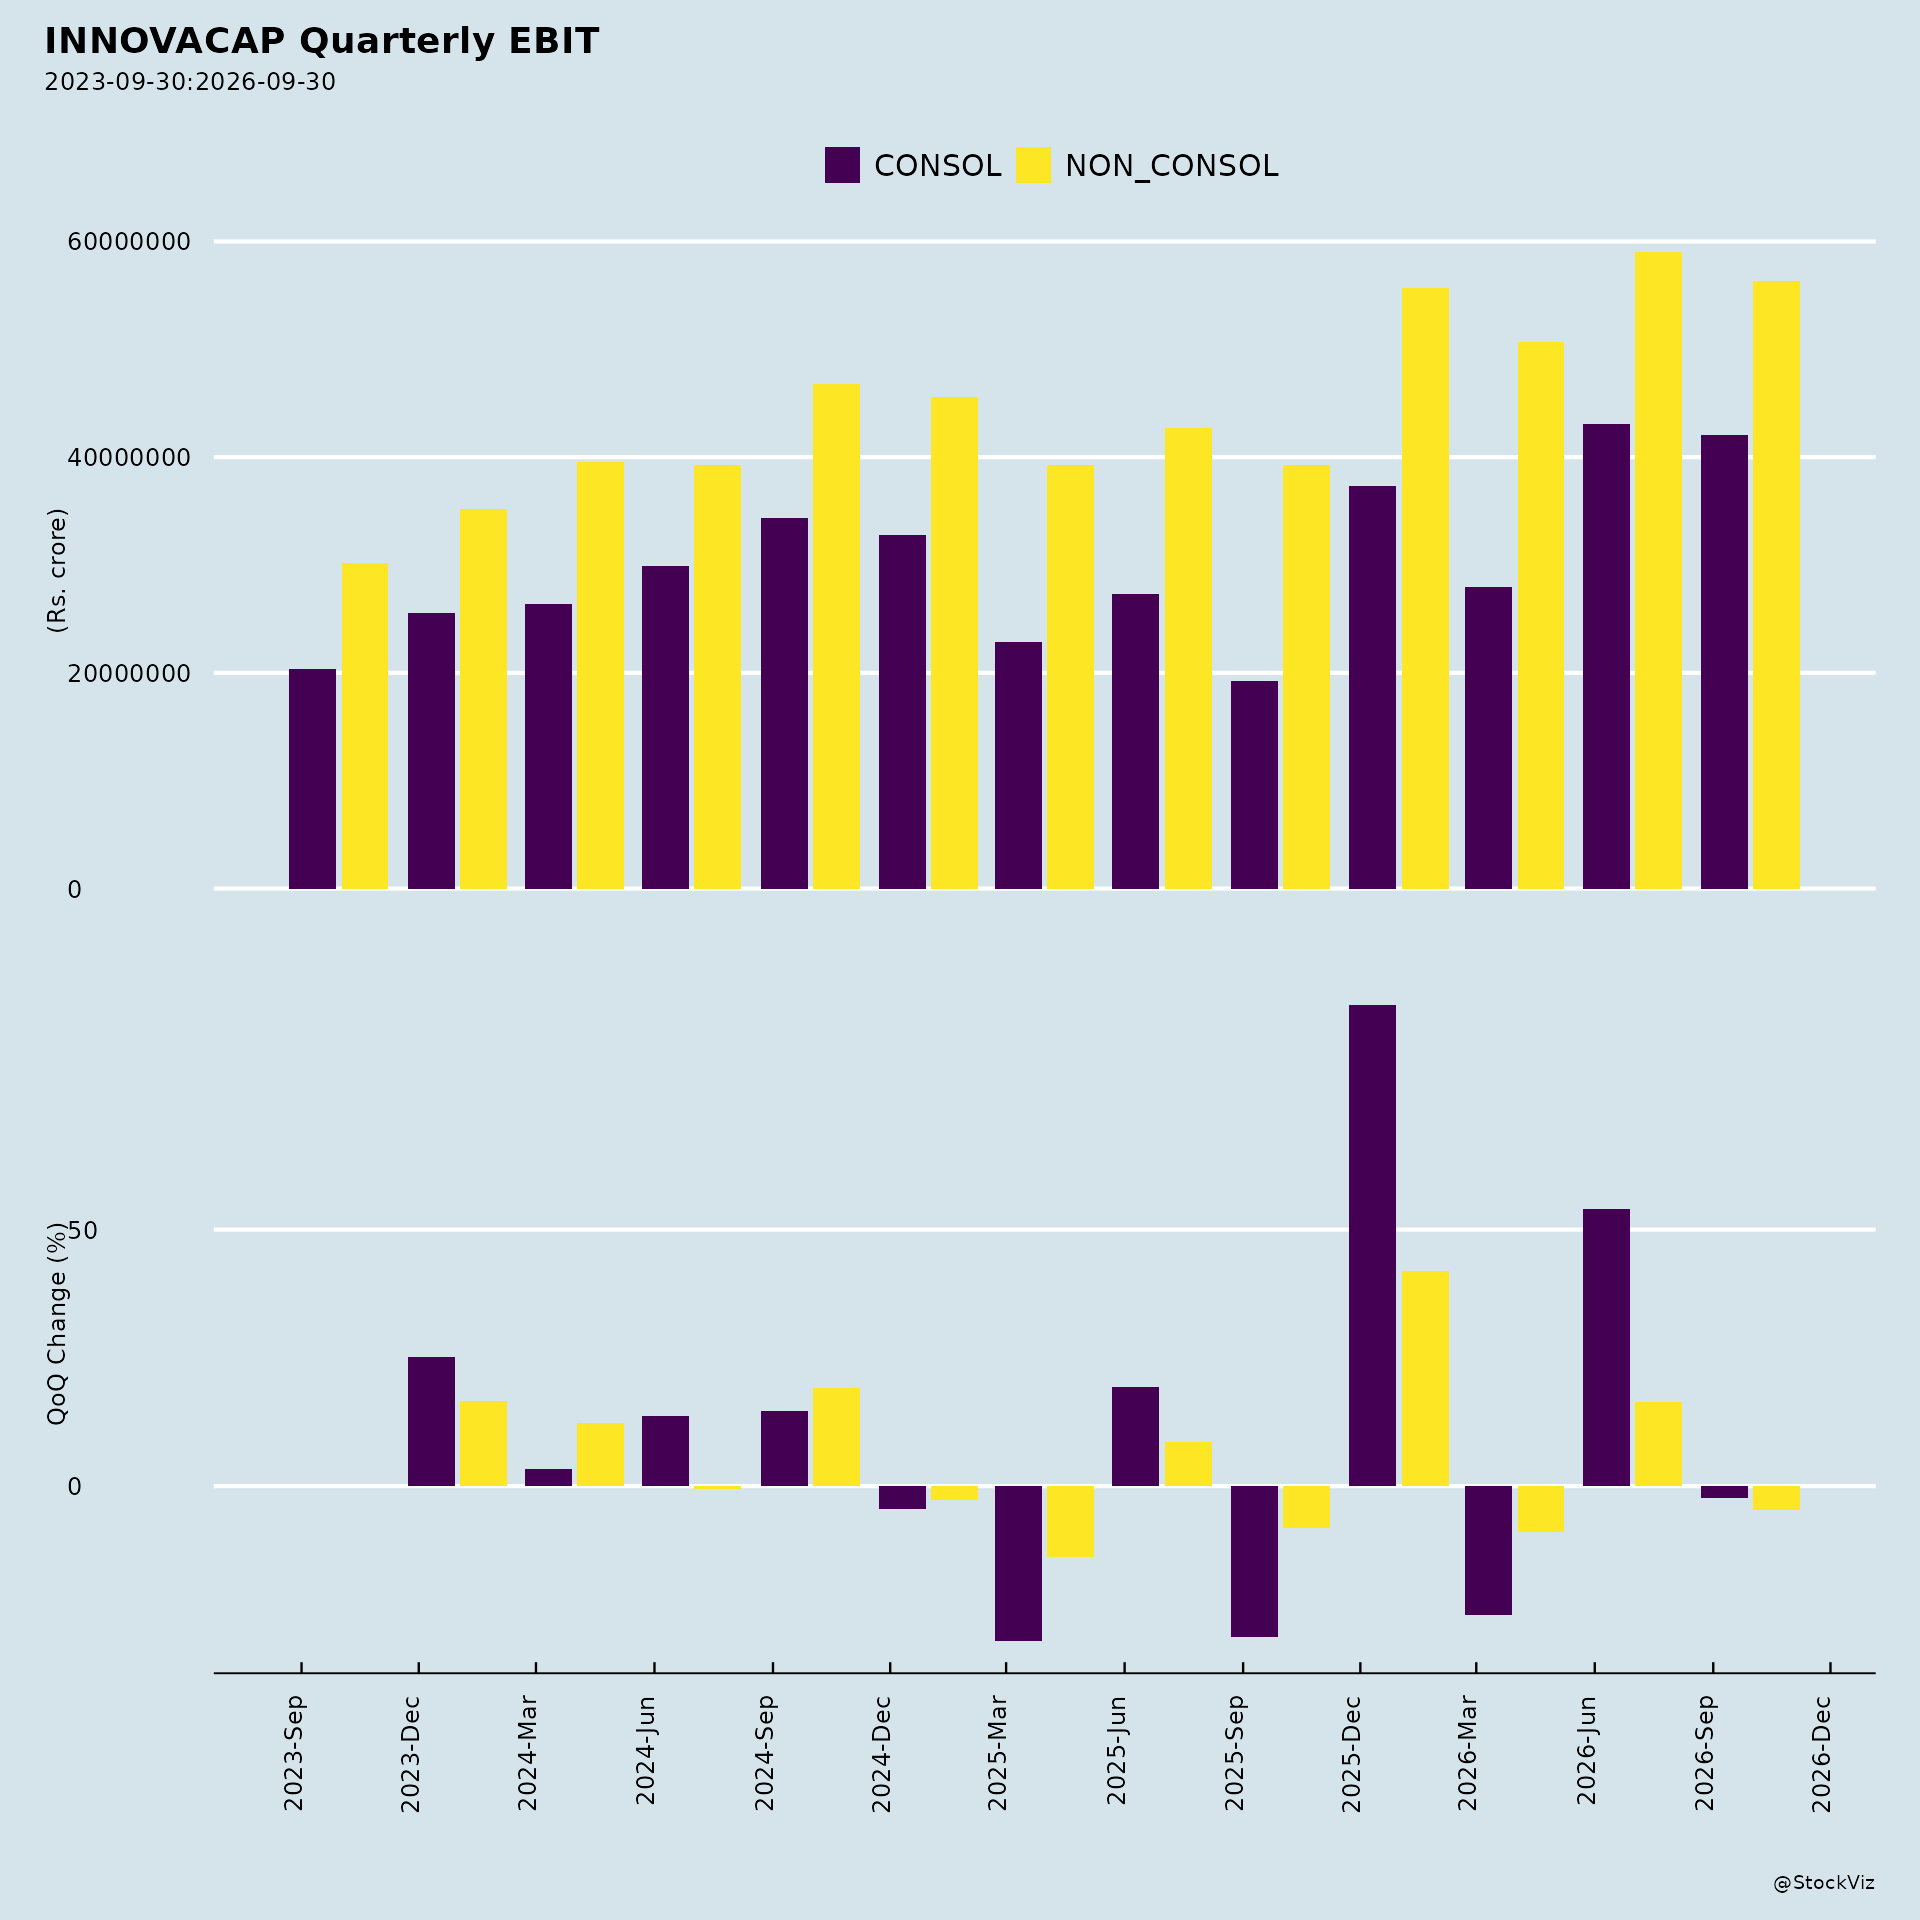
For Q1 FY27, management reported revenue from operations of ₹470.9 crores, up 34.0% from ₹351.5 crores in Q1 FY26, and EBITDA of ₹75.1 crores, up 32.7% from ₹56.6 crores, with EBITDA margin at 16.0% versus 16.1%. PAT for the quarter was ₹44.1 crores, up 42.3%, with a PAT margin of 9.4%. Management stated that growth during the quarter was supported by steady order flows, a broader product portfolio, and deeper engagement with existing and new customers, and that the Jammu facility is witnessing a steady ramp-up supported by increasing business from existing customers and onboarding of new clients.
For FY26, revenue from operations reached ₹1,630.02 crores (31.1% YoY growth), EBITDA increased 26.3% to ₹250.34 crores with a 15.4% margin, PAT stood at ₹143.18 crores (12.5% increase), and EPS rose to ₹25.02. Return metrics were ROCE of 14.6% and ROE of 13.2%. A separate summary cites FY26 revenues of ₹1,630 Cr, EBITDA of ₹250 Cr (15.4%), PAT of ₹141 Cr (8.6%), and ROCE of 14.5%.
Management guidance emphasizes strengthening manufacturing capabilities, improving capacity utilization and operational efficiencies—particularly with the ramp-up of the Kathua, Jammu facility to benefit from operating leverage—deepening client relationships, expanding the product portfolio and branded generics footprint, strengthening complex R&D and dosage capabilities to move up the value chain, and delivering consistent performance and long-term value creation in alignment with Vision 2027 and beyond. Management expressed confidence in sustaining growth while enhancing profitability.
Other Recent Developments
The Board of Directors met on September 3, 2026, from 08:01 to 08:19 hours IST, and accorded in-principle approval for the acquisition of land with an estimated investment of approximately ₹50,00,00,000 (Rupees Fifty Crore only). The company stated it will update once the final purchase/sale agreement is executed and will intimate details under regulation 30 of the Listing Regulations read with the Master Circular dated January 30, 2026, upon occurrence of the event.
Representatives of Innova Captab Limited will attend the Anand Rathi Annual Flagship Conference G-200 Summit 2026 on Monday, 21st September 2026, starting at 10:00 A.M. IST in Mumbai for 1x1 and group meetings with investors and analysts, with discussions based strictly on publicly available information and no Unpublished Price Sensitive Information shared.
The 22nd Annual General Meeting is scheduled for Wednesday, 30th September 2026, at 11:00 A.M. IST via Video Conference or Other Audio Visual Means. The cut-off date for e-Voting is Wednesday, 23rd September 2026, with e-Voting from Sunday, 27th September 2026 (09:00 A.M. IST) to Tuesday, 29th September 2026 (05:00 P.M. IST).
Broker Narrative
The first report was a cautious Add, focused on US gRevlimid/generic pricing pressure, regulatory plant issues and acute respiratory weakness as earnings risks, while leaning on RoW/India growth and stable US supplies. By the last report, the narrative upgraded to Buy and largely dropped the US gRevlimid pricing fear, replacing it with API price volatility and Jammu ramp-up risks. The core optimism shifted to structural domestic consolidation under Schedule M, Jammu capacity scaling, and export/quality certifications, while operating leverage and India/RoW growth remained persistent positive threads.
Broker Timeline
2 broker calls · 2025-06-08 to 2026-07-08
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.