IGL
Equity Metrics
September 24, 2026
Indraprastha Gas Limited
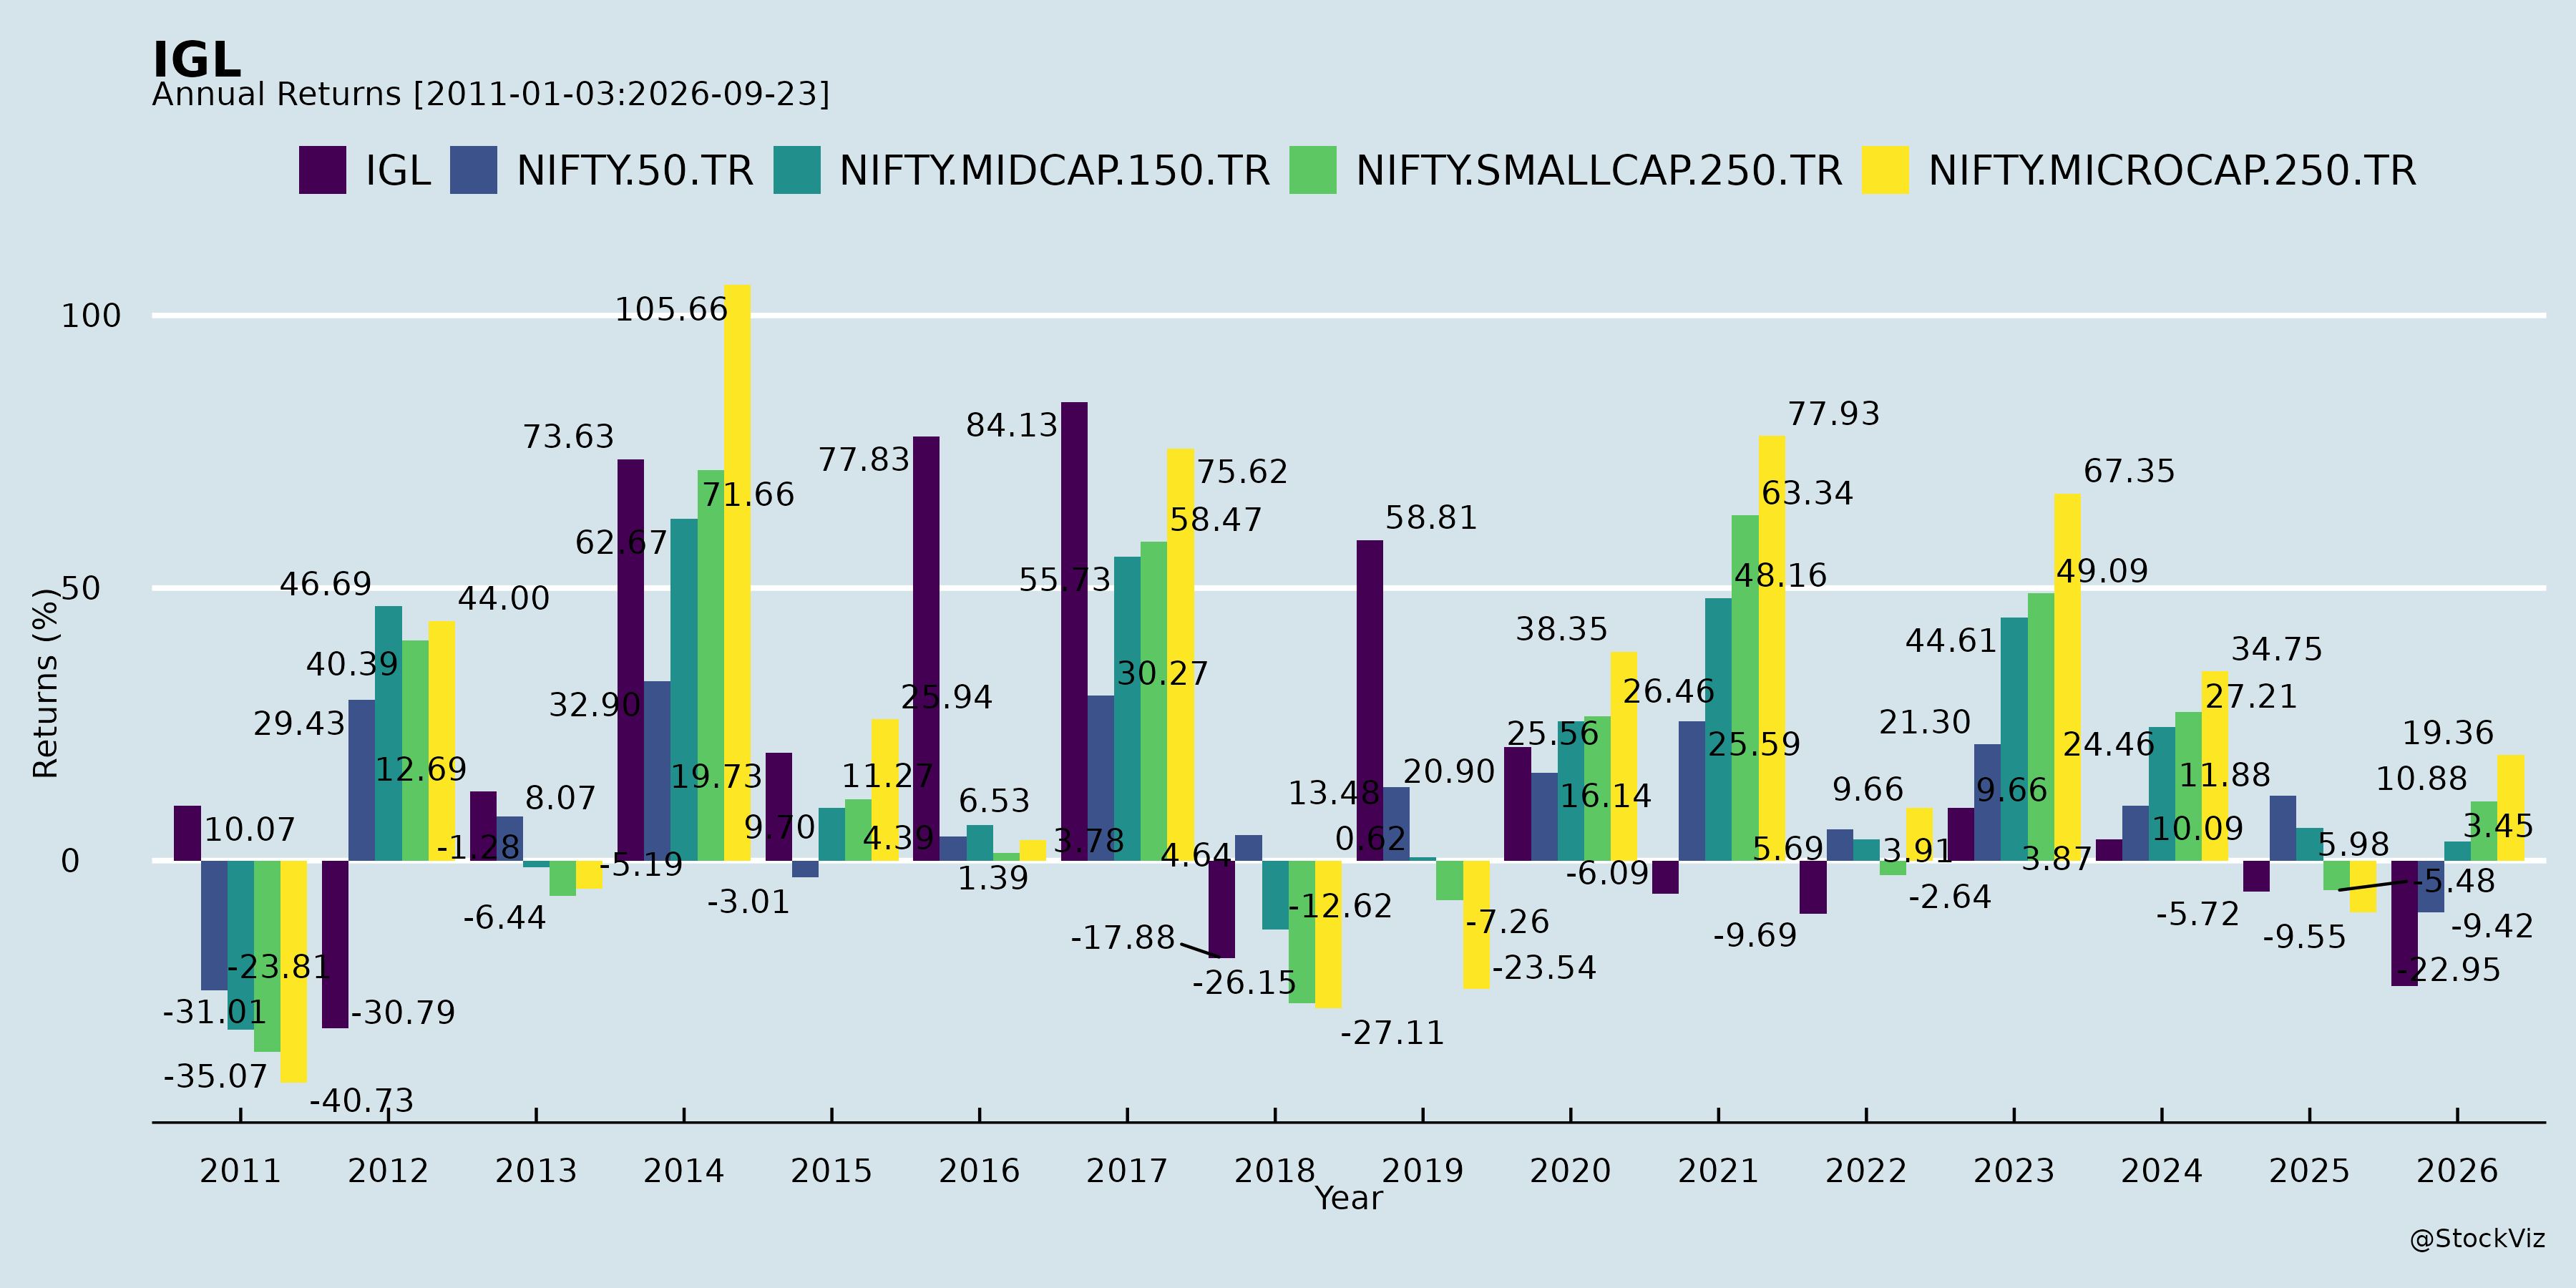
Annual Returns
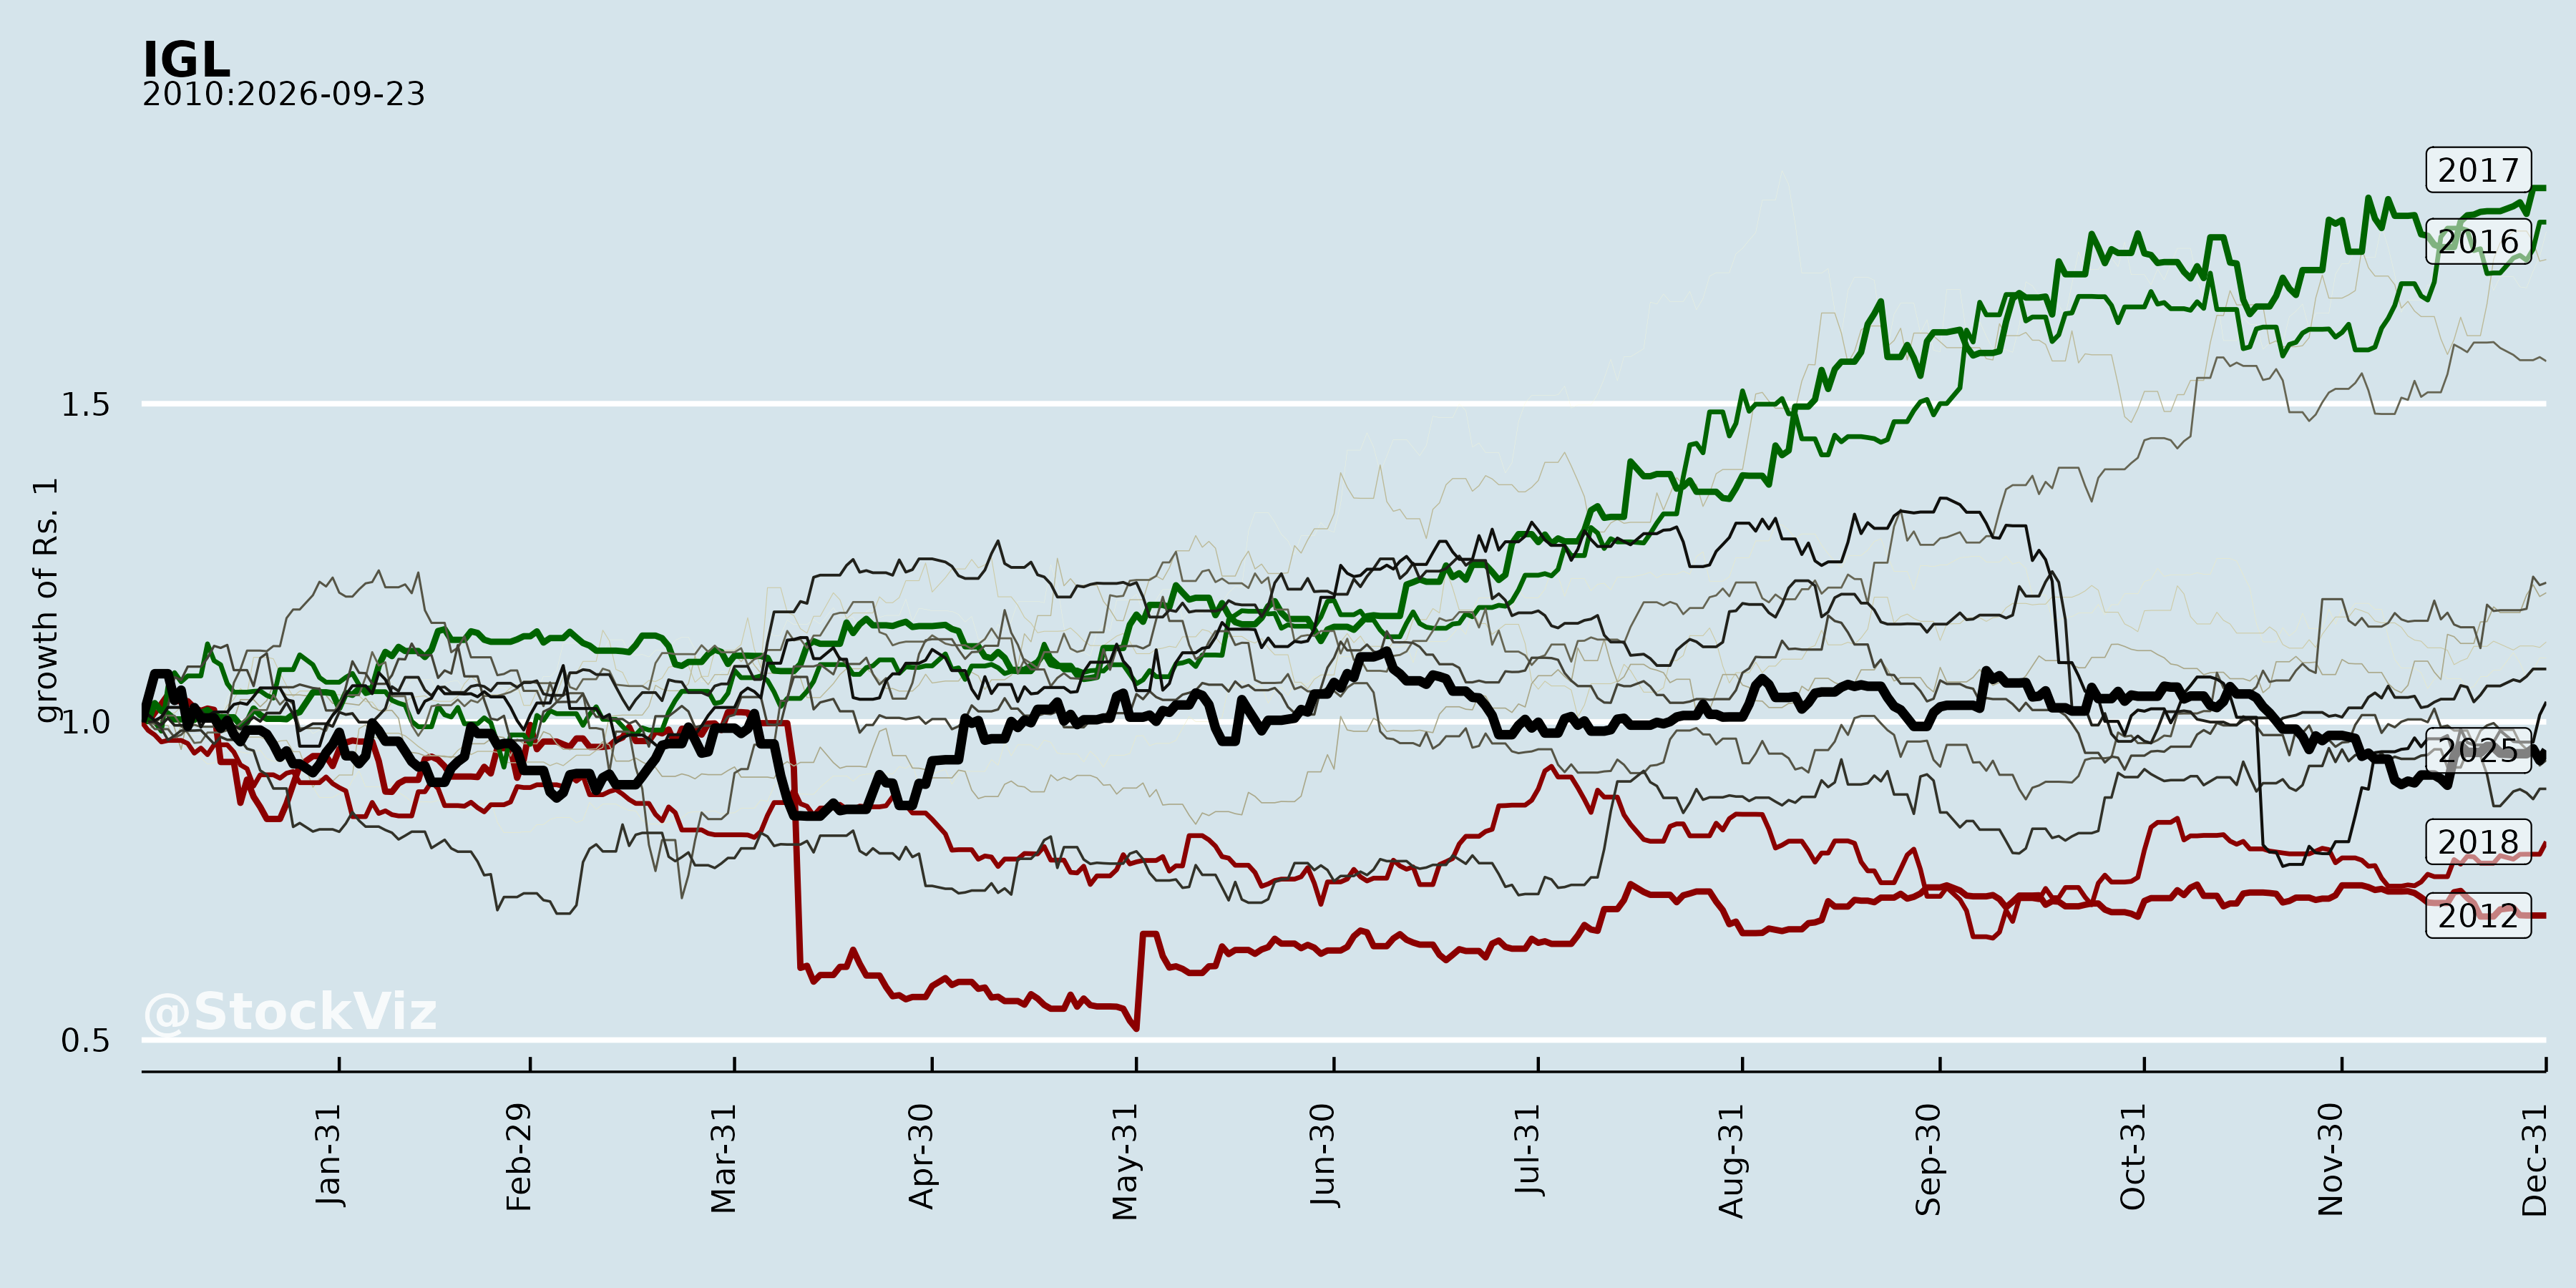
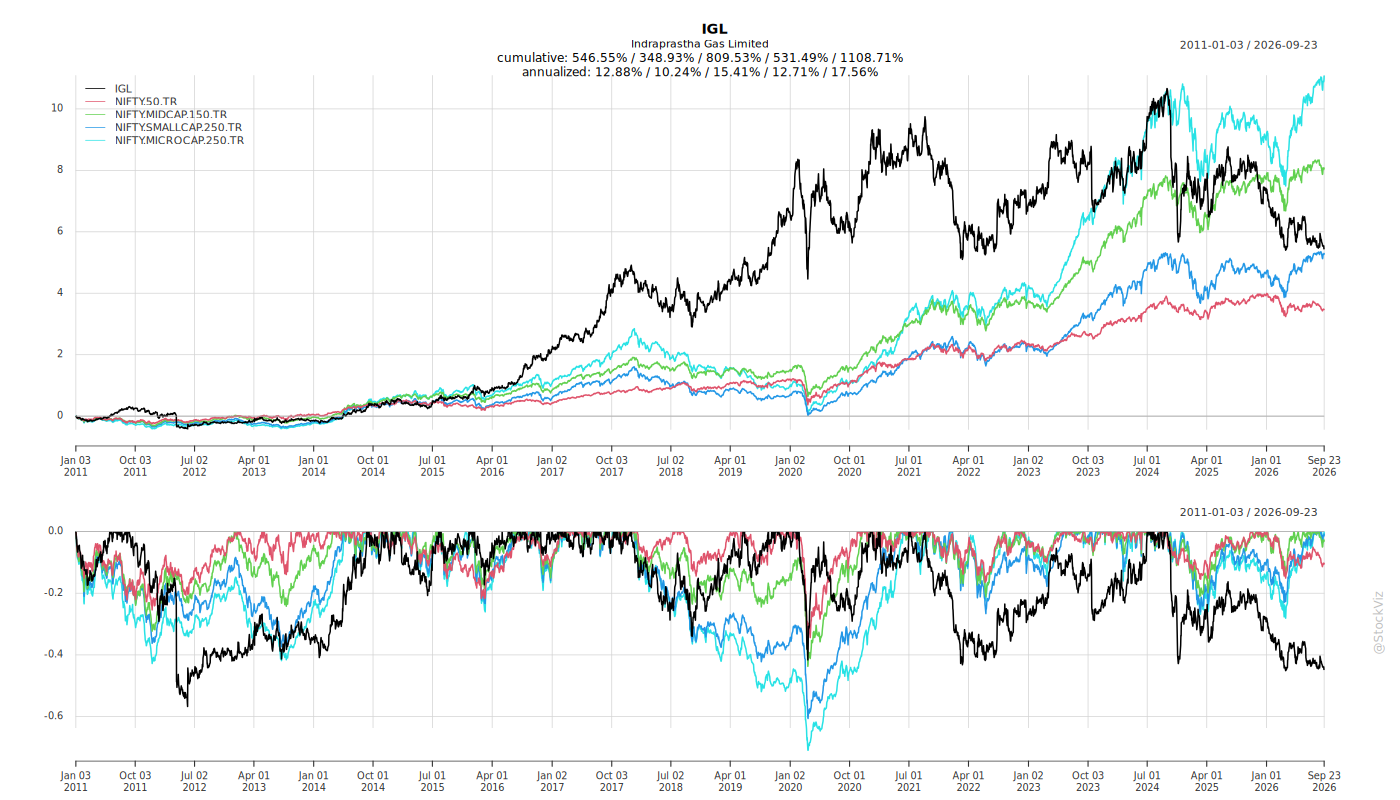
Cumulative Returns and Drawdowns
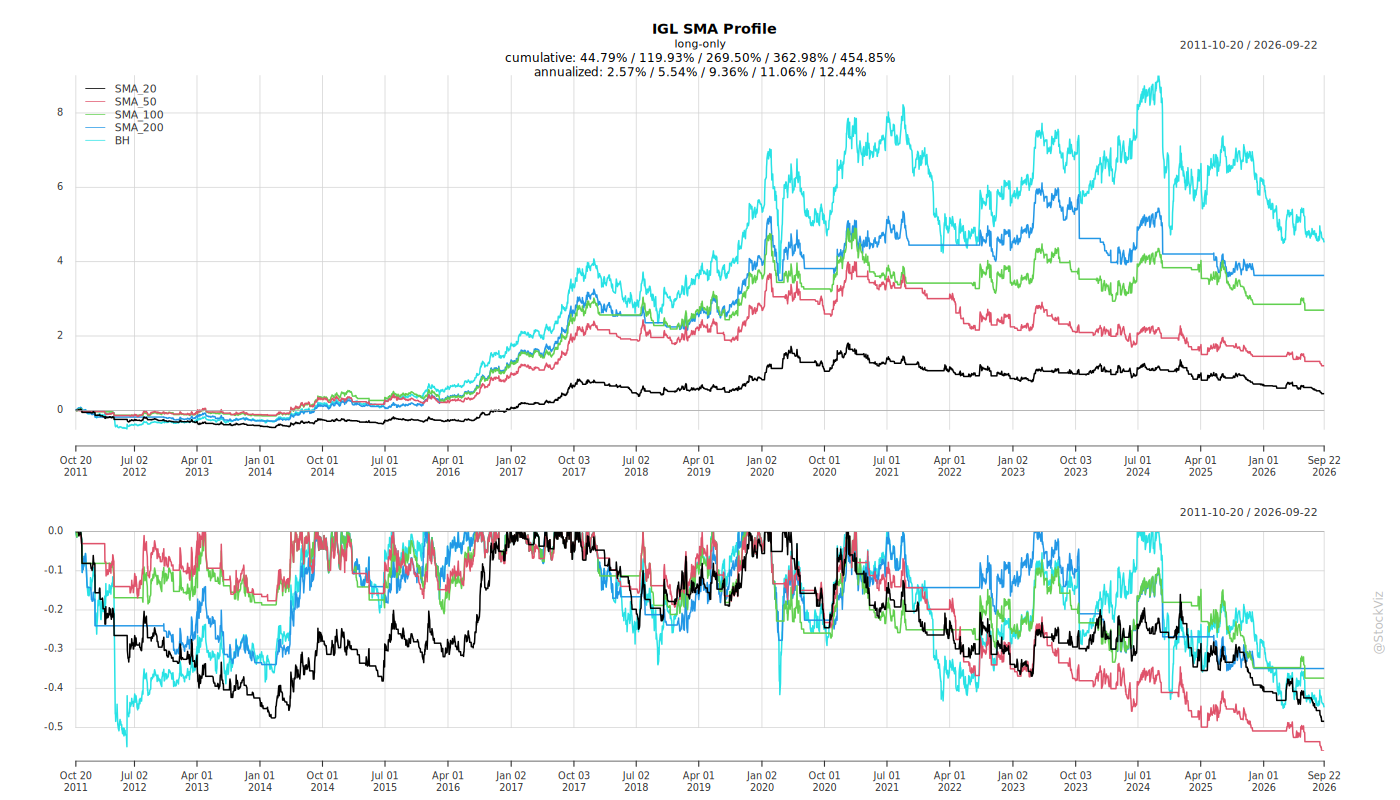
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
IGL: Recent Corporate Announcements Summary
Headwinds and Challenges
- Regulatory cost demand: The Delhi Development Authority (DDA) raised a demand of Rs. 330.73 crores (excluding interest) for increased license fees for the period up to March 2016. The company considers this demand not tenable and has reported it as a Contingent Liability.
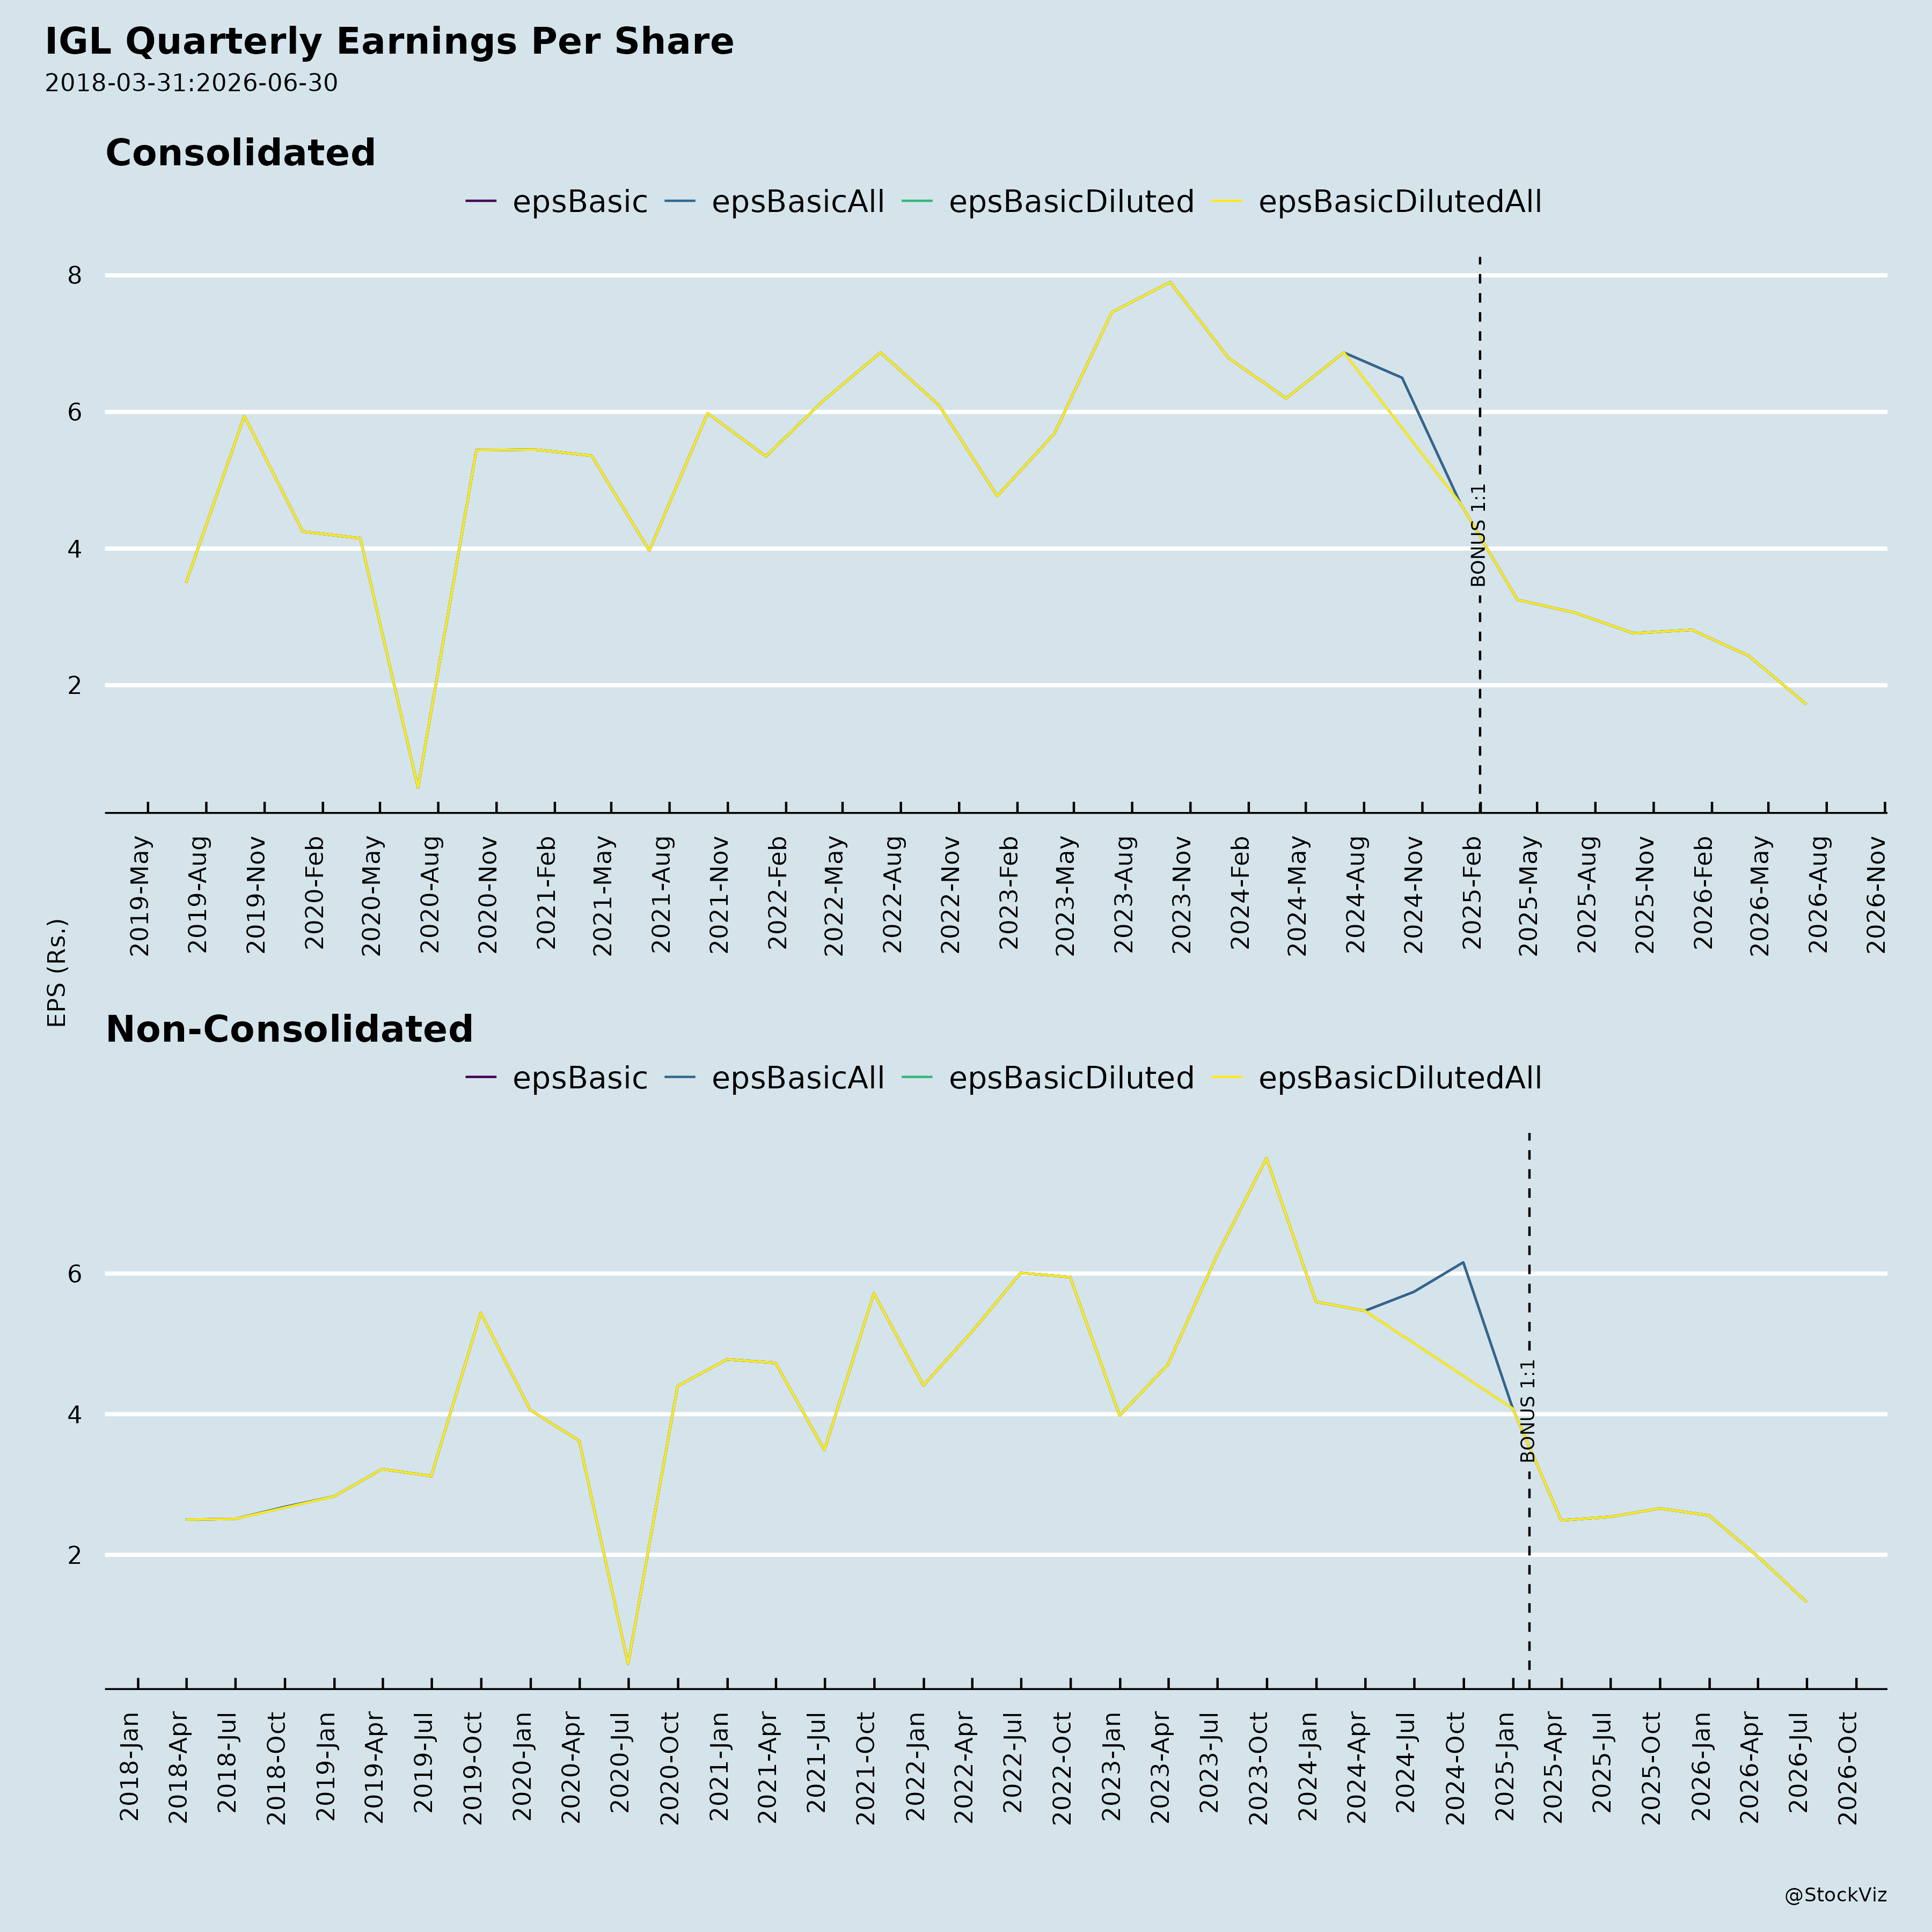
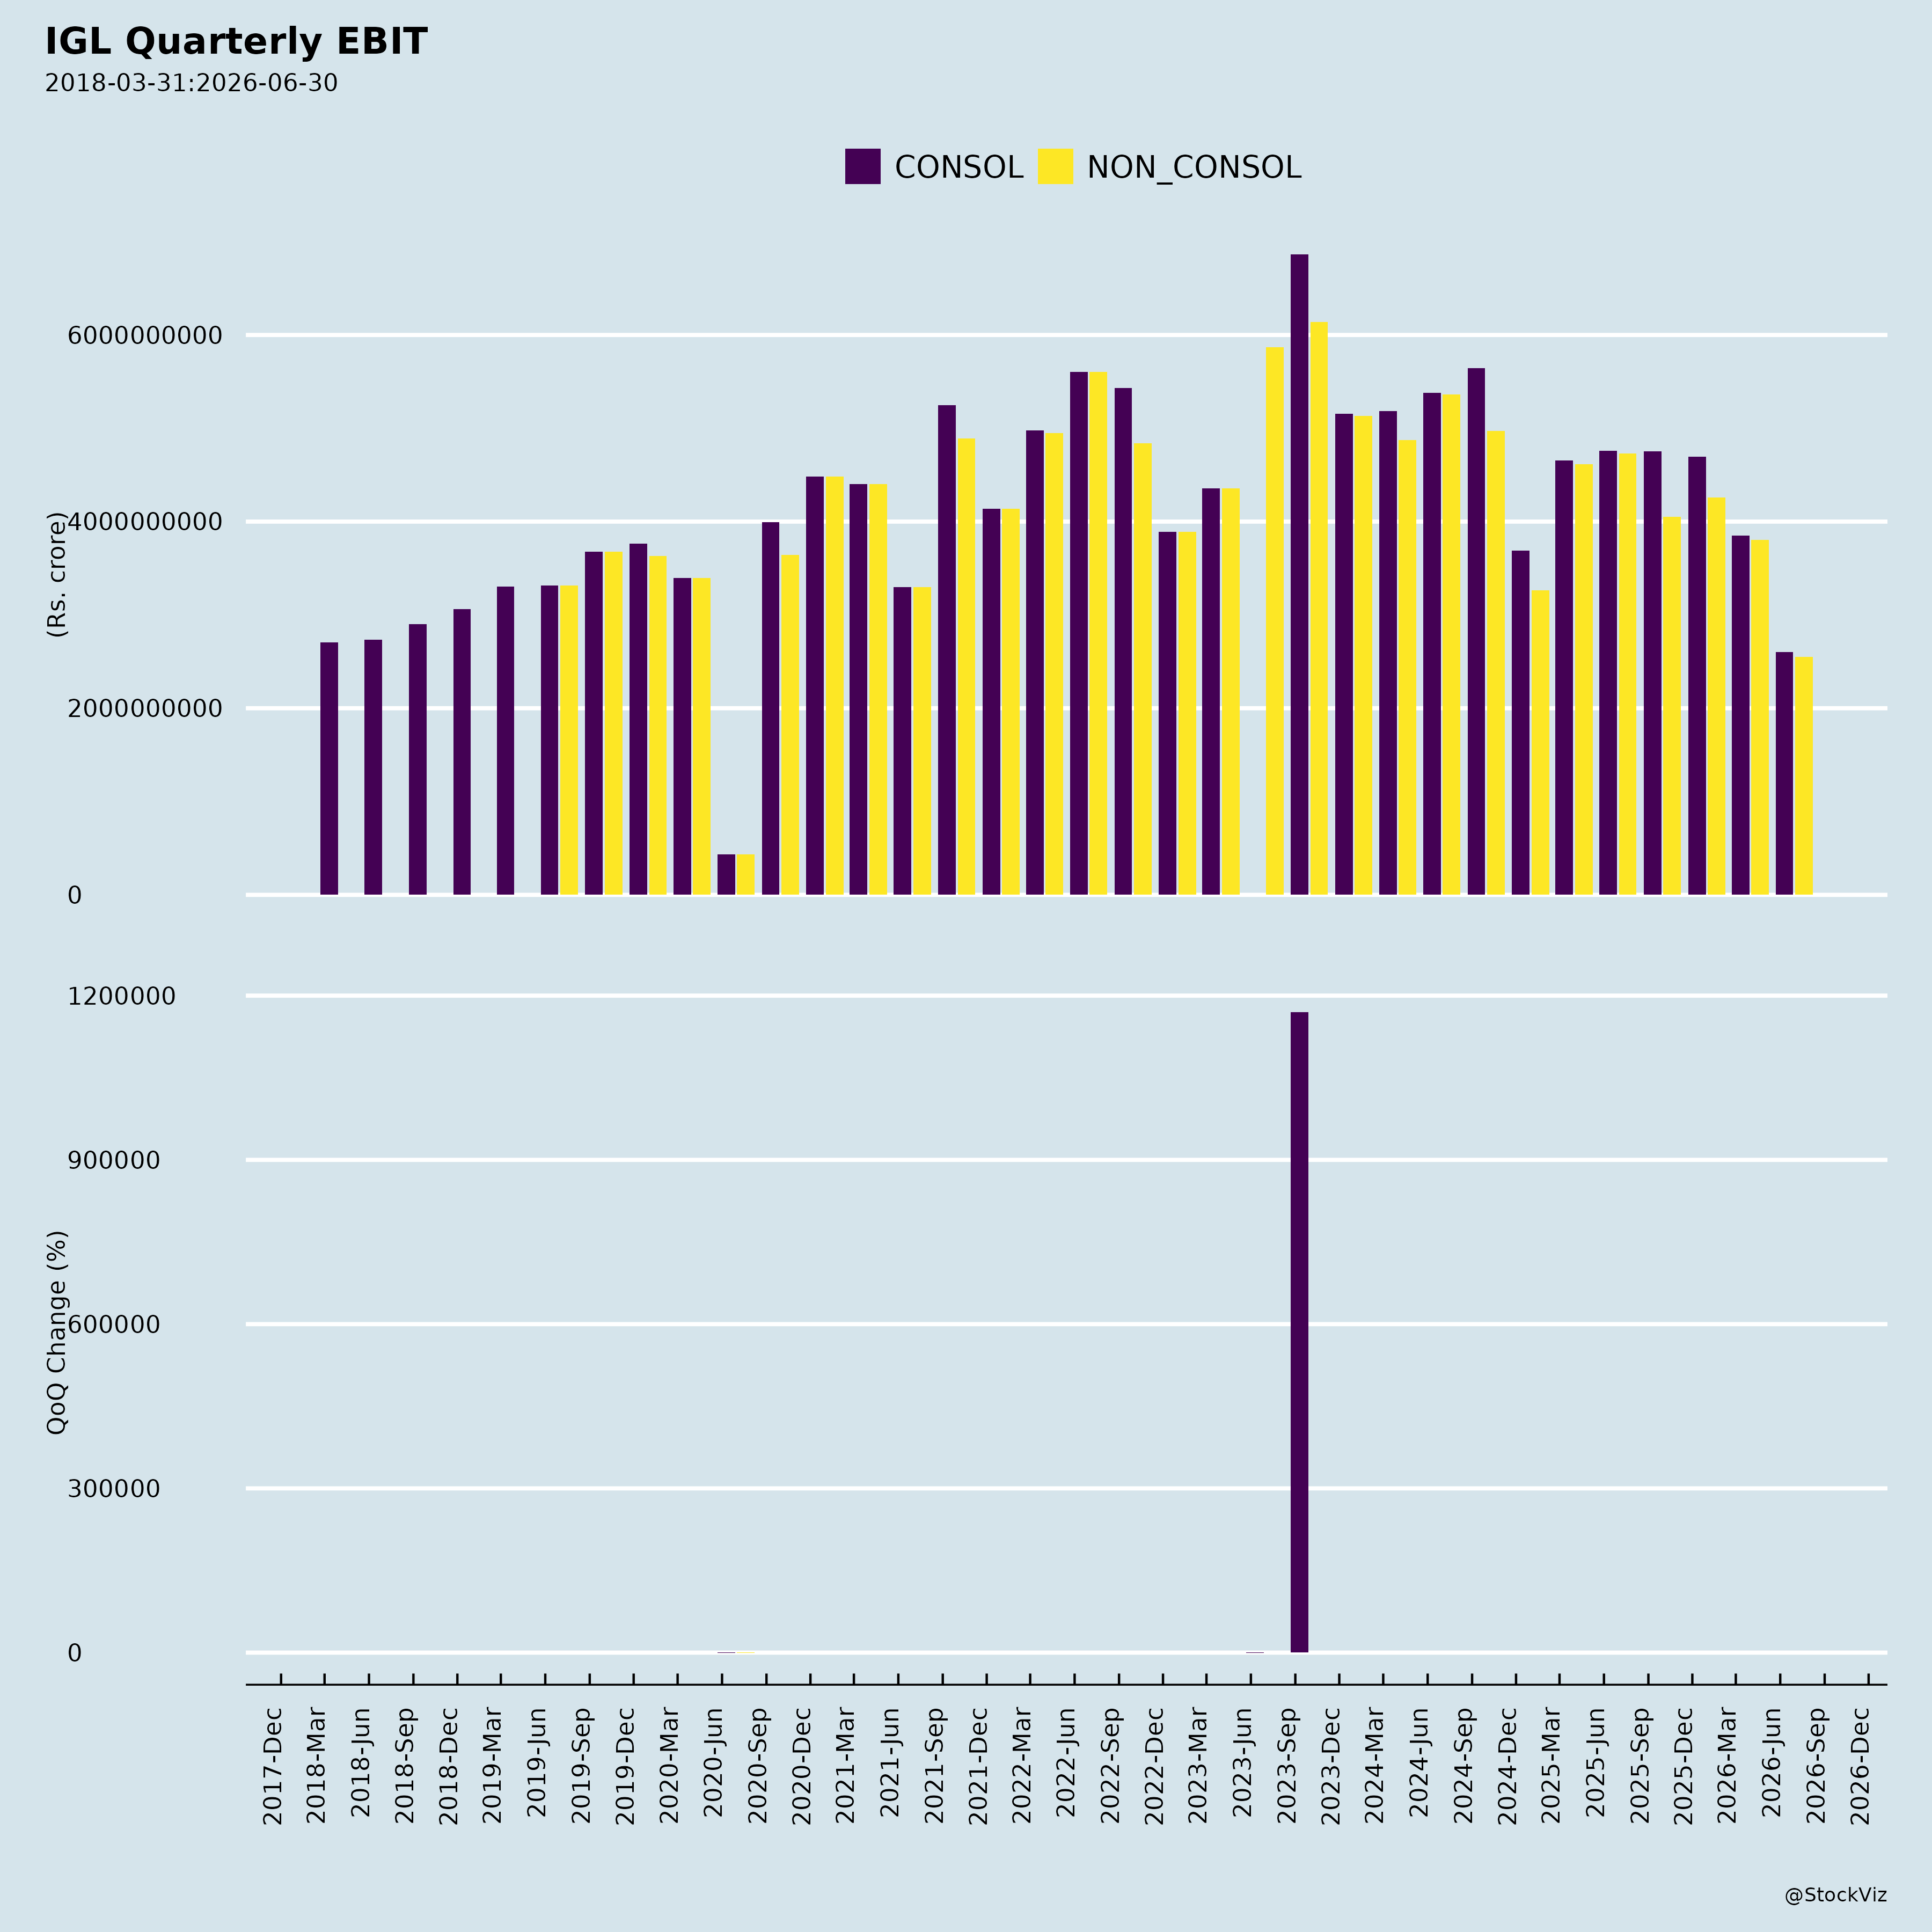
- Profitability decline: For the quarter ended June 30, 2026, Net Profit (after tax) fell to Rs. 186.18 crores, a 48% decrease compared to the previous year. EBIDTA declined to Rs. 295.50 crores, a 42% decrease.
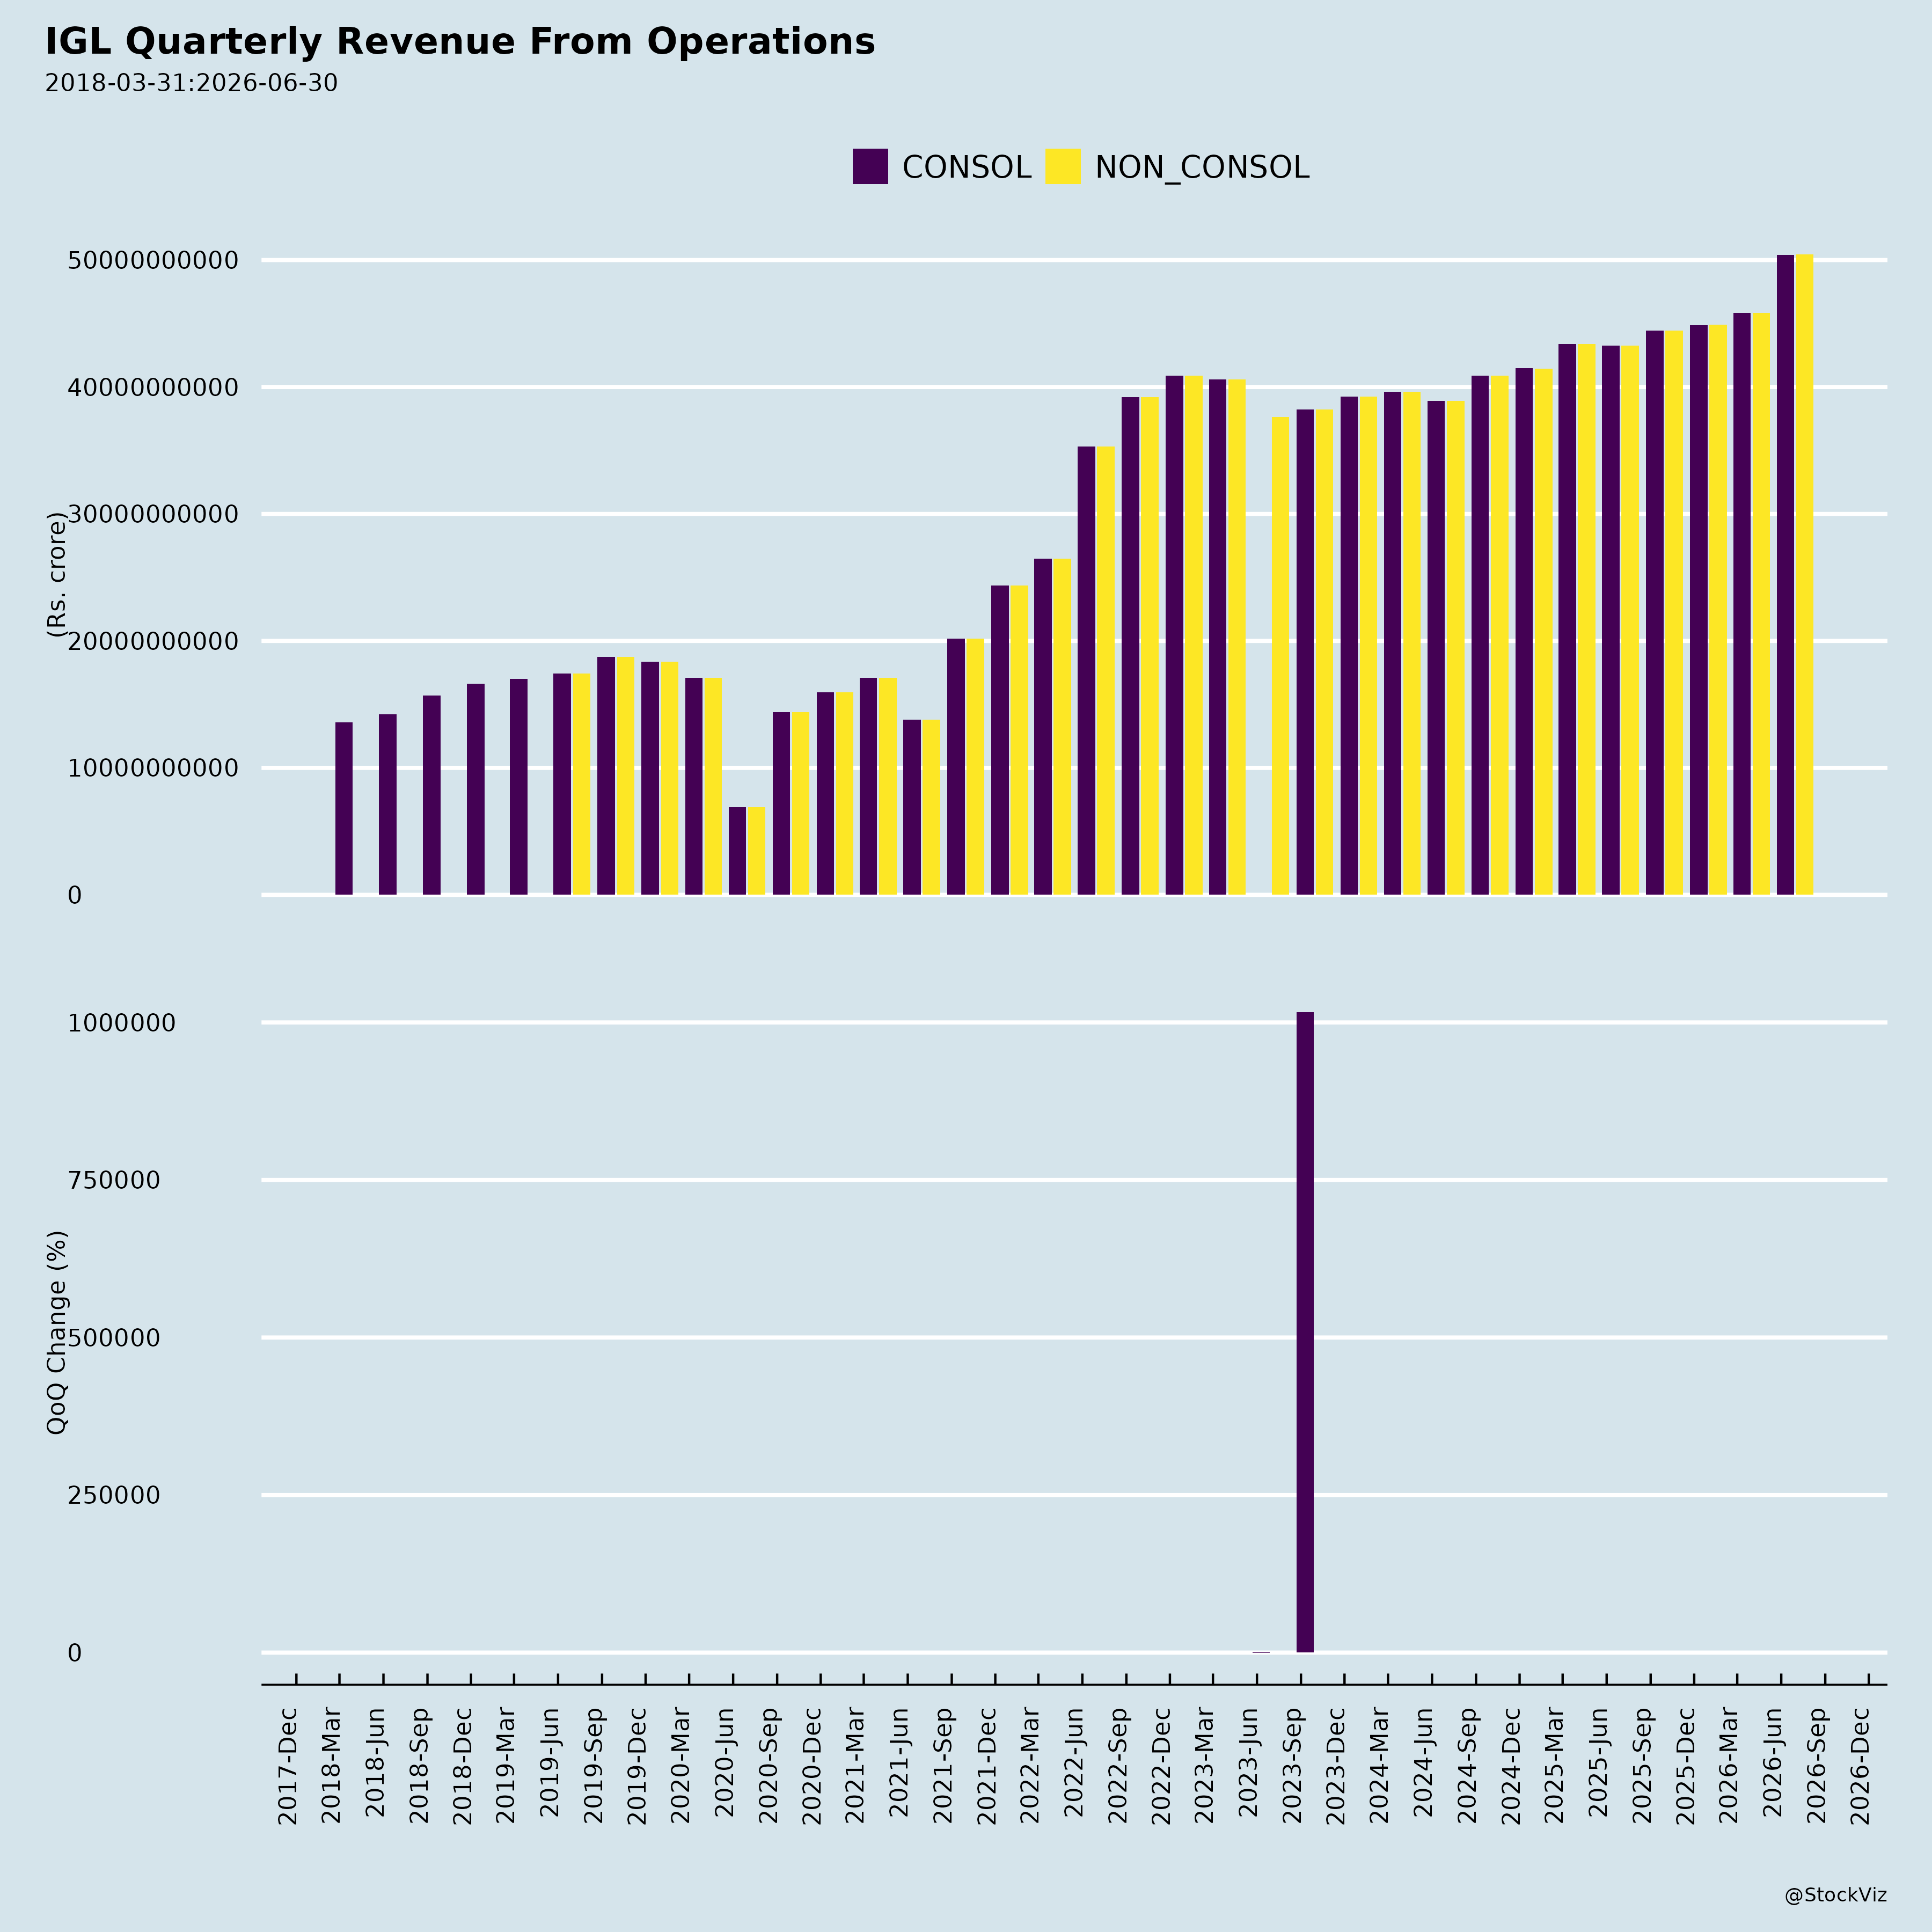
- Margin pressure despite revenue growth: Total net revenue from operations increased 17% to Rs. 4,583.44 crores, while net profit and EBIDTA fell sharply, indicating a disconnect between top-line growth and bottom-line performance.
Tailwinds and Growth Prospects
- Volume growth across segments (quarter ended June 30,
2026):
- CNG volume increased 6% to 656.82 Million Scm
- LNG volume increased 82% to 0.31 Million Scm
- PNG Domestic volume increased 7% to 71.93 Million Scm
- PNG Industrial/Commercial volume increased 4% to 104.42 Million Scm
- Revenue growth: Total net revenue from operations rose 17% to Rs. 4,583.44 crores for the quarter ended June 30, 2026.
- Subsidiary and associate holdings: The company holds a 51% stake in IGL Genesis Technologies Limited and 50% equity in two CGD companies, Central UP Gas Limited and Maharashtra Natural Gas Limited.
Key Risks
- Contingent liability risk: The DDA license fee demand of Rs. 330.73 crores (excluding interest) remains a contingent liability, with the company contesting it as not tenable.
- Earnings volatility: The sharp year-on-year decline in net profit (48%) and EBIDTA (42%) for the June 30, 2026 quarter, despite revenue growth, points to risk in converting revenue into profitability.
- Regulatory and compliance dependencies: The appointment of M/s PSMG & Associates by the Comptroller and Auditor General of India as Statutory Auditor for FY 2026-27, and the AGM/dividend record date processes, are governance events that carry procedural dependencies, including member approval for the final dividend.
Management Guidance Versus Observed Business Performance
- No forward-looking statements or management guidance were provided in the supplied material. The documents note that no Unpublished Price Sensitive Information is intended to be discussed at the scheduled investor meeting.
- Observed performance (quarter ended June 30, 2026): Standalone revenue from operations of Rs. 5,040.15 crores and net profit of Rs. 186.18 crores, alongside the volume and revenue growth figures above. Because no guidance was disclosed, no direct comparison between management guidance and observed performance can be made from the supplied material.
Key Dates and Events
- September 21, 2026: Physical One-to-One meeting with Morgan Stanley in New Delhi from 02:30 PM onwards; no Unpublished Price Sensitive Information intended to be discussed.
- September 24, 2026: 27th Annual General Meeting at 10:00 A.M. via VC/OAVM.
- October 1, 2026: Record date for the Final Dividend for FY 2025-26, subject to member approval.
- FY 2026-27: M/s PSMG & Associates, New Delhi appointed as Statutory Auditor by the Comptroller and Auditor General of India.
Broker Narrative
The broker narrative evolved from early concerns about Q4FY23 earnings misses and margin pressure driven by domestic gas costs to later fears of elevated Brent-linked input gas costs (USD93/bbl vs USD69/bbl), INR depreciation, and Delhi EV policy bans. Volume growth optimism persisted throughout but shifted from broad-based penetration of new GAs to robust growth outside Delhi NCR (~20%+ YoY, ~50% of incremental sales). Margin recovery hopes, a central tailwind in the first report, gave way to acknowledgment of margin troughing in 1QFY27 before recent price hikes provided limited relief.
Fears that came true
- The earnings miss and margin pressure fears flagged in Q4FY23 materialized, with the stock posting a -9.0% return and DISAPPOINTMENT outcome immediately after the first Buy call, and margin concerns persisting through 1HFY27 with Brent at USD93/bbl versus USD69/bbl in FY26.
- The EV transition risk flagged early materialized as N1/N2 LGV registration bans under Delhi’s EV Policy 2.0 and CAQM orders, explicitly cited as a headwind in the last report.
- Rising operating costs and weak associate contribution concerns persisted, as the last report still flagged elevated input gas costs and INR depreciation (INR95/USD vs INR88.4/USD) compounding margin pressures.
Optimism that failed
- The expected margin recovery to Rs 7.5-8.0/scm in FY24E from falling gas prices failed to materialize, as margins instead trough-ed in 1QFY27 with gas costs remaining elevated (Brent USD93/bbl) and only recent price hikes providing partial relief.
- The optimistic volume growth target of ~9 mmscmd in FY24E with ~7.2% CAGR did not translate into sustained positive returns, as the majority of subsequent broker calls resulted in DISAPPOINTMENT with actual returns mostly deeply negative over the period.
- The valuation multiple rerating to 18x (from 16x) on FY25E did not materialize, evidenced by persistent DISAPPOINTMENT outcomes across most reports and actual returns trending negative throughout the coverage period.
Broker Timeline
68 broker calls · 2023-05-15 to 2026-09-10
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.