LPG/CNG/PNG/LNG Supplier
Industry Metrics
April 16, 2026
Annual Returns
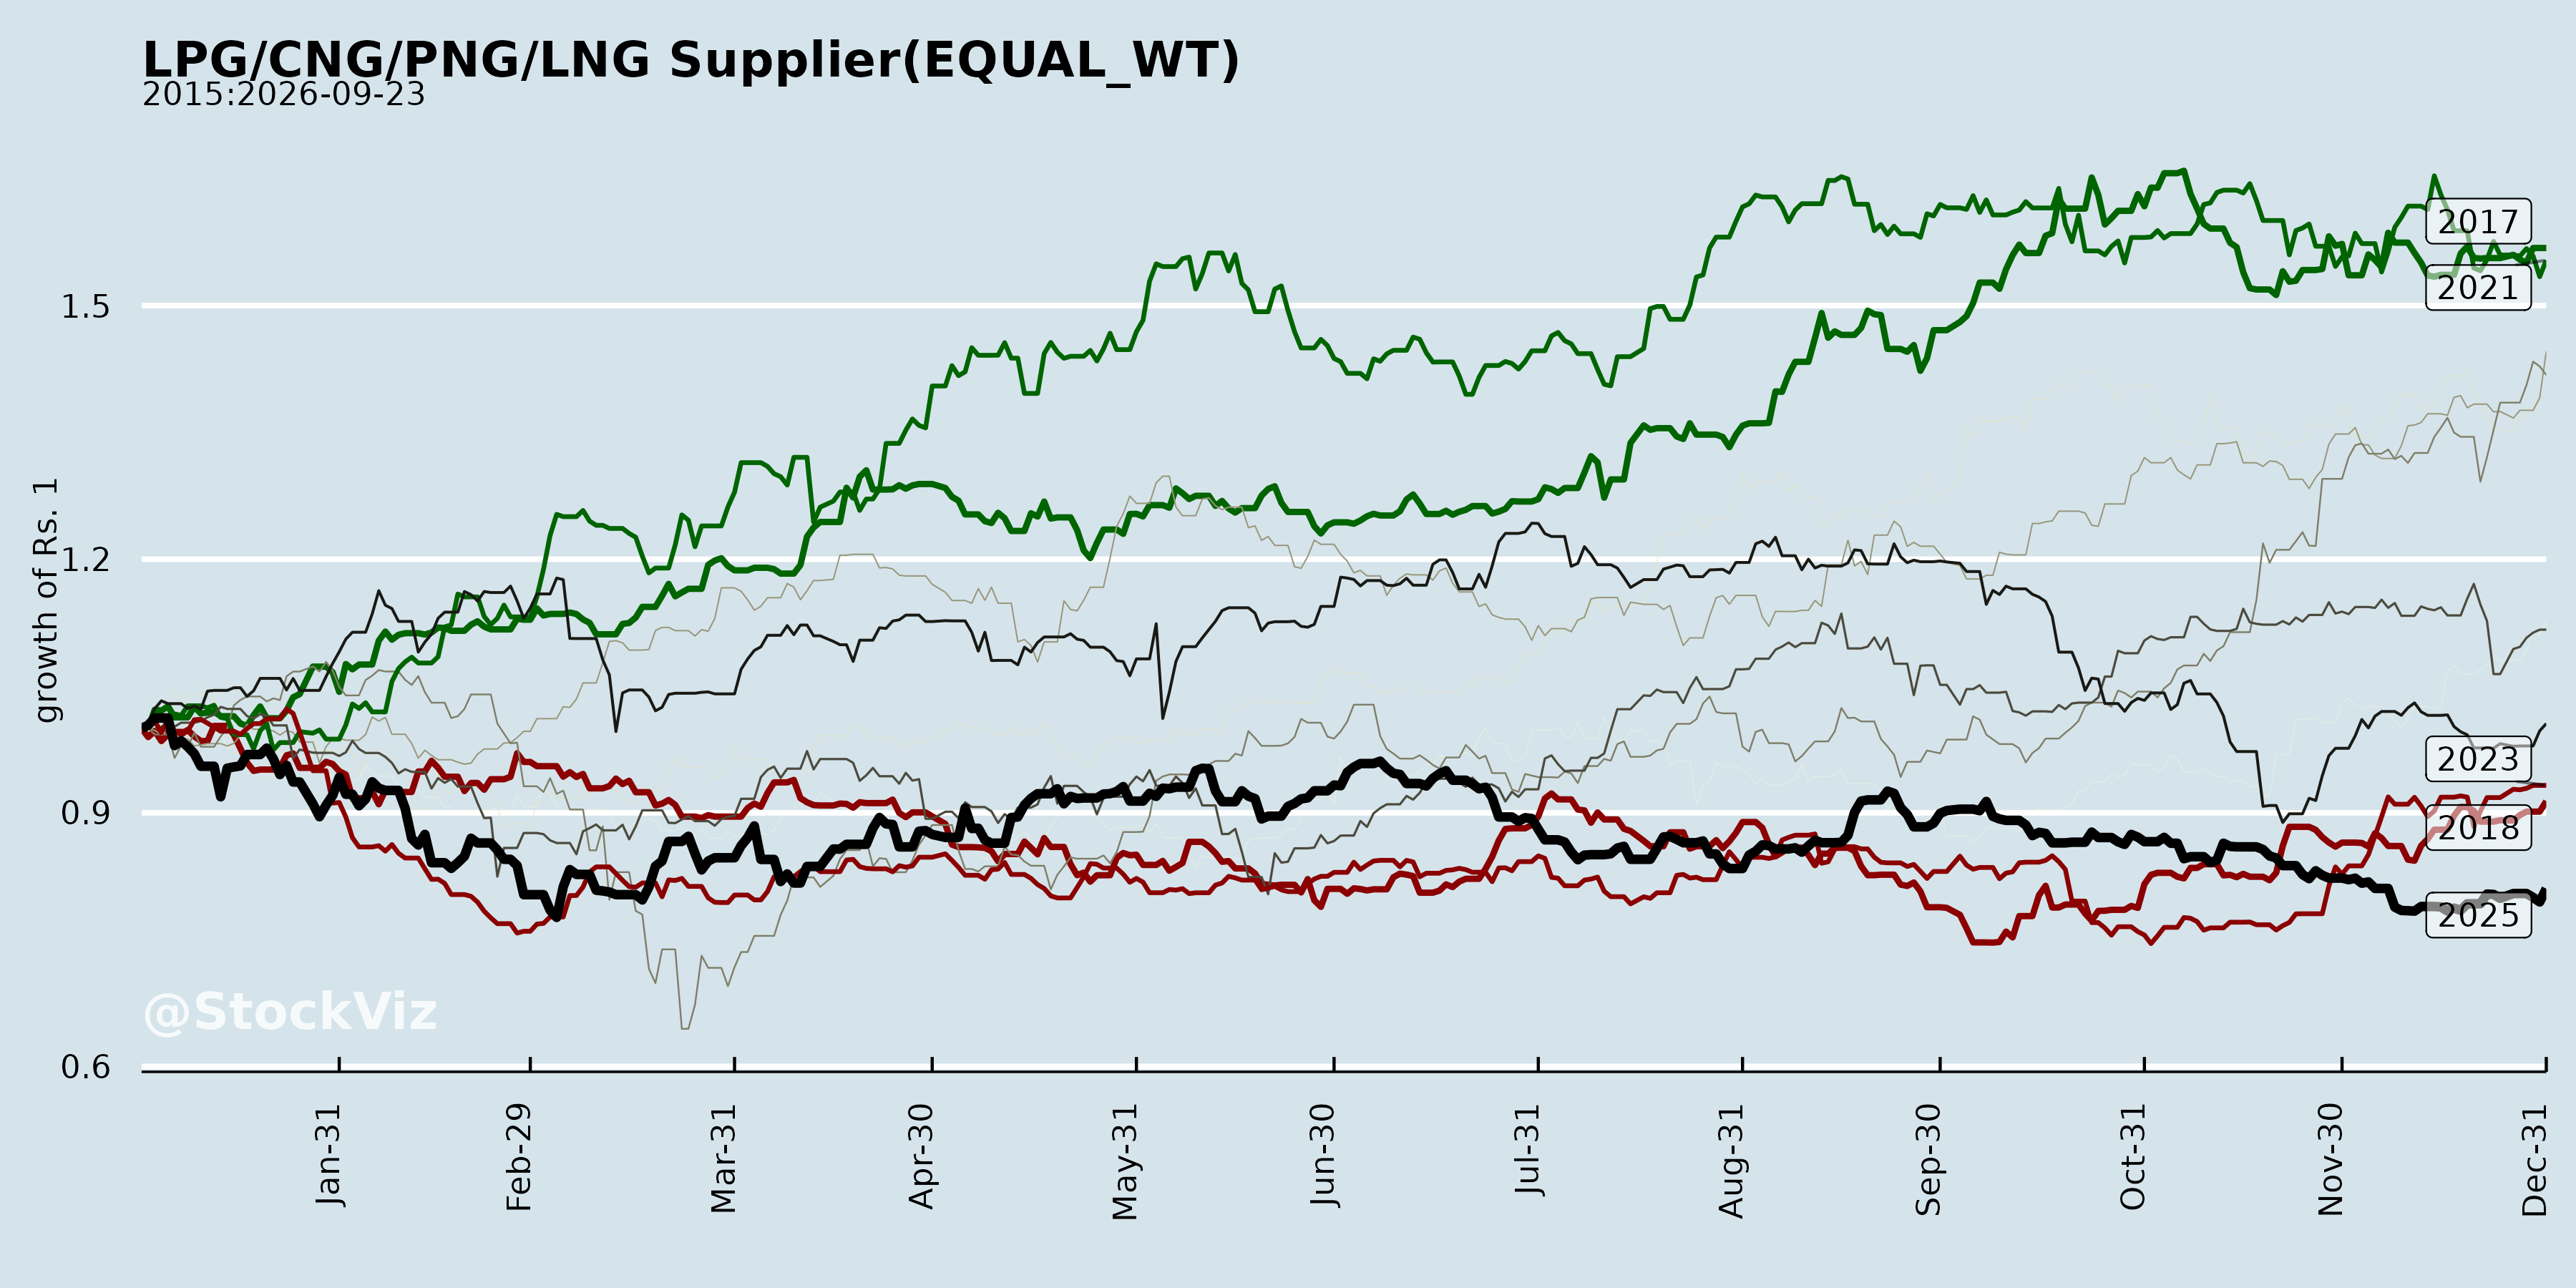
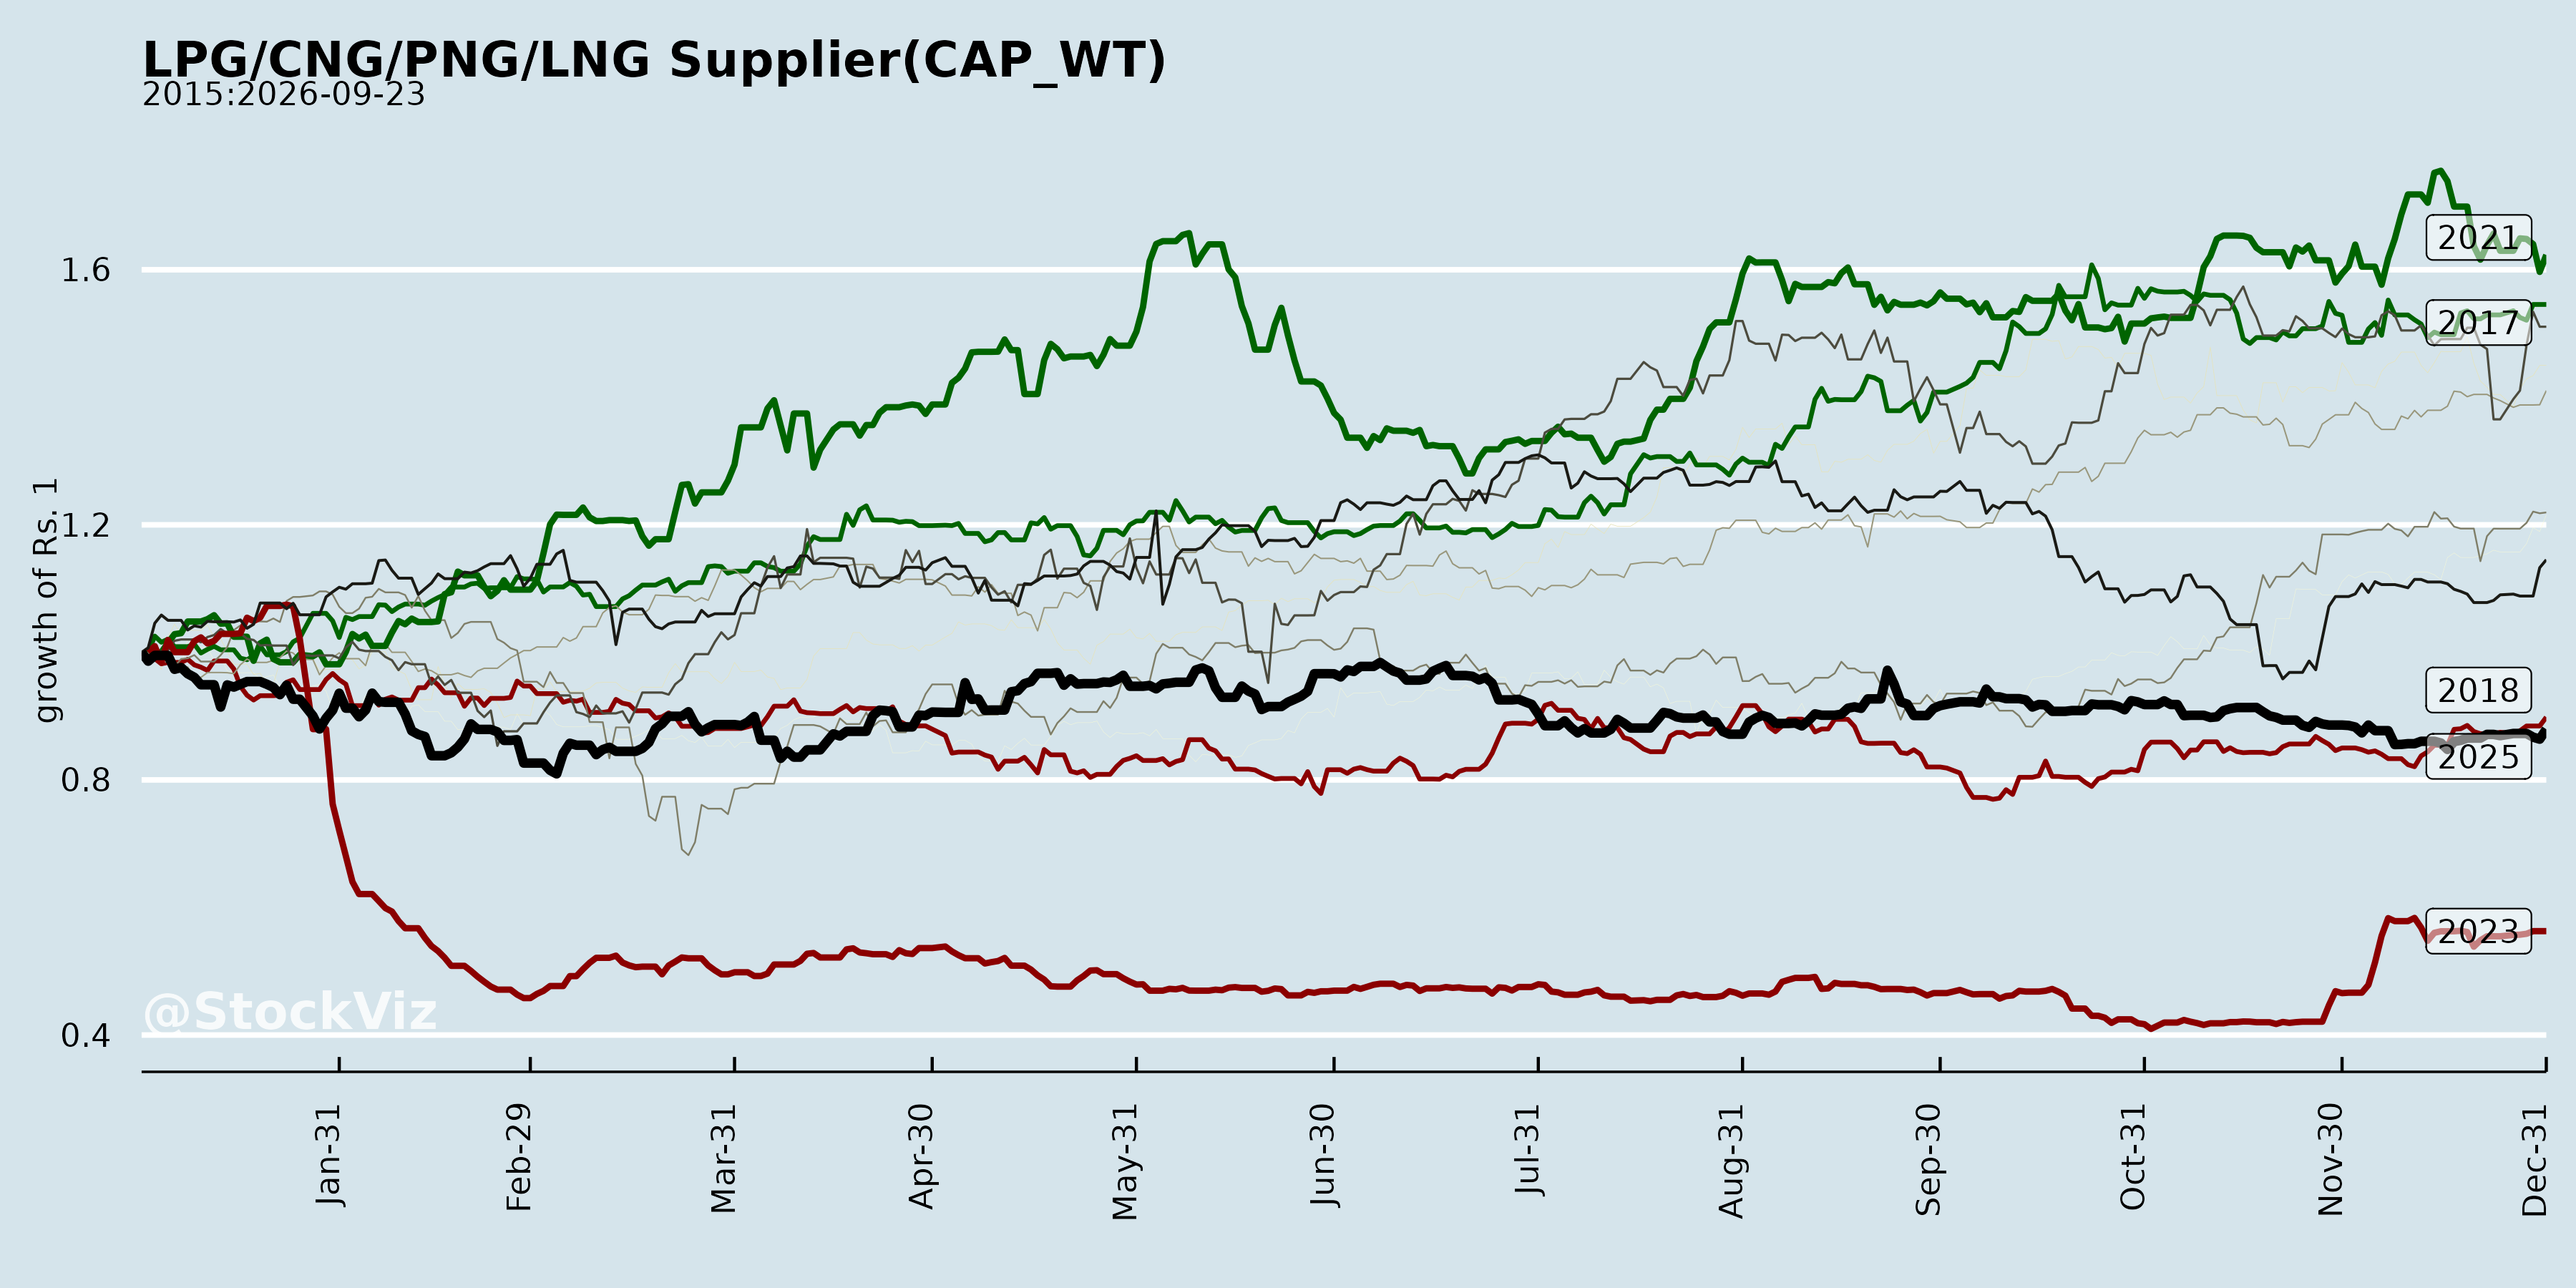
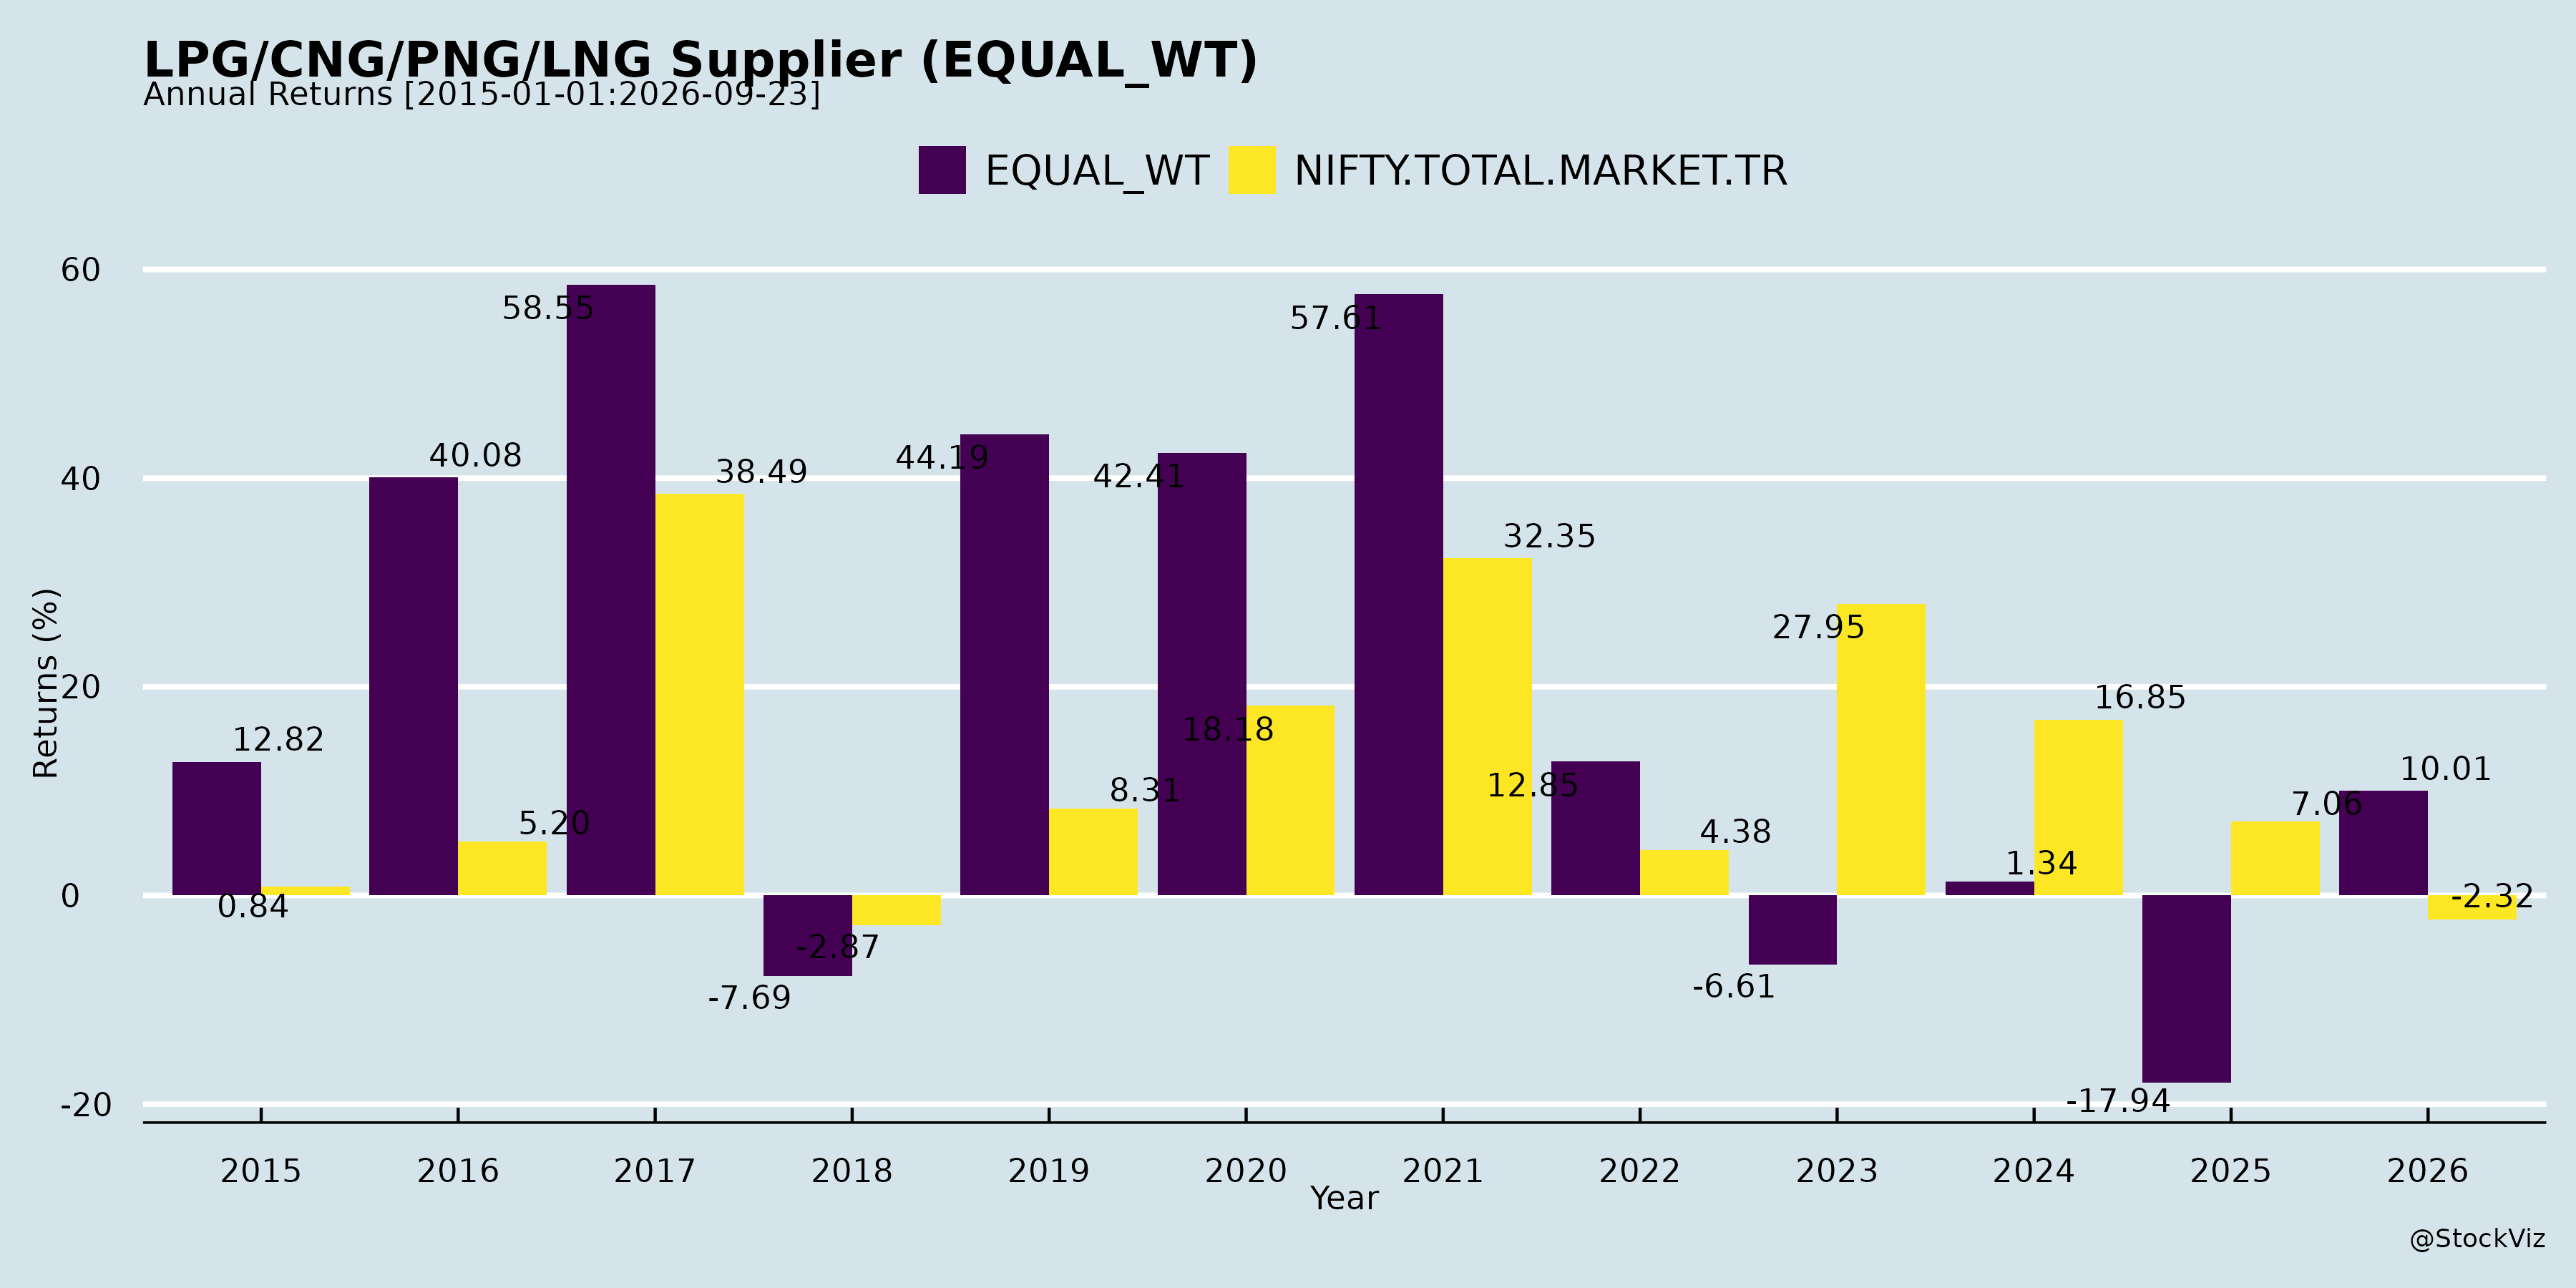
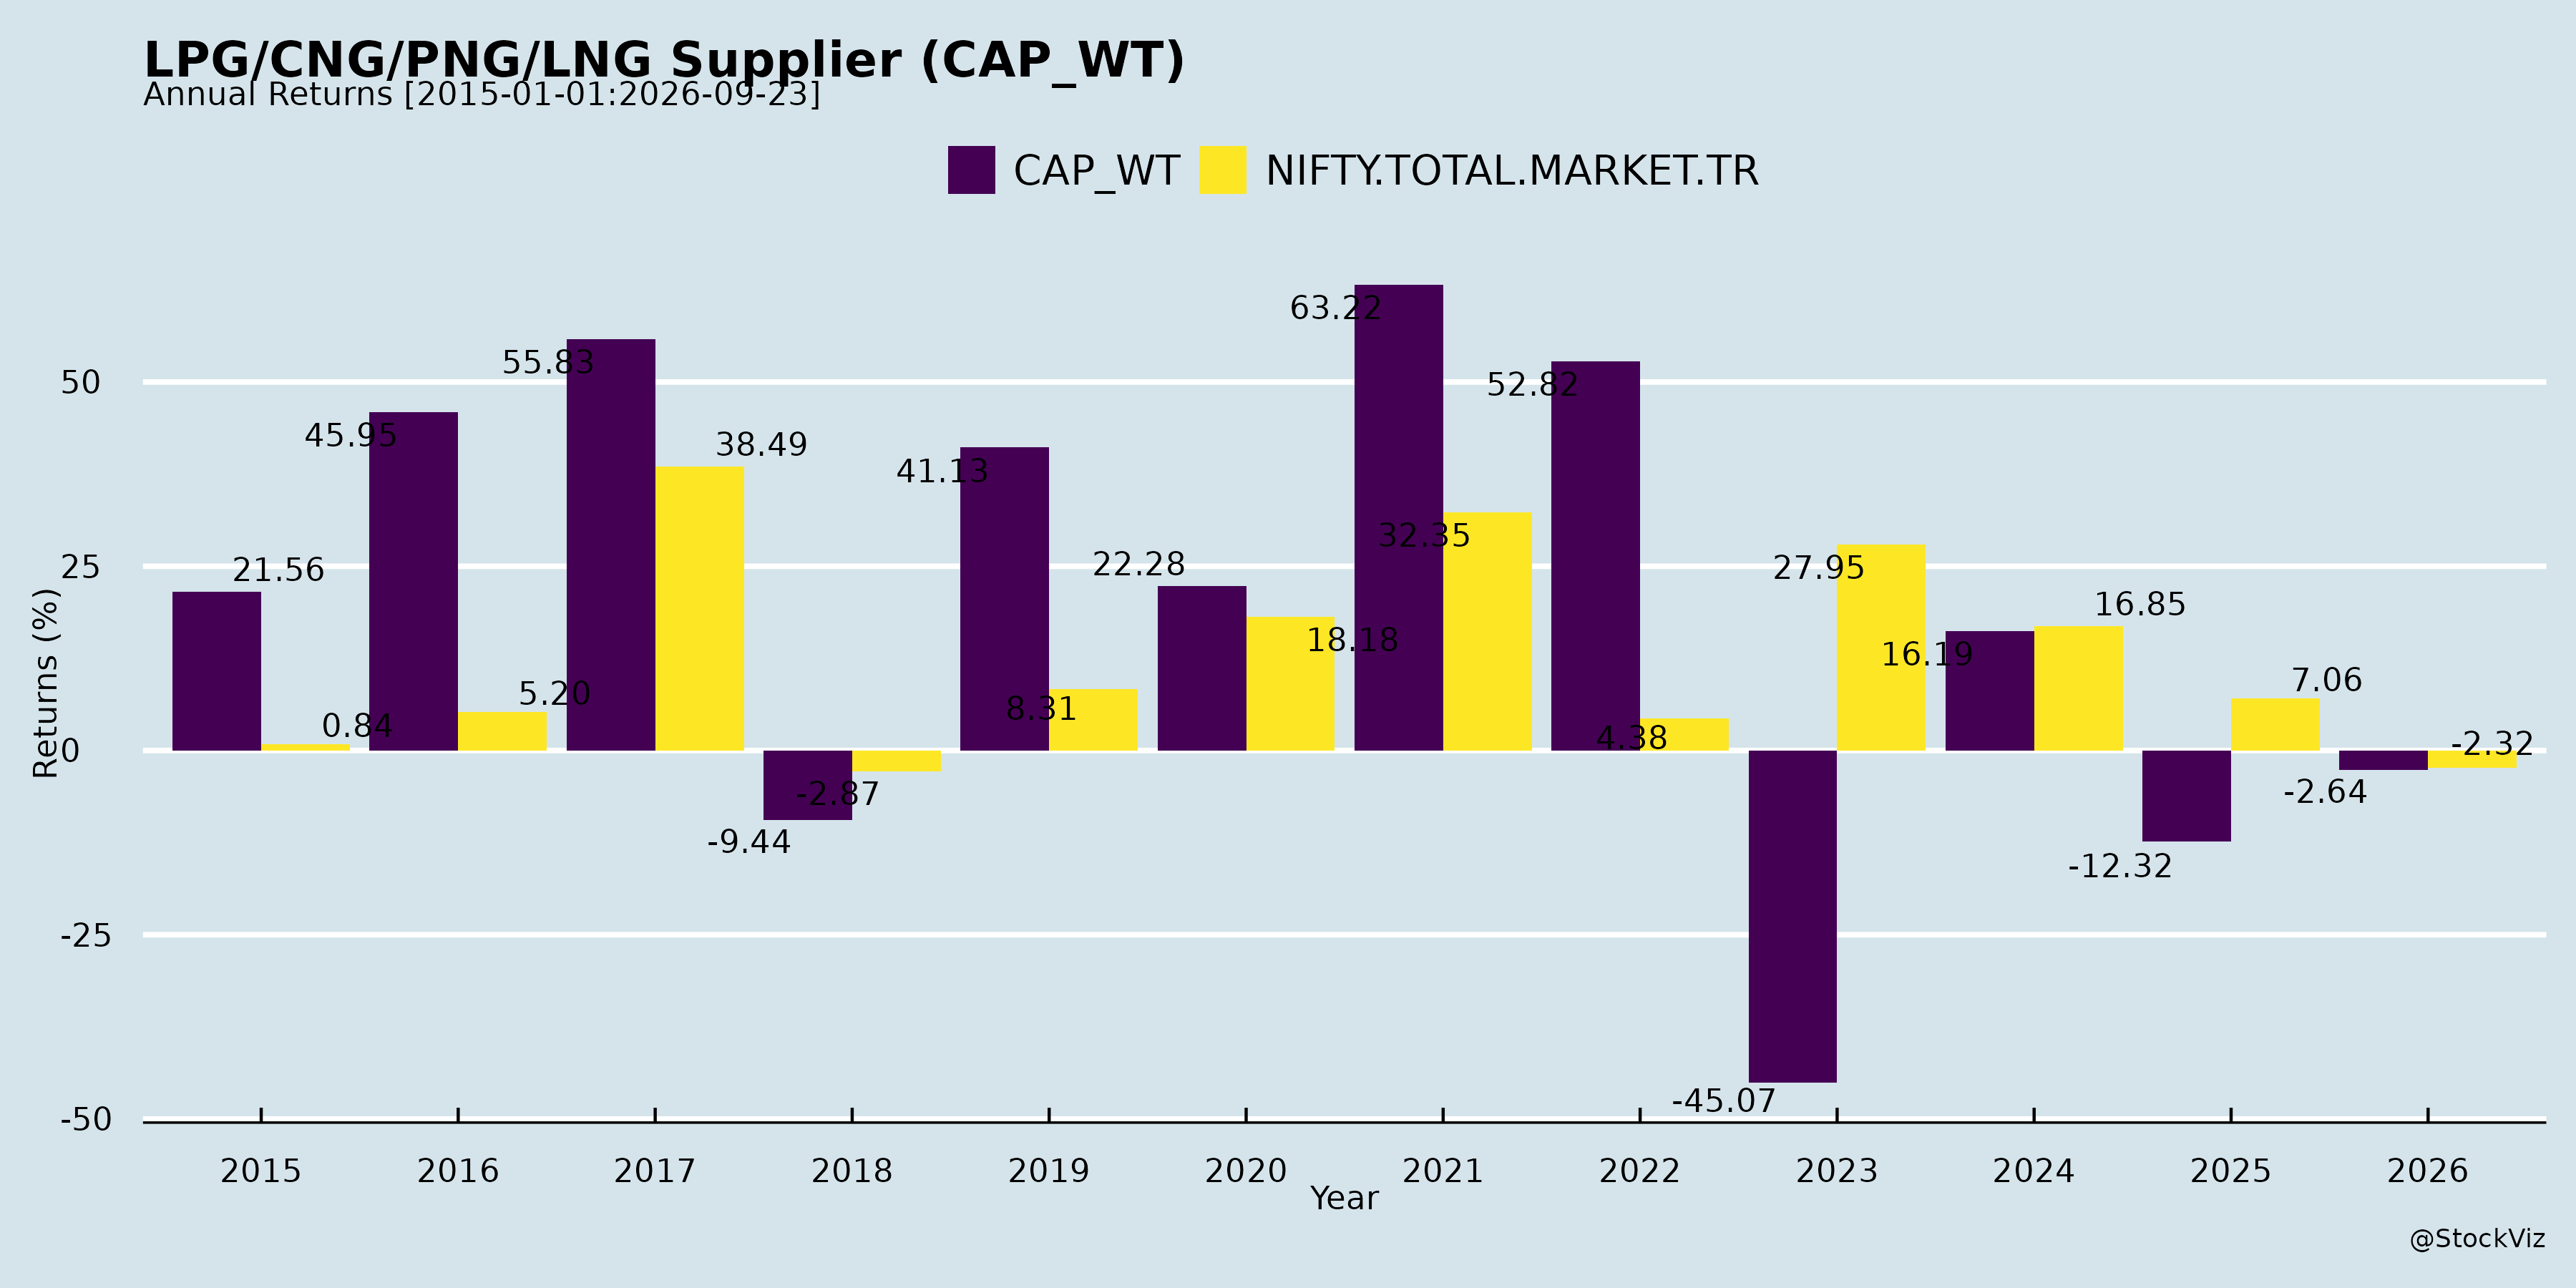
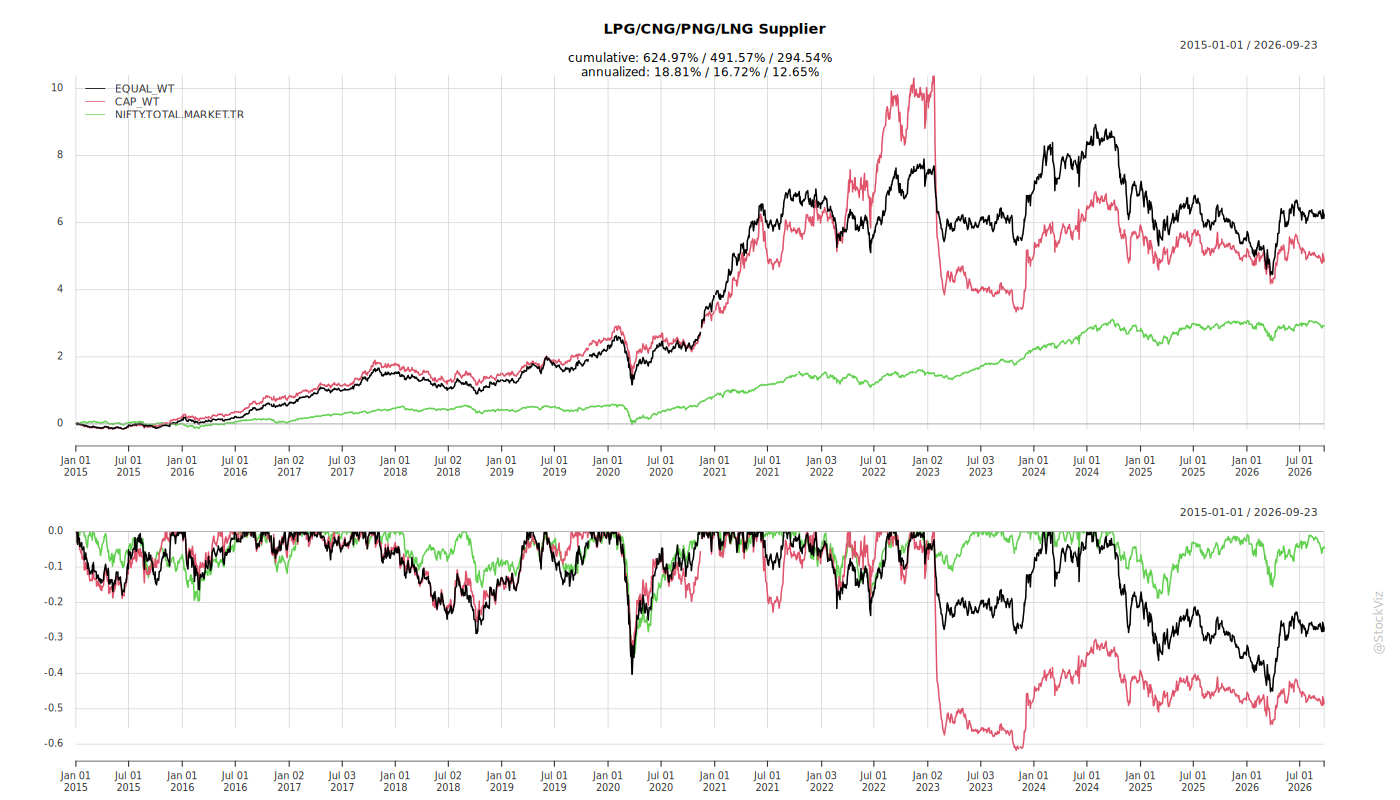
Cumulative Returns and Drawdowns
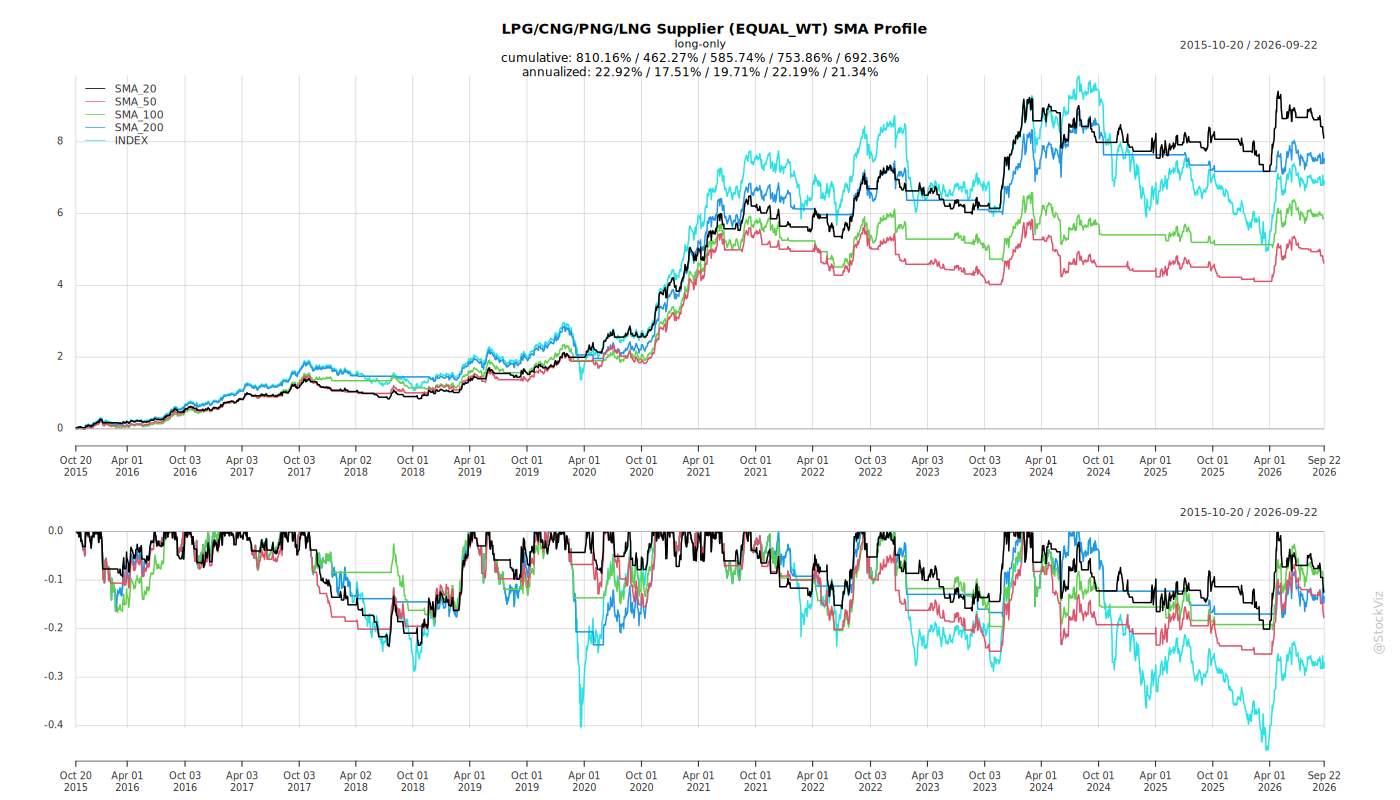
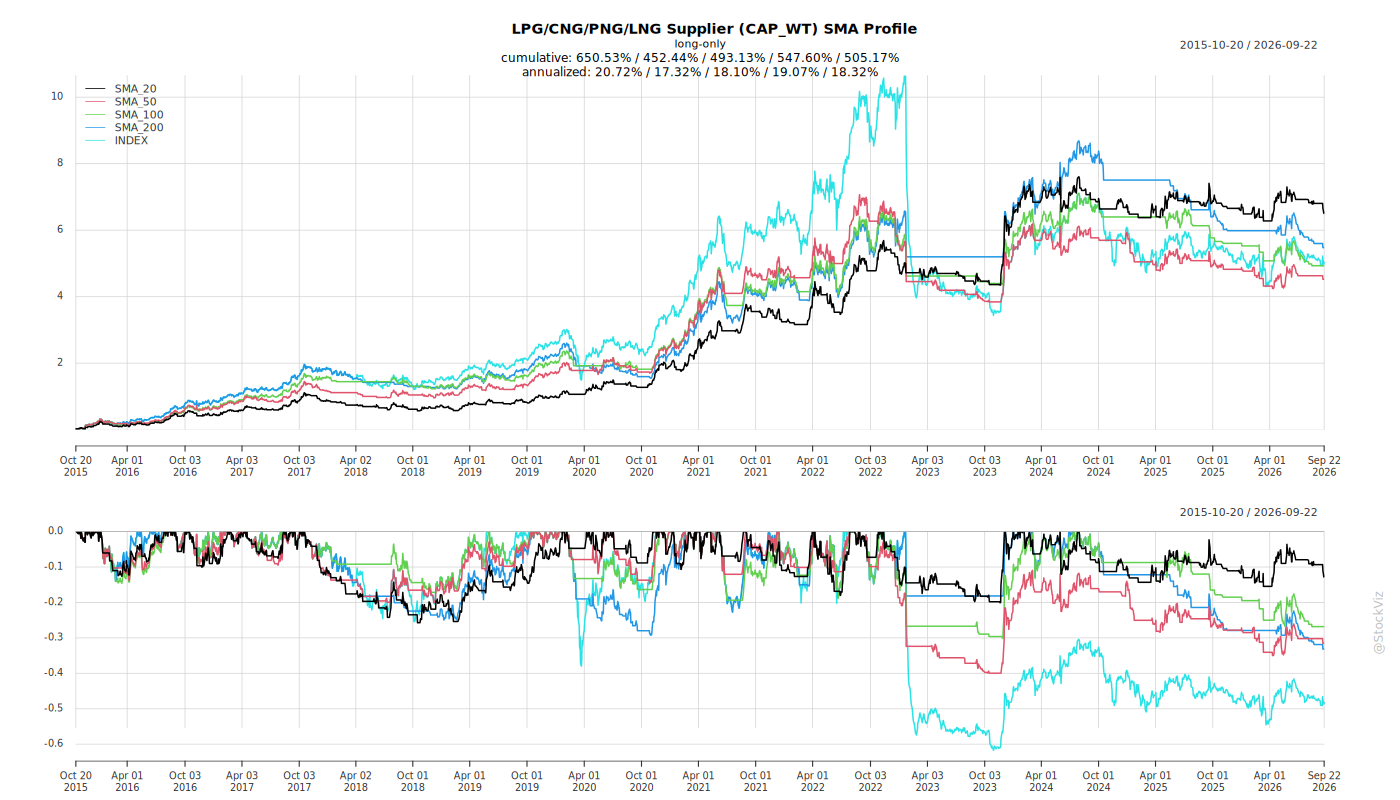
SMA Scenarios
Current Distance from SMA
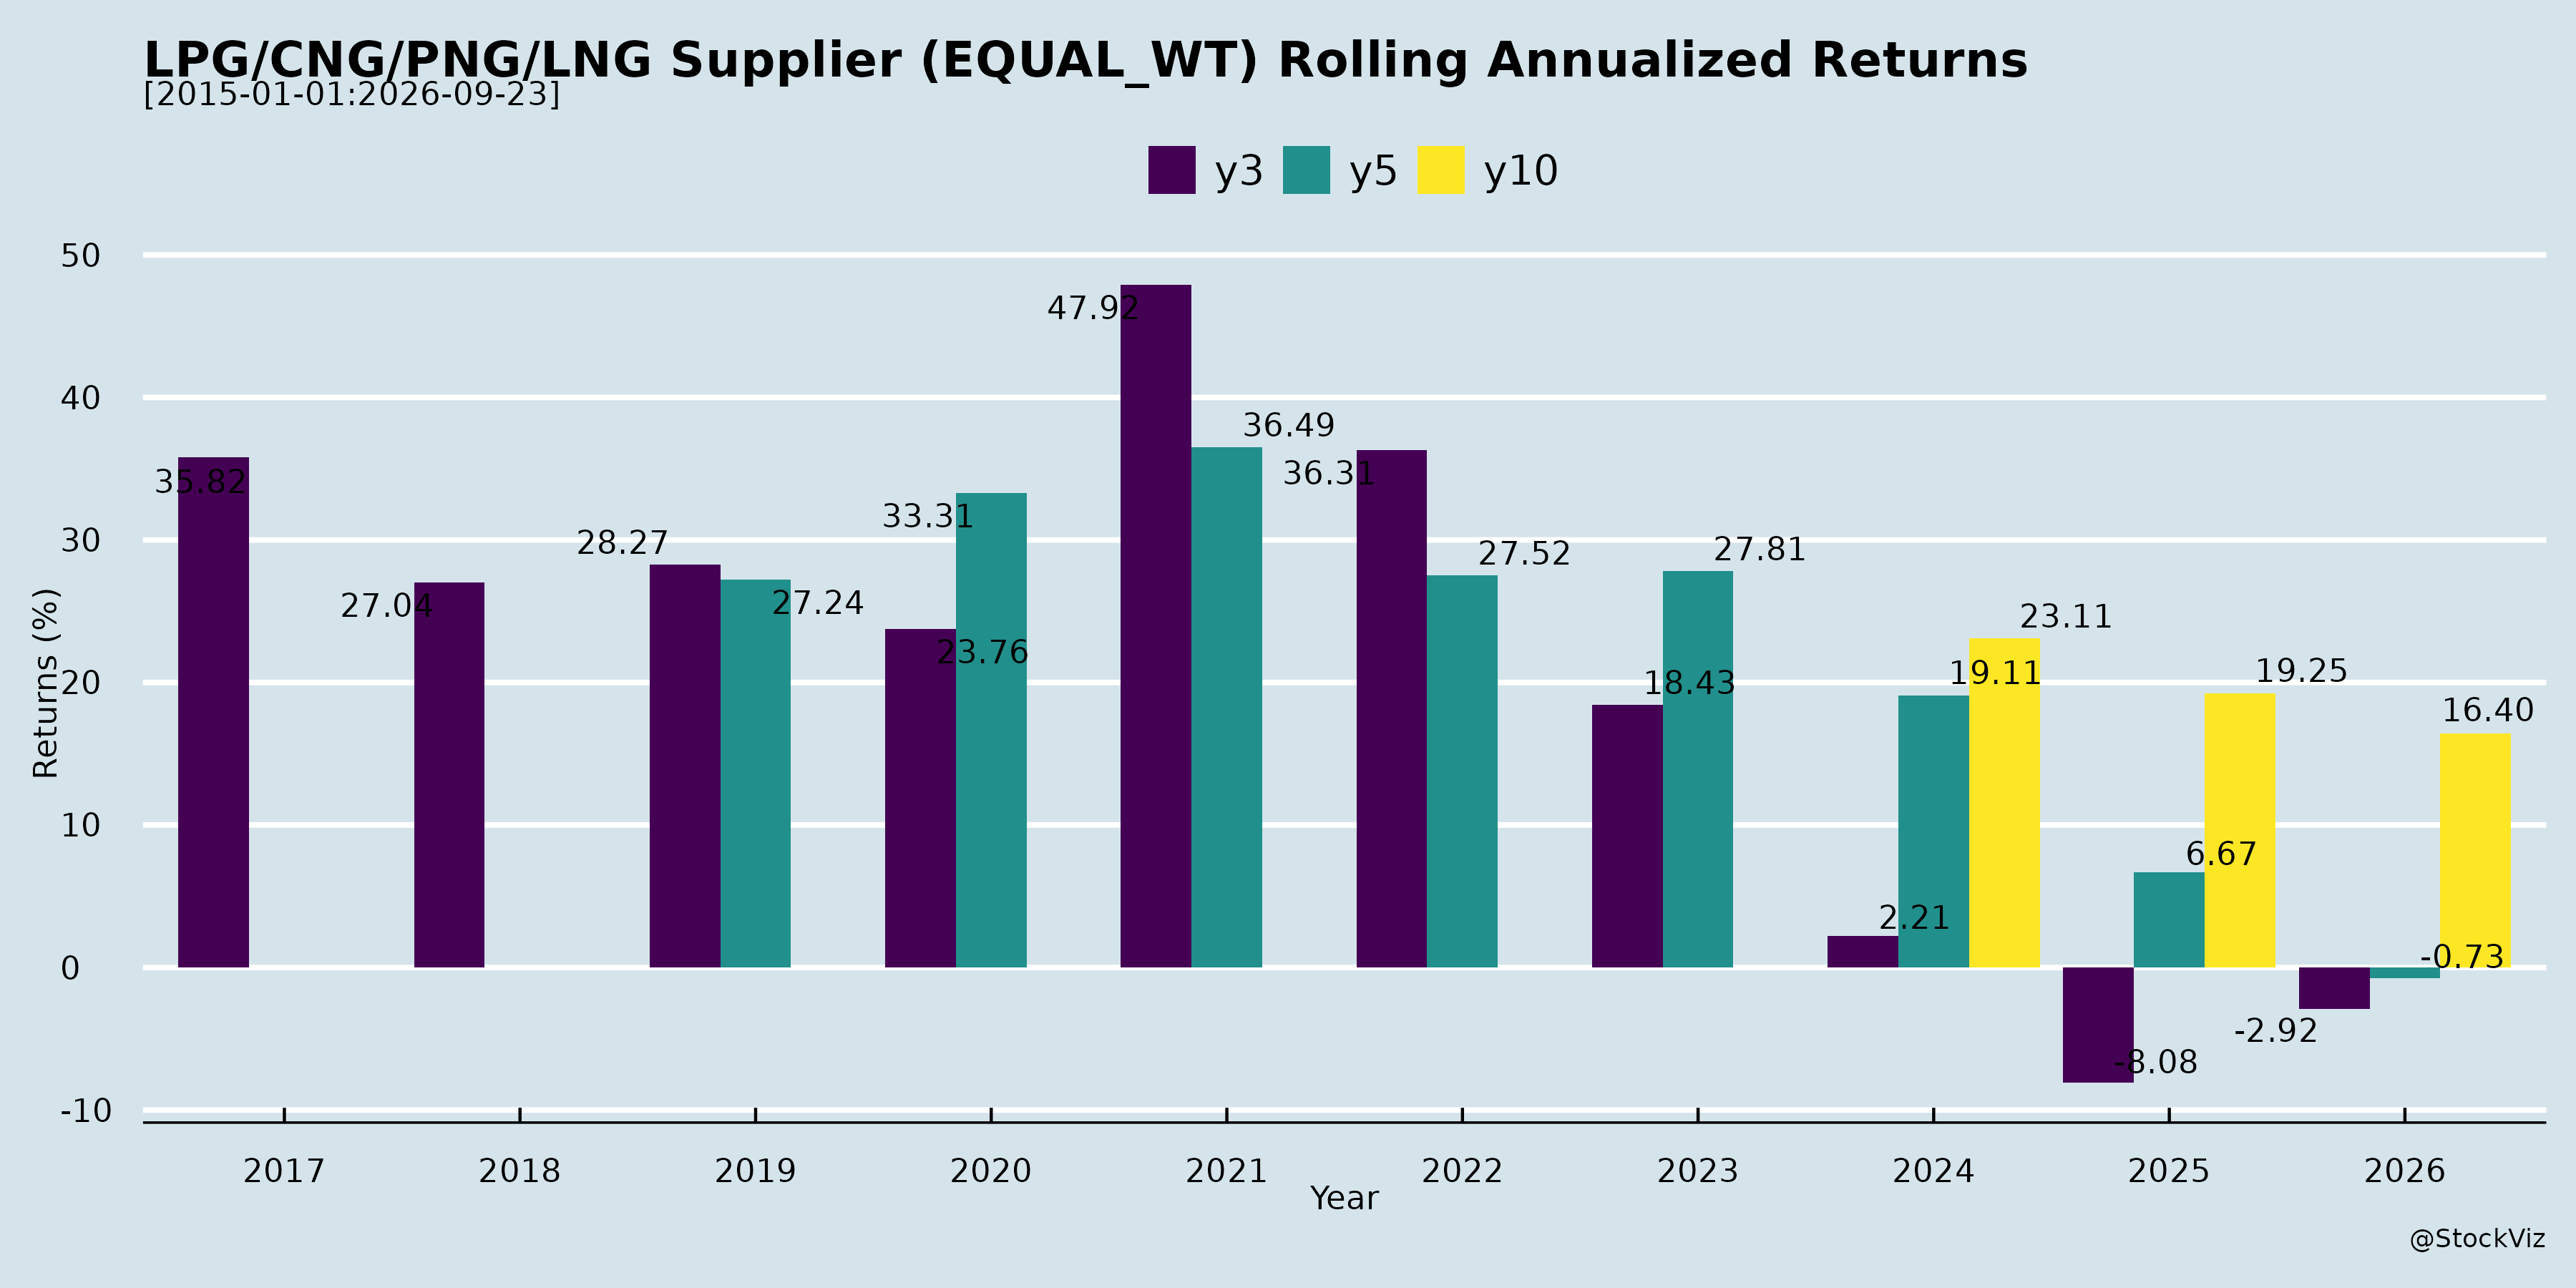
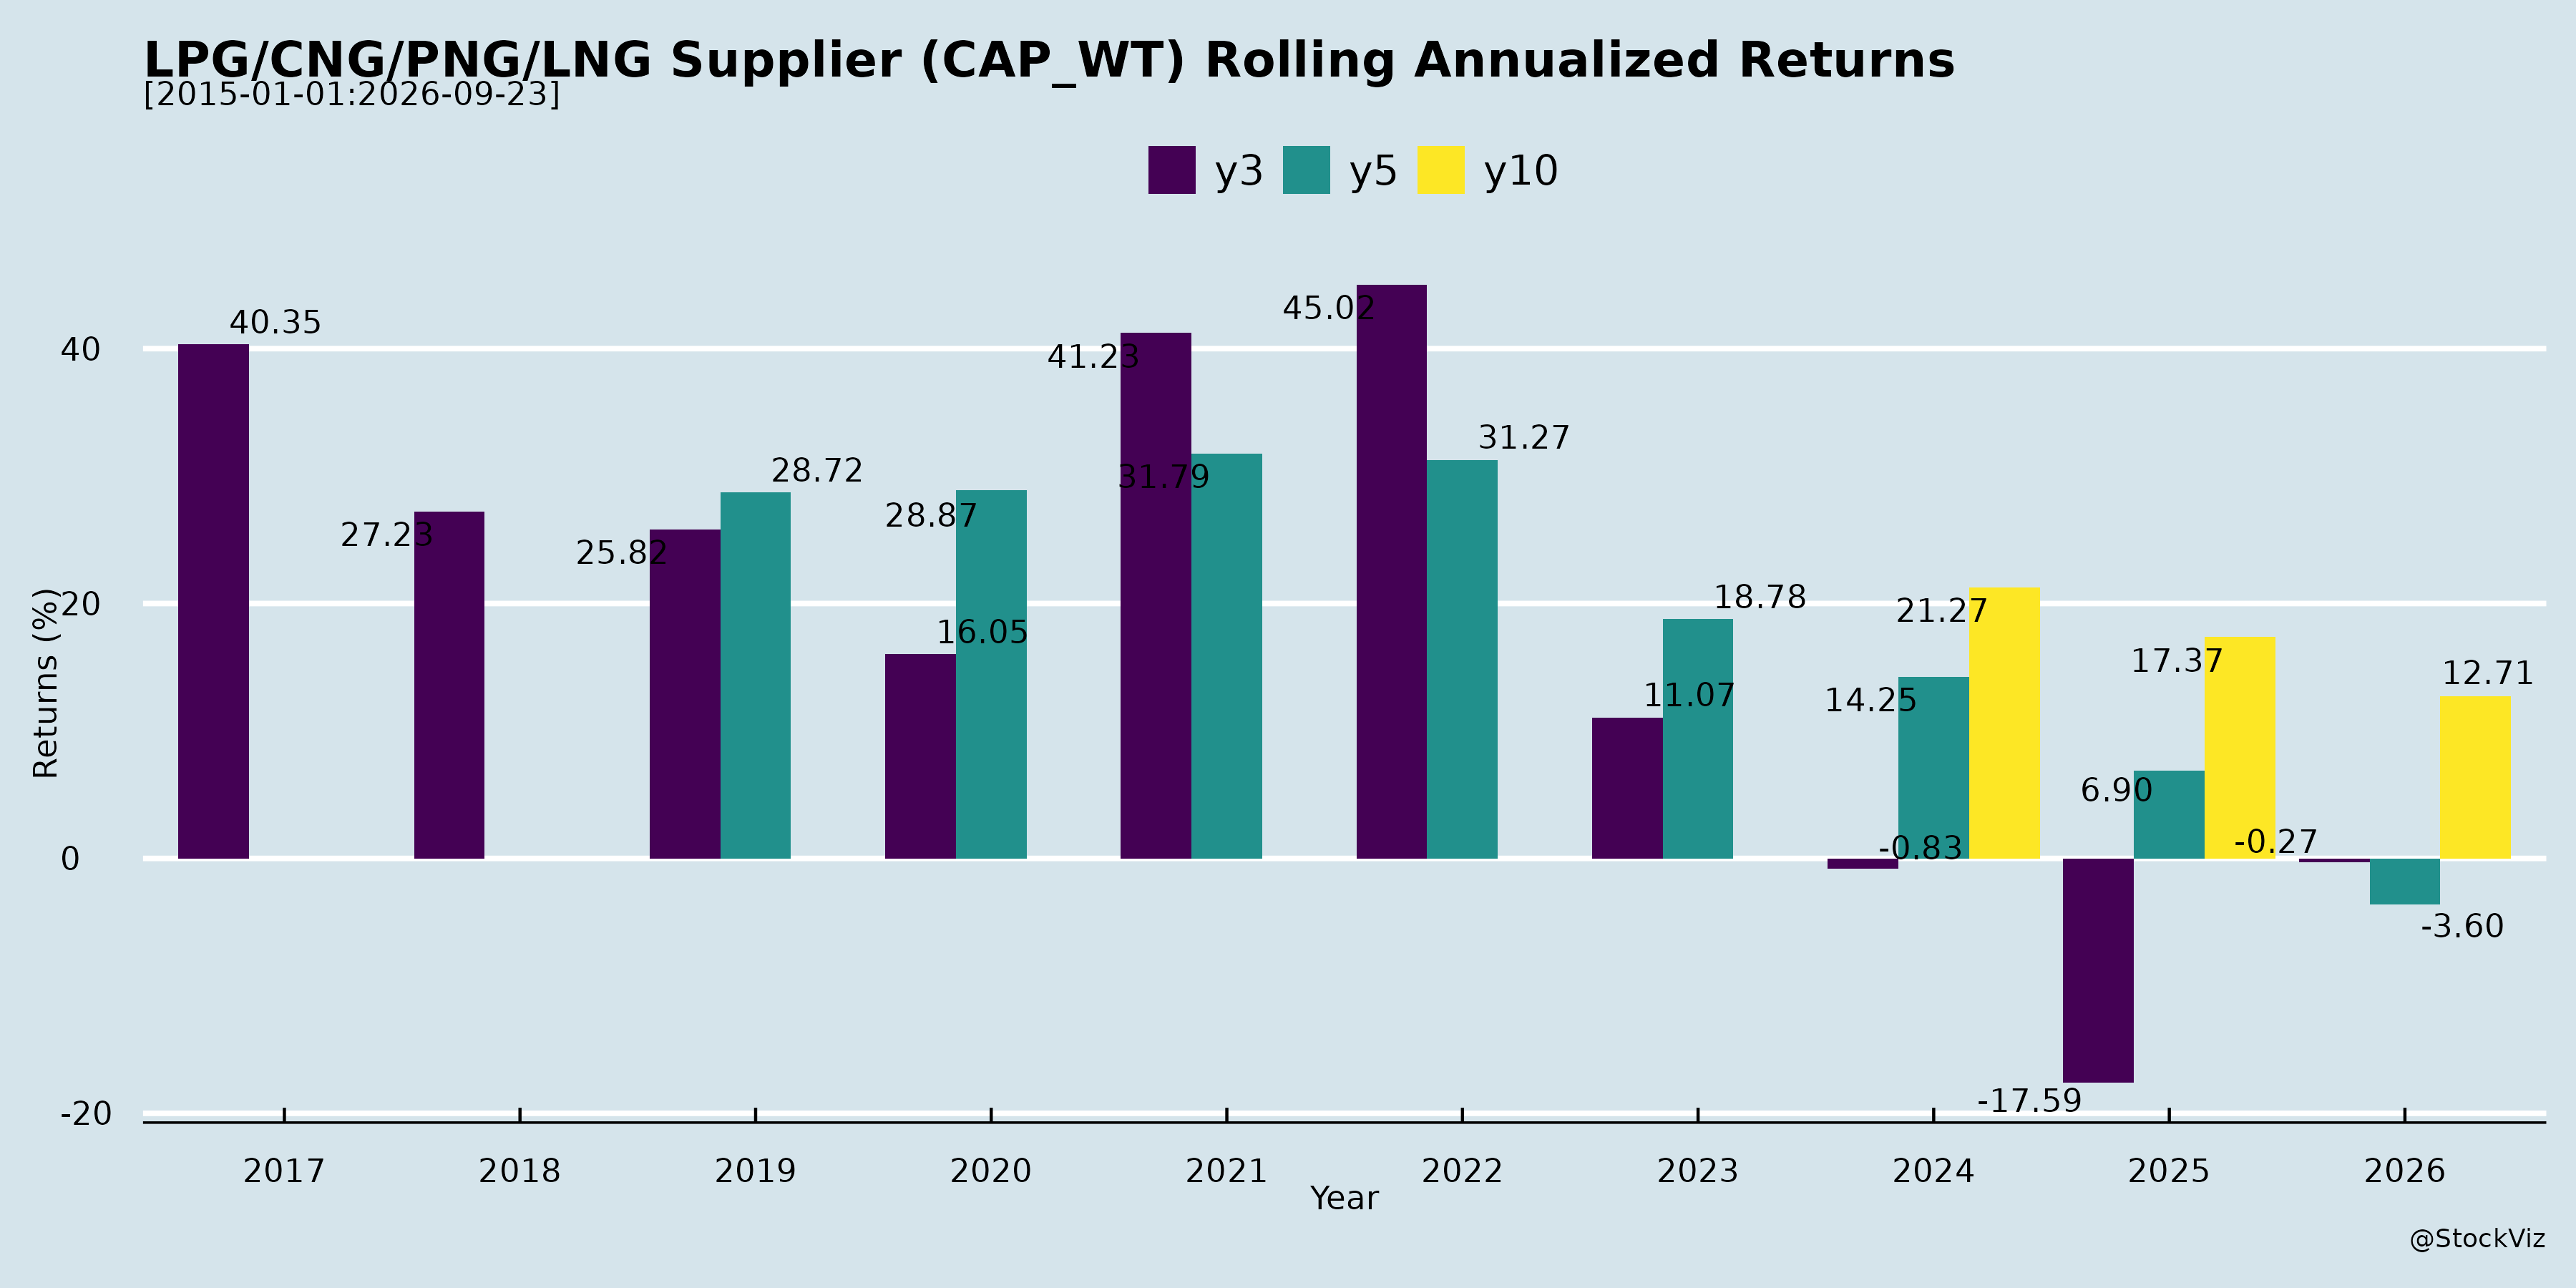
Rolling Returns
Fundamental Ratios
AI Summaries
Analyst
asof: 2025-11-30
Analysis of Indian LPG/CNG/PNG/LNG Supplier Sector
The provided documents are Q2 FY26 earnings transcripts/announcements from key players: Adani Total Gas (ATGL) and Gujarat Gas (GGL) (CGD-focused with CNG/PNG emphasis), Petronet LNG (PLL) (LNG regasification/import), Indraprastha Gas (IGL) (Delhi-NCR CGD), and references to Mahanagar Gas (MGL) and Confidence Petroleum (LPG/Cylinder focus). These highlight a mixed outlook for the sector: robust CGD infrastructure-driven growth in CNG/PNG amid APM gas shortages, propane competition in industrials, and LNG supply tailwinds emerging post-2027. Sector volumes grew 10-19% YoY (CNG-led), but EBITDA margins softened (e.g., ATGL ~20%, GGL 4.5-5.5/SCM guidance) due to gas cost pressures. Government push for 15% gas share in energy mix (from ~7%) supports long-term positivity.
Tailwinds (Positive Drivers)
- Strong Volume Momentum in Priority Segments: CNG volumes up 13-19% YoY (ATGL: 18% Q2, GGL: 13%; vehicle base +15%). Domestic PNG connections surged (ATGL: >1M milestone, +54K H1; GGL: +42K H1). Non-Morbi industrials grew 1-8% QoQ.
- Infrastructure Expansion: ATGL: 662 CNG stations (+12), 14.5K inch-km pipeline; GGL: 834 stations (+4), 43.9K km network; PLL: Dahej 5MMTPA expansion by Mar’26, Kochi utilization at record 27%.
- Policy Support: APM/NWG priority for CNG/PNG (ATGL: 57-60%; GGL: 100% domestic); Gujarat VAT-to-CST shift (ATGL: ~13% EBITDA/SCM benefit, to be passed to consumers); PNGRB Zone-1 tariff for CGD (pending implementation); GST reforms boosting CNG vehicle costs down.
- LNG Supply Outlook: Global glut expected end-2027 (PLL: affordable spot prices); new long-term deals (GGL: Qatar 1MMTPA from 2026; Indian firms tying up at Dahej).
- Diversification: EV charging (ATGL: 4.2K points, +800 Q2); biogas injection (GGL); propane entry as hedge (GGL advanced talks); awards for HSE/sustainability (ATGL, GGL).
- Financial Resilience: Credit upgrades (ATGL: AA+); healthy EBITDA (PLL: ₹1,117Cr; ATGL: ₹603Cr H1); dividend payouts (PLL: ₹7/share).
Headwinds (Challenges)
- APM Gas Shortfall: Priority allocation declined (ATGL: 59% H1 vs. 70% prior; Q2: 35-36% APM + NWG=57%; GGL: 51-64% CNG shortfall). Replaced by costlier NWG/spot, pressuring margins.
- Propane Competition: Acute in industrials (GGL Morbi: 2.13MMSCmd Q2 from 2.51, run-rate 1.7-1.8; differential ₹4-6/SCM, narrowing; propane at 12% Brent vs. gas 17-18%). Winter propane strength expected.
- Weather/Seasonal: Heavy monsoons hit infra/volumes (ATGL/GGL).
- Pricing Volatility: Spot RLNG/crude down aided price cuts (GGL: -₹3.25/SCM), but dollar appreciation (+4%) and geospatial issues hurt.
- Utilization Gaps: Kochi low (PLL: 27% peak, pipeline delays); JV ramp-up slow (ATGL IOAGPL).
Growth Prospects
- Short-Term (FY26-27): 10-16% volume growth (CNG/domestic-led; GGL: 9-10MMSCmd FY26 if propane stable); new GA maturation (ATGL: 26% CNG growth; GGL: +0.5MMSCmd non-Morbi). PNG industrials +2-3lakh SCMD in 18 months (GGL).
- Medium-Term (FY27+): Gas share to 10-11% (PLL); CNG sales +18% (1-1.2M vehicles FY26); LNG imports up (PLL: expanded Dahej/Kochi; new Gopalpur terminal ~3yrs). Propane as volume stabilizer (GGL: target lost customers).
- Capex-Driven: ₹800Cr (GGL FY26), ₹5K Cr (PLL FY26 incl. petchem); steel pipeline reach for industrials.
- ESG/Market Shift: Cleaner fuel adoption (CNG 45% cheaper vs. petrol); EV/CBG/LNG trucking synergy.
| Metric | Q2 FY26 Snapshot | FY26 Guidance |
|---|---|---|
| Volumes | CNG +13-19%; PNG +9-11% | 9-10MMSCmd (GGL); double-digit (ATGL) |
| EBITDA/SCM | ₹4.5-6.5 (GGL/ATGL) | 4.5-5.5 (GGL) |
| Capex | ₹282Cr H1 (GGL) | ₹800Cr (GGL); ₹5K Cr (PLL) |
Key Risks
- Gas Sourcing/Allocation: APM/NWG decline (natural depletion + industry growth); reliance on spot/long-term (13-17% Brent/HH linked, volatile).
- Alternate Fuels: Propane/LPG erosion in industrials (GGL Morbi baseline risk); stable diesel/EV penetration in CNG.
- Regulatory Delays: Zone-1 tariff implementation (ATGL/PLL); PNGRB allocations (D.K. Saraf report under review).
- Commodity/Geo Risks: LNG price spikes (pre-2027 tightness); Brent/HH volatility; rupee depreciation/forex (PLL lease liability).
- Execution: Infra delays (monsoon, EC clearances e.g., PLL Gopalpur); JV profitability (ATGL IOAGPL); merger timelines (GGL scheme by Dec’25).
- Demand: Festival/monsoon seasonality; industrial slowdown (consumer goods).
Overall Summary: Positive skew with infrastructure/network effects driving 10-15% growth, bolstered by policy (APM/Zone-1) and future LNG glut. However, margin compression from APM shortages and propane (industrials ~50% volumes) caps upside; FY26 volumes/margins muted but FY27 inflection likely. Sector resilient (AAA ratings, dividends), but risks tilted to gas costs/competition. Bull case: 15% gas share; Bear: Prolonged propane edge erodes 20-30% industrial volumes. Investors favor diversified CGD/LNG plays like ATGL/PLL.
Financial
asof: 2025-11-30
Analysis of Indian LPG/CNG/PNG/LNG Supplier Sector
The provided documents encompass Q3 FY25 (ended Dec 2024) and FY25 (ended Mar 2025) financial results from key players: Adani Total Gas (ATGL) and Indraprastha Gas (IGL) (CGD: CNG/PNG), Petronet LNG (PLL) (LNG regasification/import), Gujarat Gas (GGL) (natural gas distribution), and Confidence Petroleum (CPIL) (LPG bottling/cylinders). These represent ~majority of India’s organized gas distribution/import ecosystem.
Overall sector shows resilient revenue growth (5-7% YoY) driven by volume expansion (e.g., IGL +7% sales volumes), but margin pressures from higher gas costs, receivables, and regulatory hurdles. Profits stable/mixed (e.g., ATGL PAT flat YoY, IGL down 18% 9M YoY, PLL PAT down QoQ). LNG/CGD focus on infrastructure expansion amid energy transition.
Tailwinds (Positive Drivers)
- Volume Growth & Demand Shift: Strong uptake in cleaner fuels. IGL: CNG +6% YoY, PNG Domestic +17%, PNG Ind/Comm +14% (9M FY25 volumes +7% to 8.93 MMSCMD). ATGL revenue +13% YoY Q3. GGL revenue +6% YoY. CPIL revenue +17% FY25 (LPG/CNG cylinders).
- Infrastructure Expansion: CGD networks scaling (ATGL pursuing Ludhiana/Jalandhar GAs; IGL subsidiaries/associates adding capacity). PLL stable LNG throughput with UoP income recognition (₹117 Cr Q3 FY25).
- Policy Support: Govt. push for natural gas (target 15% energy mix by 2030), PNG mandates in cities, EV/CNG synergy. Dividend payouts signal confidence (IGL 200% interim; CPIL 10% final).
- Financial Resilience: Low debt defaults (all “Not Applicable”). Revenue diversification (CNG/PNG >70% in CGD firms).
Headwinds (Negative Pressures)
- Cost Inflation: RM gas costs up (IGL EBITDA margin 10% vs 16% YoY; PLL cost of materials ~86% of revenue). Excise duty hikes noted.
- Receivables & Provisions: PLL’s ₹1,666 Cr gross UoP dues (provisioned ₹703 Cr; ongoing recovery via BGs). CPIL GST ITC mismatch (unquantified).
- Margin Compression: IGL PAT -27% QoQ/-18% 9M YoY despite volumes up. ATGL PAT flat YoY amid higher dep’n/finance costs.
- Delayed Approvals: ATGL/IGL facing PNGRB/APTEL delays (e.g., Jalandhar GA transfer; Noida/Faridabad bids).
Growth Prospects
- High (Medium-Term: 10-15% CAGR):
- CGD/PNG Penetration: Urbanization/industrialization to drive PNG (domestic +17% YoY). ATGL/IGL/GGL expanding GAs (e.g., ATGL’s 3 new GAs).
- LPG/LNG Upside: CPIL LPG revenue dominance (89% Q4); PLL LNG volumes stable with Dahej/Kochi ramps.
- Capex Momentum: CPIL ₹27 Bn capex (cylinders/LPG terminals); IGL subsidiary investments (₹30 Cr FY25).
- Exports/Imports: PLL’s JV expansions; CPIL Indonesia ops.
- Catalysts: SATAT scheme (CBG), EV infra (CNG synergy), gas pricing reforms.
Key Risks
| Risk Category | Description | Mitigation/Impact |
|---|---|---|
| Regulatory | PNGRB delays (ATGL/IGL bids); UoP disputes (PLL). Adani group overhang (SSR resolved per ATGL). | High; Ongoing litigations (e.g., Supreme Court/APTEL). |
| Financial/Compliance | CPIL qualified audit (GST ITC mismatch, PF liability per SC ruling); PLL ₹963 Cr net UoP exposure. | Medium-High; Potential ₹100s Cr provisions/write-offs. |
| Operational | Gas supply volatility (RMG prices); low utilization (PLL UoP). | Medium; Hedging/BGs in place. |
| Execution | Capex delays (CPIL terminal pivot to smaller facilities). | Medium; ₹73 Cr incremental borrowings (A-rated). |
| Market | Competition (IOCL/Reliance); monsoon/volumes seasonality. | Low-Medium; Oligopoly in CGD. |
Summary: Sector poised for 10%+ growth via PNG/CNG adoption and infra (tailwinds > headwinds), but regulatory/compliance risks cap near-term upside (e.g., PLL/ATGL provisions). Investors favor IGL/GGL (strong volumes); monitor CPIL audits/PLL UoP recovery. FY26 outlook positive with policy tailwinds, but gas pricing key watch.
General
asof: 2025-12-03
Analysis of Indian LPG/CNG/PNG/LNG Supplier Sector
Using the provided documents (financial results, investor presentations, disclosures from Adani Total Gas, Petronet LNG, Gujarat Gas, Mahanagar Gas, Confidence Petroleum, and IRM Energy), here’s a structured summary of headwinds, tailwinds, growth prospects, and key risks for the sector. These companies represent key players in City Gas Distribution (CGD: PNG/CNG), LNG regasification/processing, and related infrastructure. Insights are derived from Q2/H1 FY26 performance, operational metrics, regulatory filings, and strategic updates as of Nov-Dec 2025.
Tailwinds (Positive Factors)
- Strong Operational Momentum: Volumes grew across players (e.g., Gujarat Gas: Total 8.65 MMSCMD in Q2FY26, CNG +13% YoY; IRM Energy: PNG industrial steady at ~55 mmscm/quarter; Petronet LNG: Revenue ₹22,889 Cr in H1FY26). Infrastructure expansion evident (IRM: 116 CNG stations, 6,071 inch-km pipeline; Gujarat Gas: 834 stations, ~43,900 km pipeline).
- Government & Policy Support: CGD push via PNGRB authorisations (IRM: 4 GAs covering 6 districts; Gujarat Gas: 27 districts). Biofuel blending (Gujarat Gas: CBG offtake at 9 sites; IRM/Gujarat: H2 blending pilots). Schemes like FDODO (Gujarat Gas: 1st station commissioned, 74 agreements) and retrofits (IRM: 3W/4W/LCV focus).
- Financial Resilience: Healthy EBITDA margins (Petronet: 10%; Gujarat Gas: ₹520 Cr Q2FY26; IRM: ₹322 Mn Q2FY26). Dividends declared (Petronet: ₹7/share; Gujarat Gas consistent). Debt reduction/cash-rich (Gujarat Gas: ₹2,000 Cr cash reserves).
- Sustainability Edge: Adani Total Gas: 72/100 S&P CSA score (85th percentile). ESG initiatives (tree plantation, solar, green H2/CBG blending).
- Consolidation Plays: Gujarat Gas scheme (GSPC/GSPL merger + demerger) to create integrated value chain player.
Headwinds (Challenges)
- Revenue Pressure from Gas Mix: Lean APM gas allocation impacted sales (IRM: Q2FY26 revenue dip QoQ; Petronet: Cost of materials ~87% of revenue).
- Receivables & Provisions: Petronet: ₹1,393 Cr UoP dues (provision ₹736 Cr, up from ₹469 Cr); waivers (₹29 Cr). Gujarat Gas/IR M stable but capex-heavy.
- Regulatory/Financial Disputes: Mahanagar Gas: ₹543 Cr GST demand upheld (RCM on reinstatement charges; appeal to tribunal planned, no expected outflow).
- Opex Inflation: Employee costs up (Petronet: ₹123 Cr H1FY26); depreciation rising with capex (IRM: ₹212 Mn H1FY26).
- Volume Variability: Industrial/PNG domestic growth slower in new GAs (IRM Namakkal/Trichy: nascent); seasonal/monsoon impacts.
Growth Prospects
- Volume Expansion: CGD penetration accelerating (IRM: 77,935 domestic connections; Gujarat Gas: 23.44L PNG homes). CNG push (Gujarat: 3.32 MMSCMD Q2FY26; IRM: 4 new stations Q2FY26; TNSTC 100+ buses for IRM).
- Infrastructure Scale-Up: Pipeline growth (IRM: Ahead of MWP targets); CNG stations to 834+ (Gujarat). New models (FDODO, co-located with Nayara Energy).
- Diversification: LNG/CBG/H2 blending (Petronet: Dahej/Kochi terminals; Gujarat: 19 CBG deals). EV synergies (IRM/Gujarat charging infra).
- Financial Upside: Revenue/EBITDA CAGR strong (IRM: Revenue ₹10,564 Mn FY25; Petronet PAT ₹1,656 Mn H1FY26). IPO/capex utilization (IRM: ₹2,609 Mn spent of ₹4,958 Mn).
- M&A/Listing: Gujarat Gas post-merger entity (GTL listing by Feb 2026) for pan-India gas value chain. Target: 10-15% volume CAGR via urban/rural penetration.
Key Risks
| Risk Category | Description | Evidence from Docs | Mitigation |
|---|---|---|---|
| Regulatory/Legal | GST disputes (RCM on road reinstatement); PNGRB approvals/delays; UoP recovery. | Mahanagar: ₹543 Cr upheld; Petronet: ₹1,393 Cr dues. | Appeals/tribunals; bank guarantees; contractual obligations. |
| Pricing/Supply | APM/non-APM gas volatility; UoP waivers. | Petronet impairment ₹296 Mn H1FY26; IRM lean gas impact. | Diversified sourcing; recovery mechanisms. |
| Operational | Capex overruns (₹9 Bn+ spent by IRM); volume shortfalls in new GAs. | Gujarat/IR M: Heavy infra capex; MWP compliance. | Phased rollout; OEM tie-ups (Maruti/Tata). |
| Financial | Debt (IRM/Petronet borrowings); forex/interest costs. | Petronet finance ₹120 Mn H1FY26; IRM repayments via IPO. | Cash reserves; dividends sustained. |
| Market/Competition | EV/electric adoption; oil price competition. | CNG retrofits needed; blending pilots nascent. | Schemes (3W/4W); sustainability scores. |
| ESG/External | Climate regs; monsoon disruptions. | Adani high CSA score; tree plantation drives. | Green H2/CBG; robust networks. |
Overall Sector Outlook: Positive with Moderate Risks. Tailwinds from policy/infra dominate (CGD saturation low at ~5-7% households), driving 12-15% volume growth. Headwinds (dues/regulatory) provisioned (~₹736 Cr at Petronet), not material. FY26 guidance: 10-12% revenue growth, EBITDA margins 12-14%. Sector PE ~20-25x; attractive for long-term investors amid India’s gas share target (15% by 2030).
Investor
asof: 2025-11-30
Analysis of Indian LPG/CNG/PNG/LNG Supplier Sector
Using the provided transcripts and announcements from key players (Adani Total Gas - ATGL, Petronet LNG, Gujarat Gas - GGL, Indraprastha Gas - IGL, Mahanagar Gas - MGL, and Confidence Petroleum), this analysis covers the City Gas Distribution (CGD) ecosystem (CNG/PNG), LNG regasification/import, and LPG segments. The sector benefits from India’s push for cleaner fuels (targeting 15% gas in energy mix from ~7%), but faces sourcing and competitive pressures. Data is from Q2/H1 FY26 (Apr-Sep 2025) earnings calls.
Tailwinds (Positive Factors)
- Robust Volume Growth in Priority Segments: CNG volumes up 13-19% YoY (ATGL: 18-19%, GGL: 13%); domestic PNG up 9-11% (ATGL), with >1M homes added (ATGL milestone). Vehicle base growing (GGL: 15% YoY to 16.22L). Non-Morbi industrial steady/growing 1-15% (GGL).
- Infrastructure Expansion: ATGL: 662 CNG stations (+12), 14.5K inch-km pipeline; GGL: 834 stations (+4), 43.9K km network. Petronet: Dahej at 211 TBtu, Kochi peak 27% utilization (BPCL cargoes); +5 MMTPA by Mar’26.
- Regulatory/Govt Support: Gujarat VAT realignment (15% to 2% CST from Oct’25, ~13% EBITDA/SCM benefit, to be passed on - ATGL). PNGRB Zone 1 tariff for CGD (pending implementation). 100-105% APM for domestic PNG; hopes for CNG boost (D.K. Saraf committee). Awards for safety/sustainability (ATGL, GGL).
- Cost/Supply Dynamics: Diversified sourcing (Henry Hub 16-17%, Brent 13%, HPHT/NWG); global LNG glut expected 2027-28 (Petronet, GGL). Lower spot RLNG/crude aided industrial pricing (GGL: -INR3.25/SCM).
- Diversification: EV charging (ATGL: 4.2K points, 42MW); biogas/hydrogen pilots (GGL); propane entry (GGL). Strong ratings (ATGL: AA+).
- Financial Health: Healthy EBITDA (ATGL: INR603cr H1; GGL: INR520cr Q2); dividends (Petronet: Rs7/share); capex guided (GGL: INR800cr FY26; Petronet: INR5K cr).
Headwinds (Challenges)
- APM/NWG Allocation Decline: Priority sector shortfall 51-64% (GGL CNG); ATGL H1: 59% (Q2: 35-36%, Q1:60%). Substitution with costlier NWG/spot, pressuring margins (ATGL EBITDA flat despite 16% volumes).
- Industrial/Commercial Pressure: Morbi (ceramics) volumes down 8-15% QoQ (GGL: 2.13 MMSCMD, run-rate 1.7-1.8); propane competitive (NG premium INR4-6/SCM, seasonal). Overall industrial down amid festivals/monsoon.
- Volume Mix Shifts: Petronet: Lower term LNG (shift to spot/regas, Dahej 116 TBtu); scheduling/monsoon impacted growth.
- Pricing Volatility: Spot RLNG high (17-18% Brent); forex/lease losses (Petronet: INR84cr). Margins guided lower (GGL: 4.5-5.5/SCM vs. 6.54 Q2).
- Underutilization: Kochi ~27% (Petronet); new areas maturing slowly.
Growth Prospects
- Short-Term (FY26-27): CNG/PNG penetration in 34+ GAs (ATGL: 95 districts); new connections (GGL: +27K Q2). Industrial upside from steel pipelines (GGL: +0.2-0.3 MMSCMD in 18 months; +0.5 MMSCMD FY27). Kochi pipeline commissioning FY26 (Petronet). Propane hedging (GGL: tie-ups with ports/suppliers). Volumes: GGL eyes 9-10 MMSCMD FY26 (sub-9 if propane persists).
- Medium-Term (FY27+): Global LNG supply wave (US/Qatar/Russia; spot $7-8/MMBtu). CGD target 15% energy share (10-11% feasible). EV (ATGL: 10K points); JV expansions (ATGL-IOCL: 1,095 stations). Petchem/Gopalpur (Petronet). MGL/IGL/Confidence analyst meets signal investor interest.
- Capex-Driven: INR800cr (GGL), INR5Kcr (Petronet) for networks/terminals. M&A/schemes (GGL-GSPC merger by Dec’25).
| Segment | FY26 Volume Outlook | Key Driver |
|---|---|---|
| CNG/PNG (CGD) | +10-16% YoY | Infra + Vehicles |
| Industrial PNG | Flat/Sub-10 MMSCMD (GGL) | Propane competition |
| LNG Regas | Stable/Up (Petronet: Dahej exp.) | Spot + Kochi ramp-up |
| LPG | Steady (Confidence focus) | Industrial shift |
Key Risks
- Sourcing/Allocation: APM dependency (decline offsets growth); geopolitical volatility (Russia/Ukraine). No long-term LNG tie-ups yet (Petronet Qatar pricing pending).
- Competition: Propane/LPG eroding industrial share (Morbi baseline 1.7 MMSCMD at risk); EV/MS-HSD stability vs. CNG.
- Regulatory/Delays: Zone 1 tariff nuances; EC/project slips (Petronet Gopalpur/Dahej); PNGRB allocations/use-or-pay (Petronet: INR694cr CY22 pending).
- Macro: Monsoon/festivals; Brent/spot volatility; rupee depreciation (Petronet forex hits).
- Execution: Capex overruns (Petronet petchem INR600cr spent); merger delays (GGL). Low Kochi utilization if pipeline slips.
Summary
The Indian CGD/LNG sector shows resilient growth (16% volumes ATGL, 13% CNG GGL) driven by infra/network expansion and govt. support (VAT/Zone 1), but headwinds from APM cuts (35-60%) and propane competition cap margins (guided 4.5-5.5/SCM) and industrial volumes (Morbi muted). Prospects brighten post-2027 with LNG glut enabling 10-15% gas share, EV/propane diversification. Risks center on sourcing costs (60% priority reliance) and alternates. Overall outlook positive for CNG/domestic (double-digit growth), cautious for industrial/LNG (stable but volatile). Sector capex (~INR6Kcr FY26) positions for 10-12 MMSCMD+ volumes; monitor APM reforms and global supply. Investors favor leaders like ATGL/GGL (AA+ ratings, EV/JV plays).
Recommendation: Accumulate on dips; focus on diversified players (ATGL/Petronet) for 12-15% CAGR FY26-28.
Meeting
asof: 2025-12-01
Analysis of Indian LPG/CNG/PNG/LNG Sector (as an Supplier Perspective)
The provided documents cover Q2FY26 (H1FY26) financial results, AGMs, board outcomes, and announcements from key players like Adani Total Gas (ATGL), Gujarat Gas (GGL), IRM Energy, Confidence Petroleum, Mahanagar Gas (MGL), and Petronet LNG. These firms dominate City Gas Distribution (CGD) for CNG/PNG, LPG bottling, and LNG infrastructure. Overall, the sector shows resilient volume growth (CNG up 10-20% YoY) driven by urbanization, vehicle adoption, and govt. push for gas in energy mix (target: 15% by 2030). Revenue grew 10-20% YoY across most, but PAT margins softened (12-15% EBITDA) due to higher gas costs. As a supplier (LPG/CNG/PNG/LNG), opportunities lie in upstream integration, but risks from regulation persist.
Tailwinds (Positive Drivers)
- Volume Expansion: CNG sales surged (ATGL: implied growth; IRM: +20% YoY to 31.89 mmscm; GGL steady). PNG-Domestic up 42% (IRM). Total volumes: ATGL/GGL/IRM ~10-14% YoY.
- Revenue Momentum: ATGL ₹3,075 Cr H1 (+20% YoY); GGL ₹8,044 Cr (+flat but high base); IRM ₹5,673 Cr (+15%). Driven by pricing power and infra (new CNG stations: IRM +4; ATGL expansions).
- Financial Health: Strong balance sheets (ATGL equity ₹4,509 Cr; GGL ₹8,663 Cr). Cash flows robust (IRM op. cash ₹825 Cr; GGL ₹1,021 Cr). IPO funds utilized for capex (IRM: ₹729 Cr spent).
- Policy Support: PNGRB authorizations (ATGL Jalandhar); schemes for bio-CNG/LNG (IRM VPPL investment).
- Backward Integration: Cylinder production (IRM Venuka 50% stake; Confidence LPG focus).
Headwinds (Challenges)
- Margin Pressure: PAT dipped YoY (ATGL ₹329 Cr H1 vs ₹357 Cr; IRM ₹265 Cr vs ₹307 Cr) due to gas cost inflation (ATGL ₹1,926 Cr H1). EBITDA margins 12-15% (IRM down from 15%).
- Industrial Slowdown: PNG-I&C volumes flat/down 1-6% (IRM/GGL), impacted by economic slowdown/manufacturing dip.
- Regulatory Delays: PNGRB disputes (ATGL Noida/Faridabad; Sanand); schemes pending MCA/NCLT approval (GGL composite scheme; IRM Enertech merger).
- Dues Recovery: Associates issues (IRM FGPL ₹167 Cr dues; ATGL US DOJ indictment note – no material impact).
Growth Prospects
- CGD Network Expansion: 9+ GAs operational (ATGL/GGL/IRM); new PNG homes (IRM +1,657 Q2). CNG stations ramp-up (IRM 116 total).
- Volume Targets: FY26 guidance implicit: 10-15% growth (CNG/PNG-D). Domestic PNG penetration (target 10 Cr homes by 2030).
- Diversification: Bio-CNG (IRM SKI-Clean); cylinders/LPG (Confidence); LNG regas (Petronet). Backward integration (IRM VPPL cylinders).
- Capex Pipeline: ₹1,800-2,000 Cr FY26 (ATGL CWIP ₹1,834 Cr; IRM ₹1,067 Cr). IPO funds for Tamil Nadu GAs (IRM ₹2,344 Cr unspent).
- M&A/Schemes: Amalgamations (IRM Enertech; GGL GSPC/GSPL) to simplify structure, no dilution.
Key Risks
- Gas Price Volatility: 70-80% costs tied to imported LNG; APM price hikes could squeeze margins (ATGL gas cost +26% YoY).
- Regulatory/Approval Risks: PNGRB litigations (ATGL 3 GAs); scheme sanctions (GGL/IRM pending MCA/NCLT). Delays cap infra rollout.
- Competition/Supply Constraints: Intense CGD rivalry (Adani/GAIL/Reliance); upstream shortages.
- Execution/Financial: High capex (debt up in some); recoverability (IRM FGPL ₹168 Cr). Forex (LNG imports).
- Macro: Industrial slowdown; EV shift eroding CNG (~60% volumes).
Summary Outlook: Bullish on 10-15% volume CAGR to FY27 (CNG/PNG tailwinds), supported by infra/capex. Margins resilient at 12-15% EBITDA. Prioritize regulatory navigation and cost hedging as supplier. Sector PE ~20-25x; ATGL/IRM attractive for growth. Monitor Q3 volumes for festive demand.
Press Release
asof: 2025-11-30
Summary Analysis: Indian LPG/CNG/PNG/LNG Sector (Based on Provided Documents)
The documents cover key players in India’s City Gas Distribution (CGD), LNG, and LPG sectors—primarily Adani Total Gas (ATGL), Gujarat Gas (GGL), Mahanagar Gas (MGL), Petronet LNG, and Confidence Petroleum. These reflect Q2/H1 FY26 performance (ending Sep 2025), operational expansions, strategic moves, and challenges amid India’s push for natural gas (target: 15% energy mix share by 2030). Overall, the sector shows resilient volume growth driven by CNG/PNG demand but faces margin pressure from gas costs. Below is a structured analysis of headwinds, tailwinds, growth prospects, and key risks.
Headwinds (Challenges Pressuring Margins and Costs)
- Rising Gas Costs and Supply Constraints: APM gas allocation fell to 59% (H1 FY26) from 70% (H1 FY25), forcing reliance on costlier NWG/HPHT gas (up 29-30% YoY). HPHT price at $9.77/MMBTU post-Oct 2025 offers minor relief, but NWG allocation dropped to 2.4 MMSCMD. This led to EBITDA decline (ATGL: -3% YoY to ₹603 Cr H1; GGL: ₹520 Cr Q2 vs. ₹553 Cr prior).
- Currency Headwinds: USD appreciation (~4% YoY) inflated imported gas costs, squeezing gross profits (ATGL: flat at 1% YoY growth).
- EBITDA/PAT Compression: Despite 13-20% revenue/volume growth, PAT fell 9% YoY (ATGL: ₹324 Cr H1; GGL: ₹281 Cr Q2), due to calibrated pricing to sustain volumes.
- Strategic Shifts: Confidence Petroleum abandoned a large LPG import terminal at JNPA amid volatility, signaling capex caution in logistics/infrastructure.
Tailwinds (Supportive Factors Driving Resilience)
- Strong Volume Momentum: CNG up 13-19% YoY (ATGL: 191 MMSCM Q2; GGL: 3.32 mmscmd); total sales 8.65-280 MMSCM. PNG domestic grew 9-11%, crossing 1M households (ATGL).
- Infrastructure Expansion: CNG stations rose to 662 (ATGL, +12 Q2) and 834 (GGL, +4 Q2); steel pipeline ~14,524-43,900 Inch-Km. FDODO/DODO models accelerating (GGL: 74 agreements).
- Improved Credit Profile: ATGL upgraded to AA+ (Stable) by ICRA/CRISIL/CARE, reflecting scale, parentage (Adani/TotalEnergies), and healthy net debt/EBITDA (1.16x).
- Diversification and Awards: EV charging (ATGL: 4,209 points, 42 MW); biomass (804 MT CBG sold H1); PNGRB awards for safety/sustainability. Digital platforms (SOUL, apps) boost efficiency/customer delight (98.5% digital payments).
- Promoter Strength: Adani/TotalEnergies backing; MGL-OIL MoU for LNG/clean energy.
Growth Prospects (High-Potential Opportunities)
- CGD Network Scale-Up: 34+ GAs (ATGL), pan-India footprint (GGL: 6 states/1 UT); PNG homes to 1.02M+ (ATGL), 23.44L (GGL). Target: Accelerated CNG/PNG adoption via 1,095 stations (incl. JVs).
- LNG/Clean Energy Pivot: MGL-OIL collaboration for LNG in heavy-duty transport; ATGL’s e-mobility/biomass (Harit Amrit expansion); GGL FDODO push.
- Retail/Last-Mile Focus: Confidence shifting to LPG/CNG retail (287 Auto LPG, 45 CNG outlets); small LPG terminals for efficiency.
- Policy Tailwinds: Natural gas push (7% to 15% mix); diversified sourcing (Brent-linked ~14%); matured GAs funding capex via accruals.
- Sustainability/ESG: Decarbonization (100% fleet), solar (967 kW), tree plantation; CRISIL ESG rating up to ‘61-Strong’ (ATGL).
Key Risks (Critical Vulnerabilities to Monitor)
- Gas Allocation/Price Volatility: APM shortfall (~52% H1 FY26) and global LNG dynamics could sustain cost pressures; recalibration via long-term contracts unproven at scale.
- Regulatory/Policy Shifts: PNGRB pricing, GA approvals, or APM changes; GGL’s scheme of arrangement pending MCA/NCLT finality.
- Execution/Capex Risks: High infrastructure spend (ATGL: ₹261 Cr added); debt up slightly (healthy ratios but scaling needed). Delays in FDODO/EV rollout.
- Macro/External: FX volatility, monsoon impacts on demand; competition in CGD (53 GAs total).
- Strategic/Operational: Over-reliance on CNG (76% ATGL volume); Confidence’s terminal pivot risks logistics bottlenecks.
Overall Outlook: Positive growth trajectory (16%+ volumes) with margin resilience via pricing/opex optimization, but watch gas costs (potential EBITDA recovery if APM stabilizes). Sector poised for 15-20% CAGR in volumes, backed by infra/digital push, but needs diversified sourcing to mitigate risks. ATGL/GGL lead CGD; MGL/Confidence add LNG/LPG diversity.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.