IDBI
Equity Metrics
November 18, 2026
IDBI Bank Limited
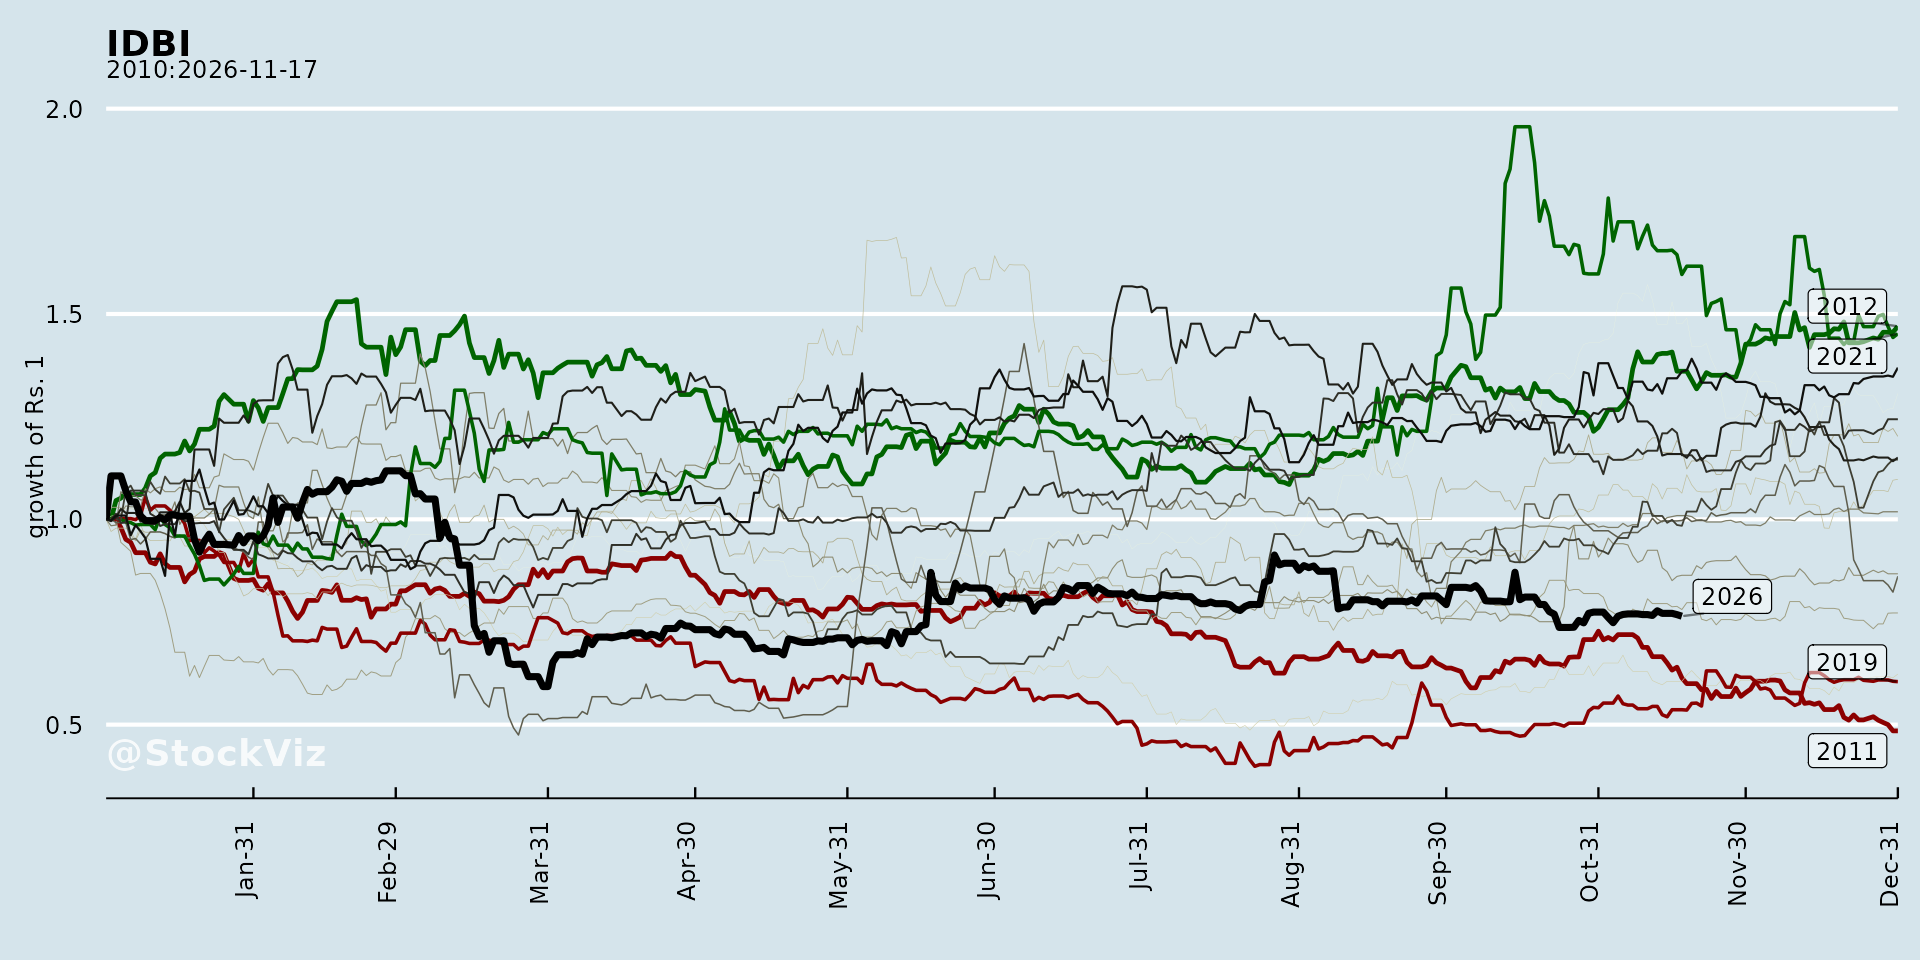
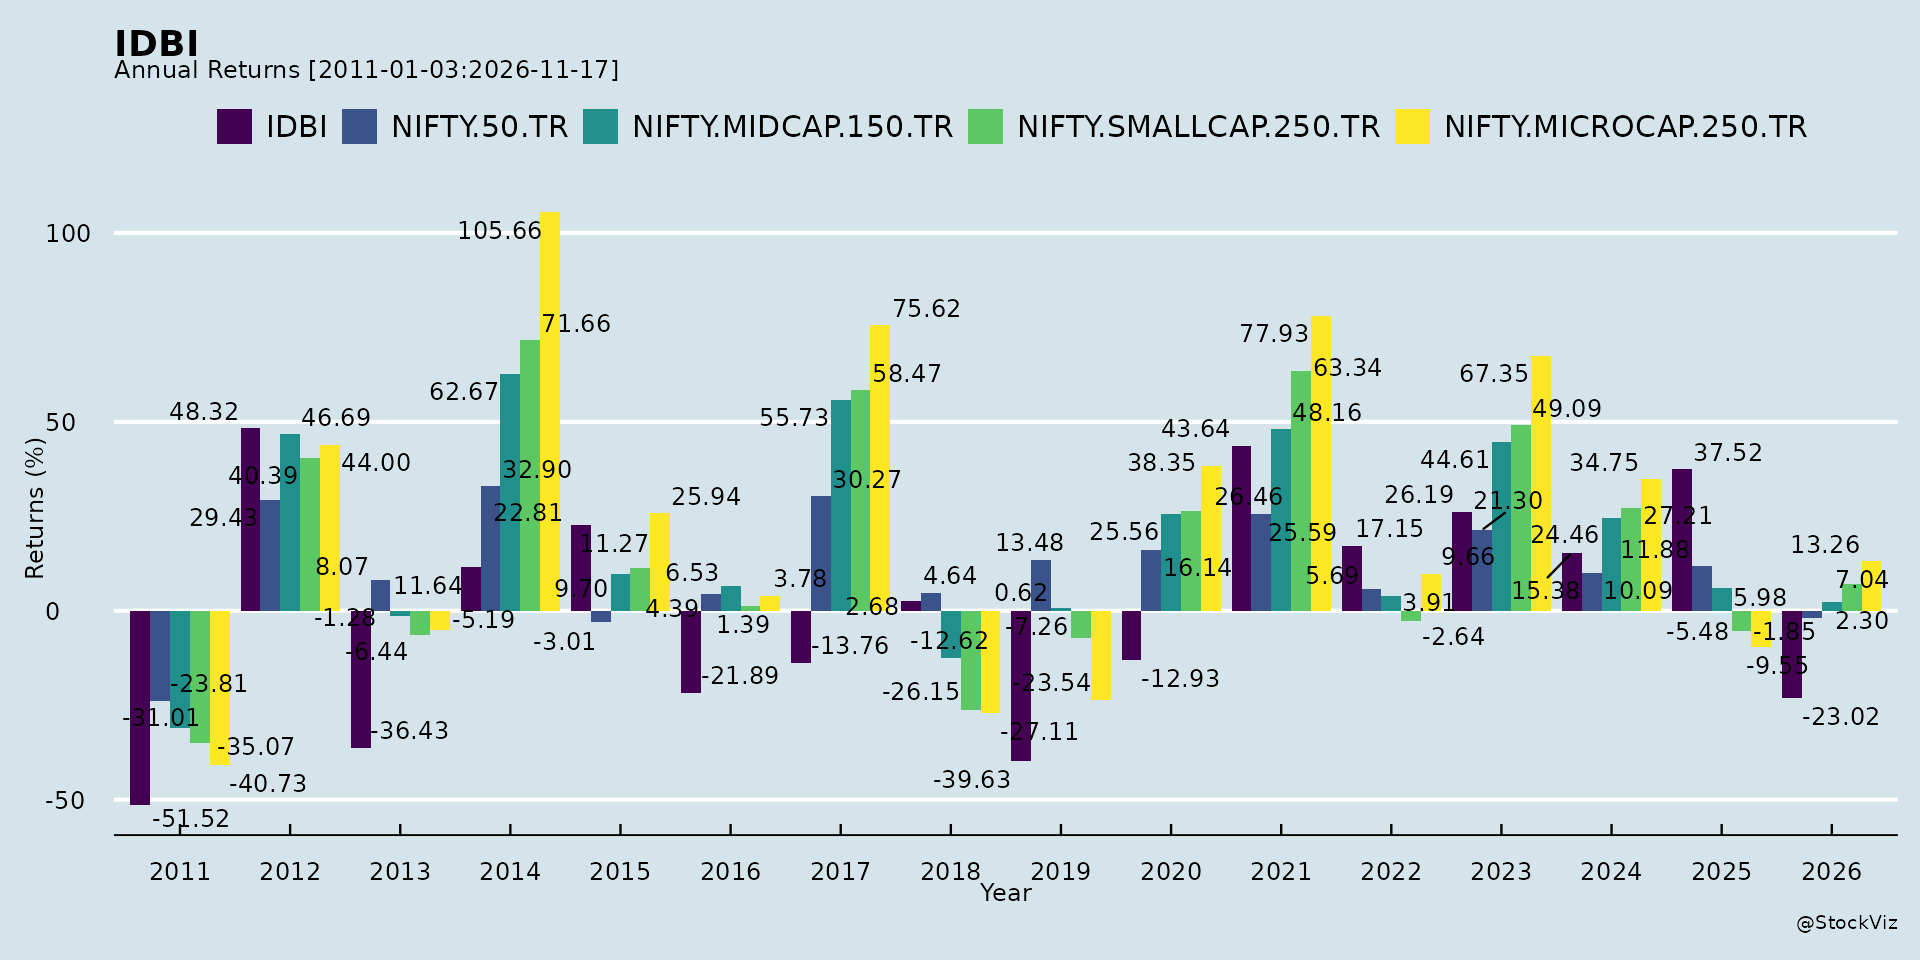
Annual Returns
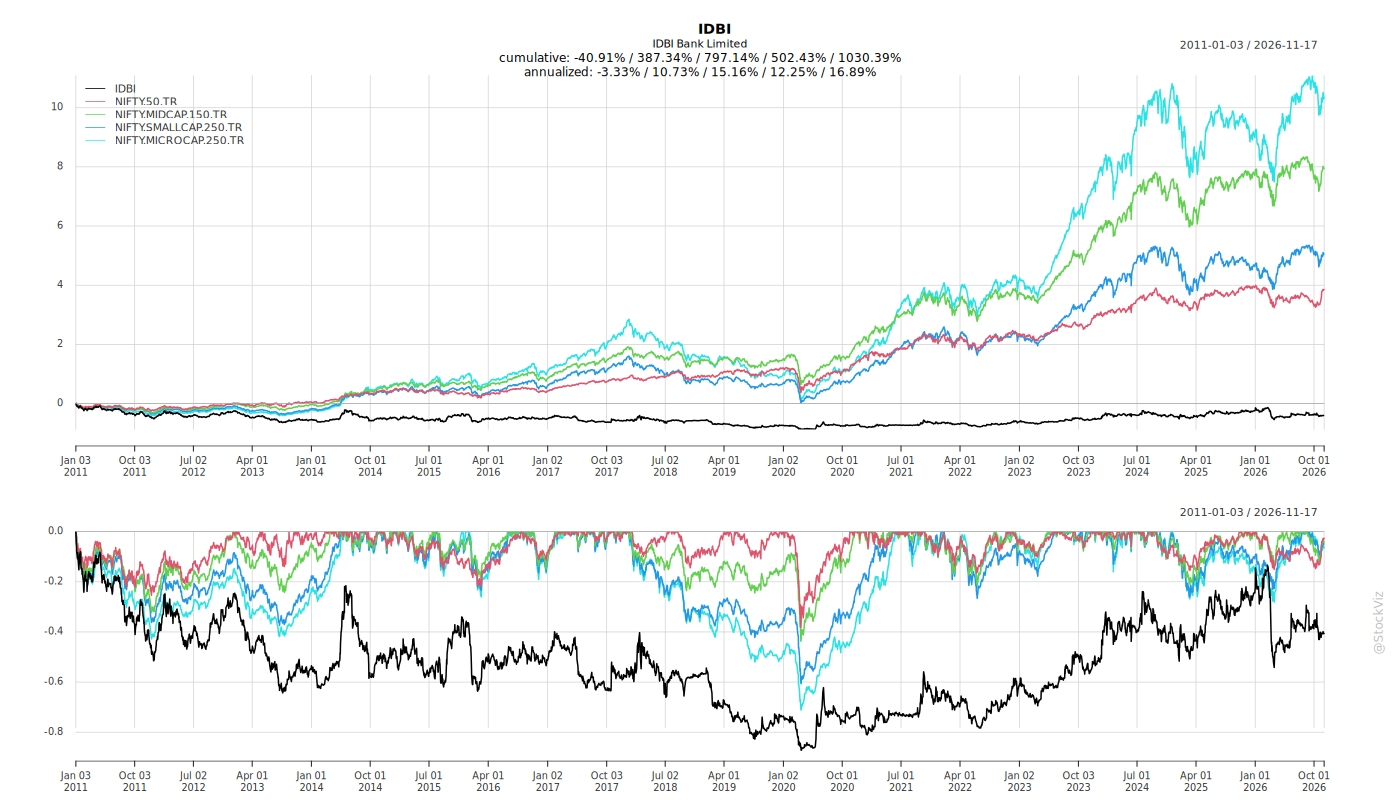
Cumulative Returns and Drawdowns
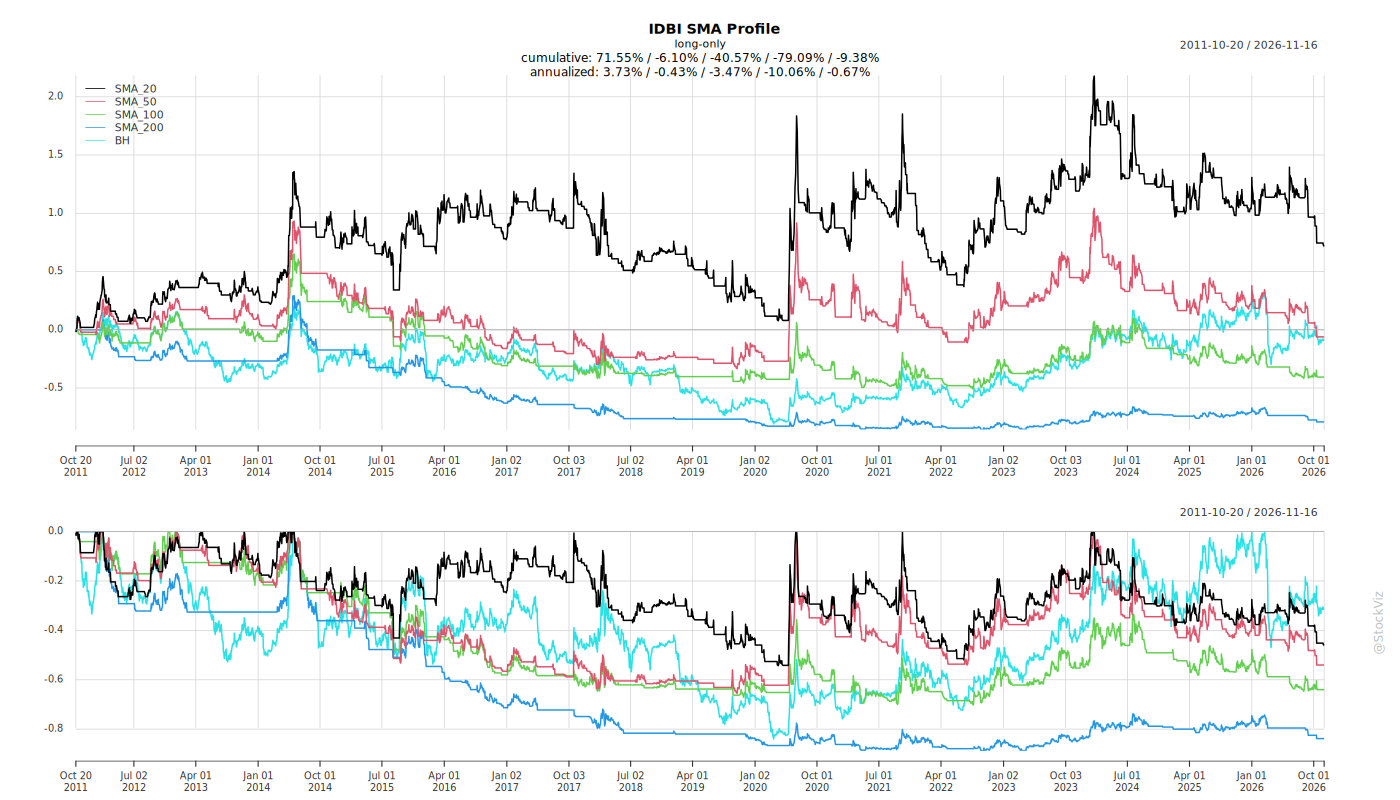
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
Headwinds and Challenges
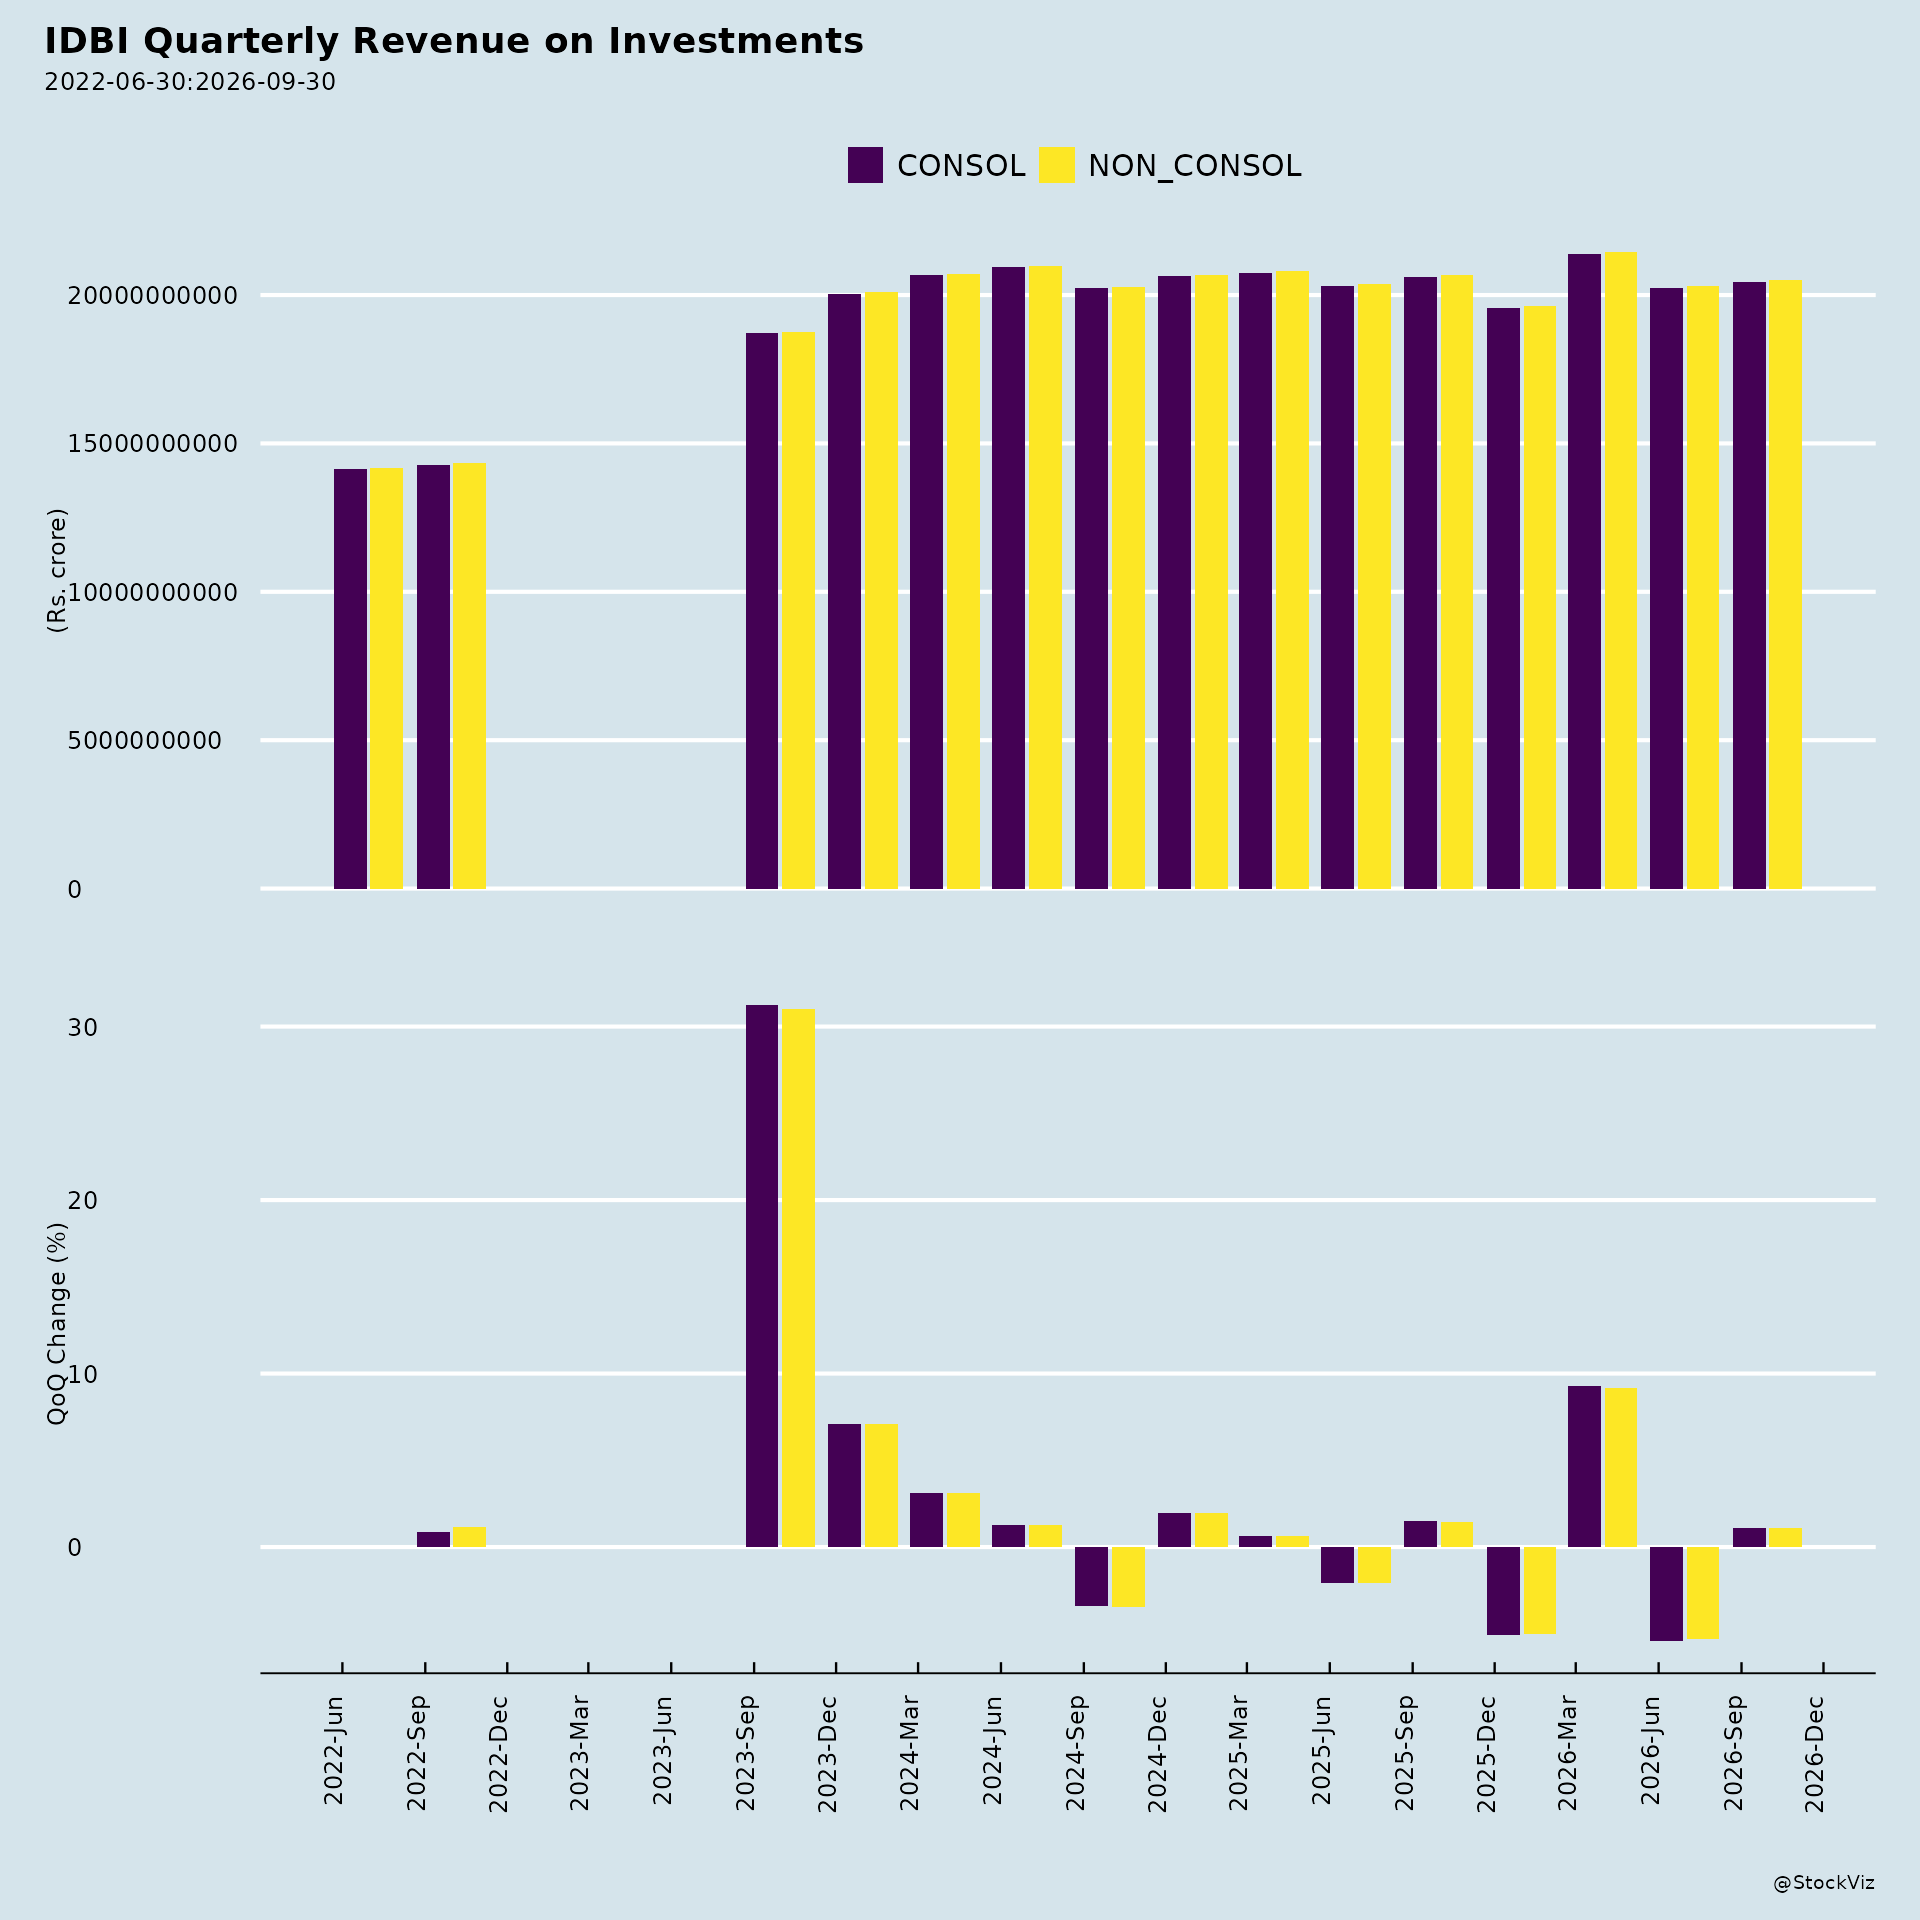
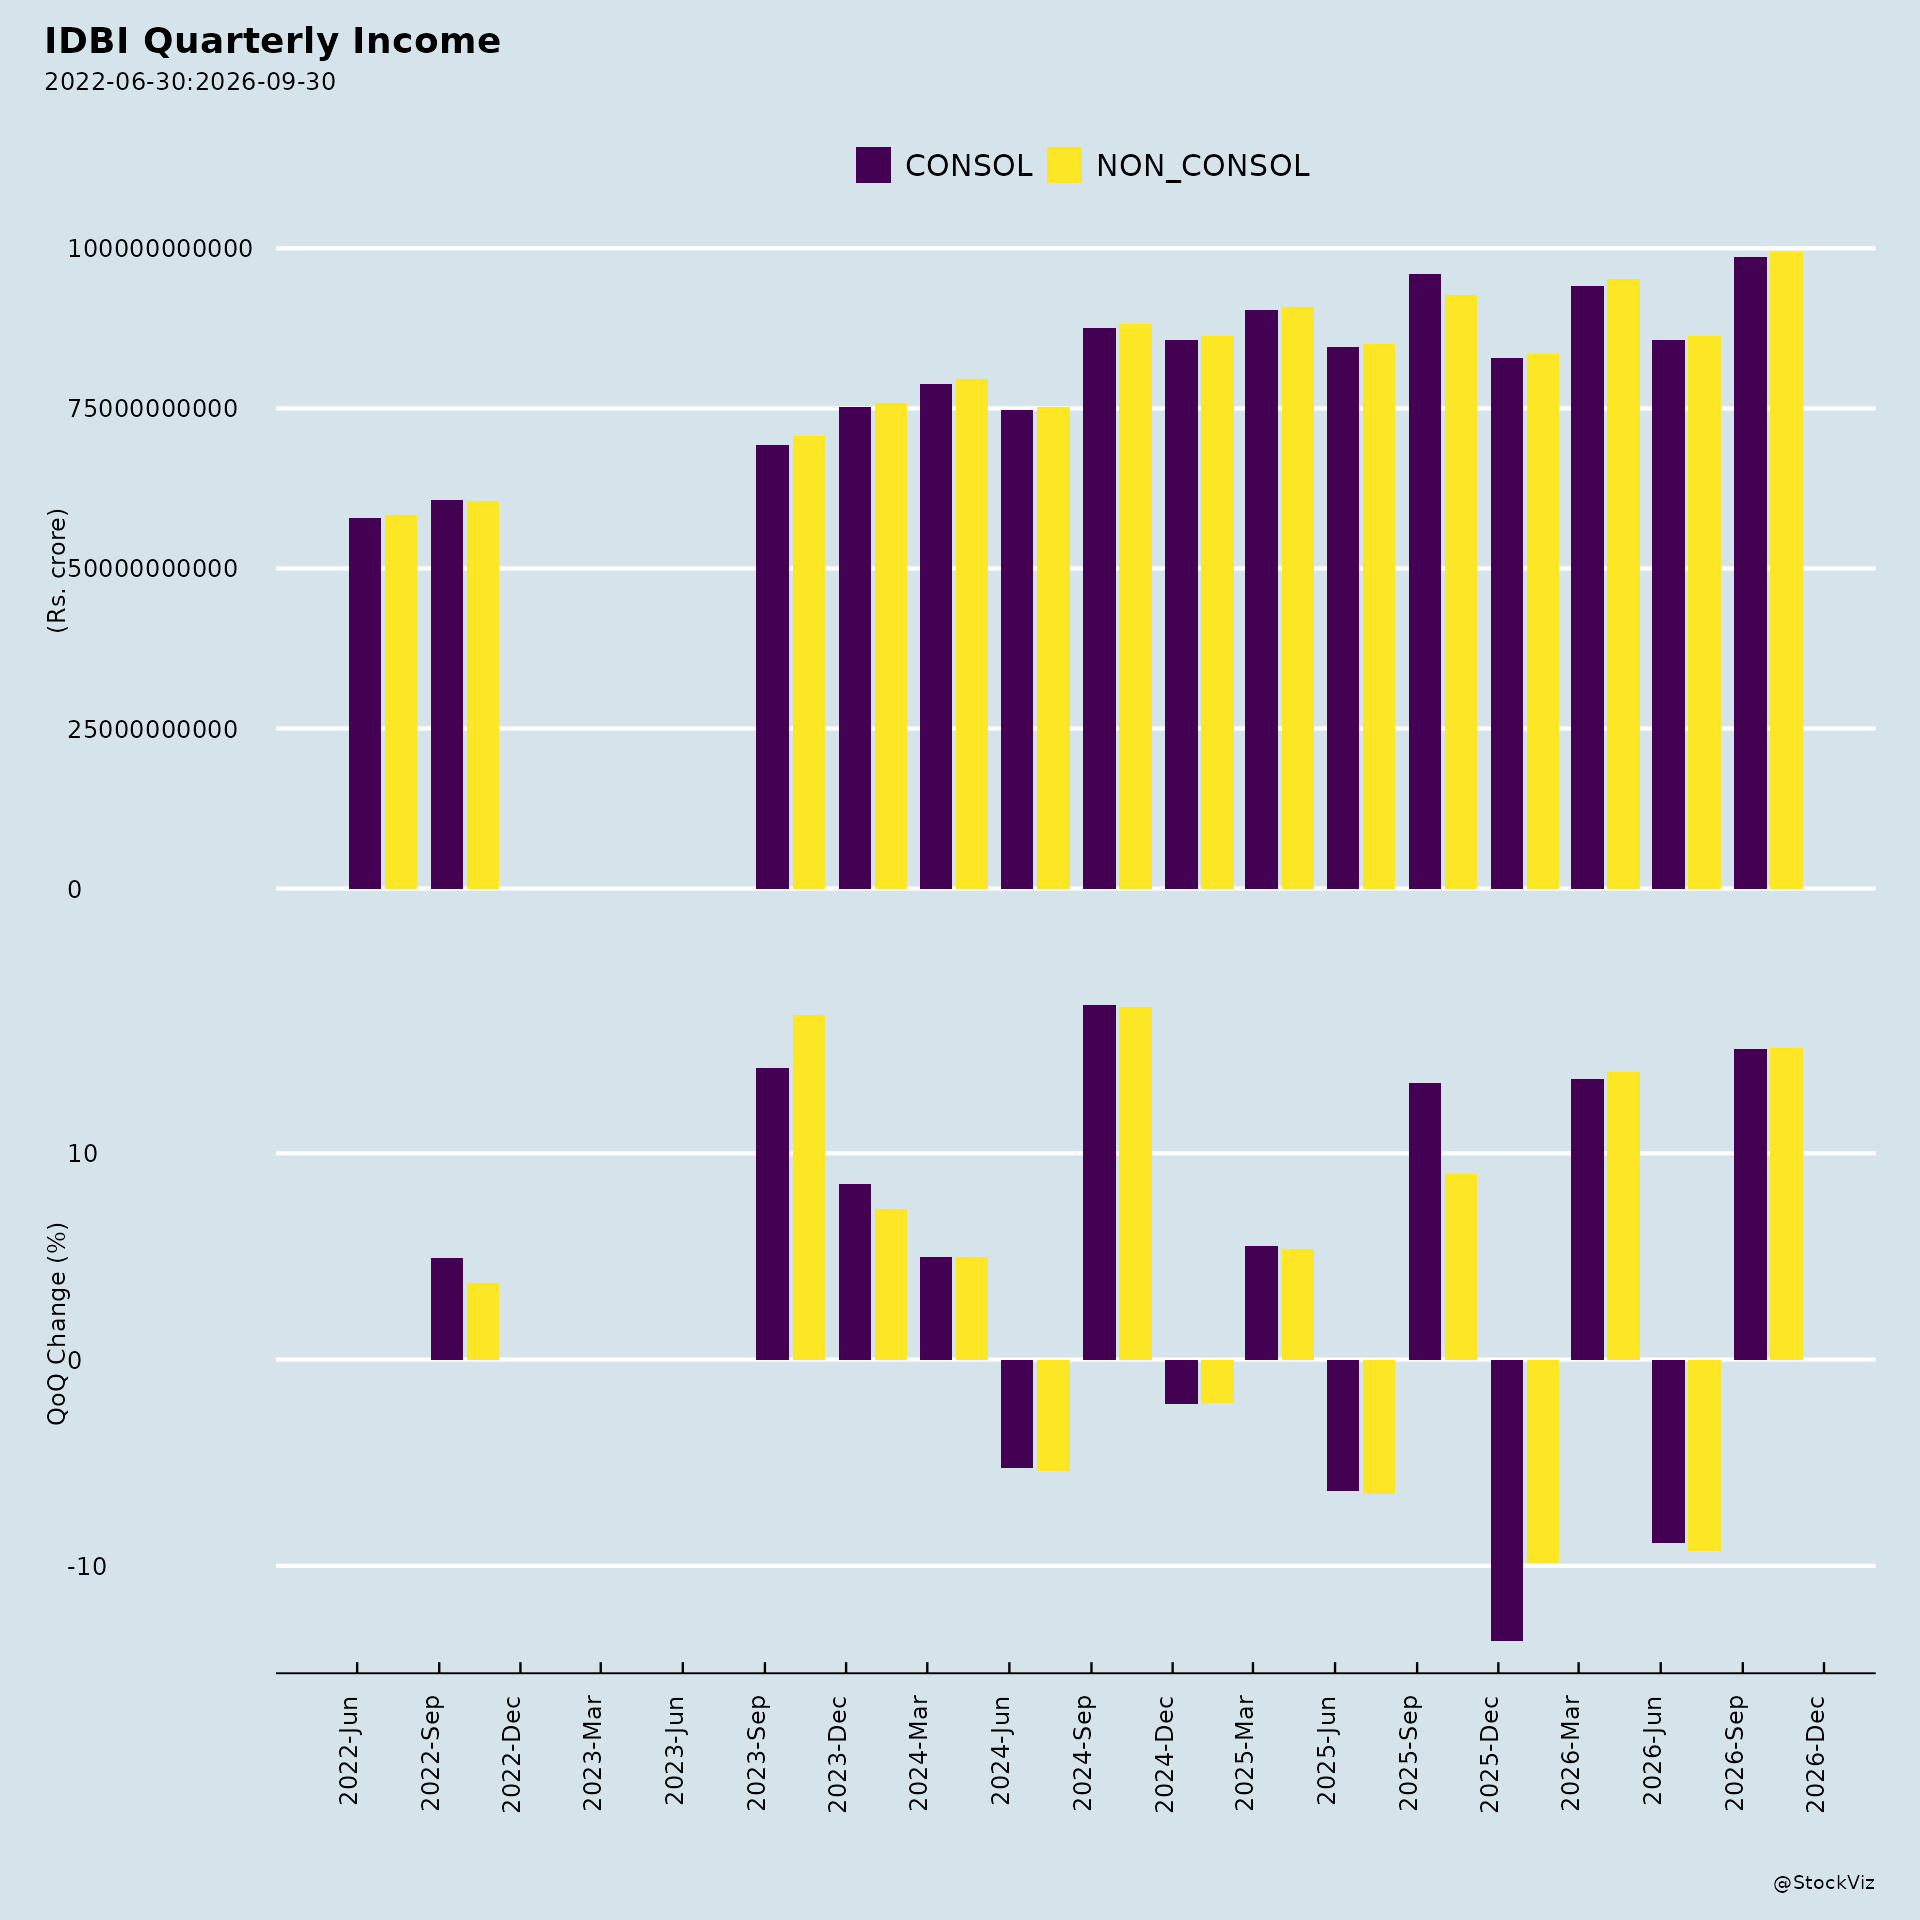
- Sequential contraction in core income. Net interest income fell 9% quarter-on-quarter (₹3,851 crore in Q4 FY2026 to ₹3,486 crore in Q1 FY2027), and interest income declined 3% QoQ. Non-interest income fell sharply — down 36% QoQ and 28% year-on-year — pulling non-interest income to total income down to 12.03% from 17.12% QoQ and 16.99% YoY.
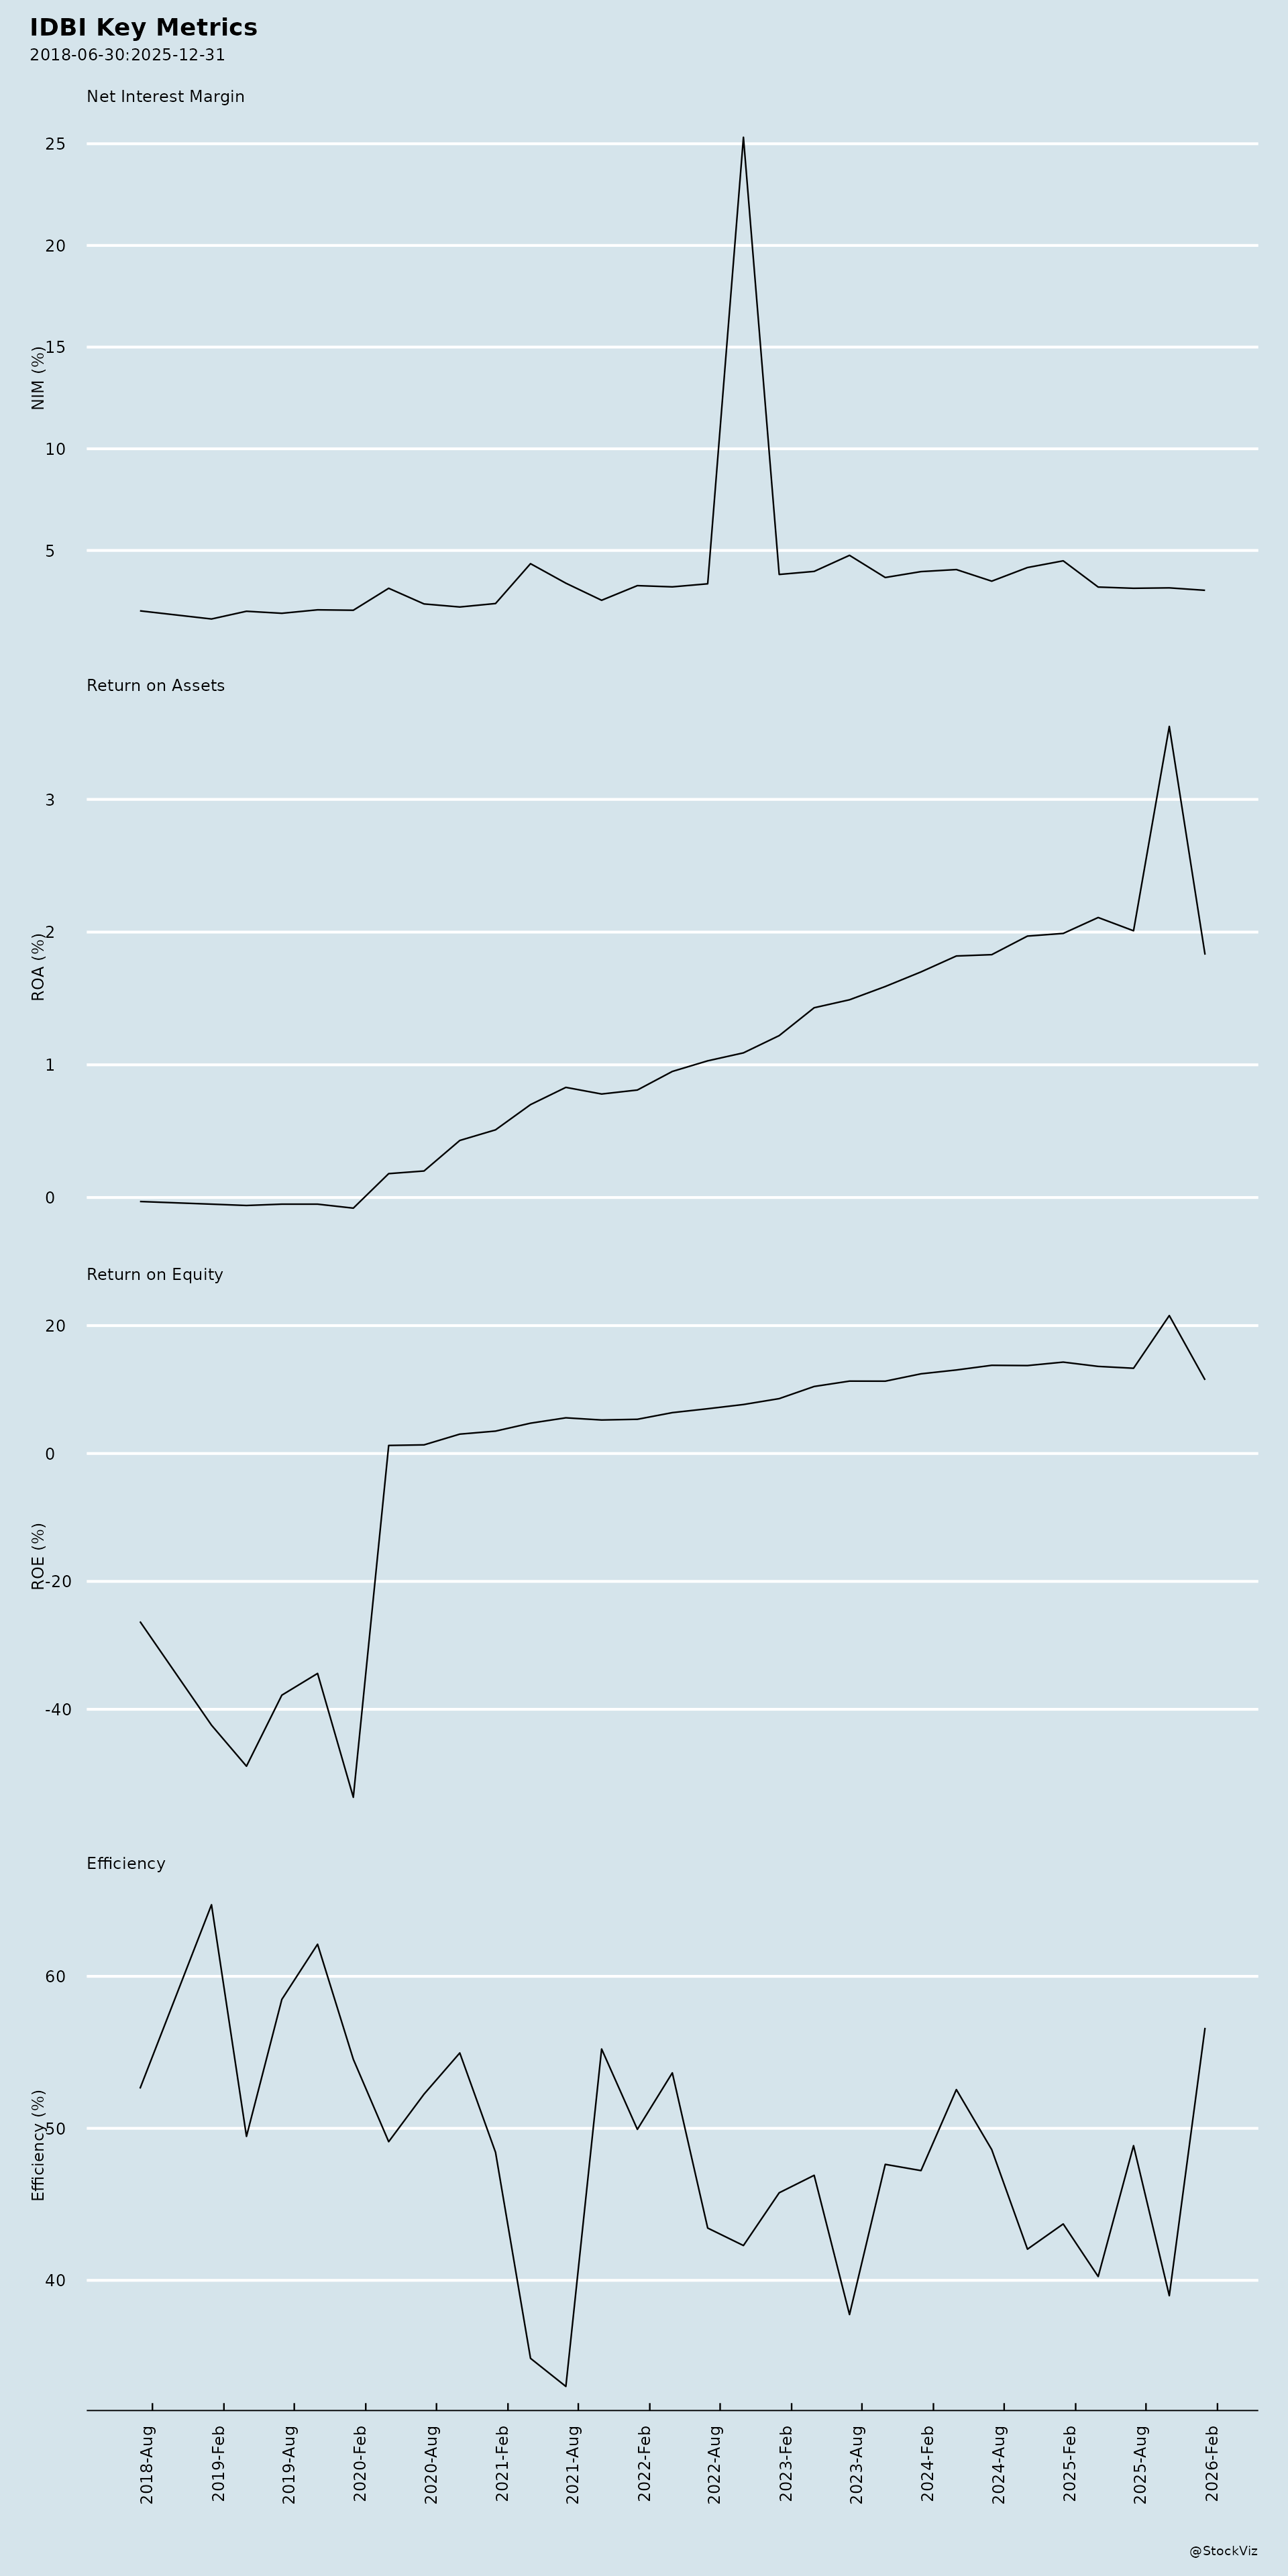
- Margin compression. NIM declined to 3.61% in Q1 FY2027 from 4.15% in Q4 FY2026 (down 54 bps QoQ) and from 3.68% in Q1 FY2026 (down 7 bps YoY).
- Cost pressure. Cost to Net Income Ratio rose to 52.02% from 44.28% QoQ and 48.86% YoY (up 774 bps QoQ, 316 bps YoY). Operating expenses increased YoY.
- Deposit and CASA attrition. Deposits fell 6% QoQ (₹3,47,163 crore to ₹3,25,757 crore) and CASA fell 8% QoQ. CASA ratio declined to 43.64% from 44.59% QoQ and 44.63% YoY. Total balance sheet contracted 5% QoQ.
- Return ratios below prior-year levels. ROA at 1.89% was down 12 bps YoY (though up 14 bps QoQ), and Return on Equity at 14.80% was down 311 bps YoY.
- Net NPA edged up sequentially. Net NPA rose 1 bp QoQ to 0.16% (though down 5 bps YoY), and Provision Coverage Ratio slipped 8 bps QoQ to 99.31%.
- Stressed asset overhang. The Bank holds ₹3,543.43 crore book cost of Security Receipts, with a marked-to-market loss of ₹862.11 crore at portfolio level, and maintains 100% provision on the carrying value. Of this, ₹2,432.33 crore relates to Government-guaranteed SRs where provision is held on a prudent basis pending actual recoveries or Government approval of claims.
- Project finance exposure under resolution. 23 accounts with outstanding of ₹315.30 crore are under a resolution process involving extension of DCCO, with resolution plans under implementation.
- Senior management transition. Shri Sunit Sarkar, Executive Director (Senior Management Position), ceased to be Senior Management Personnel due to superannuation effective end of business hours on August 31, 2026.
Tailwinds and Growth Prospects
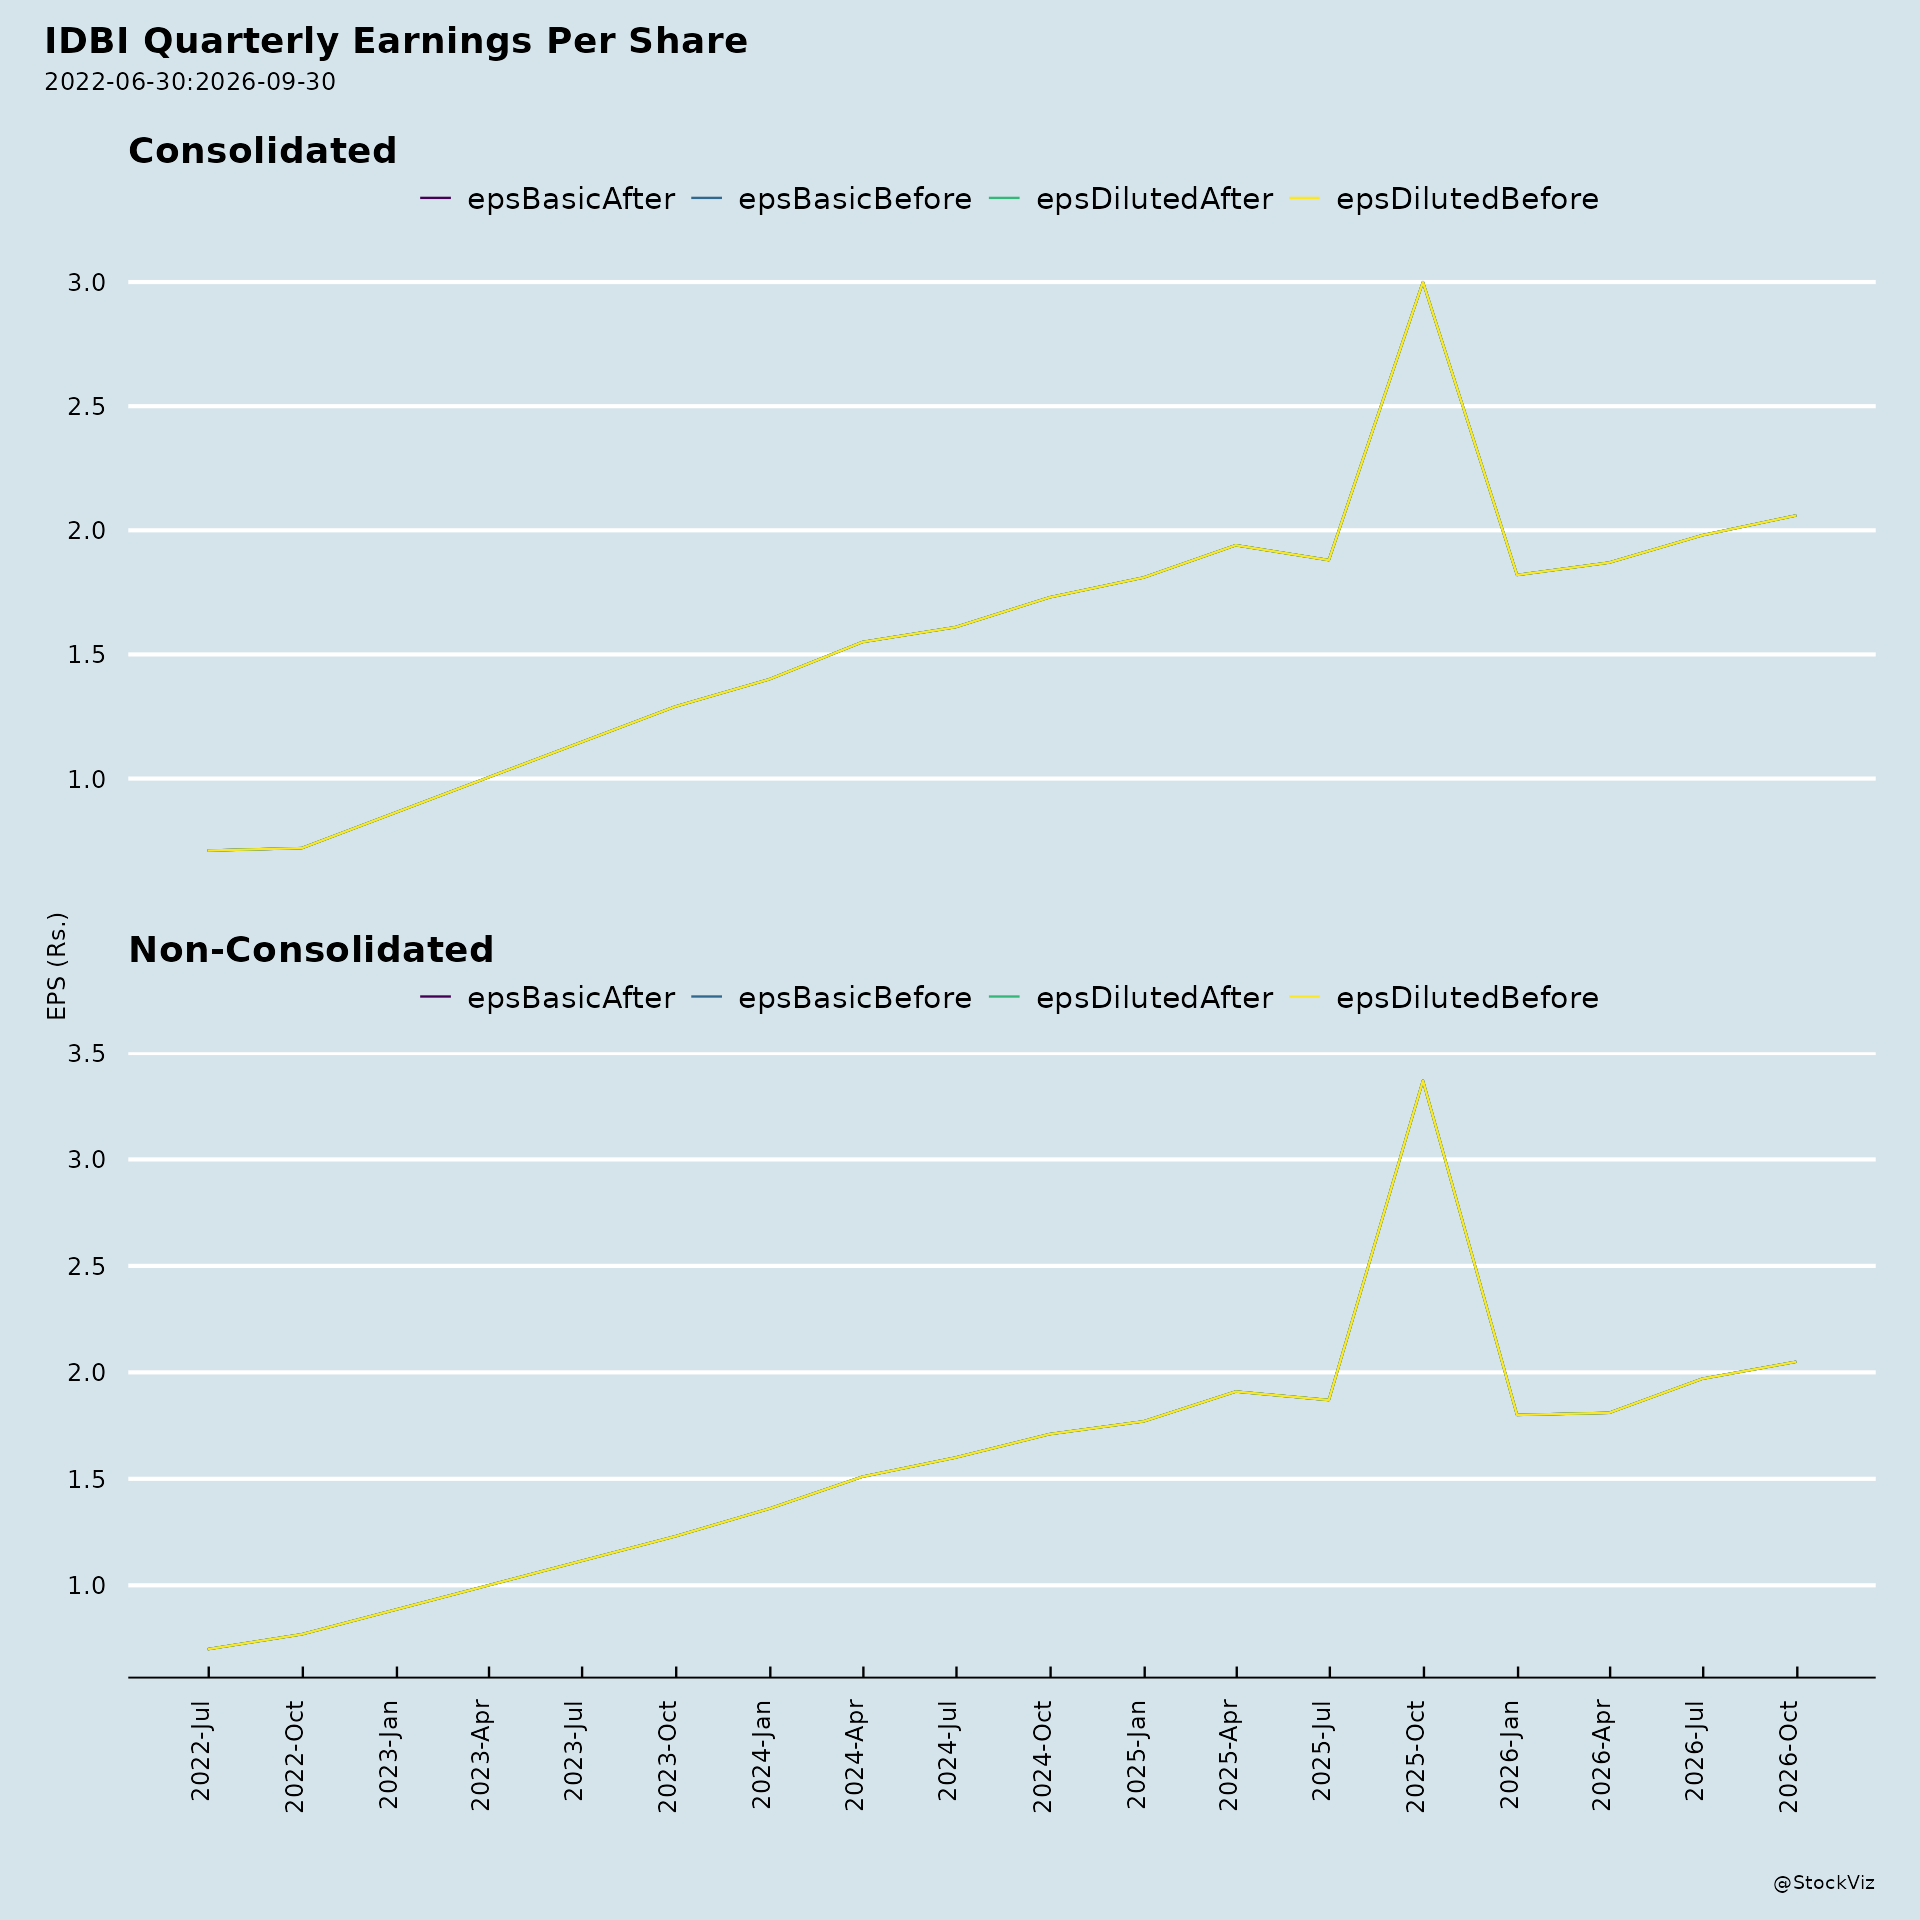
- Profit growth. Net Profit rose to ₹2,115 crore in Q1 FY2027, up 5% YoY and 9% QoQ. Basic EPS improved to ₹1.97 from ₹1.81 QoQ and ₹1.87 YoY.
- Balance sheet expansion YoY. Total business grew 15% YoY to ₹5,84,725 crore; total deposits grew 10% YoY; net advances grew 22% YoY (and 2% QoQ); CASA grew 7% YoY.
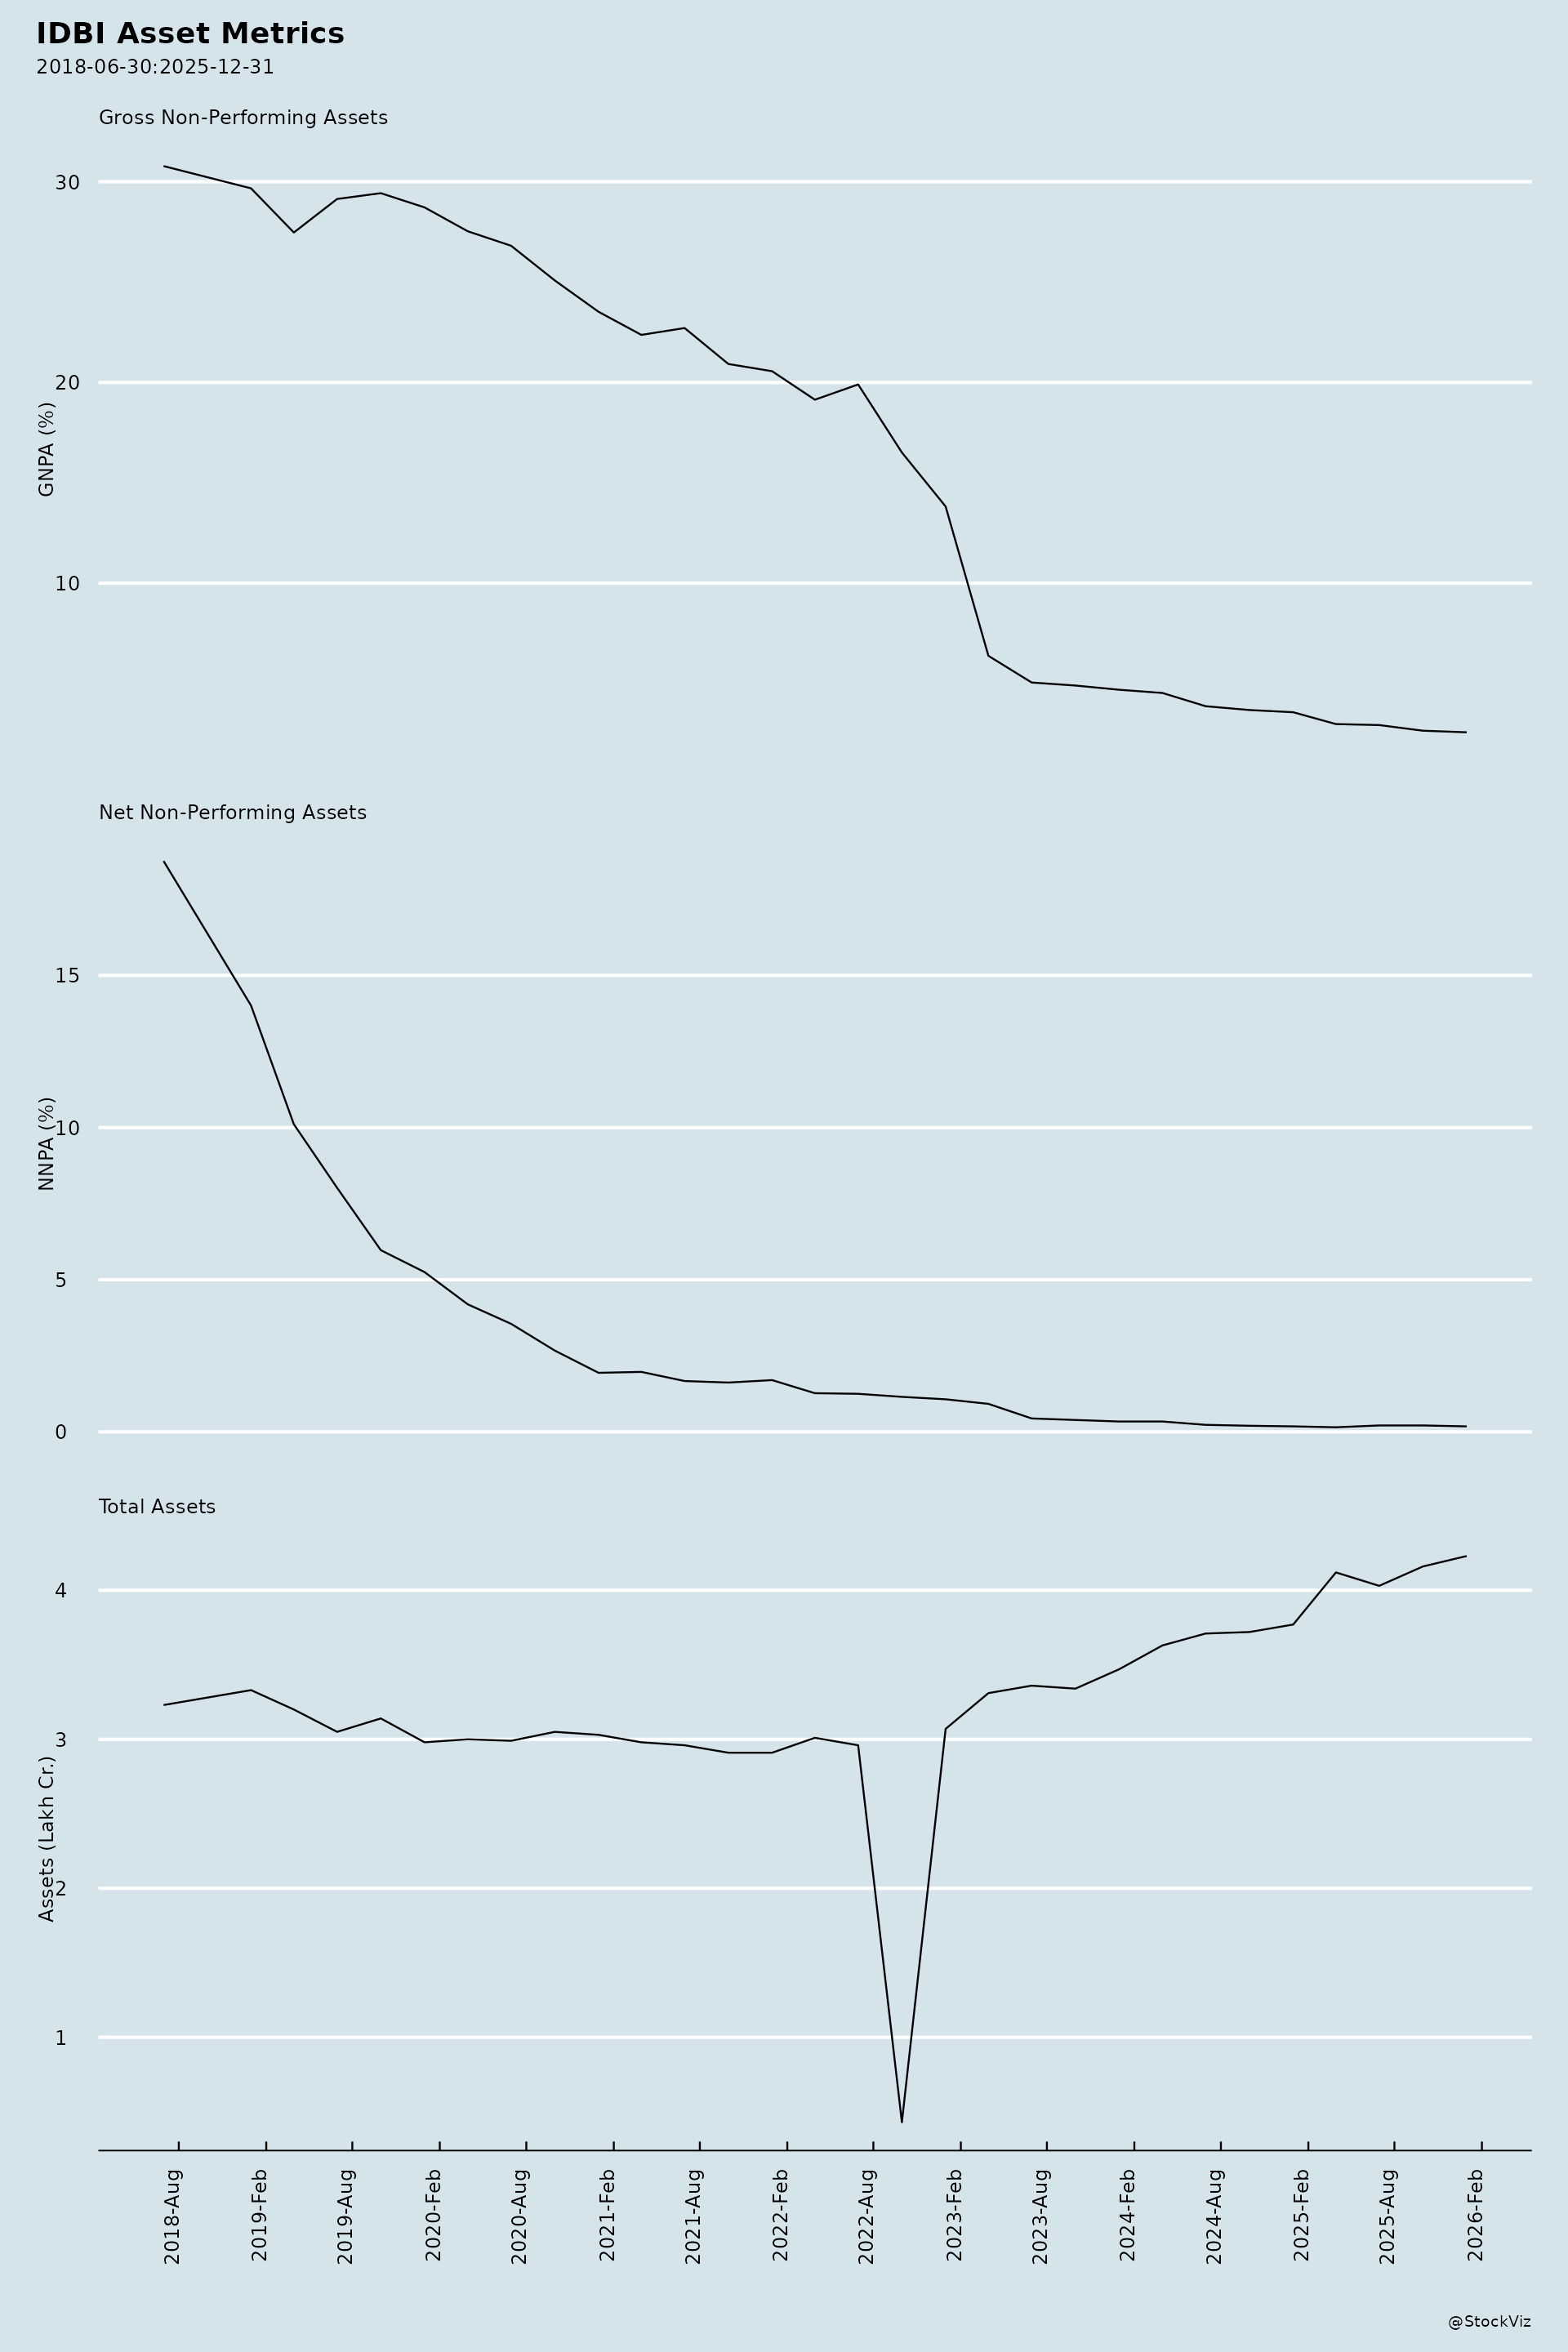
- Improving asset quality YoY. Gross NPA fell to 2.30% from 2.93% YoY (down 63 bps) and 2.32% QoQ. Net NPA fell to 0.16% from 0.21% YoY. PCR has been consistently above 99% since September 2023.
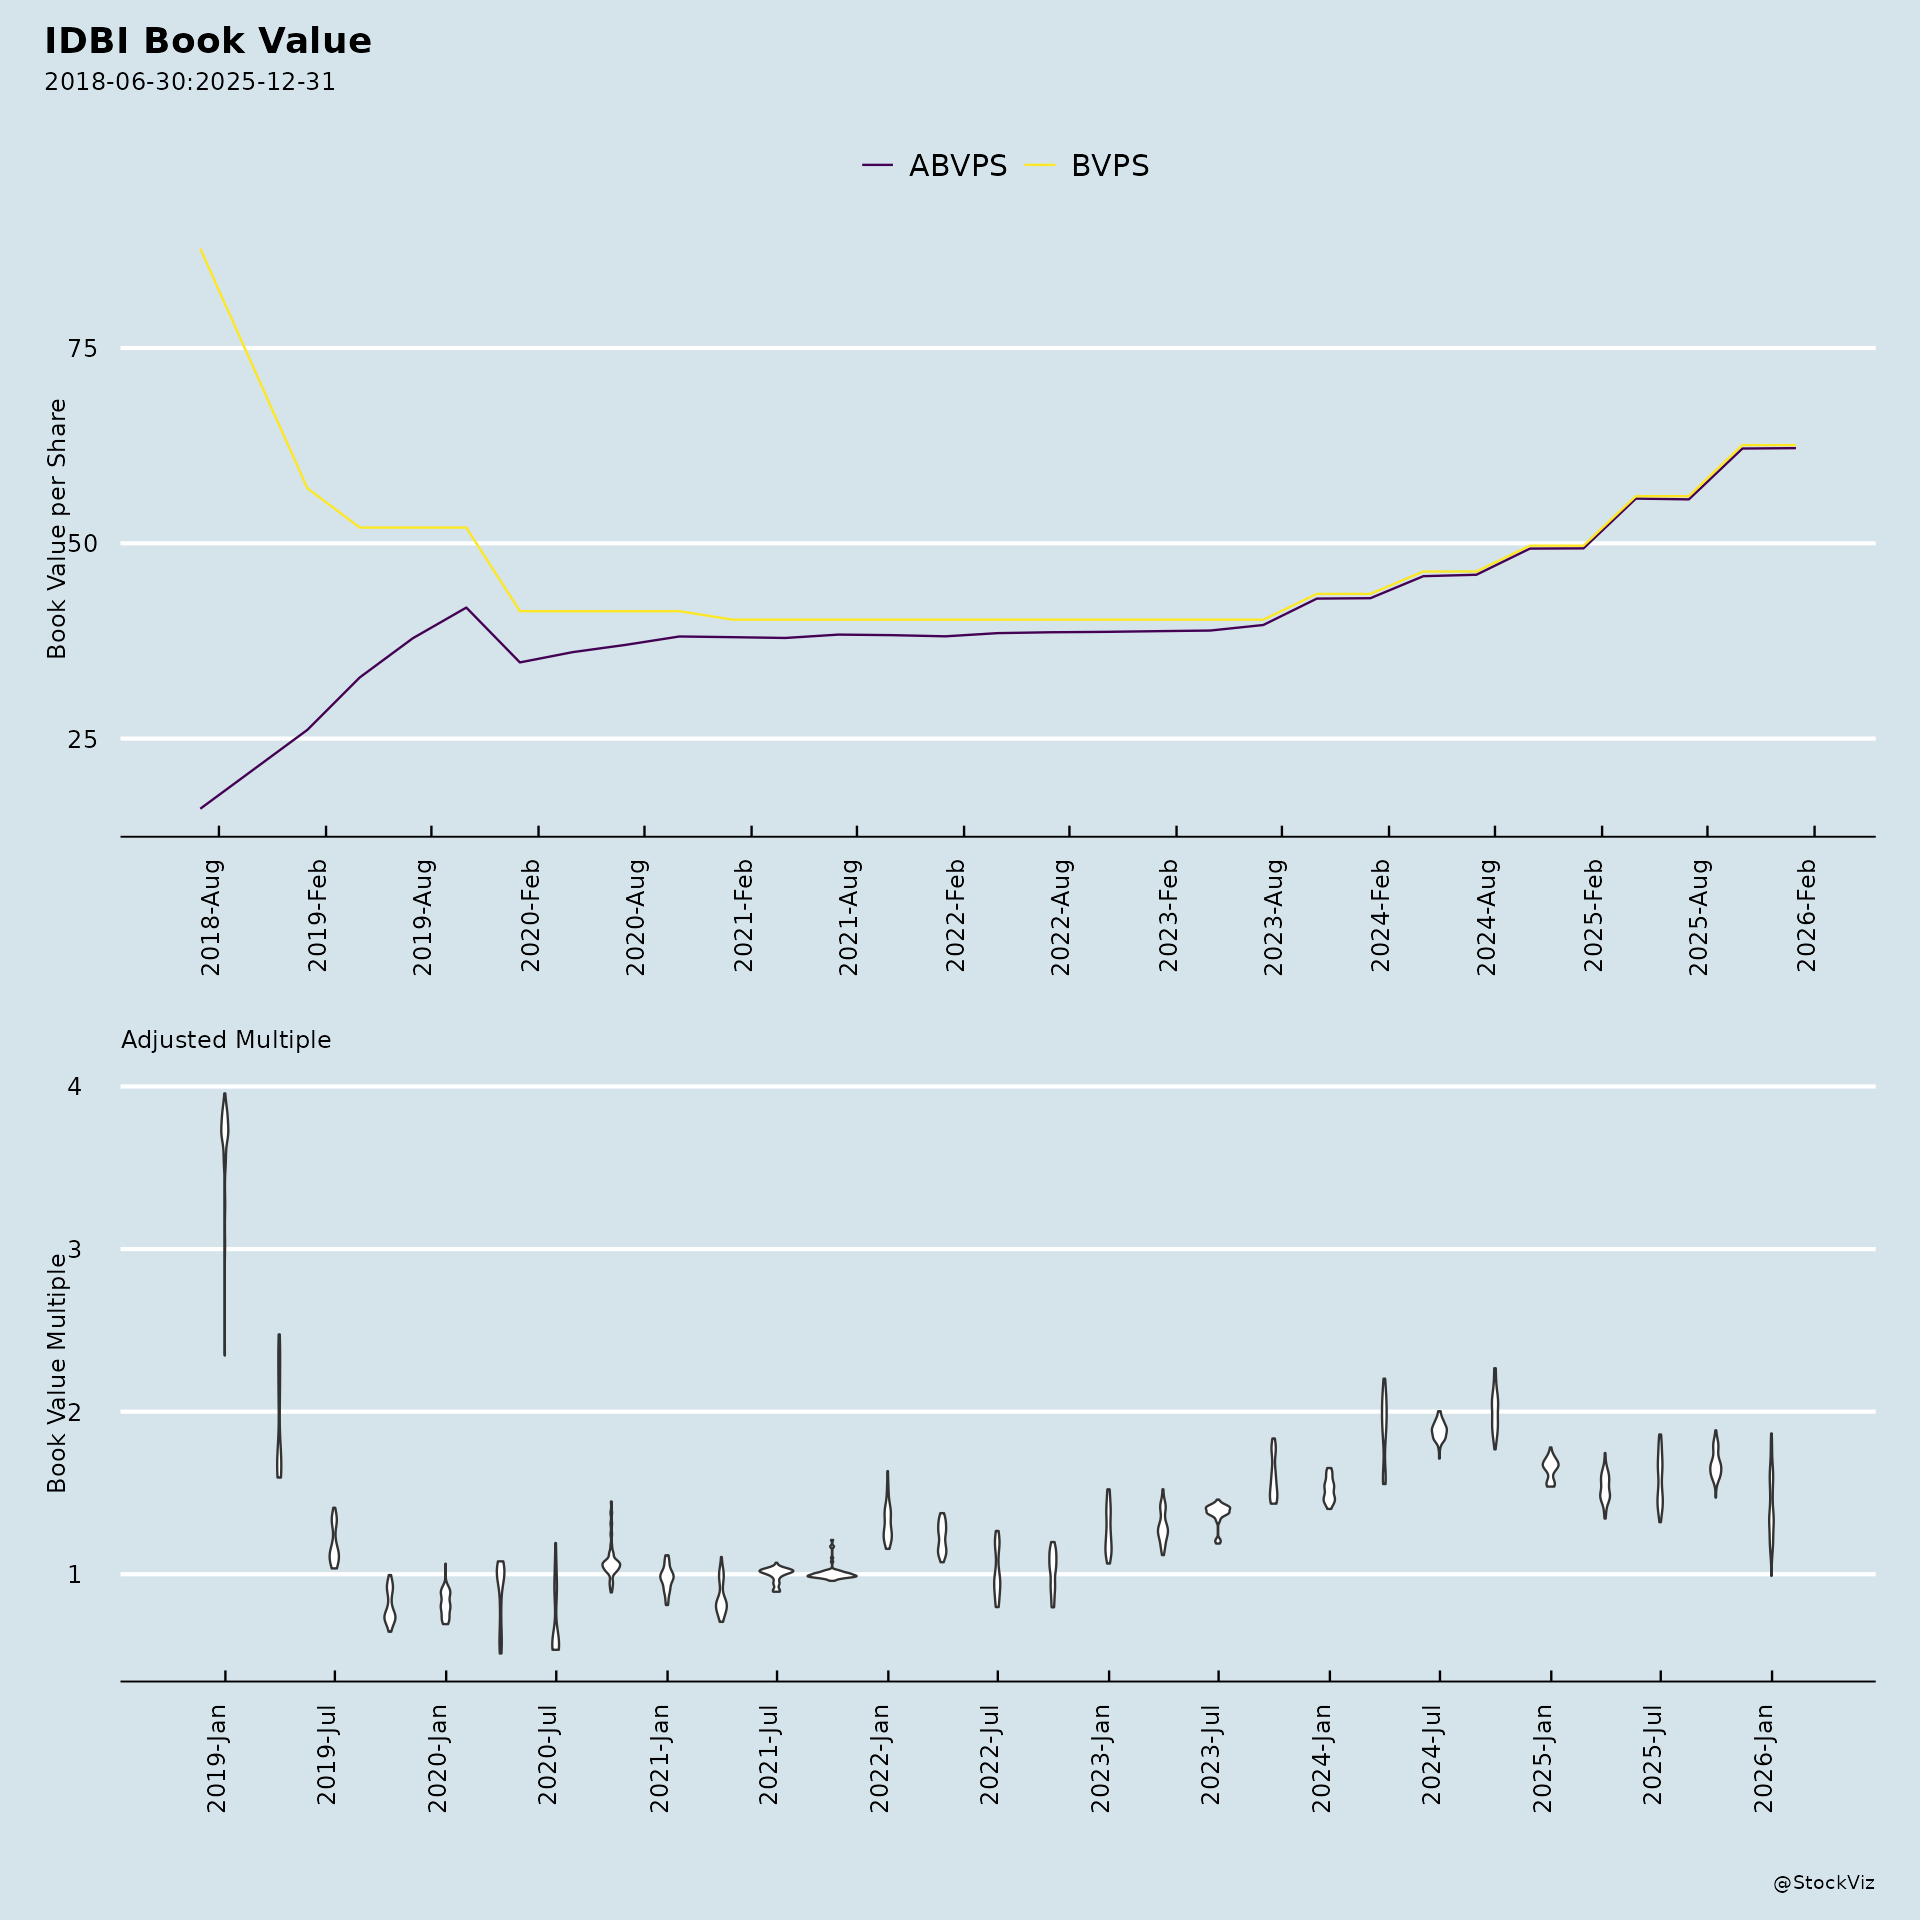
- Strong capital position. CRAR improved to 26.92%, up 153 bps YoY and 27 bps QoQ. Tier 1/CET I ratio improved to 26.38% from 23.71% YoY and 25.56% QoQ. Net worth grew 27% YoY and 6% QoQ to ₹59,024 crore.
- Lower funding costs. Cost of Deposits fell to 4.59% (down 25 bps YoY, 1 bp QoQ); Cost of Funds fell to 4.68% (down 30 bps YoY, 3 bps QoQ).
- Credit-deposit ratio improvement. Rose to 79.50%, up 810 bps YoY and 644 bps QoQ, indicating better deployment of deposits.
- Retail-weighted book. Gross advances composition was 30:70 Corporate:Retail.
- Digital and innovation initiatives. Launch of ‘IDBI Innovate 2026’, a nationwide hackathon inviting start-ups, fintechs, developers and innovators to build technology solutions for banking challenges, aimed at enhancing customer experience and operational efficiency.
- Recognition and inclusion initiatives. ‘APY Annual Award of Ultimate Achiever’ from DFS, Ministry of Finance for meeting Atal Pension Yojana enrolment targets for FY 2025-26 (awarded May 2026); ‘Internal Audit Excellence Awards 2026’ for the AI-enabled iNetra internal audit system.
- Capital reserve strengthening. Discontinuation of Investment Fluctuation Reserve following the RBI Second Amendment Direction dated May 18, 2026, with ₹1,277.83 crore transferred from IFR to General Reserve during the quarter.
- New CSR subsidiary. IDBI Foundation incorporated May 19, 2026 as a wholly owned Section 8 subsidiary; 100% of paid-up equity (10,000 shares of ₹10 each) subscribed on July 8, 2026.
- Co-lending expansion. 9 CLA partners, 28,070 loan accounts, ₹734.26 crore outstanding, weighted average ROI 9.05%, spanning MSME, housing, agri, gold and commercial vehicle loans.
Key Risks
- Margin and income volatility. The sharp QoQ declines in NII, non-interest income and NIM indicate earnings sensitivity to funding costs and non-core income.
- Deposit franchise sensitivity. The 6% QoQ deposit decline and 8% QoQ CASA decline, alongside a 95 bps QoQ fall in CASA ratio, point to potential funding mix pressure.
- Cost escalation. The 774 bps QoQ rise in Cost to Net Income Ratio signals limited operating leverage if income does not recover.
- Stressed asset recovery uncertainty. Recovery on ₹3,543.43 crore of SRs (including ₹2,432.33 crore Government-guaranteed) depends on actual recoveries or Government approval of claims; the Bank carries a ₹862.11 crore mark-to-market loss at portfolio level.
- Project finance DCCO extensions. 23 accounts (₹315.30 crore) remain under resolution plans involving DCCO extension, with implementation pending.
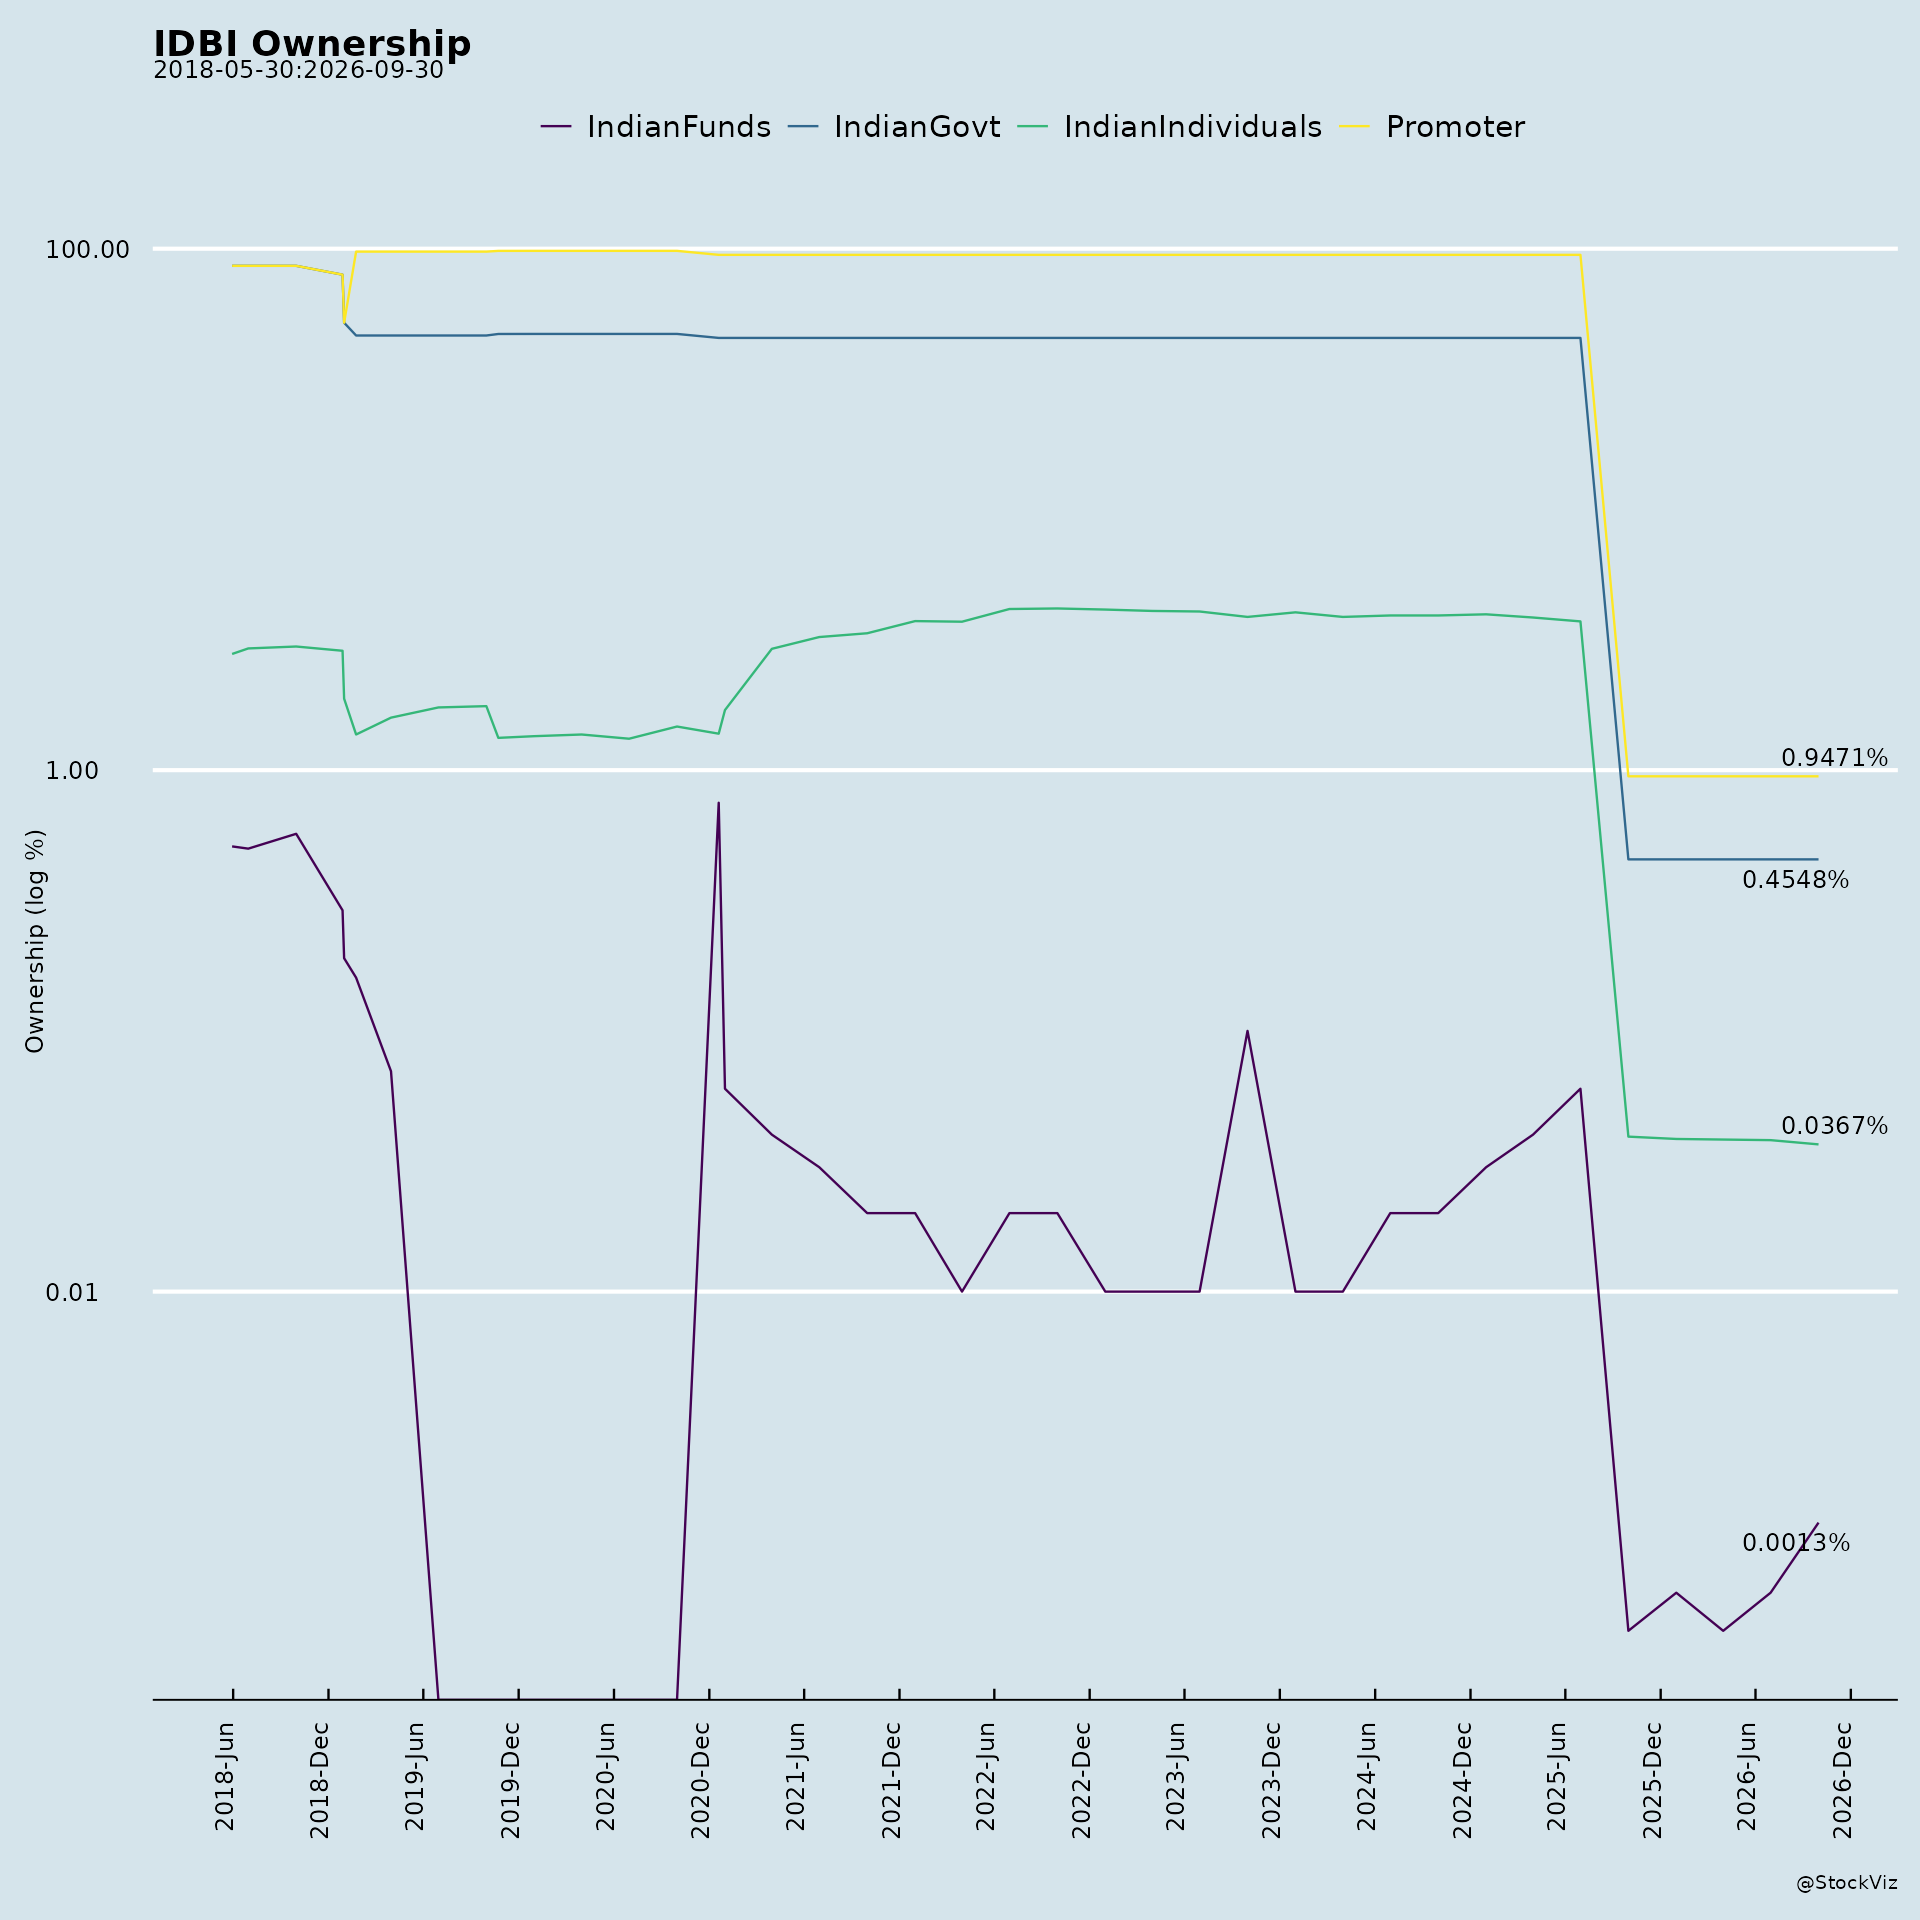
- Concentration and related-party considerations. Voting on the LIC Mutual Fund related-party transaction was restricted to non-related parties under Regulation 23(4) of SEBI LODR; voting rights of shareholders holding above 26% of paid-up capital are capped at 26% under Section 12(2) of the Banking Regulation Act, 1949.
- Key personnel changes. Superannuation of the Executive Director (Senior Management) effective August 31, 2026.
Management Guidance Versus Observed Business Performance
The supplied material does not contain explicit forward-looking guidance, targets, or projections from management. The available evidence is limited to reported performance and corporate actions:
- Profitability: Reported Net Profit of ₹2,115 crore for Q1 FY2027, with YoY growth of 5% and QoQ growth of 9%.
- Capital: CRAR of 26.92% and CET I of 26.38% as at June 30, 2026, both improved YoY and QoQ.
- Asset quality: Gross NPA 2.30% and Net NPA 0.16% as at June 30, 2026, with PCR at 99.31% and consistently above 99% since September 2023.
- Business growth: Total business ₹5,84,725 crore (up 15% YoY); deposits ₹3,25,757 crore (up 10% YoY); net advances ₹2,58,968 crore (up 22% YoY).
- Governance actions: All six resolutions at the 22nd AGM (July 21, 2026) passed with requisite majority, including adoption of FY2026 audited financial statements, reappointment of Shri Sumit Phakka as Rotational Director, appointment of Shri Abhijit Chakravorty and Shri Ketan Vikamsey as Independent Directors, reappointment of Shri Jayakumar S. Pillai as Deputy Managing Director, and approval of material related-party transactions with LIC Mutual Fund.
- Audit status: Joint Statutory Auditors Chokshi & Chokshi LLP and Suri & Co. issued unmodified limited review reports on the standalone and consolidated results for the quarter ended June 30, 2026.
Broker Timeline
1 broker calls · 2023-07-03 to 2023-07-03
CNBC-TV18: ratings, targets and commentary
Extracted from CNBC-TV18 posts; ratings and targets are as published, not current consensus. OCR may contain errors. Speaker attribution is retained; not all speakers are brokers. These statements are separate from the Broker Narrative and Broker Timeline and have no calculated performance or outcomes.
Other company commentary (not broker ratings)
| Published / source (IST) | Speaker / affiliation | Rating / target | Commentary |
|---|---|---|---|
| 2026-11-16 |
DIPAM
Arunish Chawla
SecyDIPAM
|
—
|
IDBI Bank–Fairfax deal enters its third lap, with the baton now passed to the RBI. |
| 2026-11-16 |
DIPAM
Arunish Chawla
DIPAM Secy
|
—
|
The winning bidder has to disclose its source of funds to RBI; there shouldn't be any misapprehension |
| 2026-11-16 |
DIPAM
Arunish Chawla
DIPAM Secy
|
—
|
Perceptions of IDBI funding its own purchase are wrong |
| 2026-11-16 |
DIPAM
Arunish Chawla
DIPAM Secy
|
—
|
We are moving along & we hope to close the IDBI Bank deal |
Management comments
Company-related comments from CNBC-TV18 posts in x-stream. Speakers are management of the displayed affiliation, not necessarily management of this company. Only explicit executive designations and affiliations are included; analyst, broker and investment-manager commentary remains separate. OCR may contain errors.
| Published / source (IST) | Speaker / affiliation / designation | Commentary |
|---|---|---|
|
R Doraiswamy
LIC
CEO & MD
|
|
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.