ICICILIFE
Equity Metrics
November 18, 2026
ICICI Life Insurance Limited
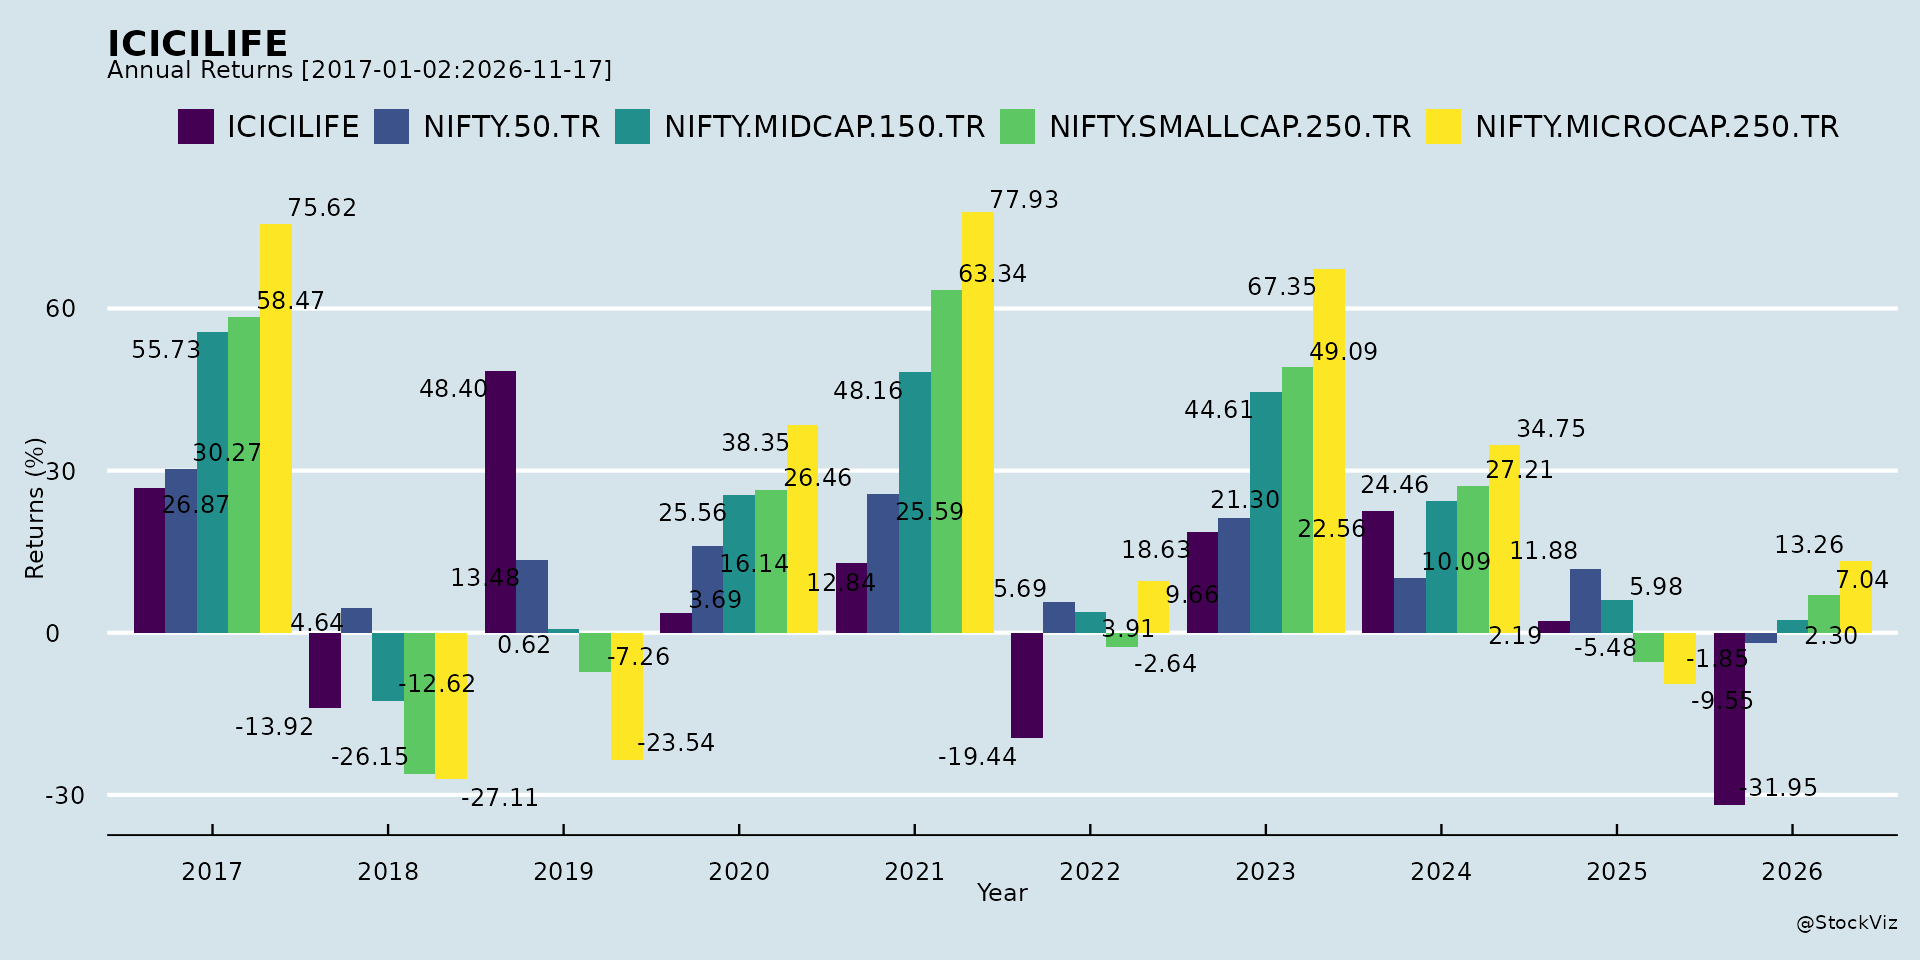
Annual Returns
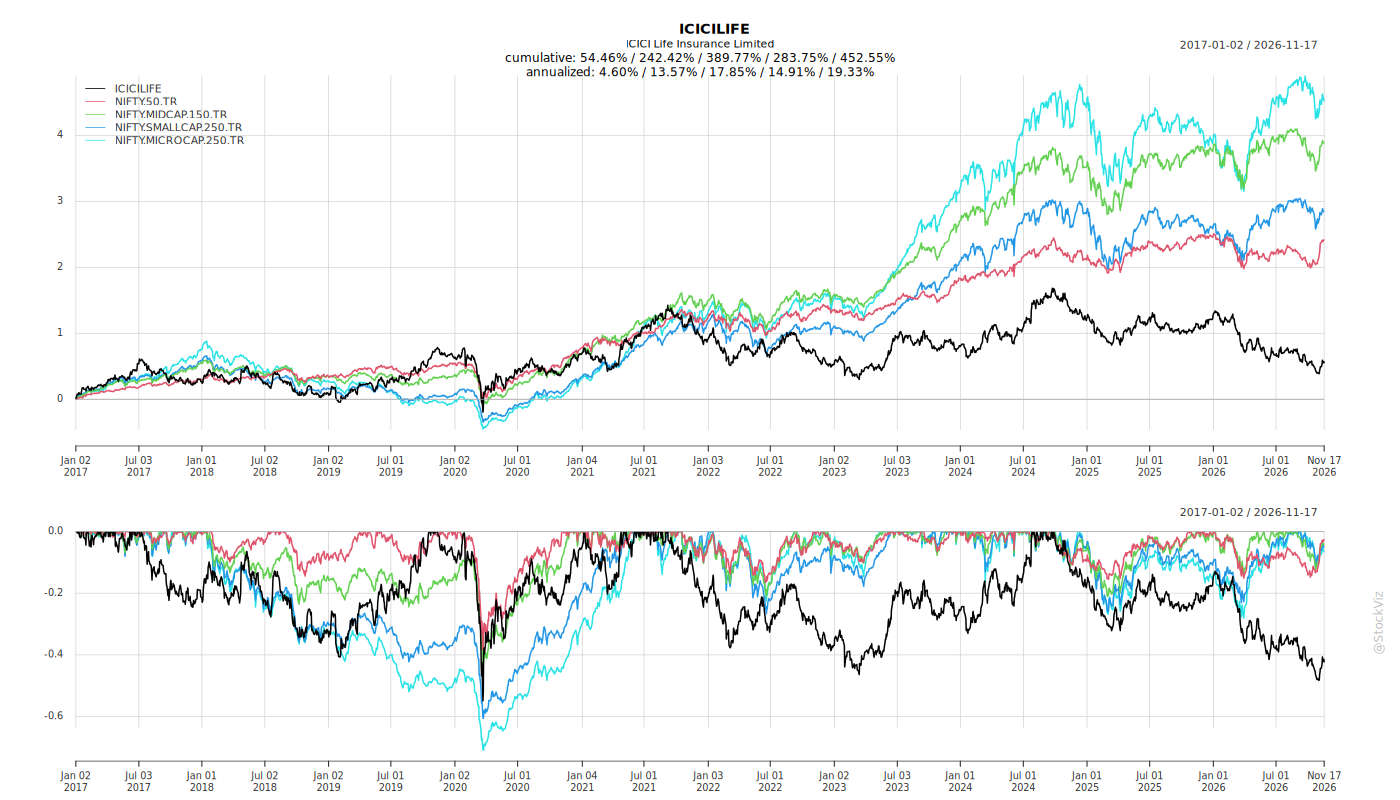
Cumulative Returns and Drawdowns
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-11-12
Headwinds and Challenges
- Retail and RWRP contraction: For October 2026, RWRP was ₹5.99 billion, a year-on-year decline of 0.3%, and Retail APE was ₹5.82 billion, down 3.2% year-on-year. These declines indicate pressure in the retail and renewal-linked parts of the business even as overall APE grew.
- Tax demand: ICICI Life Insurance Limited received a rectification order on October 19, 2026, under Section 154 of the Income Tax Act, 1961, from the Assistant Commissioner of Income Tax, Mumbai, for Assessment Year 2023. The order seeks incremental tax of ₹97,07,75,200 and incremental interest of ₹1,33,11,03,953, bringing the total tax demand to ₹3,72,36,41,785, total interest to ₹219,05,45,425, and a total demand of ₹591,41,87,210. The company has filed an appeal against the order before the appropriate authority.
Tailwinds and Growth Prospects
- Overall APE growth: APE was ₹7.97 billion in October 2026, up 8.6% year-on-year, showing expansion at the total level despite the retail decline.
- Strong new business momentum: NB premium was ₹24.37 billion, up 37.5% year-on-year, and NB sum assured was ₹1,292.60 billion, up 15.4% year-on-year, pointing to robust new business activity.
- Active investor engagement: The company scheduled meetings with investors and analysts on November 16, 17, and 20, 2026, including the JM Financial Annual India Conference, the 29th CITIC CLSA India Forum, the Avendus SPARK INDX Annual conference, and JPM 2Q27 Premium Perspectives.
- Management’s assessment of the tax order: The company has stated that there is no adverse material impact on its financial operations from the rectification order.
Key Risks
- Revenue mix risk: The year-on-year declines in RWRP and Retail APE, alongside growth in total APE and new business premium, indicate that overall growth is being carried by segments other than retail, leaving overall performance exposed to a continued retail slowdown.
- Tax dispute risk: The ₹591,41,87,210 total demand (tax of ₹3,72,36,41,785 and interest of ₹219,05,45,425) is under appeal; the outcome of the appeal and any requirement to pay or provide for the demand could affect financials despite management’s stated view of no adverse material impact.
Management Guidance Versus Observed Performance
- No forward-looking guidance or financial targets are provided in the supplied material. The only management positions available are the statement that the tax rectification order has no adverse material impact on financial operations, and the schedule of investor and analyst meetings in November 2026. Observed performance for October 2026 shows total APE growth of 8.6% and NB premium growth of 37.5%, contrasted with declines in RWRP (−0.3%) and Retail APE (−3.2%).
CNBC-TV18: ratings, targets and commentary
Extracted from CNBC-TV18 posts; ratings and targets are as published, not current consensus. OCR may contain errors. Speaker attribution is retained; not all speakers are brokers. These statements are separate from the Broker Narrative and Broker Timeline and have no calculated performance or outcomes.
Other company commentary (not broker ratings)
| Published / source (IST) | Speaker / affiliation | Rating / target | Commentary |
|---|---|---|---|
| 2026-11-12 |
Nomura
|
—
|
HDFC Life Leads Covered Insurers With 16% APE Growth, Followed By Axis Max Life At 14% & ICICI Life At 9% |
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.