HYUNDAI
Equity Metrics
November 18, 2026
Hyundai Motor India Limited
Passenger Cars & Utility Vehicles
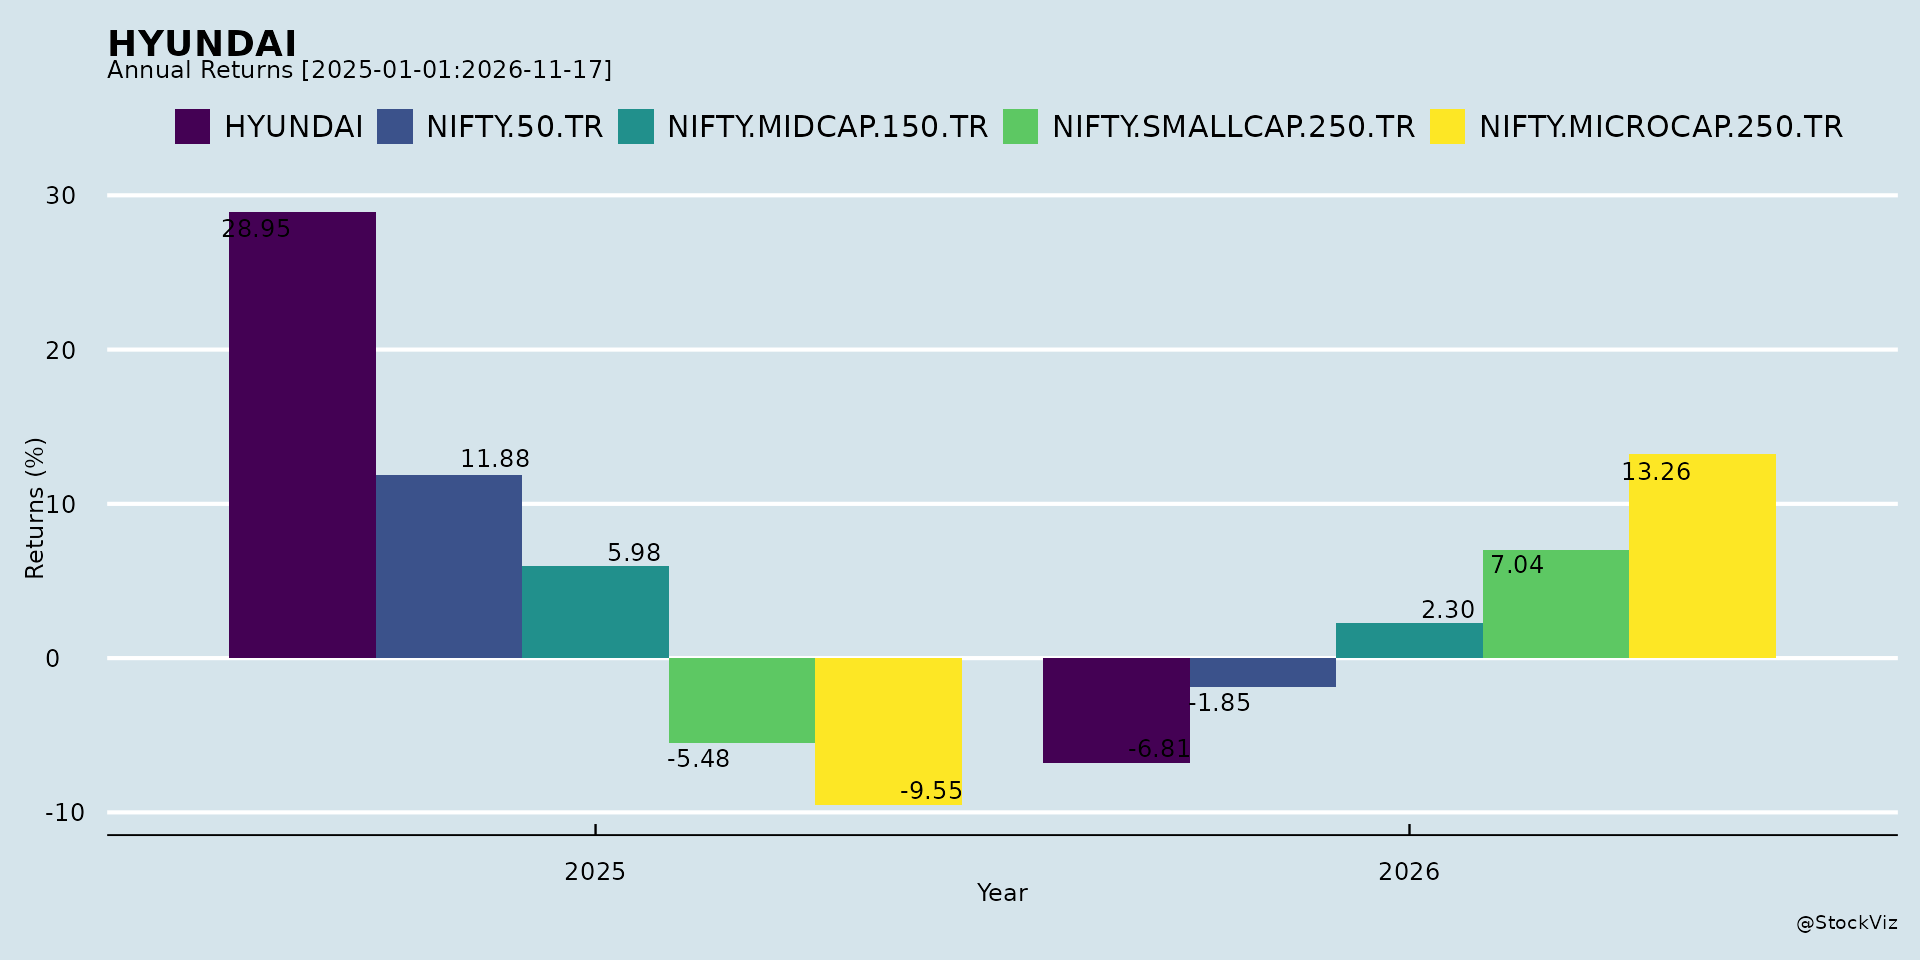
Annual Returns

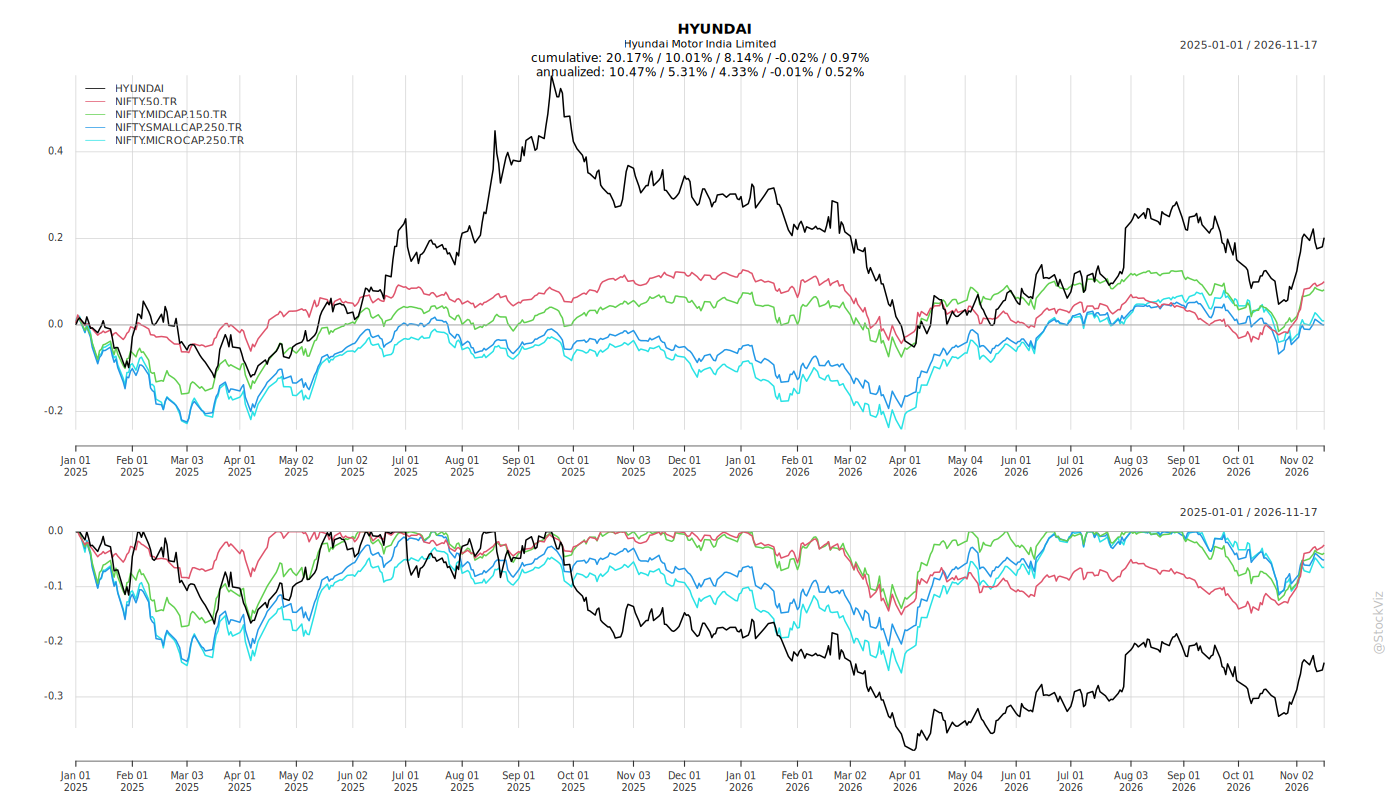
Cumulative Returns and Drawdowns
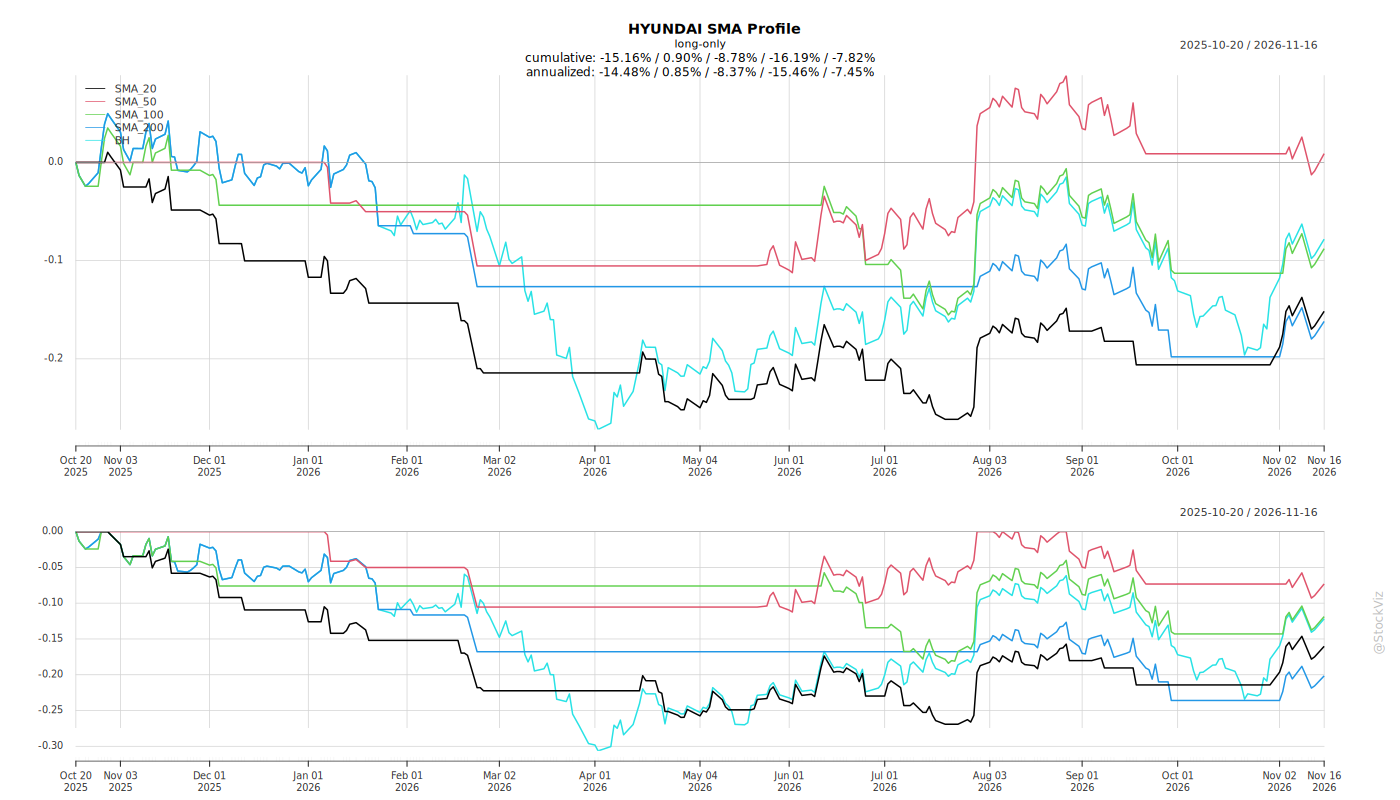
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-14
Hyundai Motor India — Recent Corporate Developments
1. Headwinds and Challenges
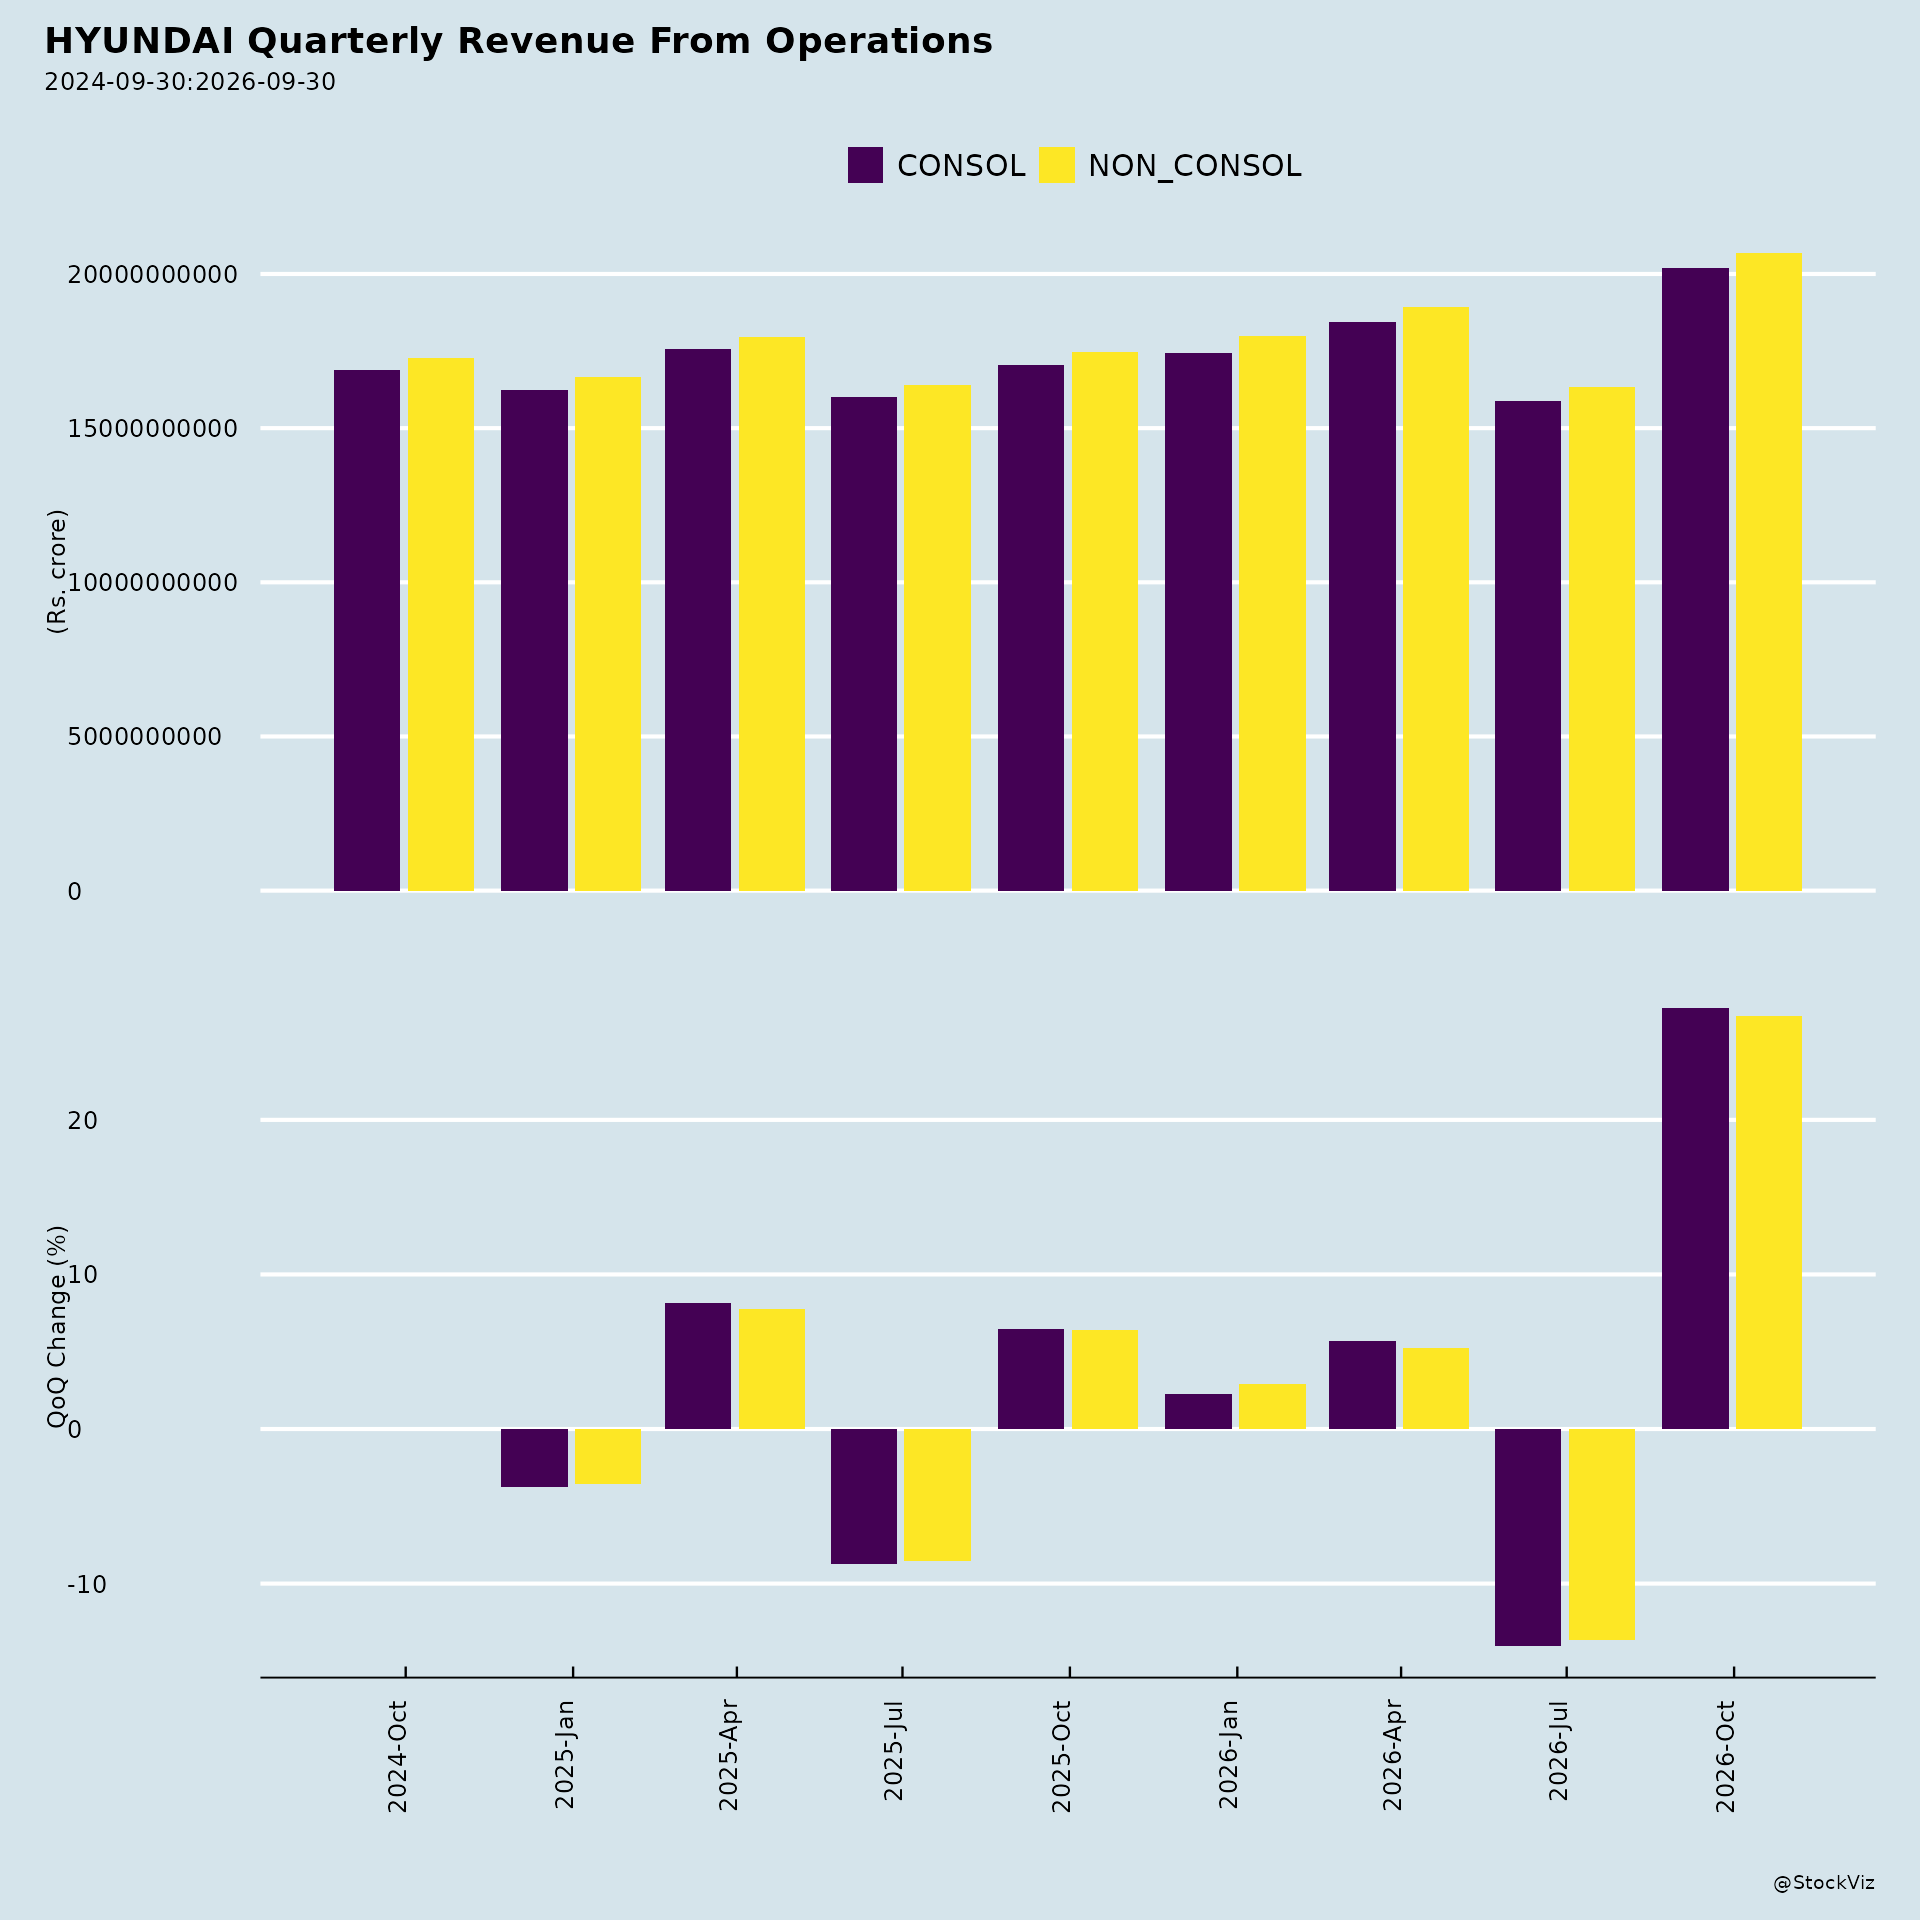
The quarter ended June 30, 2026 was described by management as a “challenging quarter, affected by multiple headwinds.” The investor presentation’s PBT movement analysis attributes margin pressure to discounts (net of price increases) and other cost factors, including capacity stabilization, commodity costs, one-offs carried from Q4 FY26, and cost reduction items.
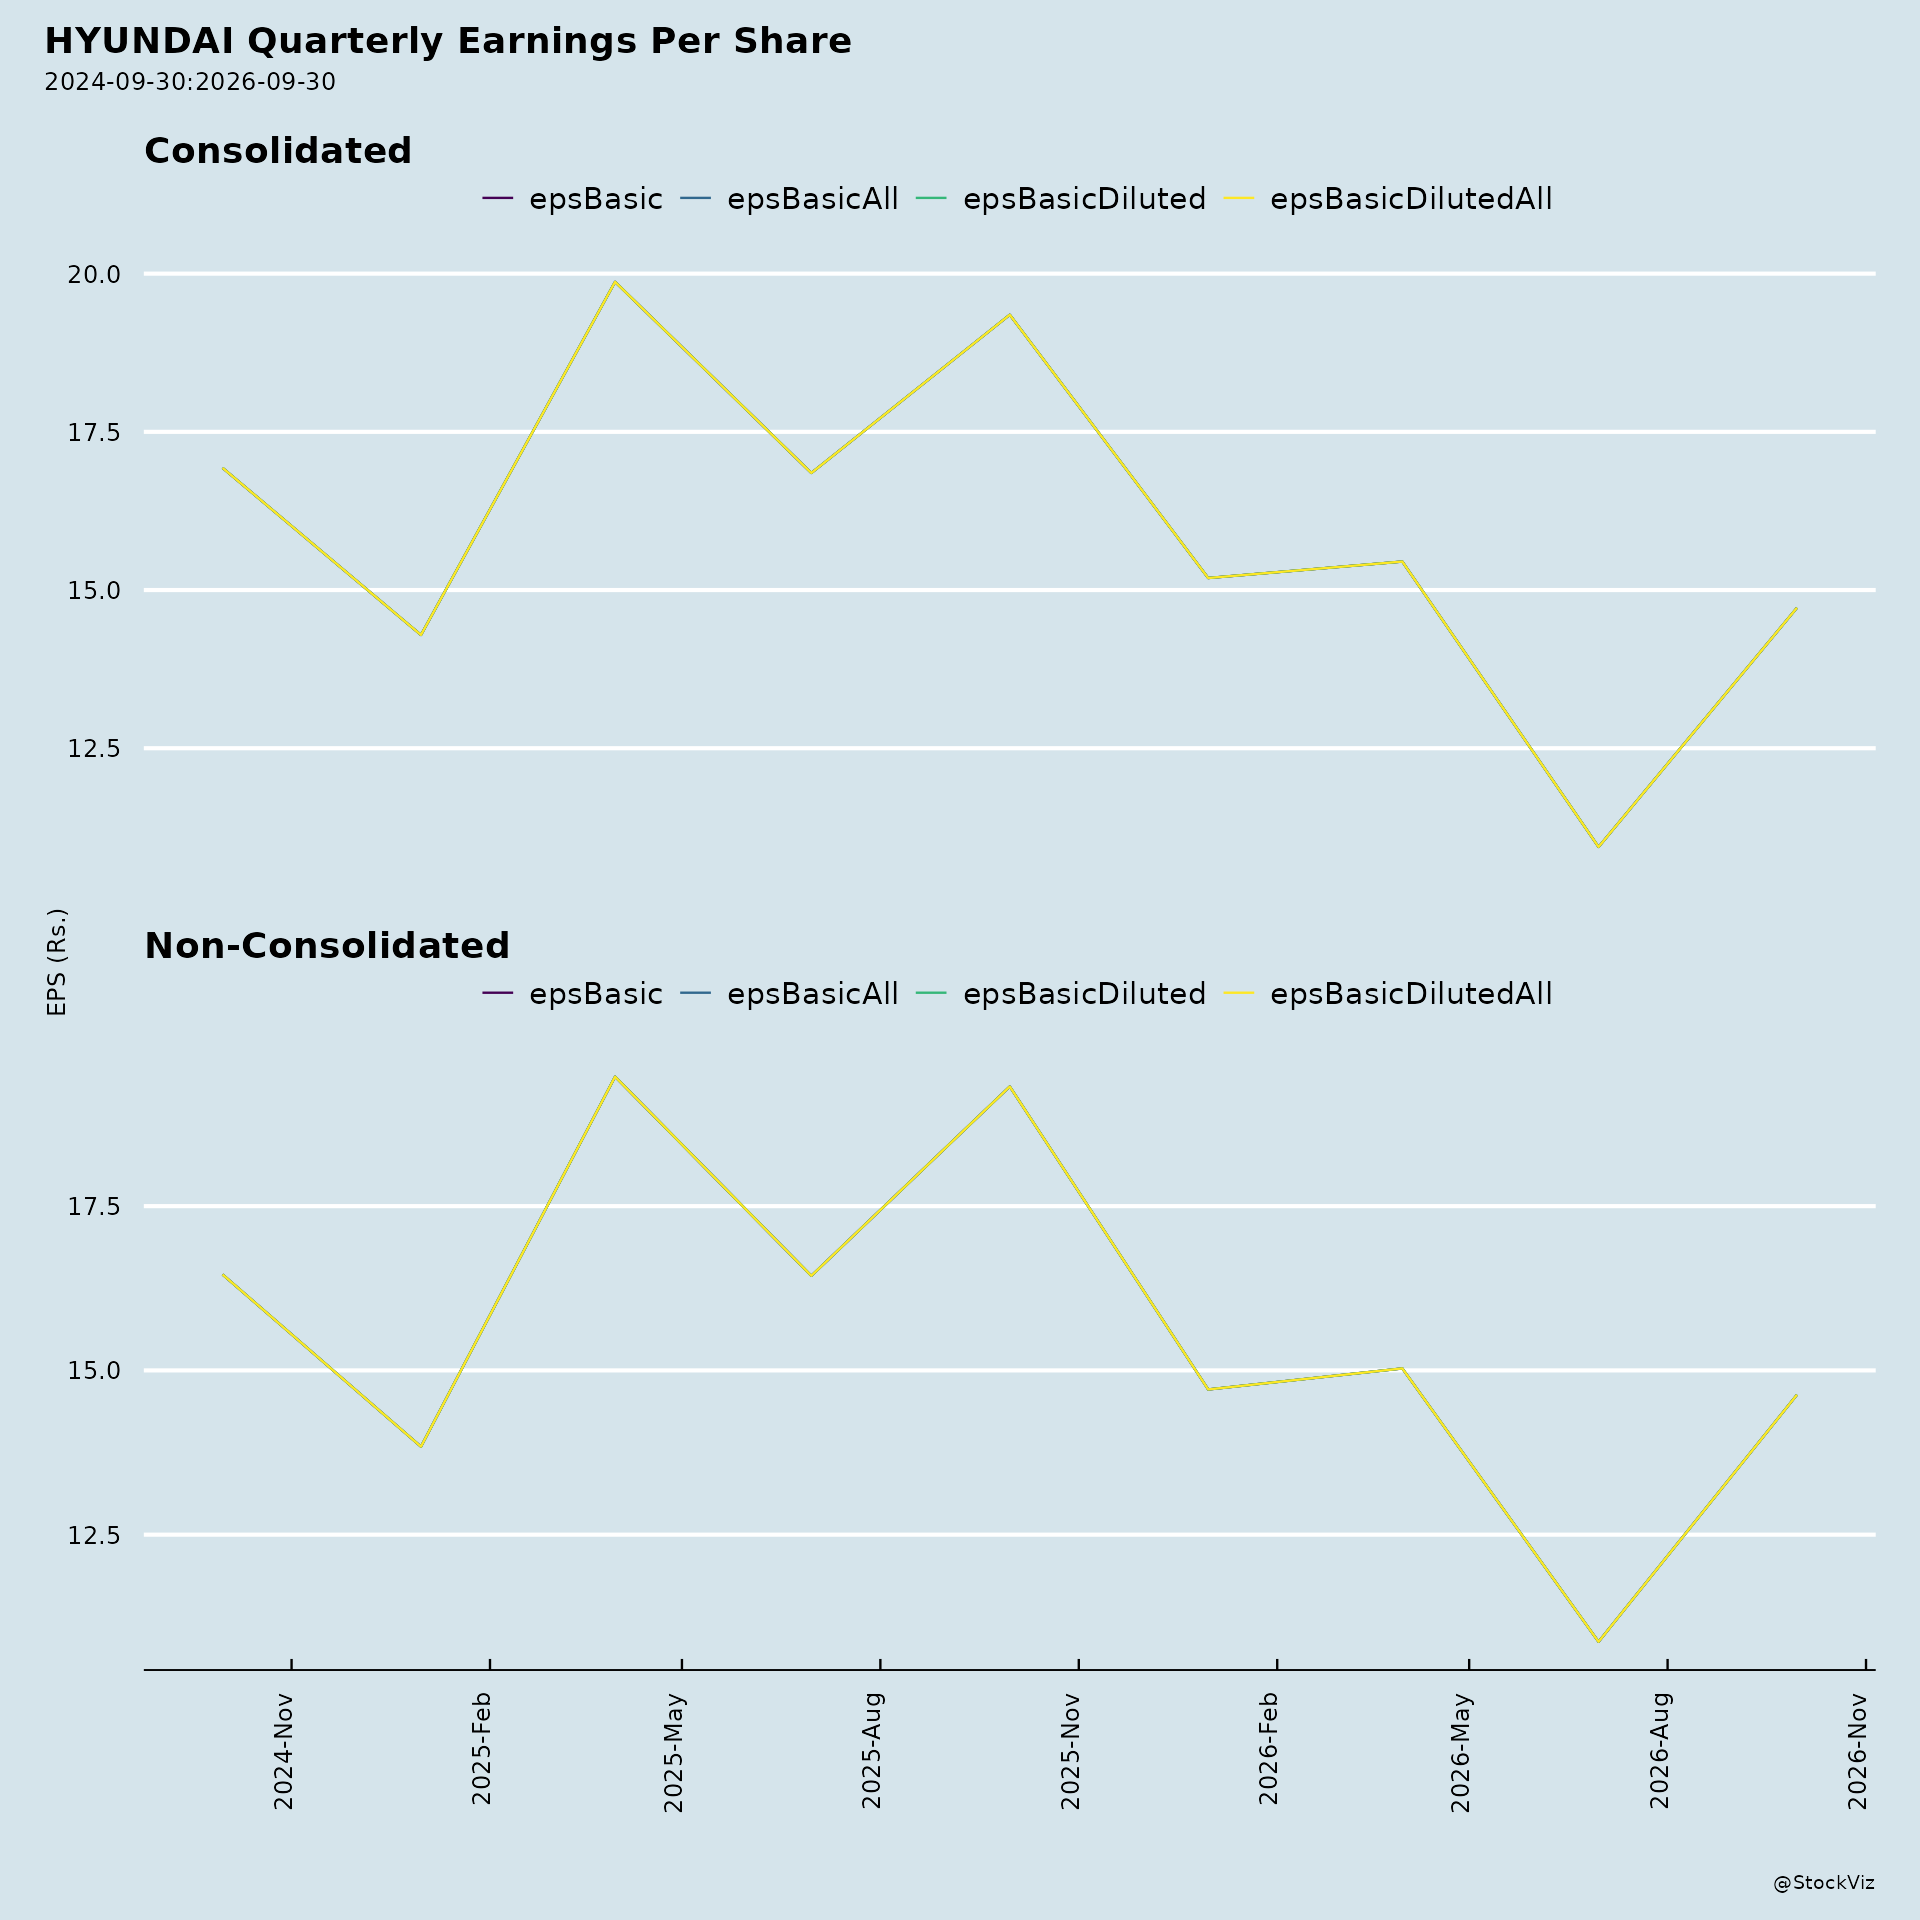
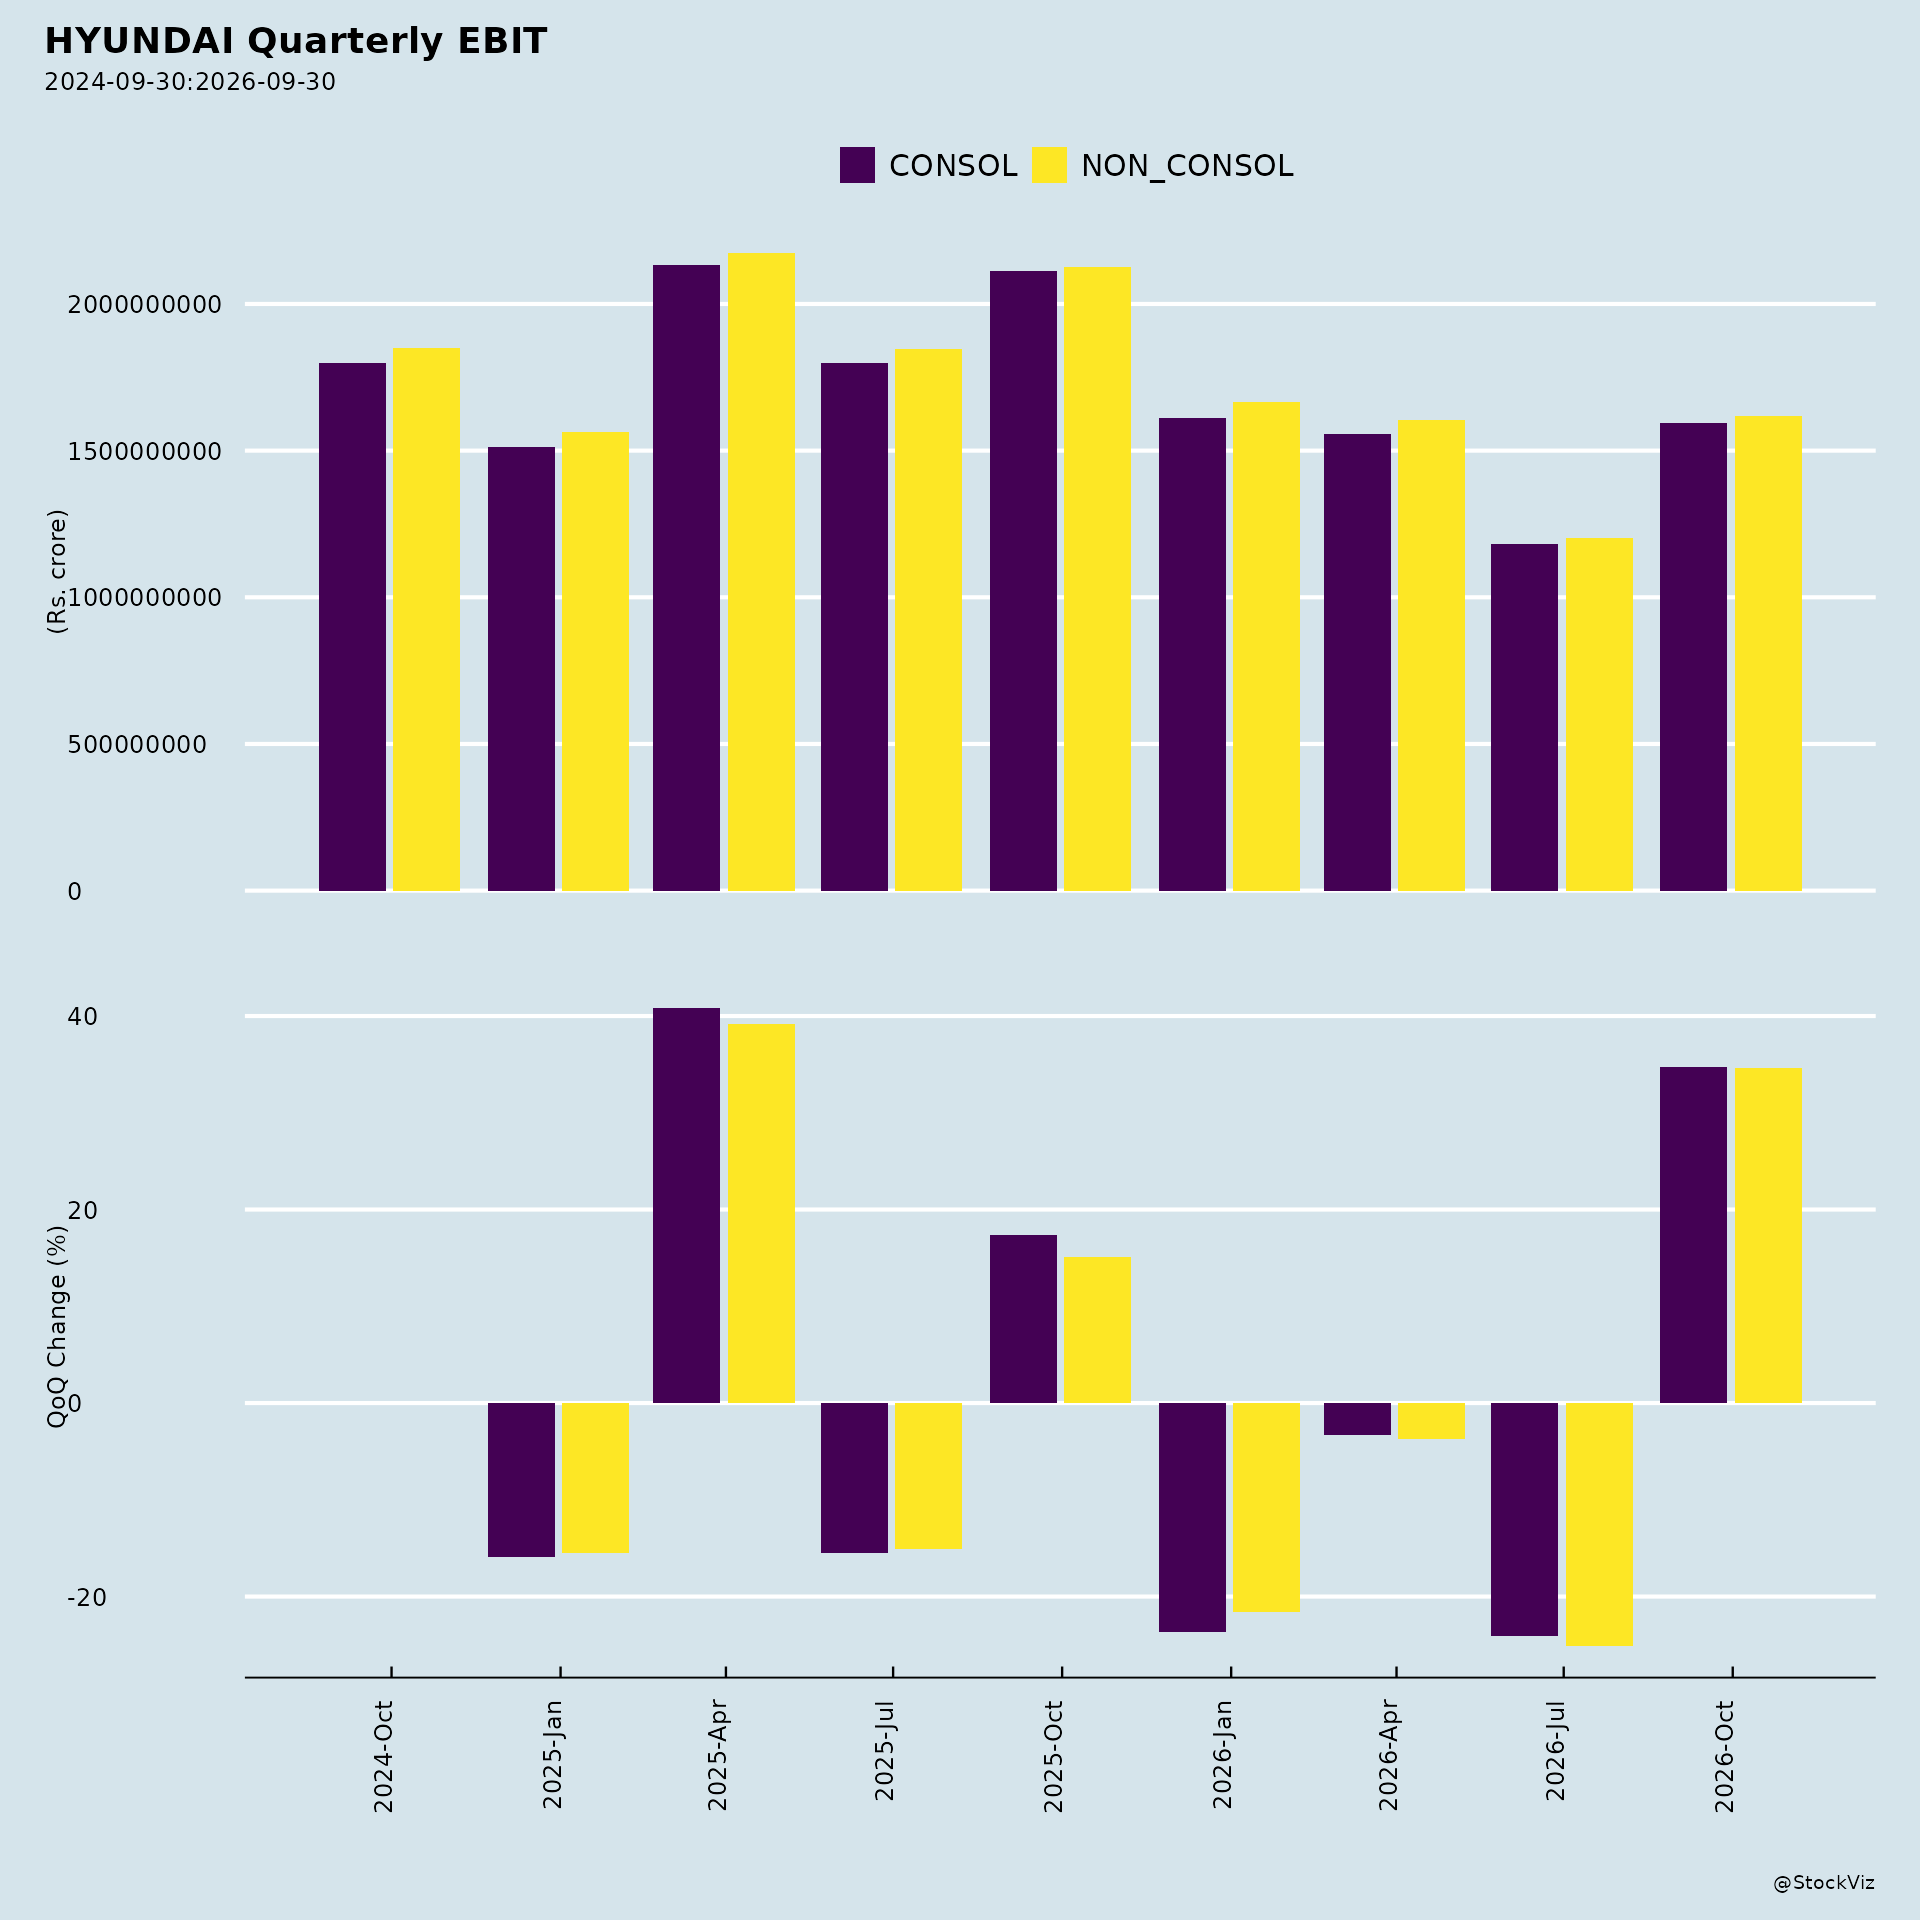
Financial performance weakened across key measures. Consolidated revenue from operations declined to ₹1,63,346 million in Q1 FY27 from ₹1,89,162 million in Q4 FY26 and ₹1,64,129 million in Q1 FY25. Profit before tax fell to ₹12,016.50 million from ₹16,038.68 million in the prior quarter and ₹18,471.96 million a year earlier. Profit after tax declined to ₹8,886.24 million from ₹12,556.32 million in Q4 FY26 and ₹13,692.34 million in Q1 FY25. Consolidated earnings per share fell to ₹10.94 from ₹15.45 and ₹16.85 in the respective comparison periods.
On a standalone basis, revenue from operations was ₹1,58,653.87 million in Q1 FY27 versus ₹1,84,519.18 million in Q4 FY26 and ₹1,60,248.94 million in Q1 FY25. Standalone PBT was ₹11,826.77 million, down from ₹15,579.44 million and ₹17,998.71 million, and standalone PAT was ₹8,831.20 million, down from ₹12,215.29 million and ₹13,357.53 million. Standalone EPS was ₹10.87 versus ₹15.03 and ₹16.44.
A regulatory uncertainty also weighs on the accounts: under the Environment Protection (End-of-Life Vehicles) Rules, 2025, effective April 1, 2025, the company has an obligation to scrap end-of-life vehicles sold in the domestic market (including self-use vehicles) from April 1, 2005 through June 30, 2026. The pricing mechanism for EPR certificates has not been notified, implementation details are not developed, and registration on the centralized online portal is pending. Because there is insufficient data to reliably estimate a range of outcomes, no provision has been recognized, and the company will continue to assess the obligation as the framework becomes available.
2. Tailwinds and Growth Prospects
The company continues to emphasize its SUV lineup. Domestic SUVs “continue to” feature in the business performance materials, and the company announced the name of its upcoming intelligent SUV, Hyundai BAYON, described as a new global SUV addition to HMIL’s strong SUV line-up and the beginning of a new chapter for Hyundai in India. The name draws inspiration from Bayonne, a city in the French Basque Country, and the announcement was made on September 14, 2026. Management said it looks forward to sharing more about Hyundai BAYON with India in the coming weeks, with more details to be revealed in the coming days.
The company is also pursuing AI integration across several areas, including inventory optimization, AI-based safety monitoring, and personalized and proactive assistance (referencing Voice of Customer).
On capital returns, the Board fixed Wednesday, August 05, 2026 as the record date for a final dividend of ₹21 per equity share, declared on May 08, 2026 subject to shareholder approval. The 30th Annual General Meeting, held August 26, 2026 via video conferencing, passed all six resolutions, including adoption of standalone and consolidated financial statements, declaration of dividend, re-appointment of Mr. Wangdo Hur as Director, appointment of Mr. Mukundan MS as Whole Time Director, and ratification of the cost auditors’ remuneration.
The company also received an ESG rating of 69.9 from SES ESG Research Private Limited for FY 2026, assigned independently and voluntarily by the rating agency without engagement from the company.
3. Key Risks
- Margin and profitability pressure: The sharp quarter-on-quarter and year-on-year declines in PBT, PAT, and EPS reflect discounting and cost pressures. The key ratios show EBITDA, EBIT, and PAT margins declining across the periods presented.
- Regulatory/EPR exposure: The End-of-Life Vehicles Rules obligation remains unquantified and unprovided for, with pricing and implementation mechanisms still pending. This creates uncertainty over a future financial impact.
- Demand and competitive environment: The characterization of the quarter as affected by multiple headwinds, alongside discounting pressure, points to a challenging demand and pricing environment.
- Governance and leadership transition: Mr. Gopalakrishnan CS ceased as Whole-time Director and Chief Manufacturing Officer due to superannuation effective close of business on August 31, 2026. Mr. Mukundan MS was appointed as Whole-time Director and Chief Manufacturing Officer effective September 01, 2026, subject to shareholder approval, and Mr. Young Geon Kim was appointed as Senior Management Personnel effective August 01, 2026.
4. Management Guidance Versus Observed Performance
Management characterized Q1 FY27 as a challenging quarter affected by multiple headwinds, and the reported results are consistent with that characterization: consolidated revenue, PBT, PAT, and EPS all declined both sequentially and year-on-year. The PBT movement analysis explicitly attributes margin impact to discounts (net of price increases) and other cost items.
Forward-looking statements are limited. Management said it looks forward to sharing more about Hyundai BAYON with India in the coming weeks and that more details about the intelligent SUV will be revealed in the coming days. The company also disclosed that its participation in a Goldman Sachs-organized conference/NDR in Hong Kong on August 31, 2026 would be based strictly on publicly available information, with no Unpublished Price Sensitive Information shared. The investor presentation includes a safe harbor statement noting risks, uncertainties, and other factors that could cause actual results to differ materially from forward-looking statements, and stating no obligation to update such statements.
Broker Narrative
Early reports centered on weak domestic demand, festive-season discounts, geopolitical export risks, and the Red Sea crisis, balanced by optimism over SUV/premium mix, Africa-Mexico-LATAM exports, rural monsoon demand, and Creta-led EV launches. Later reports shifted to commodity price pressures, raw-material cost inflation, fuel and interest-rate macro risks, and EPS cuts, while geopolitical disruptions persisted. New themes included Bayon and E-SUV launches, calibrated price hikes, Tamil Nadu incentives, capacity utilization, and an FY28 EV penetration target, yet repeated negative returns and DISAPPOINTMENT outcomes showed these drivers did not support the stock.
Fears that came true
- Weak demand and domestic slowdown flagged in 2024 materialized as the stock posted repeated negative returns and DISAPPOINTMENT outcomes from mid-2025 through 2026 despite continued Buy calls.
- Geopolitical challenges impacting exports persisted into later geopolitical disruptions and coincided with negative actual returns, undermining the export-focused narrative.
- Incremental discounts during the festive season foreshadowed persistent pricing pressure, later appearing as commodity price pressures and raw-material cost inflation that cut margins and EPS estimates.
Optimism that failed
- Favorable SUV mix and premiumization optimism failed to translate into price performance, as the stock recorded negative returns and DISAPPOINTMENTs despite this tailwind.
- Positive rural demand driven by better crop output and healthy monsoons did not offset domestic weakness, coinciding with multiple negative actual returns.
- Strong export opportunities in Africa, Mexico, and LATAM with India as a production hub failed to lift the stock, as geopolitical disruptions and negative returns persisted.
Broker Timeline
23 broker calls · 2024-11-12 to 2026-10-29
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.