HIRECT
Equity Metrics
November 18, 2026
Hind Rectifiers Limited
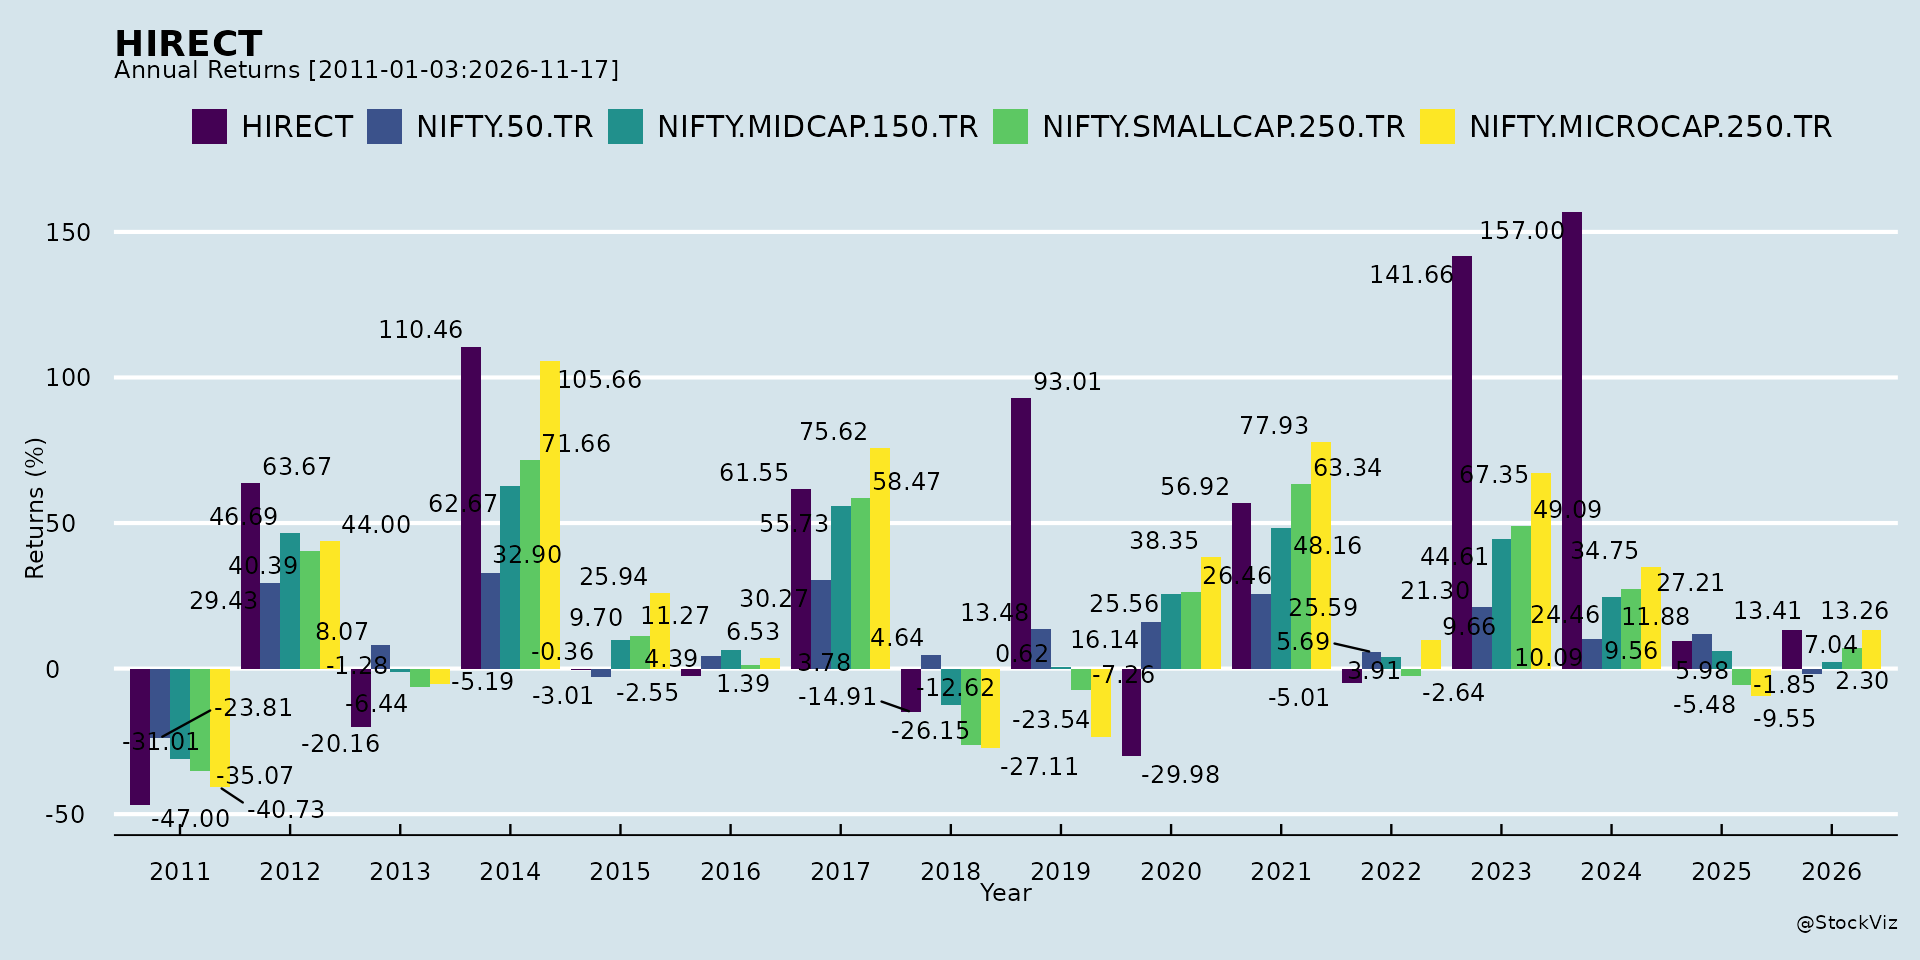
Annual Returns
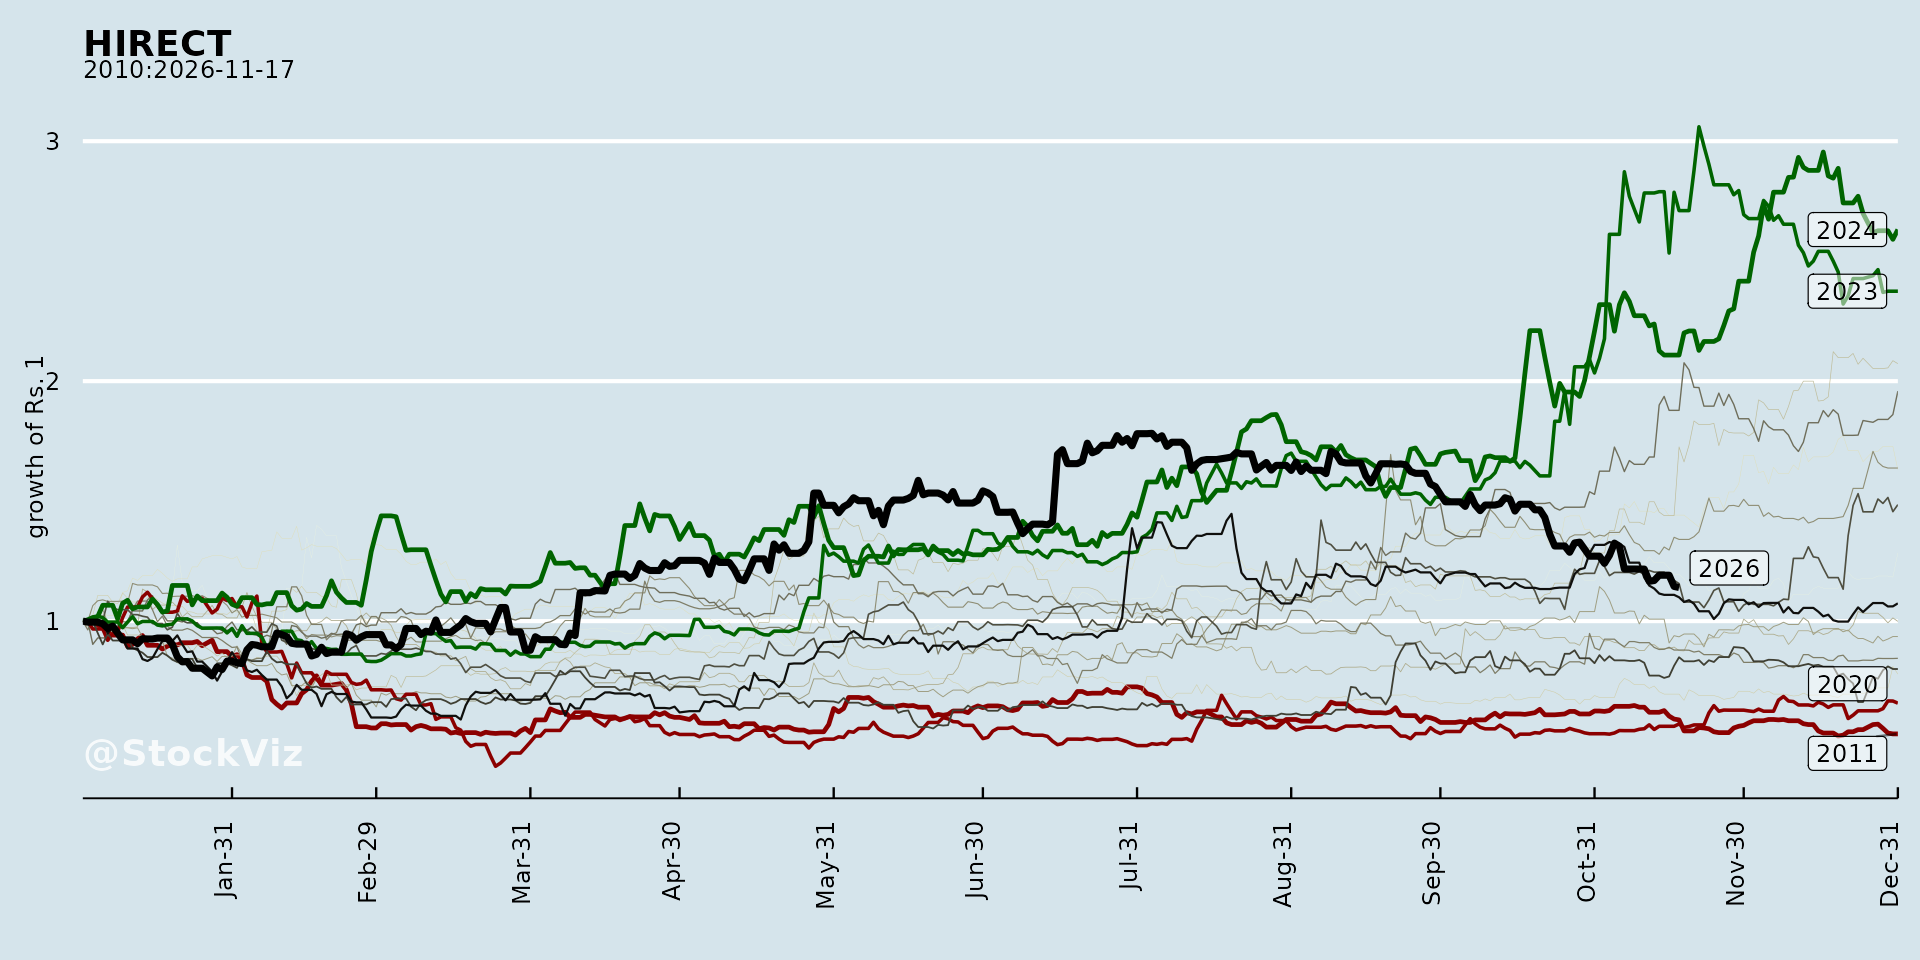
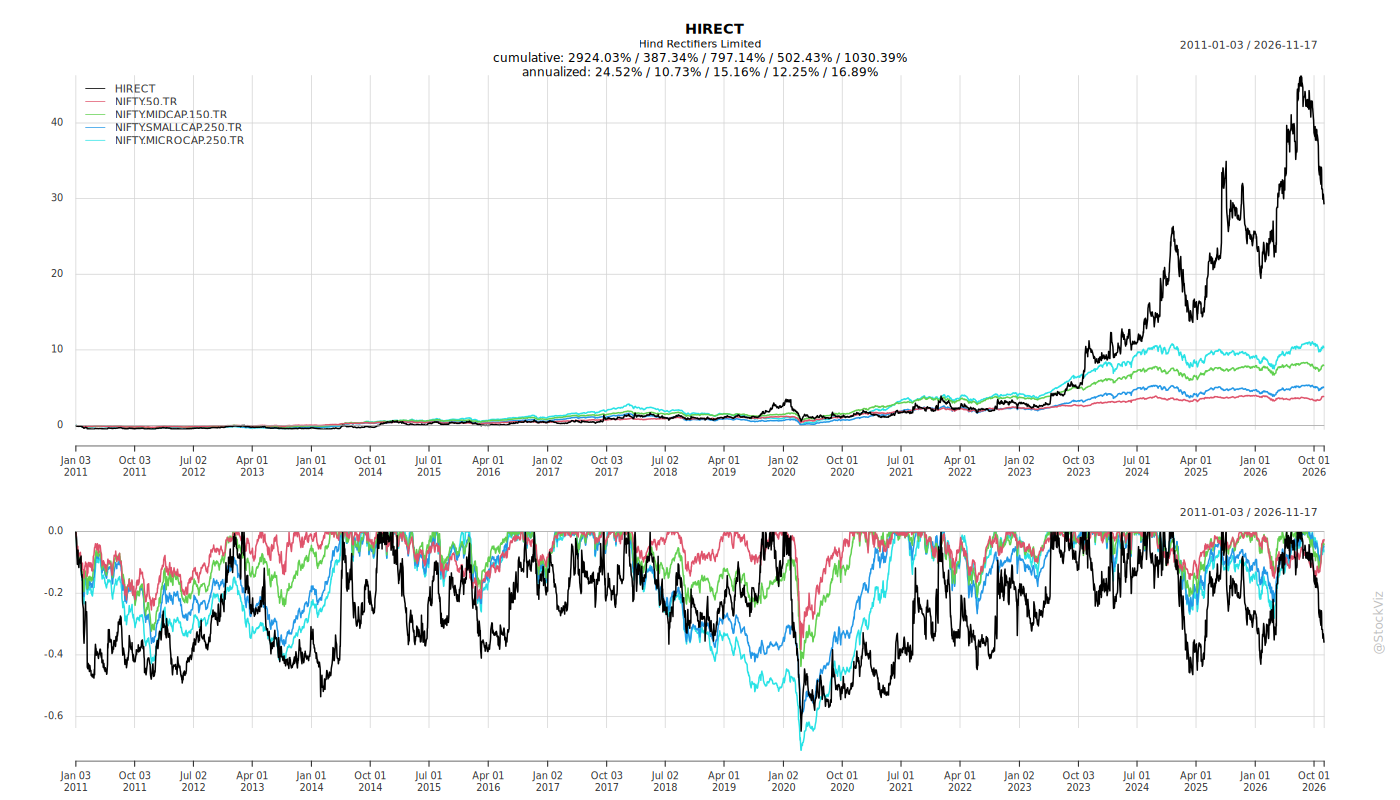
Cumulative Returns and Drawdowns
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-17
HIRECT — Recent Corporate Developments and Performance Analysis
1. Headwinds and Challenges
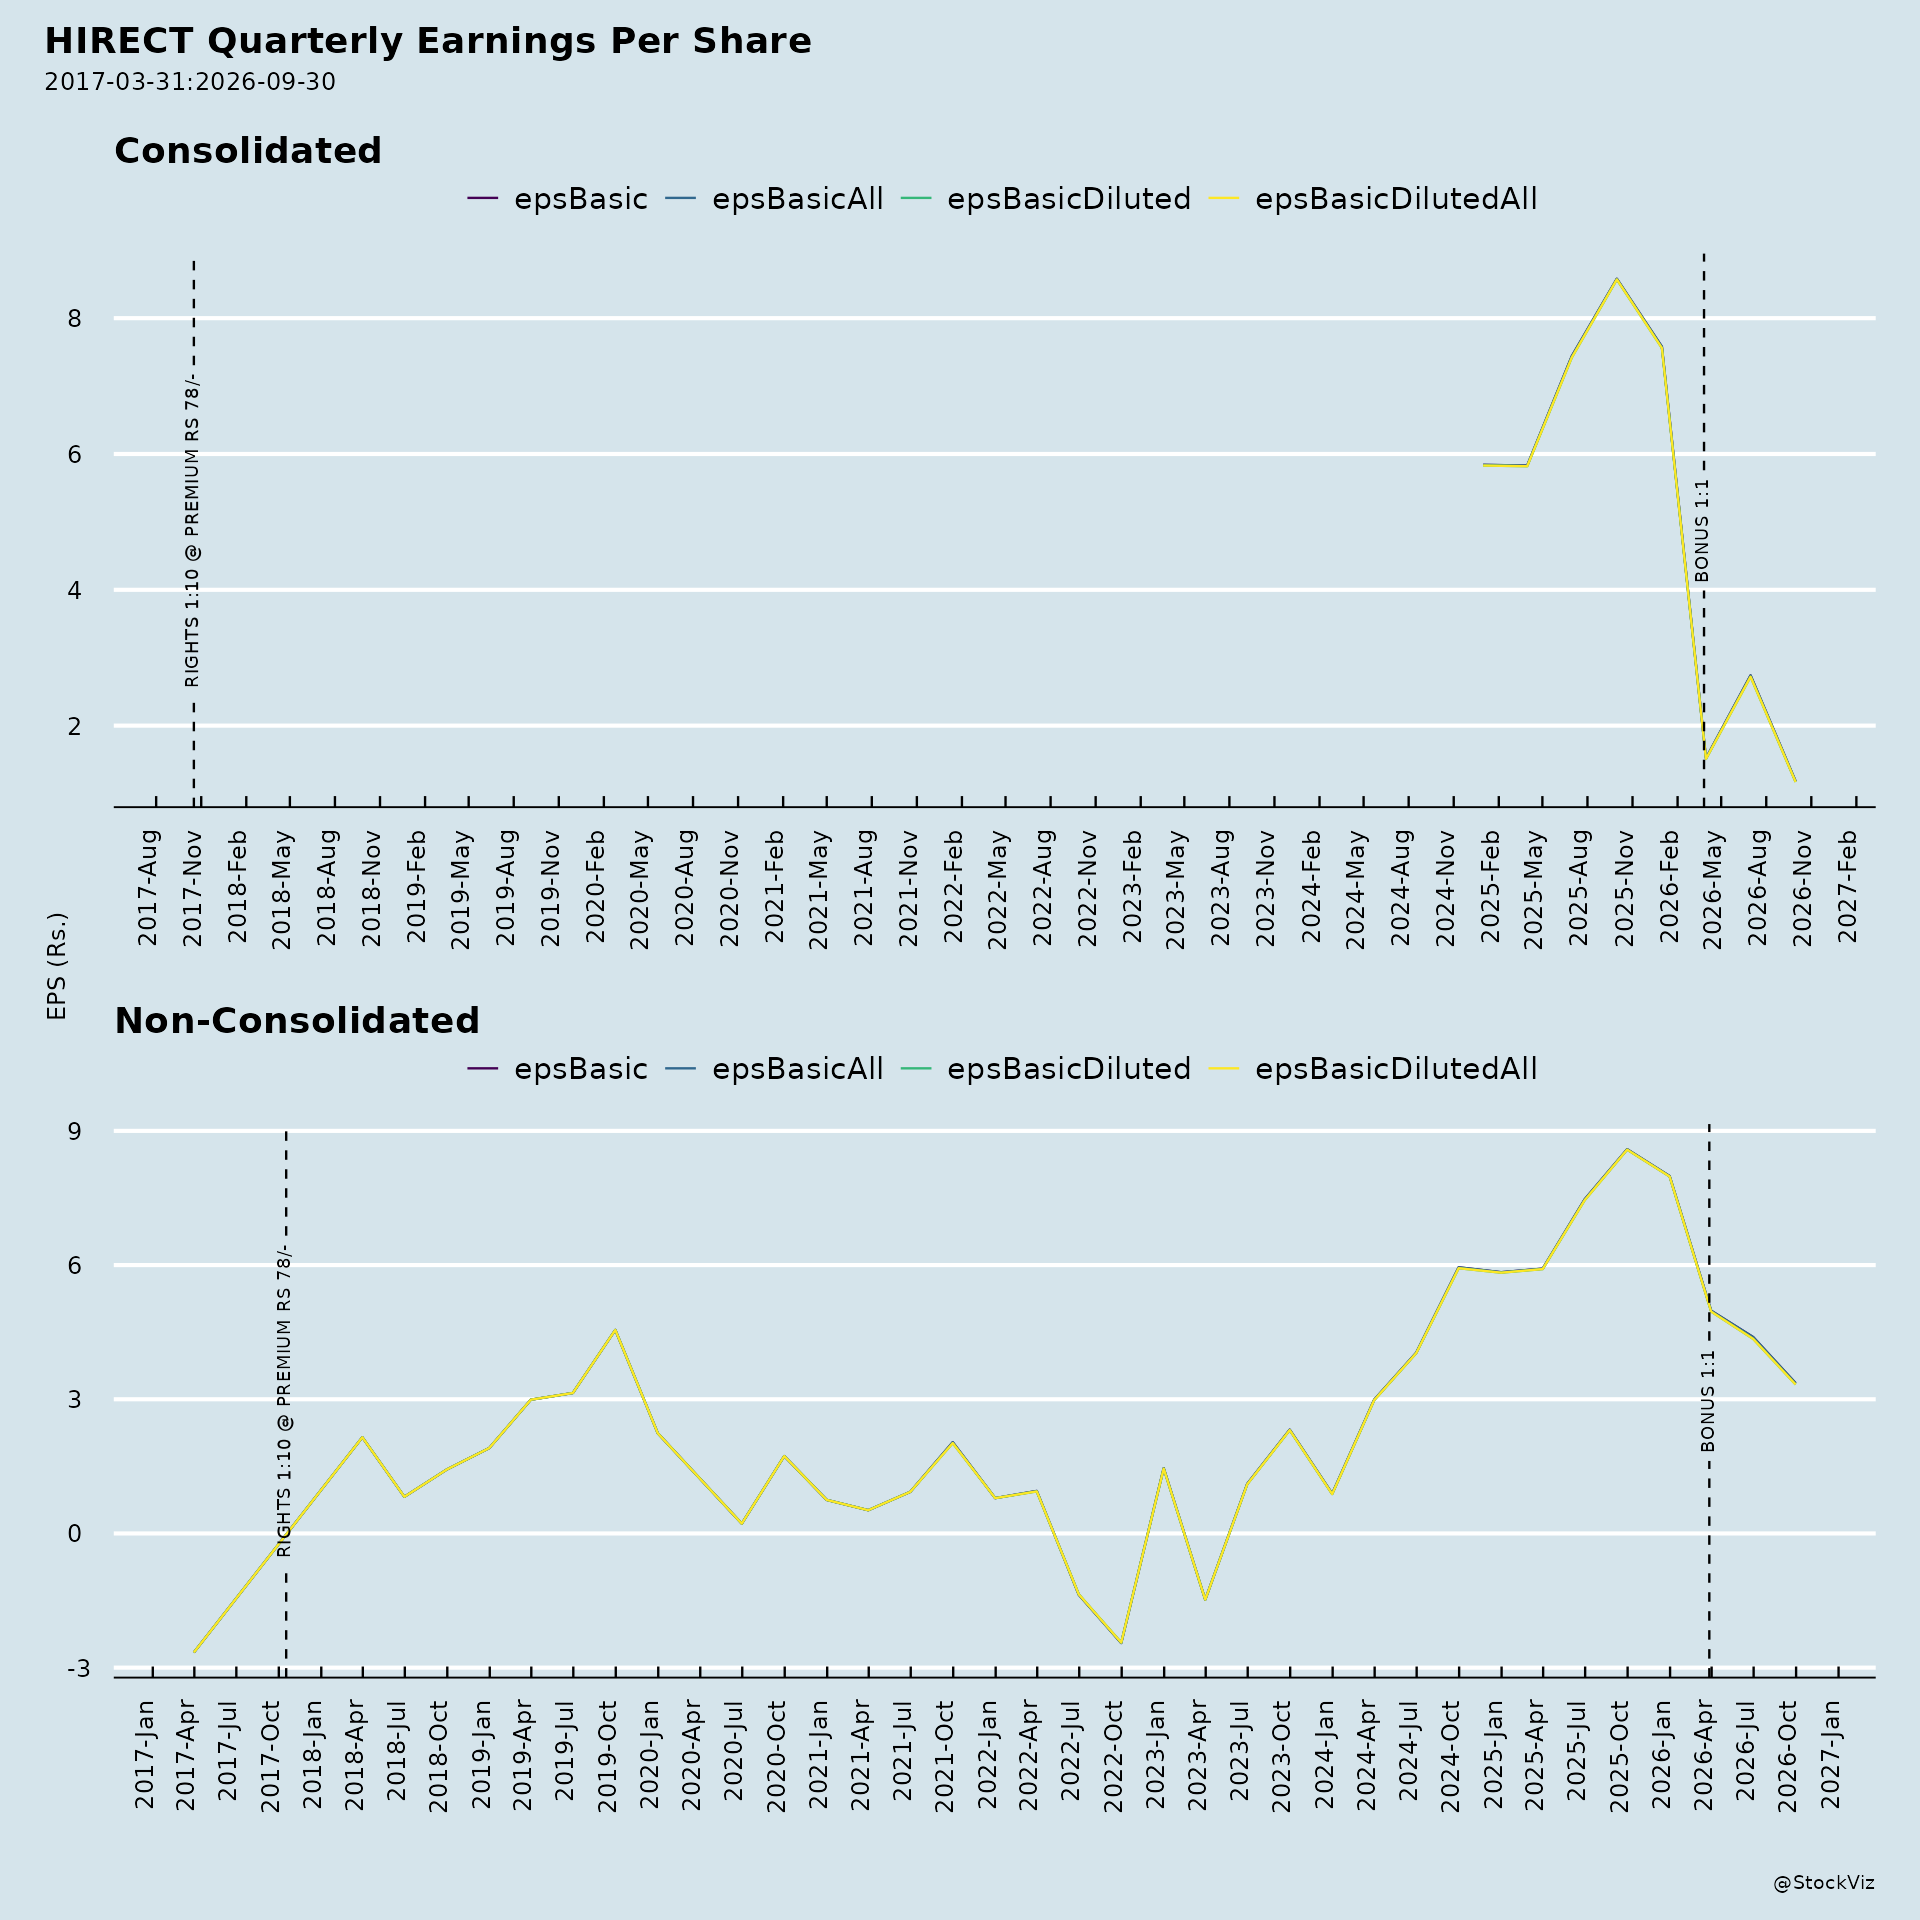
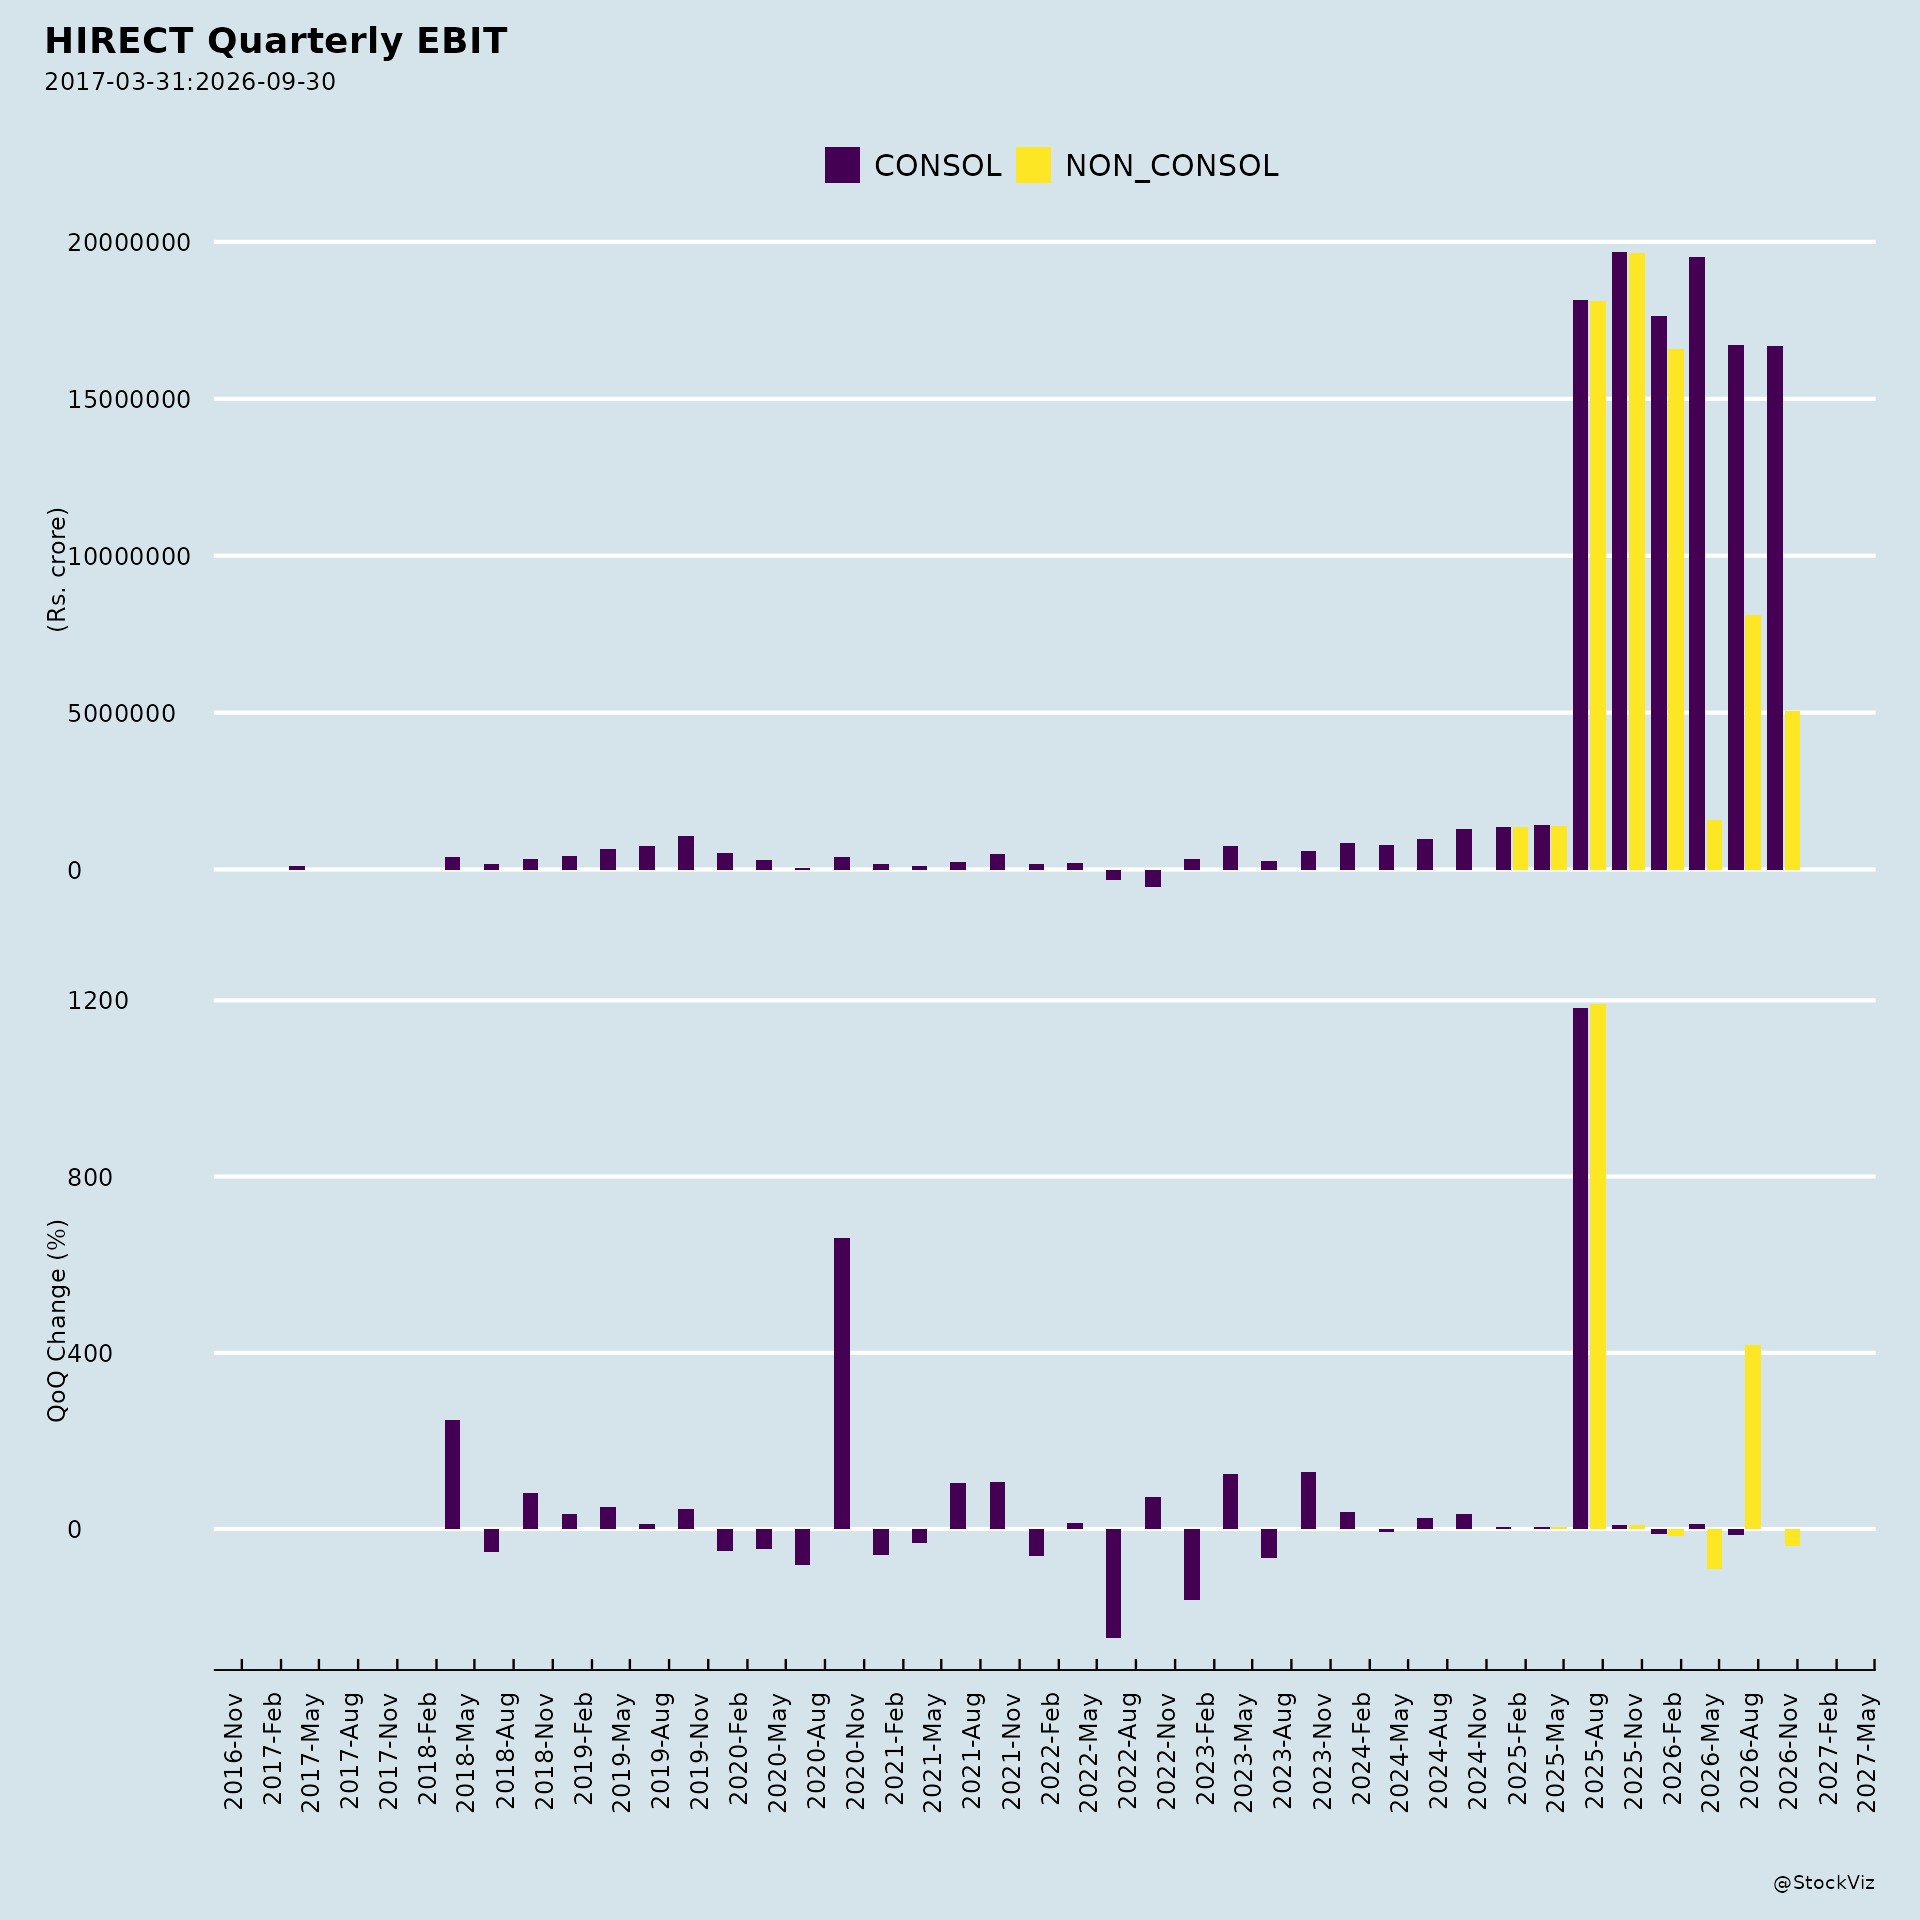
Margin pressure from Elventive France integration. The consolidation and scale-up of Elventive France drove higher employee and operating costs in Q1FY27. Consolidated EBITDA fell to ₹13.2 crore from ₹24.2 crore in Q1FY26, and consolidated PAT after minority interest declined to ₹9.4 crore from ₹12.8 crore. Management expects this near-term pressure to persist over the next 3–5 quarters as Elventive France moves toward breakeven.
Raw material cost inflation. Standalone gross profit margin moderated to 25.5% in Q1FY27 from 26.2% in Q1FY26, attributed to higher raw material costs amid volatility arising from the West Asia crisis.
Other identified headwinds. The company cites higher material cost, changes in government policies, and an increase in finance cost as material challenges. Operations are also subject to fluctuations in earnings, competition, economic growth conditions, retention of skilled professionals, time and cost overruns on contracts, and government policy risk.
Leadership transition. Mr. Douglas J. Bailey resigned as Global Chief Executive Officer effective the close of business hours on August 11, 2026, with Mr. Chidambaram Balakrishnan appointed as Global CEO with immediate effect the same day.
2. Tailwinds and Growth Prospects
Strong order book. Order book stood at ₹739.8 crore as of July 2026, anchored by the core Railway Transformer business, with Railway Electronics and Railway Electromechanical products together accounting for a meaningful share.
Entry into next-generation trainsets. Two development orders were secured in July 2026: - A maiden MEMU trainset order from Modern Coach Factory (MCF)/Indian Railways, dated July 26, 2026, covering complete propulsion systems for four MEMU trainsets (traction transformers, propulsion systems, traction motors and TCMS), valued at approximately ₹60 crore, to be executed within 24 months. - A first Vande Metro (Namo Bharat) trainset development order from Indian Railways, dated July 25, 2026, valued at approximately ₹60 crore, to be executed within 21 months.
Together these represent roughly ₹120 crore of combined orders and mark a shift from component supply toward integrated systems and solutions.
International expansion. The company secured its first United States order for traction motor assemblies, and entered the mining segment with its first U.S. order for IGBT converters. It also approved investment in up to 300 equity shares of AED 1,000 each in wholly owned subsidiary Hirect Global Holdings Limited, UAE.
Policy tailwinds. Growth prospects are supported by a record ₹2,93,030 crore allocation to the Ministry of Railways in the Union Budget 2026 for infrastructure, rolling stock, and safety systems such as KAVACH, alongside demand from electrification, sustainability goals, and high-speed rail corridors.
Operational initiatives. Backward integration in copper conductors with 350 TPM capacity, value engineering to reduce design cost, increasing the number of new products, implementation of the theory of constraints to boost productivity, and installation of modern machines to reduce production time.
3. Key Risks
- Continued consolidated margin pressure for 3–5 quarters while Elventive France scales toward breakeven.
- Raw material cost volatility, including exposure to geopolitical developments such as the West Asia crisis.
- Dependence on government policies and railway sector spending cycles.
- Execution risk on large system-level orders, including potential time and cost overruns on contracts.
- Competition and retention of skilled professionals.
- Fluctuations in earnings and general economic growth conditions.
4. Management Guidance vs. Observed Performance
Guidance: Management stated that consolidated EBITDA is expected to remain moderated over the next 3–5 quarters, followed by gradual improvement as Elventive France reaches breakeven and scales. Margins are expected to improve gradually thereafter.
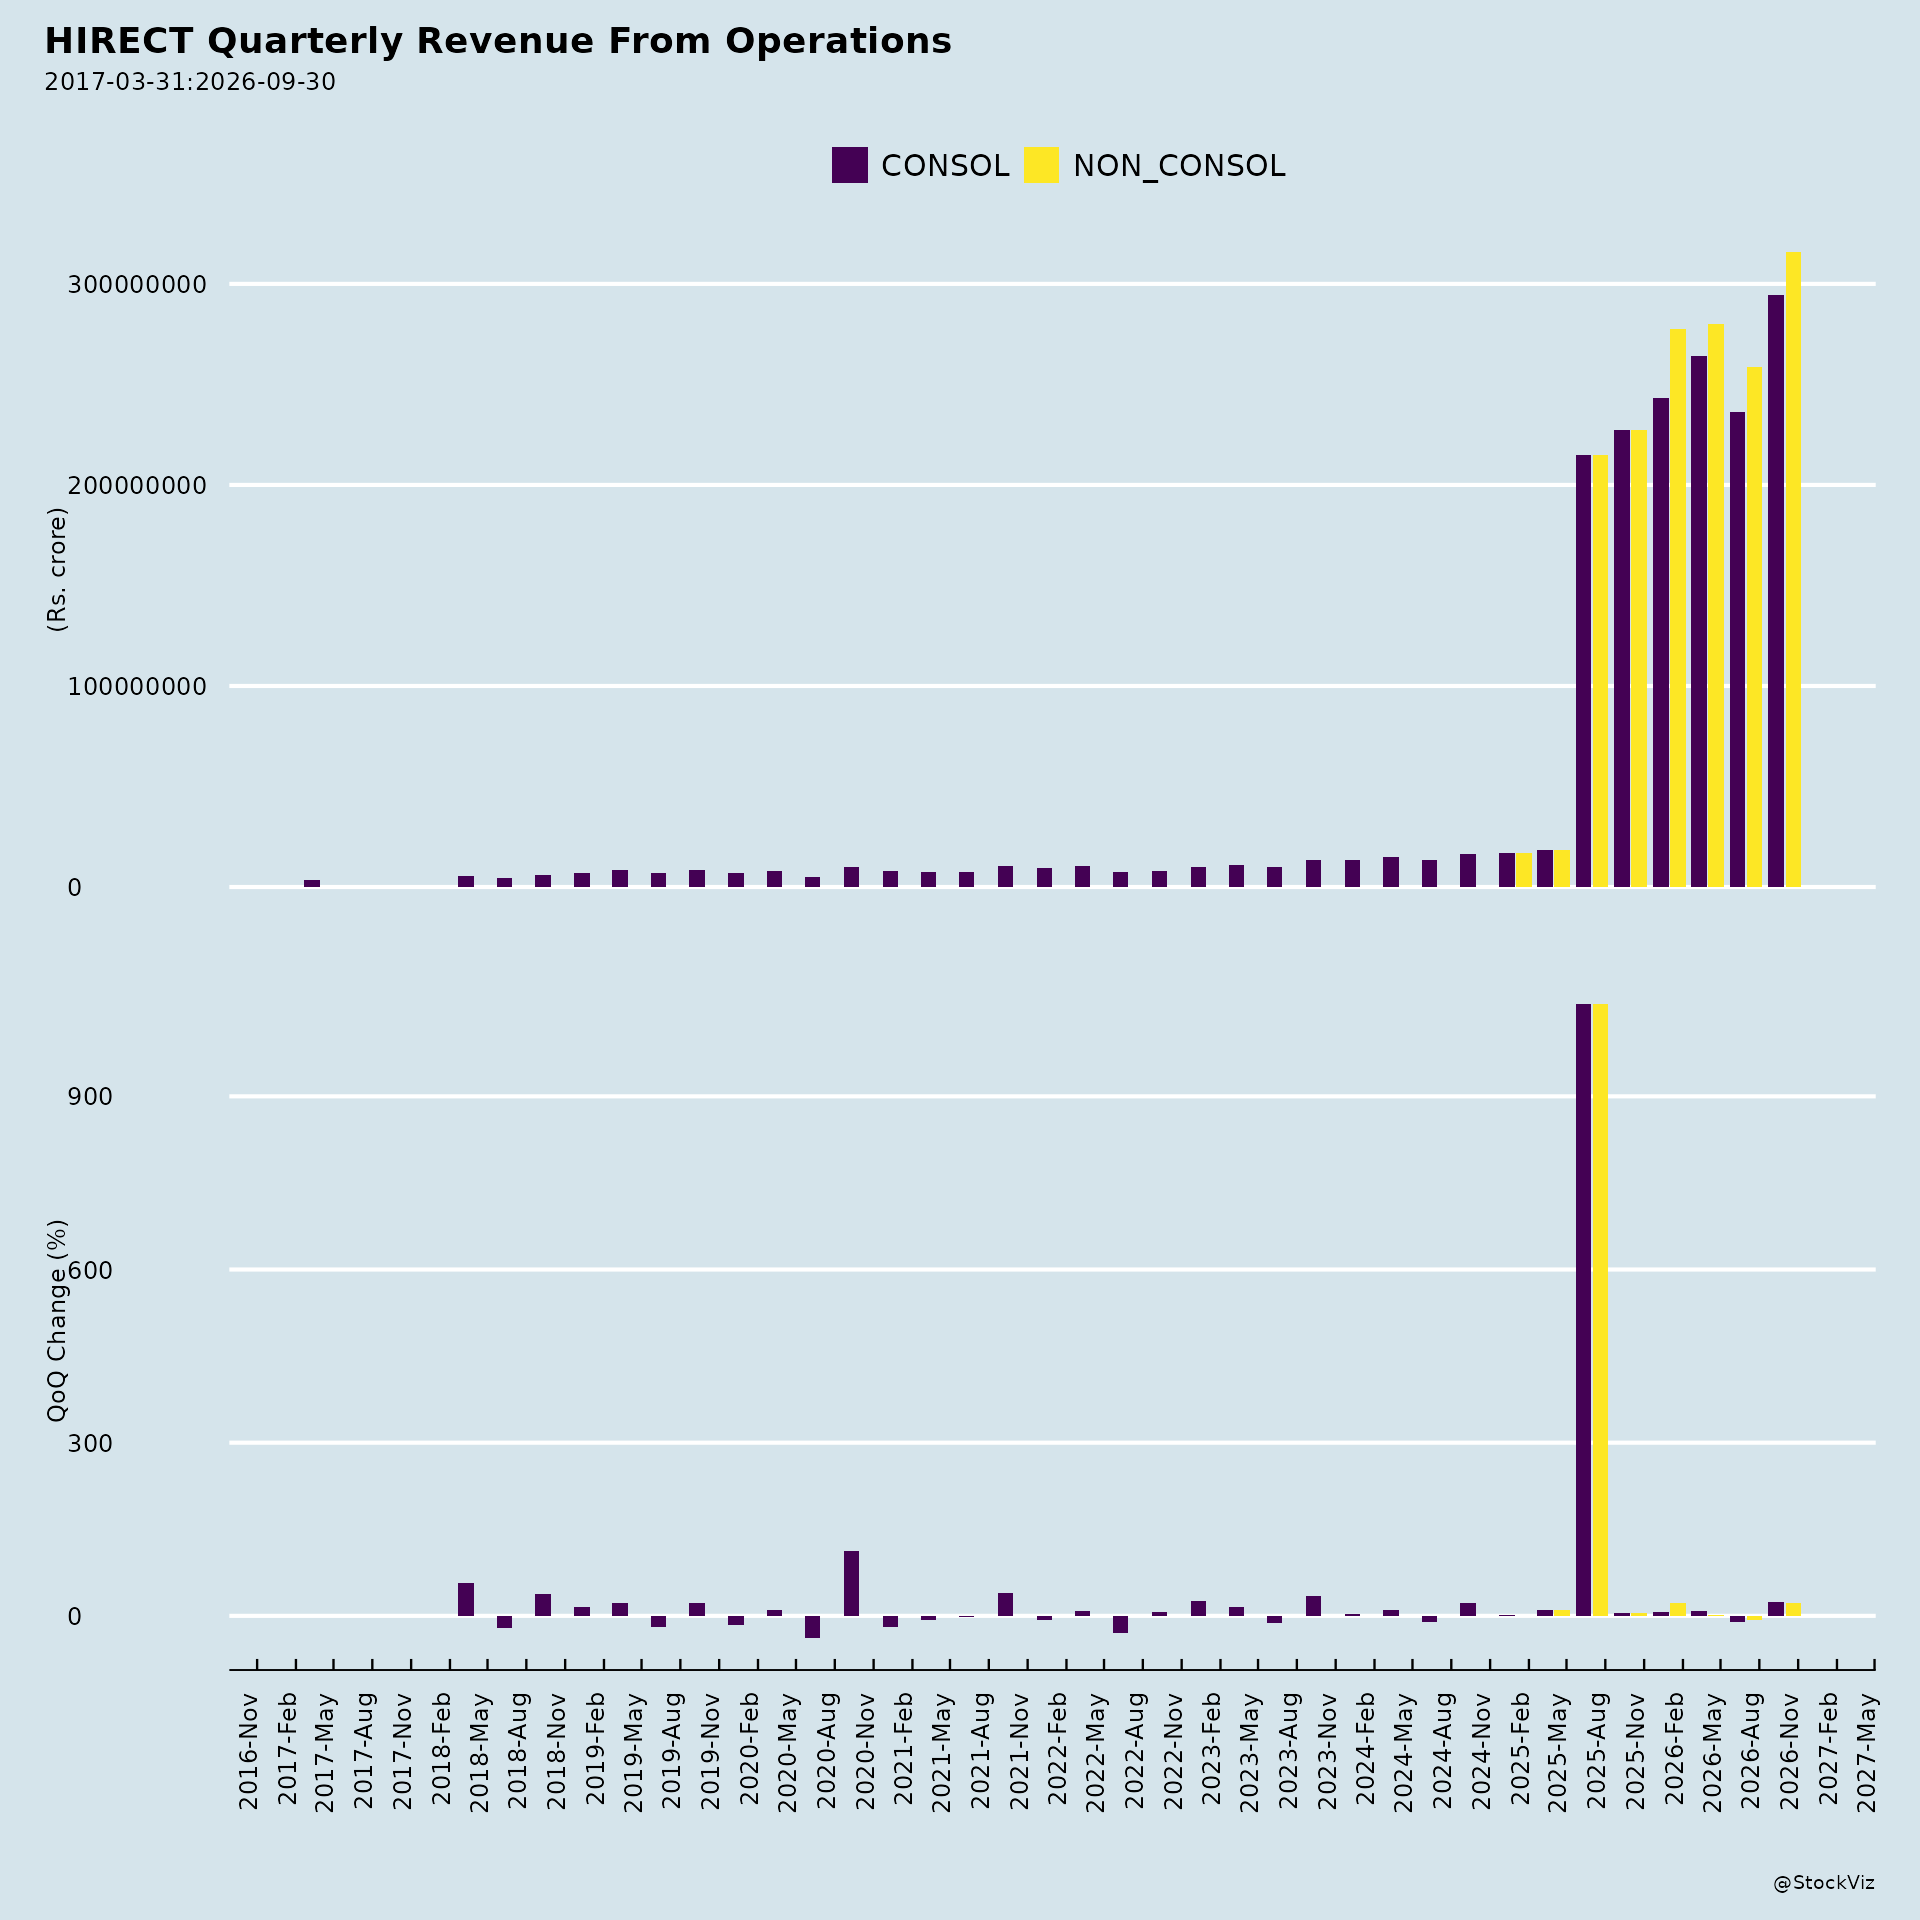
Observed performance: Q1FY27 consolidated revenue grew 20.3% YoY to ₹258.4 crore (from ₹214.8 crore), while consolidated EBITDA declined to ₹13.2 crore (from ₹24.2 crore) and PAT after minority interest fell to ₹9.4 crore (from ₹12.8 crore) — consistent with the guided near-term margin pressure. Consolidated gross profit rose 30.2% YoY to ₹73.2 crore at a 28.3% margin, and PAT included a ₹3.5 crore exceptional item from the sale of the Dehradun plant.
Standalone performance: Revenue grew 10.1% YoY to ₹236.4 crore, EBITDA rose 3.2% YoY to ₹25.1 crore (10.6% margin), and PAT increased 17.8% YoY to ₹15.1 crore (6.4% margin), indicating the core standalone business continued to expand even as consolidated margins were weighed down by the international subsidiary.
Strategic guidance: Management reiterated focus on strengthening the core railway franchise, increasing participation in higher-value products and systems, scaling technology-led businesses, and expanding into international and adjacent industrial markets — evidenced by the MEMU, Vande Metro, U.S. traction motor, and U.S. mining IGBT orders during the quarter.
5. Governance and Capital Actions
- Dividend of ₹1.40 per equity share approved at the 68th AGM on August 11, 2026, credited on August 13, 2026.
- Board approved appointment of Mr. Rahul Rai as Additional Director (Non-Executive Independent Director) for a five-year term from August 11, 2026 to August 10, 2031, subject to member approval.
- Board approved appointment of Mr. Anil Kumar Nemani as Additional Director and Whole-Time Director designated Executive Director and CFO for three years, also to act as Group CFO, subject to member approval.
- Board approved investment in Hirect Global Holdings Limited, UAE.
- A postal ballot is being sought for the above director appointments and for extension of the timeline for utilizing funds raised through a preferential issue of equity warrants until December 31, 2026 for machinery procurement.
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.