HINDPETRO
Equity Metrics
September 24, 2026
Hindustan Petroleum Corporation Limited
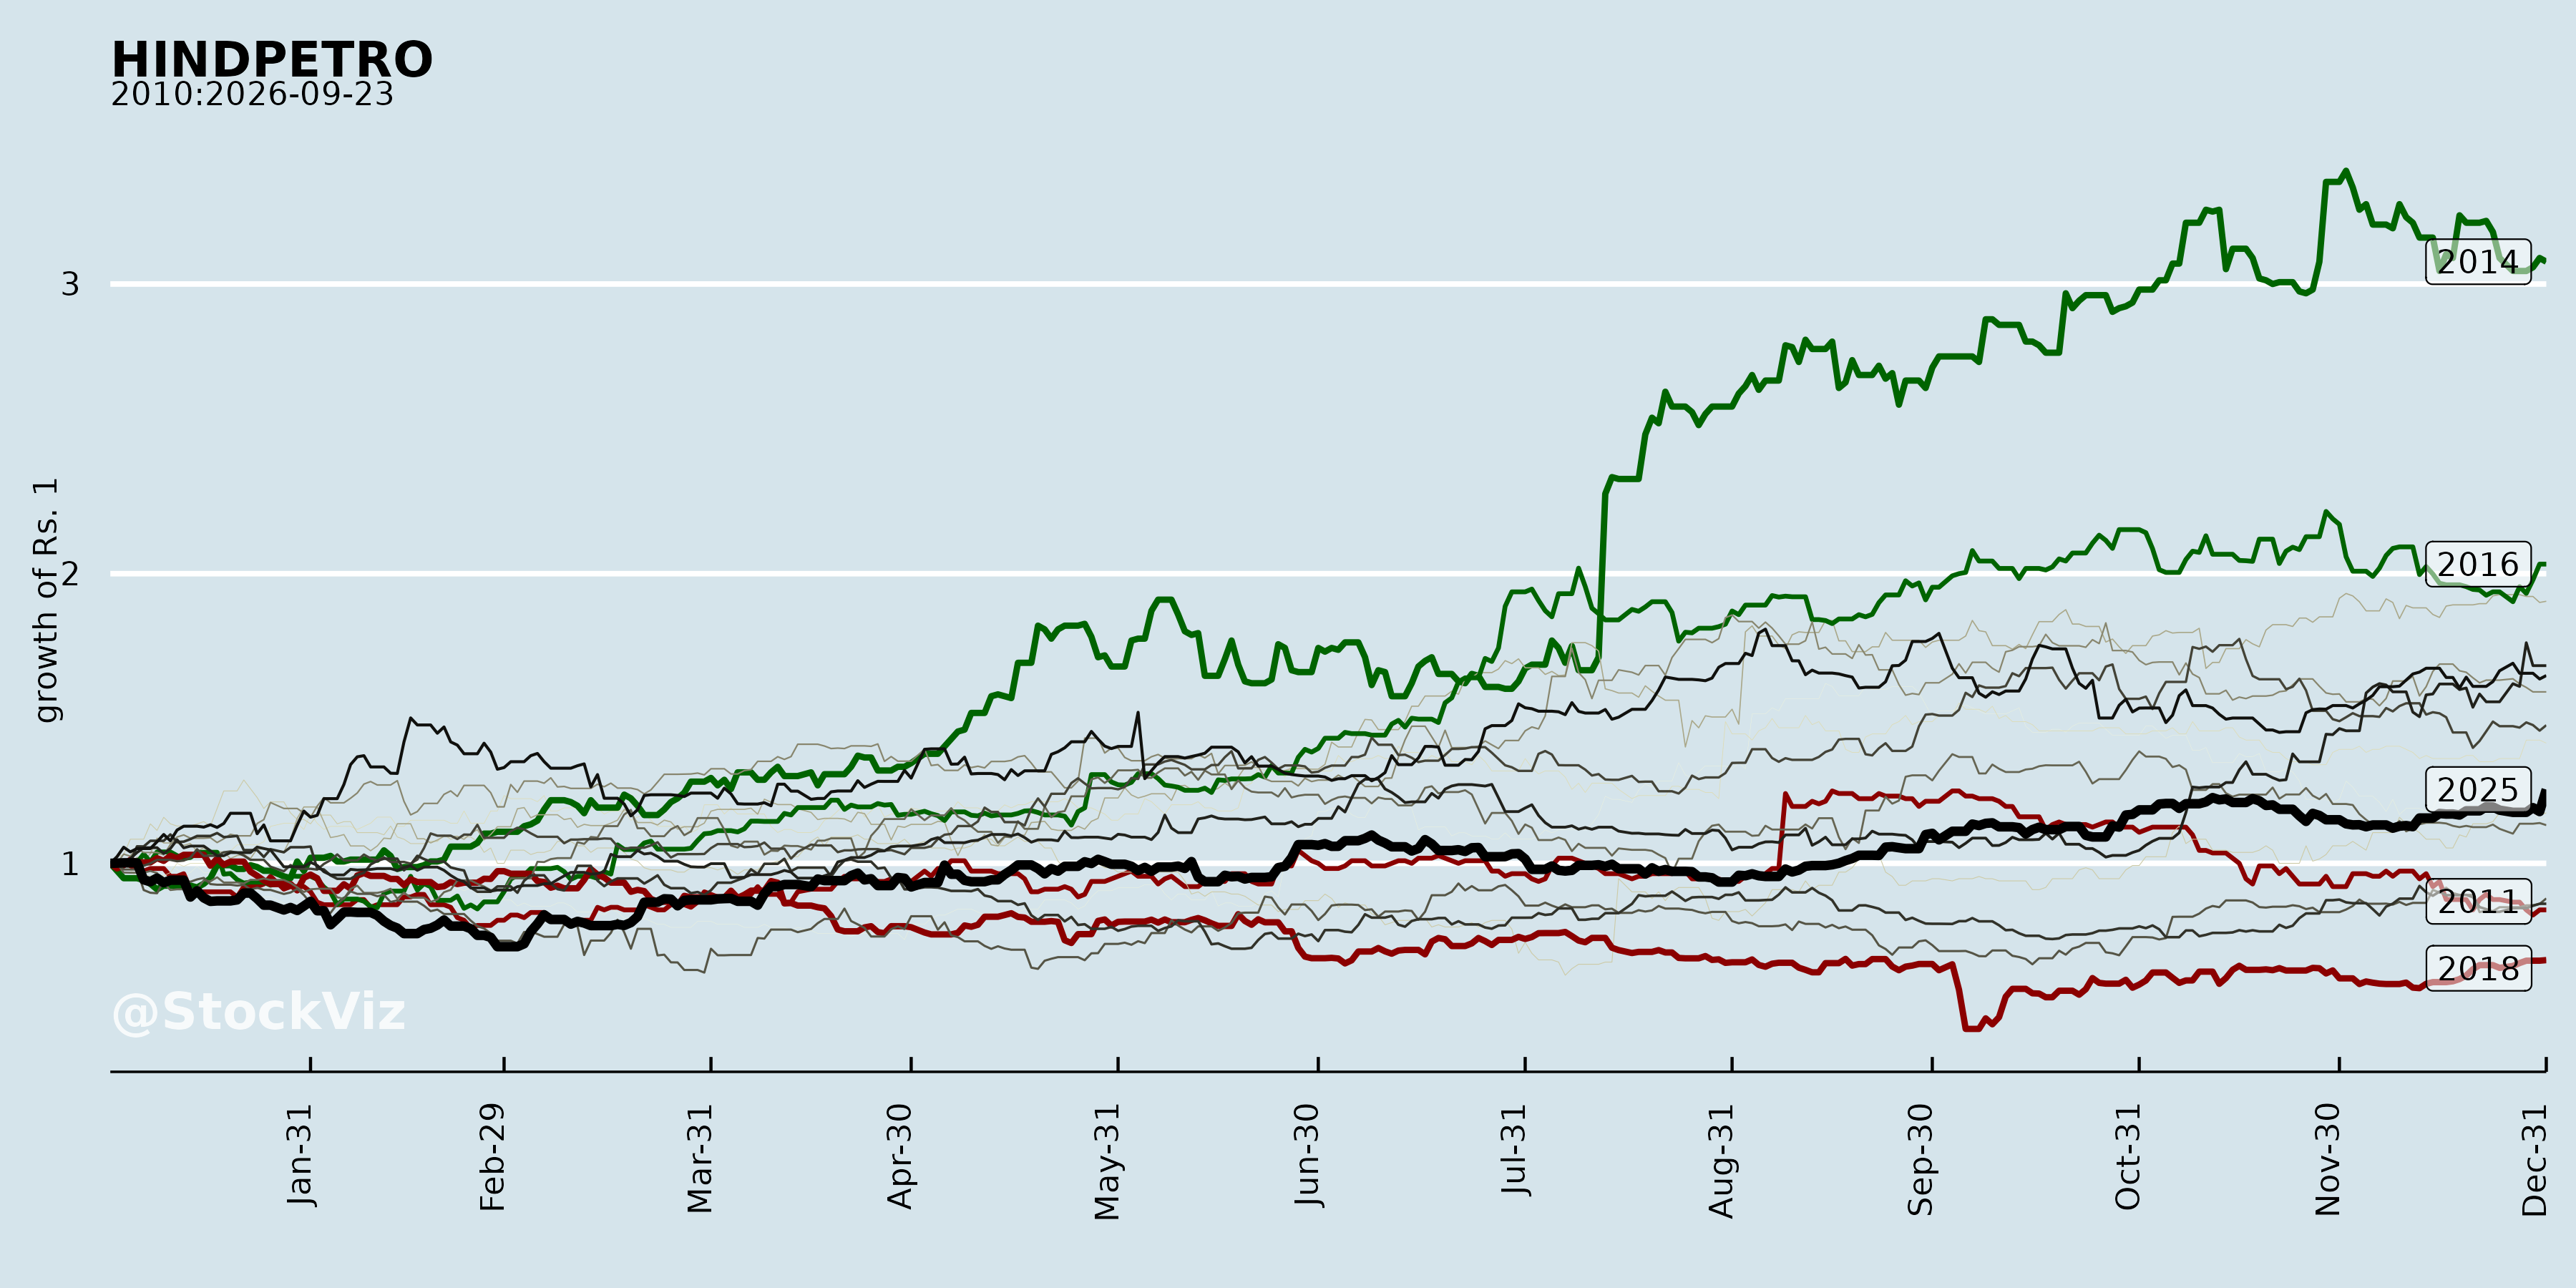
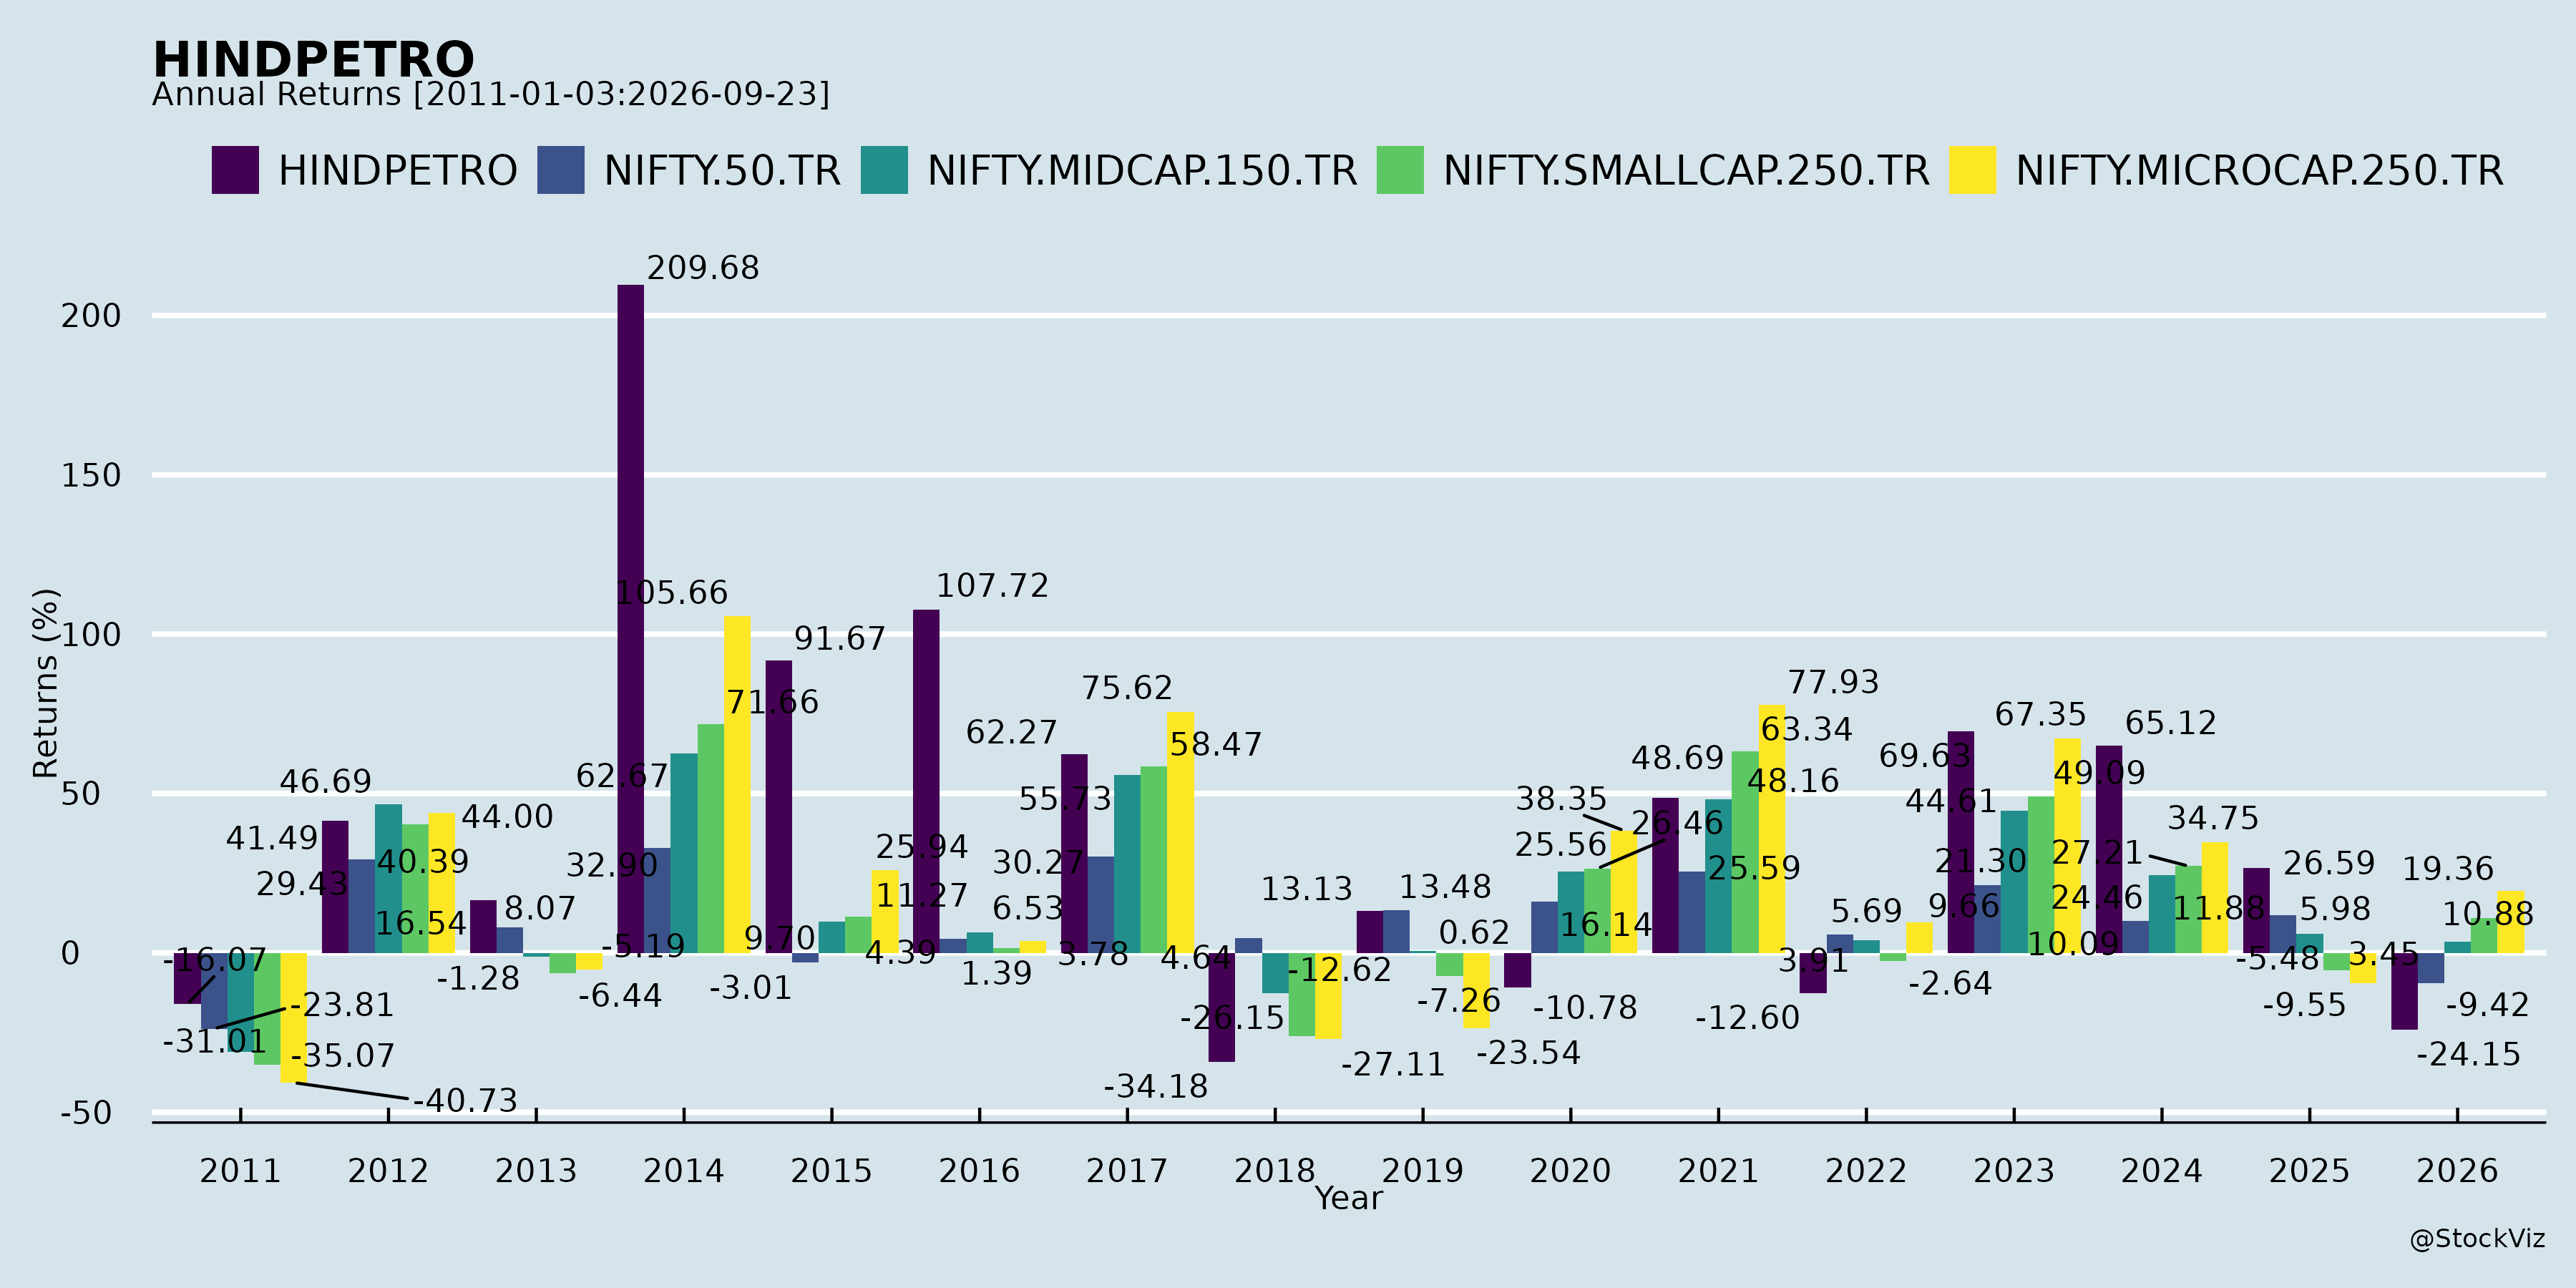
Annual Returns
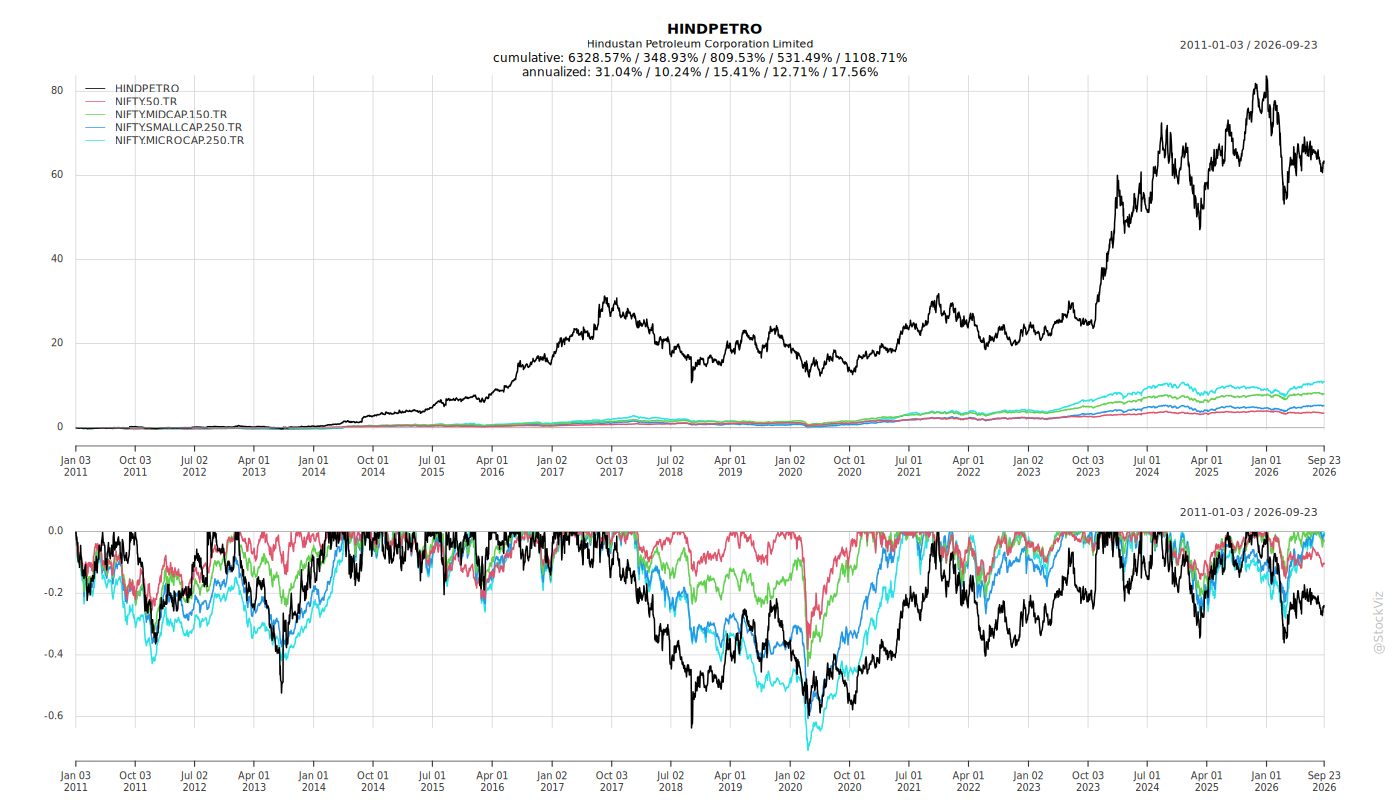
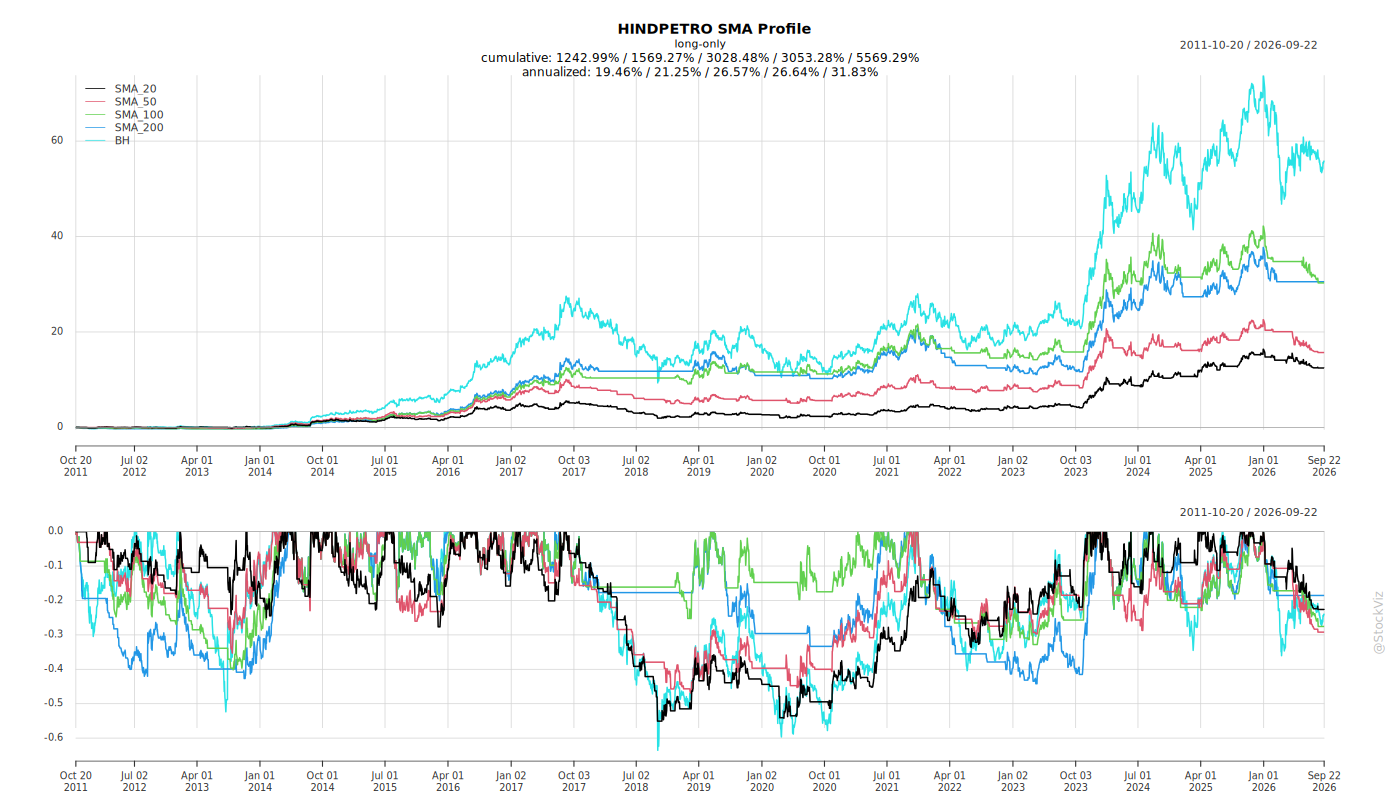
Cumulative Returns and Drawdowns
Fundamentals
Ownership
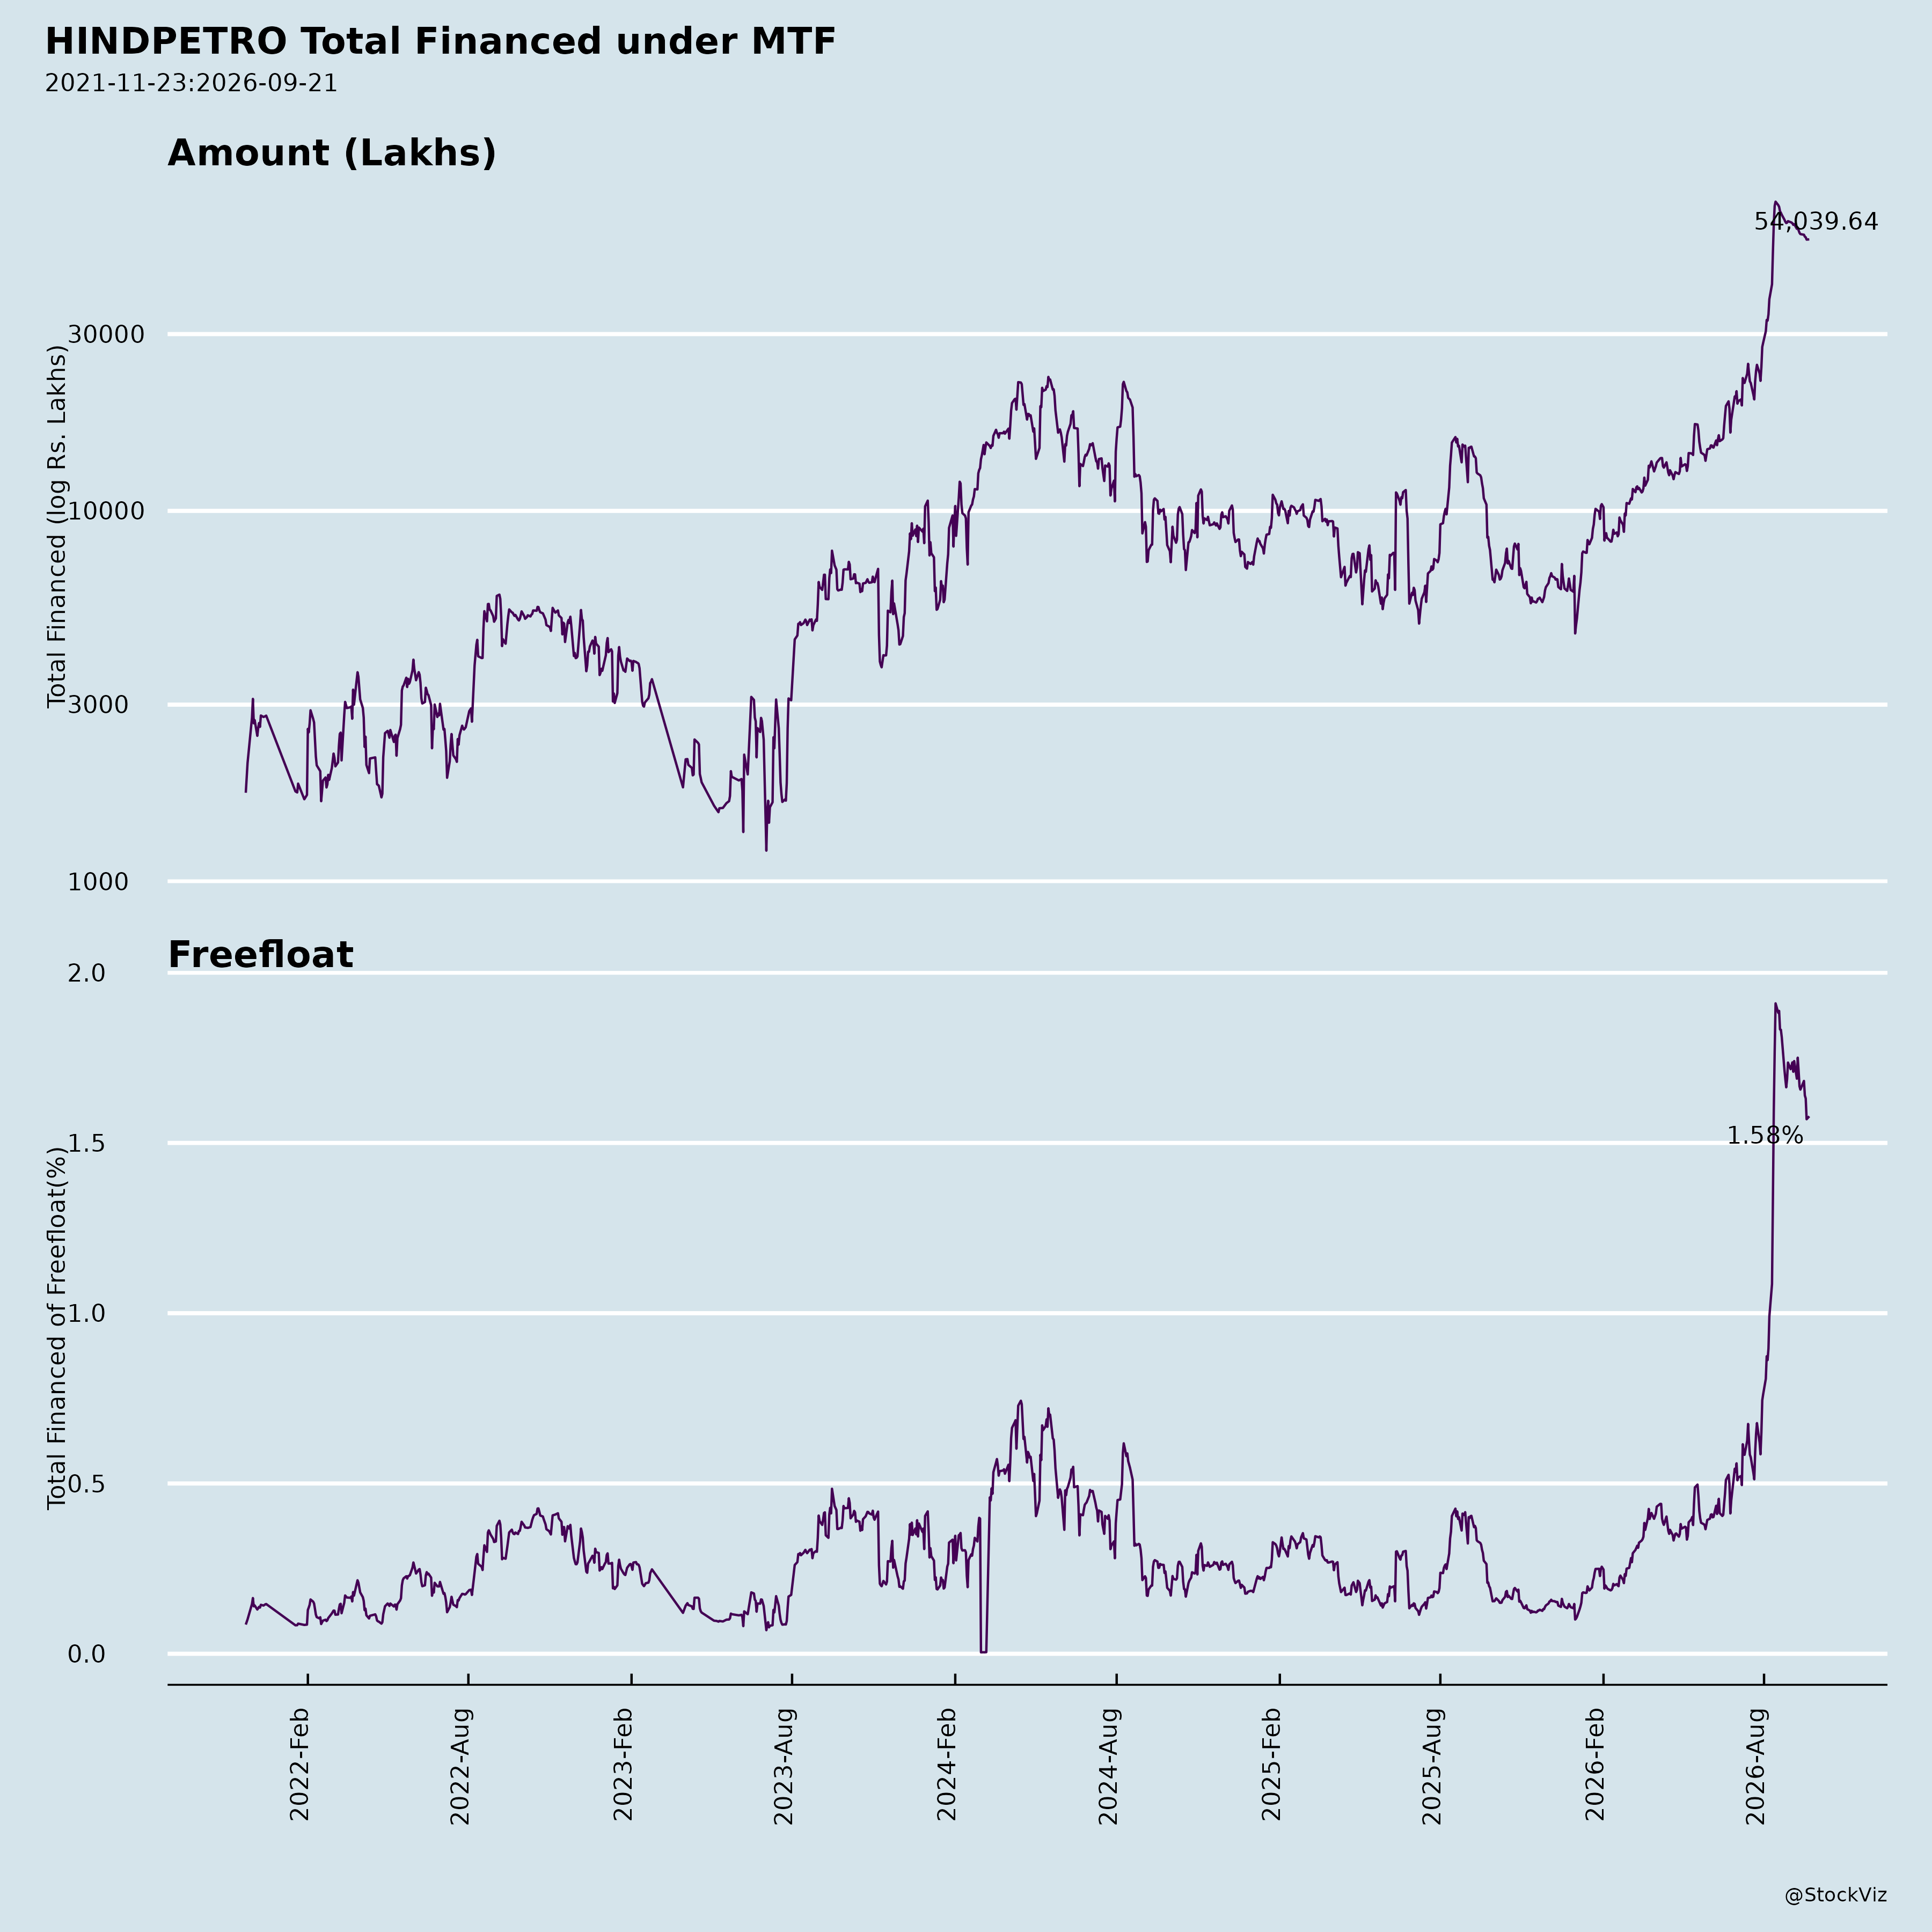
Margined
AI Summary
asof: 2026-09-16
HINDPETRO: Recent Corporate Announcements — Analysis
1. Headwinds and Challenges
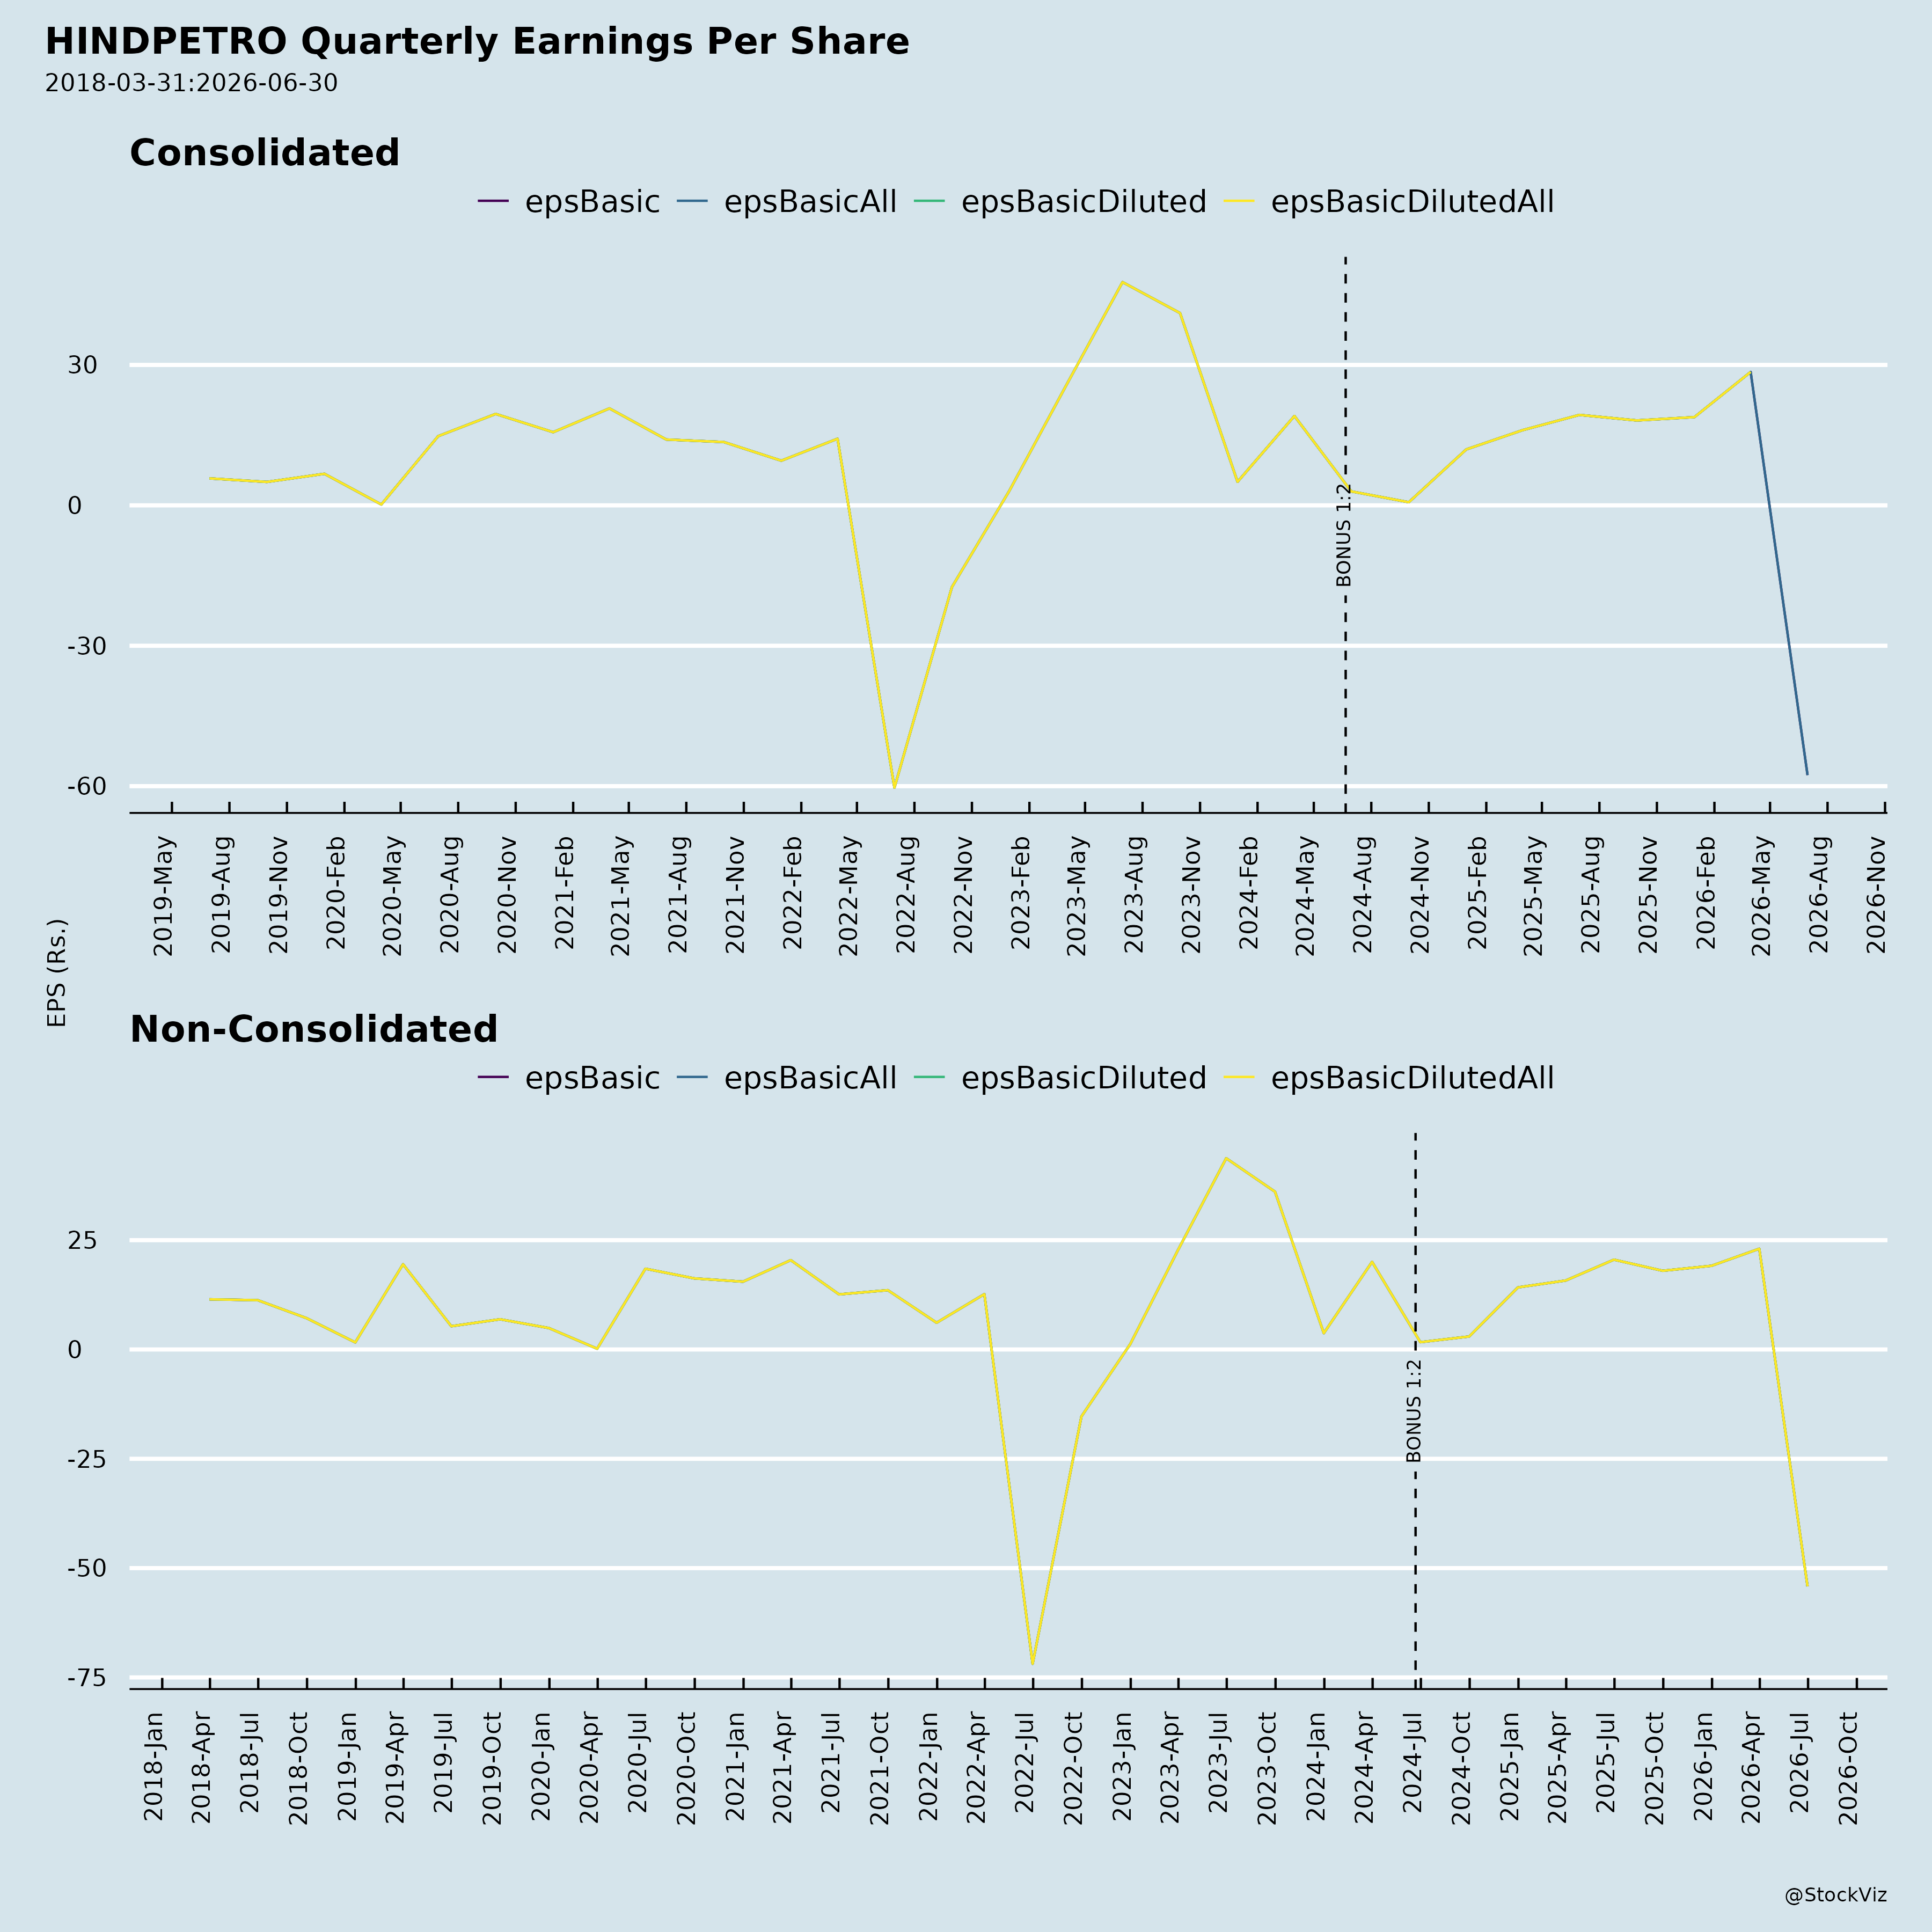
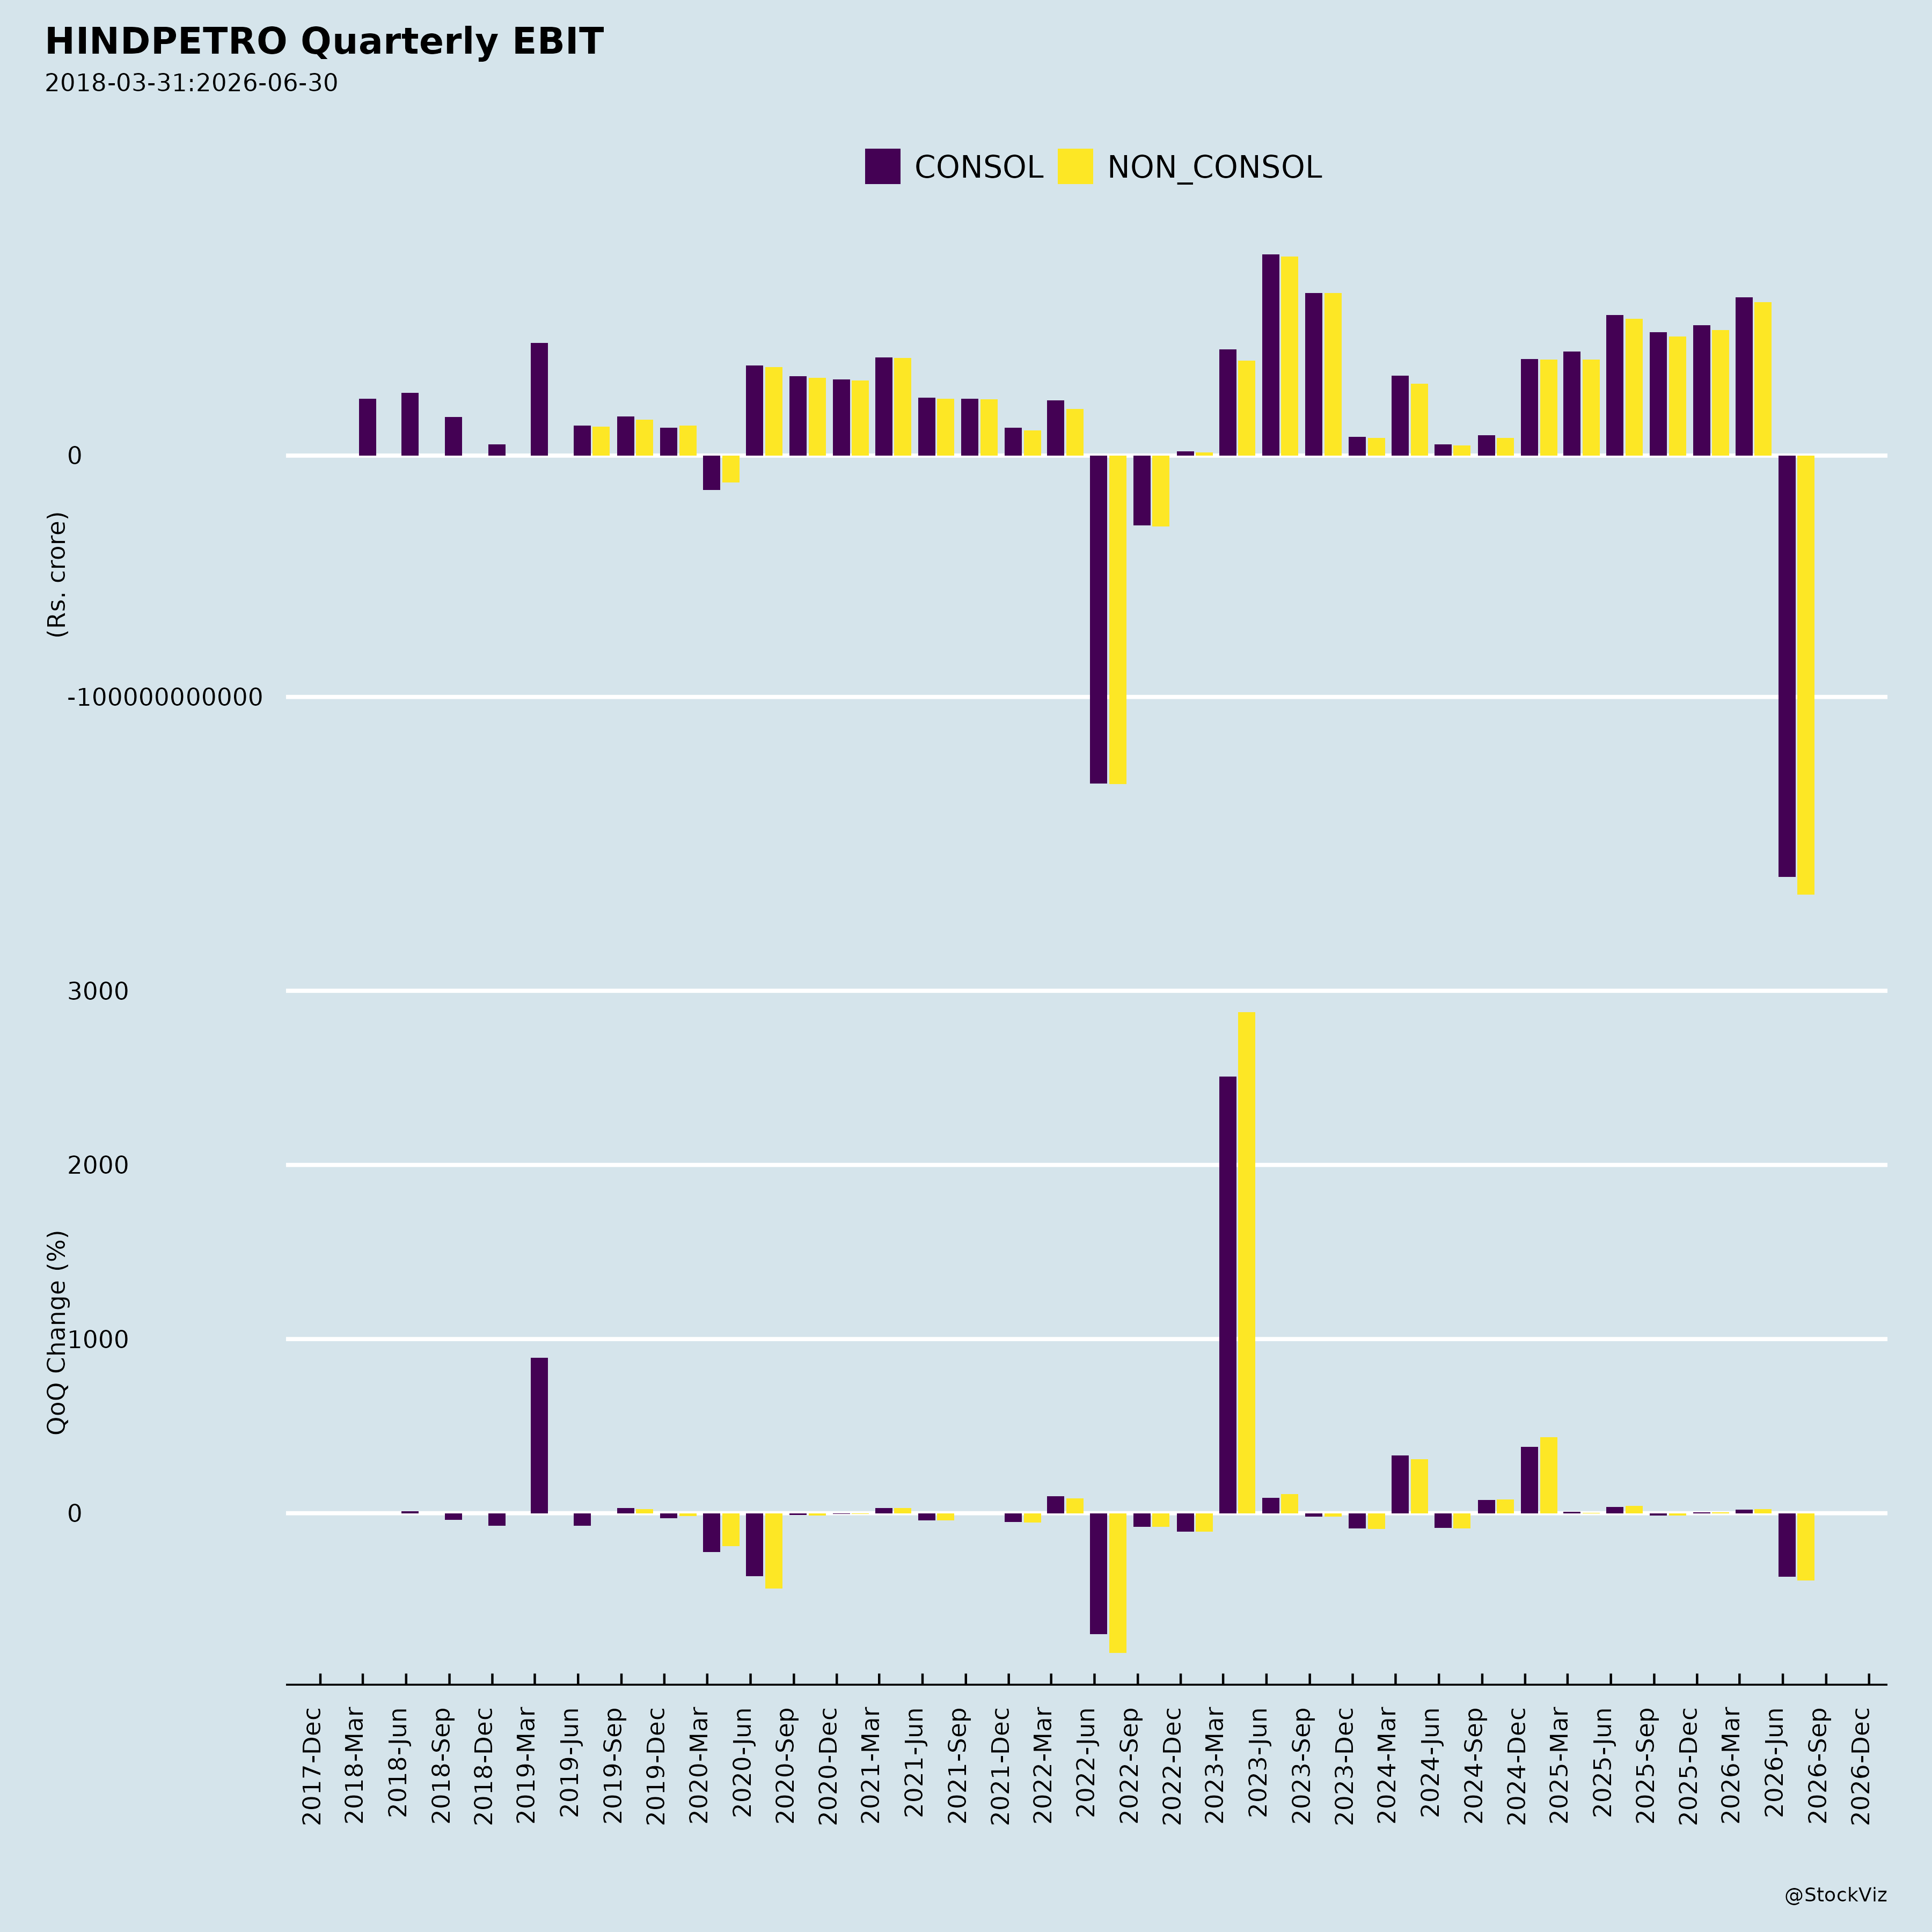
West Asia crisis impact. HPCL’s Q1 FY27 results (quarter ended June 30, 2026) explicitly reflect “the impact of the ongoing West Asia crisis.” The company reported a standalone net loss of ₹11,526 crore and a consolidated net loss of ₹12,265 crore, against a standalone PAT of ₹4,371 crore in Q1 FY26.
Suppressed marketing margins. Note 4 to the standalone results states that “due to the suppressed marketing margins on certain petroleum products, the profitability is impacted.” This is a direct drag on the marketing segment even as refining margins expanded.
LPG under-recovery buffer. Per the MoPNG letter dated April 30, 2020, when the Market Determined Price of LPG cylinders is below the Effective Cost to Consumer, OMCs retain the difference in a buffer account. In the absence of any scheme or authorisation from the Government of India towards compensation, receivable and revenue to the extent of the negative buffer has not been recognised. The cumulative unrecognised negative buffer as on June 30, 2026 was ₹16,405.92 crore, up from ₹12,798.67 crore as on March 31, 2026 and ₹13,042.56 crore as on June 30, 2025.
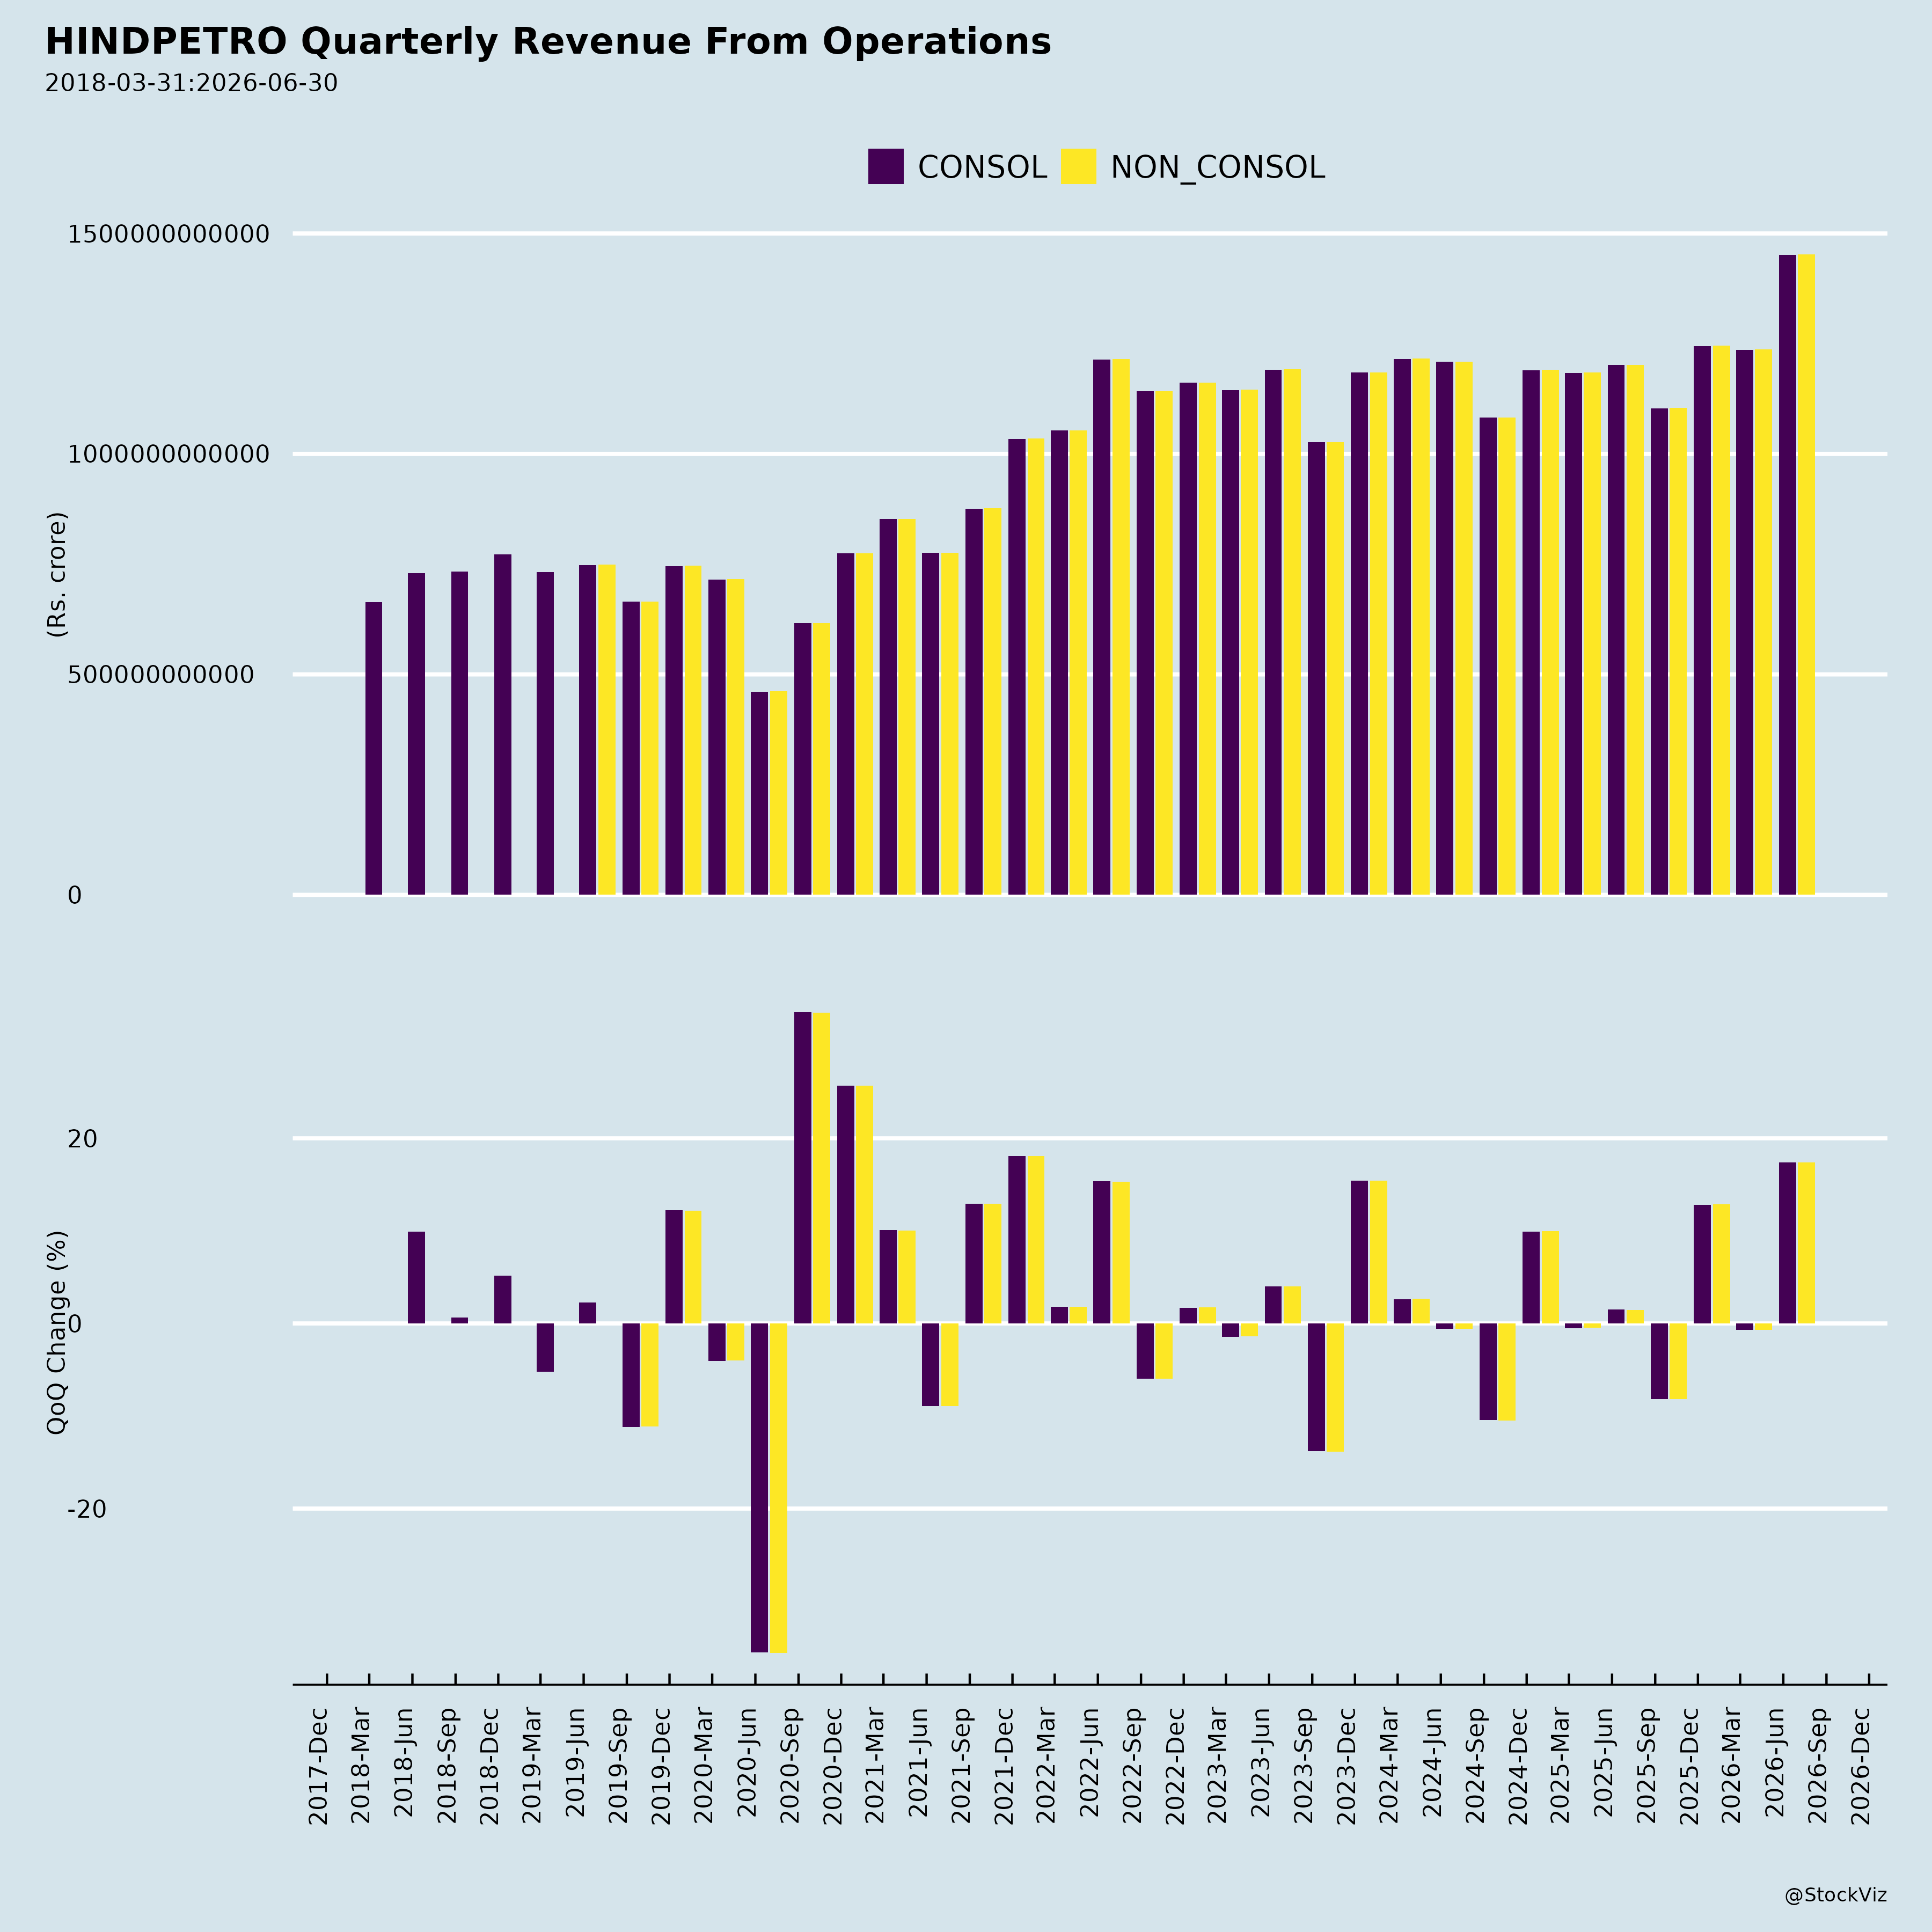
Weak domestic sales growth. While total sales including exports rose 0.6% YoY to 13.12 MMT, domestic sales growth was (0.1)%. Combined MS and HSD sales grew 8.1% YoY to 8.8 MMT.
Balance sheet strain. Standalone debt-equity ratio rose to 1.52 times as on June 30, 2026 from 0.80 times as on March 31, 2026. Outstanding debt increased to ₹72,596.95 crore from ₹47,598.66 crore. Net worth declined to ₹47,735.73 crore from ₹59,847.09 crore. The interest service coverage ratio turned negative at (17.37) times, and the debt service coverage ratio at (1.80) times. The current ratio stood at 0.56 times.
Governance observation. The auditors’ review reports note that the company did not have the required number of independent directors on its Board as stipulated under SEBI Listing Regulations 2015, for the period from April 1, 2026 to June 30, 2026 and up to the date of the report.
Audit scope limitations. The auditors did not review the Visakh Refinery branch results (total revenues ₹36,502.25 crore, net loss ₹2,635.96 crore for the quarter), relying on the Branch Auditor’s report. Certain subsidiaries, associates, joint ventures, and unincorporated joint operations were included based on unreviewed or management-certified information.
2. Tailwinds and Growth Prospects
Sharp refining margin expansion. Gross Refining Margin before export cess rose to US$23.80 per barrel in Q1 FY27 from US$3.08 per barrel in Q1 FY26.
Strong refining throughput. Refineries recorded crude throughput of 6.52 MMT, operating at 107% of capacity. Visakh Refinery ran at 106% (3.97 MMT) and Mumbai Refinery at 108% (2.55 MMT). Two new grades of crude oil were processed during the quarter.
HRRL commissioning. HPCL Rajasthan Refinery Limited declared scheduled commercial operation on June 22, 2026, and the refinery was dedicated to the Nation by the Prime Minister on July 4, 2026.
Samriddhi programme. Samriddhi 1.0, a structured EBITDA improvement programme launched in FY26, delivered accruals of approximately ₹1,691 crore. Samriddhi 2.0 has now been launched, targeting EBITDA improvement of ₹1,500 crore, of which ₹1,000 crore is targeted as accrual for FY27.
Non-fuel business expansion. HPCL signed strategic partnerships with Burger King, Travel Food Services, Devyani International, FoodMojo, Chai Fast, Araku Coffee, SARAS and Safal. With Petromin, it is creating Quick Vehicle Care Centres, envisaging 1,000 centres over three years with 100 targeted for commissioning in FY27.
Project Abhyuday 2.0. A volume growth and market leadership initiative covering 4,928 retail outlets, with outlet-level initiatives, modernisation and infrastructure upgrades.
Digital transformation. An enterprise-wide programme leveraging AI, Agentic AI, advanced analytics, digital twins, industrial IoT, cloud platforms, computer vision, robotics and drones, and intelligent process automation across refining, supply chain, marketing and corporate operations.
Network and energy transition. Retail outlets stood at 25,160, LPG distributors at 6,391, and PNG connections at 54,586 as on June 30, 2026. CNG outlets reached 2,289, solarised retail outlets 23,928 (95% of outlets powered by renewables), and EV charging stations 5,806. Solar projects at Jalgaon (10.4 MWp) and Jhansi (6.5 MWp) were commissioned during the quarter.
Infrastructure and approvals. Capex in Q1 FY27 was ₹1,734 crore. HPCL received in-principle approval from Gujarat Maritime Board for all-weather operations of the HPLNG Chhara Terminal. CGD network additions included 598 inch-km of steel and 693 inch-km of MDPE pipeline.
LPG compensation recognition. MoPNG letters dated October 3 and 24, 2025 conveyed compensation of ₹7,920 crore towards under-recoveries on domestic LPG up to March 31, 2025 and likely up to March 31, 2026, disbursable in 12 equal monthly instalments from November 2025. For April–June 2026, three instalments aggregating ₹1,980 crore were recognised under Sale of Products.
R&D and awards. HP Green R&D Centre has filed 787 patents, with 320 granted. HPCL received the SKOCH Award 2026 for HP Pay and Hyper Local Search Marketing, a FICCI award for Collaboration & Partnership for Impact, supply chain awards at the Express Logistics & Supply Chain Conclave 2026, and the 5th Edition Brand of the Year Award 2026-27.
3. Key Risks
- Continued exposure to the West Asia crisis and its effect on crude sourcing, refining economics and marketing margins.
- Suppressed marketing margins on certain petroleum products weighing on profitability.
- Growing unrecognised LPG negative buffer (₹16,405.92 crore as on June 30, 2026), dependent on future government compensation schemes.
- Elevated leverage: standalone debt-equity of 1.52 times, outstanding debt of ₹72,596.95 crore, negative interest and debt service coverage ratios, and a current ratio of 0.56 times.
- Board composition shortfall relative to SEBI Listing Regulations regarding independent directors.
- Reliance on branch auditor reports and management-certified information for certain entities and joint operations in the consolidated and standalone results.
- Supplementary audit of FY26 standalone and consolidated financial statements by the C&AG is ongoing.
- Foreign currency transaction and translation losses (₹15.21 crore standalone, ₹15.16 crore consolidated in Q1 FY27).
4. Management Guidance Versus Observed Performance
Samriddhi programme. Management states Samriddhi 1.0 delivered accruals of approximately ₹1,691 crore in FY26. Samriddhi 2.0 targets EBITDA improvement of ₹1,500 crore, with ₹1,000 crore targeted as accrual for FY27. Observed Q1 FY27 performance shows a net loss, so the FY27 accrual target remains ahead.
Vehicle Care Centres. Management envisages 1,000 centres over three years with 100 targeted for commissioning in FY27. No commissioning figures for Q1 FY27 are disclosed.
Project Abhyuday 2.0. Targeted at volume growth and market leadership at 4,928 retail outlets. Observed Q1 FY27 domestic sales growth was (0.1)%, while combined MS and HSD sales grew 8.1% YoY.
Refining performance versus capacity. Refineries operated at 107% of capacity in Q1 FY27, with Visakh at 106% and Mumbai at 108%, indicating throughput above nameplate capacity.
HRRL timeline. Scheduled commercial operation was declared on June 22, 2026, and the refinery was dedicated to the Nation on July 4, 2026, consistent with the commissioning milestone.
LPG compensation. The MoPNG-conveyed compensation of ₹7,920 crore is being recognised in 12 equal monthly instalments from November 2025; three instalments aggregating ₹1,980 crore were recognised in April–June 2026, matching the stated disbursement schedule.
Investor communication. A conference call was scheduled for July 23, 2026 at 10:00 a.m. IST, with the investor presentation made available on the company’s website. The HPCL Senior Management Team is scheduled to participate in the J.P. Morgan India Conference on September 22, 2026, from 2:00 PM onwards, with no unpublished price sensitive information proposed to be discussed.
AGM outcomes. The 74th AGM was held on August 26, 2026, via video conferencing/other audio-visual means. All 8 resolutions were passed with the requisite majority, including adoption of financial statements, declaration of a final dividend of ₹19.25 per equity share for FY2025-26, appointments of directors, payment of cost auditor remuneration, and approval of material related party transactions with HPCL-Mittal Energy Limited.
ESG rating. ESG Risk Assessments & Insights Limited assigned an ESG rating to HPCL; the company states it did not engage that agency for the rating, which was independently prepared.
Broker Narrative
The broker narrative evolved from cautious optimism in May 2023—anchored on a strong Q4FY23 EBITDA/PAT beat, robust refinery utilization at 111%, and recovering retail margins—toward pronounced bearishness by July 2026, dominated by massive marketing under-recoveries exceeding INR26,000 crore, a standalone EBITDA loss of INR161.4bn, and declining LPG volumes. Leverage concerns and a challenging operating environment persisted throughout, while the earlier tailwinds of healthy retail margins and strong GRM gave way to availability-driven crude sourcing and severe margin under-recovery.
Fears that came true
- Gross debt of Rs 645bn and net-debt/equity exceeding ~2x worsened as the company reported a standalone EBITDA loss of INR161.4bn in Q1FY27 amid elevated crude costs and high interest rates.
- Marketing margins being weaker than estimated and unsustainable materialized as an implied GMM under-recovery of INR14.9/ltr and total Q1FY27 marketing under-recoveries exceeding INR26,000 crore, correlating with DISAPPOINTMENT outcomes across 2024-2026 calls.
- The FY23 after-tax loss of Rs 89.7bn proved to be the start of sustained losses rather than a one-off, continuing through Q1FY27 and aligning with the stock’s negative returns from 2025 onward.
- The challenging operating environment flagged for FY24 persisted through 2026, with LPG sales volumes declining 22% YoY and crude sourcing remaining availability-driven rather than optimization-focused, coinciding with multiple DISAPPOINTMENT and NEUTRAL calls.
Optimism that failed
- Healthy retail diesel and petrol margins exceeding Rs 11/ltr following global price moderation failed to persist, as later periods saw GMM under-recovery of INR14.9/ltr and a standalone EBITDA loss of INR161.4bn.
- Strong refinery utilization (111% in Q4FY23, 107% for FY23) as a growth driver was undermined as crude sourcing became availability-driven rather than optimization-focused, with limited access to preferred grades and processing of non-regular crudes.
- The Q4FY23 EBITDA/PAT recovery beat (+130% YoY EBITDA, +80% YoY PAT) did not anchor a sustained turnaround, with the stock generating DISAPPOINTMENT outcomes across numerous calls from 2024 through 2026 despite continued calls for recovery.
- Vizag RUF and HRRL refinery improvements expected to boost GRM and reduce third-party procurement remained unrealized as of the last report, with benefits still deferred to future quarters while losses continued.
Broker Timeline
36 broker calls · 2023-05-15 to 2026-07-24
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.