HINDALCO
Equity Metrics
November 18, 2026
Hindalco Industries Limited
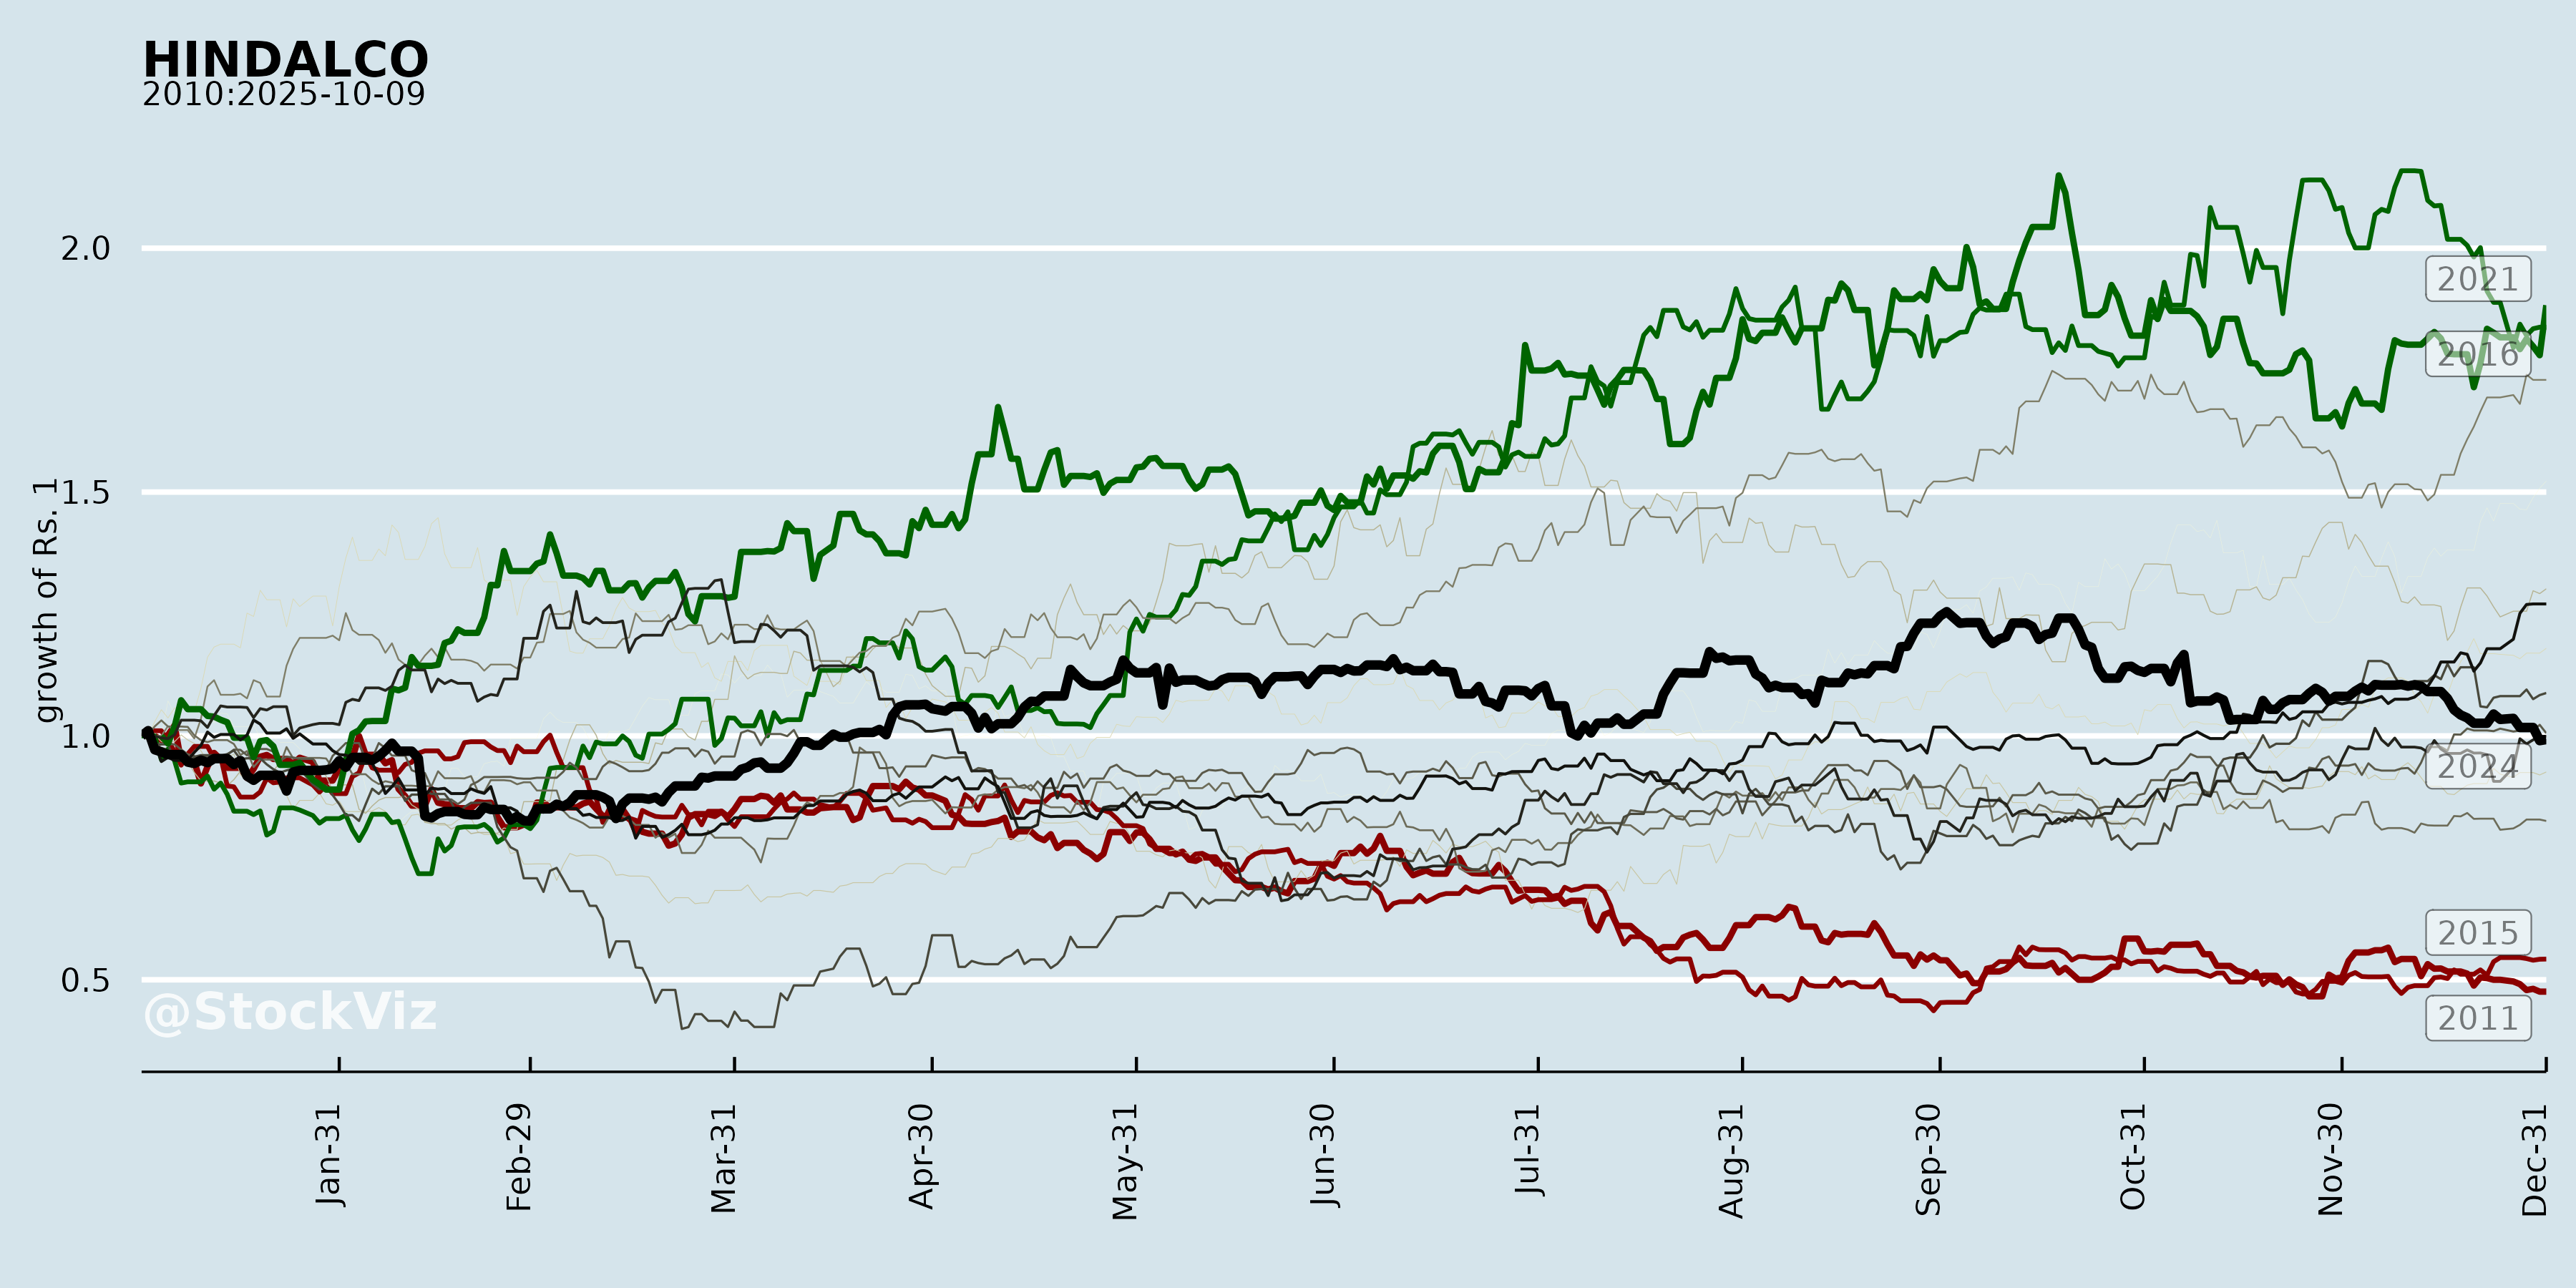
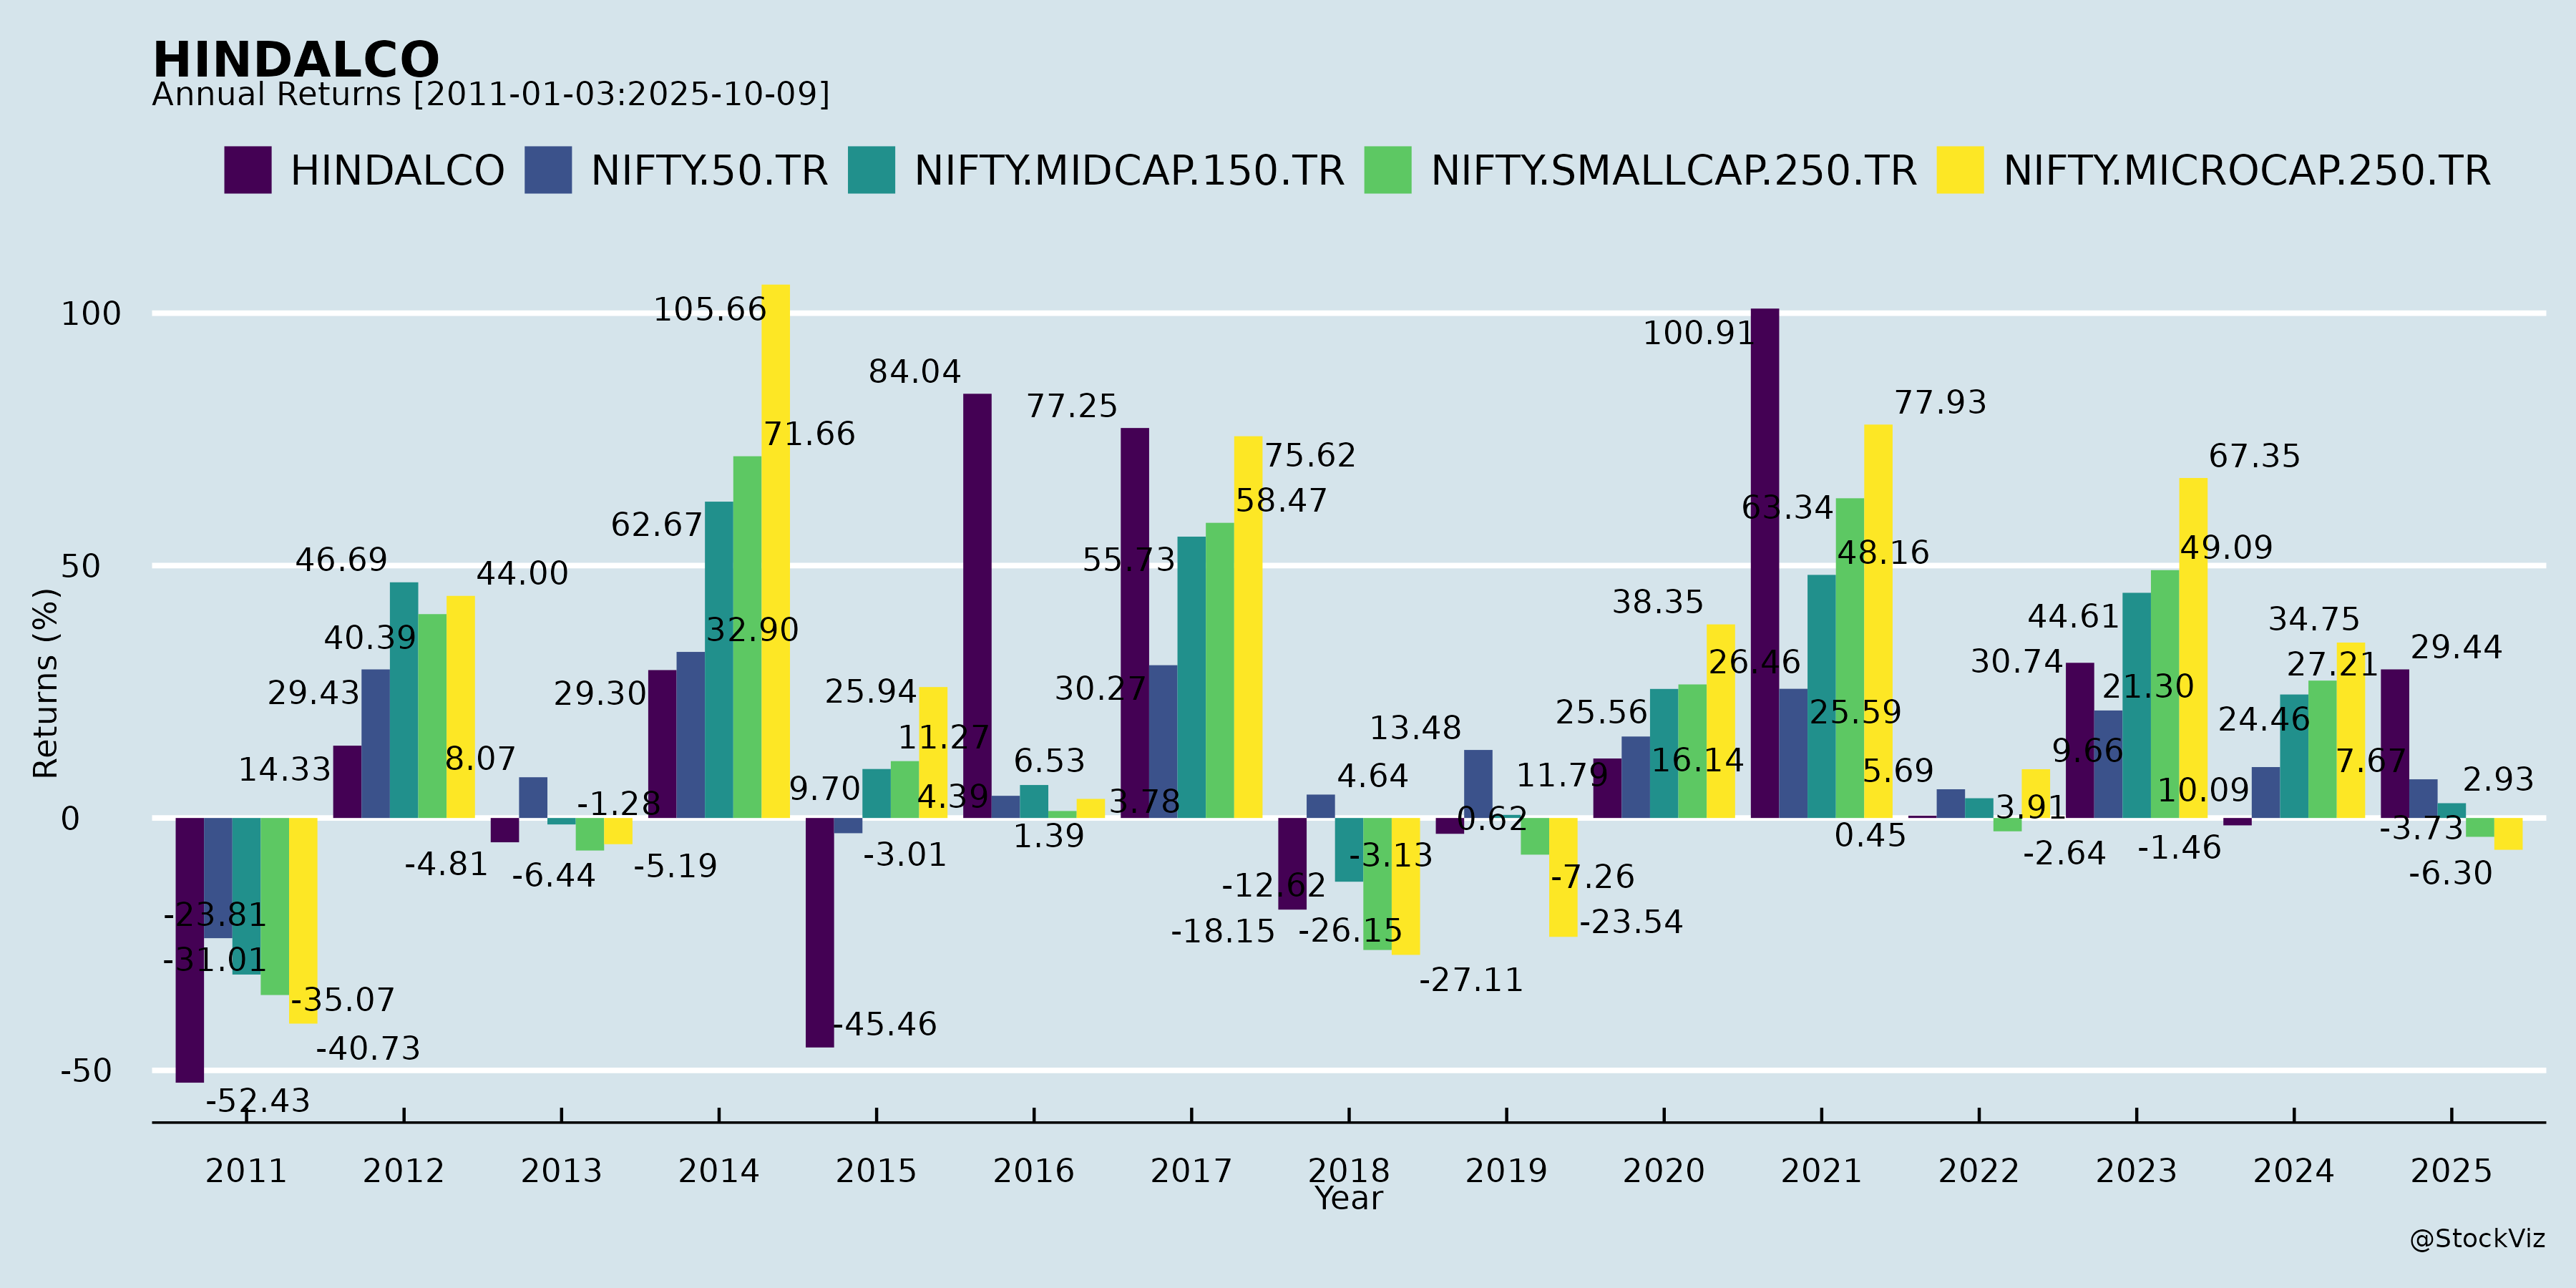
Annual Returns
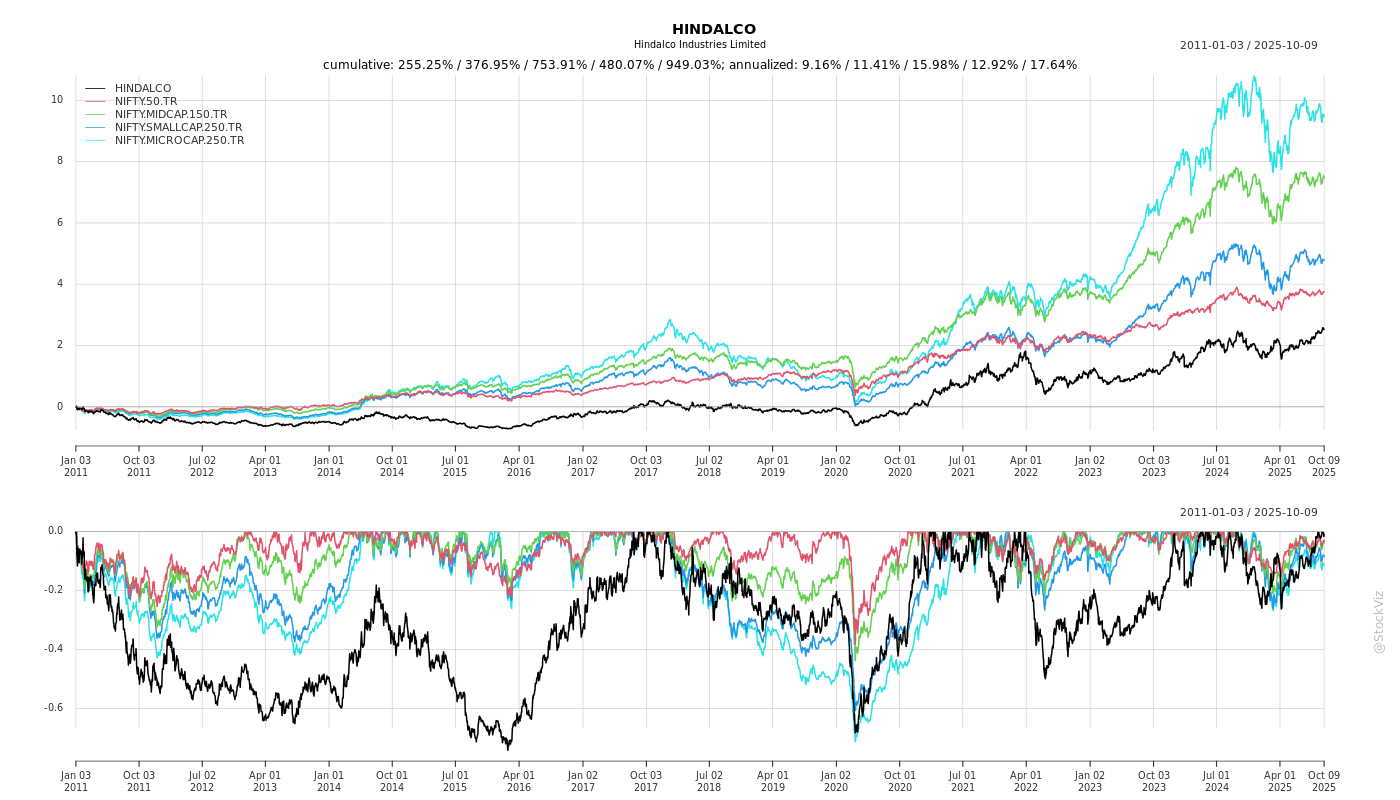
Cumulative Returns and Drawdowns
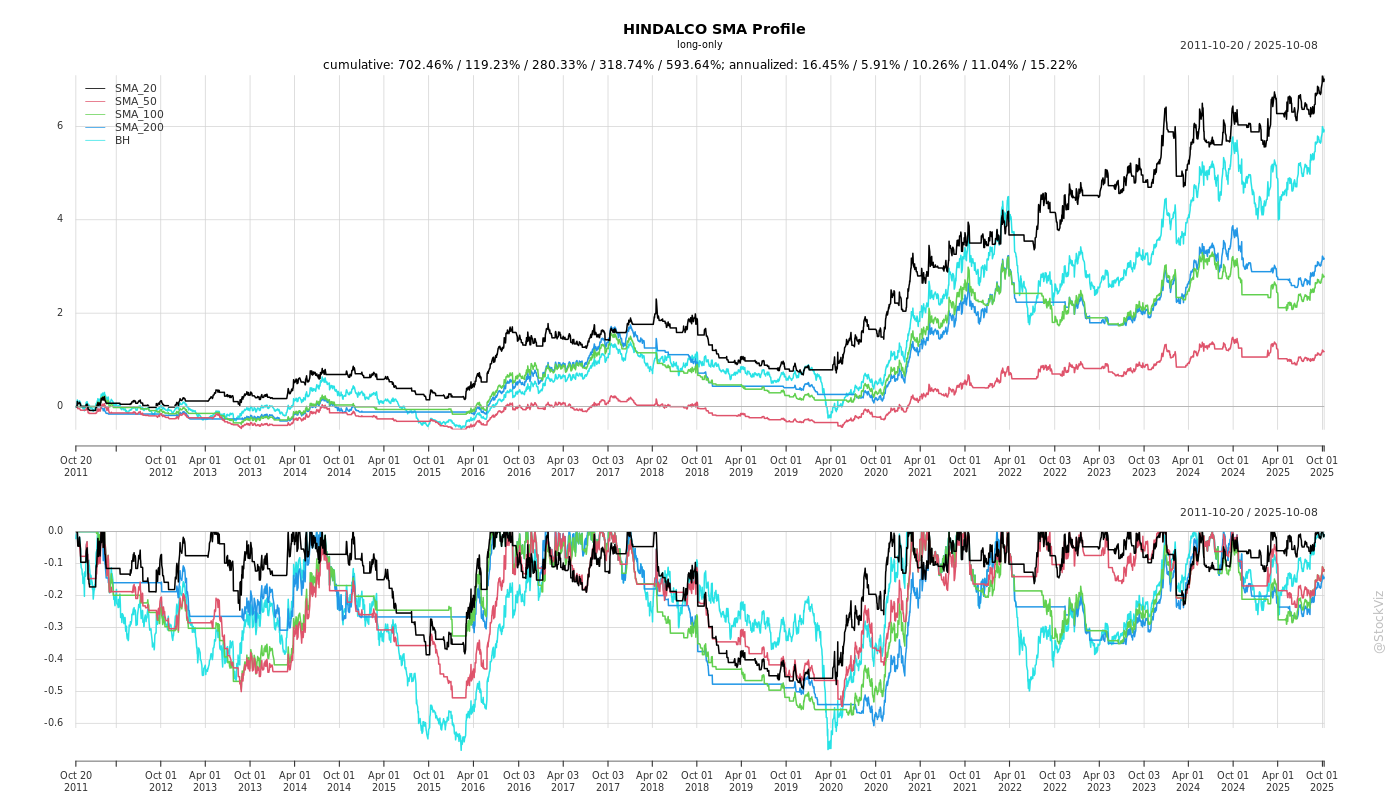
Fundamentals
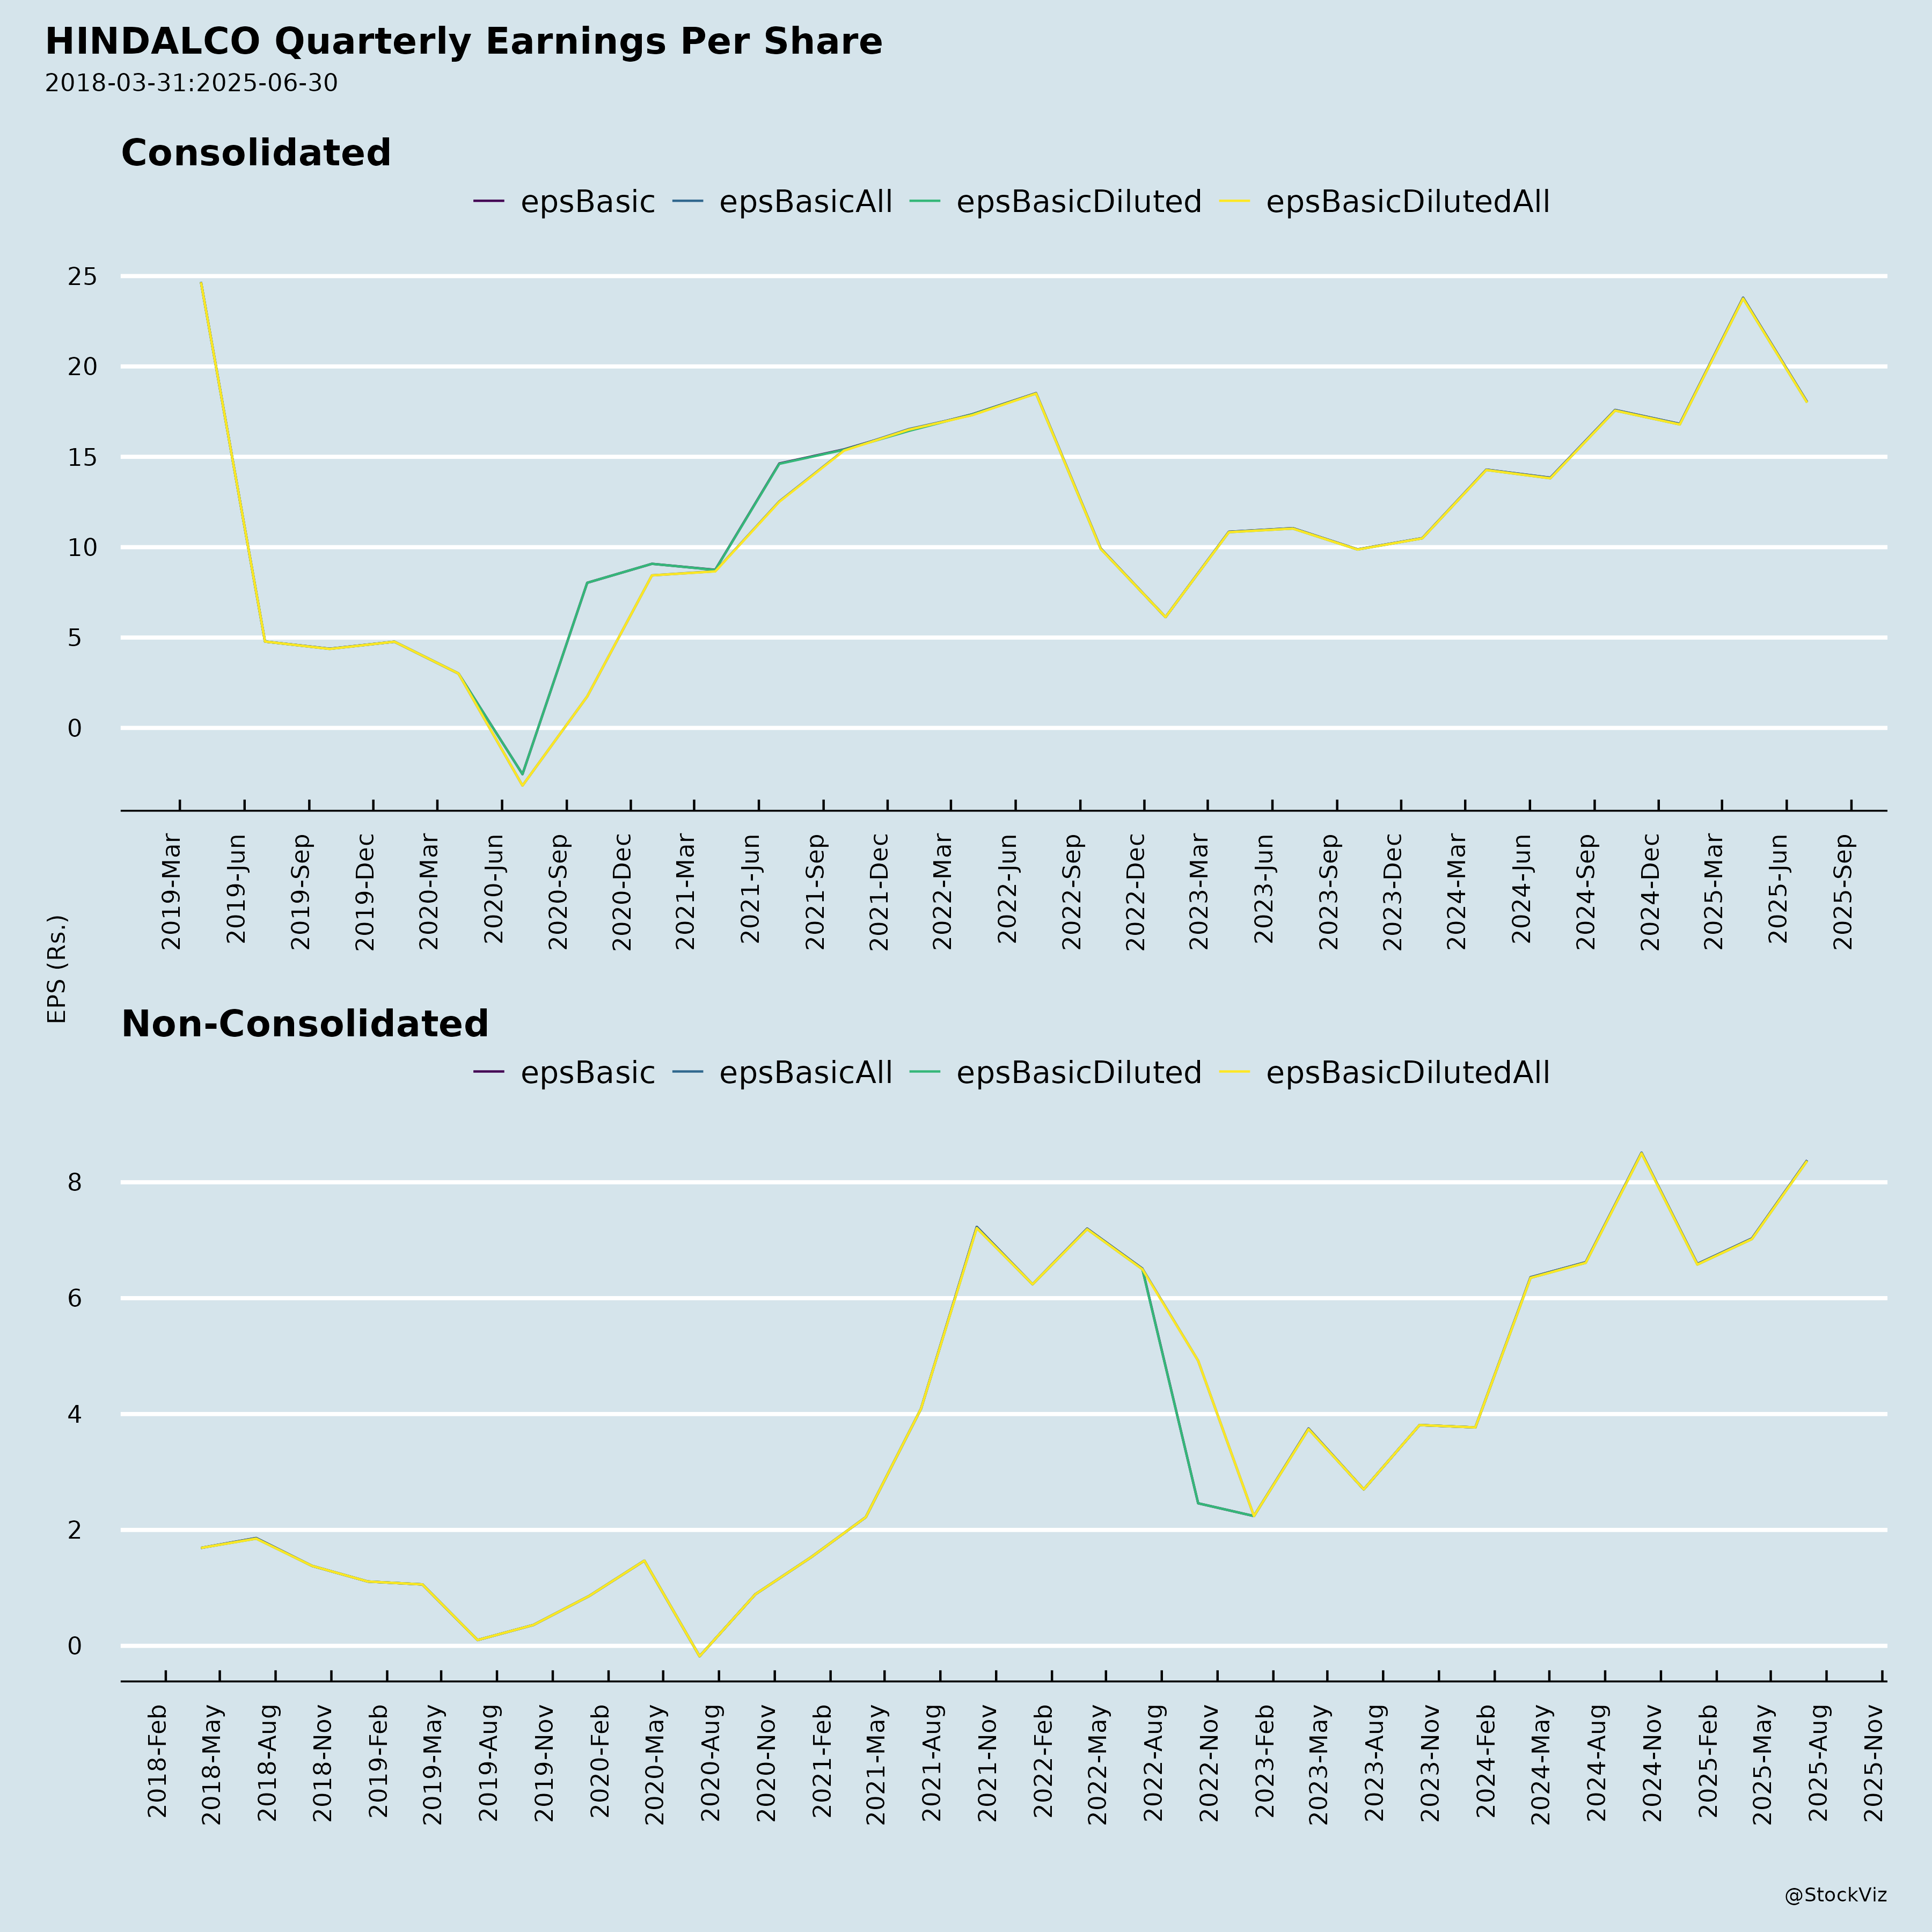
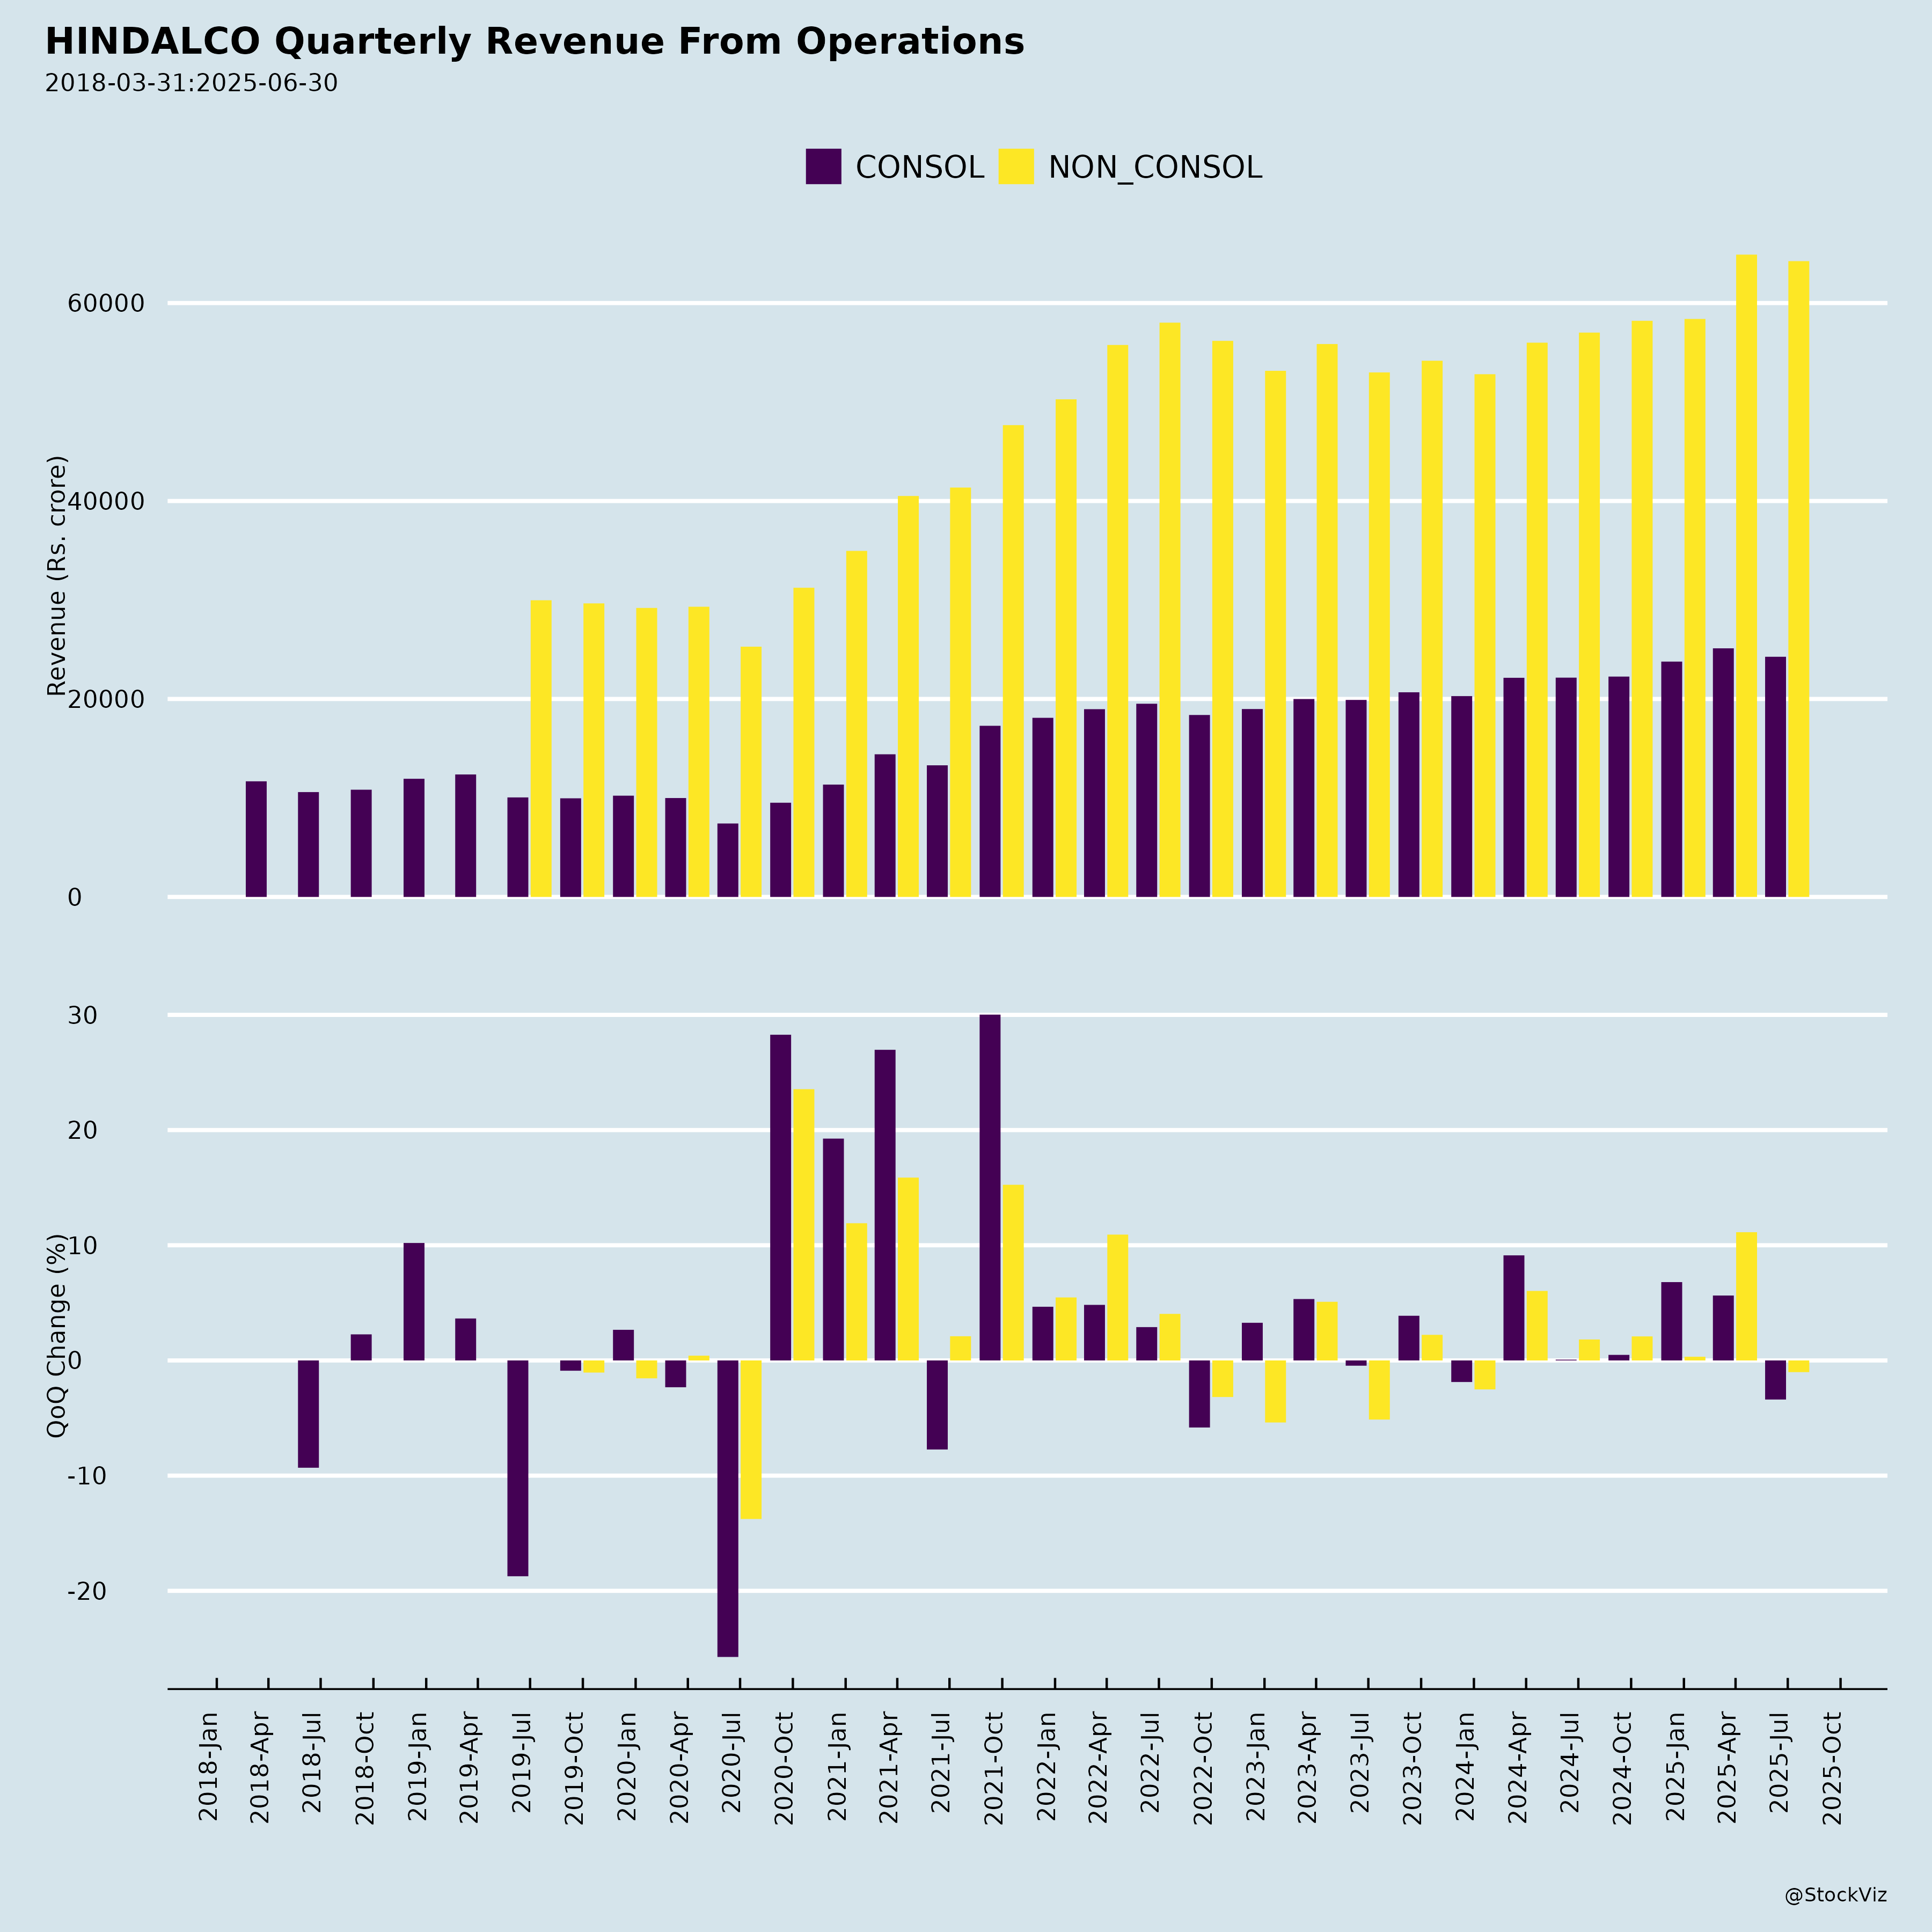
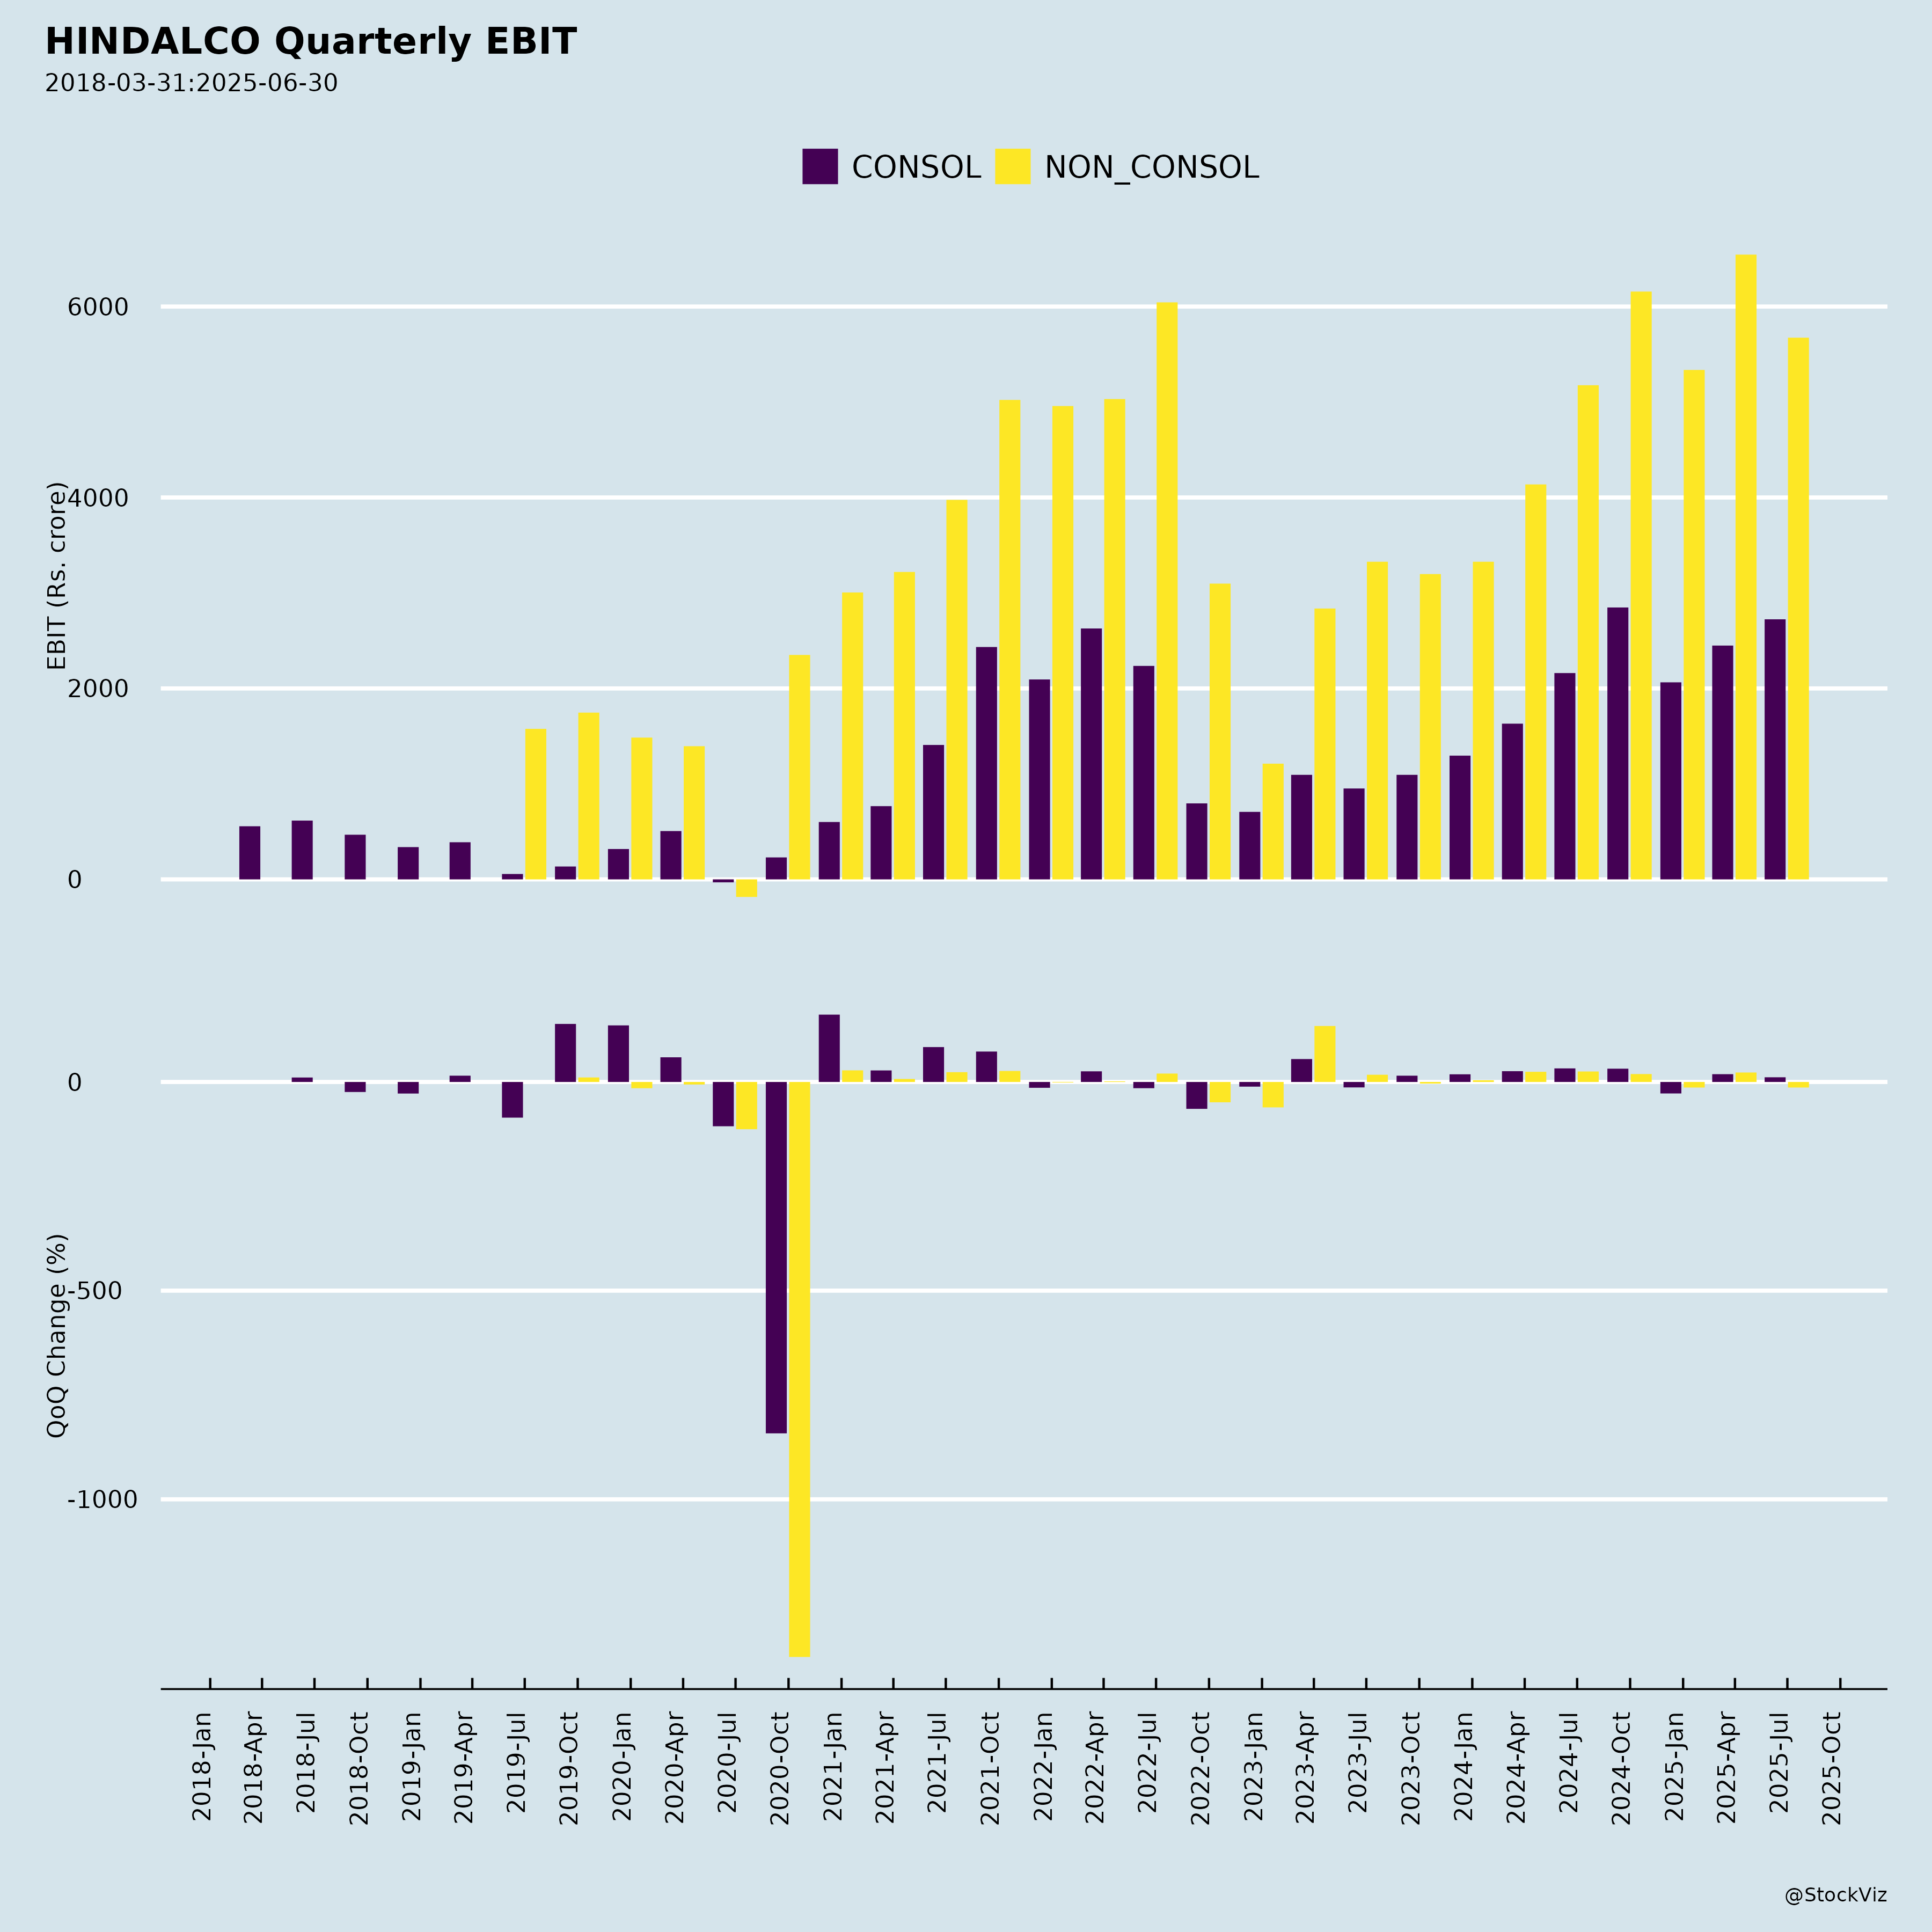
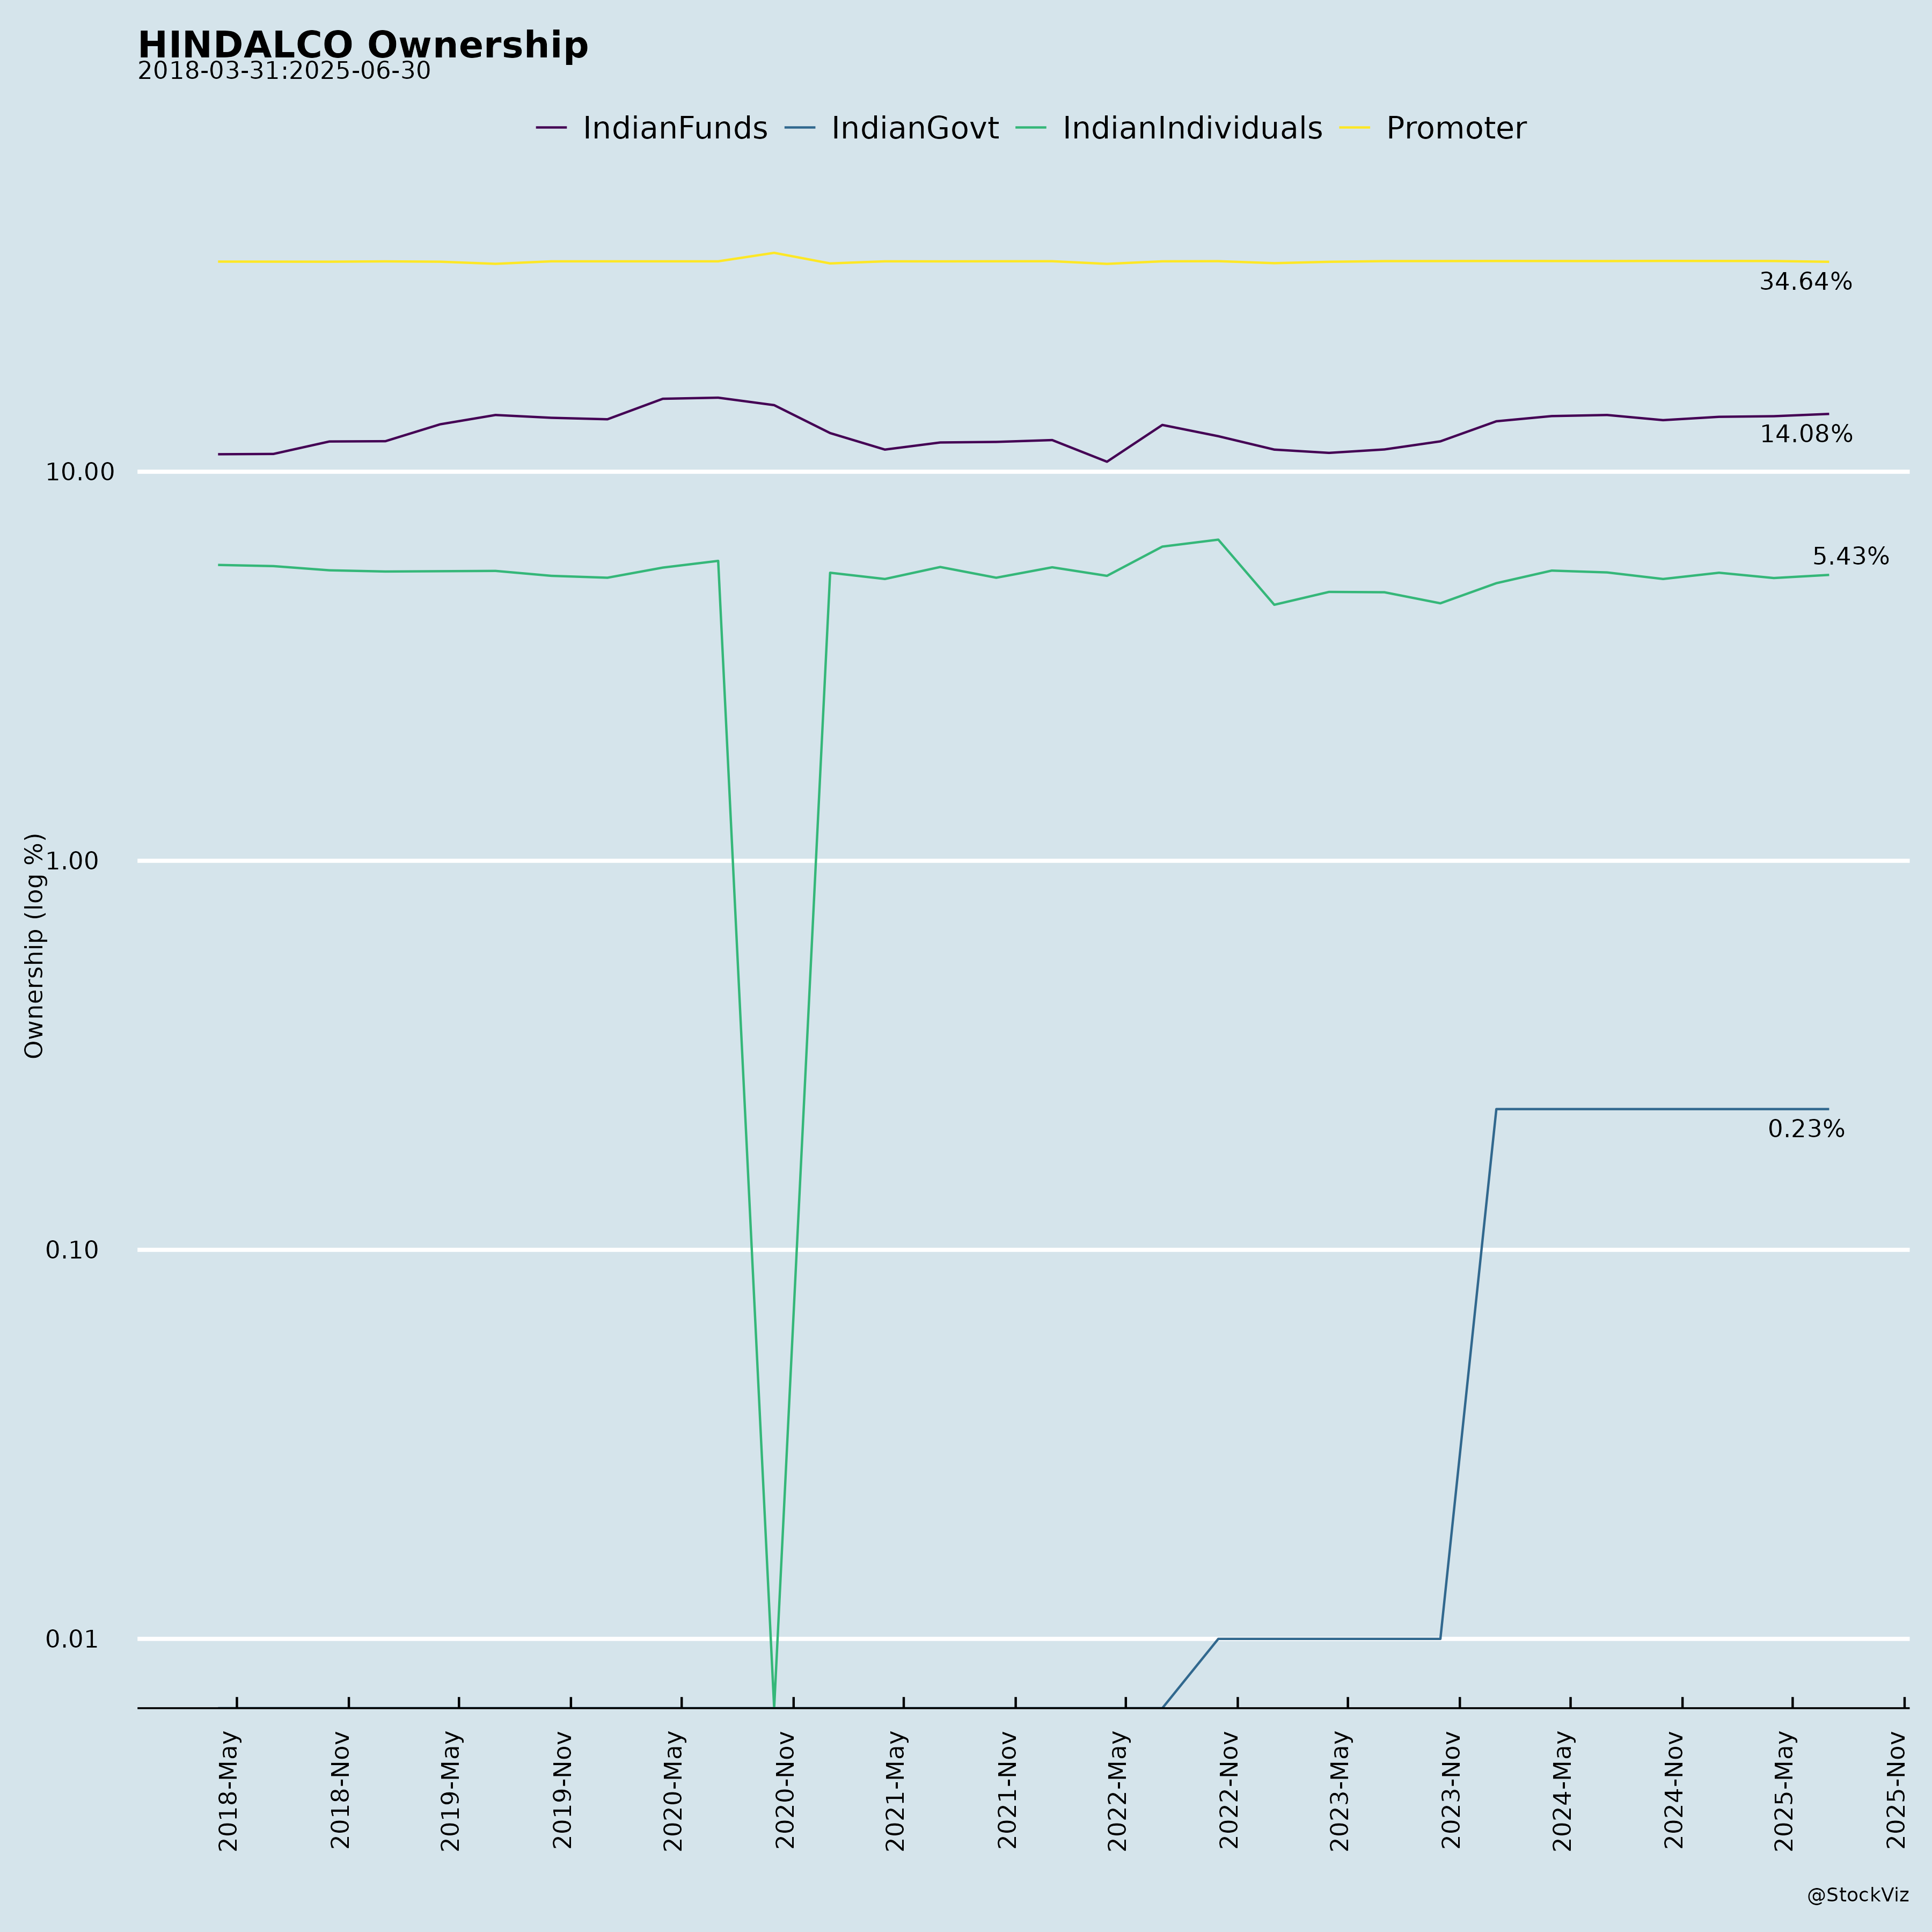
Ownership
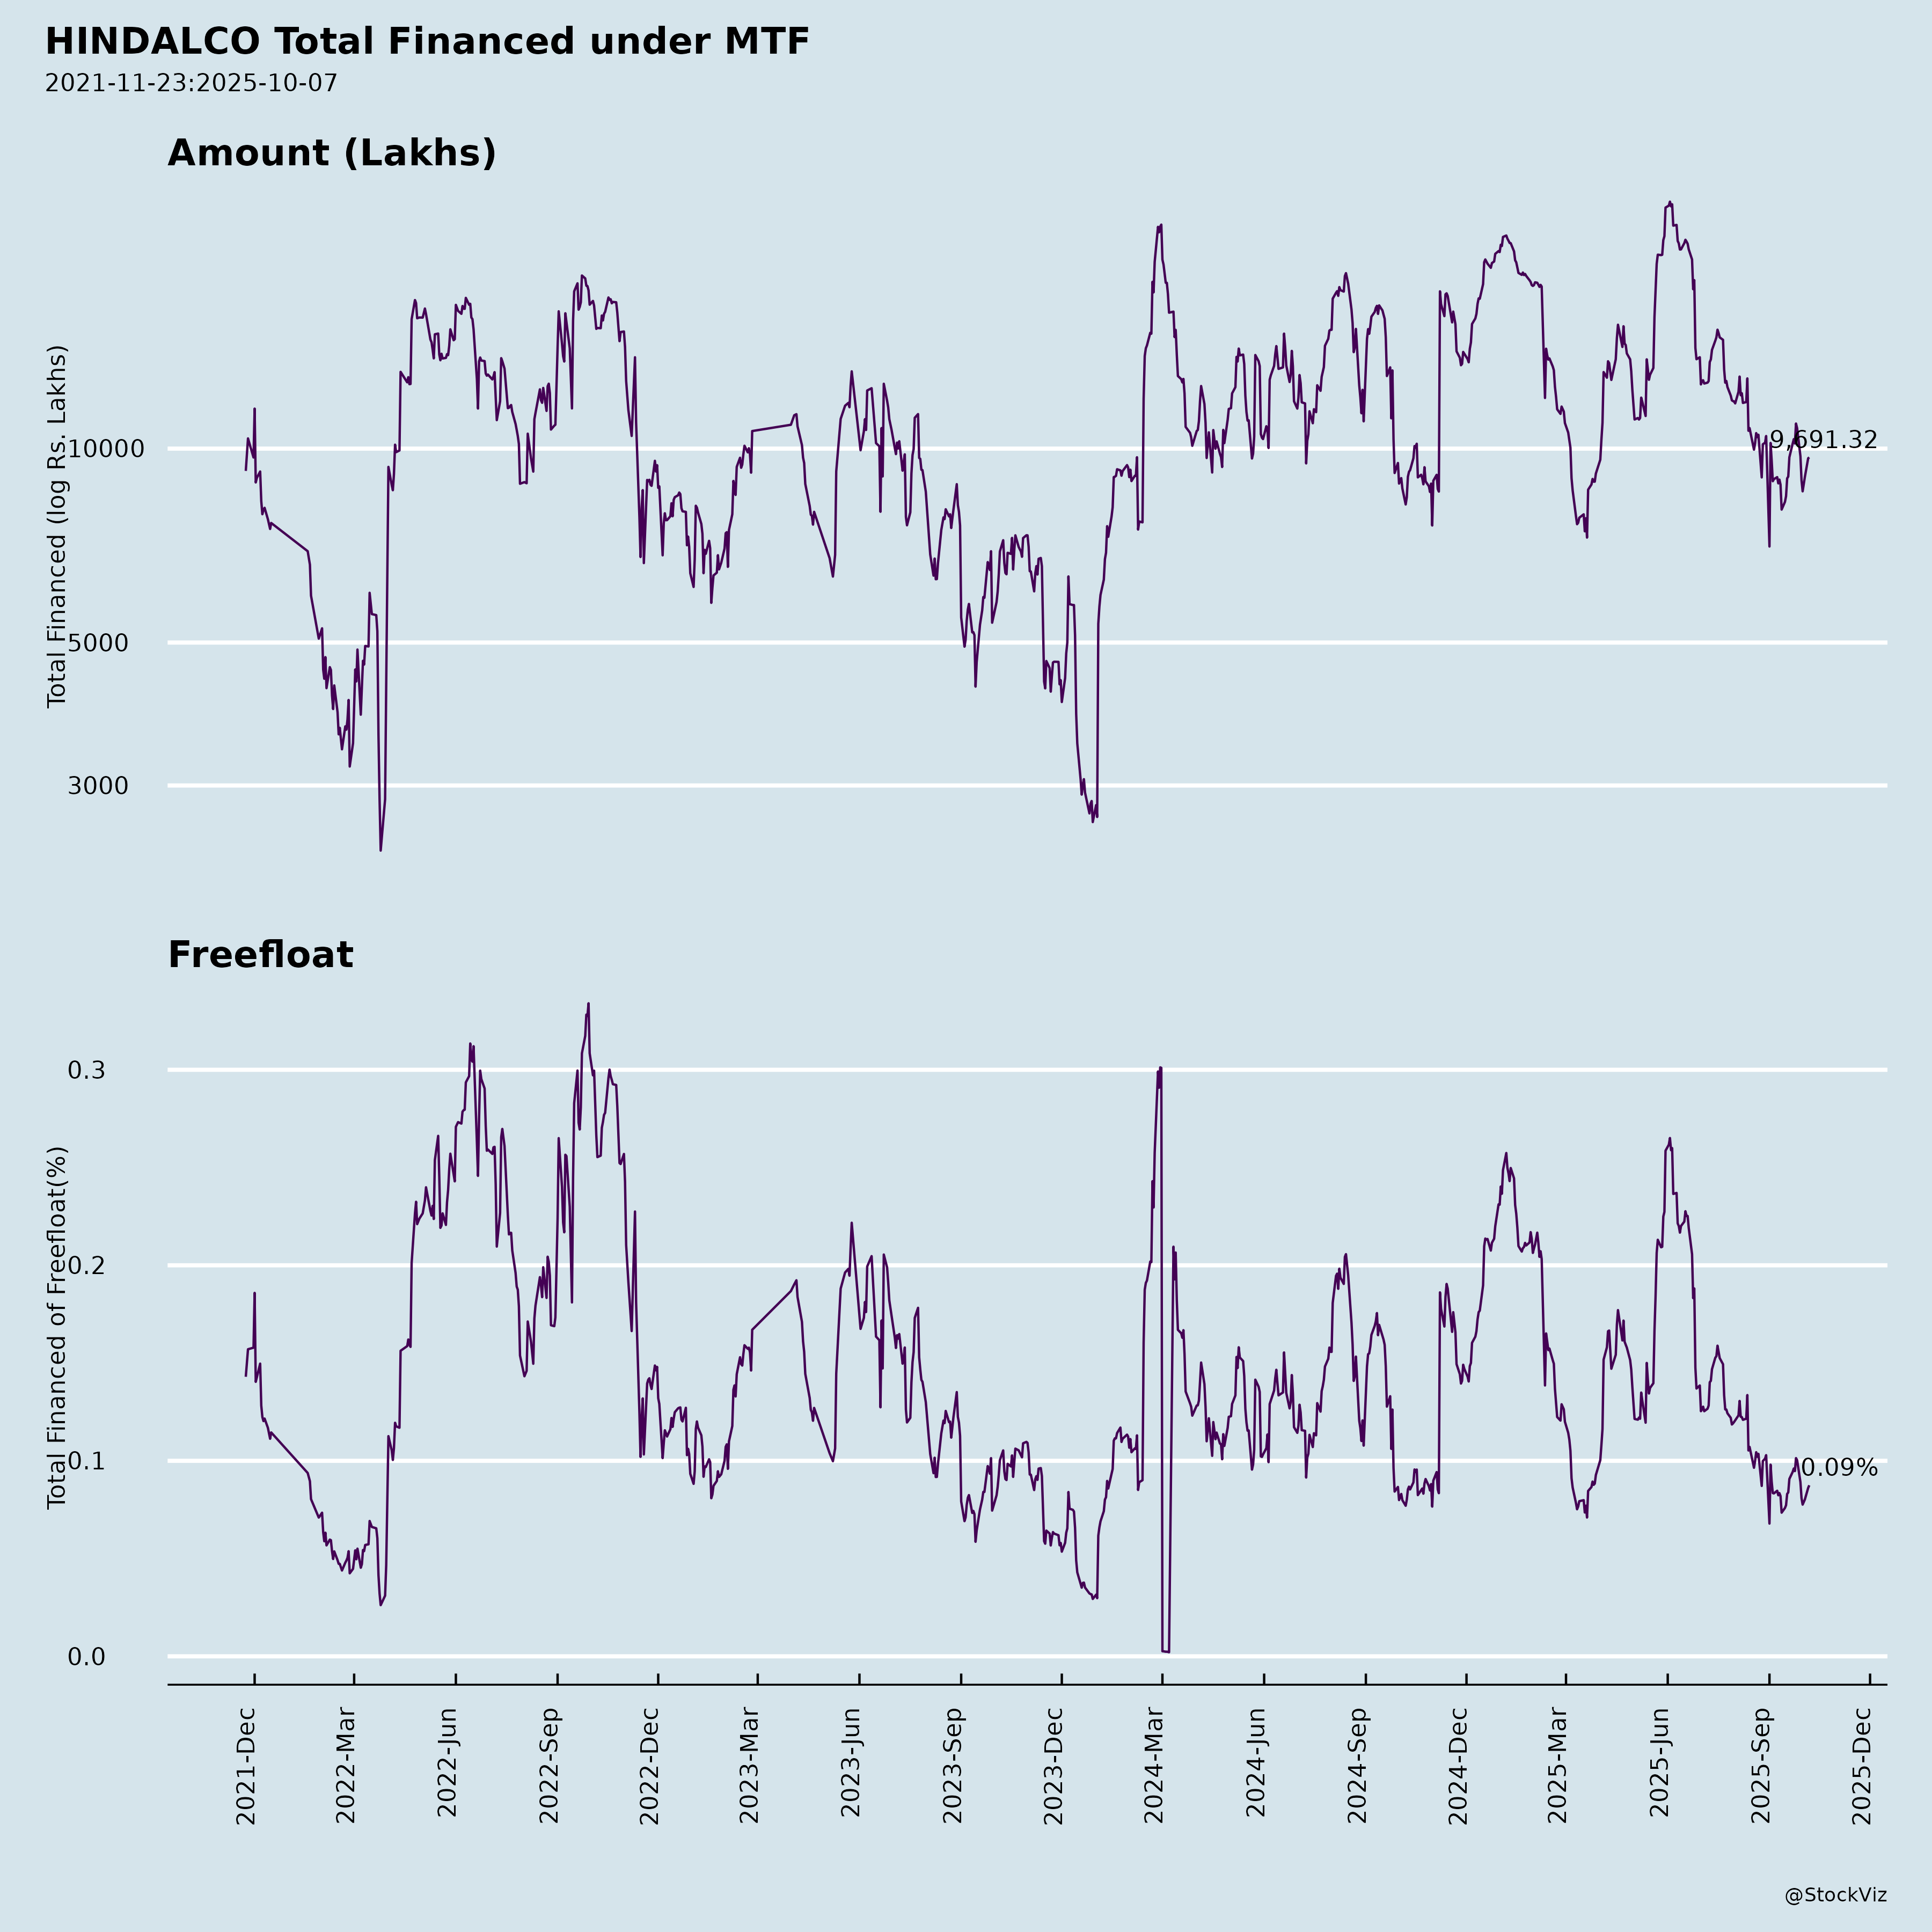
Margined
AI Summary
asof: 2026-09-14
Hindalco Q1 FY27: Headwinds, Tailwinds, Risks and Guidance vs Performance
1. Headwinds and Challenges
Macro and demand environment - Global GDP growth is projected to slow from 3.5% in 2025 to 3% in 2026 before recovering to 3.4% in 2027, amid heightened geopolitical risks. - Global inflation is projected to rise slightly from 4.1% in 2025 to 4.7% in 2026, driven by higher energy and food prices and supply-side pressures. - India’s FY27 GDP growth is projected by the RBI at 6.7%, down from 7.7% in FY26, reflecting geopolitical uncertainties, external headwinds and weather-related disruptions. Inflation is expected to rise from 2% in FY26 to 5% in FY27. - The Monetary Policy Committee retained a neutral stance, awaiting greater clarity.
Aluminium market - The Q2 CY26 environment was described as the largest-ever supply shock driving up LME. Global production fell 1% (Q2 CY26 vs Q2 CY25), with China’s Yunnan increase offset by Shandong closures, and drops in the Middle East and Africa partly offset by Indonesia and Europe. - Global consumption rose only 1% (Q2 CY26 vs Q2 CY25), with China softness in B&C and Solar offset by NEV growth, and Rest of World recovery in Packaging and Electrical offset by Transport weakness. - Medium term, higher prices support ramp-up of Indonesia, GCC, Angola and Vietnam capacities.
Copper market - In Q1 FY27, elevated LME prices led to cautious buying behaviour, and the ongoing West Asia conflict impacted overall supplies, especially imports of refined copper.
Operational and business-level challenges - Consolidated Net Debt to EBITDA rose to 1.95x as of June 30, 2026, versus 1.02x a year ago; gross debt increased to ₹103,515 crore and net debt to ₹77,495 crore. - Novelis shipments declined 5% YoY to 916 Kt in Q1 FY27 from 963 Kt. - Copper metal sales fell 16% YoY to 105 Kt and CCR sales fell 8% YoY to 96 Kt, with overall copper shipments down 18% QoQ on account of a planned major maintenance shutdown. - Alumina production (incl. Utkal) declined 2% YoY to 931 KT. - Copper Rods production fell 9% YoY. - Ash recycling offtake temporarily slowed due to rake unavailability, despite high demand from cement industries, offsite low-lying area filling and quarry backfilling. - The company reported an exceptional expense of ₹(2,299) crore in Q1 FY27, versus nil in Q1 FY26 and ₹(4,171) crore in Q4 FY26.
2. Tailwinds and Growth Prospects
Record consolidated performance - Record quarterly consolidated revenue at ₹84,825 crore, up 32% YoY. - All-time high consolidated EBITDA at ₹14,989 crore, up 73% YoY. - All-time high consolidated PAT at ₹7,013 crore, up 75% YoY. - Profit before exceptional items and tax at ₹11,692 crore, up 106% YoY.
Segment records - Record Aluminium Upstream quarterly EBITDA at ₹7,390 crore, up 81%, with EBITDA per tonne at an all-time high of $2,331, up 59%, and margins at 55% versus 44% in Q1 FY26. - Record Copper quarterly EBITDA at ₹918 crore, up 36%, despite a planned major smelter maintenance, backed by higher by-product realisations including sulphuric acid. - Record Novelis quarterly Adjusted EBITDA at $516 million, up 24% in USD terms (37% in INR terms), supported by structural cost reduction. - Record Aluminium Downstream quarterly EBITDA at ₹298 crore, up 30%, with EBITDA per tonne at $303, up 15%, led by product mix and premiumisation.
Novelis recovery and growth - Oswego hot mill restarted in early June and production is ramping up. - Bay Minette (600 Kt) commissioning process is underway; shipments expected to commence in Q1 FY28. - Over $225 million in run-rate cost savings achieved through Q1 FY27; target of $350–400 million in total savings by FY28 exit. - Long-term $600+/ton EBITDA guidance stated as intact. - Novelis entered into a $500 million short-term unsecured term loan facility (announced July 27, 2026).
India business growth pipeline - Aditya Smelter Phase 2 on track to begin metal production in FY28. - Aditya Alumina Refinery targeted for FY28; Aditya Aluminium Smelter Ph 1 (181 Kt) FY28 and Ph 2 (193 Kt) FY29; Copper Smelter FY29. - Captive coal mines: Chakla targeted H1 FY27 (FC 1 approval received, box cut done), Bandha FY27, Meenakshi FY29. - Downstream: Aditya FRP scaling up to optimal production; Battery Foil plant at Aditya and Coated AC Fins plant at Taloja commissioned; Copper Tubes and Inner Grooved Tubes plant fully operational and scaling up; Copper and e-waste recycling project to commission in FY27. - India Business targets: double down 4x by FY30 across Upstream Aluminium, Copper, Downstream Aluminium, Copper and Specialty Alumina.
Sustainability and cost positioning - 65 MW round-the-clock renewable energy project operationalised at Aditya Aluminium, described as the first of its kind in India in the C&I space; renewable capacity moving from 470 MW (Q1 FY27 exit) to 884 MW (FY27 exit). - Total waste utilisation at 80% in Q1 FY27; water recycling at 29% versus 27% a year ago. - Recognised as the World’s Most Sustainable Aluminium Company in the S&P Global CSA for the sixth consecutive year (2020–2025). - Zero fatalities during the quarter; LTIFR at 0.18 in Q1 FY27.
Tax tailwind - Transition to the new tax regime effective April 1, 2026 reduced the effective tax rate to 26% in Q1 FY27 versus 30% in Q1 FY26 and 34% in Q4 FY26, aiding PAT growth.
3. Key Risks
- Global and Indian demand-supply conditions, finished goods prices, and feedstock availability and prices.
- Cyclical demand and pricing in the company’s principal markets.
- Changes in government regulations and tax regimes.
- Economic developments within India and the countries in which the company conducts business.
- Litigation and labour negotiations.
- Geopolitical risks, including the West Asia conflict affecting copper supplies and imports.
- Weather-related disruptions affecting India’s growth and inflation outlook.
- Leverage risk: Net Debt to EBITDA at 1.95x consolidated as of June 30, 2026, up from 1.02x a year earlier, with gross debt at ₹103,515 crore.
- Execution risk on the project pipeline, including Bay Minette commissioning, Aditya smelter phases, alumina refinery and copper smelter, and downstream projects.
- Currency movements: Novelis EBITDA growth in INR terms (37%) exceeded USD terms (24%) due to favourable INR/USD movements, indicating sensitivity to exchange rates.
- Ash offtake logistics constraints (rake unavailability) affecting waste recycling rates.
4. Management Guidance Versus Observed Business Performance
Guidance and forward statements - Novelis long-term $600+/ton EBITDA guidance stated as intact. - Novelis cost savings: over $225 million run-rate achieved through Q1 FY27; target of $350–400 million total savings by FY28 exit. - Bay Minette: commissioning underway; shipments expected to commence in Q1 FY28. - Aditya Smelter Phase 2 on track to begin metal production in FY28. - Aditya Alumina Refinery FY28; Aditya Aluminium Smelter Ph 1 FY28, Ph 2 FY29; Copper Smelter FY29. - Captive coal mines: Chakla H1 FY27, Bandha FY27, Meenakshi FY29. - Copper and e-waste recycling project to commission in FY27. - India Business: double down 4x by FY30. - Novelis 2030 goals: 75% average recycled content; emissions below 3 tonnes CO₂e per tonne of FRP shipped. - Renewable capacity: 470 MW at Q1 FY27 exit, 414 MW rest of FY27, 884 MW at FY27 exit.
Observed performance against prior guidance - Oswego hot mill: guidance was for restart; observed restart in early June with production ramping up. - Novelis cost optimisation: guidance of $350–400 million by FY28 exit; observed over $225 million run-rate savings through Q1 FY27. - Aditya FRP: guidance was scaling up to optimal production levels; observed FRP volumes up 4% YoY as Aditya FRP ramps to optimal levels. - Battery foil plant at Aditya and Coated AC Fins plant at Taloja: observed commissioned. - Copper Tubes and Inner Grooved Tubes plant: observed fully operational and scaling up. - Aditya Smelter Phase 2: guidance of metal production in FY28; observed on track. - Captive coal mines: Chakla FC 1 approval received and box cut done; Bandha on track; Meenakshi on track. - Renewable energy: 65 MW RTC project operationalised at Aditya Aluminium; capacity trajectory stated from 470 MW to 884 MW. - Novelis Adjusted EBITDA: guidance context of long-term $600+/ton; observed Q1 FY27 Adjusted EBITDA per tonne at $563, up 30% YoY. - Aluminium Upstream EBITDA per tonne: observed at $2,331, up 59% YoY, with margins at 55%. - Copper EBITDA per tonne: observed at $926, up 46% YoY. - Aluminium Downstream EBITDA per tonne: observed at $303, up 15% YoY.
AGM outcomes (July 23, 2026) - All six resolutions passed with requisite majority, including adoption of audited standalone and consolidated financial statements for FY26, declaration of dividend for FY26, re-appointment of Mr. Kumar Mangalam Birla and Ms. Ananyashree Birla as directors retiring by rotation, and ratification of cost auditors’ remuneration for FY27. - Resolution 4 (Mr. Kumar Mangalam Birla) received 79.52% votes in favour and 20.48% against; Resolution 5 (Ms. Ananyashree Birla) received 76.11% in favour and 23.89% against, with public institutions voting 58.61% in favour and 41.39% against on Resolution 5.
Broker Narrative
The first Buy framed beverage-can destocking, construction/specialty softness, energy/input cost inflation, weaker metal-recycling benefits and Brazil tax/macro shipment pressure as short-term drags against contract resets above spot, automotive/EV and aerospace demand, >USD525 EBITDA/t by 4QFY24E, Bay Minette/Guthrie/Ulsan capex and a 2.3x net-debt/USD4.1b balance sheet. By the last Buy, the specific destocking/construction worries had dropped out while capacity expansion, Bay Minette commissioning, Oswego ramp-up, downstream innovation/higher value-added mix and copper sulphuric-acid strength became the core positives. The risk set changed to South Korea labour strike, US-Canada Section 232 tariffs, freight-cost inflation and LME correction, with even the firm-LME tailwind sitting beside late Buy calls whose actual returns were negative.
Fears that came true
- Cost Pressures & Inflation: the early flag of higher energy/input costs and inflation hitting short-term EBITDA margins matches DISAPPOINTMENT outcomes where Buy calls predicted +22.7% and +15.4% but actual returns were -8.7% (2024-06-03) and -2.1% (2024-07-10).
- Less Favorable Metal Benefits: the early ‘decreased benefits from metal recycling’ risk reappeared as the last report’s ‘correction in LME prices’ headwind, while 2026 Buy calls still printed negative actuals such as -8.1% (2026-08-06), -10.9% (2026-08-07) and -1.9% (2026-11-11).
- Litigation & Macro Factors: only the macro part persisted, with the early ‘overall macroeconomic slowdown’ showing up later as US-Canada Section 232 tariffs and higher global freight costs, and the 2026-11-11 Buy call printing +21.1% predicted versus -1.9% actual.
Broker Timeline
74 broker calls · 2023-05-10 to 2026-11-11
CNBC-TV18: ratings, targets and commentary
Extracted from CNBC-TV18 posts; ratings and targets are as published, not current consensus. OCR may contain errors. Speaker attribution is retained; not all speakers are brokers. These statements are separate from the Broker Narrative and Broker Timeline and have no calculated performance or outcomes.
Ratings and targets
| Published / source (IST) | Speaker / affiliation | Rating / target | Commentary |
|---|---|---|---|
| 2026-11-09 |
Citi
|
Neutral
Target: INR 1,050
Target action: lowered
|
Maintain Neutral on Hindalco; target price cut to ₹1,050. Q2 consolidated EBITDA rose 42% YoY but fell 8% QoQ. India Upstream EBITDA was ₹7,000 Cr, Downstream ₹330 Cr, Copper ₹1,670 Cr, Novelis ₹4,860 Cr. Net debt/EBITDA improved to 1.8x from 1.95x. Novelis insurance recovery reached $1.3 bn, including $900 m received. India costs expected to rise further in Q3, benefits from expansion projects remain back-ended. Limited upside seen to LME prices from current levels. |
Other company commentary (not broker ratings)
| Published / source (IST) | Speaker / affiliation | Rating / target | Commentary |
|---|---|---|---|
| 2026-11-09 |
Hindalco
Satish Pai
|
—
Horizon: Before March 2027
|
$519 m Recovered For Insurance, Expect Another $100-150 m Expected Before March 2027 |
| 2026-11-09 |
Hindalco
Satish Pai
|
—
Horizon: H2FY27
|
Novelis EBITDA tracking toward $500/tonne; FCF positive by Q4FY27. Bay Minette commercial sales to start in Feb 2027. Solid domestic demand & global aerospace offset weak global construction. $519 m insurance money recovered; $100-150 m more due by March 2027. H2FY27 standalone EBITDA guided at ₹1,200-1,300 cr per quarter. |
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.