HGS
Equity Metrics
September 24, 2026
Hinduja Global Solutions Limited
Business Process Outsourcing (BPO)/ Knowledge Process Outsourcing (KPO)
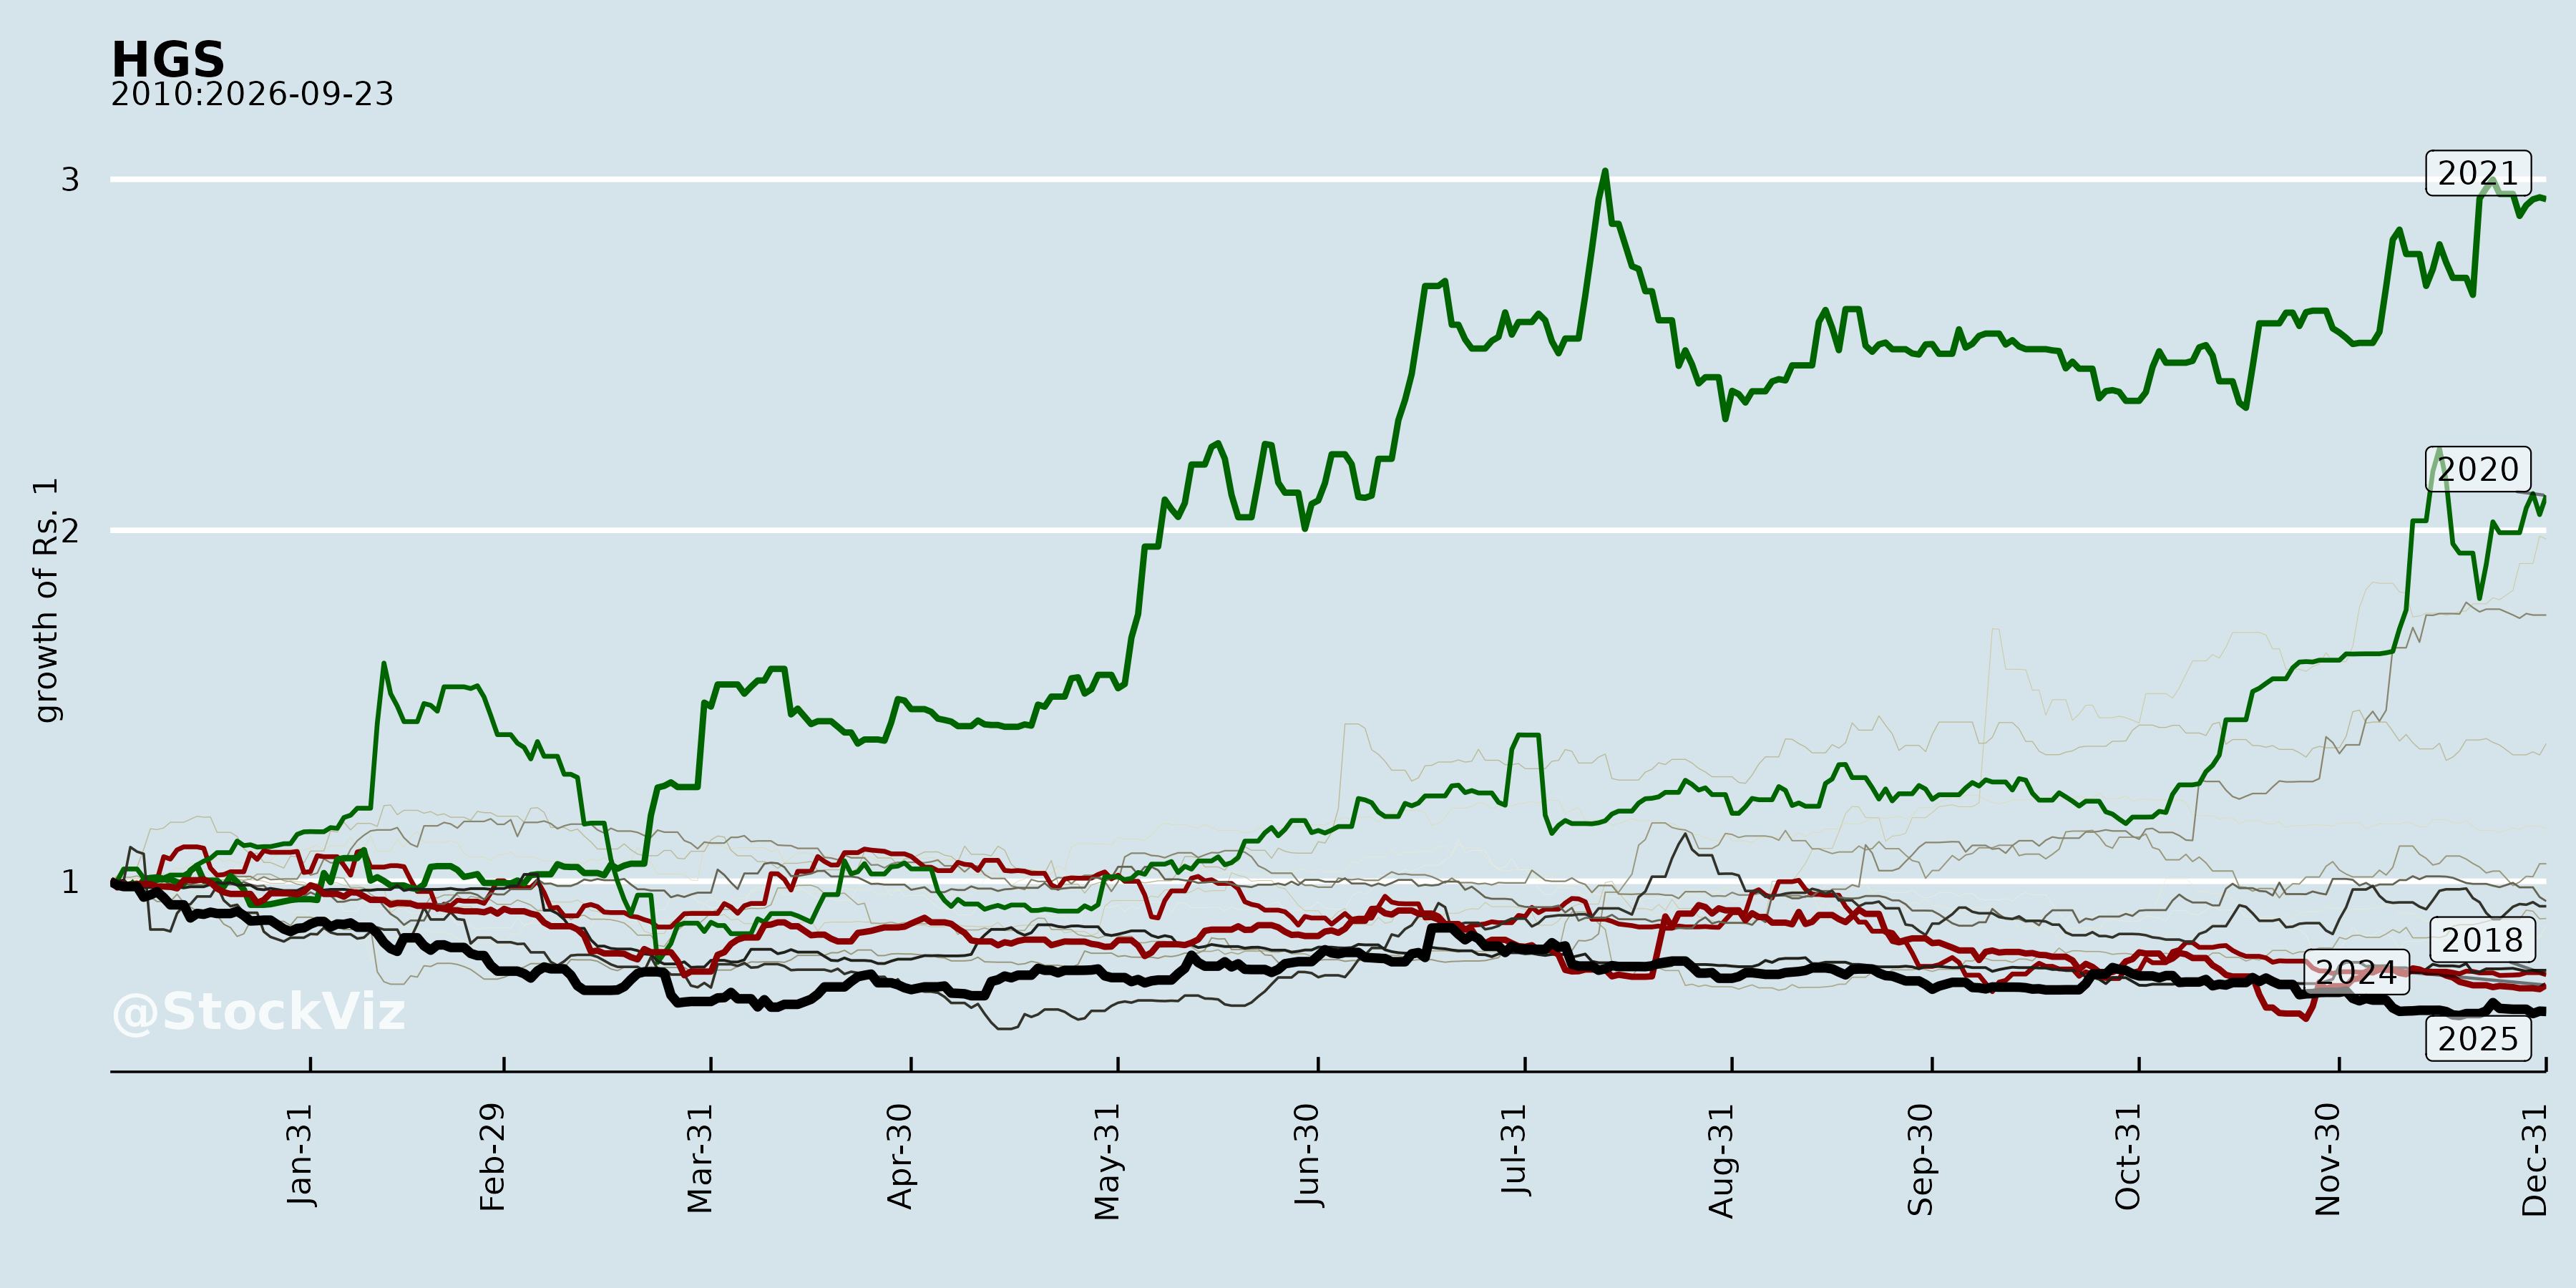
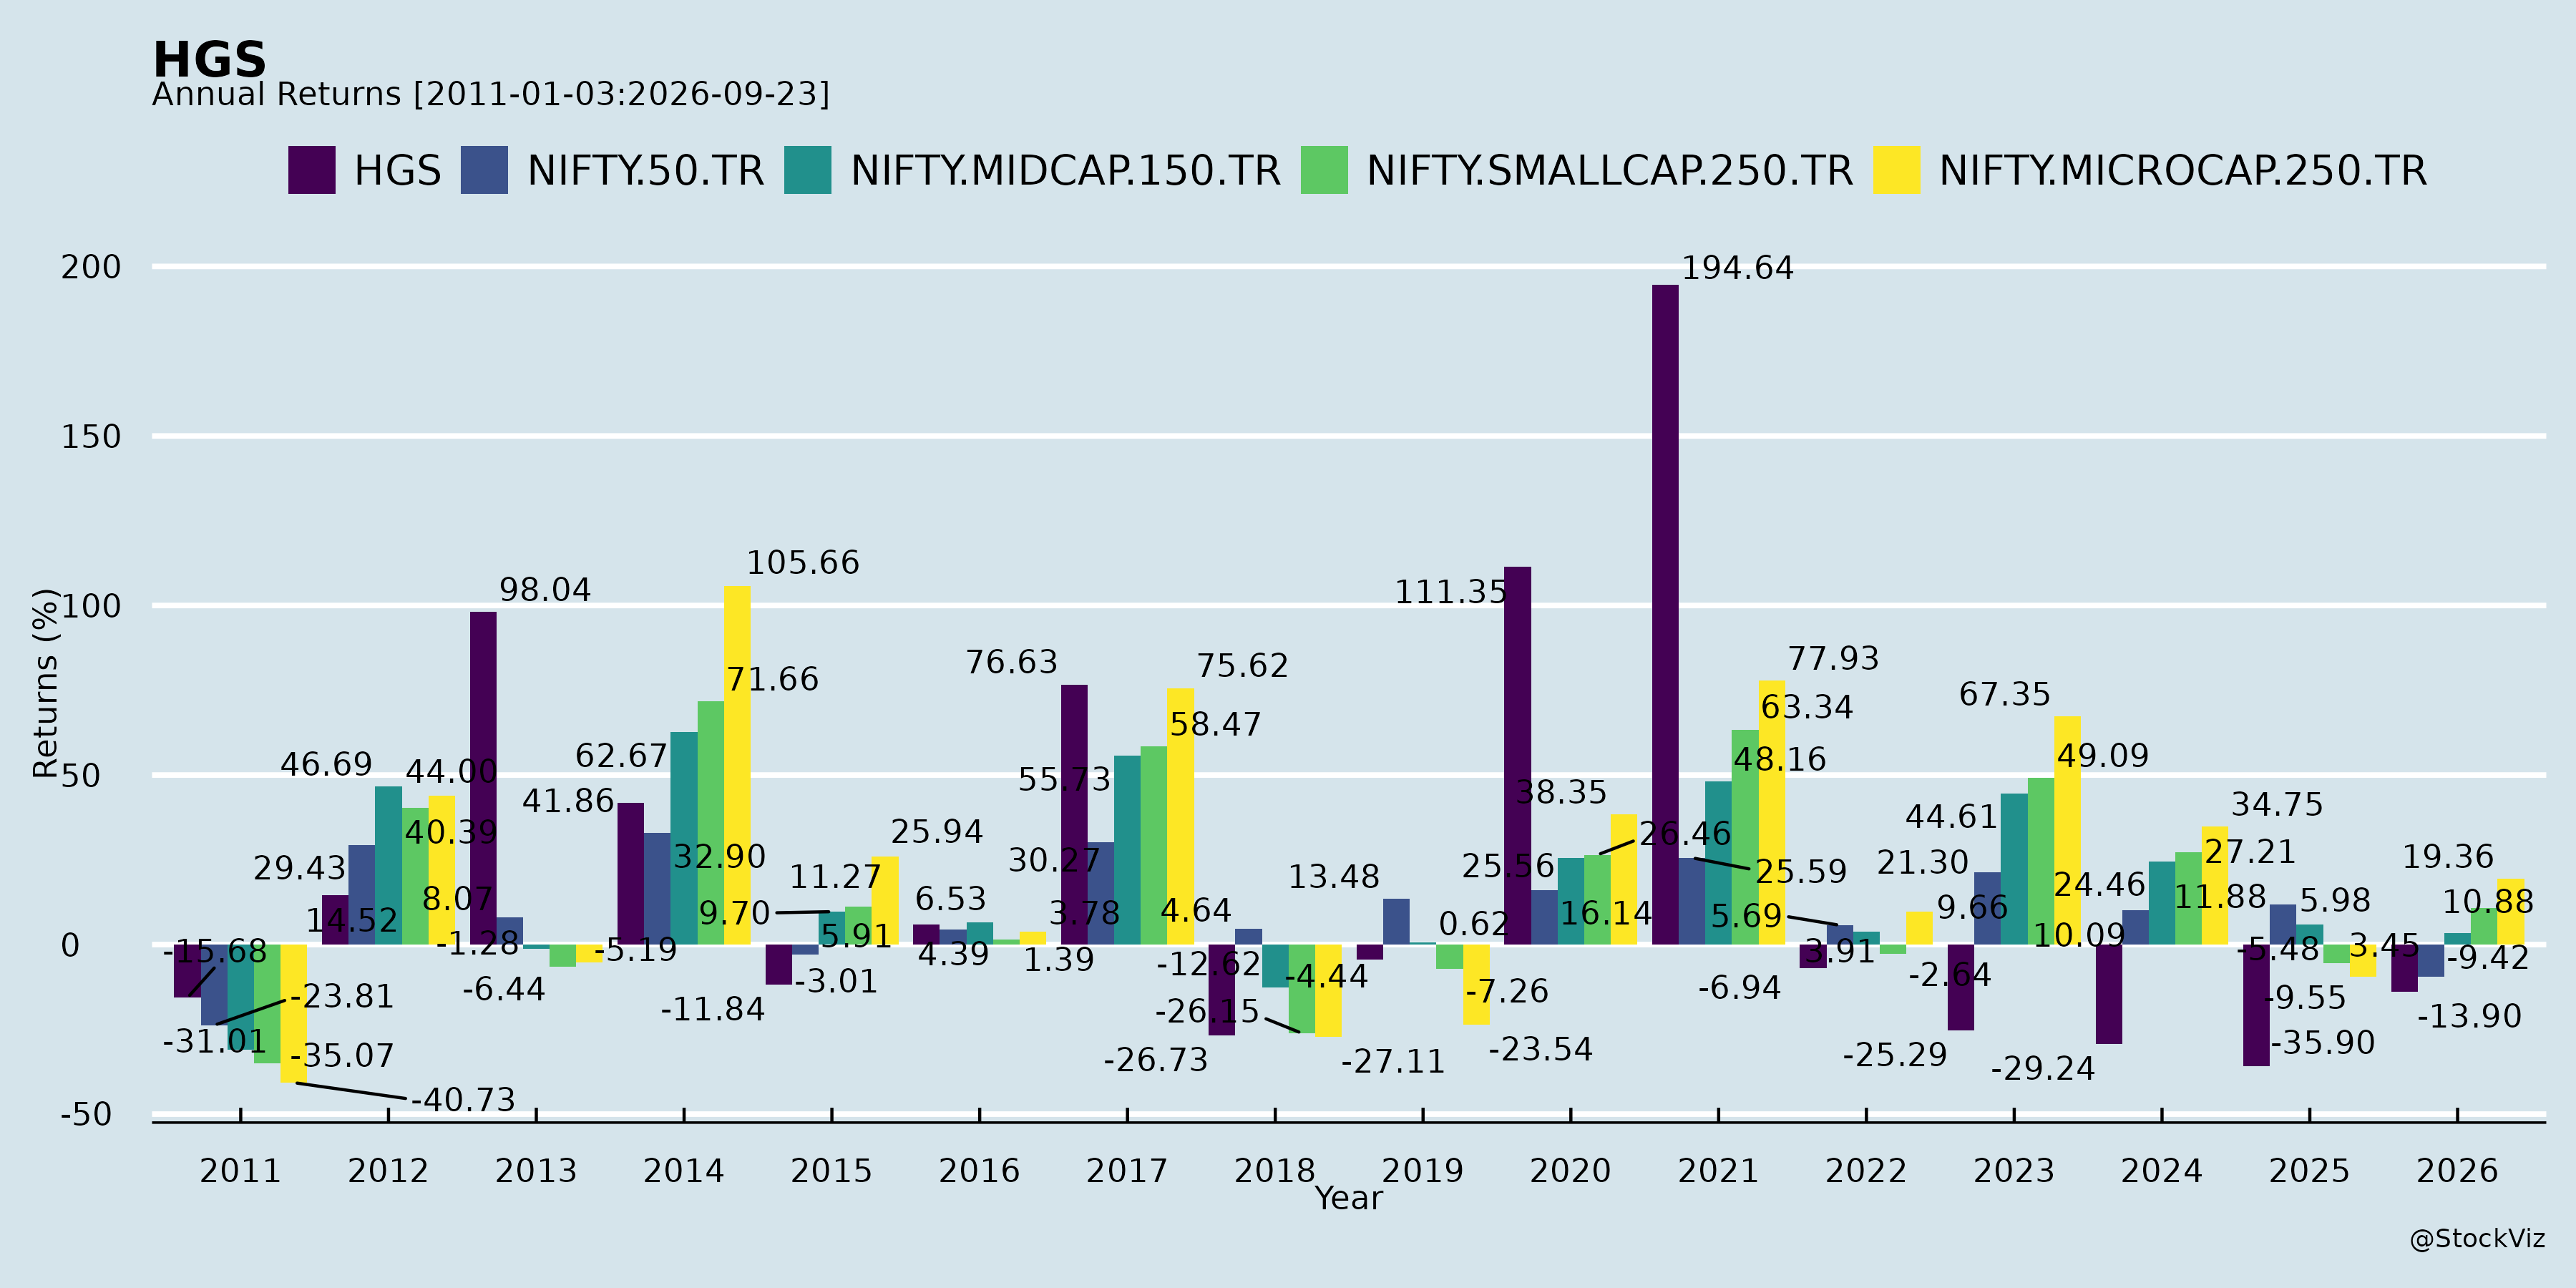
Annual Returns
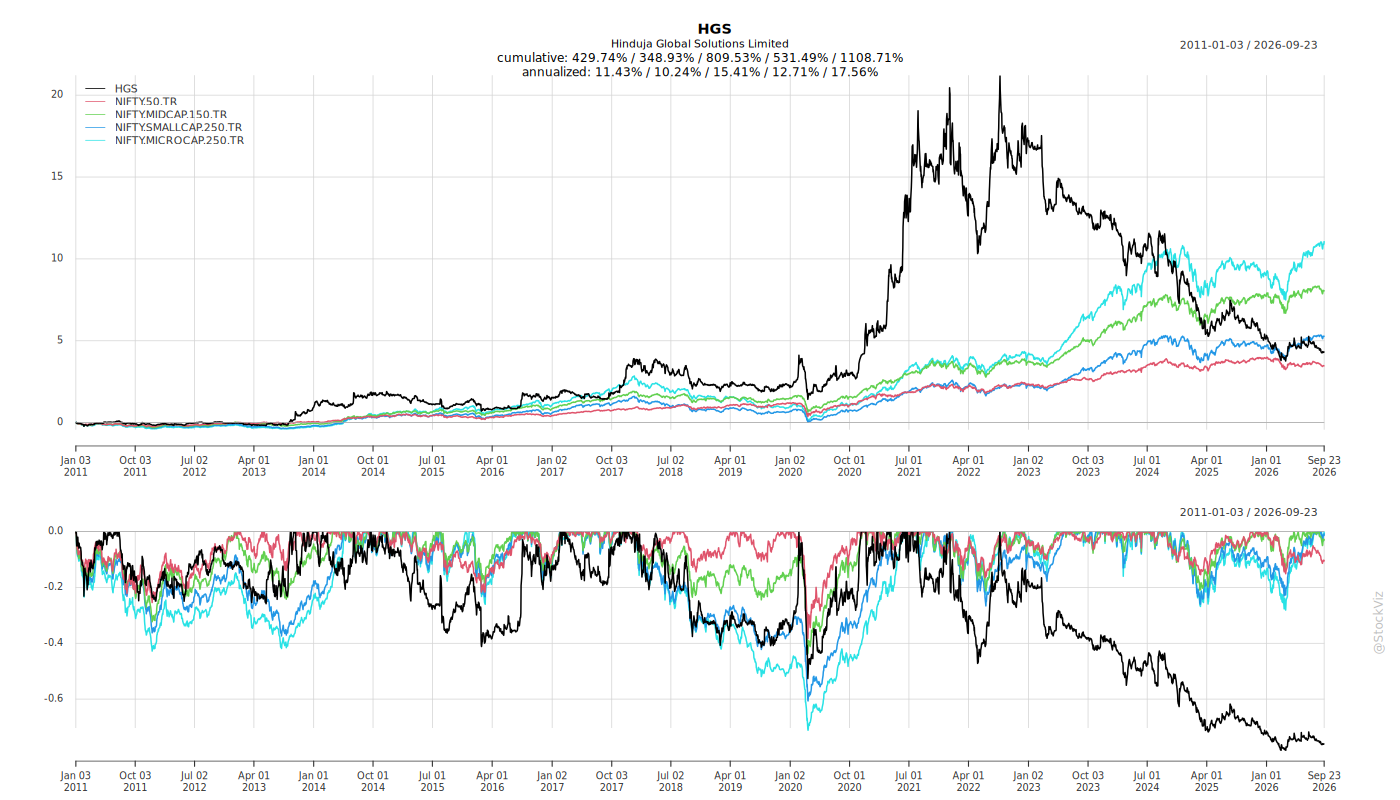
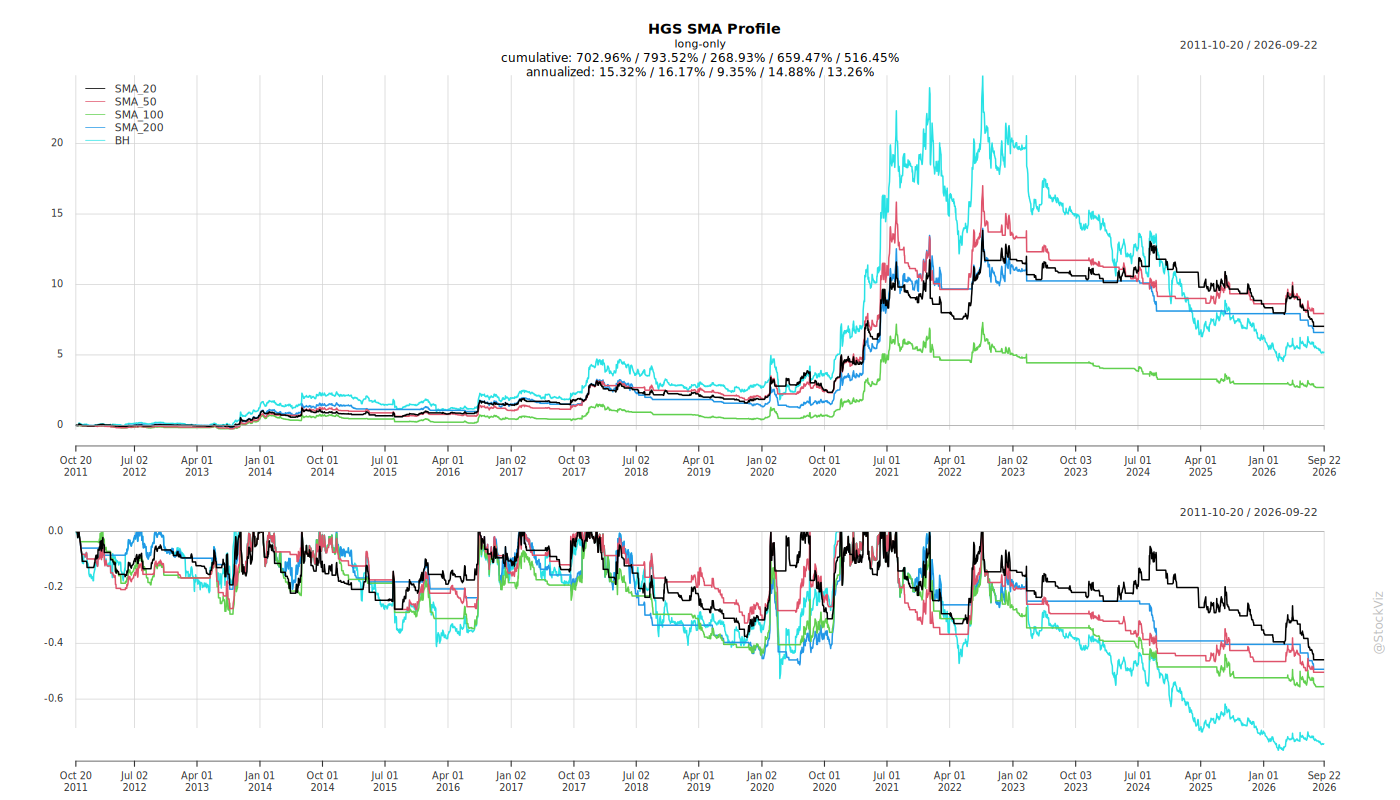
Cumulative Returns and Drawdowns
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-18
HGS Q1 FY2027: Headwinds, Tailwinds, Risks, and Guidance Versus Performance
1. Headwinds and Challenges
Planned runoff of legacy contracts. HGS is working through a planned transition in which some legacy contracts are completing as expected. Management stated these contracts were largely labor-priced, and their runoff is occurring on schedule. The company described the quarter as absorbing the planned phase-out of a large client engagement along with related one-time costs.
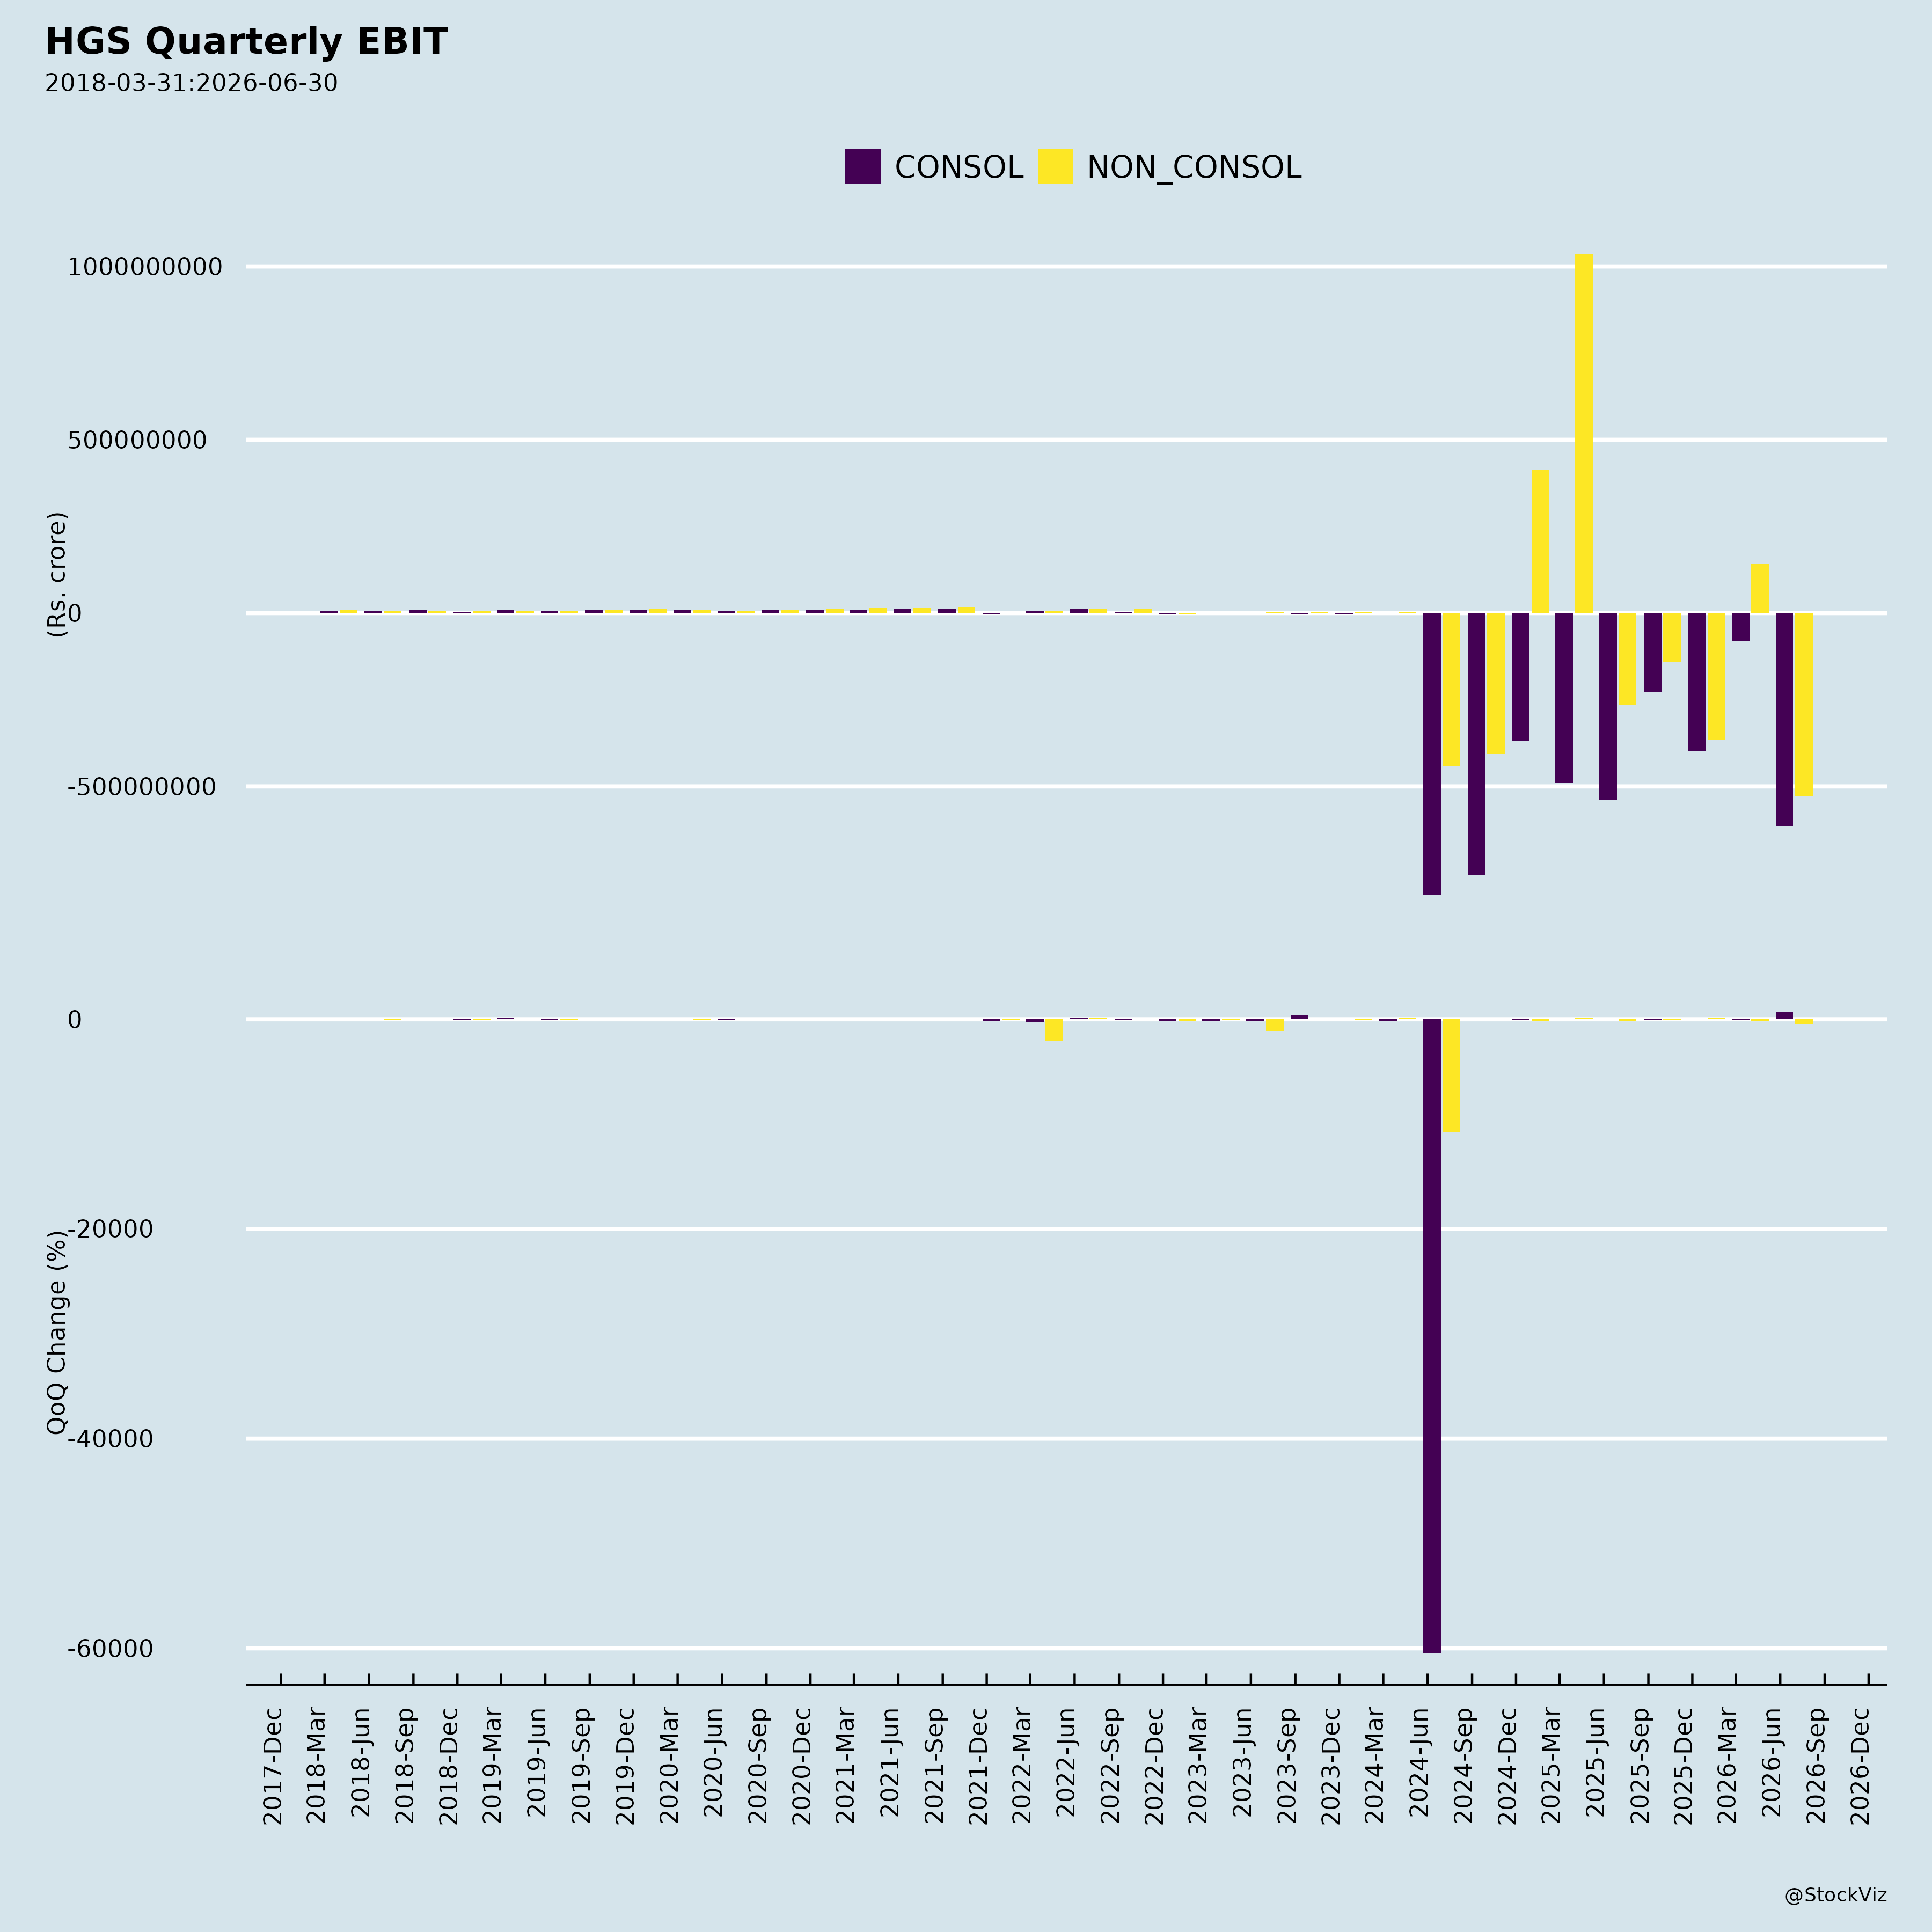
Margin compression from the new business mix. The contracts replacing the runoff carry a different profile: more technology content, more offshore delivery, and commercials increasingly tied to outcomes rather than headcount. Management noted the impact on margins is immediate because of ramp and training costs. Total EBITDA margin was 9.7% in Q1 FY2027, compared with 15.7% in the previous quarter and 13.5% year-on-year.
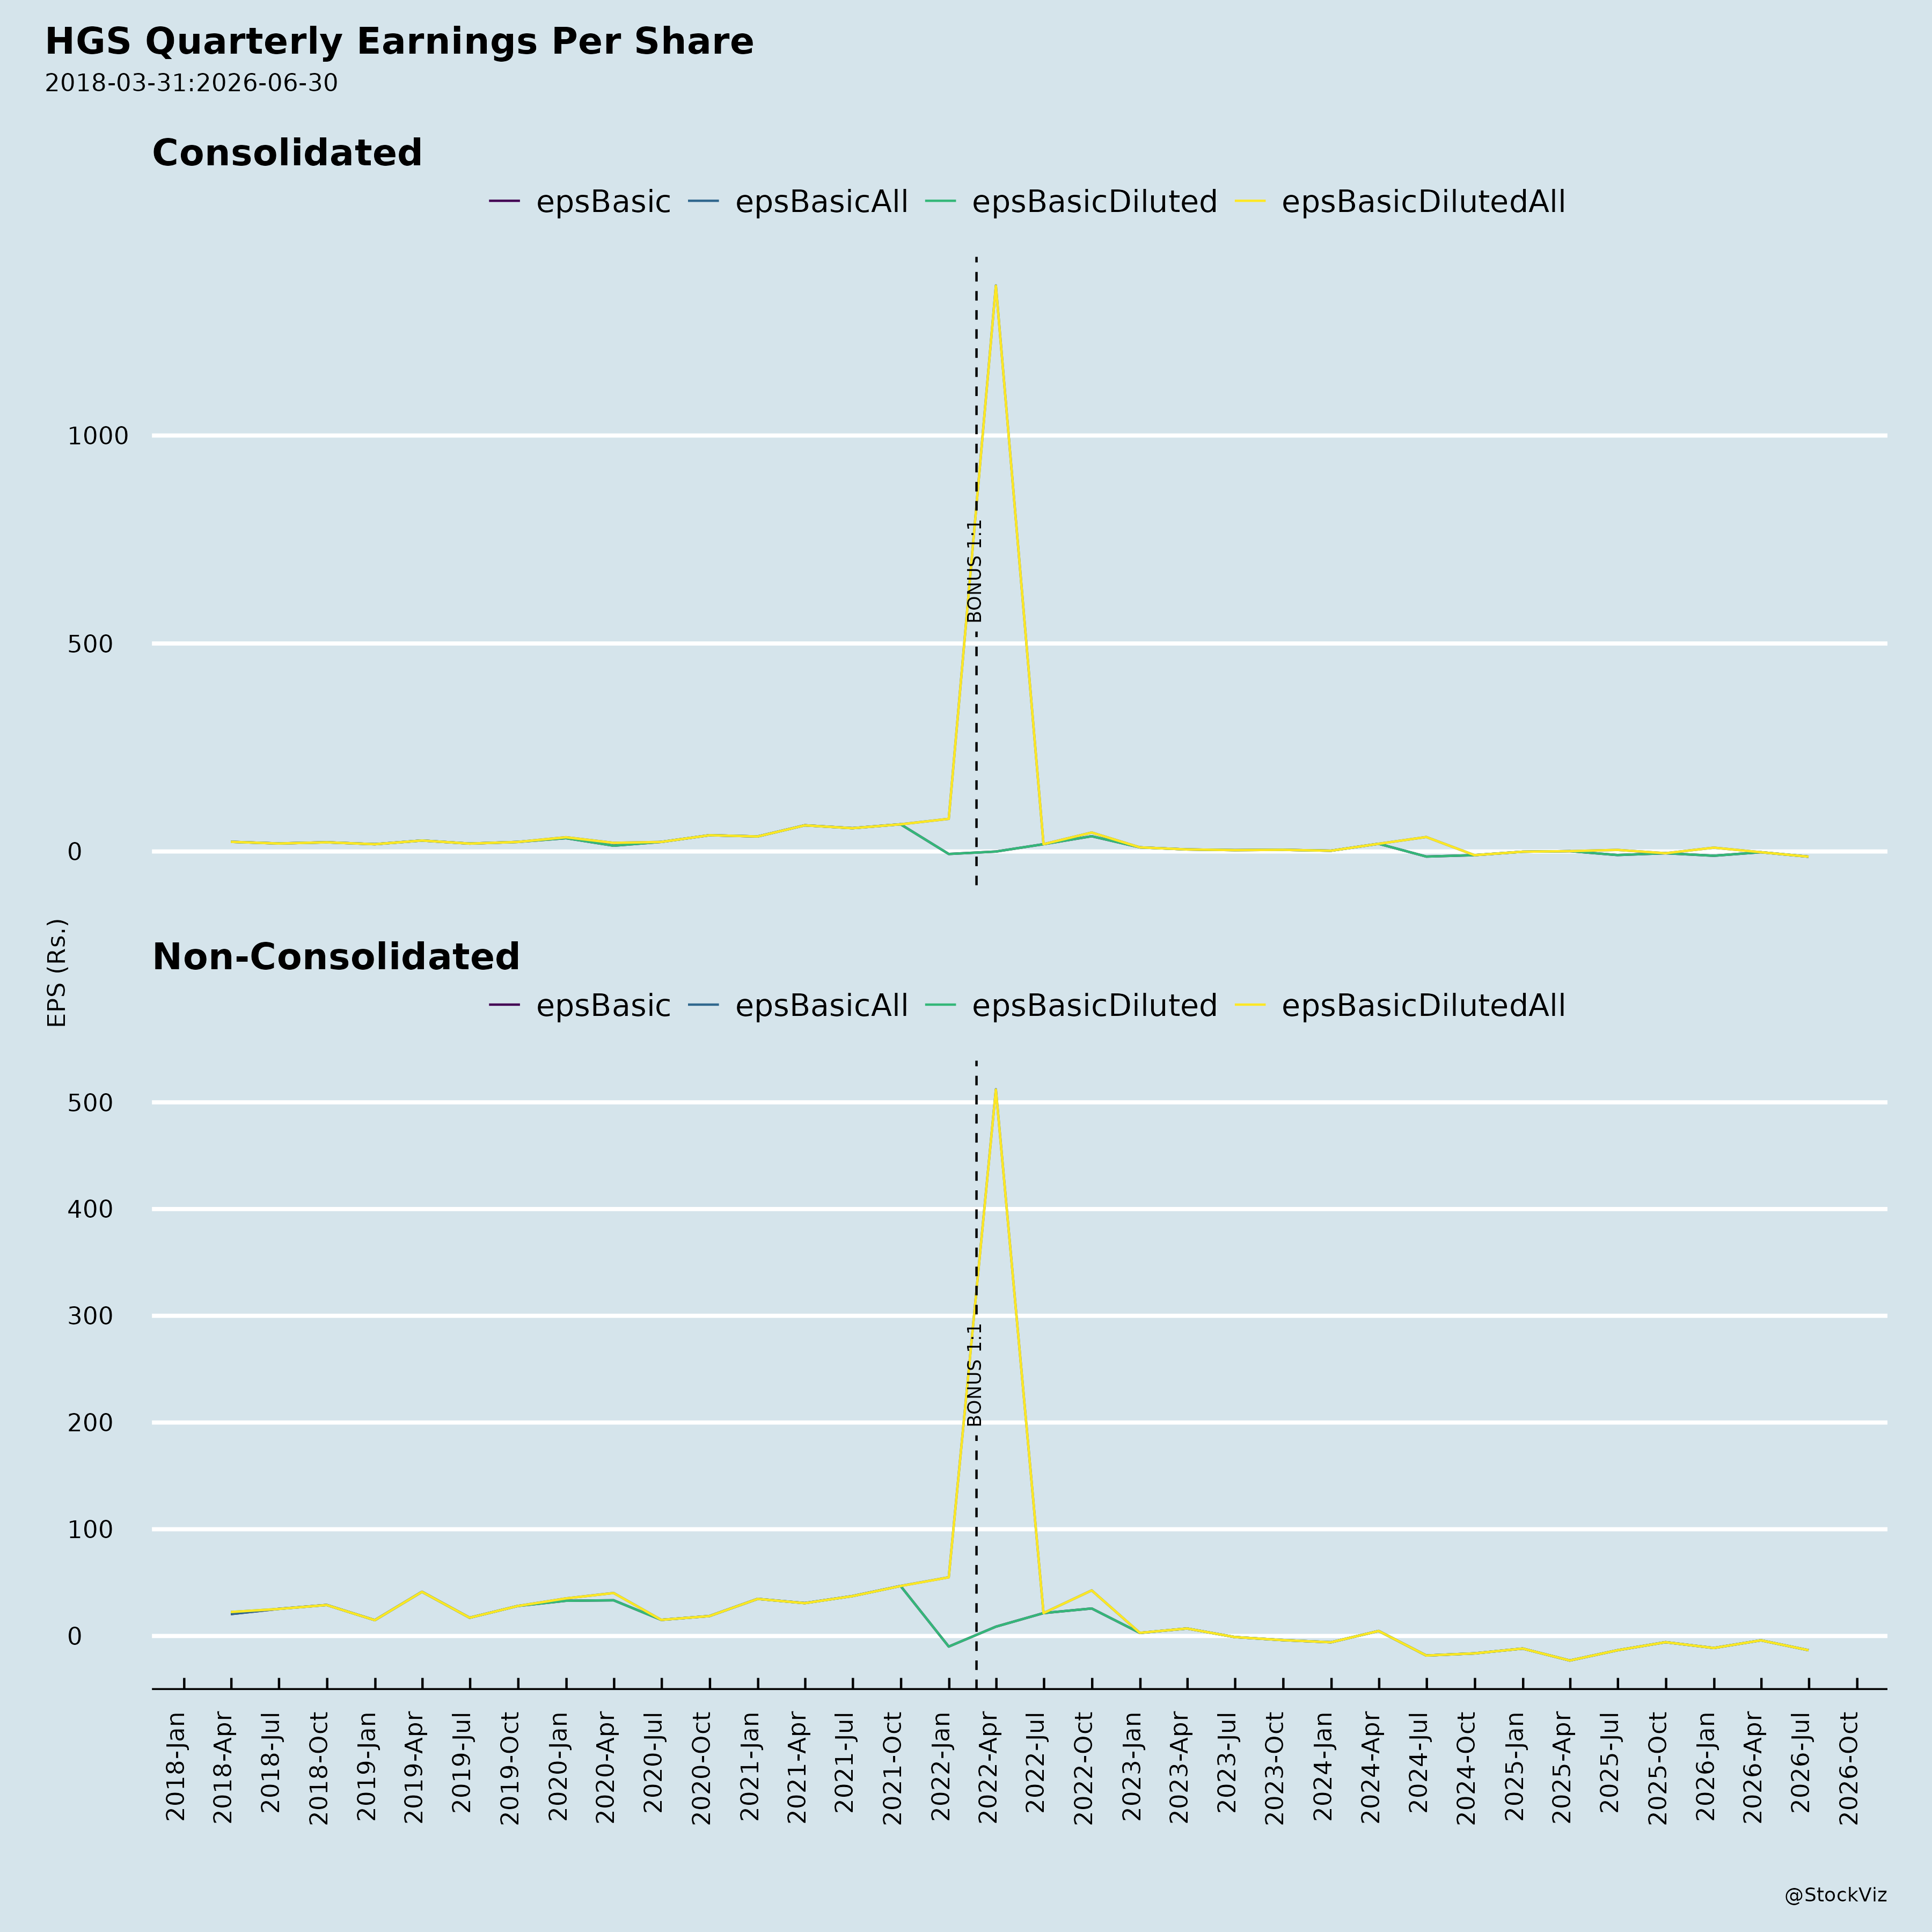
Profitability decline. Profit before tax before exceptional items was negative Rs. 52.8 crores, compared with positive Rs. 14.1 crores in the previous quarter and negative Rs. 26.5 crores in the corresponding quarter of the previous year. Total PAT was negative Rs. 66.3 crores, compared with negative Rs. 13.6 crores in the previous quarter and positive Rs. 11.2 crores a year earlier. The year-ago quarter included Rs. 57.5 crores from discontinued operations, which did not repeat.
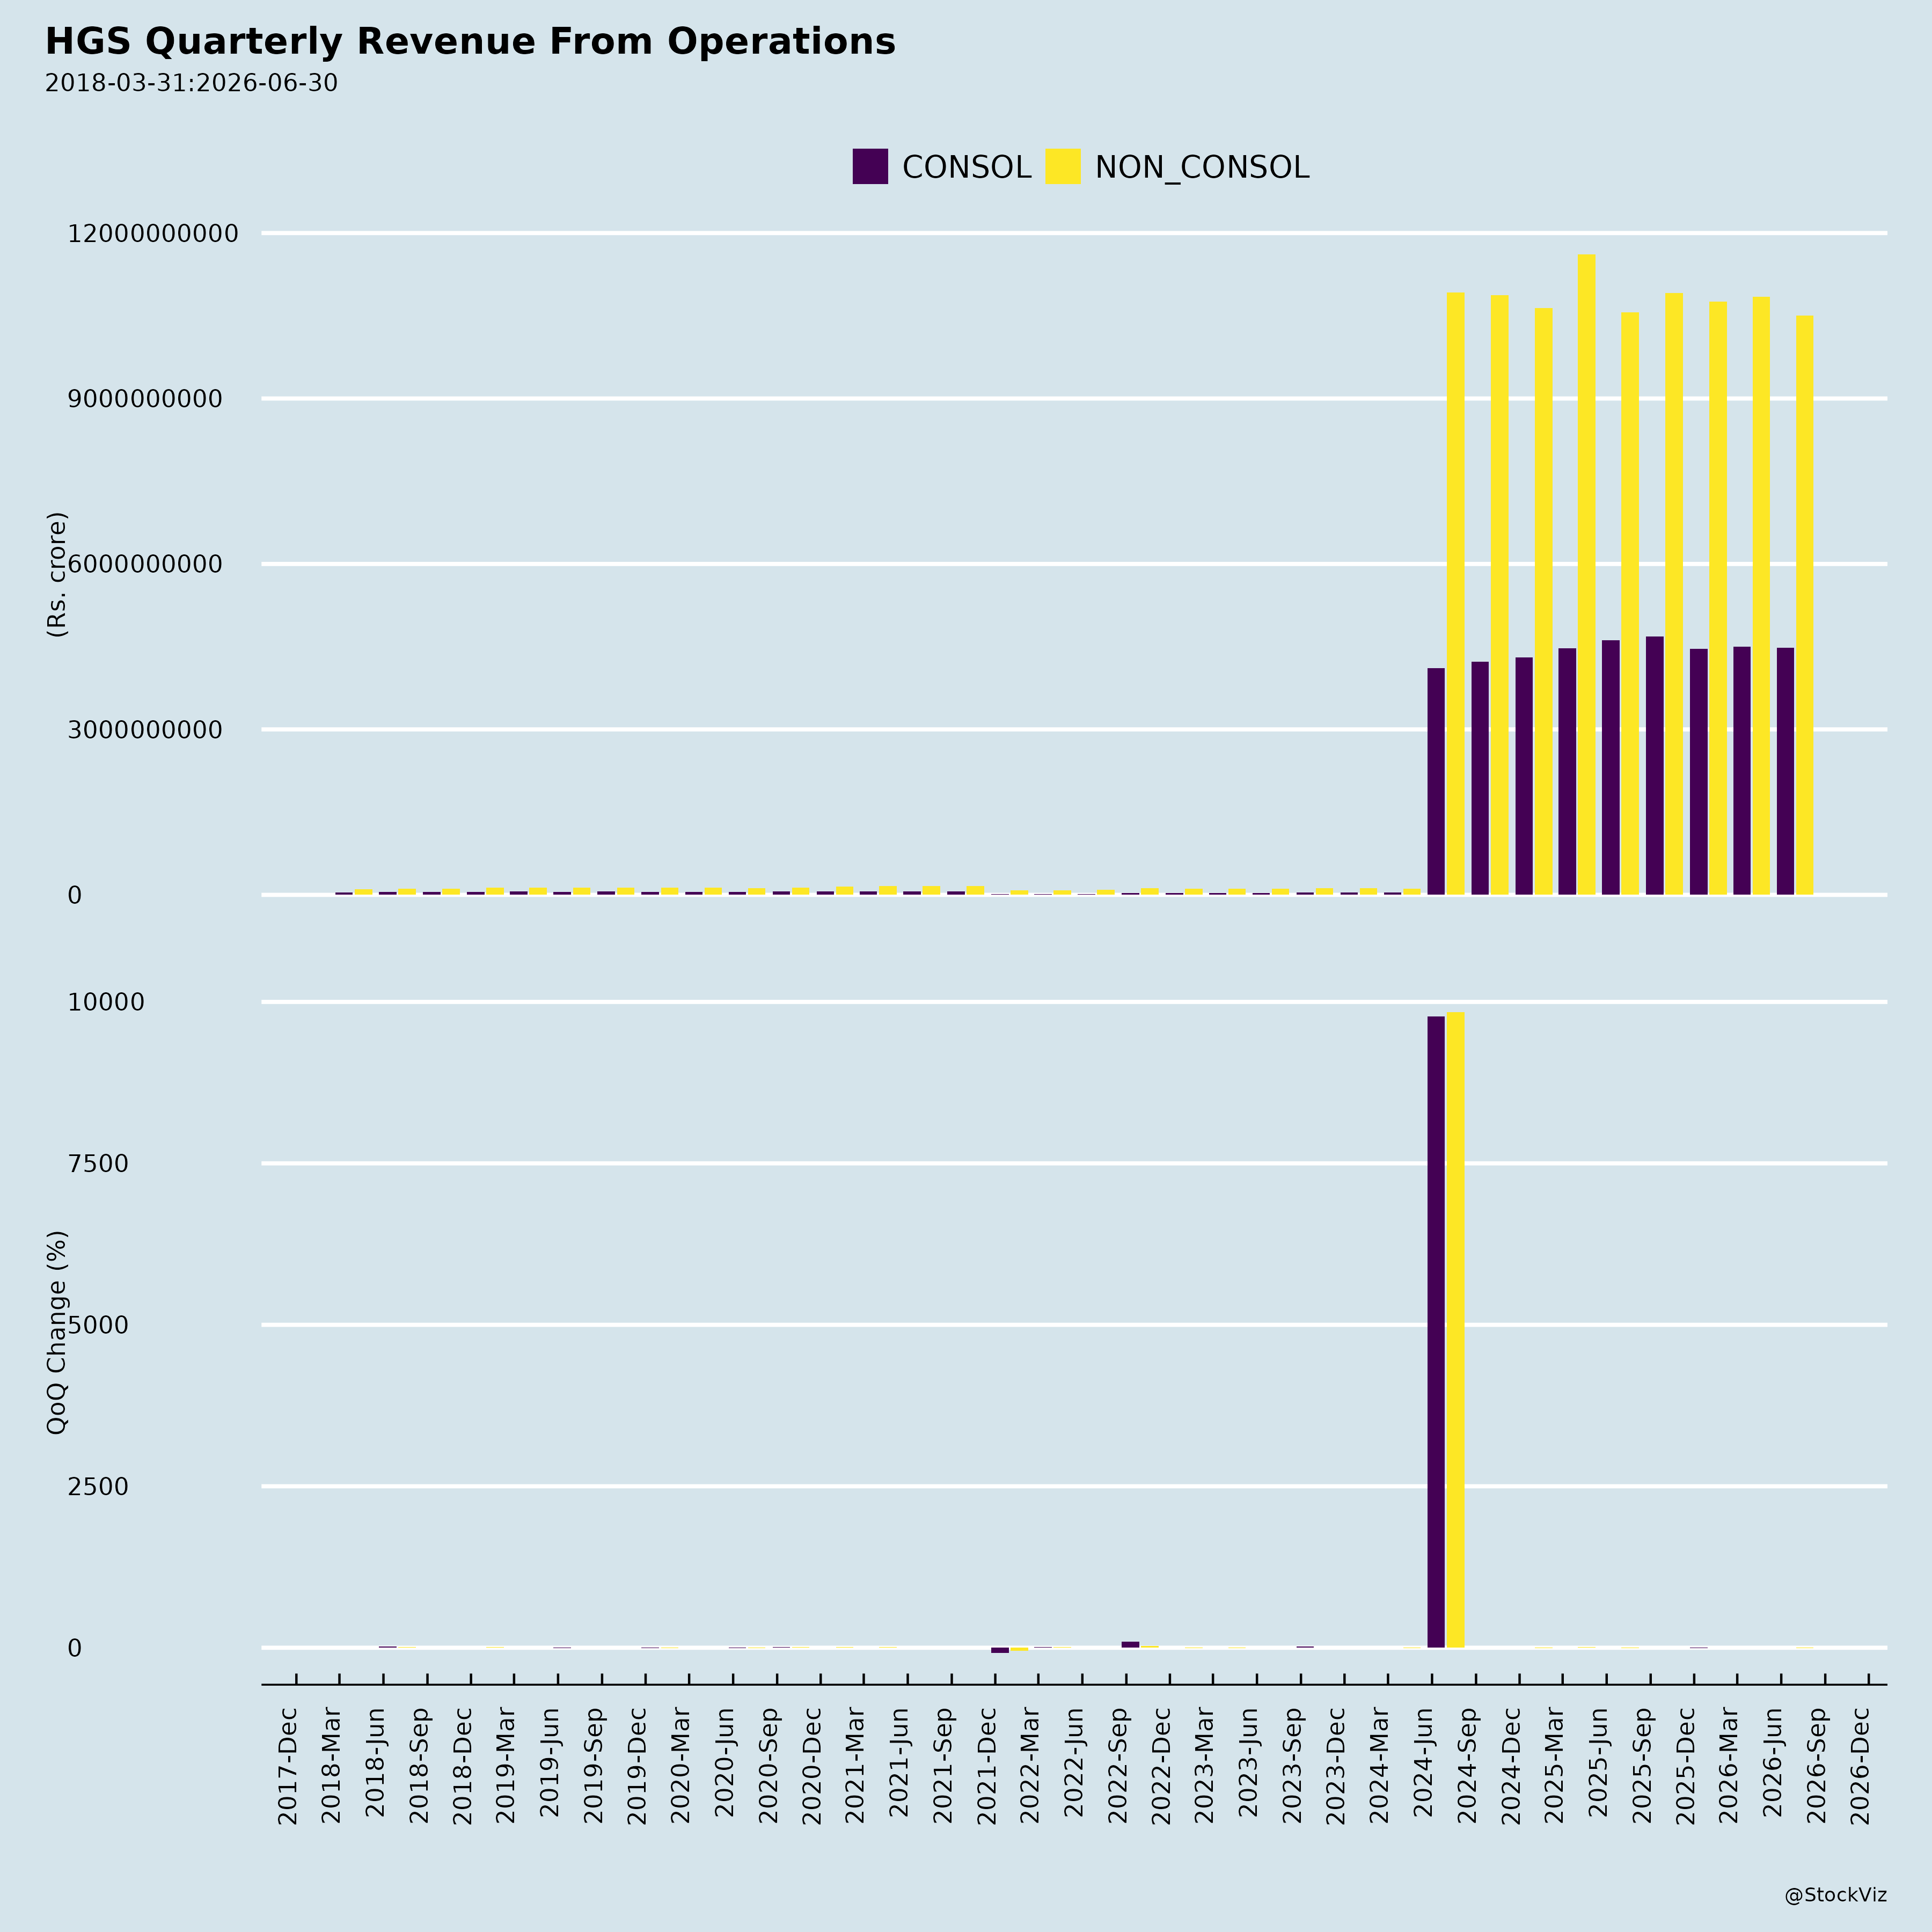
Revenue moderation. Revenue from operations was Rs. 1,050.4 crores, moderating around 3.2% sequentially and marginally lower by 0.6% year-on-year. Total income was Rs. 1,201.2 crores, down 4.3% sequentially and up 1.2% year-on-year.
Slow ramp of new client wins. New logos are at an early stage, particularly within the OSS business. Management indicated it typically takes around 6 to 8 months before new clients begin contributing meaningfully, starting at roughly $150,000 to $300,000 of work before scaling. Training, onboarding, and ramp-up costs are incurred in the first three months.
Client readiness constraints on AI adoption. While clients want to move from AI pilots to production deployments, not all are ready with the data and governance structures required. Management cited this as an ongoing challenge to the pace of transition.
Digital television headwinds. The linear TV business faces significant headwinds, described as industry-wide in India and globally. Mitigation has included bundling broadband with DTV in certain markets, rolling out IPTV, and cost optimization.
Macro uncertainty and client prudence. Management described macro uncertainties and client prudence as likely to persist in the near term, with clients waiting to see how AI contributions play out.
Tax dispute overhang. The GAAR panel passed a directive on October 30, 2025 characterizing the treatment of tax losses under the demerger of NXT Digital’s DMC business as an “impermissible avoidance arrangement,” directing the DCIT-AO to disregard the brought forward losses of the demerged entity. Total tax reduction referenced was Rs. 281.59 crores. HGS filed a writ petition with the Bombay High Court on November 7, 2025; the court heard it on December 19, 2025 and passed an order in the company’s favor, admitting the petition and granting an interim stay on implementation of the GAAR Panel direction. The final financial impact will be known only upon completion of proceedings before the Assessing Officer. No adjustment was considered necessary in the Q1 FY2027 standalone results.
Labour Codes. The Government notified the Labour Codes on November 21, 2025. HGS recognized a financial impact of Rs. 4.56 crores and Rs. 8.70 crores under Ind AS 19 as an exceptional item in the standalone results for the quarter and year ended March 31, 2026. Central Rules were notified on May 8, 2026, but corresponding State Rules and certain operational clarifications remain pending; the company will record any additional accounting impact as required.
2. Tailwinds and Growth Prospects
AI-led transformation momentum. Multiple AI-embedded client engagements are moving forward, with clients increasingly treating AI as part of real operating models focused on measurable outcomes, productivity, speed, quality, and business impact. Management stated every new deal closed recently has AI components enabled, with AI performing at least 20% to 30% of the work initially, scaling toward 60% to 70% as clients gain comfort.
New client additions. HGS added 19 new logos across CX and digital services and 8 clients in HRO and payroll processing in Q1 FY2027. As of June 30, 2026, HGS had 439 active CX/Digital clients and 889 HRO/Payroll processing clients/brands. Management expects the pace of new logo additions to remain strong through FY2027, referencing approximately 78 to 79 new logos added in the prior fiscal year.
Strong pipeline. The pipeline remains strong in agentic AI, process automation, contact center, digital modernization, and platform services.
New market positioning. At the end of March 2026, HGS introduced a sharper market position as an “intelligent experiences partner,” with the portfolio clarified under three solution areas: Intelligent Interactions, Intelligent Operations, and Intelligent Platforms. Management reported traction and excitement from clients, translating into leads and inbound interest from existing customers.
Outcome-led commercial model. HGS is moving a growing share of contract value onto outcome-linked and non-headcount commercial structures. The 90-day proof of value model is designed to help clients move faster to outcomes; if it does not work, the client does not pay.
Verticalization. HGS is verticalizing into four markets where it has depth: BFSI, Consumer Products and Retail, Healthcare, Public Sector and Utilities. This involves codifying knowledge into reusable assets, vertical agent libraries, and package solutions.
MENA expansion. HGS incorporated HGS MENA IT Consulting L.L.C. in Dubai, UAE, as a wholly owned subsidiary of HGS International, Mauritius, to build technology and consulting capabilities across the MENA region.
Diversified vertical mix. Tech, Media and Telecom was the largest vertical at 46% of total revenue, followed by CG and Retail at 19%, BFSI at 17%, Public Sector at 12%, Health and Life Sciences at 3%, and others at 4%. Management described the vertical mix as more diversified compared with prior quarters, with lower dependence on the largest vertical.
Broadband growth and Project GANGA. Project GANGA was launched on June 9, 2026, flagged off by the Chief Minister of Uttar Pradesh, building on an MoU signed in March 2026 between the State Transformation Commission and OneOTT Intertainment Ltd. The initiative aims to develop 8,000 to 10,000 entrepreneurs into Digital Service Providers, with 50% being women, connecting over 2 million households with high-speed broadband over the next 2 to 3 years and generating over 100,000 employment opportunities. Over 2,000 applications were received on the Project GANGA portal and app as of August 4, 2026, and about 500 applicants had been trained in business operations, technology, and field services. Management stated Project GANGA is not a negative cash flow play and is structured on a no profit, no loss basis for the enablement role, with ISP broadband pricing in line with competition in Uttar Pradesh.
CelerityX enterprise business. CelerityX added IndusInd Nippon Life Insurance, Panvel Municipal Corporation, and Farmacross to its client portfolio, while securing repeat contracts from L&T Finance, Tata Communications, and Sify. Management identified CelerityX as a forward growth engine and noted repeat contracts are longer duration, providing comfort and confidence.
High-speed broadband adoption. High-speed adoption (101 Mbps and above) rose from 11% in Q1 last year to 15% this quarter on an expanding subscriber base. Customers opting for the entry pack of 10 to 30 Mbps reduced from 22% to 18%, with the mid-band of 31 to 100 Mbps stable at around 67%.
Recognition. HGS received recognition including AMLens winning at the Banking Tech Awards USA 2026, HGS Philippines GPTW certification for the second consecutive year, OneOTT Intertainment’s “Best Future Ready Network of the Year 2025-26” at the 12th BCS Ratna Awards, a special mention at the Avasant Banking Digital Services 2026 RadarView, recognition as a Notable Provider in the Forrester BPO Services Landscape Q2 2026, ranking 25th globally in the OA500 2026, and listing in the Everest Group-BPS Top 50 2026.
Balance sheet strength. Total assets were Rs. 11,474 crores as of June 2026 against Rs. 11,556.7 crores in March 2026. Total equity was Rs. 8,402.5 crores against Rs. 8,436.1 crores. Gross treasury and cash surplus was Rs. 6,605 crores against total borrowings of Rs. 1,279 crores, leaving a net treasury and cash surplus of Rs. 5,326 crores compared with Rs. 5,346 crores at the end of March. Interest cost declined to Rs. 45.5 crores from Rs. 48.1 crores sequentially and Rs. 57.9 crores year-on-year.
Divestments of step-down subsidiaries. IMCL, a subsidiary of HGS, approved divestment of its entire shareholdings in Bhima Riddhi Infotainment Private Limited (51%) and Vinsat Digital Private Limited (51.15%). Upon completion, both will cease to be step-down subsidiaries. For Bhima Riddhi, expected completion is on or before September 30, 2026, with total consideration of Rs. 16 crore. For Vinsat, expected completion is on or before December 31, 2026, with total consideration of Rs. 7.17 crore.
3. Key Risks
- Execution risk on the transition. The shift to outcome-linked, technology-heavy contracts carries immediate margin absorption from ramp and training costs. Management views this as a one-time cost and investment phase rather than a structural change in earning power, and expects operating leverage to return as volume normalizes and investments commercialize.
- Timing risk on new client revenue. New logos take 6 to 8 months to contribute meaningfully, and revenue contribution is expected to build progressively as projects mature and scope expands.
- Client readiness risk on AI. Not all customers are ready with the data and governance story required to move from pilots to production deployments.
- Digital television decline. The linear TV business faces significant headwinds, mitigated through bundling, IPTV, and cost optimization, with mitigation efforts described as ongoing.
- Macro and client prudence. Macro uncertainties and client prudence may persist in the near term.
- Tax dispute. The final financial impact of the GAAR matter will be known only upon completion of proceedings before the Assessing Officer, despite the interim stay granted by the Bombay High Court.
- Labour Codes. State Rules and certain operational clarifications remain pending, and additional accounting impact may be recorded as required.
- Project GANGA execution. The initiative involves training and enabling thousands of entrepreneurs into Digital Service Providers, with KPIs on training, loan disbursement, network rollout, and customer onboarding to be shared in subsequent quarters.
4. Management Guidance Versus Observed Business Performance
Margin trajectory. Management stated the margin compression was not due to demand or delivery, noting operating expenses stayed broadly flat at around Rs. 1,084.9 crores while revenue moderated. The quarter absorbed one-time costs related to the planned phase-out of a large client engagement and front-loading of investments in sales, solutions, domain hiring, and AI capability build, including Agent X and the 90-day POV model. Management expects operating leverage to return as volume normalizes and these investments commercialize, and expects gradual improvement in both growth and margins through the year. Observed performance: EBITDA margin was 9.7% in Q1 FY2027 versus 15.7% sequentially and 13.5% year-on-year, with PBT before exceptional items negative Rs. 52.8 crores.
New client ramp. Management indicated new clients typically take 6 to 8 months to contribute meaningfully, starting at $150,000 to $300,000, with margin impacts in initial months, and expected growth and margin attractiveness before the end of the year. Observed performance: 19 new CX/digital logos and 8 HRO/payroll clients added in Q1 FY2027, with revenue contribution expected to build progressively.
Runoff completion. Management stated the deliberate ramp-downs should come to an end before the end of the current fiscal year. Observed performance: contracts running off are doing so on schedule as expected.
Revenue growth drivers. Management expects the largest expansion growth driver in FY2027 to be in the AI digital space, with existing clients driving growth as they adopt intelligent experiences and AI/digital technology. Observed performance: revenue from operations was marginally lower by 0.6% year-on-year and moderating around 3.2% sequentially.
Margin accretion from AI. Management stated the client pool gives confidence that AI investments are medium-term margin accretive rather than dilutive. Observed performance: near-term margin absorption is occurring as capabilities scale up.
Project GANGA. Management stated Project GANGA entered execution/operational mode in Quarter 2, and at the end of Quarter 2 the company expects to be in a much better and completely different position in terms of reporting. KPIs on trained individuals, loan disbursements under the CM YUVA Scheme, network rollouts, and customer onboarding are to be shared in the next quarter. Observed performance: over 2,000 applications received as of August 4, 2026, and about 500 applicants trained as of the call date.
Dividend. The Board recommended a final dividend of Rs. 5 per equity share for FY2025-26 at its meeting on June 4, 2026. The 31st AGM is scheduled for Friday, September 25, 2026, via video conferencing, with book closure from September 19 to September 21, 2026, and a record date of September 18, 2026. The final dividend, if approved, will be paid within 30 days from the date of approval.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.