HAVELLS
Equity Metrics
October 23, 2026
Havells India Limited
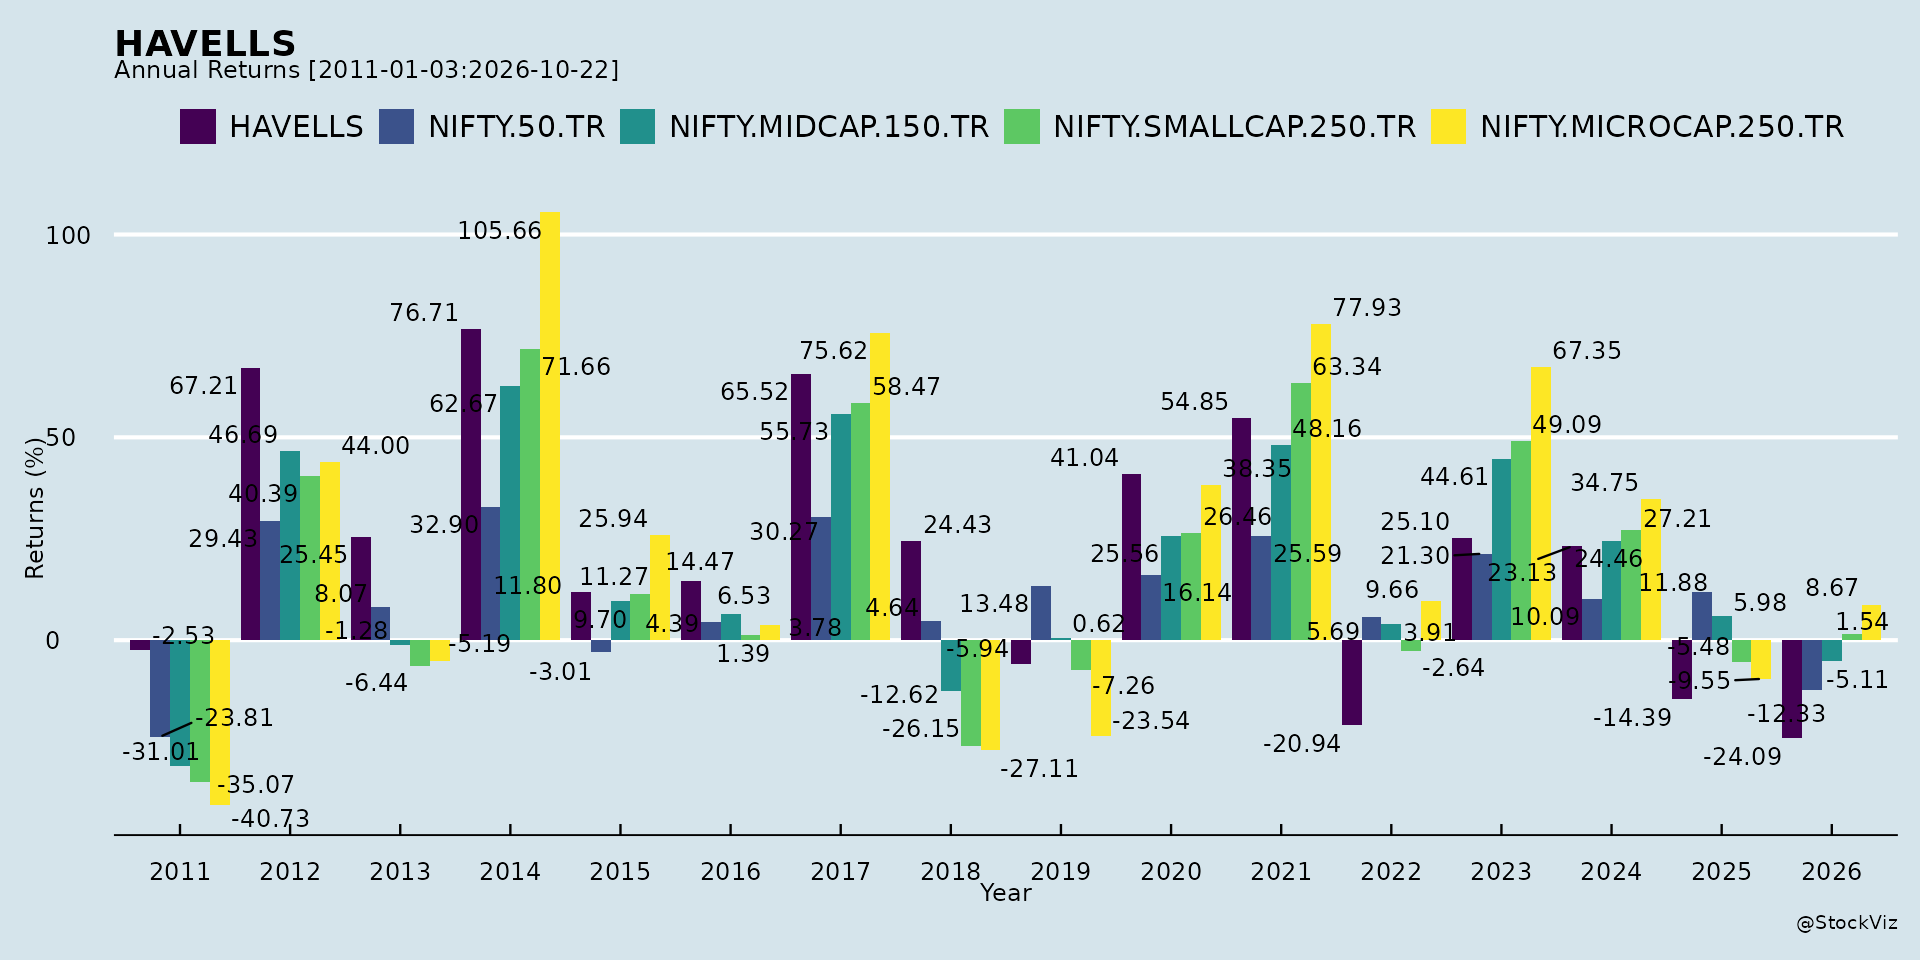
Annual Returns
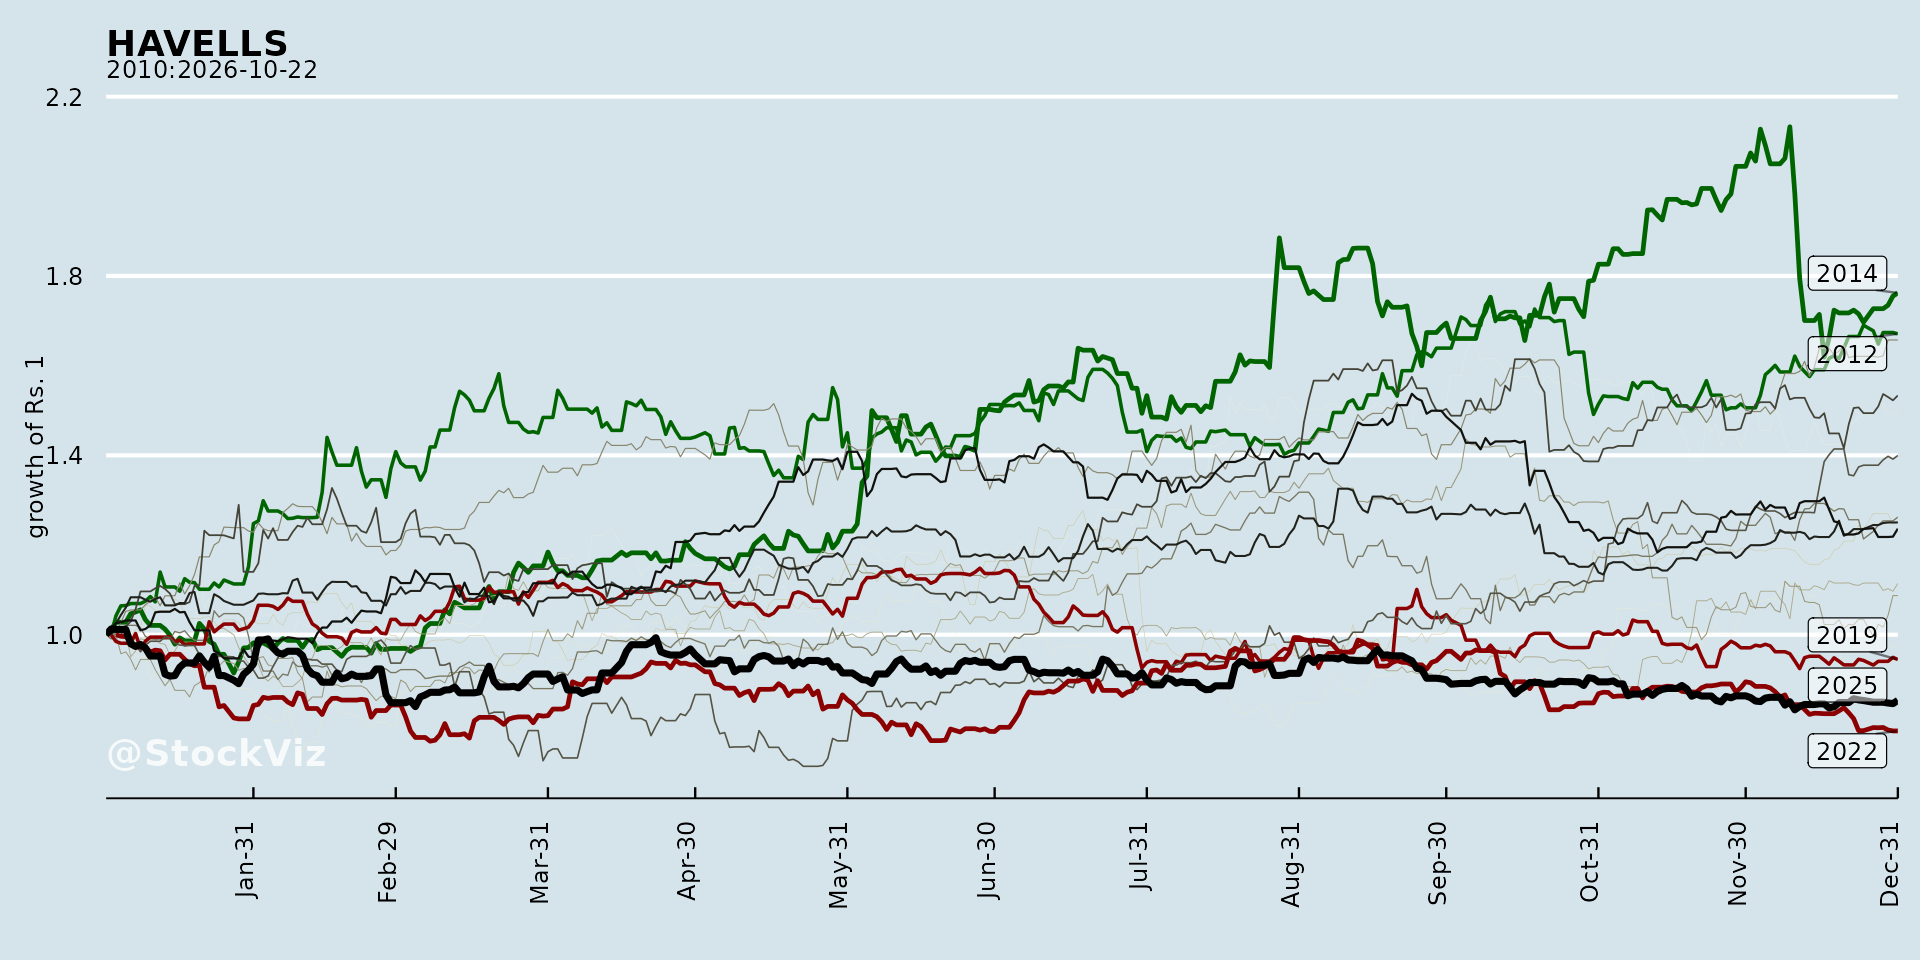
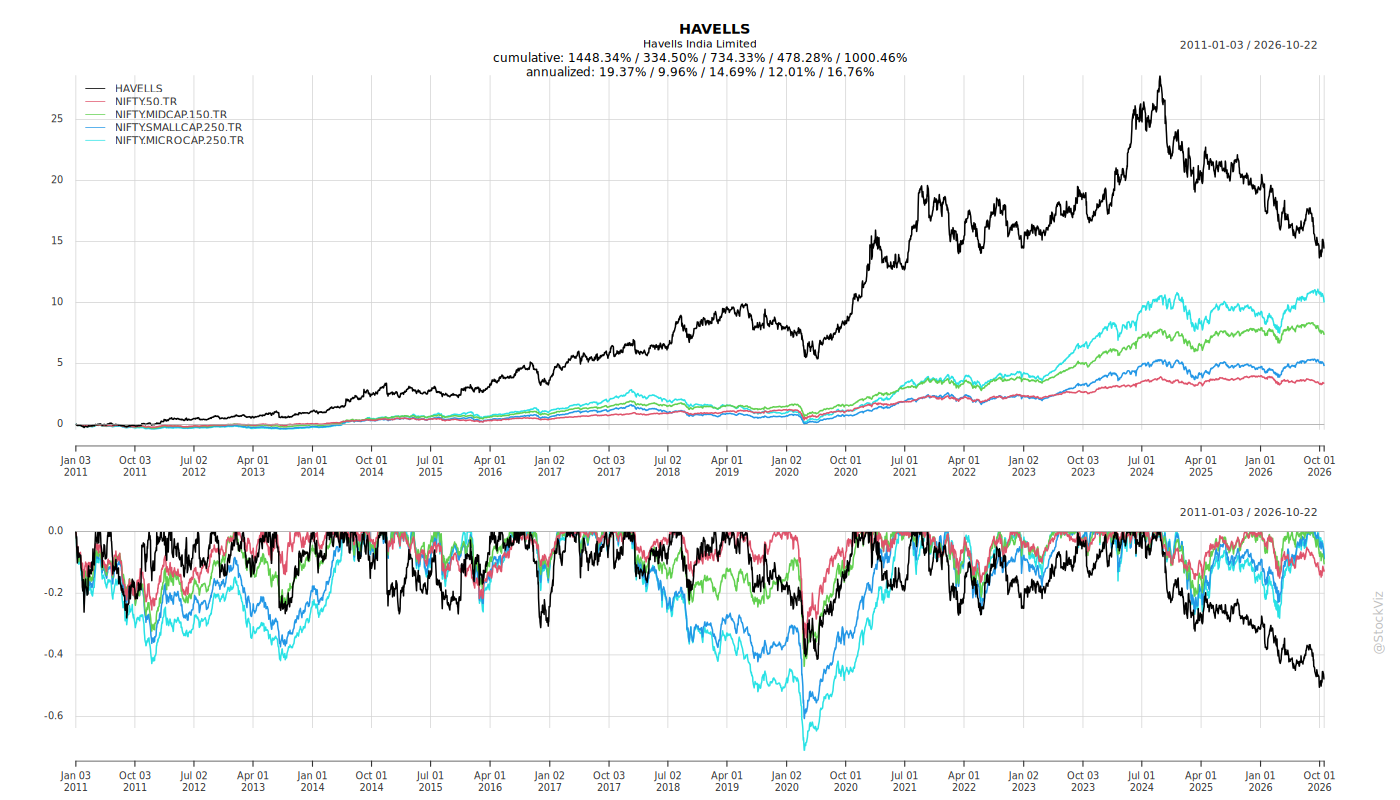
Cumulative Returns and Drawdowns
Fundamentals
Ownership
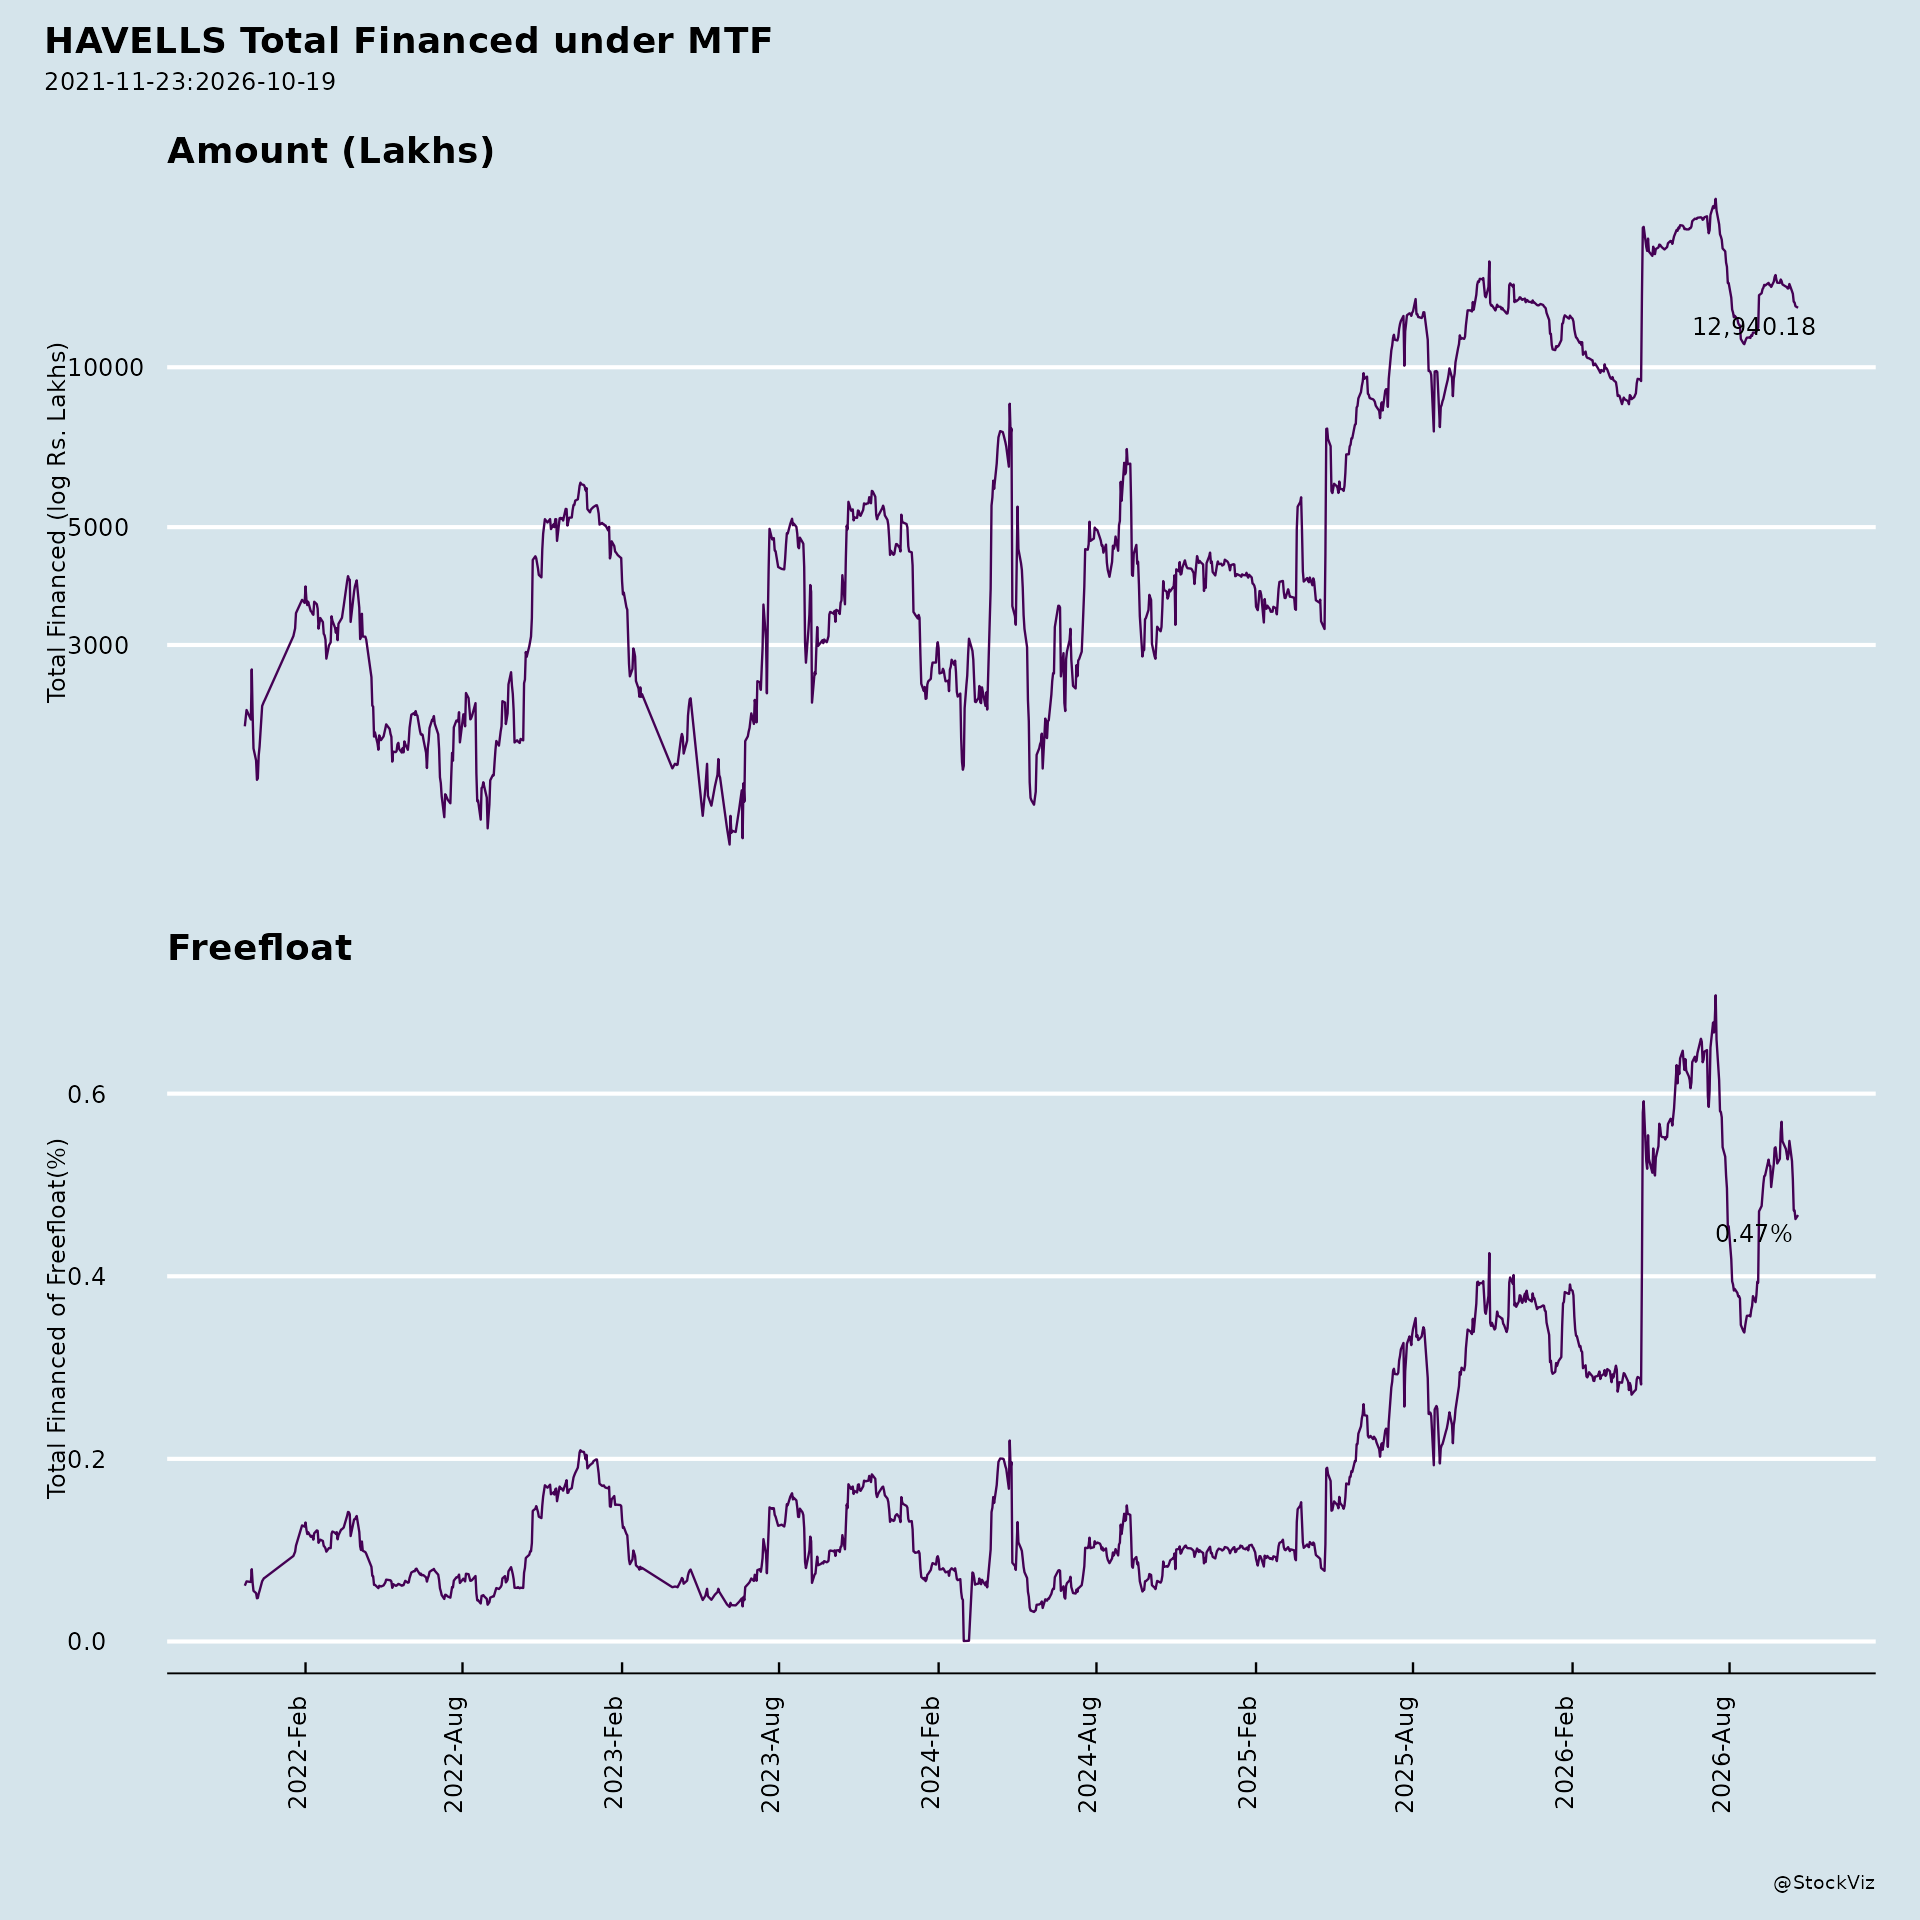
Margined
AI Summary
asof: 2026-09-16
Havells India — Recent Corporate Announcements
1. Headwinds and Challenges
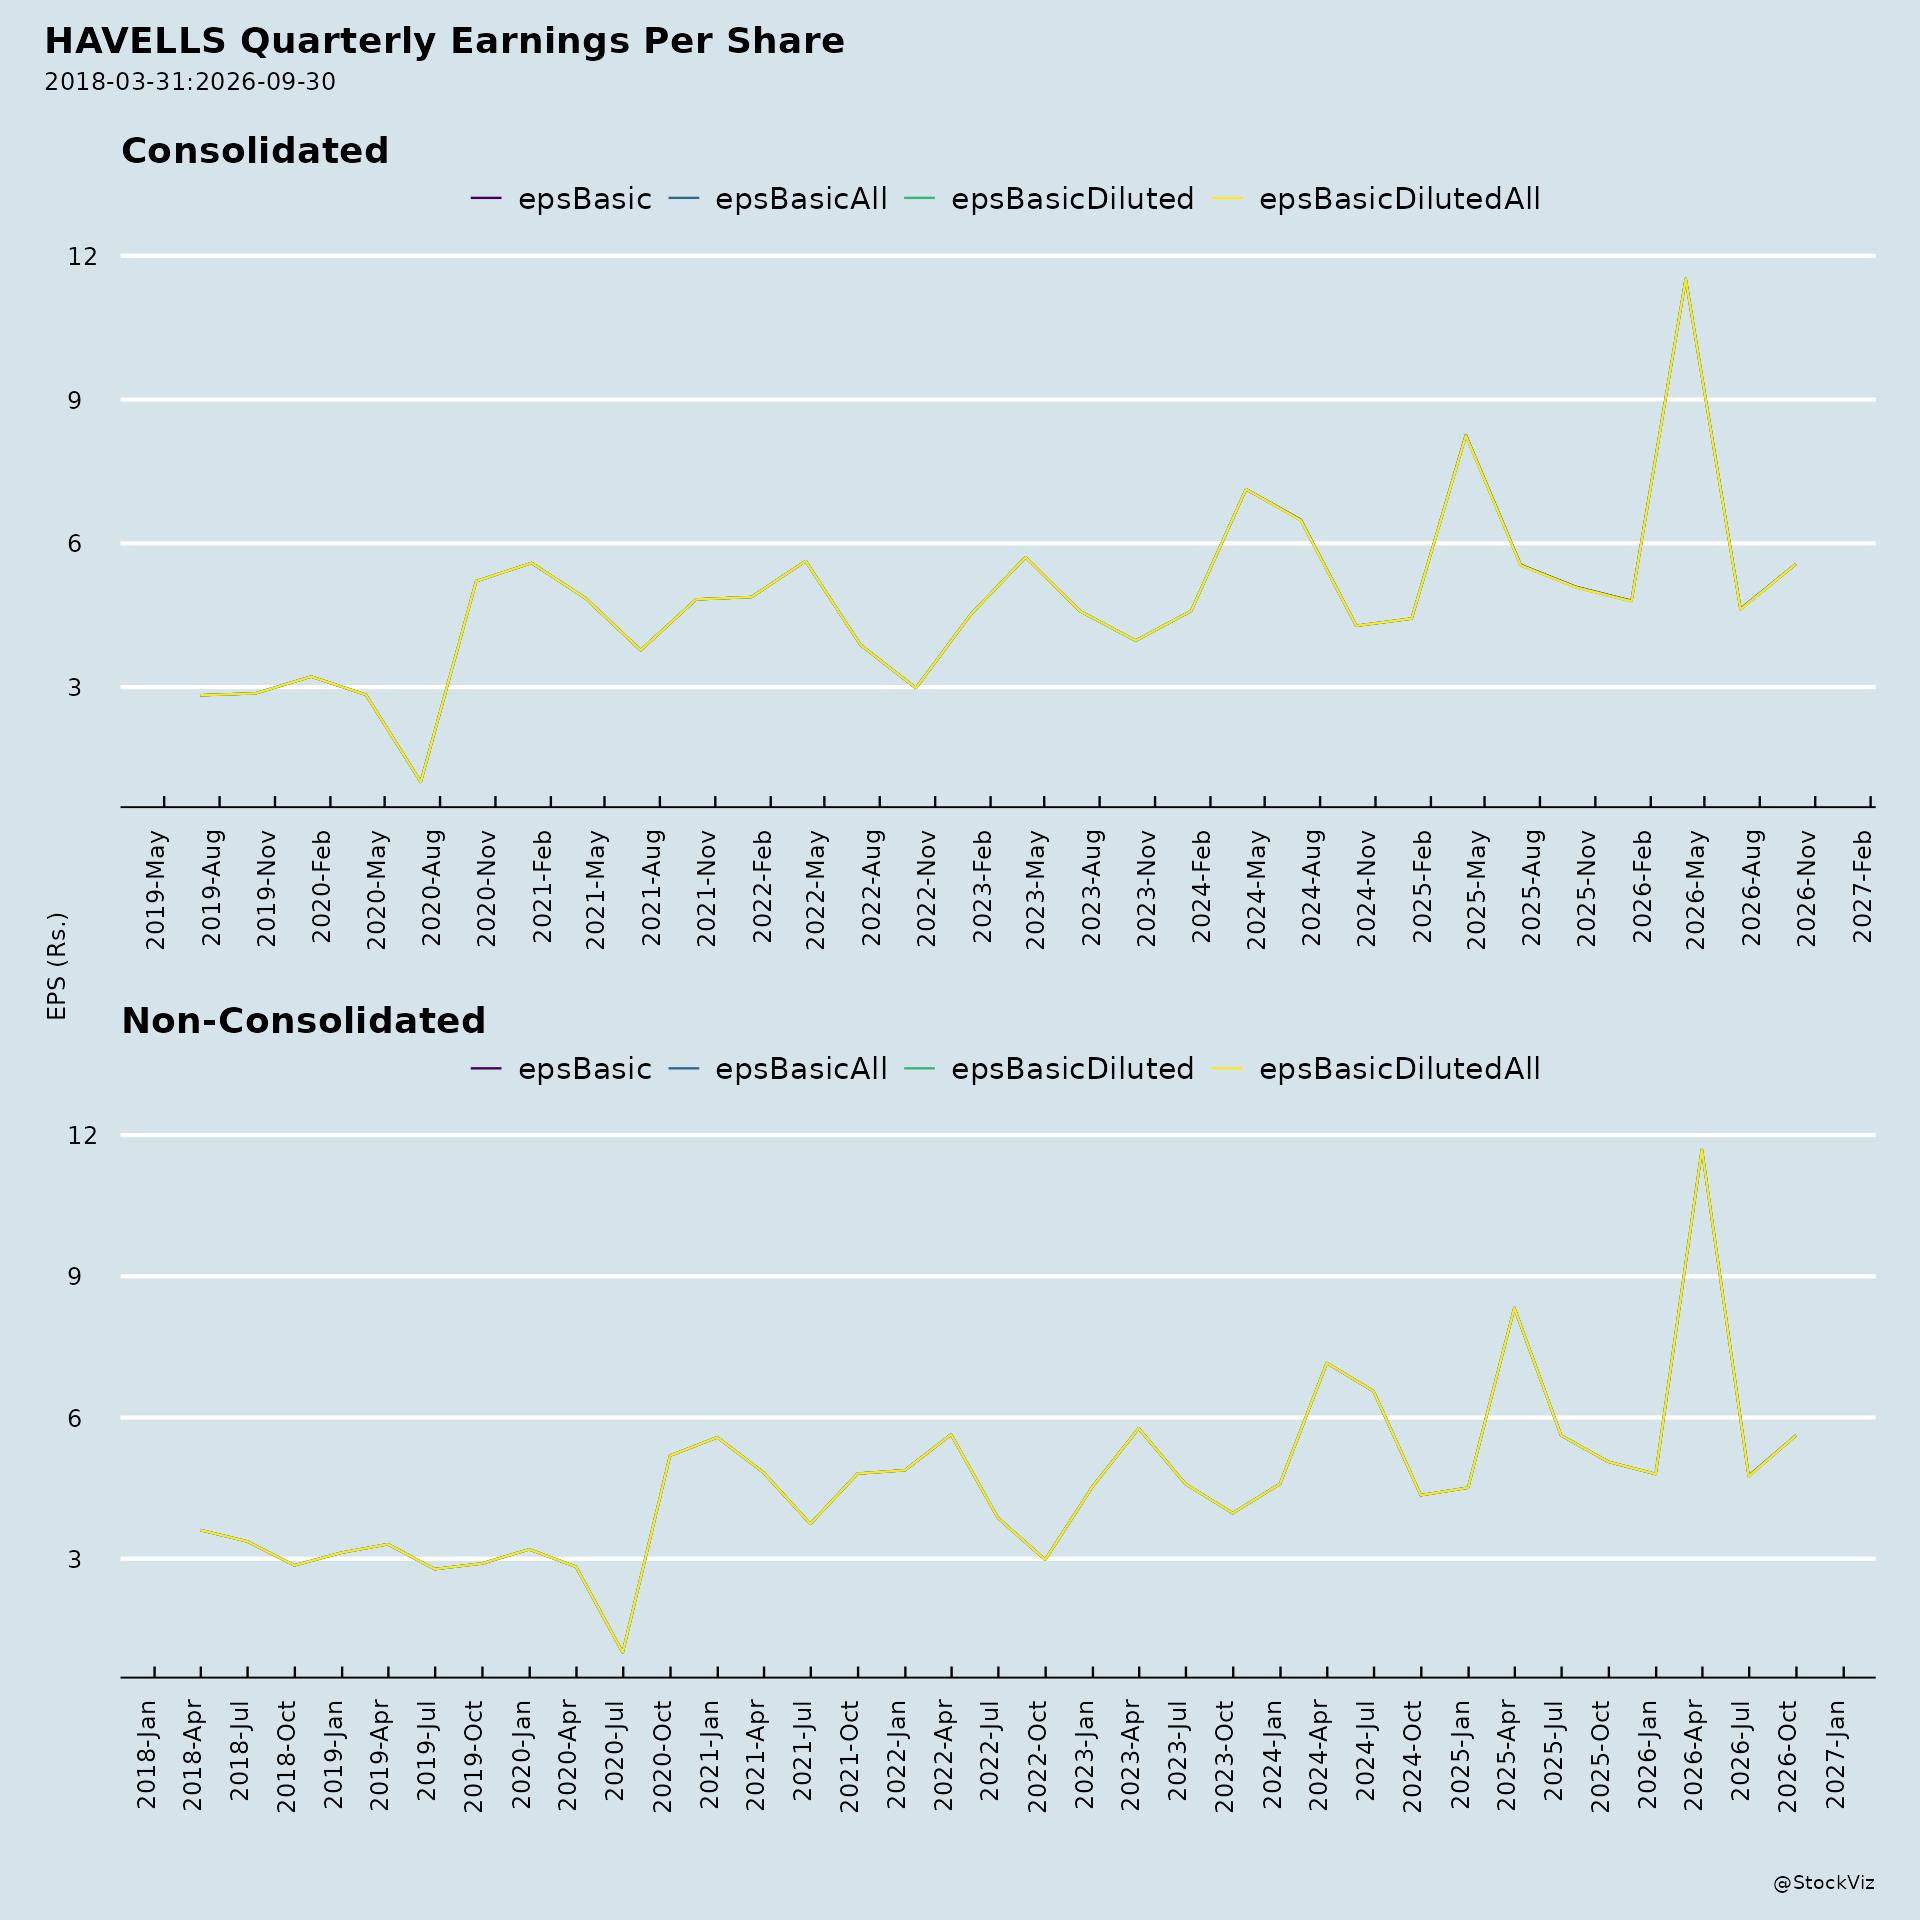
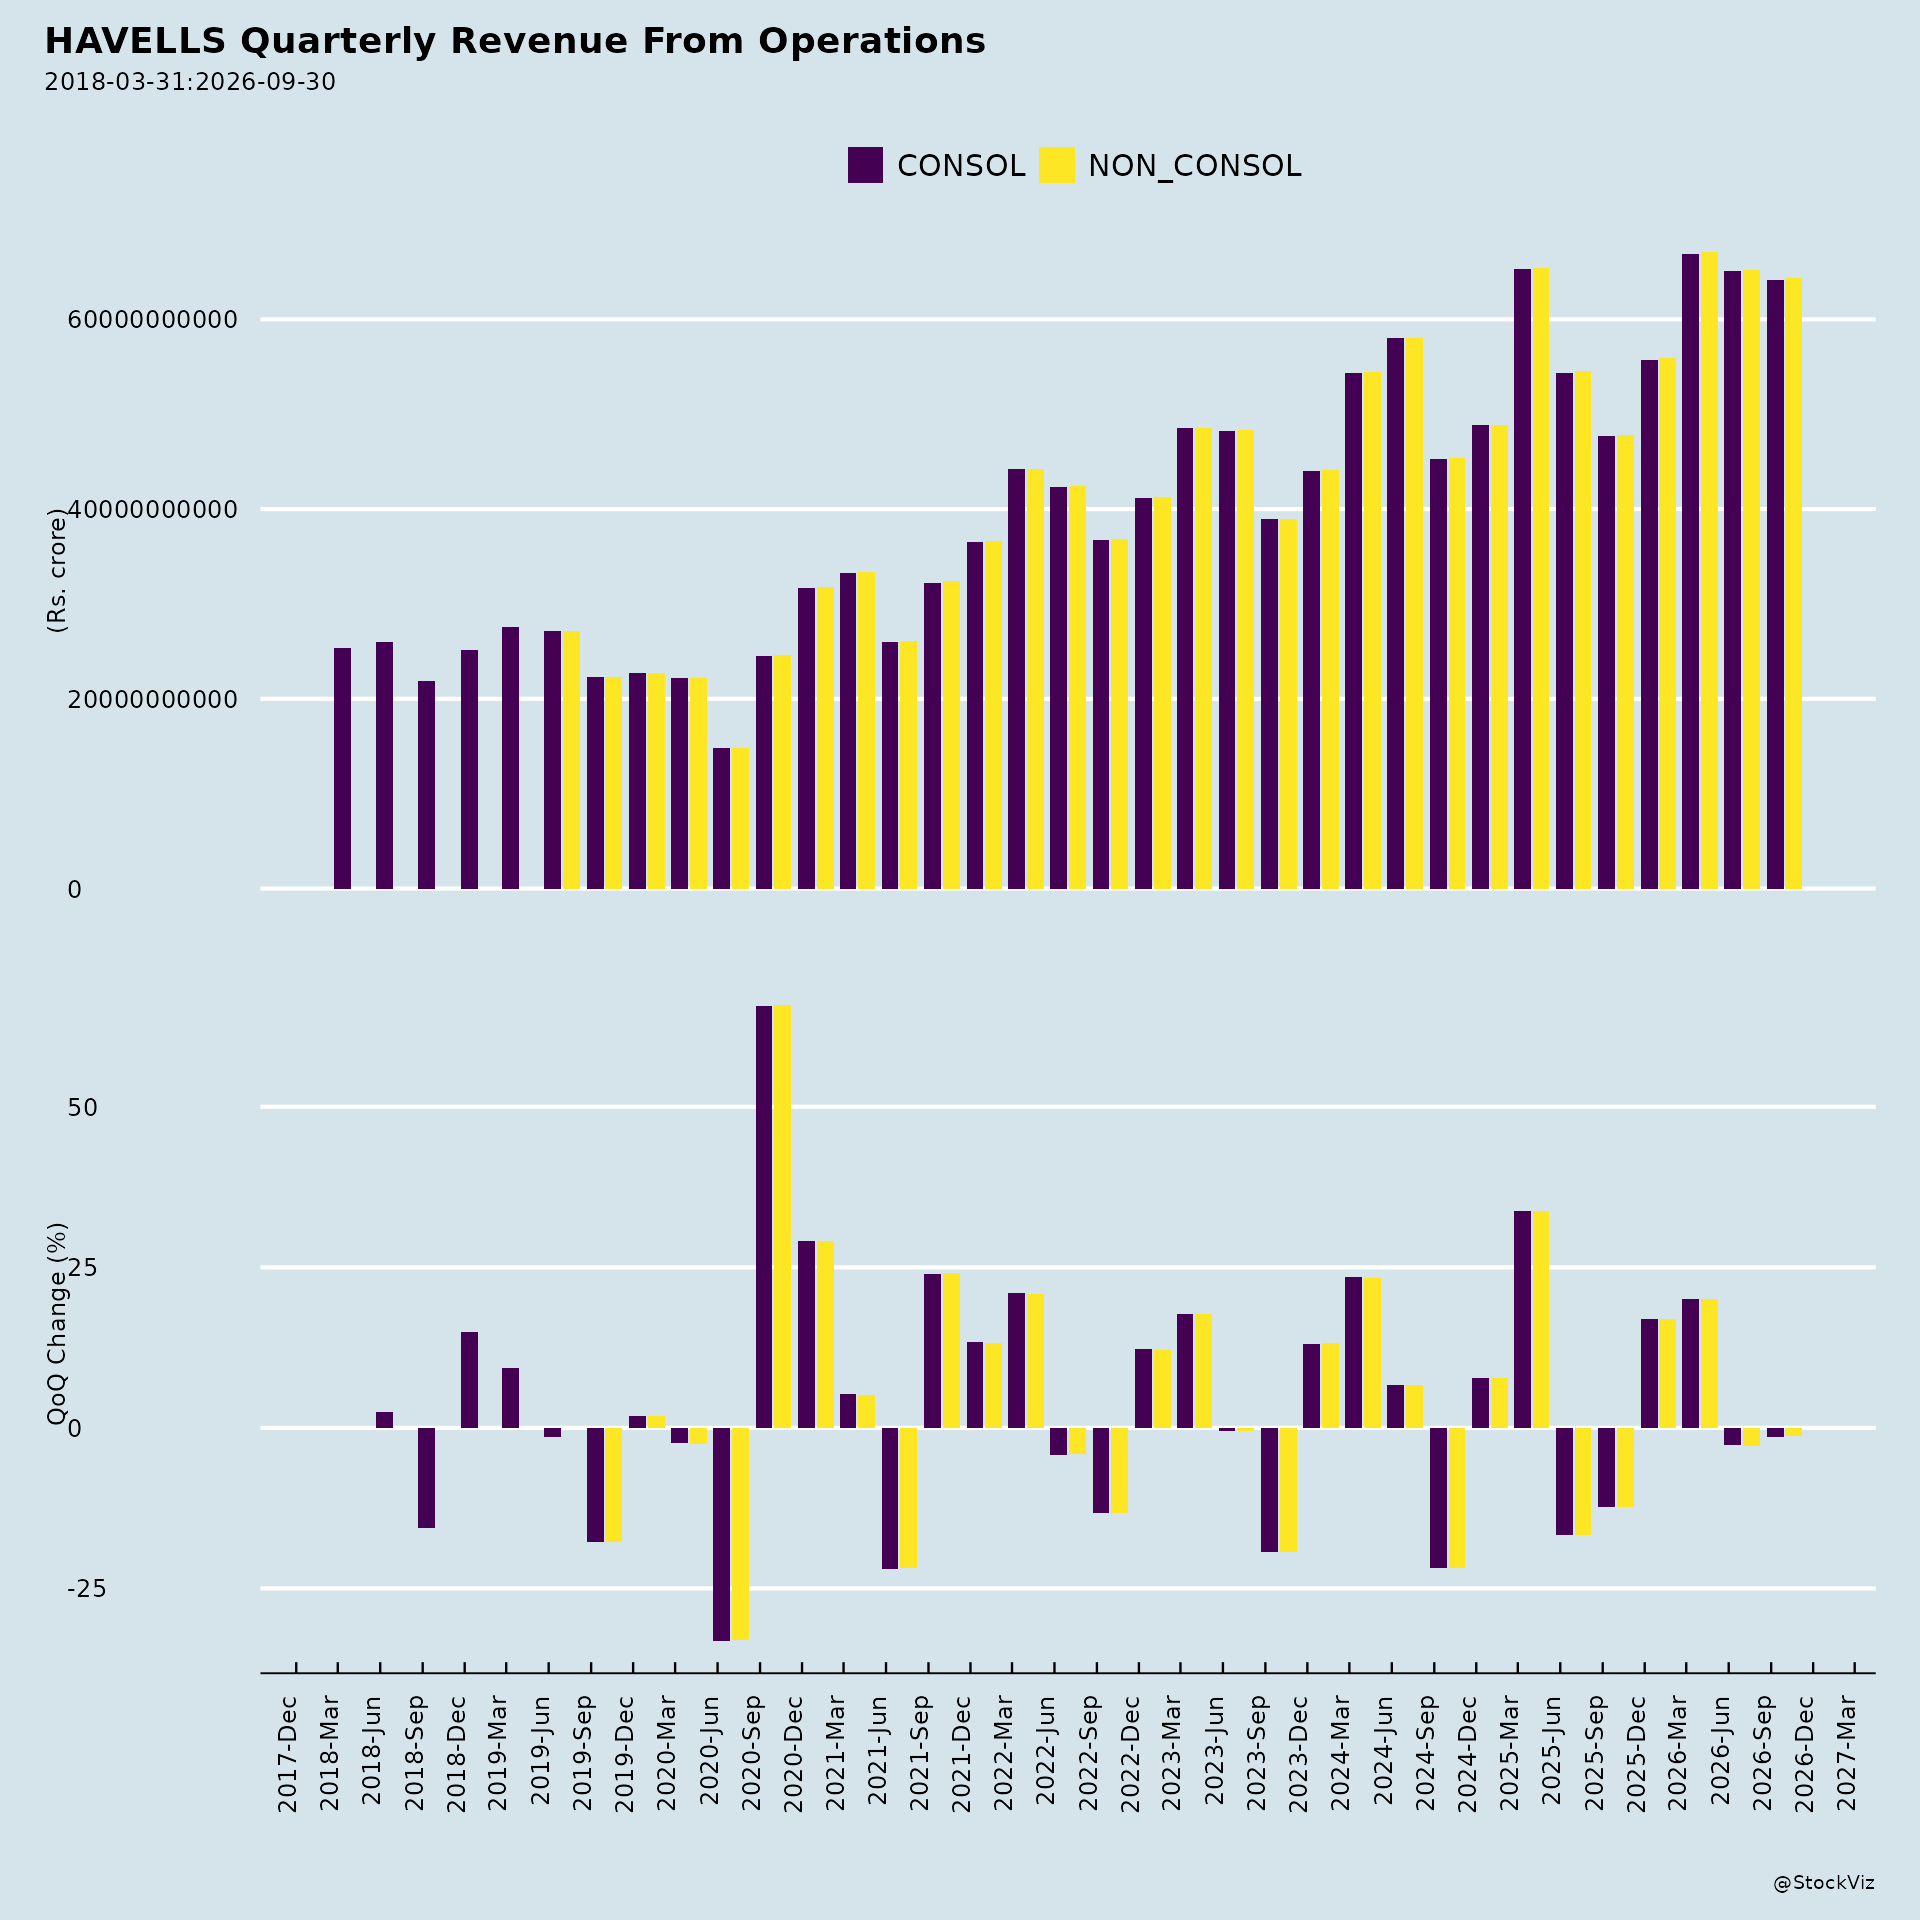
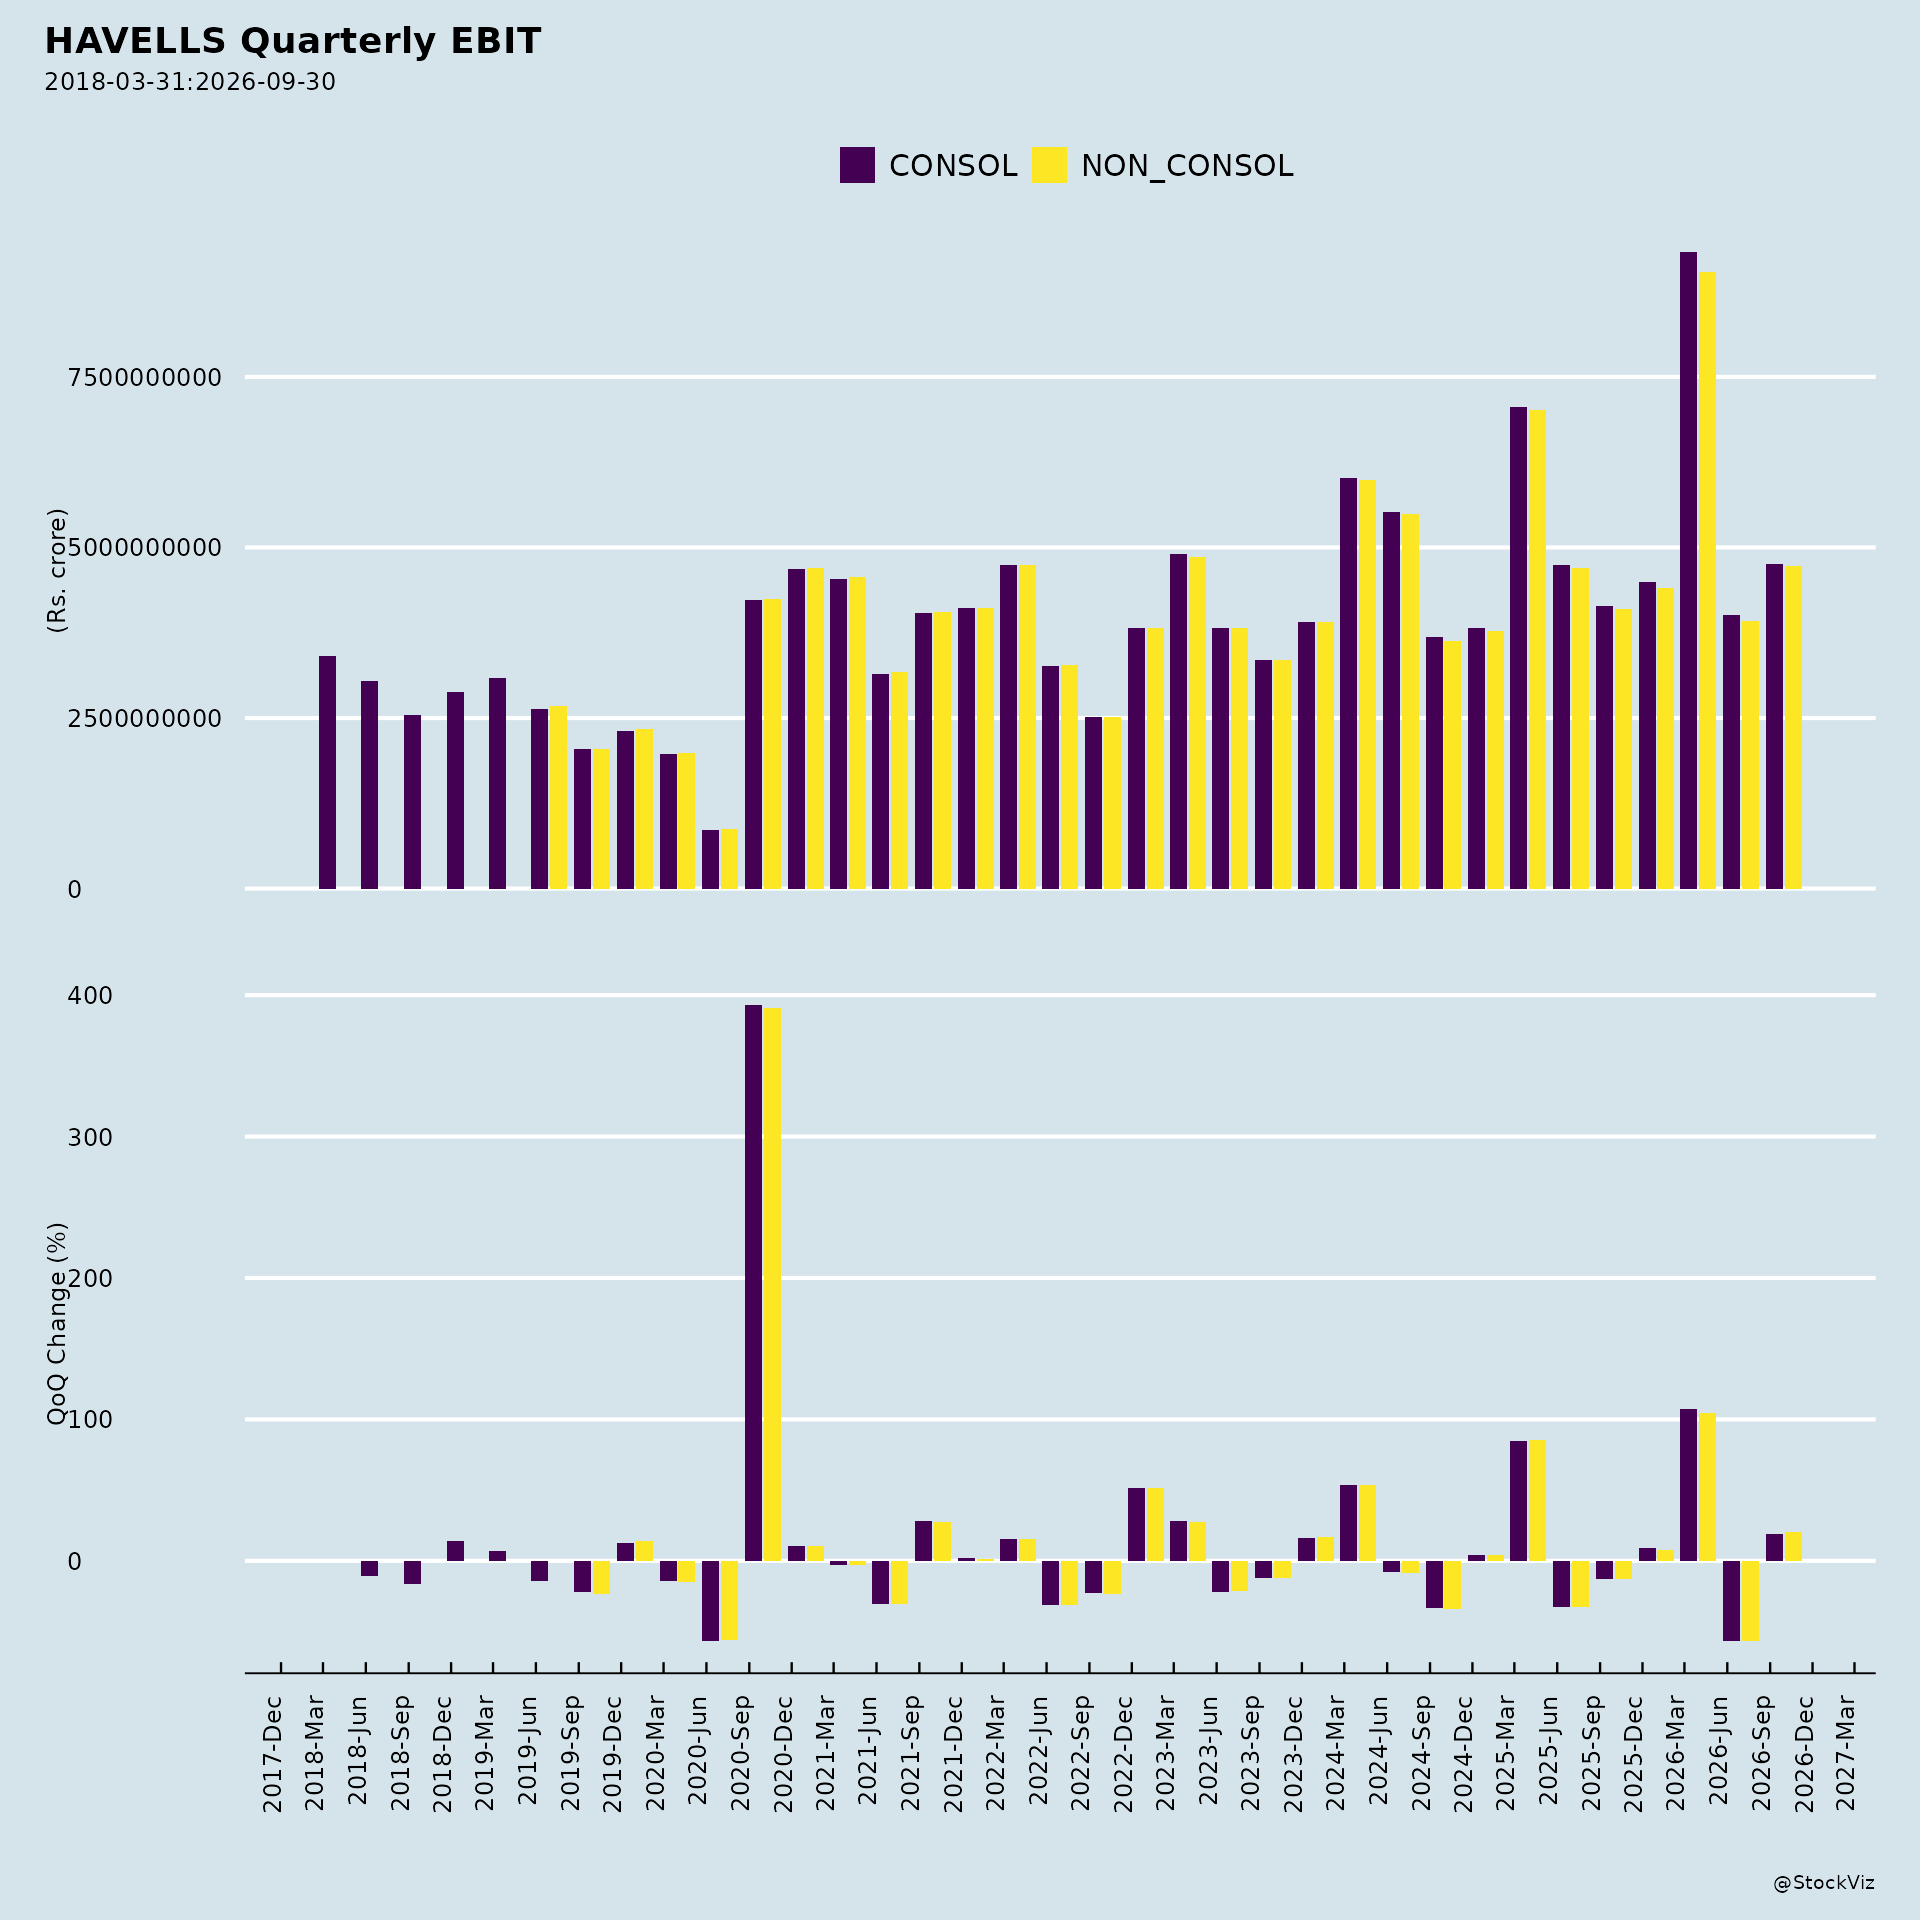
Inflationary pressure and margin compression. Q1 FY27 (quarter ended 30 June 2026) saw net revenue grow 19.7% year-on-year to Rs 6,510 crores, but EBITDA fell 8.8% to Rs 474 crores and PAT declined 15.3% to Rs 298 crores. EBITDA margin contracted to 7.3% from 9.6% a year earlier. The company attributes this to a doubling of advertising and sales promotion spends (Rs 286 crores versus Rs 142 crores, up 100.8%) and to raw material inflation.
West Asia disruption. The results summary notes that demand was resilient “despite inflationary pressures & West-Asia war related uncertainties.” In Switchgears, exports were disrupted by the West Asia situation, and segment revenue declined 3.5% year-on-year to Rs 608 crores.
Delayed summer. Q1 experienced a decent summer, but its delayed onset restricted the full benefit for cooling products.
Renewables margin dilution. The Renewables segment’s contribution margin fell to 8.3% in Q1 FY27 from 21.0% a year earlier, which the company describes as a scale-up stage effect.
Lloyd losses. The Lloyd Consumer segment posted a segment loss of Rs 51 crores in Q1 FY27, wider than the Rs 20 crores loss a year earlier, with contribution margin at 9.2% versus 11.1%.
Working capital and cash flow. Operating net cash flow was negative Rs 186 crores in Q1 FY27. Inventories rose to Rs 5,016 crores from Rs 4,398 crores in March 2026, mainly in Cables. Inventory days increased to 78 from 71 a year earlier, and the current ratio slipped to 1.6 from 1.8.
2. Tailwinds and Growth Prospects
Broad-based revenue growth. Total revenue rose 19.7% year-on-year. Cables grew 27.0% to Rs 2,456 crores; Electrical Consumer Durables grew 12.0% to Rs 1,113 crores; Lighting & Fixtures grew 4.5% to Rs 390 crores; Lloyd grew 15.7% to Rs 1,460 crores; and Others grew 11.0% to Rs 169 crores.
Renewables as a new strategic segment. Effective 1 April 2026, Havells introduced a separate Renewables segment and SBU covering Solar, Solar Pumps, Battery Energy Storage (BESS) and EV Chargers (EVSE). Renewables revenue grew 235.9% year-on-year to Rs 314 crores. The company states the industry is experiencing strong tailwinds and that steady-state contribution margin is expected in the 10–12% range.
BESS collaboration with Pixii AS. On 9 July 2026, Havells announced a strategic collaboration with Norway-based Pixii AS to develop and introduce advanced Battery Energy Storage Systems for India. The MoU covers a phased roadmap: pilot installations to validate commercial opportunities, co-development of an all-in-one storage solution, local manufacturing in India, and co-development of India-tailored solutions. The press release cites India’s residential and C&I BESS market as expected to reach approximately Rs 10–12k crores by FY30, growing at over 100% CAGR over the next three years.
Price actions and normalising spend. Calibrated and staggered price hikes were undertaken across categories to offset raw material inflation, and the company states that the frontloaded Q1 brand-building spend will normalise for the rest of the year, supporting a positive margin outlook.
Segment margin resilience. Contribution margins held well across most categories in an inflationary environment: Switchgears 36.7%, Cables 16.1%, Lighting & Fixtures 31.2%, ECD 24.0%, Others 15.5%.
3. Key Risks
- Raw material inflation and the adequacy of price hikes to offset it.
- Export disruption linked to the West Asia situation, already visible in Switchgears.
- Continued losses in the Lloyd Consumer segment.
- Renewables margin profile during the scale-up phase, with steady-state contribution still expected rather than achieved.
- Elevated advertising and sales promotion spending; profitability depends on this normalising as guided.
- Working capital build-up, particularly inventory in Cables, and negative operating cash flow in the quarter.
- The company’s own disclosure notes that actual results may differ materially from forward-looking statements due to factors including changes in government regulations, tax regimes, economic developments in India and countries where it operates, exchange rate and interest rate movements, competing products and their pricing, and product demand and supply constraints.
4. Management Guidance Versus Observed Performance
A&P spend normalisation. Management states the Q1 step-up in brand-building, led by media investments, “would normalise for the rest of the year,” and that with recent price hikes and normalising A&P spends, “margin outlook remains positive.” Observed Q1 performance shows the opposite direction so far: EBITDA margin at 7.3% versus 9.6% a year earlier, with A&P at 4.4% of net revenue versus 2.6%.
Renewables steady-state margin. Management expects steady-state contribution of 10–12%. Observed Q1 FY27 contribution margin was 8.3%, below that range, against 21.0% in Q1 FY26.
Capex. Full-year capex is expected at Rs 1,400 crores, primarily towards capacity addition in Cables and investment in a new R&D centre. Q1 FY27 capex was Rs 332 crores; FY26 capex was Rs 1,484 crores.
Segment realignment. The company revised reportable segments effective 1 April 2026, carving Solar, Solar Pump and EVSE out of Others and Switchgears into Renewables, and moving Water Purifier and Personal Grooming into Electrical Consumer Durables. Comparative figures have been restated.
Governance. On 19 June 2026 the Board approved the appointment of Shri Ashish Dhawan and Ms Shanti Ekambaram as Additional Directors (Independent) with effect from that date. A postal ballot sought member approval for both as Independent Directors for a first term of five years; e-voting ran from 1 August 2026 to 30 August 2026. Both special resolutions passed.
Investor engagement. Havells is participating in the J.P. Morgan India Conference on 21 September 2026 in Mumbai, with Group and One-on-One physical meetings from 10 am onwards; no unpublished price sensitive information will be shared.
Audit status. The Q1 FY27 standalone and consolidated results were limited reviewed by Price Waterhouse & Co Chartered Accountants LLP, which issued unmodified reports. The consolidated results include four subsidiaries not reviewed by their auditors, reflecting total revenue of Rs 14.21 crores and total net loss after tax of Rs 6.04 crores for the quarter, which management considers immaterial to the Group.
Broker Narrative
The narrative shifted from early-2023 optimism around B-B resilience, softening commodity inflation, and Sri City capacity expansion to sustained skepticism as B-C weakness, Lloyd margin drag, and inventory liquidation delays triggered DISAPPOINTMENTs through 2024. By 2026, the focus moved to competitive intensity and raw material pass-through constraints (copper/forex), with only RAC penetration and e-commerce growth cited as remaining tailwinds. Despite repeated Buy/Accumulate calls, the stock declined continuously from mid-2023 to 2026.
Fears that came true
- Sluggish B-C Demand correlated with sustained negative returns and DISAPPOINTMENTs from late 2023 through 2026.
- Unseasonal Rains & Weak Summer correlated with immediate negative returns in Jul-Aug 2023 (-12.7% to -19.9%).
- Profitability Drag at Lloyd correlated with persistent DISAPPOINTMENTs as margin pressure persisted into 2026.
- RAC Industry Competition & Commodity Volatility correlated with last report’s confirmation of competitive intensity and copper/forex pass-through limits.
- Delayed Inventory Liquidation correlated with Q1FY24 DISAPPOINTMENTs.
Optimism that failed
- Softening Commodity Inflation failed; last report cites higher copper/forex costs as constraint.
- Resilient B-B Demand failed to prevent continuous stock declines through 2024-2026.
- Fan Price Hikes failed to sustain healthy performance; stock fell through 2024-2026.
- Sri City Plant Strategic Expansion failed to deliver margin benefits; profitability drag persisted.
- Lloyd Market Share Gains failed; Lloyd profitability drag remained a headwind.
Broker Timeline
60 broker calls · 2023-06-15 to 2026-09-16
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.