HAL
Equity Metrics
November 18, 2026
Hindustan Aeronautics Limited
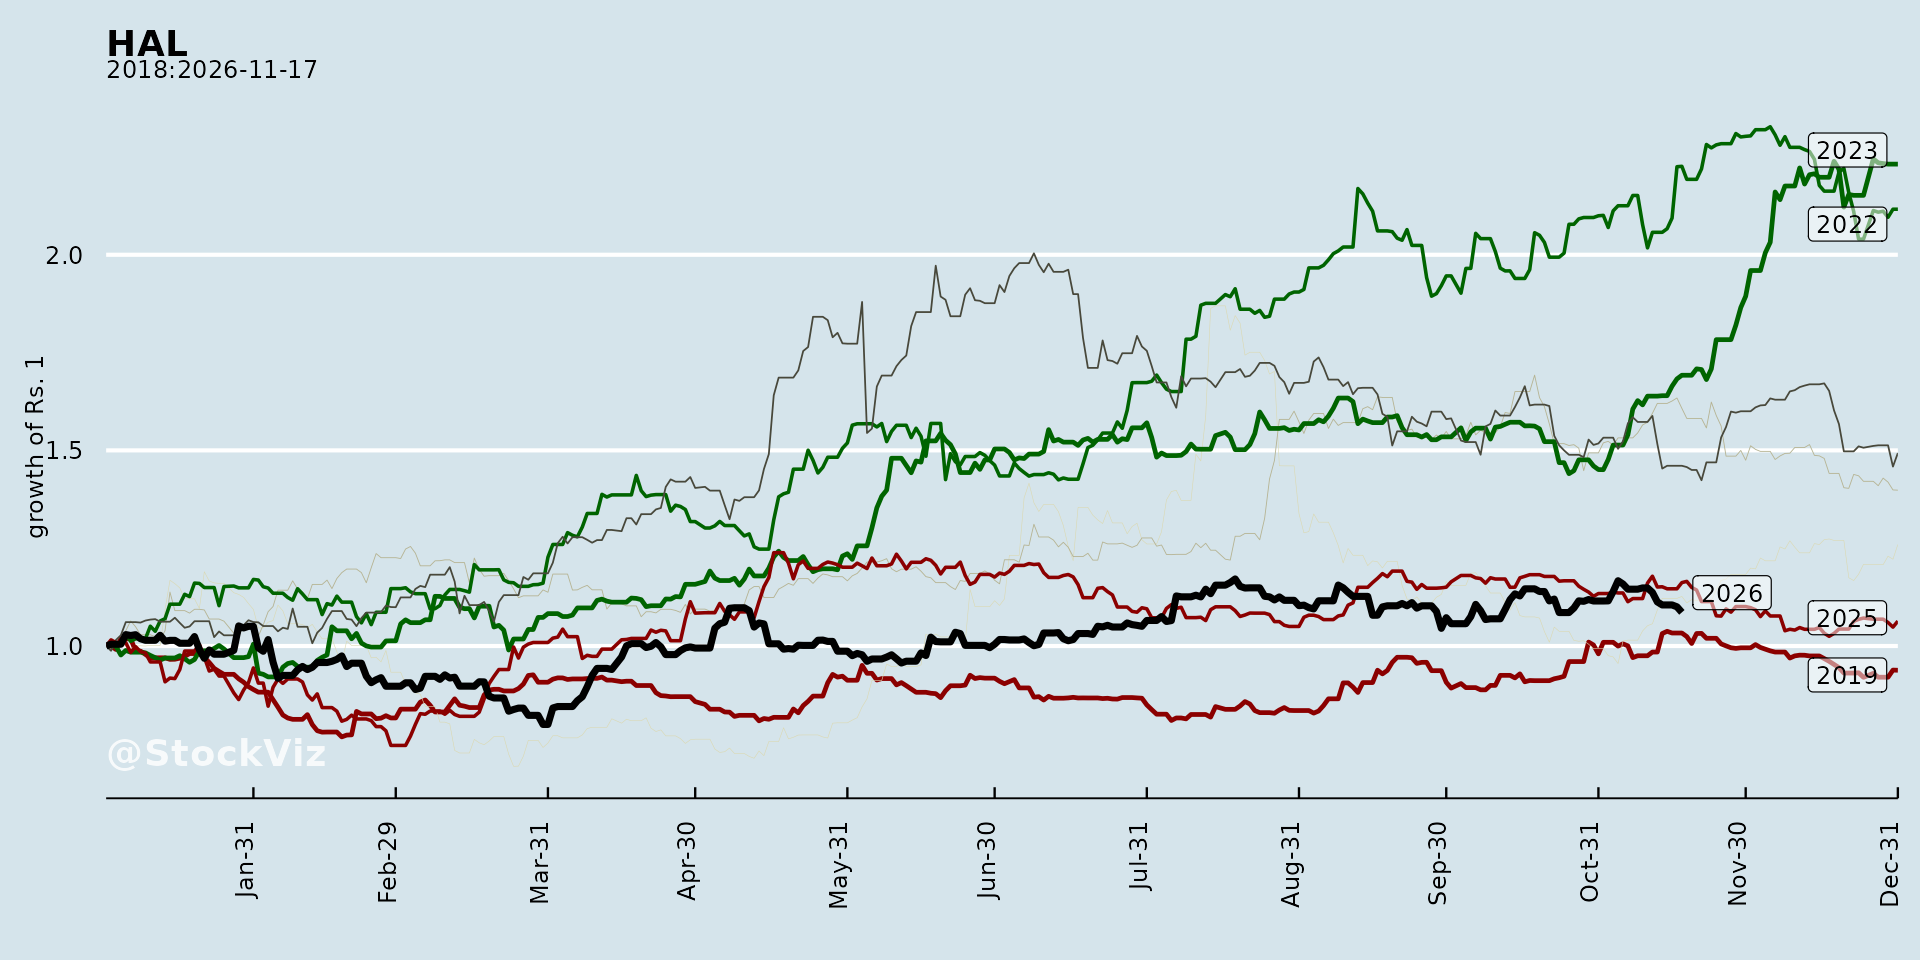
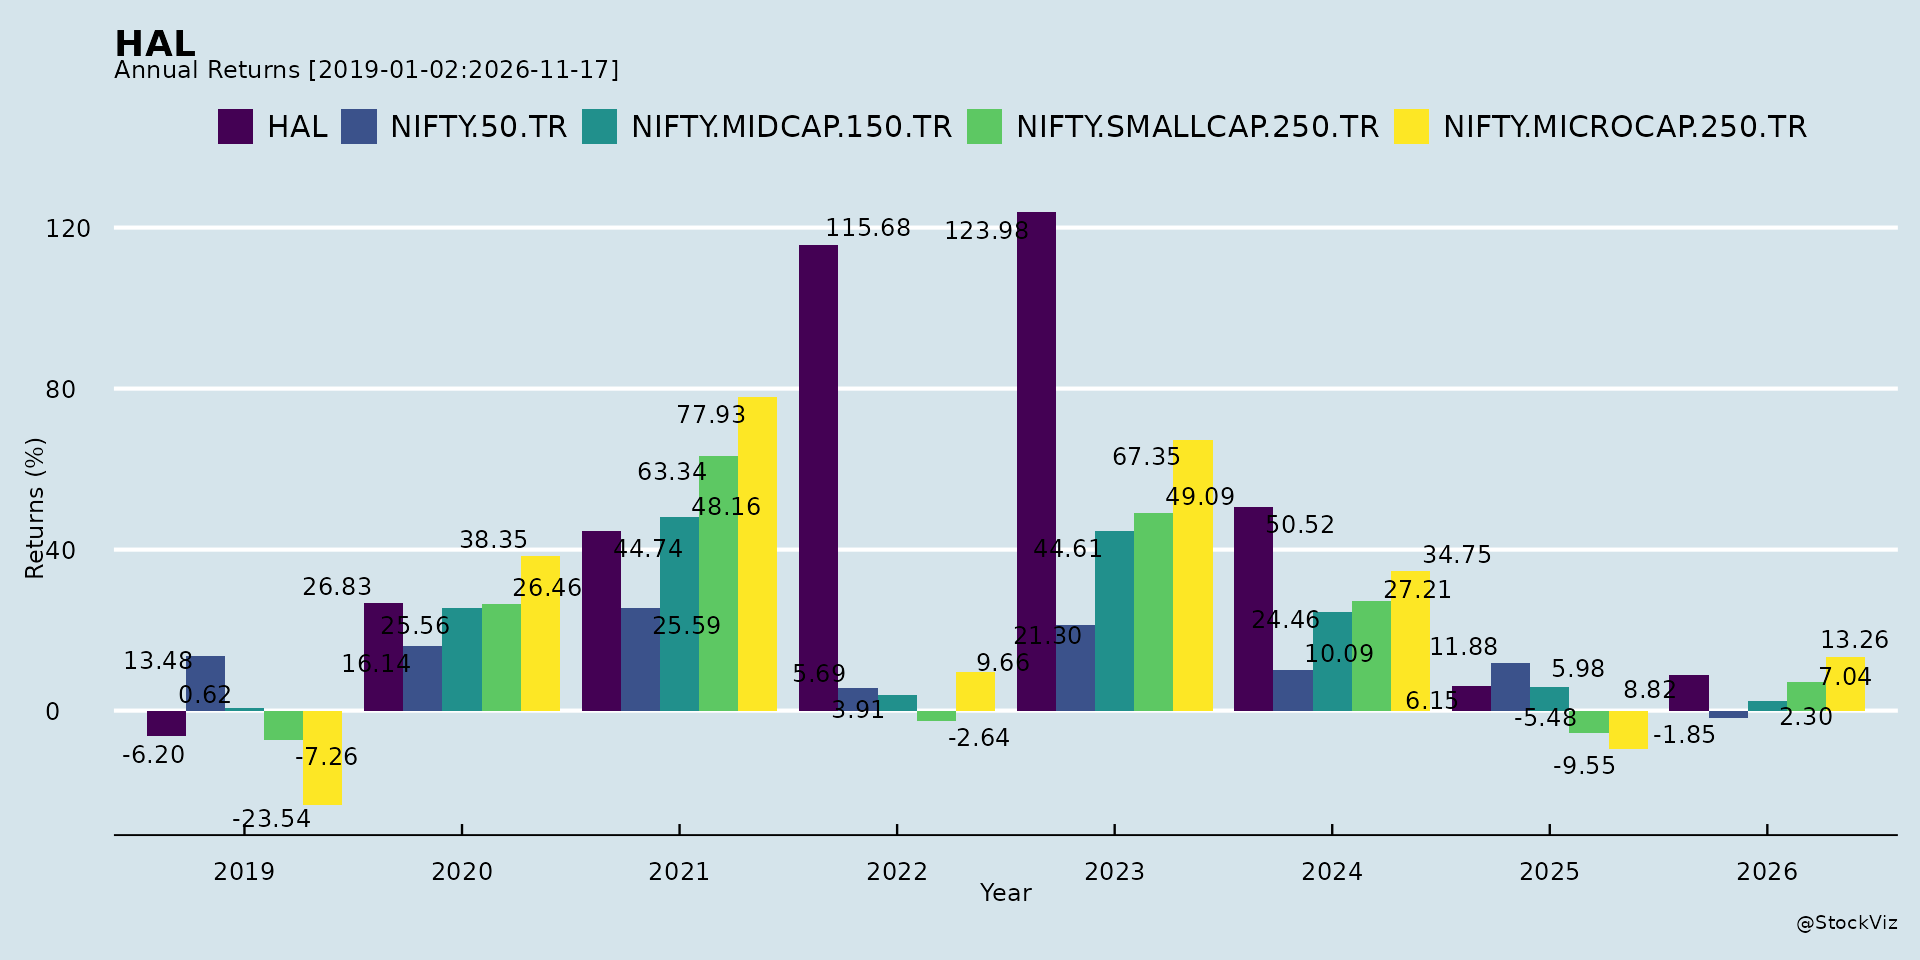
Annual Returns
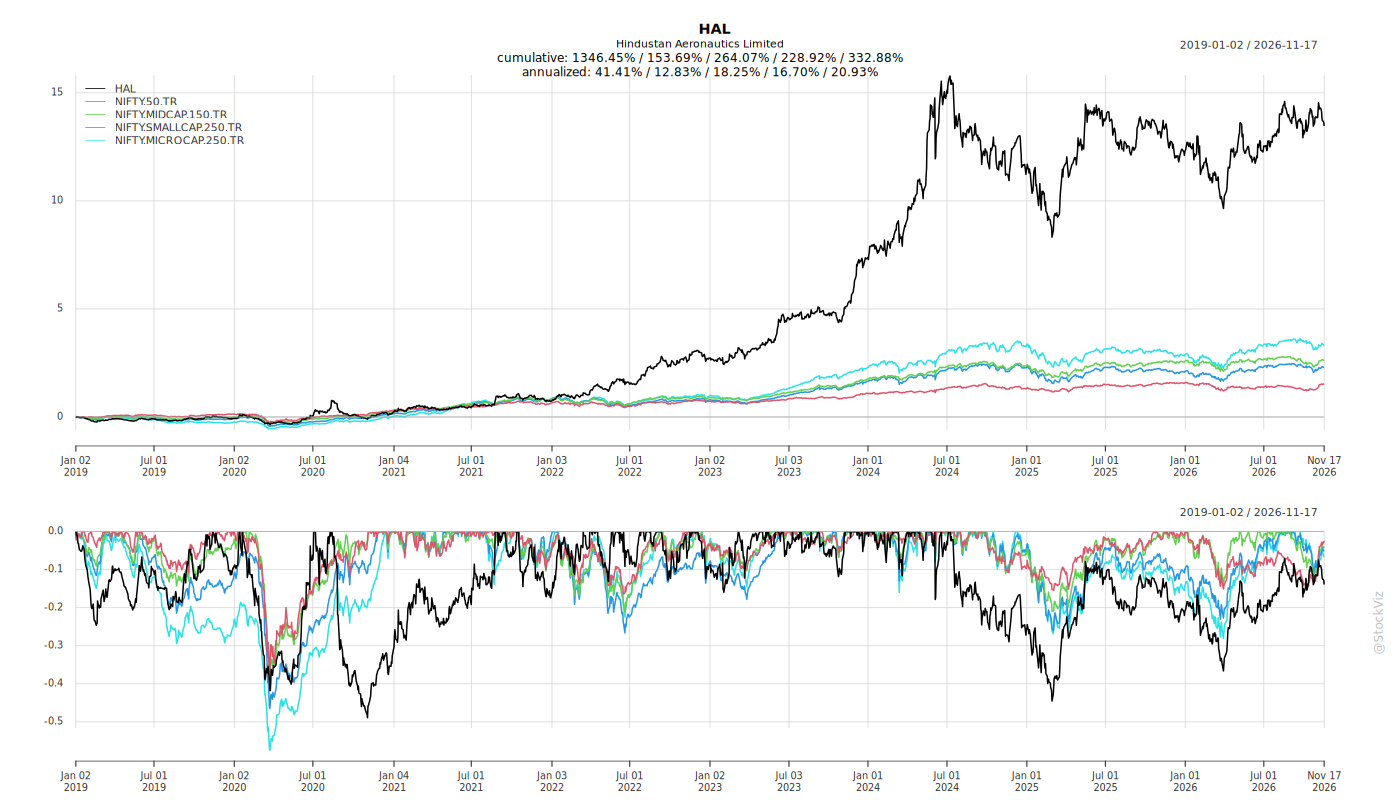
Cumulative Returns and Drawdowns
Fundamentals
Ownership
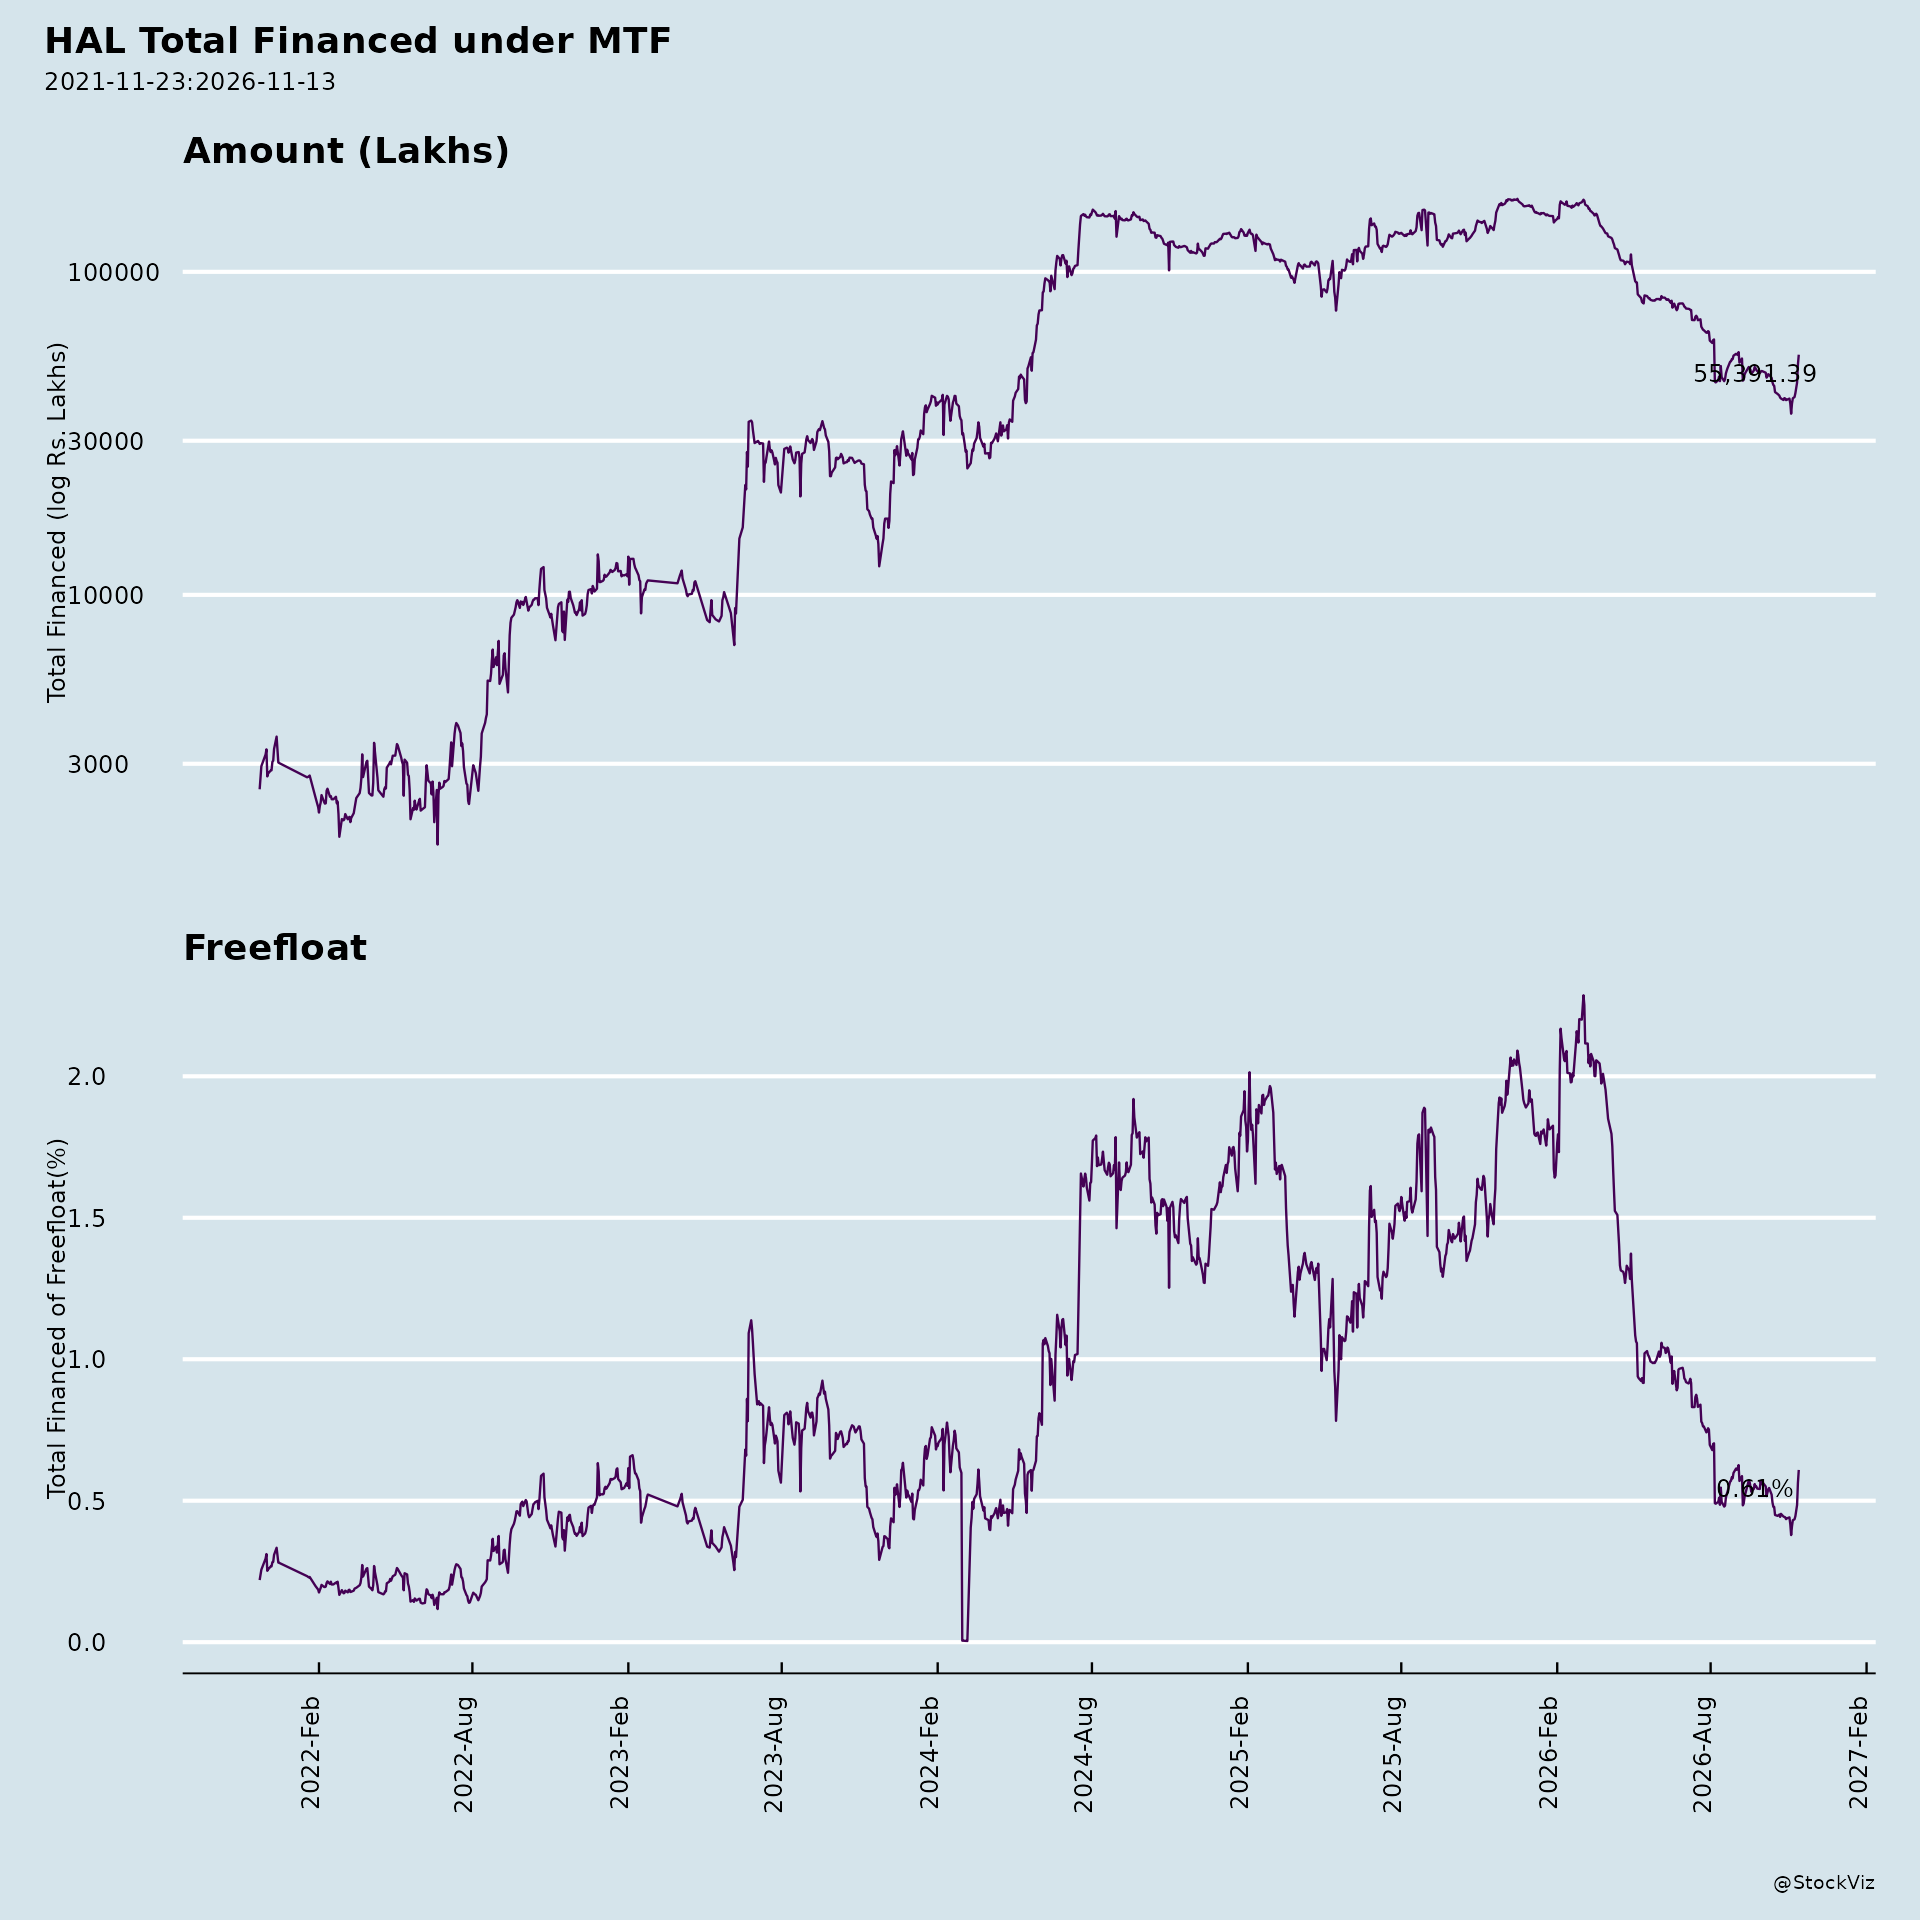
Margined
AI Summary
asof: 2026-09-16
HAL — Recent Corporate Announcements: Analysis
1. Headwinds and Challenges
Pricing uncertainty on FPQ sales. The 4th Pay Revision Committee (PPRC) process remains incomplete, and the existing FPQ (arising out of the 3rd PPRC) is valid only up to 2022-23. Because finalisation has taken more than three years, HAL has provisionally recognised FPQ sales for FY 2025-26 and for the June 2026 quarter using 2024-25 prices, without any escalation. This means reported revenue for the quarter rests on provisional pricing rather than a settled price basis.
Employee cost distortion from gratuity ceiling revision. Following the DPE OM dated 3.8.2017 and the IDA revision to 51.80% effective 01.10.2025 (notified 8.10.2025), the gratuity ceiling rose from Rs. 20 lakh to Rs. 25 lakh. An additional liability of Rs. 32,733 lakh was given effect in the quarter and year ended 31.03.2026, and a further Rs. 237 lakh arose in the quarter ended 30.06.2026 (nil in the comparable prior-year quarter). HAL states employee cost for the June 2026 quarter is therefore not comparable with the corresponding previous quarter and year.
Governance and board composition non-compliance. The auditors draw attention to non-compliance with Regulation 17(1) of the SEBI LODR Regulations and Section 149(4) of the Companies Act, 2013 on the required composition of the Board. Separately, with effect from 5 April 2026, the company was not in compliance with Sections 177 and 178 of the Companies Act and Regulations 18(1) and 19(1) of the LODR Regulations concerning the constitution of the Audit Committee and the Nomination and Remuneration Committee, due to the absence of the requisite number of Independent Directors.
Distressed joint ventures. Several JV disclosures point to financial stress: - HATSOFF Helicopter Training Pvt. Ltd. reported a net profit of Rs. 1,055.68 lakh for the three months ended 30 June 2026, but its current liabilities exceeded current assets by Rs. 8,262.39 lakh, with significant accumulated losses and substantial erosion of net worth. The OEM declared obsolescence of the projector system and stopped product support; replacement requires about INR 28 crore with a 6–8 month lead time. A Military Dhruv Cockpit from CAE Inc. remains undelivered, with USD 4,892,777 paid against a proforma invoice and a revised estimated price of USD 1,36,92,777 quoted in June 2019 that was valid only up to March 2020. - HALBIT Avionics Pvt. Ltd. had a net liability of Rs. 1,146.11 lakh and net current liability of Rs. 1,221.72 lakh as on 30 June 2026, indicating an uncertainty that may cast doubt on its ability to continue as a going concern. - Multirole Transport Aircraft Ltd. — the Board in its 47th meeting on 09 February 2023 accorded in-principle approval for voluntary liquidation, subject to Government of India approval and other steps. - Infotech HAL Limited — the NCLT Bangalore Bench order dated 22 August 2025 admitted its Section 10 petition under the IBC, 2016, commenced the corporate insolvency resolution process, and appointed an Interim Resolution Professional. - HAL-Edgewood Technologies Pvt. Ltd. did not prepare financial statements for the three months ended 30 June 2026 and was not consolidated; the impact is stated as not material. The Board had accorded in-principle approval for its voluntary winding up in its 406th meeting on 22 September 2017.
Flood-related inventory liability. Inventory at the LCA TD store was damaged in a September 2022 flood. For customer-owned items, the loss was reassessed from Rs. 5,590 lakh to Rs. 1,091 lakh, with the excess provision of Rs. 4,499 lakh reversed by 31 March 2026; a provision of Rs. 1,091 lakh is being maintained as a future liability.
2. Tailwinds and Growth Prospects
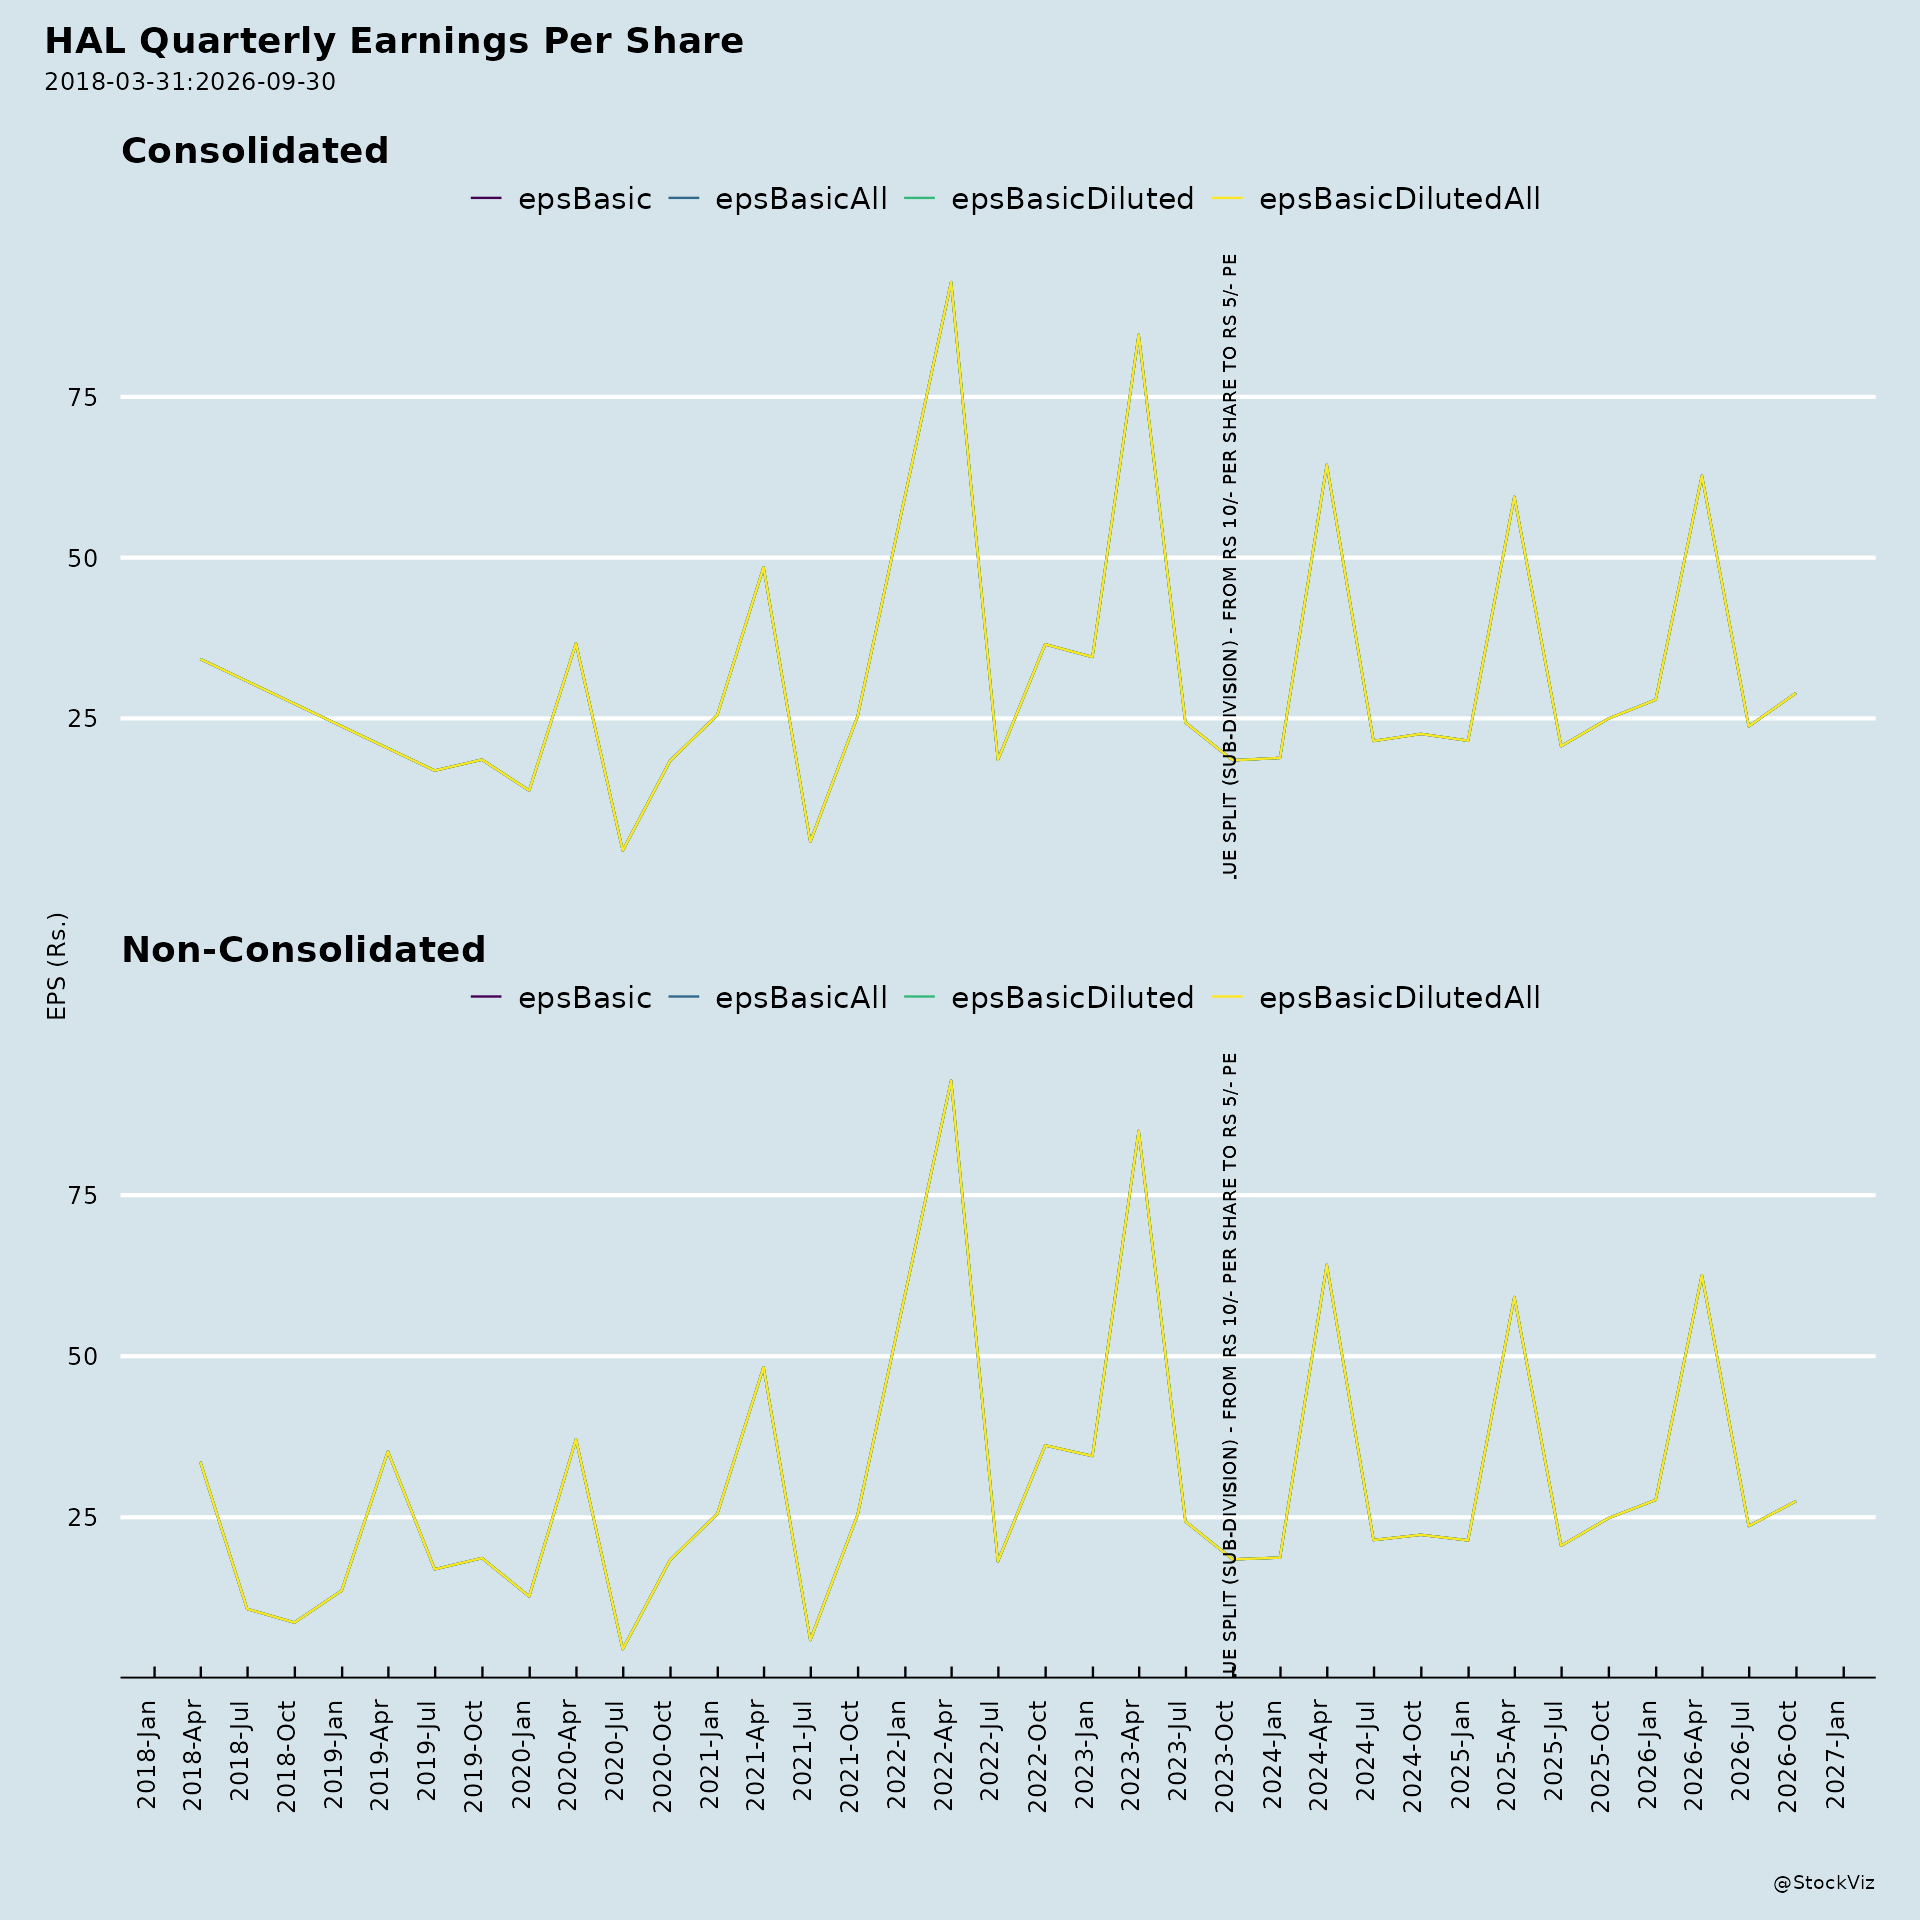
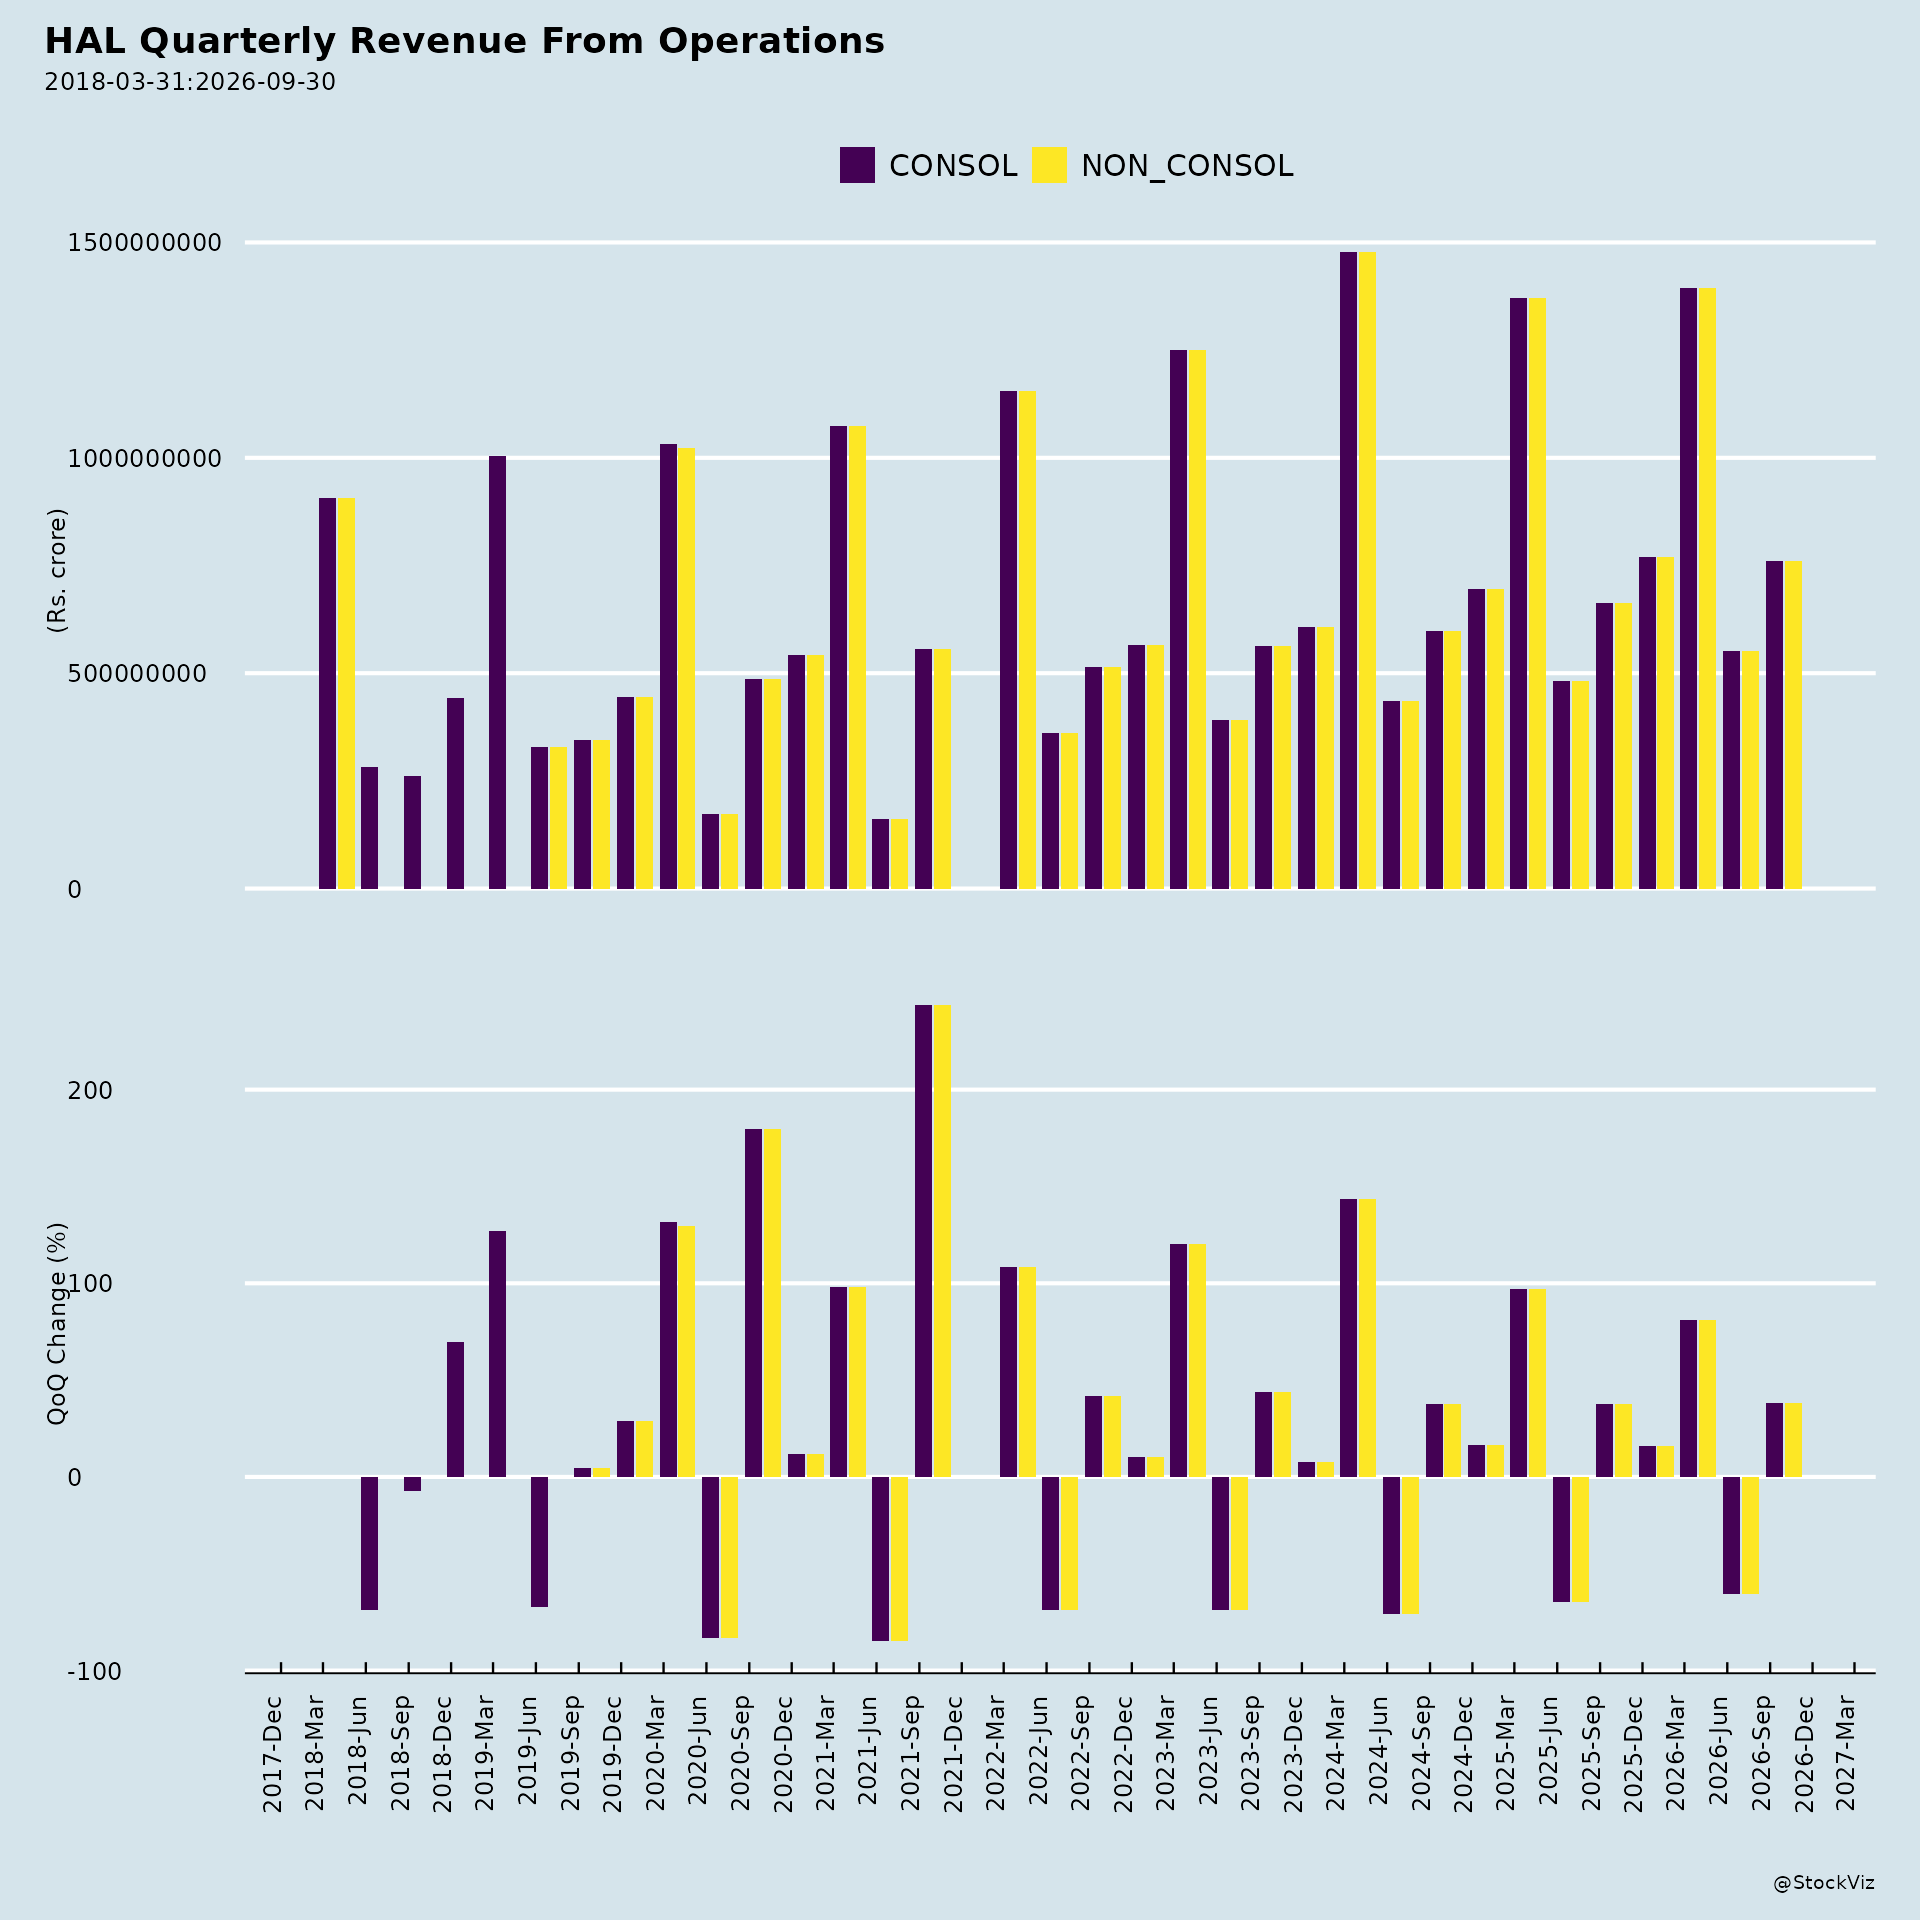
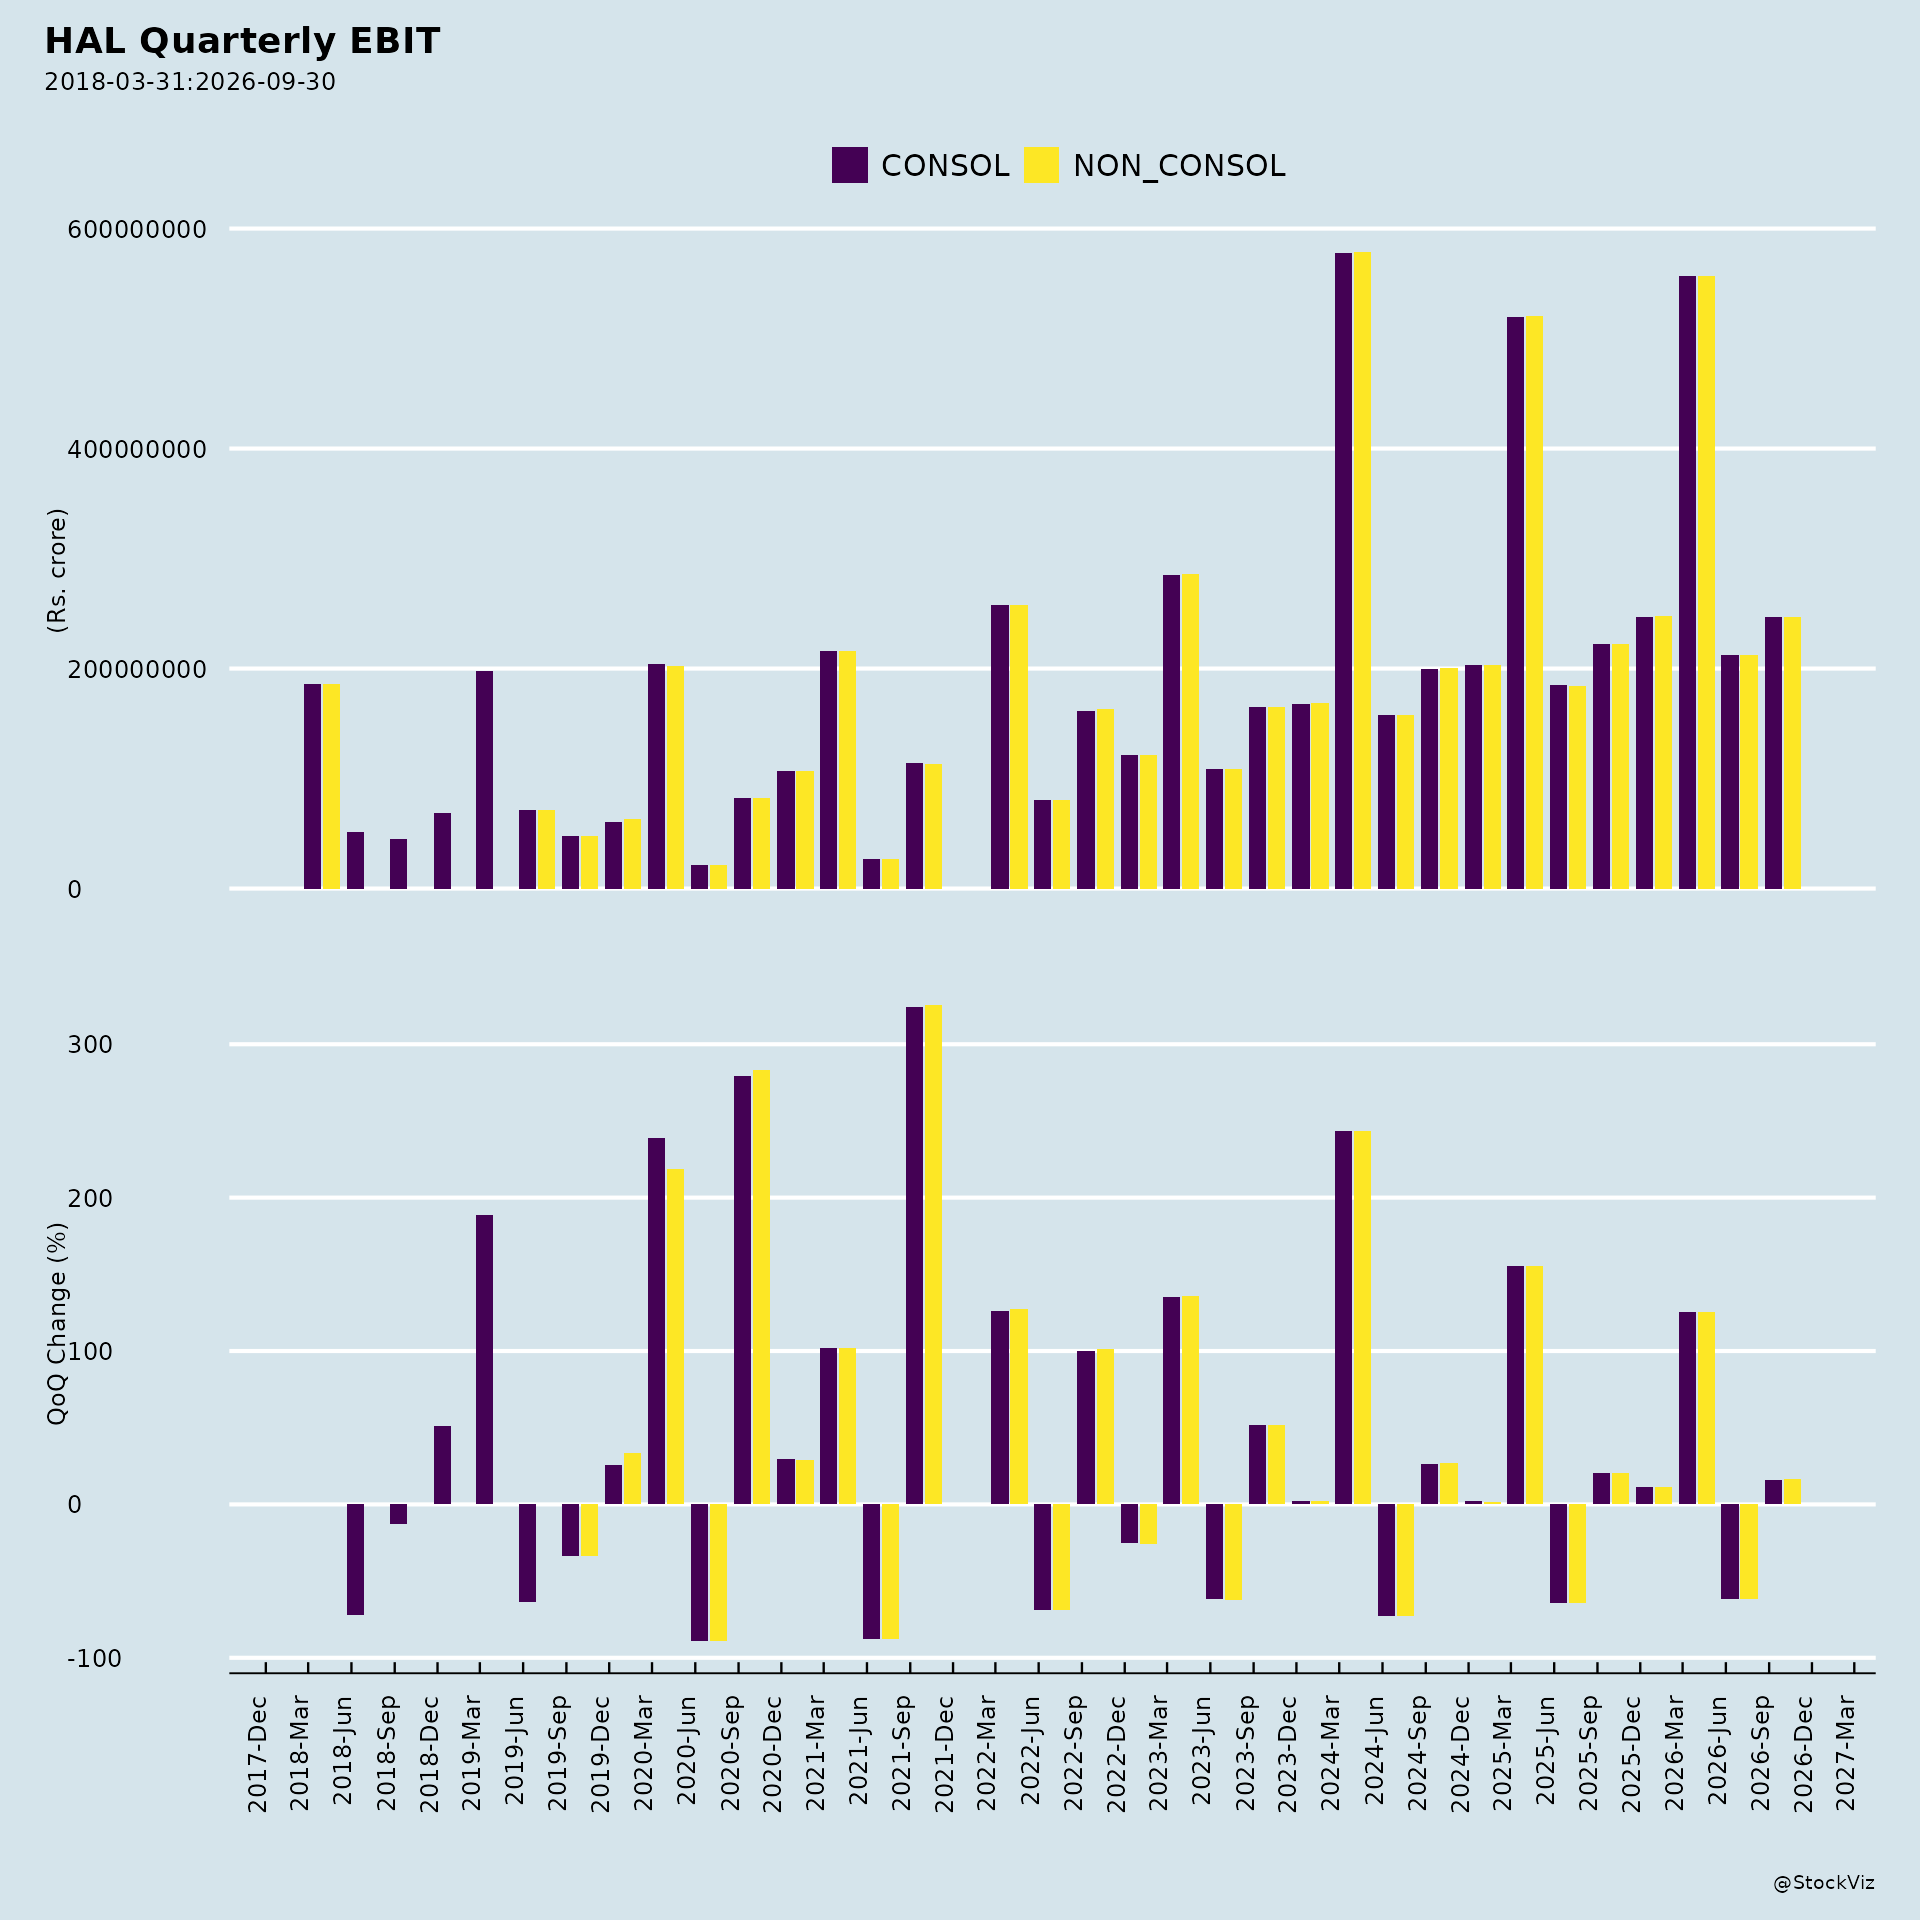
Revenue and profit growth year-on-year. Standalone revenue from operations rose to Rs. 5,51,528 lakh in the quarter ended 30 June 2026 from Rs. 4,81,914 lakh in the quarter ended 30 June 2025. Standalone net profit rose to Rs. 1,58,061 lakh from Rs. 1,37,715 lakh, and standalone EPS rose to Rs. 23.63 from Rs. 20.59. Consolidated net profit rose to Rs. 1,58,966 lakh from Rs. 1,38,377 lakh, with consolidated EPS at Rs. 23.77 versus Rs. 20.69.
JV contribution to consolidated results. Share of profit of joint ventures accounted using the equity method was Rs. 1,161 lakh in the June 2026 quarter, up from Rs. 1,028 lakh a year earlier.
Dividend track record. The Board approved and paid an interim dividend of Rs. 35 per equity share (700% of face value of Rs. 5) during 2025-26, and on 29 June 2026 recommended a final dividend of Rs. 10 per equity share (200% of face value) for FY 2025-26, subject to shareholder approval at the ensuing AGM.
Multi-year defence contracts at HATSOFF. Among the factors cited in support of HATSOFF’s going-concern basis is that the company has been able to secure multi-year contracts from the Defence forces with increased training hours.
Investment in advanced materials research. HAL invested Rs. 245 lakh (245,000 equity shares of Rs. 100 each) in “Systems Testing and Research for Advanced Materials Foundation,” incorporated as a Section 8 company on 18 September 2024. As at 30 June 2026, 200,000 shares had been allotted, with allotment of 45,000 shares awaited.
Clean audit opinion. The Statutory Auditors, M/s. Gupta Nayar & Co., issued an unmodified opinion on both the standalone and consolidated audited financial results for the quarter ended 30 June 2026.
3. Key Risks
- Provisional revenue recognition. Continued delay in 4th PPRC finalisation means FPQ sales for FY 2025-26 and Q1 FY 2026-27 are recognised at 2024-25 prices without escalation, leaving revenue subject to revision once prices are firmed up.
- Going-concern uncertainties at JVs. HATSOFF and HALBIT Avionics both carry disclosures indicating conditions that may cast doubt on their ability to continue as going concerns, though management has prepared their financial statements on a going-concern basis citing board affirmation, multi-year contracts, banker discussions, promoter funding ability, and phased liability liquidation.
- Insolvency and liquidation exposure. Infotech HAL Limited is under corporate insolvency resolution following the NCLT order of 22 August 2025; Multirole Transport Aircraft Ltd. and HAL-Edgewood Technologies Pvt. Ltd. have in-principle approvals for voluntary winding up/closure.
- Board and committee compliance gaps. Non-compliance with board composition requirements and, from 5 April 2026, with audit and nomination/remuneration committee constitution requirements, represents a regulatory and governance risk.
- Obsolescence and supply-chain exposure at HATSOFF. OEM-declared obsolescence of the projector system, cessation of product support, and unresolved pricing/delivery negotiations with CAE Inc. create operational and cost-escalation risk.
- Residual flood liability. A provision of Rs. 1,091 lakh for flood-affected customer-owned inventory is maintained as a future liability.
4. Management Guidance Versus Observed Business Performance
The source material does not contain forward financial guidance (such as revenue or margin targets) against which performance can be compared. The observable guidance-type statements and their accompanying evidence are:
- FPQ pricing stance. Management states that, on a conservative basis, 2024-25 prices have been considered for FY 2025-26 and June 2026 without any escalation, pending 4th PPRC finalisation. Observed performance reflects this: Q1 FY 2026-27 standalone revenue of Rs. 5,51,528 lakh and consolidated revenue of Rs. 5,51,517 lakh are recognised on this provisional basis.
- Gratuity liability guidance. Management quantified the additional liability from the higher gratuity ceiling at Rs. 32,733 lakh for the quarter and year ended 31.03.2026, and Rs. 237 lakh for the quarter ended 30.06.2026. Both figures are reflected in the reported results, with the June 2026 quarter’s employee cost explicitly flagged as not comparable to the prior-year quarter.
- Going-concern assertions at JVs. Management’s position that HATSOFF and HALBIT Avionics remain going concerns is supported in the disclosures by specific factors — board affirmation of ability to meet obligations, multi-year defence contracts with increased training hours, ongoing discussions with ICICI Bank, ECB principal repayment of Rs. 500 lakh during the reporting period (prior year Rs. 7,668.79 lakh), interest serviced up to 04 September 2023, and positive operating cash flows at HALBIT. These assertions sit alongside the disclosed negative net worth, net current liability positions, and accumulated losses.
- Dividend recommendation. The Board’s recommendation of a Rs. 10 final dividend for FY 2025-26 follows the Rs. 35 interim dividend paid during 2025-26, both subject to shareholder approval at the ensuing AGM.
- Audit outcome. Management’s financial results were audited by the Statutory Auditors, who issued an unmodified opinion for the quarter ended 30 June 2026, consistent with the company’s stated compliance with Regulation 33 of the LODR Regulations.
Broker Narrative
The stance stayed constructive (Add on 2023-05-14 to Buy on 2026-11-13) on the same orderbook/indigenisation thesis, which evolved from a Rs818bn orderbook (Rs260bn manufacturing + Rs166bn ROH) and IAF targets (73 Mk1A, 108 Mk2, 140 AMCA) into a ~INR1.0trn 2-year pipeline plus 14 GE F404 engines, the Safran SAFHAL JV, GE/Honeywell ties, LMRH AoN (~INR200bn) and exports. The margin frame flipped: Q4FY23 gross-margin expansion to 61.9% (sourcing efficiencies, richer ROH mix) and a top-end 26.0% EBITDA margin became a 312bps YoY gross-margin contraction to 52.9%, while the May-2023 Tejas Mk1A execution risk remains a live headwind (now with supply-chain issues). Early cautions that faded as the stock posted large positive actuals (+177.1%/+163.4%/+157.3%) were high provisions (16.7% of revenue), the Rs786mn LCA inventory-damage charge, one-time tax/interest benefits, and ‘upside priced in’ at 19.5x FY25E EPS.
Fears that came true
- Tejas Mk1A execution-delay risk flagged in May-2023 persisted into the 2026-11-13 headwind (execution on Tejas Mk1A deliveries and supply-chain issues) and aligns with the DISAPPOINTMENT/negative-actual stretch: 2024-05-19 actual -24.7% and ICICI 2025-03-26/04-02/05-17 actuals of -10.1%/-11.9%/-13.5%.
Optimism that failed
- Gross-margin expansion to 61.9% (from 59.9%) on sourcing efficiencies and a higher ROH revenue share failed to hold, as the last report cites a 312bps YoY gross-margin contraction to 52.9%.
Broker Timeline
48 broker calls · 2023-05-14 to 2026-11-13
CNBC-TV18: ratings, targets and commentary
Extracted from CNBC-TV18 posts; ratings and targets are as published, not current consensus. OCR may contain errors. Speaker attribution is retained; not all speakers are brokers. These statements are separate from the Broker Narrative and Broker Timeline and have no calculated performance or outcomes.
Ratings and targets
| Published / source (IST) | Speaker / affiliation | Rating / target | Commentary |
|---|---|---|---|
| 2026-11-13 |
CLSA
|
Outperform
Target: INR 5,625
Target action: maintained
|
Maintain Outperform on HAL with a target price of ₹5,625; PAT growth driven by higher engine & helicopter deliveries, aircraft deliveries & treasury income; margins fall 60 bps but remain flat for H1FY27; cash pile rises 7% YoY to US$5 Bn on large advances & conservative accounting; start of MK1A deliveries in 2H & visibility on GE engine production deal key catalysts; HAL remains the cheapest pure-play defence stock despite its sector-leading position |
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.