Aerospace & Defense
Industry Metrics
April 16, 2026
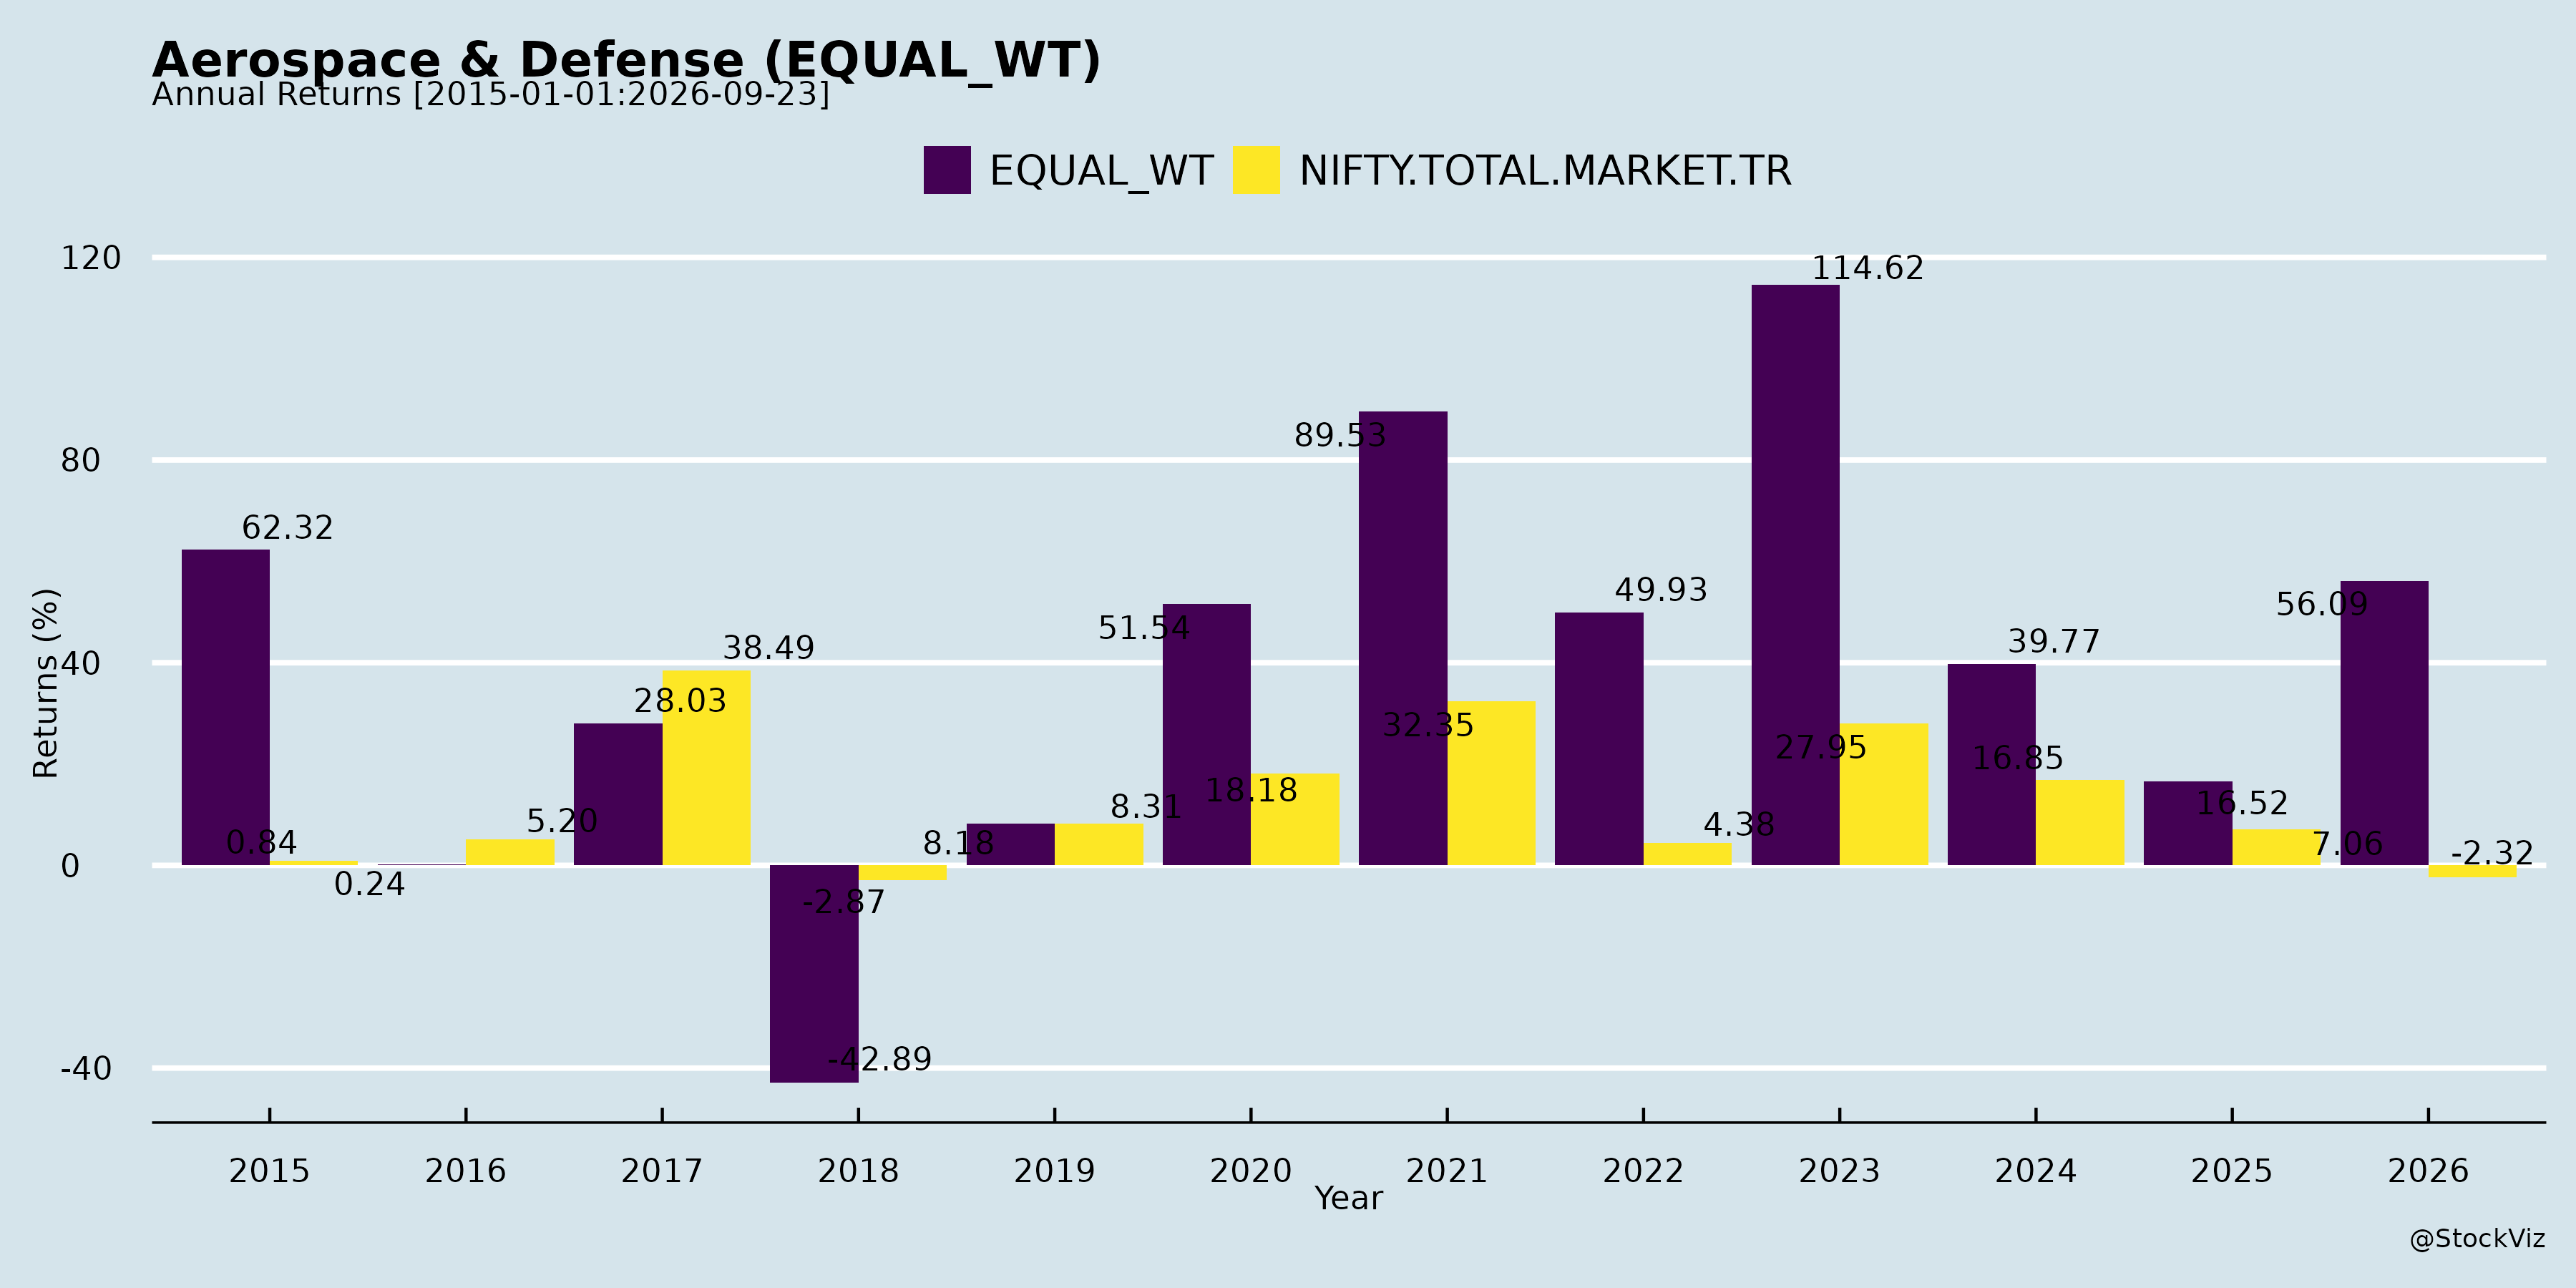
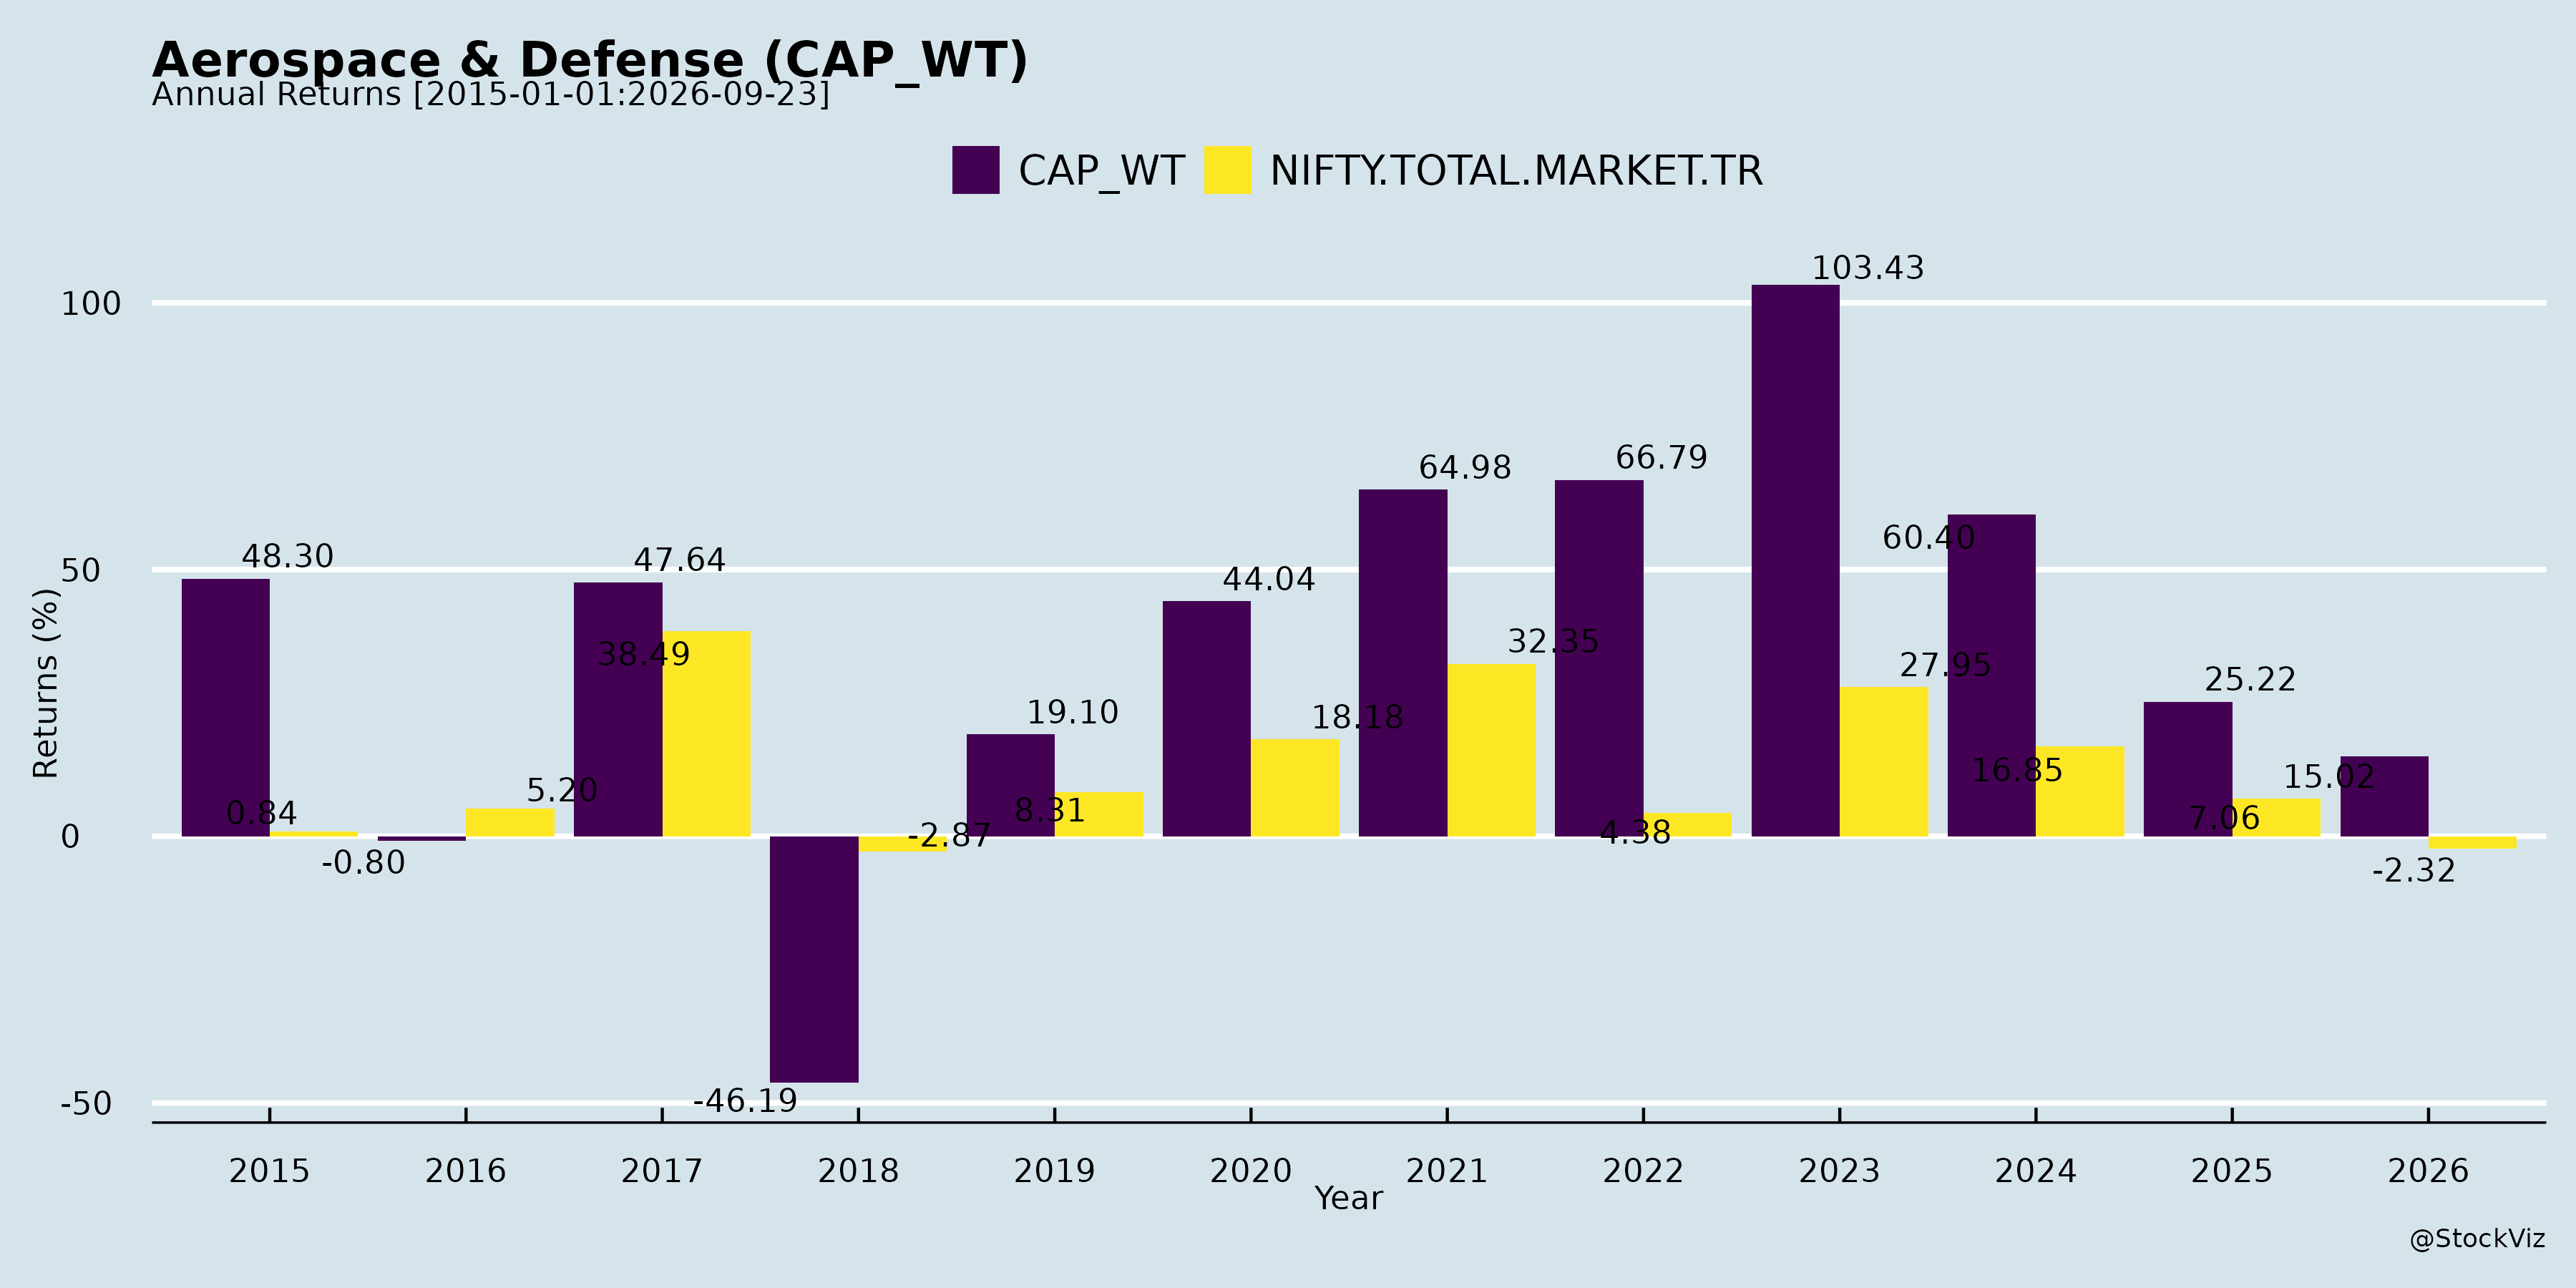
Annual Returns
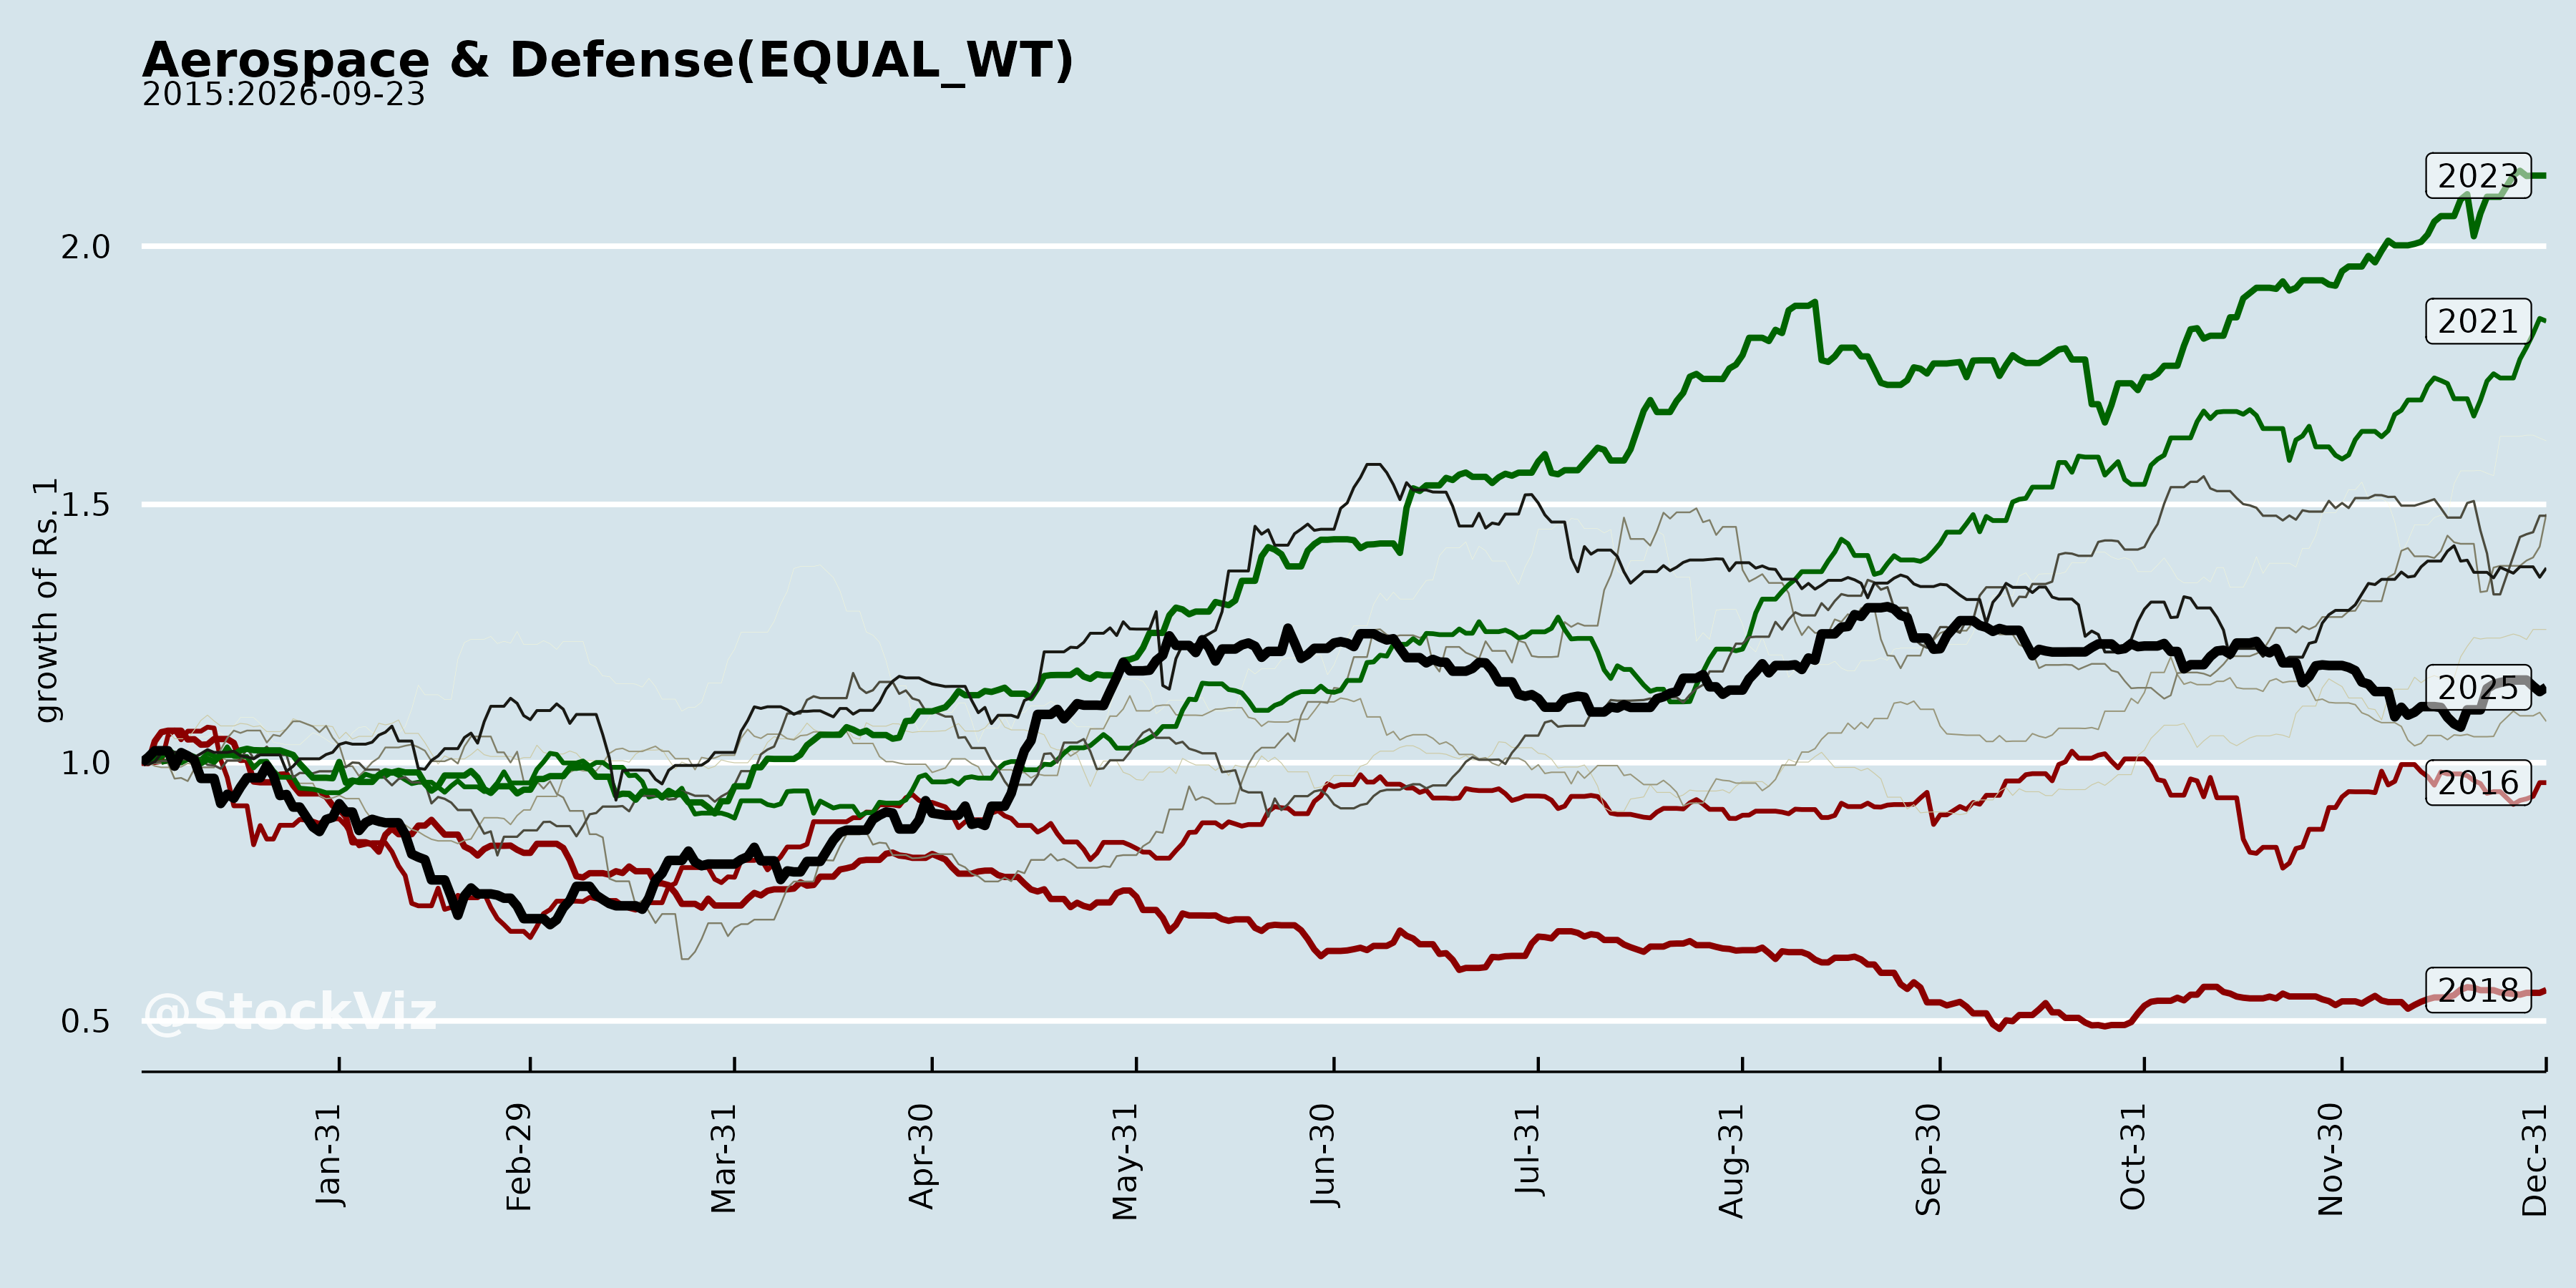
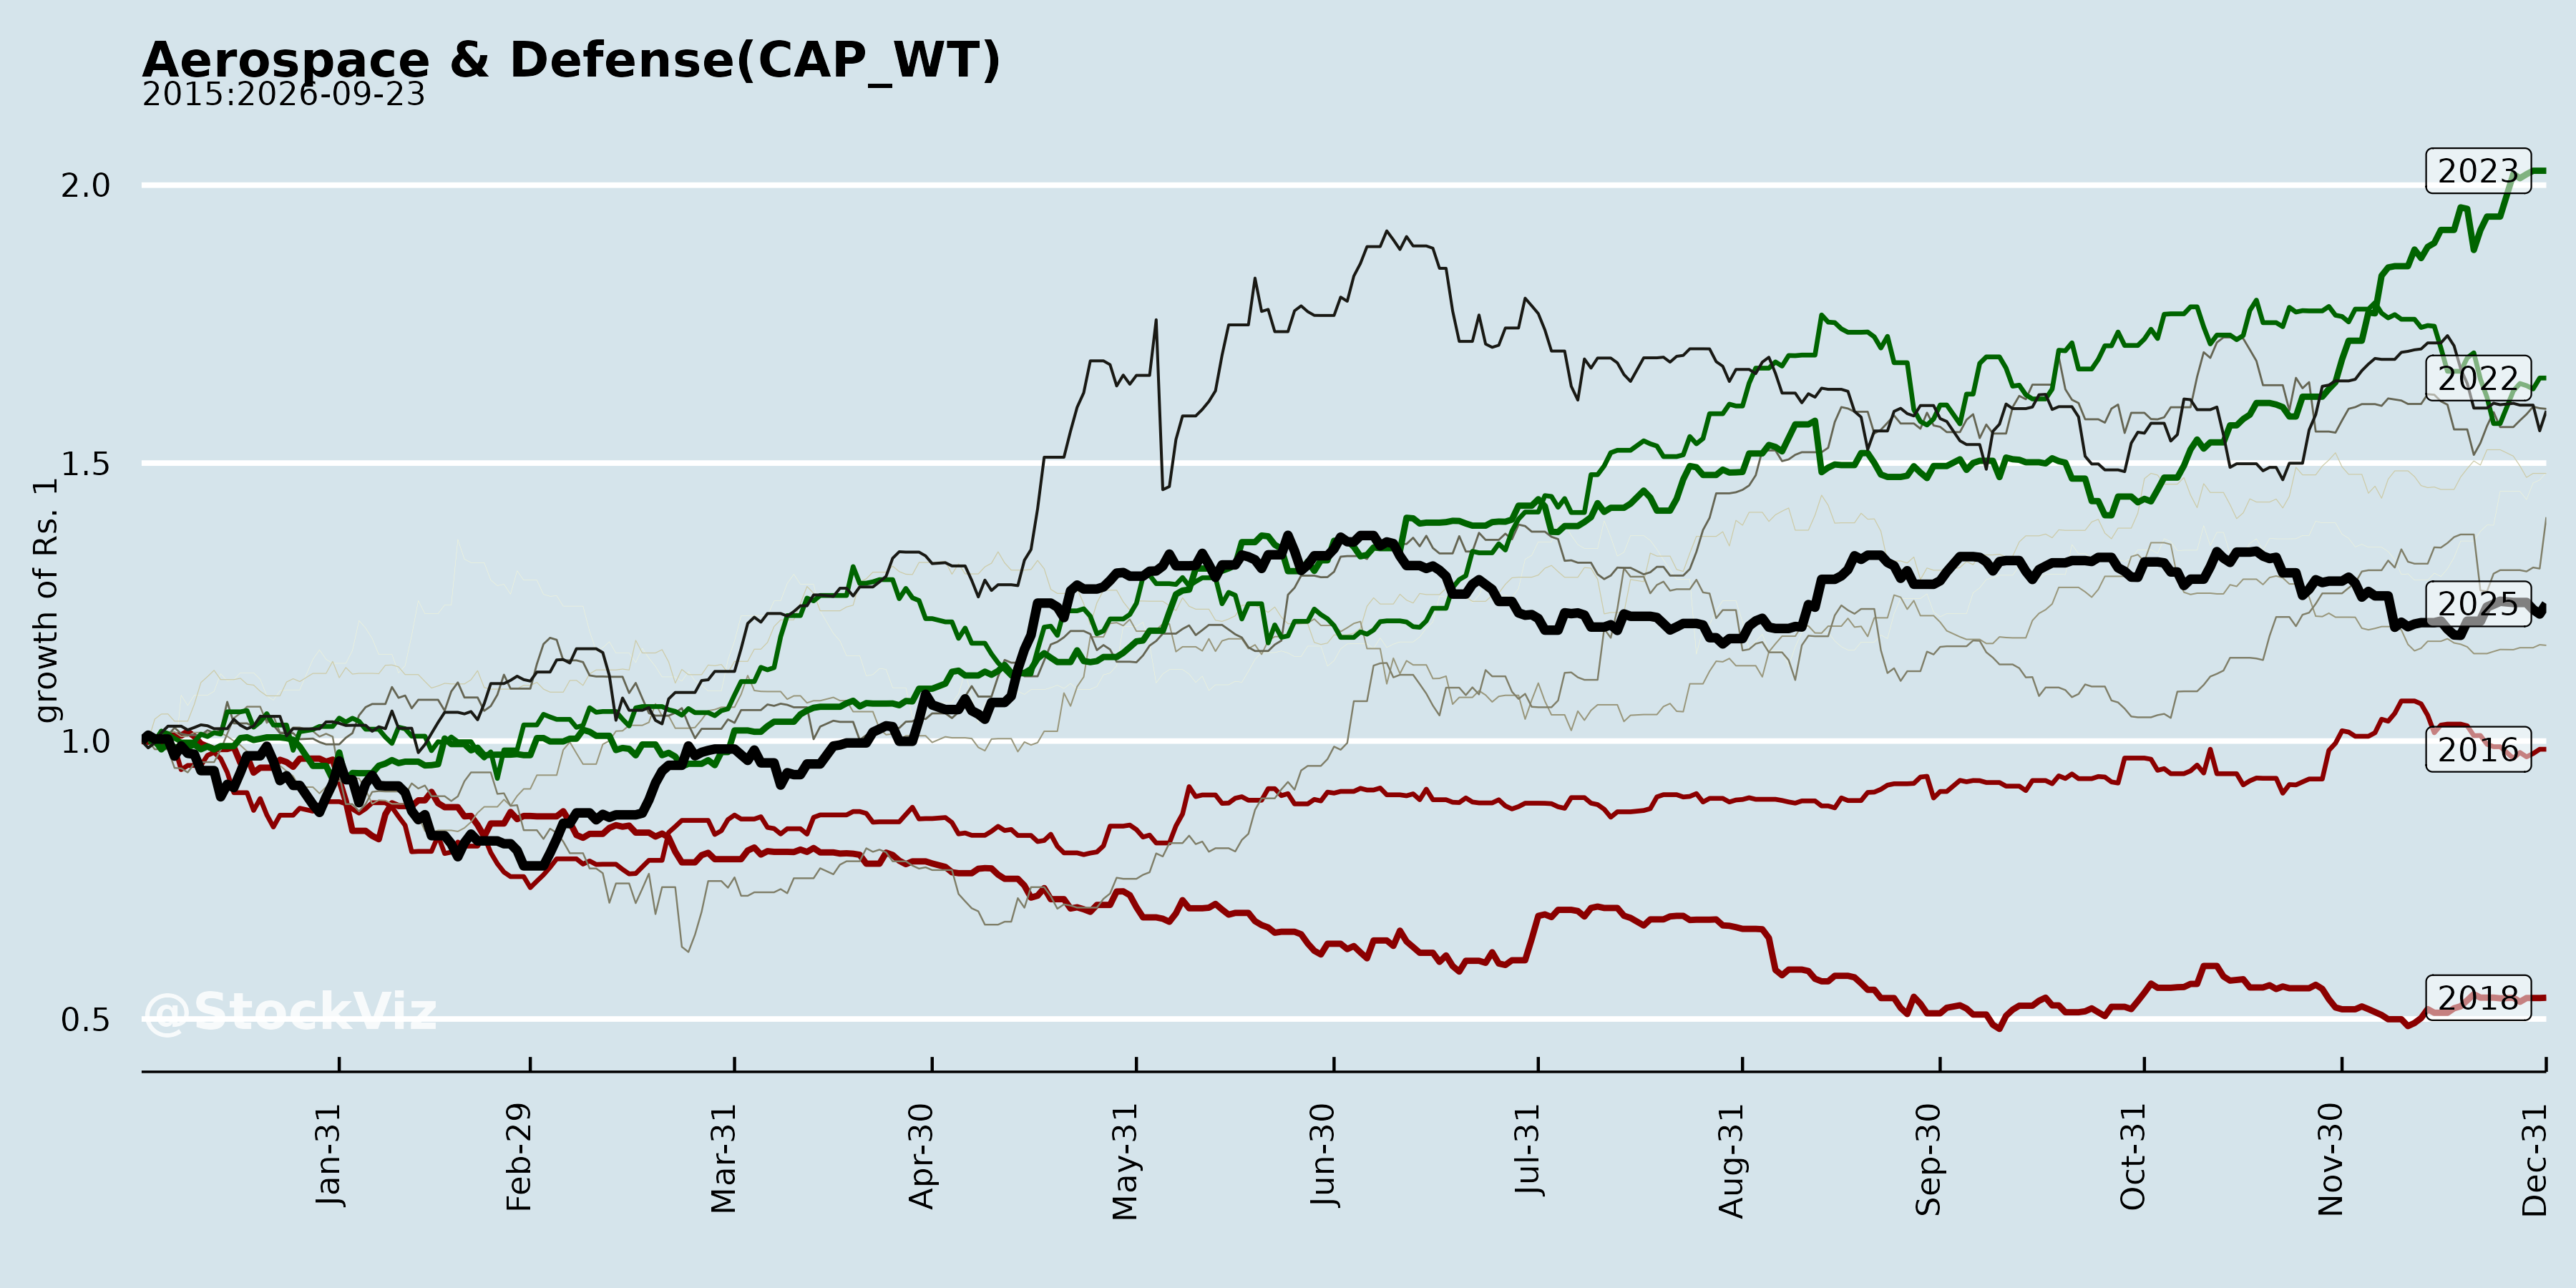
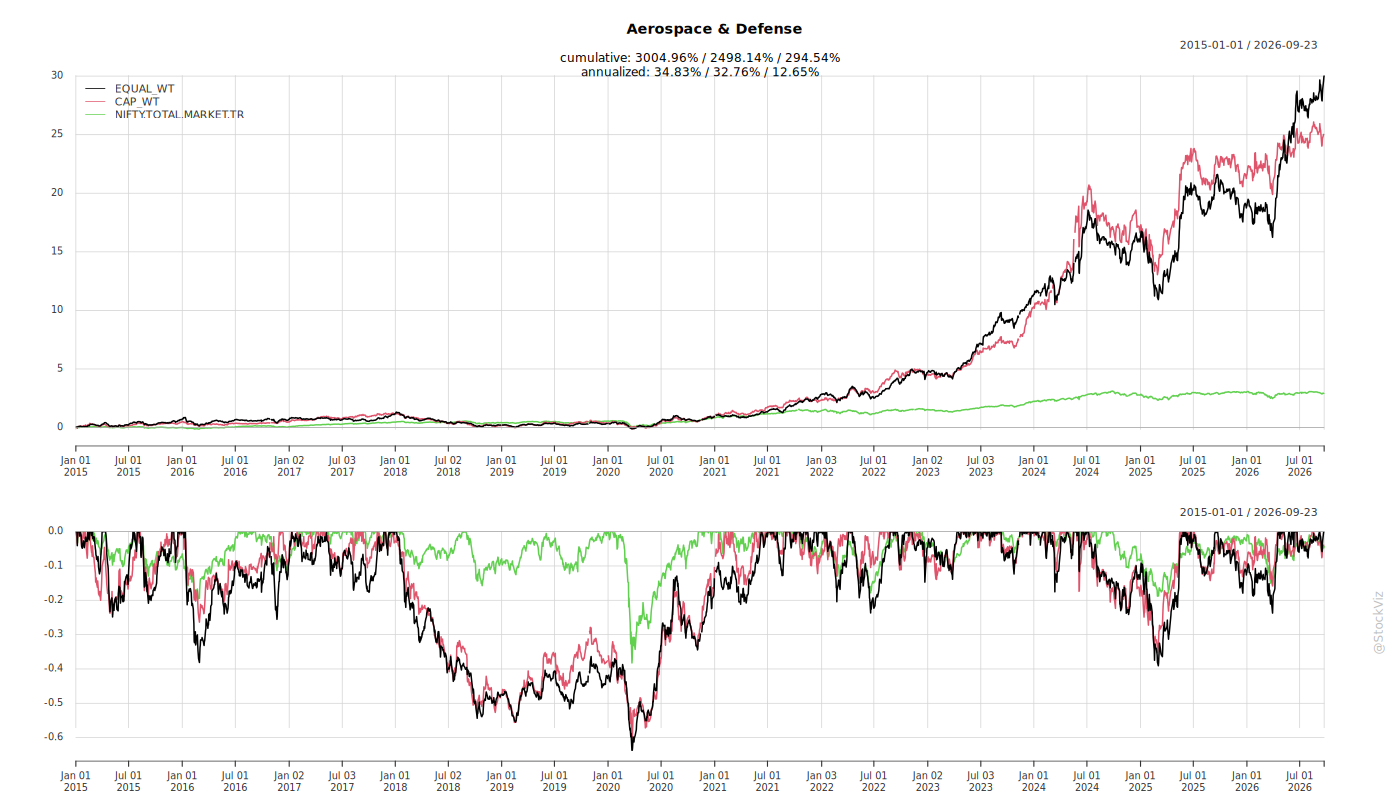
Cumulative Returns and Drawdowns
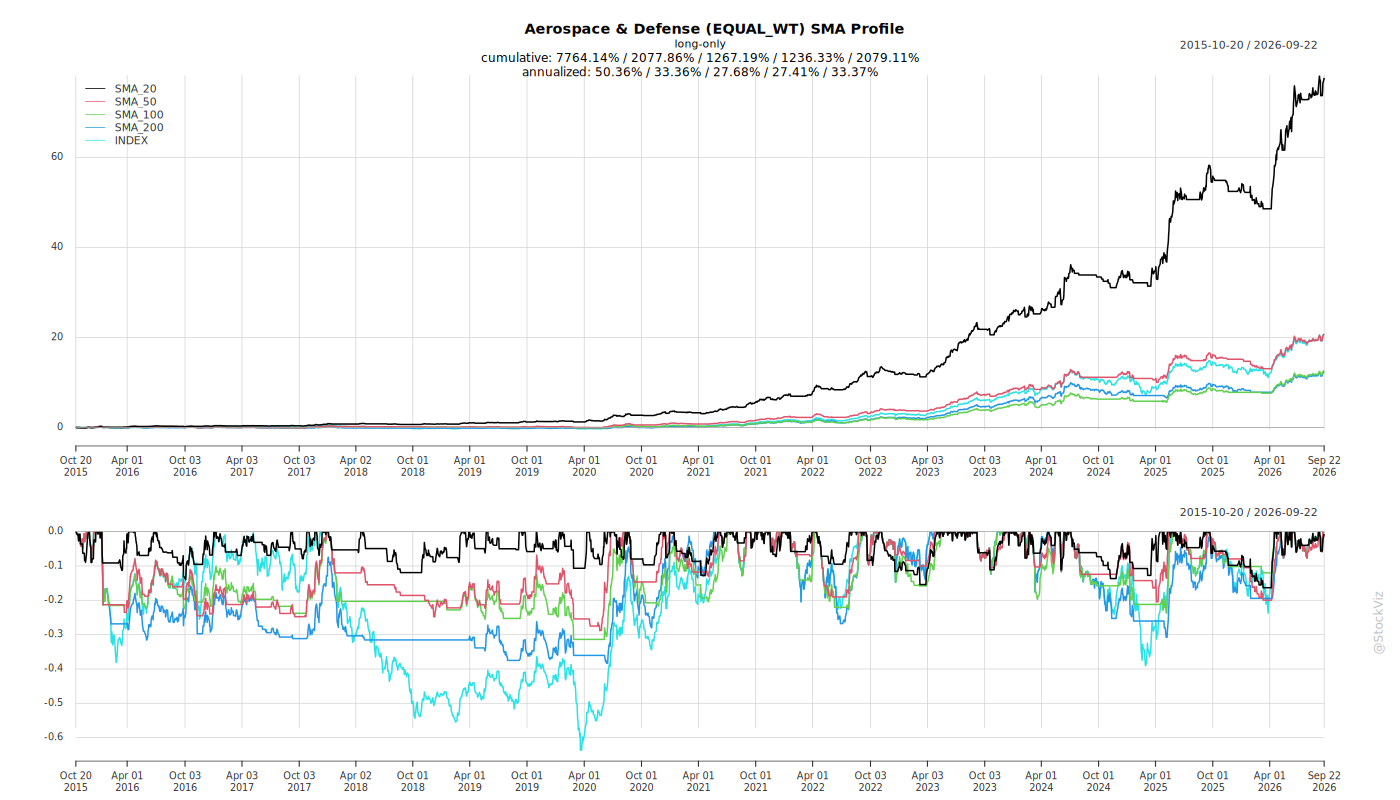
SMA Scenarios
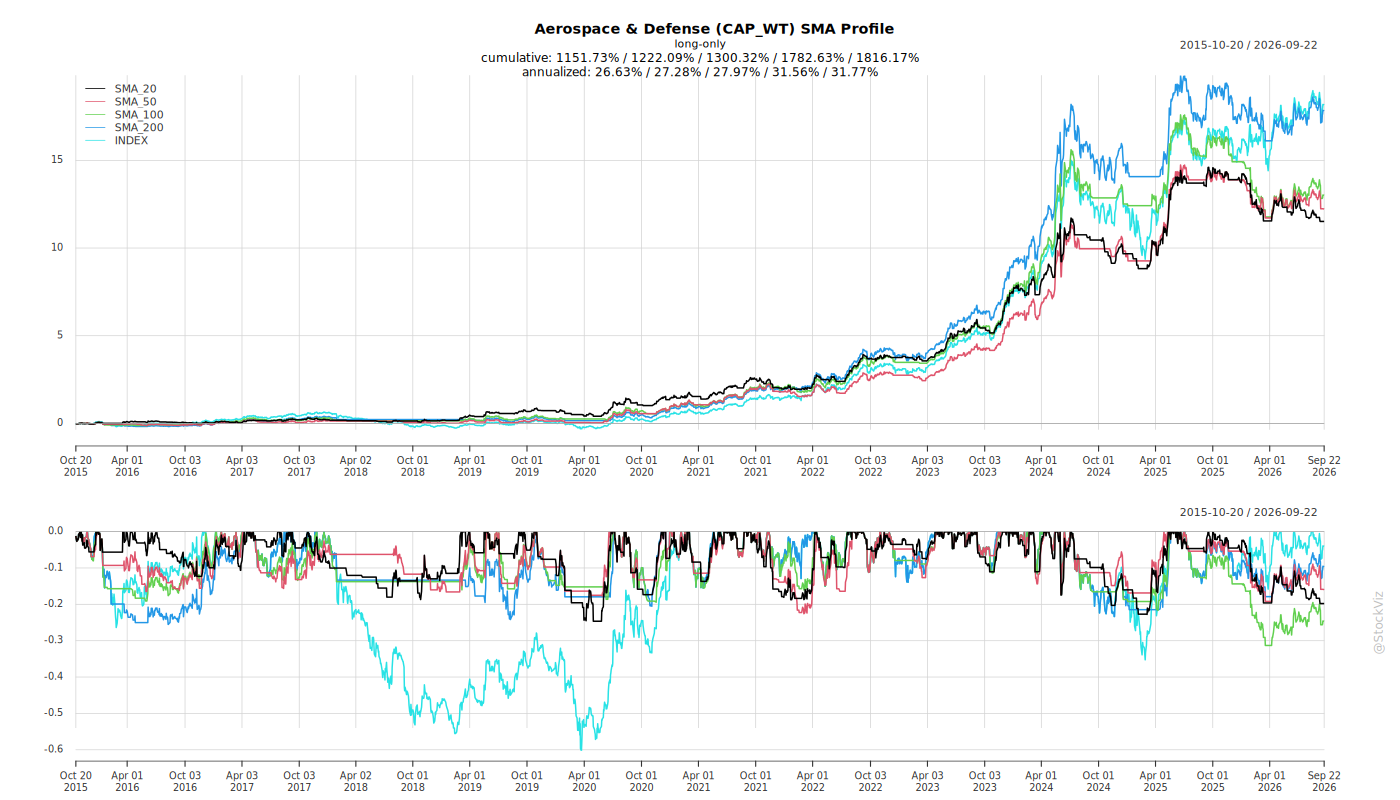
Current Distance from SMA
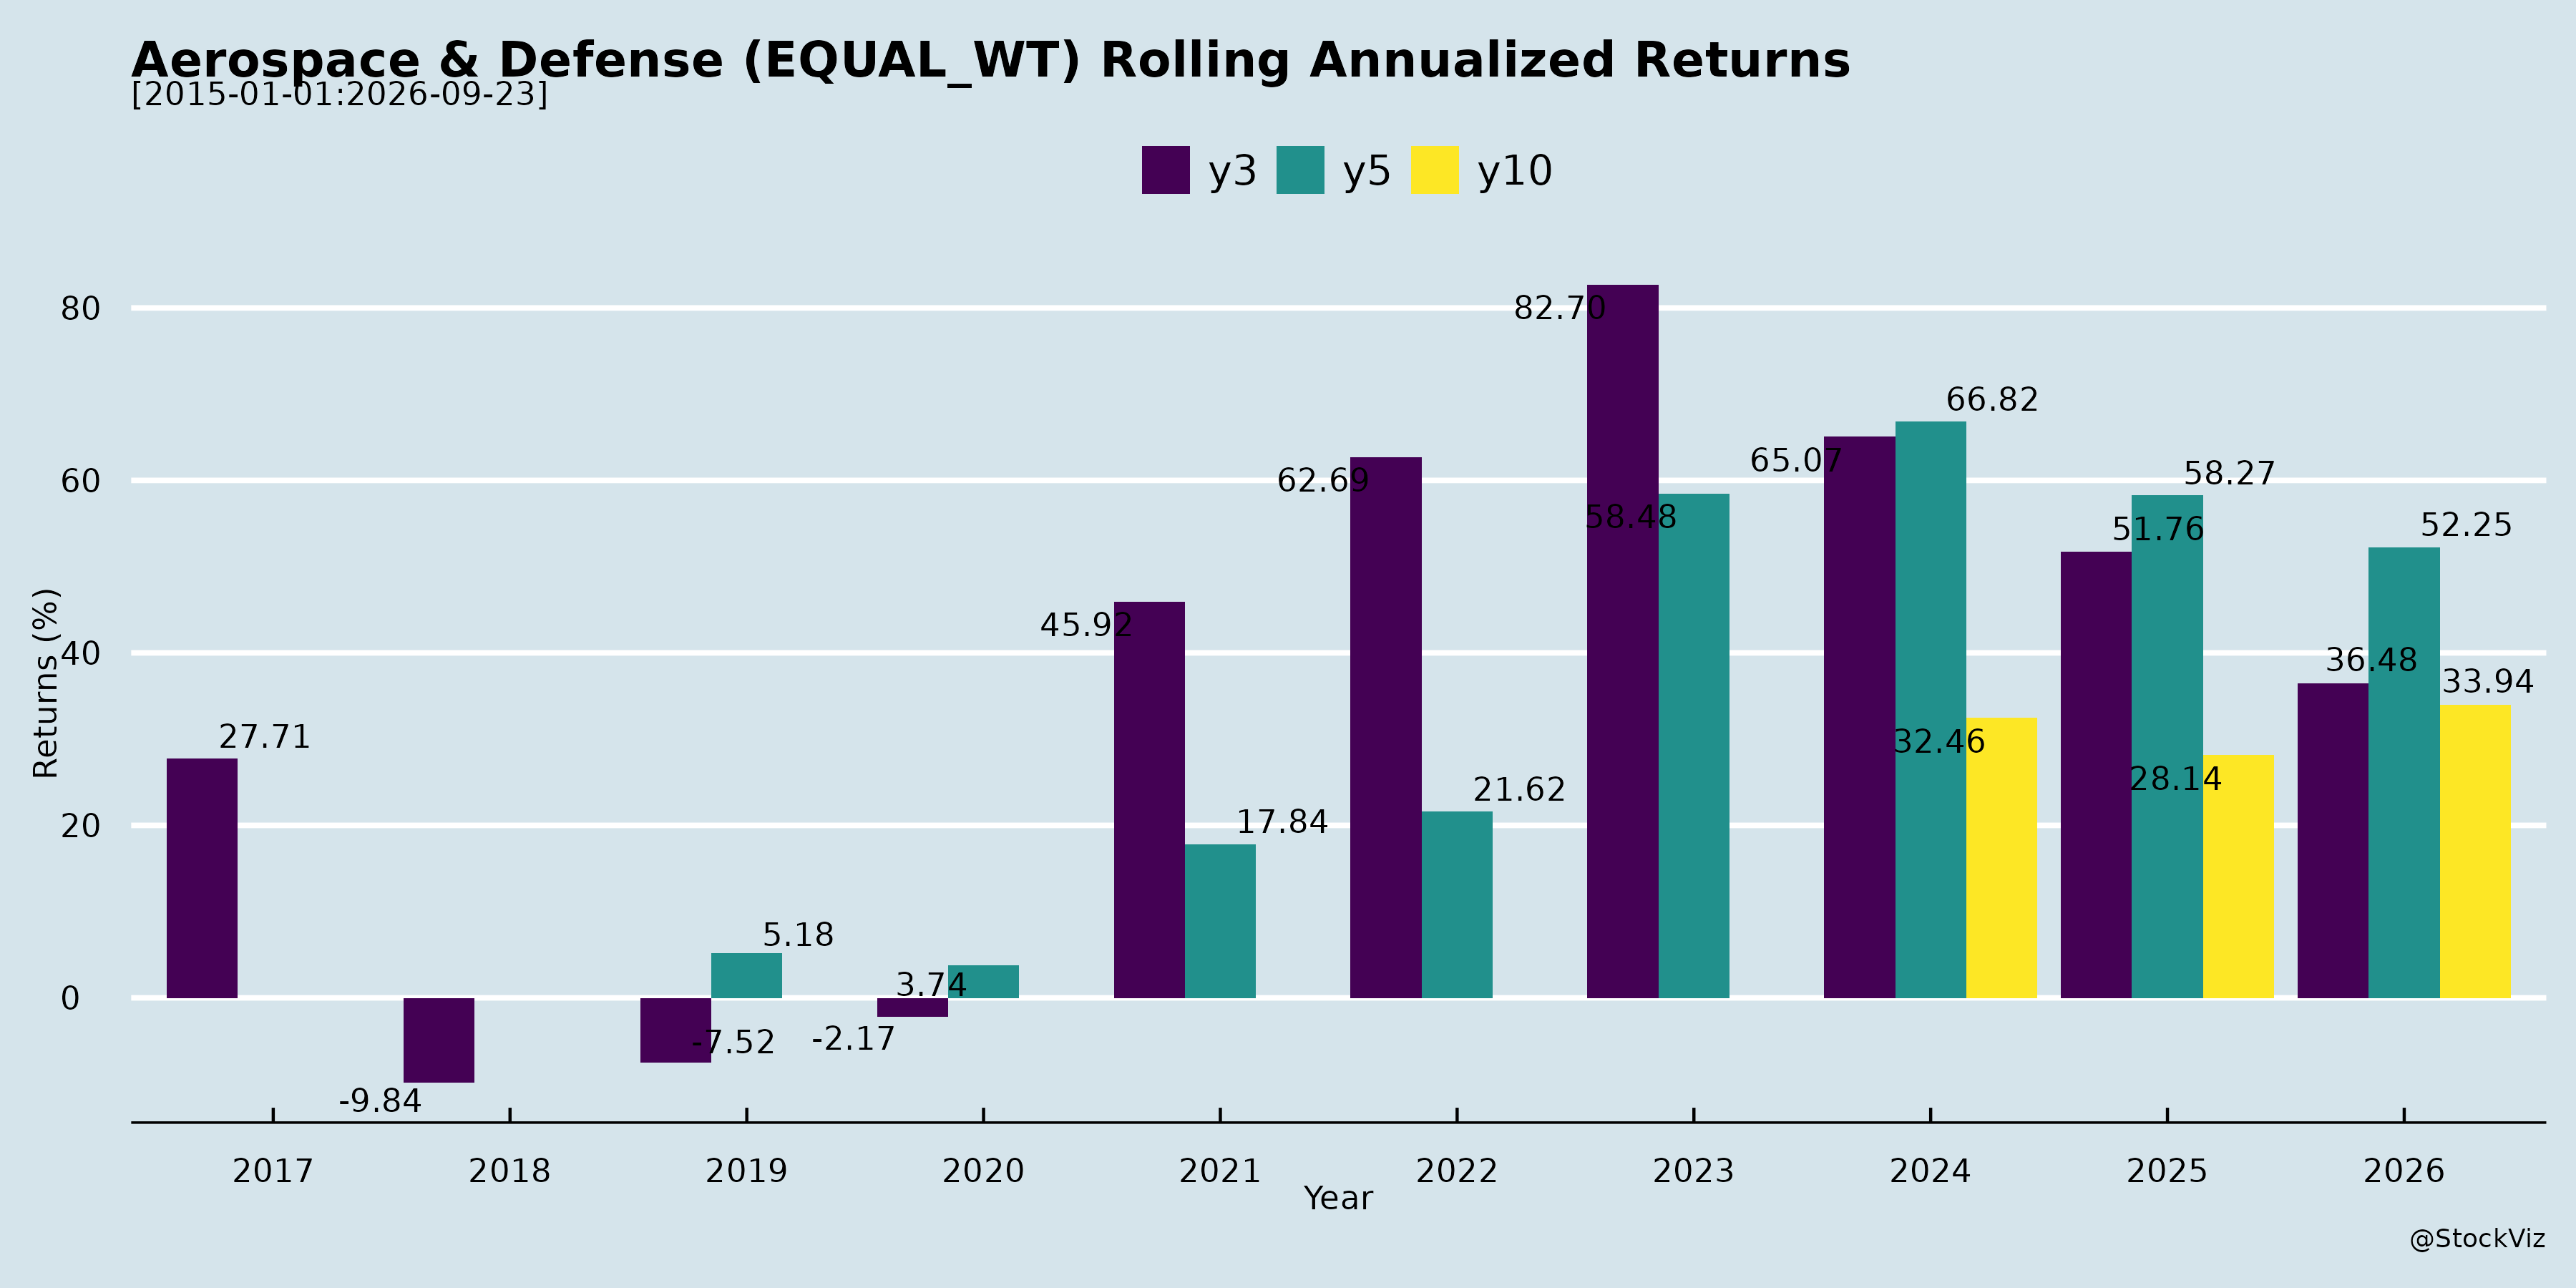
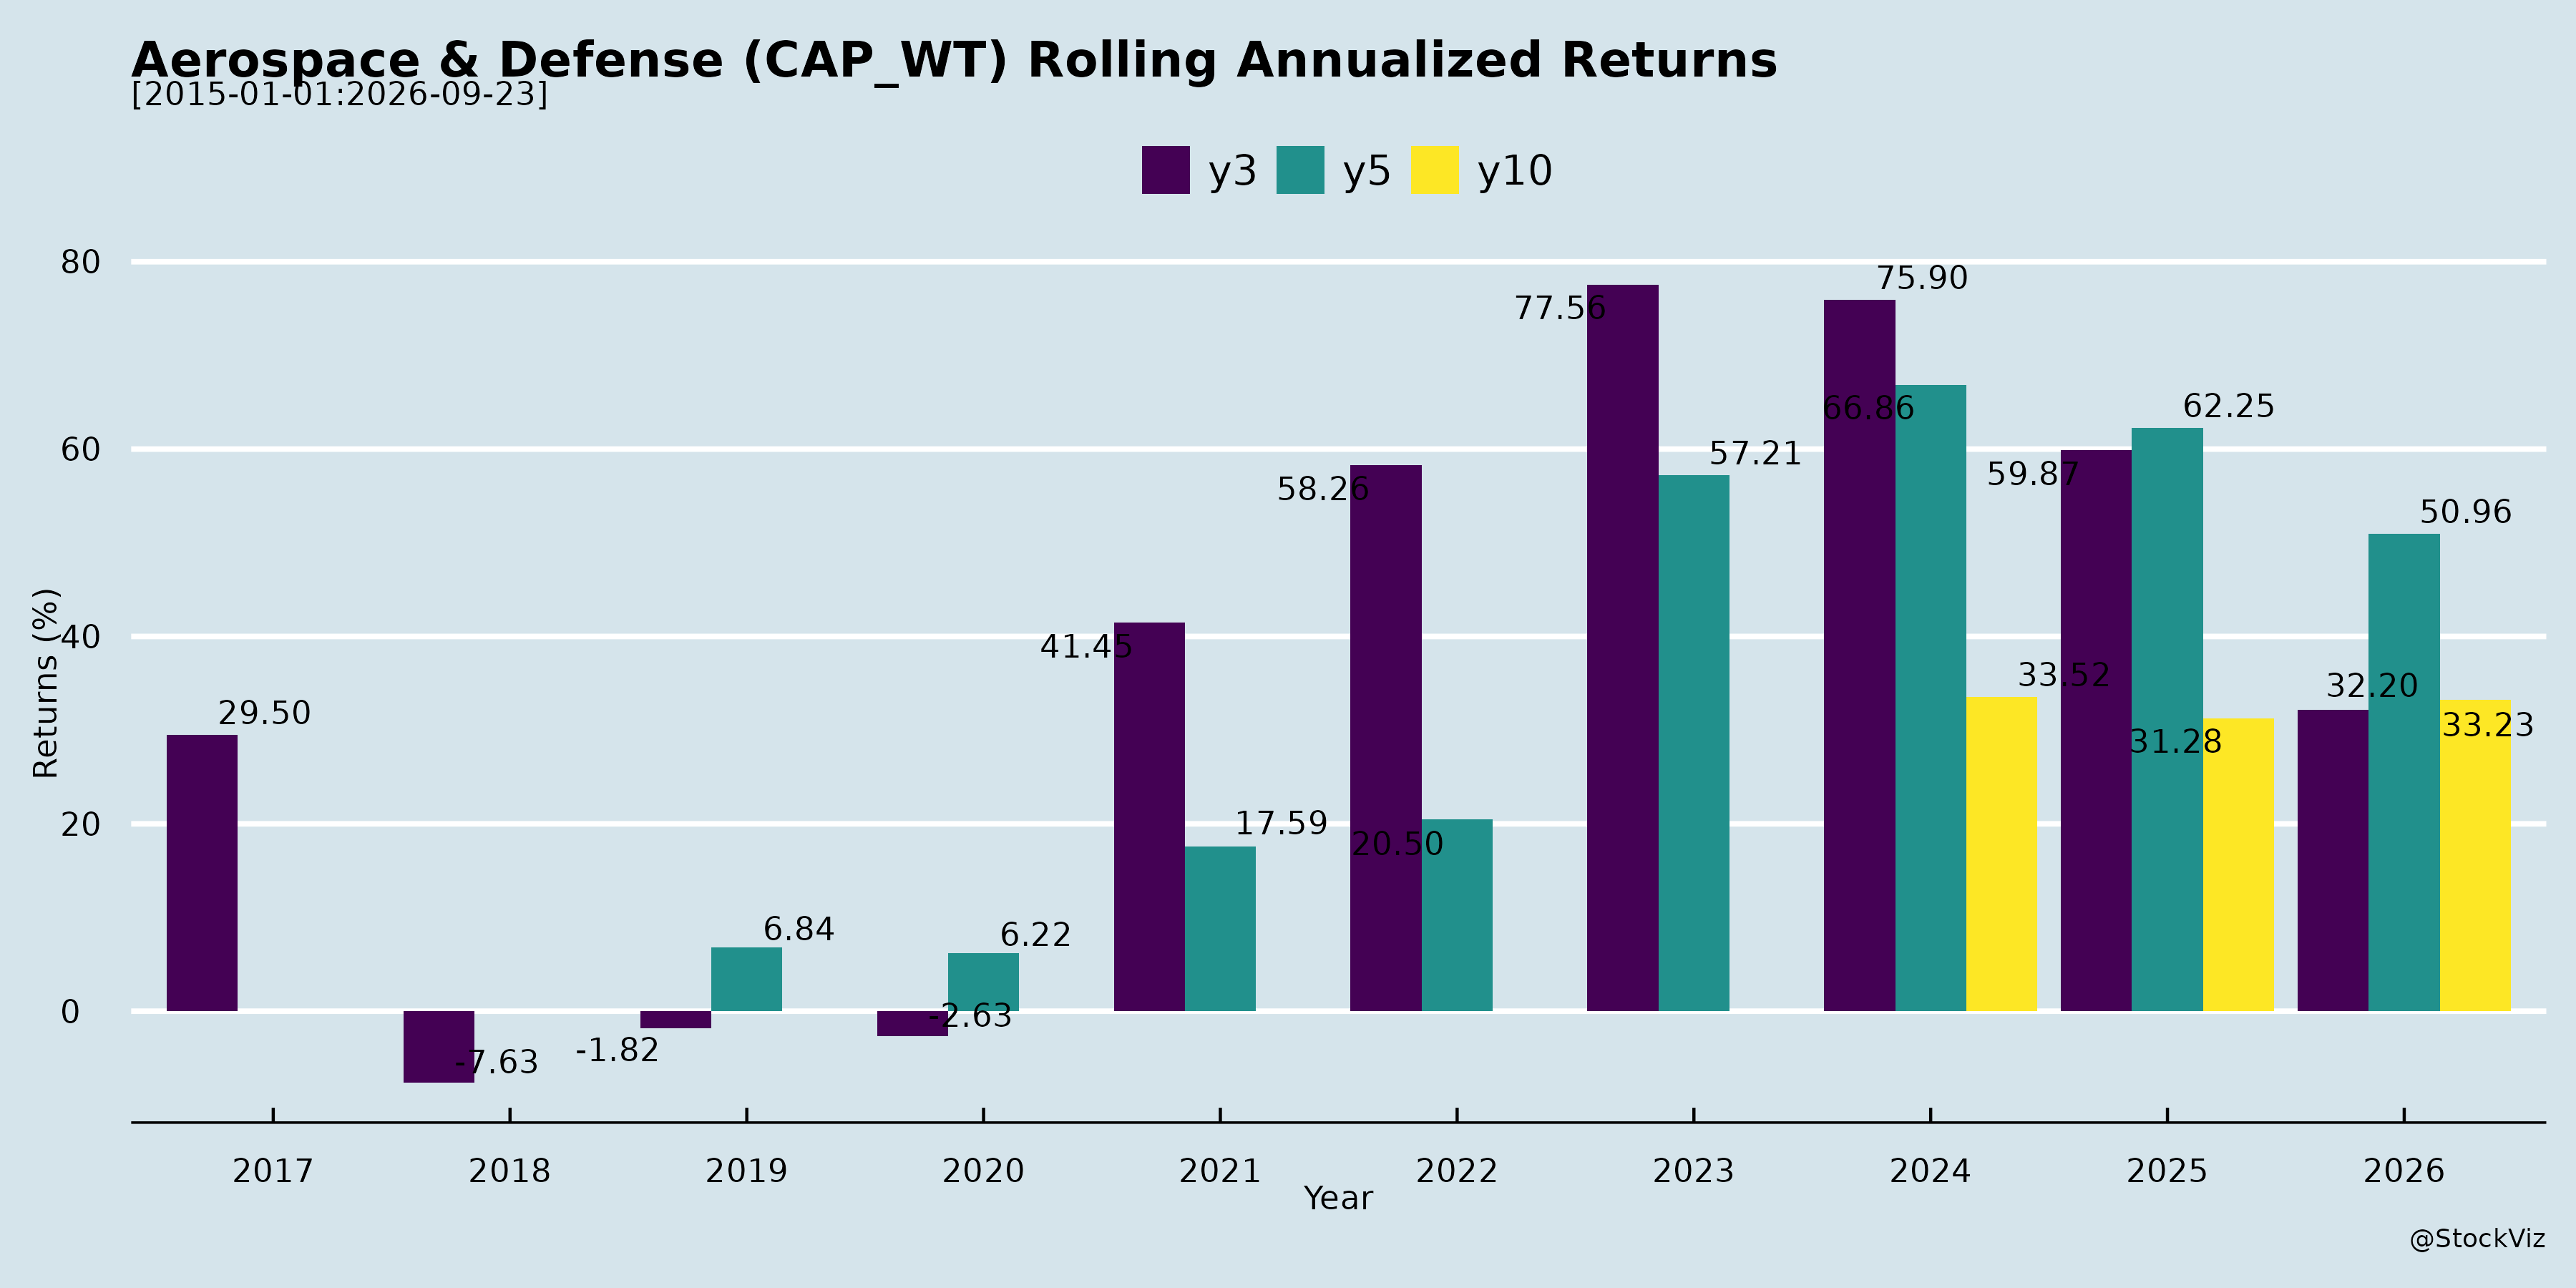
Rolling Returns
Fundamental Ratios
AI Summaries
Analyst
asof: 2025-11-30
Indian Aerospace & Defense Sector Analysis (Based on Provided Documents)
The documents primarily consist of Q2/H1 FY26 earnings transcripts, regulatory filings, and investor meet intimations from key players like Bharat Electronics (BEL), Garden Reach Shipbuilders (GRSE), Data Patterns, Astra Microwave, Mishra Dhatu Nigam (MIDHANI), and others (e.g., HAL, BDL, MTAR, Paras). These reveal a robust sector buoyed by government initiatives but facing execution hurdles. Below is a structured analysis of headwinds, tailwinds, growth prospects, and key risks, followed by a summary.
Tailwinds (Positive Drivers)
- Government Push & Massive Approvals: DAC AONs worth ~INR 1.4 lakh crores (including INR 79k cr recent batch) for QRSAM (~INR 30k cr), P-17 Bravo (INR 70k cr), LPDs (INR 35k cr), MCMVs (INR 32k cr), NGC corvettes, etc. RFPs issued for INR 8.7k cr (e.g., SPVs, survey vessels). Emphasis on indigenization (Atmanirbhar Bharat) favors DPSUs/private players.
- Strong Order Books & Visibility: BEL (INR 75.6k cr, targeting INR 57k cr inflows FY26 incl. QRSAM); GRSE (INR 20k cr, eyeing INR 50k cr by FY26-end); Astra (INR 2.2k cr consolidated); MIDHANI (INR 2.2k cr); Data Patterns (INR 1.3k cr). Multi-year execution (e.g., QRSAM 5-6 yrs).
- Execution Momentum: BEL (15-16% YoY H1 revenue growth, EBITDA 30%); GRSE (45% YoY Q2 growth); Data Patterns (109% H1 growth). Improving cash flows, capex (BEL INR 1.4k cr DSIC; GRSE expansions).
- Exports & Diversification: BEL targeting 10% exports; GRSE eyeing European commercial ships; MIDHANI (INR 94 cr FY25 exports, NADCAP certification); space (ISRO missions, Gaganyaan).
- Tech/Indigenization: EW suites (Su-30), radars (Uttam, Virupaksha), ABHED jackets (MIDHANI), metal powders (additive mfg.).
Headwinds (Challenges)
- Revenue Volatility & Product Mix: BEL/GRSE/Data Patterns note H1/H2 mix similarity but low-margin “strategic” orders (e.g., Data Patterns INR 180 cr). MIDHANI Q2 dip due to WIP/superalloy processing delays (2-4 months cycle).
- Supply Chain Disruptions: MIDHANI raw material imports/geopolitical issues; BEL/others highlight obsolescence/component shortages.
- Working Capital Pressure: Data Patterns (343 days); Astra improving but historical highs.
- Delays in Key Programs: QRSAM (FoPM trials, 12-18 months post-order); Kusha (prototypes by 2029); AMCA RFI stage; LCA Mk1A sensor issues.
- Competition: Shipbuilding (MDL, HSL, L&T vs. GRSE); EW/radars (multiple consortia).
Growth Prospects
- Short-Term (FY26-FY27): BEL (INR 27k cr inflows ex-QRSAM); GRSE (NGC INR 30k cr, P-17 Bravo); Astra (INR 1.4k-1.5k cr FY27, 2x in 3-4 yrs to $250 mn); MIDHANI (INR 1.3k cr FY26, 10-20% CAGR); Data Patterns (INR 1k cr H2 inflows).
- Medium-Term (FY28-FY30): QRSAM/Uttam/Su-30 production ramp-up (Astra 3x); AMCA/LCA Mk2 (avionics); shipbuilding (INR 1.5 lakh cr pipeline); space (Gaganyaan, SSLV, LEO sats); energy (AUSC 740 alloy).
- Long-Term Vision: Astra ($1 bn ambition); GRSE (32-40 ship capacity); exports (BEL 10%, MIDHANI 10-15%); new verticals (drones, counter-UAV, metal powders, ABHED).
- Capex & Expansion: BEL DSIC (INR 1.4k cr); GRSE brownfield/greenfield; MIDHANI forging upgrades/metal bank.
- Sector TAM: Defense roadmap to 2040; imports (superalloys/titanium INR 8k cr); shipbuilding (207 vessels ~INR 50k cr).
| Company | FY26 Guidance | 3-5 Yr Outlook |
|---|---|---|
| BEL | 15%+ growth, >27% EBITDA, INR 57k cr inflows | QRSAM/Kusha/AMCA ramp |
| GRSE | 25-30% growth | INR 50k+ cr OB, expansions |
| Astra | INR 1.15k-1.2k cr | 2x to $250 mn, then $1 bn |
| MIDHANI | INR 1.3k cr, 23% EBITDA | 10-20% CAGR, capex-led |
| Data Patterns | INR 850 cr+ rev | High-value radars/EW |
Key Risks
- Order Delays: RFP/contract timelines (e.g., QRSAM by Mar’26; NGC 3-4 months); prototype trials (Kusha 2029).
- Execution/Supply Chain: Raw materials (MIDHANI metal bank mitigates); obsolescence (BEL); WIP buildup.
- Margin Pressure: Low-margin strategic orders (Data Patterns); product mix volatility.
- Capex Execution: Funding/timing (BEL/GRSE/MIDHANI); infra bottlenecks.
- Competition/Geopolitics: Bids (counter-drone losses); imports disruptions; forex volatility.
- Regulatory/Policy: Pay revisions (BEL 4th PRC FY27); export certifications (NADCAP).
- Macro: Defense budget execution; global tensions affecting exports.
Summary
Bullish Outlook with Execution Focus: The sector is in a high-growth phase (tailwinds from INR 1.4 lakh cr AONs, indigenization, exports), with companies guiding 15-30% FY26 growth and 2-3x medium-term multiples (e.g., Astra). Order books provide 1-2 yr visibility; capex addresses capacity. Headwinds (delays, supply chains) are manageable via initiatives like metal banks. Risks center on timelines/margins, but diversified pipelines (missiles, ships, space) mitigate. Overall: Strong buy-on-dips potential; expect 20%+ sector CAGR FY26-30, led by QRSAM/AMCA/shipbuilding. Investors should track Q3 order inflows & capex updates.
General
asof: 2025-12-03
Analysis of Indian Aerospace & Defense (A&D) Sector
Using the provided documents (primarily Reg 30 disclosures from NSE/BSE filings by key players like BEL, HAL, BDL, GRSE, Data Patterns, Zen Technologies, Apollo Micro Systems, Astra Microwave, MTAR Technologies, AXISCADES, and Paras Defence), I’ve analyzed the sector’s headwinds, tailwinds, growth prospects, and key risks. These filings reflect a mix of PSUs (public sector undertakings) and private players, highlighting governance challenges in PSUs alongside private sector momentum in indigenization and partnerships. The sector benefits from India’s “Atmanirbhar Bharat” push, rising defense budgets (~₹6.2 lakh crore in FY25), and export growth (₹21,083 crore in FY24).
Summary Table
| Category | Key Highlights from Documents | Implications |
|---|---|---|
| Headwinds | - Repeated SEBI LODR non-compliances (Reg 17/18/19/20/21) in PSUs (HAL: ₹10L fine; BDL/GRSE: ₹5-9L each) due to govt-delayed Independent Director (ID) appointments. - No material financial impact claimed, but waiver requests signal dependency/control issues. |
Governance drag on PSUs; repeated disclosures erode investor confidence. |
| Tailwinds | - Strong ESG adoption (BEL: 73.8/100 CARE rating). - Tech transfers/partnerships (Paras: DRDO ToT for T-90 DNS; AXISCADES-Altera expansion for mission-critical defense apps). - Corporate actions (Zen: 76% acquisition of Anawave; Astra: subsidiary rename to Astra Defence Tech). |
Policy support (Make-II, iDEX); private sector agility complements PSUs. |
| Growth Prospects | - Private precision engineering/export focus (MTAR: 79% exports, space/defense/nuclear/clean energy; ₹676Cr turnover). - Indigenization (ToT, acquisitions); media/analyst engagement (Apollo TV interview). - Sustainability (MTAR BRSR: ISO certifications, solar initiatives, 95% sustainable sourcing). |
12-15% CAGR to ₹1.75 lakh crore by 2030; exports to double; private capex rising. |
| Key Risks | - Govt dependency (PSU board composition); minor events (Data Patterns promoter group demise). - No major financial hits from fines, but escalation possible. - Supply chain/value chain unassessed for ESG (MTAR: 0% value chain audits). |
Regulatory fines, delays in appointments, geopolitical supply disruptions. |
Narrative Summary
Headwinds (Challenges Pressuring the Sector)
- Governance & Compliance Bottlenecks in PSUs: Dominant PSUs (HAL, BDL, GRSE) face recurring fines (e.g., NSE/BSE penalties totaling ₹20-30L across Q1-Q3 FY26) for inadequate board composition (e.g., insufficient IDs, women IDs, committee shortfalls). Root cause: Appointments by Ministry of Defence/President, beyond company control. While waivers are sought under SEBI SOP (Sl. No. 3(a)), repeated filings (Oct-Nov 2025) highlight systemic delays, potentially deterring investors amid SEBI’s tightening norms.
- Limited Private Sector Scale: Privates like MTAR report high employee turnover (25% FY25 vs. 5-8% prior), signaling talent retention issues in a niche skill sector.
Tailwinds (Positive Momentum)
- ESG & Sustainability Push: BEL’s “73.8” ESG rating (Oct 2025) underscores improving disclosures. MTAR’s comprehensive BRSR (Aug 2025) details ESG integration (e.g., ISO 45001/14001, solar power, zero-liquid discharge, 95% sustainable sourcing), positioning the sector for global tenders/export compliance.
- Strategic Partnerships & Indigenization: Private firms lead here—Paras’ DRDO ToT for T-90 tank DNS (Nov 2025), AXISCADES-Altera tie-up for FPGA-based defense apps (Nov 2025), Zen’s subsidiary acquisition (Nov 2025). PSUs stabilize core production (e.g., HAL compliance post-Jun 2025).
- Operational Resilience: No material financial impacts from fines; MTAR’s 79% export contribution (to 6 countries) shows diversification.
Growth Prospects (High-Potential Opportunities)
- Indigenization & Private Participation: Govt-DRDO ToTs (Paras) and acquisitions (Zen/Anawave for defense sims) align with 75% local content targets. MTAR’s focus on precision components (35% aerospace, 64% clean energy generators) taps space (ISRO), defense, nuclear, and hydrogen tech—turnover up ~17% YoY to ₹676Cr.
- Export & Diversification: MTAR’s 14-state/6-country reach; sector exports eyed at $5Bn by 2025. Emerging areas: Mission-critical apps (AXISCADES), optics/electronics (Astra).
- Sustainability as Differentiator: MTAR’s waste recycling (100% metal scrap), water management, and low GHG intensity signal readiness for green defense procurements.
- Overall Outlook: Sector poised for 12-15% CAGR (Deloitte est.), driven by ₹3.2L Cr capex pipeline, iDEX schemes, and private investments (e.g., Zen’s integration).
Key Risks (Potential Vulnerabilities)
- Regulatory & Governance Risks: Escalating SEBI fines if waivers denied; PSUs (80% sector revenue) remain govt-tethered.
- Talent & Operational Risks: High turnover (MTAR), no differently-abled hires; unassessed value chains (0% ESG audits).
- Execution & Geopolitical Risks: Dependency on DRDO/govt orders; minor disruptions (e.g., promoter events in Data Patterns). No cyber/data breaches reported, but MTAR notes no formal anti-bribery policy.
- Macro Risks: Water/energy stress (MTAR: 65KL water withdrawal); inflation in raw materials.
Investment Takeaway: PSUs offer stability but governance overhang; privates (MTAR, Paras, Zen) drive growth via agility/tech. Bullish long-term on indigenization, but monitor PSU reforms. Sector rating: Overweight with near-term caution on compliances.
This analysis is derived solely from the documents; broader market data (e.g., Nifty India Defence TRI ~100% CY25 YTD) corroborates trends.
Investor
asof: 2025-12-03
Indian Aerospace & Defense Sector Analysis (Based on Q2 FY26 Earnings Transcripts & Filings)
The provided documents (earnings transcripts, regulatory filings from Nov 2025) cover key players like Bharat Electronics Ltd (BEL), Garden Reach Shipbuilders (GRSE), Data Patterns, Astra Microwave, Mishra Dhatu Nigam (MIDHANI), and others (HAL, BDL, MTAR, Paras, etc.). They highlight robust H1 FY26 performance amid govt-backed indigenization. Overall sector sentiment is bullish, driven by massive AONs (INR1.4L Cr+), order books (e.g., BEL INR75k Cr), and programs like QRSAM/Kusha/AMCA. Revenue growth (15-45% YoY), EBITDA margins (20-30%), and capex signal multi-year expansion.
Tailwinds (Positive Catalysts)
- Govt Push & Indigenization: DAC approvals (INR79k Cr recent; INR1.4L Cr total) for QRSAM (INR30-40k Cr), LPDs (INR35k Cr), P-17 Bravo (INR70k Cr), NGC corvettes. Atmanirbhar focus reduces imports (e.g., MIDHANI: INR8k Cr superalloys imported annually).
- Strong Order Books & Inflows: BEL (INR75.6k Cr, +INR14.75k Cr inflows); GRSE (INR20k Cr, eyeing INR50k Cr); Astra (INR2.2k Cr consolidated); MIDHANI (INR2.2k Cr, +INR500 Cr pipeline). Emergency procurements (BEL: INR1.35k Cr received, INR2k Cr pipeline).
- High Margins & Execution: BEL EBITDA 30% (guidance >27%); GRSE PAT 9%+; Data Patterns 22% (post low-margin strategic order). Diversified mix (radars, missiles, EW, ships).
- Exports & Diversification: BEL targeting 10% exports; GRSE/MPV exports; space (ISRO Gaganyaan/PSLV). Non-defence (GRSE hybrids, MIDHANI energy).
- Capex/Infra: BEL DSIC (INR1.4k Cr); GRSE brownfield/greenfield (32→40 ships); MIDHANI metal bank/ABHED jackets.
Headwinds (Challenges)
- Quarterly Volatility: Product mix/long cycles cause dips (MIDHANI -20% YoY Q2 revenue despite +4% VoP; BEL H1 growth 16% but H2 back-loaded).
- Supply Chain/Raw Materials: Imports disruptions (MIDHANI scrap limits, geopolitics); BEL/others note obsolescence/component issues.
- Working Capital Pressure: Data Patterns 343 days; high inventories (MIDHANI).
- Execution Delays: QRSAM FoPM (12-18 months pre-production); Kusha prototypes (2029 orders); ship trials (GRSE P-17 Alpha ahead, but NGC contract 3-4 months).
- Competition/Bidding: L1 processes (GRSE NGC L1); RFPs (AMCA consortia: BEL-L&T vs. Data-BEML-Bharat Forge).
Growth Prospects
| Timeframe | Key Drivers | Projected Outcomes |
|---|---|---|
| FY26 (Short) | QRSAM (ex-BEL INR27k Cr inflows); HAL LCA (97 aircraft, INR2.5k Cr avionics); GRSE NGC (INR30k Cr); MIDHANI titanium/superalloys (INR1k Cr execution). | BEL: 15%+ revenue, >27% EBITDA; GRSE: 25-30% growth; Sector: INR50k+ Cr from recent AONs. |
| FY27-28 (Medium) | Uttam/Virupaksha radars; Su-30 EW; P-17 Bravo/LPDs; AMCA prototypes; Astra FY27 INR1.4-1.5k Cr. | Astra: 2x current (INR2.25-2.5k Cr by FY30); GRSE INR50k Cr book; Exports 5-10%. |
| FY29+ (Long) | Kusha (BEL >QRSAM); AMCA production; UAVs (Archer-NG/MALE); Space (LEO/SSLV); Shipbuilding (207 vessels, INR5k Cr). | Astra $1B aspiration; BEL/MIDHANI 20% CAGR; Sector TAM INR15-20k Cr (Data Patterns products). |
- Multipliers: Private sector entry (Data Patterns systems integrator); JVs (Astra-ARC $100M book); Tech (EW radars, ABHED jackets).
Key Risks
- Order/Timeline Delays (High): Govt RFPs/AON→Contract (2-2.5 yrs, e.g., GRSE LPD); Trials (QRSAM FoPM, Kusha prototypes).
- Execution/Tech Risks (Medium-High): Complex systems (5-6 yr timelines); Obsolescence (BEL 5-10% spillover).
- Margin Dilution (Medium): Strategic low-margin orders (Data Patterns INR180 Cr); Product mix shifts.
- Supply Chain/Geopolitics (Medium): Raw material imports (MIDHANI metal bank mitigates); Export LC issues (BEL).
- Capex/Funding (Low-Medium): INR1-1.4k Cr spends (BEL/GRSE); Debt-free but scaling needs (Astra space).
- Competition (Medium): PSUs vs. Pvt (L&T/BEL AMCA); Imports (70-80% radars/EW).
Summary
Bullish Outlook: Sector poised for 15-30% CAGR (FY26-30), fueled by INR1L+ Cr pipelines, indigenization (QRSAM/AMCA/Kusha), and exports/space. BEL/GRSE lead with execution visibility; MIDHANI/Astra diversified growth. Tailwinds >> Headwinds; risks manageable via capex (e.g., metal banks, DSIC).
Valuation Context: Sustained 20-30% EBITDA, order books 2-3x FY revenue imply re-rating. Monitor QRSAM contract (Q4 FY26) as catalyst. Overall: High Growth, Moderate Risk – Strategic buy for 3-5 yr horizon.
Press Release
asof: 2025-11-30
Indian Aerospace & Defense Sector Analysis (Based on Provided Announcements)
The provided documents highlight announcements from 12 key players (PSUs like BEL, HAL, BDL, GRSE, MIDHANI; private firms like Data Patterns, Zen Technologies, Apollo Micro Systems, Astra Microwave, MTAR Technologies, AXISCADES, Paras Defence) spanning FY24-25 results, Q2/H1 FY26 updates, order wins, and strategic MoUs. These reflect a robust sector buoyed by government indigenization (Aatmanirbhar Bharat), surging orders, and export growth, but with pockets of quarterly volatility. Overall order books exceed Rs. 35,000+ Cr across sampled firms, signaling multi-year visibility. Below is a structured summary of headwinds, tailwinds, growth prospects, and key risks.
Tailwinds (Strong Positive Drivers)
- Order Inflows & Backlog Explosion: Massive wins across segments—BEL (Rs. 528 Cr: radars/jammers), BDL (Rs. 6,668 Cr new orders; Rs. 22,700 Cr book), Data Patterns (Rs. 1,287 Cr book incl. negotiations), Zen (Rs. 108 Cr tank simulators), Paras (Rs. 40 Cr counter-drone/RF jammers), Astra (Rs. 2,209 Cr consolidated book). GRSE/MTAR report strong execution pipelines.
- Revenue & Profit Growth: Stellar performances—BDL FY25 turnover +40% (Rs. 3,300 Cr), exports +640% (Rs. 1,200 Cr); GRSE Q2 revenue +42%, PAT +57%; Data Patterns H1 revenue +109%, Astra H1 +7.2%; AXISCADES Q2 +13%, H1 EBITDA +26%.
- Export Momentum: Record highs—BDL/MIDHANI (Rs. 94 Cr, up 48%); Data Patterns’ first export radar success.
- Policy & Strategic Boost: HAL-UAC MoU for SJ-100 aircraft (civil defense pivot); Apollo-IIT-Chennai-Navy tripartite for EW/guidance tech; MoD simulation framework enabling Zen’s order.
- Diversification: Anti-drone (Paras/Zen/BEL), space (Astra-ISRO), civil aviation (HAL), simulators—aligning with UDAN/Atmanirbhar.
Headwinds (Challenges & Pressure Points)
- Quarterly Volatility: Dips noted—Astra Q2 revenue -7% (Rs. 213 Cr), MTAR Q2 -13% QoQ (Rs. 136 Cr); AXISCADES non-core segments -11%.
- Margin Compression: Data Patterns Q2 gross margin 38.5% (vs. 76% YoY) due to low-margin strategic deliveries; Astra Q2 EBITDA margin stable but PAT -15%.
- Execution Intensity: H1 often <50% of annual revenue (e.g., AXISCADES notes H2 defense skew); supply chain/scale-up strains in high-tech (radars/EW).
- Sector Concentration: Heavy reliance on MoD (90%+ orders for many); automotive/energy slowdowns hit AXISCADES.
Growth Prospects (High Potential, Multi-Year Horizon)
- Revenue Visibility: Order books imply 2-4x FY25 revenue coverage (e.g., BDL Rs. 22.7k Cr vs. Rs. 3.3k Cr sales); MTAR guides 30-35% FY26 growth (vs. prior 25%), AXISCADES targets Rs. 9,000 Cr by FY30 (+40% CAGR core domains).
- Indigenization Tailwind: 15-year MoD roadmap for next-gen comms/warfare/anti-drone; HAL’s SJ-100 as “game-changer” for regional jets (200+ needed); GRSE’s warship dominance (114+ delivered).
- Export & Private Capex: 640% surges signal global traction; private firms (Data Patterns/Zen) gaining MoD repeat trust.
- Capacity/Infra Ramp: AXISCADES’ 3M sq.ft. complex; MTAR’s 9 units; collaborations (Apollo MoU) for R&D scale.
- Projections: Sector poised for 15-20% CAGR (aligned with budget hikes), driven by Rs. 6L+ Cr defense capex pipeline.
Key Risks (Notable Vulnerabilities)
- Execution & Delay Risks: Large projects (ships/radars) prone to slippage (GRSE/MTAR emphasize “project execution strategy”); H2 dependency amplifies.
- Geopolitical/Supply Chain: Import reliance lingers; Russia ties (HAL) vulnerable to sanctions; raw material inflation (MIDHANI sales flat YoY).
- Margin & Competition Pressures: Low-margin strategic bids (Data Patterns); rising private competition in drones/EW.
- Macro/Regulatory: Budget cuts, election cycles, forex volatility (exports 10-15%); forward-looking disclaimers cite economic/tax/litigation risks.
- Overdependence: 85-90% domestic/MoD exposure; non-core slowdowns (AXISCADES automotive).
Overall Summary
The sector exhibits strong tailwinds from policy-driven indigenization and order surges, outweighing headwinds like quarterly dips and margin squeezes. Growth prospects are exceptional (30%+ FY26 upside for leaders like BDL/GRSE/Data Patterns), fueled by Rs. 25,000+ Cr order books and exports. However, risks center on execution in a capex-heavy environment. Bullish outlook: Sector could mirror BDL’s 40% growth trajectory, targeting self-reliance in radars/EW/drones/ships. Investors should monitor H2 execution and MoD budgets for confirmation. Positive sentiment reinforced by MoUs and record milestones.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.