GREAVESCOT
Equity Metrics
November 18, 2026
Greaves Cotton Limited
Compressors Pumps & Diesel Engines
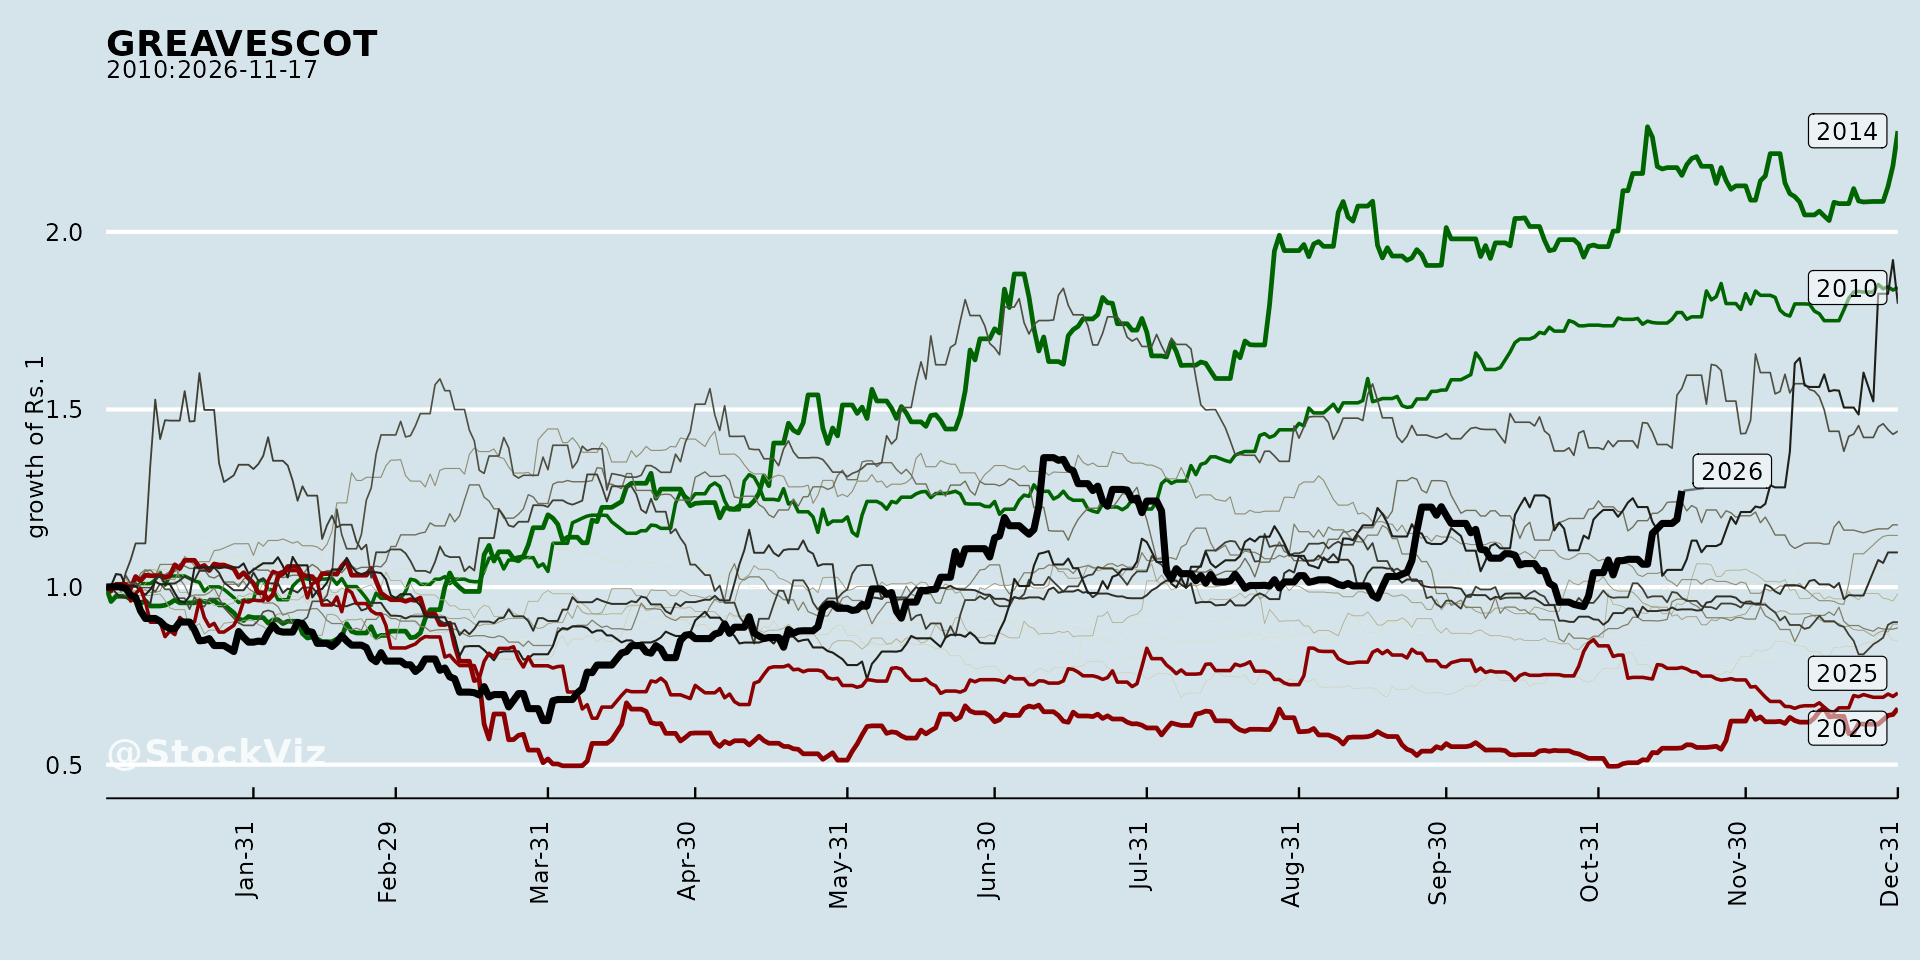
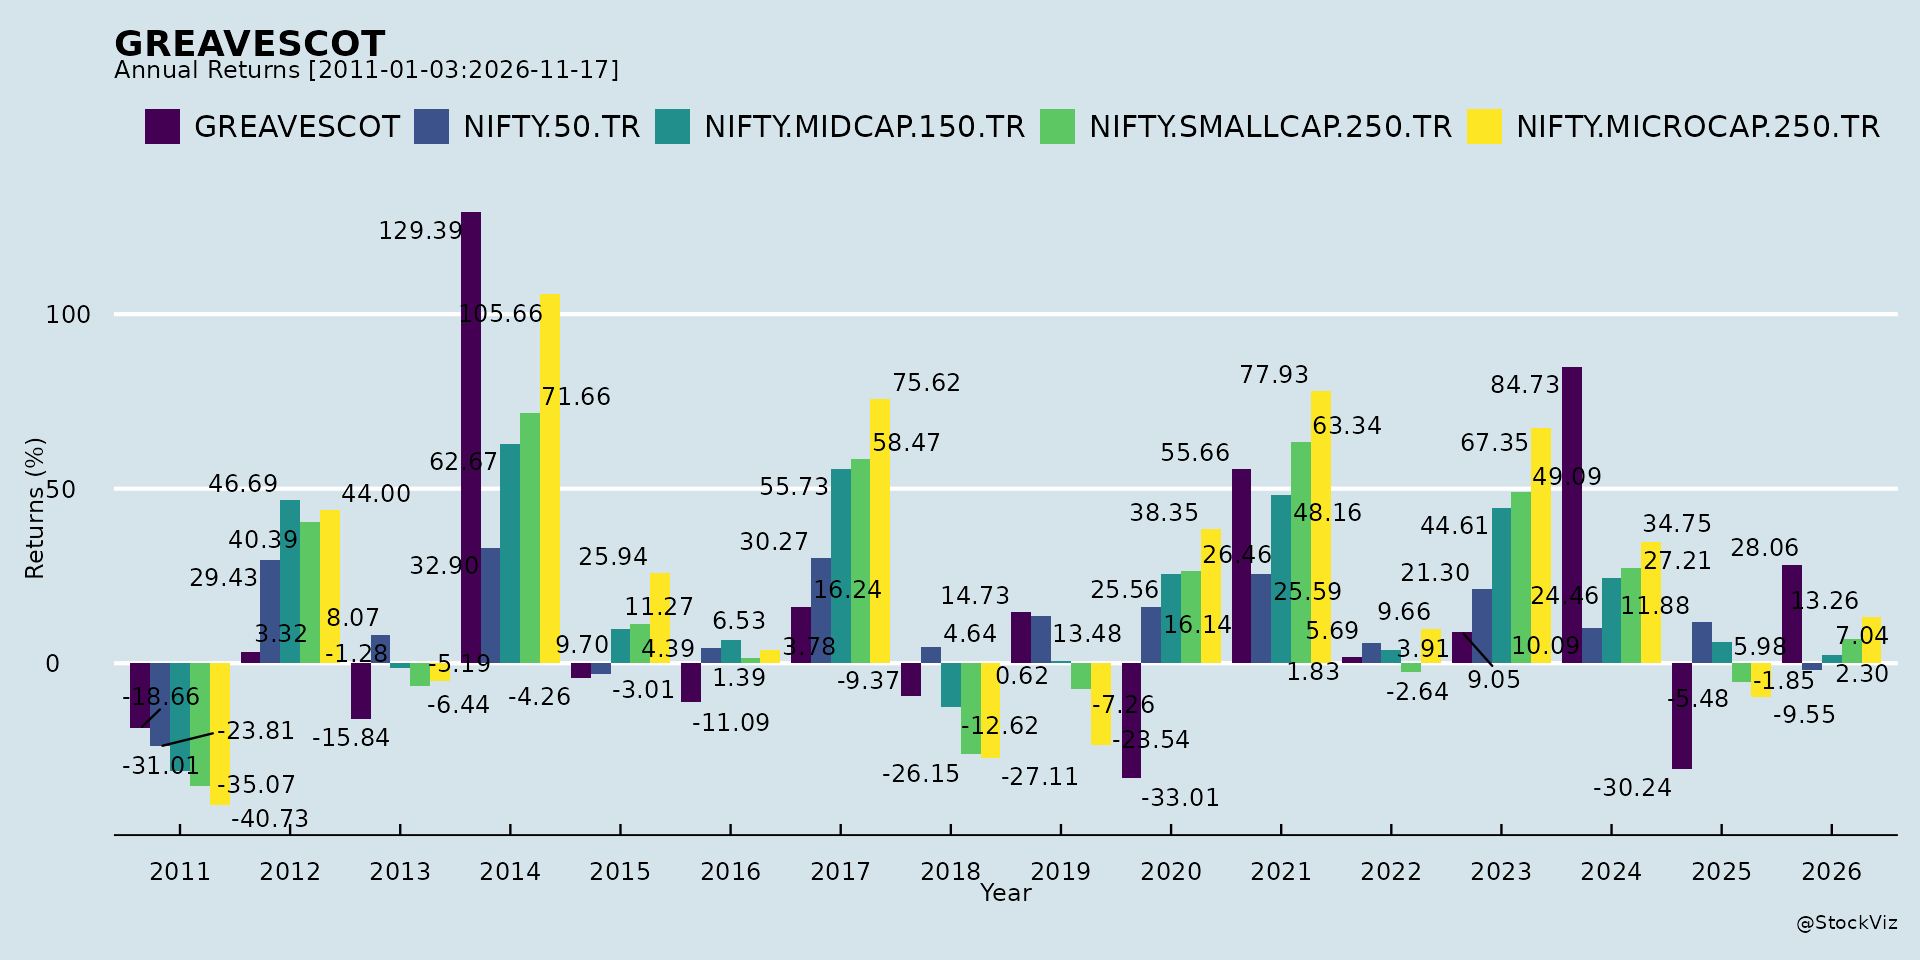
Annual Returns
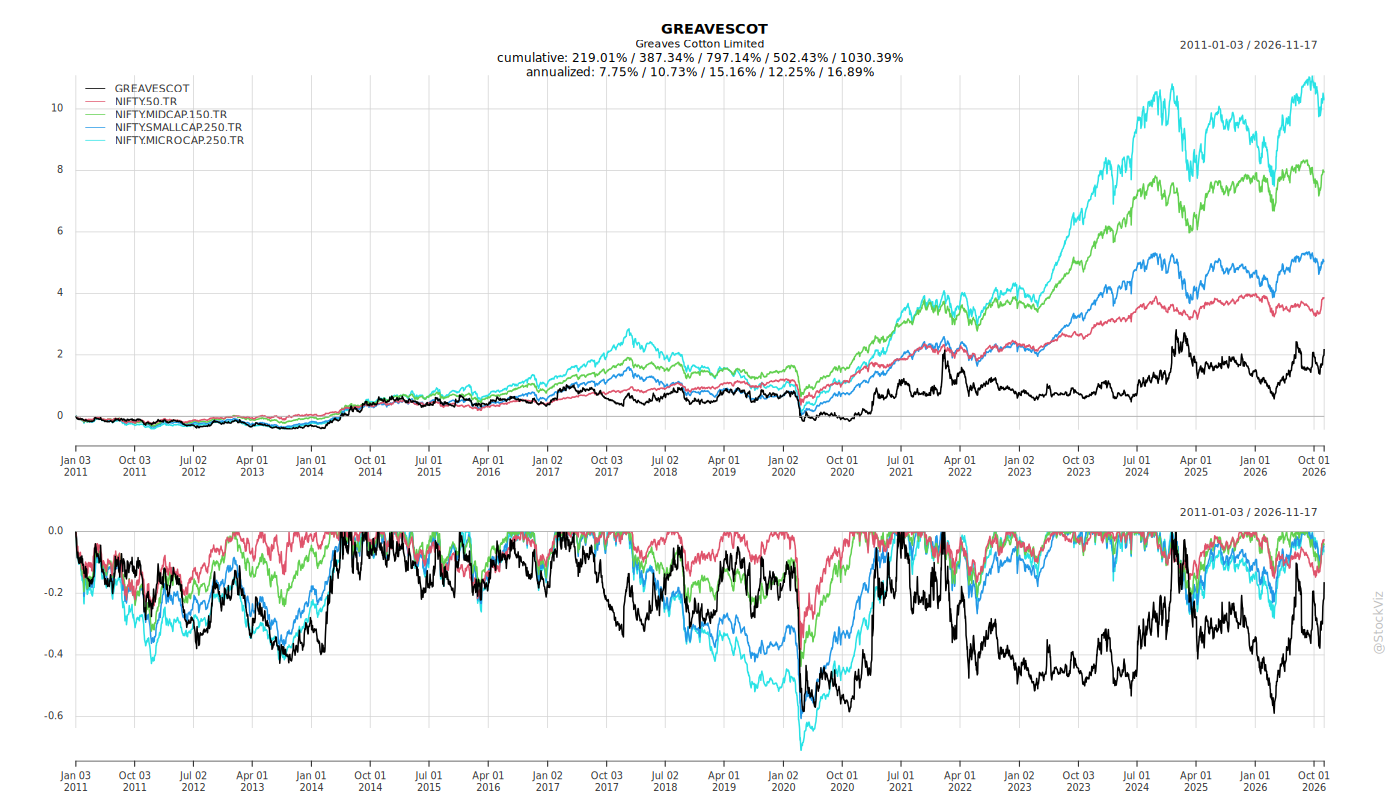
Cumulative Returns and Drawdowns
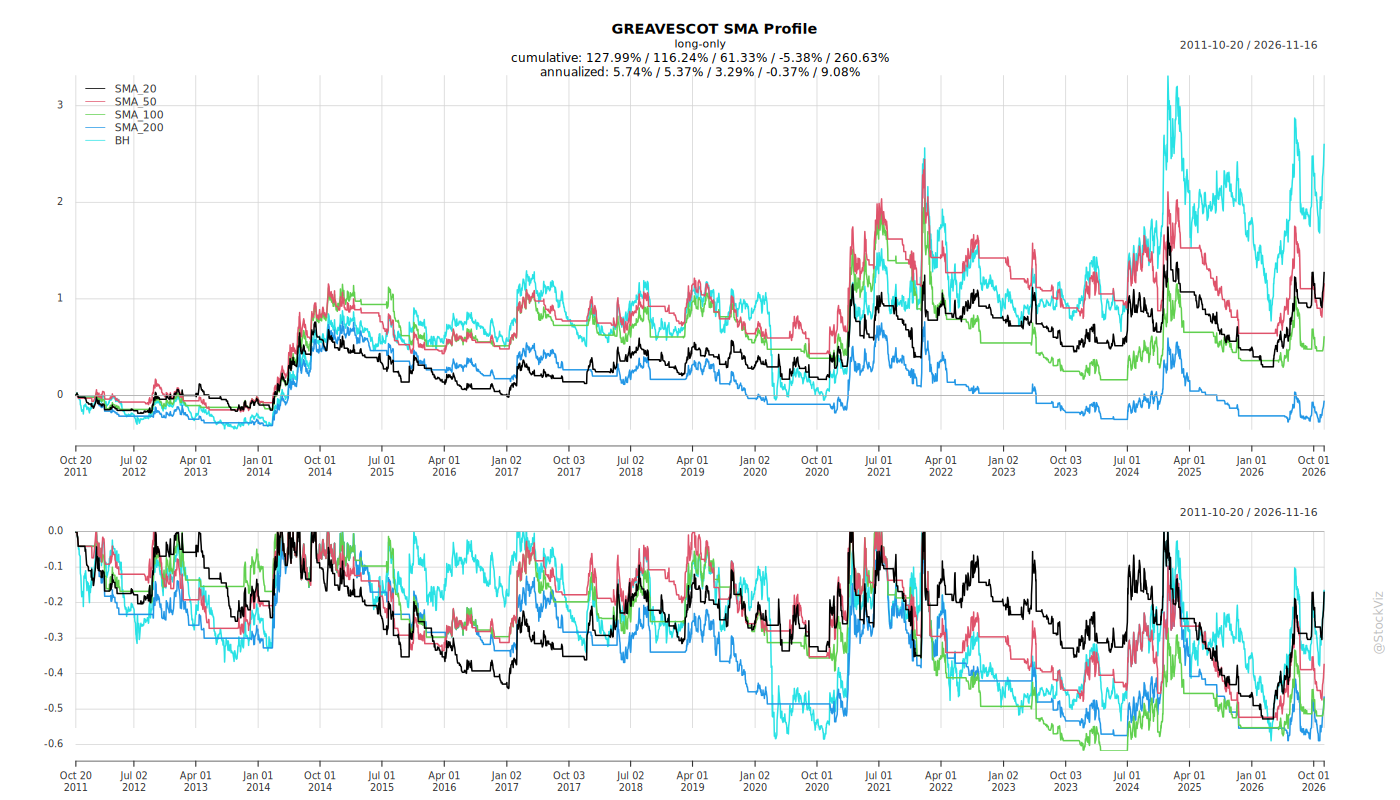
Fundamentals
Ownership
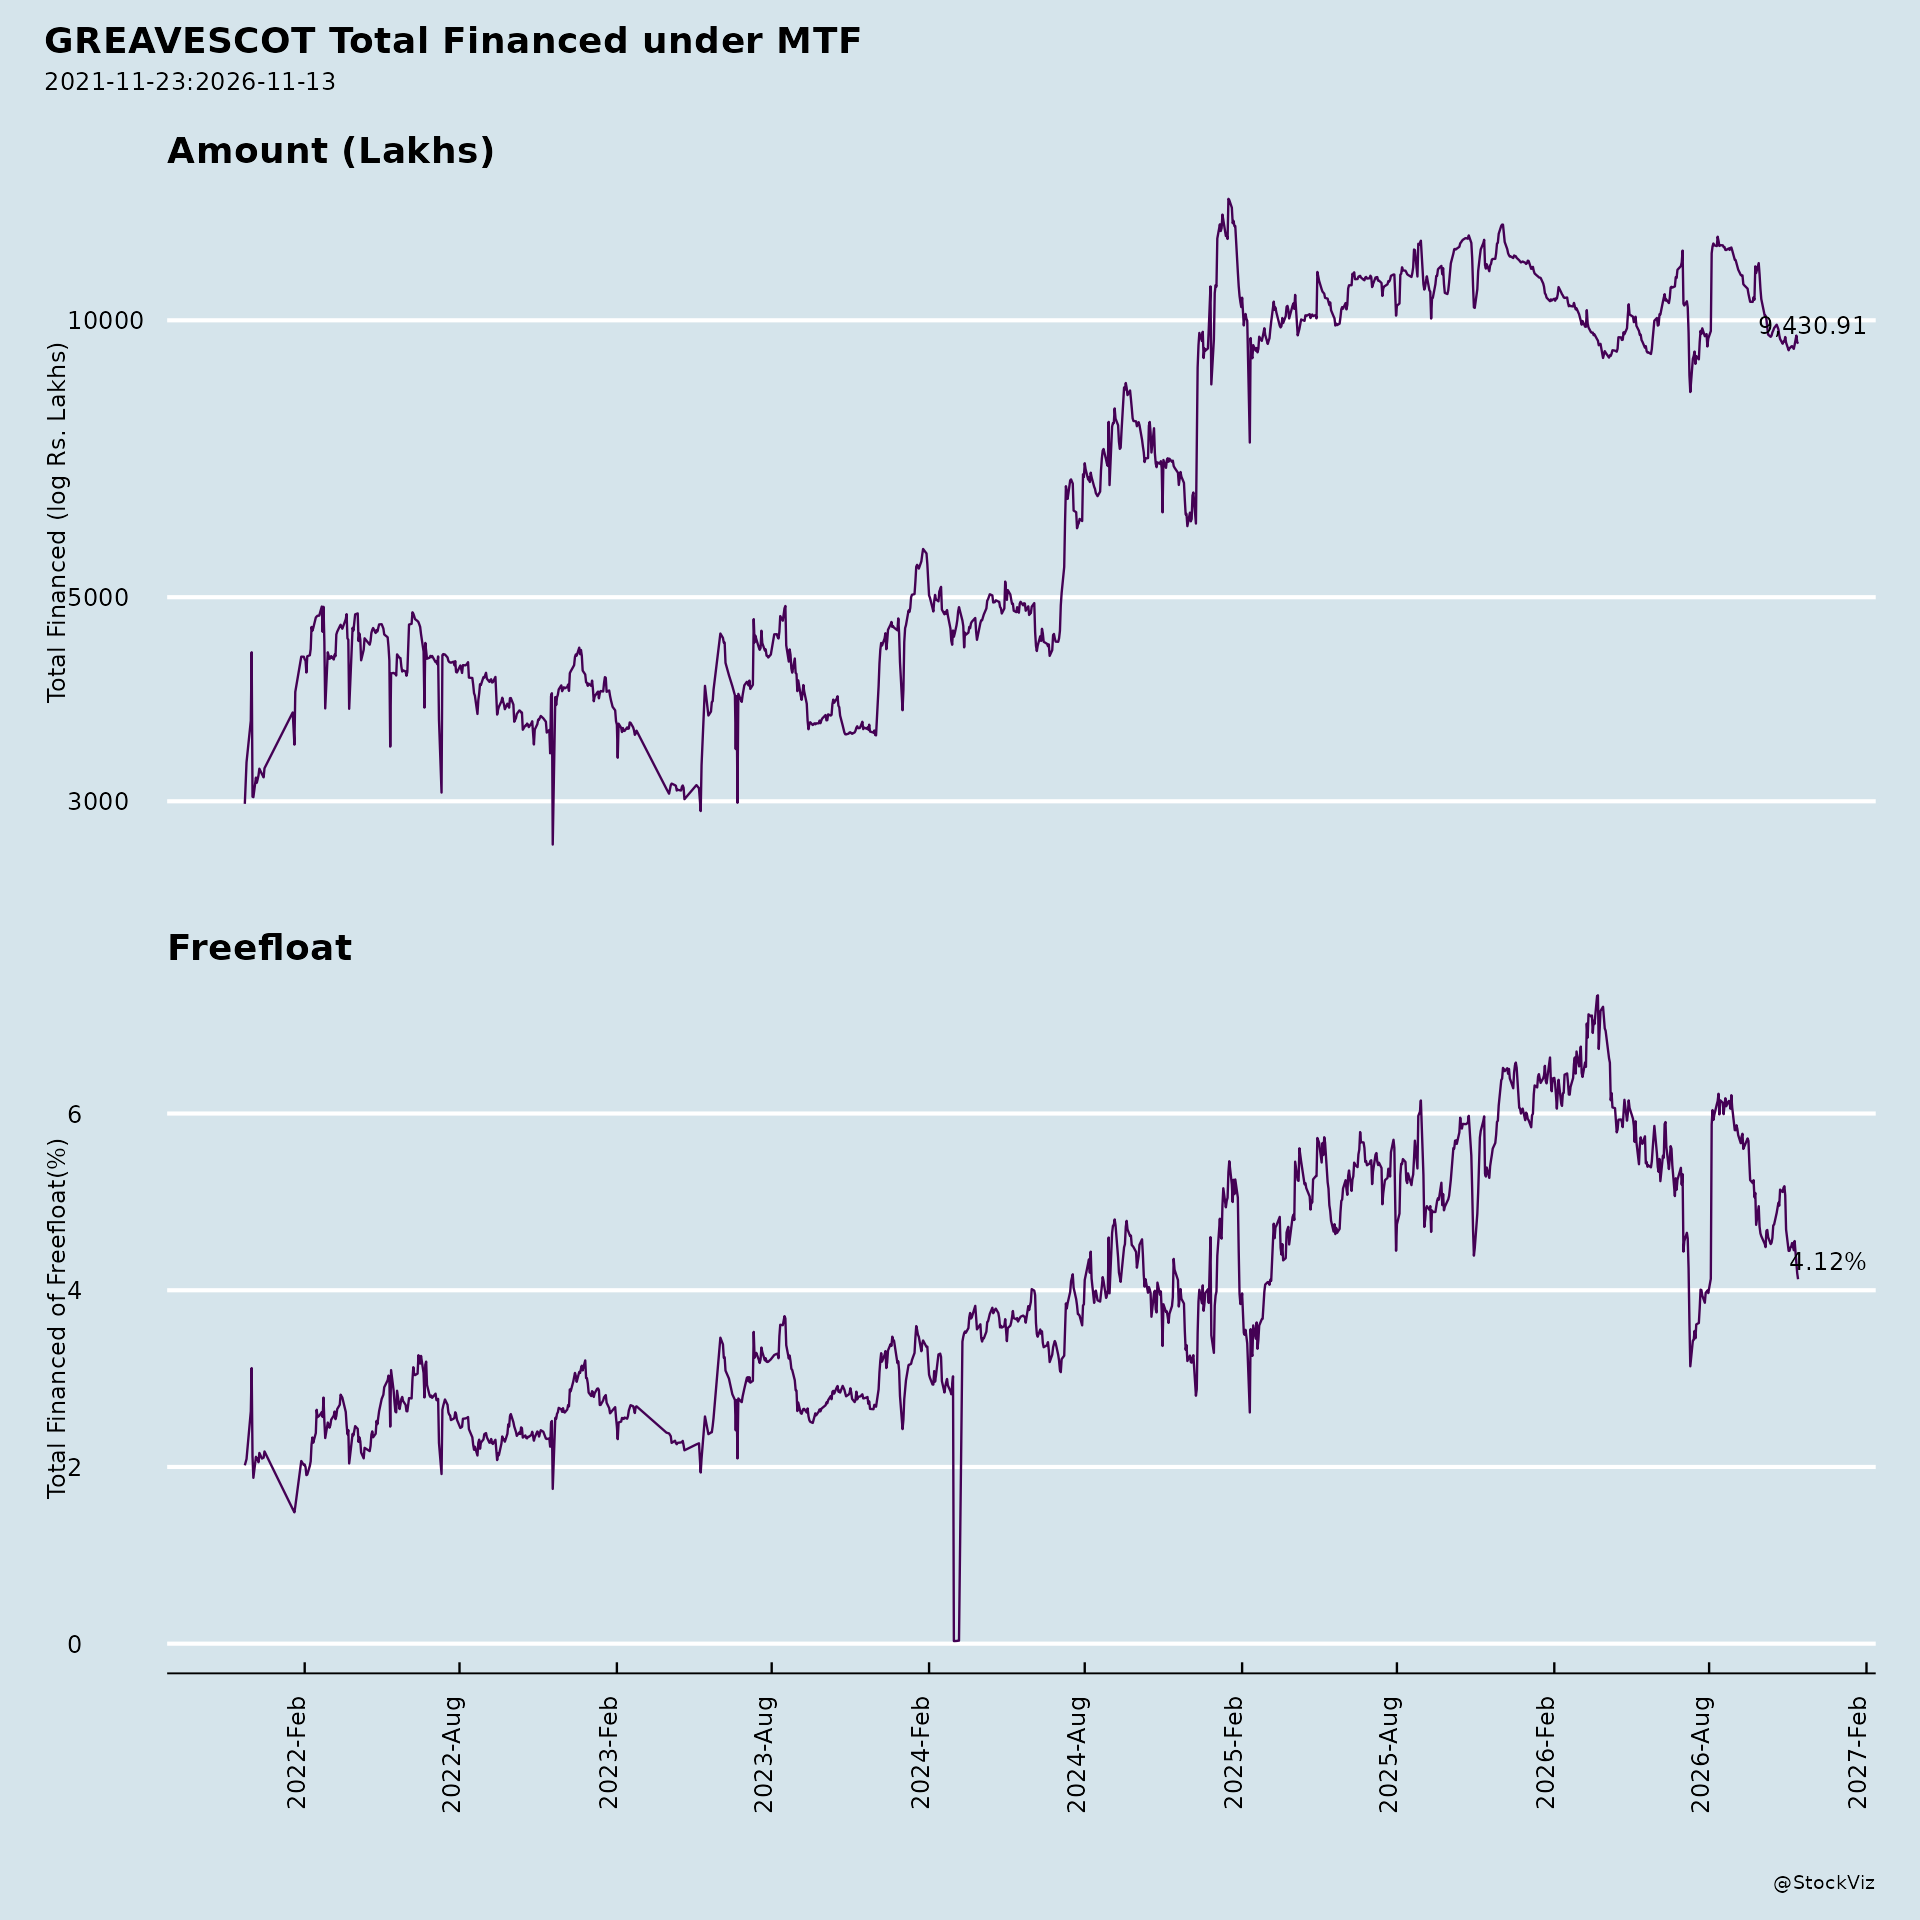
Margined
AI Summary
asof: 2026-09-17
Headwinds and Challenges
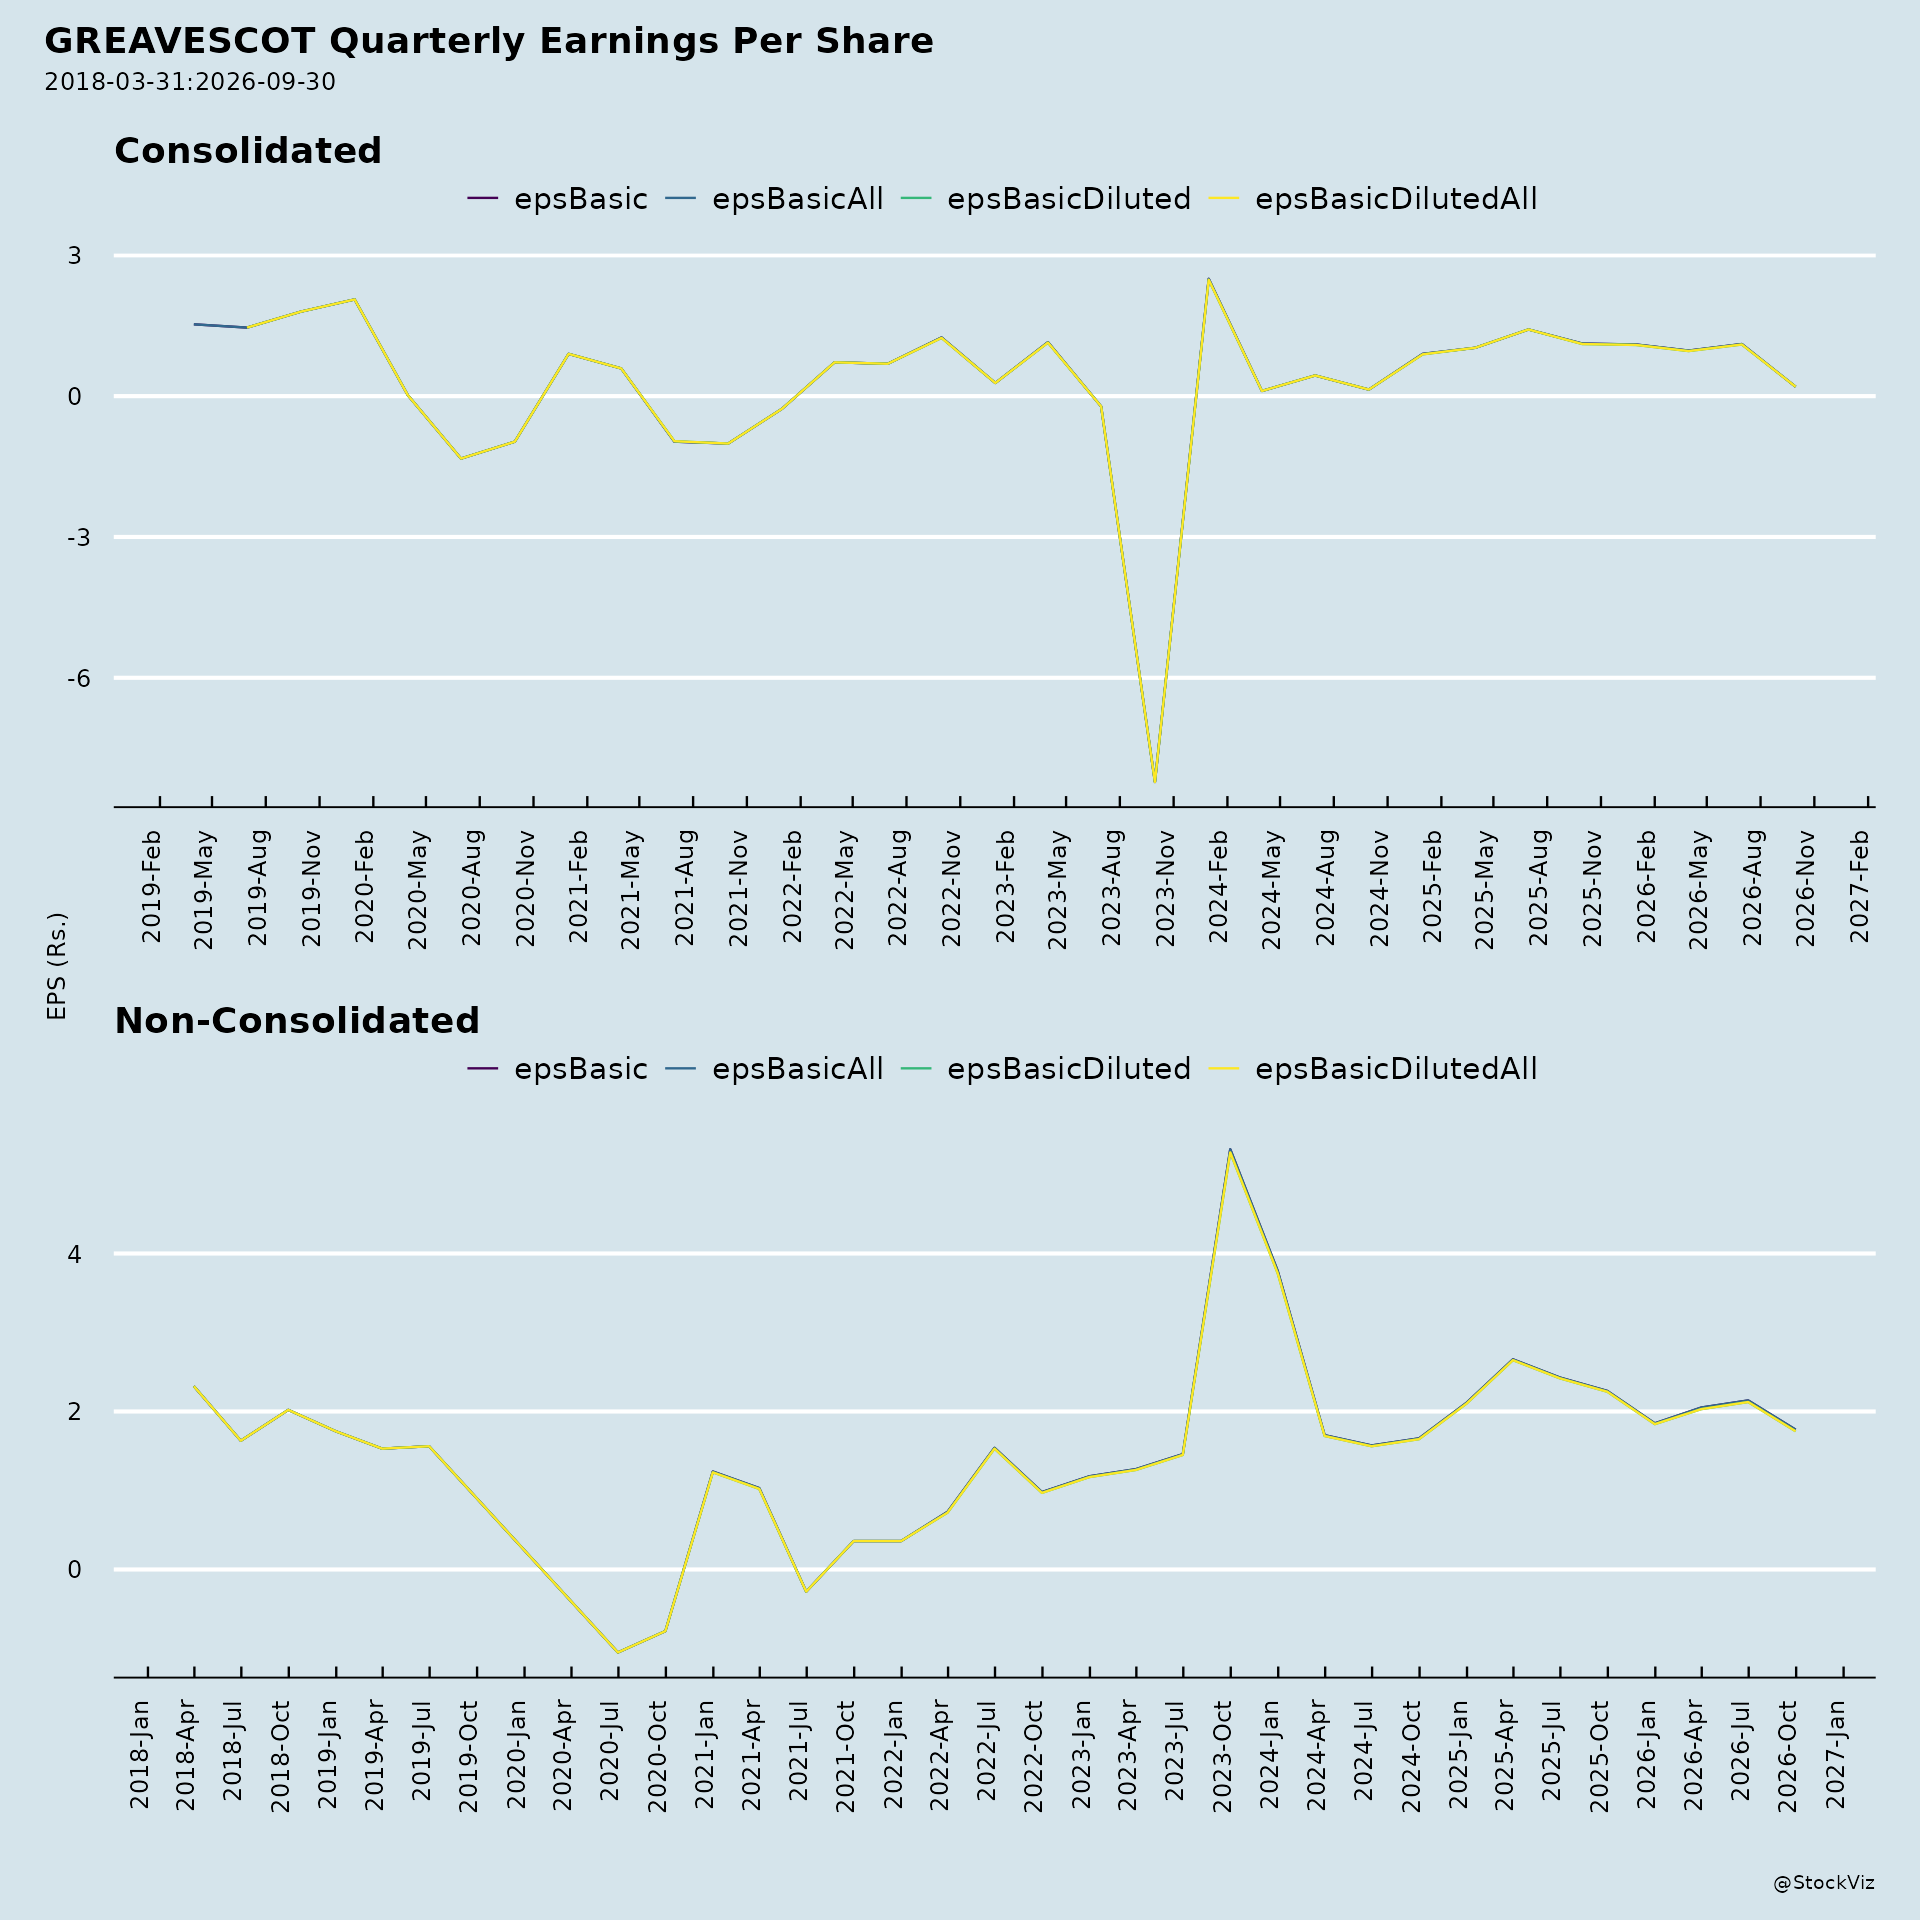
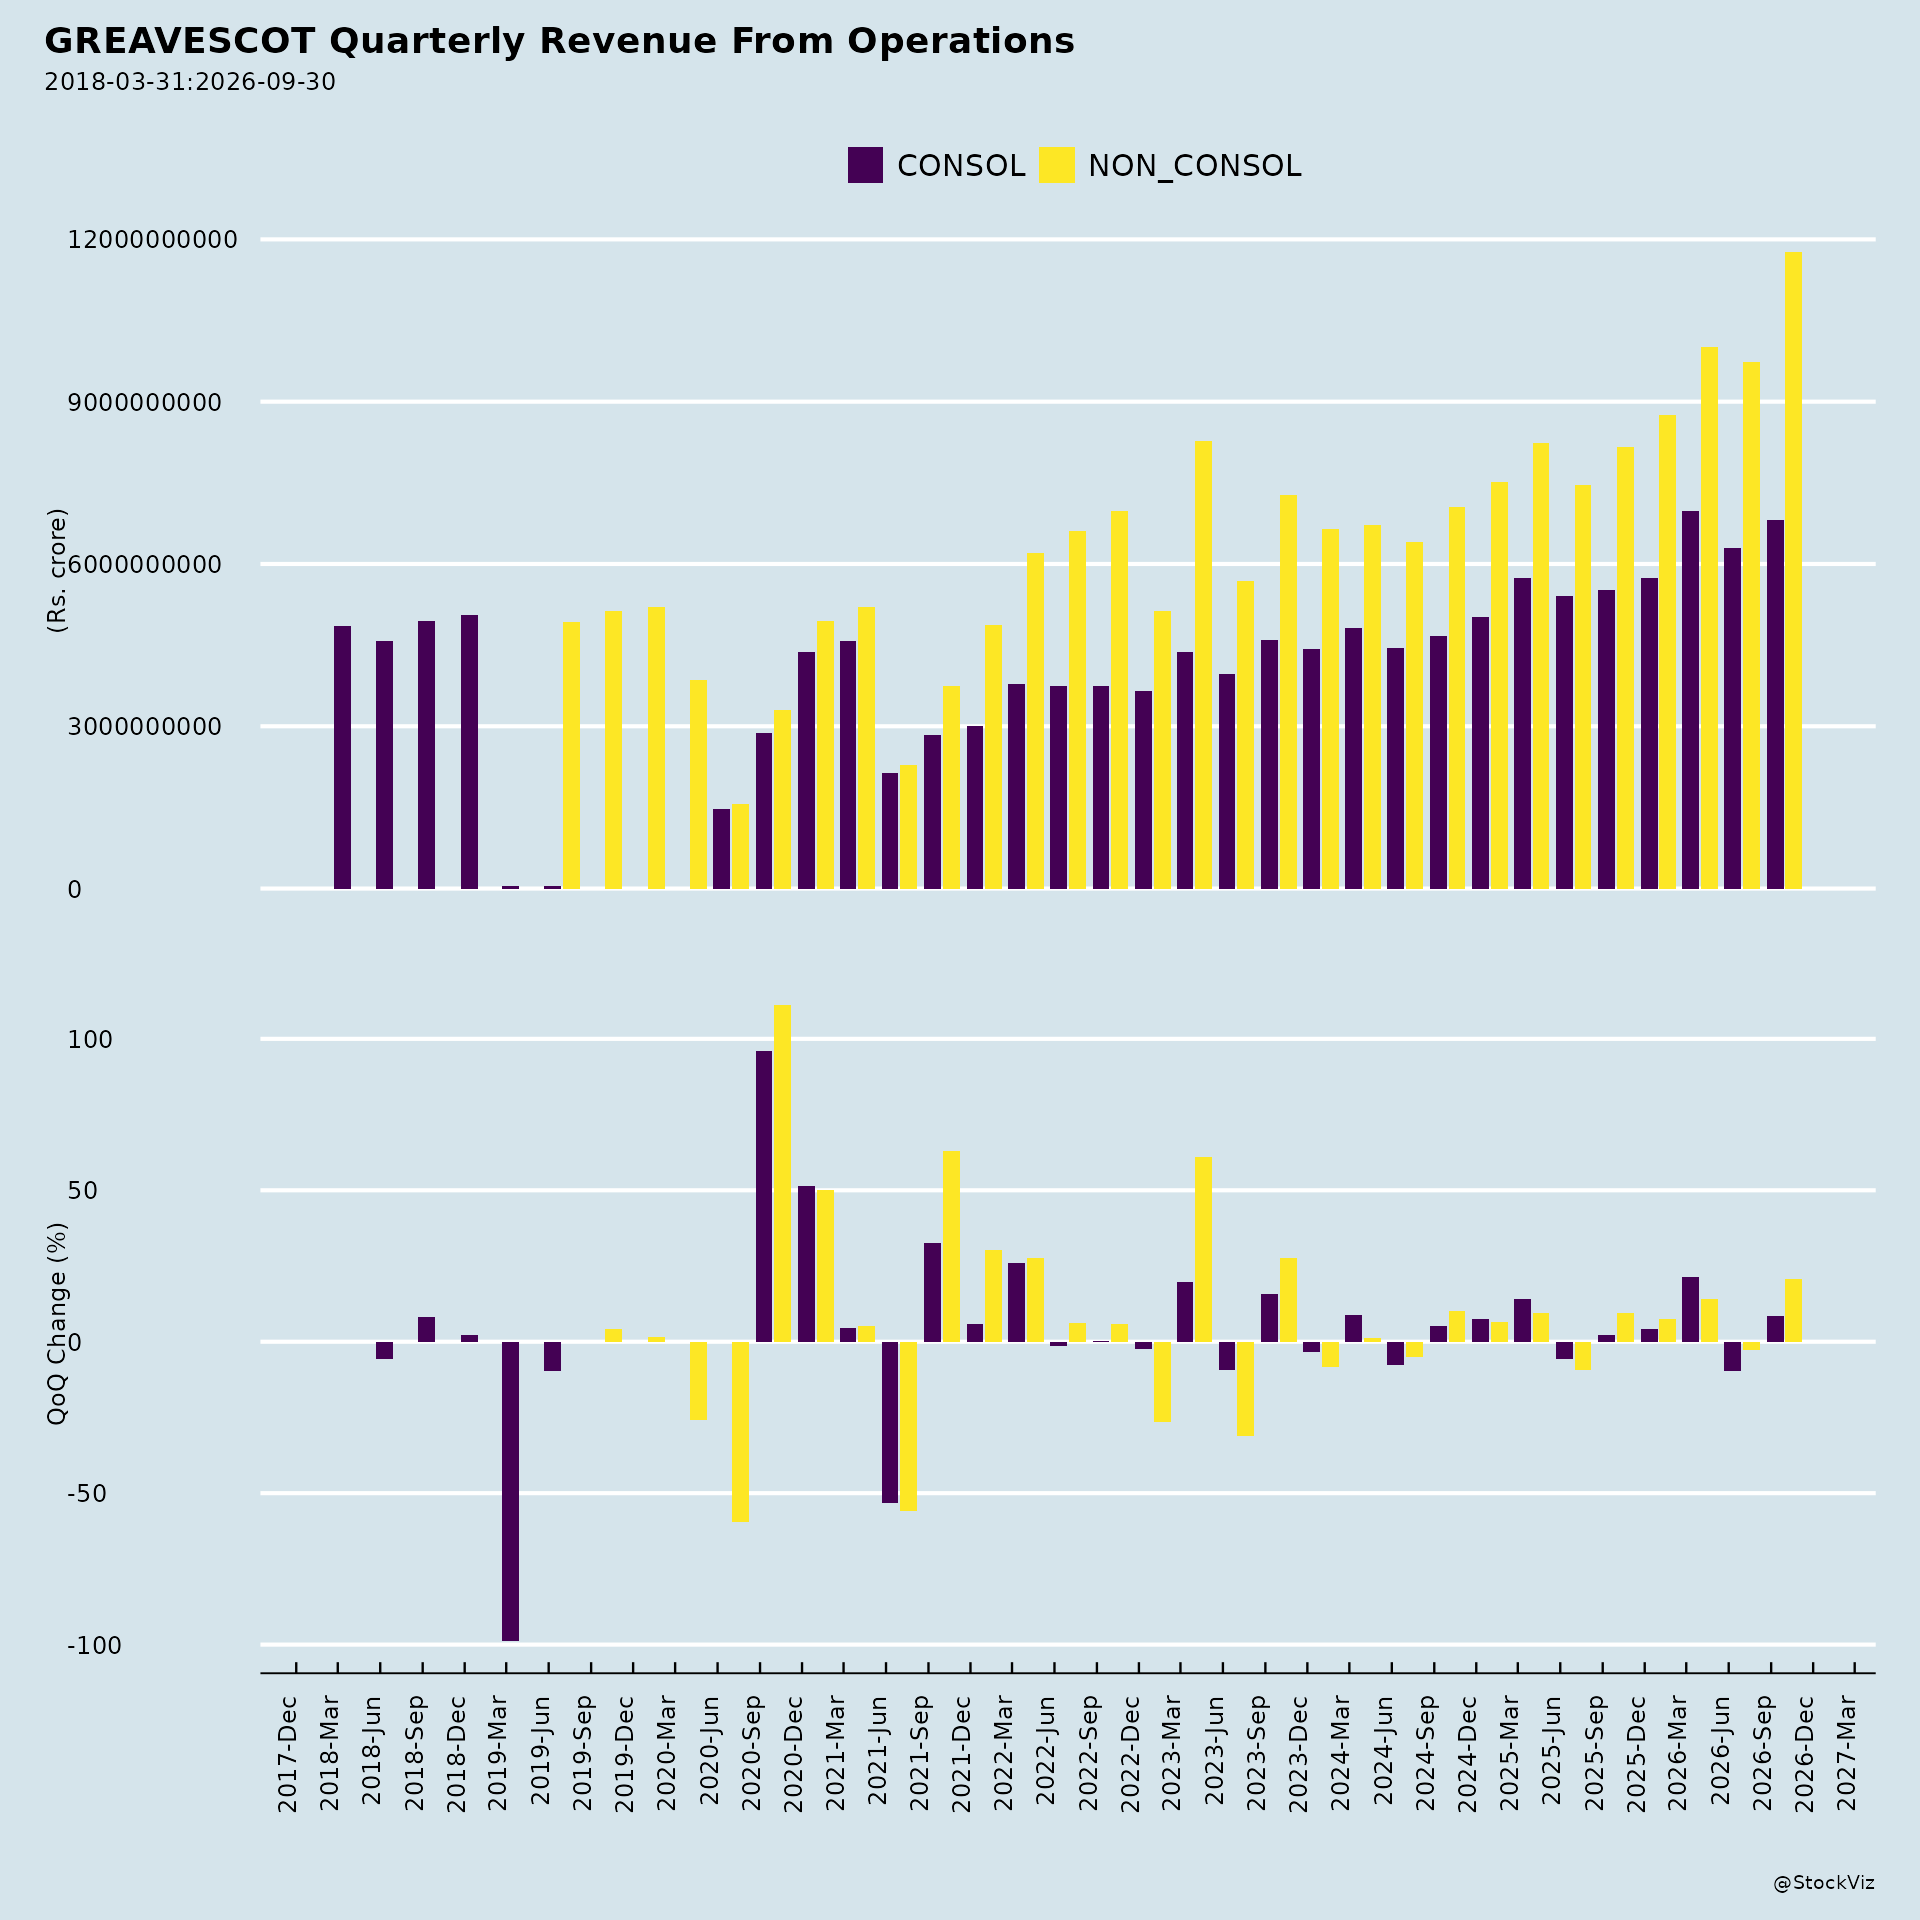
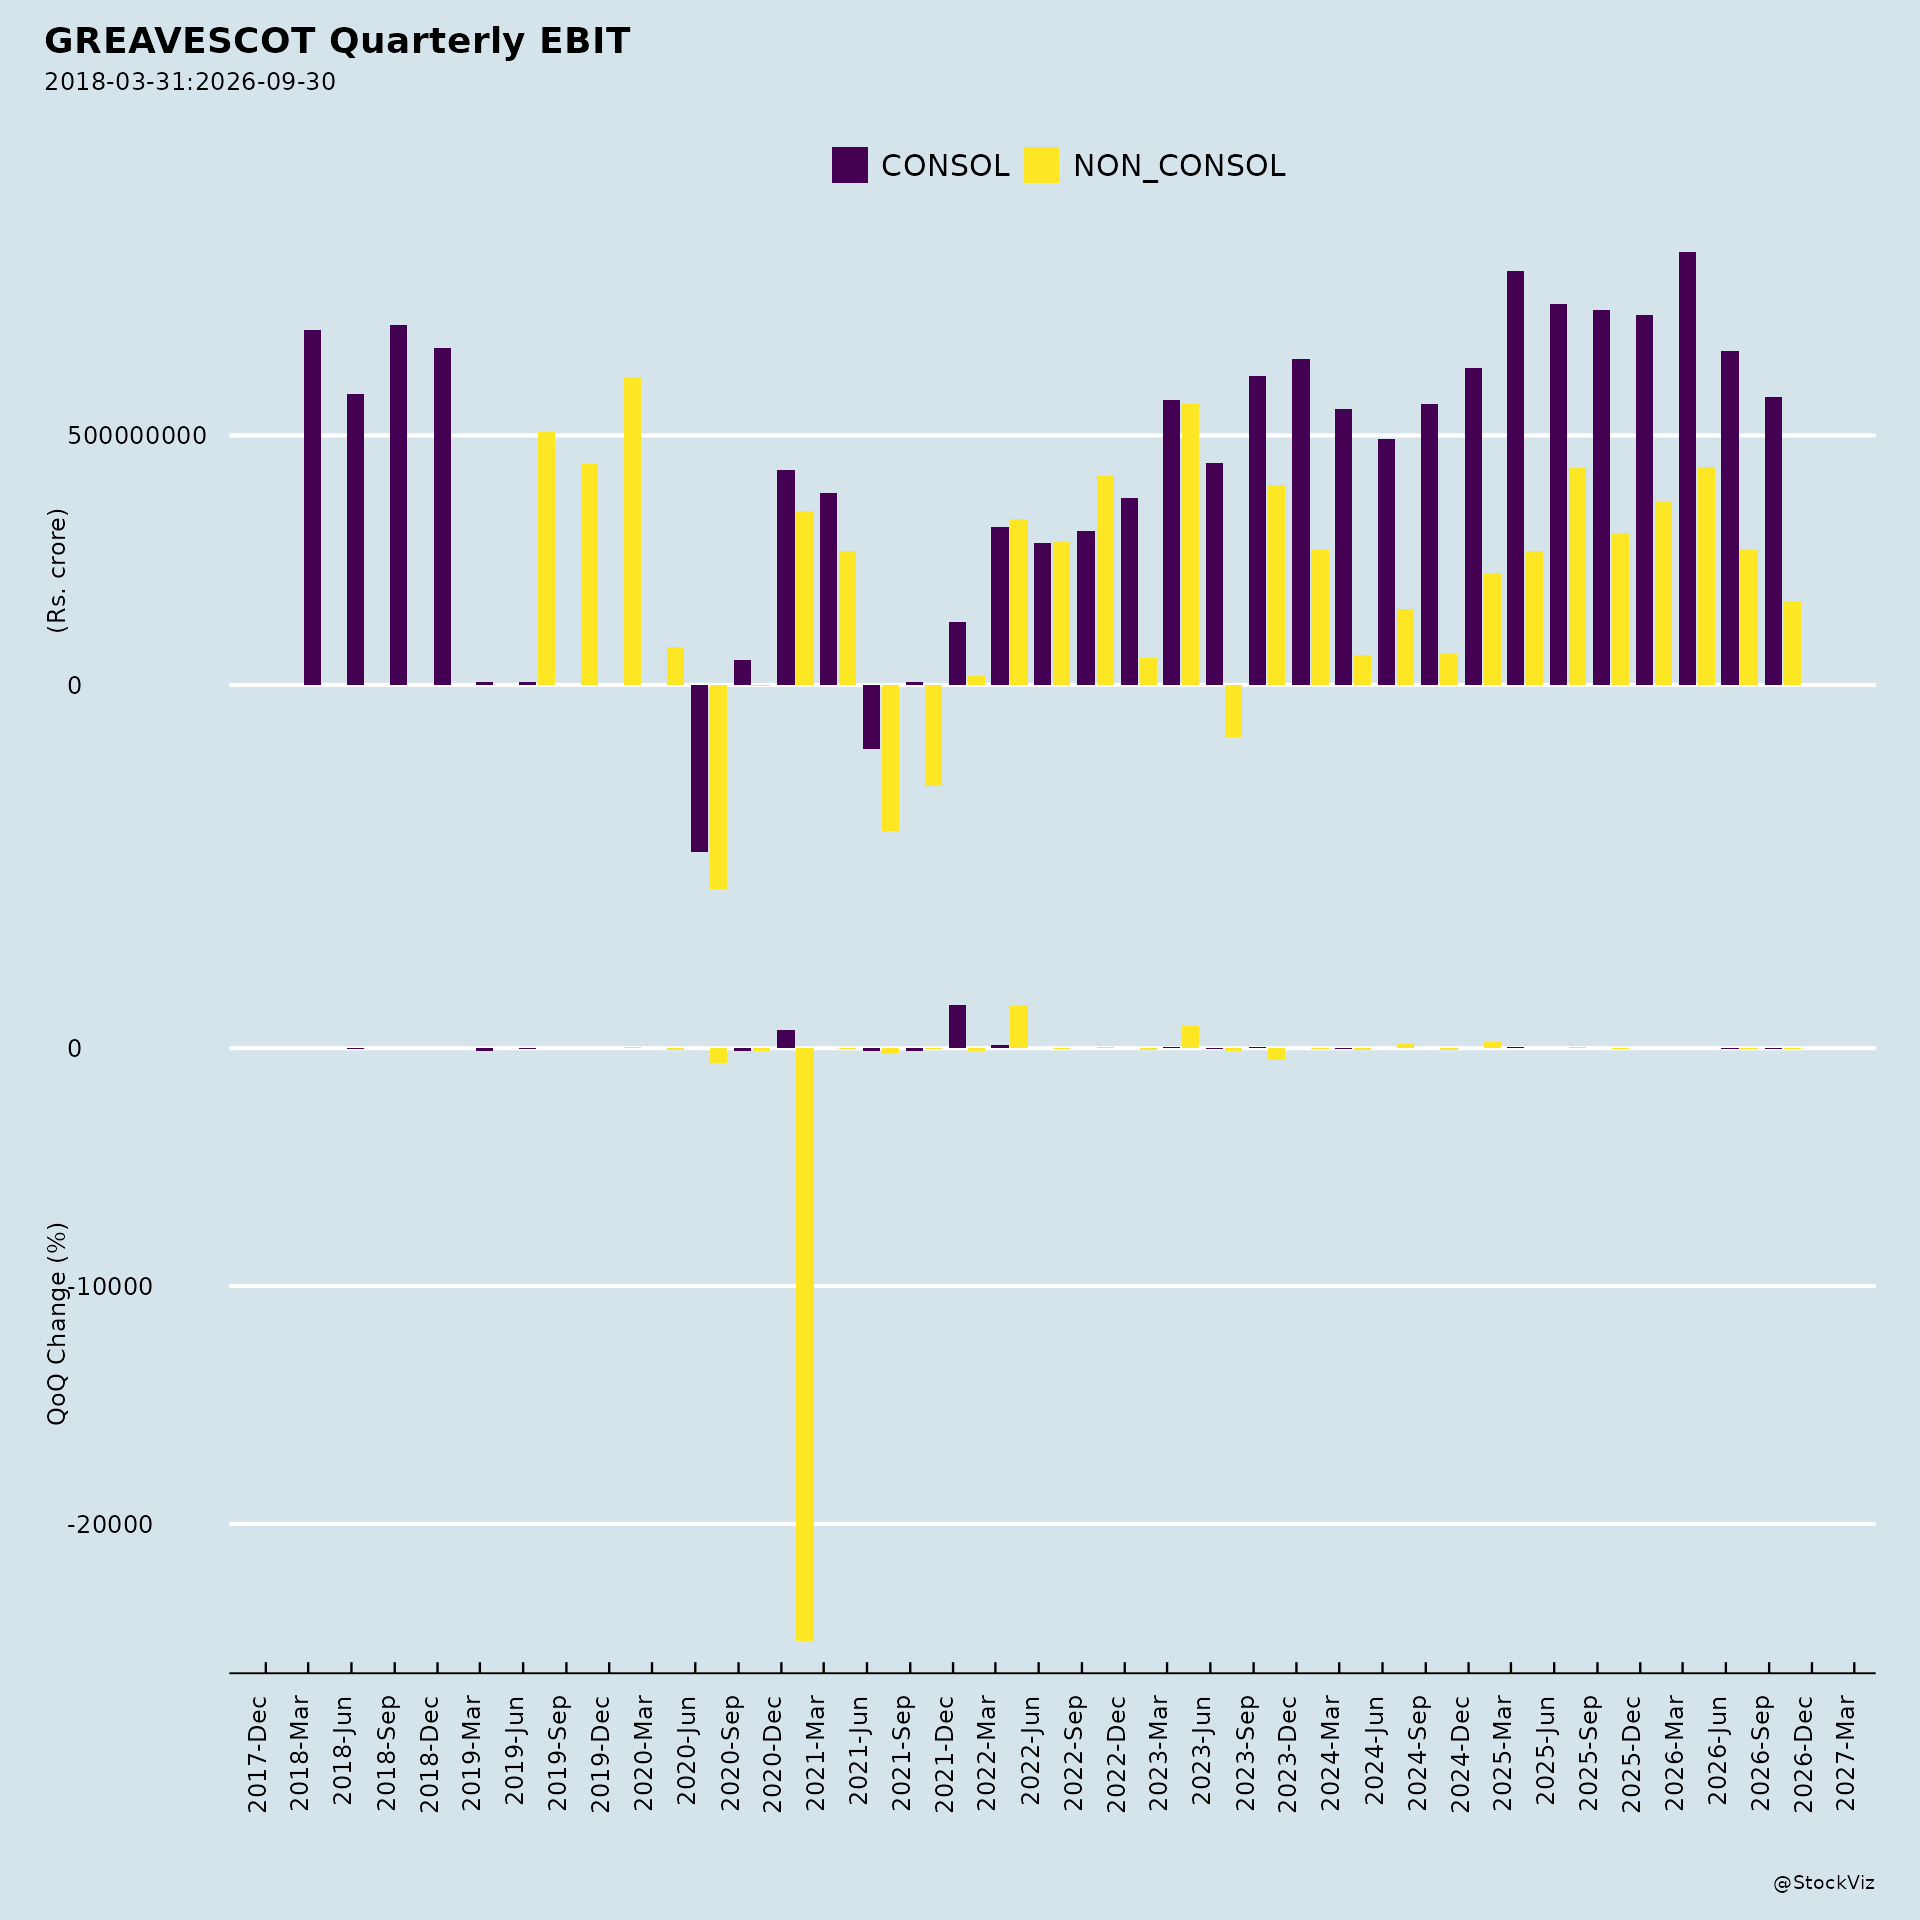
Margin compression despite revenue growth. In Q1 FY27, GCL Consolidated revenue grew 31% YoY to ₹974 crore, but EBITDA declined 1% to ₹56 crore and EBITDA margin fell from 7.6% to 5.8%. Core Businesses revenue grew 16% YoY to ₹710 crore, yet EBITDA fell 2% to ₹90 crore with margin declining from 14.9% to 12.6%. GCL Standalone EBITDA declined 7% to ₹71 crore with margin down from 14.0% to 11.3%. The company attributes this to higher commodity costs during the quarter alongside deliberate investments in capabilities and growth initiatives.
Industrial Solutions decline. Industrial Solutions revenue fell 4% YoY to ₹80 crore in Q1 FY27 (9% growth post portfolio rationalization).
Prior exceptional charges. In the quarter ended March 31, 2026, an impairment provision of ₹15.98 crore was recognized on tangible and intangible assets under development, following an impairment indicator from significant adverse changes in expected project execution and customer demand. A ₹15.75 crore provision was also accrued in FY26 related to the four Labour Codes notified on November 21, 2025, with finalization of Central/State Rules still being monitored.
GEML IPO withdrawal. On July 31, 2026, GEML informed SEBI and the stock exchanges that it would not avail the one-time relaxation (SEBI circular dated April 7, 2026) permitting extension of validity of observation letters expiring between April 1 and September 30, 2026. The SEBI Final Observations dated May 8, 2025 lapsed, and GEML stated it will not proceed with the IPO, citing the proposed rights issue and restrictions under SEBI ICDR Regulations on further issuances.
Subsidiary losses. The consolidated review report notes that one subsidiary’s consolidated results and two subsidiaries’ standalone results reflect total revenues of ₹296.38 crore and total net loss after tax of ₹53.68 crore for Q1 FY27. Segment results show Electric Mobility & Other Vehicles reported a loss of ₹45.77 crore in Q1 FY27.
Retail supply constraints. The Retail business demonstrated operational resilience “despite supply constraints,” with portfolio pruning now completed.
Tailwinds and Growth Prospects
Strong consolidated and core revenue growth. Consolidated revenue grew 31% YoY in Q1 FY27, with growth across both Core and investee businesses. Core businesses grew 16% YoY (19% post portfolio rationalization).
Energy Solutions momentum. Energy Solutions revenue grew 21% YoY to ₹203 crore. The domestic MHP (58.5–500 KVA) genset business grew 32% YoY. The company deployed its first 1250 kVA Megaseries genset in SAARC, commissioned a BESS pilot, and continues focus on export markets in Africa, SAARC, and the Middle East.
Mobility Solutions growth. Mobility Solutions revenue grew 18% YoY to ₹427 crore, with strong revenue growth of 36% YoY in the Auto segment supported by domestic demand and steady exports. Share of non-3W diesel engines OE business reached 60% in Q1 FY27. Engineered Components grew 14% YoY, securing new OEM orders from CAT (UK) and TAFE.
GEML EV performance. E2W volumes grew 101% YoY in Q1 FY27, with market share expanding from 4.3% in FY26 to 5.6% in June 2026. GEML achieved a milestone of 4 lakh electric scooters sold and market leadership in Bihar with 19%+ market share. L5 Vahan volumes grew 39% YoY. GEML raised ₹530 crore through a fully subscribed rights issue, with GCL fully subscribing to its entitlement of approximately ₹331 crore.
GFL expansion. Greaves Finance Limited’s total managed AUM rose to ₹560 crore from ₹521 crore in March 2026, expanded to 86 locations (12 more added), and raised ₹50 crore from GCL, increasing net worth to ₹153 crore.
International expansion. International business revenue share is at 13% of Core business sales. A wholly owned subsidiary, Greaves International Trading FZE, was incorporated in Dubai, UAE, as a gateway to the Middle East and Africa.
Strategic initiatives. The company appointed a CTO to lead R&D and New Product Development, commissioned a Robotic Gantry Cell at the CSN manufacturing facility, and initiated delivery of FM-UL compliant fire-fighting engines for export customers while executing a defence order for direct supply to the Armed Force.
Key Risks
The investor presentation’s disclaimer identifies known or unknown risks and uncertainties that could cause actual results to differ materially, including: general economic and business conditions in India and overseas; ability to successfully implement strategy; research and development efforts; growth and expansion plans; technological changes; changes in the value of the Indian Rupee and other currency changes; changes in Indian and international interest rates; changes in laws and regulations; increasing competition and industry conditions; changes in political conditions in India; and changes in foreign exchange control regulations in India.
The Greaves.Next strategy references to projected revenues, EBITDA margins, growth trajectories, operational targets, and future performance are based on management’s current assumptions, internal estimates, forecasts, and expectations, and are subject to significant risks, uncertainties, market dynamics, regulatory developments, execution challenges, and other factors, many beyond the company’s control.
Management Guidance Versus Observed Performance
Guidance provided (Greaves.Next): - Energy Solutions share to increase to become a dominant part of portfolio - Organic growth engine at 16–20% CAGR - EBITDA margins of 13–15% - Prudent investment plan of ₹500–700 crore - Expanding beyond India with focus on increasing international business share - Priority on execution discipline, portfolio mix optimization, and capital efficiency
Observed performance (Q1 FY27): - Core Businesses revenue grew 16% YoY, at the lower end of the 16–20% CAGR guidance range - Core Businesses EBITDA margin was 12.6%, below the 13–15% guided range - GCL Consolidated EBITDA margin was 5.8%, well below the guided range - International business revenue share stood at 13% of Core business sales, described as “on track” - Capex plans for Core businesses described as “on track”
The Q1 FY27 performance shows revenue growth within but at the lower bound of the guided organic growth range, while EBITDA margins remain below the guided 13–15% range for Core Businesses, with the company citing commodity costs and deliberate growth investments as factors.
Broker Timeline
1 broker calls · 2023-05-16 to 2023-05-16
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.