GODREJPROP
Equity Metrics
November 18, 2026
Godrej Properties Limited
Residential Commercial Projects
Annual Returns
Cumulative Returns and Drawdowns

Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
Headwinds and Challenges
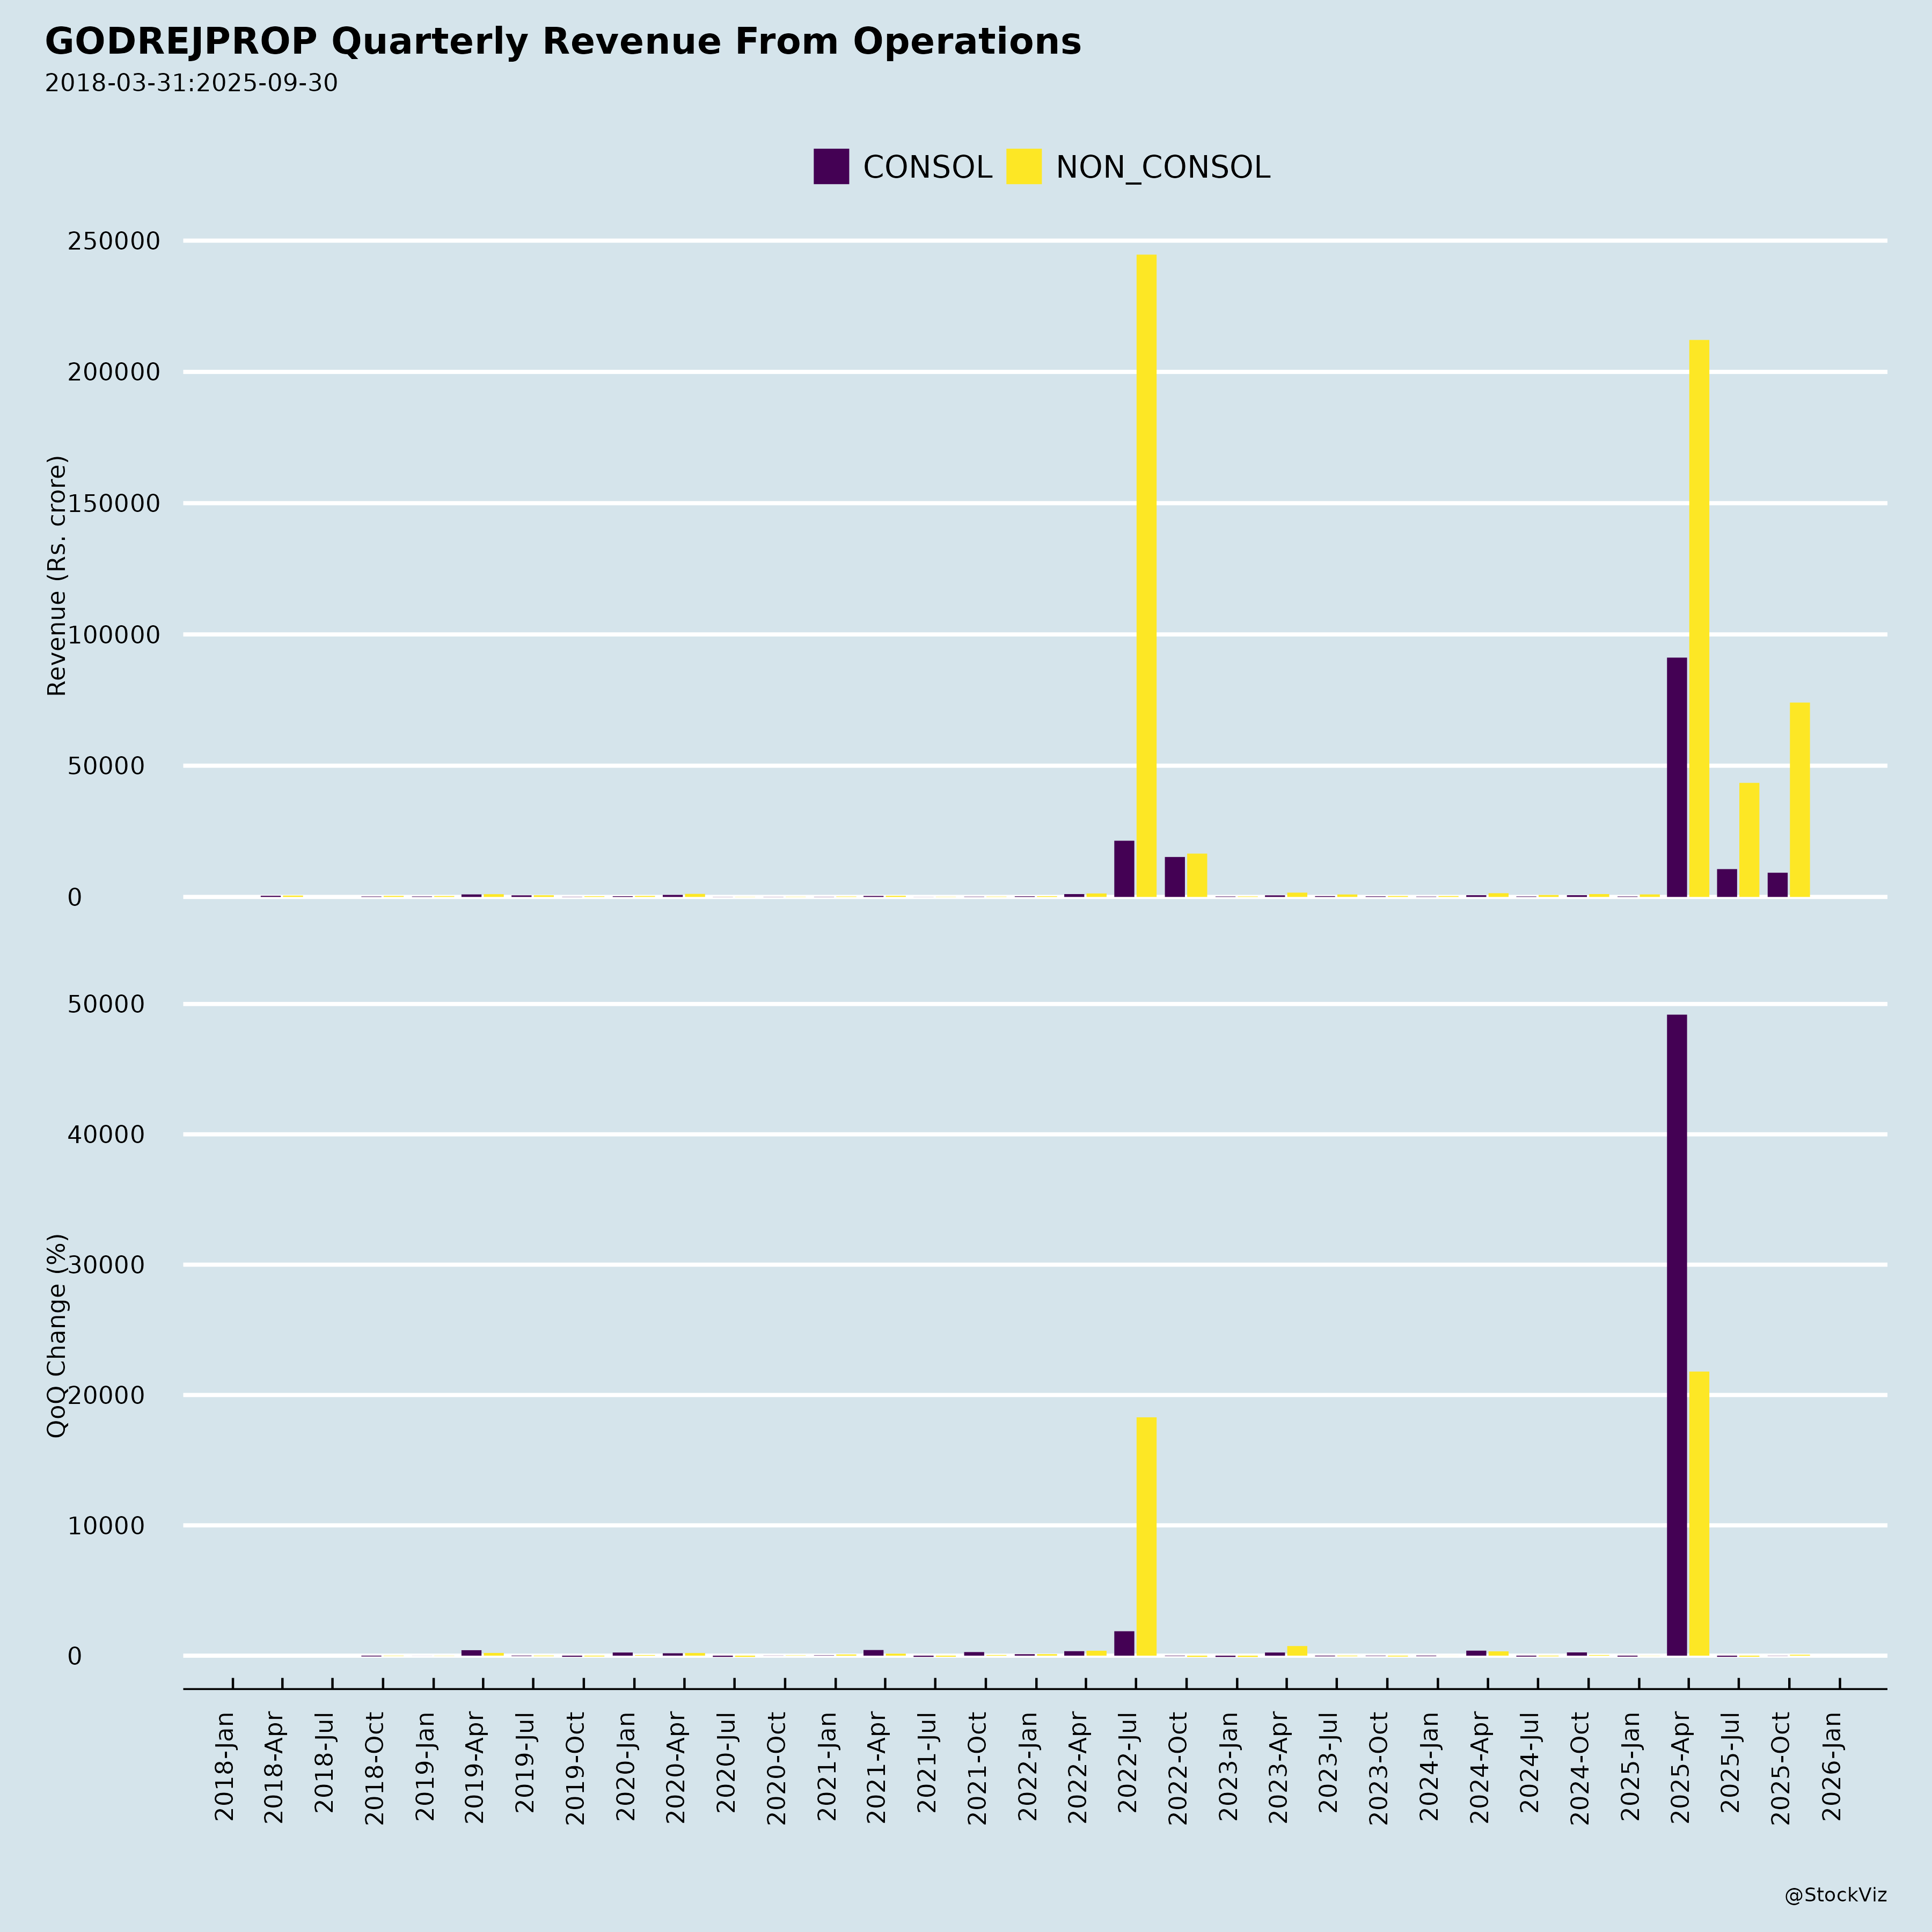
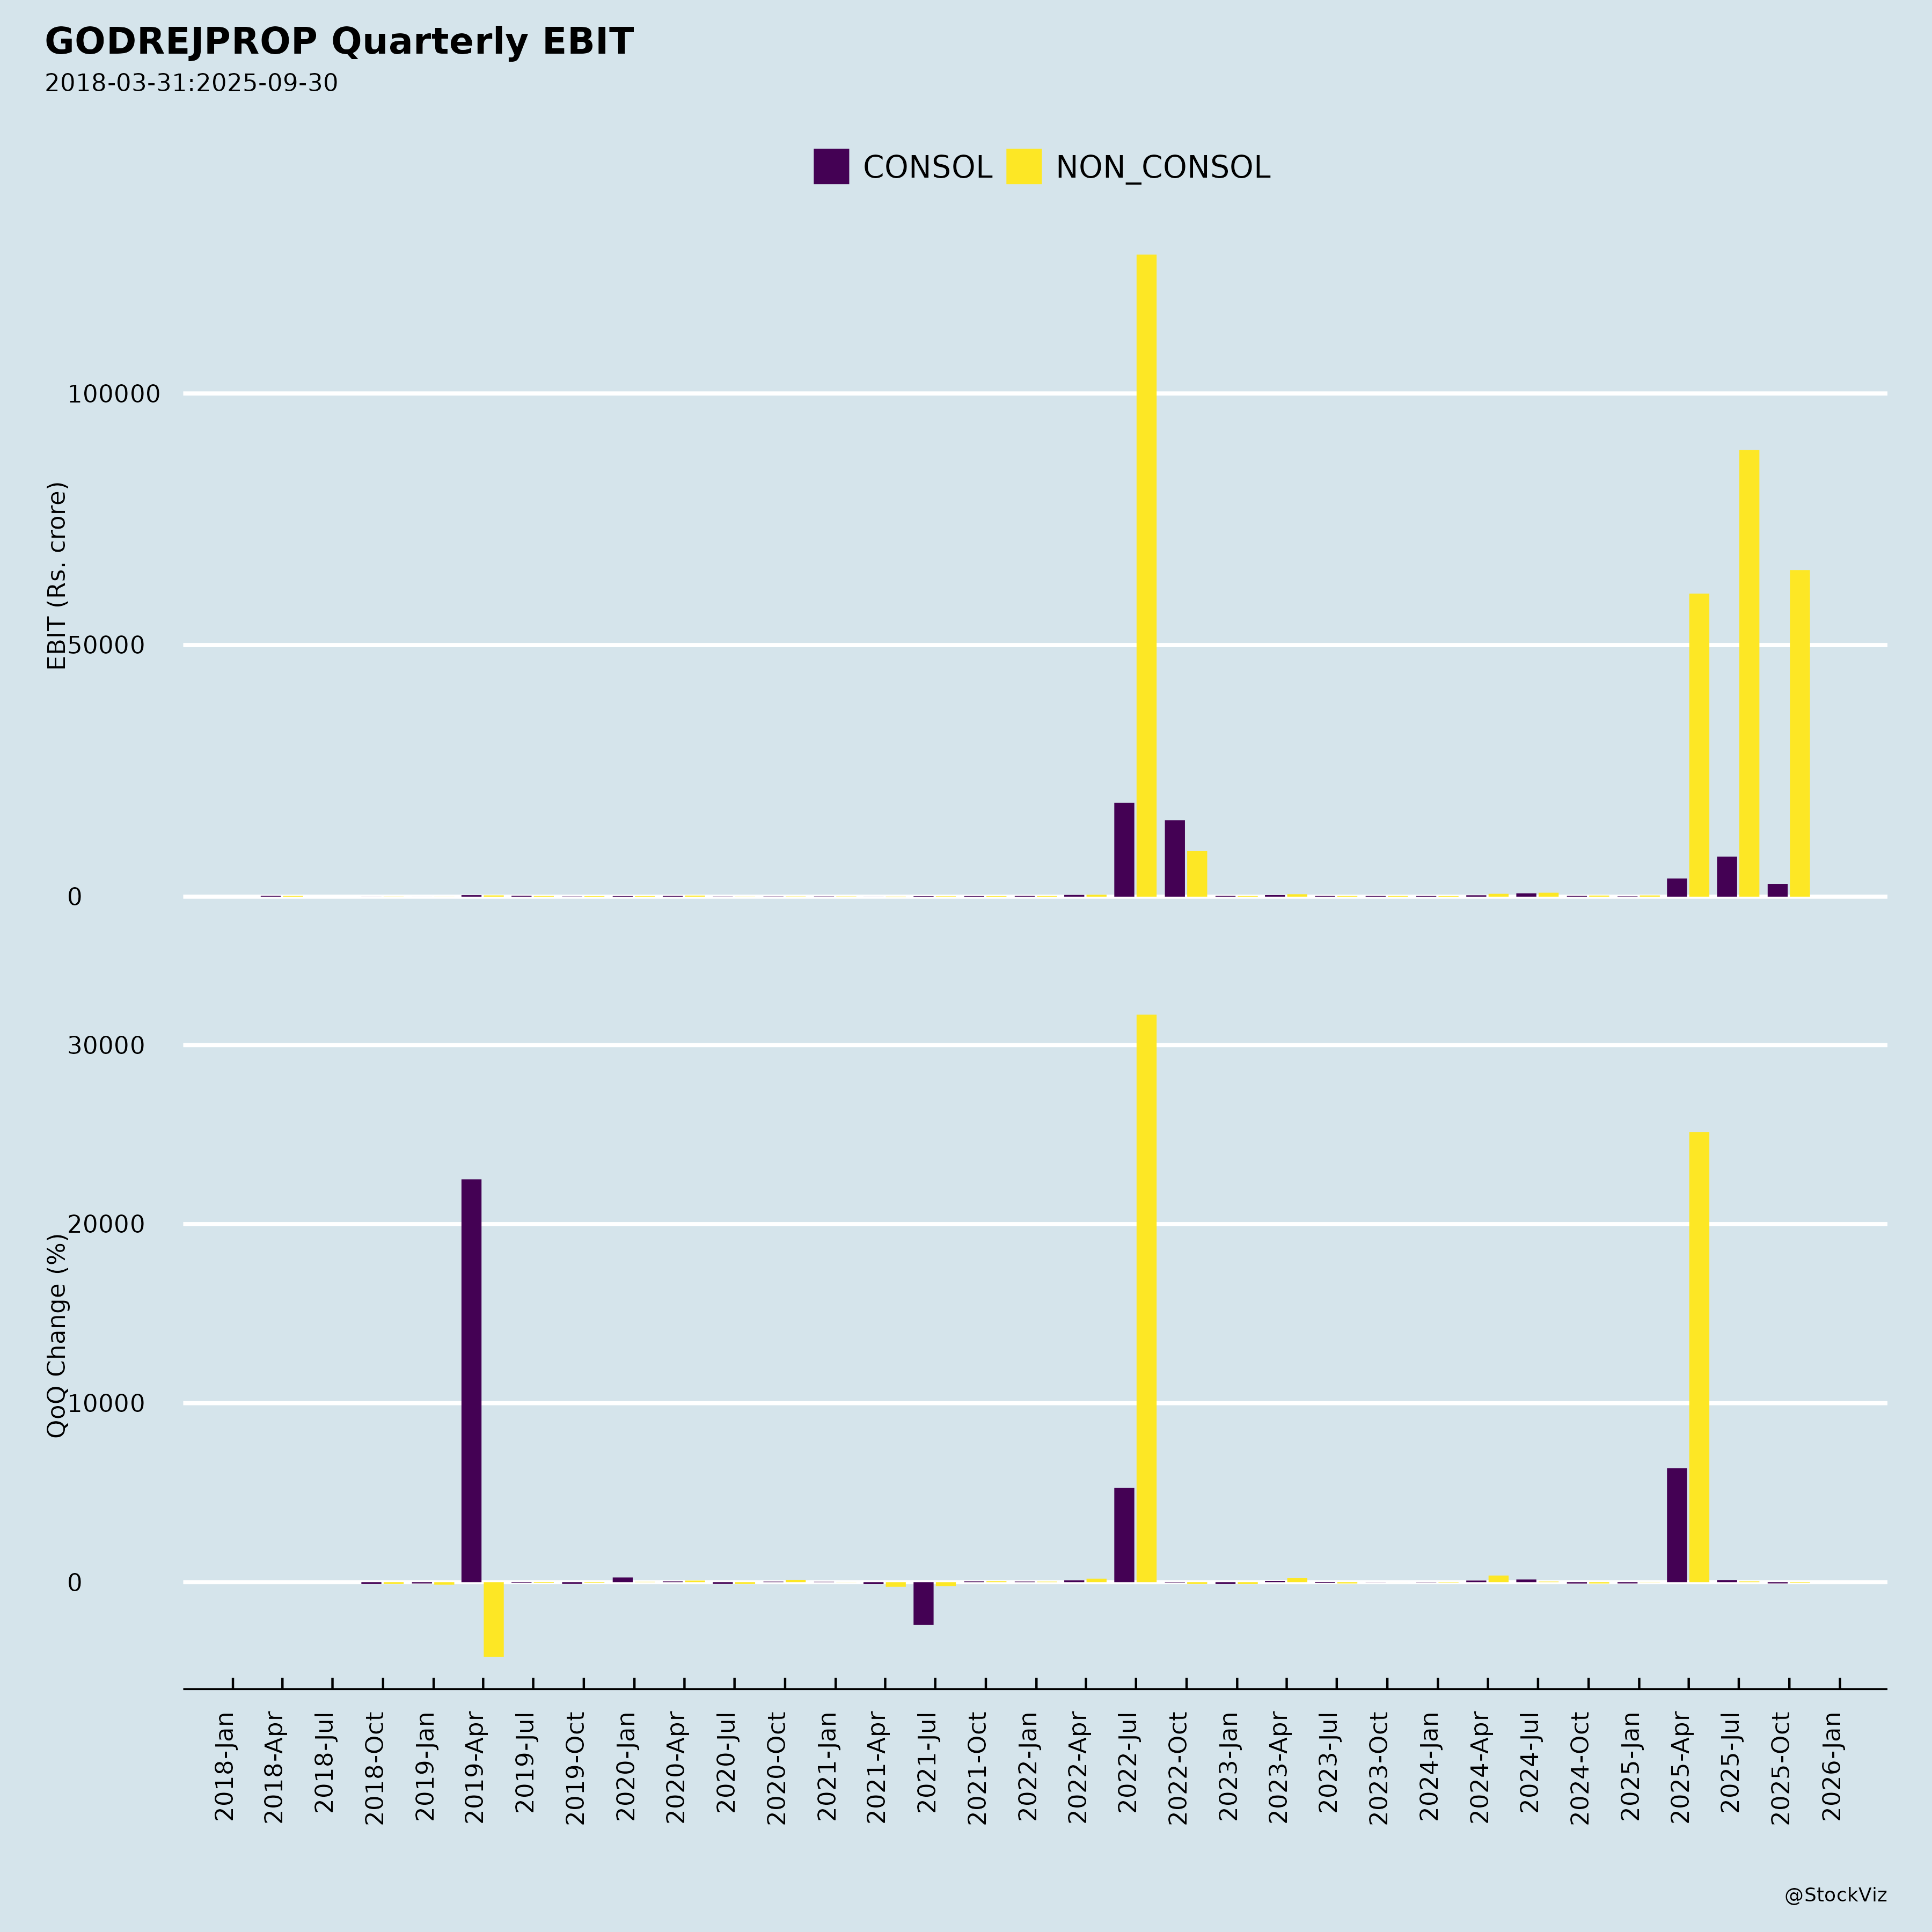
Weak quarterly financial performance. In Q1 FY27, total income fell 16% year-on-year to INR 1,337 crores, profit before tax declined 44% to INR 480 crores, and net profit after tax declined 42% to INR 350 crores. Adjusted EBITDA margin dropped to 41.7% from 58.1% in Q1 FY26. Sequentially, total income was down 66% from Q4 FY26.
Operating cash flow volatility. Q1 FY27 operating cash flow was INR 399 crores, down sharply from INR 4,631 crores in Q4 FY26. The company attributes this to deliveries falling to 0.9 million sq. ft. in Q1 FY27 from 7.4 million sq. ft. in Q4 FY26, which reduced collections by approximately INR 3,600 crores quarter-on-quarter, while construction outflows rose 54% year-on-year to INR 2,244 crores. Net cashflow for the quarter was negative INR 1,193 crores.
Rising leverage and borrowing costs. Net debt increased to INR 7,637 crores as of June 30, 2026, from INR 6,414 crores as of March 31, 2026 and INR 4,637 crores as of June 30, 2025. The net debt-to-equity ratio rose to 0.39 from 0.33 and 0.26 at those respective dates. Average borrowing cost (year-to-date) increased to 7.15% from 7.05% in FY26.
Regulatory penalty. On July 3, 2026, the company received a certified copy of an order dated June 8, 2026 from the Chhattisgarh Real Estate Regulatory Authority imposing a penalty of INR 10 lakh under Section 3(1) read with Section 59 of RERA, relating to alleged advertisement of ‘Project – Greenvale Estate’ prior to obtaining RERA registration. The company states the advertisements were circulated by third parties without its knowledge or consent, allegedly misusing the Godrej brand, and that it initiated legal measures and takedown actions. The company obtained the project’s registration certificate from CGRERA on June 25, 2026, is evaluating legal remedies, and states there is no material impact on financial or operational activities.
Delivery-dependent revenue recognition. The company notes that deliveries depend on receipt of regulatory approvals and can be delayed beyond initial expectations, and that revenue recognition depends on project work completion, the underlying business model, economic interest, and accounting method.
Quarterly variability in operating cash flow. Management states that operating cash flow will vary quarterly due to volatility in collections, which depend on bookings, construction progress, milestones achieved, and deliveries, whereas outflows are largely evenly spread over the year with an increasing trend due to growing scale.
Tailwinds and Growth Prospects
Scale and market position. Godrej Properties describes itself as India’s largest residential real estate developer by booking value, booking volume, and cash collections in both FY25 and FY26, with approximately 258 million sq. ft. of developable area across India and 126 projects as of June 30, 2026. It has delivered approximately 79 million sq. ft. since FY18.
Q1 FY27 sales momentum. Booking value rose 22% year-on-year to INR 8,651 crores on 3,738 units and 6.2 million sq. ft. This was the sixth consecutive quarter with booking value above INR 7,000 crores and the twelfth consecutive quarter above INR 5,000 crores. Collections rose 18% year-on-year to INR 4,348 crores. Key launches included Godrej Vanantara, Bengaluru (INR 3,237 crores), Godrej Samaris, Gurugram (INR 1,248 crores), and Godrej Brooklyn Avenue, Hyderabad (INR 317 crores).
Business development pipeline. In Q1 FY27, the company added three new projects with approximately 8.0 million sq. ft. of saleable area and expected booking value of INR 9,500 crores: Greater Noida DMIC, NCR (5.78 million sq. ft., INR 7,000 crores), Noida Sector 150 (1.09 million sq. ft., INR 2,000 crores), and Chennai Plotted-2 (1.18 million sq. ft., INR 500 crores), all 100% owned.
Revenue recognition pipeline. The company expects booking value of INR 40,000 crores to be delivered and recognized in P&L by FY28, representing a more than 2x increase over the approximately INR 15,000 crores recognized in FY25–FY26. Major projects expected to be delivered by FY28 include Godrej Reserve (MMR), Godrej Aristocrat (Gurugram), Godrej Zenith (Gurugram), Godrej MSR City (Bengaluru), Godrej Woodscapes (Bengaluru), and others.
Cash flow and free cash flow targets. The company expects to deliver INR 52,000–55,000 crores of collections and INR 20,000–22,000 crores of operating cash flow cumulatively for FY27 and FY28, which it states will enable it to be free cash flow positive by FY28. It expects approximately INR 20,000 crores of operating cash flow between Q2 FY27 and Q4 FY28.
Return on equity target. GPL intends to deliver 20% ROE from FY28 while retaining market share leadership.
Execution scale-up. Construction and related outflow increased 54% year-on-year in Q1 FY27, which the company states reflects an increased pace of execution expected to be seen in deliveries in FY28. Of 52 projects acquired between FY21 and FY25, 51 have been launched; 7 of 18 projects acquired in FY26 have also been launched.
Geographic expansion. The company is expanding into new micro-markets within core cities and testing new markets through plotted development projects, having recently entered Indore, Panipat, Raipur, Baroda, and Coimbatore.
Sustainability positioning. GPL ranks #1 globally in the Real Estate and Management sector on the S&P Global Dow Jones Best-in-Class Indices for 2025 and #1 globally with a score of 100/100 in GRESB 2025. It was included in TIME World’s Most Sustainable Companies 2026 as the only Indian real estate company on the list, received CDP ‘A’ list inclusion in 2025, and received SBTi validation of near-term, long-term, and Net Zero goals in January 2026. As of FY26, 100% of projects in the reporting boundary are certified or under certification for green building rating systems.
Brand and lifestyle differentiation. The company opened On Court, one of India’s largest indoor padel facilities with four international-standard courts developed in partnership with PadelPark India, at its 145-acre Godrej City township in Panvel. Godrej City Panvel also announced a new phase of 3 and 4 bed Sky Villas near its 9-hole golf course. Management notes the facility caters to both competitive players and newcomers, aiming to support Padel All Stars in introducing the sport to more people while building an active lifestyle ecosystem at the township.
Capital access. The company cites the largest QIP ever in Indian real estate (INR 6,000 crores) in December 2024 and the lowest bank funding rates in the sector.
Key Risks
- Regulatory and approval risk: Deliveries depend on receipt of regulatory approvals and can be delayed beyond initial expectations. The CGRERA penalty illustrates exposure to RERA compliance issues, including third-party misuse of the Godrej brand in advertisements.
- Execution and delivery risk: Revenue recognition depends on project work completion, business model, economic interest, and accounting method. The company’s FY28 delivery and revenue recognition targets are subject to these dependencies.
- Cash flow timing risk: Operating cash flow varies quarterly due to collection volatility tied to bookings, construction progress, milestones, and deliveries. Q1 FY27 demonstrated this with a sharp sequential decline.
- Leverage risk: Net debt and net debt-to-equity have risen, and average borrowing costs increased year-to-date.
- Market and macroeconomic risk: The company’s forward-looking statements note that actual results might differ materially due to changes in industry structure, significant changes in political and economic environment in India and overseas, tax laws, import duties, litigation, and labor relations.
- Joint venture cash access risk: The company notes timing differences in cash collection from customers in project SPVs and pending transfer to GPL due to non-availability of RERA limits and restrictions in agreements with JV partners whereby GPL cannot withdraw cash until particular milestones are achieved.
Management Guidance Versus Observed Performance
FY27 guidance versus Q1 FY27 actuals:
| Particulars | FY26 Actual | FY27 Guidance | FY27 YTD Actual | Achievement |
|---|---|---|---|---|
| Launch value (INR crore) | 42,200 | 48,000 | 10,500 | 22% |
| Booking value (INR crore) | 34,171 | 39,000 | 8,651 | 22% |
| Customer collections (INR crore) | 19,965 | 24,000 | 4,348 | 18% |
| Deliveries (million sq. ft.) | 12.1 | 13.5 | 0.9 | 7% |
| Business development by expected booking value (INR crore) | 42,100 | 20,000 | 9,500 | 48% |
The company’s updated management assessment indicates it is on track to meet or exceed guidance for launch value, booking value, customer collections, and business development. Deliveries are shown as not on track to meet guidance based on Q1 FY27 performance of 0.9 million sq. ft. against the full-year guidance of 13.5 million sq. ft.
Operating cash flow guidance: Management states operating cash flow will improve in the rest of FY27, with estimated balance 9M FY27 operating cash flow of approximately INR 8,600 crores, against Q1 FY27 actual of INR 399 crores. The company expects cumulative FY27–FY28 collections of INR 52,000–55,000 crores and operating cash flow of INR 20,000–22,000 crores, enabling free cash flow positivity by FY28.
Revenue recognition guidance: The company expects INR 40,000 crores of booking value to be delivered and recognized in P&L by FY28, versus approximately INR 15,000 crores recognized in FY25–FY26.
ROE guidance: GPL intends to deliver 20% ROE from FY28.
Delivery pipeline guidance: Major projects and phases expected to be delivered by FY28 include Godrej Reserve (MMR, 100% owned), Godrej Aristocrat (Gurugram, 100% owned), Godrej Zenith (Gurugram, 100% owned), Godrej MSR City (Bengaluru, 50% profit share), Godrej Woodscapes (Bengaluru, 100% owned), Godrej Horizon (MMR, 100% owned), Godrej Jardinia (Noida, 100% owned), Godrej Tropical Isle (Noida, 100% owned), Godrej Riverine (Noida, 100% owned), Godrej Avenue Eleven (MMR, 50% profit share), Godrej Ascend (MMR, 100% owned), Godrej Lakeside Orchard (Bengaluru, 100% owned), Godrej Evergreen Square (Pune, 100% owned), Godrej Ananda (Bengaluru, 49% profit share), and Godrej Blue (Kolkata, 100% owned). GPL’s economic interest in these projects ranges from approximately 74% to 85–90%.
Corporate structure guidance: The board approved a Scheme of Amalgamation of Godrej Housing Projects Private Limited (formerly Godrej Housing Projects LLP) with Godrej Properties Limited on August 4, 2026, subject to NCLT and other approvals. GPL holds 95% of GHPPL and the balance 5% is held by Godrej Projects Development Limited, a wholly owned subsidiary of GPL, making GHPPL an indirect wholly owned subsidiary. No shares will be issued by GPL in consideration, and there will be no change in GPL’s shareholding pattern. The rationale includes consolidation of real estate business, streamlining group structure, pooling of technical resources, cost reduction, and reducing time for consolidation of financials.
Leadership transition: The board approved the re-designation of Pirojsha Godrej from Whole-time Director designated as Executive Chairperson to Non-Executive Non-Independent Director and Chairperson effective August 14, 2026, subject to member approval via postal ballot. This follows the planned generational transition after Nadir Godrej’s retirement as Chairperson and Managing Director of Godrej Industries Limited and Pirojsha Godrej’s succession as Executive Chairperson of Godrej Industries Limited and Chairperson of Godrej Industries Group effective August 14, 2026. Pirojsha Godrej will continue to provide strategic guidance, oversee long-term vision and growth agenda, support key stakeholder relationships, and mentor senior leadership. He ceased to be Key Managerial Personnel upon re-designation. The postal ballot e-voting runs from August 21, 2026 to September 19, 2026, with results to be declared on or before September 21, 2026.
Dividend: The 41st AGM is scheduled for August 4, 2026, with a dividend of INR 10 per share of face value INR 5 each. The record date for dividend is July 28, 2026.
Investor engagement: Godrej Properties officials are scheduled to participate in the Jefferies India Forum 2026 on September 16, 2026, in Gurgaon for one-on-one and group meetings.
Broker Narrative
The broker narrative shifted from a June 2021 market-timing hold—warning that Nifty’s sharp run-up could top out and correct while citing intact technicals and RSI scope for upside—to an October 2026 company-specific buy centered on Godrej Properties’ launch pipeline, GDV, pre-sales, collections, net debt, WACC, cap rates, and FY27–FY28 cash-flow and RoE targets. Growth upside remained a persistent theme, but the emphasis moved from near-term index momentum to operational and balance-sheet execution, with Nifty correction fears replaced by leverage, cost-of-capital, and profitability concerns.
Fears that came true
- The early Nifty top-and-correction warning materialized as the stock slid into extended drawdowns, with repeated negative actual returns and DISAPPOINTMENT outcomes from 2024 through 2026.
- Net debt rose INR2.7b QoQ to INR79b in 2QFY27, confirming leverage pressure alongside weak share-price performance.
- WACC increased to 11.1% from 10.6% and the commercial cap rate widened to 8.5% from 8.0%, compressing valuations and forcing a lower target price.
- 2QFY27 PAT fell 64% YoY to INR1.5b with an operating loss of INR4.7b, corroborating the earnings deterioration behind numerous DISAPPOINTMENT results.
Optimism that failed
- The June 2021 confidence that an intact uptrend and RSI of 72.87 implied more upsides failed as Godrej Properties corrected sharply instead of sustaining gains.
- Despite 31% YoY collections growth to INR53b and resilient pricing in Mumbai and southern markets, 2QFY27 PAT dropped 64% YoY and an operating loss of INR4.7b was recorded, so revenue momentum did not prevent profitability collapse.
Broker Timeline
37 broker calls · 2021-06-07 to 2026-10-24
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.