FEDERALBNK
Equity Metrics
November 18, 2026
The Federal Bank Limited
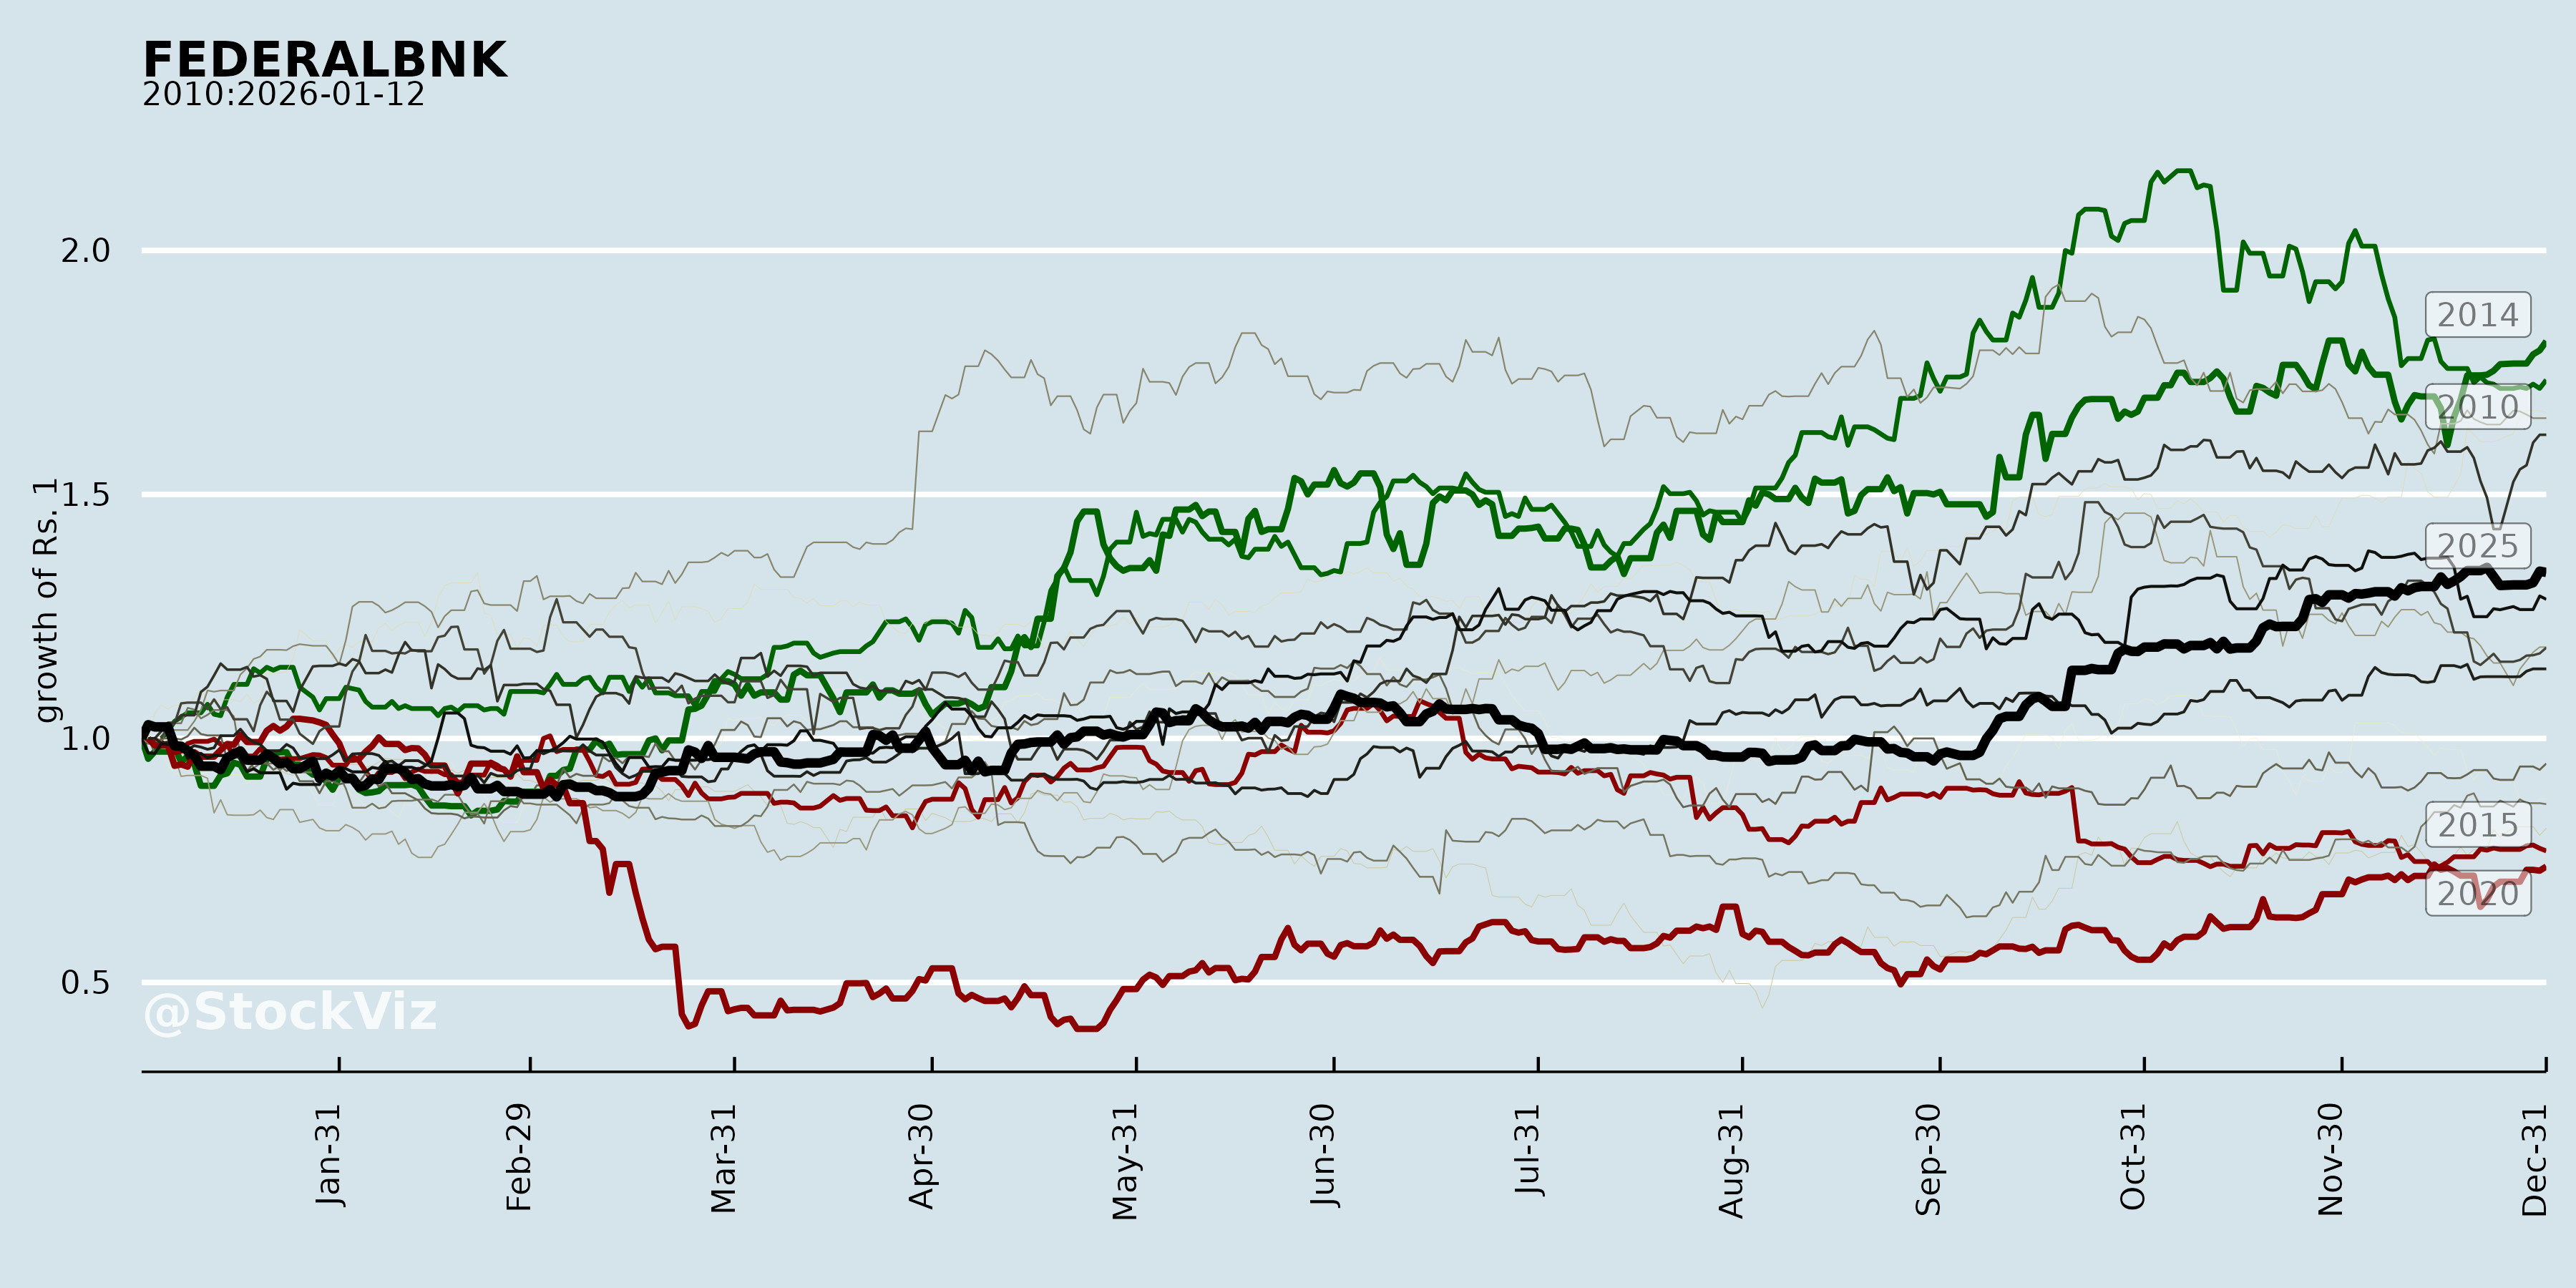
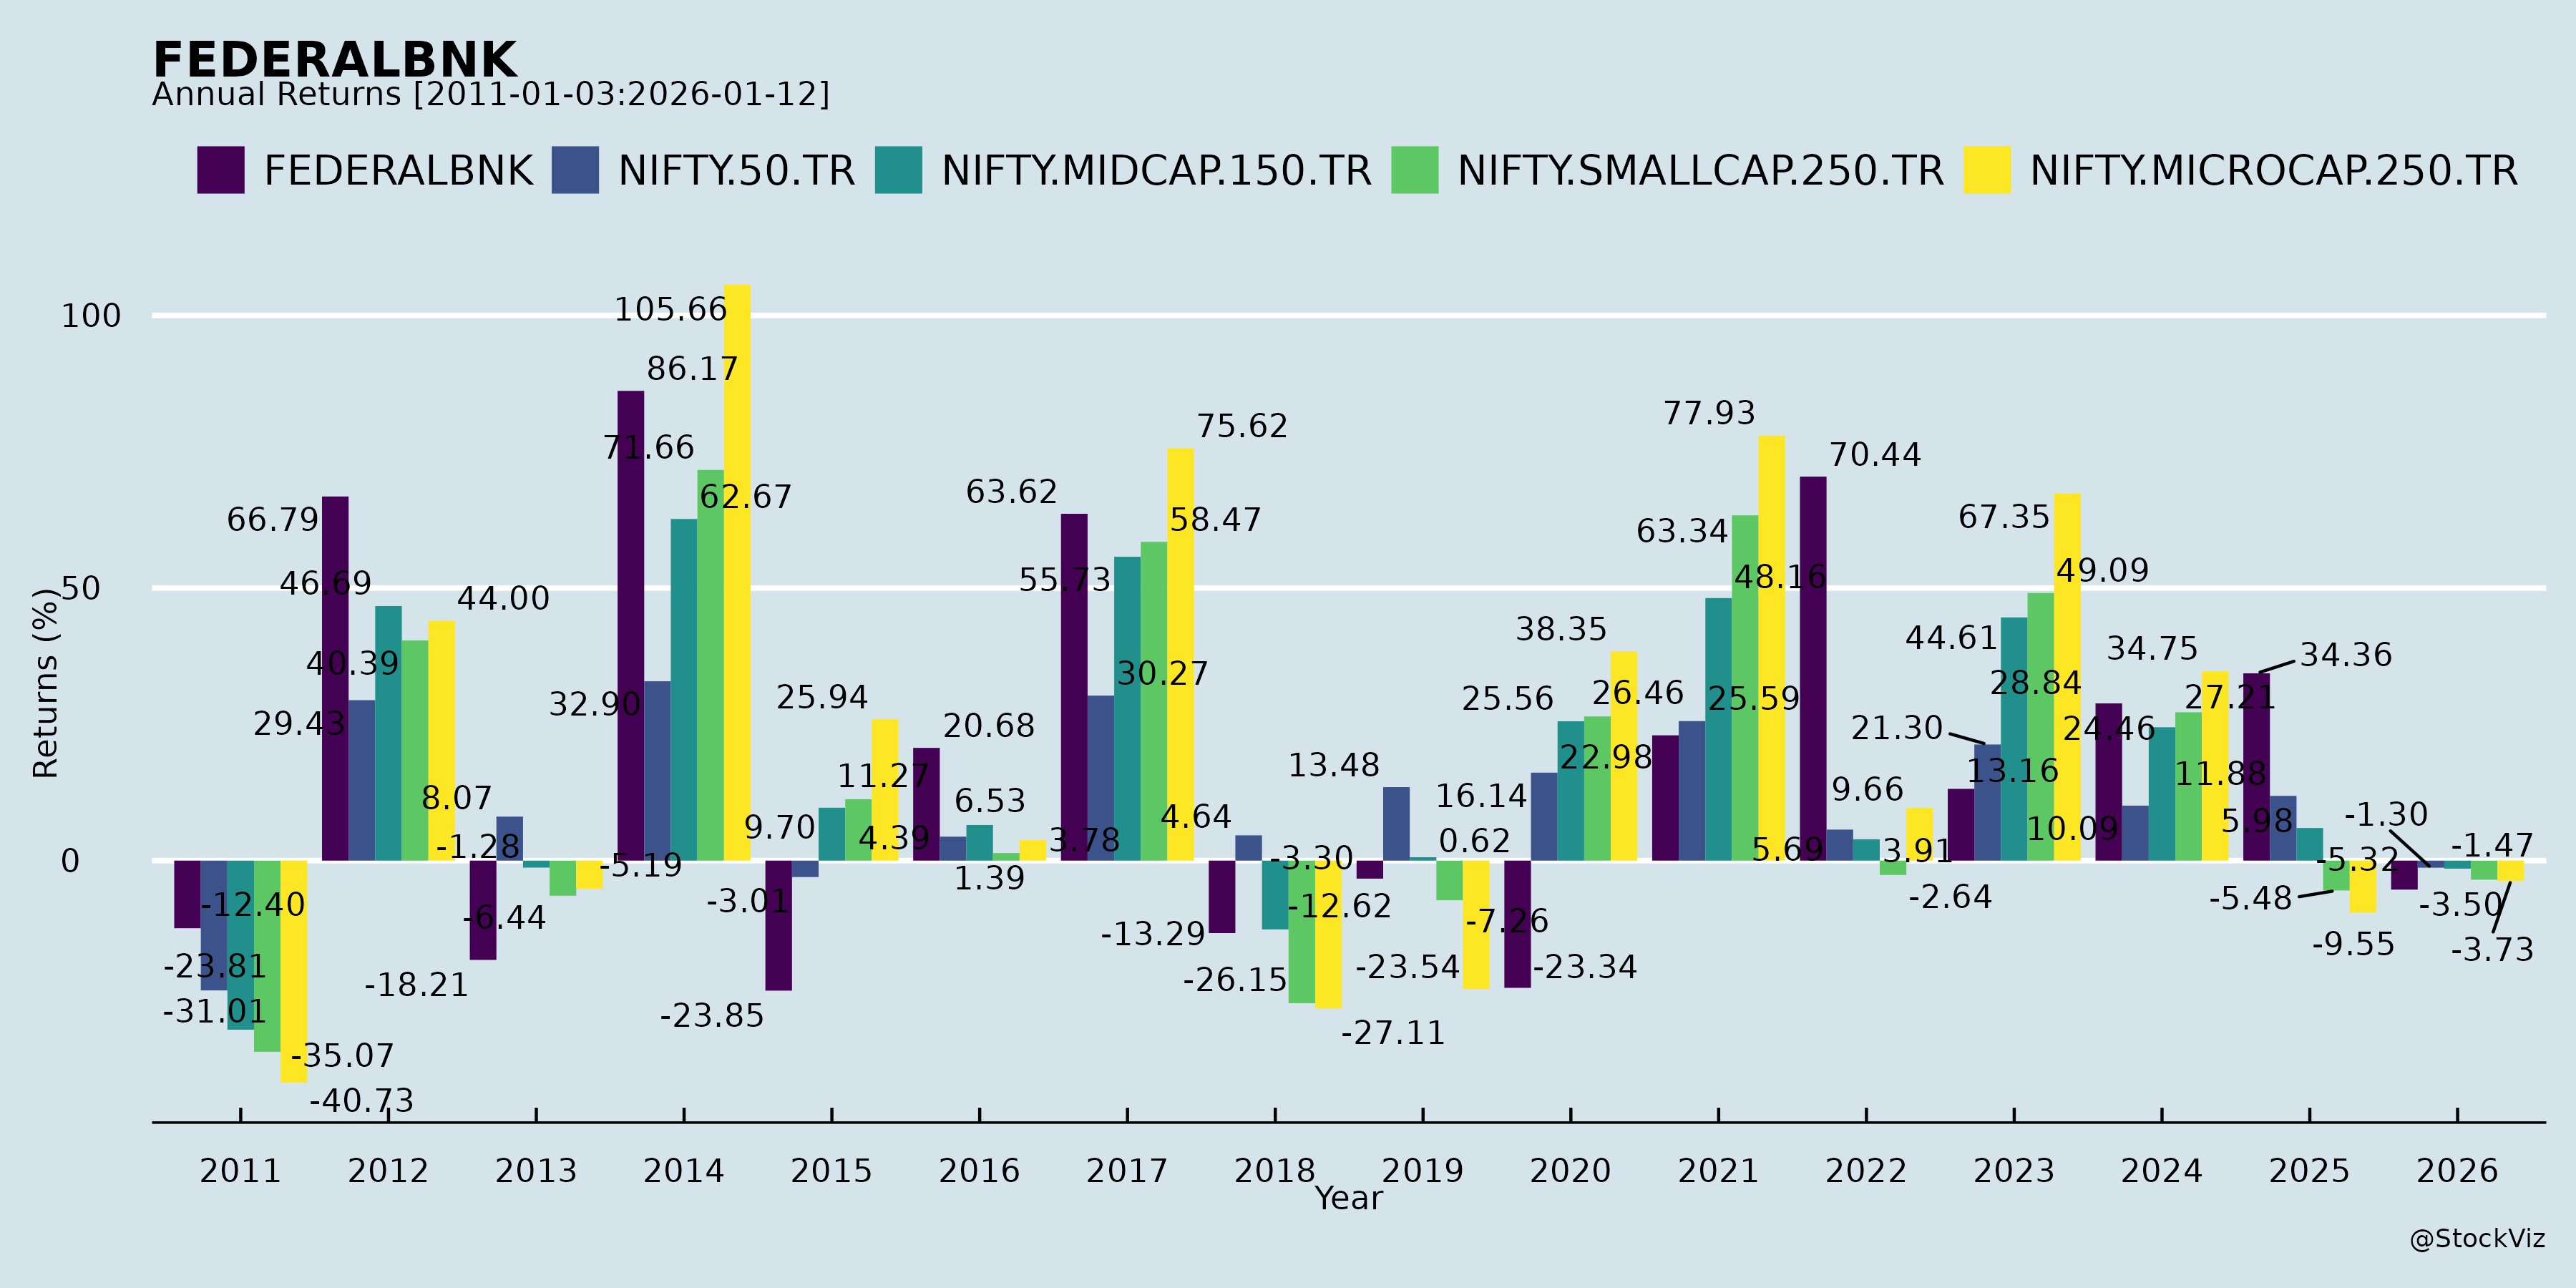
Annual Returns
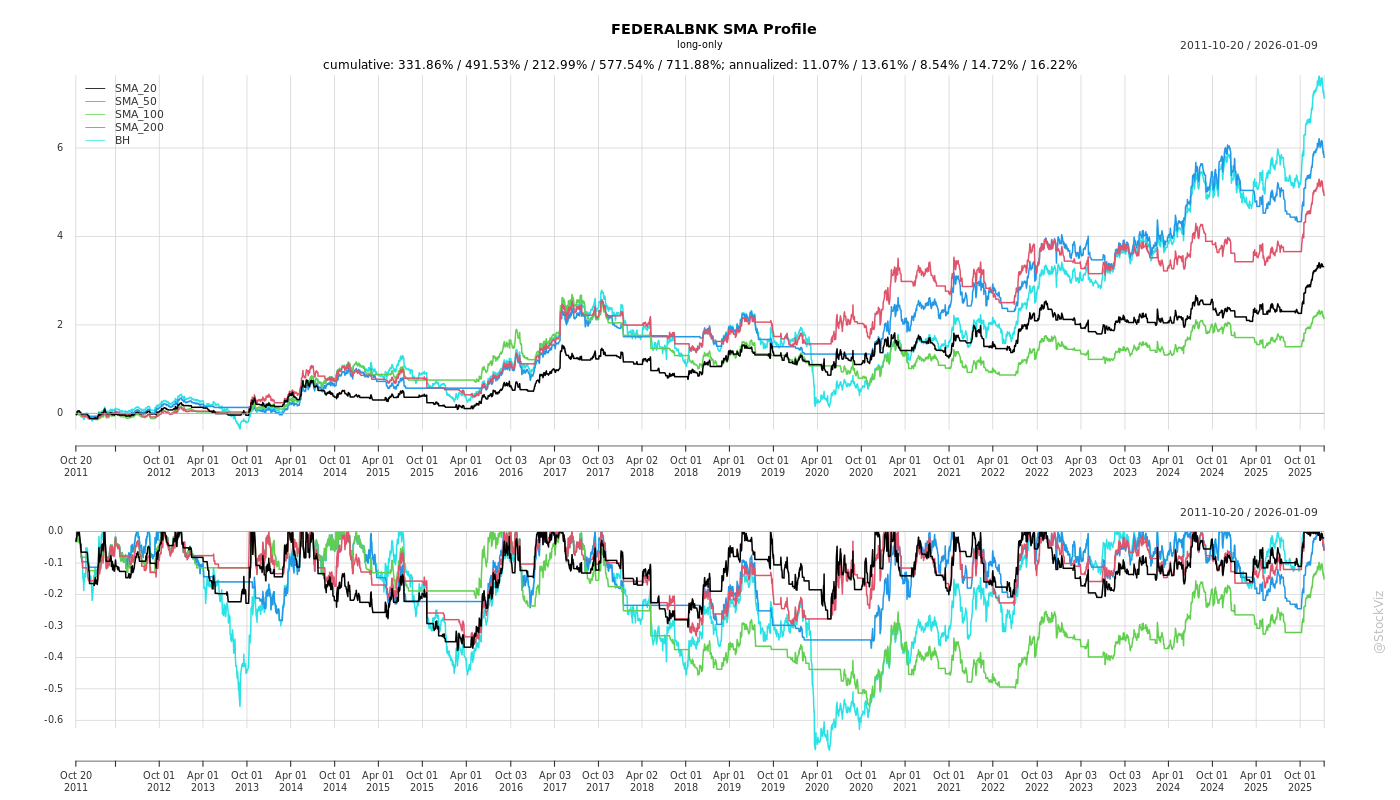
Cumulative Returns and Drawdowns

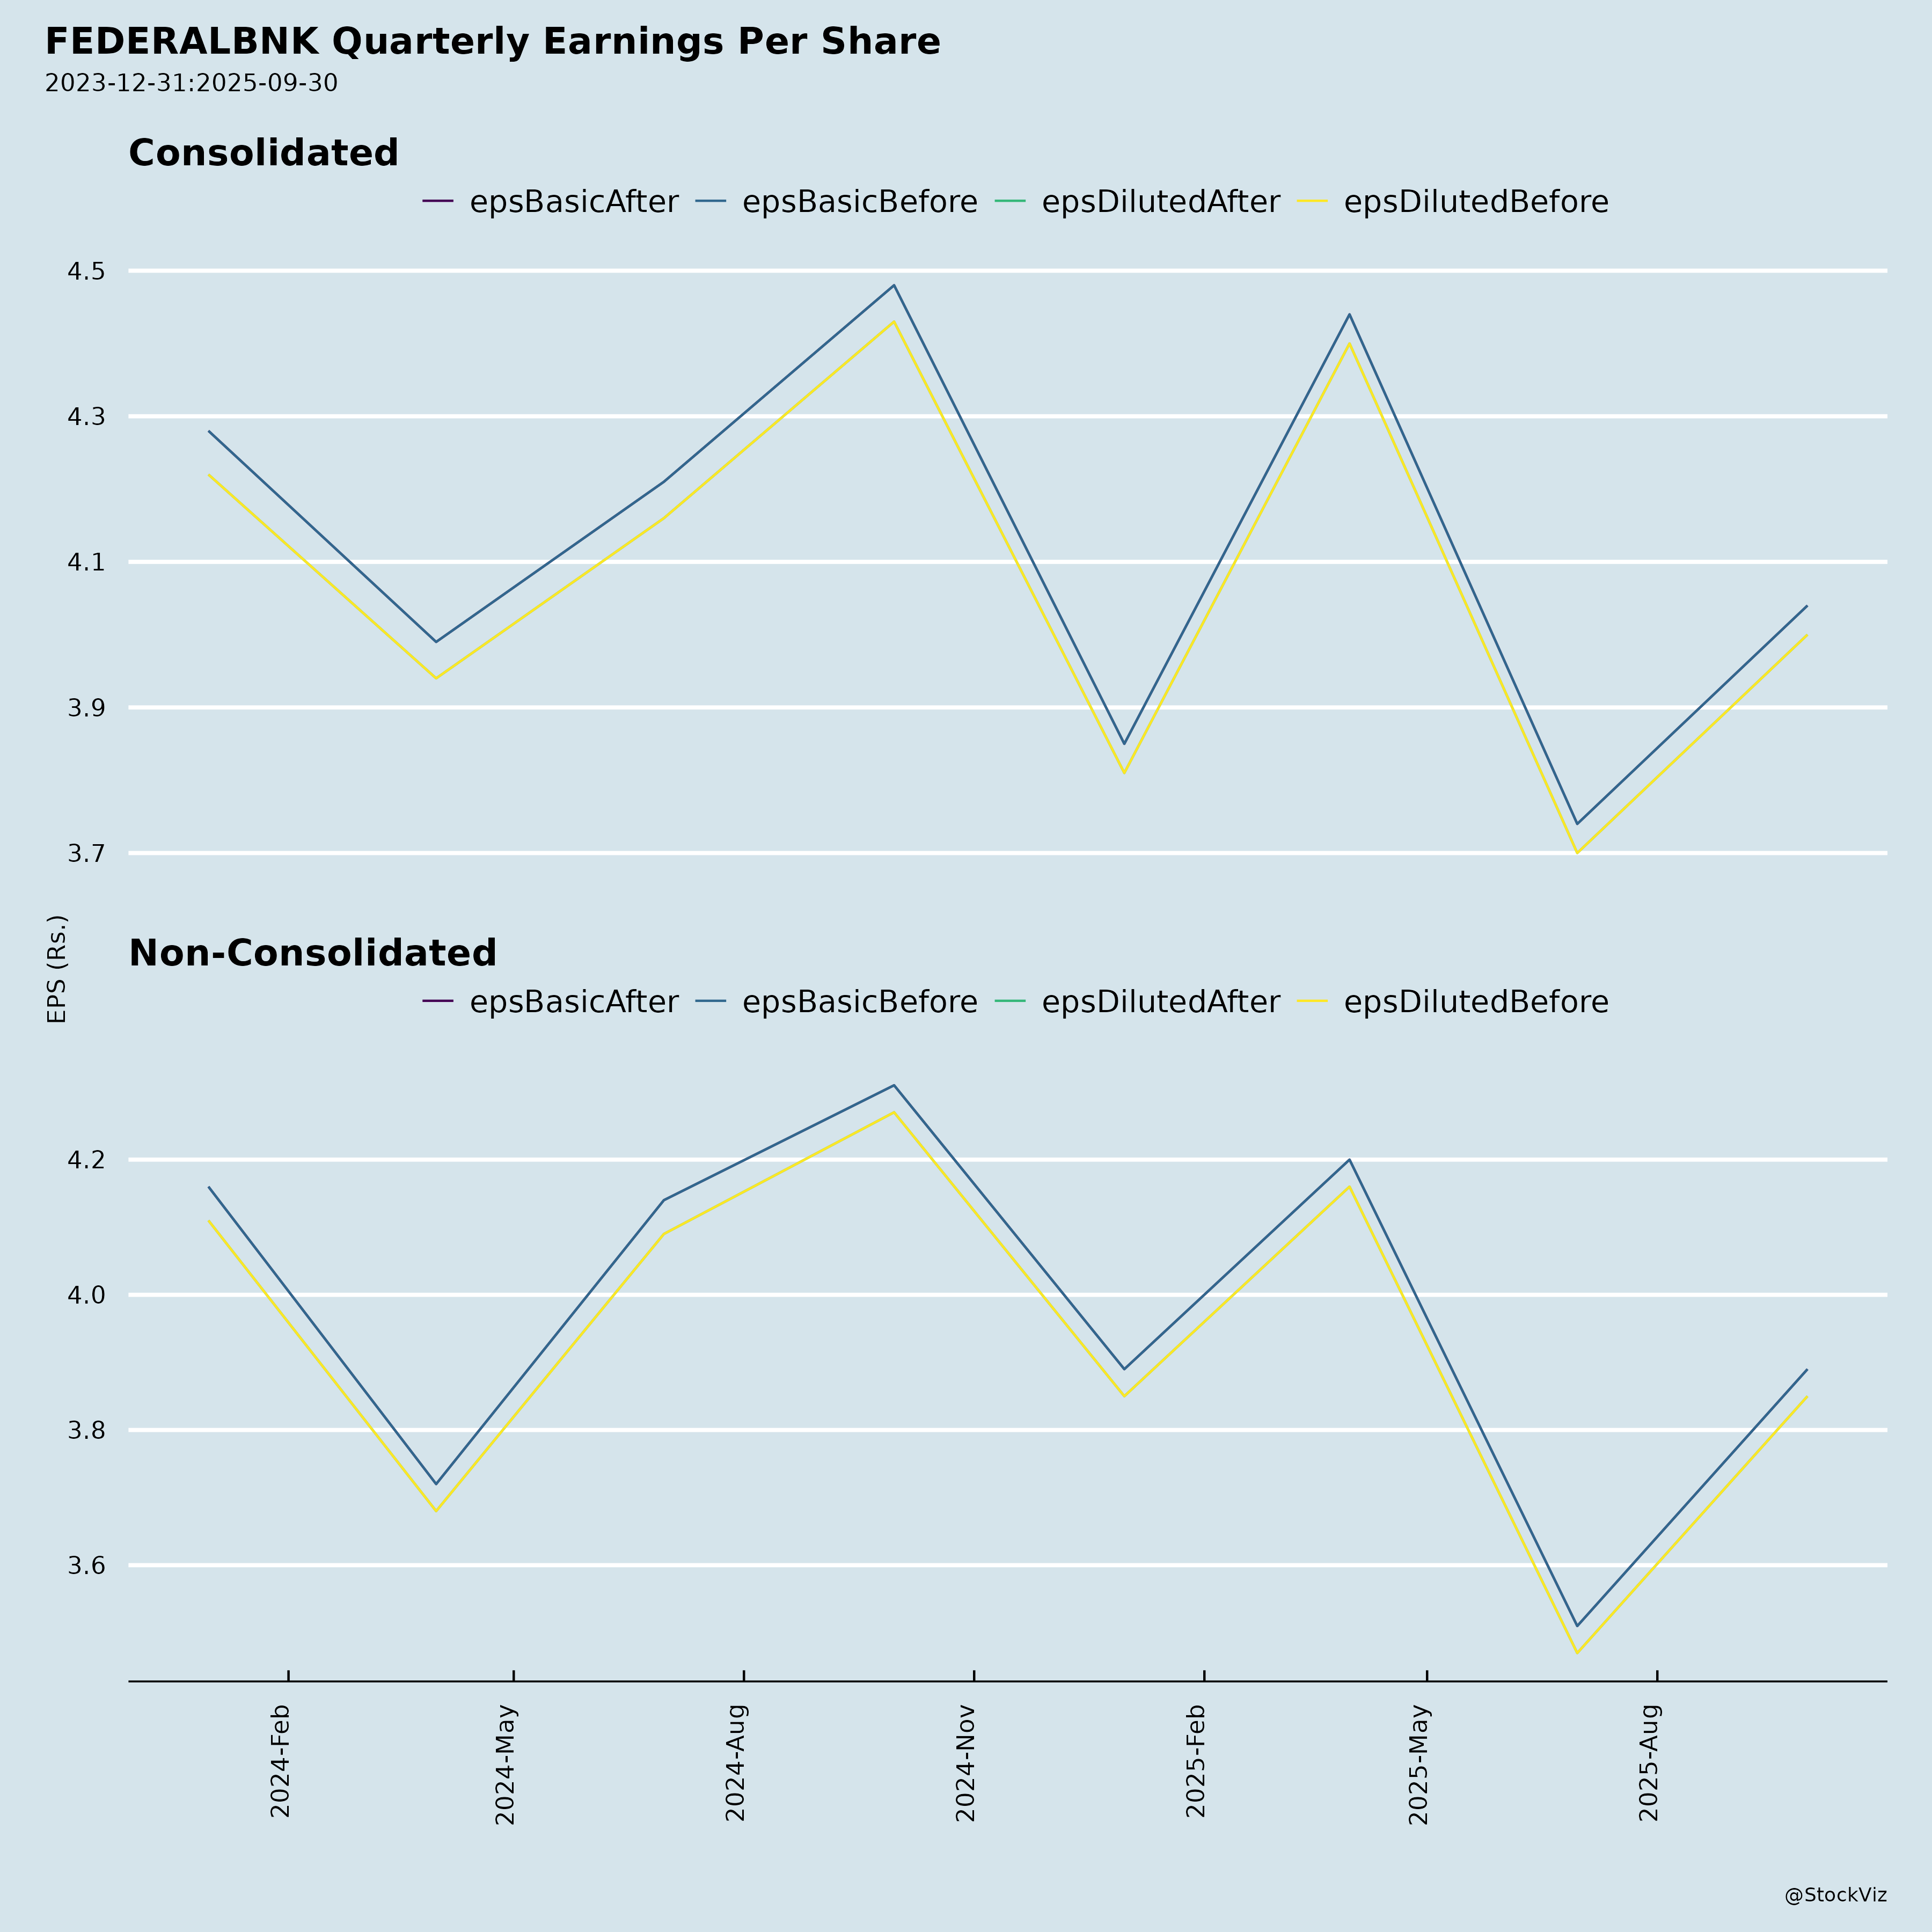
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
FEDERALBNK — Recent Corporate Announcements: Analysis
1. Headwinds and Challenges
- Treasury income remained subdued through a volatile market period in Q1 FY27, even as core earnings grew. Management noted the quarter was one in which “treasury had a challenging period,” with earnings coming from the core business rather than market gains.
- Asset yield compression: NIM expansion of 39 bps YoY to 3.33% was achieved despite a 44 bps compression in asset yield, offset by a 60 bps fall in cost of funds.
- Macro/currency headwinds: The rupee may still face headwinds from global events.
- Emerging risk areas integrated into governance: AI/model adoption, digital fraud and financial crime, data privacy and digital regulation, third-party technology dependencies, climate transition, and geopolitical/trade fragmentation.
- Cost absorption: The Cost-to-Income ratio improved 239 bps YoY to 52.50% while absorbing the annual wage revision.
2. Tailwinds and Growth Prospects
- Supportive macro backdrop: ~7% real GDP growth outlook, system credit growth of approximately 19% YoY, system-wide NPAs at multi-year lows (~1.8%), firm domestic consumption, RBI inflation tolerance band of 4% ±2%, fiscal consolidation with FY27 fiscal deficit targeted at 4.3% of GDP, current account deficit of ~1.5% of GDP for FY27 supported by GCC remittance corridors, and FX reserves of approximately US$707 bn.
- Identified growth engines: MSME relationships, NR banking, transaction banking, wealth and mass affluent segments, asset mix reshaping toward higher-yielding secured retail and mid-market corporate exposure, digital distribution expansion, and the Blackstone strategic investment.
- Segment momentum in Q1 FY27: Commercial Banking +22.96% YoY, CV/CE +21.07%, Gold Loans +33%, LAP +21%, Credit Cards +36%, and Corporate & Institutional Banking +16.12% YoY (book surpassing ₹1 lakh crore).
- Liability franchise deepening: CASA grew 18.26% YoY against total deposit growth of 11.37%; NR deposits reached ₹1,05,123.41 crore, up 14.24% YoY, building on the ₹1 lakh crore milestone crossed in the prior quarter.
- Funding initiative: Board approval on August 21, 2026 for raising funds via foreign currency denominated bonds through the IFSC Banking Unit at GIFT City, in one or more tranches, up to an aggregate equivalent of USD 500 million, with a maximum tenor of up to five years.
- Network expansion: 10 branches added in Q1 FY27, taking the network to 1,650 outlets.
3. Key Risks
- External uncertainty: The Bank’s balanced risk approach and pivot toward secured, granular segments are described as buffers against external uncertainty; the restructured book stands at ₹1,541.30 crore, or 0.55% of gross advances.
- Governance-identified emerging risks: AI/model adoption, digital fraud and financial crime, data privacy and digital regulation, third-party technology dependencies, climate transition, and geopolitical/trade fragmentation.
- Currency/macro risk: INR may still face headwinds from global events.
- Market volatility affecting non-core income: Treasury income was subdued amid a volatile market period.
4. Management Guidance vs. Observed Performance
- Credit cost: Management has guided that credit cost is being managed toward a targeted 50–60 bps range through the cycle. In Q1 FY27, credit cost declined 24 bps to 0.41%, below the guided through-cycle range.
- CASA accretion: Management expects CASA accretion to continue independent of the business banking cycle, reflecting the structural, relationship-led nature of deposit growth under Project Breakthrough 4.0 targets tracked through FY28. Observed Q1 FY27 performance: CASA balances up 18.26% YoY to ₹1,03,163.15 crore, with the CASA ratio improving 188 bps YoY to 32.23% — growth well ahead of the overall deposit book (+11.37% YoY).
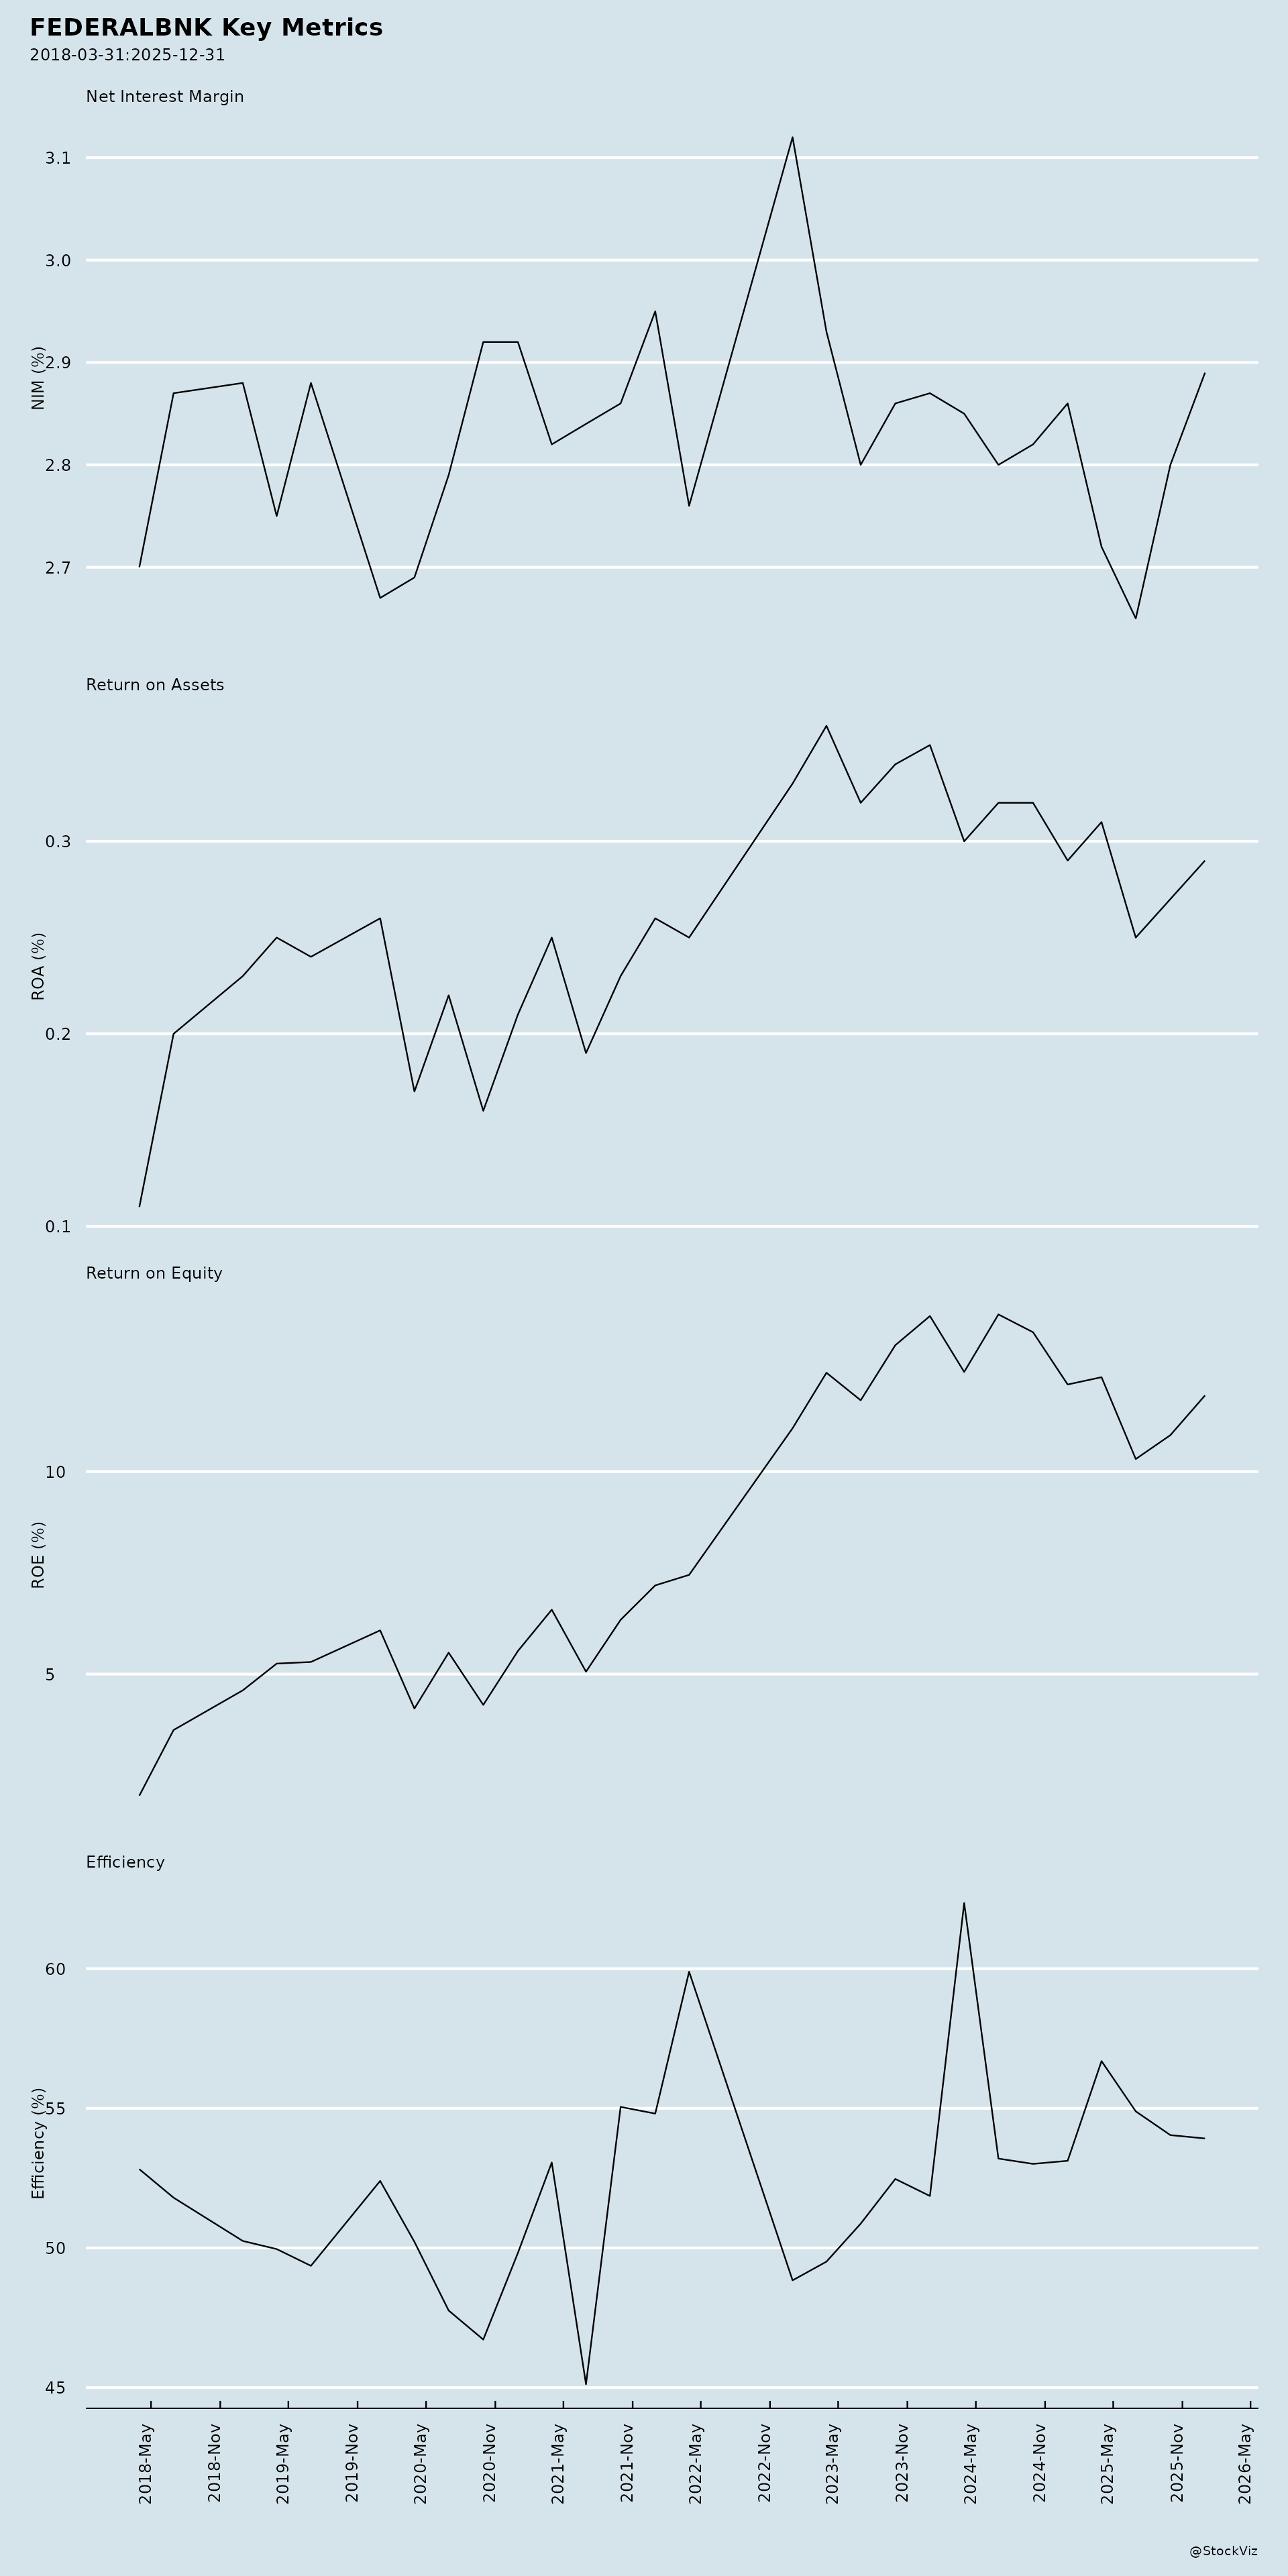
- Margin focus: Management described NIM expansion as a core focus. Observed: NIM expanded 39 bps YoY to 3.33%, with Net Interest Income growing 26.06% to ₹2,945.89 crore, well ahead of advances growth of 14.94%.
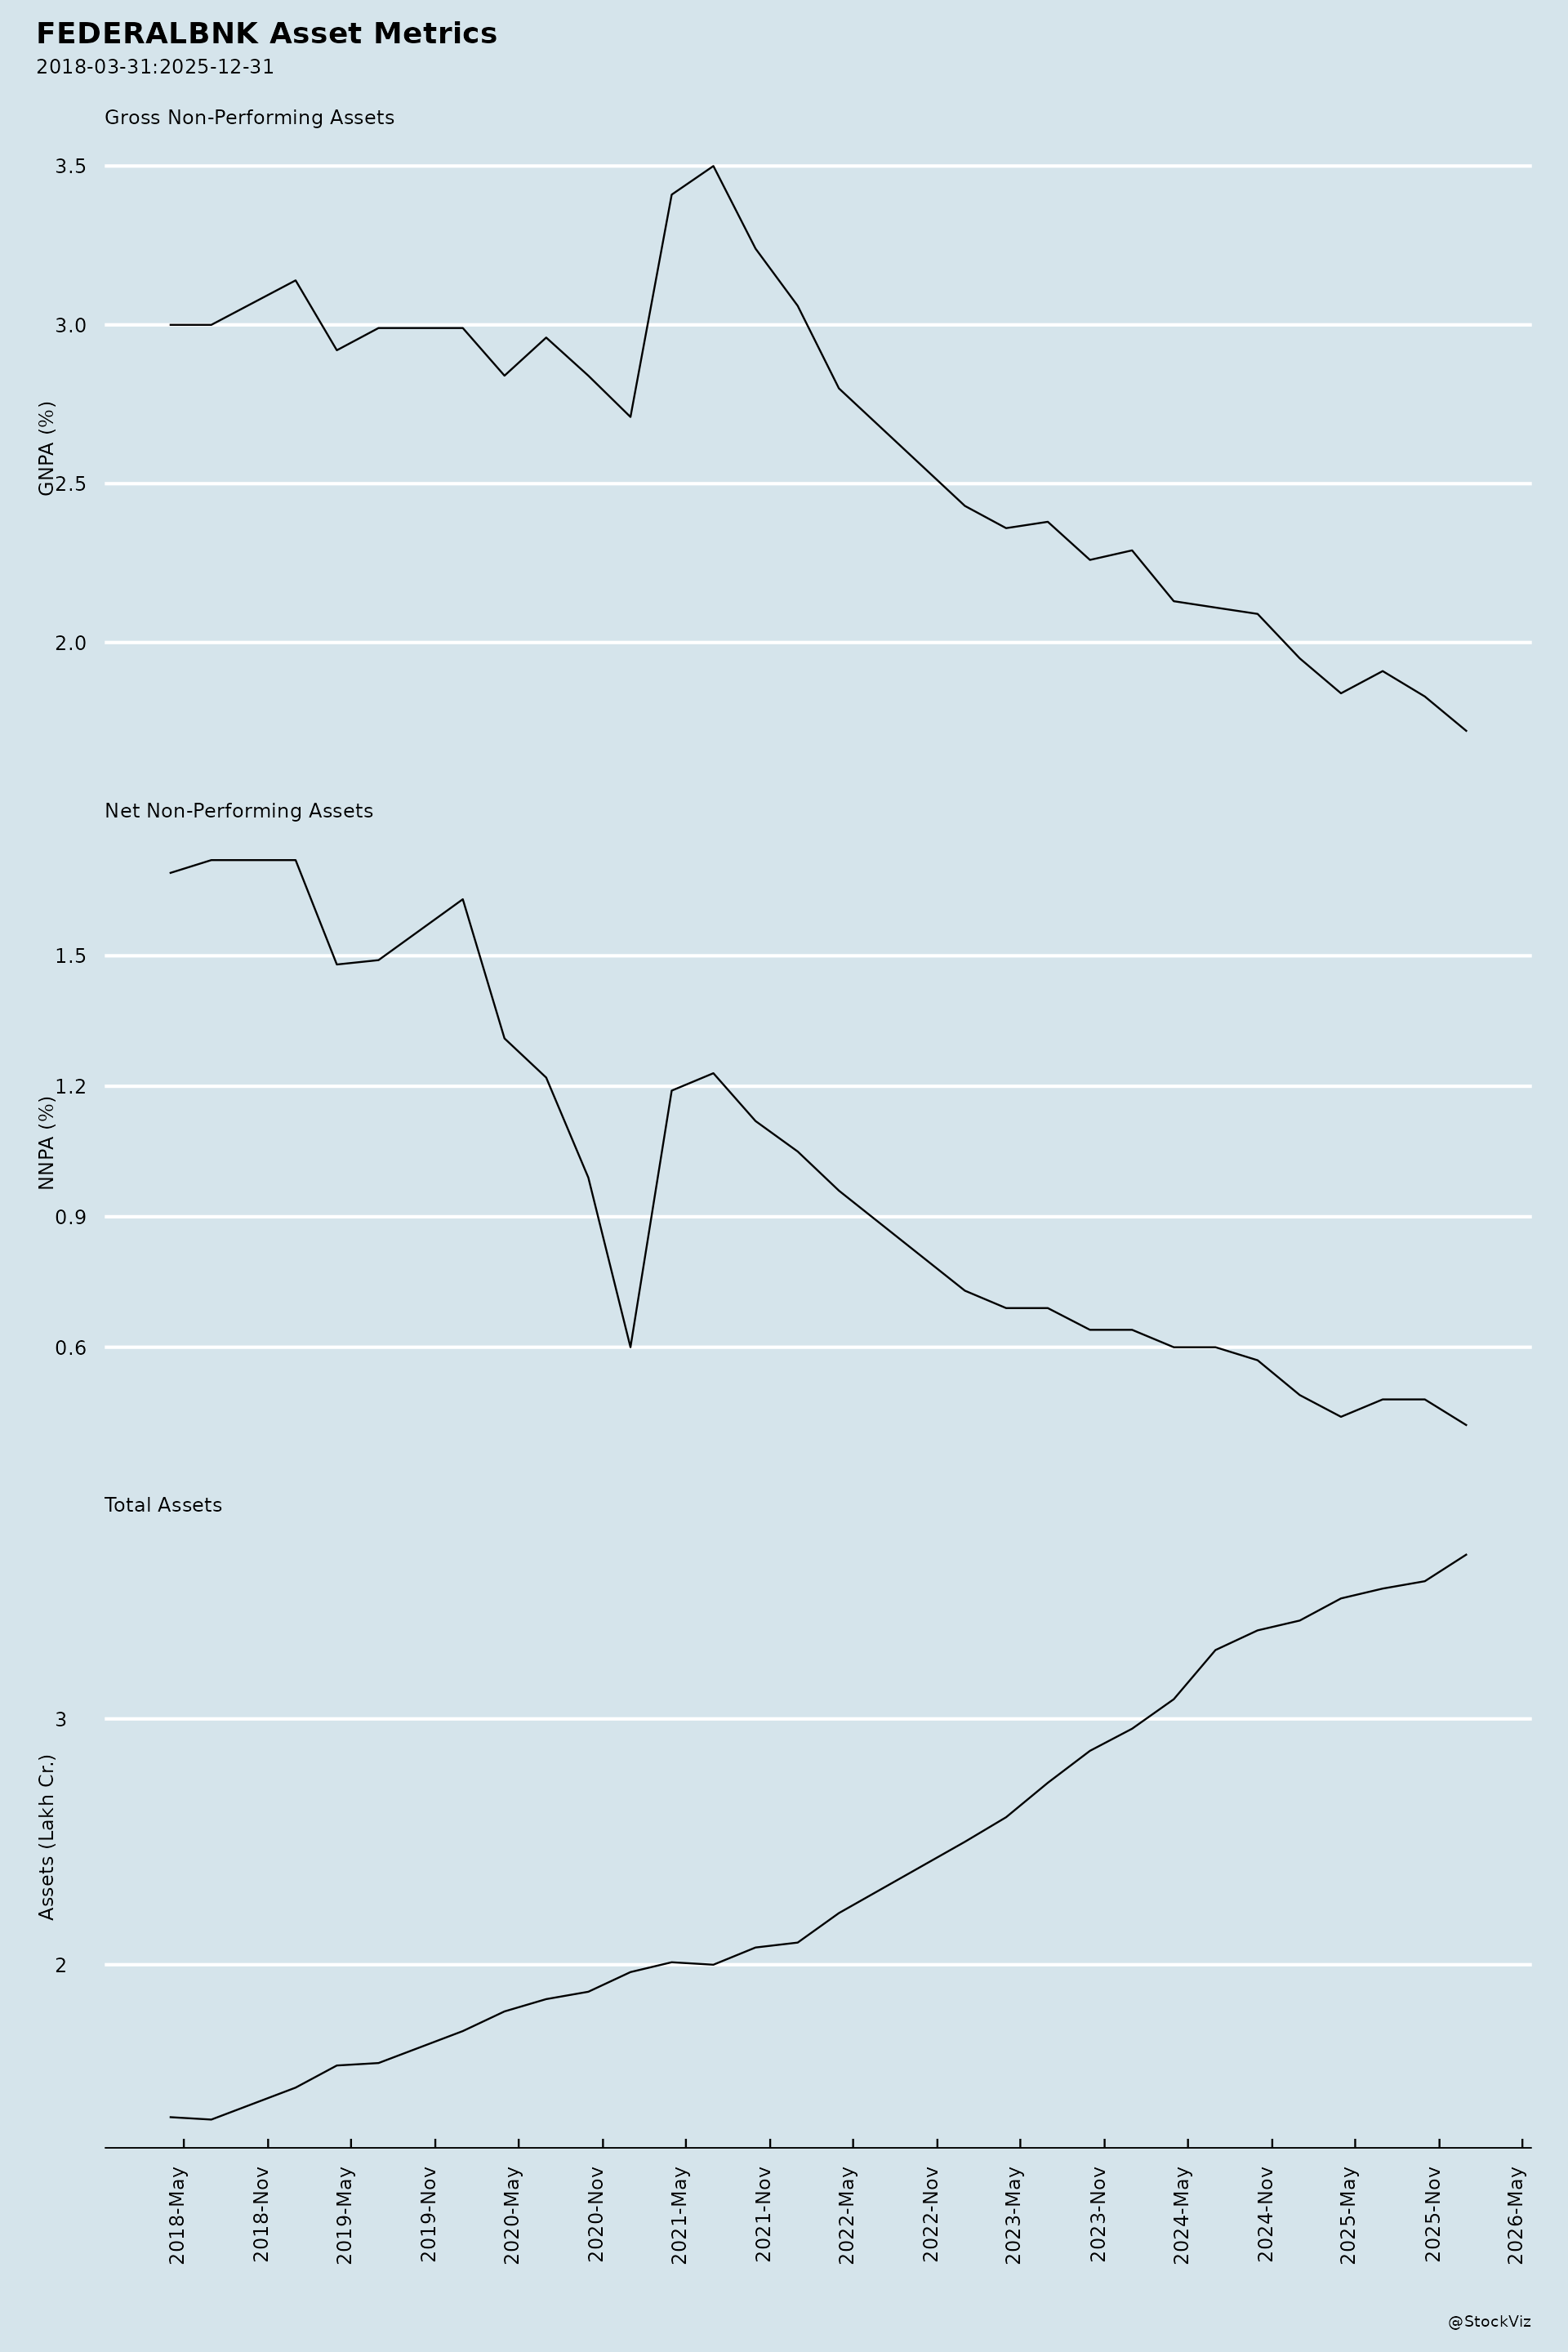
- Asset quality: Net NPA at 0.18% (decadal low), Gross NPA at 1.52%, fresh slippages down 37.79% YoY to ₹409.48 crore, and Provision Coverage Ratio (excluding TWO) at 87.37%, up 1,296 bps YoY; coverage including technical write-offs at 94.23%.
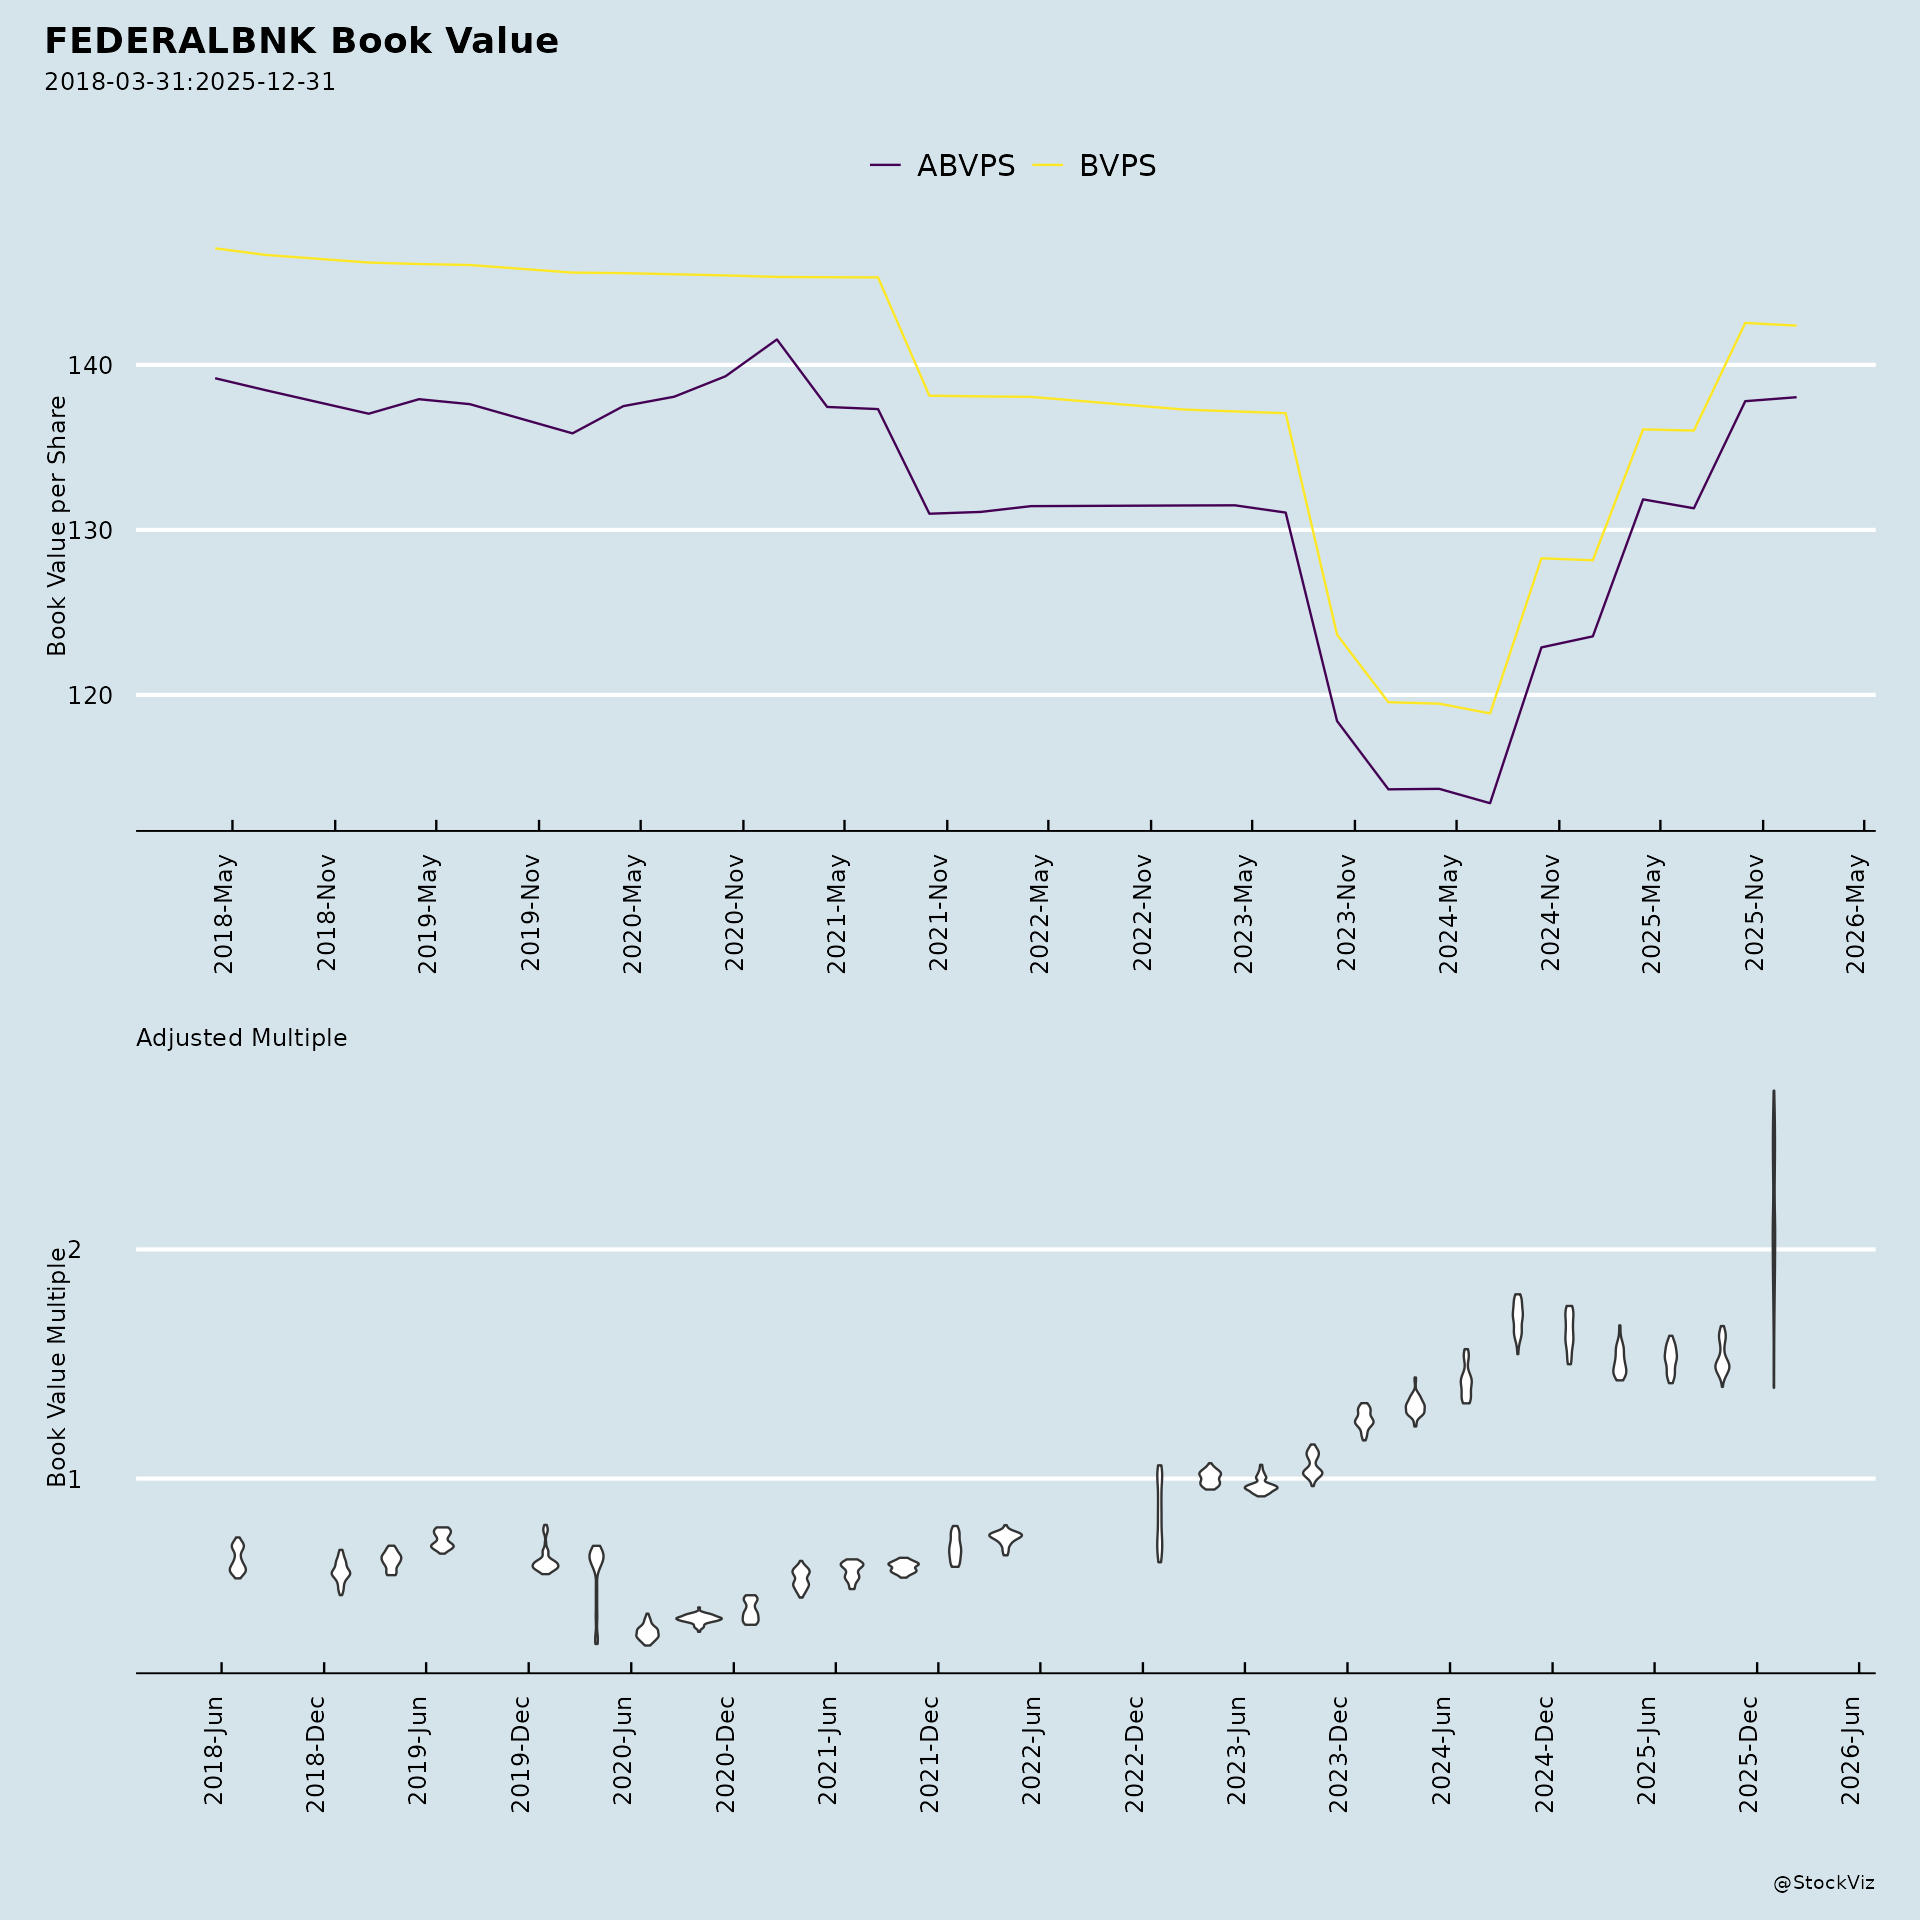
- Profitability and returns: Net profit of ₹1,176.93 crore, up 36.57% YoY; EPS up 36.06% to ₹19.15; RoA improved 22 bps YoY to 1.22%; RoE expanded 171 bps YoY to 12.01%; Book value per share grew 17.02% YoY to ₹161.87.
- Capital position: Capital Adequacy Ratio of 16.97% and Tier-1 Capital Ratio of 15.89%, described by management as strong entering the rest of the year.
Additional Key Facts
- All seven resolutions at the 95th Annual General Meeting held on August 21, 2026 were approved with the requisite majority.
- The Nomination, Remuneration, Ethics and Compensation Committee approved allotments of equity shares (face value ₹2 each) on September 12, 2026: 65,396 shares under ESOS 2010, 72,373 shares under ESOS 2017, and 3,135 shares under ESIS 2023.
- Representatives of the Bank met institutional investors/analysts outside India from September 9–11, 2026, with no unpublished price sensitive information shared.
- The Bank is described as a 95-year franchise and the 6th largest private-sector bank in India by balance sheet, with total business of ₹5.98 lakh crore and a balance sheet of ₹3.93 lakh crore for Q1 FY27; 1,650 banking outlets, 2,112 ATMs/recyclers, and 19.2 million customers; fully publicly held with no promoter and a market cap of approximately ₹81,721 crore as of September 4, 2026.
Broker Narrative
The broker narrative shifted from an early recovery thesis—where NIM contraction, CASA outflows and rising slippages were key risks while credit growth, deposit accretion and improving asset quality supported a Buy call—to a Hold stance in which those growth drivers largely delivered (advances ~21% YoY, deposits ~19% YoY, NIM stable at 3.32%, GNPA/NNPA down to 1.32%/0.17%, PAT up 45%) but valuation, elevated cost-to-income (52–54%), non-recurring treasury gains, deposit competition and bancassurance/M&A risks limited further re-rating.
Fears that came true
- Cost pressure persisted rather than faded, with cost-to-income moving from 49.5% in Q4FY23 to an expected 52–54% and capping incremental operating leverage even as the rating turned Hold.
- Higher cost of deposits and funding competition endured, mirroring the earlier 55 bps QoQ cost-of-funds jump and 5.1% deposit cost, with liability repricing now seen as able to offset repo-hike margin support alongside recent flat or negative actual returns.
Broker Timeline
100 broker calls · 2023-05-08 to 2026-10-21
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.