EUROBOND
Equity Metrics
November 18, 2026
Euro Panel Products Limited
Aluminium Copper & Zinc Products
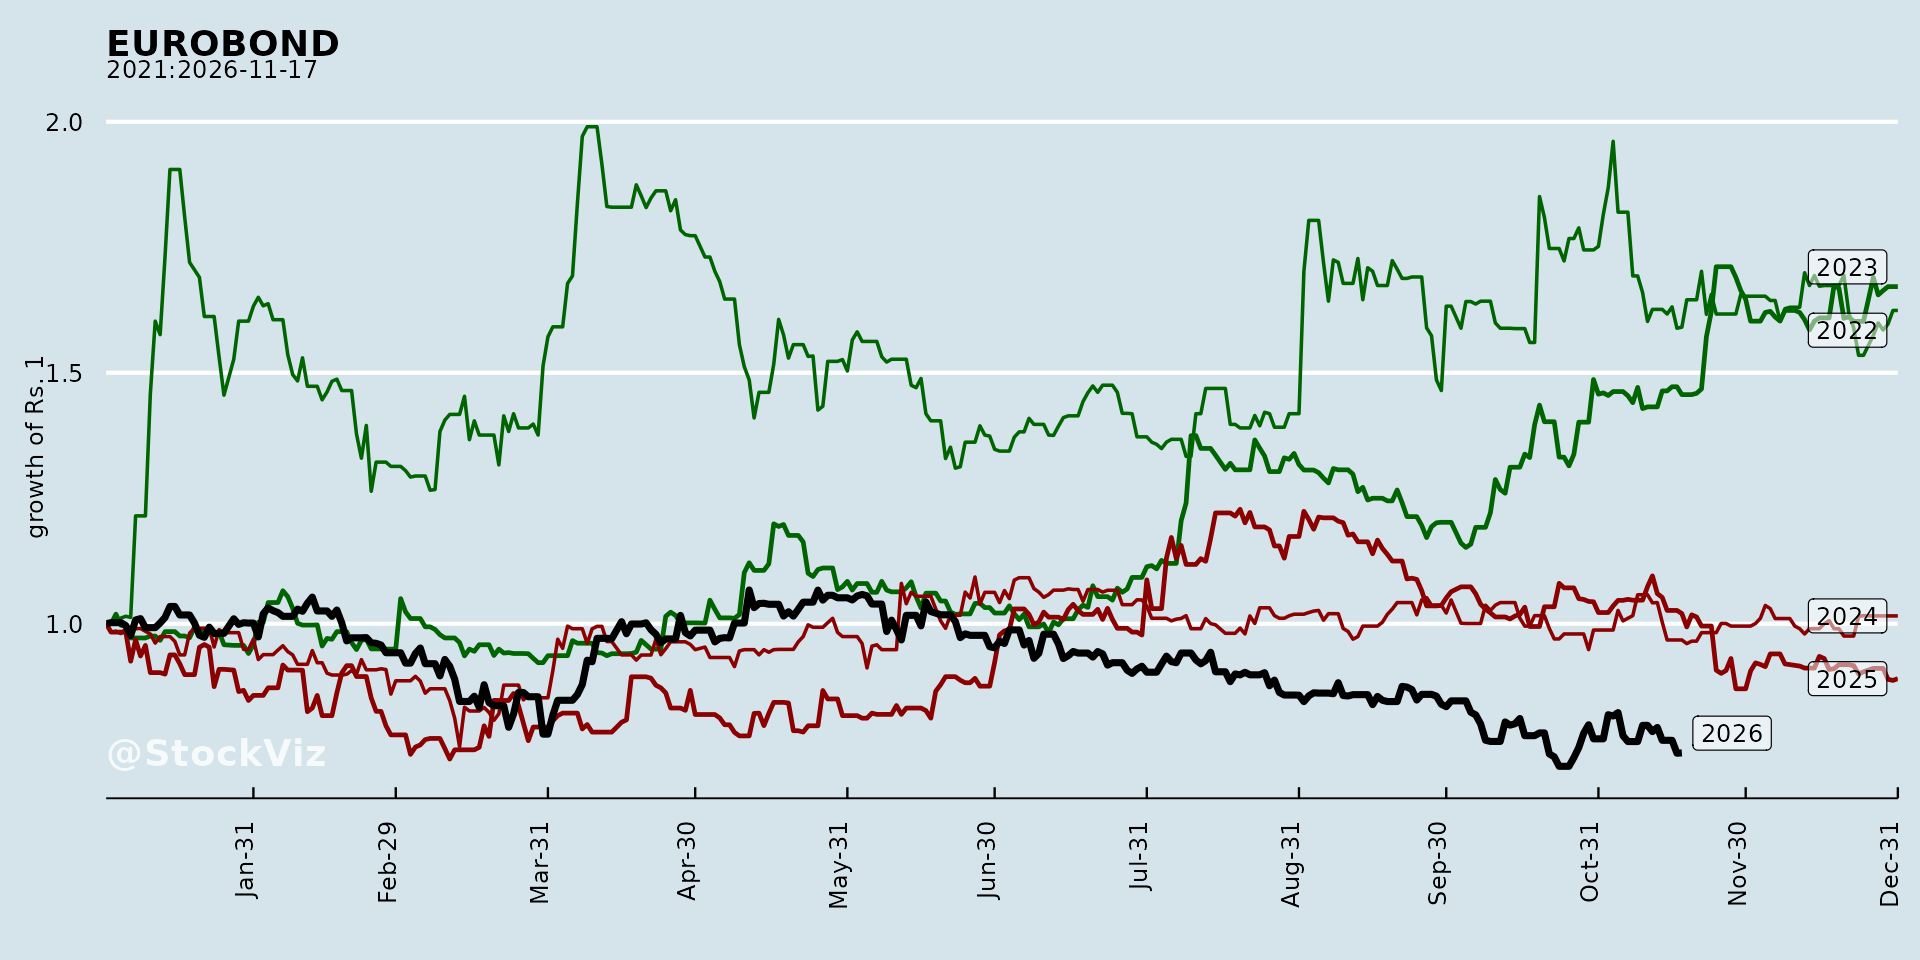
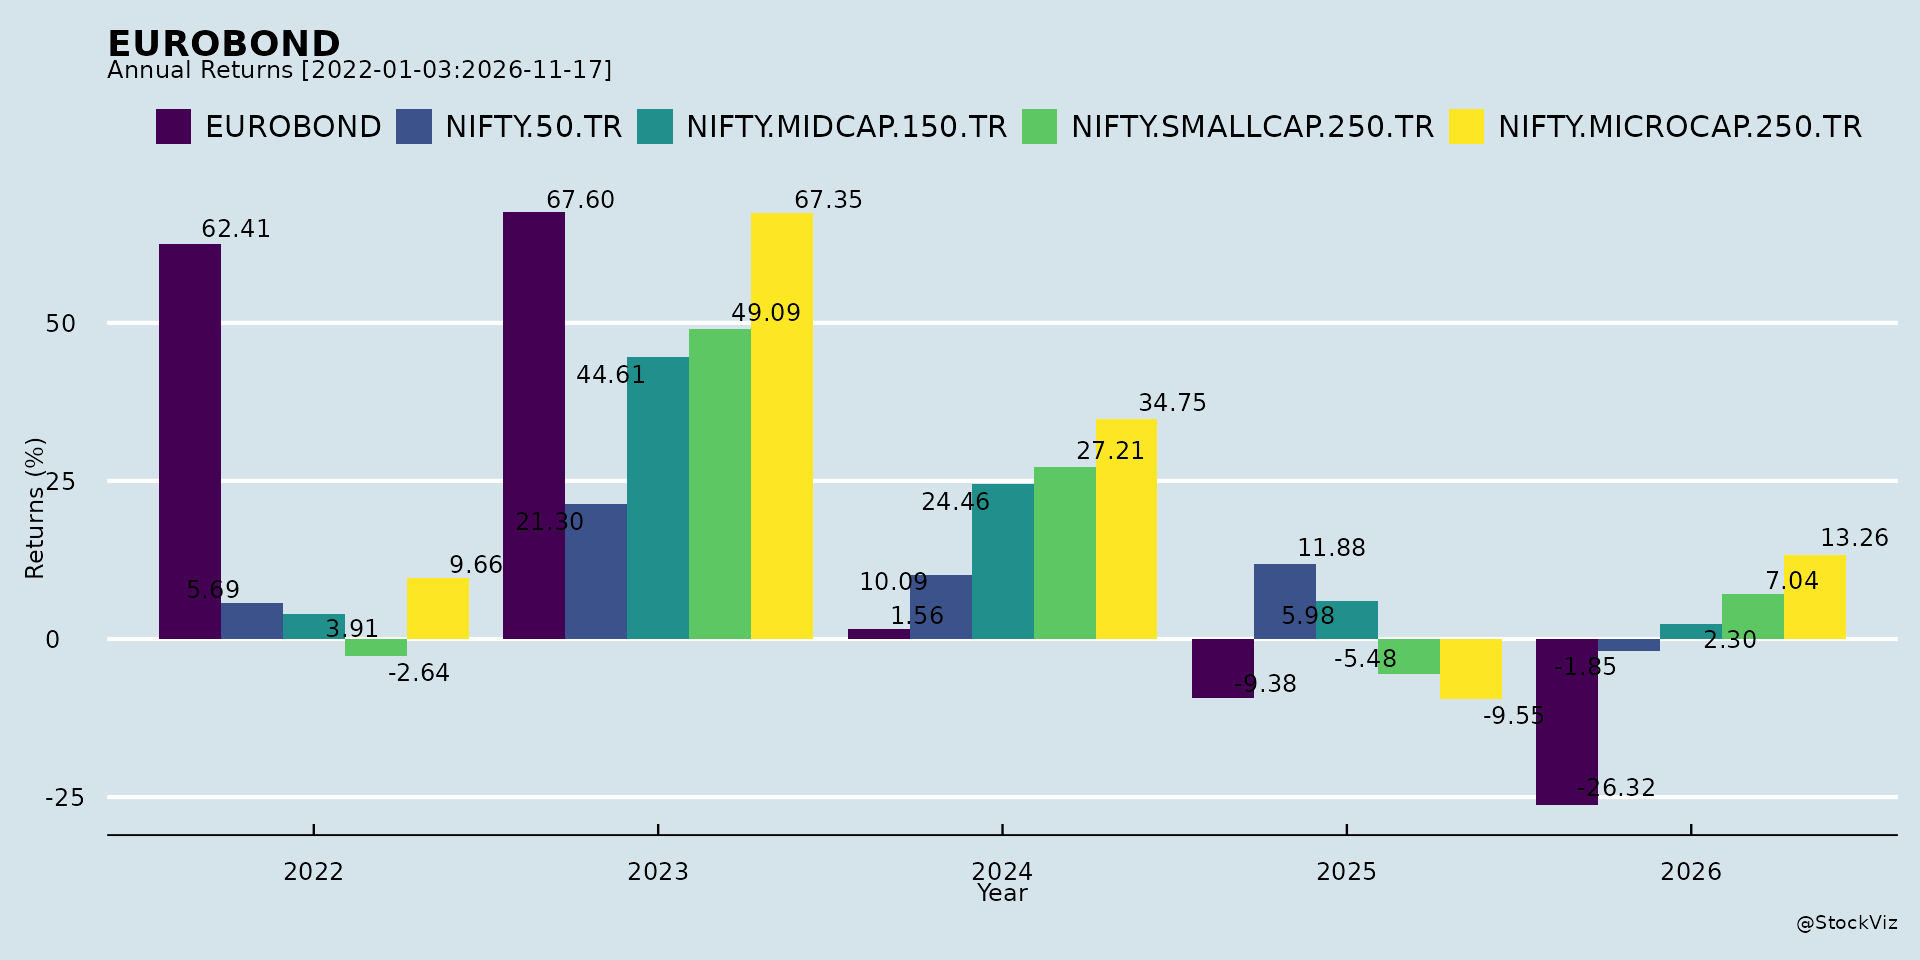
Annual Returns
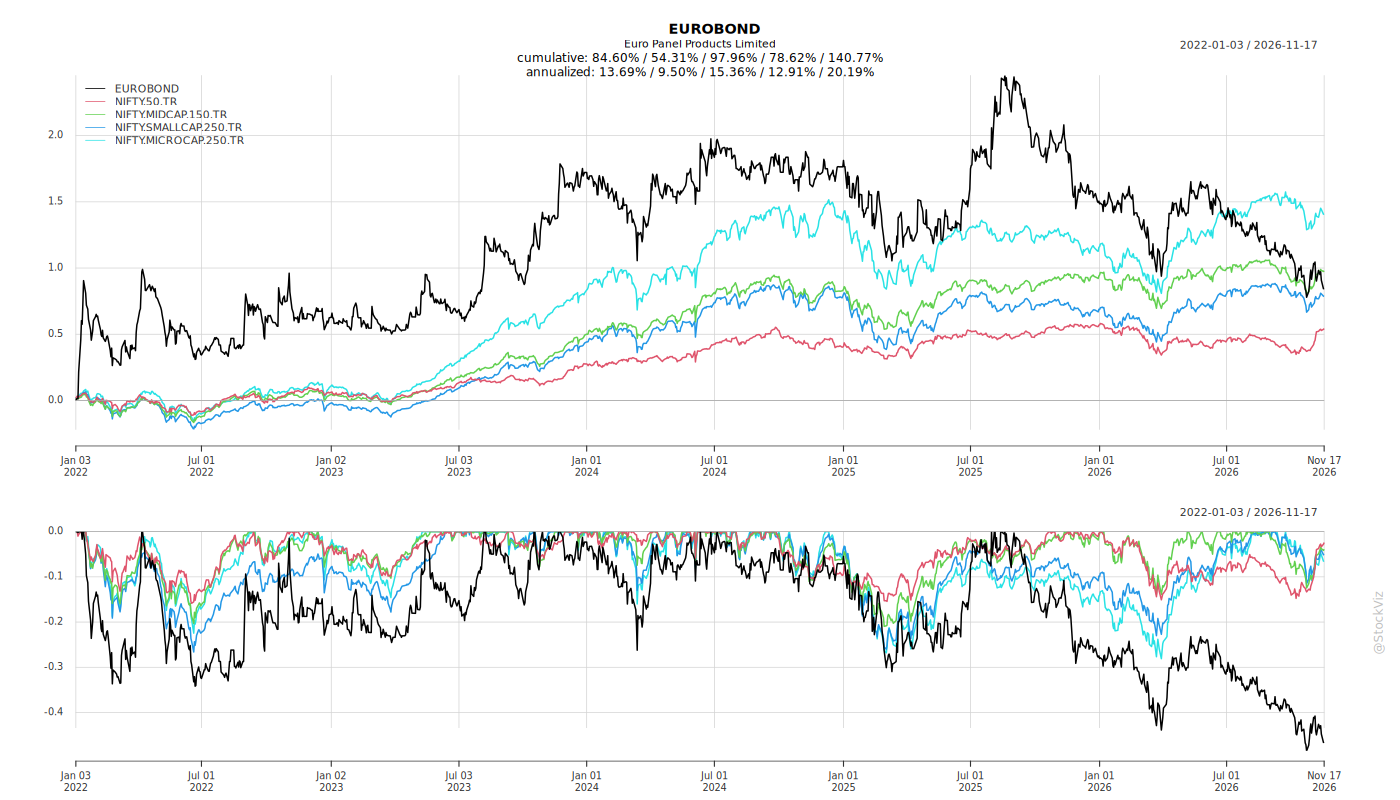
Cumulative Returns and Drawdowns
Fundamentals
Ownership
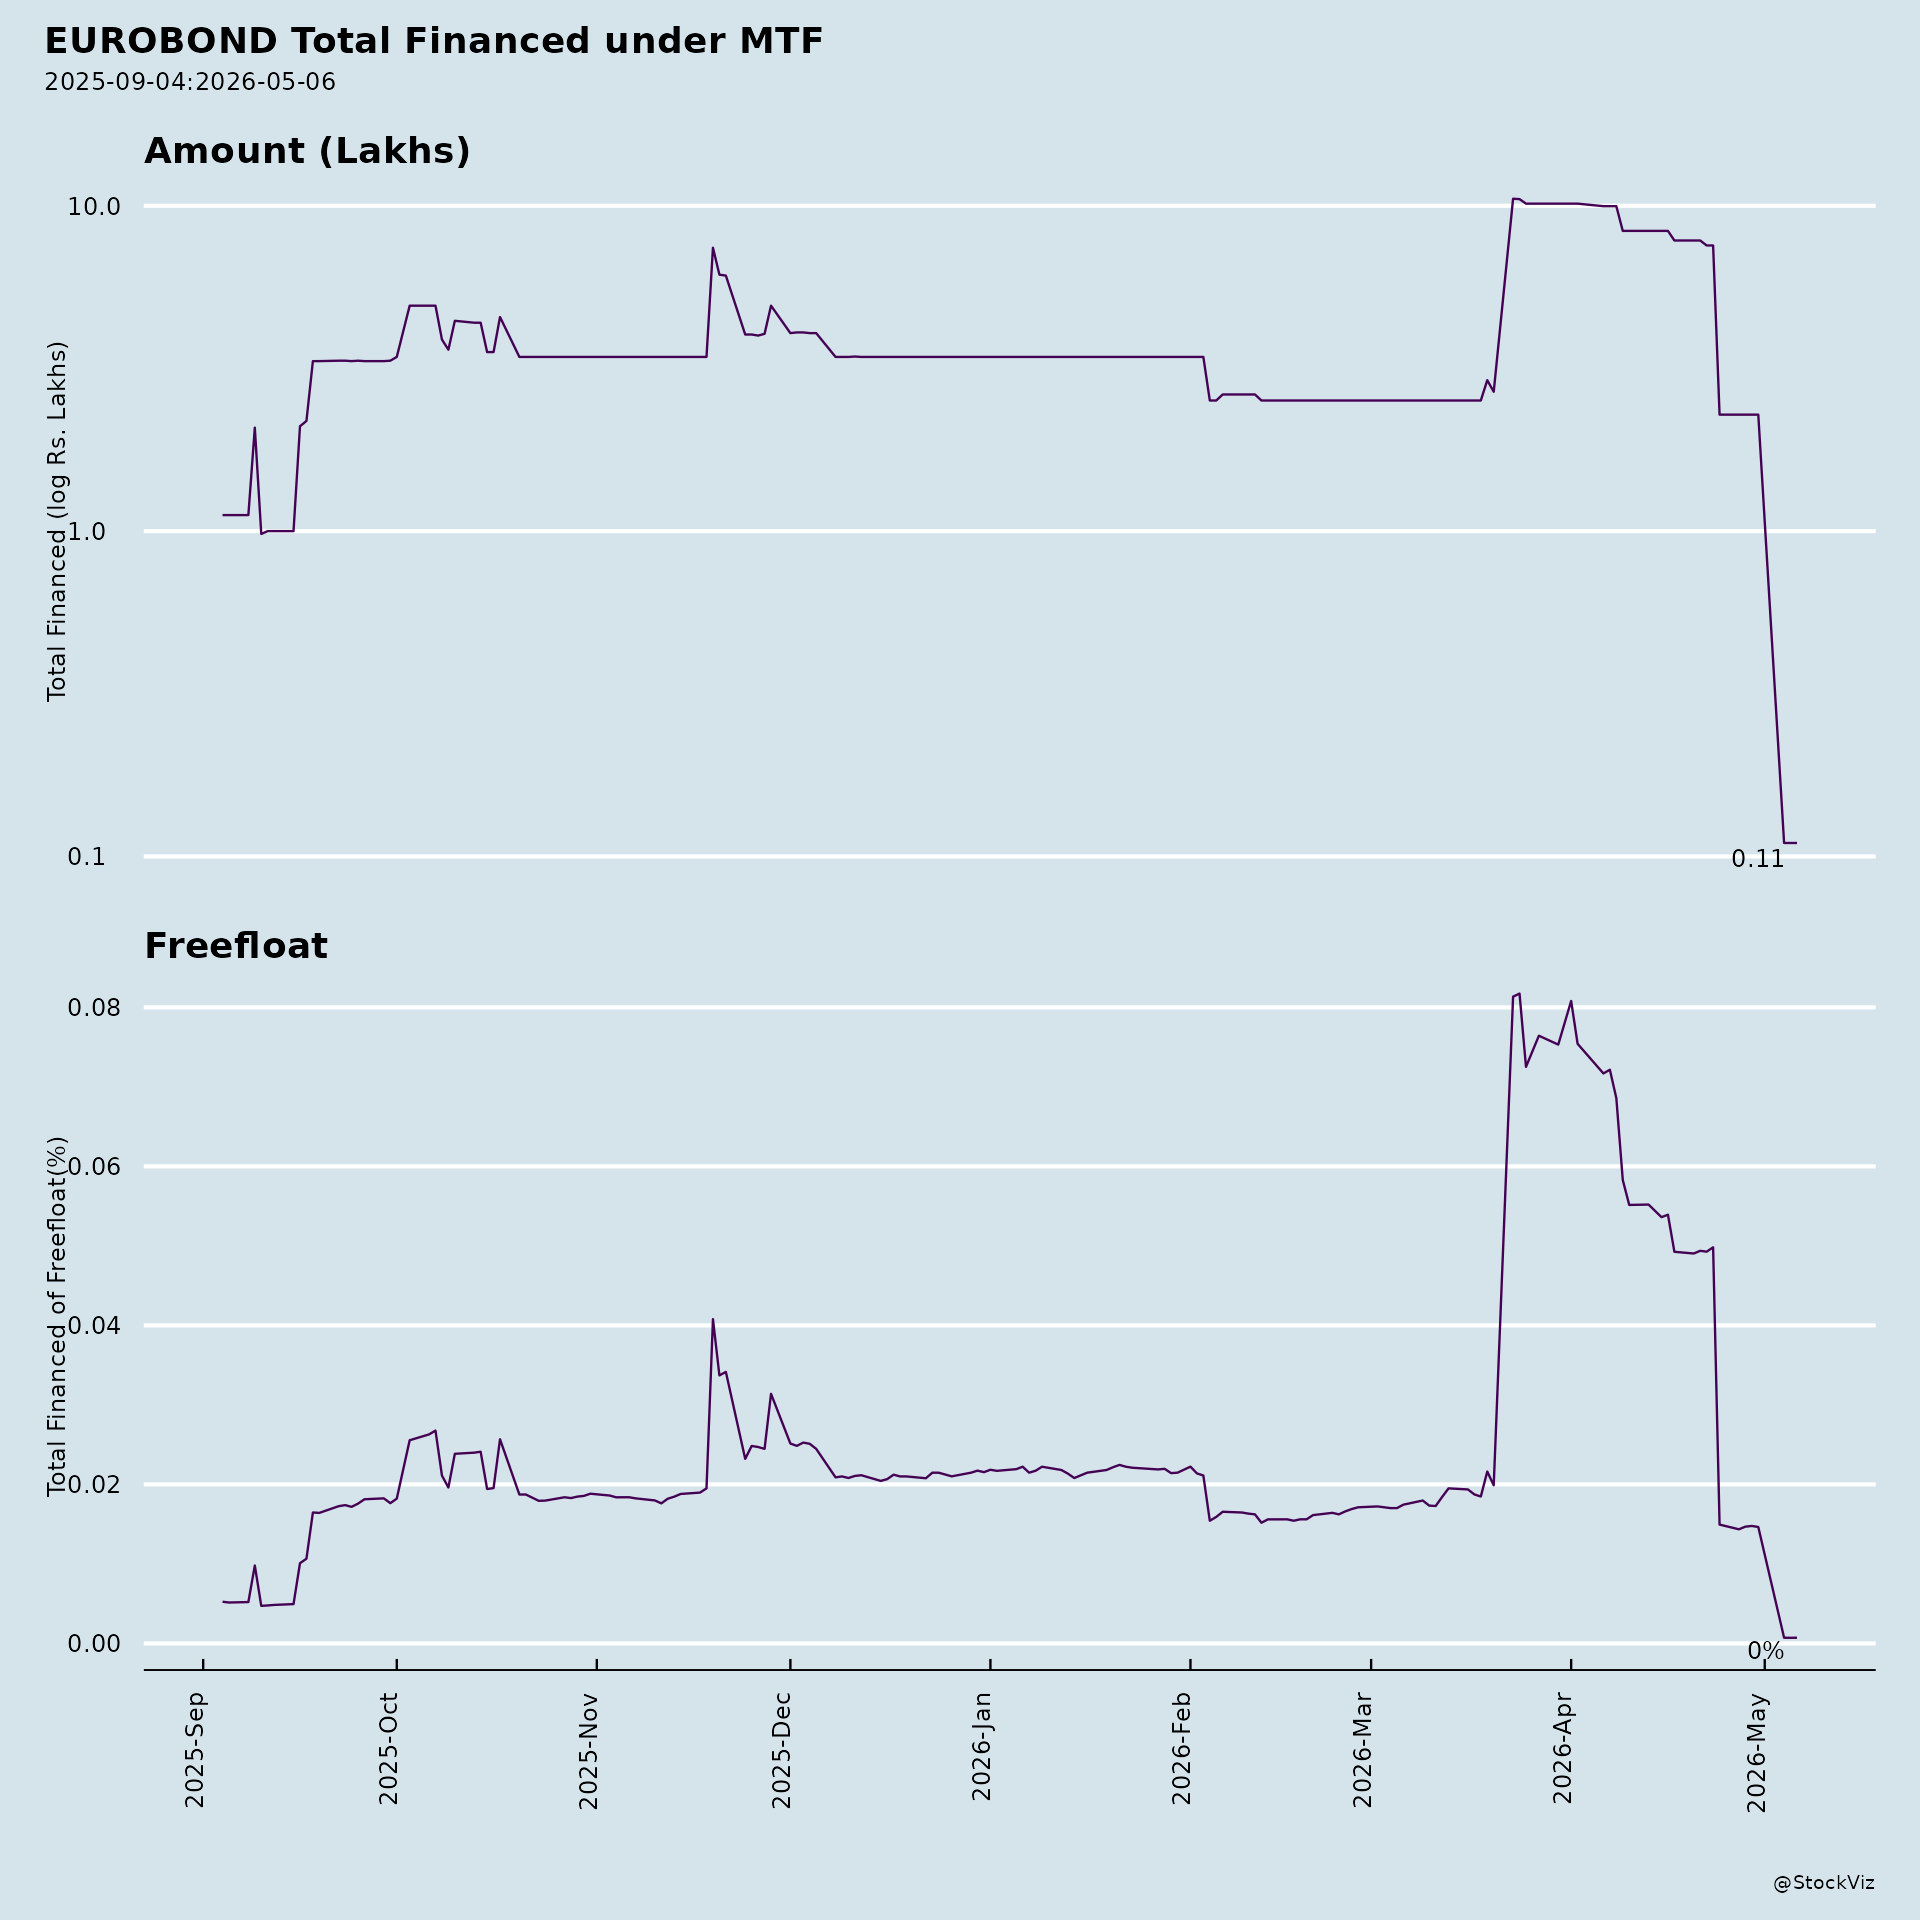
Margined
AI Summary
asof: 2026-09-19
EUROBOND (Euro Panel Products Limited) – Recent Corporate Developments
1. Headwinds and Challenges
- Raw material price volatility: Management identifies volatility in aluminium and polymer raw material prices as a material challenge.
- Competitive intensity: The company faces intense competition from both organised and unorganised manufacturers, alongside pricing pressures within the building materials industry.
- Cost pressures: Rising logistics and transportation costs are cited as a headwind.
- Policy and trade exposure: Changes in government policies and trade regulations present ongoing challenges.
- Weather-related loss: Heavy rains caused damage to inventory at the factory. As of the August 14, 2026 board meeting, management was still in the process of ascertaining the amount and subsequently lodging a claim with the insurance company.
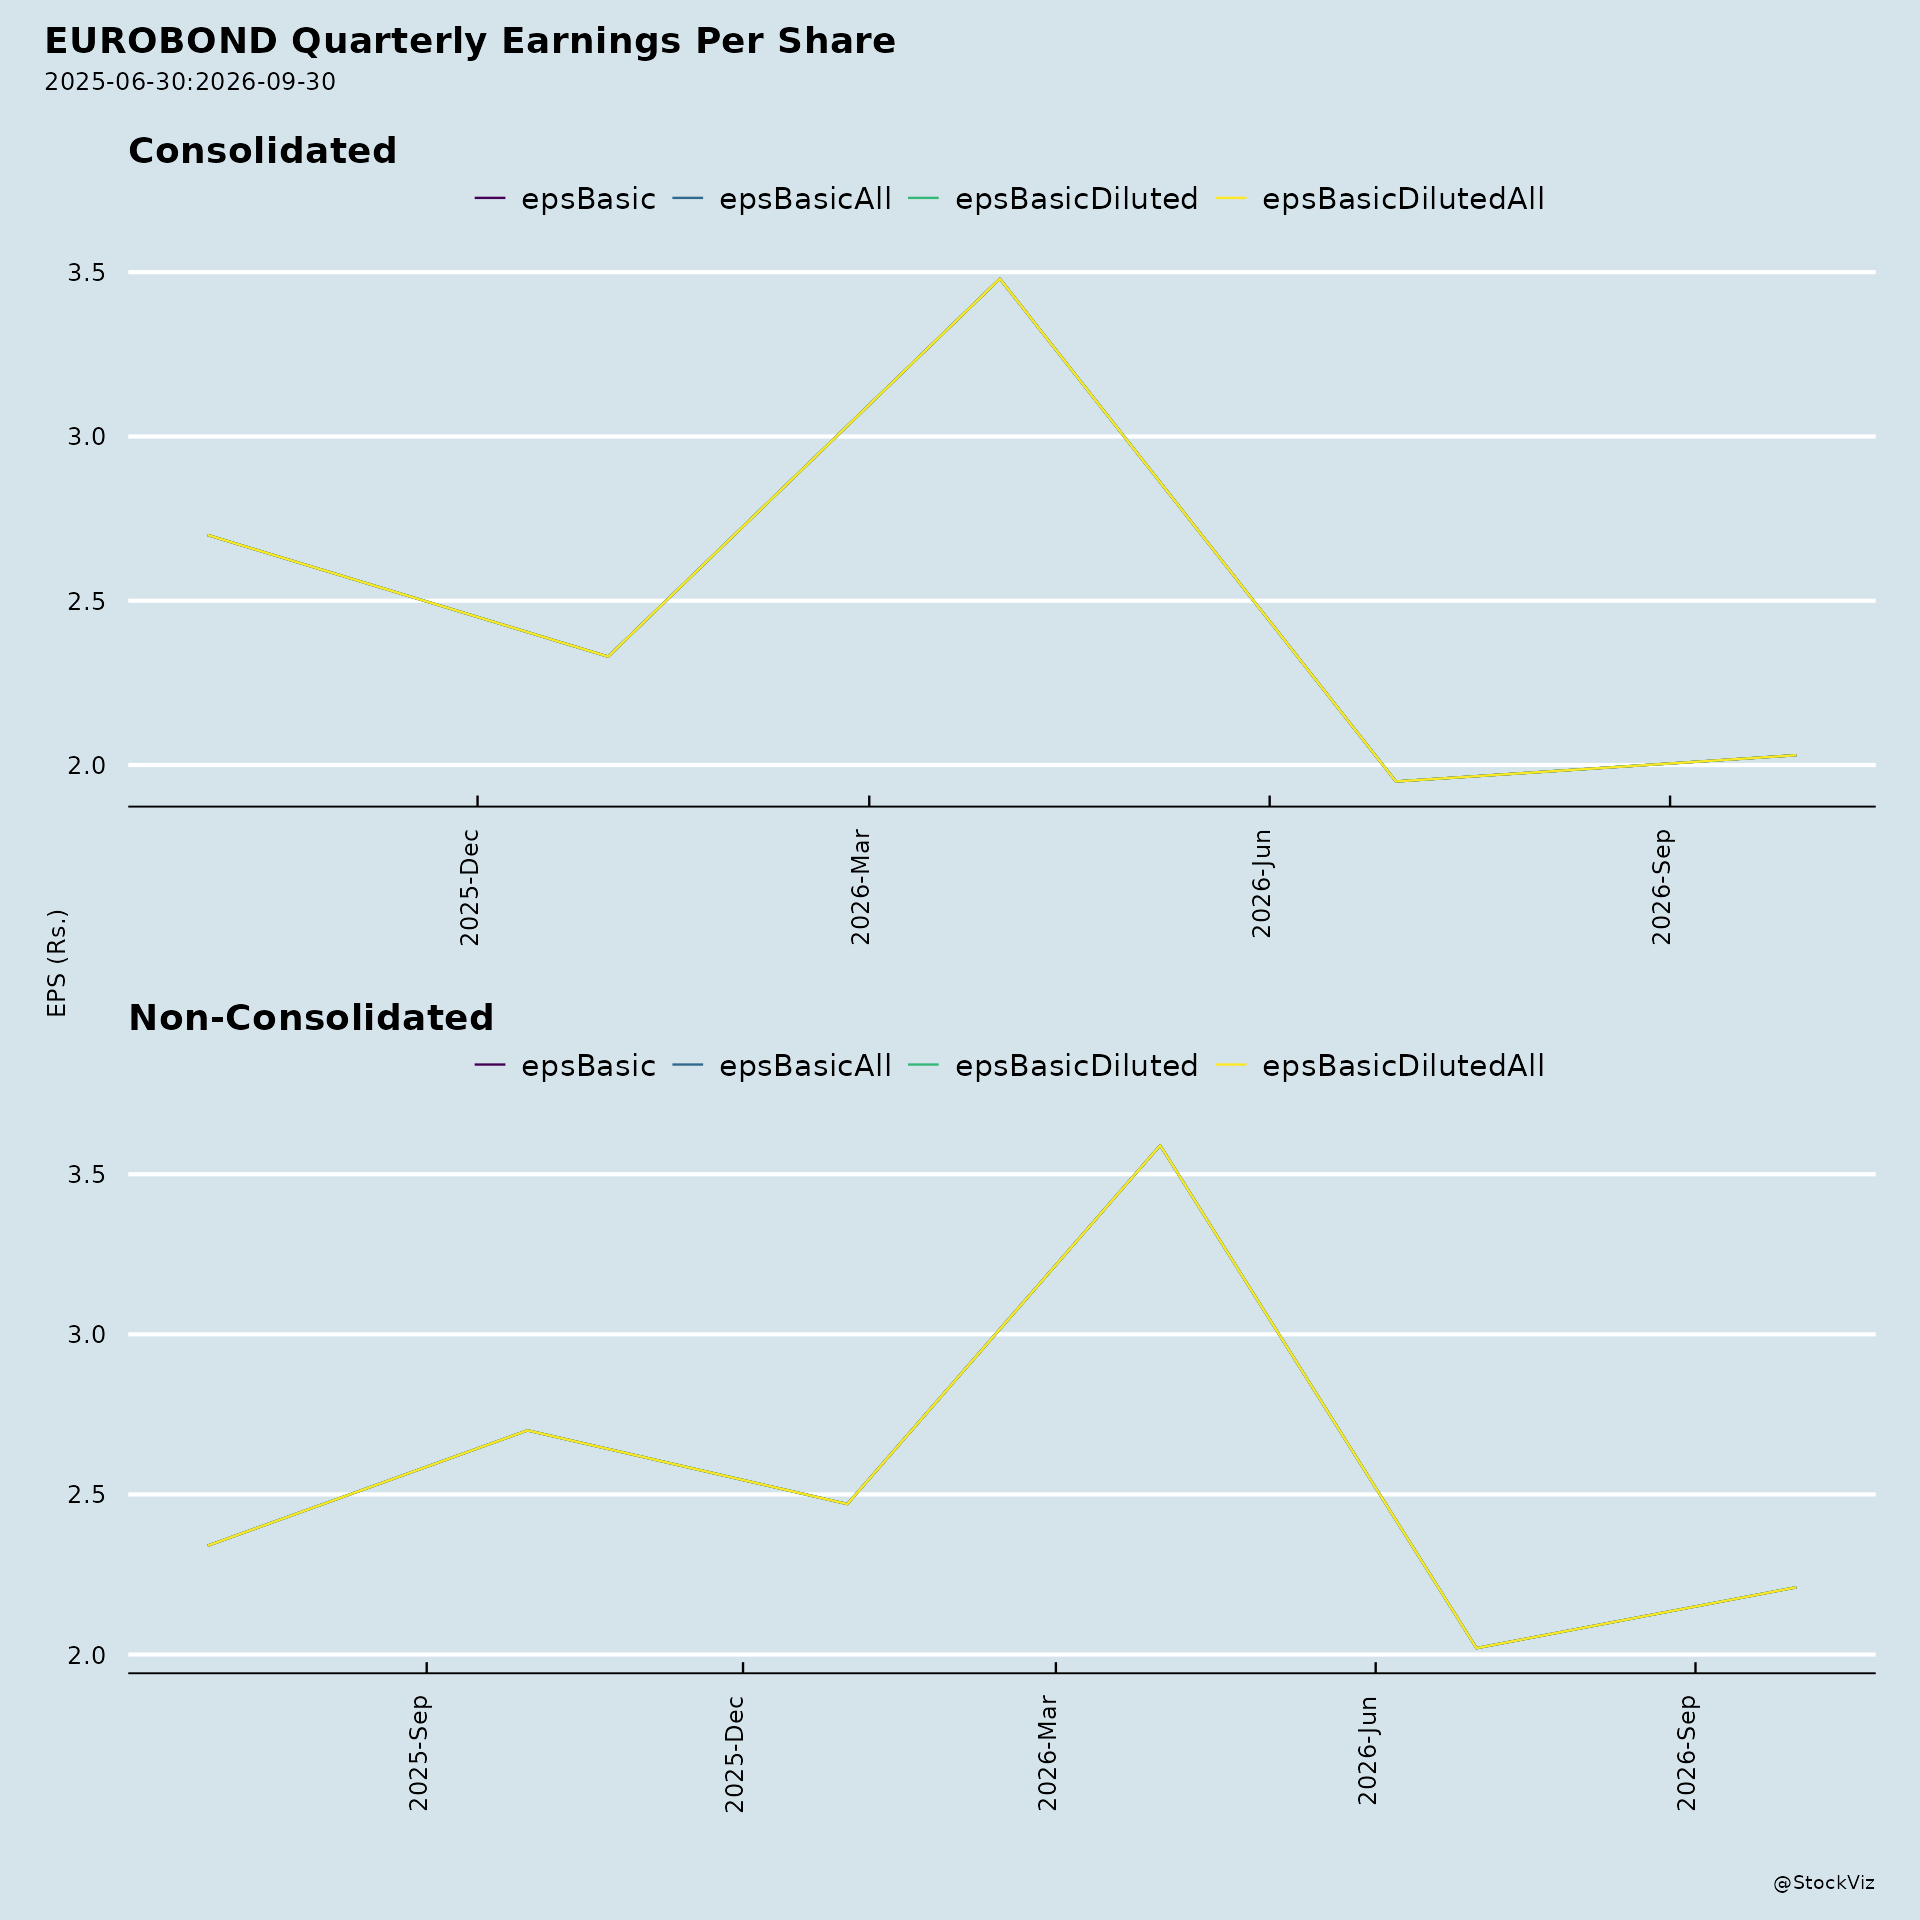
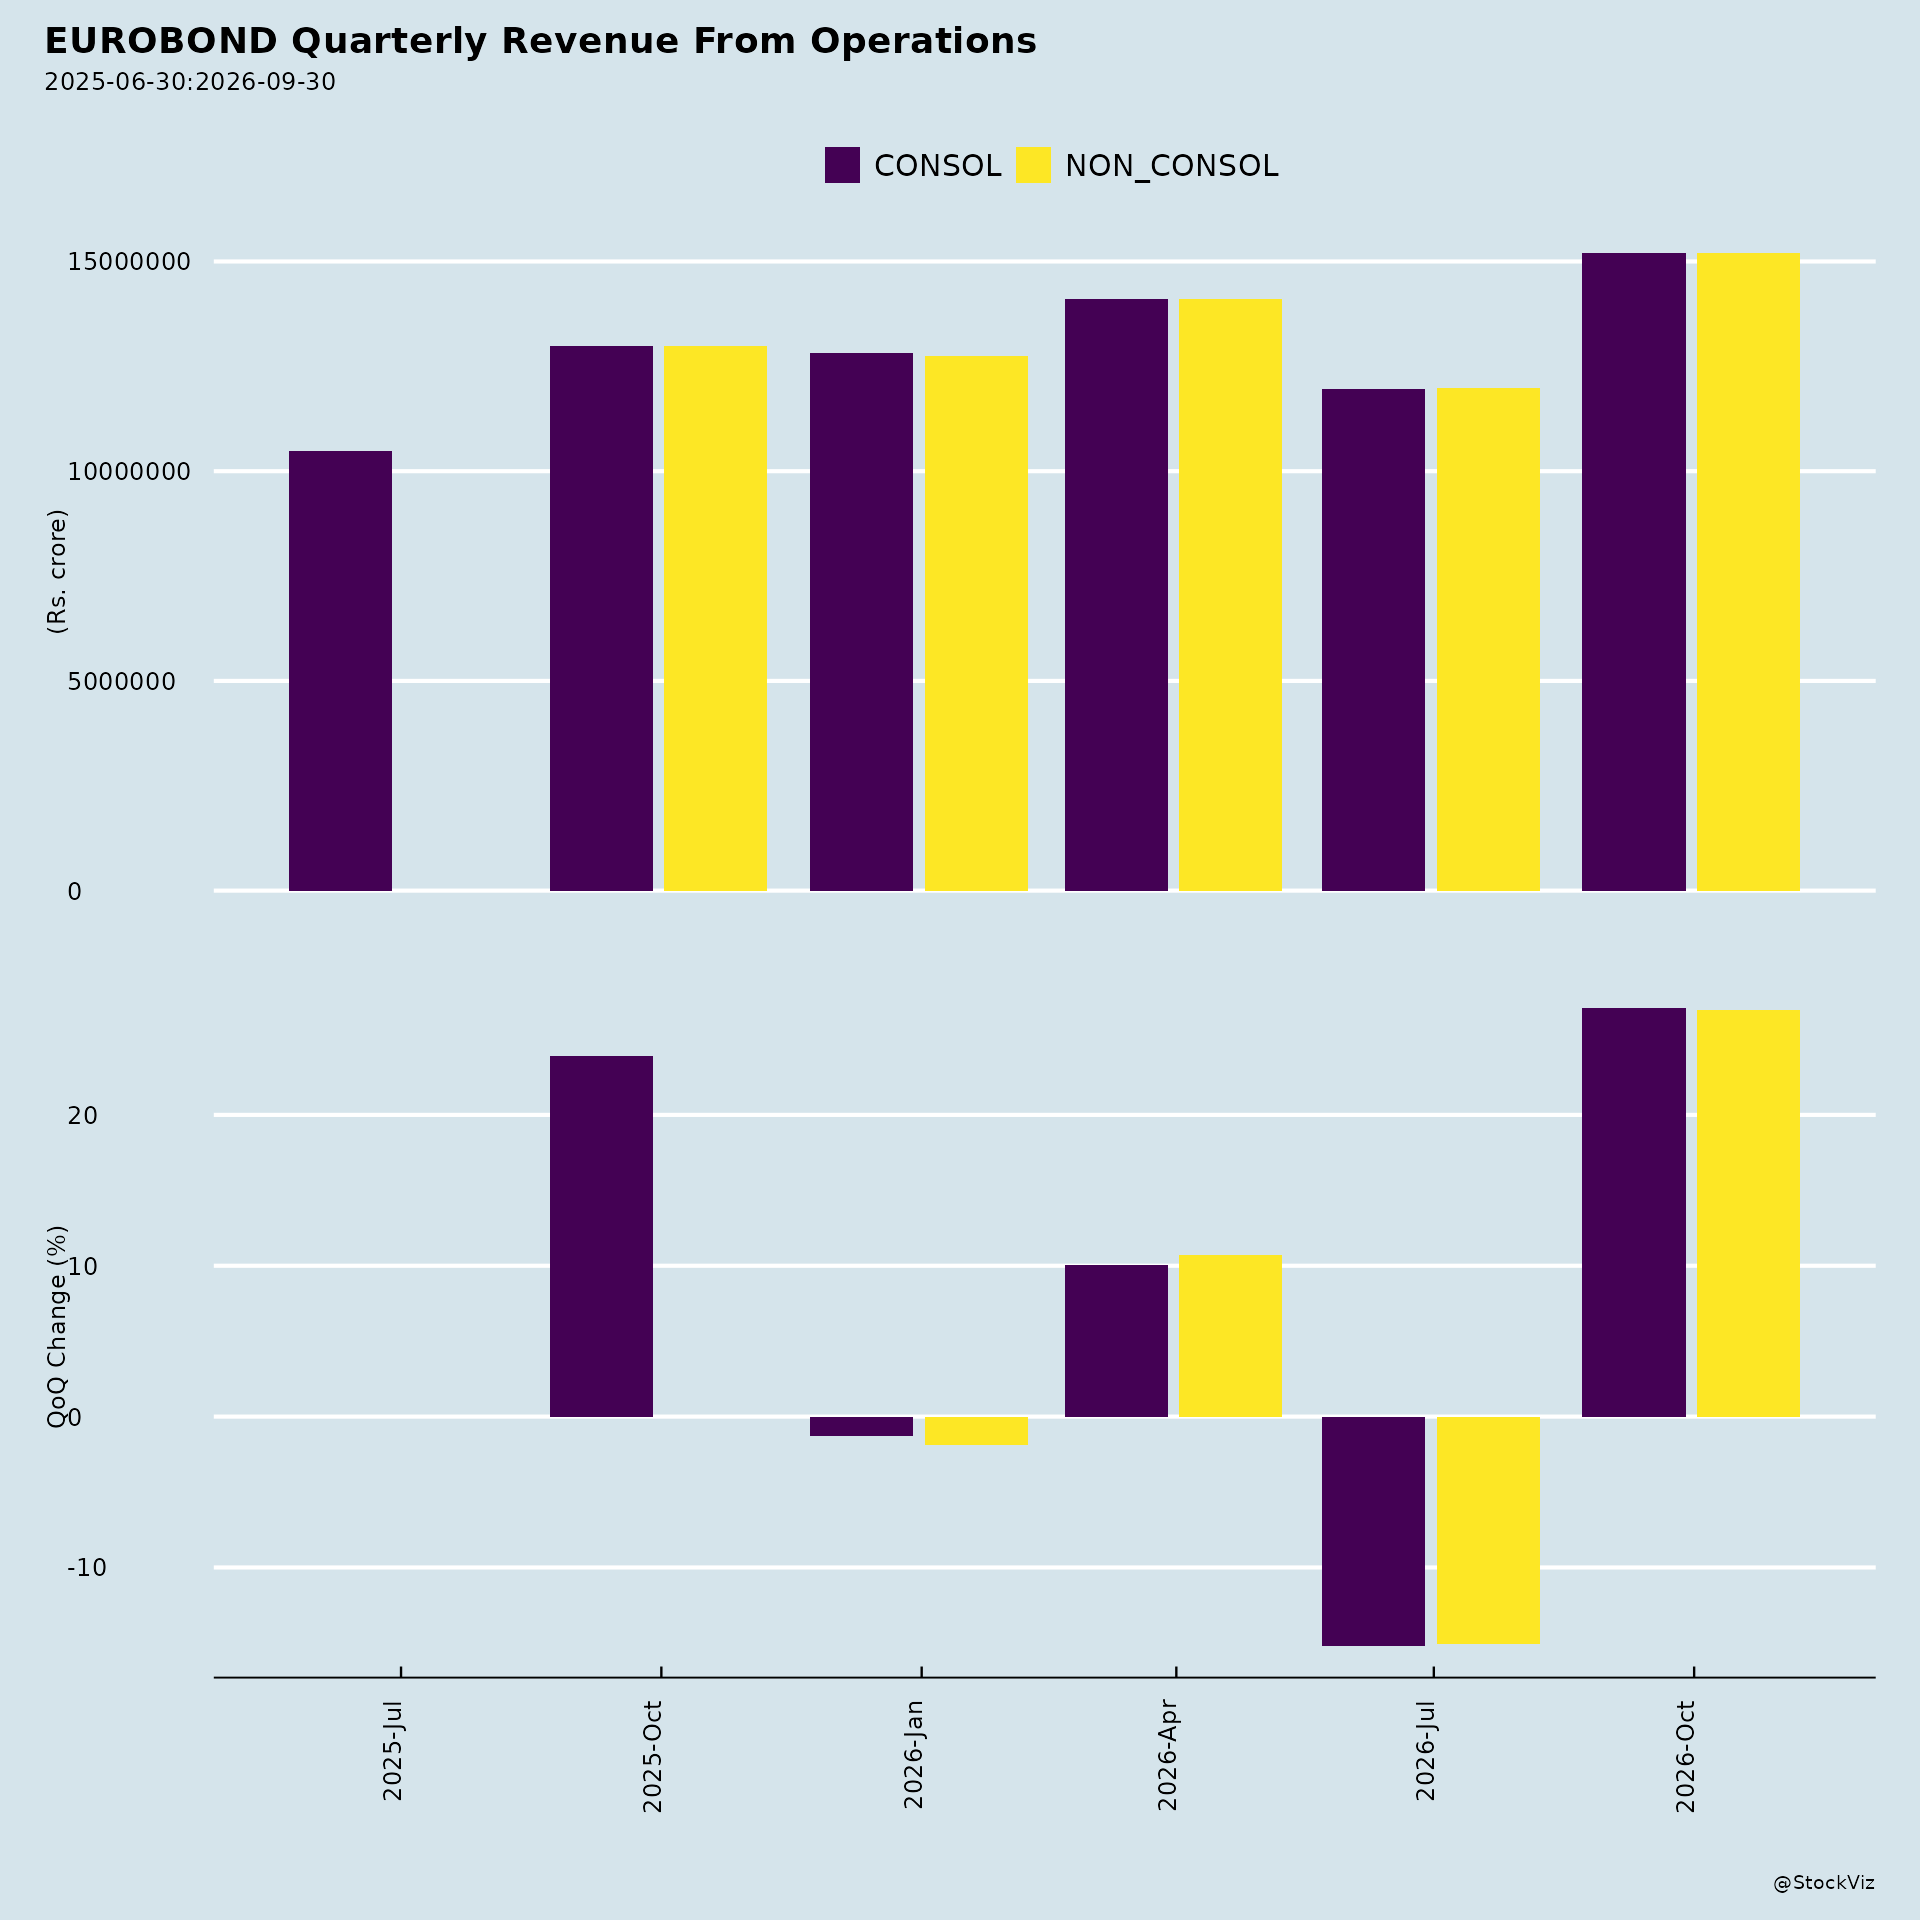
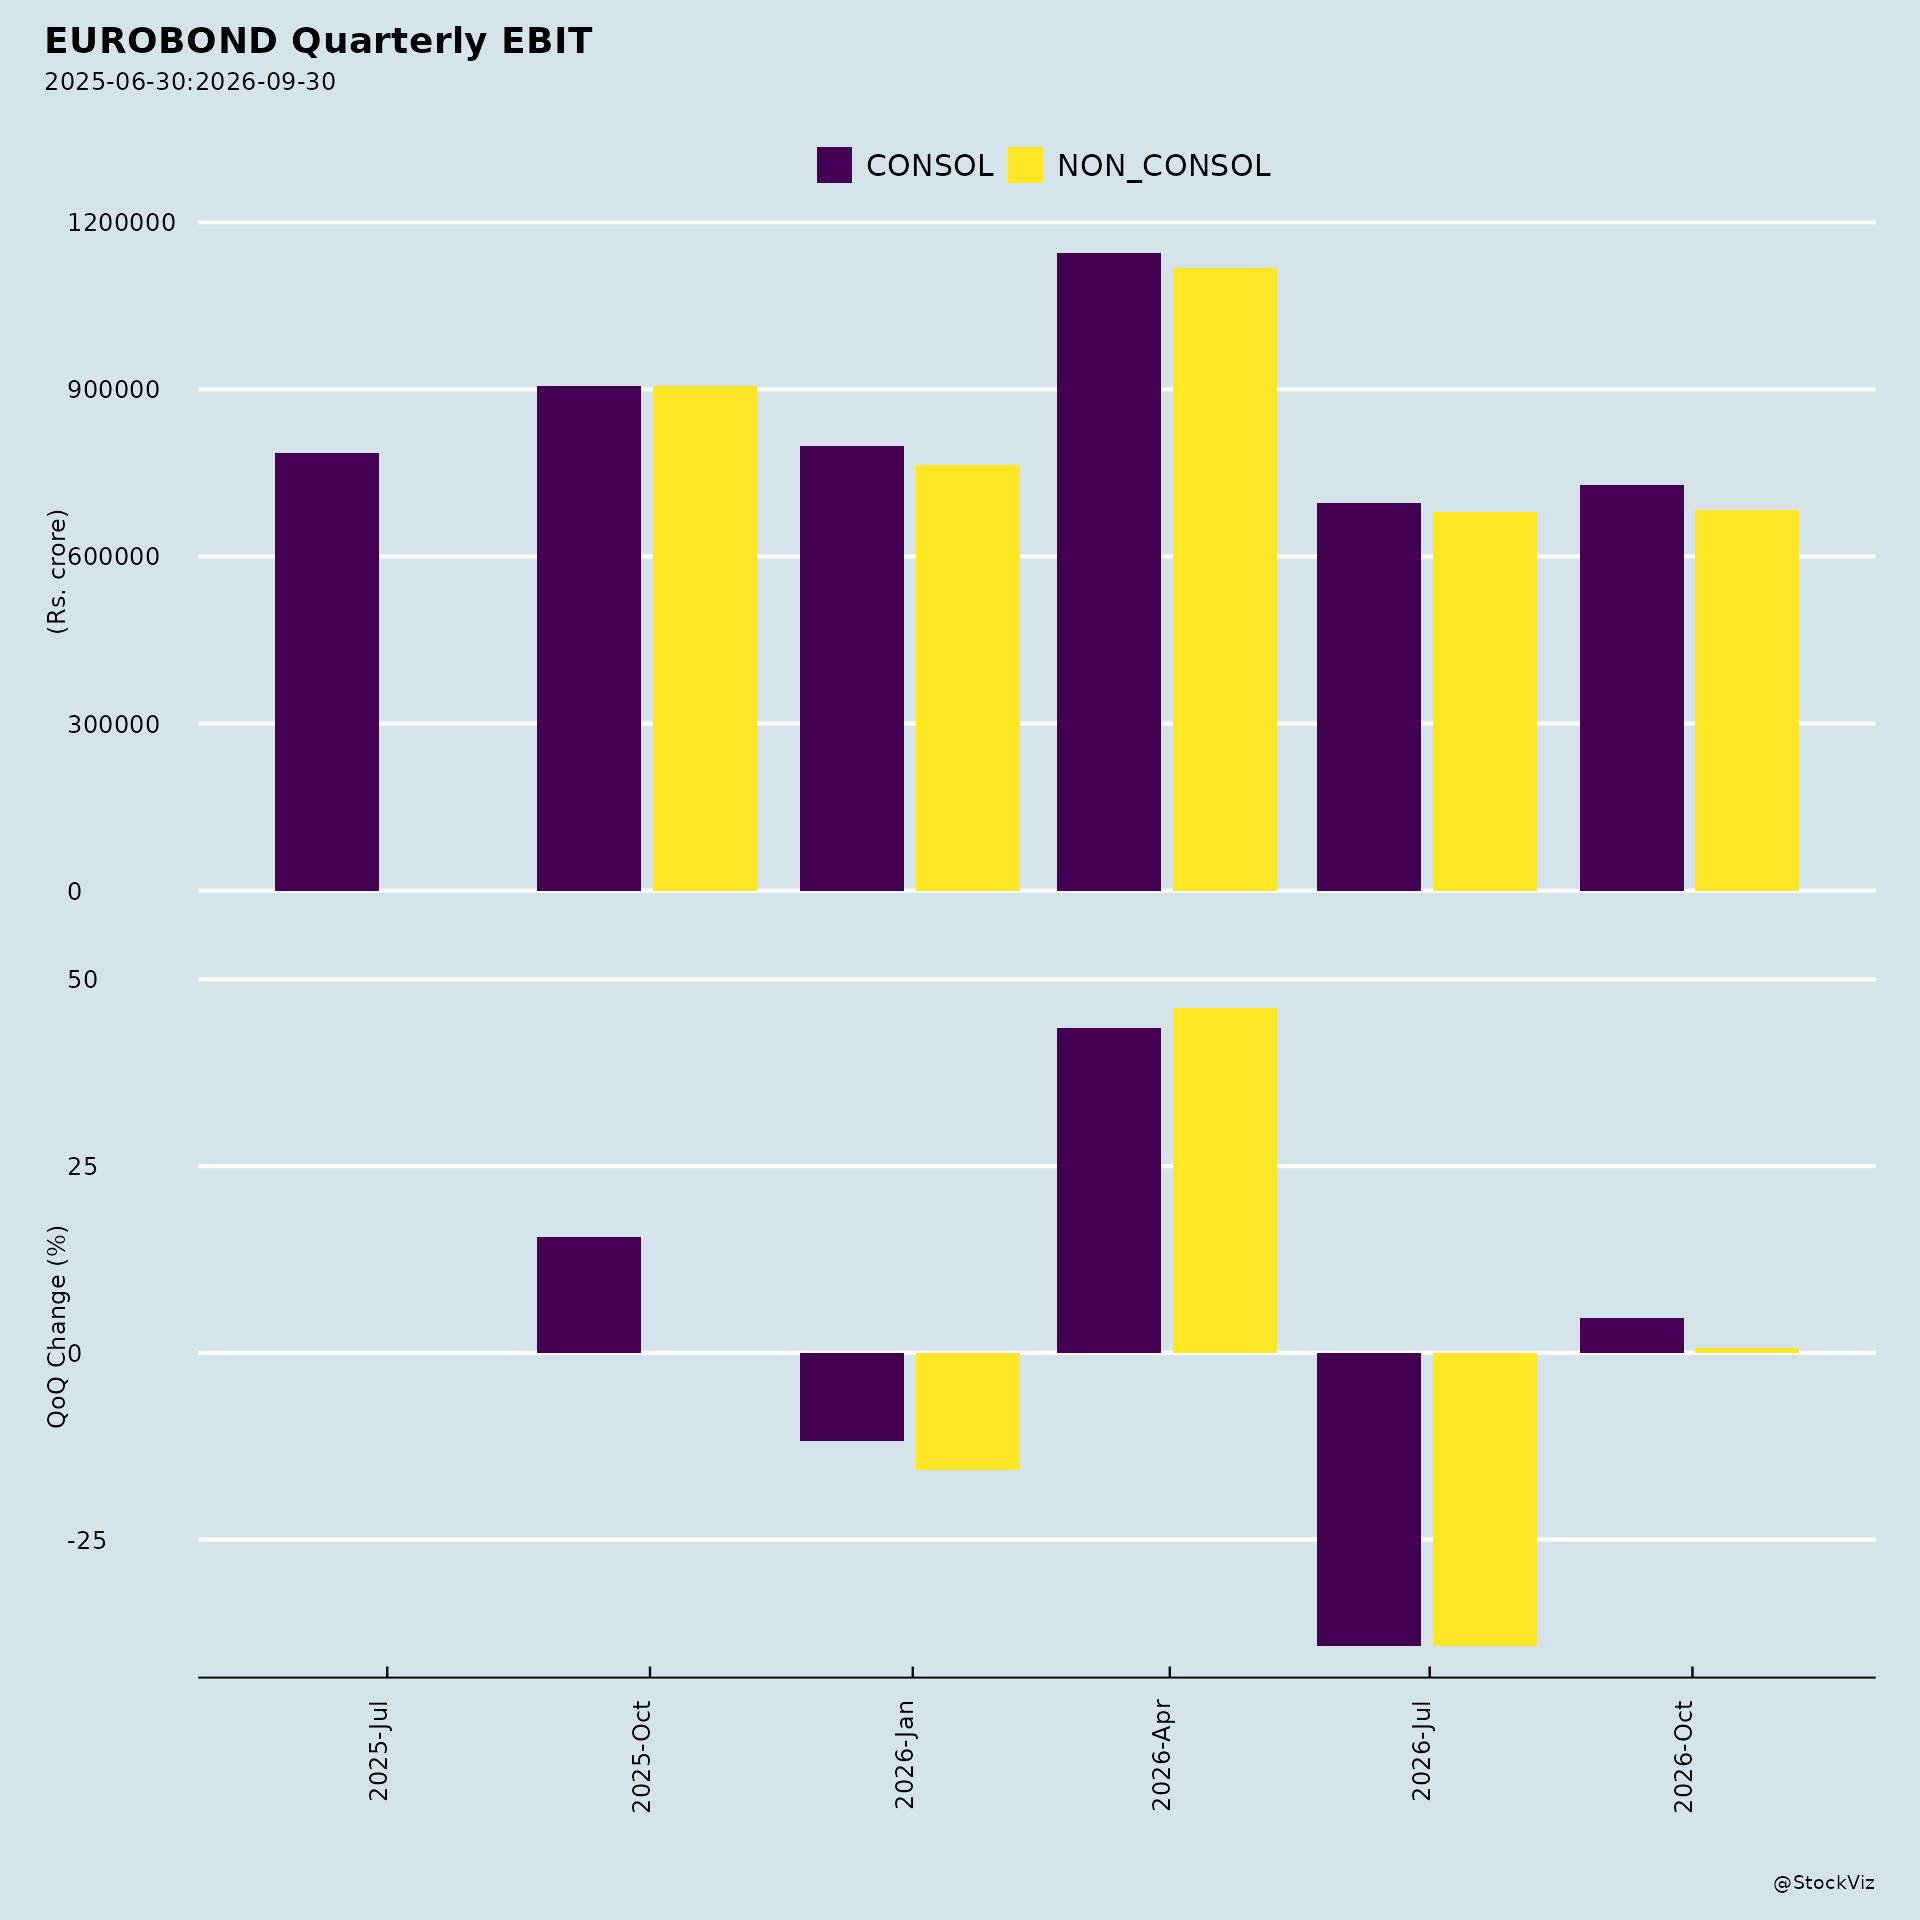
- Sequential moderation in performance: Standalone revenue from operations declined from ₹14,104.14 lakhs in the quarter ended March 31, 2026 to ₹11,962.41 lakhs in the quarter ended June 30, 2026. Standalone profit before tax fell from ₹1,145.65 lakhs to ₹696.39 lakhs over the same period, and standalone profit for the period declined from ₹880.71 lakhs to ₹495.52 lakhs. On a consolidated basis, revenue declined from ₹14,108.63 lakhs to ₹11,981.28 lakhs, and profit for the period fell from ₹852.21 lakhs to ₹478.17 lakhs.
- Finance cost increase: Standalone finance costs rose to ₹372.05 lakhs in the June 2026 quarter from ₹200.52 lakhs in the March 2026 quarter and ₹306.76 lakhs in the June 2025 quarter. Consolidated finance costs showed a similar trend (₹372.29 lakhs versus ₹200.55 lakhs and ₹306.76 lakhs).
- Subsidiary drag: The wholly owned foreign subsidiary in Qatar (Euro Panel Products Trading W.L.L.) reported total revenue of ₹18.86 lakhs and a net loss after tax of ₹18.63 lakhs for the quarter ended June 30, 2026. Its interim financial information was not reviewed by auditors and was furnished by management, which stated it is not material to the Group.
2. Tailwinds and Growth Prospects
- Renewable energy expansion: On July 27, 2026, EUROBOND commissioned a 2.2 MW grid-connected solar facility at Moti Falod, Surat, completing the third phase of its energy expansion and bringing total operational solar capacity to 3.6 MW. This allows the facility to offset 50% of its total factory power requirements, up from a previous 20% offset capability. The plant is designed to generate 30 lakh units of clean electricity annually. The transition began with a 520 kW installation in 2020 and expanded to 1.4 MW in 2024.
- Resource conservation: The company operates Zero Liquid Discharge operations with in-house sewage and effluent treatment facilities that reclaimed over 1,322,500 litres of treated water over the preceding six months, used for site gardening, greenbelt maintenance, and general facility requirements.
- Green building alignment: As Indian Green Building Council frameworks emphasise supply chain transparency, developers and architects are seeking low-carbon building materials. EUROBOND’s clean energy setup and water reclamation systems offer environmental benchmarks that can help commercial and residential developments achieve green building certifications.
- Quality infrastructure: The company expanded its in-house laboratory’s NABL accreditation scope from 16 to 51 parameters covering coil, coating, core, ACP, and MCP. It is described as the only ACP manufacturer in India holding NABL accreditation across 51 parameters.
- Demand environment: Strong domestic demand is supported by urbanisation, sustained public investment in infrastructure, industrial expansion, commercial real estate growth, and increasing demand for modern architectural façade solutions and aluminium composite panels.
- Subsidiary expansion: The company incorporated Euro Sealant Private Limited on April 28, 2026, and Eurobond Dimensions Private Limited (70% stake, registered office in Mumbai) received its certificate of incorporation on July 15, 2026. Euro Panel Products Trading W.L.L. was incorporated in Qatar on August 28, 2025.
- Capital markets milestone: The company successfully migrated from the NSE Emerge platform to the Main Boards of NSE and BSE.
3. Key Risks
- Raw material and pricing risk: Volatility in aluminium and polymer prices combined with pricing pressures in the building materials industry.
- Competitive risk: Pressure from organised and unorganised manufacturers.
- Regulatory and trade risk: Changes in government policies and trade regulations.
- Cost inflation risk: Rising logistics and transportation costs.
- Unquantified inventory loss: The rain-related damage to factory inventory had not yet been quantified as of August 14, 2026, and the insurance claim was yet to be lodged.
- Unreviewed subsidiary financials: The Qatar subsidiary’s interim financial information has not been reviewed by auditors; the auditor’s conclusion on the consolidated statement relies solely on management-certified information for that entity.
- Governance transition: Two new Independent Directors — Mr. Rajesh Nagardas Gandhi (DIN: 02644916) and Mr. Samarth Ishwar Bhimani (DIN: 11873660) — were appointed as Additional Directors for five-year terms on August 14, 2026, subject to member approval at the ensuing Annual General Meeting.
4. Management Guidance Versus Observed Business Performance
- Guidance: Management expects sustainable revenue growth supported by increasing market demand, expansion of domestic and international business operations, improved operating margins through better efficiency, higher contribution from value-added and premium products, continued investment in technology and manufacturing capabilities, and effective working capital management.
- Observed performance: Standalone revenue from operations for the full year ended March 31, 2026 was ₹50,393.24 lakhs, with profit after tax of ₹2,719.72 lakhs. Consolidated revenue from operations for FY 2025-26 was ₹50,320.34 lakhs, with consolidated profit after tax of ₹2,656.45 lakhs. The company reported FY 2025-26 revenue from operations of ₹503.20 crore and profit after tax of ₹26.84 crore.
- Quarterly trend: The June 2026 quarter showed sequential declines in revenue and profitability relative to the March 2026 quarter, though standalone revenue was higher than the June 2025 quarter (₹11,962.41 lakhs versus ₹10,483.58 lakhs). Standalone profit for the June 2026 quarter (₹495.52 lakhs) was lower than both the March 2026 quarter (₹880.71 lakhs) and the June 2025 quarter (₹572.25 lakhs). Consolidated profit for the June 2026 quarter (₹478.17 lakhs) was also lower than the June 2025 quarter (₹572.25 lakhs).
- International expansion: The Qatar subsidiary contributed ₹18.86 lakhs in revenue and a net loss after tax of ₹18.63 lakhs for the June 2026 quarter, indicating early-stage operations. The newly incorporated Euro Sealant Private Limited and Eurobond Dimensions Private Limited had not yet contributed to reported results as of the June 2026 quarter.
- Operational investments: The solar commissioning, water reclamation, and NABL accreditation expansion reflect progress on the stated focus on technology, manufacturing capabilities, and responsible operations, though their financial impact is not separately quantified in the supplied results.
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.