EMAMIREAL
Equity Metrics
September 24, 2026
Emami Realty Limited
Residential Commercial Projects
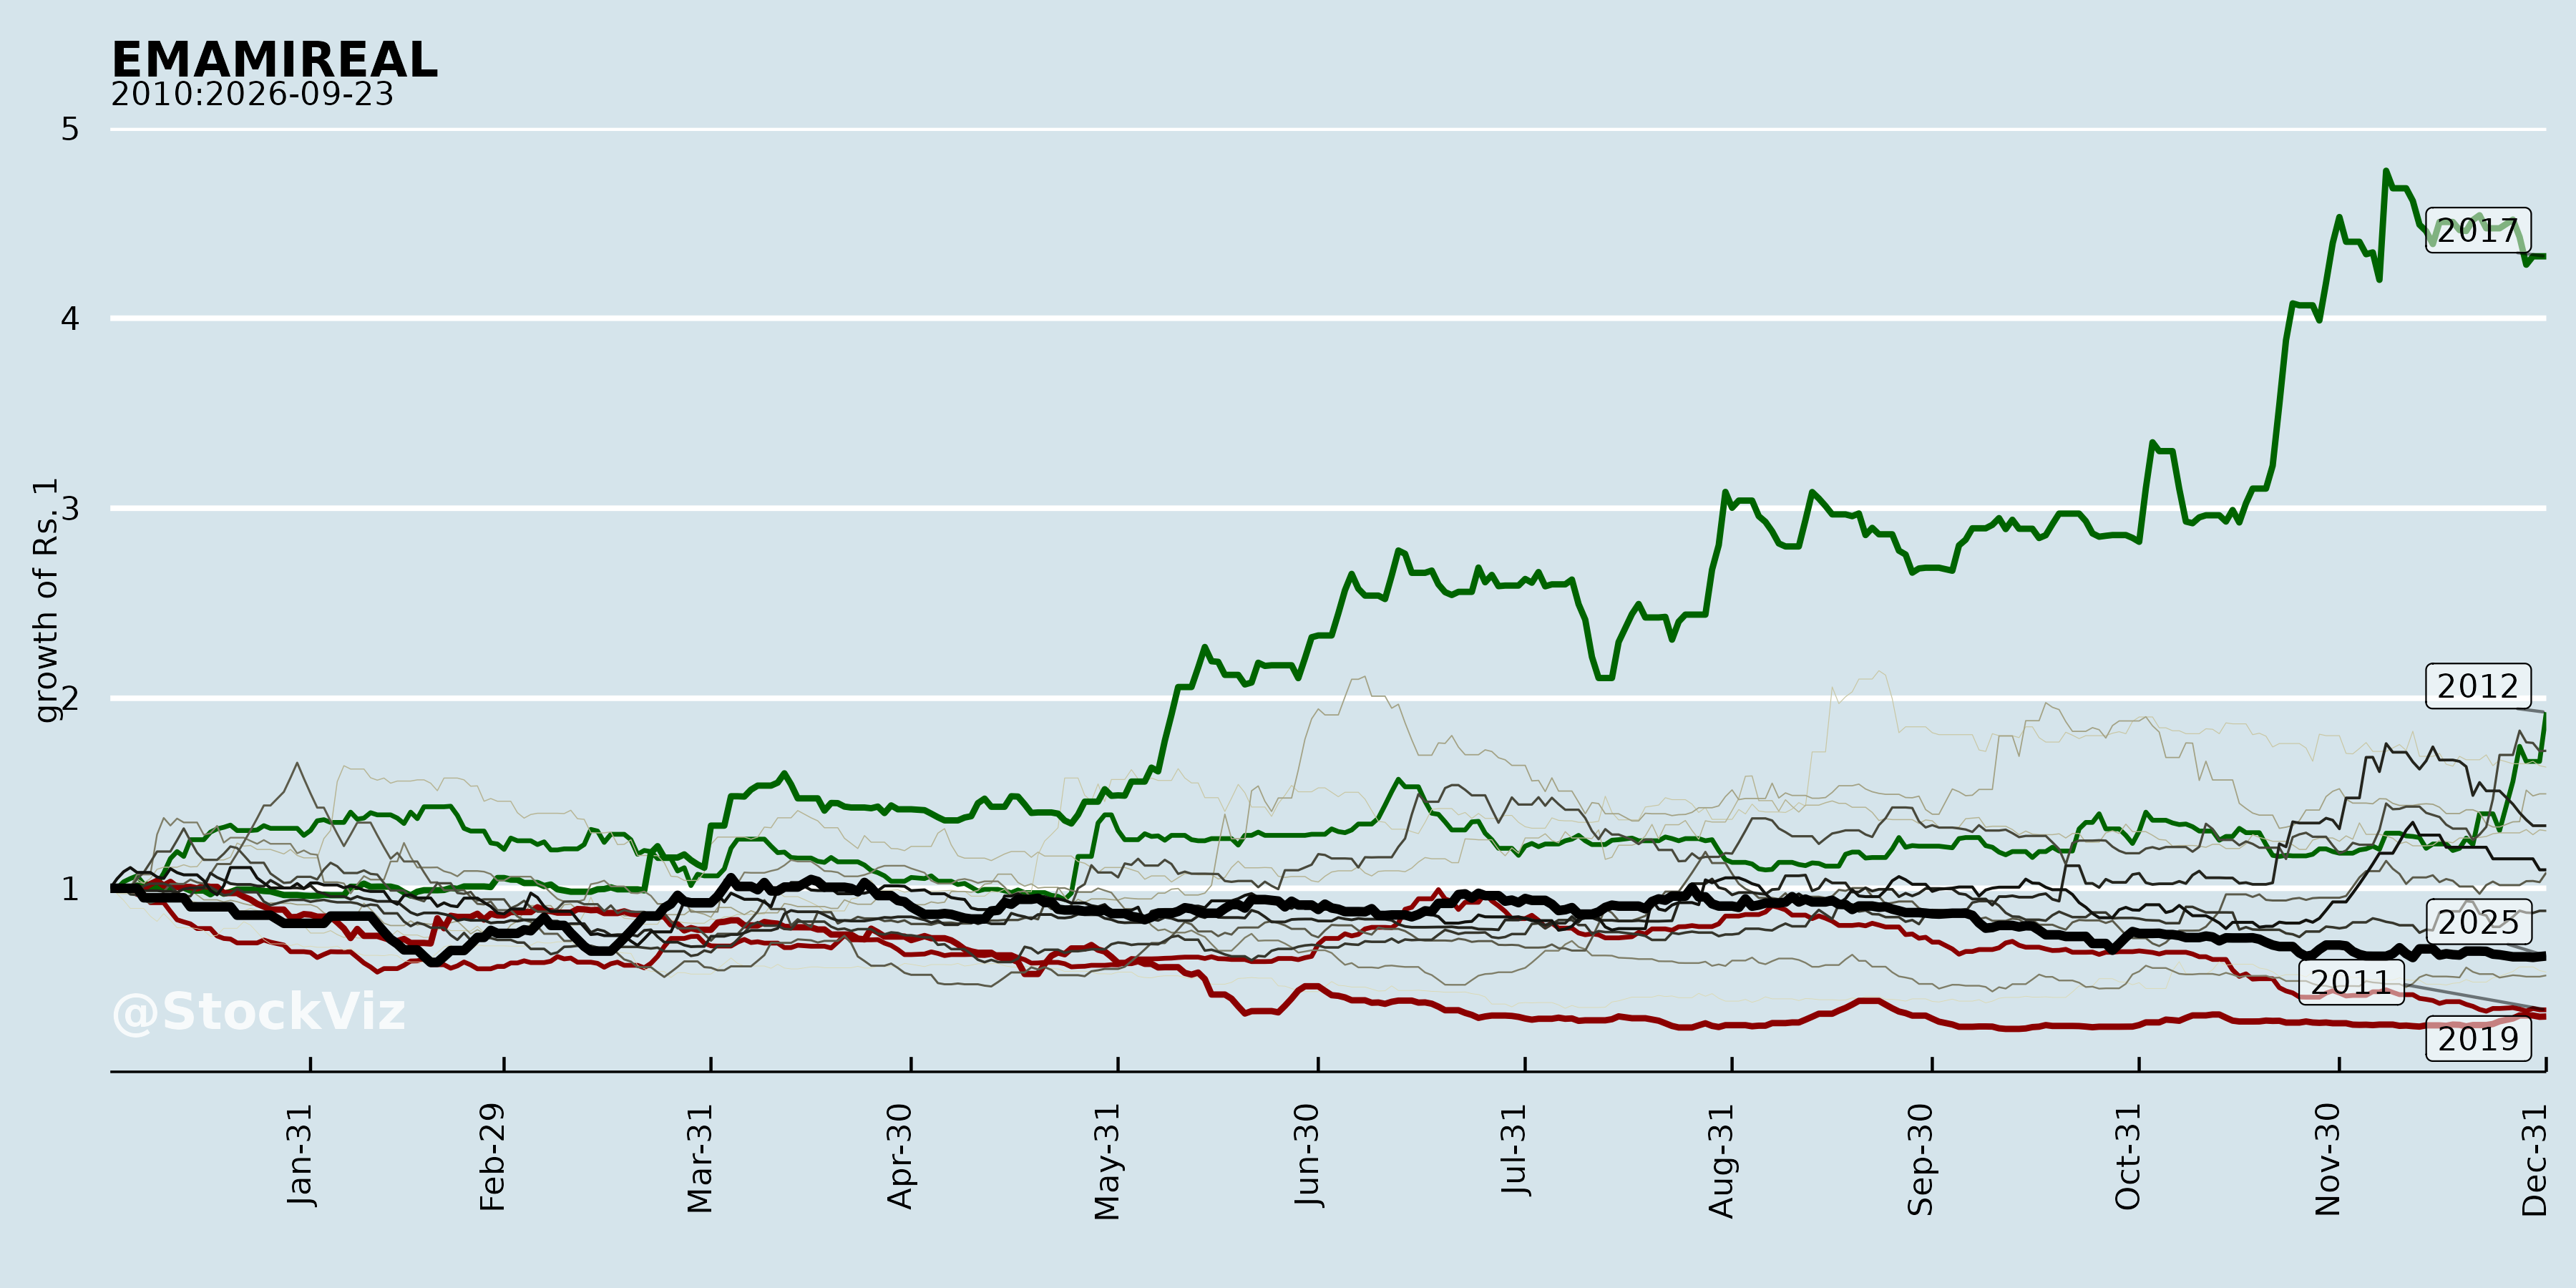
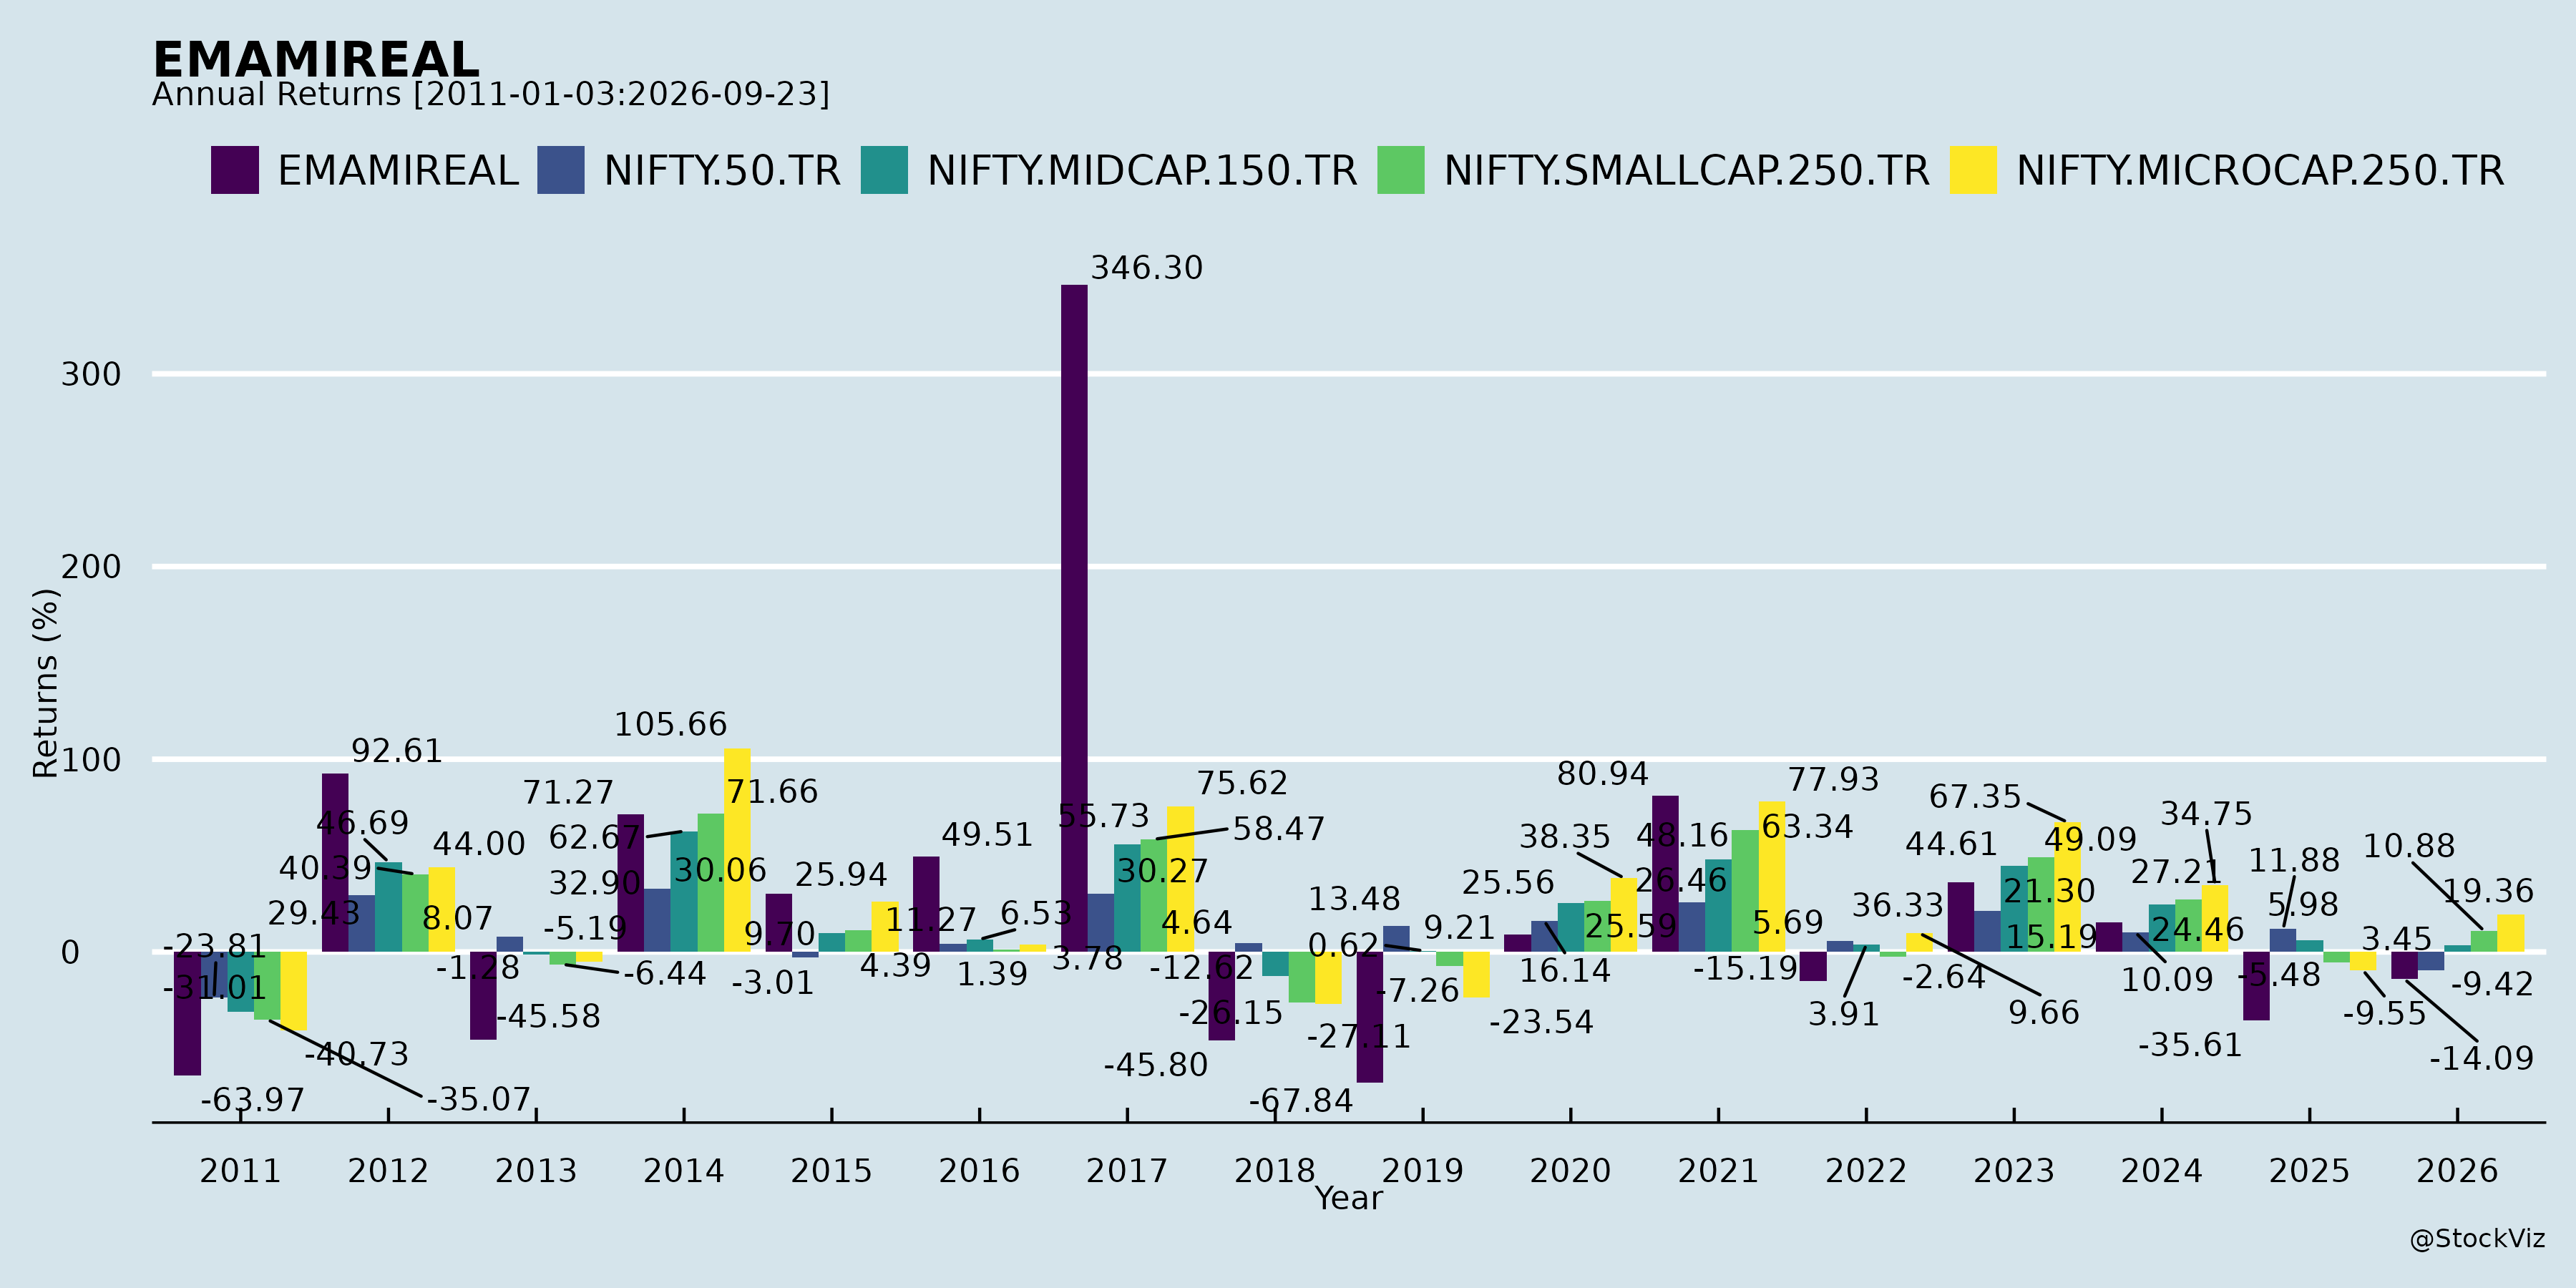
Annual Returns
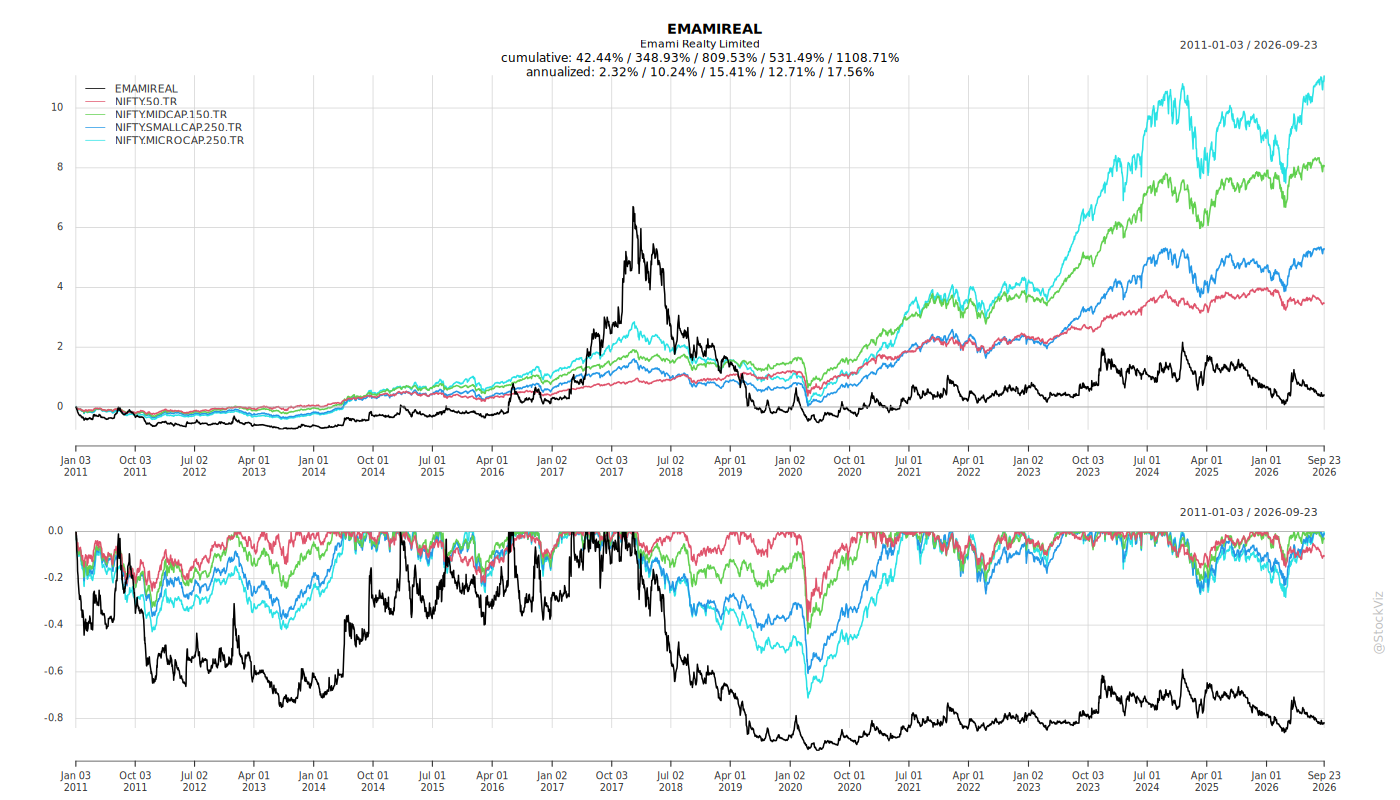
Cumulative Returns and Drawdowns
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-19
Headwinds and Challenges
- Project execution depends heavily on manual labour, leaving timelines exposed to workforce availability and wage cost increases.
- Inconsistent approval processes and regulatory frameworks across states are causing project delays and cost overruns.
- Sustained price appreciation has strained affordability for first-time and middle-income buyers, moderating sales volumes.
- Slower adoption of PropTech, digital sales tools, and green practices creates competitive risk, given the upfront capital and upskilling costs involved.
- Emami Realty received an Adjudication Order from SEBI (Order/JS/RJ/2026-27/32718, dated September 11, 2026) levying a penalty of Rs. 2,00,000 for alleged violations, including incorrect classification of investments as inventories and failure to obtain prior audit committee approval for a related party transaction.
Tailwinds and Growth Prospects
- India’s real estate demand remains strong, supported by rising urbanization, growing disposable incomes, and a supportive interest rate environment.
- West Bengal is positioned as an underappreciated opportunity, with an estimated Rs. 1 lakh crore in committed investment, an expanding infrastructure corridor, and a surge in IT and Global Capability Centre (GCC) demand.
- The company aims to capitalize on these drivers through its premium portfolio, strong brand equity, and focus on sustainable, future-ready developments.
- The company has a diverse portfolio across residential, commercial, and mixed-use developments.
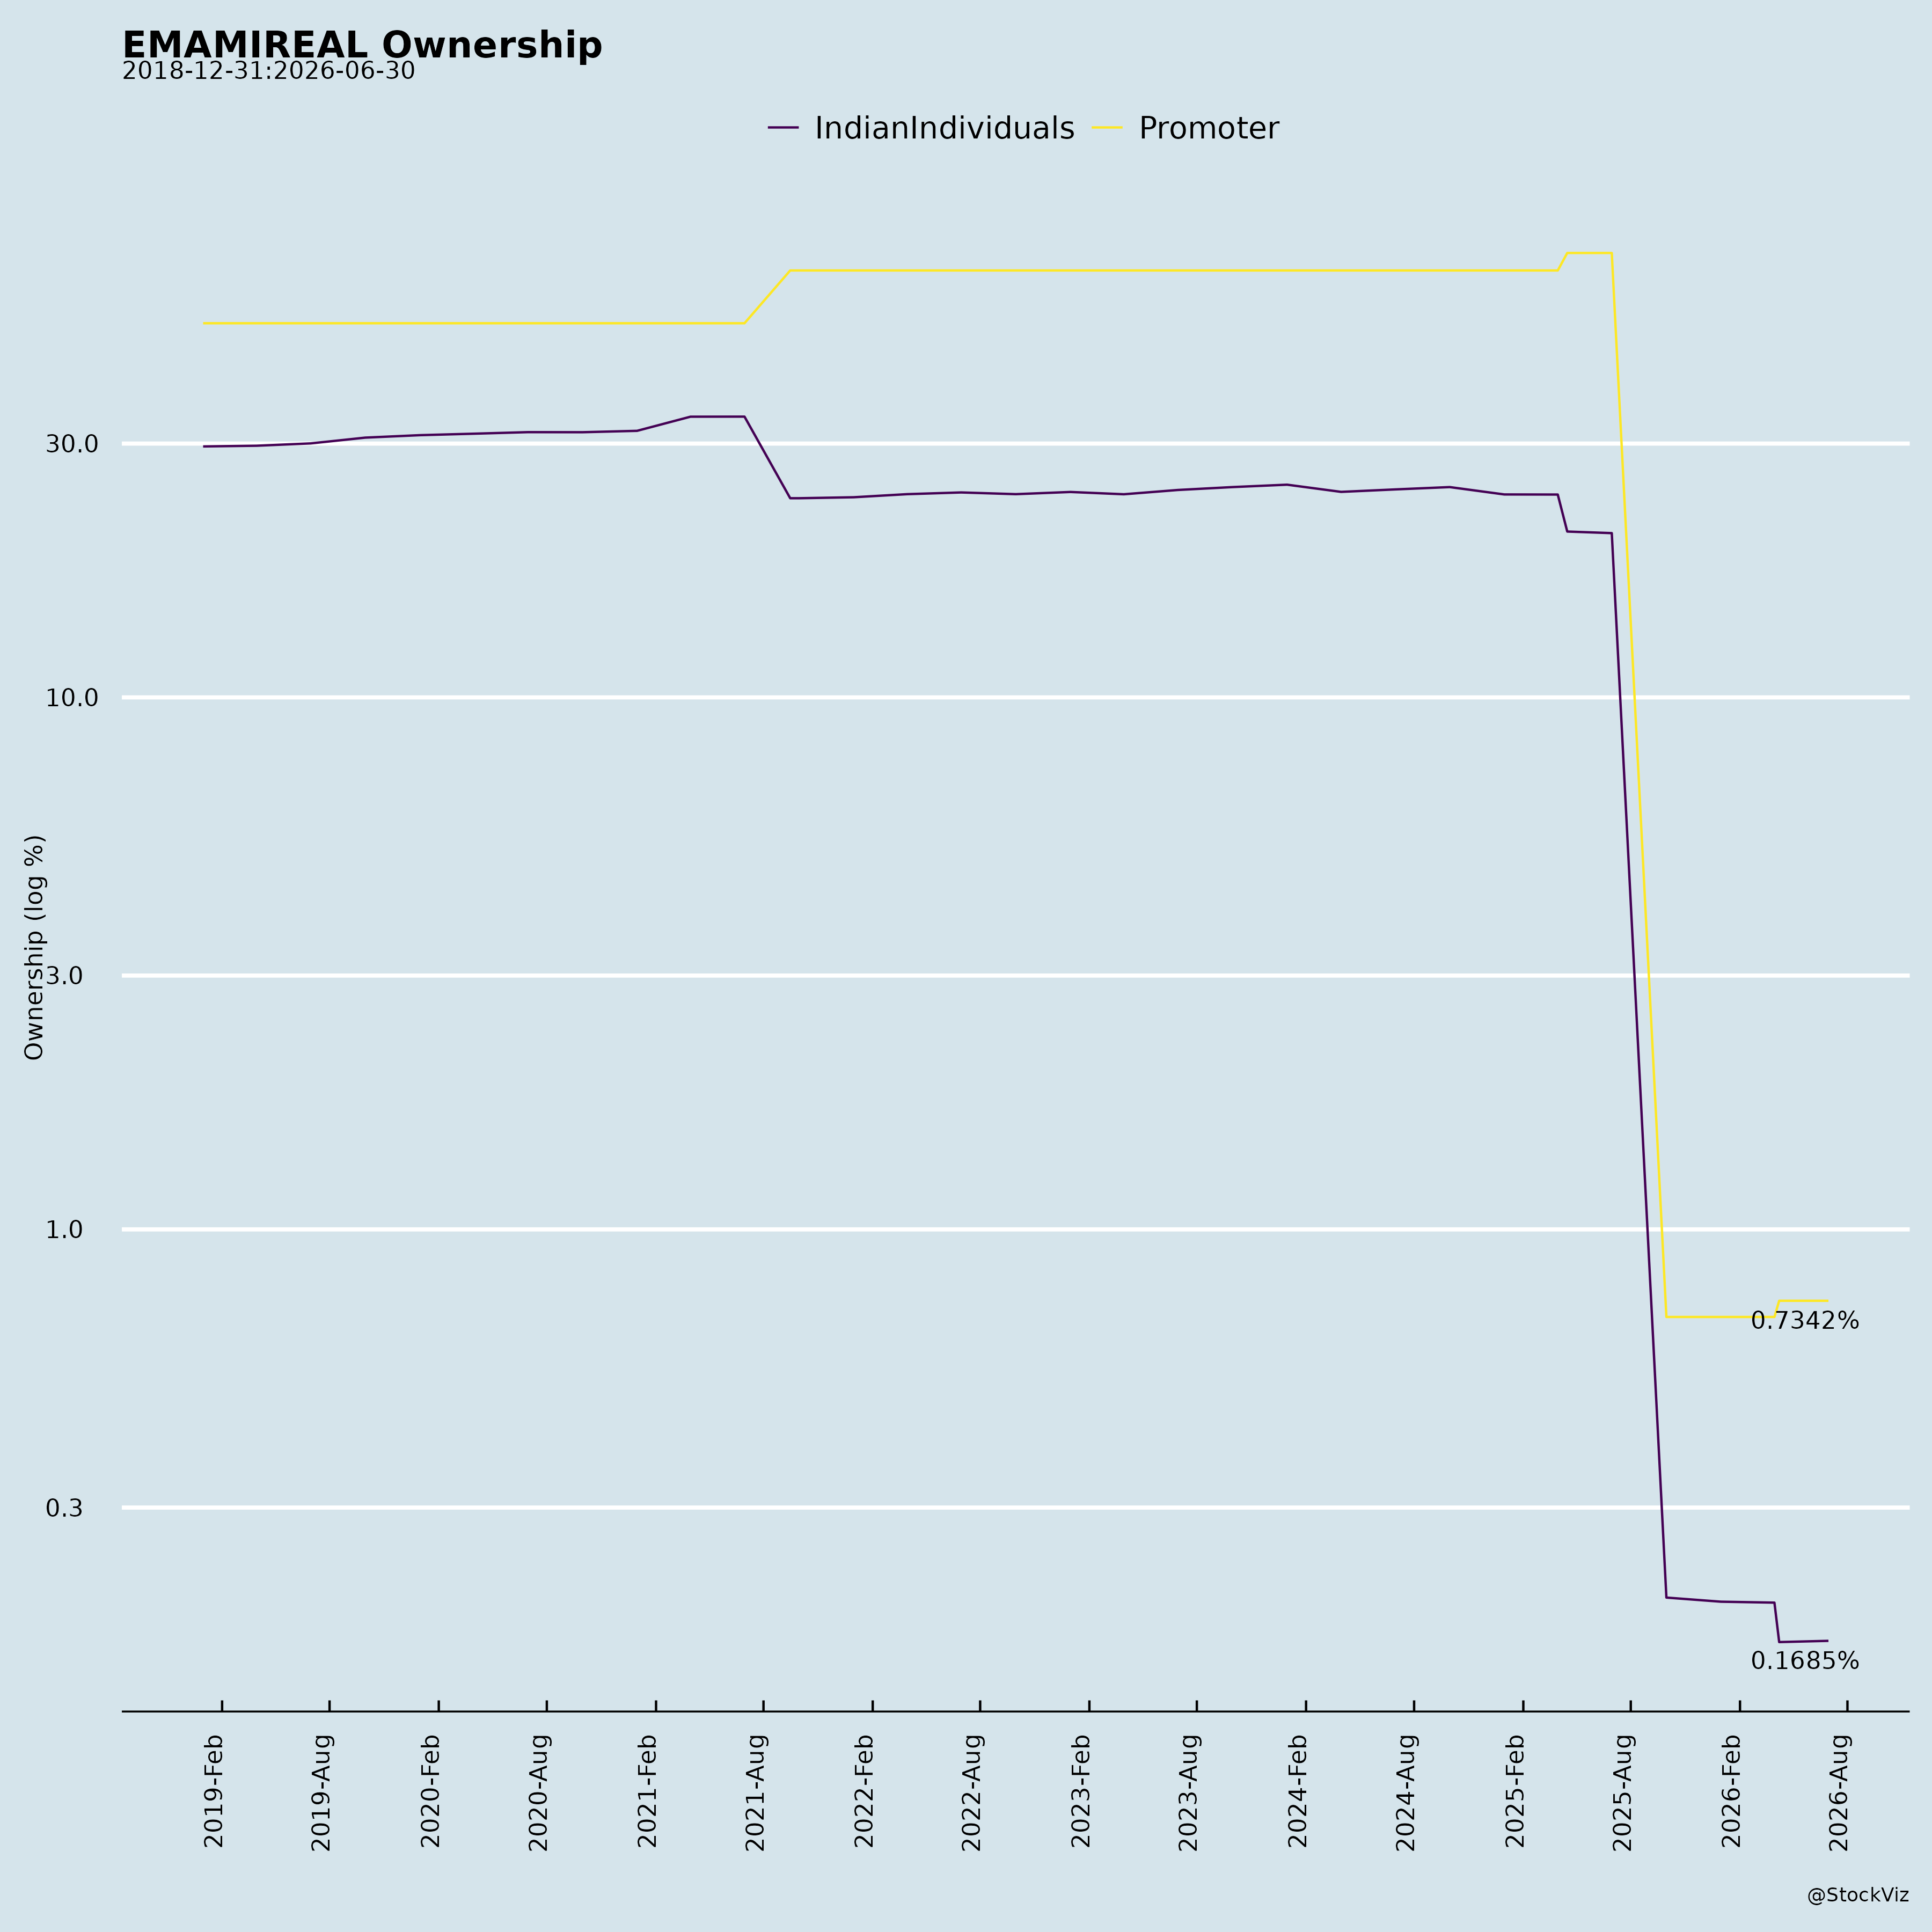
- Recent share capital increases have occurred through preferential allotment of equity shares and convertible warrants to promoter group entities, including 82,00,000 convertible warrants allotted on 16th April, 2025 by way of conversion of unsecured loans. Following this allotment, the issued, subscribed and paid-up equity share capital stands at Rs. 1,040.68 Lakhs divided into 5,20,33,889 equity shares of Rs. 2 each.
Key Risks
- The SEBI penalty relates to financial statement classifications in FY22 and FY23 and a lack of prior audit committee approval for a related party transaction with Lohitka Properties LLP in 2016. Management stated there is no other material impact on the company’s financials or operations besides the penalty payment.
- Execution risk from labour dependence, state-level regulatory inconsistency, affordability-driven demand moderation, and lagging technology adoption could affect project timelines and costs.
Management Guidance vs. Observed Performance
- Management expects the residential real estate market to remain stable, supported by steady urbanization, rising household incomes, and continued government emphasis on infrastructure and housing-linked policies.
- The company aims to leverage its project pipeline and market presence to achieve sustainable growth by focusing on timely execution of ongoing projects and disciplined capital allocation.
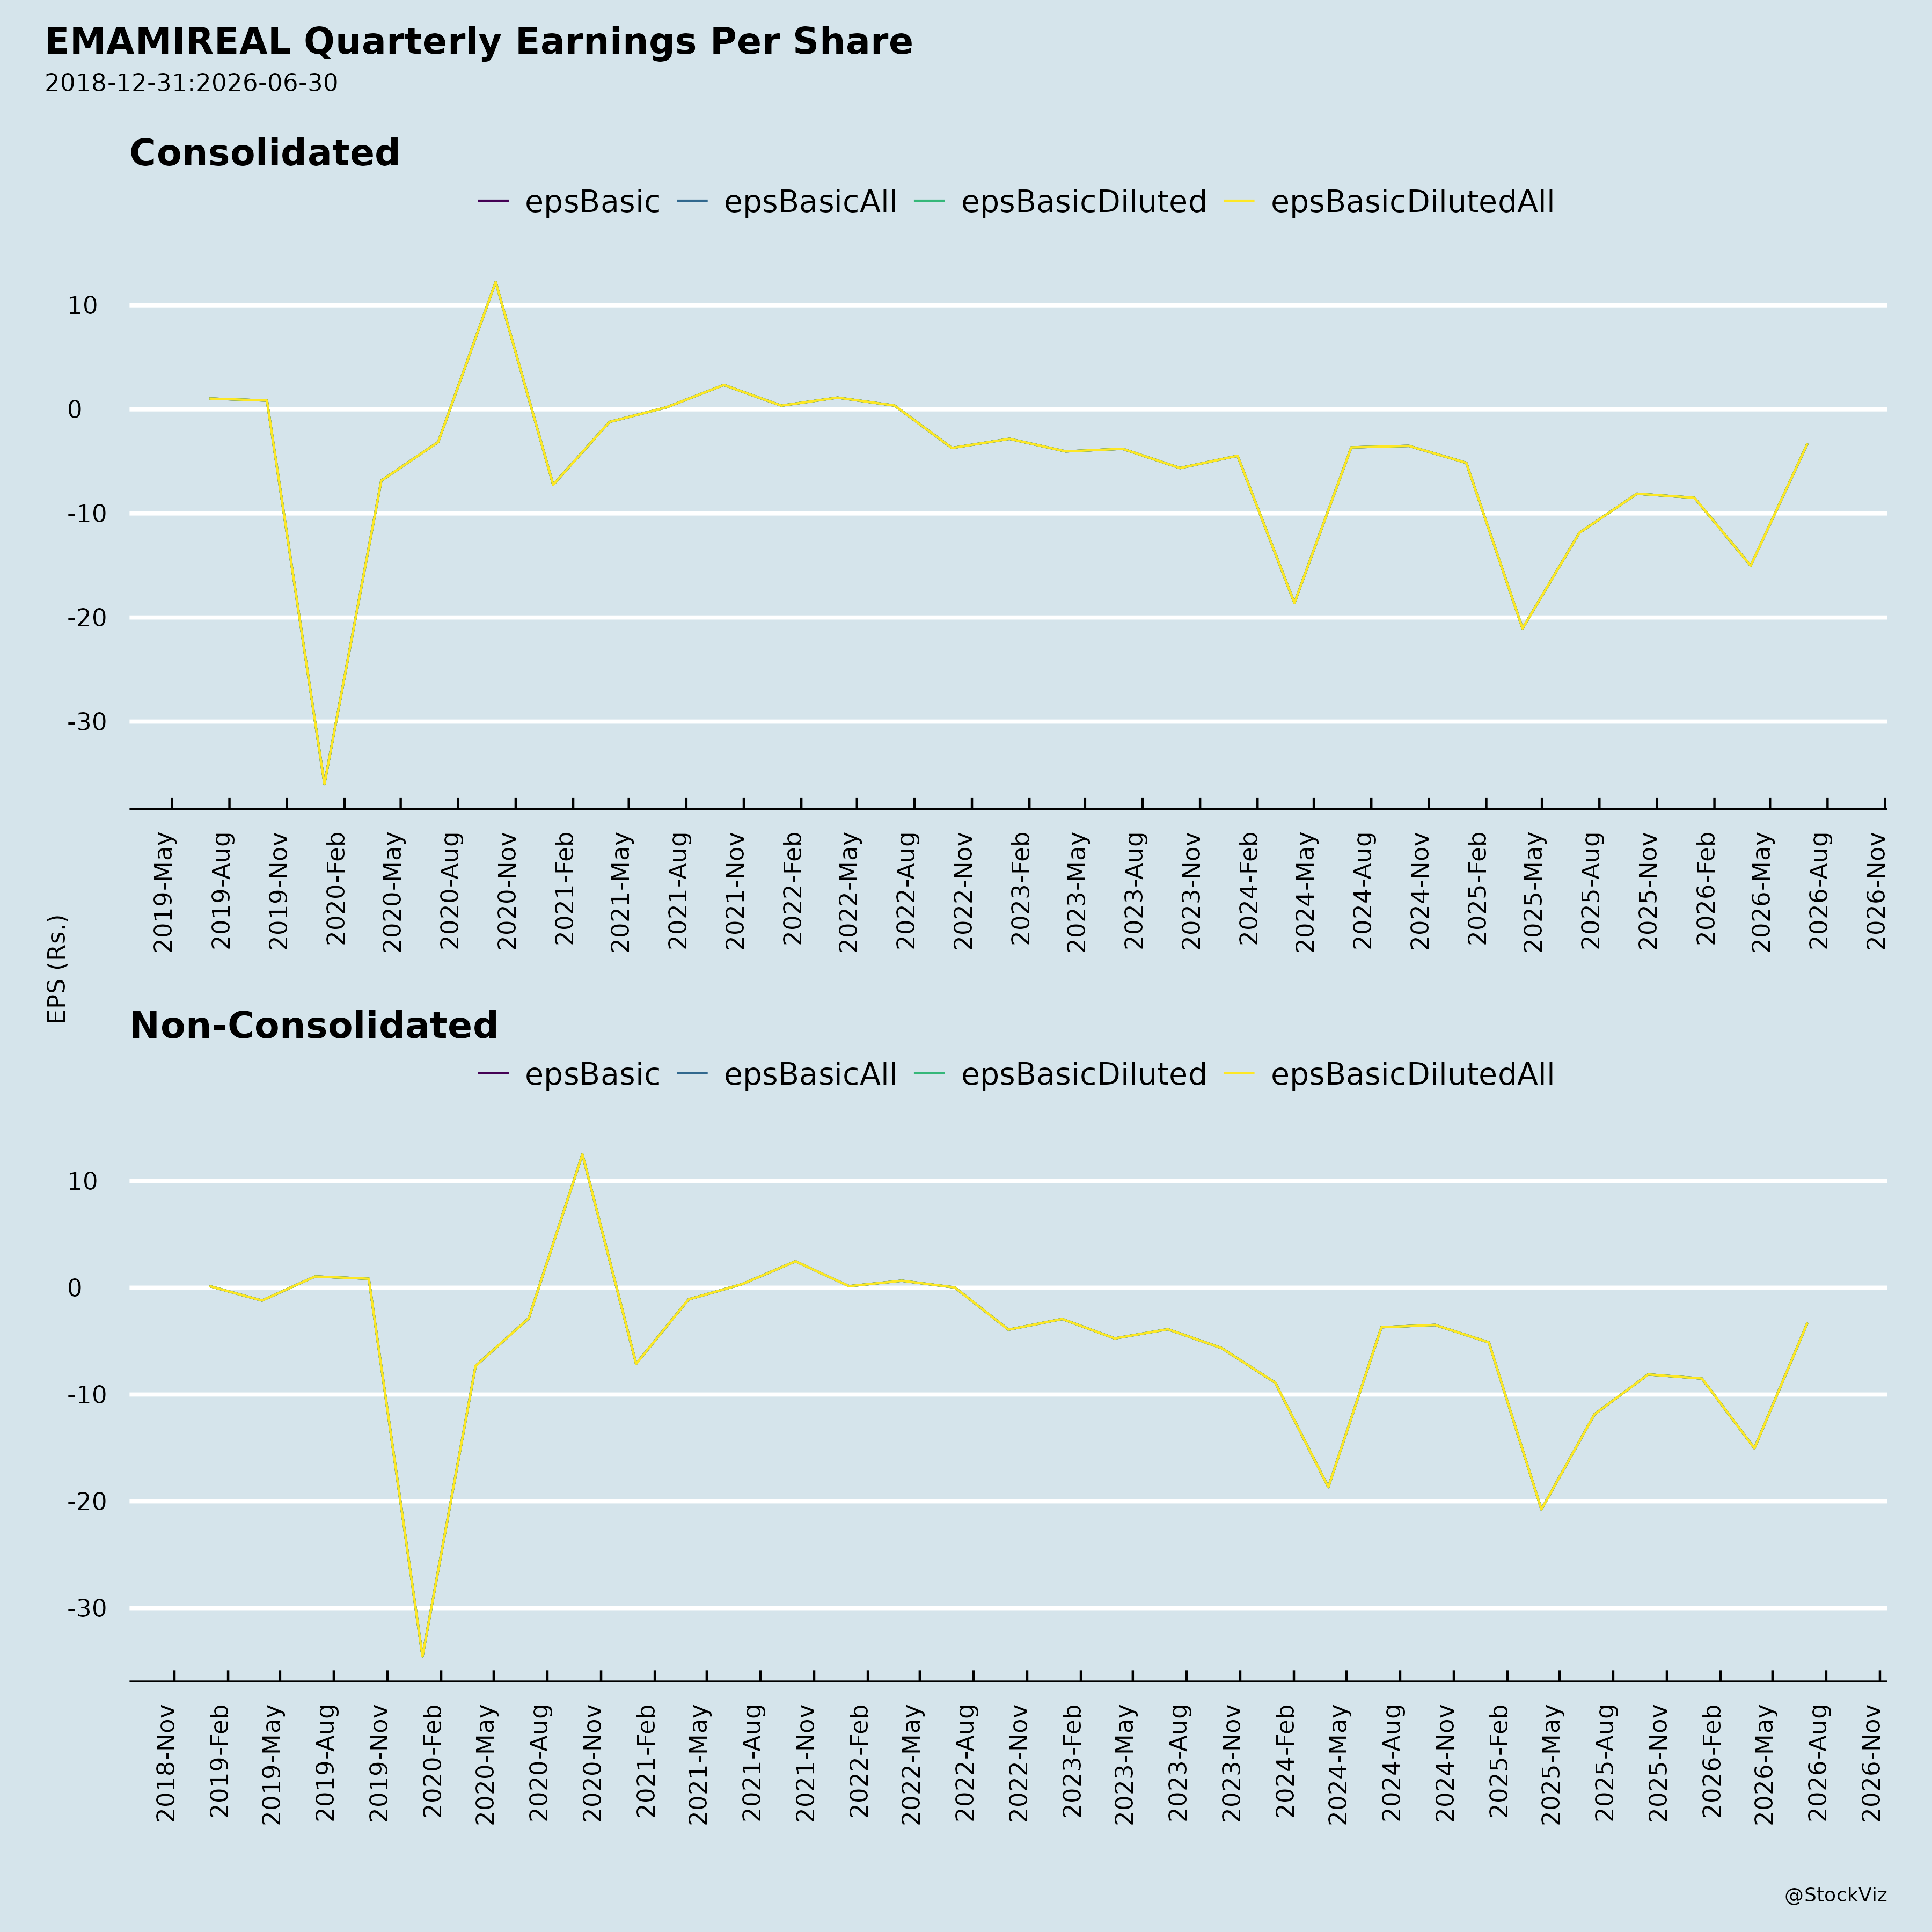
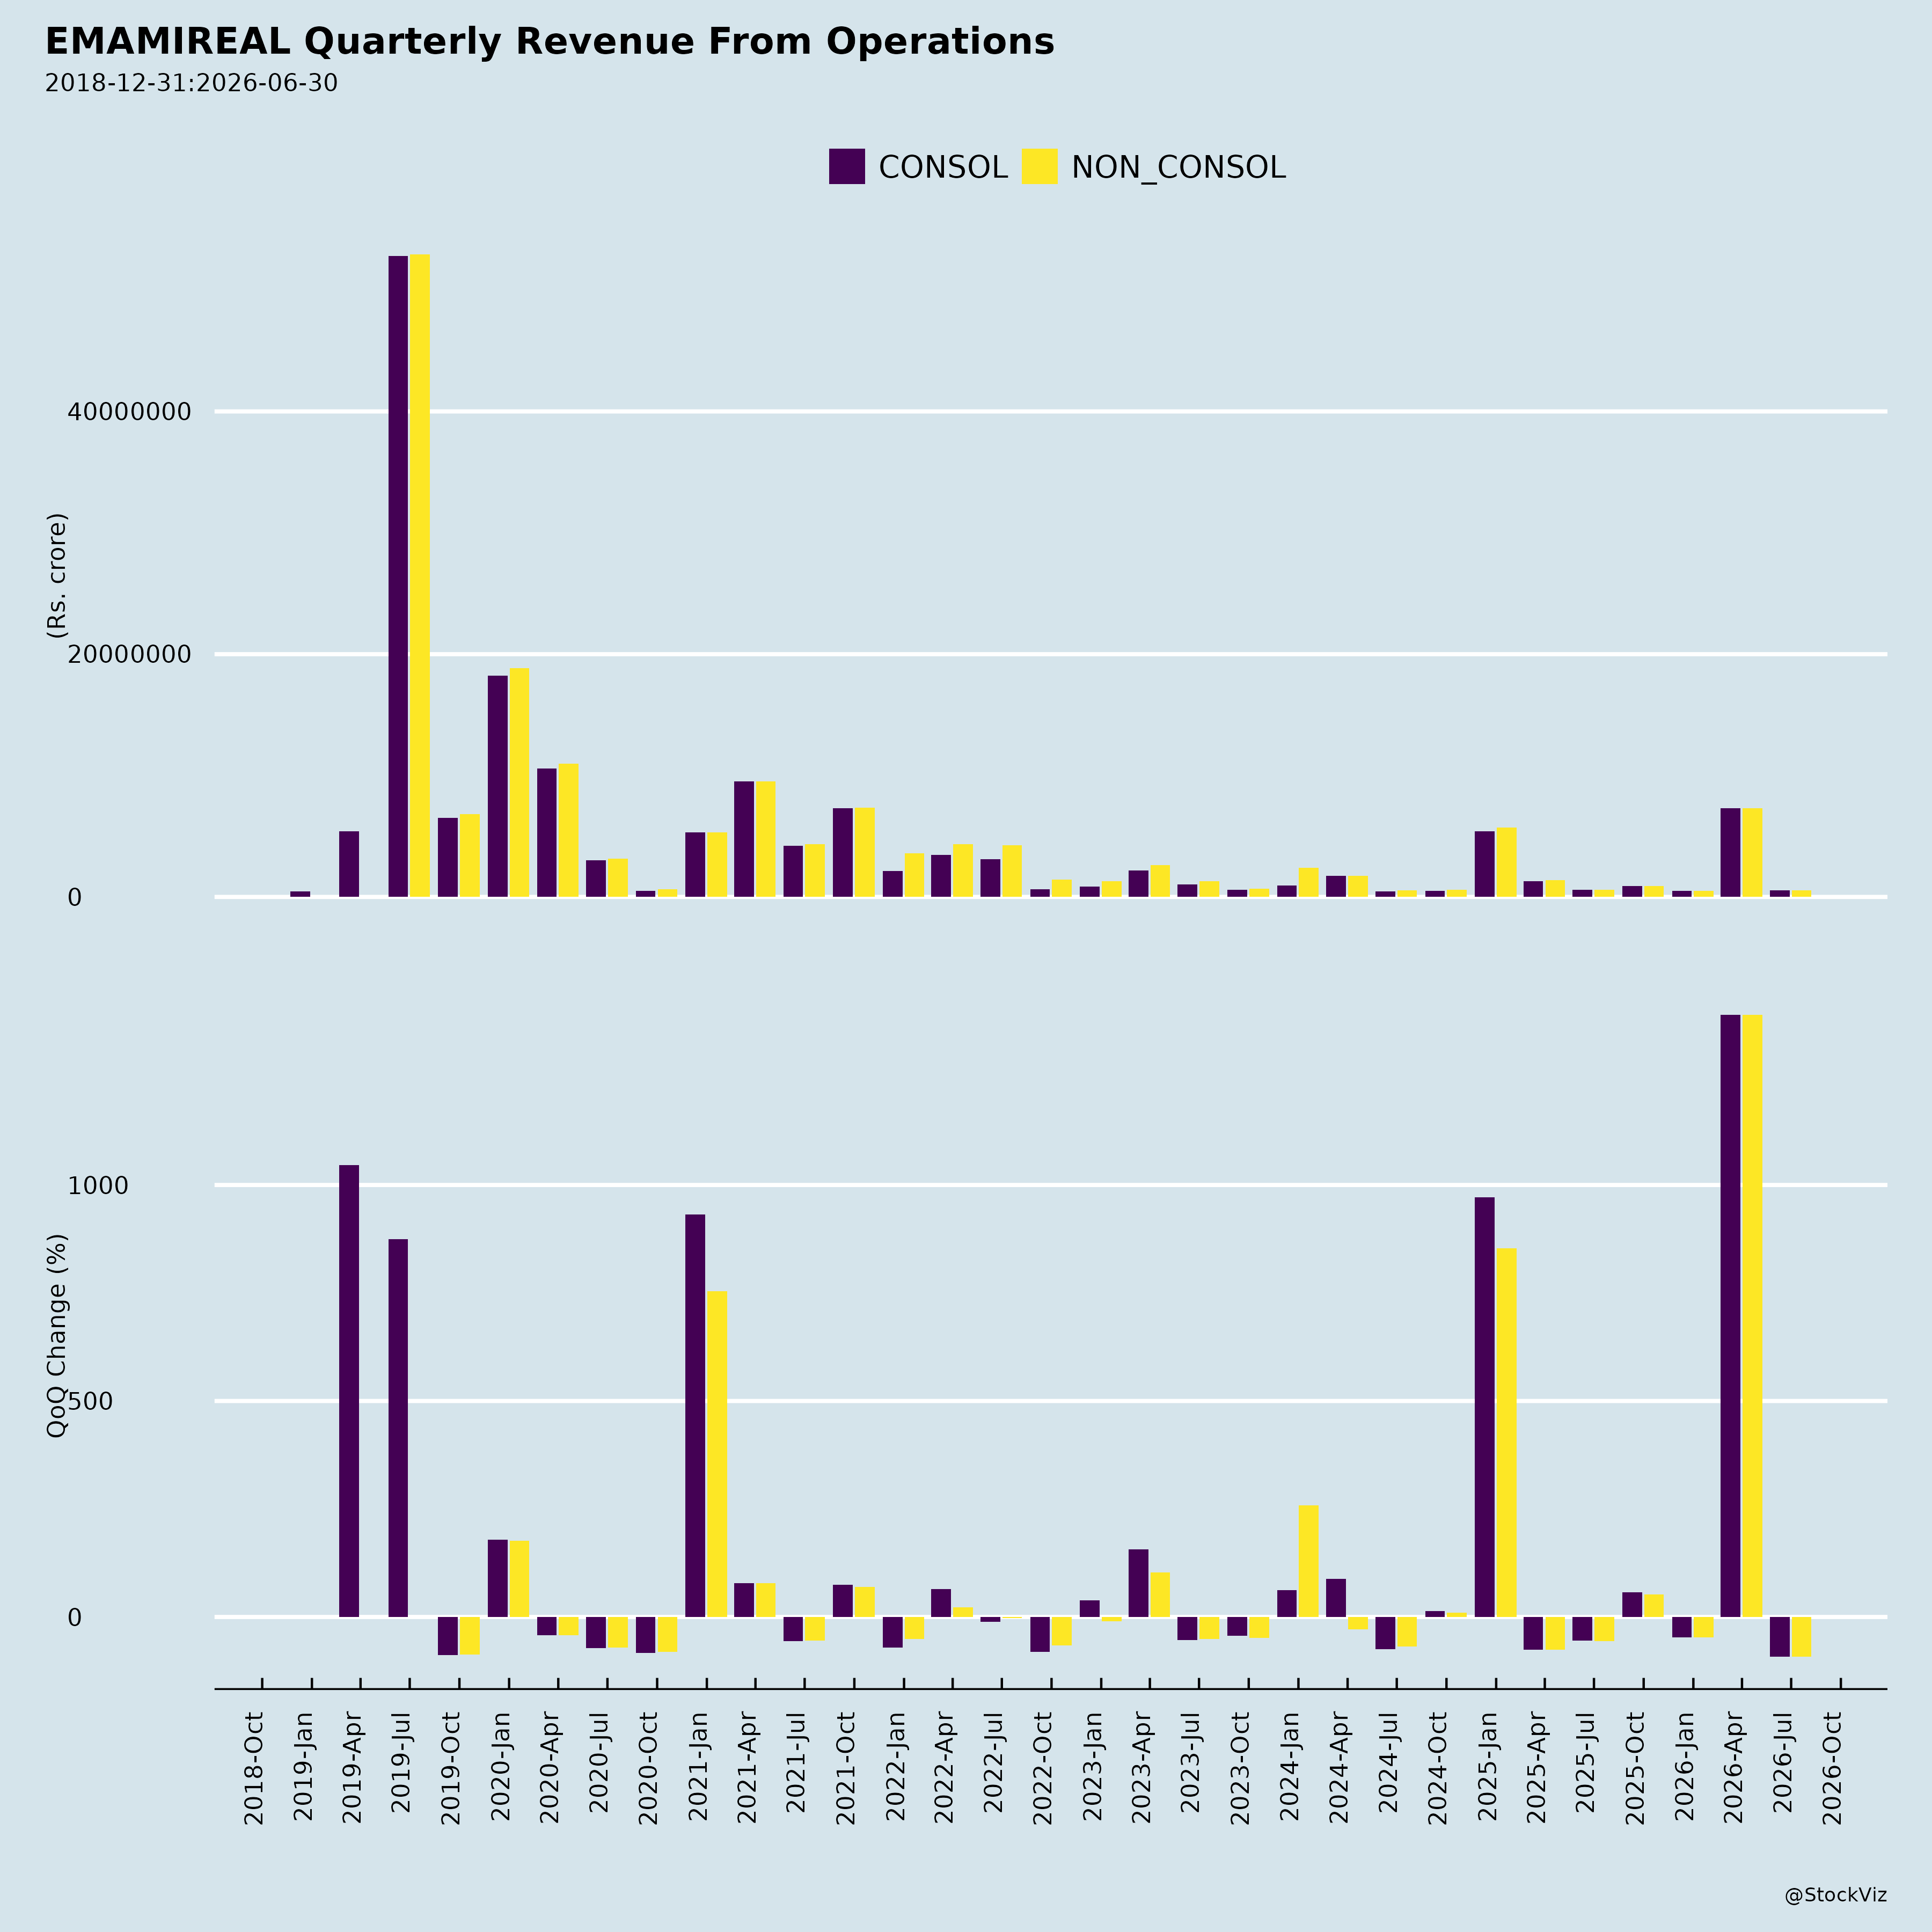
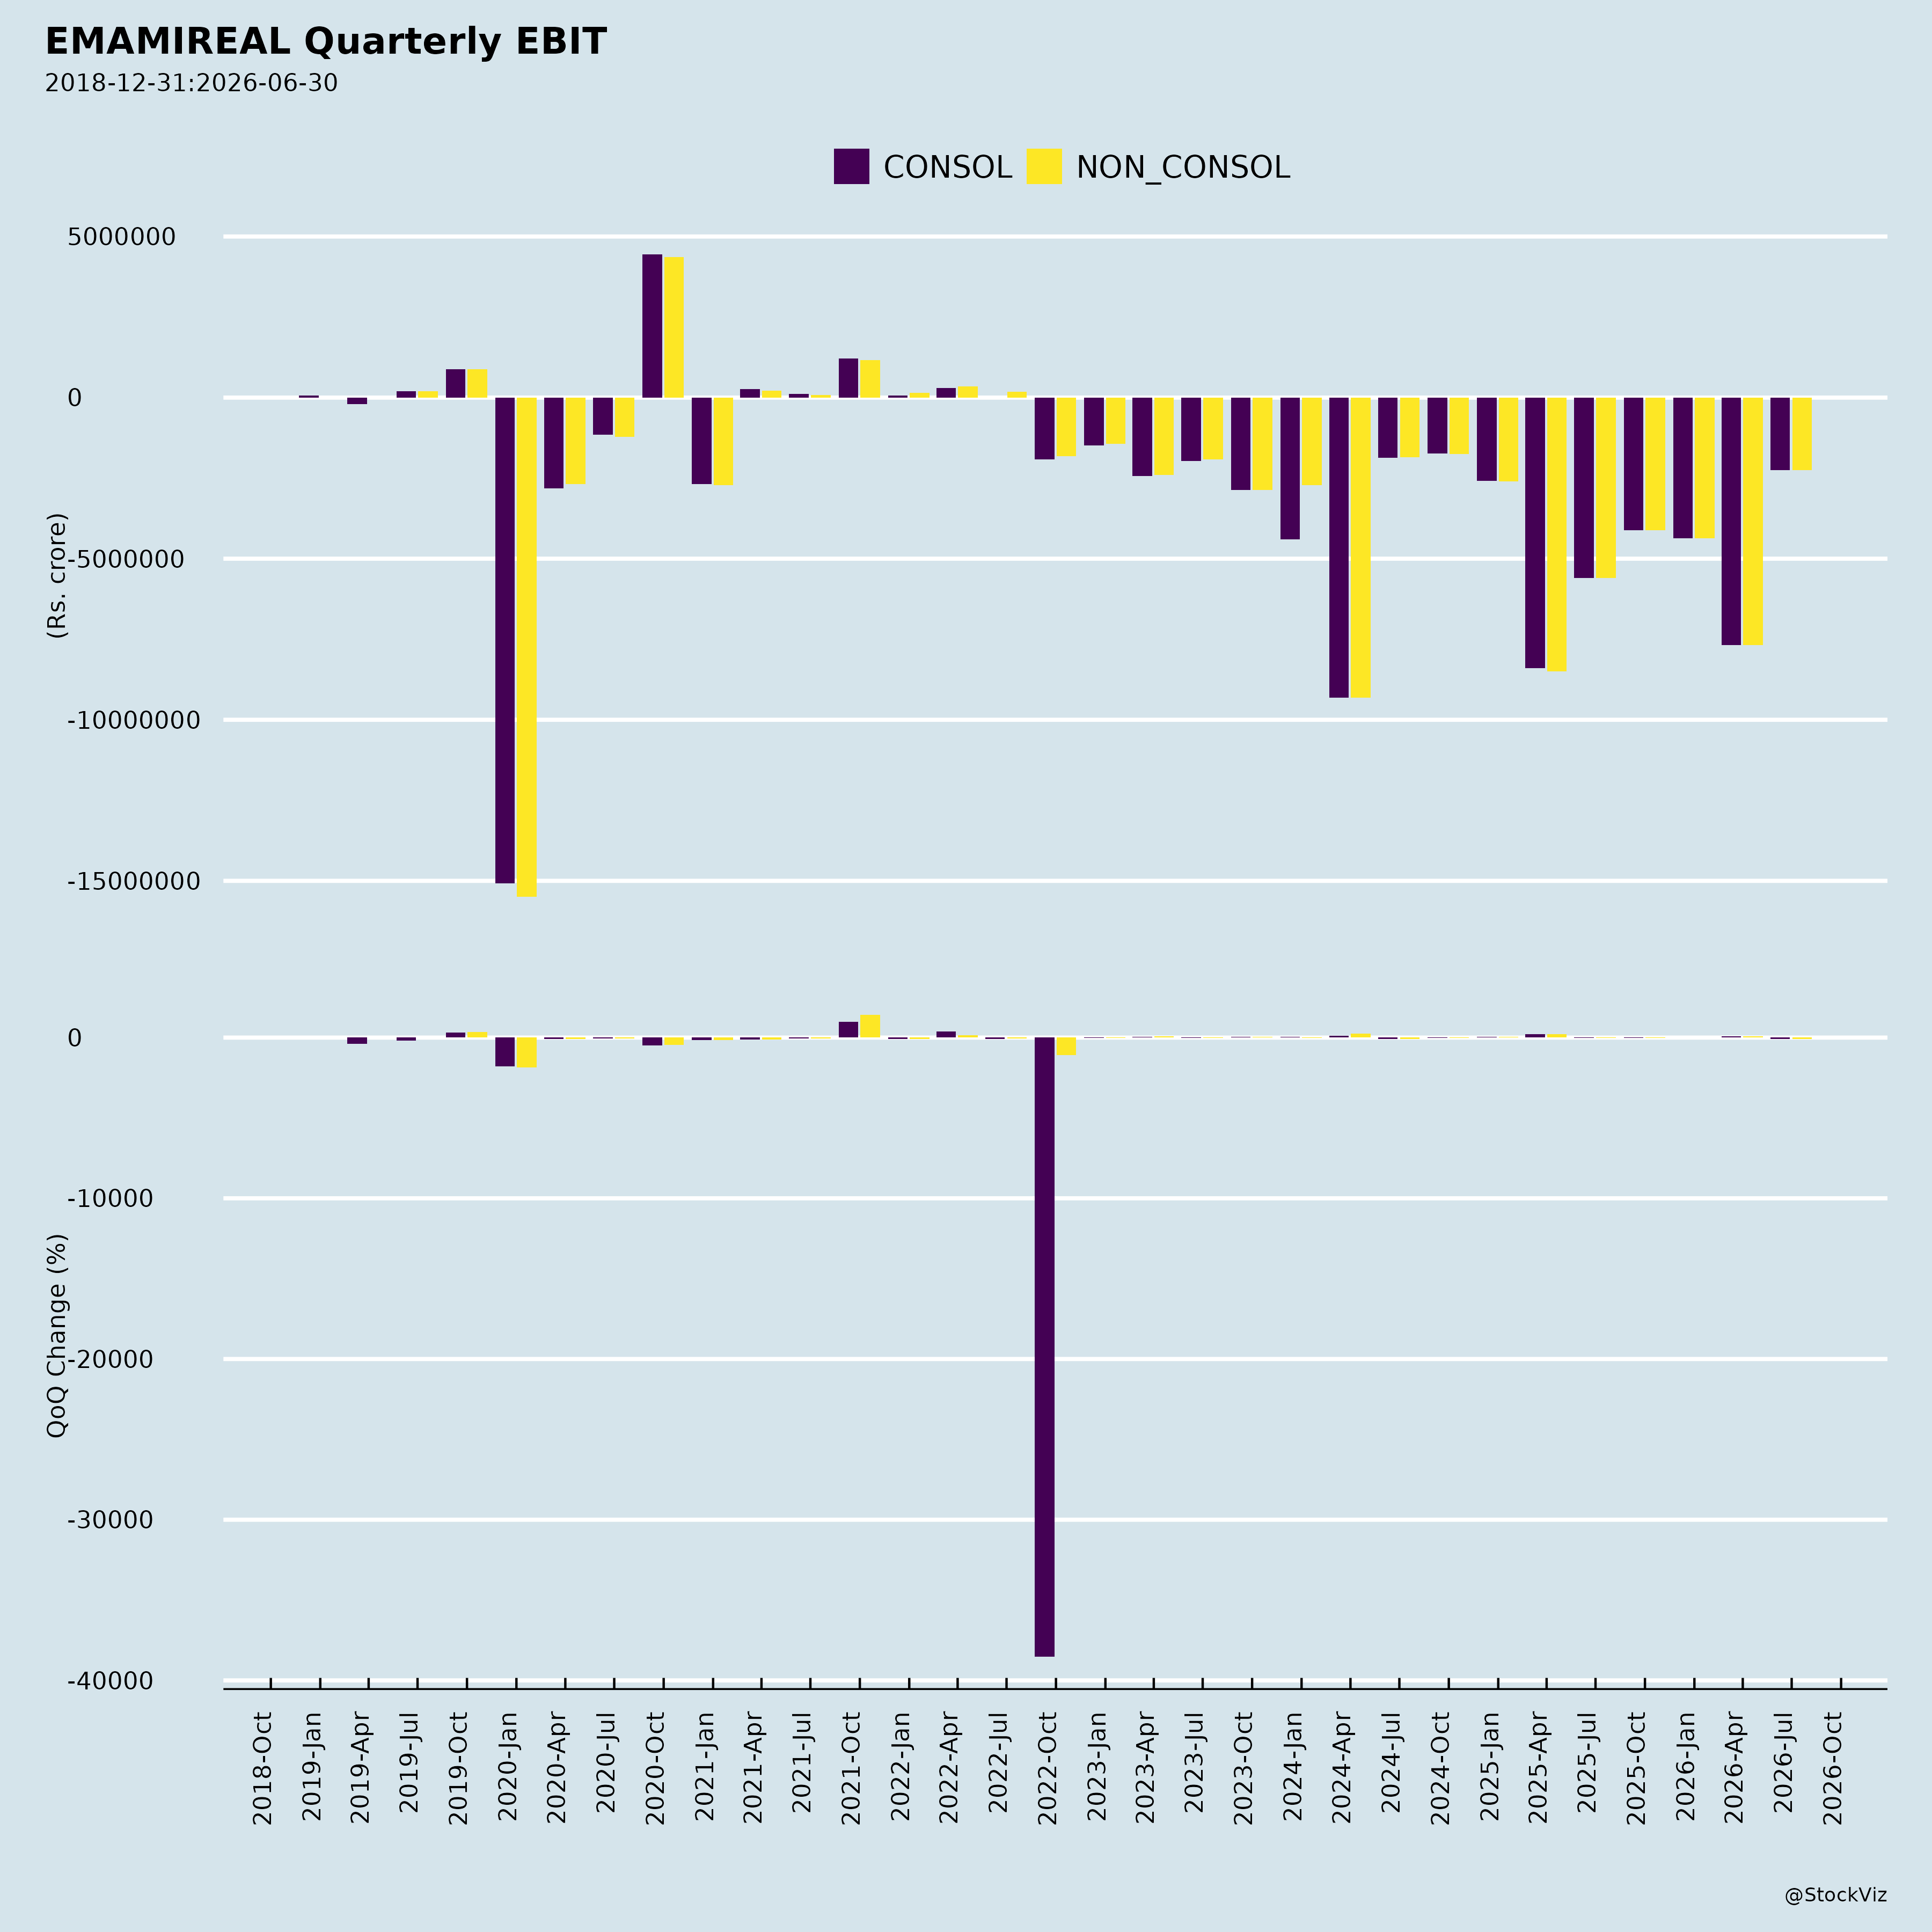
- Against this guidance, observed performance for the financial year 2025-26 shows a total revenue of Rs. 12,066.72 Lakhs and a loss after tax of Rs. 18,953.52 Lakhs on a standalone basis.
- For the first quarter ended 30 June, 2026, the Board approved unaudited standalone and consolidated financial results, on which the statutory auditors, M/s Agrawal Tondon and Co, issued Limited Review Reports with an unmodified opinion.
- The Board also approved the dissolution of the Demerger Committee with immediate effect at its meeting on 13 August, 2026, and appointed M/s. V. K. Jain & Co., Cost Accountants, as Cost Auditors for the financial year 2026-27.
- The 18th Annual General Meeting is scheduled for Tuesday, 29th September, 2026, at 11:30 a.m. through video conferencing or other audio-visual means.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.