DRREDDY
Equity Metrics
November 18, 2026
Dr. Reddy’s Laboratories Limited
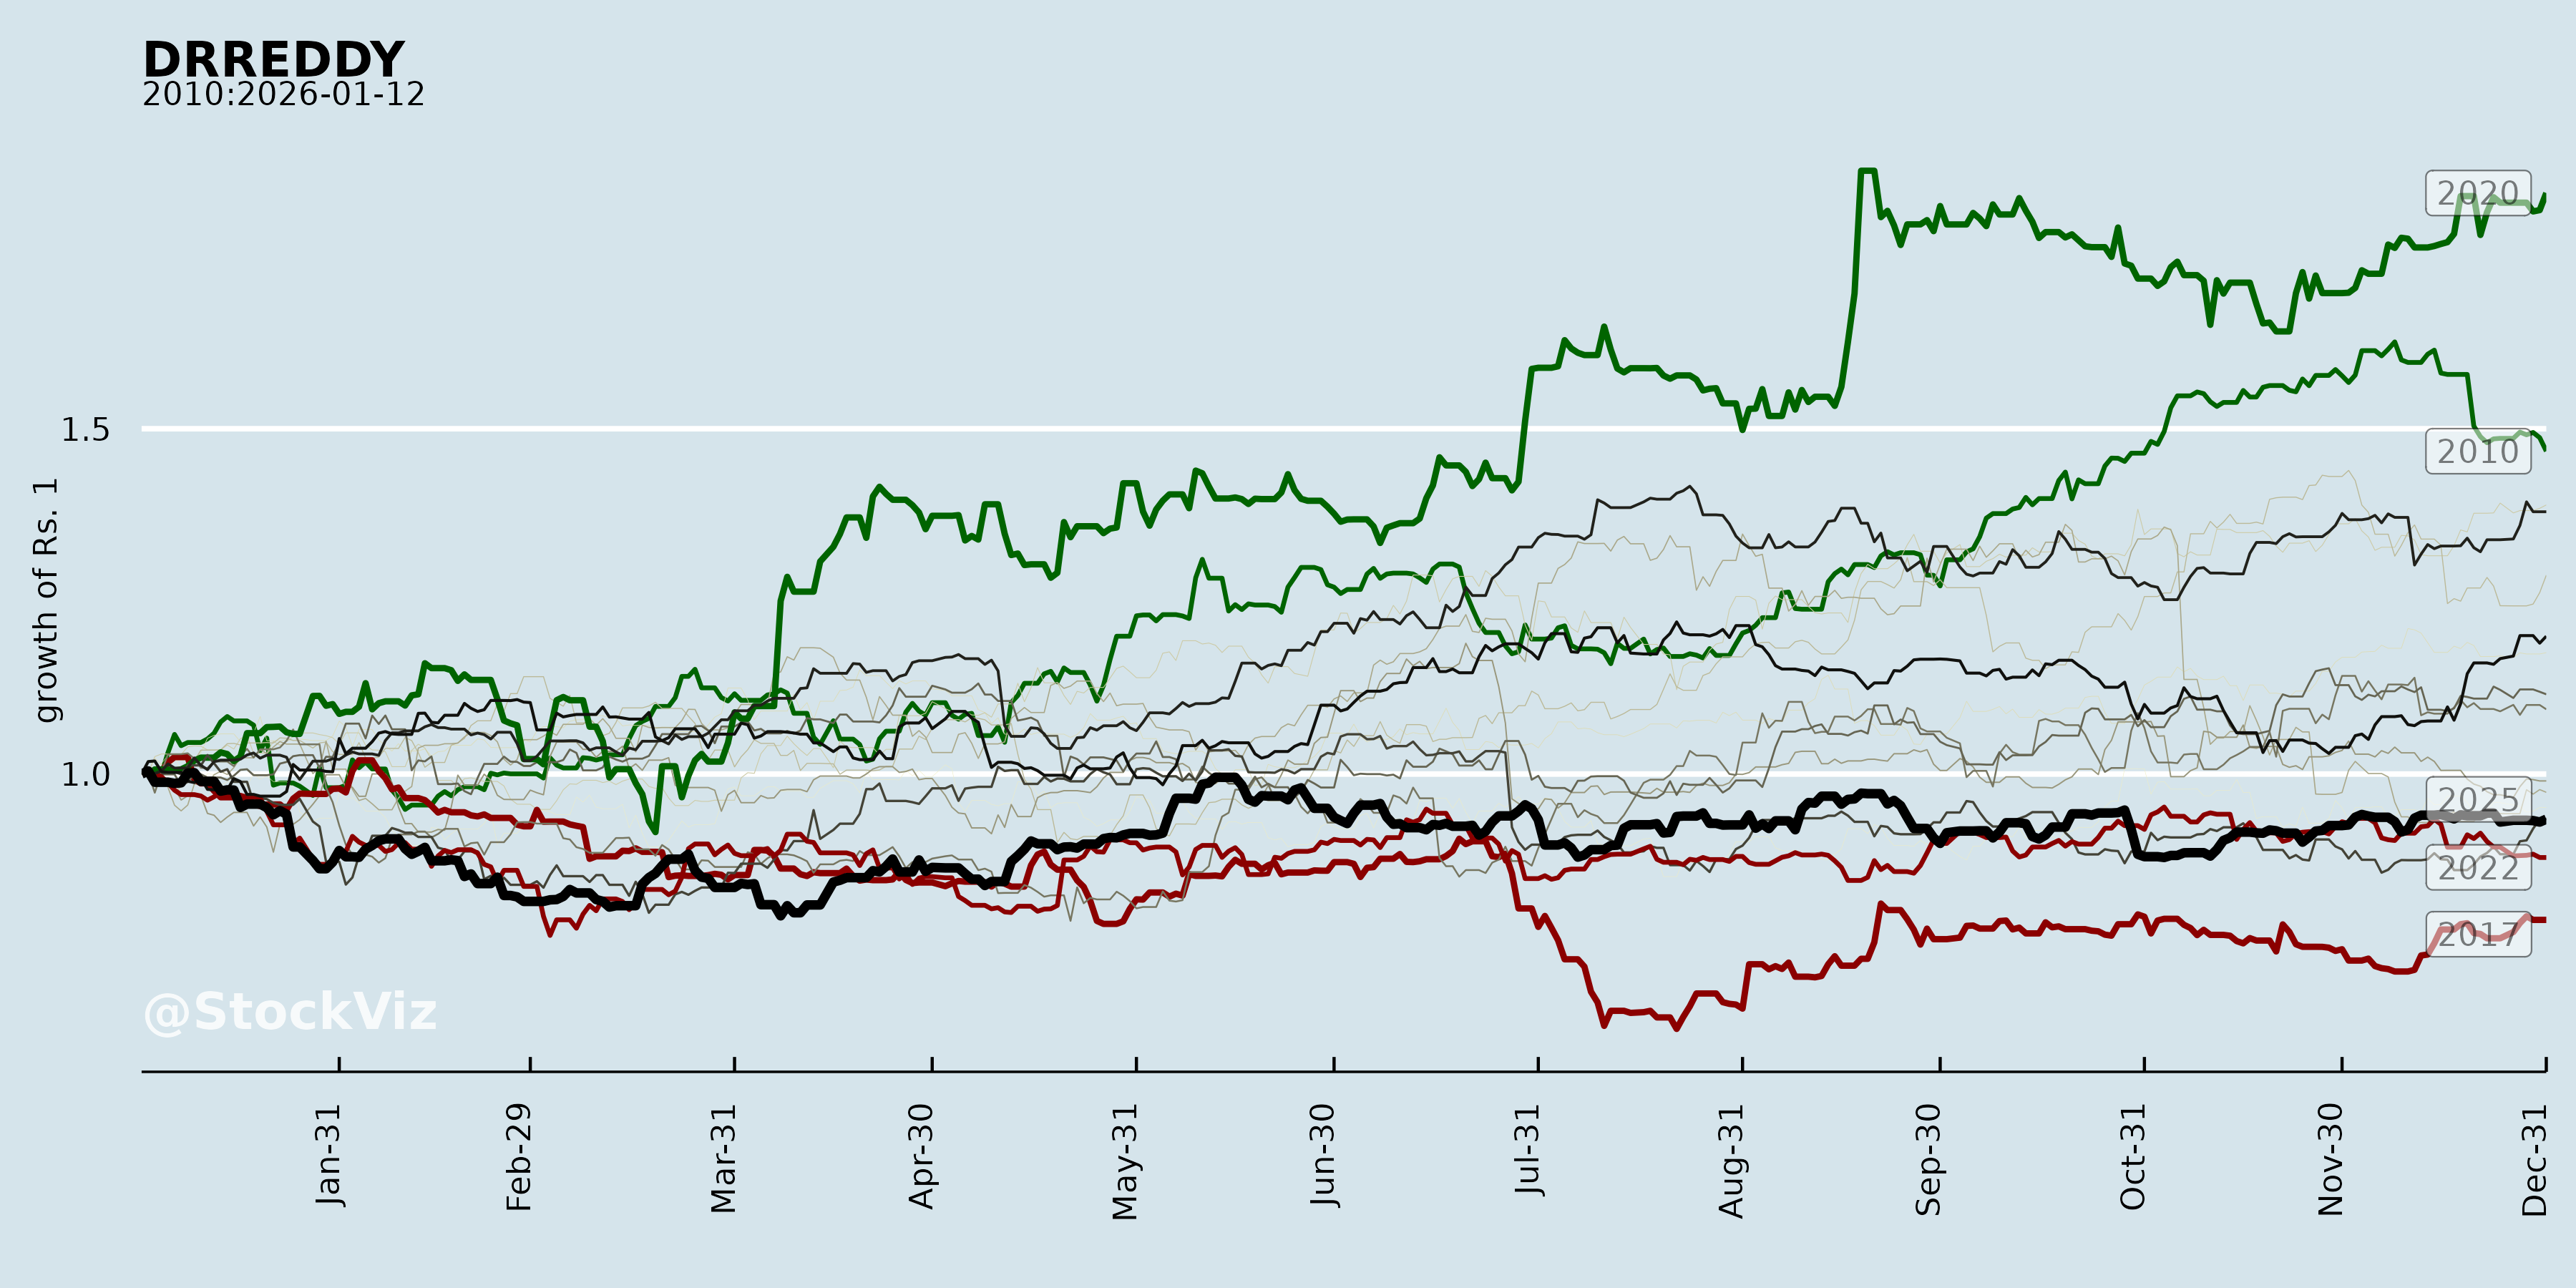
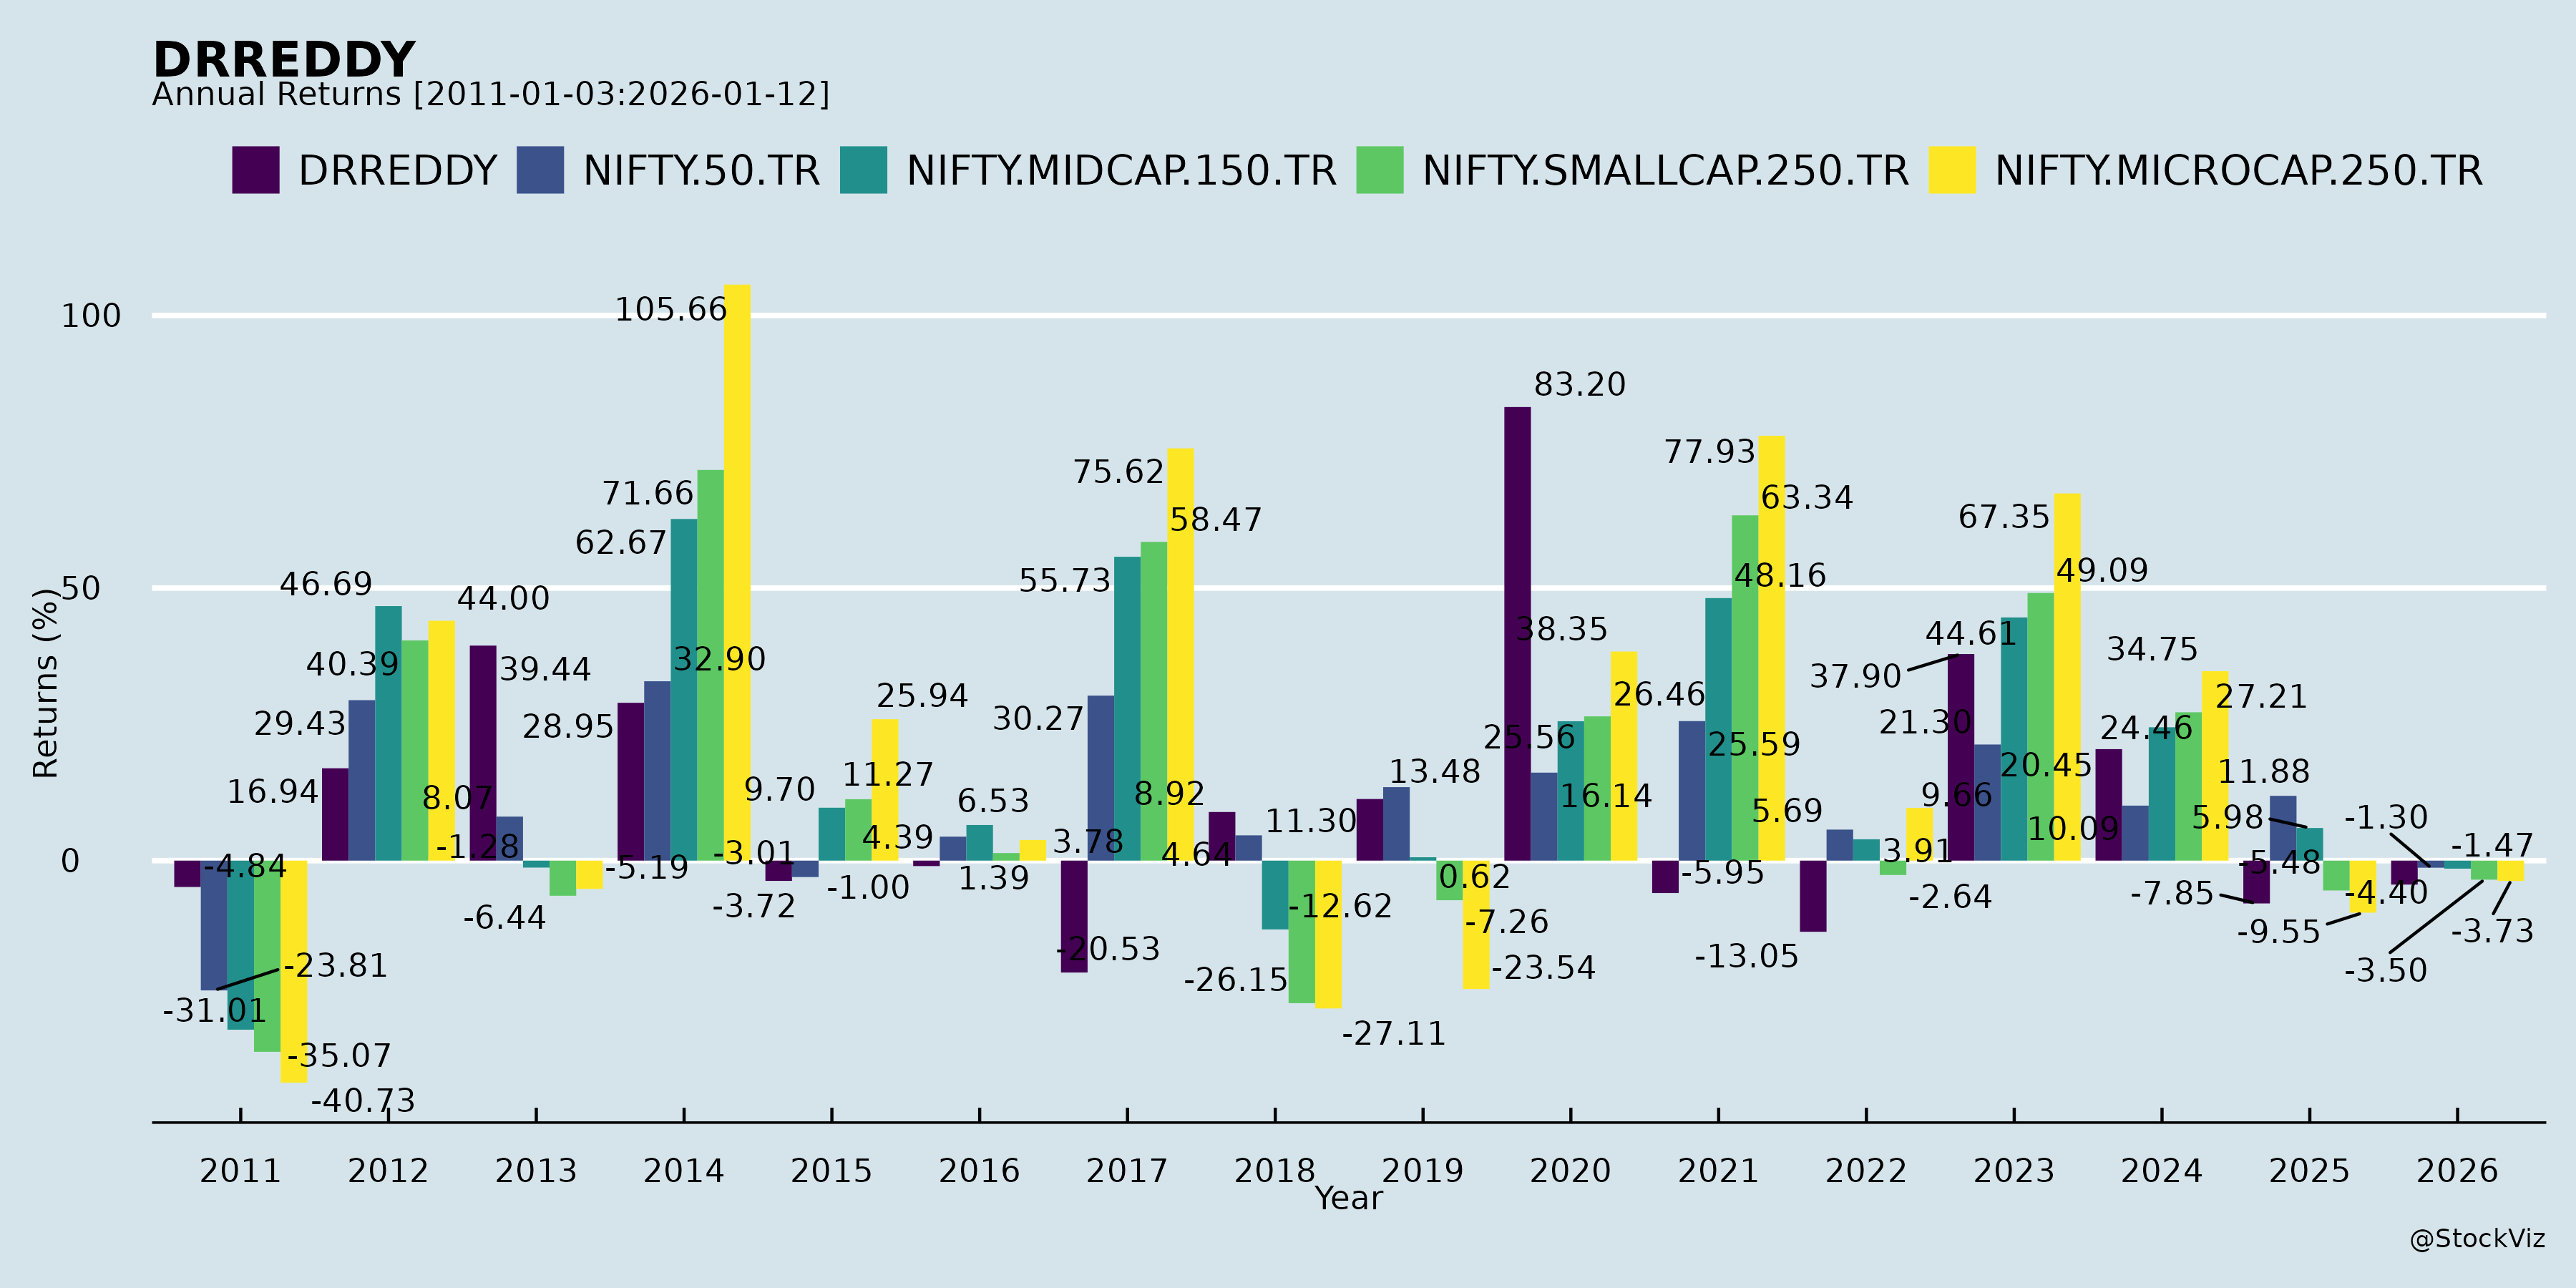
Annual Returns
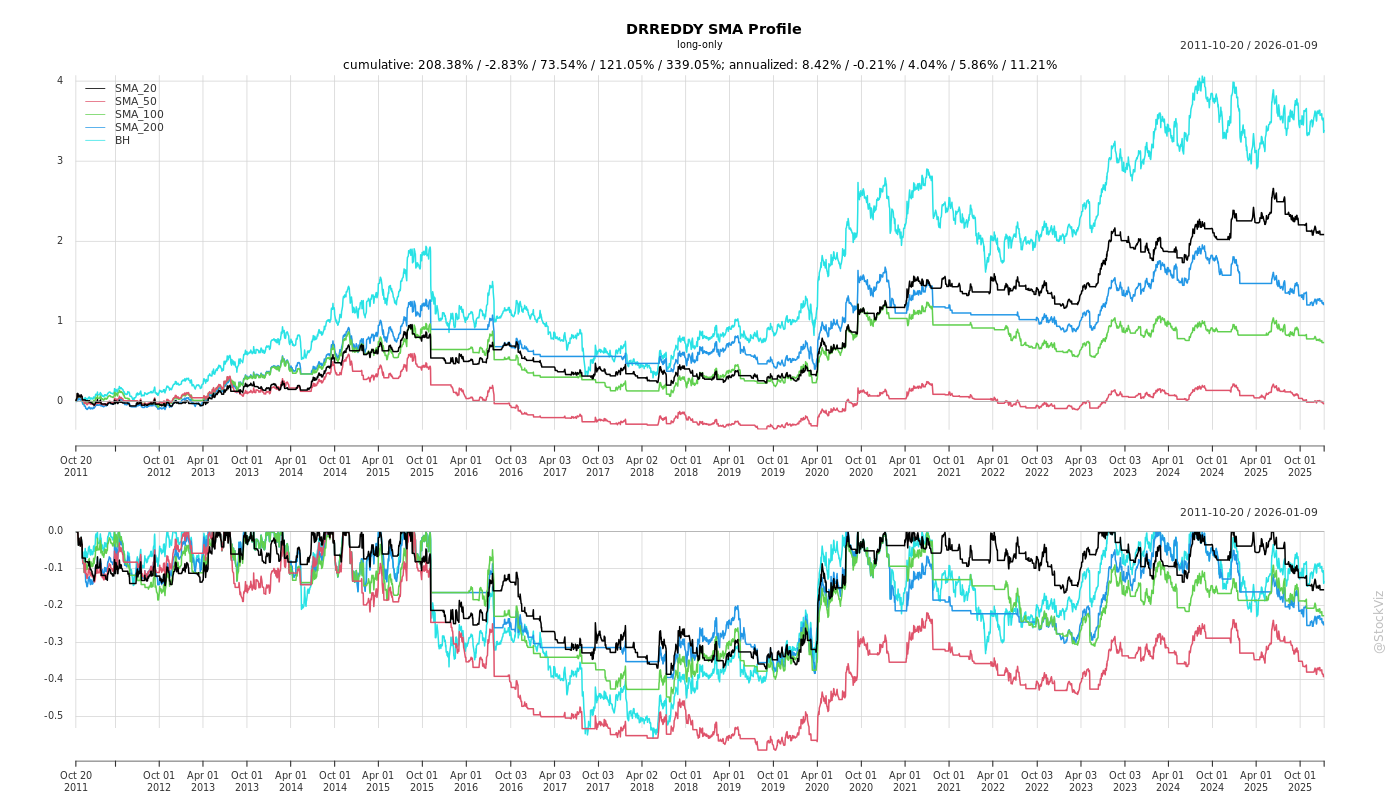
Cumulative Returns and Drawdowns

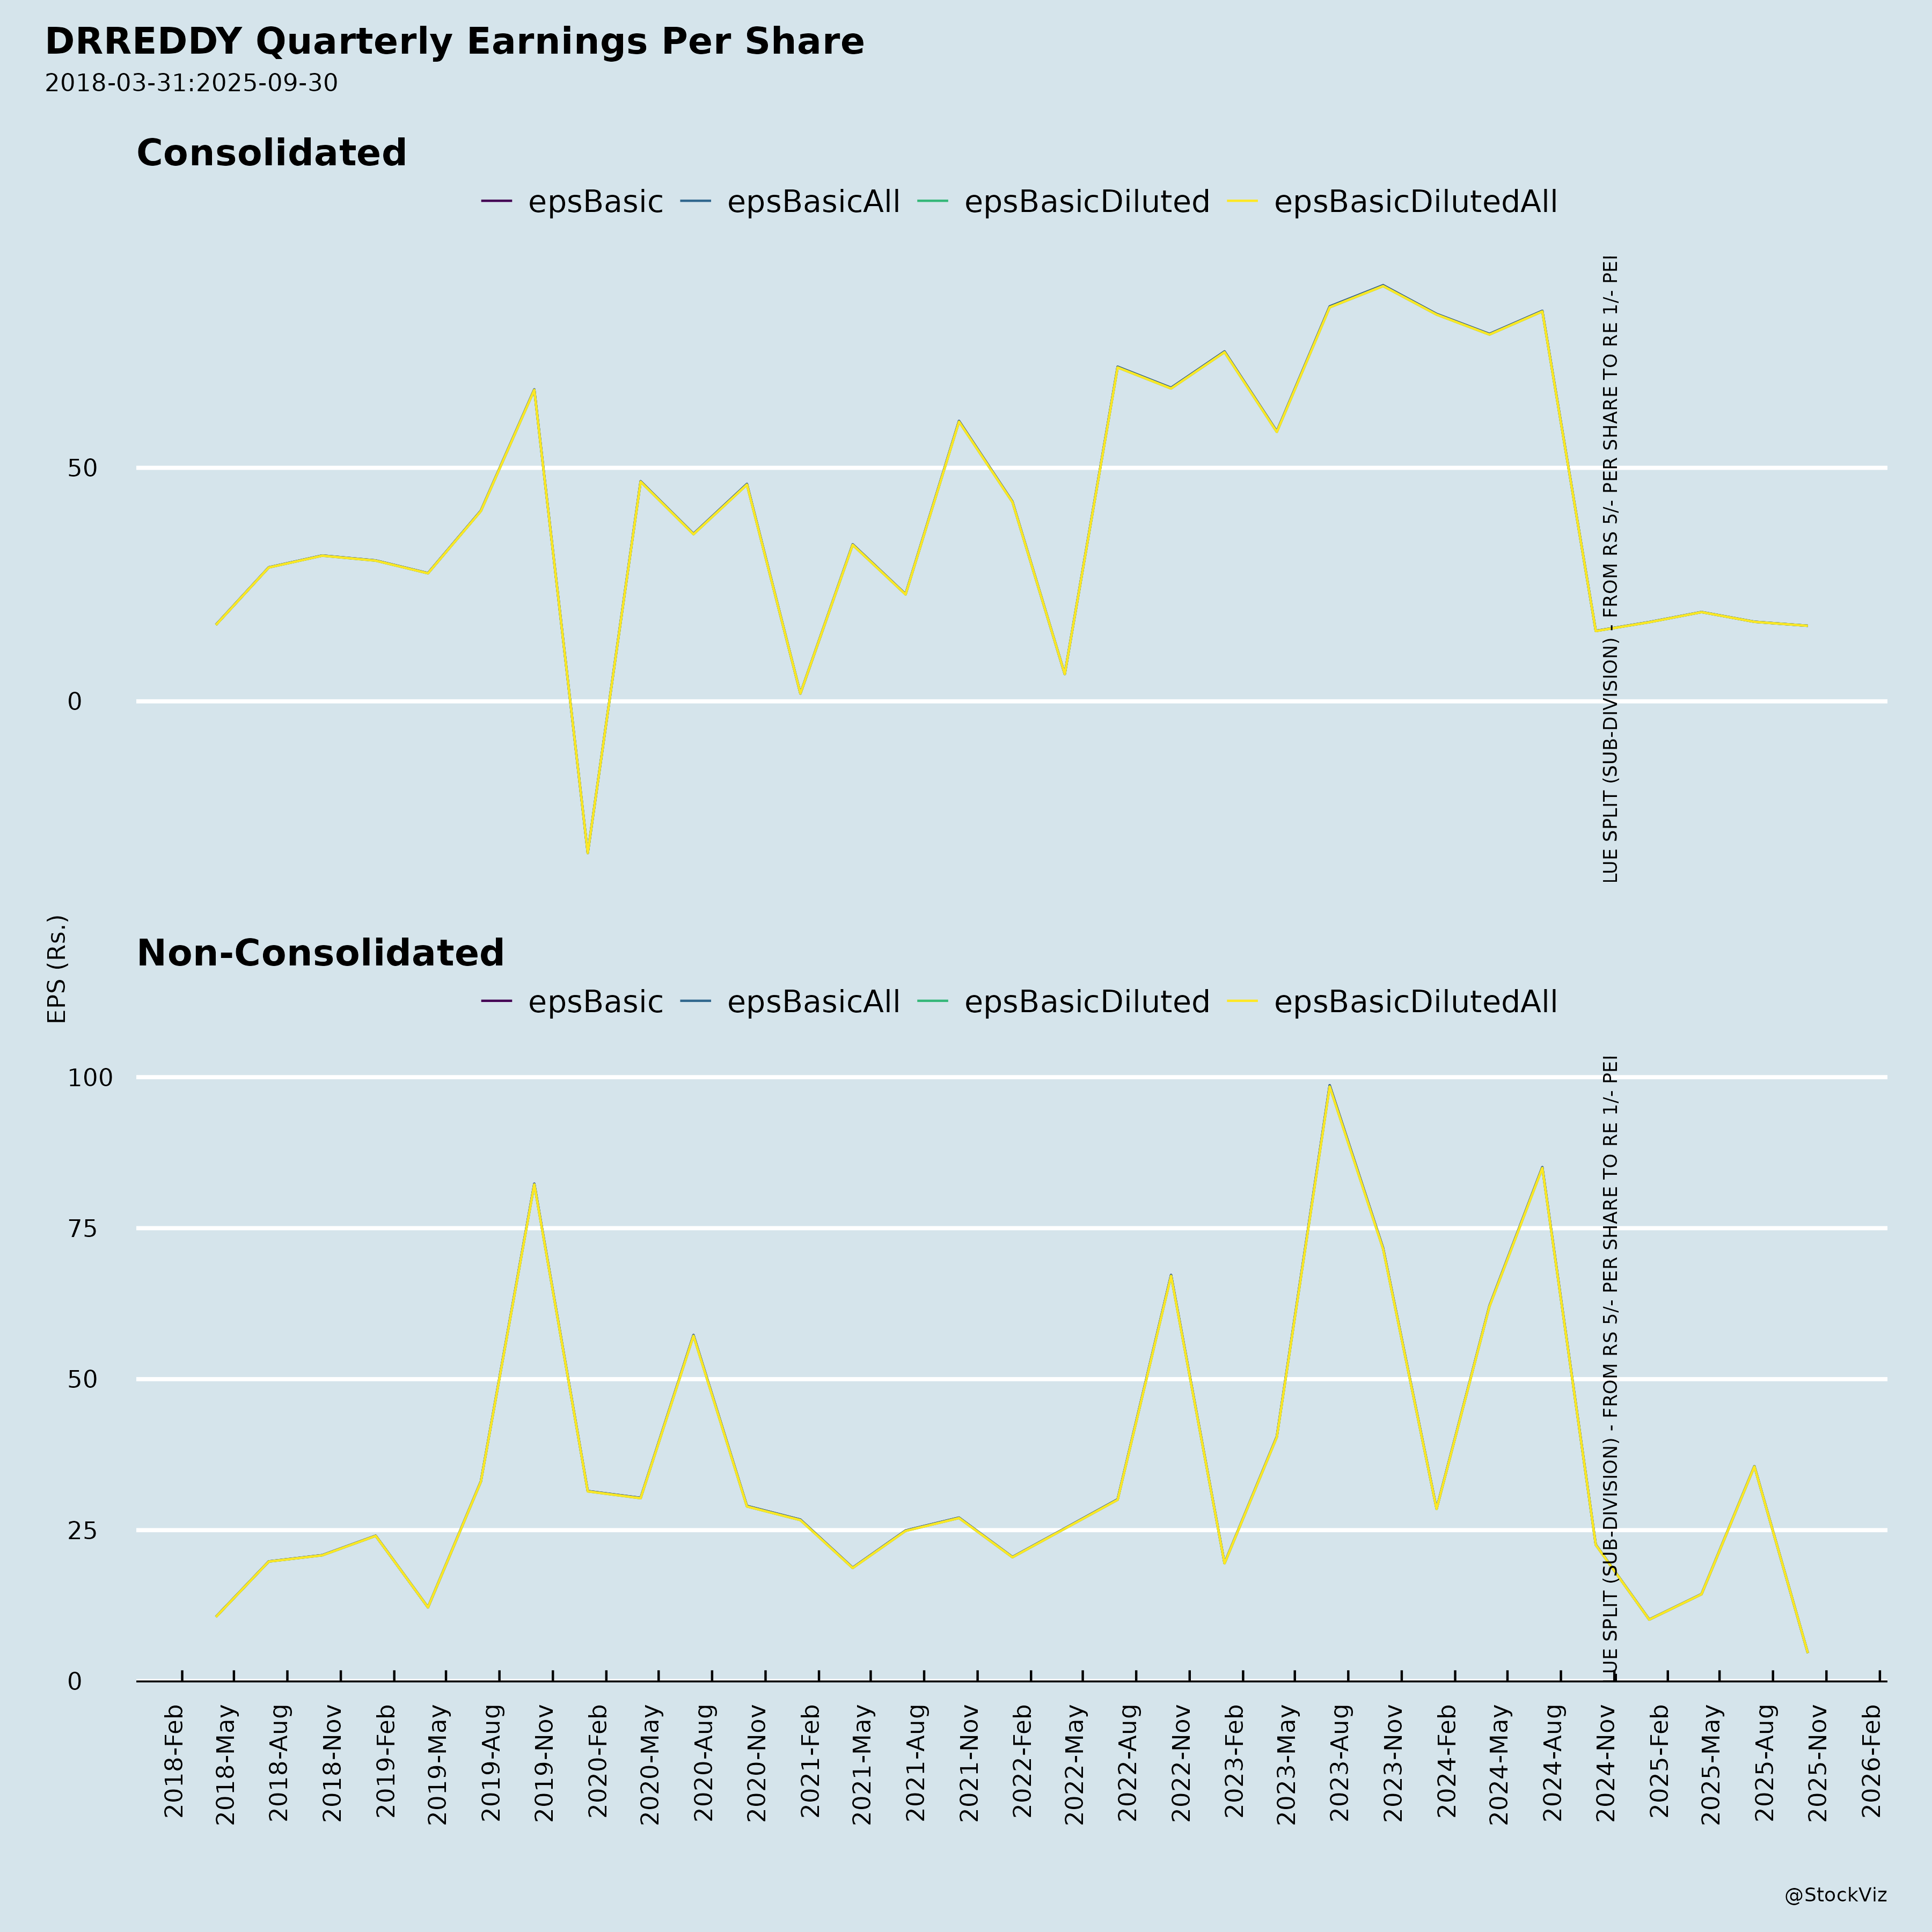
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-14
Headwinds and Challenges
- The rituximab biosimilar approval is for the U.S. market, but Dr. Reddy’s will not commercialize the product there itself. Under a commercialization agreement, Fresenius Kabi holds the exclusive rights to commercialize the product in the United States. This means Dr. Reddy’s participation in the U.S. commercial opportunity is through a partner rather than directly.
- The U.S. rituximab biosimilar market is described as one of the world’s most important pharmaceutical markets, but the announcement does not quantify the expected revenue or margin contribution to Dr. Reddy’s.
- The company’s broader biosimilars business is still described as being in a build-out phase, with several pipeline products in oncology and autoimmune diseases at various stages of development for global launches, and with manufacturing capacity being ramped up to support global expansion plans. This indicates ongoing investment and execution requirements.
- The forward-looking disclaimer in the press release identifies a wide range of risks and uncertainties that could cause actual results to differ materially from expectations, including general economic conditions, competition, regulatory changes, and the impact of acquisitions or reorganization.
Tailwinds and Growth Prospects
- On August 1, 2026, Dr. Reddy’s announced that the U.S. FDA approved its rituximab biosimilar, a biosimilar to Rituxan® (rituximab), for the U.S. market. The approval strengthens the company’s growing global biosimilars portfolio and advances its biosimilars business in the United States.
- The product was developed, manufactured and submitted for approval by Dr. Reddy’s. The approval followed a successful recent Pre-License Inspection (PLI) by the U.S. FDA at the company’s biologics manufacturing facility in Bachupally, Hyderabad. This reflects the company’s capabilities in bringing complex biologic medicines to highly regulated markets.
- The rituximab biosimilar has already been commercialized in India, the European Union, the United Kingdom and more than 25 emerging markets, and has received marketing approval in Switzerland and Canada. This provides a track record of regulatory approvals and commercial presence across multiple geographies.
- The company’s Biologics team has over 25 years of development into a fully integrated organization with capabilities in development, manufacture and commercialization of biosimilars in oncology and immunology. It has a current portfolio of six commercial products marketed in India, with some products marketed in more than 30 other countries.
- In 2024, Dr. Reddy’s launched its first biosimilar in the United Kingdom, Versavo® (biosimilar bevacizumab). This followed the launch of pegfilgrastim in the U.S. and Europe through a partner. The company also launched its rituximab biosimilar in Europe in 2025. The biosimilars business is described as having a key role in driving both near-term and long-term growth.
- The company is ramping up manufacturing capacity to support global expansion plans, and has several pipeline products in oncology and autoimmune diseases in various stages of development for global launches across developed and emerging markets.
Key Risks
- The press release includes a forward-looking statement disclaimer noting known and unknown risks and uncertainties that could cause actual results, performance or events to differ materially from those expressed or implied. These include general economic conditions, performance of financial markets, credit defaults, currency exchange rates, interest rates, mortality and morbidity levels and trends, changing levels of competition, changes in laws and regulations and in the policies of central banks and/or governments, the impact of acquisitions or reorganization including related integration issues, and the susceptibility of the industry and markets to economic downturns as a result of natural disasters, epidemics, pandemics or other widespread illness, including coronavirus (COVID-19).
- Additional risks and uncertainties are identified in the company’s public filings with the Securities and Exchange Commission, including those listed under the “Risk Factors” and “Forward-Looking Statements” sections of the Annual Report on Form 20-F for the year ended March 31, 2026.
- The company assumes no obligation to update any information contained in the press release.
Management Guidance Versus Observed Business Performance
- The rituximab biosimilar approval was received on the FDA’s goal date, which Sridevi Khambhampaty, Global Head, Biologics, described as reflecting the company’s capabilities in developing and manufacturing complex biologic medicines for global markets. This indicates that the approval timeline met the regulatory goal date.
- The product was developed, manufactured and submitted for approval by Dr. Reddy’s, and the approval followed a successful recent Pre-License Inspection (PLI) by the U.S. FDA at the Bachupally, Hyderabad biologics manufacturing facility. This suggests that the facility passed the inspection and that the company’s development and manufacturing capabilities performed as required for the approval.
- The rituximab biosimilar has been commercialized in India, the European Union, the United Kingdom and more than 25 emerging markets, and has received marketing approval in Switzerland and Canada. This demonstrates execution of the company’s stated strategy of expanding its biosimilars portfolio across developed and emerging markets.
- In 2024, the company launched its first biosimilar in the United Kingdom, Versavo® (biosimilar bevacizumab), following the launch of pegfilgrastim in the U.S. and Europe through a partner. The company also launched its rituximab biosimilar in Europe in 2025. These launches are consistent with the company’s description of its biosimilars business as having a key role in driving near-term and long-term growth.
- The company states it is ramping up manufacturing capacity to support global expansion plans and has several pipeline products in oncology and autoimmune diseases in various stages of development for global launches across developed and emerging markets. The observed performance of obtaining the U.S. FDA approval for rituximab biosimilar and the prior launches in multiple markets provide evidence of progress against this stated direction, though the announcement does not provide financial figures or specific guidance metrics to compare against.
Broker Narrative
The broker narrative evolved from 2023 concerns over gRevlimid-driven US revenue declines, base-margin misses, domestic Covid-base drags, US pricing and regulatory risk, and Russia/EM weakness toward a 2026 focus on NRT integration costs, Semaglutide relaunch delays, PSAI and NRT revenue declines, and forex volatility, while balance-sheet strength and launch-pipeline optimism gave way to margin recovery via lower R&D and overheads plus biosimilar approvals. Persistent themes include gRevlimid-related US revenue pressure and generic price erosion, now extended to Europe, alongside forex headwinds; resolved themes include the acute Russia slump and domestic Covid-base distortion, which later turned into 15% Russia growth and 17% domestic formulation growth.
Fears that came true
- The early warning of lower gRevlimid-driven US revenues materialized, as the final report cites a YoY US revenue decline due to the high base of gRevlimid, a backdrop associated with multiple DISAPPOINTMENT outcomes and negative actual returns in the history.
- US pricing pressure flagged at the outset persisted into generic price erosion in Europe and NRT revenue declines from higher distributor rebates, recurring in periods marked by DISAPPOINTMENT-rated calls and weak actual returns.
- Forex volatility cautioned in early Russia/EM weakness resurfaced in the last report as a drag on other income, corresponding to flat or negative actual returns in several later reports.
Optimism that failed
- The early expectation of ongoing meaningful gRevlimid earnings support through FY23–25E failed to sustain, as the latest report treats gRevlimid as a high base causing US revenue decline rather than a continued earnings cushion.
Broker Timeline
67 broker calls · 2023-05-10 to 2026-10-26
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.