DLF
Equity Metrics
November 18, 2026
DLF Limited
Residential Commercial Projects
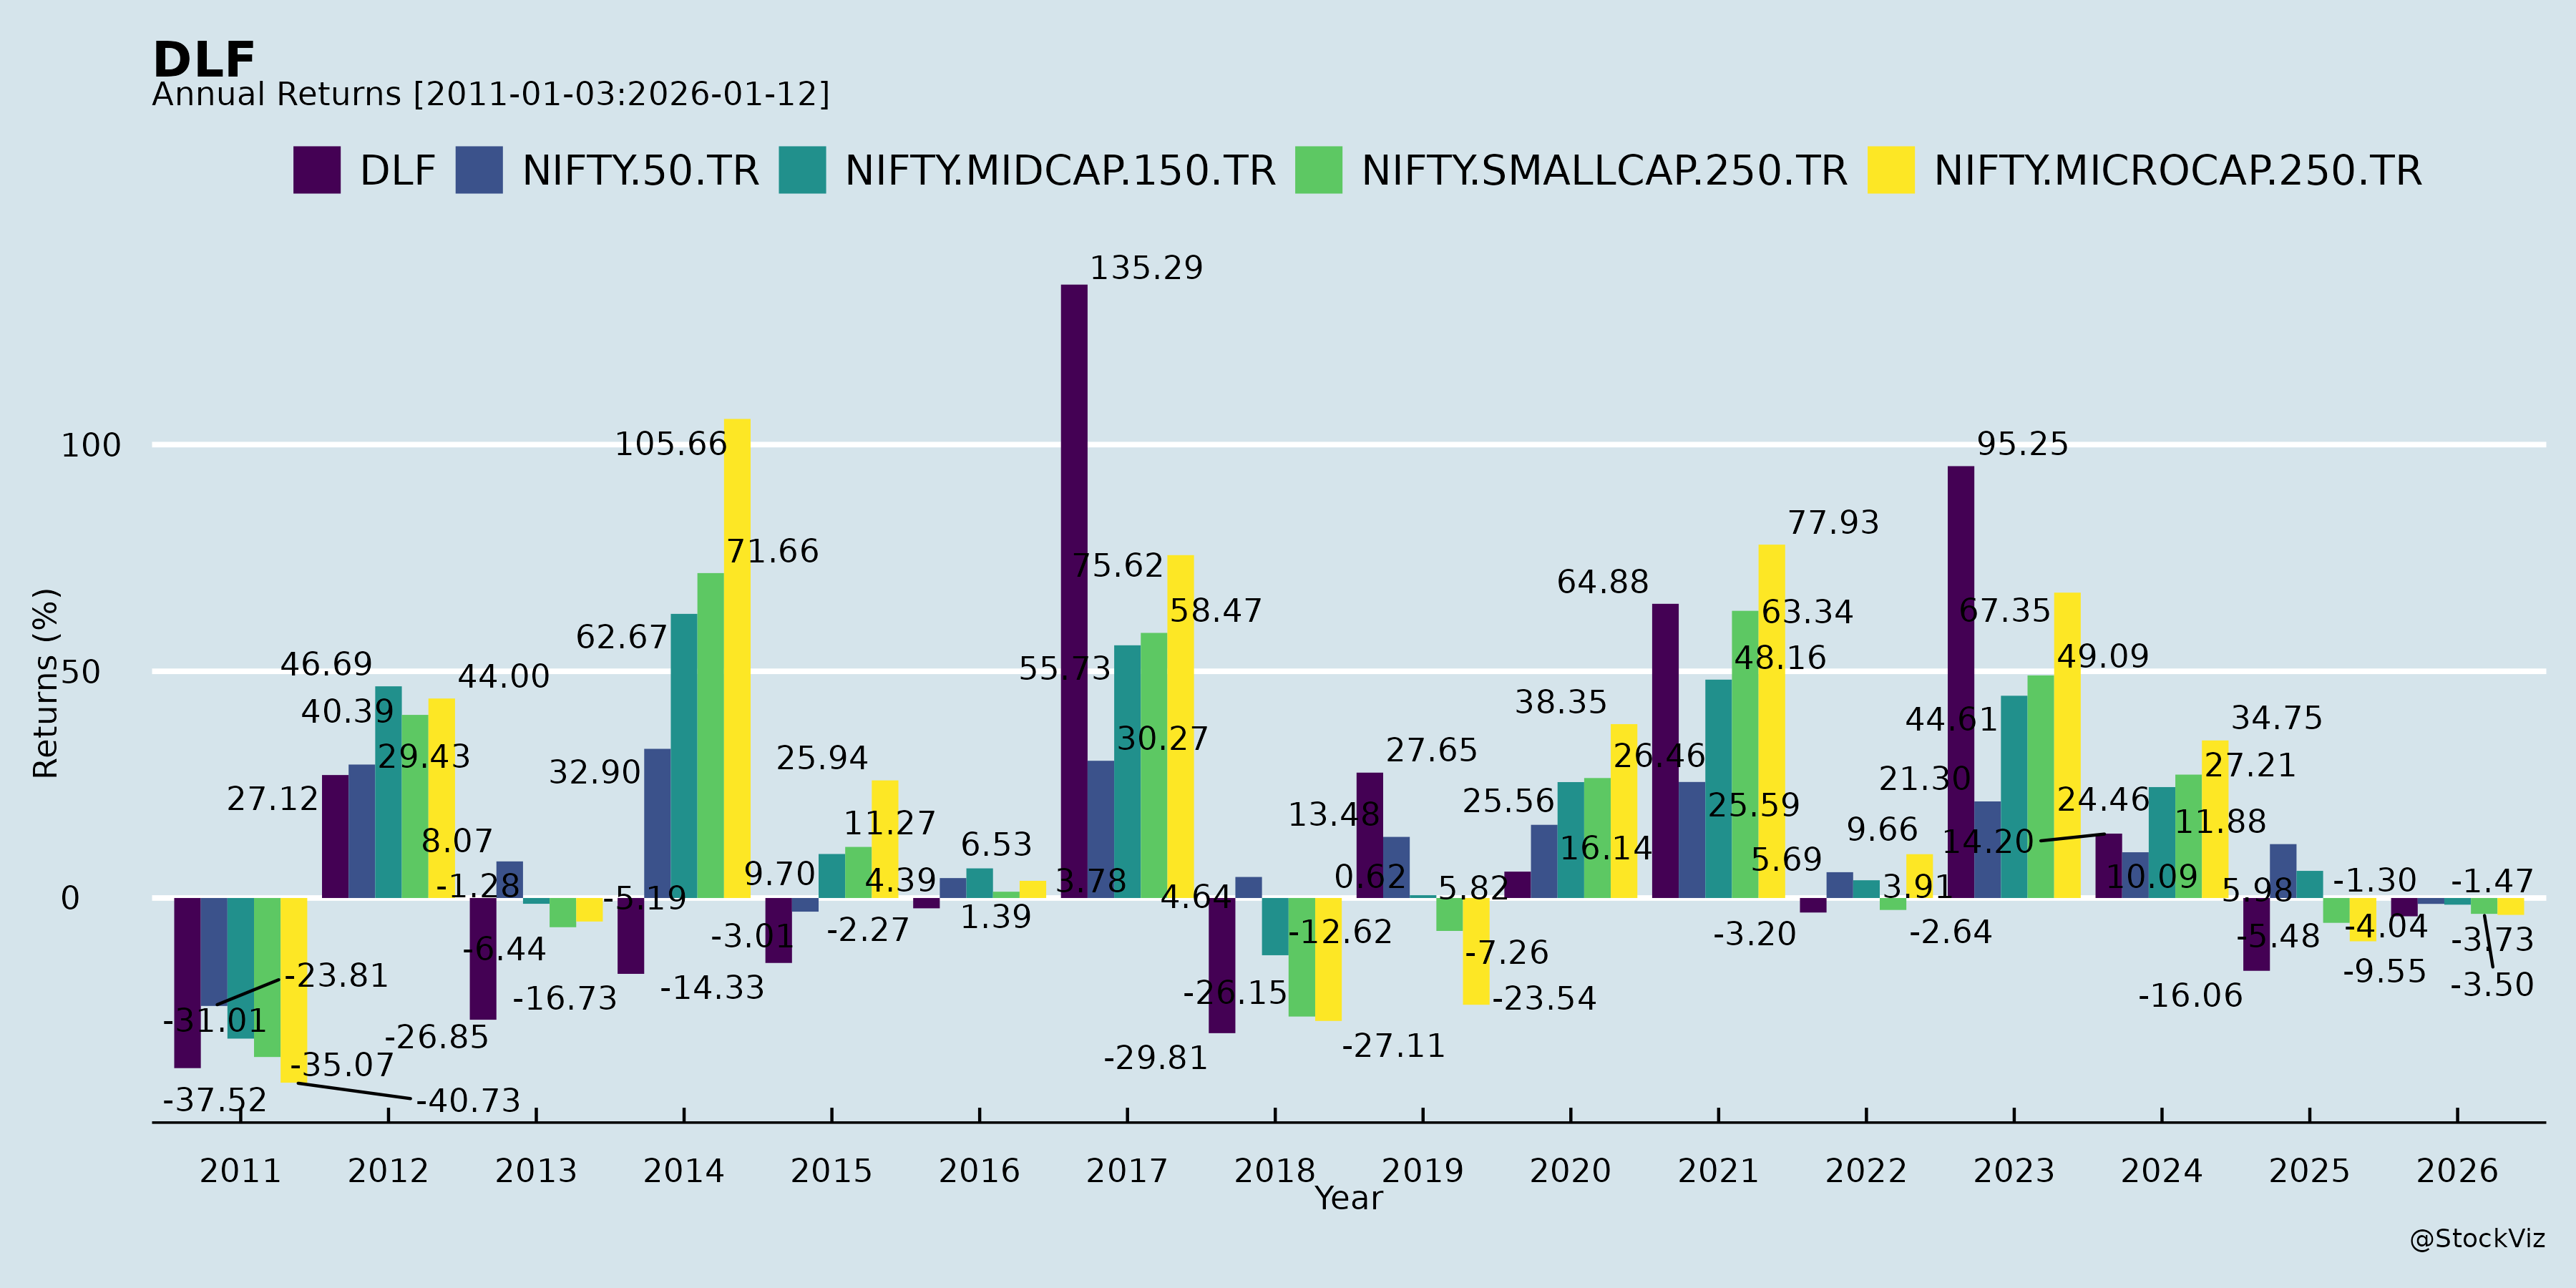
Annual Returns
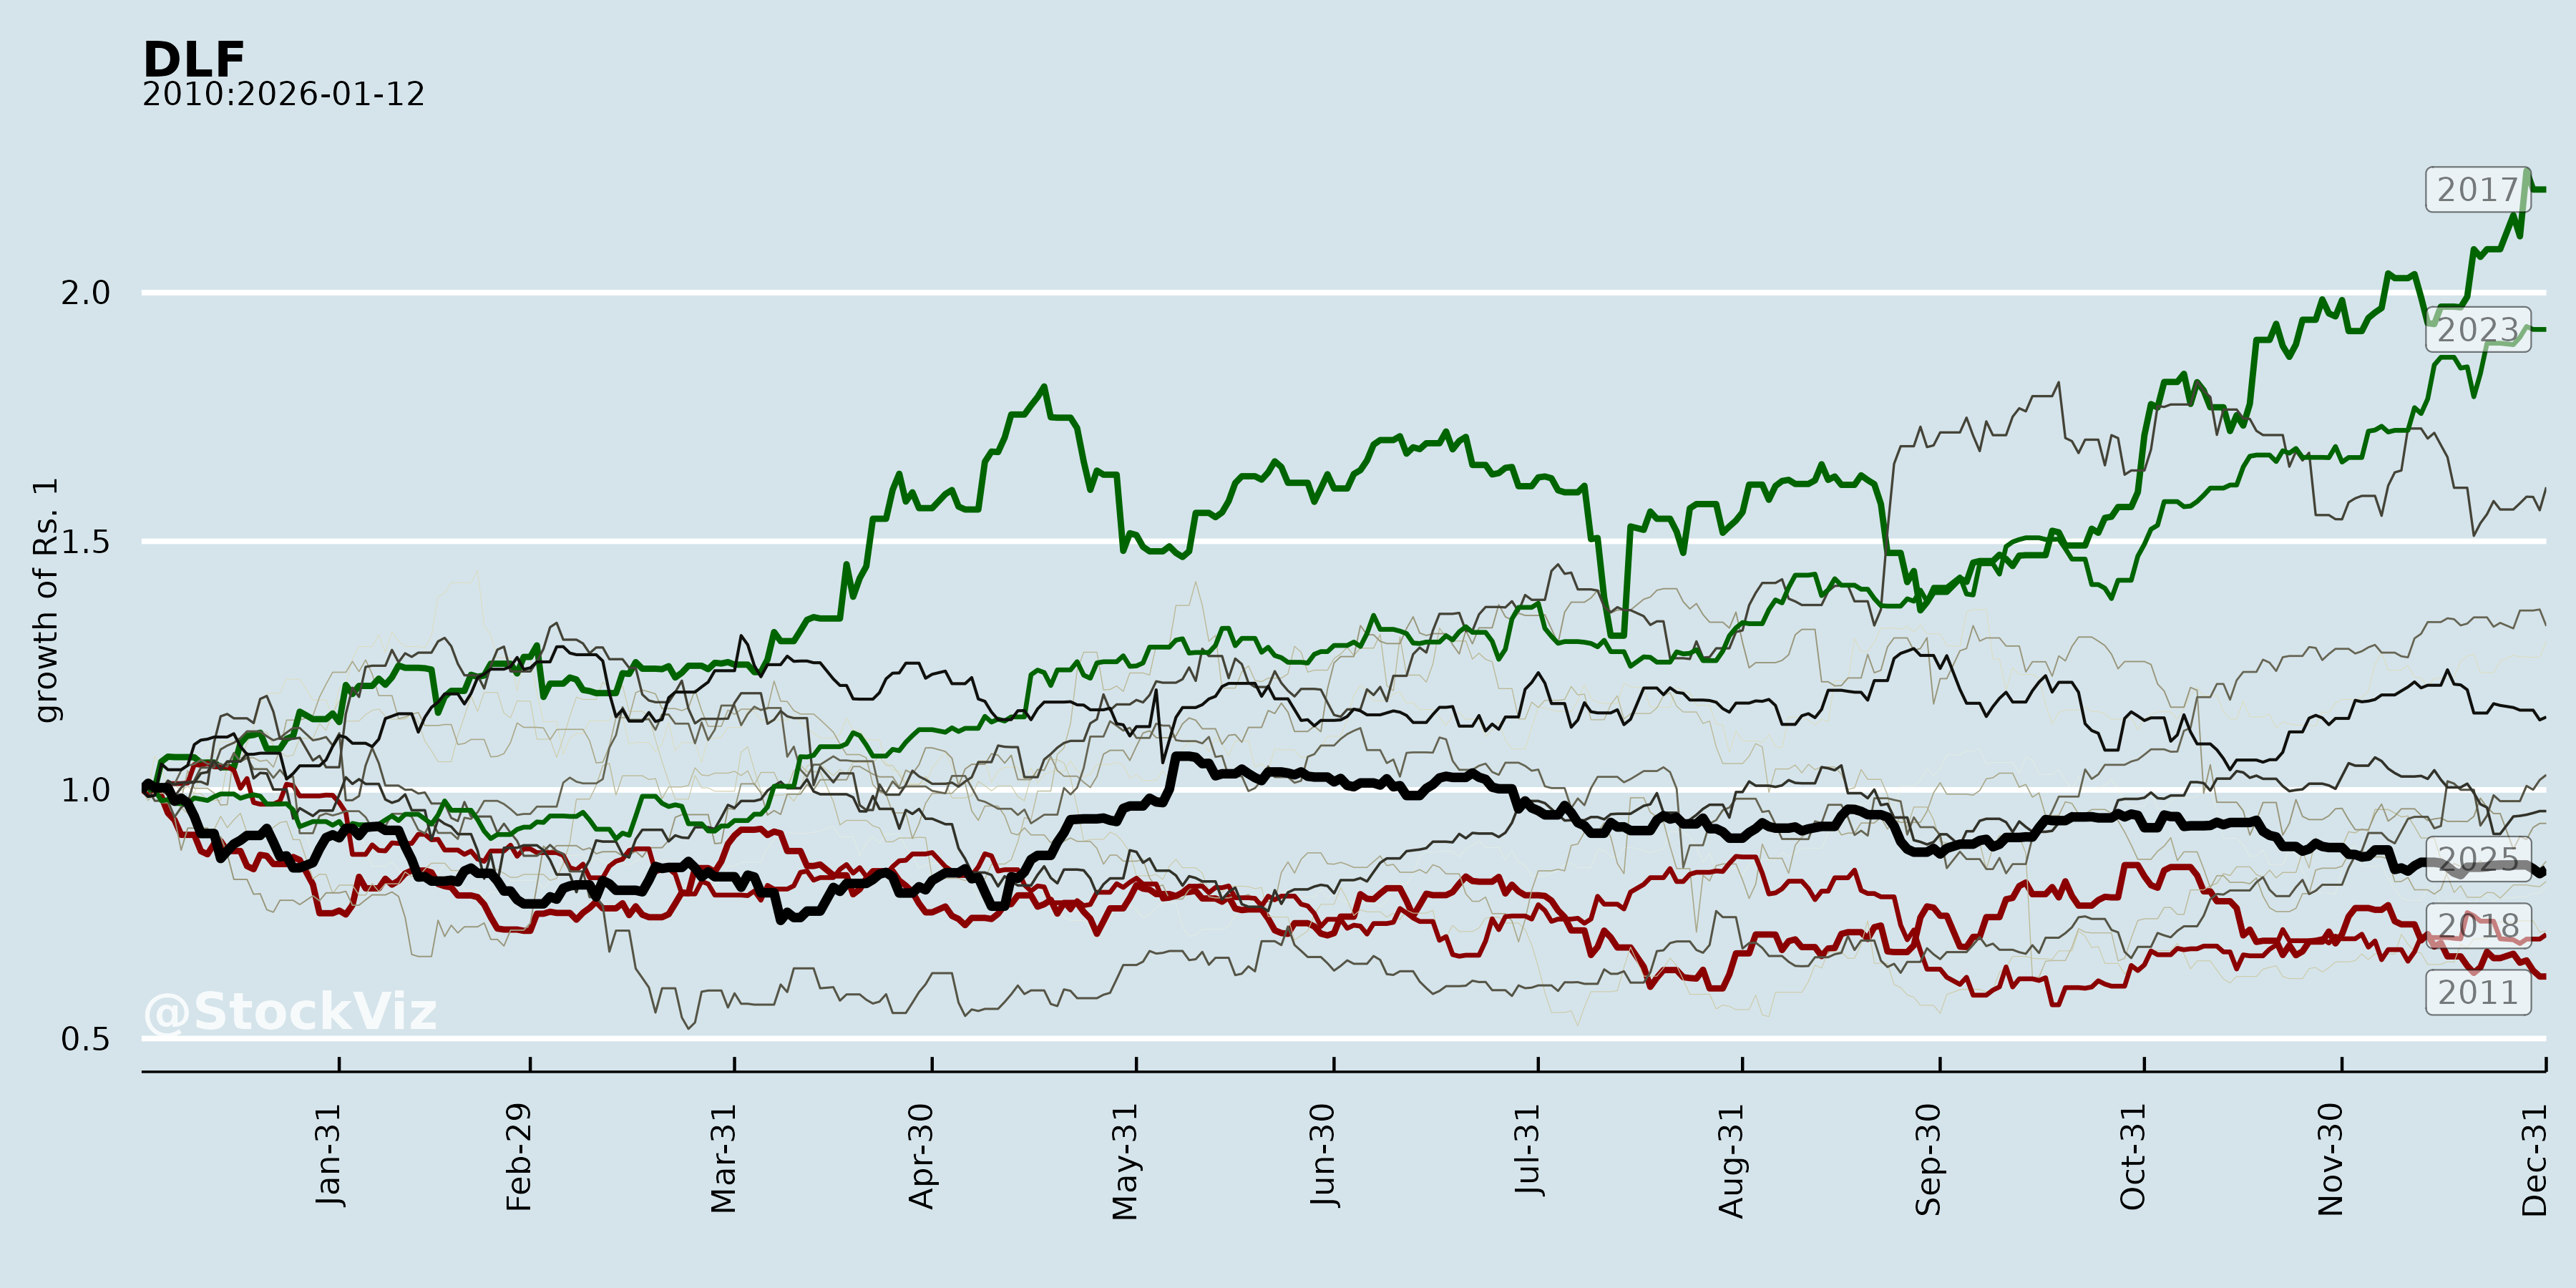
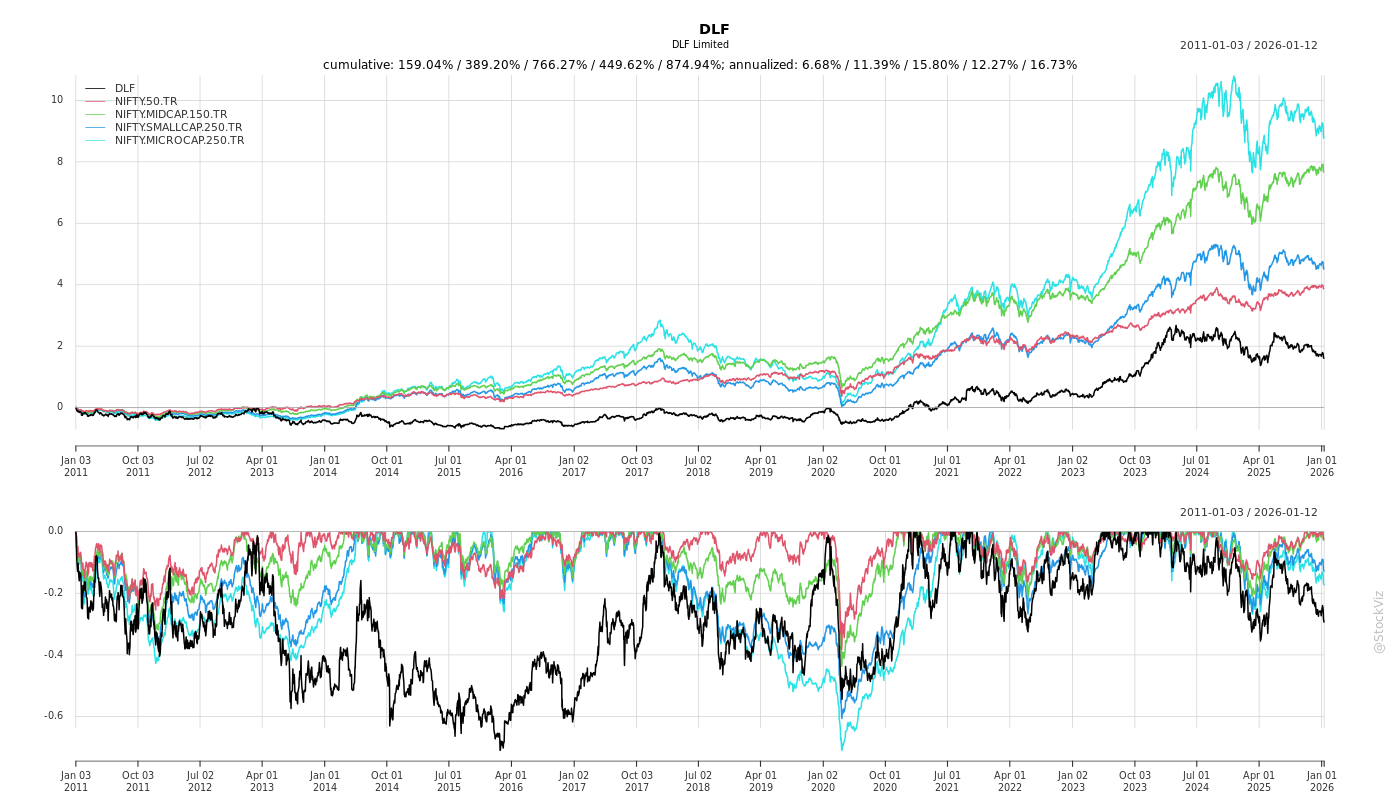
Cumulative Returns and Drawdowns
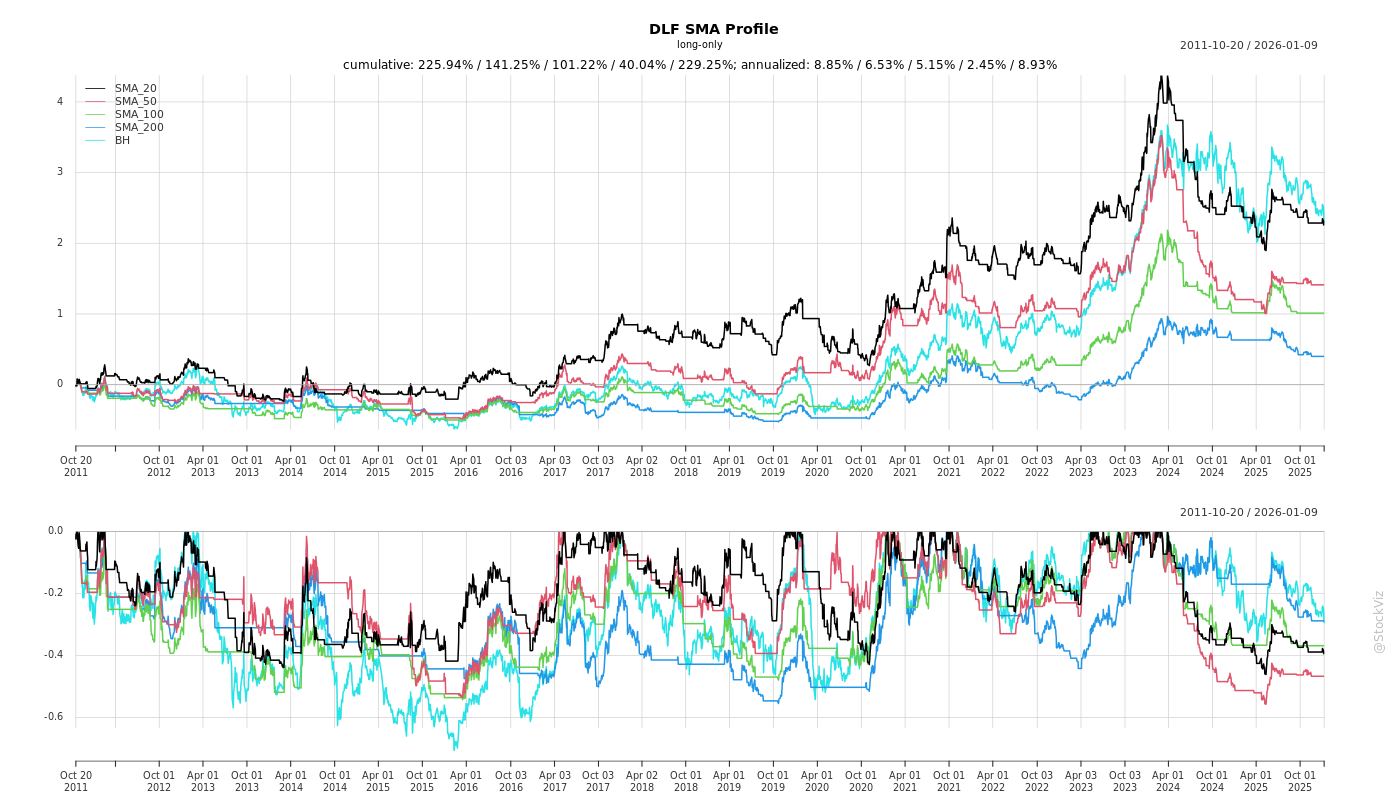
Fundamentals
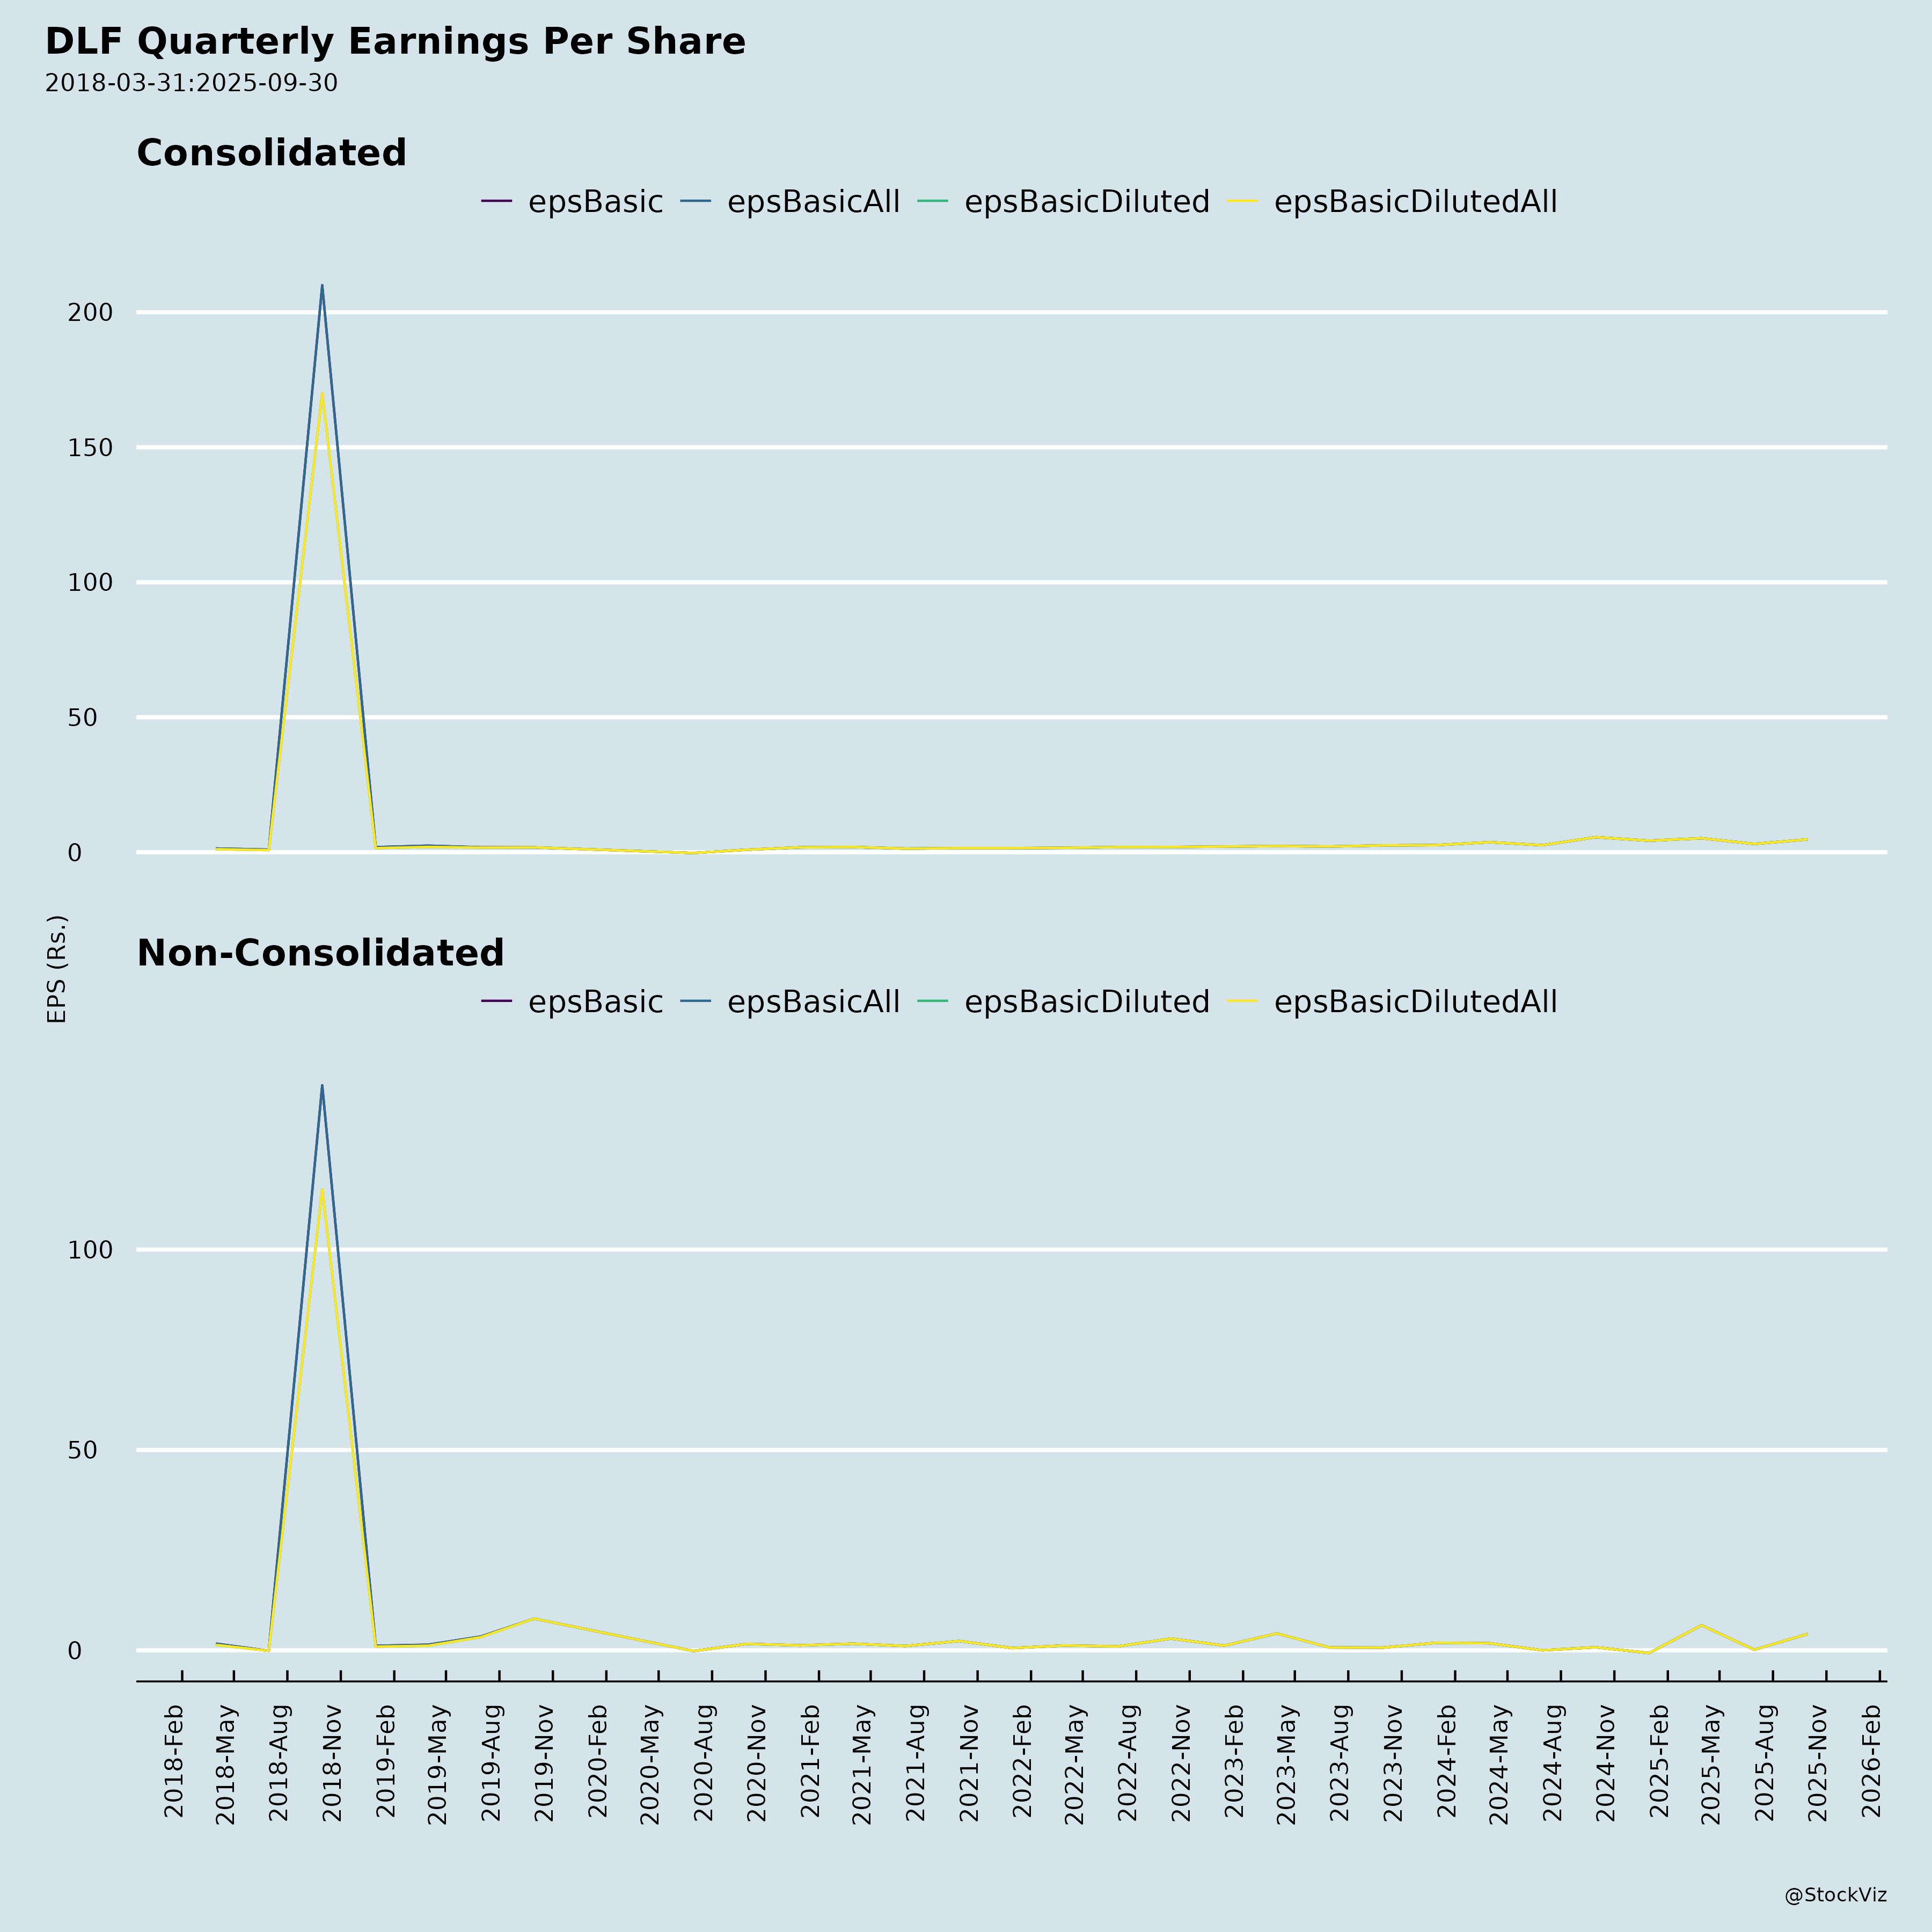
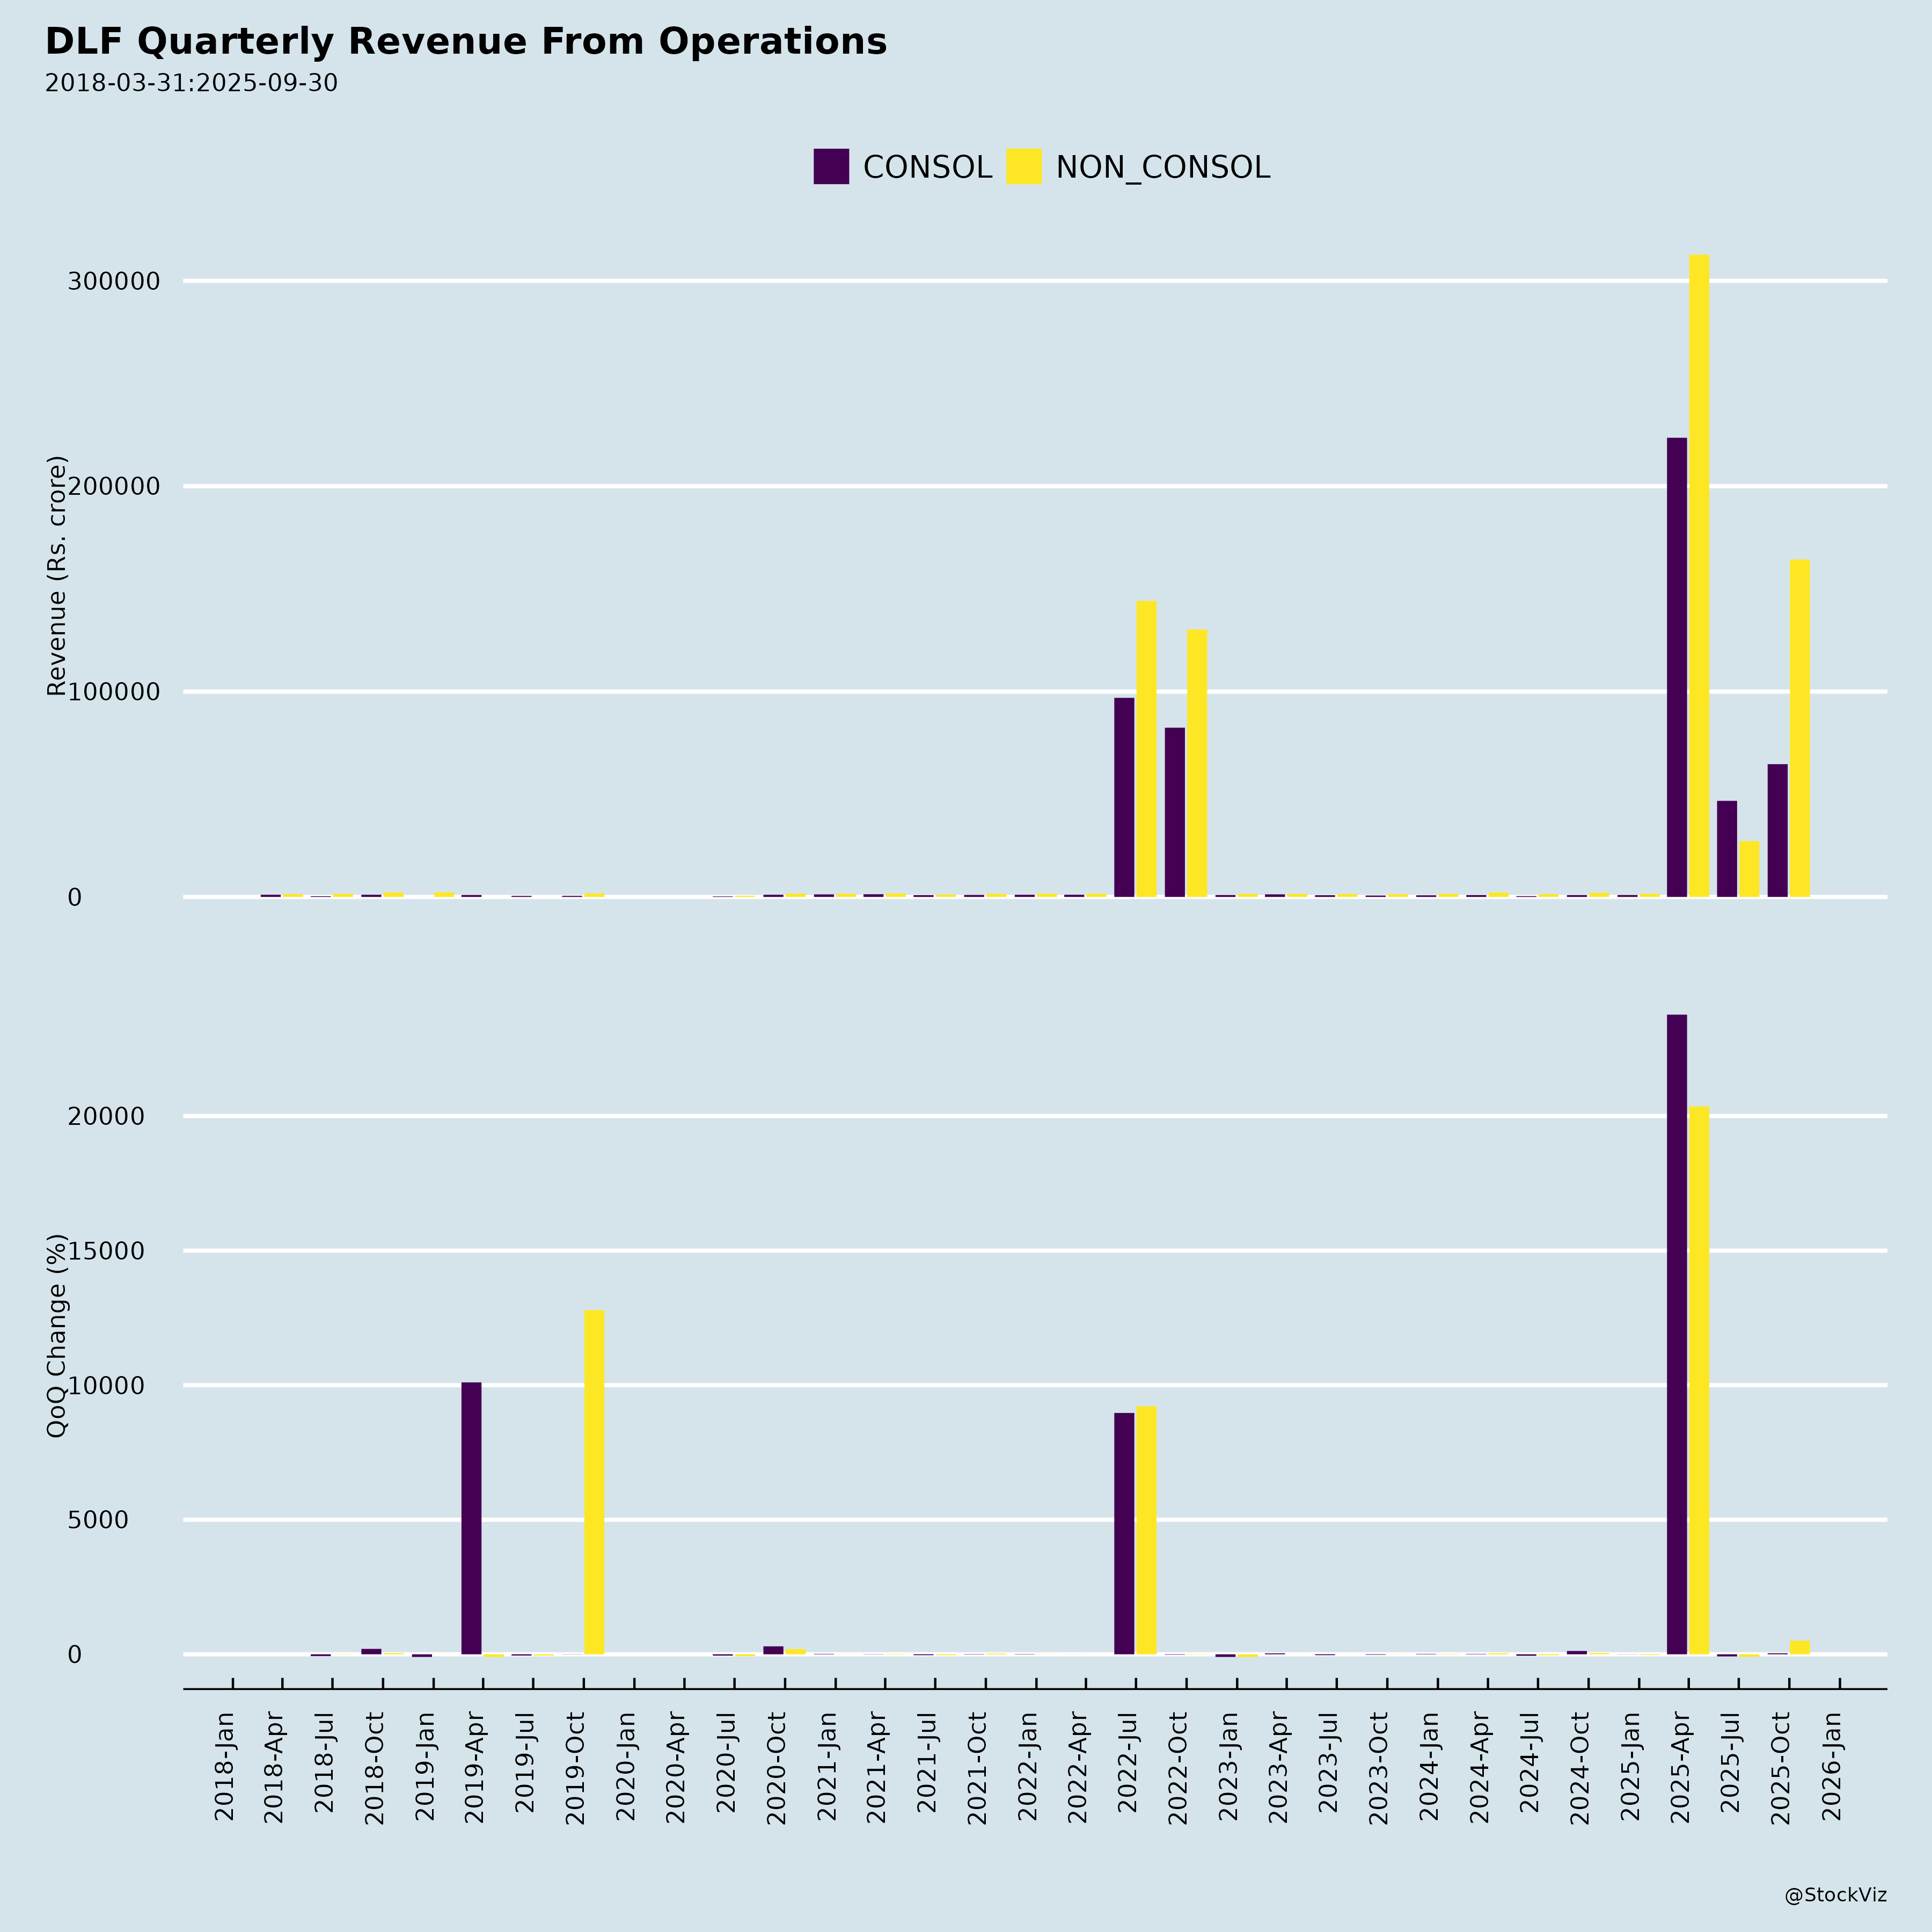
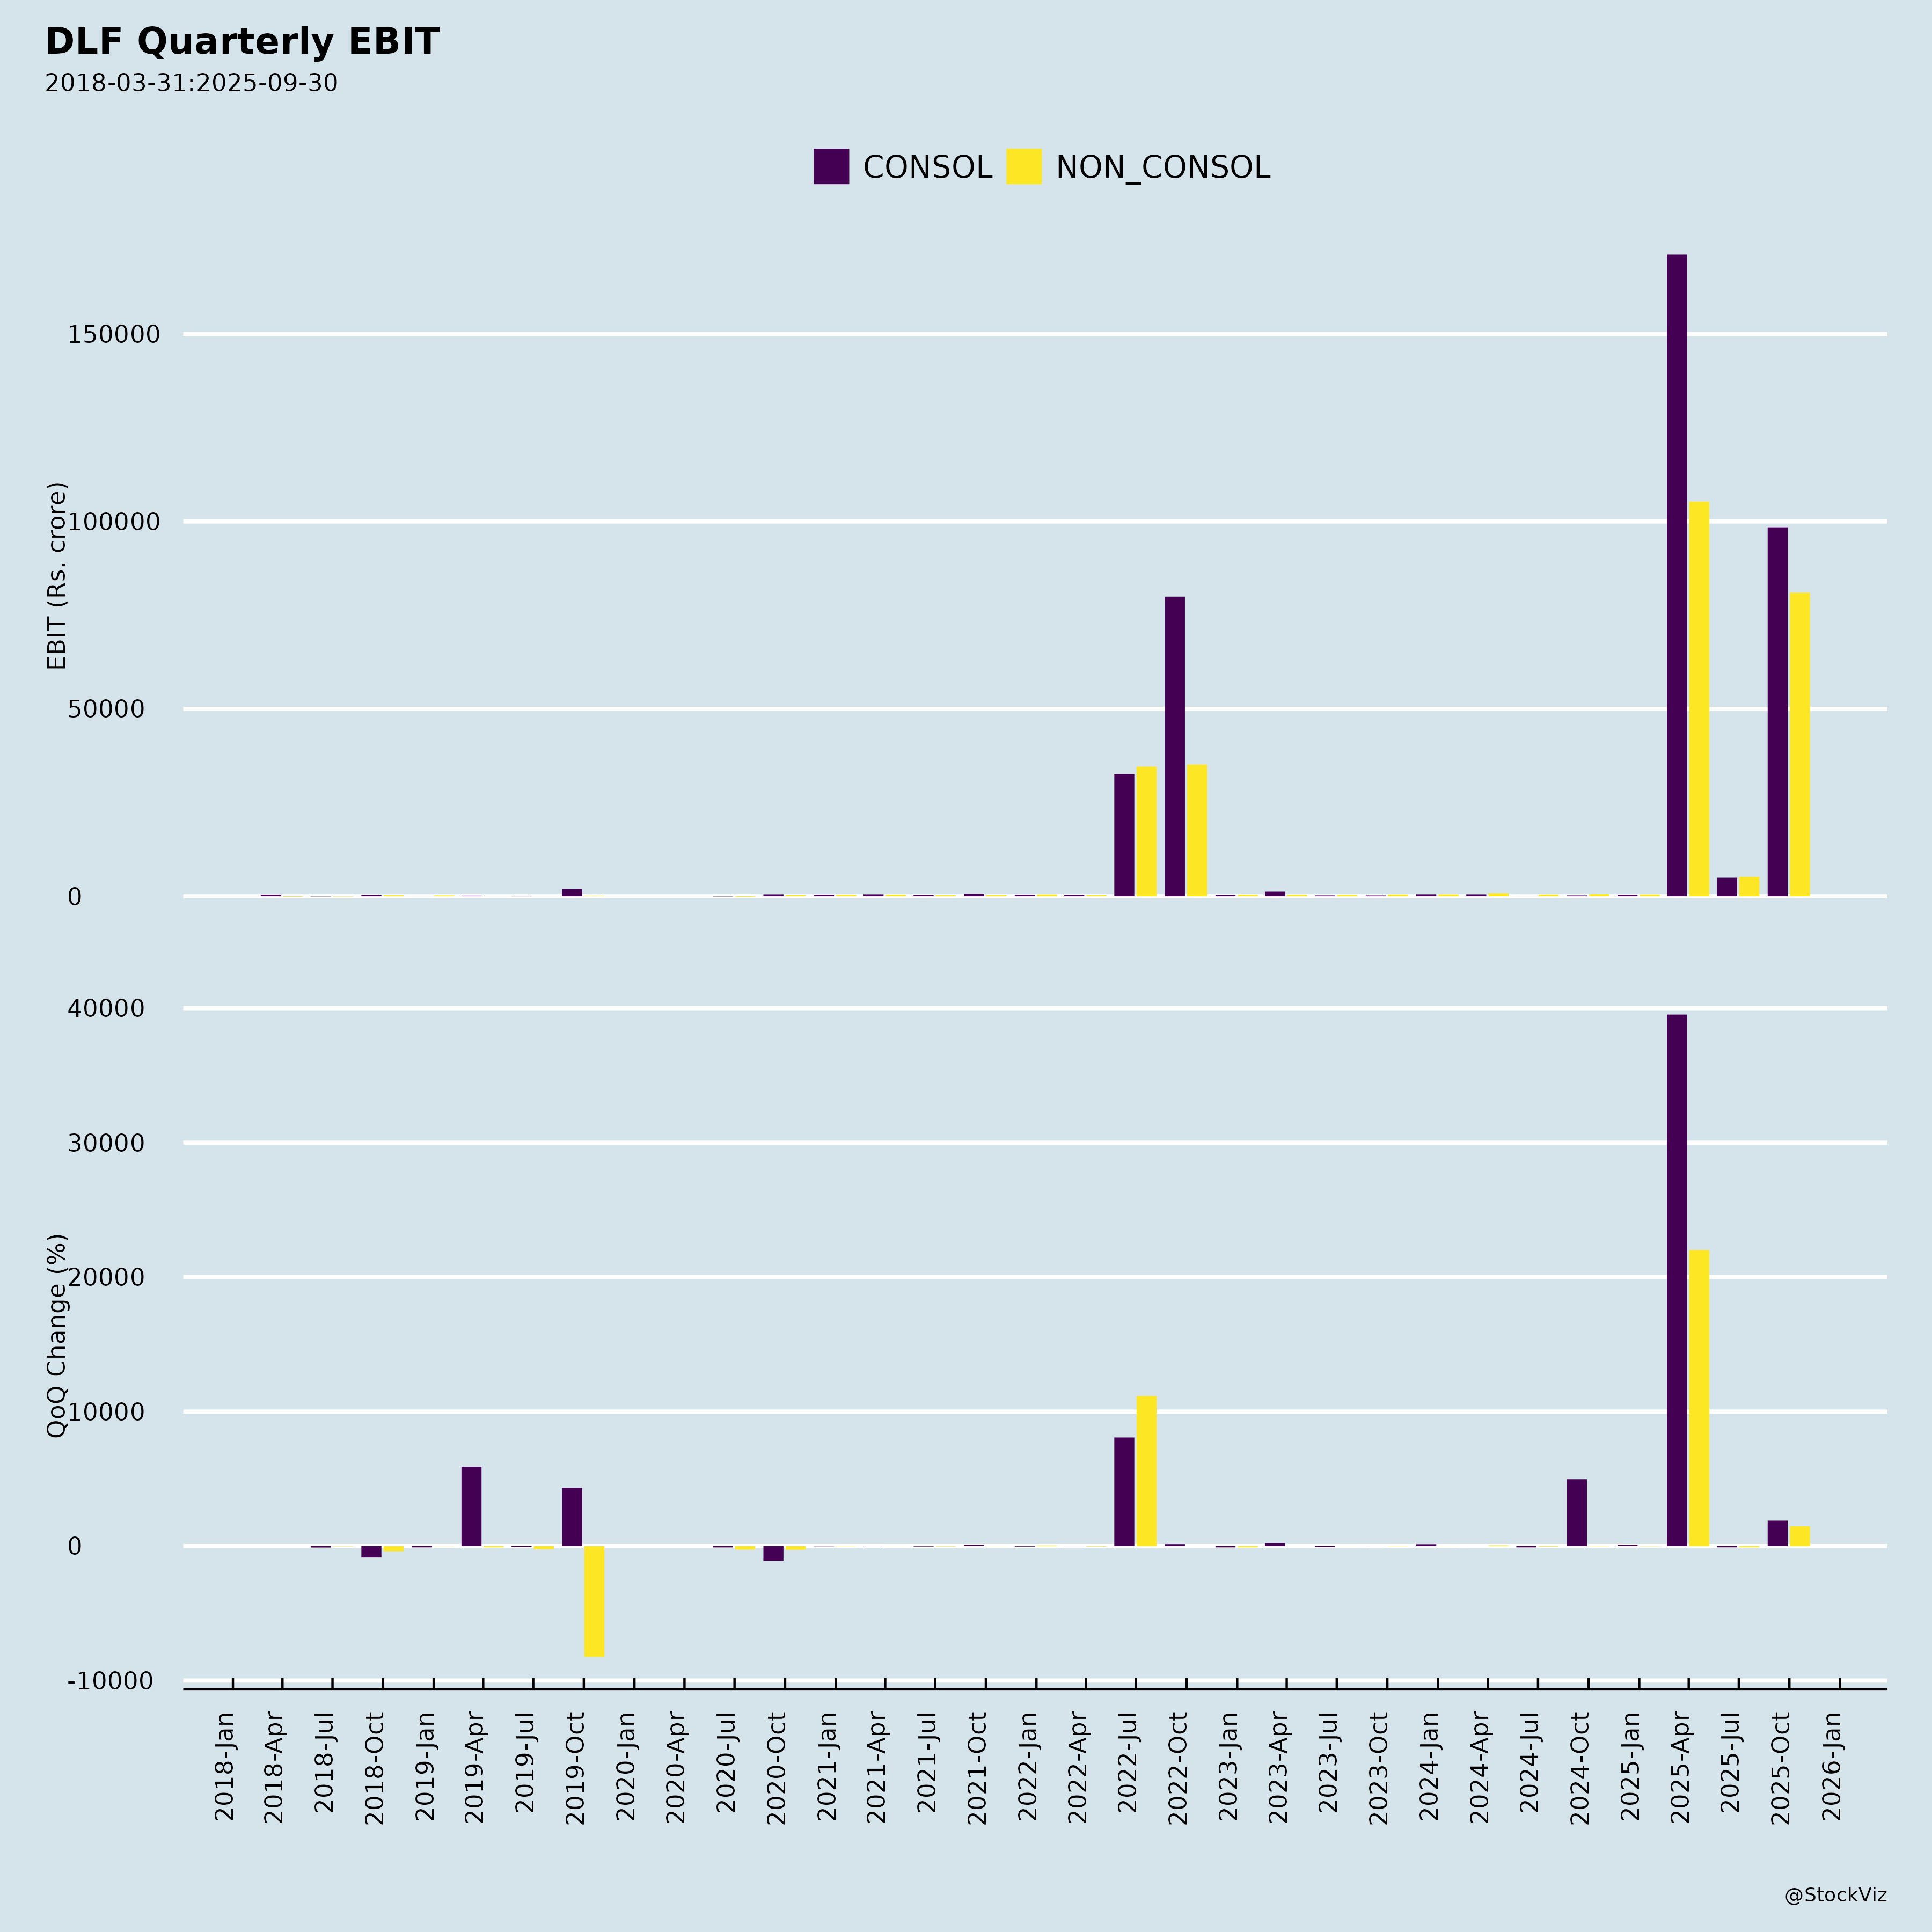
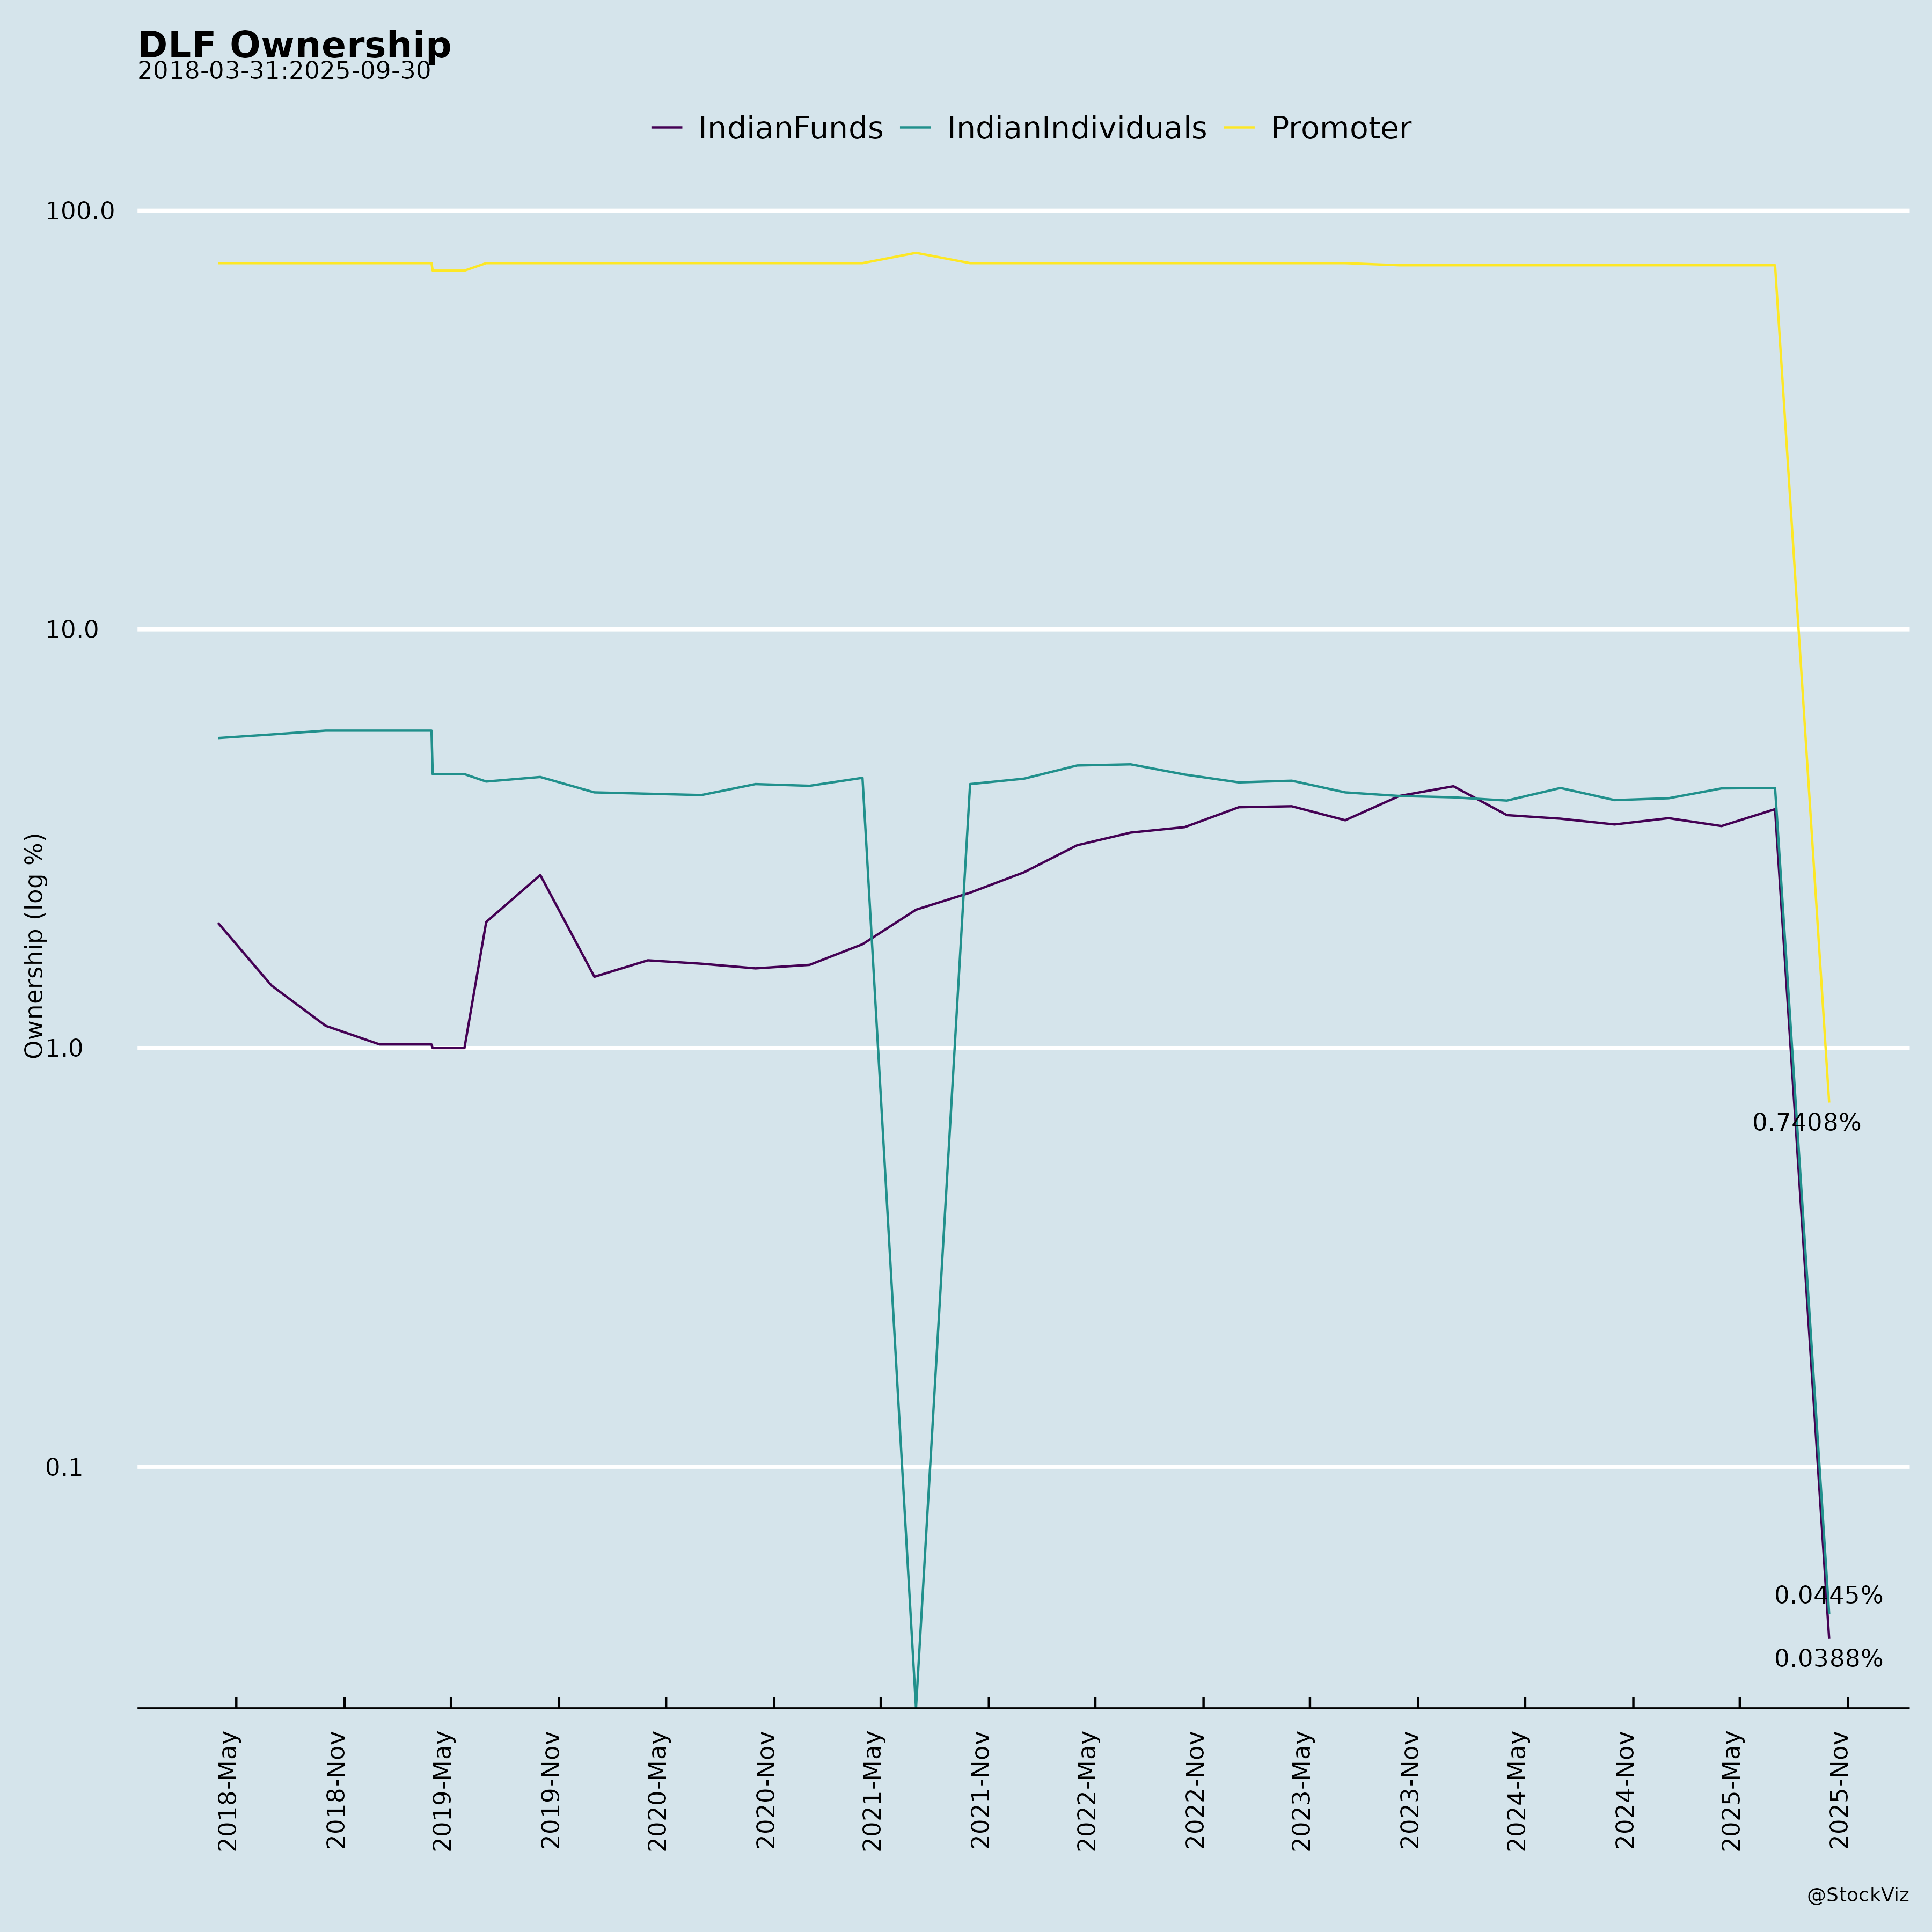
Ownership
Margined
AI Summary
asof: 2026-09-14
DLF — Recent Corporate Announcements: Summary
1. Headwinds and Challenges
- Deferred launches weighed on sales bookings. DLF’s Q1FY27 new sales bookings stood at ₹657 crore, which the company attributes to the timing impact of deferred launches. Management states it expects the requisite approvals for planned launches to be received soon.
- Macroeconomic caution. While expressing confidence in achieving business goals, management states it maintains “a cautious eye on the overall macroeconomic developments.”
- Global turbulence. The Chairman notes the Indian economy has maintained stability “through intense global turbulence,” framing the external environment as a backdrop requiring resilience.
- Execution and external risk factors. Forward-looking statements are qualified by risks and uncertainties including earnings fluctuations, ability to manage growth, competition, economic growth in India, ability to attract and retain highly skilled professionals, time and cost overruns on contracts, government policies and actions related to investments, regulation and policies, and general interest and fiscal policies prevailing in the economy.
2. Tailwinds and Growth Prospects
- Government infrastructure focus. The Chairman cites the Government’s focus on infrastructure as unlocking opportunities in urbanisation through real estate, and DLF’s demonstrated track record as positioning it to take advantage of these opportunities.
- Launch pipeline. Management references a launch pipeline for new products of approximately ₹60,000 crore in the medium term, and states it remains well positioned to bring upcoming products to market with sustained customer demand, strong brand positioning, deep market presence, and a defined launch pipeline.
- Land bank and policy upside. Growth prospects include significant upside from TOD/TDR policy and a high-quality land bank at established locations, supporting sustainable growth from the existing land bank without dependency on incremental acquisitions.
- Annuity/rental expansion. The annuity portfolio stands at approximately 50 million sq. ft. with industry-leading occupancy of 95%. Management aims to reach approximately ₹10,000 crore of rental income in the medium term, expand DLF’s portfolio to 25% of the total portfolio from 10% currently, and grow the retail portfolio to 15% of total portfolio size.
- New retail destinations. During the current fiscal, three new retail destinations aggregating approximately 1.5 msf of gross leasable area are to commence operations — DLF Midtown Plaza (New Delhi), which has already commenced operations, DLF Summit Plaza (DLF 5, Gurugram), and DLF Promenade (Goa) — and are expected to drive significant growth in the retail business.
- Structural upcycle. Management states DLF is well positioned to capitalize on the structural upcycle in the sector, supported by a significant land bank, robust launch pipeline across development and rental businesses, strengthened balance sheet, and consistent cash flow generation.
- Development potential. The group has 275 msf (approx.) of development potential across residential and commercial segments, including current projects under execution in the identified pipeline.
3. Key Risks
- Risks and uncertainties that could cause actual results to differ materially from forward-looking statements include: earnings fluctuations; ability to manage growth; competition; economic growth in India; ability to attract and retain highly skilled professionals; time and cost overruns on contracts; government policies and actions related to investments, regulation and policies; and general interest and fiscal policies prevailing in the economy.
- Timing risk around launches is evident in Q1FY27, where deferred launches affected sales bookings, with approvals still awaited for planned launches.
4. Management Guidance vs. Observed Business Performance
Guidance and forward-looking statements: - Aim to reach approximately ₹10,000 crore of rental income in the medium term. - Expand DLF’s portfolio to 25% of the total portfolio from 10% currently. - Grow the retail portfolio to 15% of total portfolio size. - Launch pipeline for new products of approximately ₹60,000 crore in the medium term. - Expectation that requisite approvals for planned launches will be received soon. - Confidence in achieving stated medium-term growth goals.
Observed performance (Q1FY27, quarter ended 30 June 2026, results approved by the Board on 3 August 2026): - Consolidated revenue: ₹1,605 crore; gross margins: 51%; EBITDA: ₹476 crore; net profit: ₹794 crore (y-o-y growth of 4%); operating cash flow: ₹1,317 crore. - New sales bookings: ₹657 crore, reflecting the timing impact of deferred launches. - Collections: ₹2,406 crore. - Net cash position: ₹15,200 crore, with RERA 70% A/c at ₹11,305 crore. - DCCDL (DLF Cyber City Developers Limited) consolidated: revenue ₹1,917 crore; EBITDA ₹1,474 crore (y-o-y growth of 9%); net profit ₹717 crore (y-o-y growth of 21%); rental income ₹1,444 crore; net debt ₹18,136 crore. - Credit ratings: ICRA AAA/Stable and CRISIL AAA/Stable. - Rental portfolio: approximately 50 msf with occupancy of 95%.
Prior-year context (Fiscal 2026, per the Chairman’s Speech at the 61st AGM on 3 August 2026): - New sales bookings of ₹20,143 crore and net profit of ₹4,408 crore; annuity portfolio at approximately 50 million sq. ft.
The Q1FY27 sales bookings figure of ₹657 crore reflects the deferment of planned launches against a stated pipeline, while the company points to sustained customer demand and a defined launch pipeline in support of its medium-term growth goals. The annuity business shows continued momentum, with DCCDL net profit growing 21% y-o-y and occupancy at 95%, alongside the stated medium-term ambition of approximately ₹10,000 crore in rental income.
Other key facts: Executives of DLF Limited will participate in the 2026 Jefferies India Forum on 17 September 2026 in Gurugram for One to One and Group Meet sessions, with outcome intimations to be provided post-conclusion.
Broker Narrative
The broker narrative evolved from a technical, short-term Sell call in February 2021—citing weak volume, negative RSI divergence, and resistance at prior monthly tops—to a fundamental, medium-term Buy thesis in October 2026 anchored by pre-sales guidance, rental income targets, land bank depth, and net cash surplus. Early themes centered on chart-based momentum and exhaustion, while later reports emphasize operational execution in Gurgaon, high commercial occupancy, and phased revenue inflection from FY28. A persistent thread is caution around regional concentration and project execution risk, though the analytical lens shifted from price action to balance-sheet and cash-flow visibility.
Fears that came true
- The early headwind that DLF faced resistance at previous major tops and formed a spinning-top/double-top pattern found echo in later DISAPPOINTMENT outcomes where anticipated upside failed, such as the 2024-04-16 Buy call predicting +11.1% but delivering -19.0%.
- The flagged negative weekly RSI divergence and lack of volume support corresponded with repeated 2024-2025 buy recommendations that called for double-digit gains yet resulted in negative actual returns, exemplified by the 2025-01-28 Motilal Oswal Buy (+35.5% predicted vs -13.3% actual).
Broker Timeline
49 broker calls · 2021-02-15 to 2026-10-19
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.