DCAL
Equity Metrics
November 16, 2026
Dishman Carbogen Amcis Limited
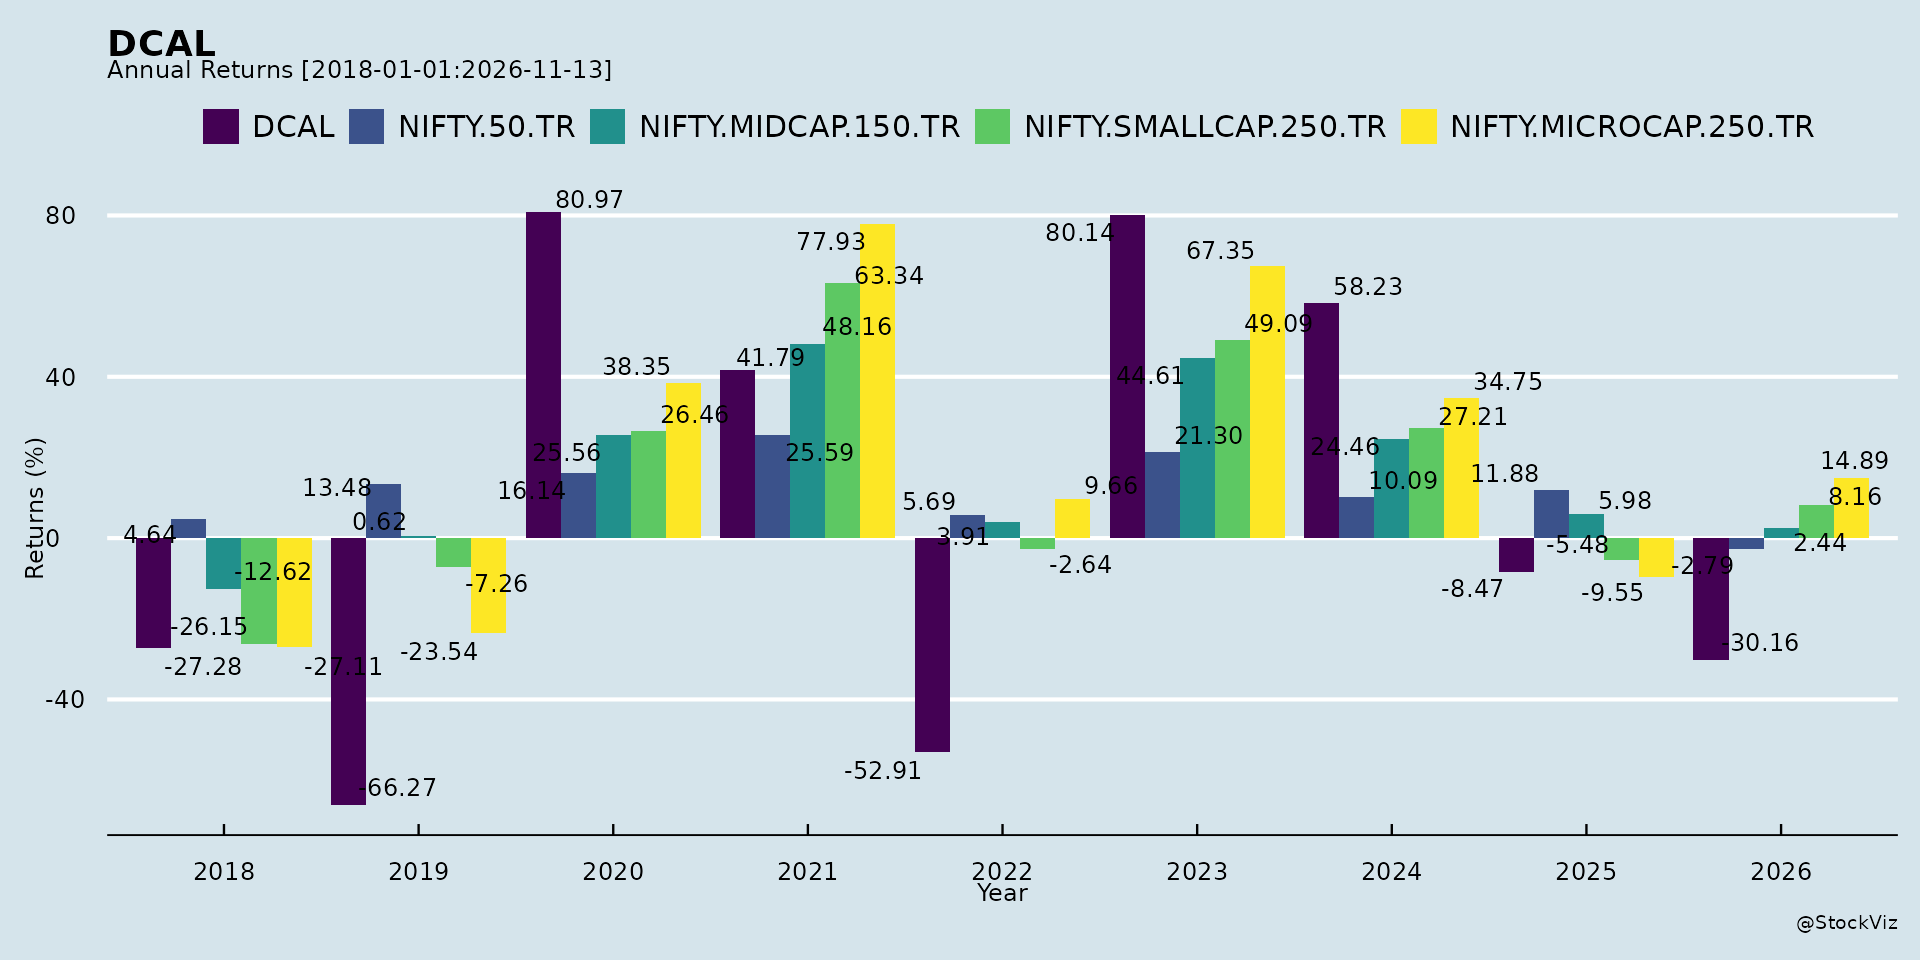
Annual Returns
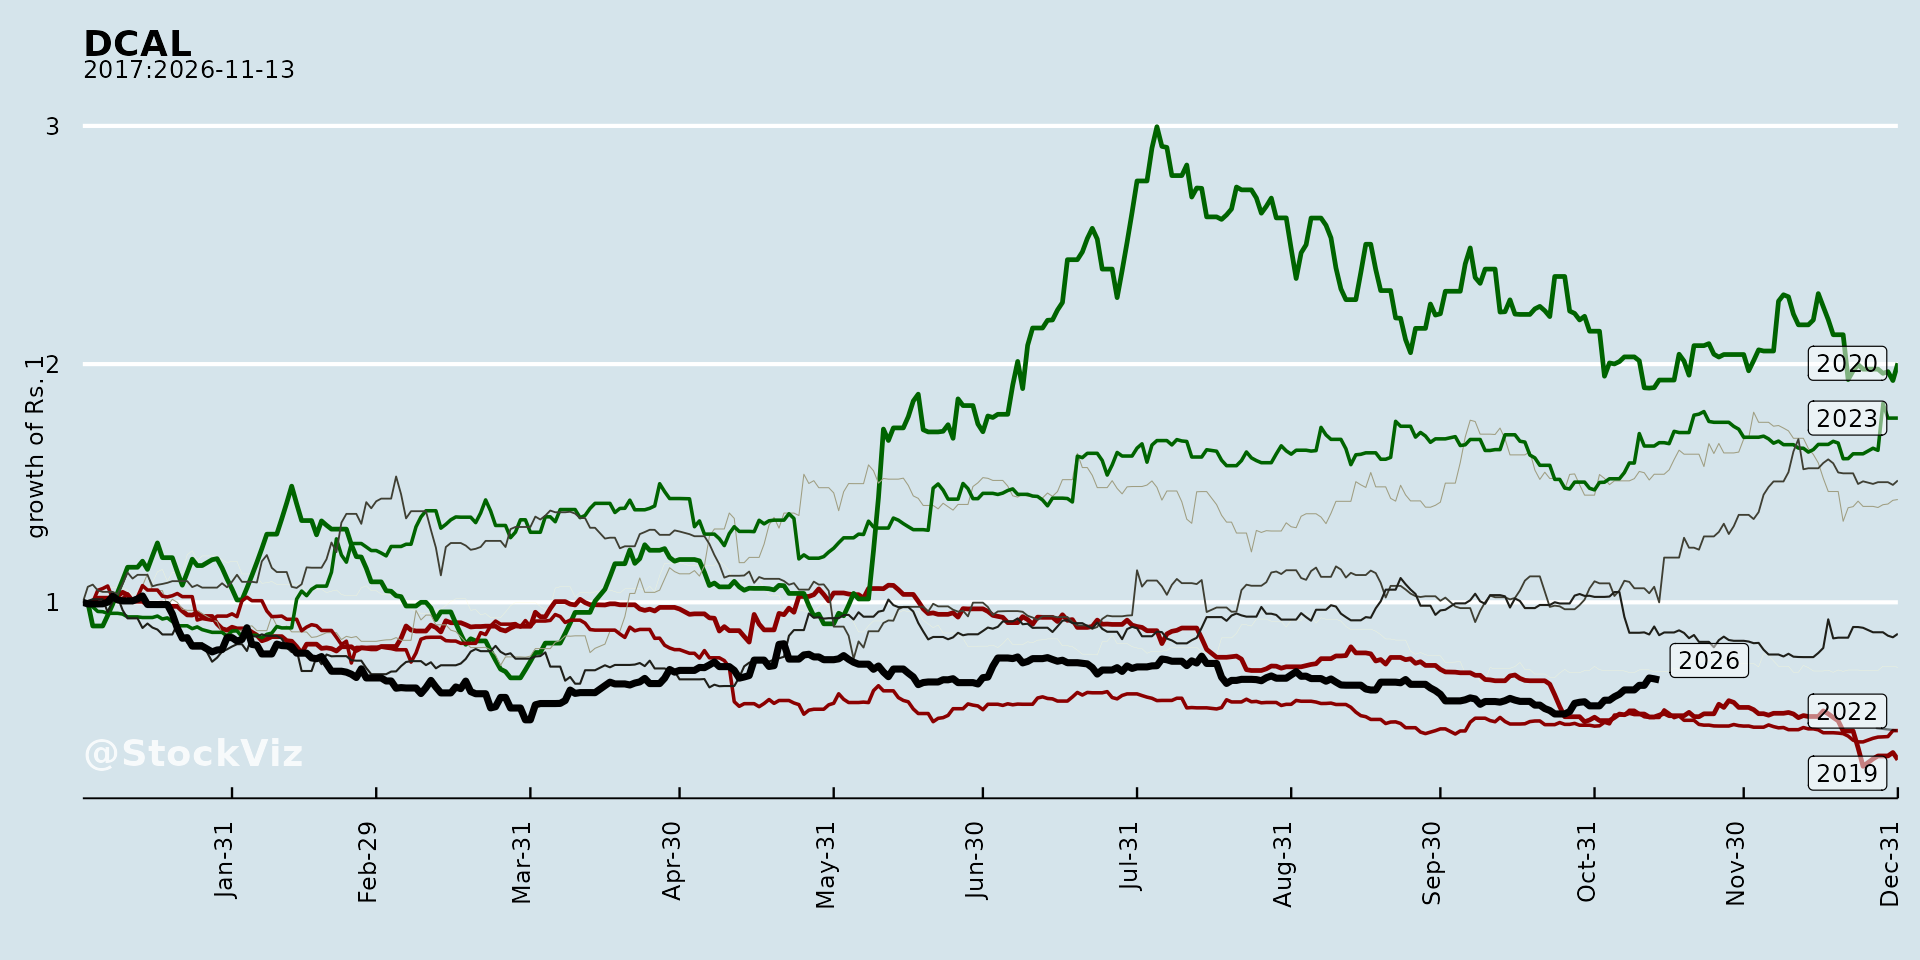
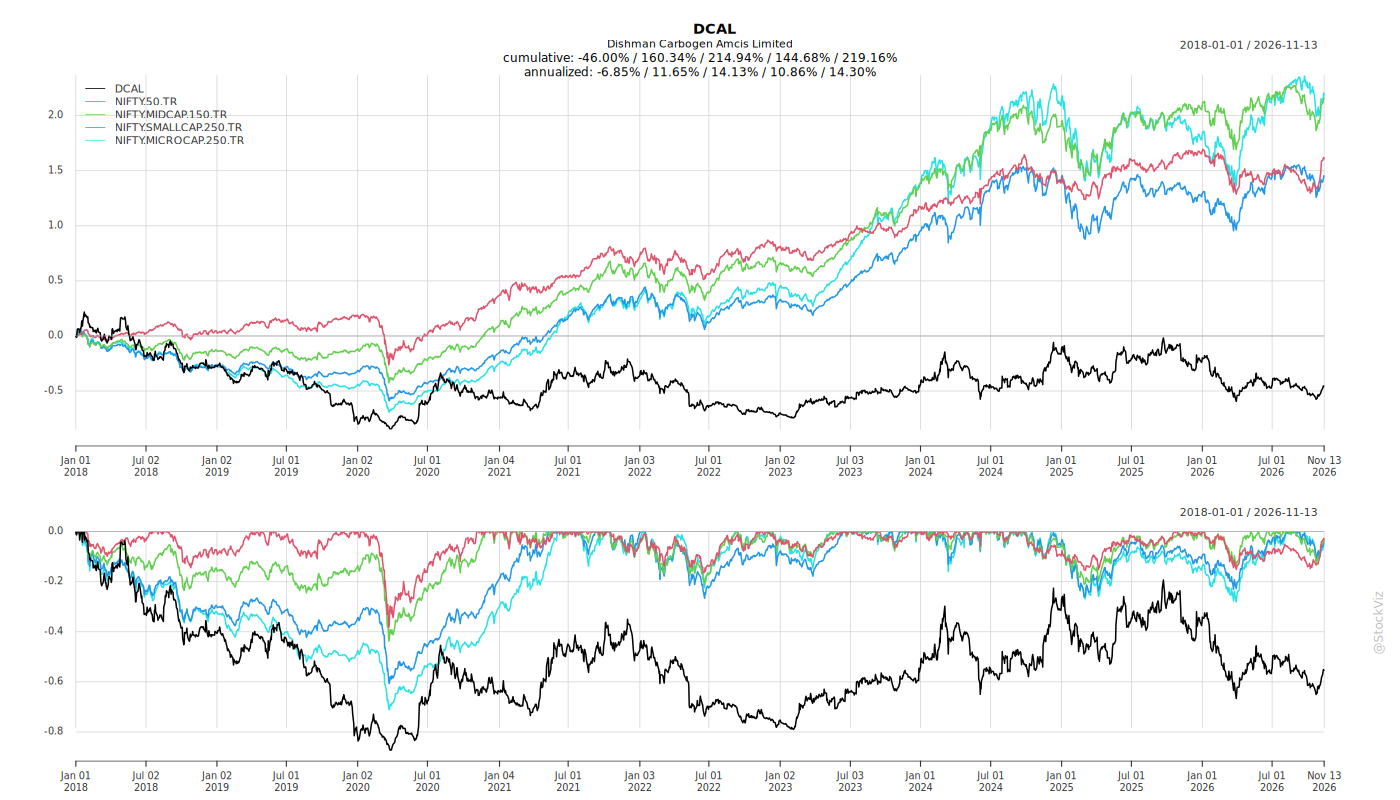
Cumulative Returns and Drawdowns
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-17
Dishman Carbogen Amcis — Q1 FY27 Earnings Summary
1. Headwinds and Challenges
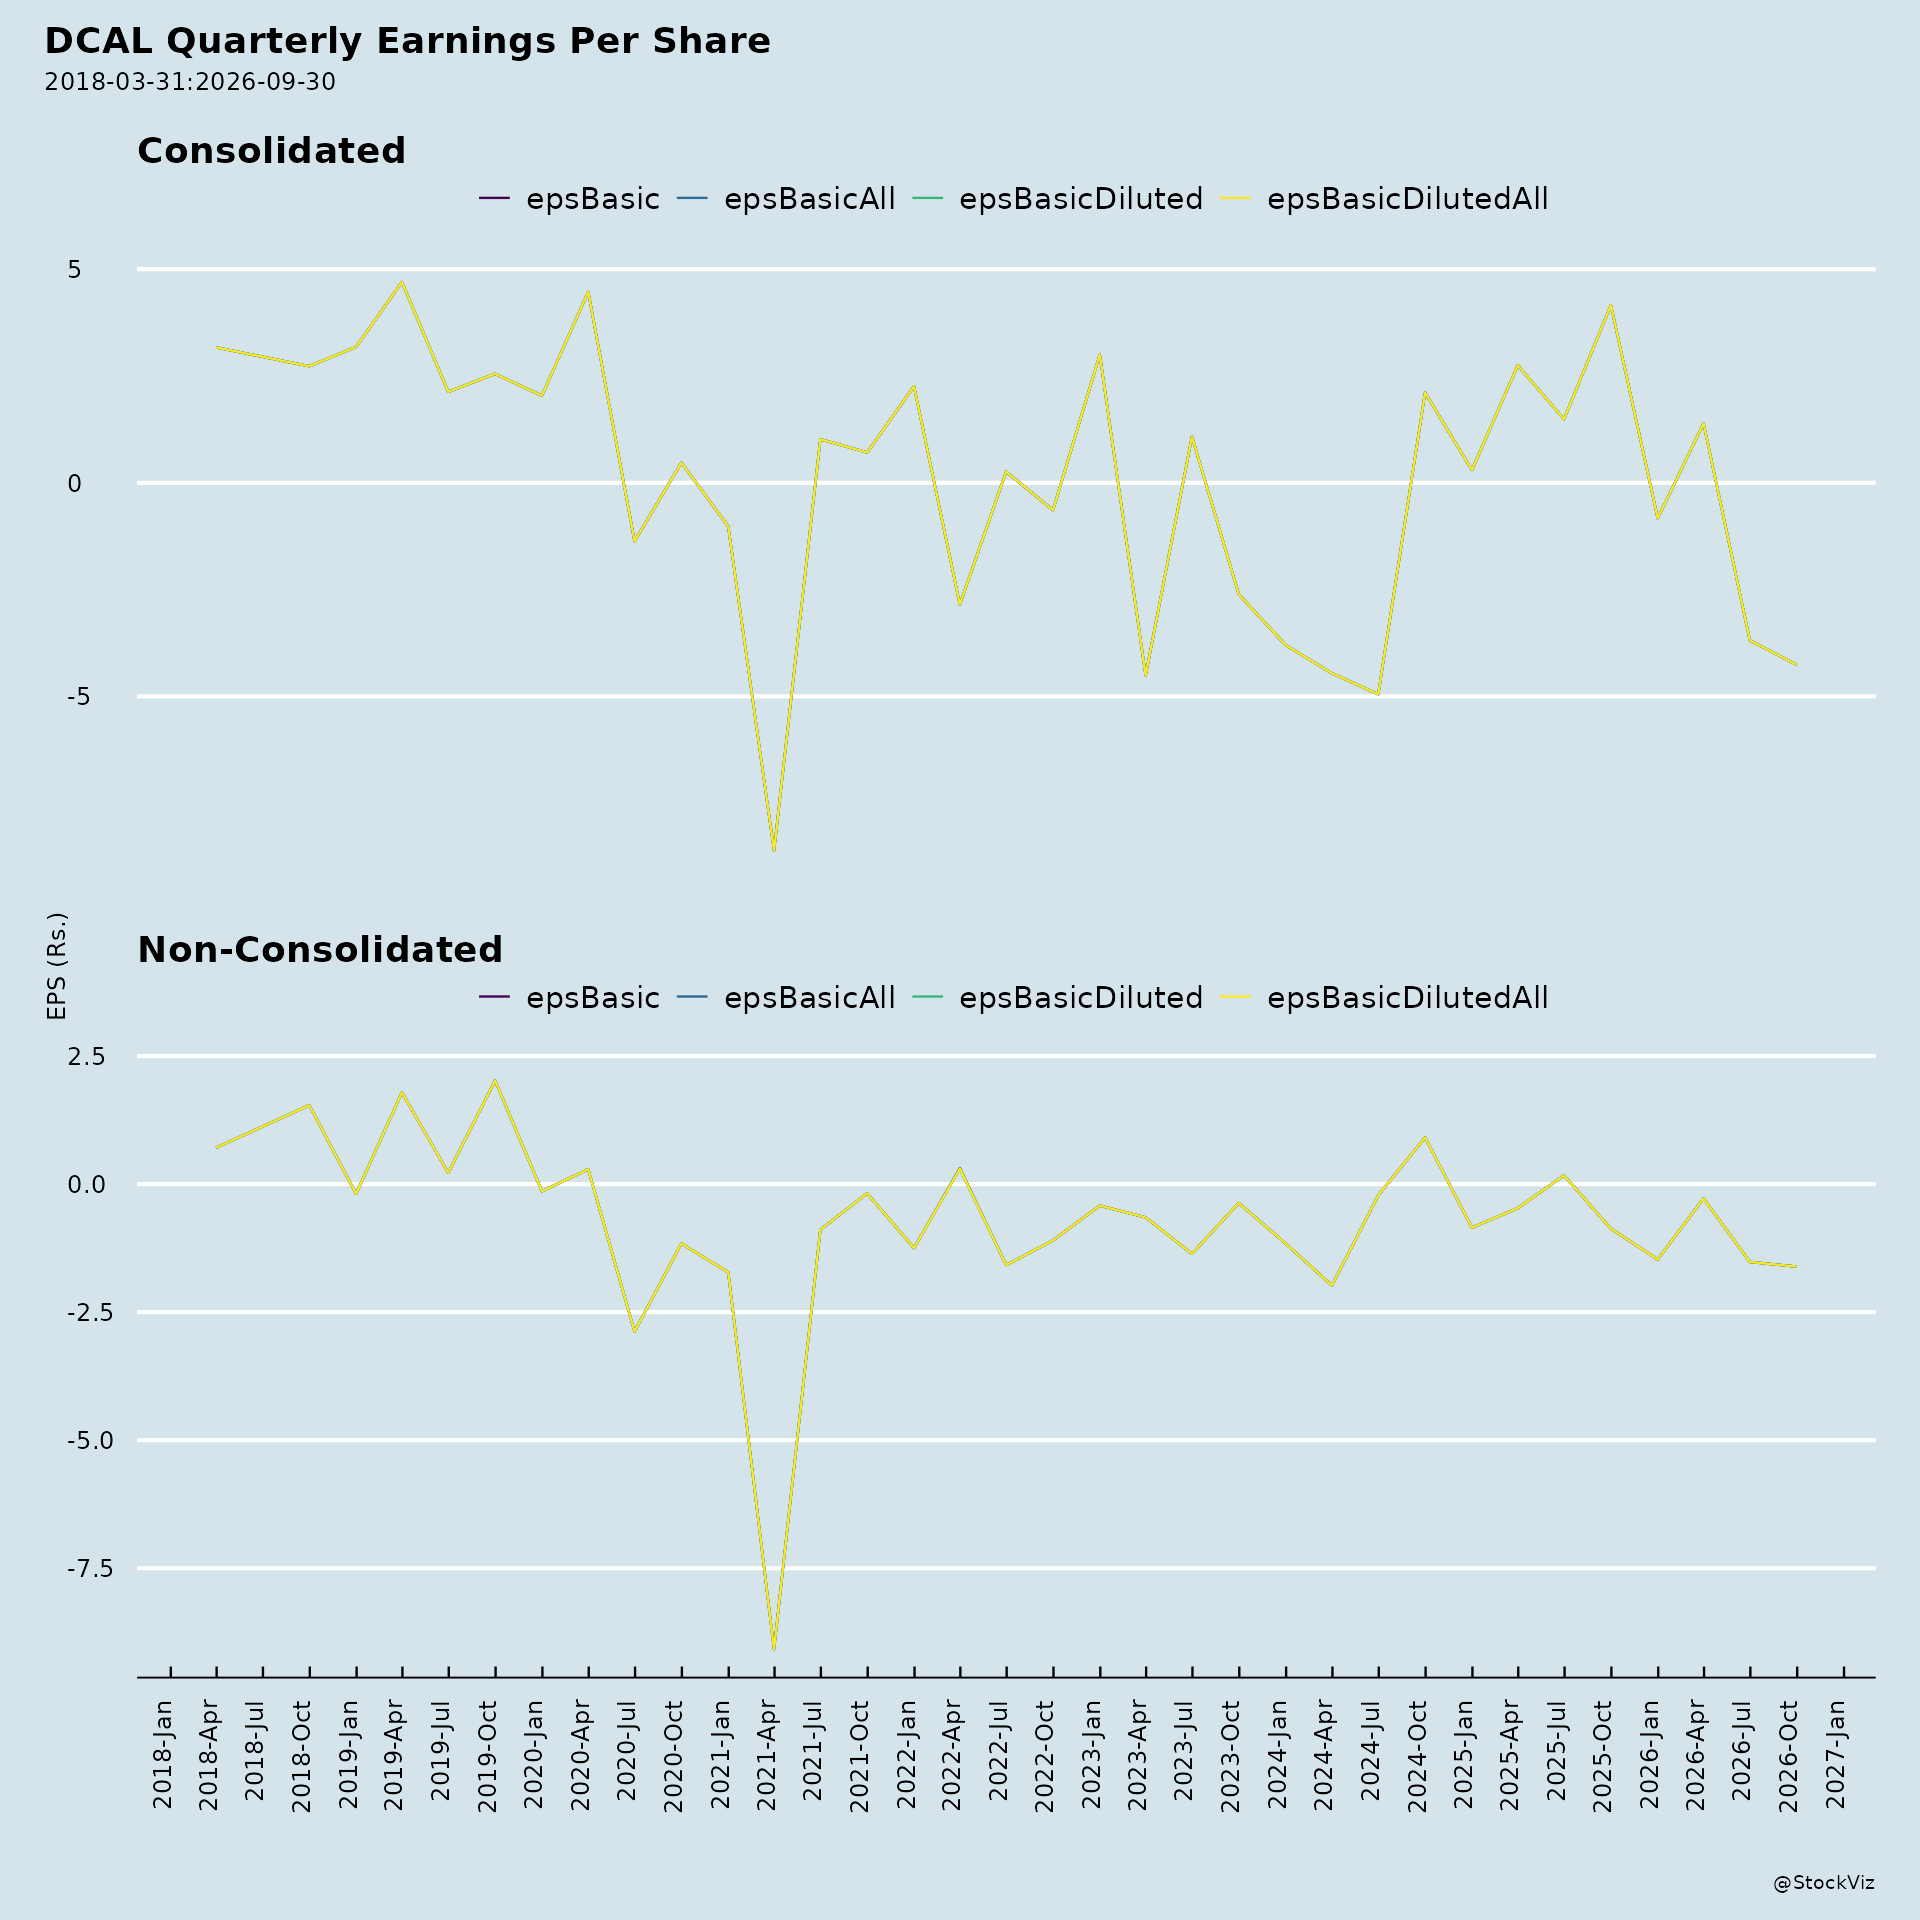
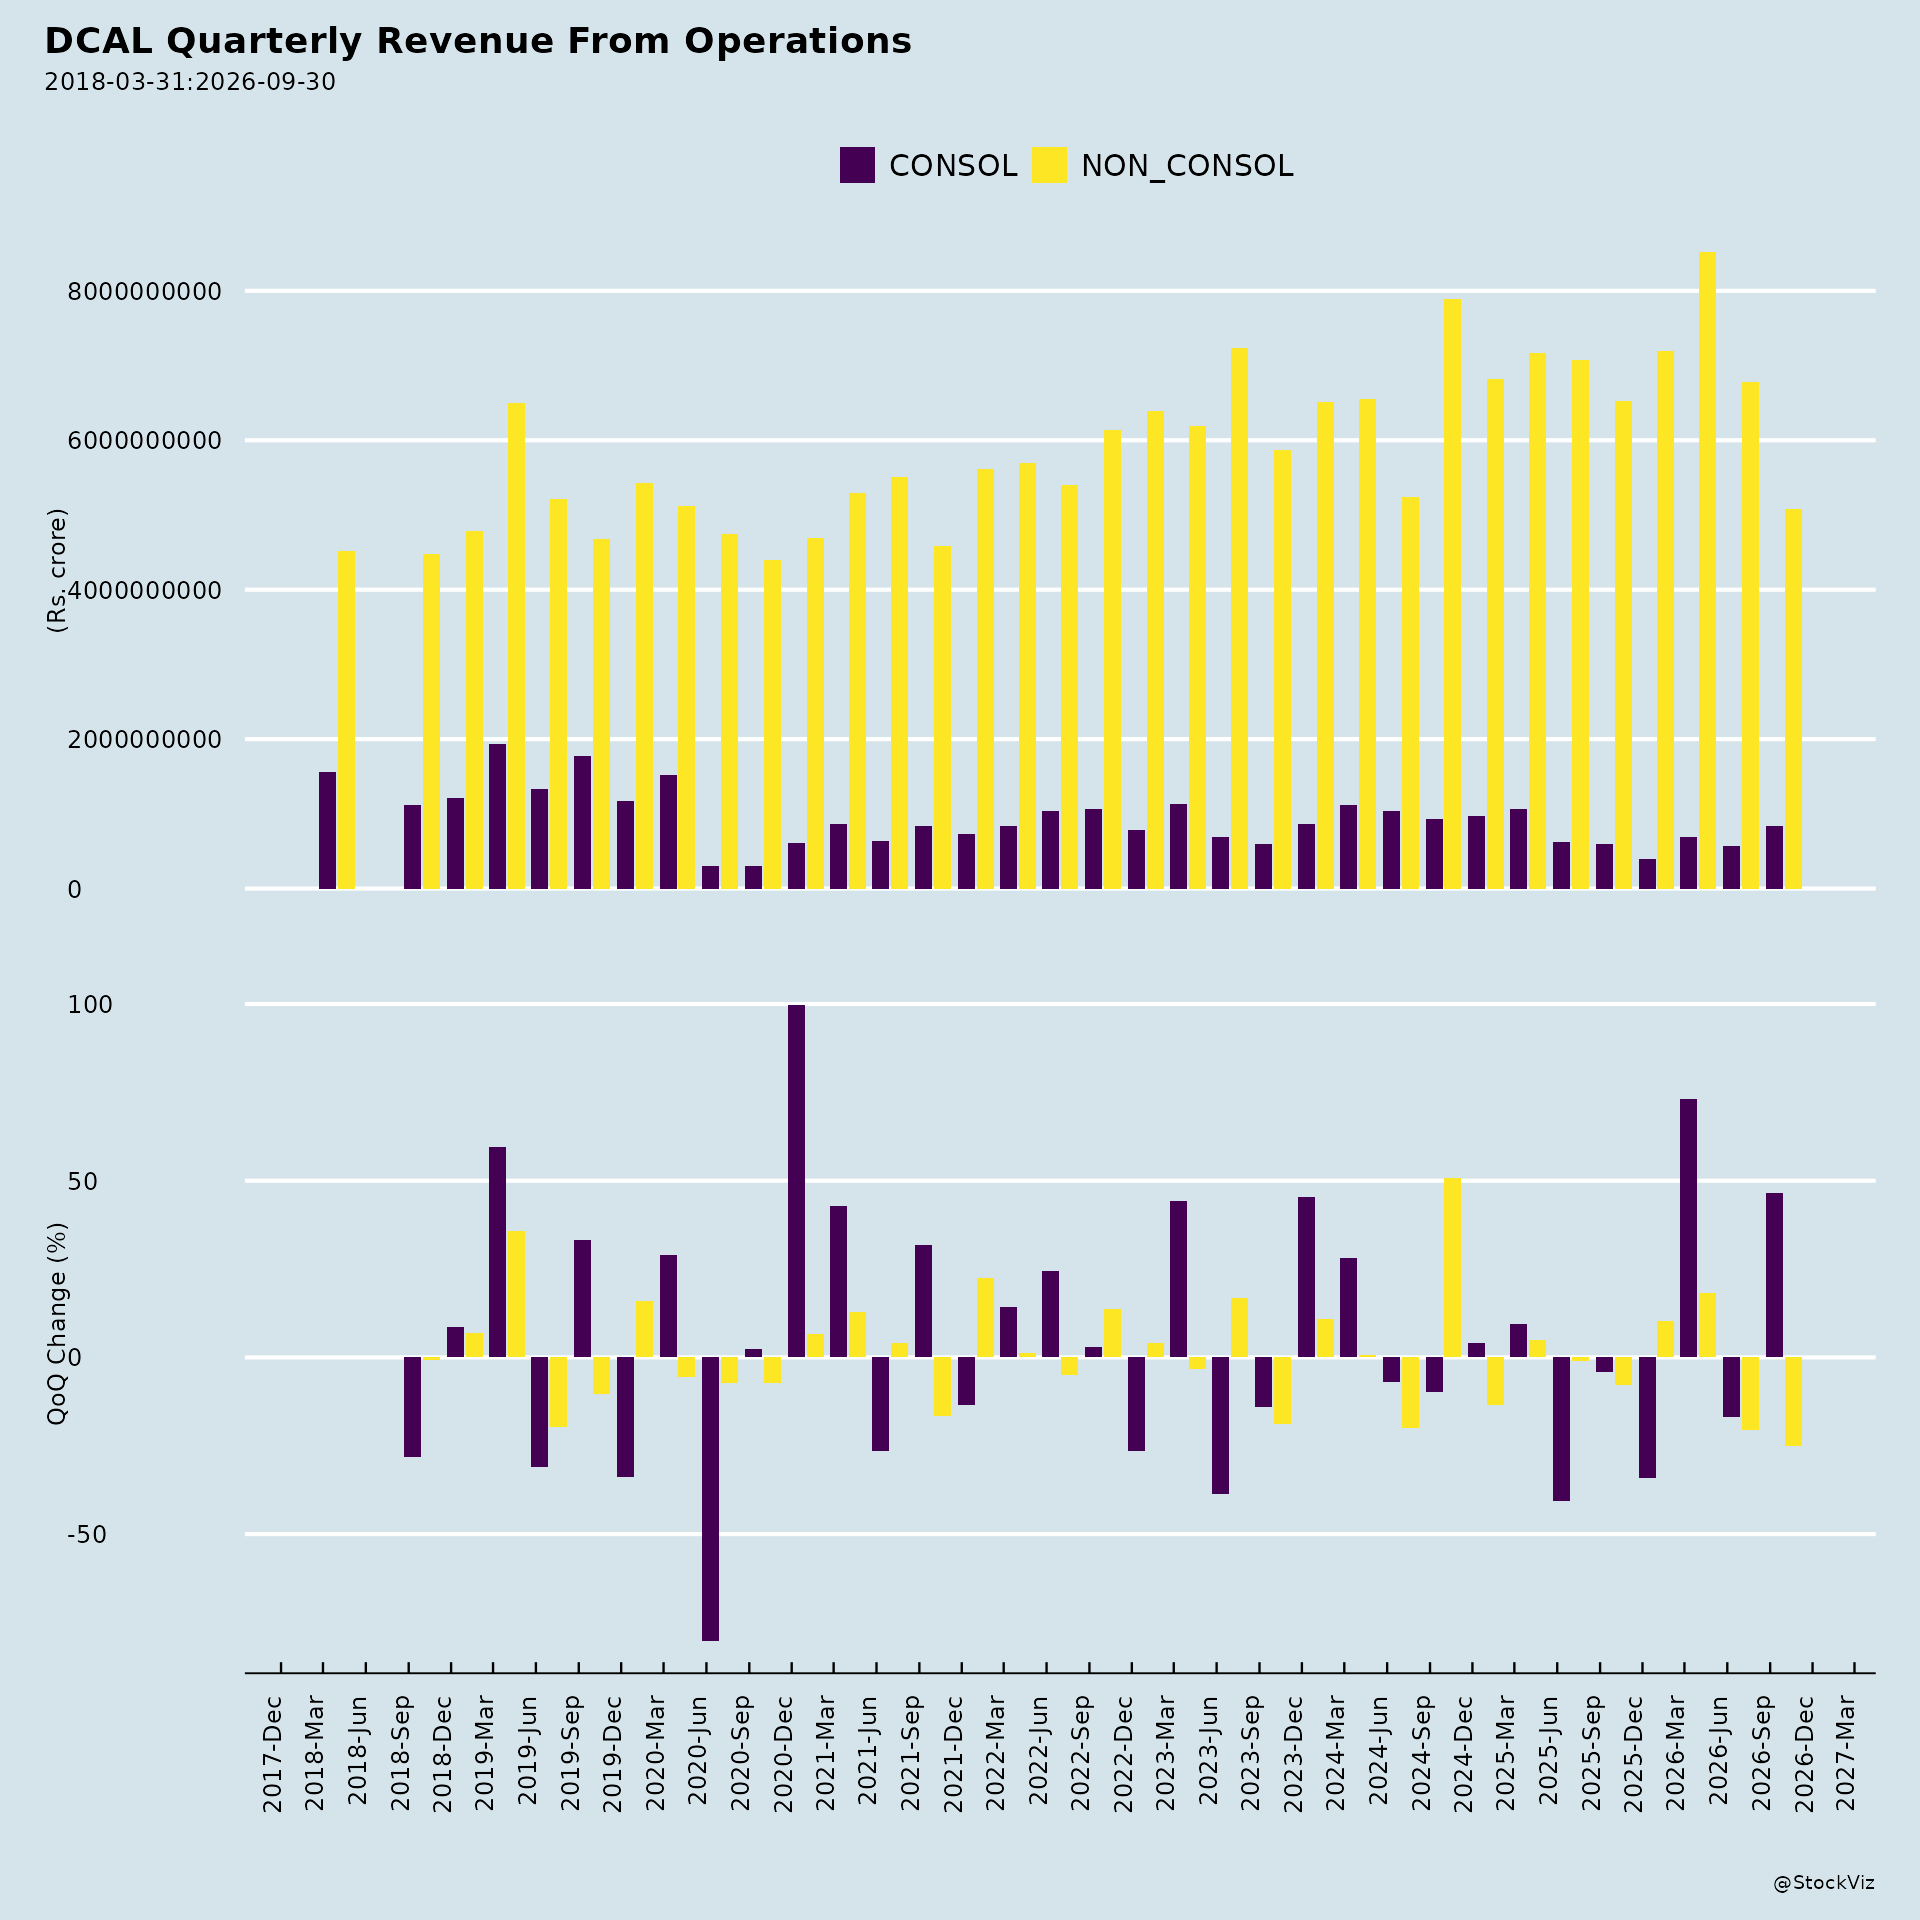
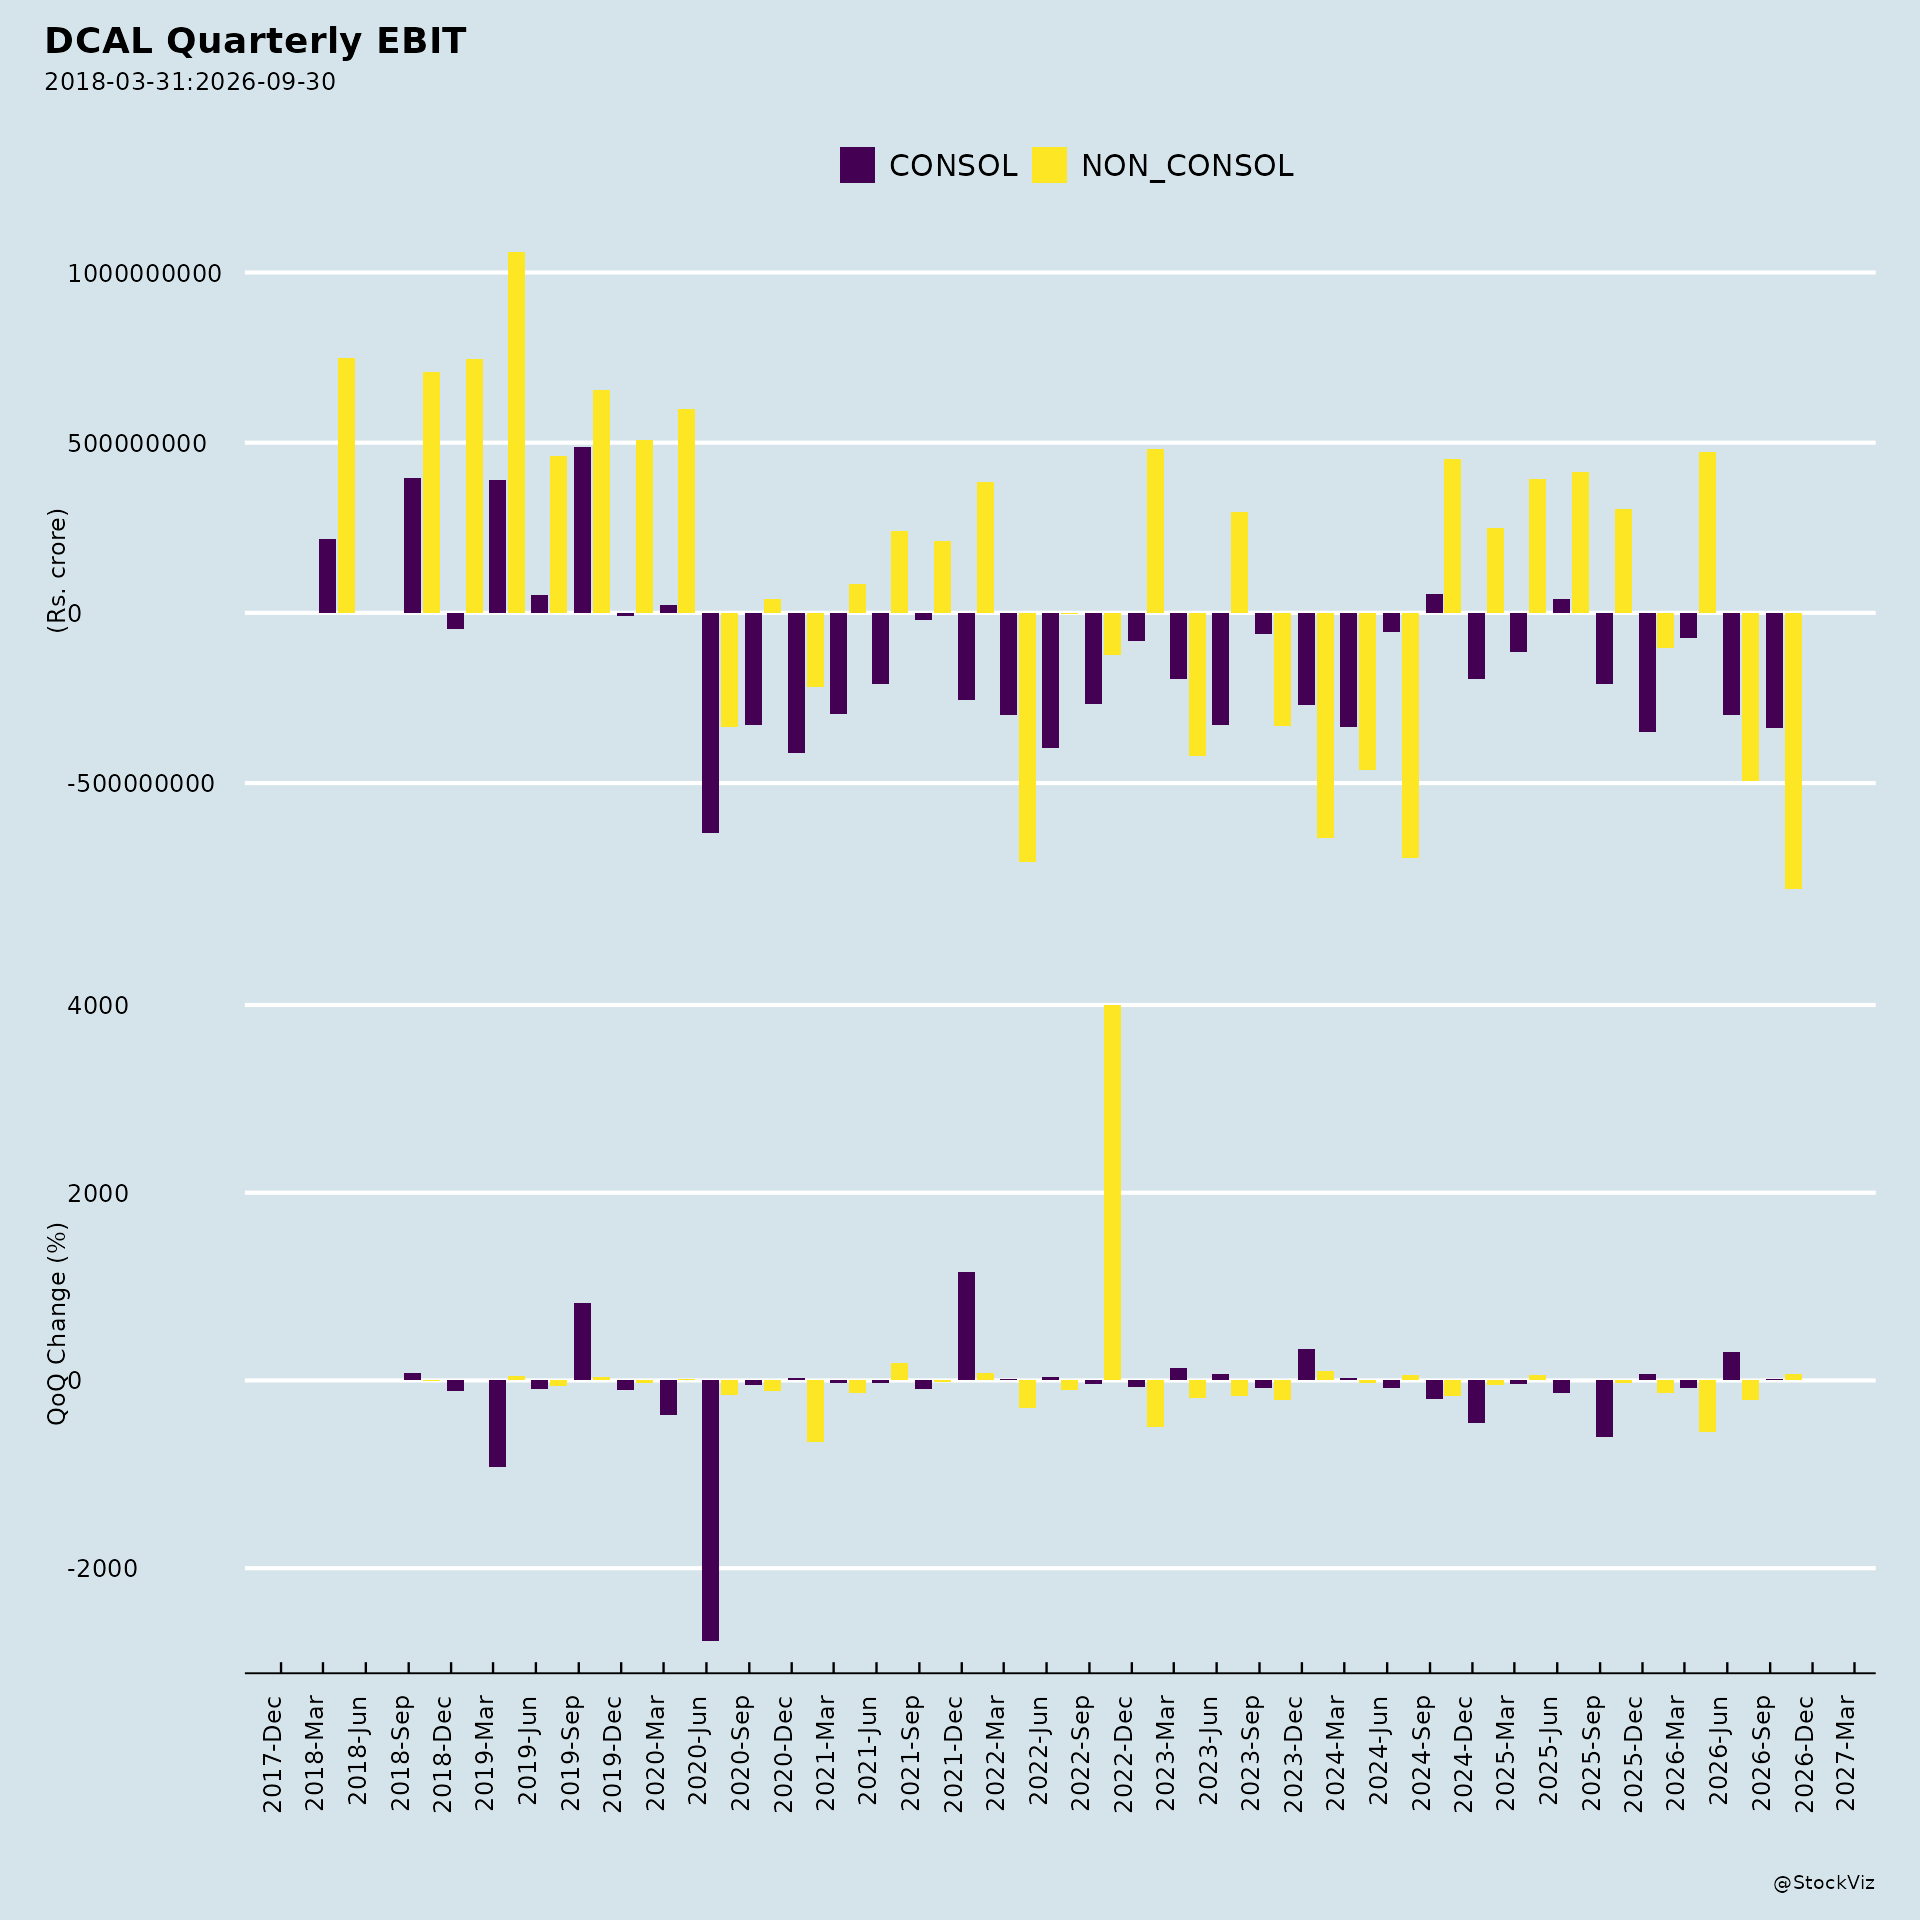
Soft Q1 FY27 performance. Consolidated revenue from operations for the quarter ended 30 June 2026 was INR 6,776 million, down 4% from INR 7,080 million in the comparable quarter of the prior year. EBITDA fell to INR 600 million from INR 1,406 million, and the company reported a loss before tax of INR 512 million and a net loss after tax of INR 578.8 million (consolidated). The standalone entity reported a net loss after tax of INR 239.1 million for the quarter.
Deferred order. Management attributed the revenue shortfall primarily to one order worth approximately INR 10 million (as stated on the call) that was postponed to the second half of the financial year from Q1. Because a large share of the cost base — notably employee costs at roughly 50% of the P&L — is fixed, the deferred revenue had a disproportionate impact on EBITDA.
Foreign exchange drag. A foreign exchange impact of approximately INR 117.3 million, mainly from USD/CHF fluctuation, weighed on other expenses.
Segment margin compression. The CDMO segment posted an EBITDA margin of 6.3% versus 17.9% a year earlier, driven by the revenue deferment and the forex loss. The Marketable Molecules segment margin normalized to 18.6% from 32% in Q1 FY26, when there had been a large amount of analogue sales; the current quarter reflected a higher mix of cholesterol sales.
French entity not yet at breakeven. Management stated that the French drug product entity is taking longer than expected to reach breakeven, with revenue conversion from increased RFPs potentially slipping into the next financial year.
Biotech funding slowdown. Management noted a slowdown in funding for biotech companies, who are the main customers for development work at the Swiss CDMO entity.
Destocking. Post-pandemic customer destocking is still being observed.
QoQ lumpiness. Management acknowledged that the B2B, new-chemical-entity nature of the business makes quarterly results inherently lumpy, with Q4 historically the strongest quarter because it aligns with customers’ budget cycles, and Q3 historically weak.
Abandoned QIP. Exceptional items of INR 1.69 crores in the quarter represent transaction costs for a proposed QIP of equity shares. These costs were incurred in the previous financial year and written off in the current quarter after management decided to abandon the issue due to adverse market conditions and an altered fundraising plan.
High-cost debt in India. Management acknowledged that roughly one-third of operating profit goes toward finance costs. Bulk of cash sits at the Swiss entity level, and regulatory restrictions prevent a subsidiary from lending to the parent, so that cash cannot be used to pay down Indian debt; it is instead held as deposits against lower-cost overseas borrowings.
Goodwill amortization. Standalone goodwill of INR 579.32 crores remains outstanding as of 30 June 2026. The Board revised the useful life of goodwill to 99 years effective 1 January 2015, applicable prospectively from 1 April 2024, with impairment testing at each financial year end. Had goodwill not been amortized, depreciation and amortization for the quarter would have been lower by INR 1.65 crores.
2. Tailwinds and Growth Prospects
Commercial product approval. A new commercial product from a big pharma customer was approved by the U.S. FDA, adding another commercial product to the portfolio. This occurred just four days before the 17 August call, not within Q1. Management described the molecule as promising and noted it received accelerated approval, but said it was premature to quantify incremental revenue pending customer forecasts.
Late-phase pipeline expansion. More than 13 late-phase projects, including PPQ campaigns, are now in the portfolio. Three late-phase molecules were added in the prior quarter as they were promoted from Phase I/II into Phase III. ADC-related molecules with higher priority status at the FDA were also secured.
Regulatory clearances. The Naroda site successfully completed an MFDS (Republic of South Korea) inspection. Both Bavla and Naroda sites now hold certifications from all major international health authorities. Dishman Carbogen Amcis Limited was granted two CEPs from EDQM in Europe, and two new liquid softgel drug products were approved in Myanmar.
Tech transfers from Switzerland to India. A commercial contract was signed with a U.S. company to tech transfer a legacy project from Switzerland to the Bavla site, with completion targeted within the financial year. A second major legacy project tech transfer was approved by a prominent Swiss MNC and has been initiated. Three further tech transfers from Switzerland to India are in advanced discussion. Management framed these as active life cycle management of commercial products, benefiting customers through lower prices while supporting group margins.
Japanese client co-investment. The co-investment with the Japanese client is proceeding on track, with operations expected in the course of the next calendar year. Management noted the customer has received multiple approvals across geographies and that the second co-investment will add capacity to supply additional quantities.
Specialty business strength. The cholesterol, Vitamin D, and analogues business developed well in Q1, with the VDA business increasing both sales and margin. New wool grease sources at more attractive prices were accessed, and new markets for cholesterol and Vitamin D derivatives were penetrated in Vietnam, Africa, and South America. Cost reduction programs are ongoing and showing first signs.
Commercial organization build-out. Angela Ameriks was appointed Global Chief Commercial Officer, bringing decades of CDMO experience including prior roles at Hovione and Lonza. New sales leadership was hired for India, and recruiting is underway for roles in the UK, Central Europe, and the U.S. West Coast (a hire starting 1 September). Inside sales and prospecting roles are also being added.
SPRINT initiative. The initiative to acquire early-phase projects at Carbogen Amcis is described as successful, with promising projects acquired. The packaged drug substance product continues to be promoted, with high interest in the bioconjugation space.
CDMO inquiry momentum. Naroda is seeing a steep increase in RFPs, with several in final negotiation, plus semiconductor-related CDMO business for Japan and fine chemical projects for Europe. Bavla is seeing large projects primarily through the Carbogen Amcis connection. The company is also exploring analytical services for customers and restarting some API work for the Netherlands entity.
Softgel growth. The softgel drug cooperation business has grown significantly over the last year, with interest from many customers in India and abroad.
Microcyclic peptide launch. Naroda supported the launch of a microcyclic peptide in the U.S. market in July, with the U.S. multinational formally acknowledging Carbogen Amcis’s contribution.
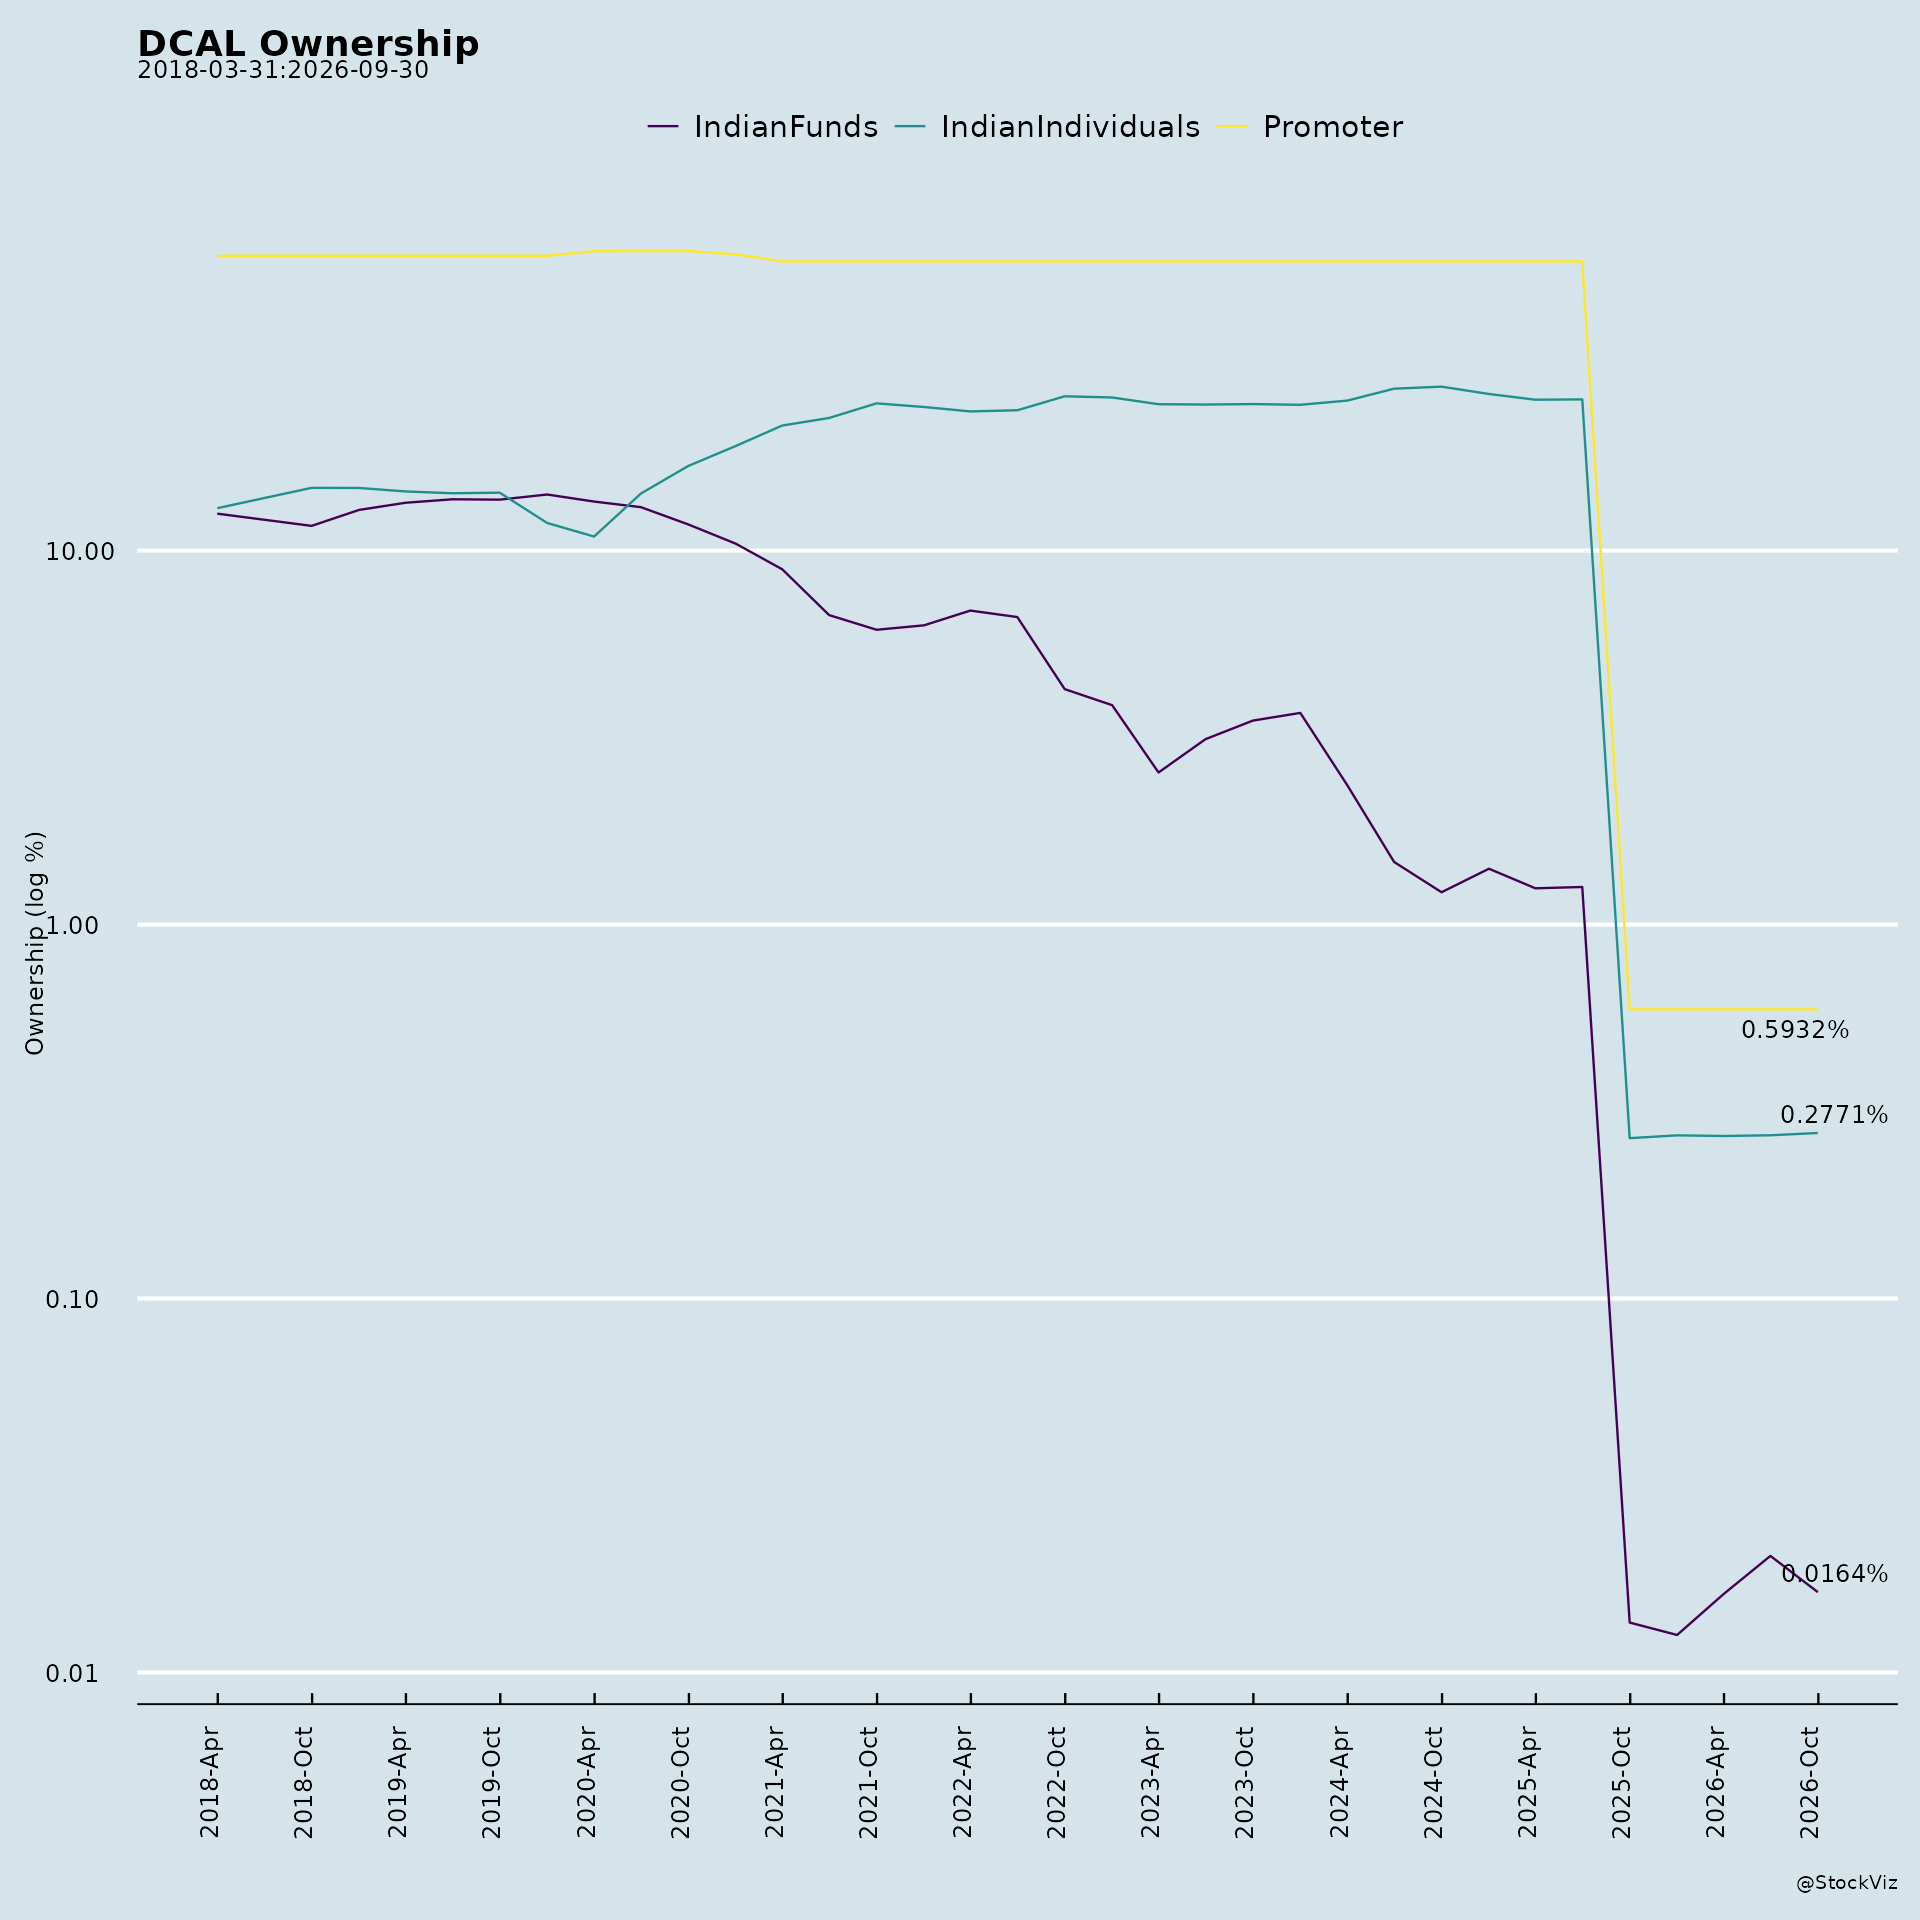
Fundraise for debt reduction. Shareholders approved raising up to CHF 200 million in foreign currency at the promoter entity level for infusion into the Indian entity as an external commercial borrowing. The interest cost is 4% all-inclusive with a 10-year tenor. RBI approval has been obtained. Management expects conclusion within 60–90 days, with funds used to prepay high-cost Indian debt and finance future capex or working capital. The promoter entity will raise funds largely against personal assets and guarantees; there is currently no plan to pledge listed shares, though a brief or smaller pledge could occur if required.
3. Key Risks
Quarterly earnings volatility. Management explicitly stated that QoQ swings are inherent to the business model, which involves 700–800 programs across development phases, and recommended evaluating performance on a two-to-three-year or at minimum annual basis.
Customer concentration and demand timing. Shipments are driven by customer demand and molecule performance, making revenue timing difficult to predict. The Q1 deferment illustrates this exposure.
Regulatory and inspection risk. Inspections are scheduled for later this year, with more information to be communicated when they occur. Historical EDQM observations at the Bavla site were referenced as a prior constraint on performance.
Forex exposure. USD/CHF fluctuation materially affected the quarter, and foreign exchange fluctuation in respect of cash flow hedges is a recurring other comprehensive income item.
Debt and refinancing execution risk. The promoter-level fundraise involves condition precedents, bank diligence, and multi-jurisdiction documentation. Management cited July–August European holidays as a factor in the 60–90 day timeline. Existing NCDs carry prepayment lock-ins and penalties that affect refinancing flexibility.
Goodwill impairment testing. Consolidated goodwill exceeds INR 4,000 crores and is tested for impairment annually using external valuation reports. Standalone goodwill of INR 579.32 crores is amortized over a 99-year life with annual impairment testing.
Biotech funding environment. Continued weakness in biotech funding could delay conversion of early-phase and SPRINT projects into revenue.
French entity breakeven timing. Continued delay in reaching breakeven at the French injectables plant would weigh on group performance.
4. Management Guidance vs. Observed Performance
FY27 group revenue guidance: single-digit growth. Management guided to single-digit revenue growth for the full group in FY27. Observed Q1 performance was a 4% decline in consolidated revenue from operations versus the comparable quarter. Management attributed the gap to the deferred order and maintained the full-year guidance.
FY27 EBITDA margin guidance: similar to last year, possibly slightly higher. Observed Q1 consolidated EBITDA was INR 600 million versus INR 1,406 million a year earlier, with the CDMO segment margin at 6.3% versus 17.9%. Management stated it is fairly confident of achieving an EBITDA margin at least similar to last year, and emphasized that incremental top-line revenue would translate disproportionately to EBITDA given the fixed cost base.
India entity FY27 guidance: revenue up at least 30–35%, operating margin close to 10%. Observed standalone Q1 revenue was INR 570.8 million versus INR 628.6 million a year earlier, with an operating margin of negative 20.71% and a net loss after tax of INR 239.1 million. The standalone interest service coverage ratio was 0.85 times and the debt service coverage ratio was 0.21 times.
FY28–FY29 aspiration: more than 10% YoY revenue growth and EBITDA margin closer to 25–26%. Management cited expected double-digit growth in the French entity and India operations, and a return to margins seen prior to the EDQM issues at the Indian sites. No FY28–FY29 performance has yet been observed.
Net debt guidance: CHF 140–150 million, reducing by roughly CHF 8–9 million. Observed net debt excluding lease liabilities was CHF 153.6 million as of 30 June 2026. Q1 capex was CHF 4.9 million.
Interest expense guidance: INR 35–40 crores per quarter, roughly INR 130–140 crores for the full year. Observed Q1 consolidated finance cost was INR 37.09 crores, within the guided quarterly range.
Q2 FY27 guidance: not provided. Management declined to give quarterly guidance, stating it can provide full-year and three-year guidance but not Q2.
Fundraise timeline: 60–90 days. Shareholder approval was obtained, RBI approval is in place, and management stated the fundraise is being worked upon with conclusion expected in the next 60–90 days. As of the call date, the funds had not yet flowed.
Japanese co-investment: operational in the course of next year. Management stated the co-investment is on track and expects operations in the course of the next calendar year. No operational milestone has yet been observed.
ADC revenue. Q1 ADC revenue was approximately INR 150 crores, including linker, payload, and hyper molecule.
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.