DALBHARAT
Equity Metrics
November 18, 2026
Dalmia Bharat Limited
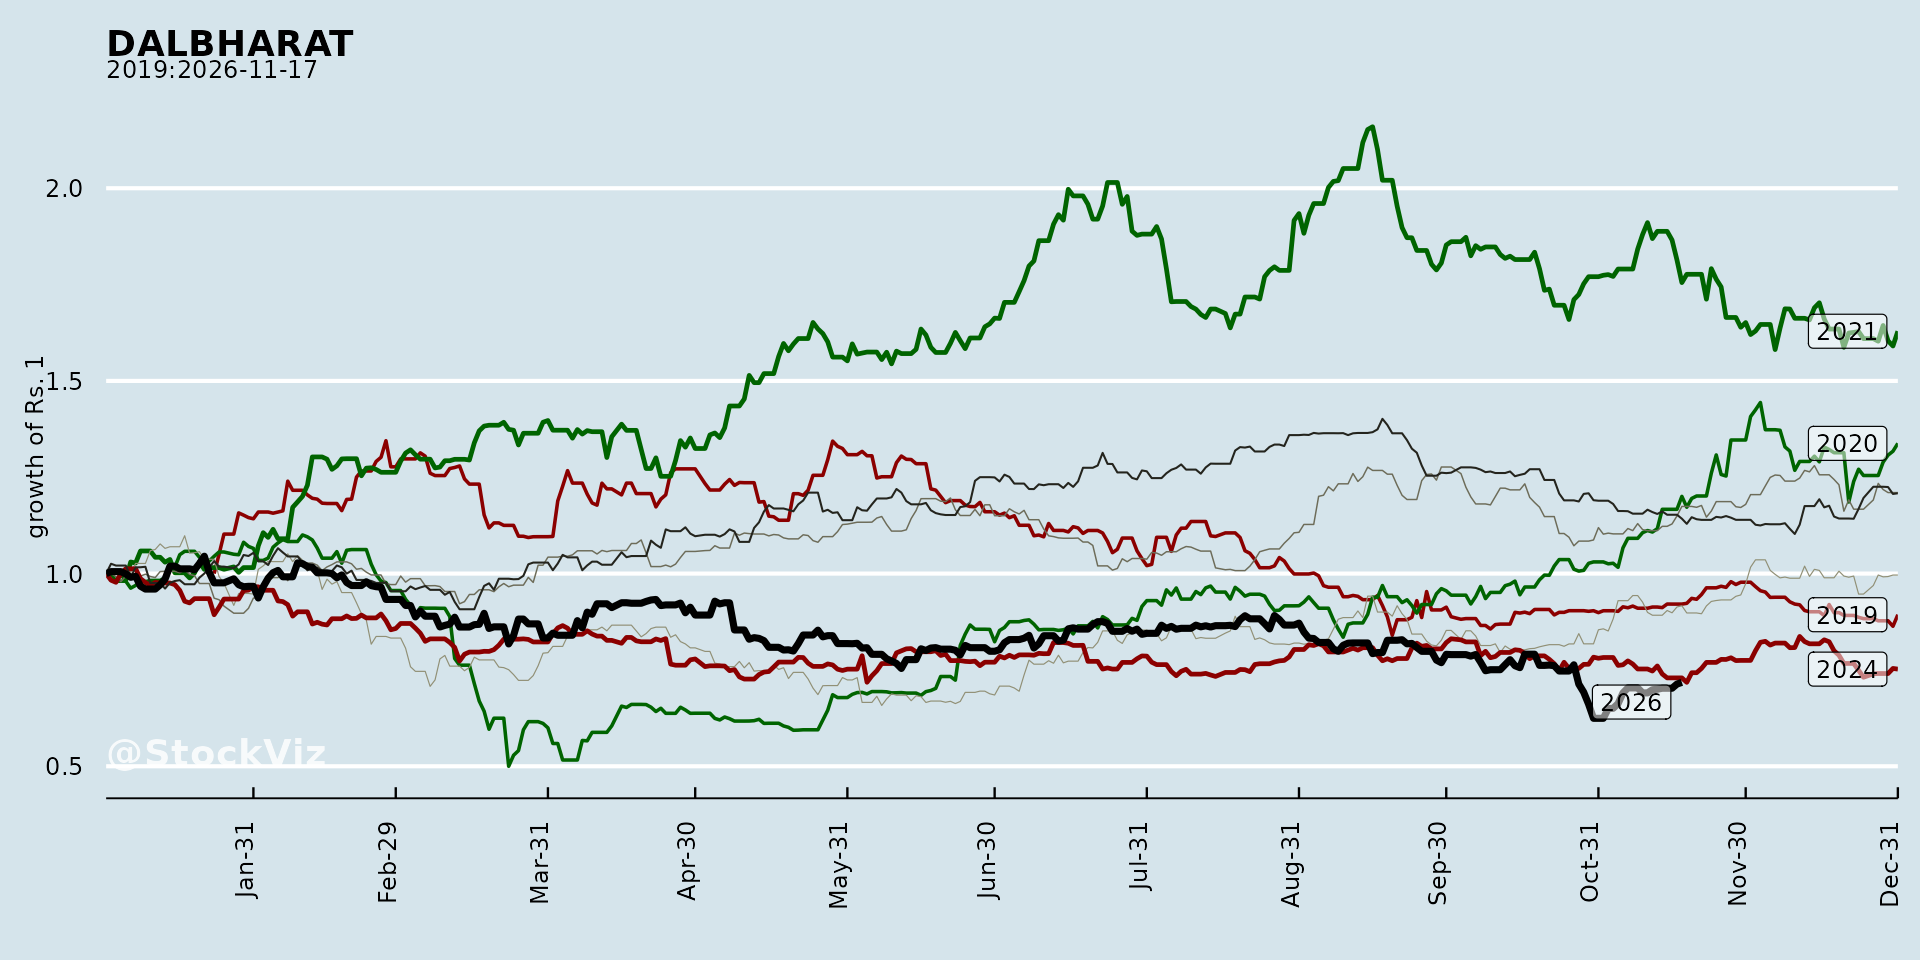
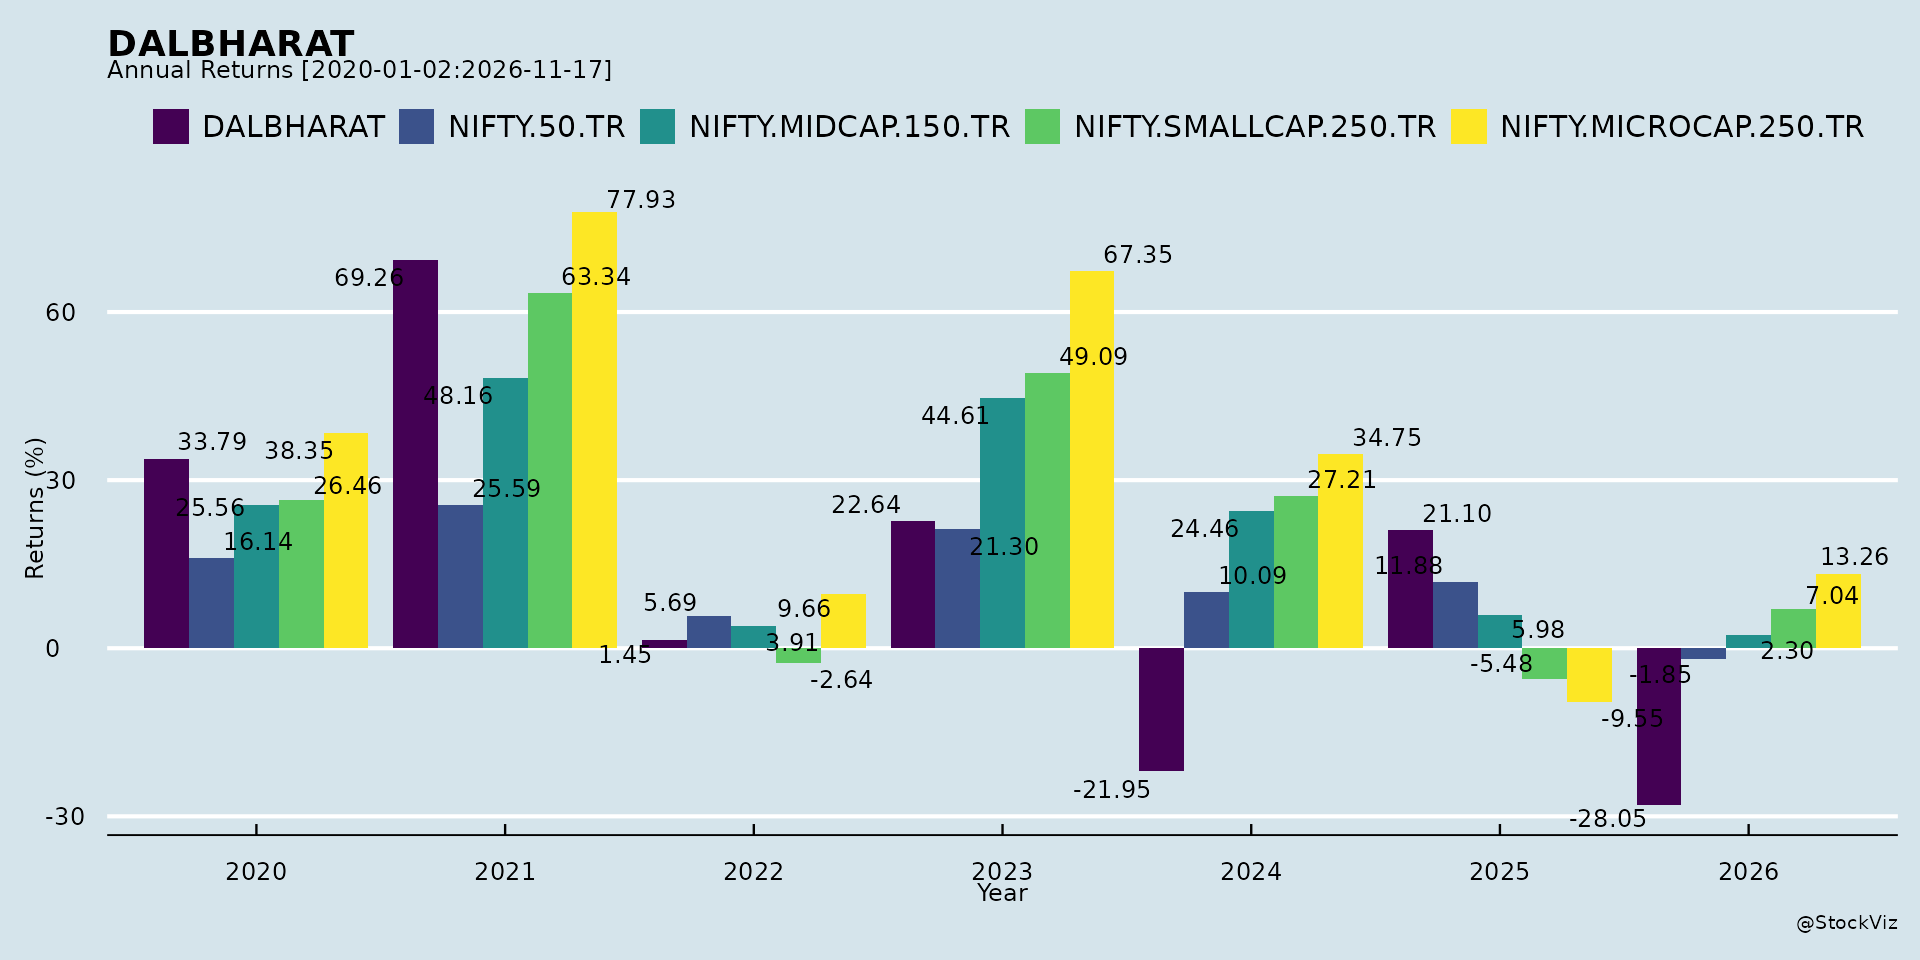
Annual Returns
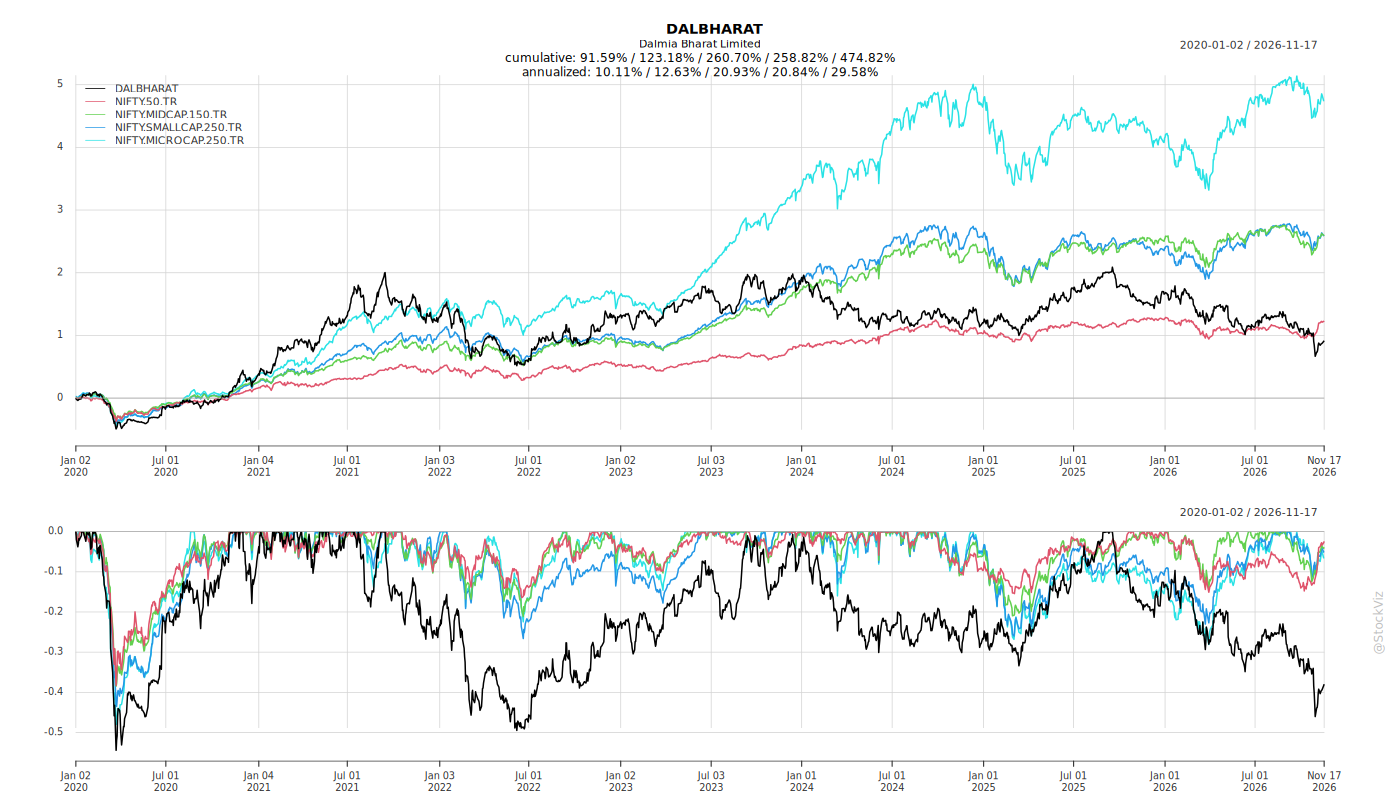
Cumulative Returns and Drawdowns
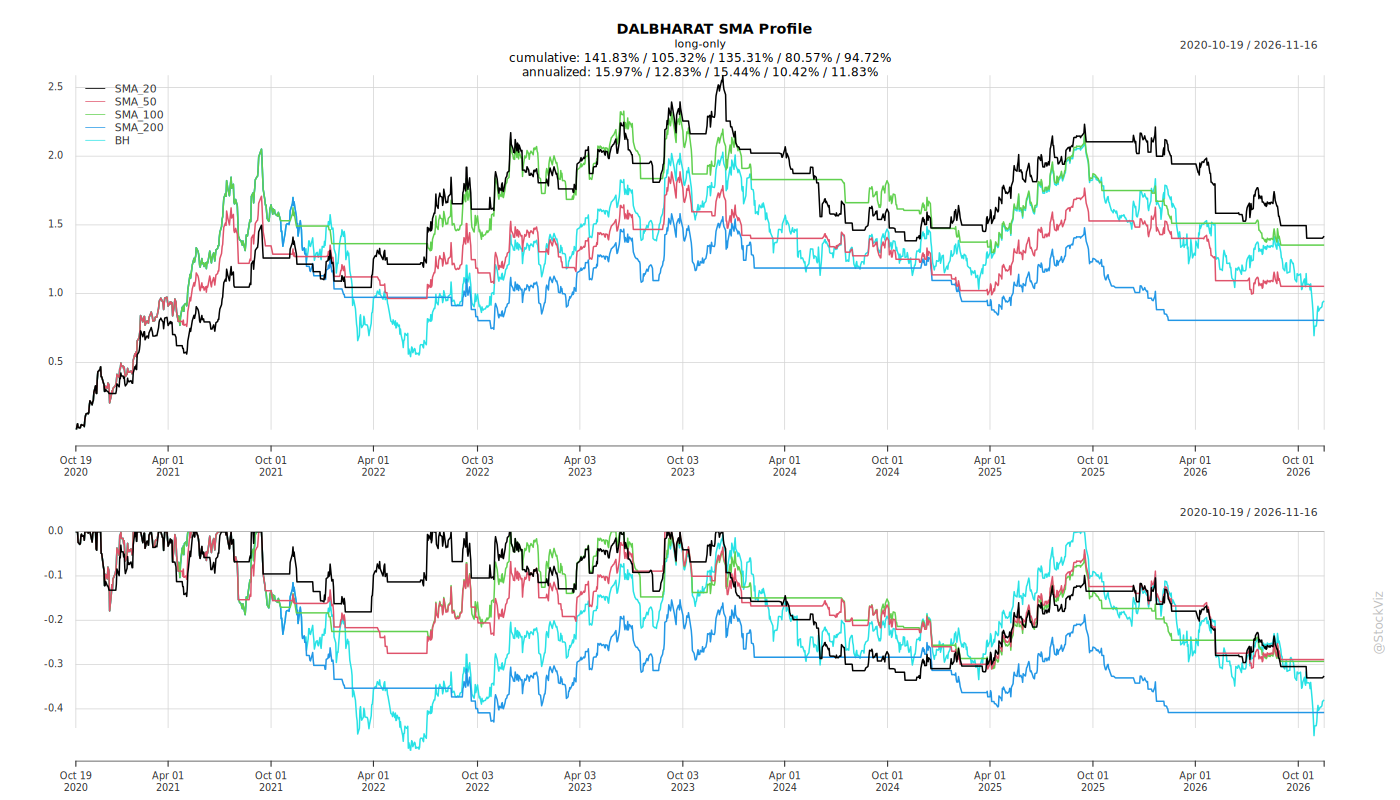
Fundamentals
Ownership
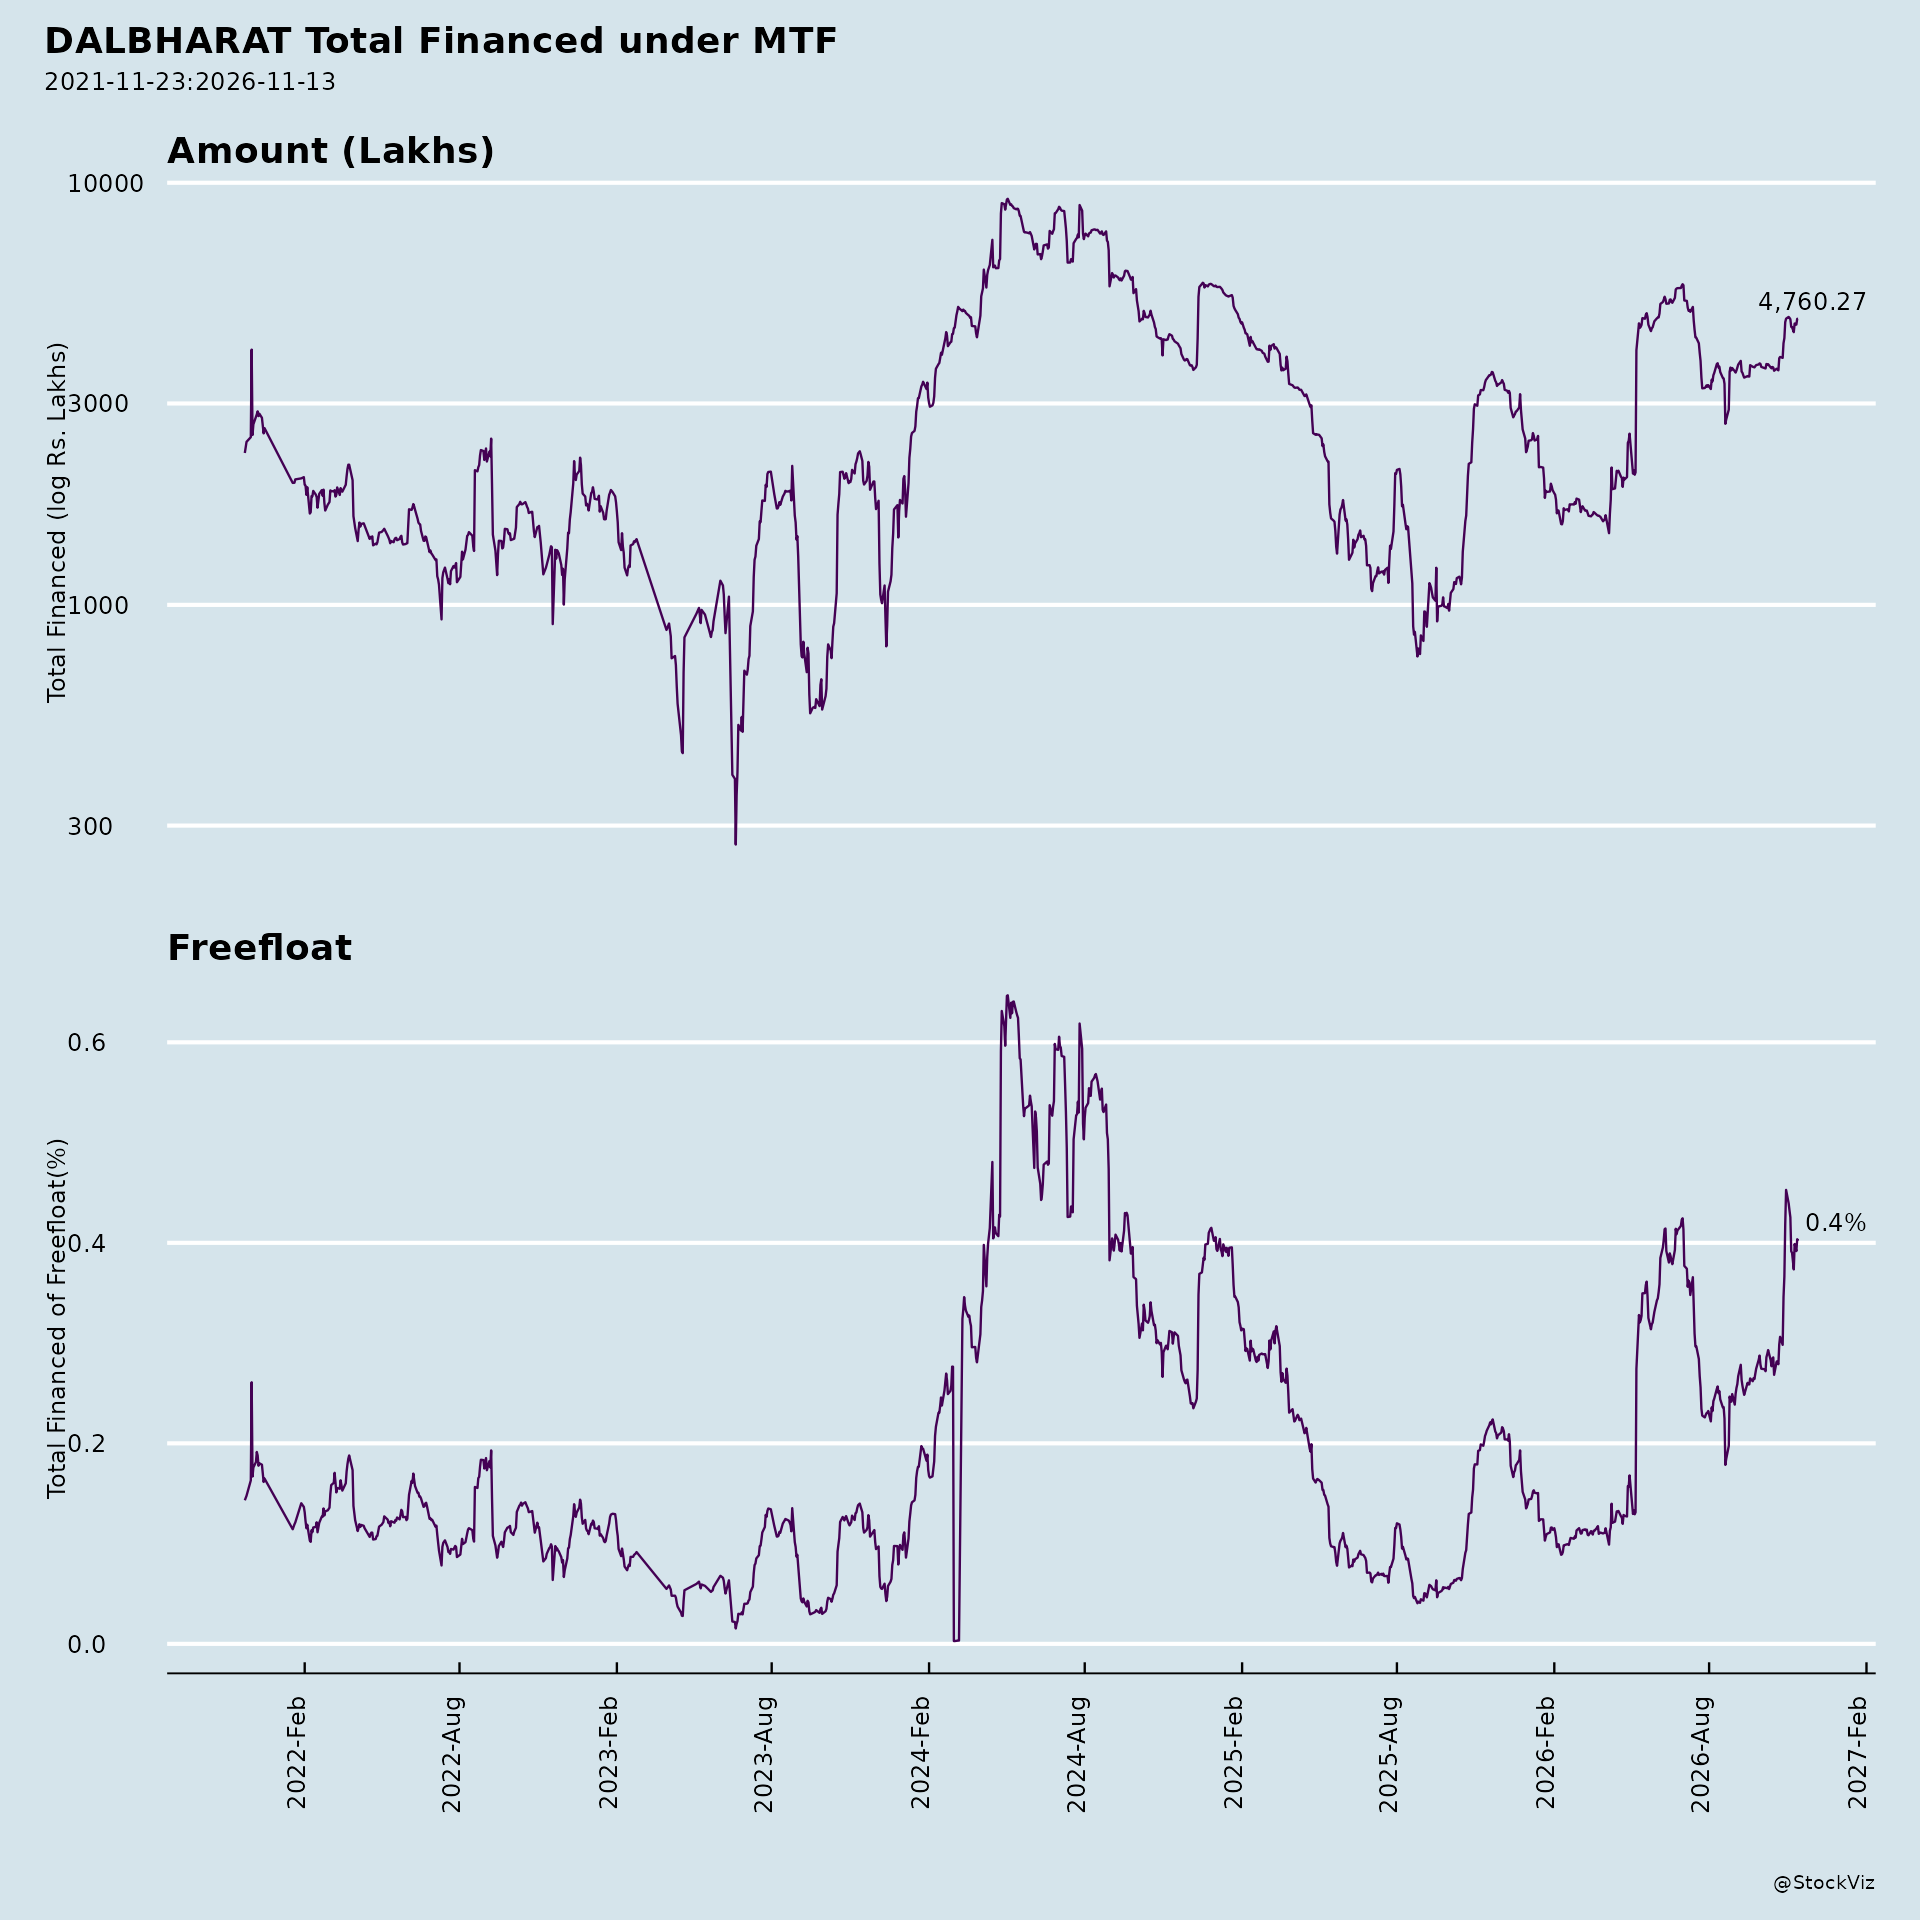
Margined
AI Summary
asof: 2026-09-16
Dalmia Bharat (DALBHARAT): Recent Corporate Announcements — Summary
1. Headwinds and Challenges
Input cost inflation. The quarter ended June 30, 2026 was marked by elevated input costs. Pet coke prices surged to nearly $160 per ton before moderating to $130–$135 per ton, still well above pre-war levels of $110–$115 per ton. Raw material cost per ton of production rose 12% Q-o-Q to INR823, driven by higher limestone raising costs and other headwinds. Power and fuel cost per ton of production increased 10% Y-o-Y to INR1,045. Blended fuel cost rose Q-o-Q from INR1.36 per Kcal to INR1.47 per Kcal. Packing bag prices rose sharply from about INR9.5 per bag pre-war to almost INR14 per bag in Q1, moderating thereafter but remaining above historical levels. Employee cost increased 13% Q-o-Q to INR245 crores, and other expenses rose 3% Q-o-Q to INR632 crores. Clinker freight per ton of dispatches increased 11% Q-o-Q due to higher road movement.
State elections in key markets. Several of the company’s key operating markets underwent state elections during the quarter, which typically causes temporary moderation in construction activity and slower project execution. Management noted the first two months saw modest growth, followed by meaningful improvement in June as labor returned to sites post-elections, aided by a delayed monsoon.
Geopolitical uncertainty. The West Asia conflict drove cost escalations during the quarter. Management noted that while input costs moderated from peak levels, a resurgence in hostilities remains a key factor influencing near-term cost trends, and the cost environment is expected to stay elevated in Q2.
Pricing pressure in specific markets. Bengal saw some suppression of prices, though most markets held steady and South saw some uptick in early July.
Execution delays. The Pune plant start-up was pushed forward due to teething troubles at the execution start point, described as a new location for the company. Management stated the project is back on track.
Jaypee asset ramp-up. The acquired assets carry fixed costs and some legacy issues, and volumes are yet to ramp up. Management expects the initial period to be tricky, with a couple of quarters needed to reach EBITDA breakeven and roughly 7–8 quarters for EBITDA per ton to align with Dalmia’s normal average.
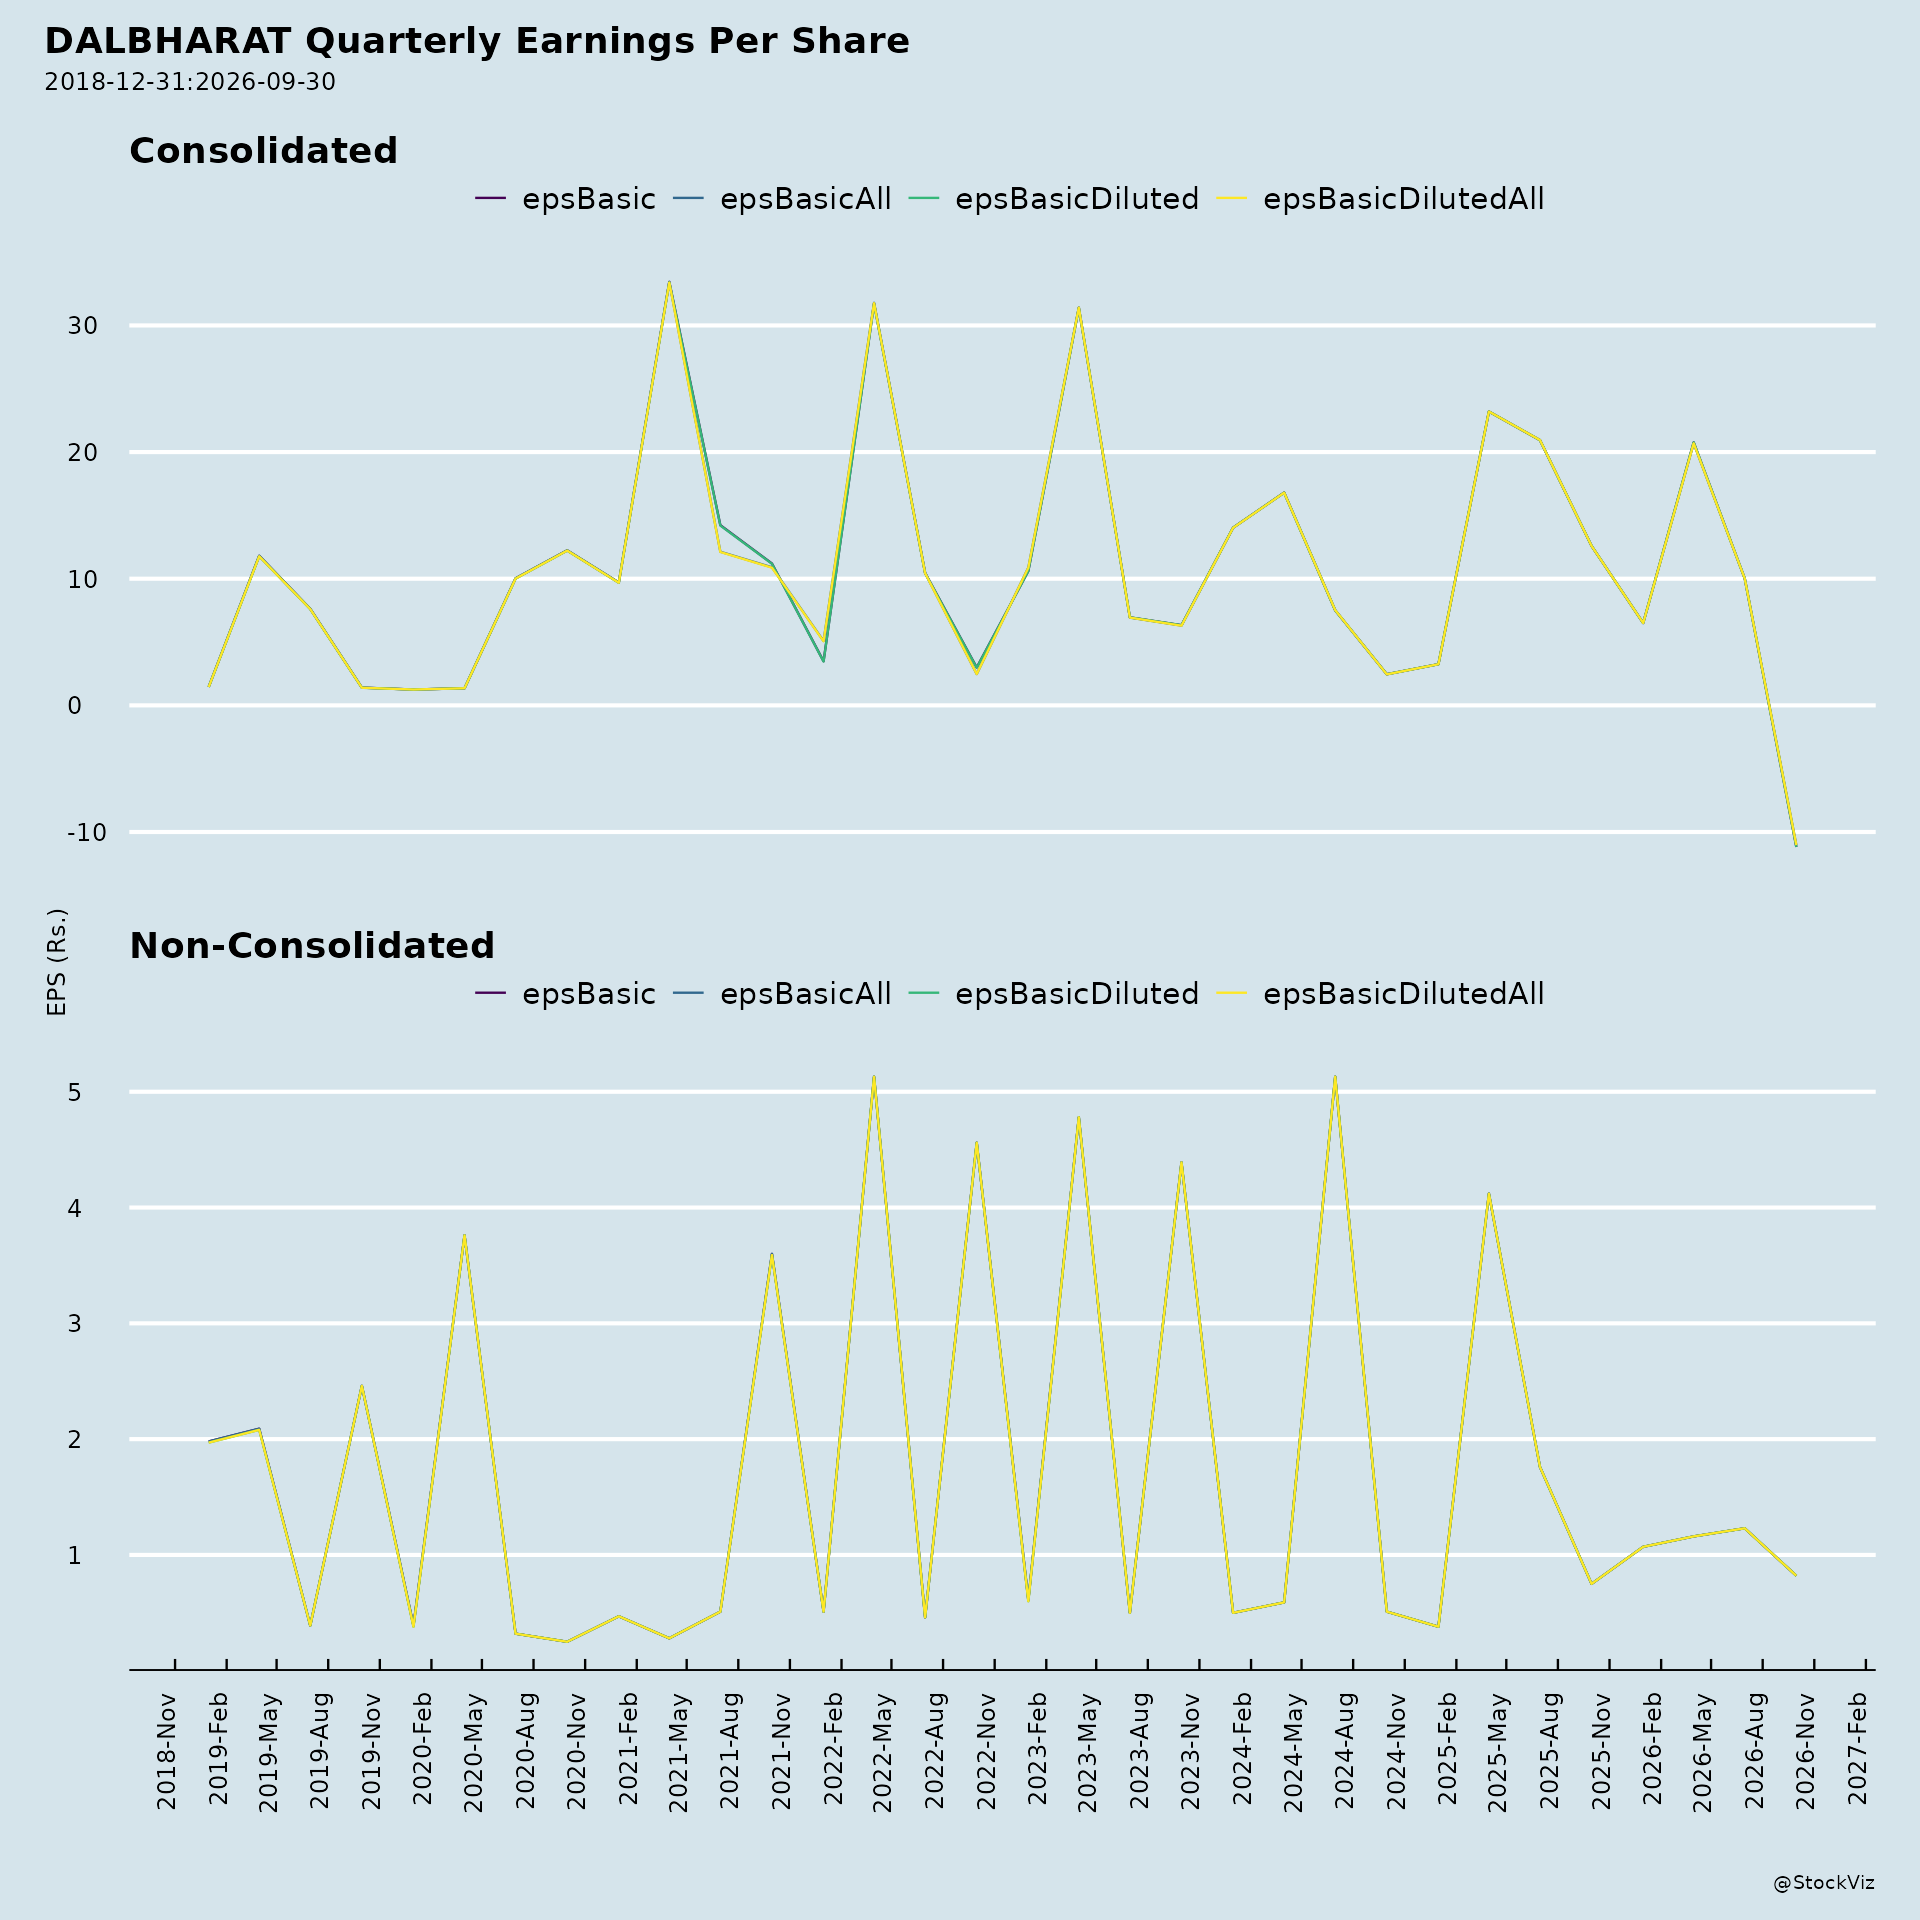
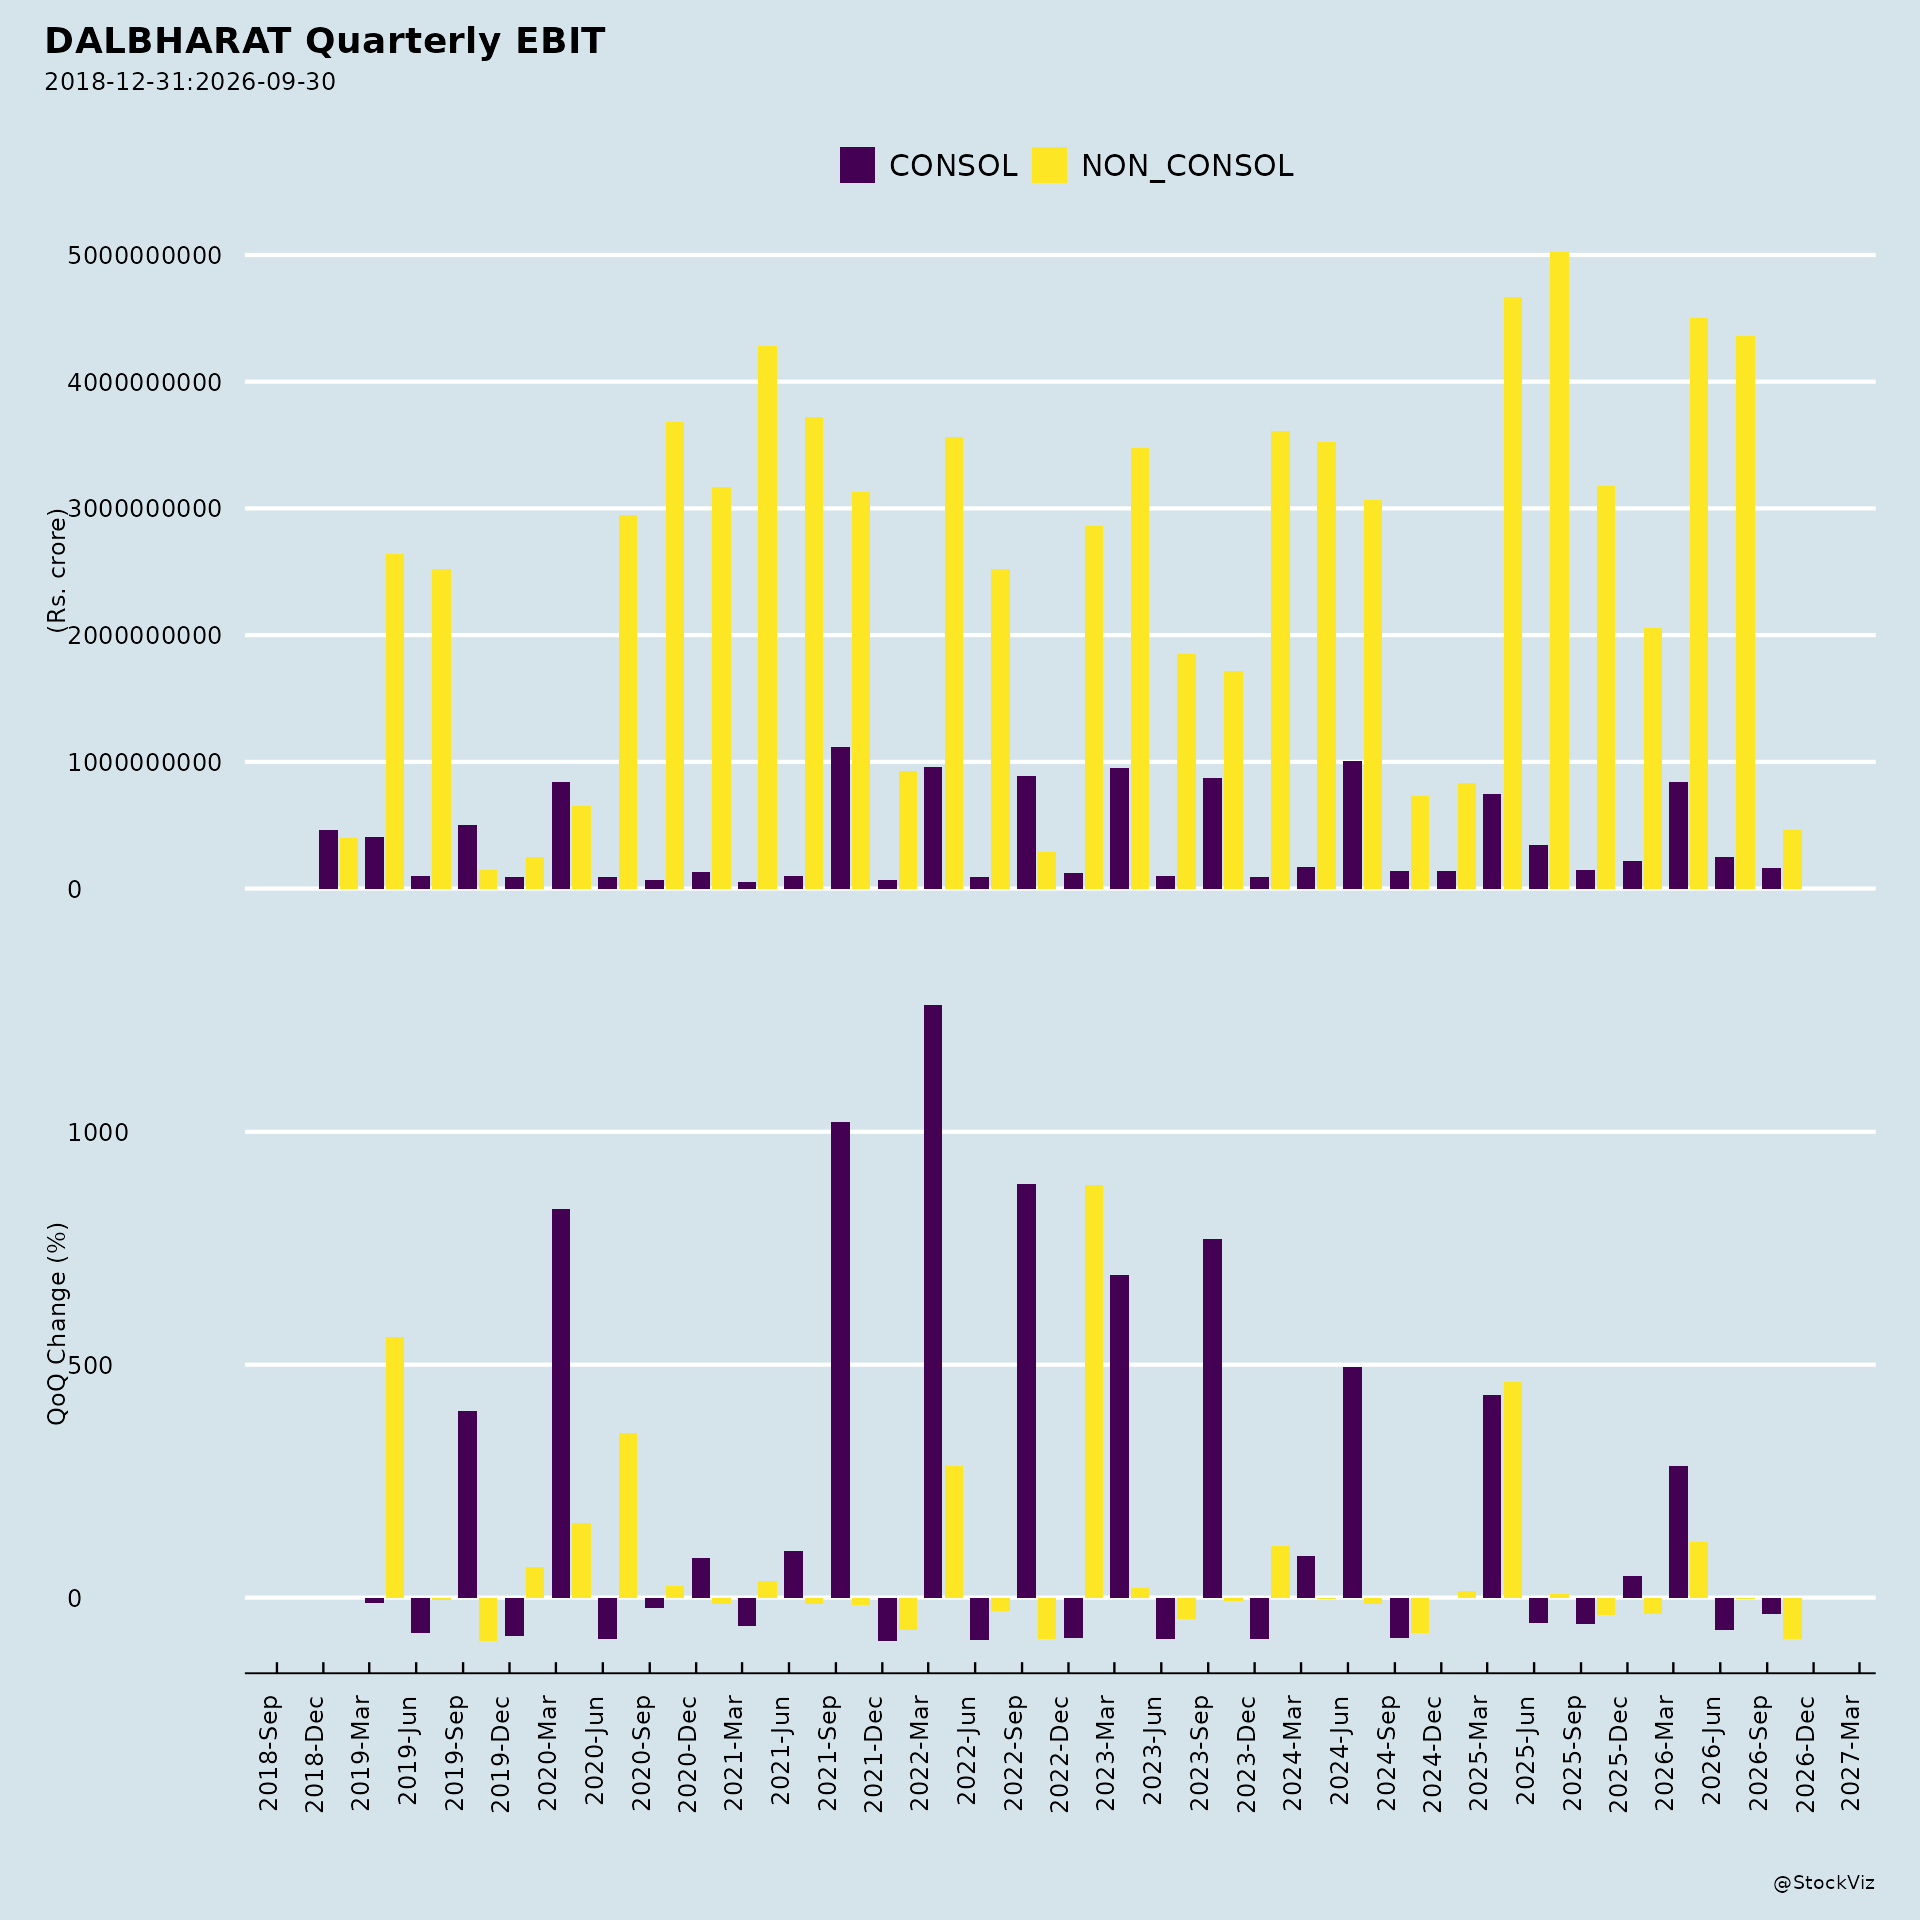
Financial impact. EBITDA declined 11% Q-o-Q to INR805 crores on an absolute basis, and 8.8% Y-o-Y. EBITDA per ton declined 16.4% Y-o-Y to INR1,055, though it improved 3% sequentially. PBT fell 51.0% Y-o-Y to INR254 crores and PAT fell 51.4% Y-o-Y to INR192 crores, impacted by an exceptional item of INR182 crores (stamp duties, transaction fees and related overheads from the Jaypee acquisition). Finance cost rose 36% Y-o-Y to INR147 crores due to higher gross debt from acquisition funding. Depreciation rose 12% Y-o-Y to INR361 crores.
2. Tailwinds and Growth Prospects
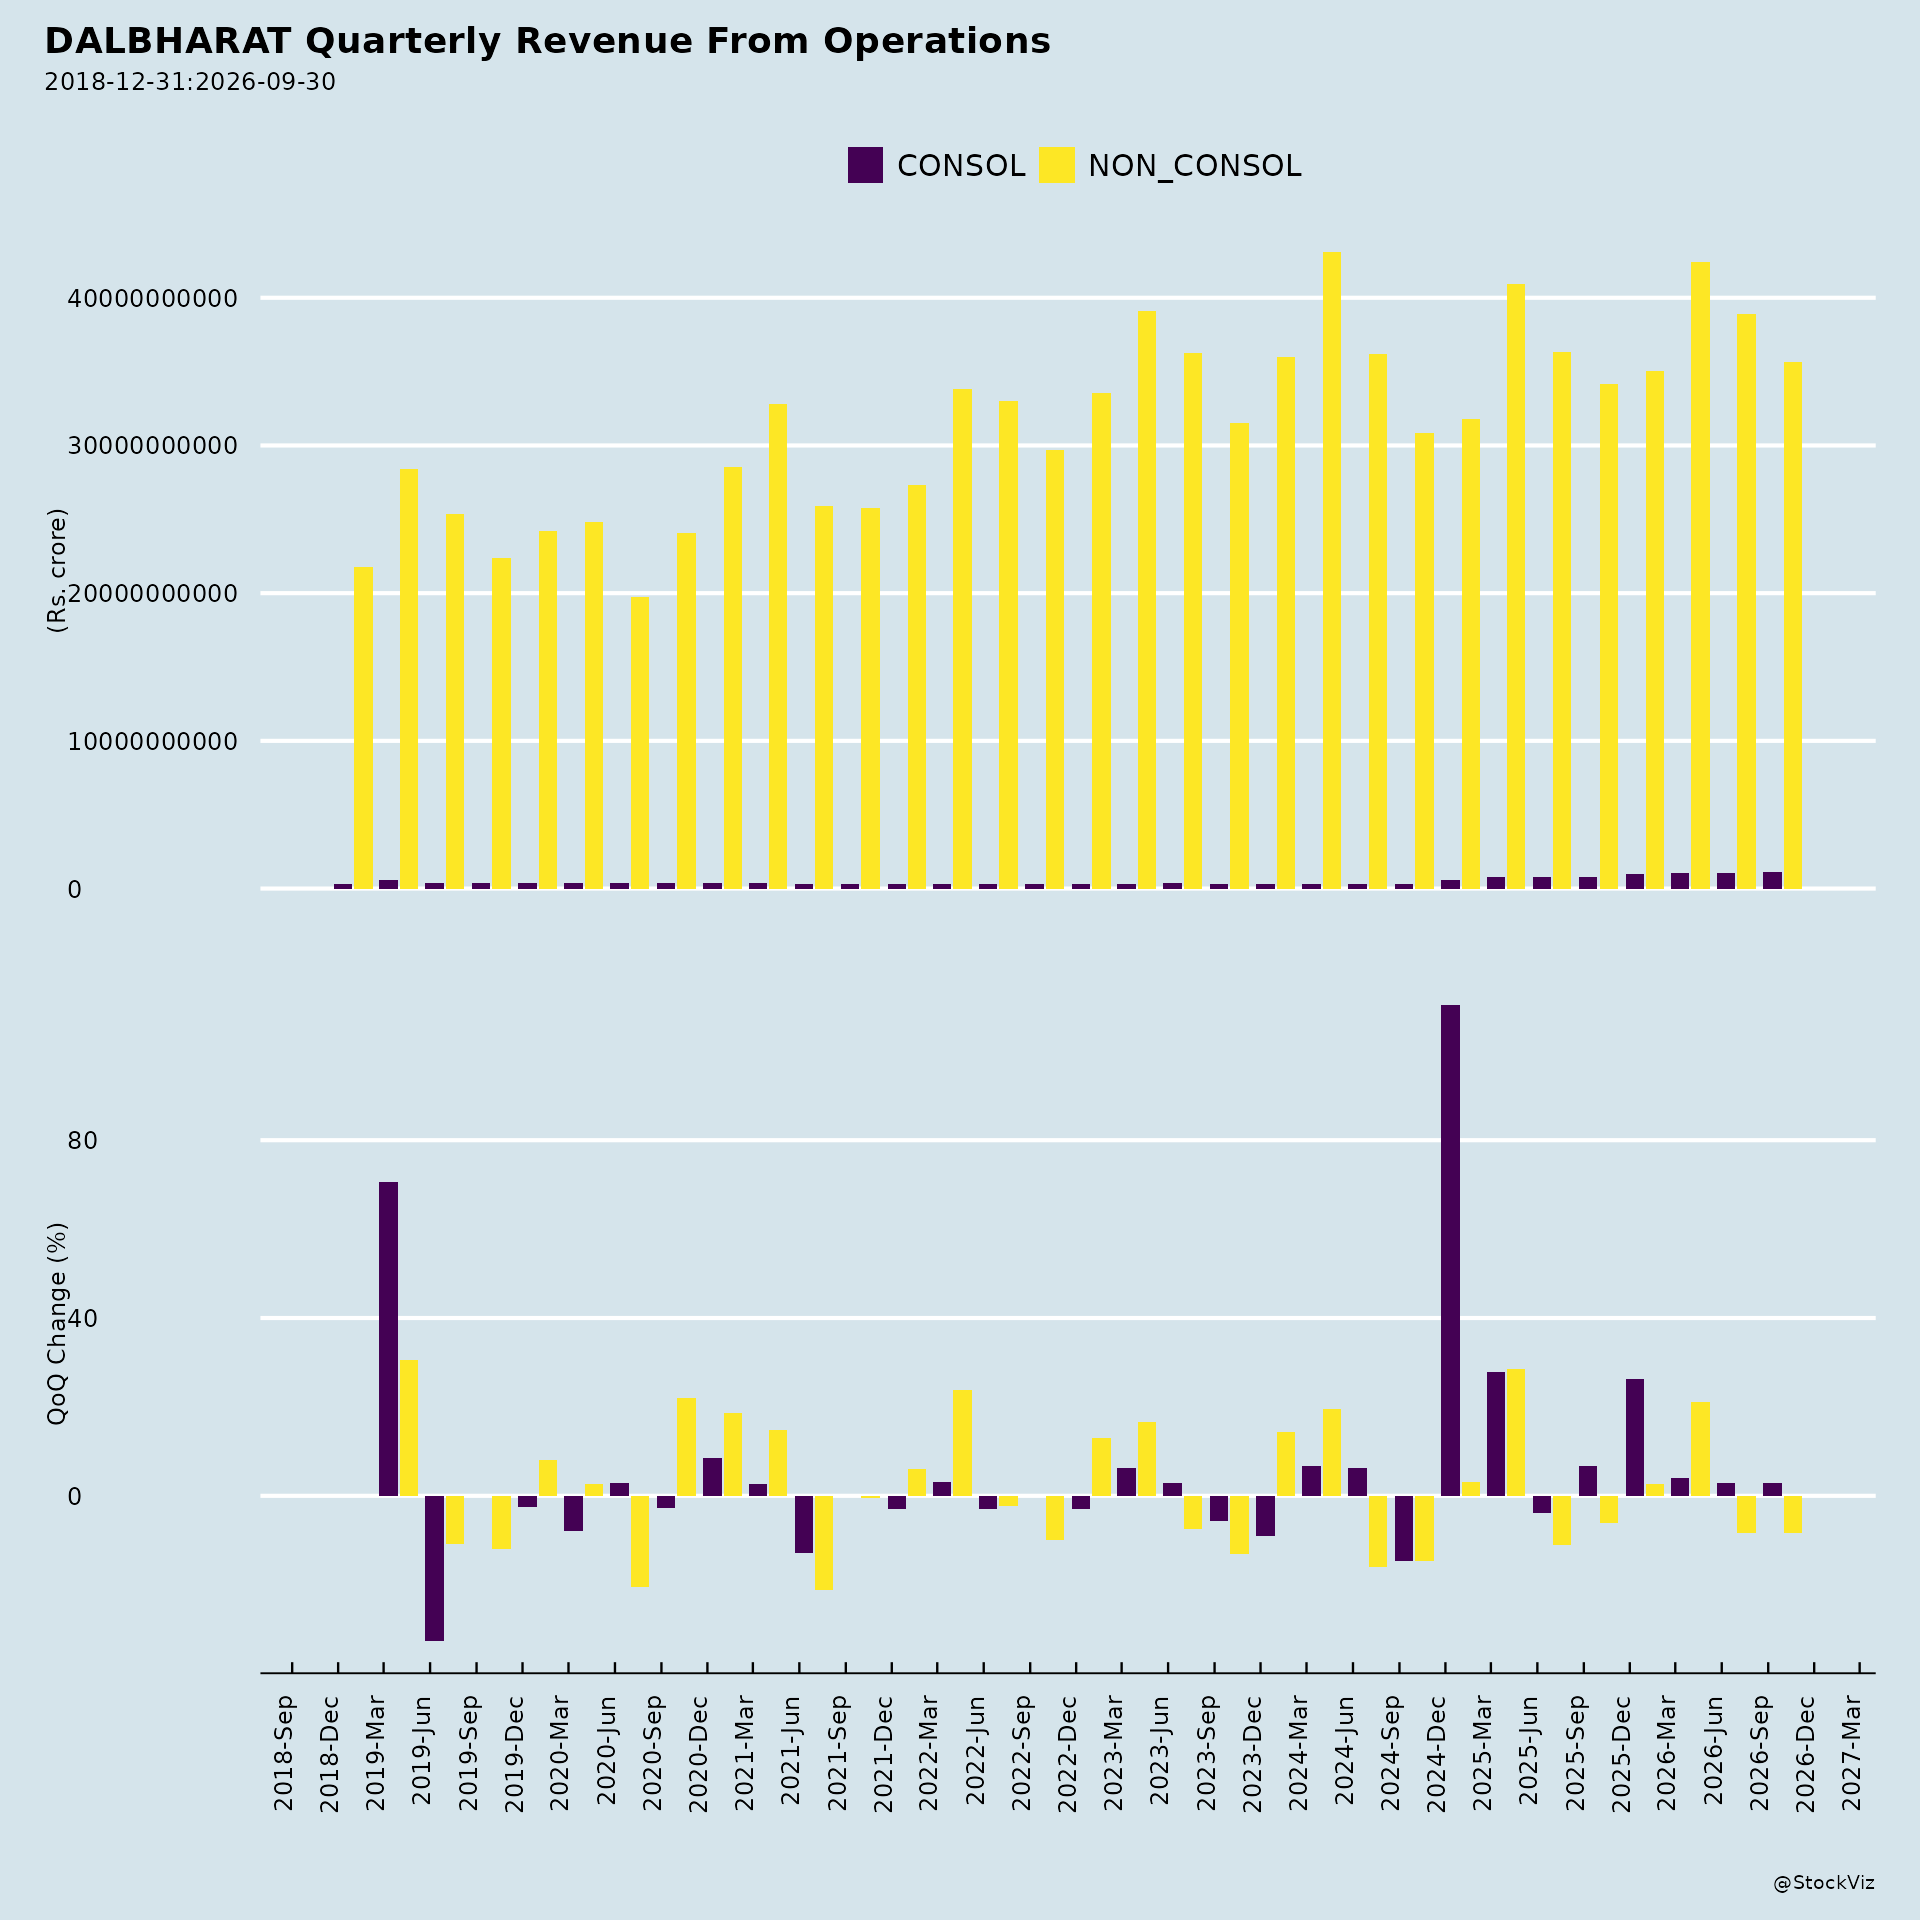
Healthy volume growth. Despite a disrupted quarter for operating regions, sales volume grew 9% Y-o-Y to 7.6 MnT. Excluding the one-off Rajgangpur breakdown impact in the prior quarter, this was the third straight quarter of healthy volume growth. Management indicated performance was at least 200–250 bps above the industry, based on early assessment.
Premiumization. The share of premium products in the portfolio moved to 25%. The company introduced Weather365, a premium-plus offering, which received an encouraging customer response.
Pricing and cost actions. Healthy price increases of about INR10–15 in South and INR15–20 in East enabled passing on a significant portion of input cost inflation. Procurement and operational initiatives — better planning, inventory management, diversified sourcing and fuel mix optimization — generated savings of more than INR150 per ton during the quarter. Management described these as a permanent change in ways of working rather than a one-time benefit. Realizations improved 6% Q-o-Q.
Jaypee acquisition and Central India entry. The company completed the acquisition of Jaiprakash Associates’ cement undertaking on May 29, 2026 at an enterprise value of INR2,850 crores, adding 5.2 MnTPA of cement capacity and 3.3 MnTPA of clinker capacity across four plants in Madhya Pradesh and Uttar Pradesh. Installed cement capacity increased to 54.7 MnTPA. Commercial production commenced at the 2.5 MnTPA Chunar Grinding Unit on June 20, 2026, and trial run started at the 3.3 MnTPA Rewa Clinker Unit in July — within 50 days of completing the acquisition. The asset offers debottlenecking and brownfield expansion opportunities. Dalmia had already seeded these markets over the past couple of years, providing a head start. The assets are expected to contribute meaningfully to volumes from Q3 onwards.
Capacity expansion pipeline. With the Jaypee acquisition plus ongoing projects at Belgaum, Kadapa and Pune, cement capacity is expected to reach about 67 million tons by Q3 FY28. Belgaum is progressing ahead of schedule and expected to commence commercial production within six months. At Kadapa and Pune, site excavation is underway with contractors mobilized. An 18 MW WHRS facility is being installed at the Rewa plant. The company is working on additional projects to be announced in due course. Management reiterated a directional aspiration of becoming a pan-India player at roughly 110 million tons by FY31, with flexibility on timing.
Renewable energy. 48% of power consumption was sourced through renewable energy, with the share expected to rise as more renewable capacity is added. The company entered into agreements to acquire 41% stake (26% on fully-diluted basis) in Oyster Green Hybrid Five Private Limited for approximately INR17 crores to source hybrid wind and solar power as a captive consumer for the Kadapa plant.
Incentives. INR45 crores in incentives were accrued and INR60 crores collected during the quarter, with outstanding incentives at INR822 crores. Accrual is expected to remain in the INR45–50 crores per quarter range over the next couple of years.
Macro backdrop. Management cited India’s growth projection at 6.6% for FY27, all-time high GST collections of INR6.3 lakh crores in Q1 FY27, public capex at 21% of the annual budgeted outlay in the first two months, and inflation largely within the RBI’s comfort range. Cement demand is expected to grow at a healthy 7% for the financial year, with industry demand growing about 7–8% Y-o-Y in Q1.
Balance sheet strength. Despite funding the acquisition, leverage stood at 1.47x net debt to EBITDA, comfortably below 2x. Gross debt increased to INR9,108 crores and net debt to INR4,431 crores. The average cost of debt remained range bound at about 7%. Capex commitment for FY27 is expected at around INR3,200–3,400 crores, in line with earlier guidance.
Governance and shareholder matters. At the 13th AGM held June 30, 2026, all resolutions passed with requisite majority, including adoption of FY26 financial statements, declaration of a final dividend of Rs. 5.00 (250%) per equity share, re-appointment of Mr. Puneet Yadu Dalmia as director, re-appointment of Walker Chandiok & Co LLP as statutory auditors for FY27–FY31, and a special resolution authorizing fund raising through issuance of securities. The fund-raising resolution received 94.87% votes in favor, with 5.13% against.
3. Key Risks
- Sustained input cost pressure. Management expects the cost environment to stay elevated in Q2, with an estimated INR70–80 per ton increase in input costs over and above Q1, excluding negative operating leverage. This estimate was described as subject to reassessment given evolving conditions.
- Geopolitical escalation. Renewed hostilities in West Asia could further influence fuel and input cost trends.
- Monsoon uncertainty. Potential El Nino effects on monsoon progress warrant close monitoring.
- Pricing volatility. Cement pricing remains dynamic; management could not indicate what would make price increases stick, particularly regarding the East India price gap versus other regions.
- Execution and ramp-up risk. Jaypee asset ramp-up faces fixed costs and legacy issues; Pune faced execution teething troubles; the Northeast has excess clinker relative to grinding capacity, with a balancing grinding unit on the agenda but not yet announced.
- Leverage and capital allocation. The company has an enabling authorization for fund raising and an aspiration to reach 110–130 million tons, which would require significant capex. Management stated it will remain flexible and will not “burst the bank,” with balance sheet health a priority.
- Land and reserve access at Jaypee. The 100 million ton limestone reserve requires ongoing land procurement; existing land is sufficient for the initial few years, with adjacent assets available and further expansion planned gradually. No exact cost estimate was provided.
- Industry capacity additions in East. Management estimated 10–11 million tons of industry-wide capacity addition in each of FY27 and FY28 in the East, though it declined to hazard a guess on whether the region is in the last leg of massive capacity addition.
4. Management Guidance Versus Observed Business Performance
Volume growth. Management guided that, outside acquisitions or new capacities, the company wants to grow in line with the industry (7–8%), with additional capacity layered on top. Observed Q1 FY27 volume growth was 9% Y-o-Y, which management assessed as at least 200–250 bps above the industry, though it noted not all industry results were out.
Capex. FY27 capex commitment was guided at around INR3,200–3,400 crores, stated to be in line with earlier guidance. About INR510 crores was spent during the quarter excluding acquisition cost. Management indicated the Jaypee capex would not significantly change this number.
Cost reduction. Management stated the previously targeted cost reduction of INR50–100 per year remains on track, describing it as a continuous activity rather than formal guidance. In Q1, procurement and operational initiatives generated savings of more than INR150 per ton.
Jaypee EBITDA trajectory. Management guided a couple of quarters to reach EBITDA breakeven and roughly 7–8 quarters for EBITDA per ton to align with Dalmia’s normal average. No financial performance from the acquired assets has yet been reported, as the acquisition completed May 29, 2026 and ramp-up is ongoing.
Depreciation. Management guided FY27 depreciation to increase by INR100 crores as Jaypee plants are commissioned and Belgaum commercialized, with a further INR100–150 crores increase in FY28 on Kadapa and Pune commissioning. Q1 depreciation rose 12% Y-o-Y to INR361 crores, attributed to capitalization of the Umrangso clinker unit in January 2026.
Incentive accrual. Management guided incentive accrual to remain in the INR45–50 crores per quarter range for the next couple of years. Q1 accrual was INR45 crores, consistent with that range.
Capacity milestone. Management guided cement capacity to reach about 67 million tons by Q3 FY28, describing this as an indicative milestone on a clear path, with the East grinding unit potentially taking capacity toward 70 million tons, and timing flexibility of a quarter or two not materially changing the trajectory.
Treasury yields. Management indicated treasury yields would average close to about 6.5%, explaining that Q1 other income of INR139 crores included mark-to-market gains on treasury investments as yields corrected after the policy announcement and RBI measures to attract global capital.
Broker Narrative
The broker story stayed predominantly Buy/positive on capacity expansion, infrastructure/housing demand, green power/cost savings and a path to higher EBITDA/ton, but the early hope that softening petcoke/coal would offset input-cost pressure was overtaken by events. From 2023-05-31 to 2026-11-02 the narrative shifted from warning about raw-material, inventory, slag/flyash, rail-freight/diesel costs to explicitly admitting rising power & fuel/packaging costs, commodity prices, sequential negative operating leverage, demand slowdown, expansion delays, competition and floods. The record is dominated by DISAPPOINTMENT/NEUTRAL outcomes with negative actual returns (first report -28.6%; 2024-04-08 +36.2% predicted vs -24.7% actual), with only a few SUCCESSes and the latest +8.1% actual still PENDING.
Fears that came true
- Early warnings of higher raw-material/slag/flyash costs and high-cost opening inventory materialized as the last report cites rising input costs, power & fuel and packaging costs, higher commodity prices and a further ~₹70–80/ton Q3FY27 increase, while the first Buy already ended at -28.6% actual/DISAPPOINTMENT and calls such as 2024-04-08 (+36.2% predicted, -24.7% actual) also disappointed.
- The early diesel/fuel-price leg of the cost warning persisted as elevated fuel prices are expected to add ~₹70–80/ton in Q3FY27, consistent with repeated negative actual returns and DISAPPOINTMENT outcomes across the 85 reports.
Optimism that failed
- The early tailwind of softening fuel costs (petcoke and coal) did not hold, since the last report lists rising power & fuel costs, elevated fuel prices and a further ~₹70–80/ton Q3FY27 cost increase despite expected ₹50–100/ton annual savings.
- The original capacity ramp was delayed/scaled back: the first report targeted 70–75 mtpa by FY27E and 110–130 mtpa by FY31, while the last report flags delays and sees only 66.7 mtpa by FY28E from 54.7 mtpa, with many expansion-era Buy calls still DISAPPOINTMENTs.
- Strong infrastructure/housing demand was not sustained smoothly: the last report flags a demand slowdown plus heavy rainfall/floods in East/Northeast, matching negative actuals such as 2026-03-23 (+37.7% predicted, -14.1% actual, DISAPPOINTMENT).
Broker Timeline
85 broker calls · 2023-05-31 to 2026-11-02
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.