COSMOFIRST
Equity Metrics
November 18, 2026
COSMO FIRST LIMITED
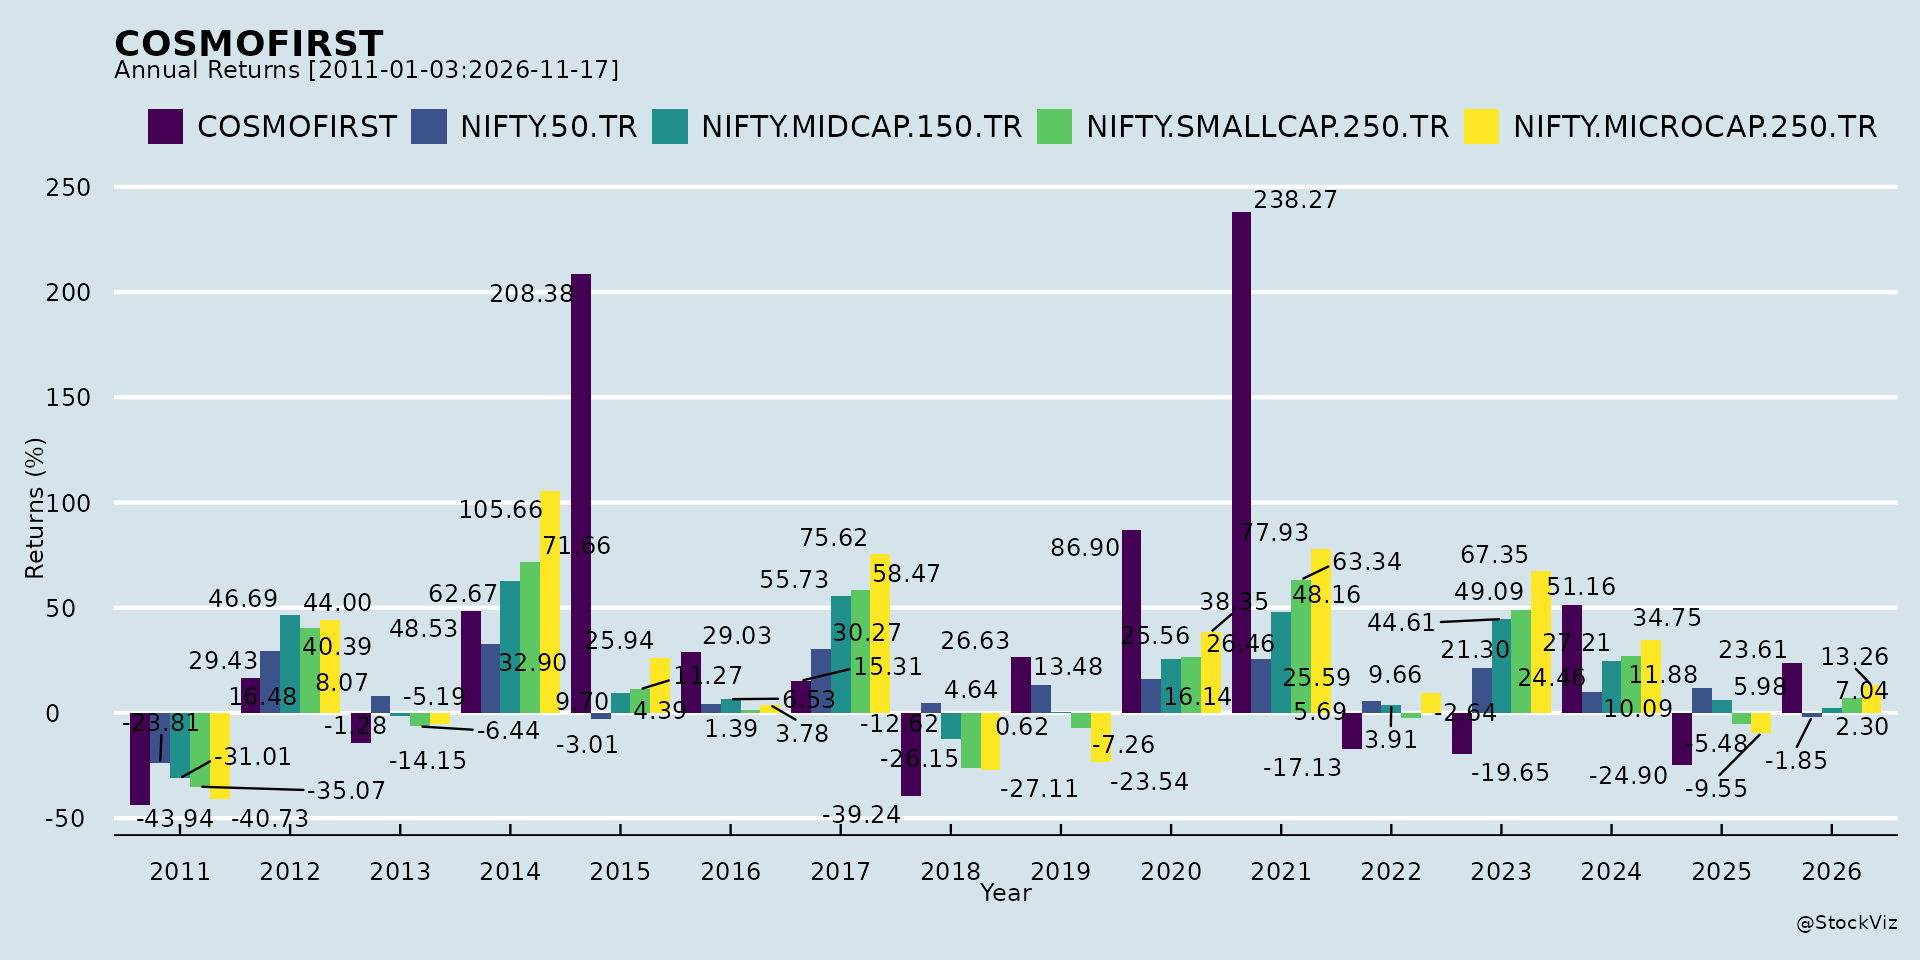
Annual Returns
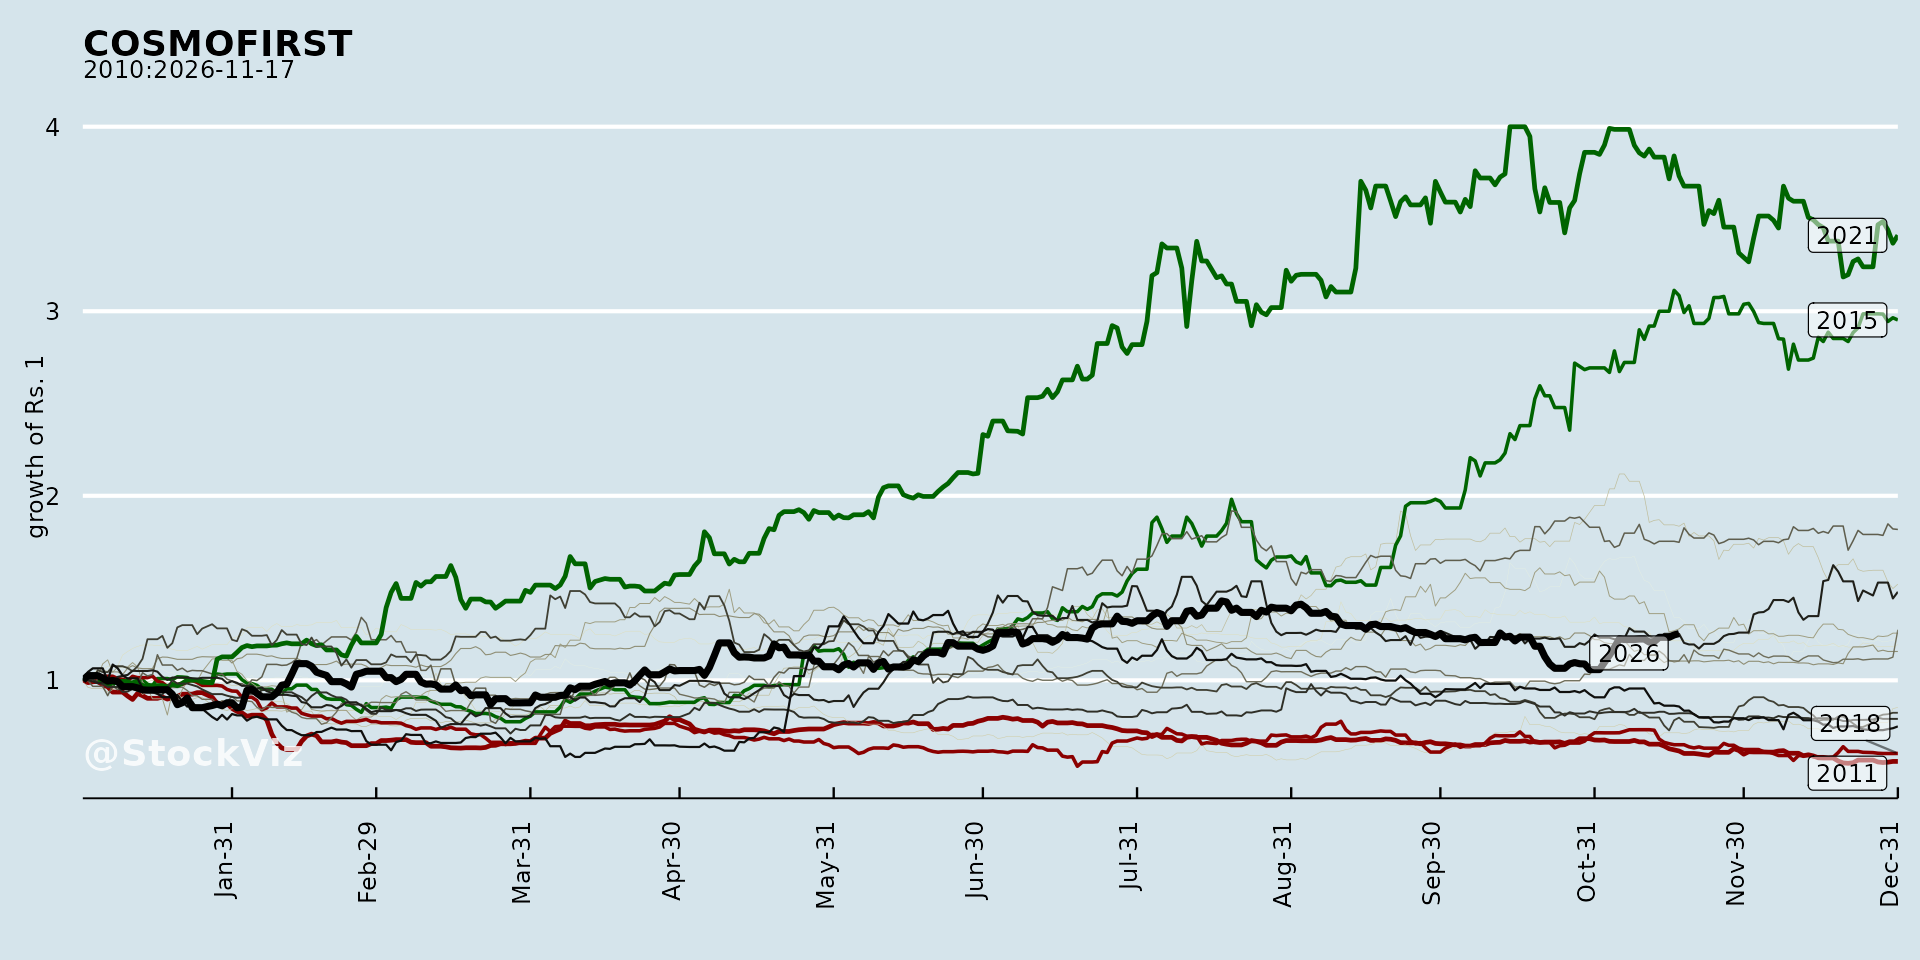
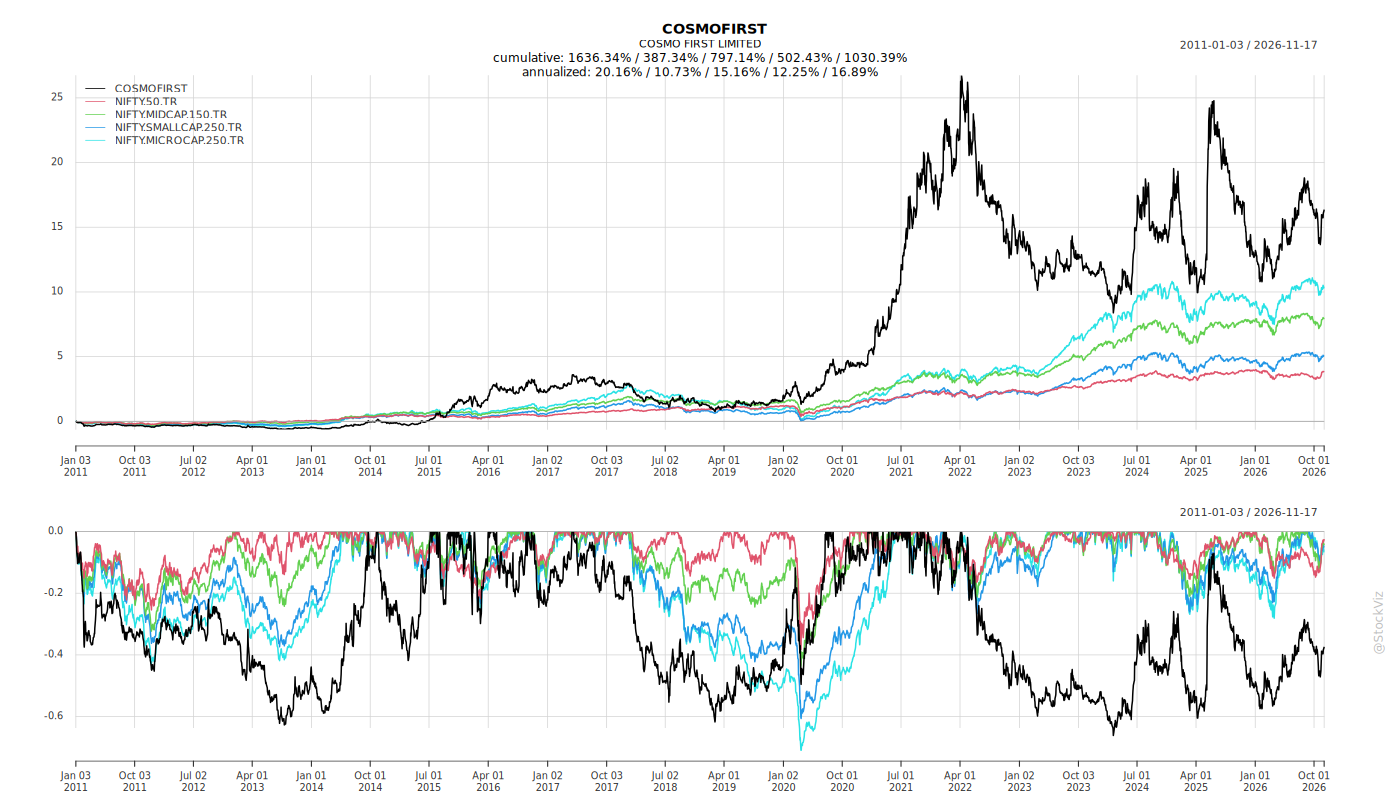
Cumulative Returns and Drawdowns
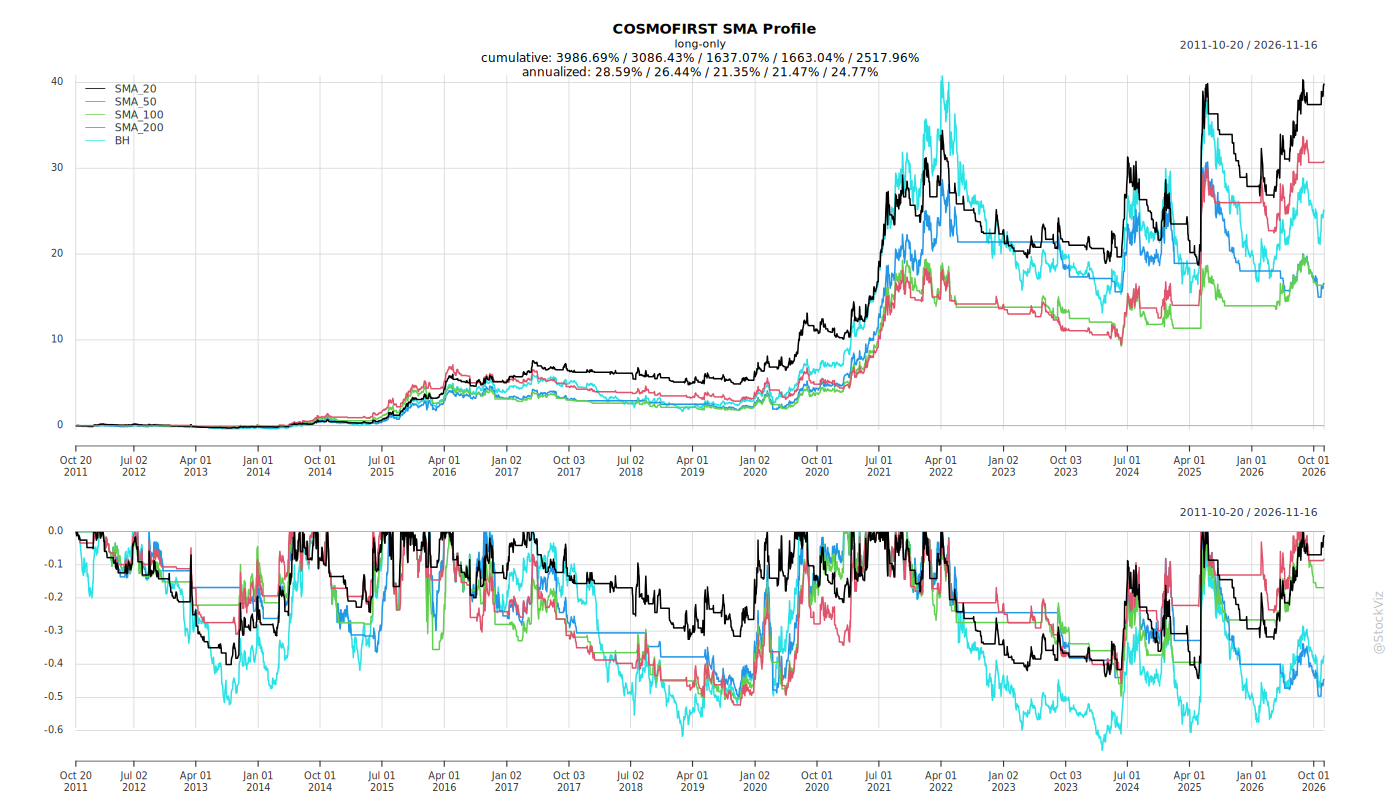
Fundamentals
Ownership
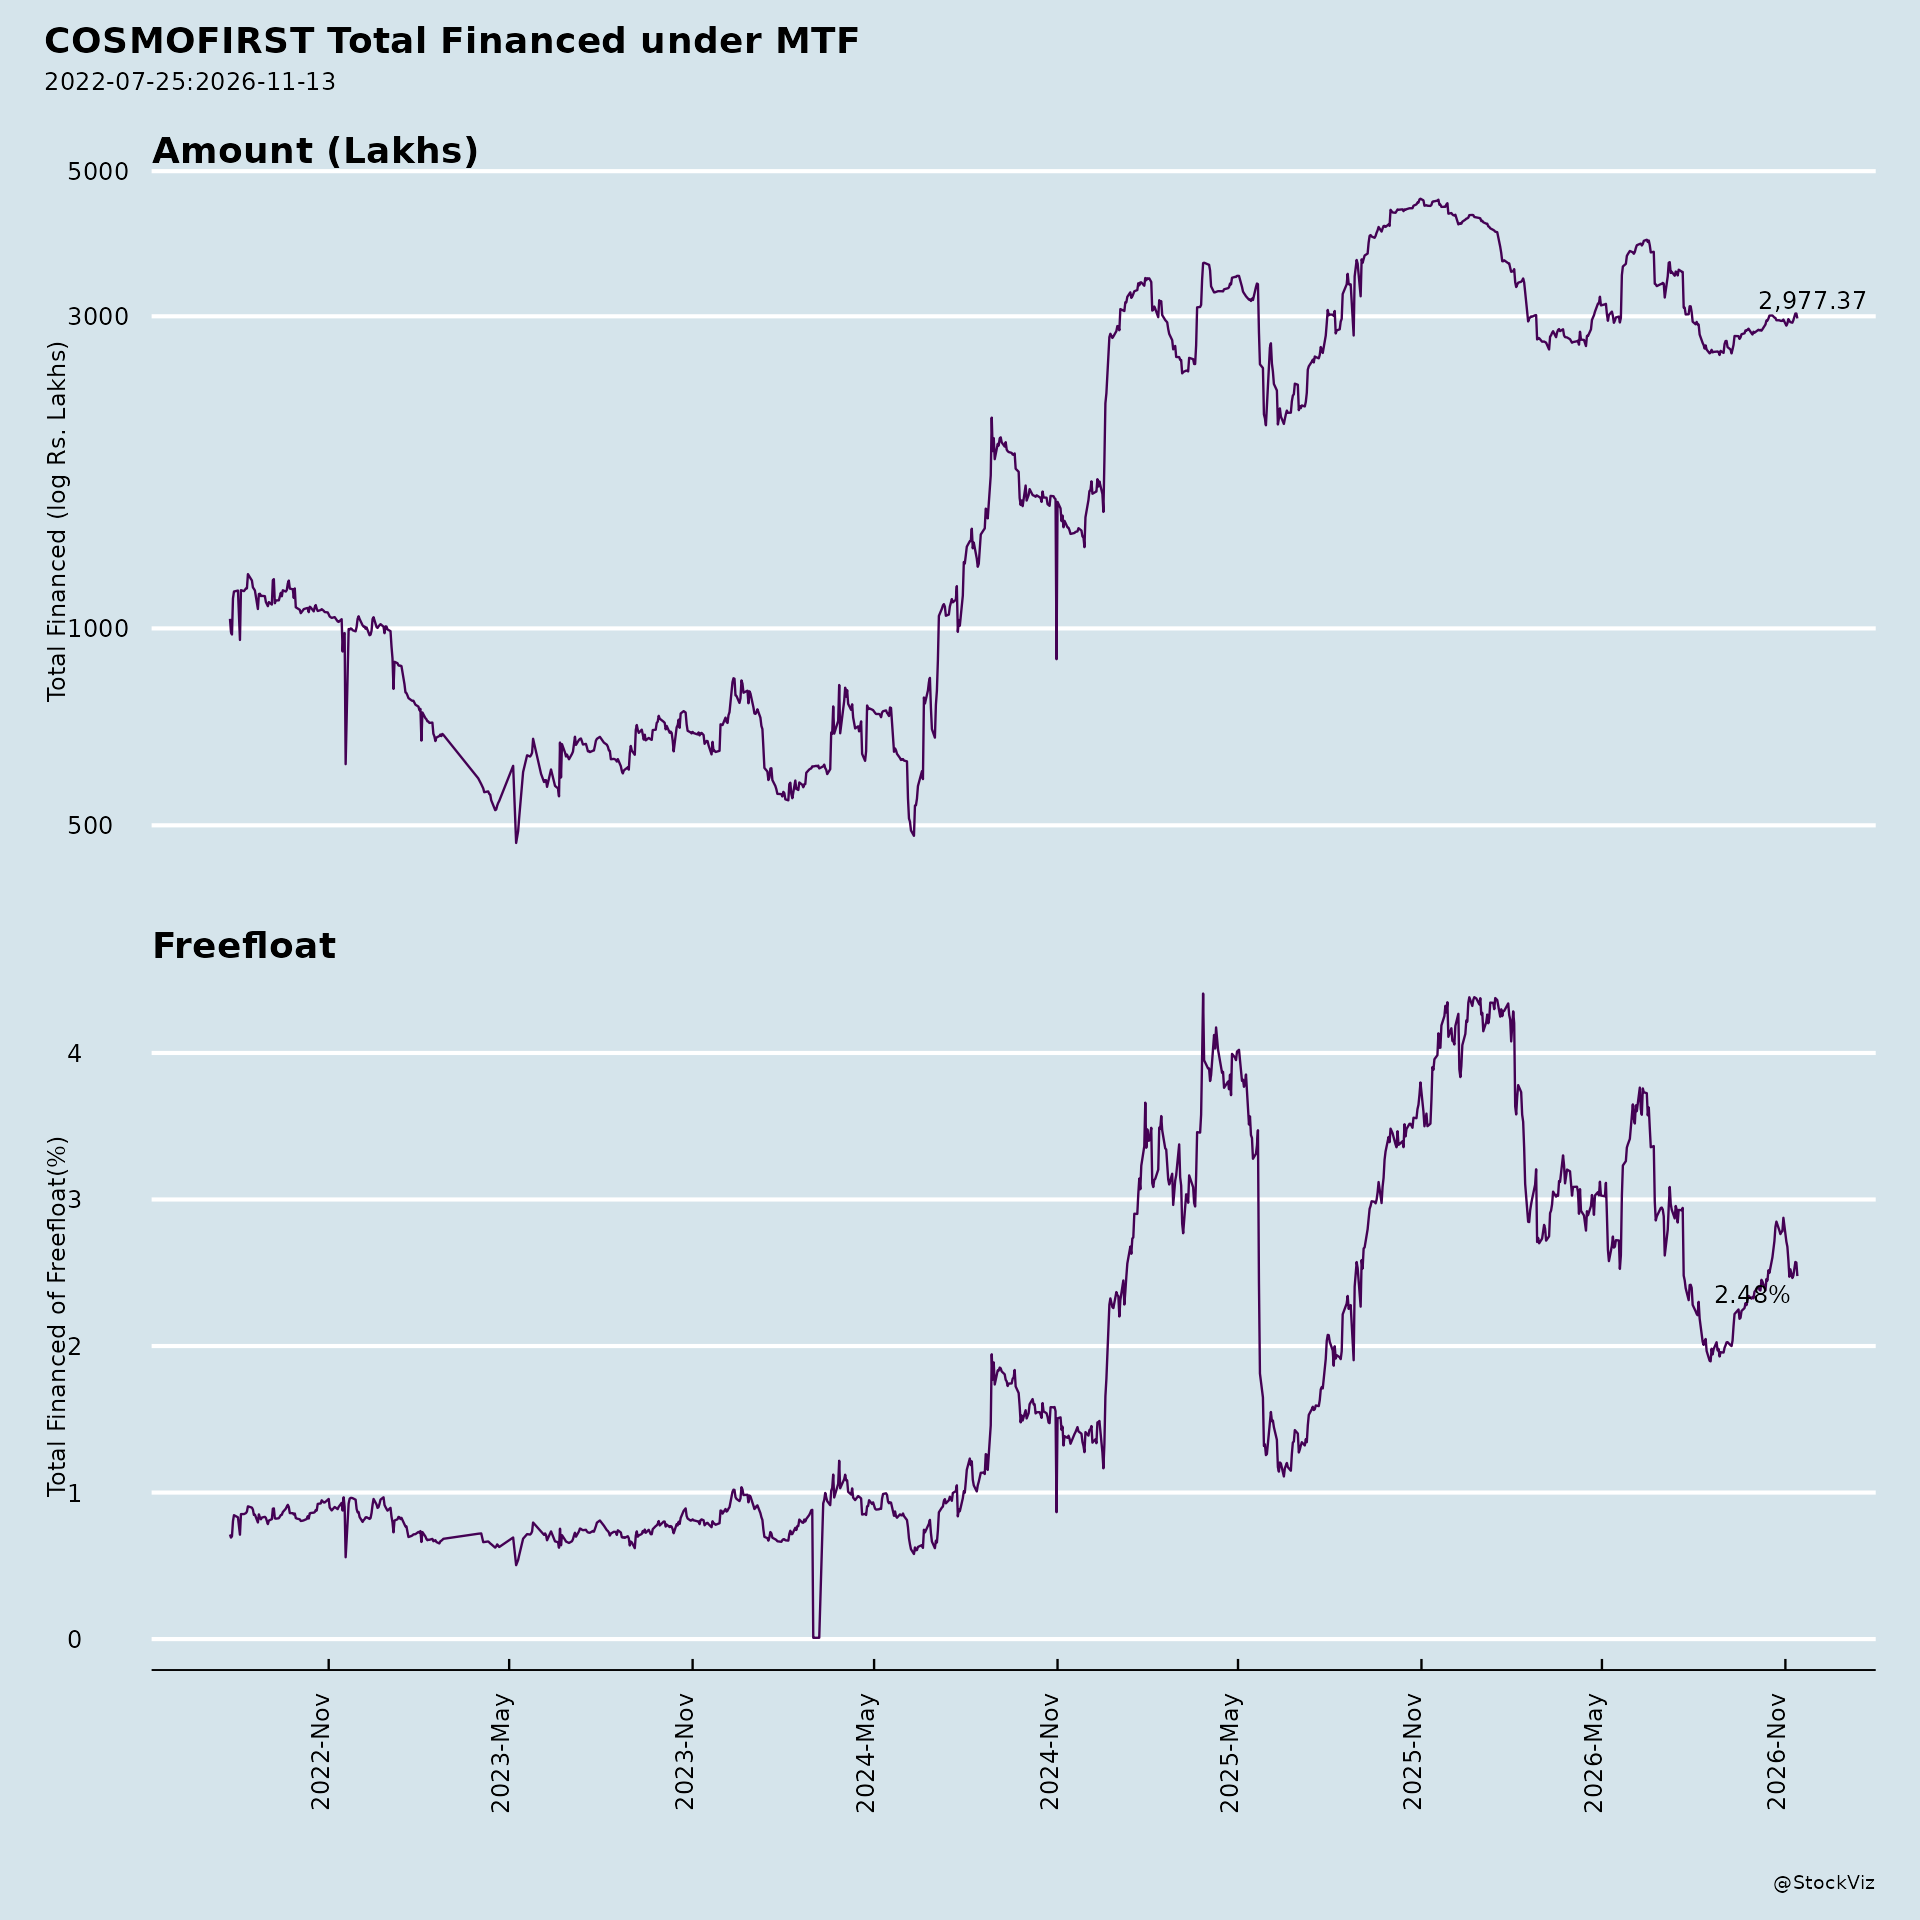
Margined
AI Summary
asof: 2026-09-18
COSMOFIRST — Recent Corporate Announcements: Analysis
1. Headwinds and Challenges
- Working capital pressure from raw material prices: Net working capital increased by Rs 85 crores due to increased raw material prices following the West Asia war. Despite this, net debt at June 2026 end was flat at the Q4 FY26 level of Rs 1,166 crores (2.3 times EBITDA).
- Elevated leverage: Net debt of Rs 1,166 crores at 2.3x EBITDA remains a constraint, even as management expects it to reduce significantly over the next two years.
- Loss-making newer businesses: In Q1 FY27, the Petcare segment reported a loss of Rs 14.84 crores and Cosmo Consumer a loss of Rs 2.03 crores. For FY26, Petcare lost Rs 42.18 crores and Cosmo Consumer Rs 14.04 crores.
- Prior exceptional loss: An exceptional item in the quarter and year ended 31 March 2026 represented a provision by the Company’s Netherlands subsidiary towards the ultimate loss (net of recovery from insurance/legal process) related to an unauthorised bank transfer matter reported earlier.
- Tax regime uncertainty: Following amendments under the Finance Act, 2026, the Company re-evaluated its option to adopt the concessional tax regime. Current tax for the quarter continued under the existing regime, with deferred tax remeasured; consequential adjustments from the final tax computation will be recognised in the last quarter of the financial year.
- Modest standalone profitability: Standalone PBT was Rs 37.93 crores in Q1 FY27 versus Rs 39.52 crores in Q4 FY26, indicating the standalone entity’s profit was broadly flat sequentially even as consolidated revenue rose.
2. Tailwinds and Growth Prospects
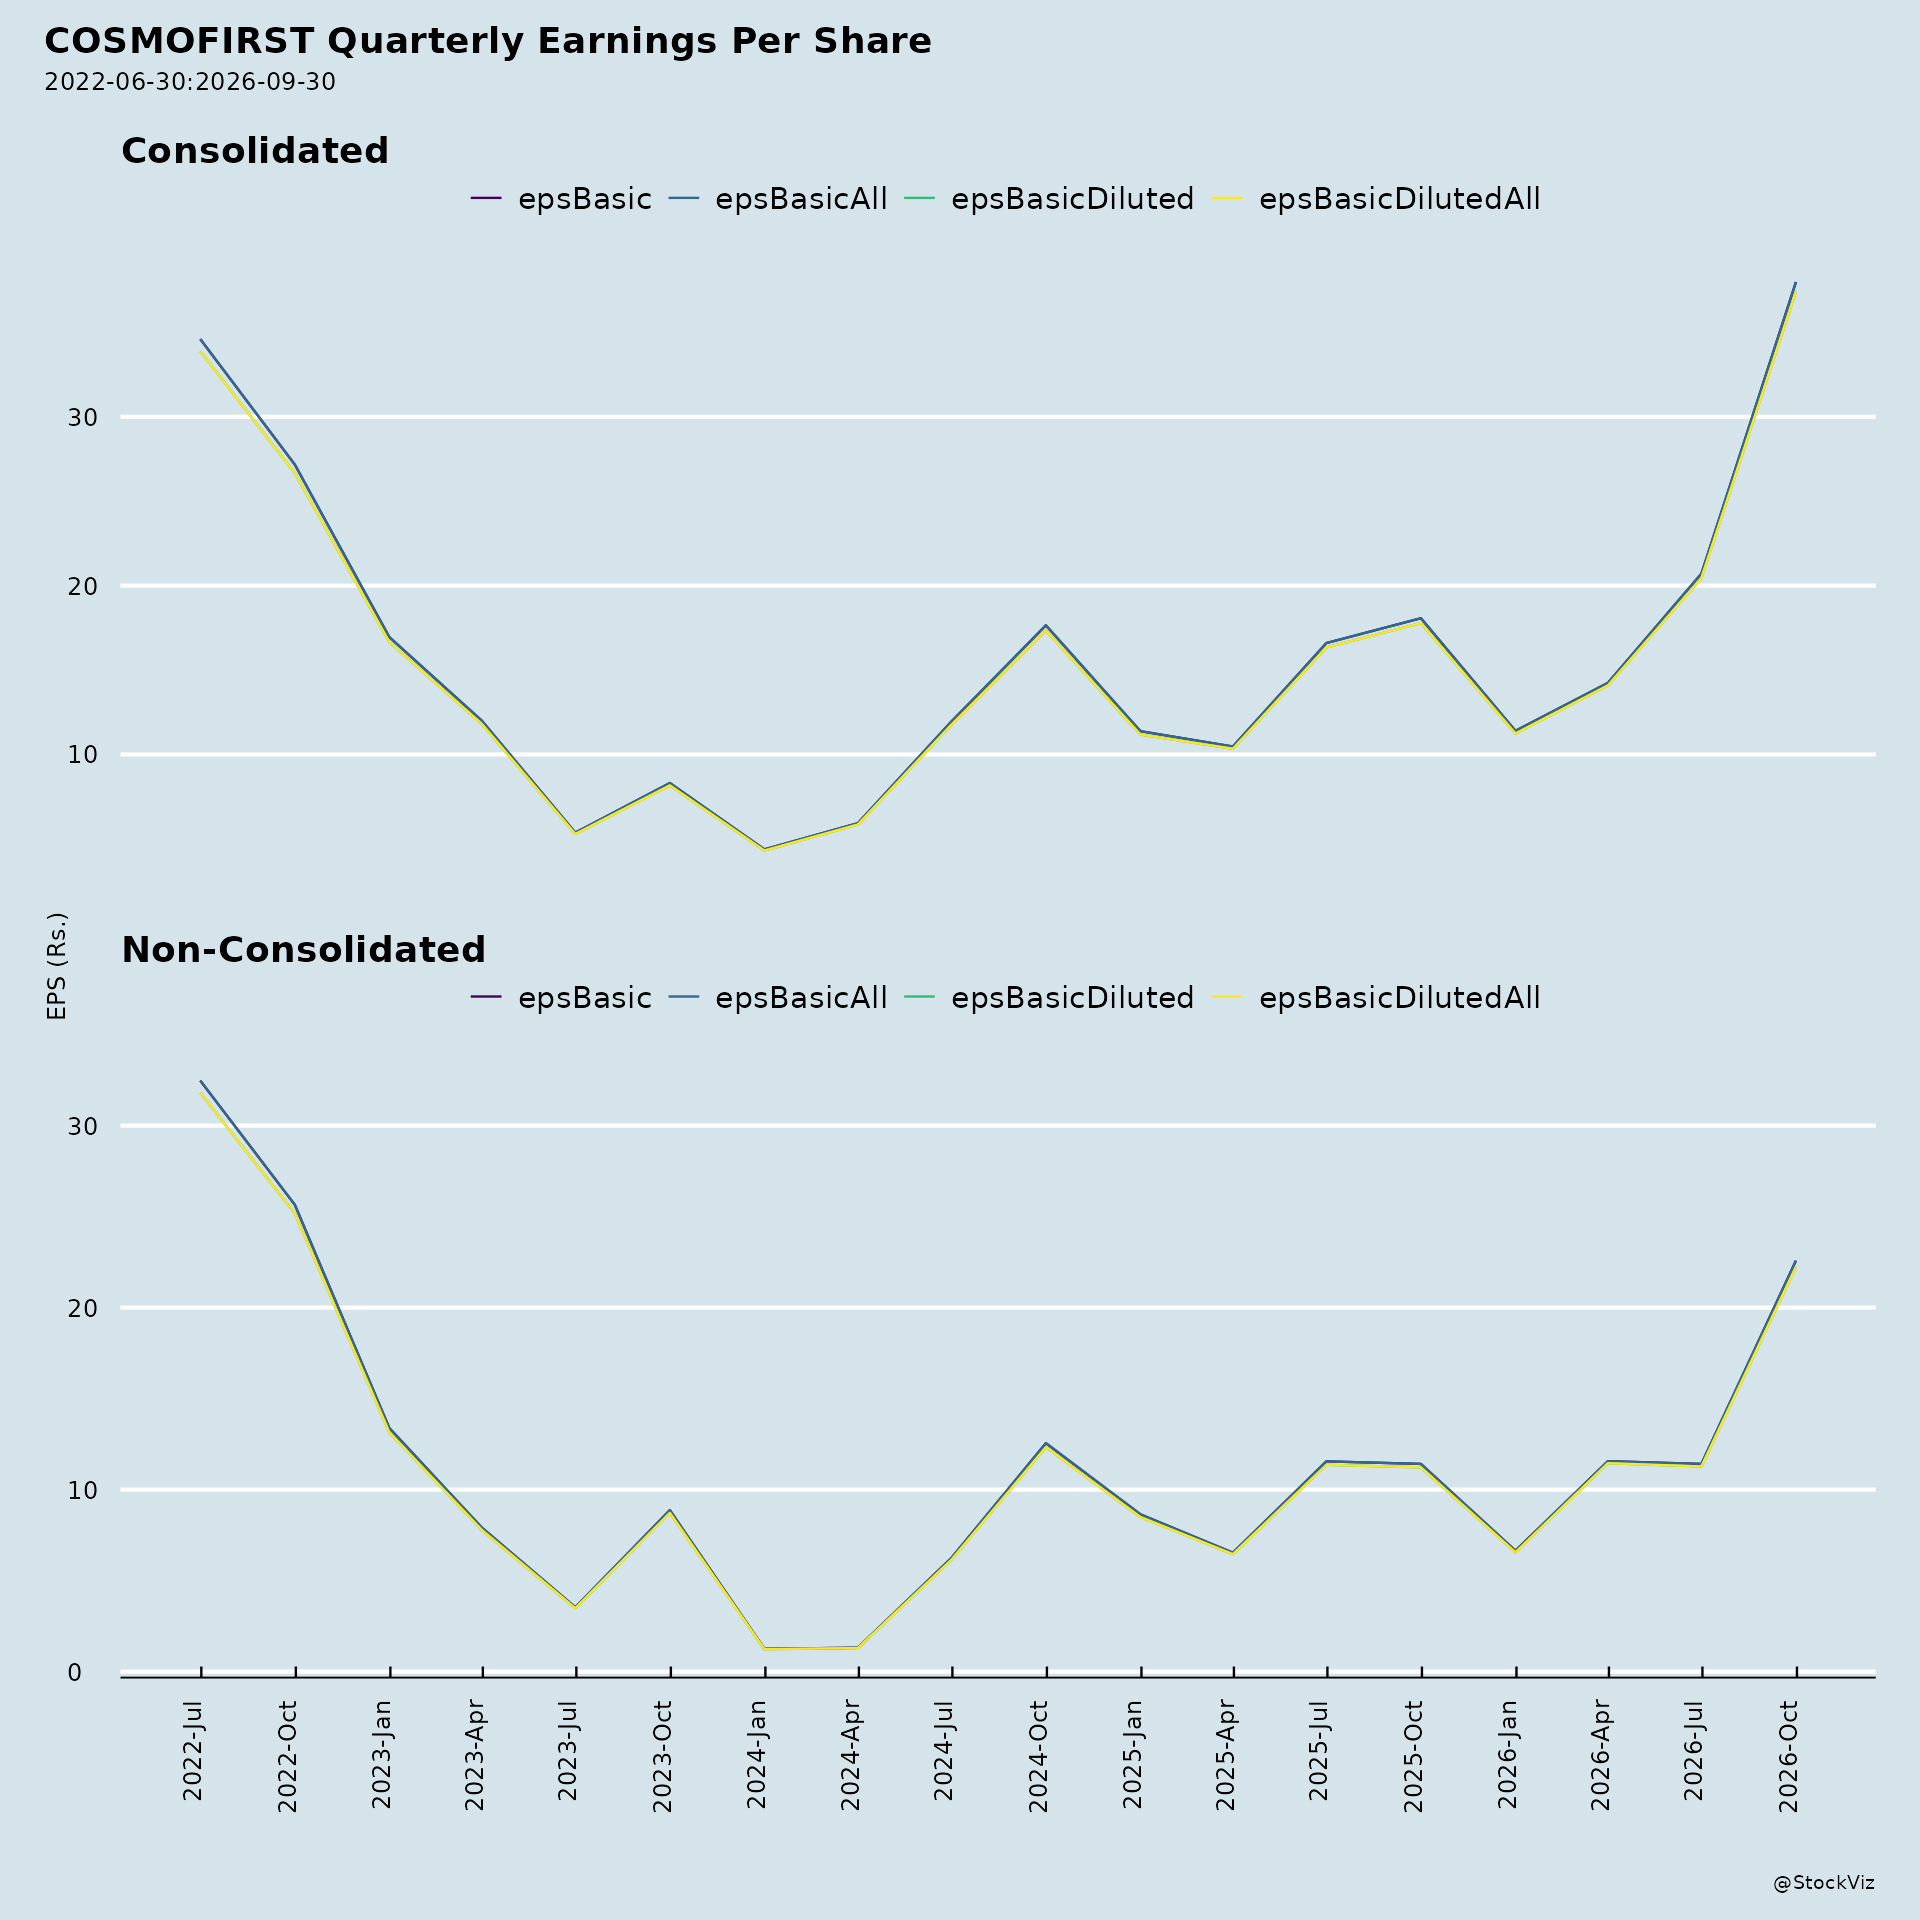
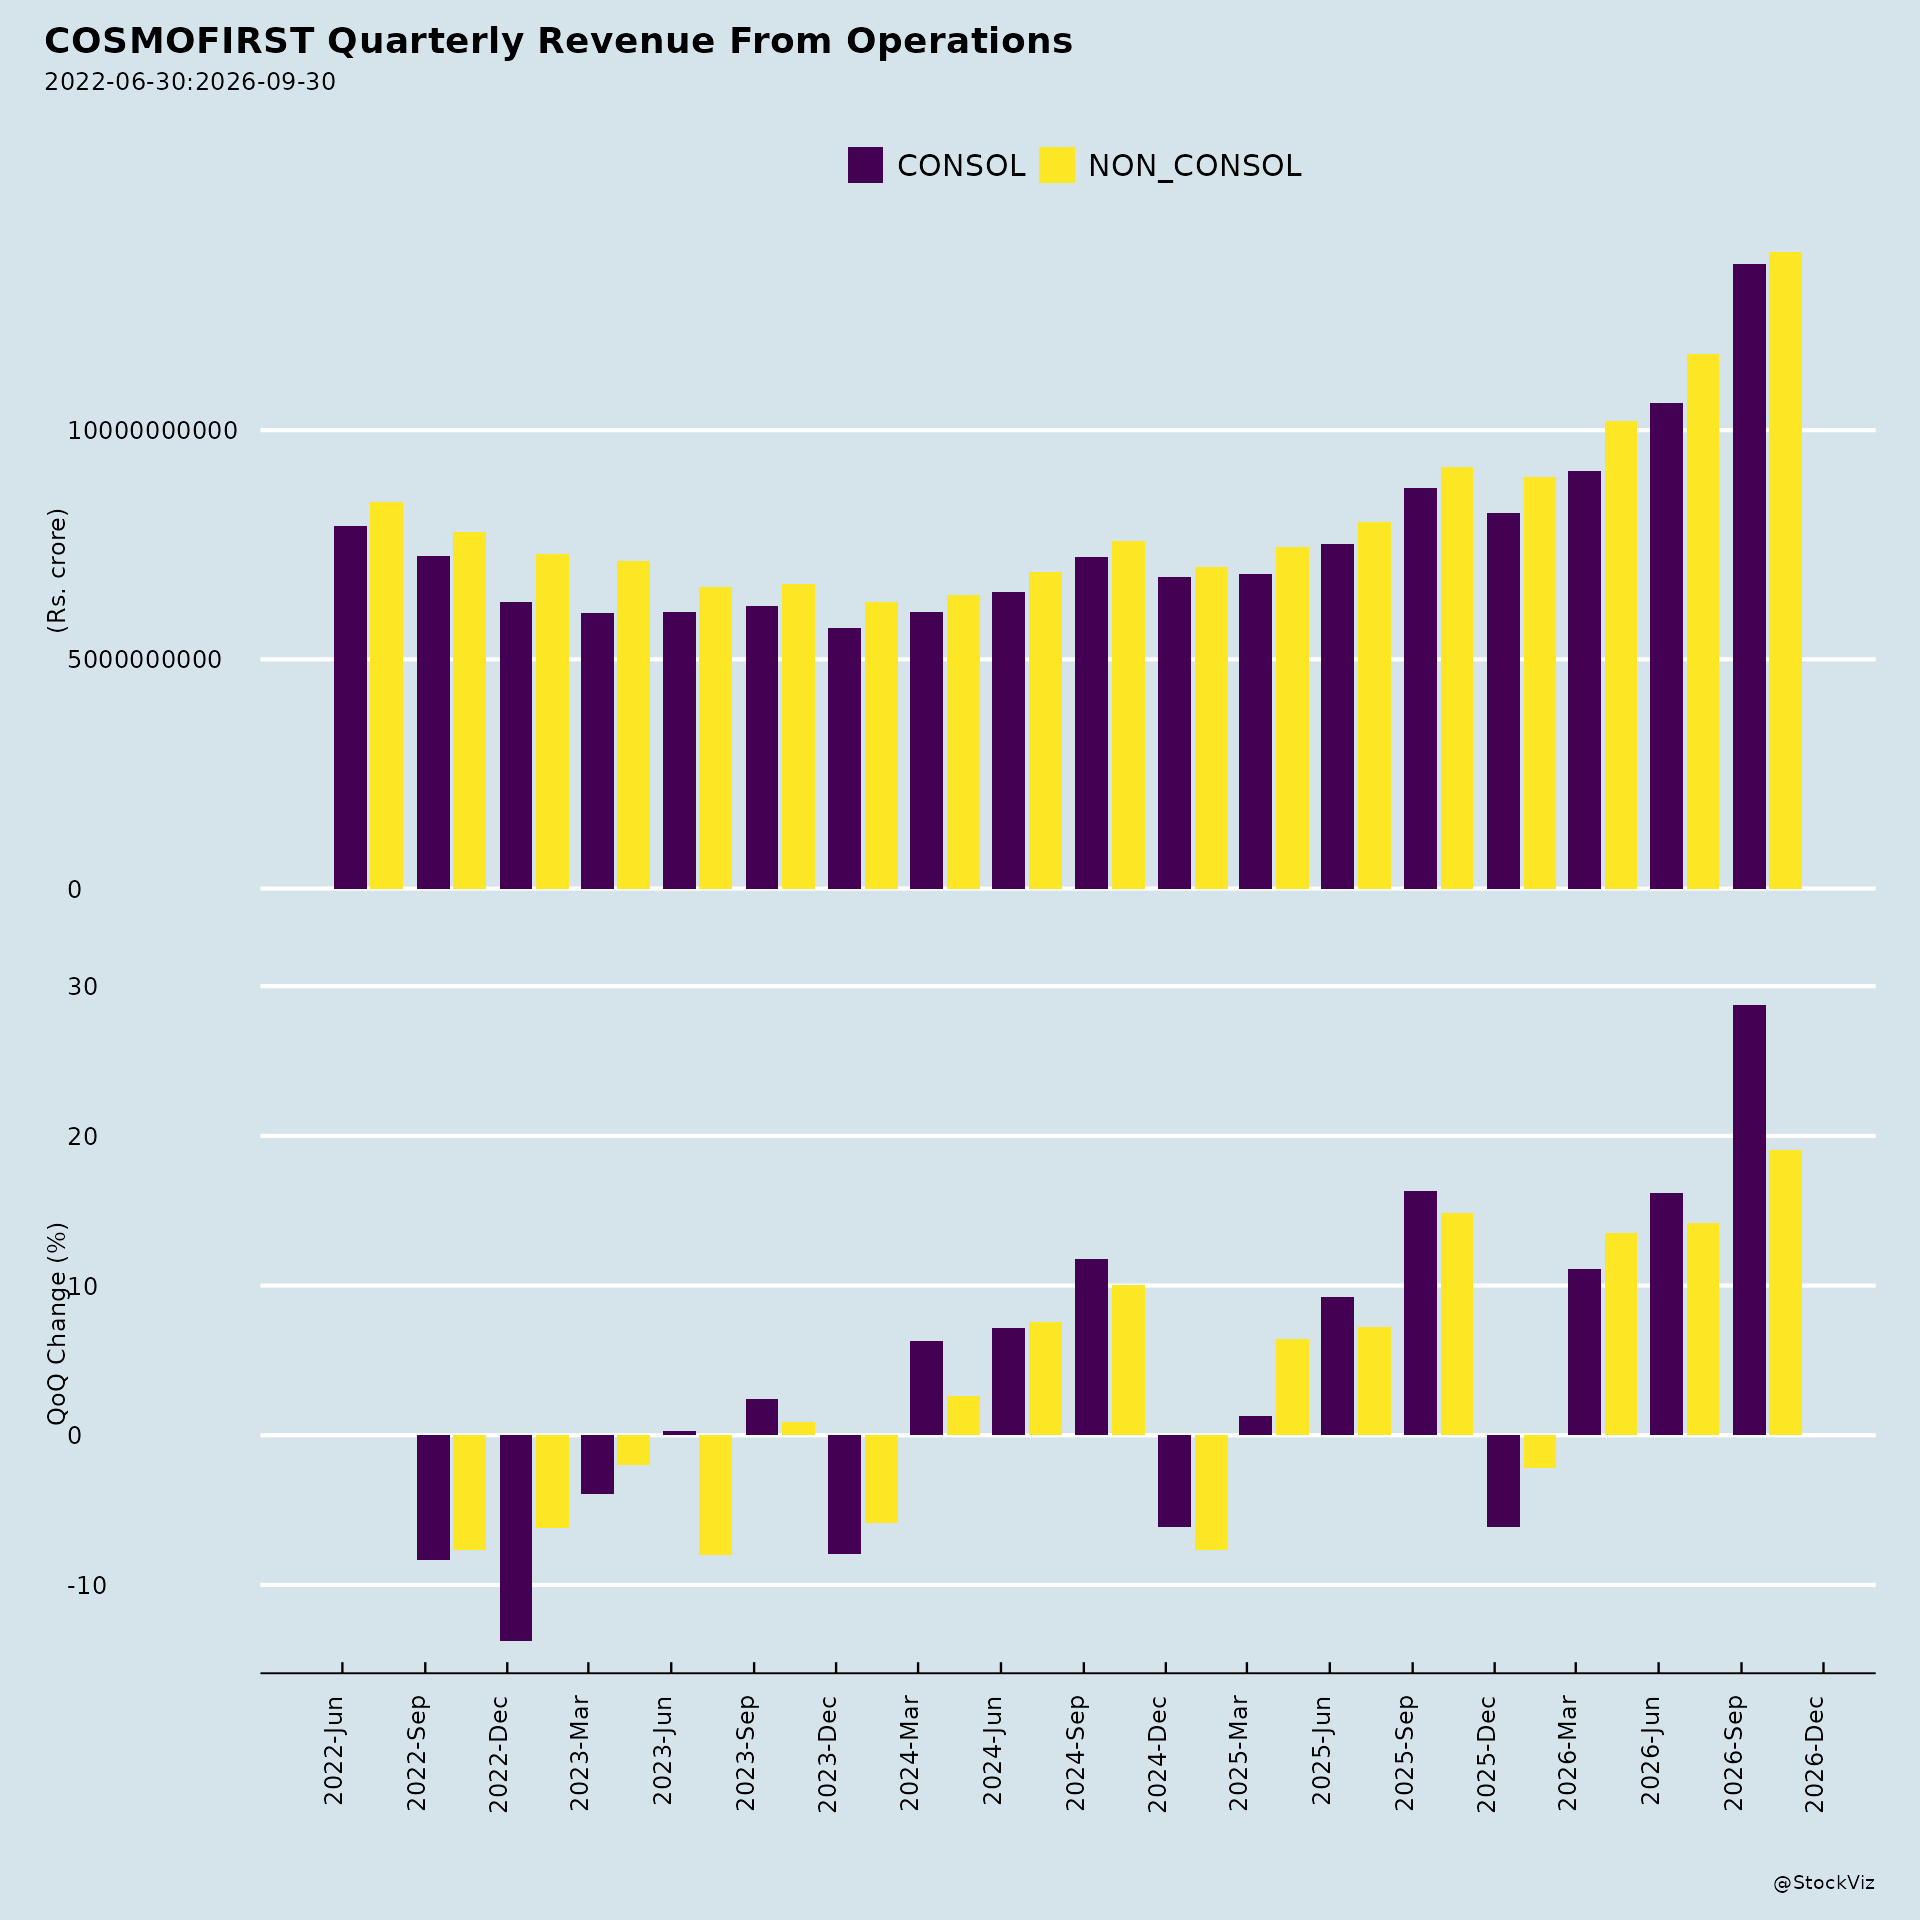
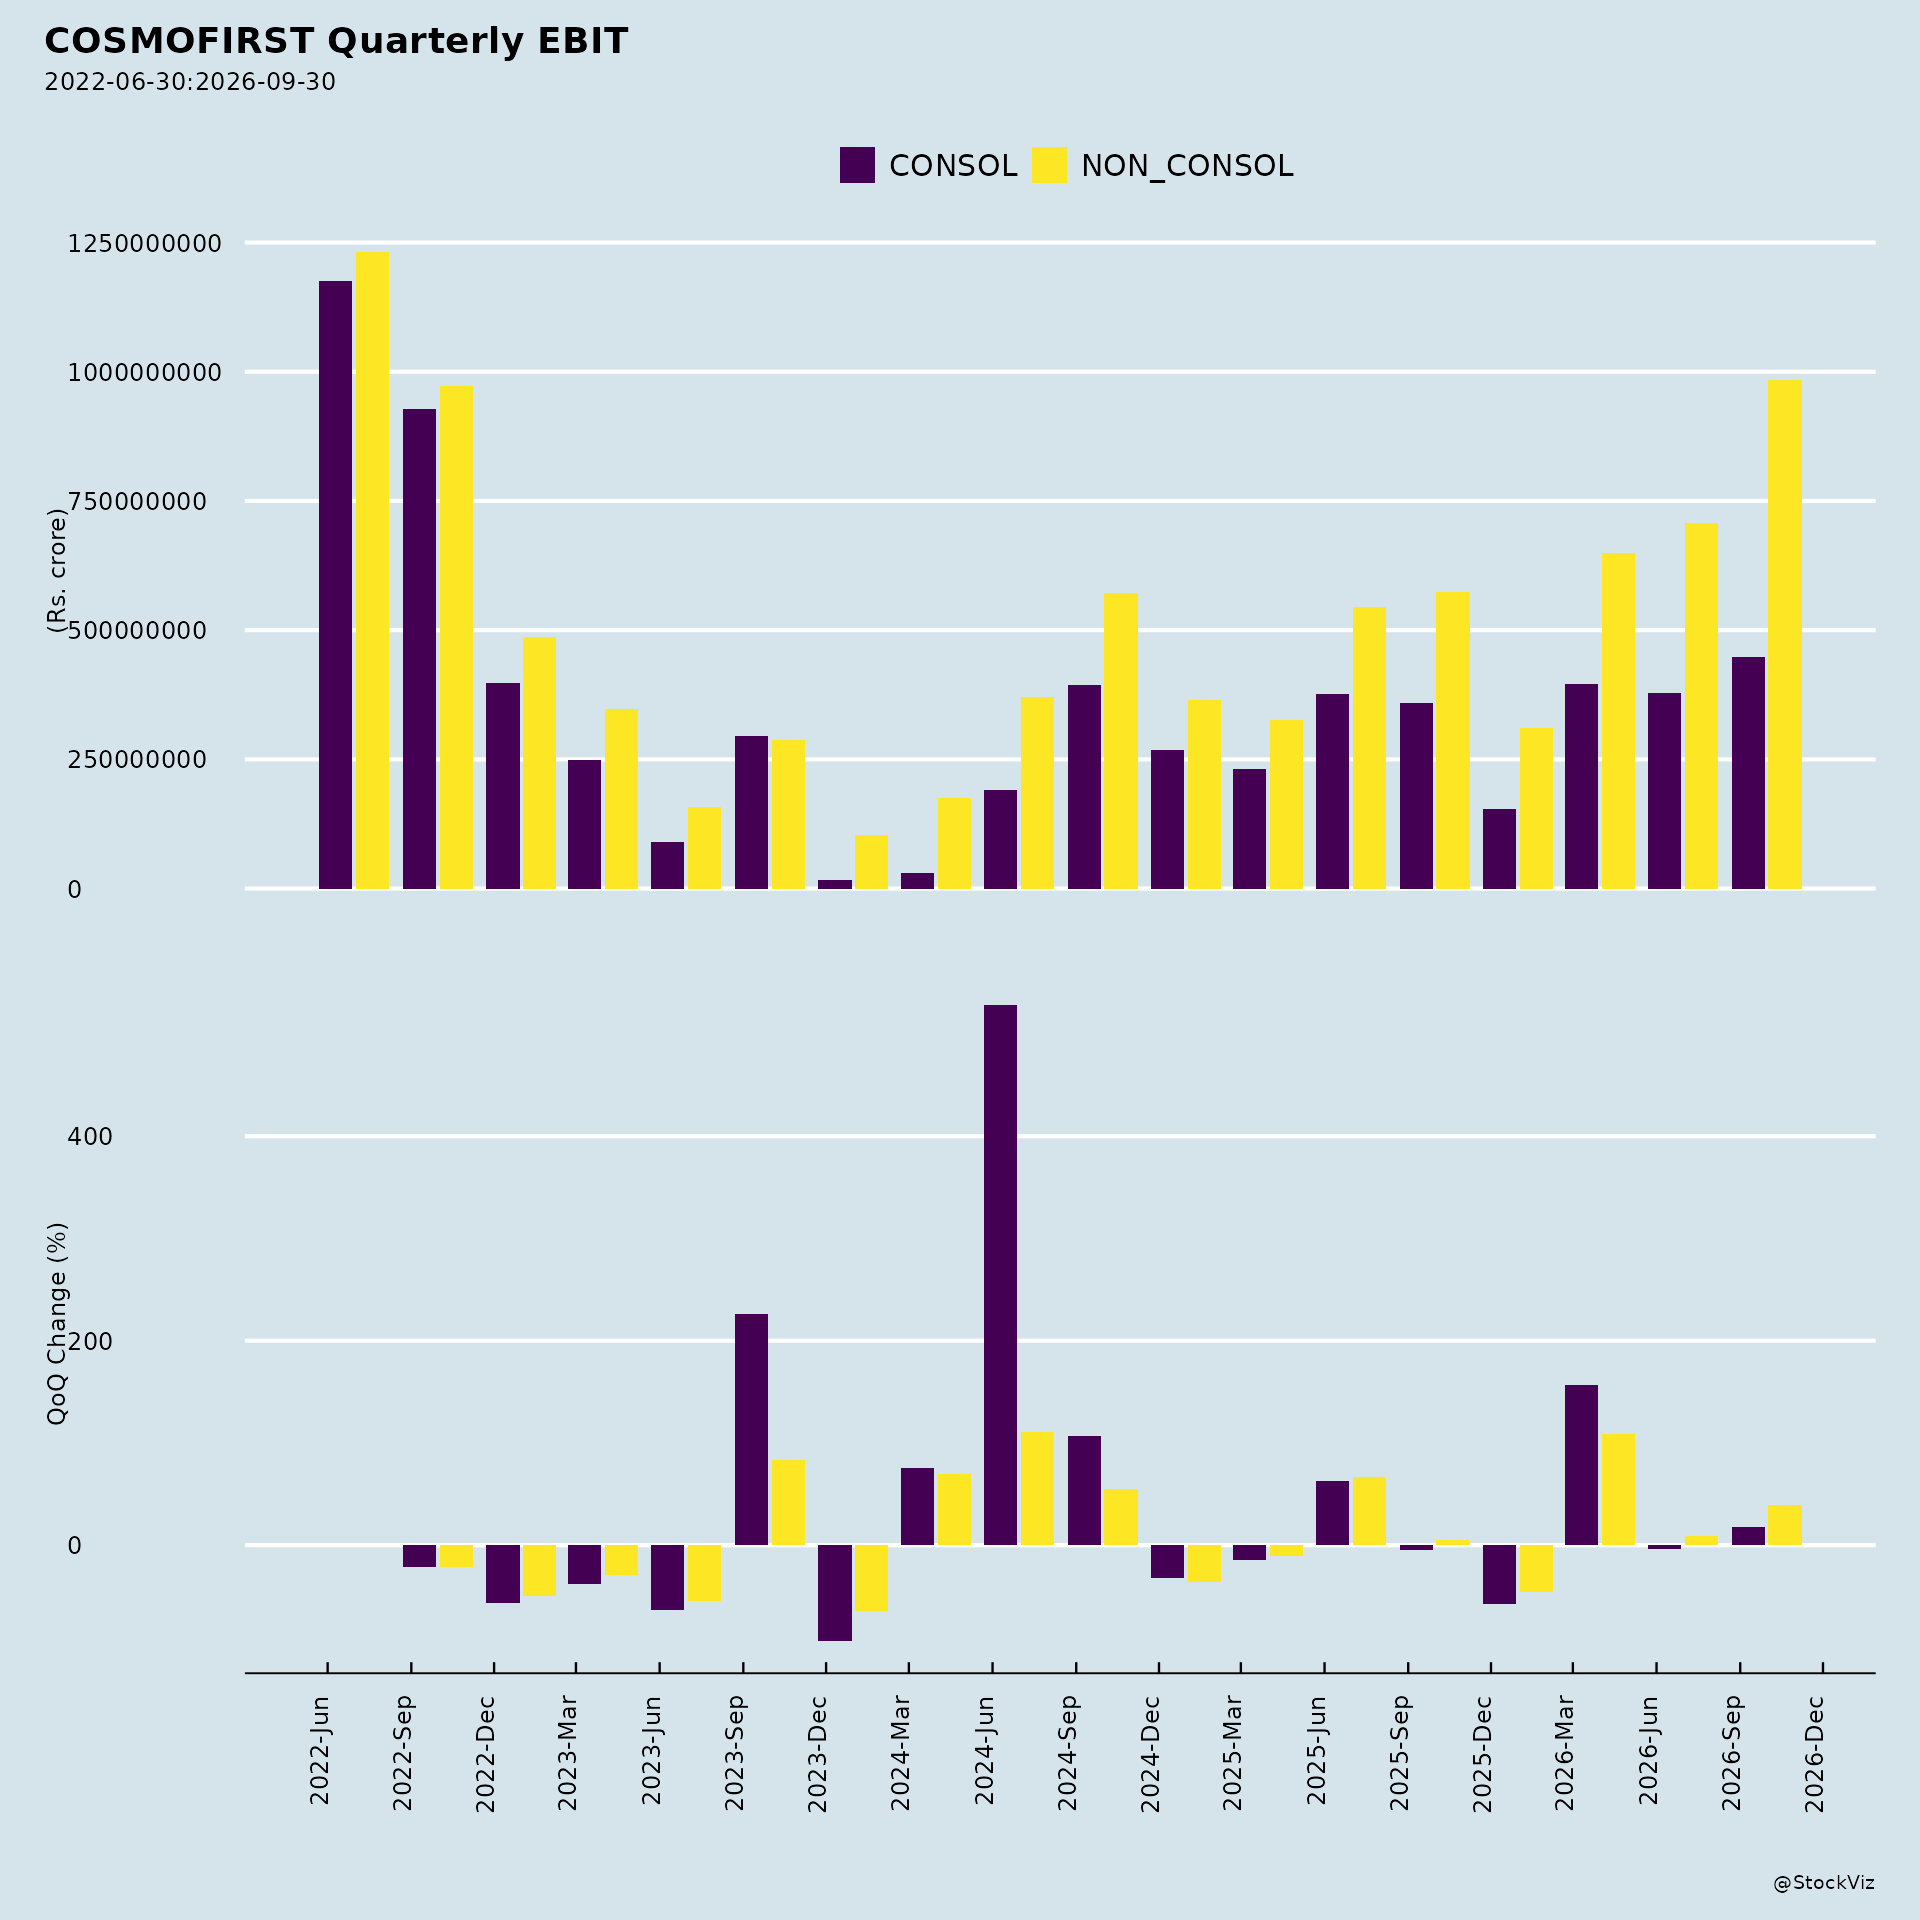
- Q1 FY27 consolidated performance: Net revenue of Rs 1,166 crores (versus Rs 800 crores in Q1 FY26), EBITDA of Rs 147 crores (versus Rs 116 crores), PBT of Rs 71 crores (versus Rs 54 crores), PAT of Rs 54 crores (versus Rs 43 crores), and EPS of Rs 20.7 (versus Rs 16.6).
- Volume and margin drivers: EBITDA improvement was attributed to higher sales volume (9%), improved base BOPP and BOPET films margins, enhanced performance of the USA film business post reduction in USA tariffs, and better performance by specialty chemical and rigid packaging.
- Specialty Chemicals: 34% topline growth year-on-year with 25% EBITDA in Q1 FY27.
- Cosmo Plastech (Rigid Packaging): Over 58% topline growth year-on-year in Q1 FY27 and turned EBIT positive. The business is augmenting 50% capacity growth over the next two quarters through minimal capex.
- Consumer-facing businesses: Zigly (Petcare) grew 70% year-on-year; Cosmo Consumer (window films, paint protection films, ceramic coatings) grew multi-fold, with FY25-26 being its first year of operation.
- US tariff reversal: Post reversal of additional customs duty imposed in FY25-26 on imports from India into the USA, the US subsidiary received a refund of about USD 7 million in July 2026, not yet appropriated pending finalisation of customers’ refunds.
- Joint venture: A 50:50 joint venture with Filmax Corporation, Korea — Filmax Cosmo Korea Limited — was incorporated on 15 May 2026 for distribution, sale and marketing of flexible packaging and other products.
- Product and market expansion: SIES SOP Star Awards 2026 (three awards), a Mexican patent for a multilayer metallized cast polypropylene film, UV additive-embedded Green Graphic films, a first 4C Cosmo Car Care Centre in Pune, four new Zigly retail centres, dairy market onboarding and new freezer-grade/barrier packaging in Plastech, and FIPSA 2026 awards for responsible packaging.
- Certifications: ISO 45001:2018 certification secured for Waluj, Shendra and Karjan units.
3. Key Risks
- Leverage and debt servicing: Net debt at 2.3x EBITDA, with finance costs of Rs 38.36 crores in Q1 FY27 (versus Rs 31.71 crores in Q1 FY26), rising year-on-year.
- Commodity/input price volatility: The working capital increase was directly linked to raw material prices after the West Asia conflict, exposing the business to input cost swings.
- Continued losses in new businesses: Petcare and Cosmo Consumer remain loss-making at the segment level, requiring sustained investment before contributing positively.
- Regulatory and tax exposure: The tax position depends on management’s assessment of the timing of exercising the concessional tax regime option, with final-year adjustments deferred to Q4.
- Subsidiary governance/control incident: The unauthorised bank transfer matter at the Netherlands subsidiary resulted in a provision, highlighting operational control risk in overseas operations.
- Unreviewed subsidiary financials: The consolidated results include one subsidiary reviewed by another auditor (revenues Rs 145.91 crores, PAT Rs 14.05 crores) and five subsidiaries not reviewed (revenues Rs 32.55 crores, PAT Rs 2.79 crores), plus an unreviewed joint venture.
- Customer refund exposure: The USD 7 million US customs refund has not been appropriated pending finalisation of customers’ refunds, leaving a contingent outflow.
4. Management Guidance Versus Observed Performance
- Revenue growth guidance: Management stated FY26-27 revenue should grow at 20% on an overall basis, with the four new businesses expected to grow 60%. Observed: Q1 FY27 consolidated revenue of Rs 1,166 crores versus Rs 800 crores in Q1 FY26 represents approximately 46% year-on-year growth, above the full-year guidance pace. Segment data show Specialty Chemicals at Rs 66.20 crores, Cosmo Plastech at Rs 36.09 crores, Cosmo Consumer at Rs 11.15 crores and Petcare at Rs 49.36 crores for Q1 FY27.
- Net debt reduction: Management stated net debt will reduce significantly in the next two years. Observed: net debt at June 2026 end was flat at the Q4 FY26 level of Rs 1,166 crores, with the working capital increase of Rs 85 crores offsetting underlying cash generation.
- Rigid packaging profitability: Management stated FY27 focus shall be on achieving higher profitability through higher capacity utilisation, improving sales mix and improved efficiency, alongside 50% capacity augmentation over the next two quarters. Observed: Cosmo Plastech turned EBIT positive in Q1 FY27 with over 58% topline growth year-on-year.
- B2B profitability: Management stated all B2B businesses are profitable now, with FY27 focus on higher ROCE, specialty films sales, sweating out of assets and growing new B2B and B2C businesses. Observed: Packaging films, Specialty Chemicals and Cosmo Plastech all reported positive segment results in Q1 FY27, while Cosmo Consumer and Petcare remained negative.
- Specialty Chemicals momentum: The subsidiary continued to perform well with 34% topline growth year-on-year and 25% EBITDA in Q1 FY27, consistent with the stated scale-up trajectory.
- Capital returns: The 49th AGM on 5 August 2026 approved a dividend of 40% (Rs 4 per equity share), alongside adoption of FY26 audited financial statements and re-appointment of directors.
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.