CIPLA
Equity Metrics
November 18, 2026
Cipla Limited
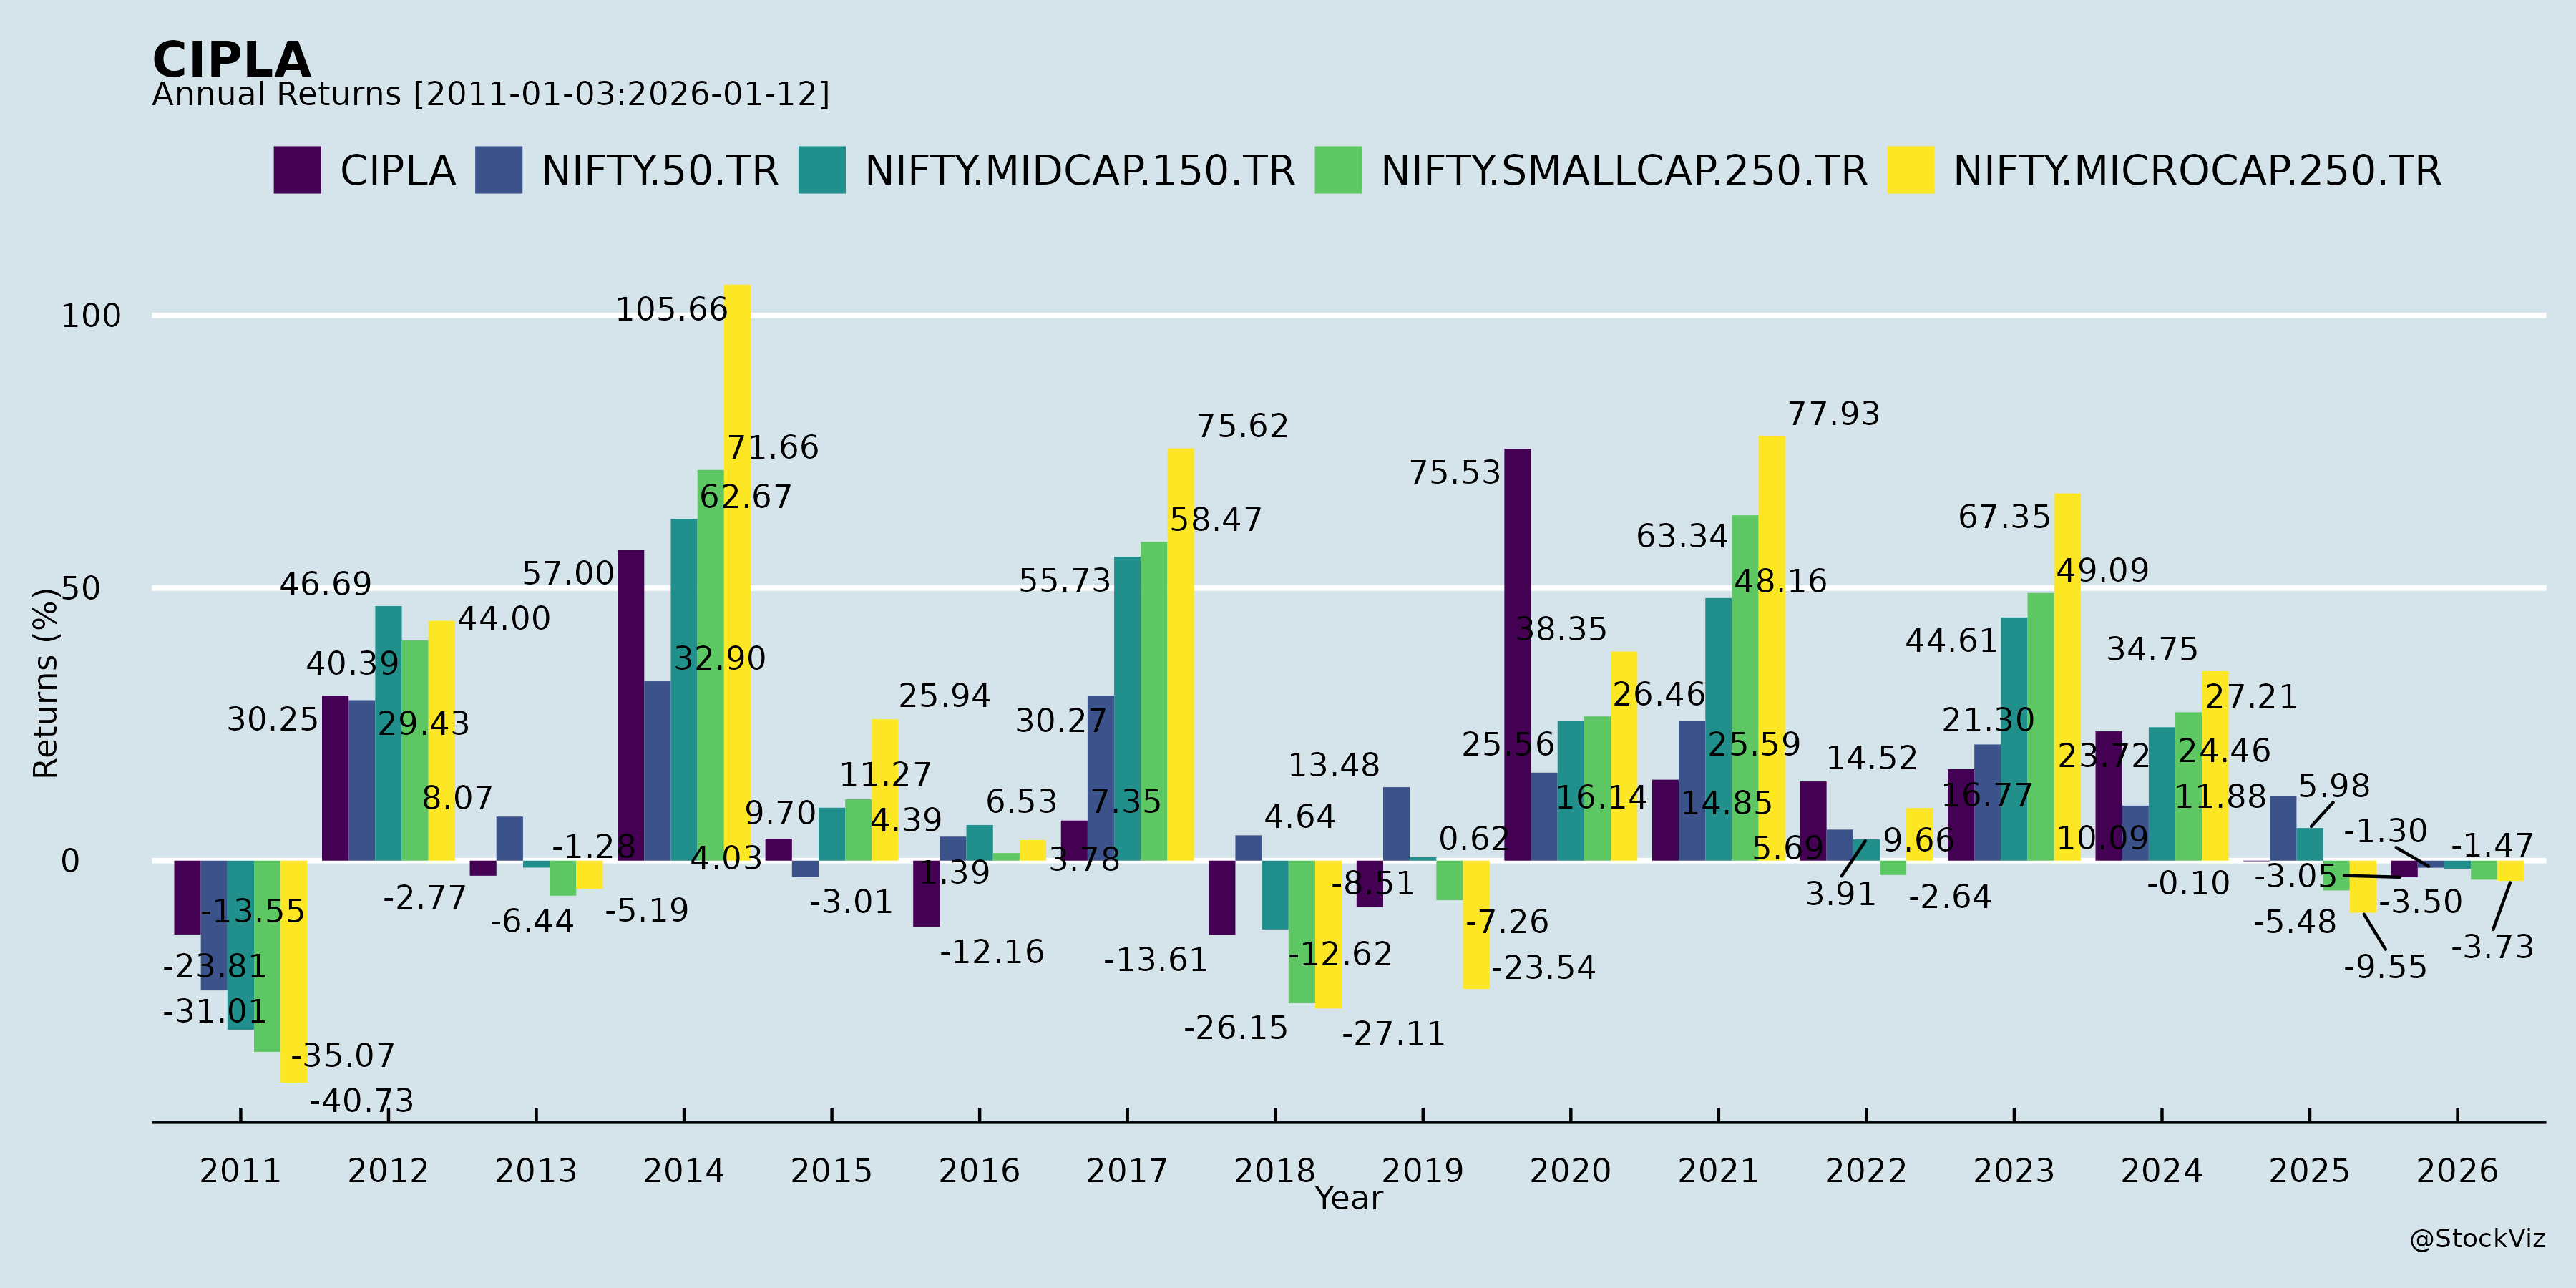
Annual Returns
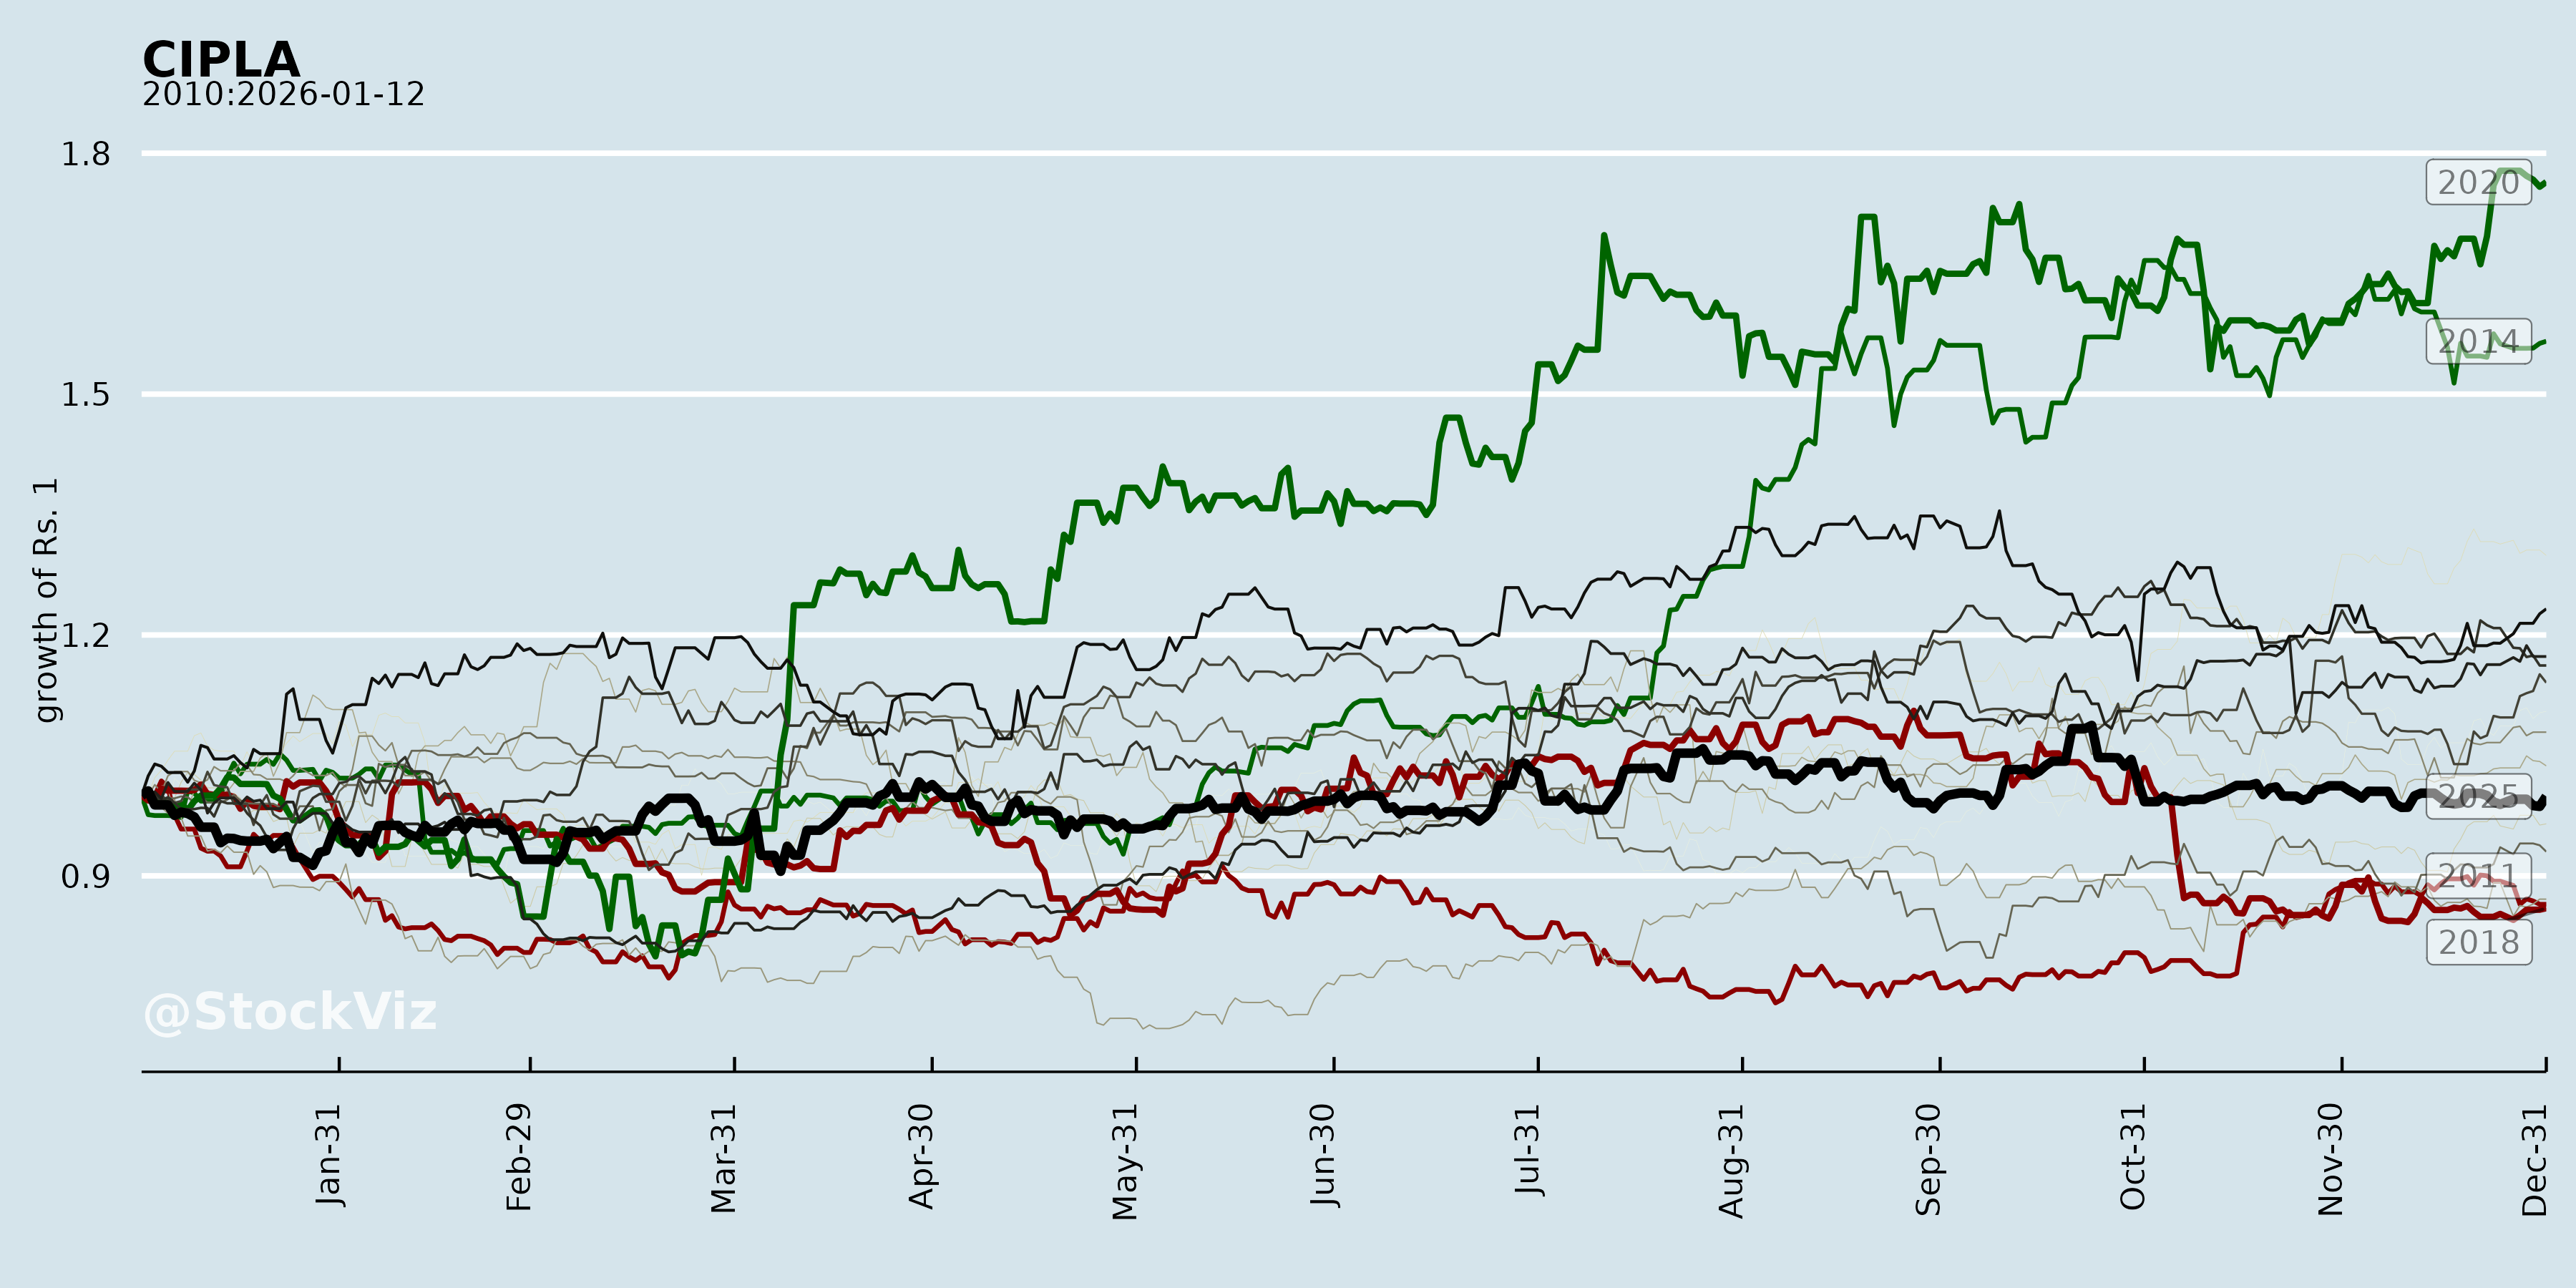
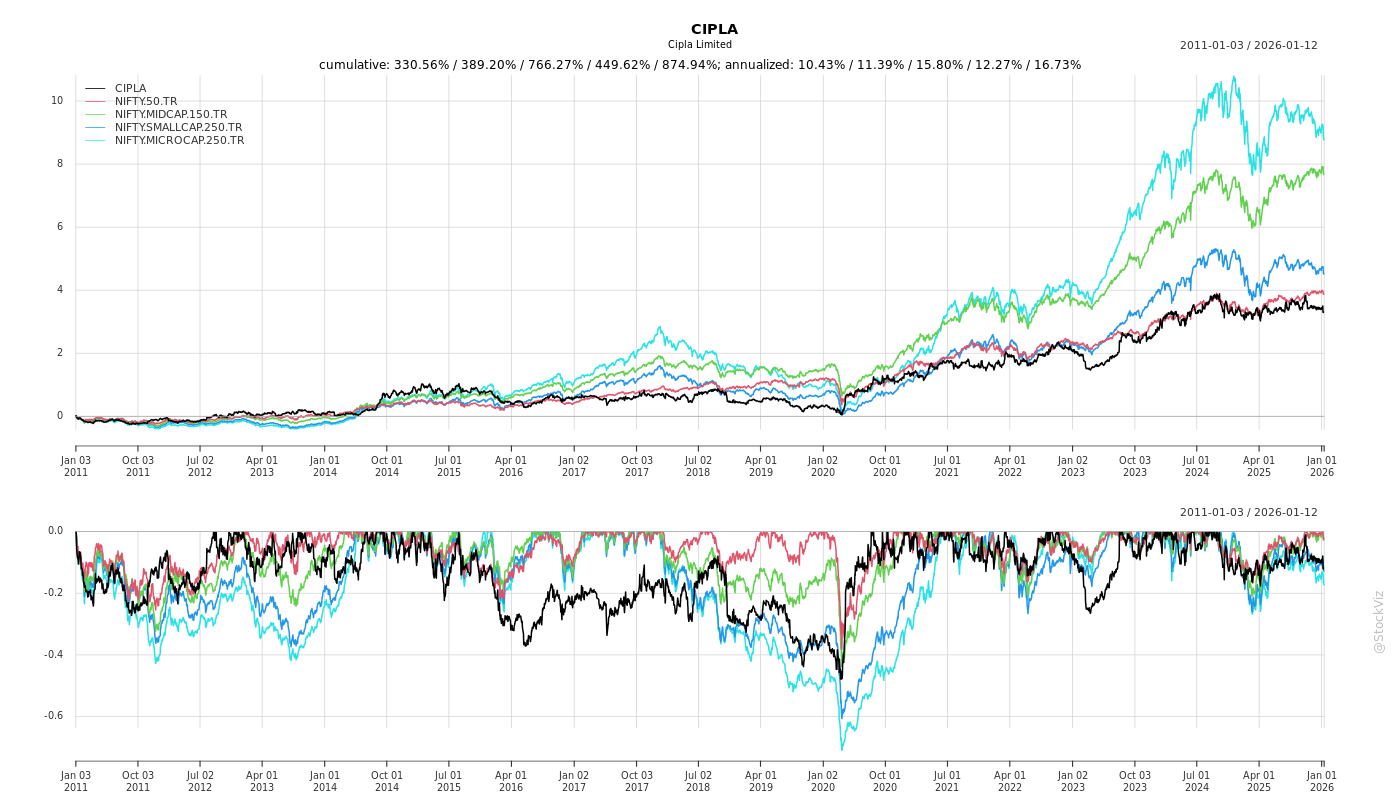
Cumulative Returns and Drawdowns
Fundamentals
Ownership
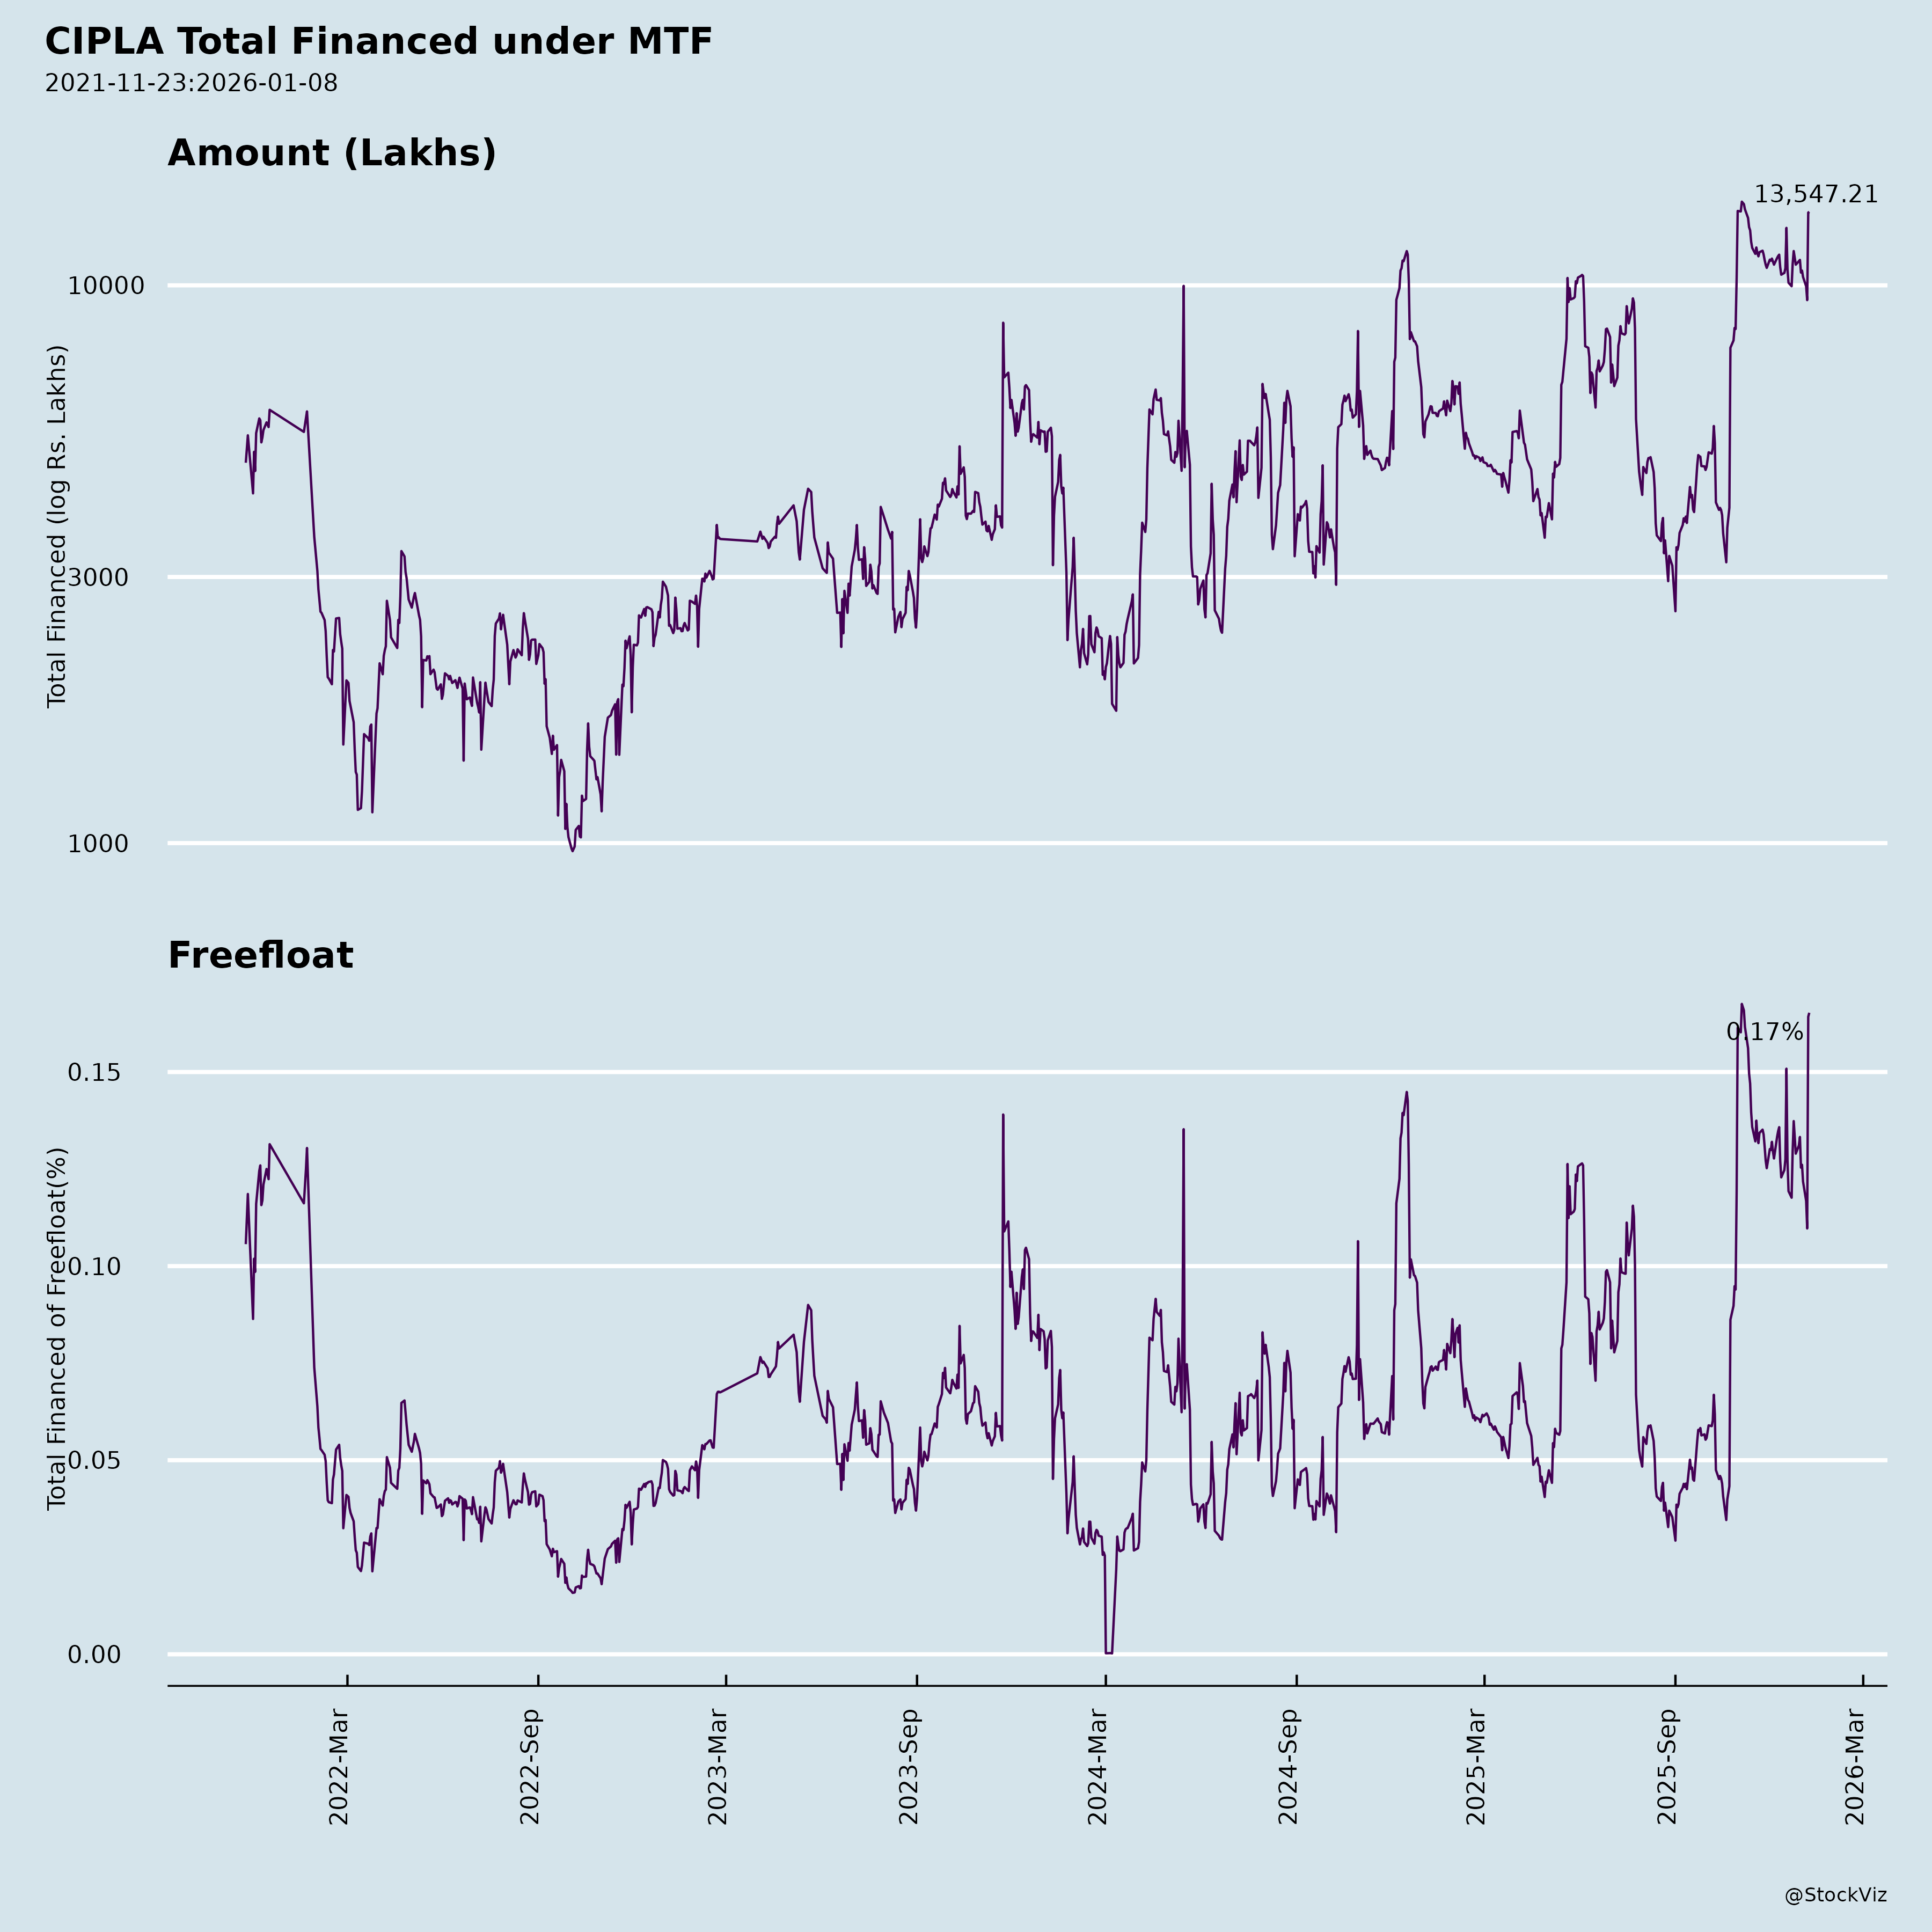
Margined
AI Summary
asof: 2026-09-14
Cipla: Recent Corporate Announcements — Summary
1. Headwinds and Challenges
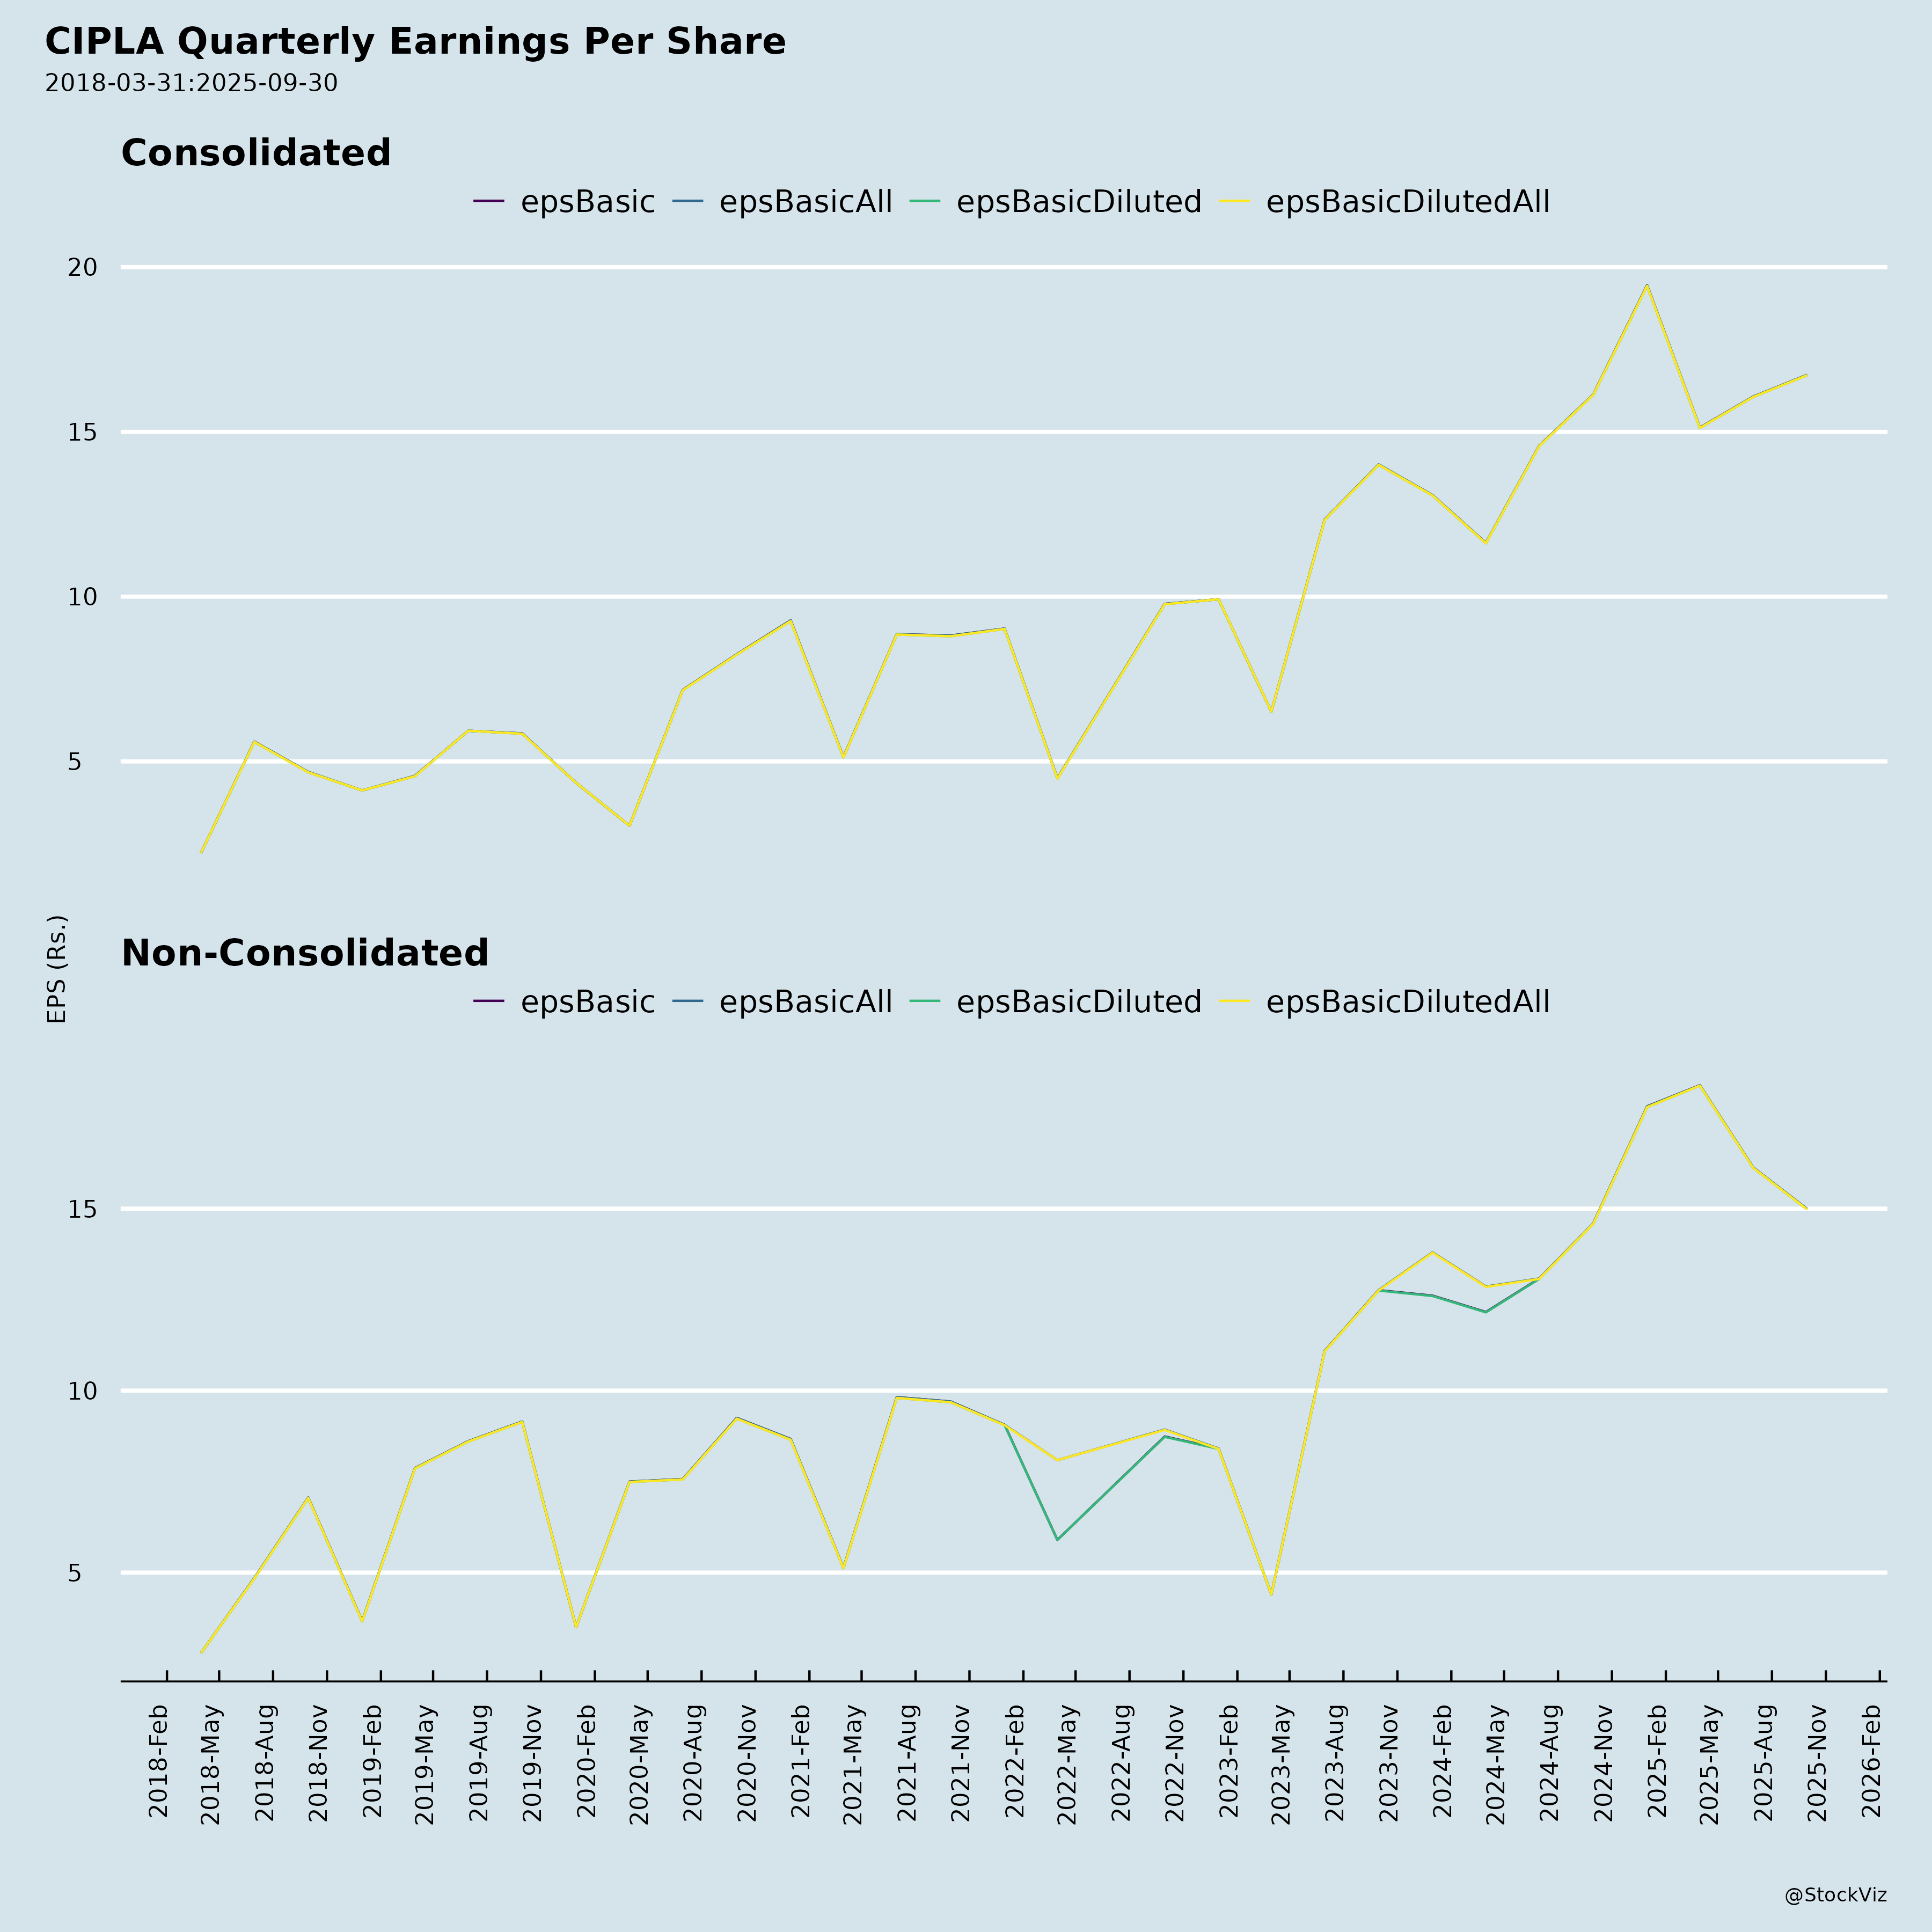
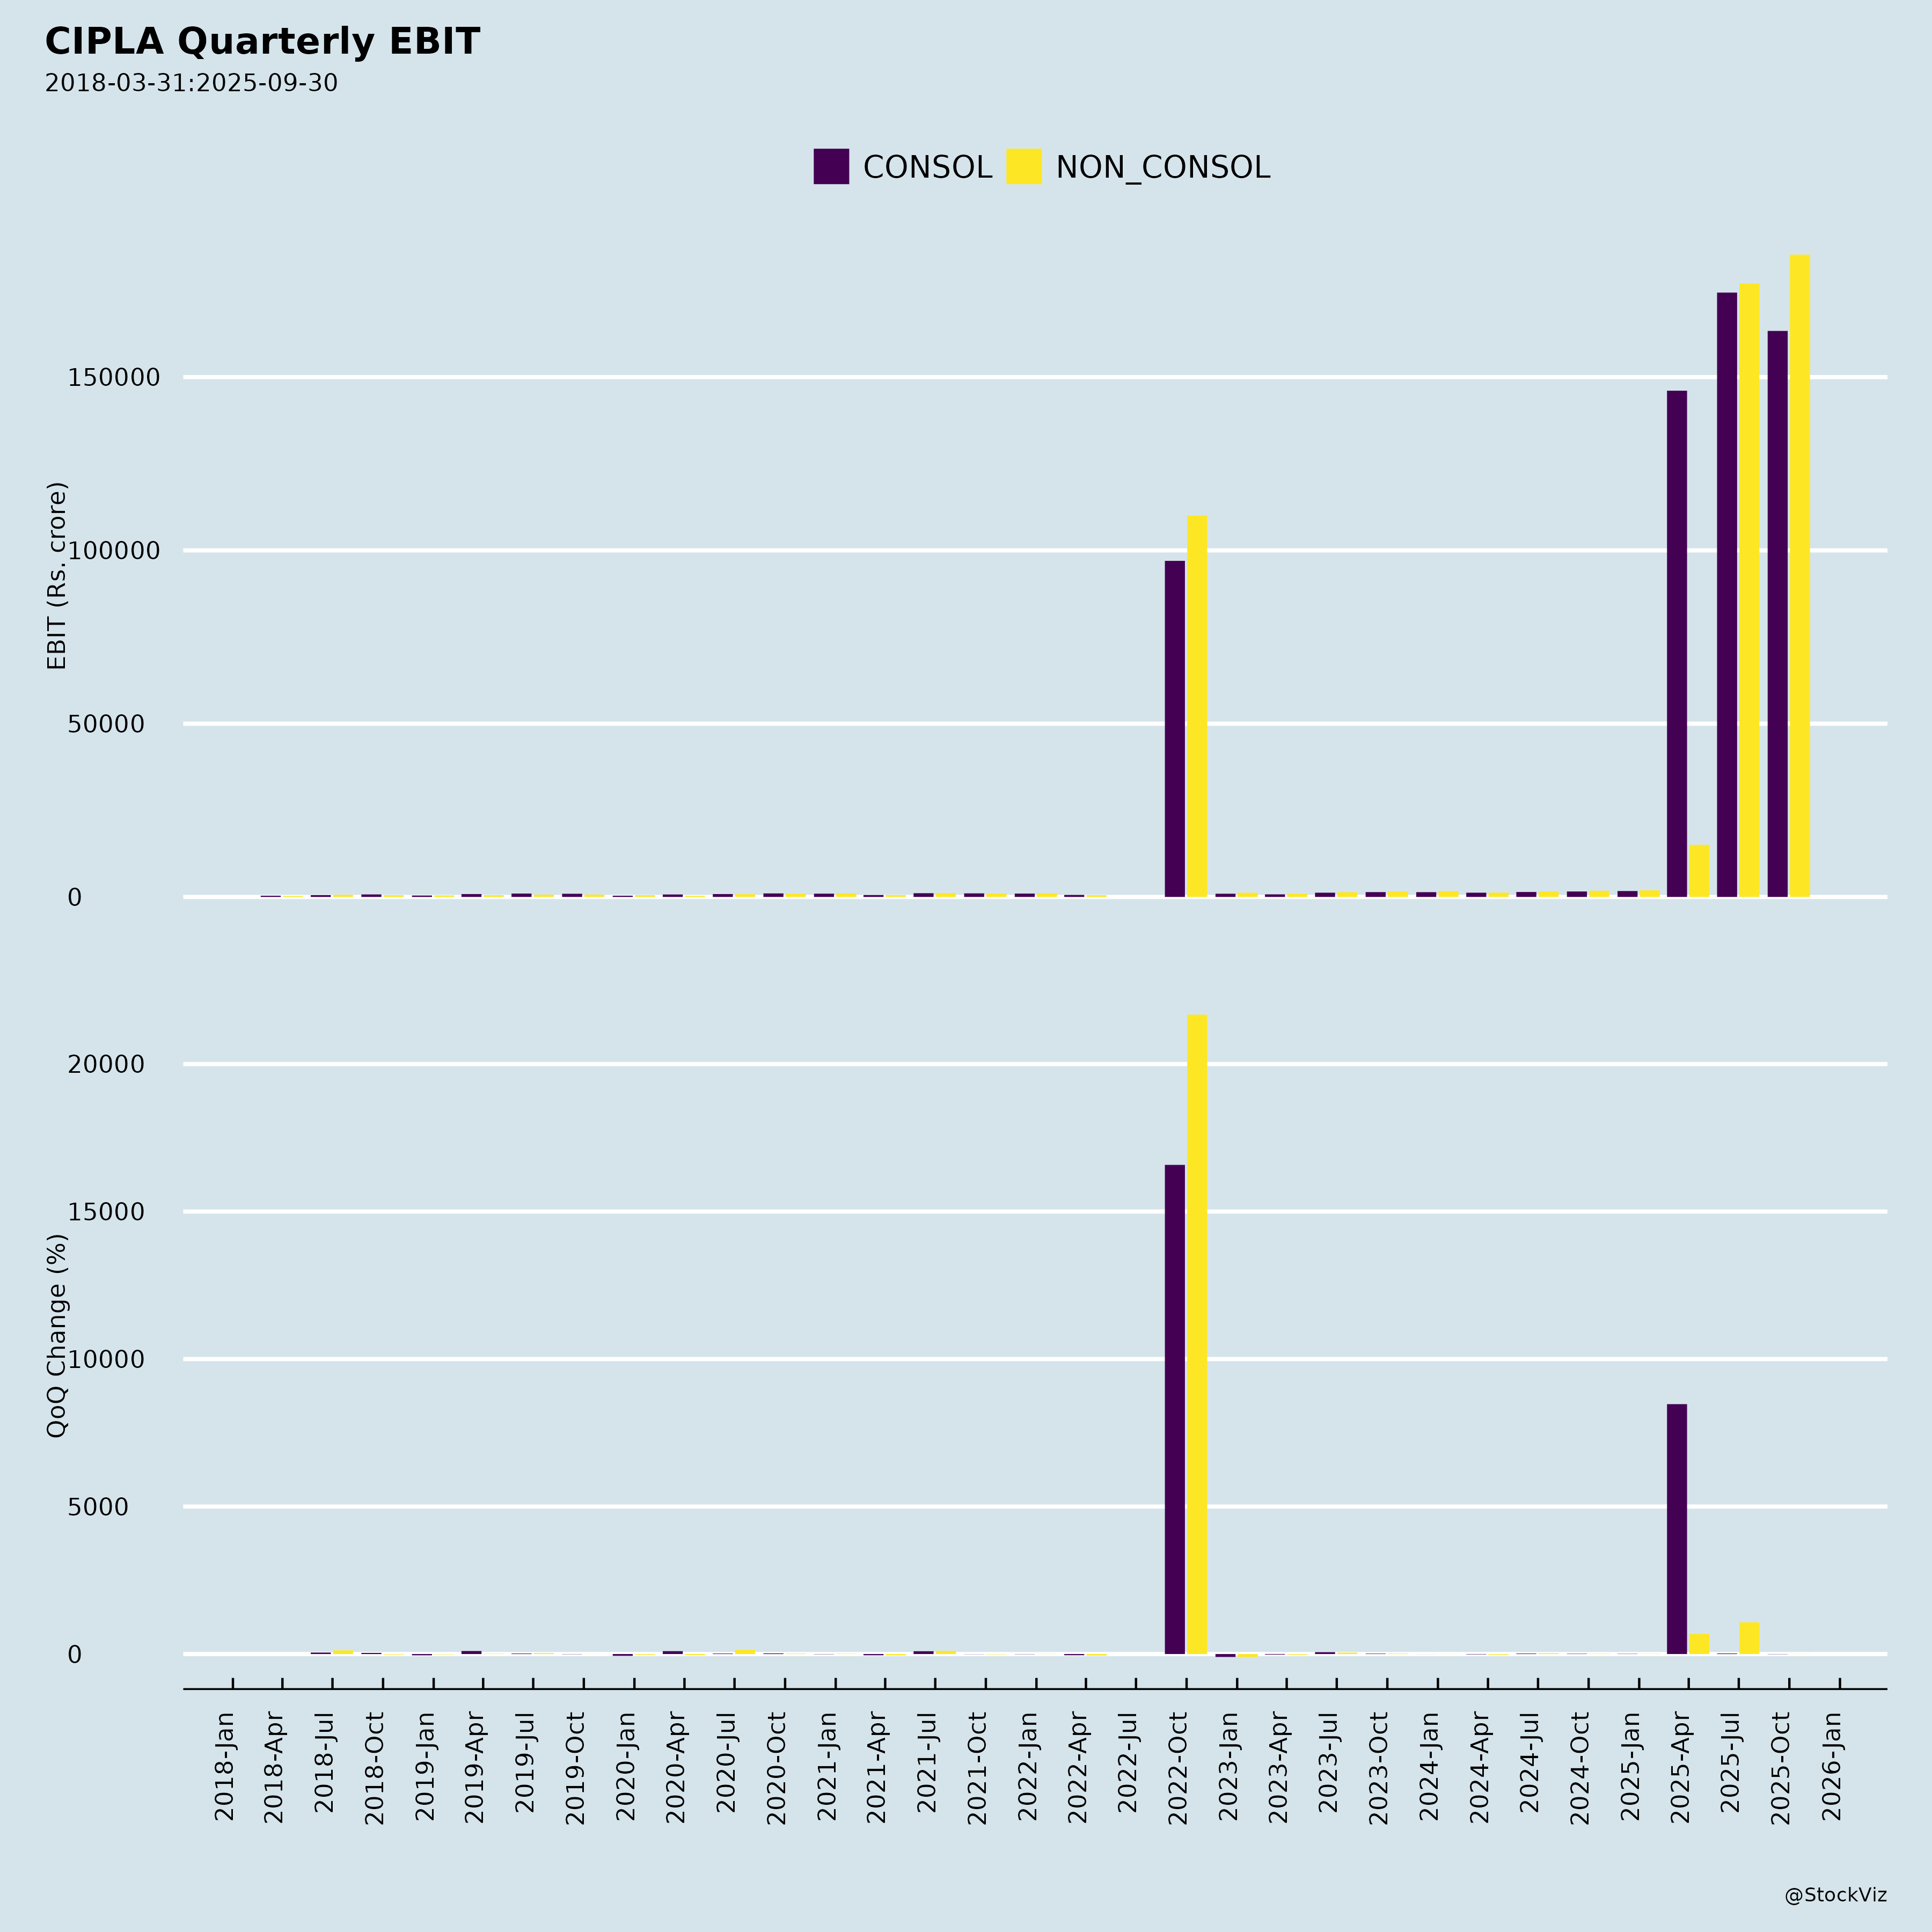
- Q1FY27 profitability declined sharply year-on-year. Revenue from operations rose to INR 7,119 Cr in Q1FY27 from INR 6,957 Cr in Q1FY26, but EBITDA fell to INR 1,192 Cr (16.7% margin) from INR 1,778 Cr (25.6%), and PAT fell to INR 789 Cr (11.1%) from INR 1,298 Cr (18.7%). Material cost rose to INR 2,667 Cr from INR 2,171 Cr, and employee benefits expense rose to INR 1,497 Cr from INR 1,312 Cr.
- Other operating income and other income declined. Other operating income fell to INR 42 Cr from INR 120 Cr; other income fell to INR 211 Cr from INR 259 Cr.
- North America requires adaptation to evolving business dynamics. The segment presentation is framed around adapting to these dynamics, with gVentolin supply ramp-up planned over coming quarters following initial shipments.
- South Africa OTC underperformed the market. Cipla OTC growth was 0.6% against market growth of 3.5%, although the prescription business (9.8% vs 6.9%) and overall business (6.5% vs 5.7%) grew faster than the market.
- The AGM MD & GCEO address was titled “Highest-ever Yearly Revenue Despite Multiple Headwinds,” indicating that headwinds were present through FY26 even as revenue reached a record.
- Forward-looking statement risk factors cited in the investor presentation include risks, uncertainties, pandemic and other factors, ability to implement strategy, growth and expansion plans, obtaining regulatory approvals, technological changes, earnings fluctuation, foreign exchange rates, international operations and exports, and market risks.
- Leadership transition. Mr Ashish Adukia relinquished the Global CFO and KMP position effective close of business on 23 July 2026, transitioning to an internal business leadership role; Mr Dinesh Jain was appointed Global CFO and KMP effective 24 July 2026.
2. Tailwinds and Growth Prospects
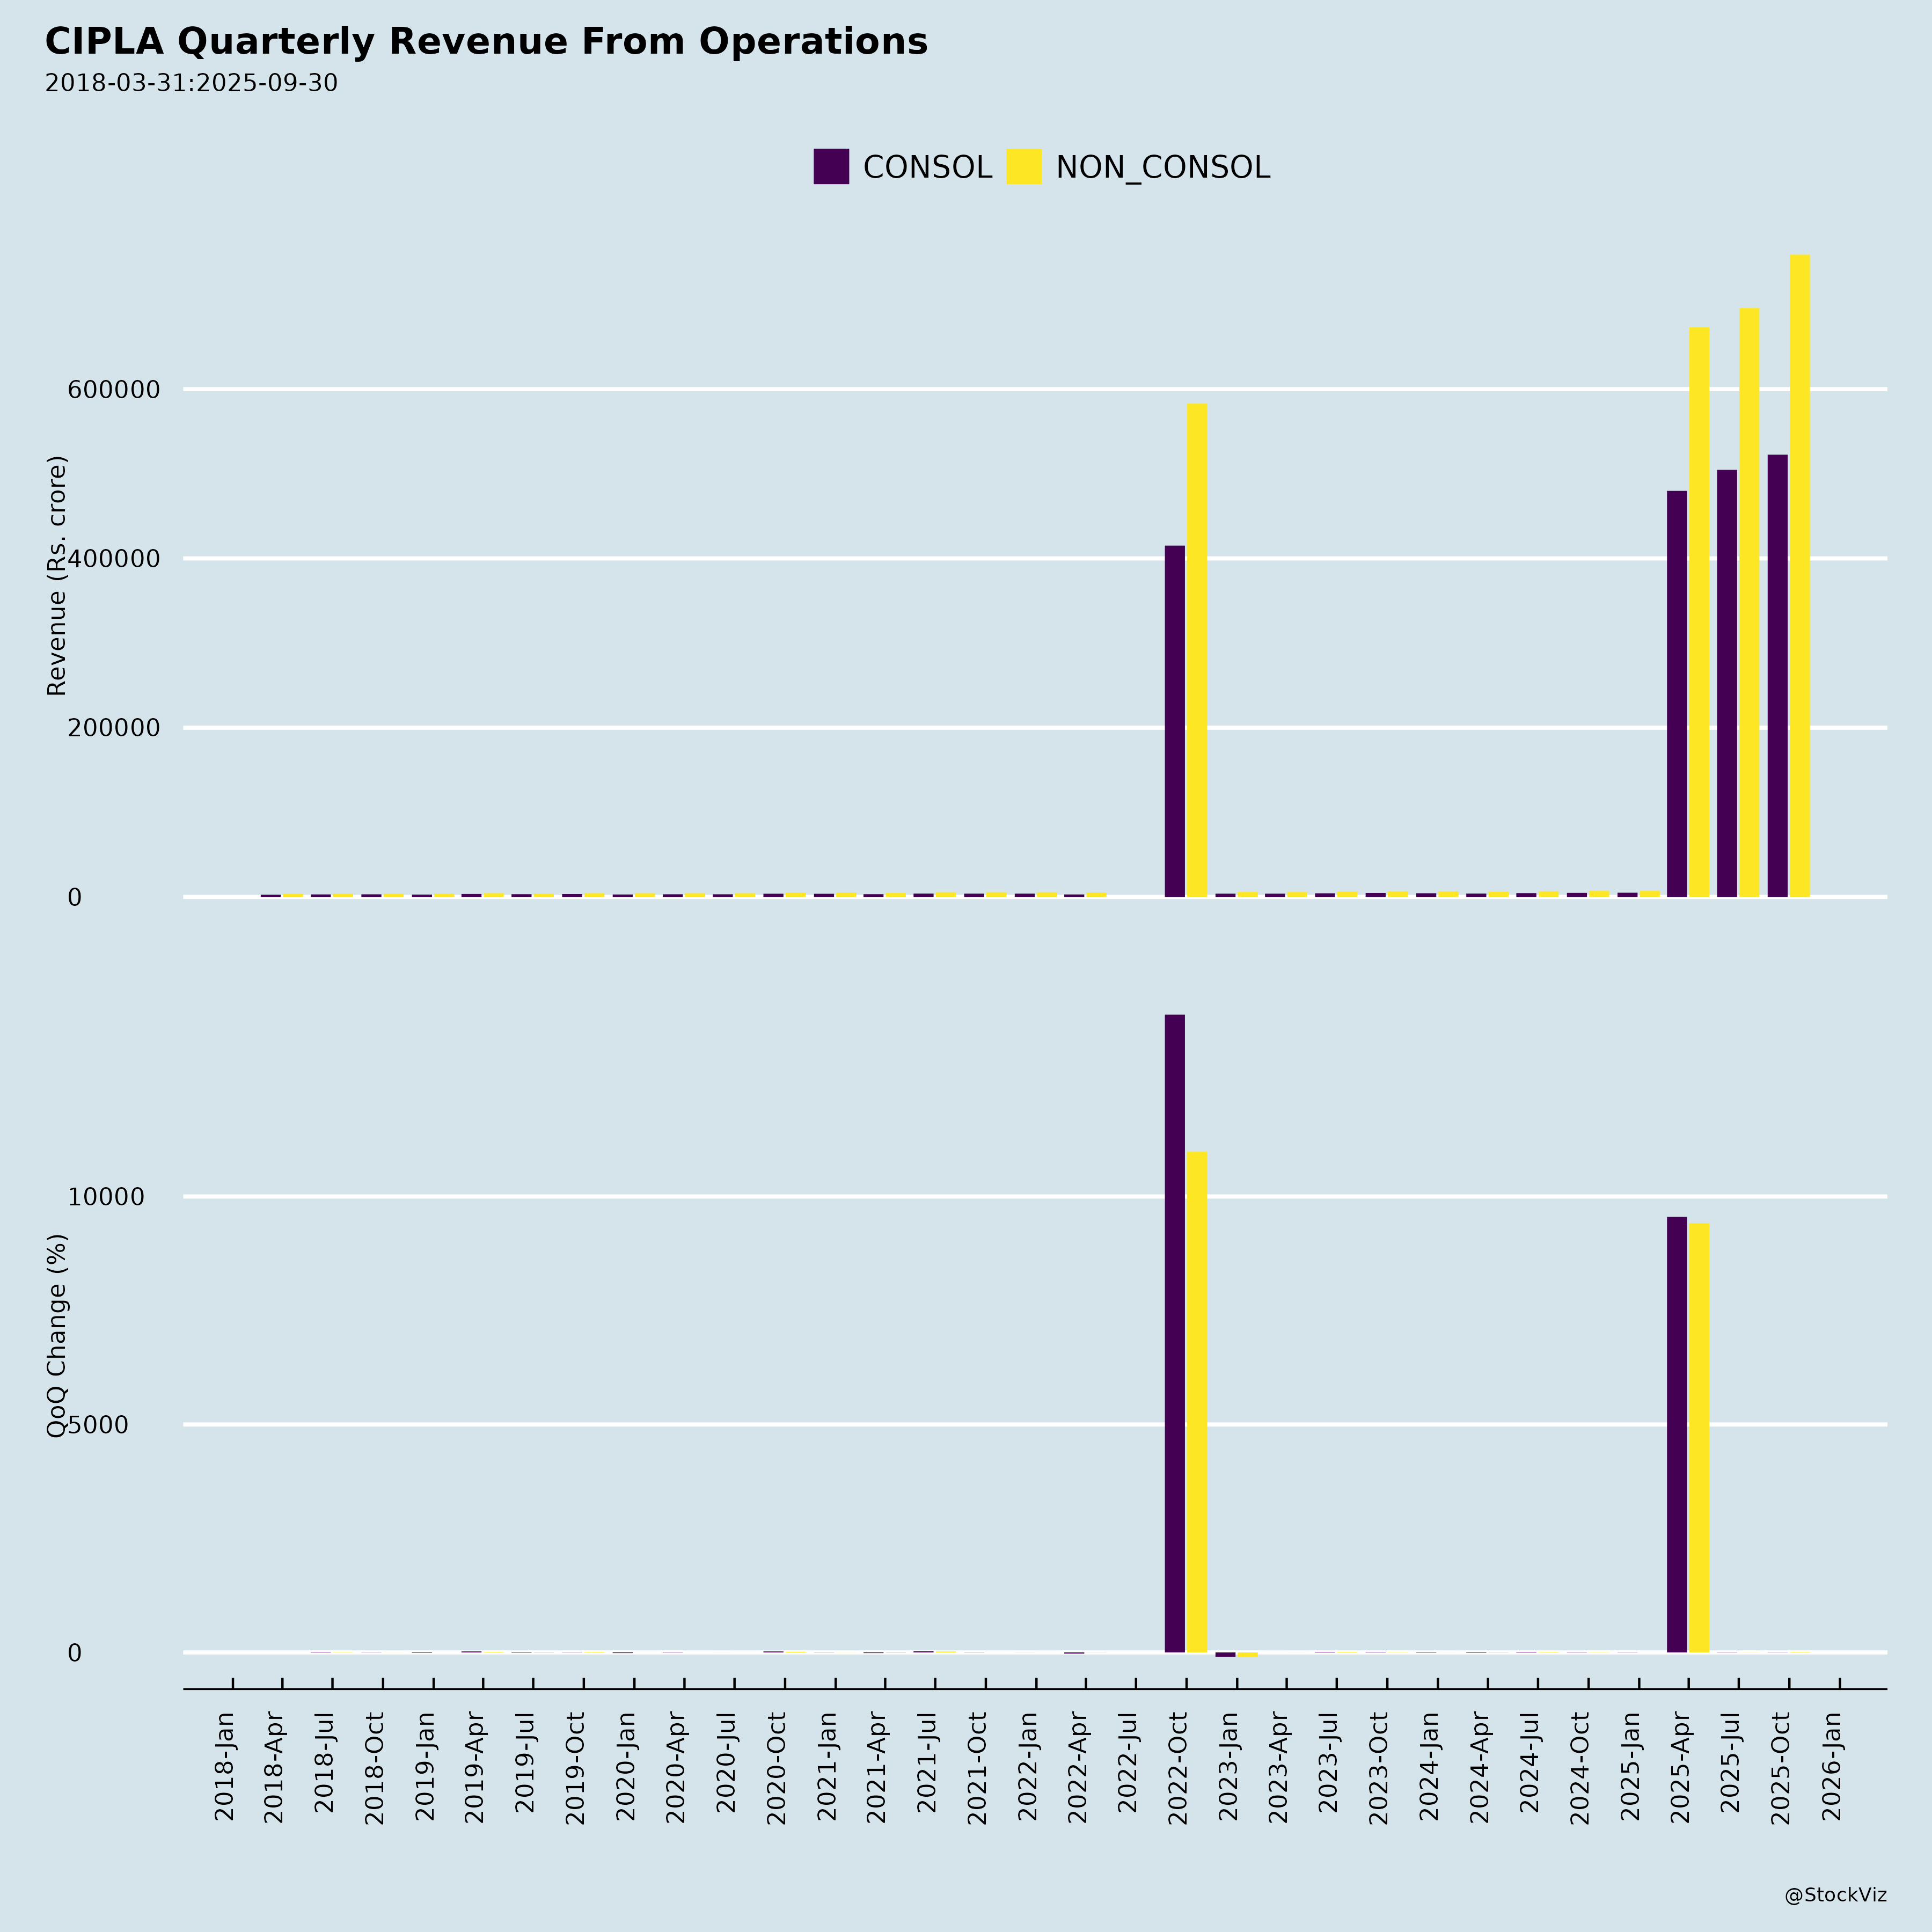
- Highest-ever quarterly revenue. Q1FY27 revenue of INR 7,119 Cr was described as the highest Q1 revenue; “One India” recorded its highest-ever quarterly revenue of INR 3,452 Cr.
- India Rx brand strength. 23 brands in IPM Top 300 ranks; 33 brands with revenue above INR 100 Cr; Foracort is the biggest respiratory brand in IPM at over INR 1,000 Cr; seven therapies hold IPM Top 5 ranks. Recent launches target priority therapies, including an anti-allergy respiratory portfolio with Bilastine + Montelukast.
- Consumer brands. One India consumer brands revenue of INR 481 Cr; South Africa consumer brands revenue of ZAR 405 Mn.
- North America. gProventil ranked No. 1 with 21% total market share and more than 50 million inhaler units supplied cumulatively to the U.S.; gVentolin launched in the U.S. during the quarter with initial shipments executed; recent launches include Nintedanib, Dapagliflozin and Liraglutide. The ANDA/NDA portfolio totals 278 approved, tentatively approved, under approval and partnered products across Cipla Ltd, Invagen, PEPFAR and partnered categories.
- South Africa. Private business revenue of ZAR 906 Mn in Q1FY27; 10 brands with MAT market revenue above ZAR 100 Mn; highest number of brands in the top 30 (6), top 50 (11) and top 100 (20) within the generics segment; healthy performance across Respiratory, CNS and Alimentary TR & Metabolism.
- Biosimilar partnership. Invagen Pharmaceuticals Inc., a wholly owned subsidiary, entered a strategic partnership with Qilu Pharmaceutical Co., Ltd. for exclusive licensing and supply of QL2107, a biosimilar to Keytruda (pembrolizumab), in the United States. Qilu handles development, regulatory registration and supply; Cipla USA Inc. handles commercialization. Management stated goals to expand the biosimilar portfolio in coming fiscal years, launch QL2107 subject to regulatory approval, and bring a high-quality, affordable pembrolizumab biosimilar to U.S. patients.
- Inzpera acquisition and amalgamation. Cipla acquired 100% of Inzpera, adding a differentiated pediatrics and wellness portfolio. The Scheme of Amalgamation (by Absorption) of Inzpera Healthsciences Limited into Cipla Limited is proceeding under an NCLT Mumbai Bench order dated 18 August 2026; the NCLT dispensed with meetings of equity shareholders and unsecured creditors, and there are no secured creditors in the Transferee Company.
- Partnerships and innovation. Secured rights from Eli Lilly to distribute and promote Yurpeak in India; exclusive marketing and distribution rights for Pfizer brands (Corex, Dolonex, Neksium, Dalacin C); CGT portfolio (Ciplostem, Regenacip, Xtiktr) gaining traction in India; launches of Voltido Trio, Afrezza (inhaled insulin) and Zemdri (Plazomycin); expanded DPI capabilities in the U.S. and MDI in the U.S. and Morocco.
- Financial strength. Strong $1Bn+ net cash position; cash and cash equivalents of INR 10,094 Cr as at June 2026; total debt of INR 600 Cr.
- Quality and ESG. 46 regulatory inspections completed in FY26 with no critical observations; 82% reduction in Scope 1 and Scope 2 GHG emissions versus FY2019-20; 2.6x water positive; all Cipla India manufacturing operations ZWTL re-certified; 84% renewable electricity usage; inclusion in the 2026 Dow Jones Best in Class World Index; committed to net zero by 2050.
- Investor engagement. Meetings scheduled with analysts and institutional investors, including the Jefferies India Forum Conference in Gurgaon on 17 September 2026 and the Kotak Healthcare Conference in Mumbai on 18 September 2026, both in person, subject to change due to unforeseen circumstances.
3. Key Risks
- Regulatory approval risk for pipeline products, including the QL2107 pembrolizumab biosimilar launch, which is subject to regulatory approval.
- Execution and supply ramp-up risk on gVentolin in the U.S. over coming quarters.
- Foreign exchange and international operations risk, including exposure to market risks, as cited in the forward-looking statement risk factors.
- Profitability pressure evidenced by the Q1FY27 margin contraction and higher material and employee costs.
- Dependence on partner-led products and in-licensing arrangements for several growth initiatives.
- Scheme of Amalgamation process risk: shareholders and unsecured creditors have 30 days from receipt of notice to submit representations to the NCLT, with a simultaneous copy to the registered office, failing which it will be presumed they have no objection.
- Investor meeting schedule risk: the schedule is subject to change due to unforeseen circumstances involving the investor or the company.
4. Management Guidance Versus Observed Business Performance
- Biosimilar portfolio expansion. Management stated goals to expand the biosimilar portfolio in coming fiscal years and to launch QL2107 subject to regulatory approval. Observed performance: the Qilu partnership for QL2107 in the U.S. has been announced; no launch has been reported in the supplied material.
- gVentolin U.S. ramp-up. Management indicated supply ramp-up planned over the coming quarters. Observed performance: gVentolin was launched in the U.S. during Q1FY27 with initial shipments executed.
- Highest-ever yearly revenue despite multiple headwinds. The AGM MD & GCEO address framed FY26 as delivering highest-ever yearly revenue despite multiple headwinds. Observed performance: Q1FY27 revenue of INR 7,119 Cr was the highest Q1 revenue, while EBITDA and PAT declined year-on-year.
- Financial discipline. Management highlighted building scale with financial discipline and a strong $1Bn+ net cash position. Observed performance: cash and cash equivalents of INR 10,094 Cr and total debt of INR 600 Cr as at June 2026.
- ESG goals. Goals for FY2029-30 include 80% renewable electricity share for India manufacturing, 30% absolute reduction in Scope 1 and 2 emissions from an FY2023-24 baseline, water neutrality for India manufacturing, and maintaining ZWL status. Observed progress: 57% renewable electricity share, 21% emissions reduction, 2.6x water positivity in FY26, and ZWTL re-certification of India manufacturing operations.
- AMR and safety goals. Goals include one antibiotic product per Cipla India site certified per AMR manufacturing standard, zero fatality in manufacturing operations, and 20% or above representation of women in the Cipla Leadership Group from an FY25 baseline. Observed progress: zero fatality in manufacturing operations; 14.8% women representation in the Cipla Leadership Group; AMR certification for two sites targeted for March 2027.
- Responsible procurement goal. Minimum 80% of critical Indian suppliers to comply with the Cipla ESG framework. Observed progress: preparation of the supplier assessment ESG framework.
Broker Narrative
Brokers evolved from flagging Indore/Goa USFDA scrutiny and gAdvair/gAbraxane launch delays in 2023 to a 2026 narrative built on gAdvair/gVentolin approvals and a pembrolizumab biosimilar partnership, while still citing Pithampur clearance as a key risk. Persistent themes included regulatory plant delays, Africa tender pressures, US price erosion, and margin compression. The growth driver mix shifted from lanreotide and respiratory share gains to GLP-1 branded chronic therapies, biosimilars, and a higher US filing run-rate, with earlier earnings estimate cuts replaced by guided FY27 EBITDA margin expansion.
Fears that came true
- Regulatory clearance delays persisted from Indore/Goa to Pithampur, and lanreotide was discontinued over partner Pharmathen’s Greece facility issues, echoing early USFDA fears alongside repeated DISAPPOINTMENT outcomes and negative actual returns from 2024–2026.
- Marquee launch delays materialized as gAdvair remained pending until H1FY27, while gRevlimid loss of exclusivity weighed on US sales and API sales fell ~59% YoY during the 2024–2026 disappointment cluster.
- US price erosion and margin pressure continued, with gross margin contracting 208 bps YoY to 64.4% and one Africa region hit by loss of tenders, undermining earnings through the period of negative actual returns.
Optimism that failed
- Lanreotide’s 17%+ US market-share momentum did not sustain, as it was discontinued due to regulatory issues at Pharmathen’s Greece facility, removing a key US growth driver.
- India’s projected 12% revenue CAGR and trade-generics double-digit growth stalled, with trade generic and consumer portfolios growing slower and consumer growth only expected to regain double-digit momentum later.
- SAGA’s Africa outperformance (8.9% vs 4.4% market CAGR) reversed, with one Africa region impacted by loss of tenders instead of continued market-beating growth.
Broker Timeline
73 broker calls · 2023-05-12 to 2026-10-28
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.