CESC
Equity Metrics
September 24, 2026
CESC Limited
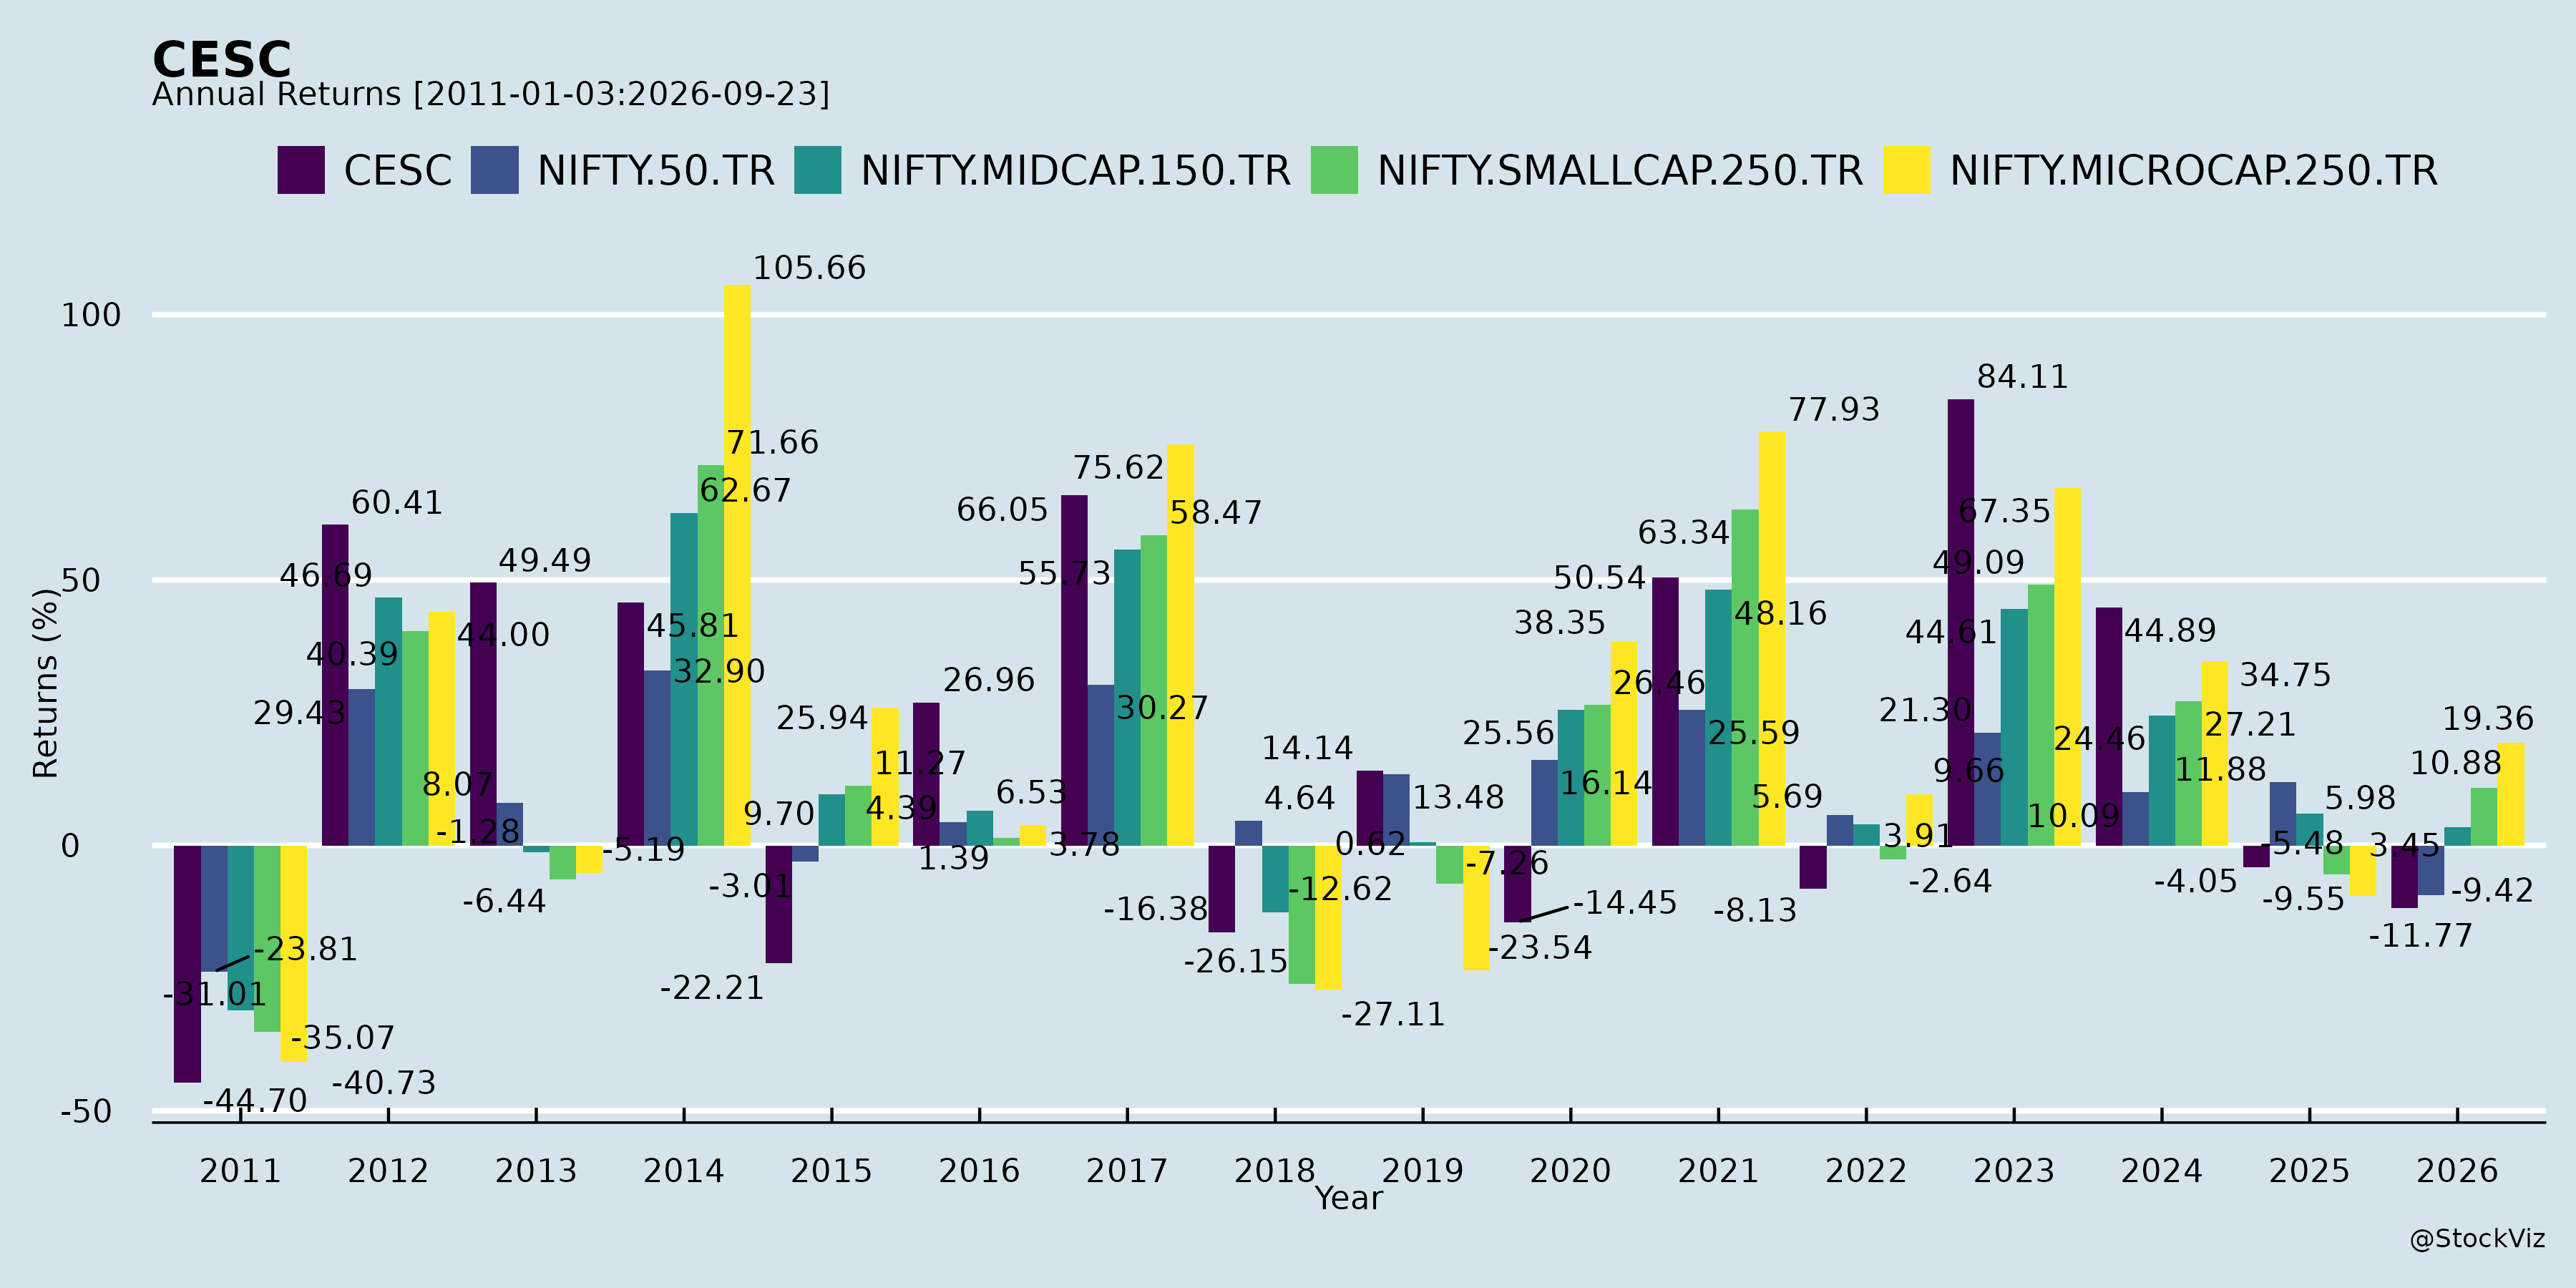
Annual Returns
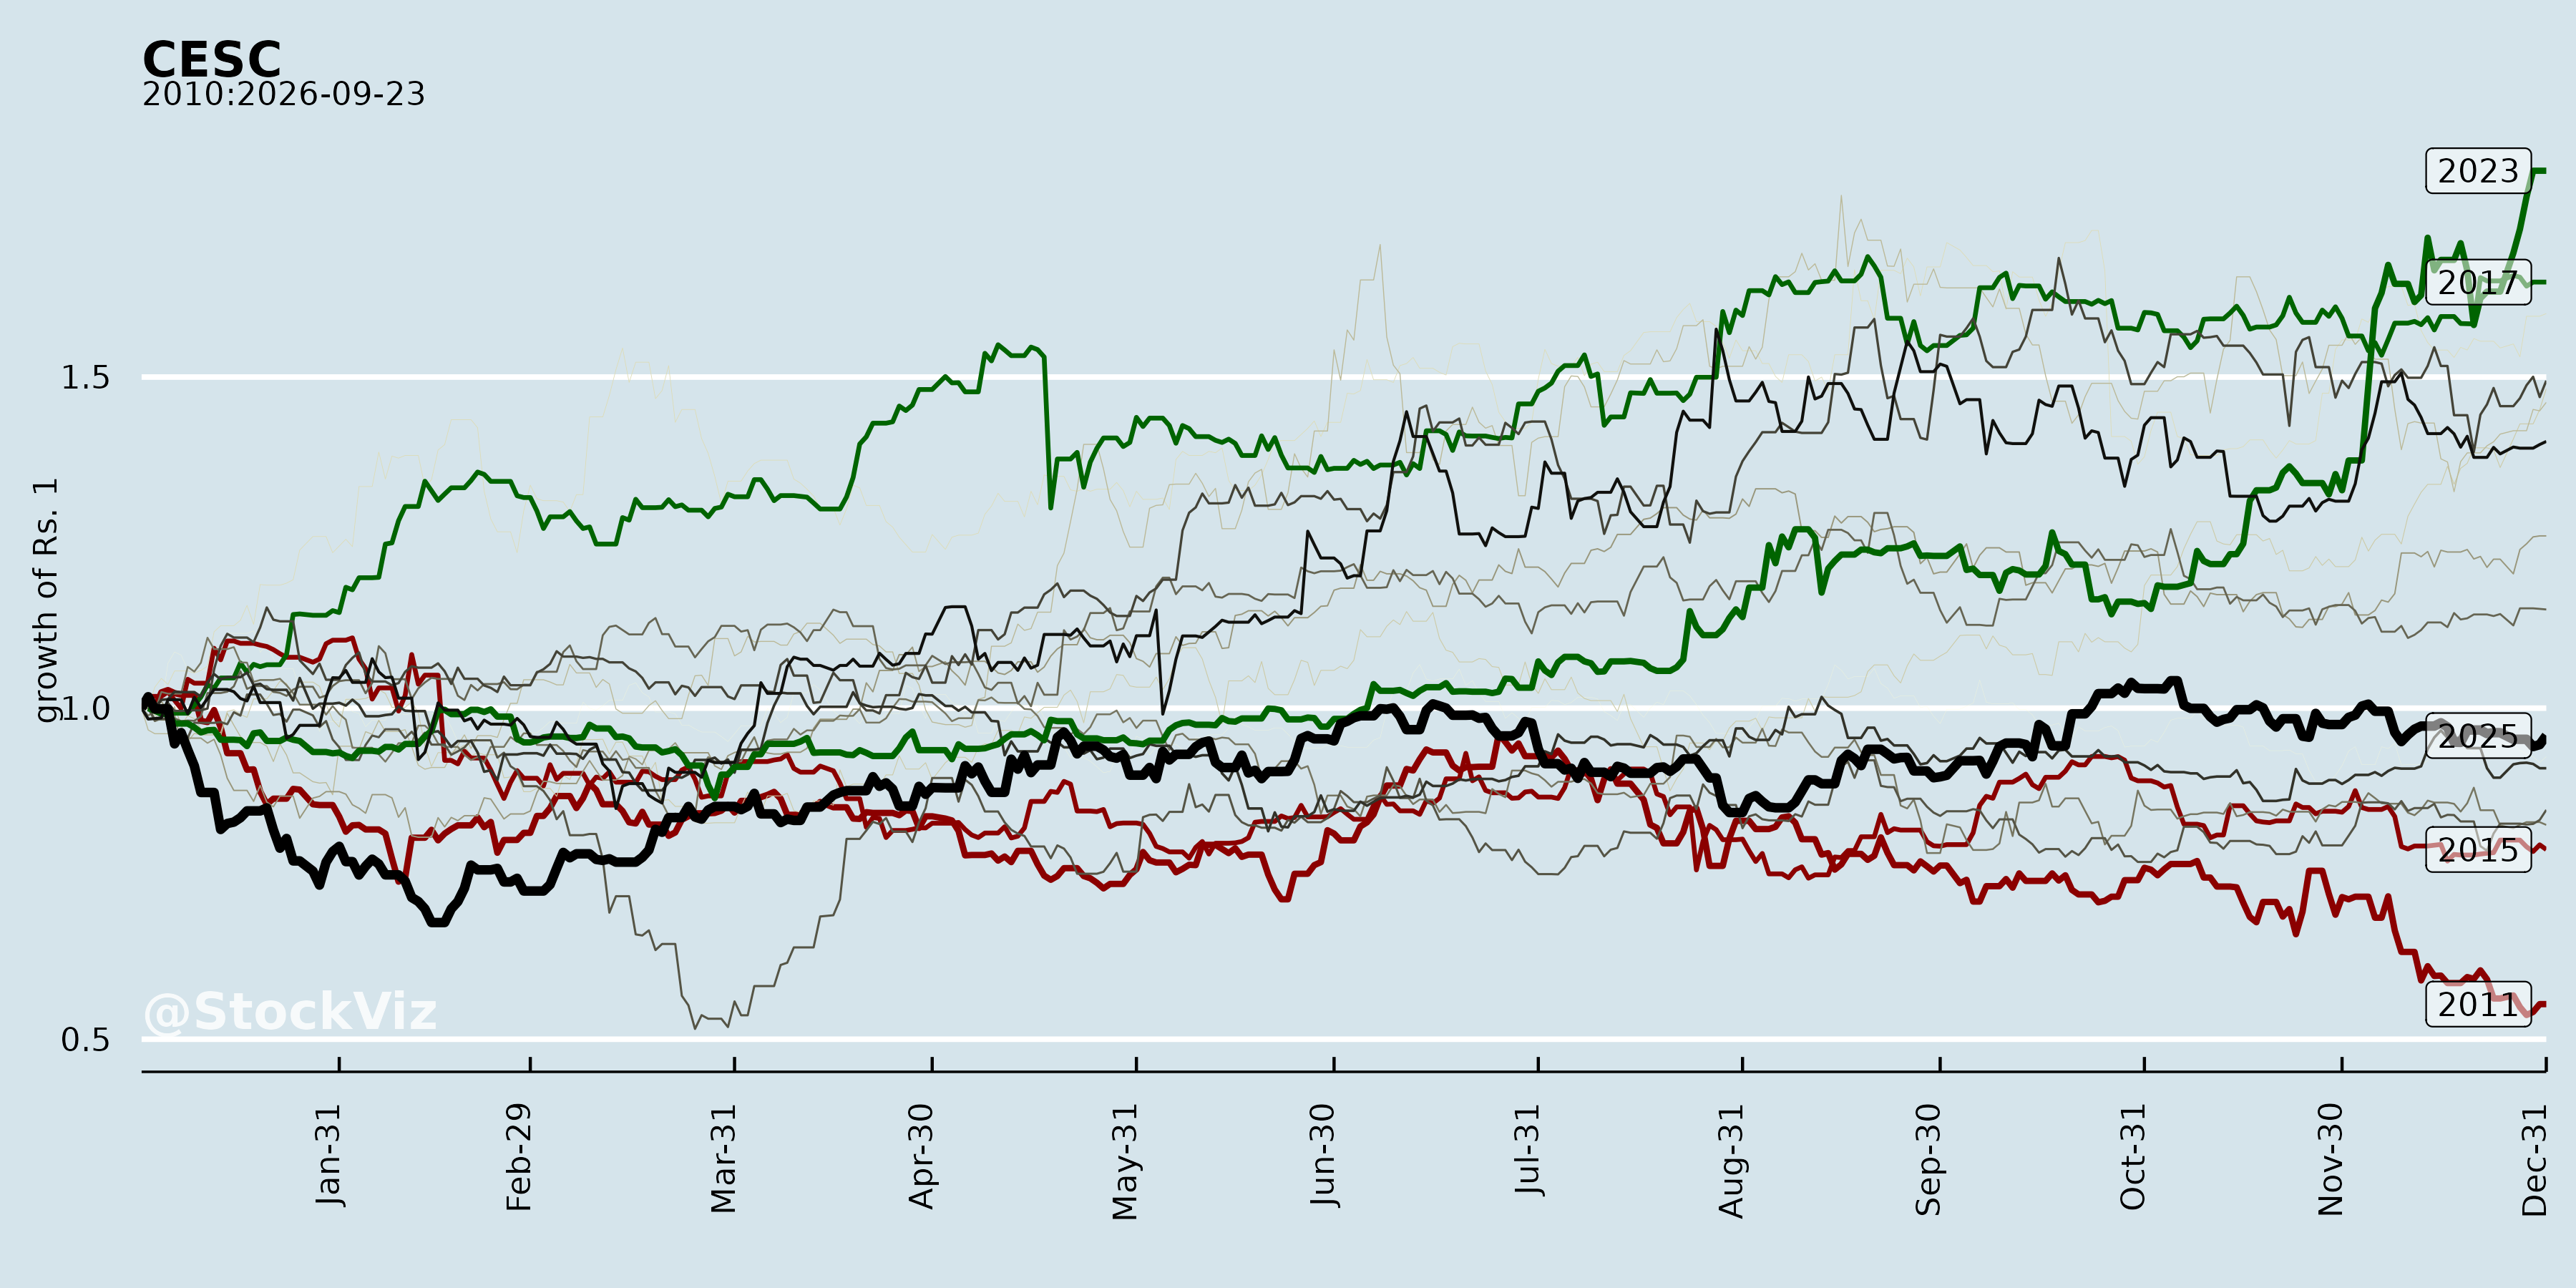
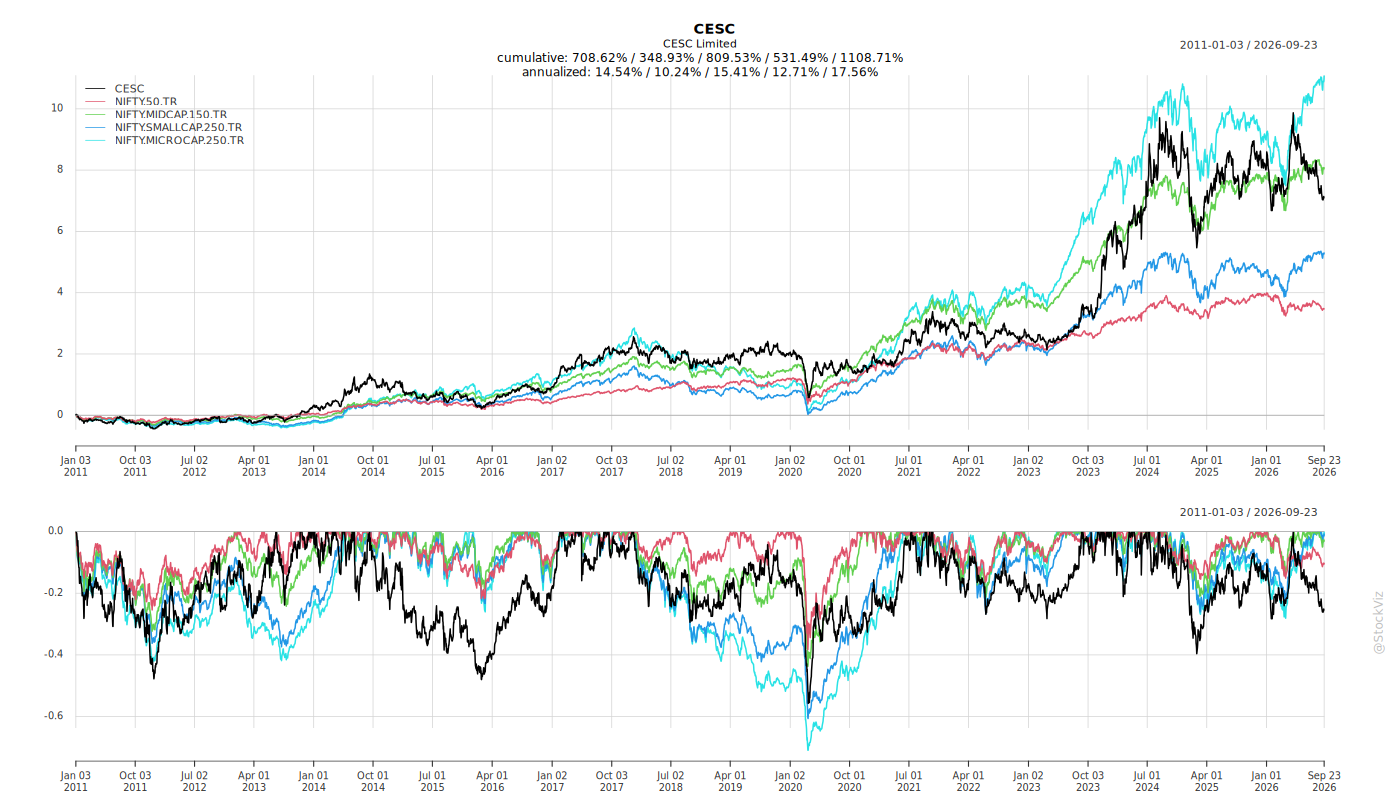
Cumulative Returns and Drawdowns
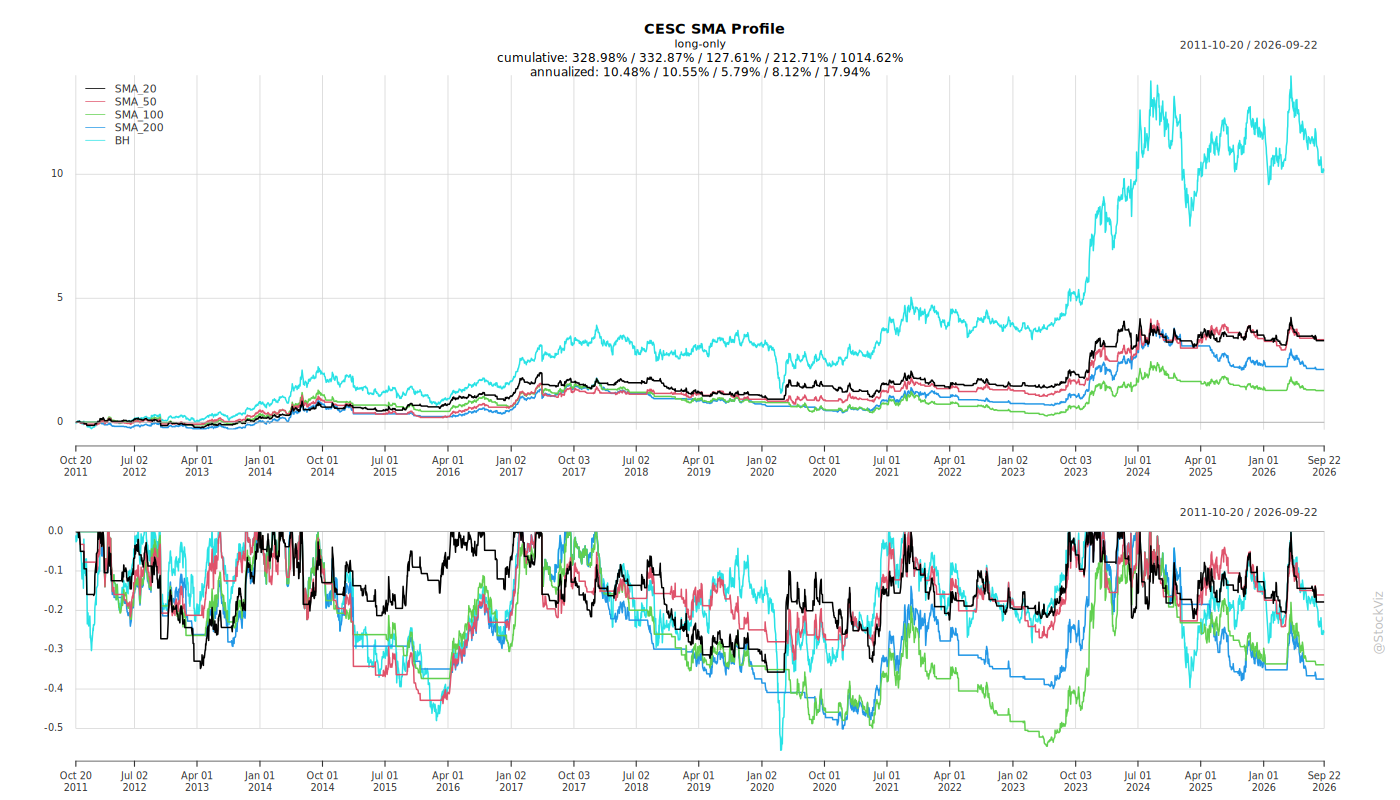
Fundamentals
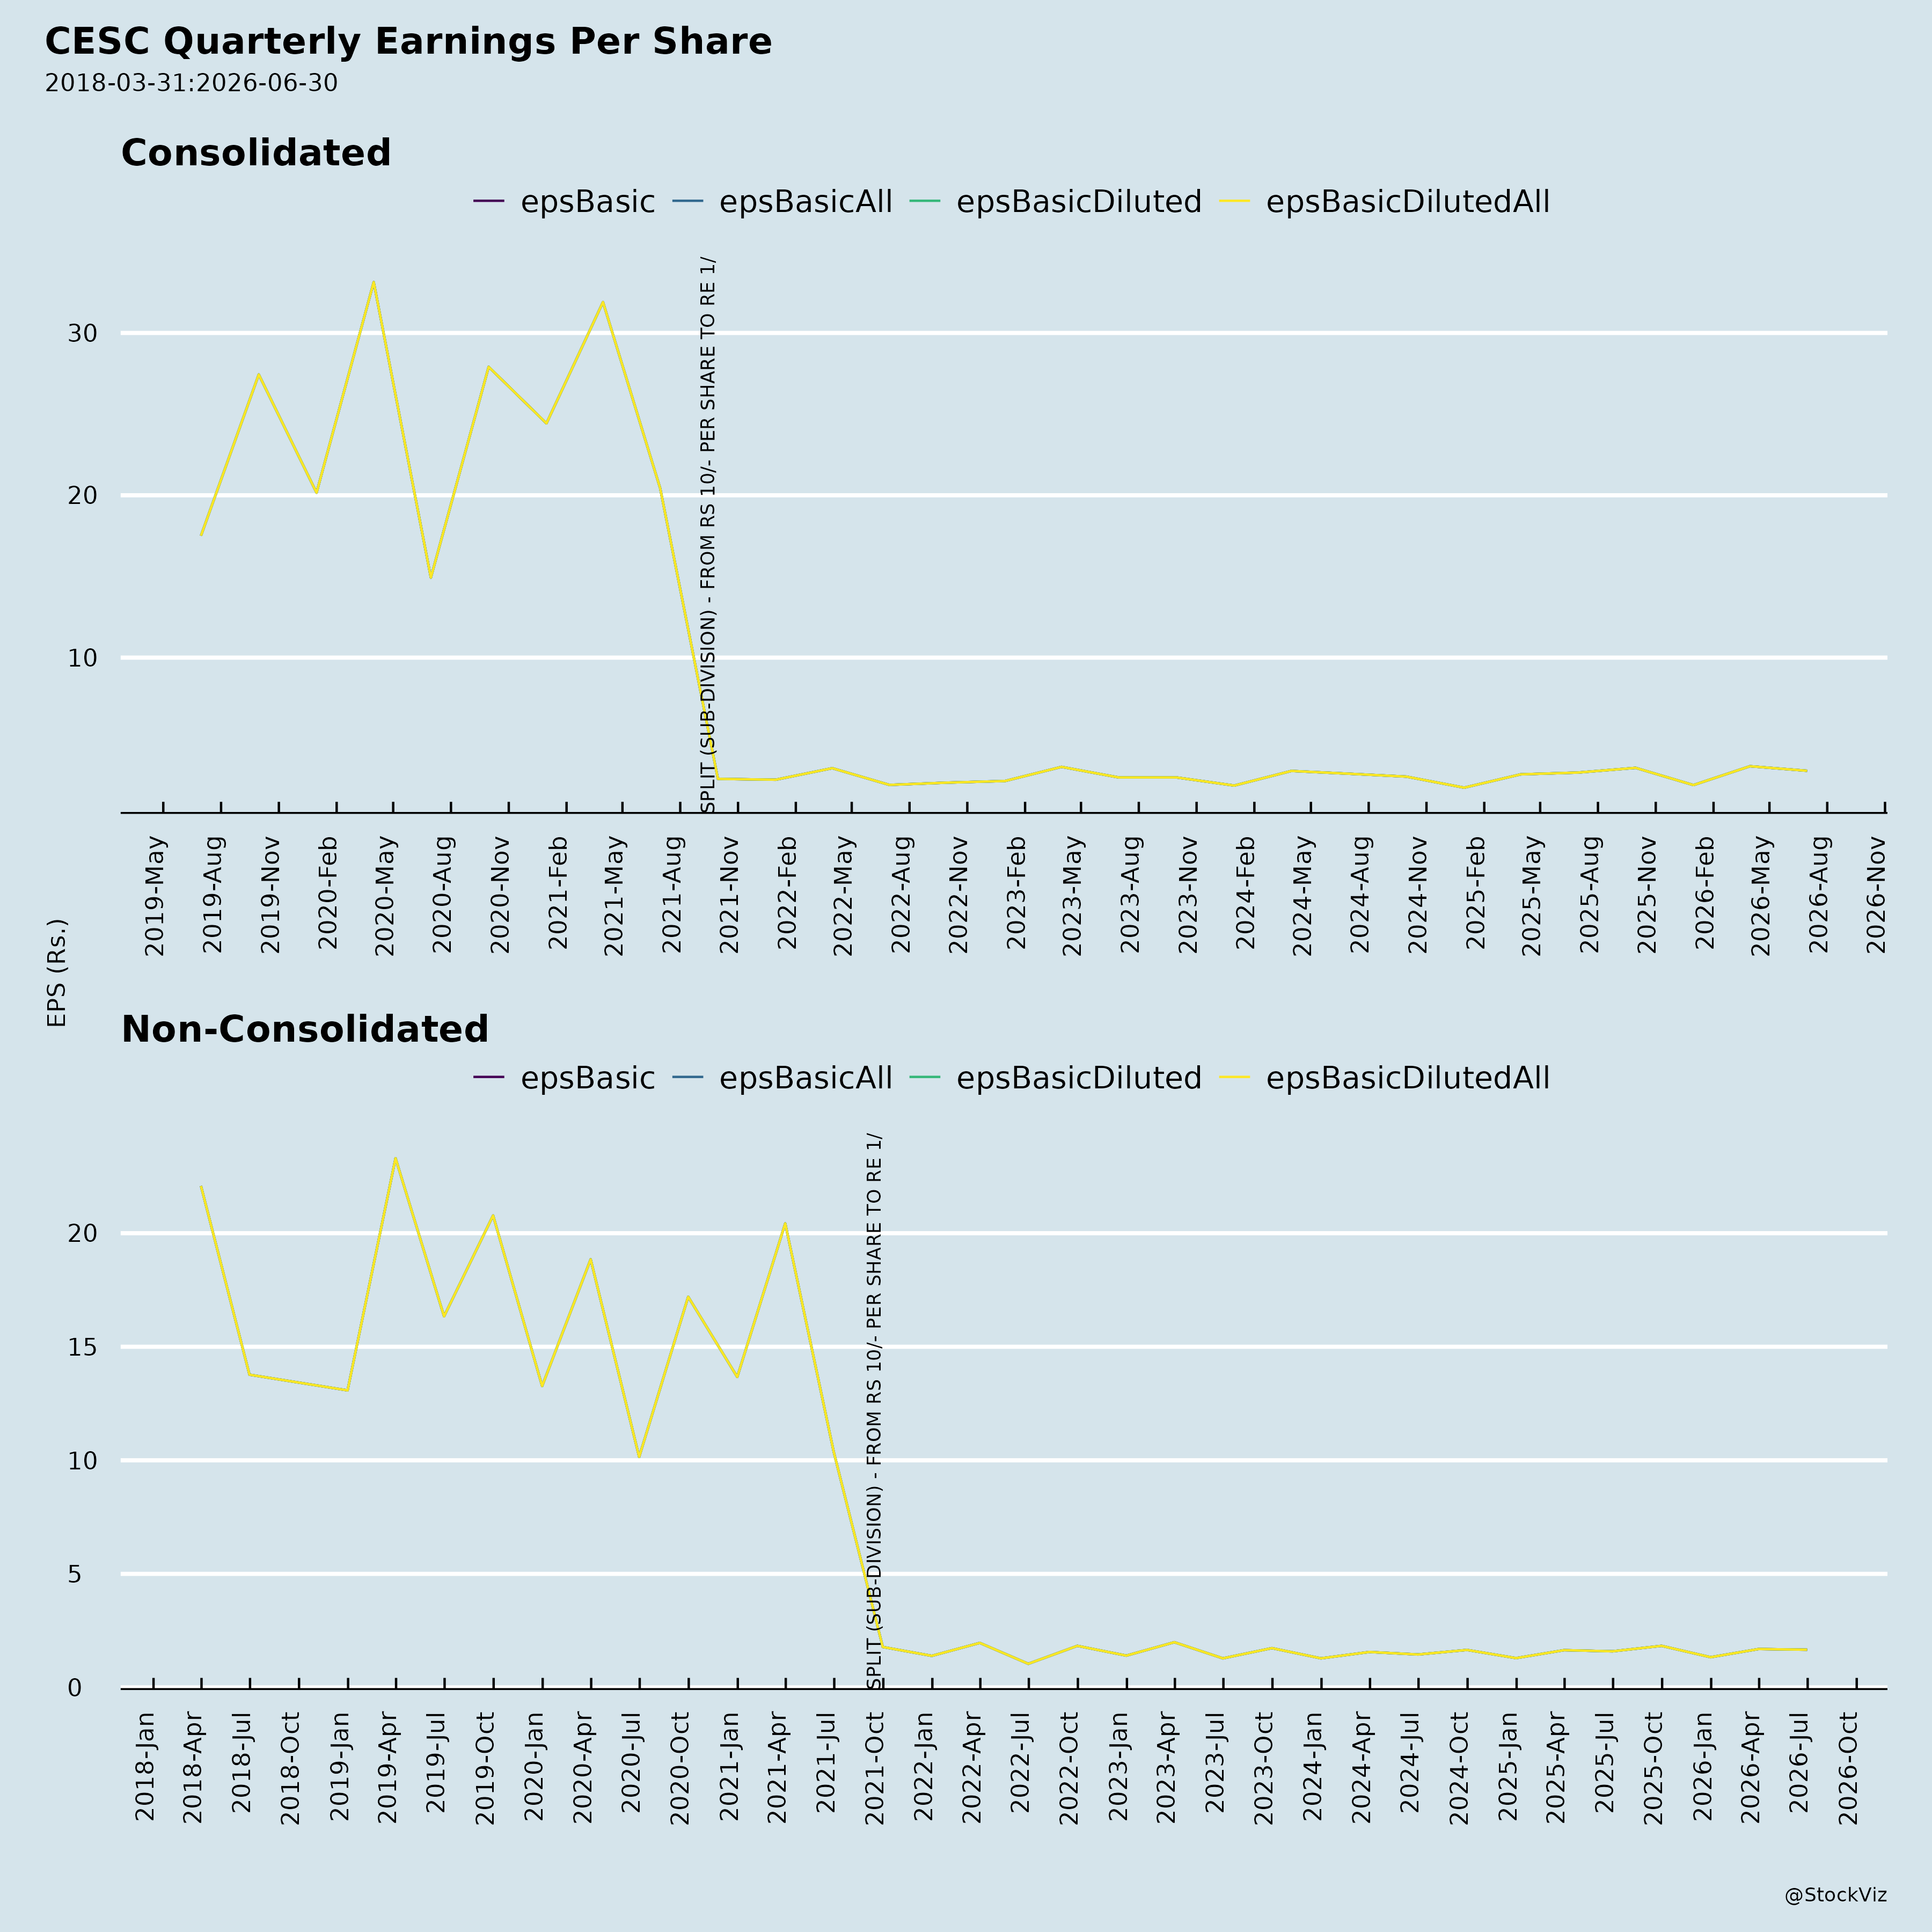
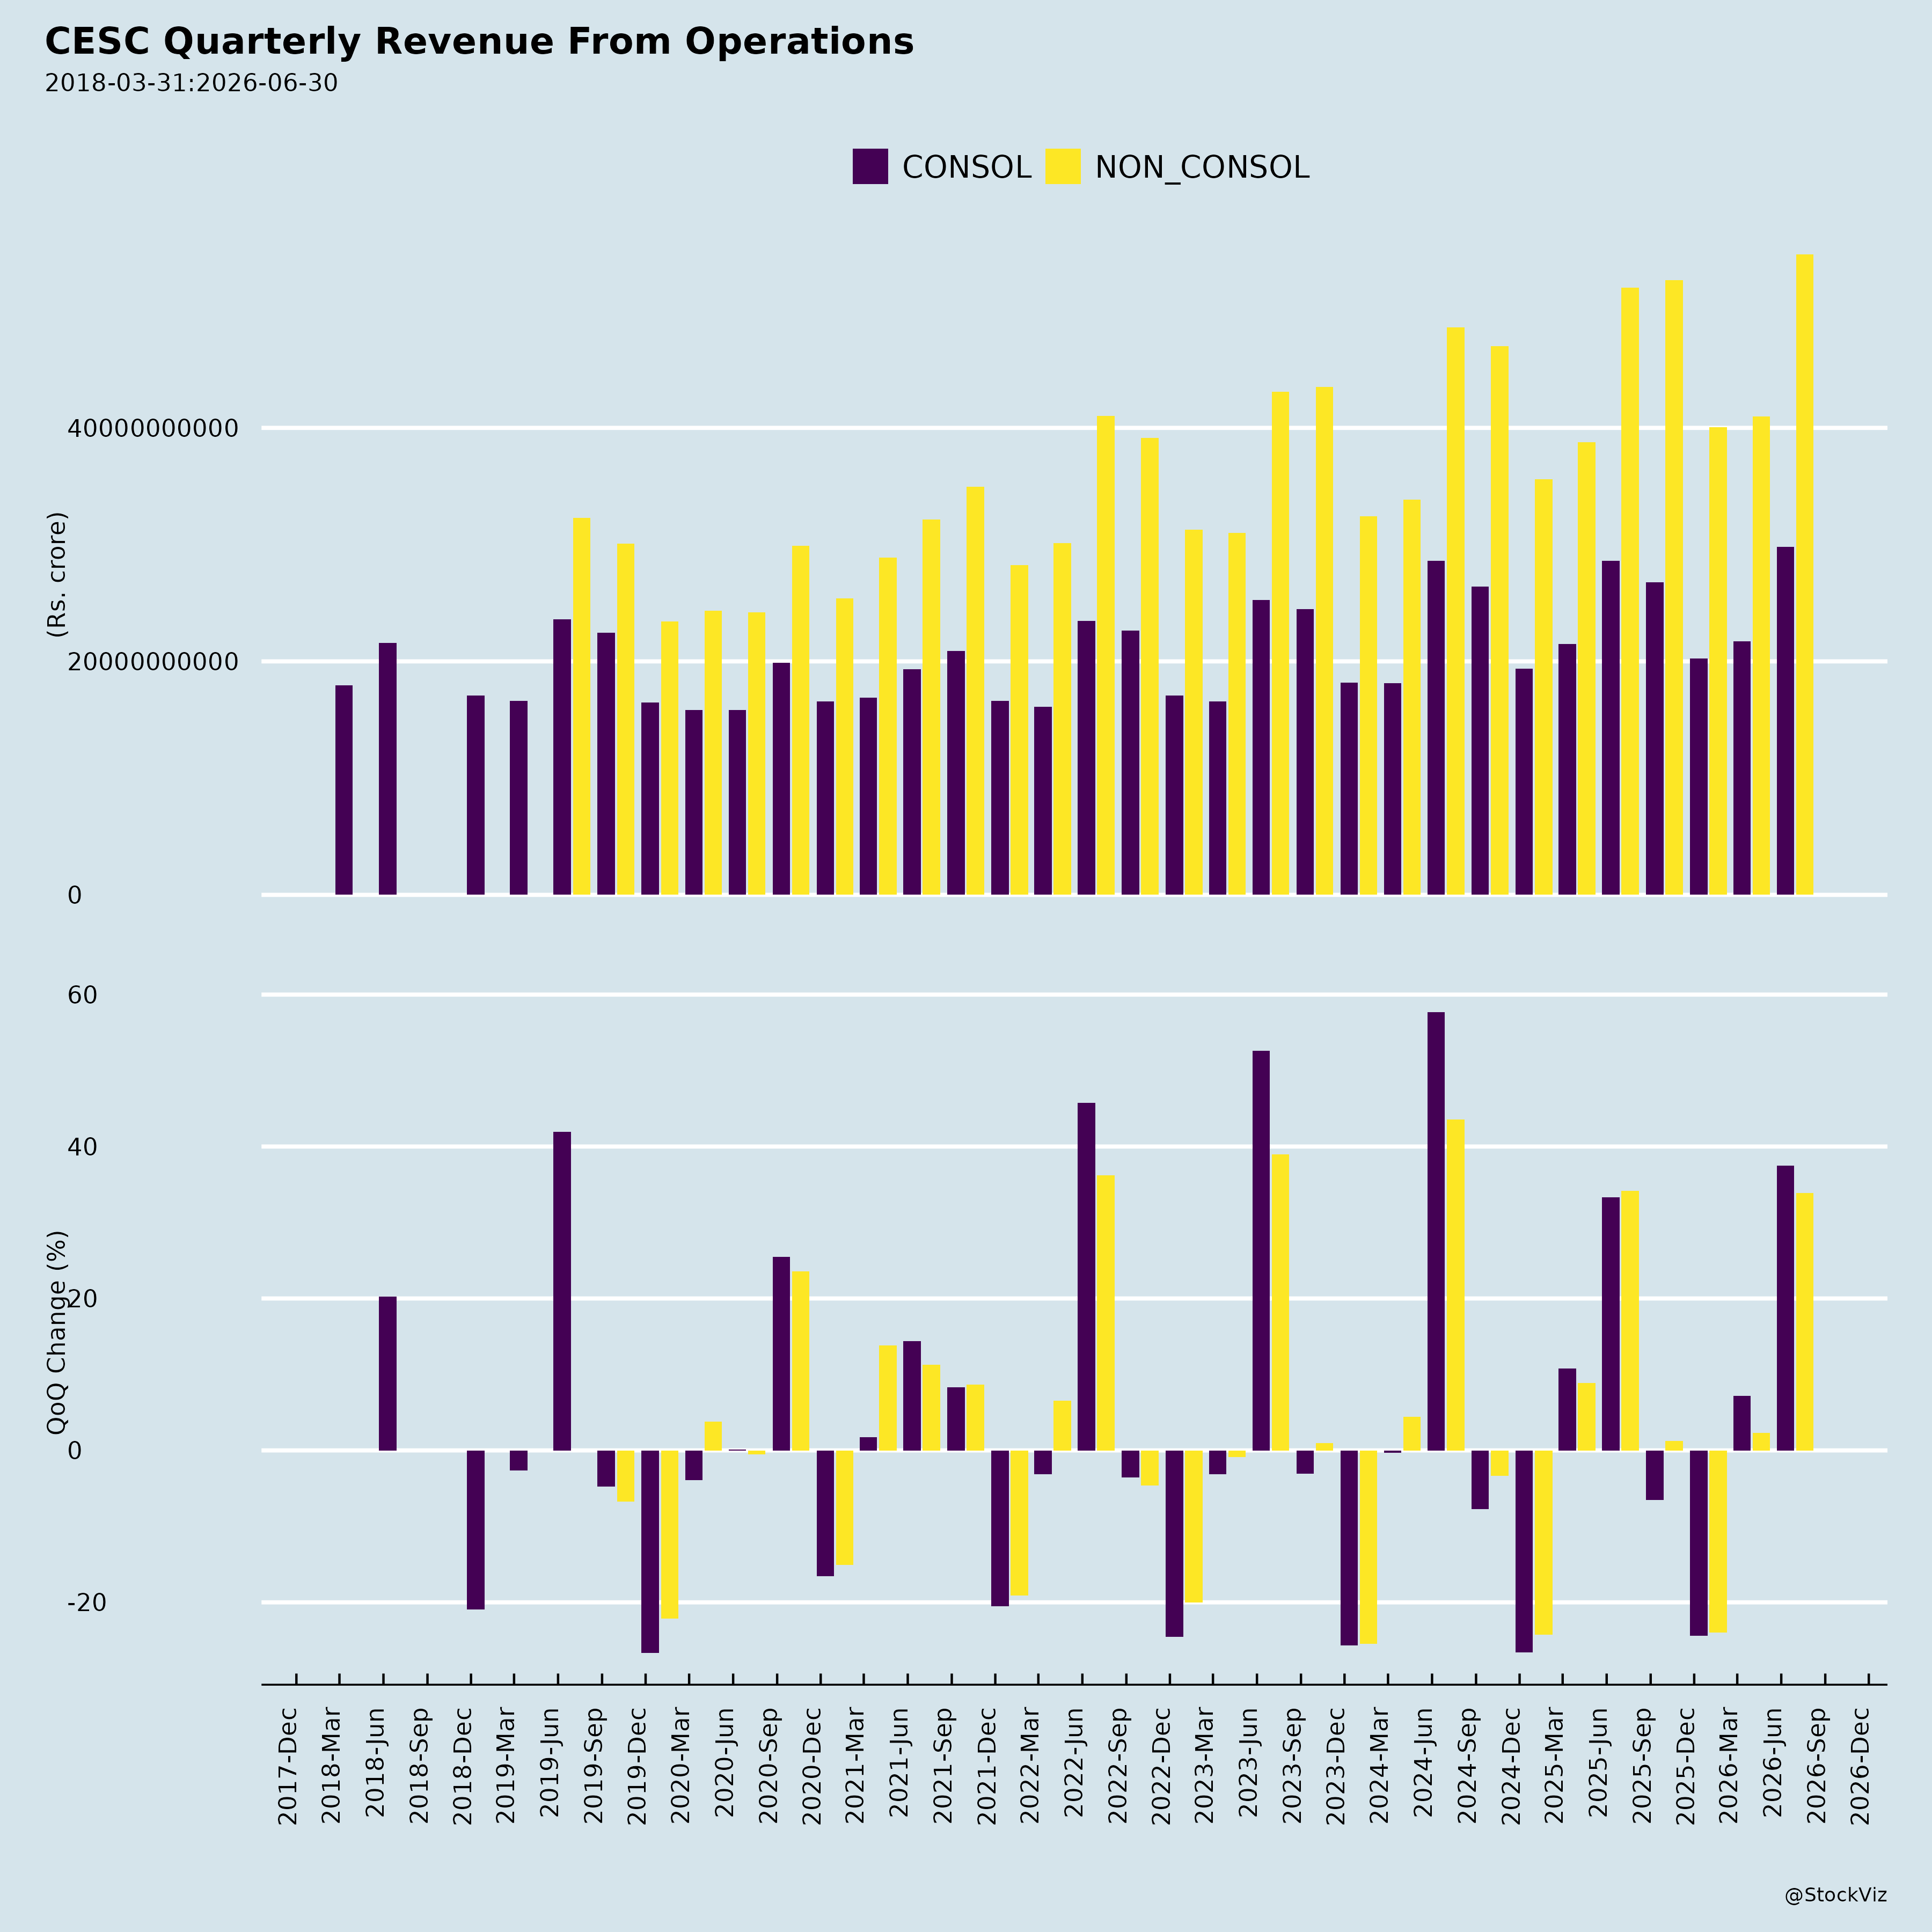
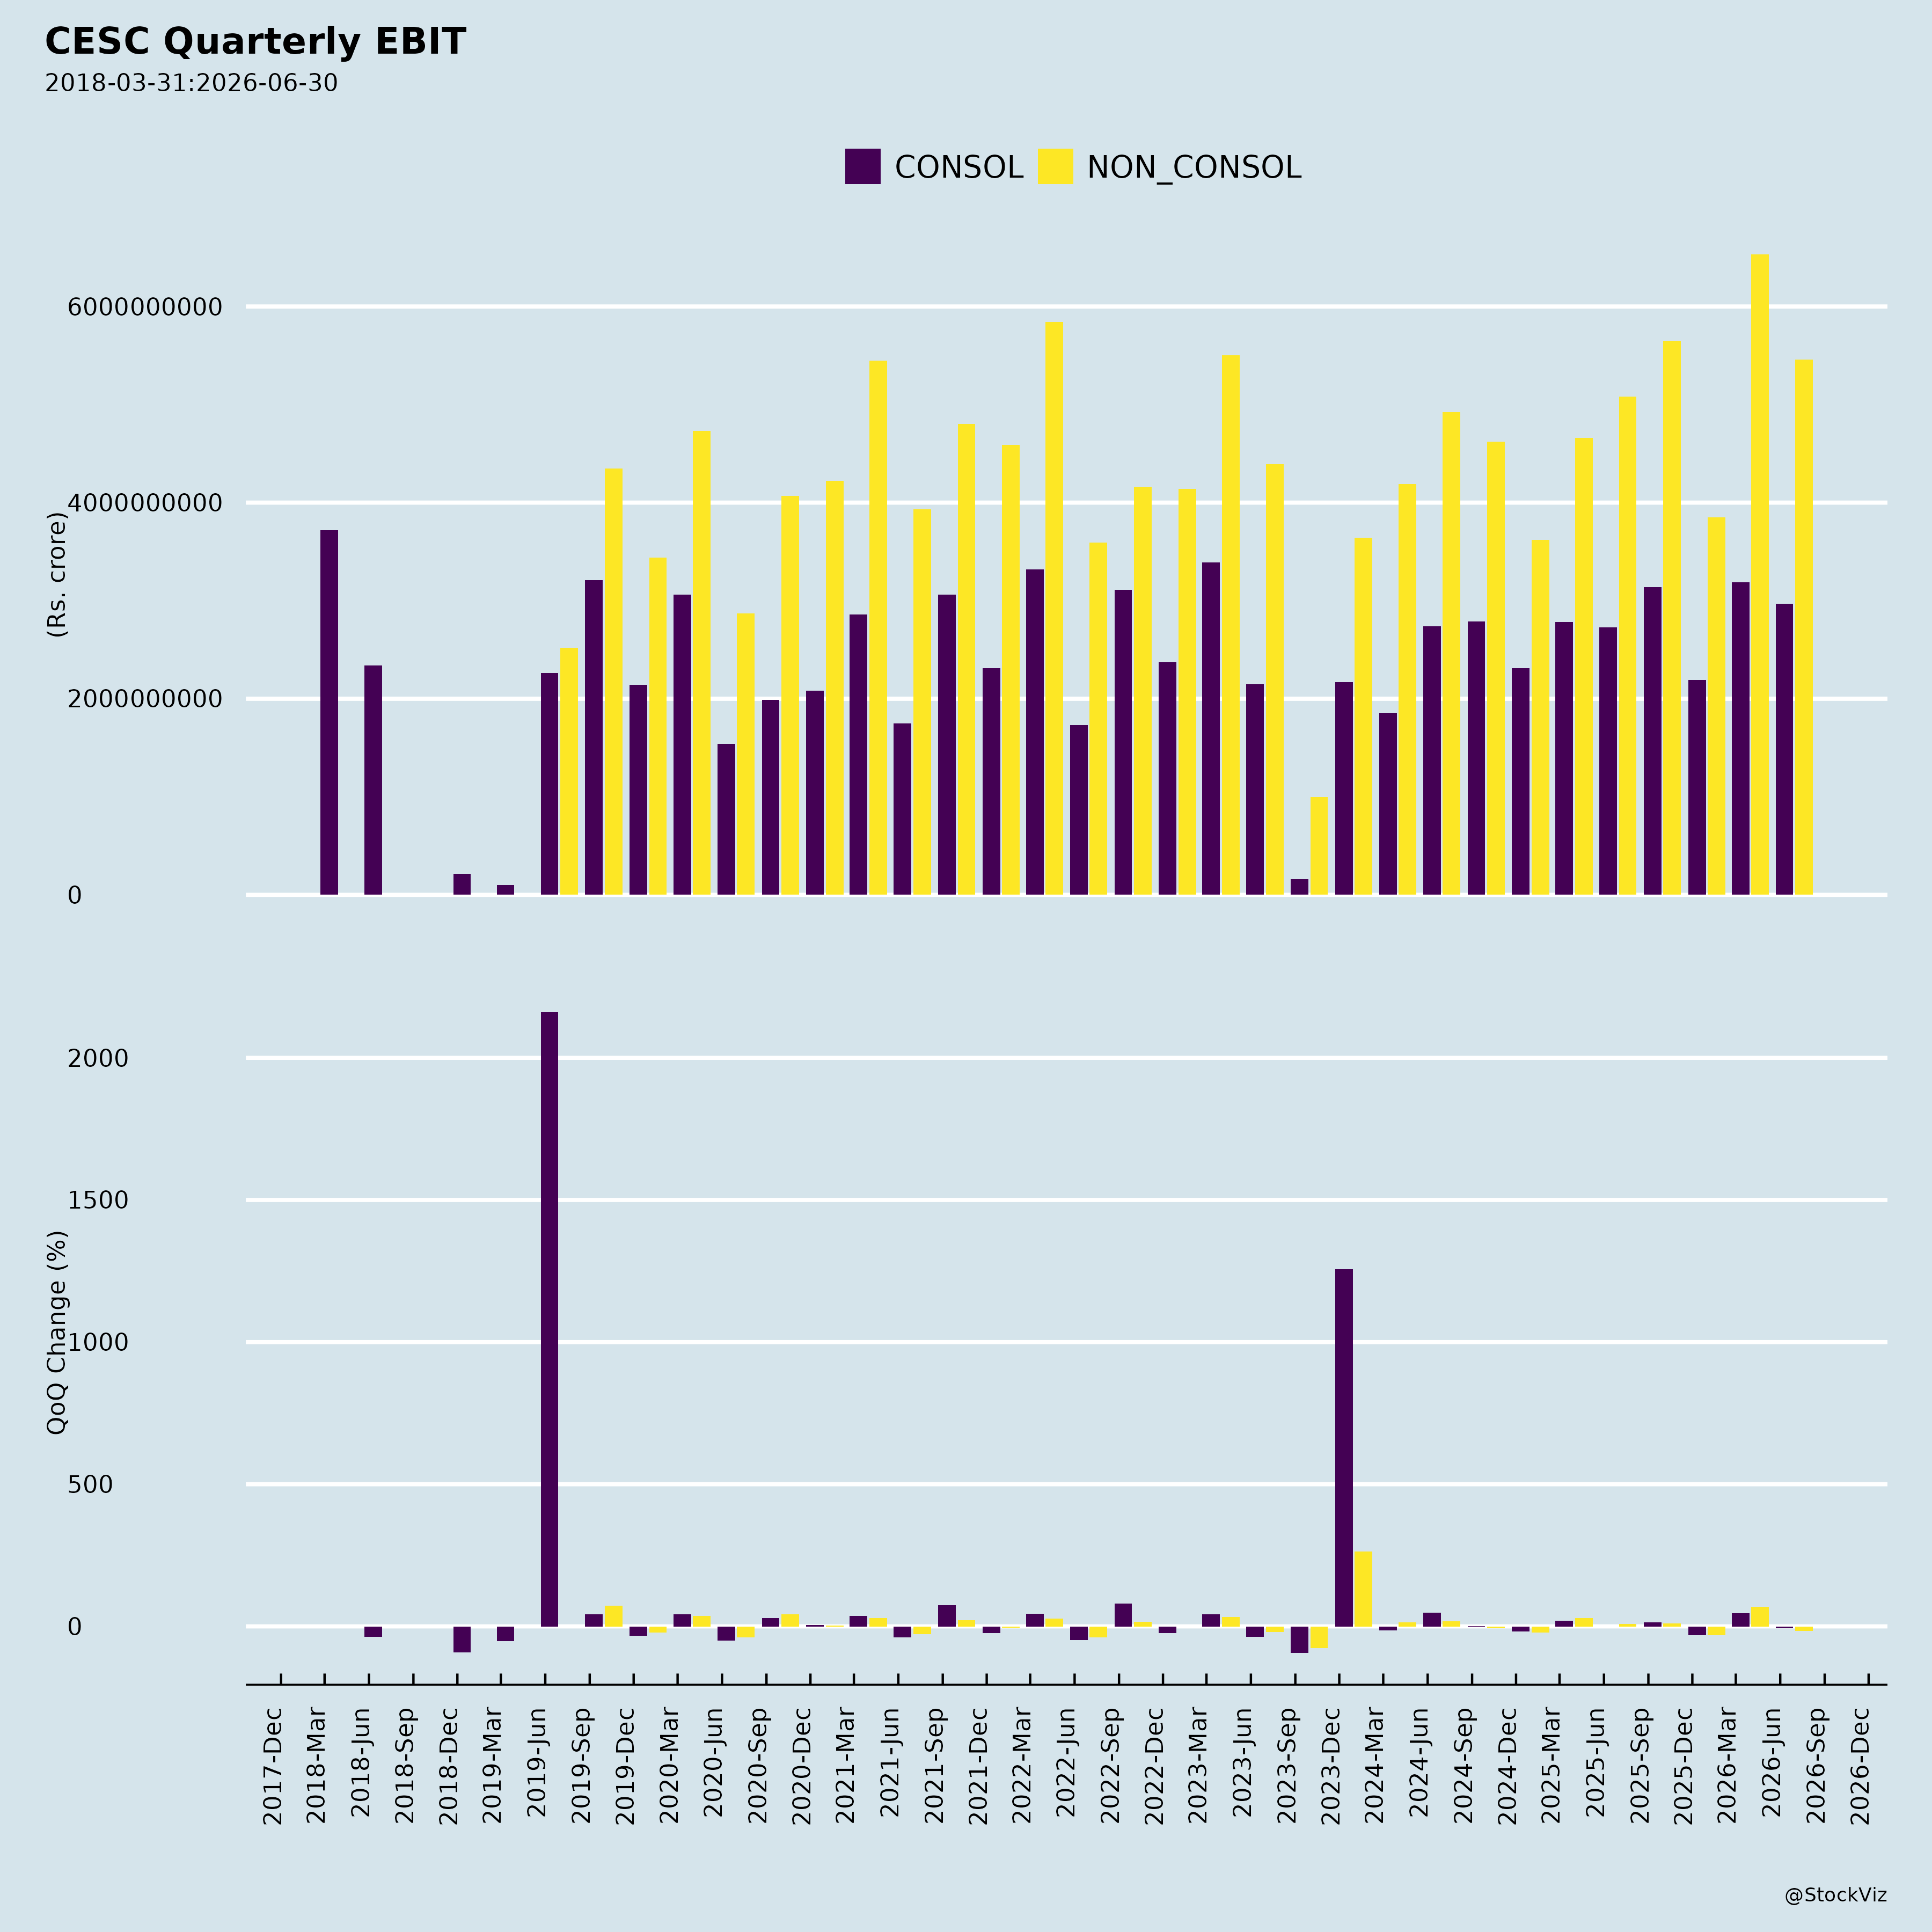
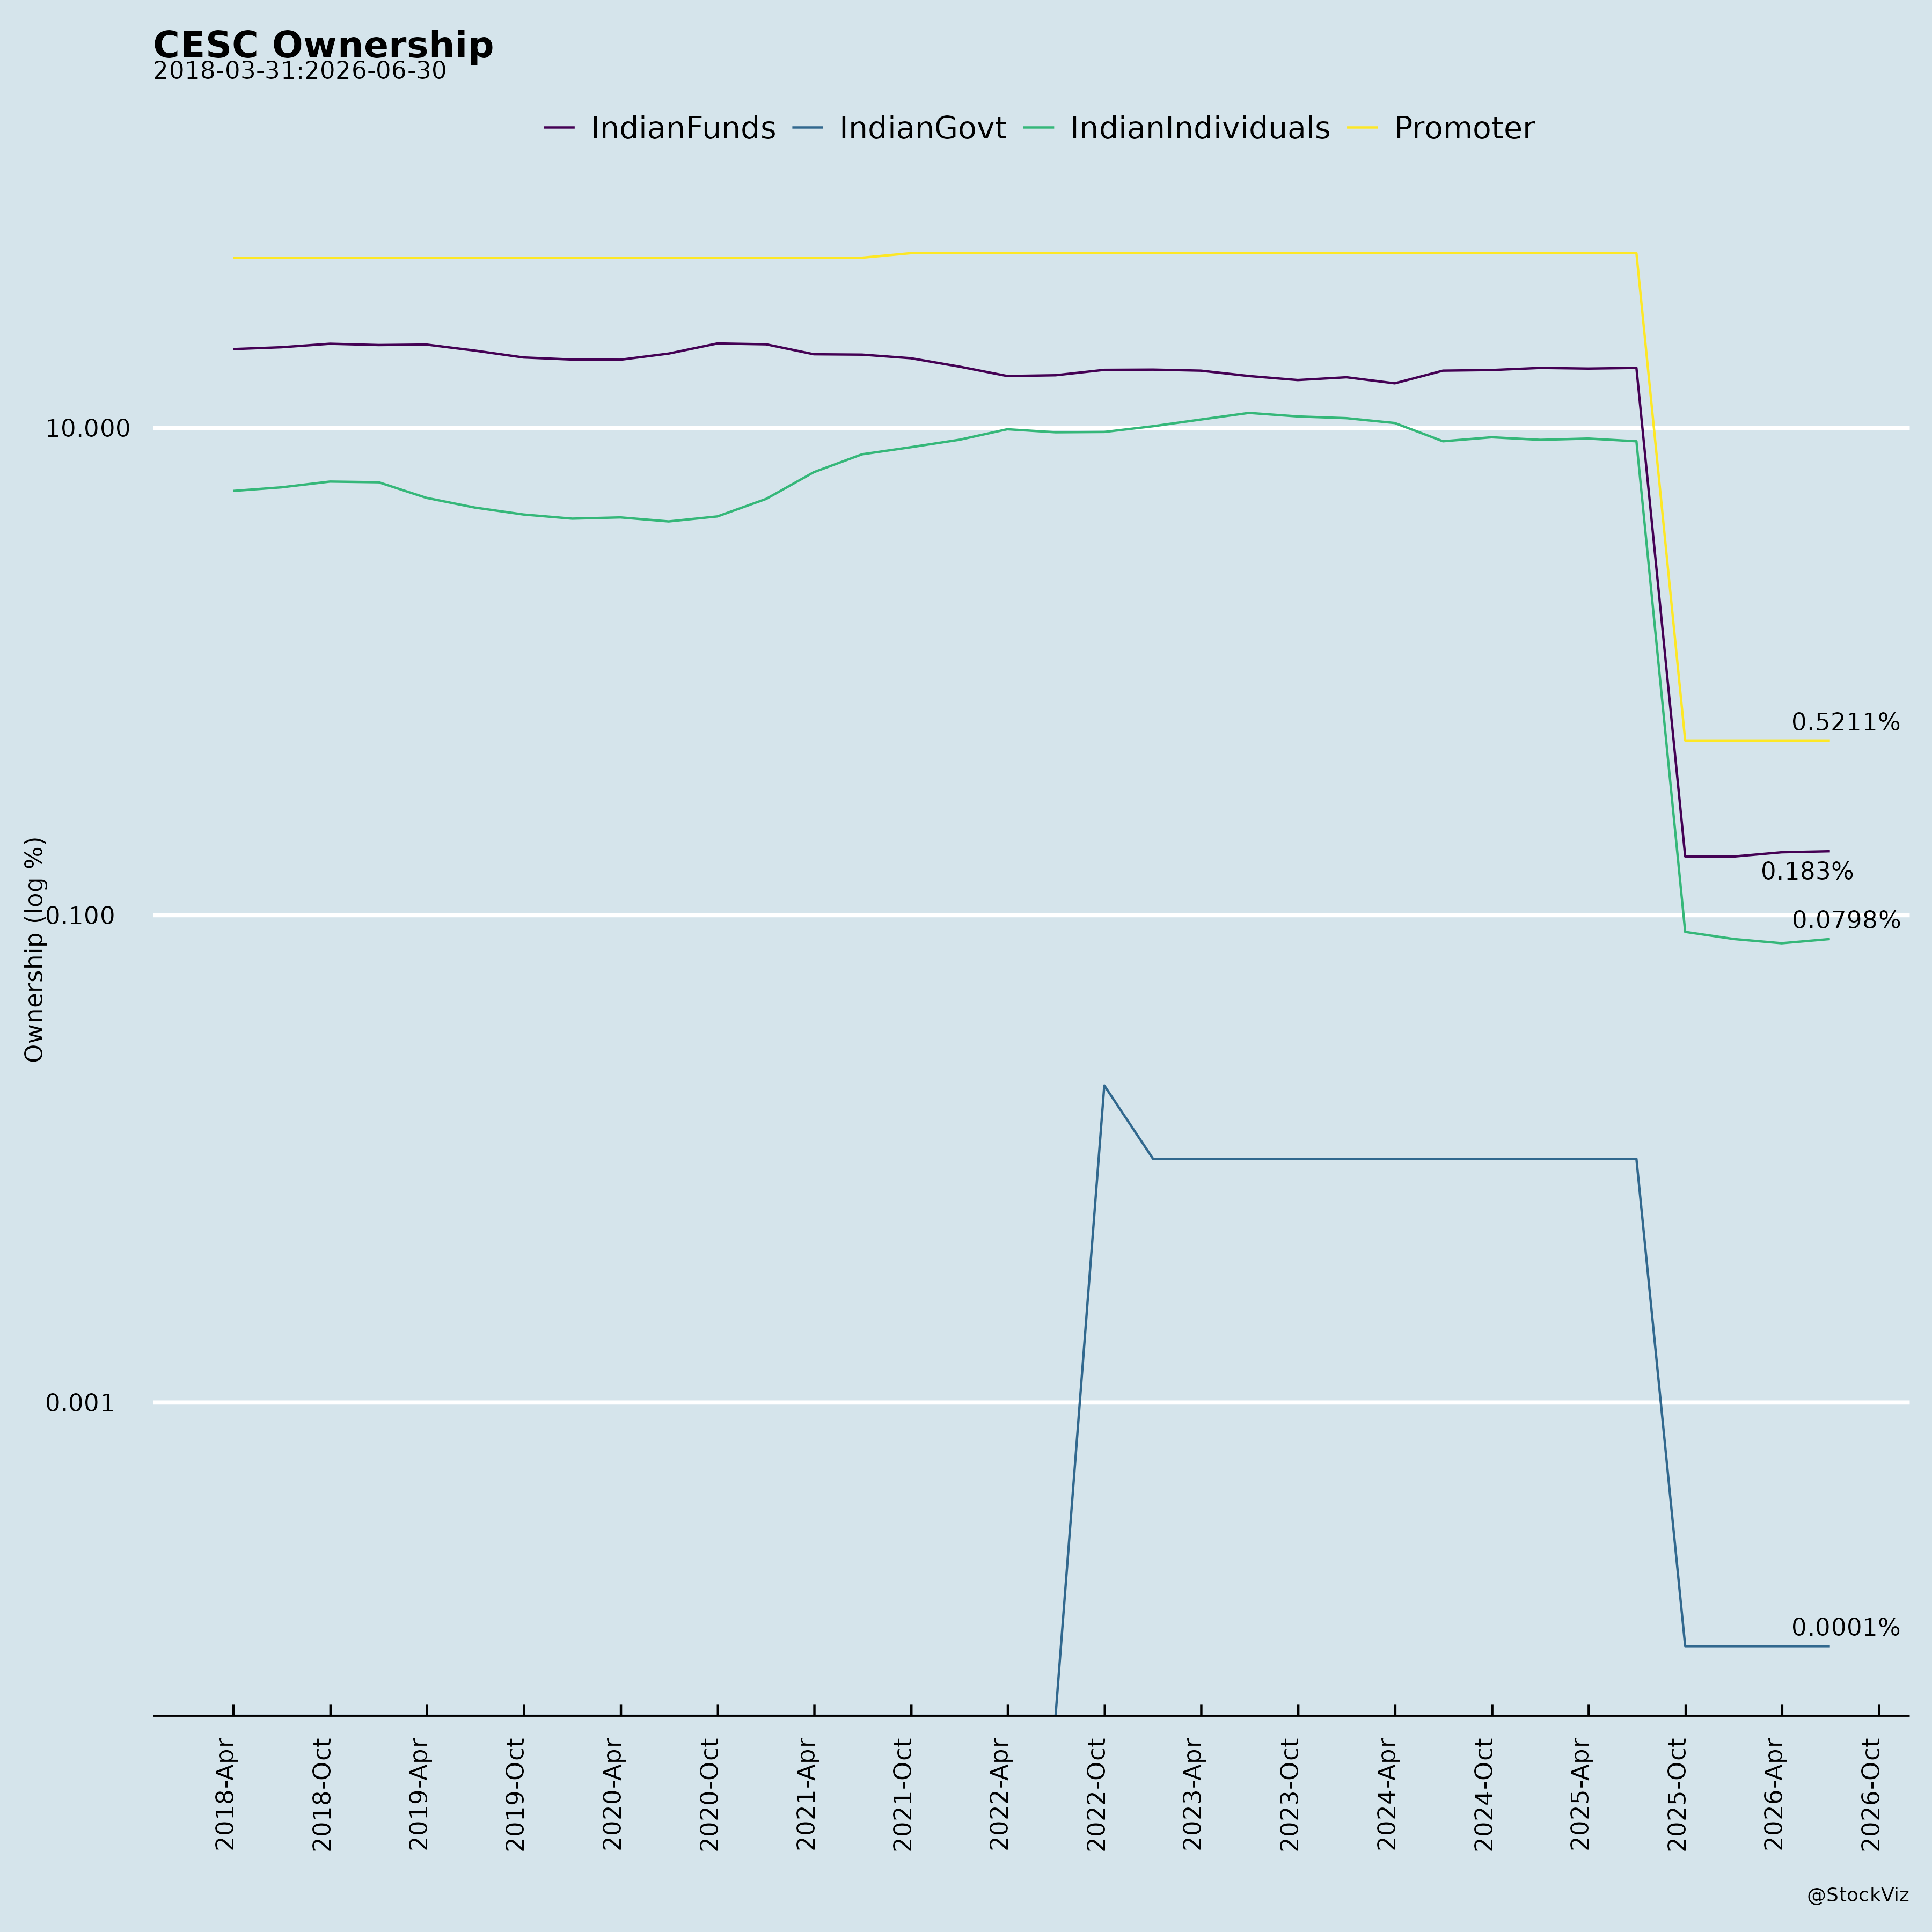
Ownership
Margined
AI Summary
asof: 2026-09-16
CESC: Recent Corporate Developments
Headwinds and Challenges
The supplied material does not identify specific headwinds or challenges. The disclosures are largely transactional and event-based, covering the annual general meeting, investor conference participation, subsidiary incorporations, and a renewable energy award. No operational, regulatory, financial, or competitive pressures are described.
Tailwinds and Growth Prospects
CESC is expanding its renewable energy footprint through multiple channels:
New renewable subsidiaries: On September 8, 2026, CESC incorporated two wholly owned subsidiaries — Purvah Nexgen Energy Private Limited (CIN: U35105WB2026PTC289483) and RPSG Nexgen Energy Private Limited (CIN: U35105WB2026PTC289476) — each with subscribed and paid-up capital of Rs. 1,00,000/-. Both entities are intended to explore opportunities in the renewable power sector.
SECI award for round-the-clock renewable power: Purvah Green Power Private Limited, a CESC subsidiary, received a Letter of Award from Solar Energy Corporation of India Limited (SECI) on August 14, 2026, for supply of 70 MW of Firm and Dispatchable Renewable Energy Round-the-Clock (FDRE-RTC) power from ISTS-connected renewable energy projects under SECI-FDRE-RTC-V. The tariff is Rs. 5.25/kWh over a 25-year period from the Scheduled Commencement of Supply Date. The transaction is domestic and does not involve related party transactions.
Investor engagement: CESC is participating in three upcoming investor conferences — the Morgan Stanley India Industrials & Energy Seminar on September 16, 2026 (virtual), the CLSA Investor’s Forum in Hong Kong from September 21–22, 2026 (physical), and the PL Capital Investor Conference in Mumbai on September 29, 2026 (physical). These engagements may support visibility with institutional investors.
Key Risks
The supplied material does not set out material risks. The only risk-adjacent item is the creation of charge/security on properties, which was one of the resolutions put to shareholders at the Forty-Eighth Annual General Meeting held on September 11, 2026. All six resolutions concerning ordinary and special businesses were passed with the requisite majority, including adoption of audited financial statements, payment of interim dividend, re-appointment of Mr. Shashwat Goenka, continuation of directorship of Mr. Paras Kumar Chowdhary, creation of charge/security on properties, and ratification of cost auditors’ remuneration.
Management Guidance Versus Observed Business Performance
The supplied material contains no management guidance or forward-looking statements beyond the stated intent that the two newly incorporated subsidiaries “will explore opportunities in the renewable power sector.” No financial targets, capacity goals, or timelines are provided against which observed performance could be compared. The SECI Letter of Award to Purvah Green Power (70 MW FDRE-RTC at Rs. 5.25/kWh for 25 years) is the principal observable business development, but the material does not indicate whether it aligns with or departs from prior management guidance.
Broker Narrative
The narrative evolved from early optimism on tariff hikes and non-Kolkata asset performance toward a more complex picture where renewables ambition grew (3GW → 4.5GW) and acquisition-driven growth was emphasized, while operational headwinds like Malegaon losses and margin erosion became prominent. The tariff-hope theme persisted but regulatory income actually fell 21% YoY, undermining the early thesis that past expenses would be allowed through. Buy ratings remained consistent across all 11 reports despite deteriorating fundamentals and repeated negative returns.
Fears that came true
- Regulatory income down 21% YoY to INR 1.8bn confirms the early fear about tariff hike delays and past-expense recognition issues.
- Malegaon loss widened from INR 170mn to INR 430mn QoQ with T&D loss at 36%, materializing the risk flagged in the first report.
- Haldia PAT declined 19.3% YoY, contradicting the claim that non-Kolkata assets were performing well and improving profit contribution.
Optimism that failed
- EBITDA declined 2% YoY to INR 10.8bn with margins falling to 19% from 20.1%, failing the profit growth thesis targeting INR 20bn by FY26E.
- Q1 consolidated PAT was 7% below estimate despite multiple Buy calls promising +16-33% returns.
- Standalone PAT grew only 4% YoY while 9 of 11 Buy calls resulted in DISAPPOINTMENT outcomes with negative actual returns.
Broker Timeline
11 broker calls · 2024-05-31 to 2026-08-14
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.