CENTUM
Equity Metrics
November 18, 2026
Centum Electronics Limited
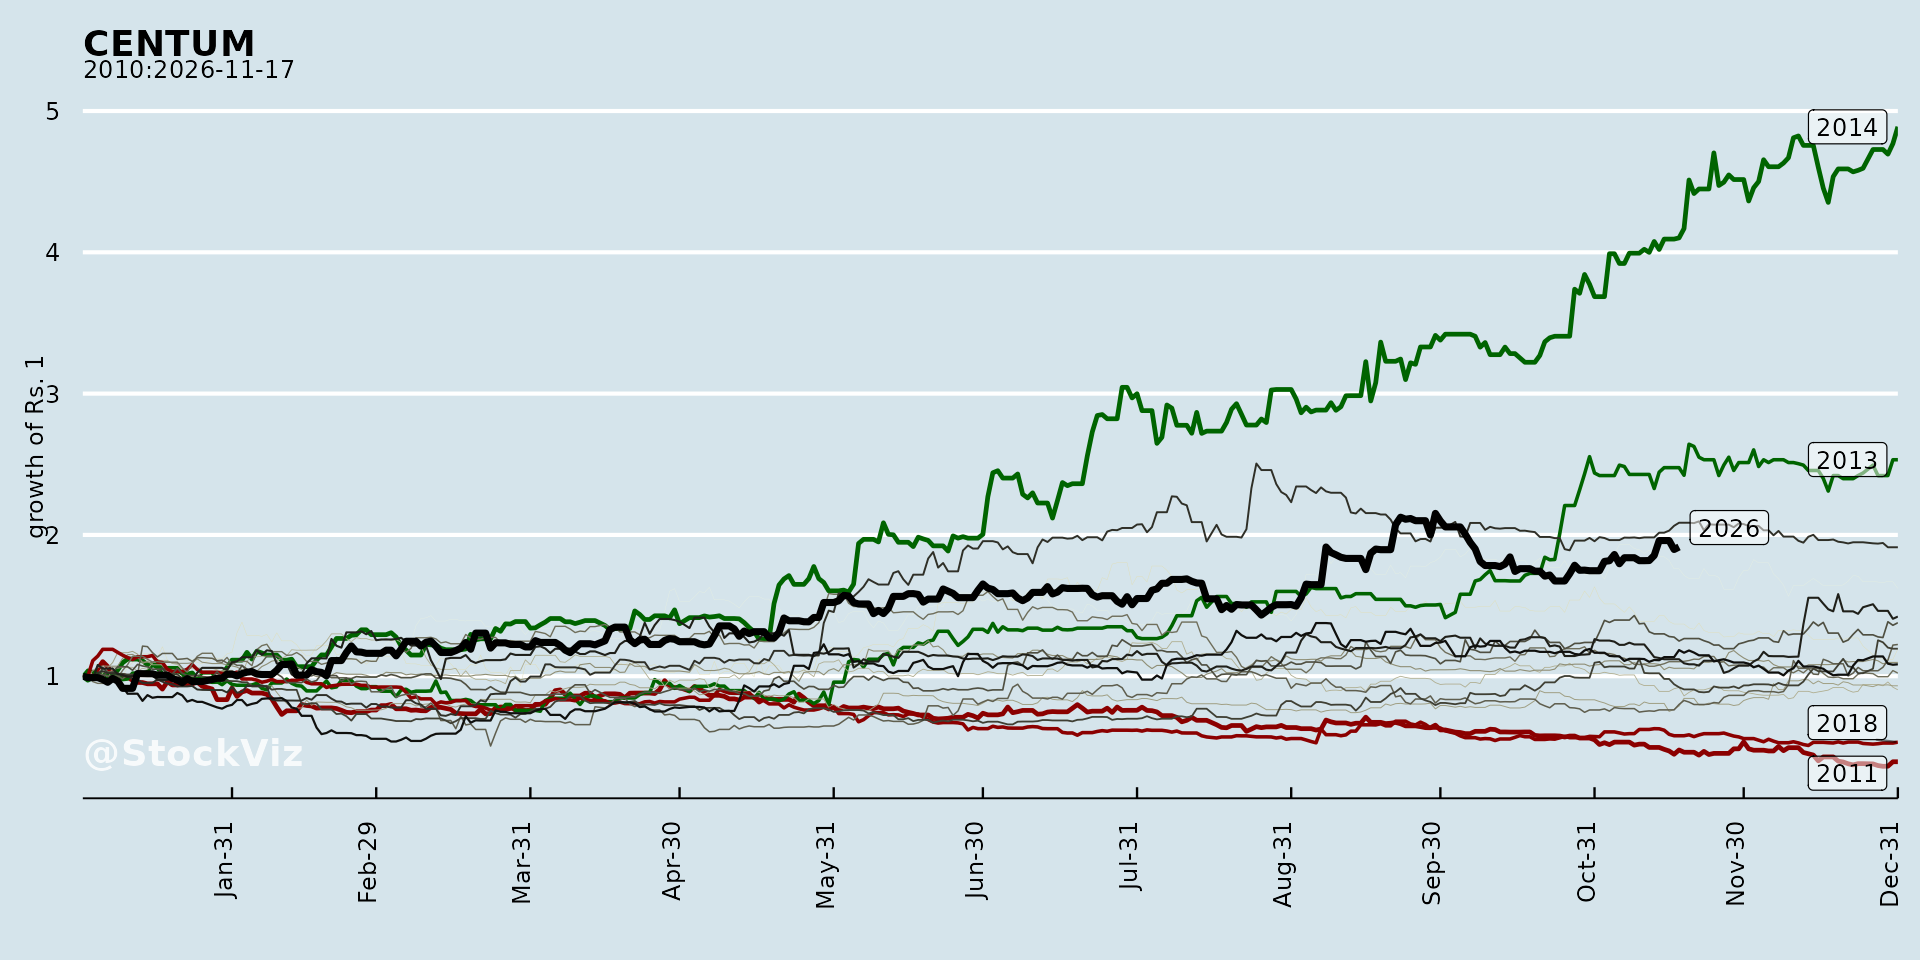
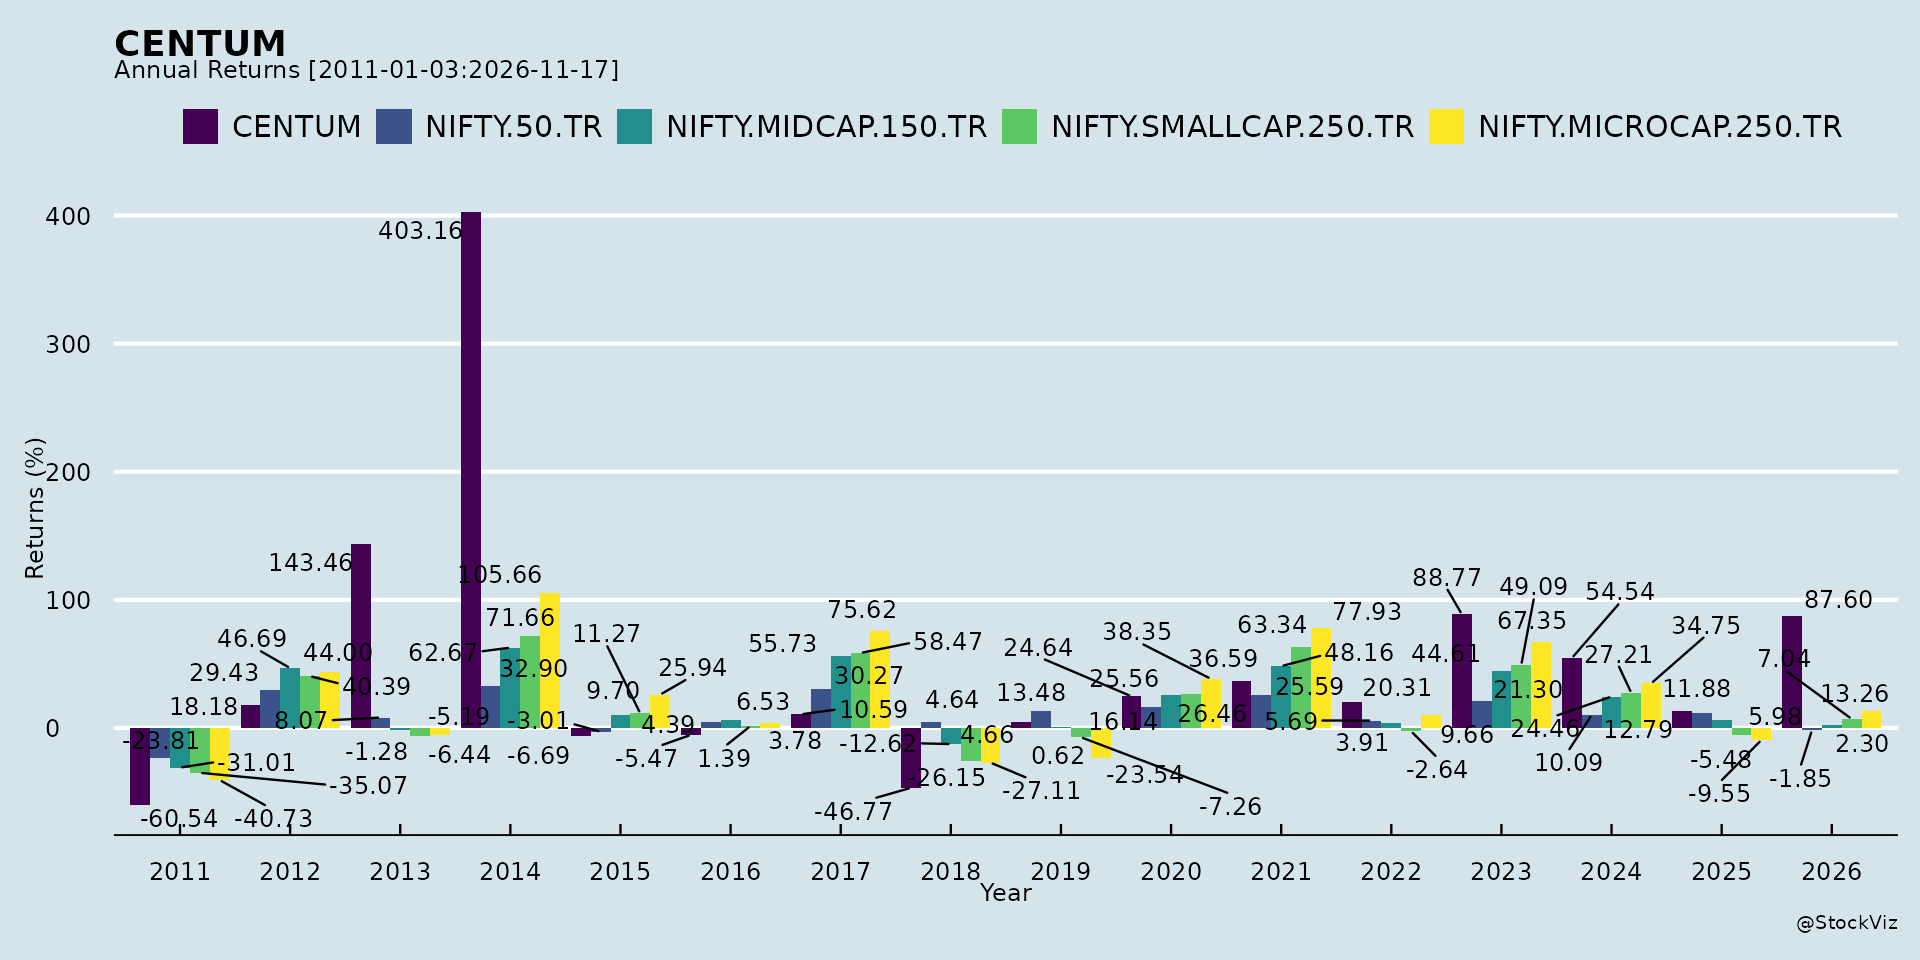
Annual Returns
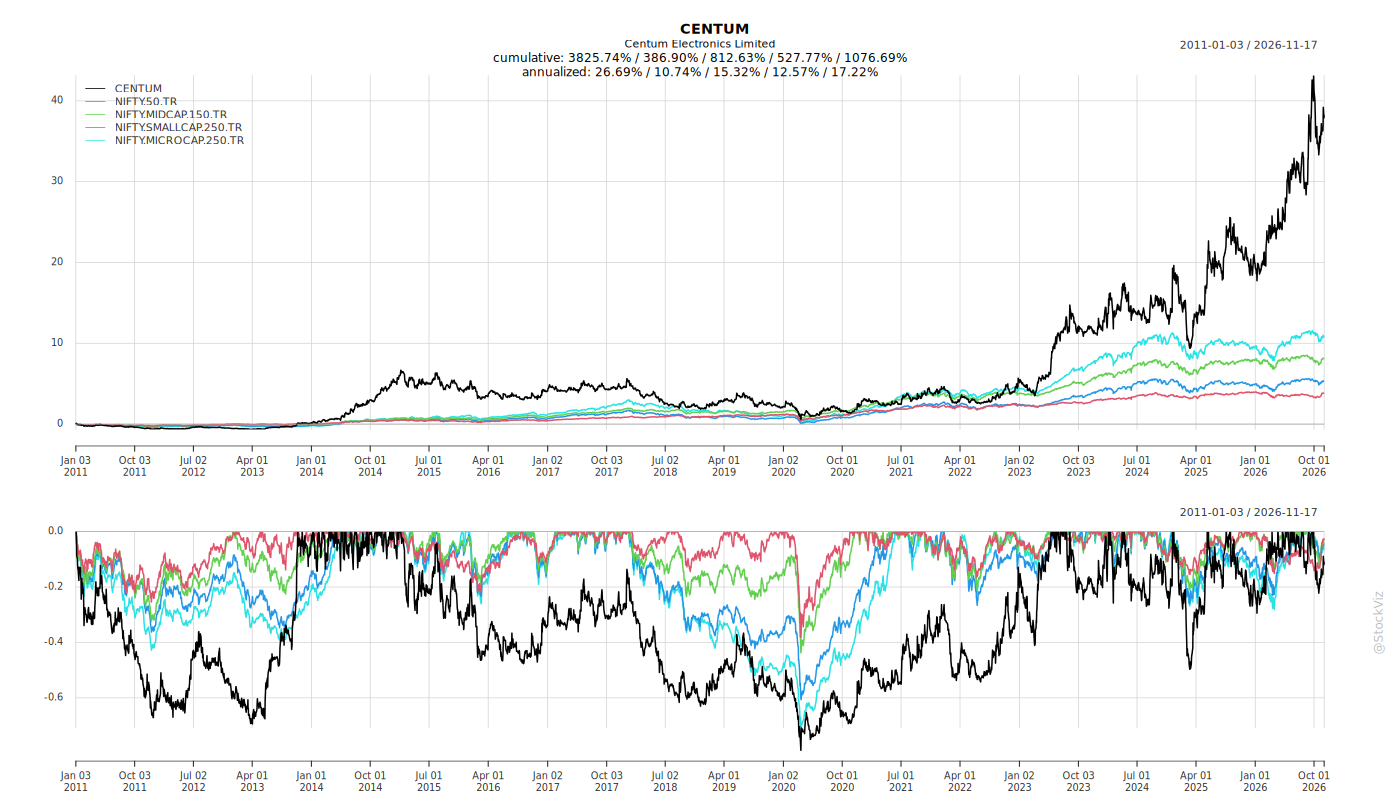
Cumulative Returns and Drawdowns
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-17
Headwinds and Challenges
- Overseas subsidiary losses and wind-down. Centum T&S Group Société Anonyme (S.A.) and its underlying overseas subsidiaries incurred losses that eroded net worth. The Company had provided for the carrying value of its investment in Centum T&S Group S.A. amounting to Rs. 1,537.83 million, disclosed as an exceptional item for the year ended March 31, 2026. The Court of Lyon approved transfer of substantially all of the operating business and employees of Centum T&S Group S.A. and certain underlying overseas subsidiaries to successful bidders by judgement dated June 04, 2026; following completion, those entities no longer retained operating assets or business activity. Subsequent to the quarter ended June 30, 2026, the court converted the proceedings into liquidation judiciaire procedure and appointed a judicial liquidator on July 02, 2026.
- Discontinued Canadian operations. The Board decided on December 19, 2025 to discontinue business operations of Centum E&S (Centum Equipment’s ET Systems), Canada, and Centum T&S (Centum Technologies ET Solutions), Canada, step-down subsidiaries. The Company is making necessary regulatory filings and intimations with relevant regulatory authorities. Management had provided for the carrying value of trade receivables amounting to Rs. 396.00 million, inventory amounting to Rs. 100.78 million, and written back liabilities amounting to Rs. 1.54 million, disclosed as an exceptional item for the year ended March 31, 2026. In the consolidated results, management provided for the carrying value of assets amounting to Rs. 289.38 million and wrote back liabilities amounting to Rs. 45.34 million for the year ended March 31, 2026. During the quarter ended June 30, 2026, the Company recovered Rs. 24.17 million out of such trade receivables provided for and wrote back liabilities amounting to Rs. 3.15 million, disclosed as an exceptional item.
- Goodwill and intangible write-downs on consolidation. The Group provided for goodwill arising on consolidation of Rs. 376.23 million, intangible assets (including under development) amounting to Rs. 178.33 million, and inventory amounting to Rs. 100.78 million, disclosed as profit/(loss) from discontinued operations for the year ended March 31, 2026.
- New Labour Codes cost. The Company assessed implications of the New Labour Codes and recognised an incremental cost of Rs. 31.81 million towards employee benefits during the year ended March 31, 2026, and continues to monitor developments.
- Forward-looking statement risk factors. Forward-looking statements involve known and unknown risks, uncertainties and other factors which may cause actual results, financial condition, performance or achievements to differ materially, including future changes or developments in the company’s business, its competitive environment, and political, economic, legal, and social conditions.
Tailwinds and Growth Prospects
- Export order win. The Company secured an export order from a Global OEM customer for the Design, Development and Delivery of Electronic Systems, valued at approximately USD 3.22M (approximately ₹305 Million), to be executed over the next 7 months. This was described as a significant milestone and a major strategic win for Centum’s Build to Specification (BTS) export business, strengthening the Company’s position as a trusted partner for advanced electronic systems in the global defence and aerospace ecosystem.
- Industry tailwinds. China+1 diversification, government incentives (PLI, EMC 2.0, ISM 2.0), semiconductor expansion, high-value vertical expansion, value-chain upgrade, rising defence budgets and indigenisation mandates, global OEMs seeking Indian defence partners, modernisation across radar, EW & missile platforms, and space sector expansion.
- Proposed manufacturing facility. Mr. Nikhil Mallavarapu, Joint Managing Director, along with other representatives, met Shri M. B. Patil, Hon’ble Minister for Large and Medium Industries and Infrastructure Development, Government of Karnataka, and discussions were held regarding the Company’s proposed new manufacturing facility in Karnataka and related matters. This disclosure followed media reports published on August 7, 2026 relating to the proposed facility.
- Business profile. Centum operates in two business segments (BTS & EMS) with ~1,650 employees, an order book of INR 18 Bn as on 30th Jun 26, 54% exports revenue, 17 patents granted, 350,000 sq ft manufacturing footprint, and key certifications including SAMAR L5, ISO 13485, IATF 16949, and ISO 27001.
Key Risks
- The overseas subsidiary wind-down and liquidation judiciaire proceedings, with a judicial liquidator appointed on July 02, 2026, following the June 04, 2026 Court of Lyon judgement transferring operating business and employees to successful bidders.
- The discontinued Canadian operations and related regulatory filings and intimations, with provisions taken on trade receivables, inventory, and asset carrying values.
- Goodwill, intangible asset, and inventory write-downs recognised in discontinued operations.
- Incremental employee benefit costs from the New Labour Codes, with continuing monitoring of developments.
- Forward-looking statement risk factors including changes in the company’s business, competitive environment, and political, economic, legal, and social conditions.
Management Guidance Versus Observed Business Performance
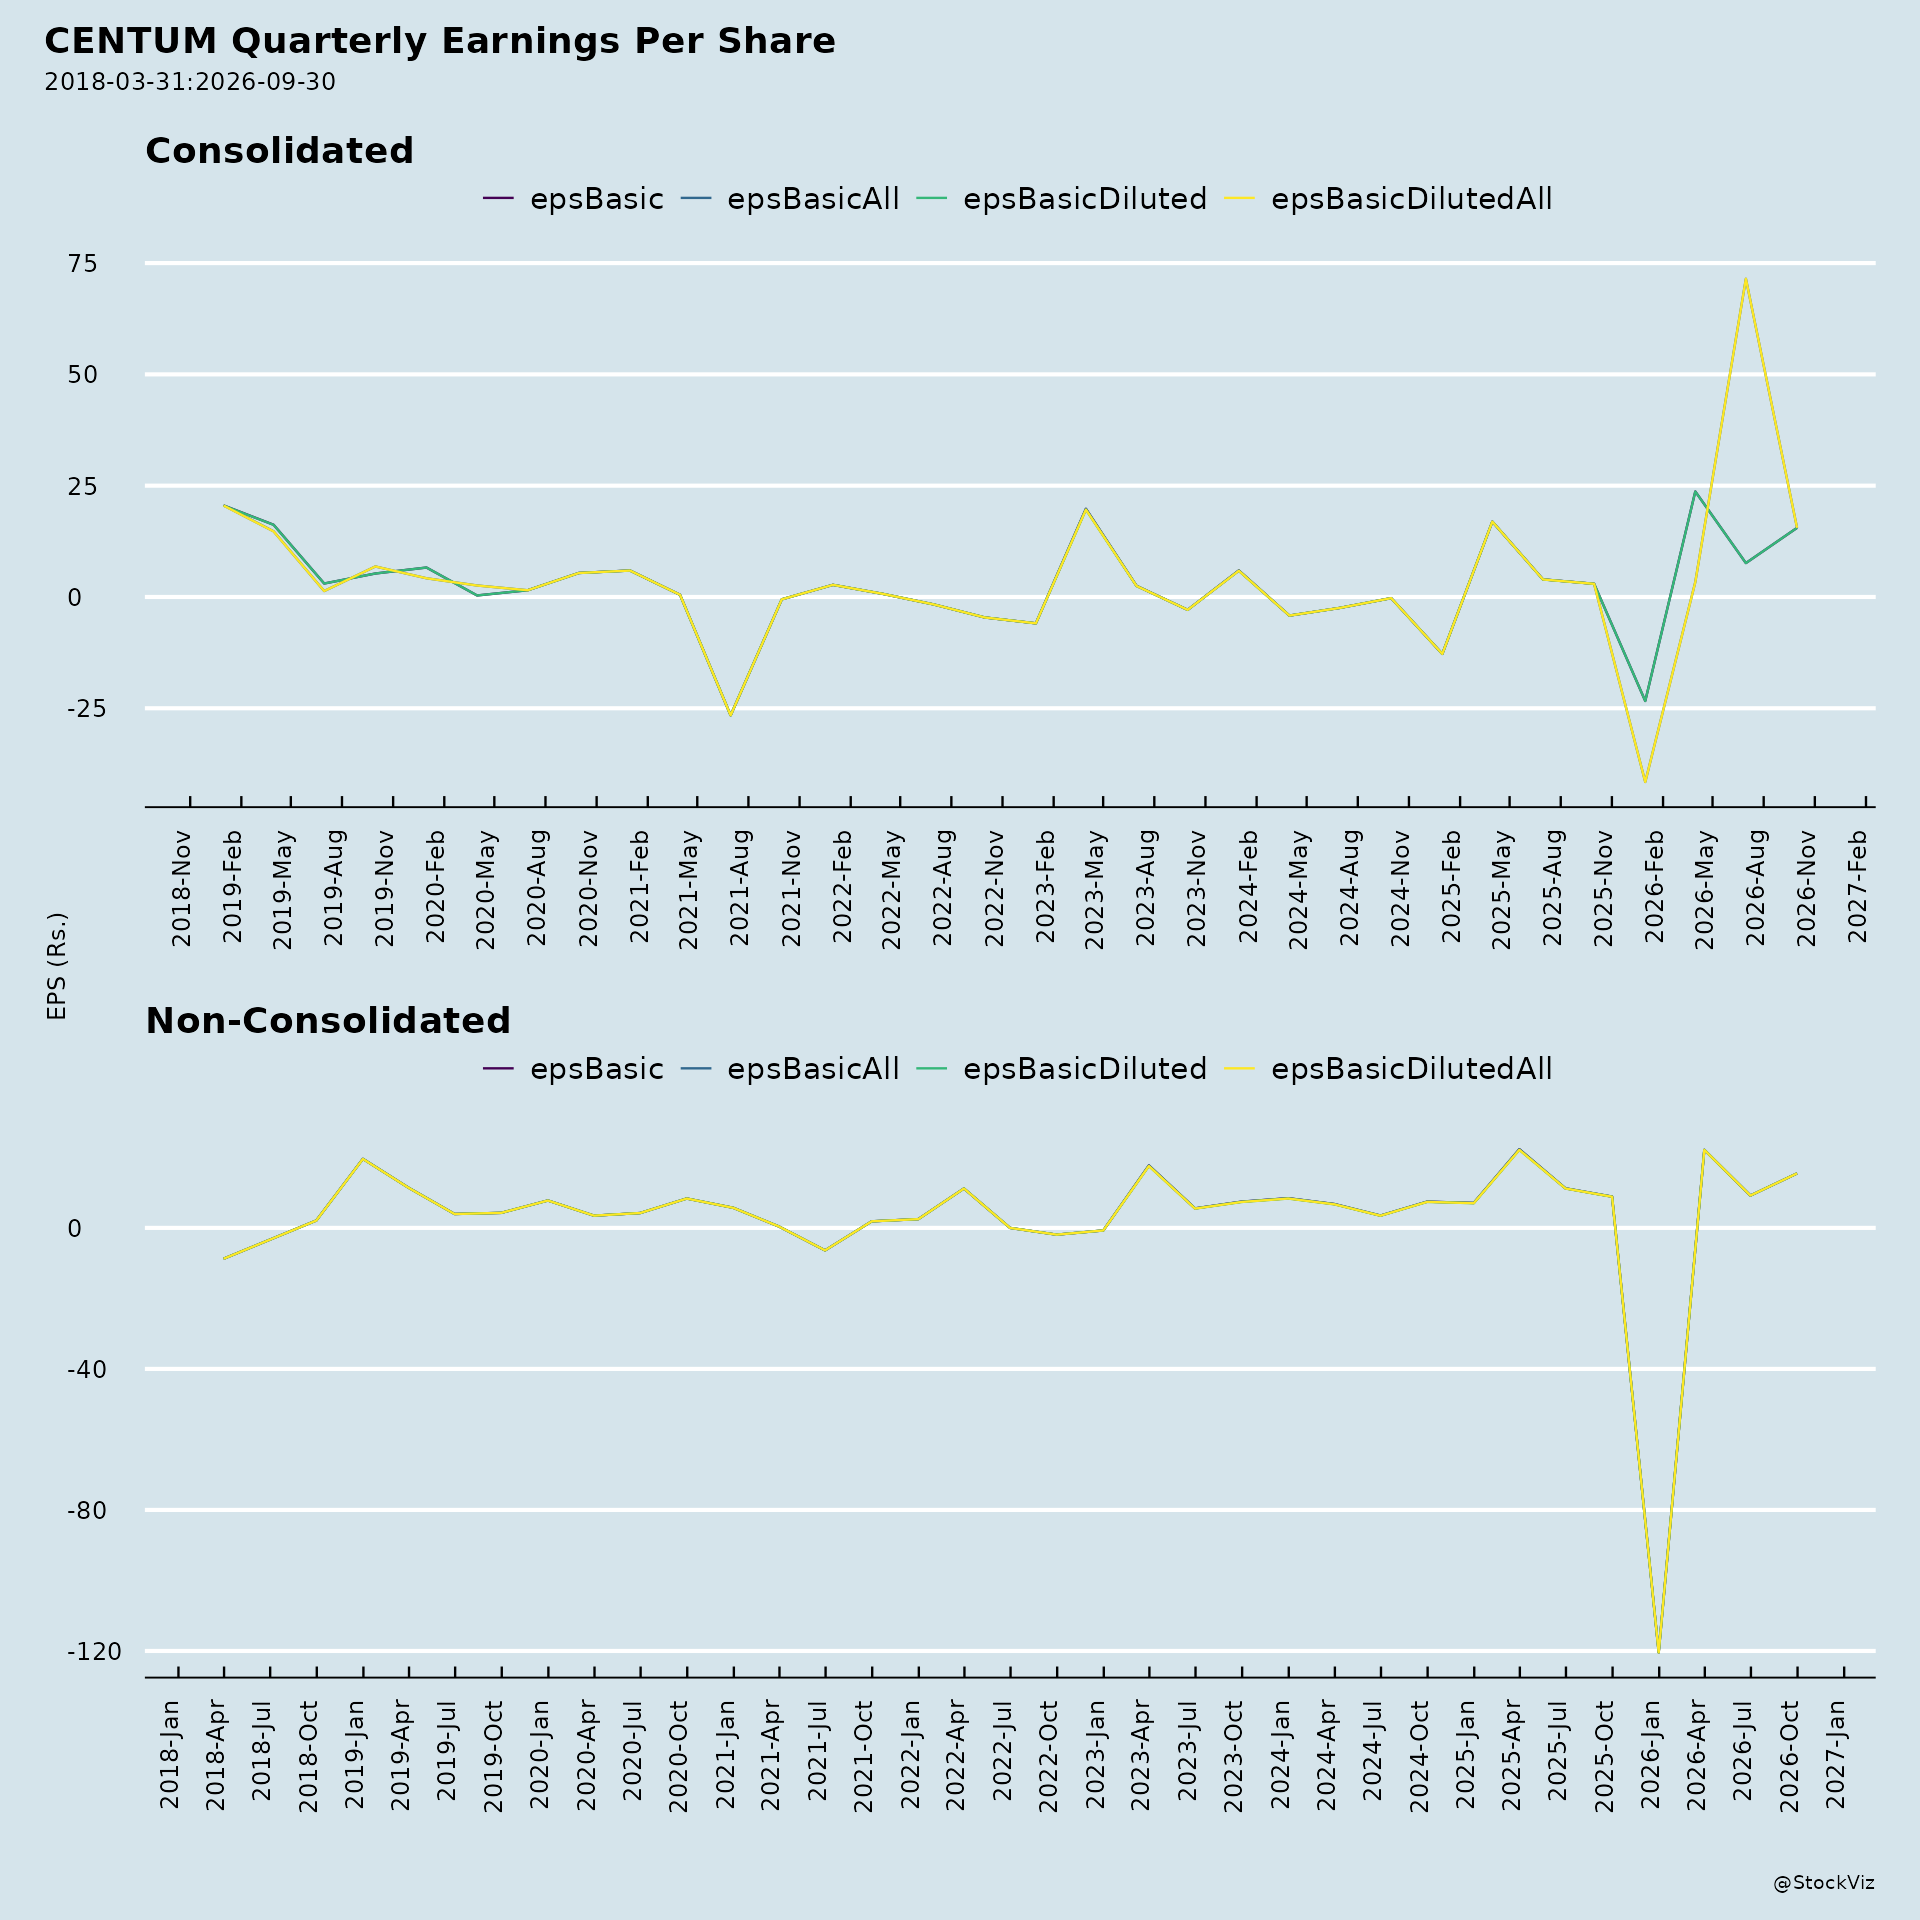
- Q1 FY27 (quarter ended June 30, 2026) standalone results: Total income Rs. 2,070.91 million; profit before exceptional items and tax Rs. 155.02 million; exceptional items Rs. 27.52 million; profit before tax Rs. 182.54 million; profit for the period Rs. 135.33 million; basic and diluted EPS Rs. 9.17.
- Q1 FY27 consolidated results: Total income Rs. 2,064.58 million; profit before tax from continuing operations Rs. 159.52 million; profit after tax from continuing operations Rs. 112.31 million; profit after tax from discontinued operations Rs. 942.69 million; profit for the period Rs. 1,055.00 million; basic and diluted EPS from continuing and discontinued operations Rs. 71.47.
- Prior-year comparatives (restated): For the quarter ended June 30, 2025, standalone total income was restated from Rs. 1,826.05 million to Rs. 1,880.24 million; total expenses from Rs. 1,599.99 million to Rs. 1,668.22 million; profit before tax from Rs. 226.06 million to Rs. 212.02 million; profit for the period from Rs. 164.99 million to Rs. 154.51 million; basic EPS from Rs. 11.22 to Rs. 10.49; diluted EPS from Rs. 11.17 to Rs. 10.48.
- Amalgamation impact: The Scheme of Amalgamation of wholly owned subsidiary Centum T&S Private Limited with the Company, approved by the Bengaluru Bench of the NCLT by order dated October 29, 2025, became effective from October 29, 2025 with an appointed date of April 01, 2024. Accounting was done applying the Pooling of Interest method, and previous year/quarter figures were restated.
- QIP utilisation: Proceeds from the QIP (net of share issue expenses) of Rs. 2,006.79 million are to be utilised towards repayment/prepayment, in full or in part, of certain outstanding borrowings and general corporate purposes. Unutilized funds from the QIP amounting to Rs. 149.90 million were placed in fixed deposits with banks, Rs. 440.00 million invested in mutual funds, and Rs. 10.19 million in other balance with bank as at June 30, 2026.
- Capital increase: The Board approved allotment of 3,000 equity shares to employees who exercised options under the Centum Restricted Stock Unit Plan 2021, increasing paid-up equity share capital from Rs. 14,75,90,160 to Rs. 14,76,20,160.
- AGM outcomes (August 13, 2026): All five resolutions were passed with requisite majority — adoption of standalone financial statements (98,04,613 votes in favour, 10 against), adoption of consolidated financial statements (98,04,607 in favour, 16 against), declaration of a final dividend of Rs. 5/- per equity share of face value Rs. 10/- each for FY ended March 31, 2026 (98,04,611 in favour, 12 against), re-appointment of Ms. Tanya Mallavarapu (DIN: 01728446) as Director retiring by rotation (98,04,588 in favour, 35 against), and remuneration payable to Cost Auditors K.S. Kamalakara & Co. of Rs. 1,50,000/- per annum plus applicable taxes and out-of-pocket expenses for FY 2026-27 (98,04,608 in favour, 15 against).
- Management forward-looking statements: Management notes forward-looking statements based on currently held beliefs and assumptions relating to the company’s general business plans, strategy, future financial condition, growth prospects, and future developments in its industry and competitive and regulatory environment, while cautioning viewers not to place undue reliance on them.
- Investor meeting: The company’s representatives will be meeting with various analysts and institutional investors in a virtual group meeting on September 9, 2026, starting at 2:00 pm IST, and no Unpublished Price Sensitive Information (UPSI) is intended to be discussed.
Broker Narrative
The Buy call and the core domestic defence/space growth thesis persisted, with the order pipeline expanding from BTS ₹650–665 Cr and EMS ₹763 Cr to a ₹1,952 Cr book (BTS ₹959 Cr, +47% YoY) by September 2026, but the margin recovery ran a year behind schedule: the 13–15% margin promised for FY26 is now only targeted in FY28, after BTS/EMS mix gains lifted EBITDA margin back to 12.7% in Q2FY27 from 7.1% in Q2FY26. The narrative also shifted from a near-term FY26 rebound (H2FY26 strength, margin guidance, moderating overseas losses, European/Canadian recovery) to a multi-year compounding story (FY27E revenue ₹1,240 Cr, FY28E ₹1,587 Cr/EPS ₹87.4, 20–22% medium-term BTS margins, semiconductor equipment toward US$45–50 Mn, EW exports and a satellite-payload facility), even though the FY26 revenue-implied (FY27E at 25–30% growth) margin sat below the originally guided 13–15%. Headwinds moved from external factors (Europe macro, overseas losses, Canadian divestment) to internal execution and balance-sheet constraints (component shortages with 40–50-week PCB lead times, raw-material inflation, BTS working capital and execution risk, and borrowing headroom largely used up, prompting a ₹500 → ₹1,000 Cr limit hike), yet the bullish tone never flagged that the stock had already fallen about 13.9% on the 2026-09-23 Buy.
Optimism that failed
- The H2FY26 rebound and 13–15% FY26 EBITDA margin guidance did not materialize: a year later, the last report targets 12.5–13% near-term margin and only expects to cross 13% in FY28, and Q2FY27’s 12.7% margin (+84 bps YoY implies ~11.9% a year earlier, even with Q2FY26 at 7.1%) points to an FY26 average below the 13% floor, despite gross margins being flat YoY.
- The MoU-flagged GRSE naval navigation (potential ₹500–600 Cr) and BEL EW/radar/military-comms pipeline did not materialize at the touted scale, with the last report citing only a ₹51 Cr tactical air navigation order and a ~₹30 Cr EW export order and naming neither partner.
Broker Timeline
4 broker calls · 2025-11-14 to 2026-11-06
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.