BPCL
Equity Metrics
November 18, 2026
Bharat Petroleum Corporation Limited
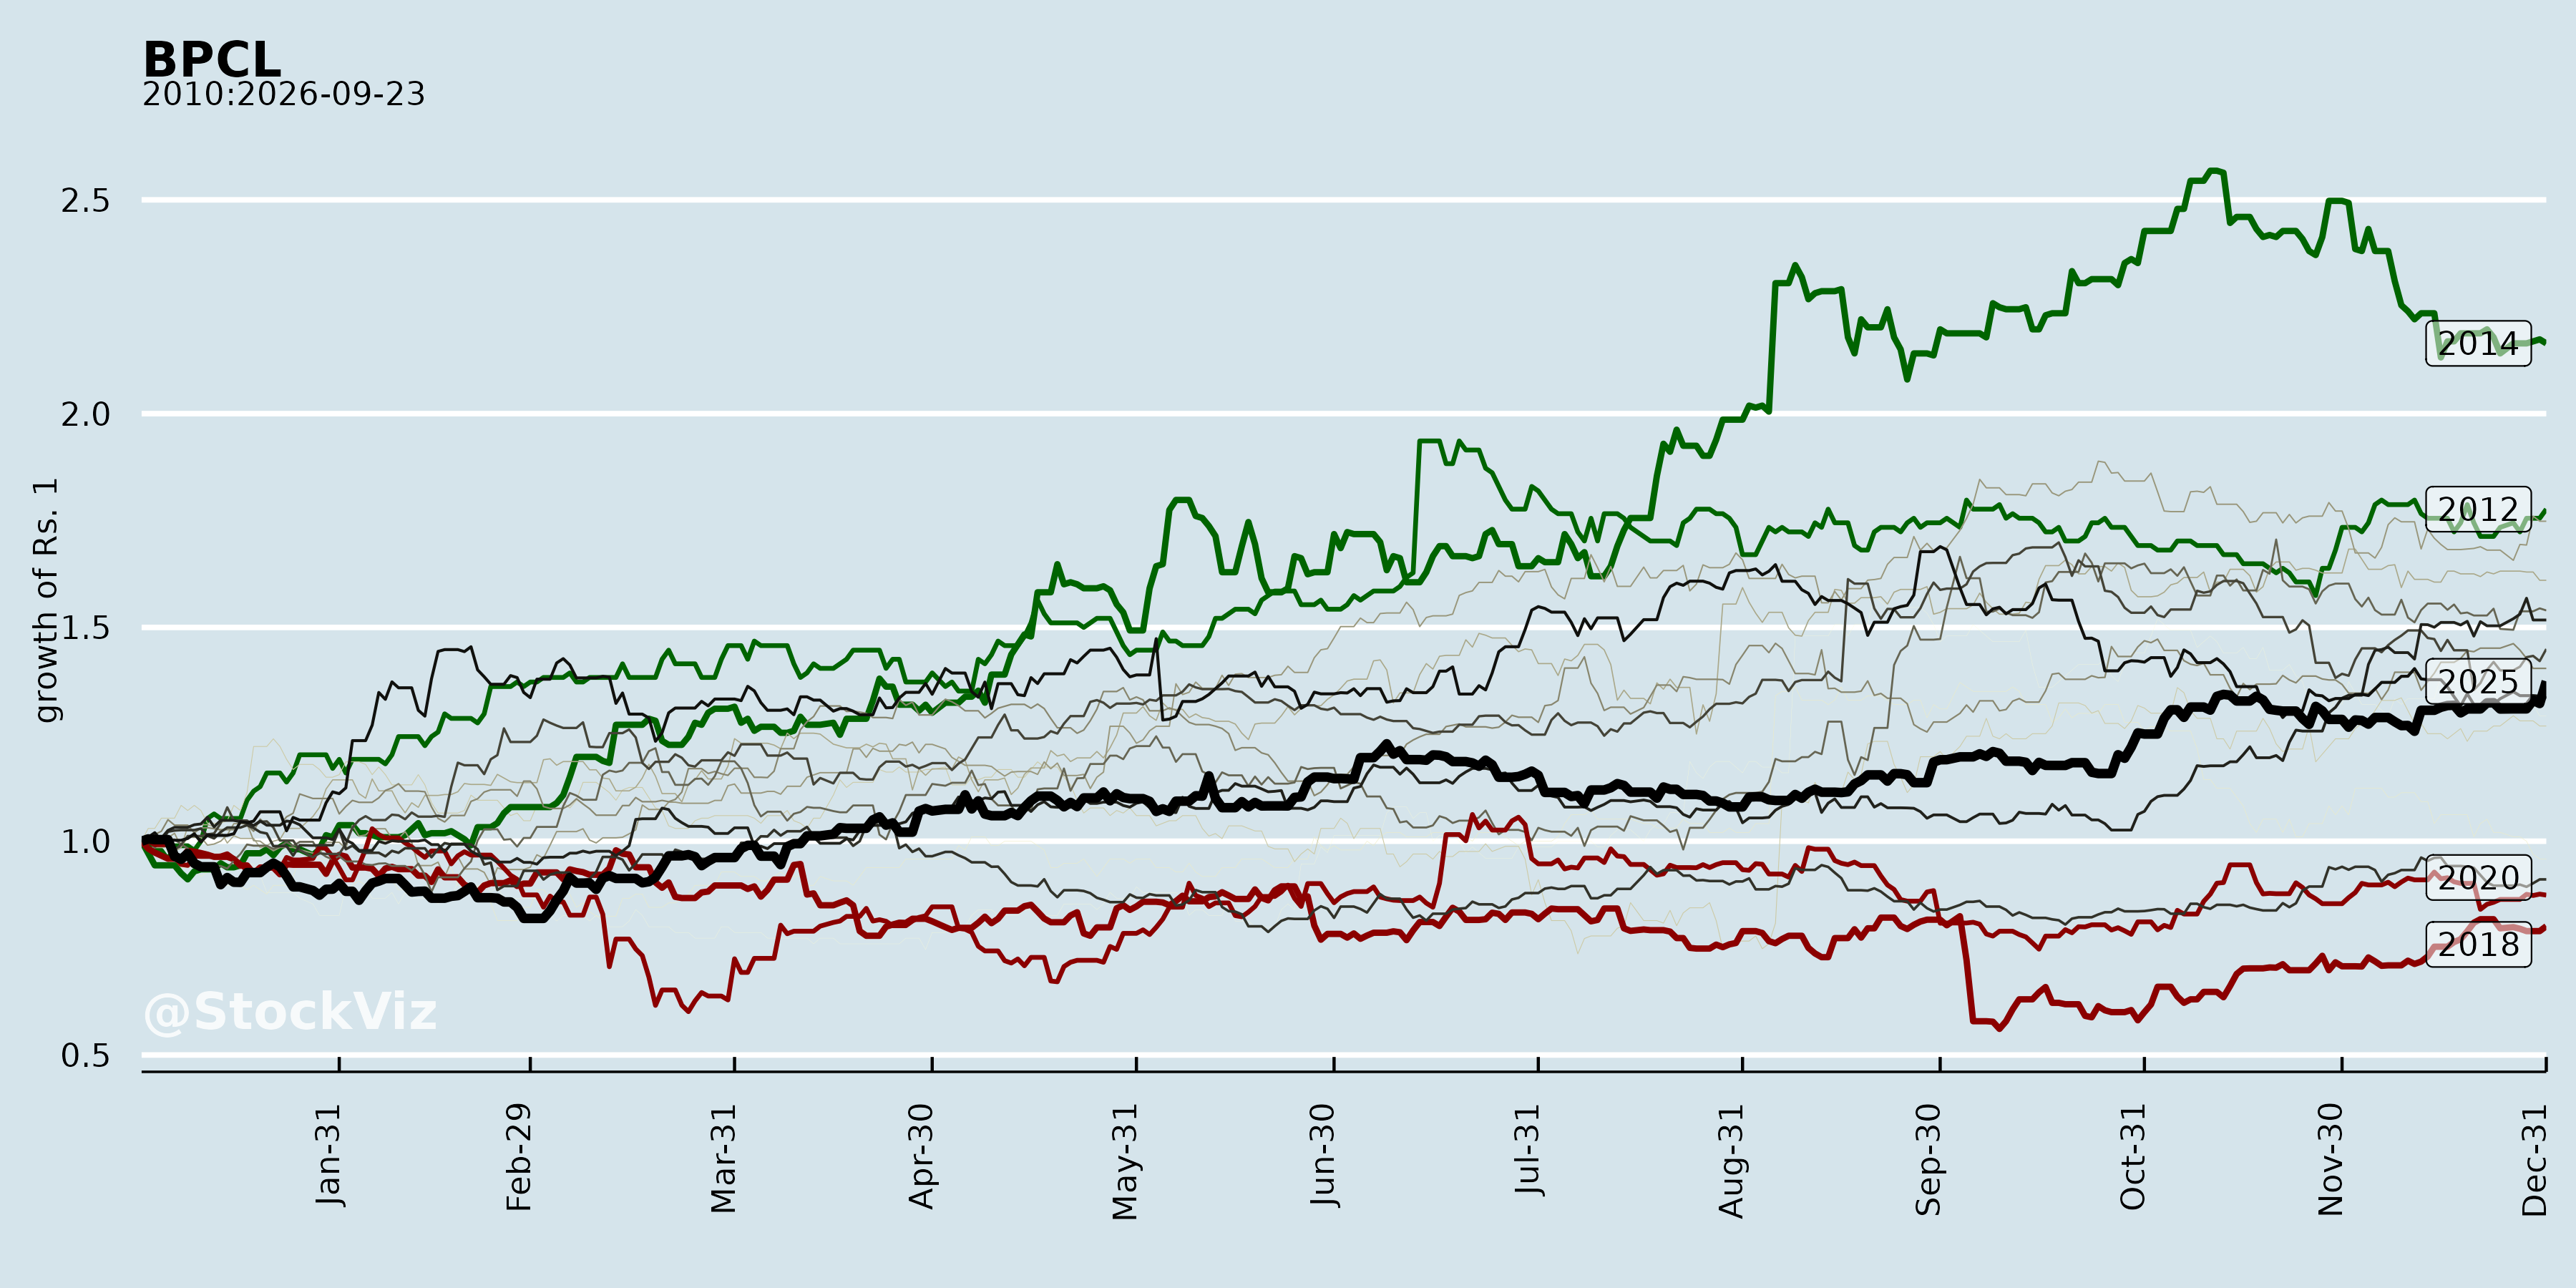
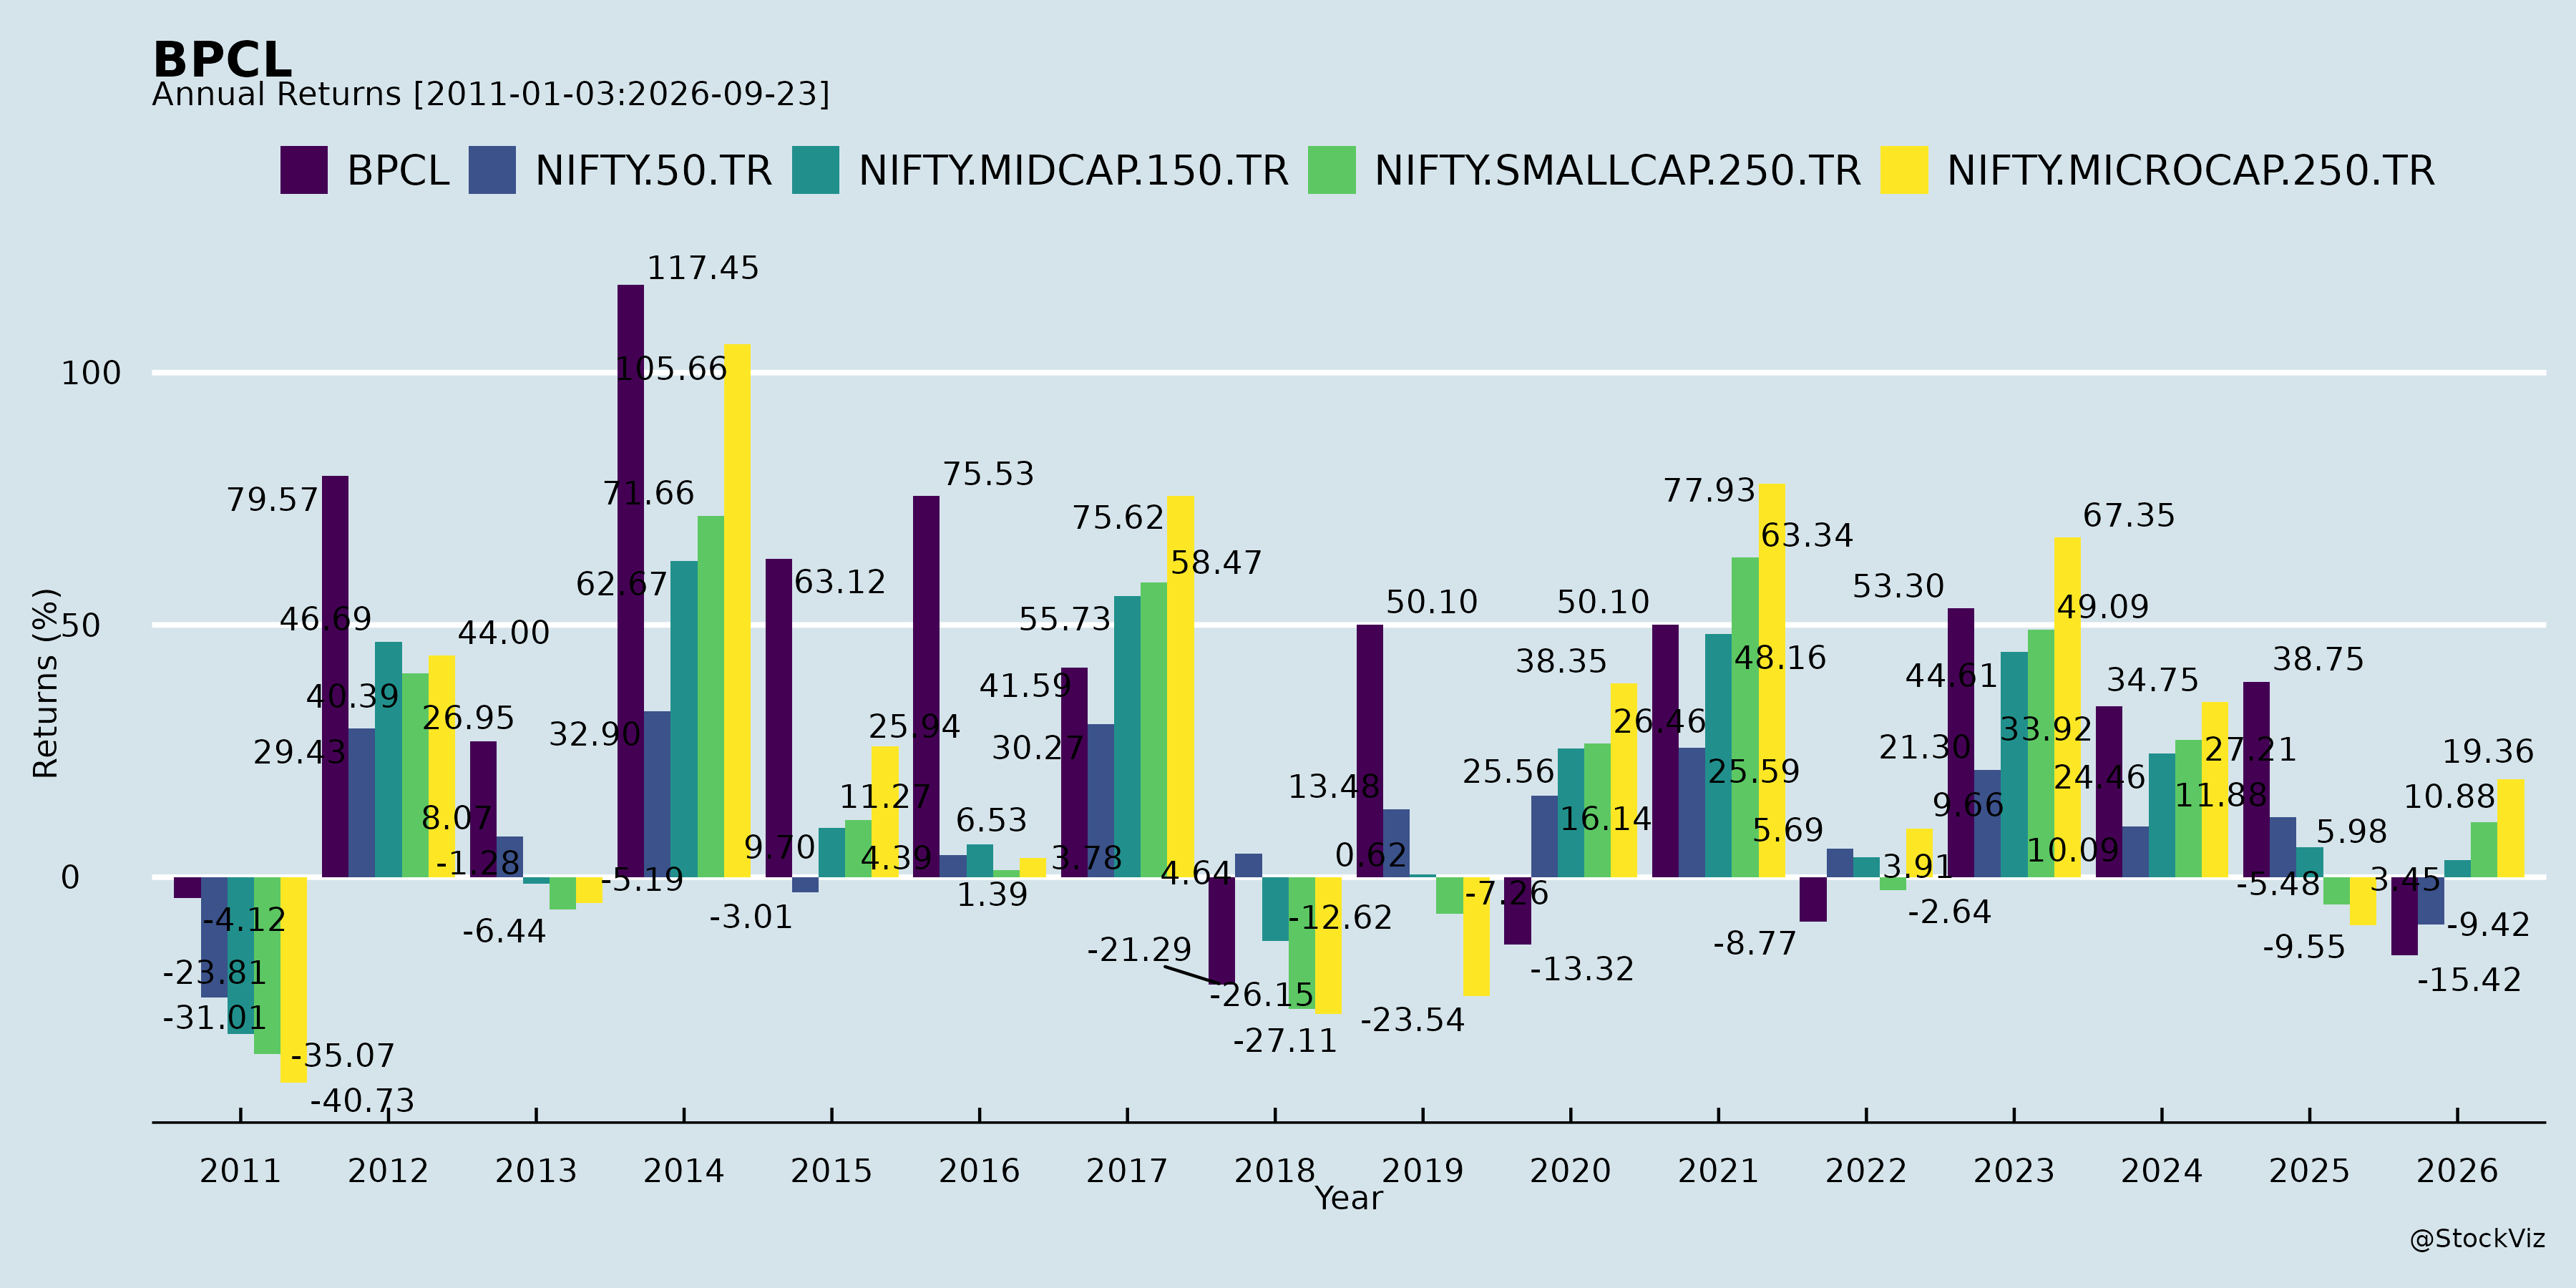
Annual Returns
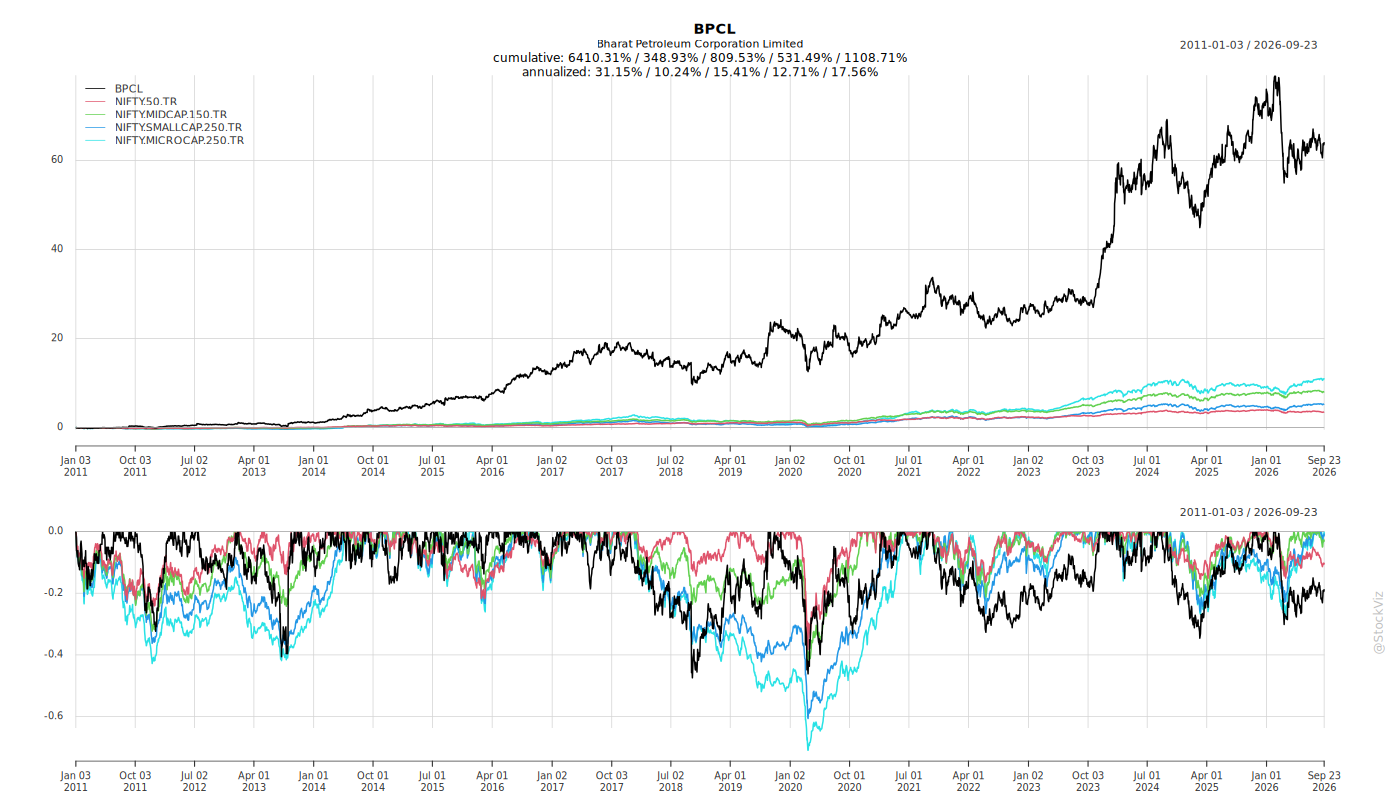
Cumulative Returns and Drawdowns
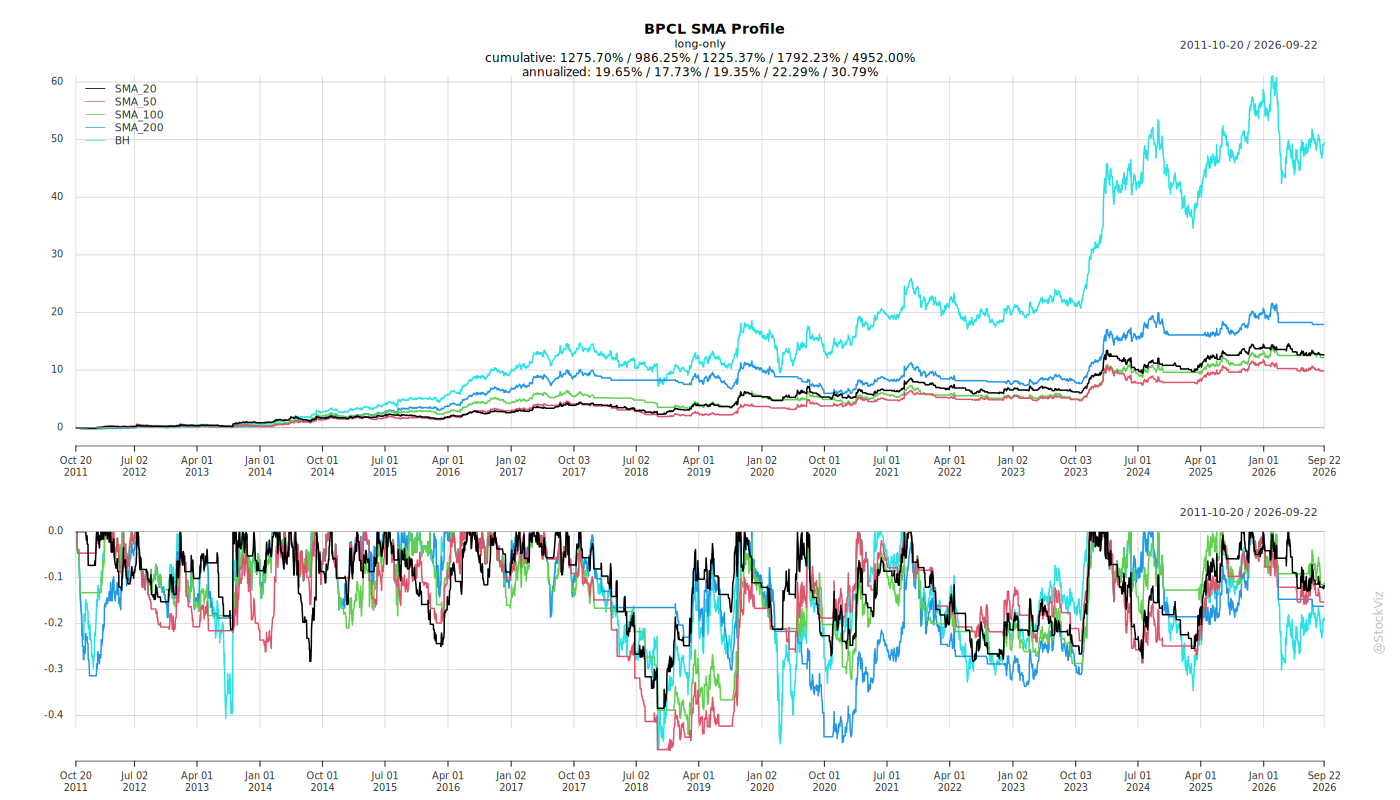
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-14
BPCL: Recent Corporate Developments
Headwinds and Challenges
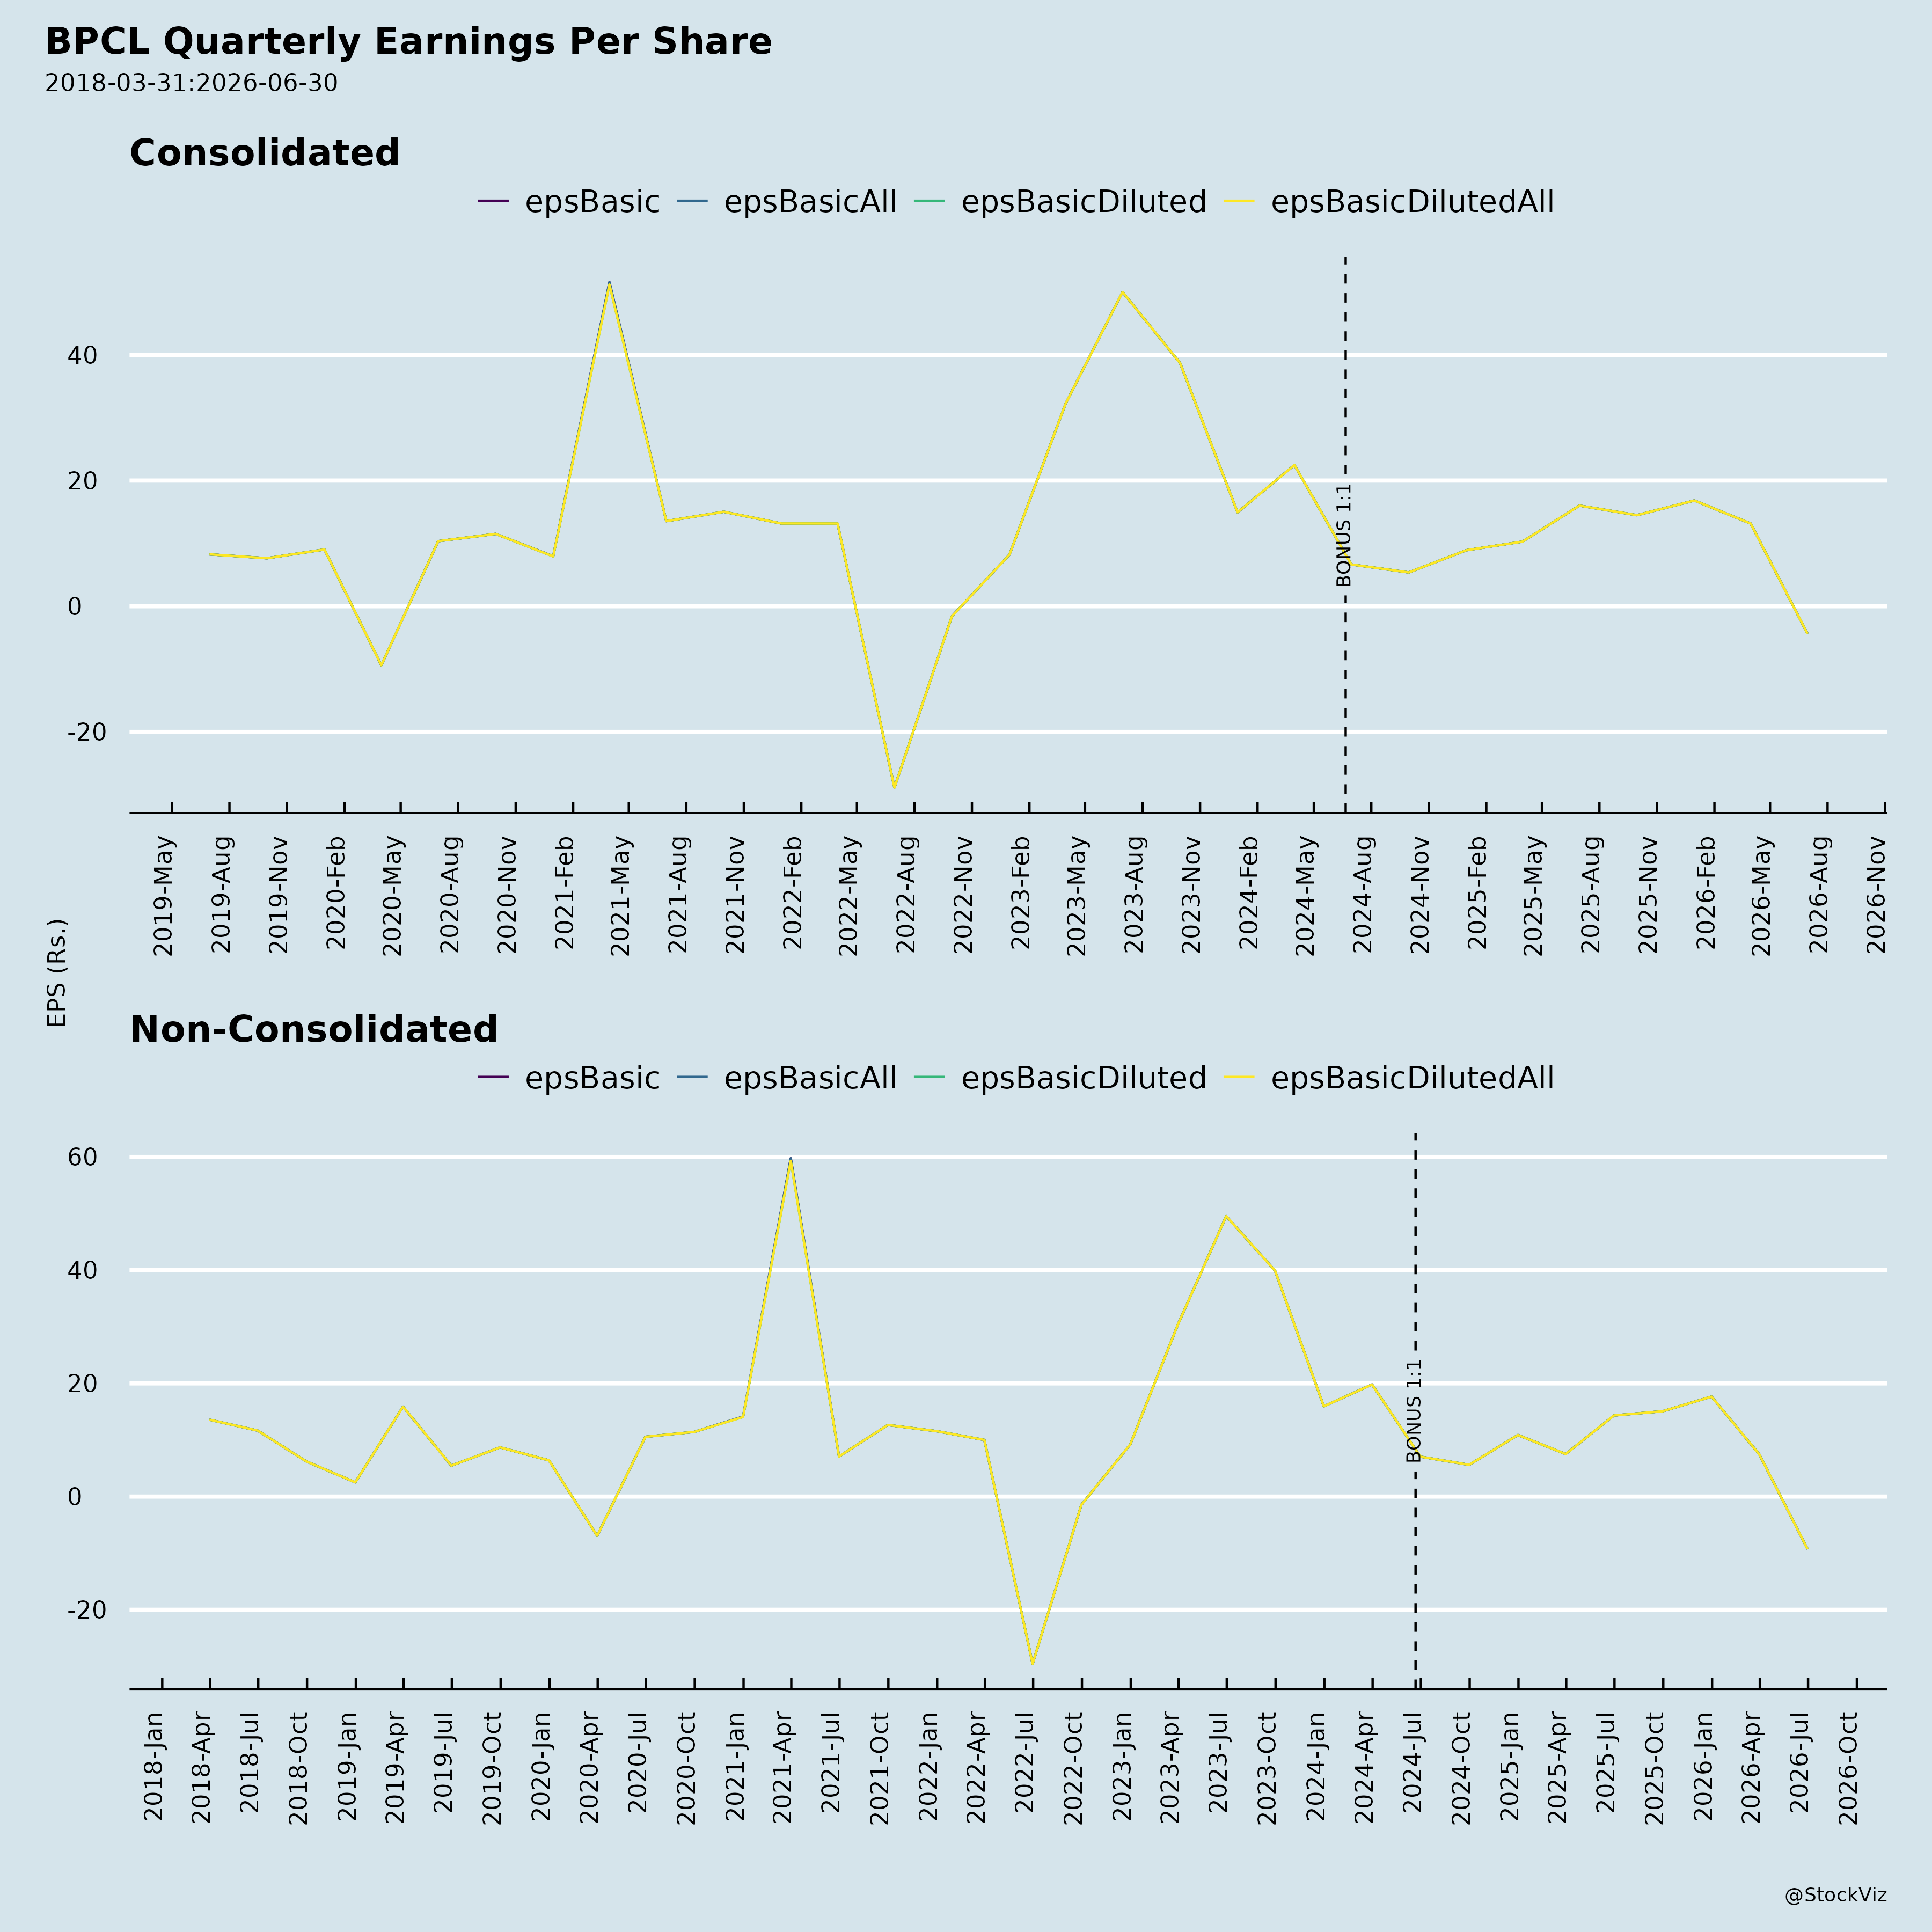
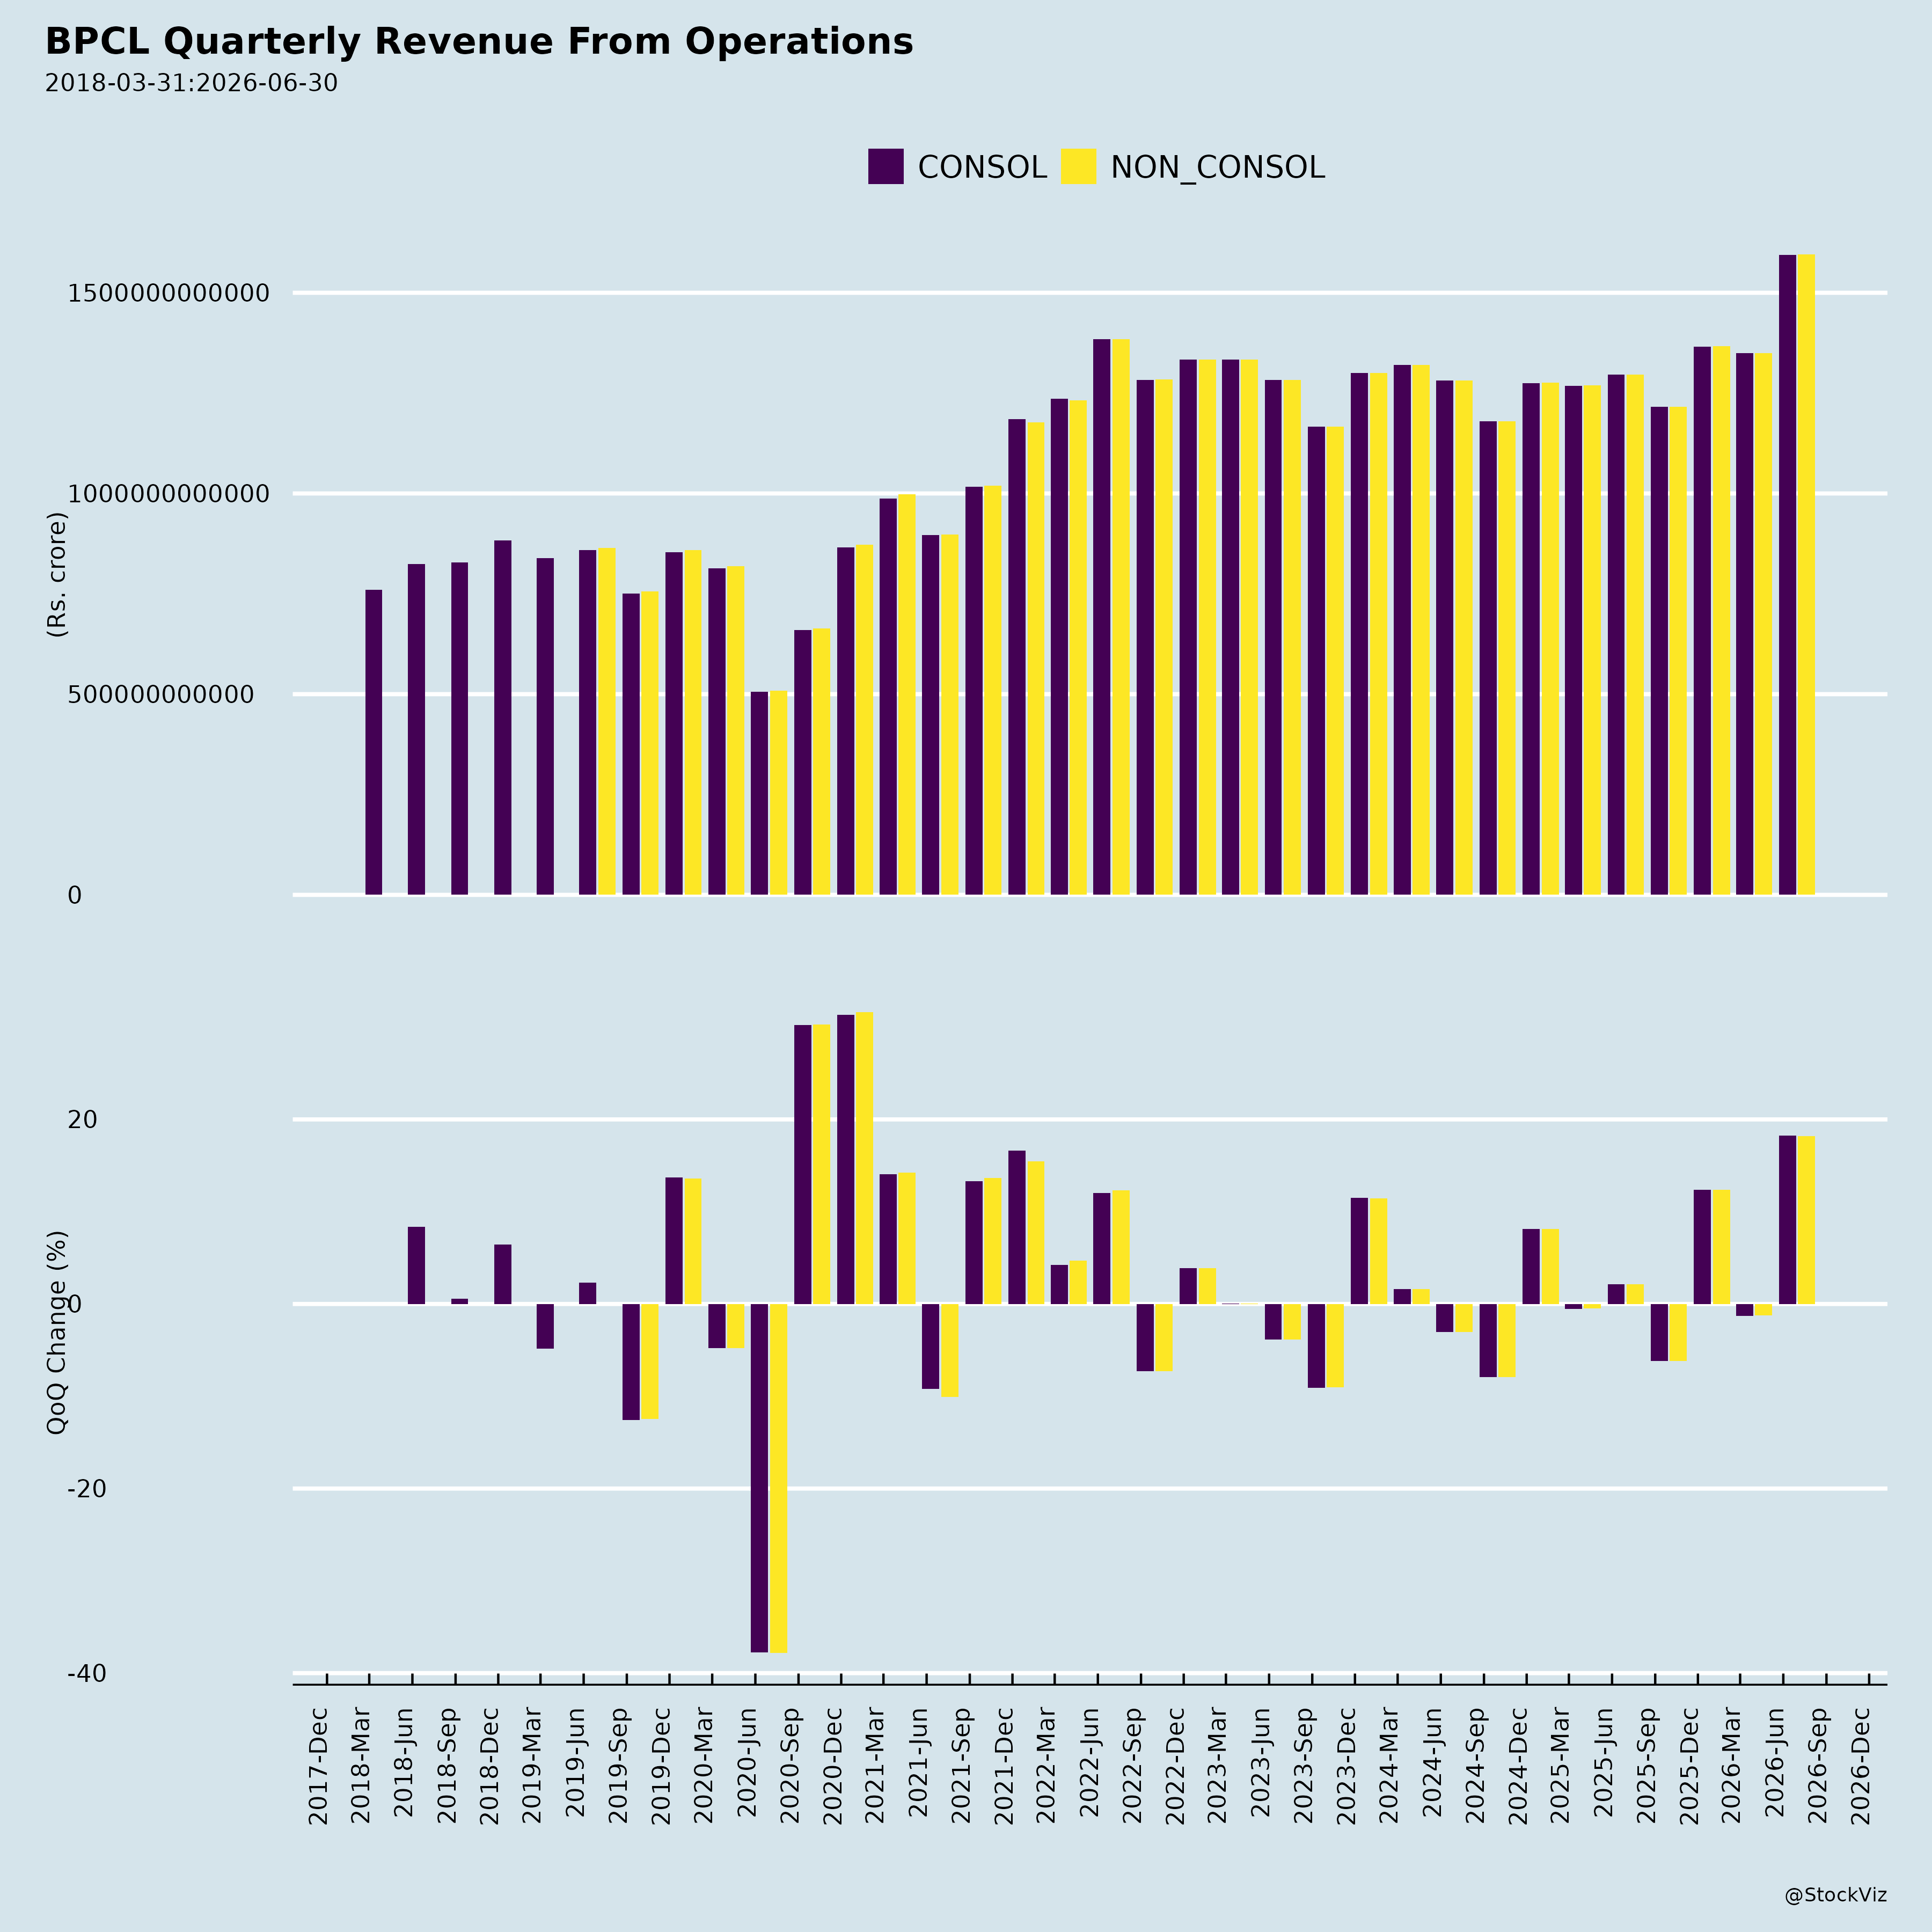
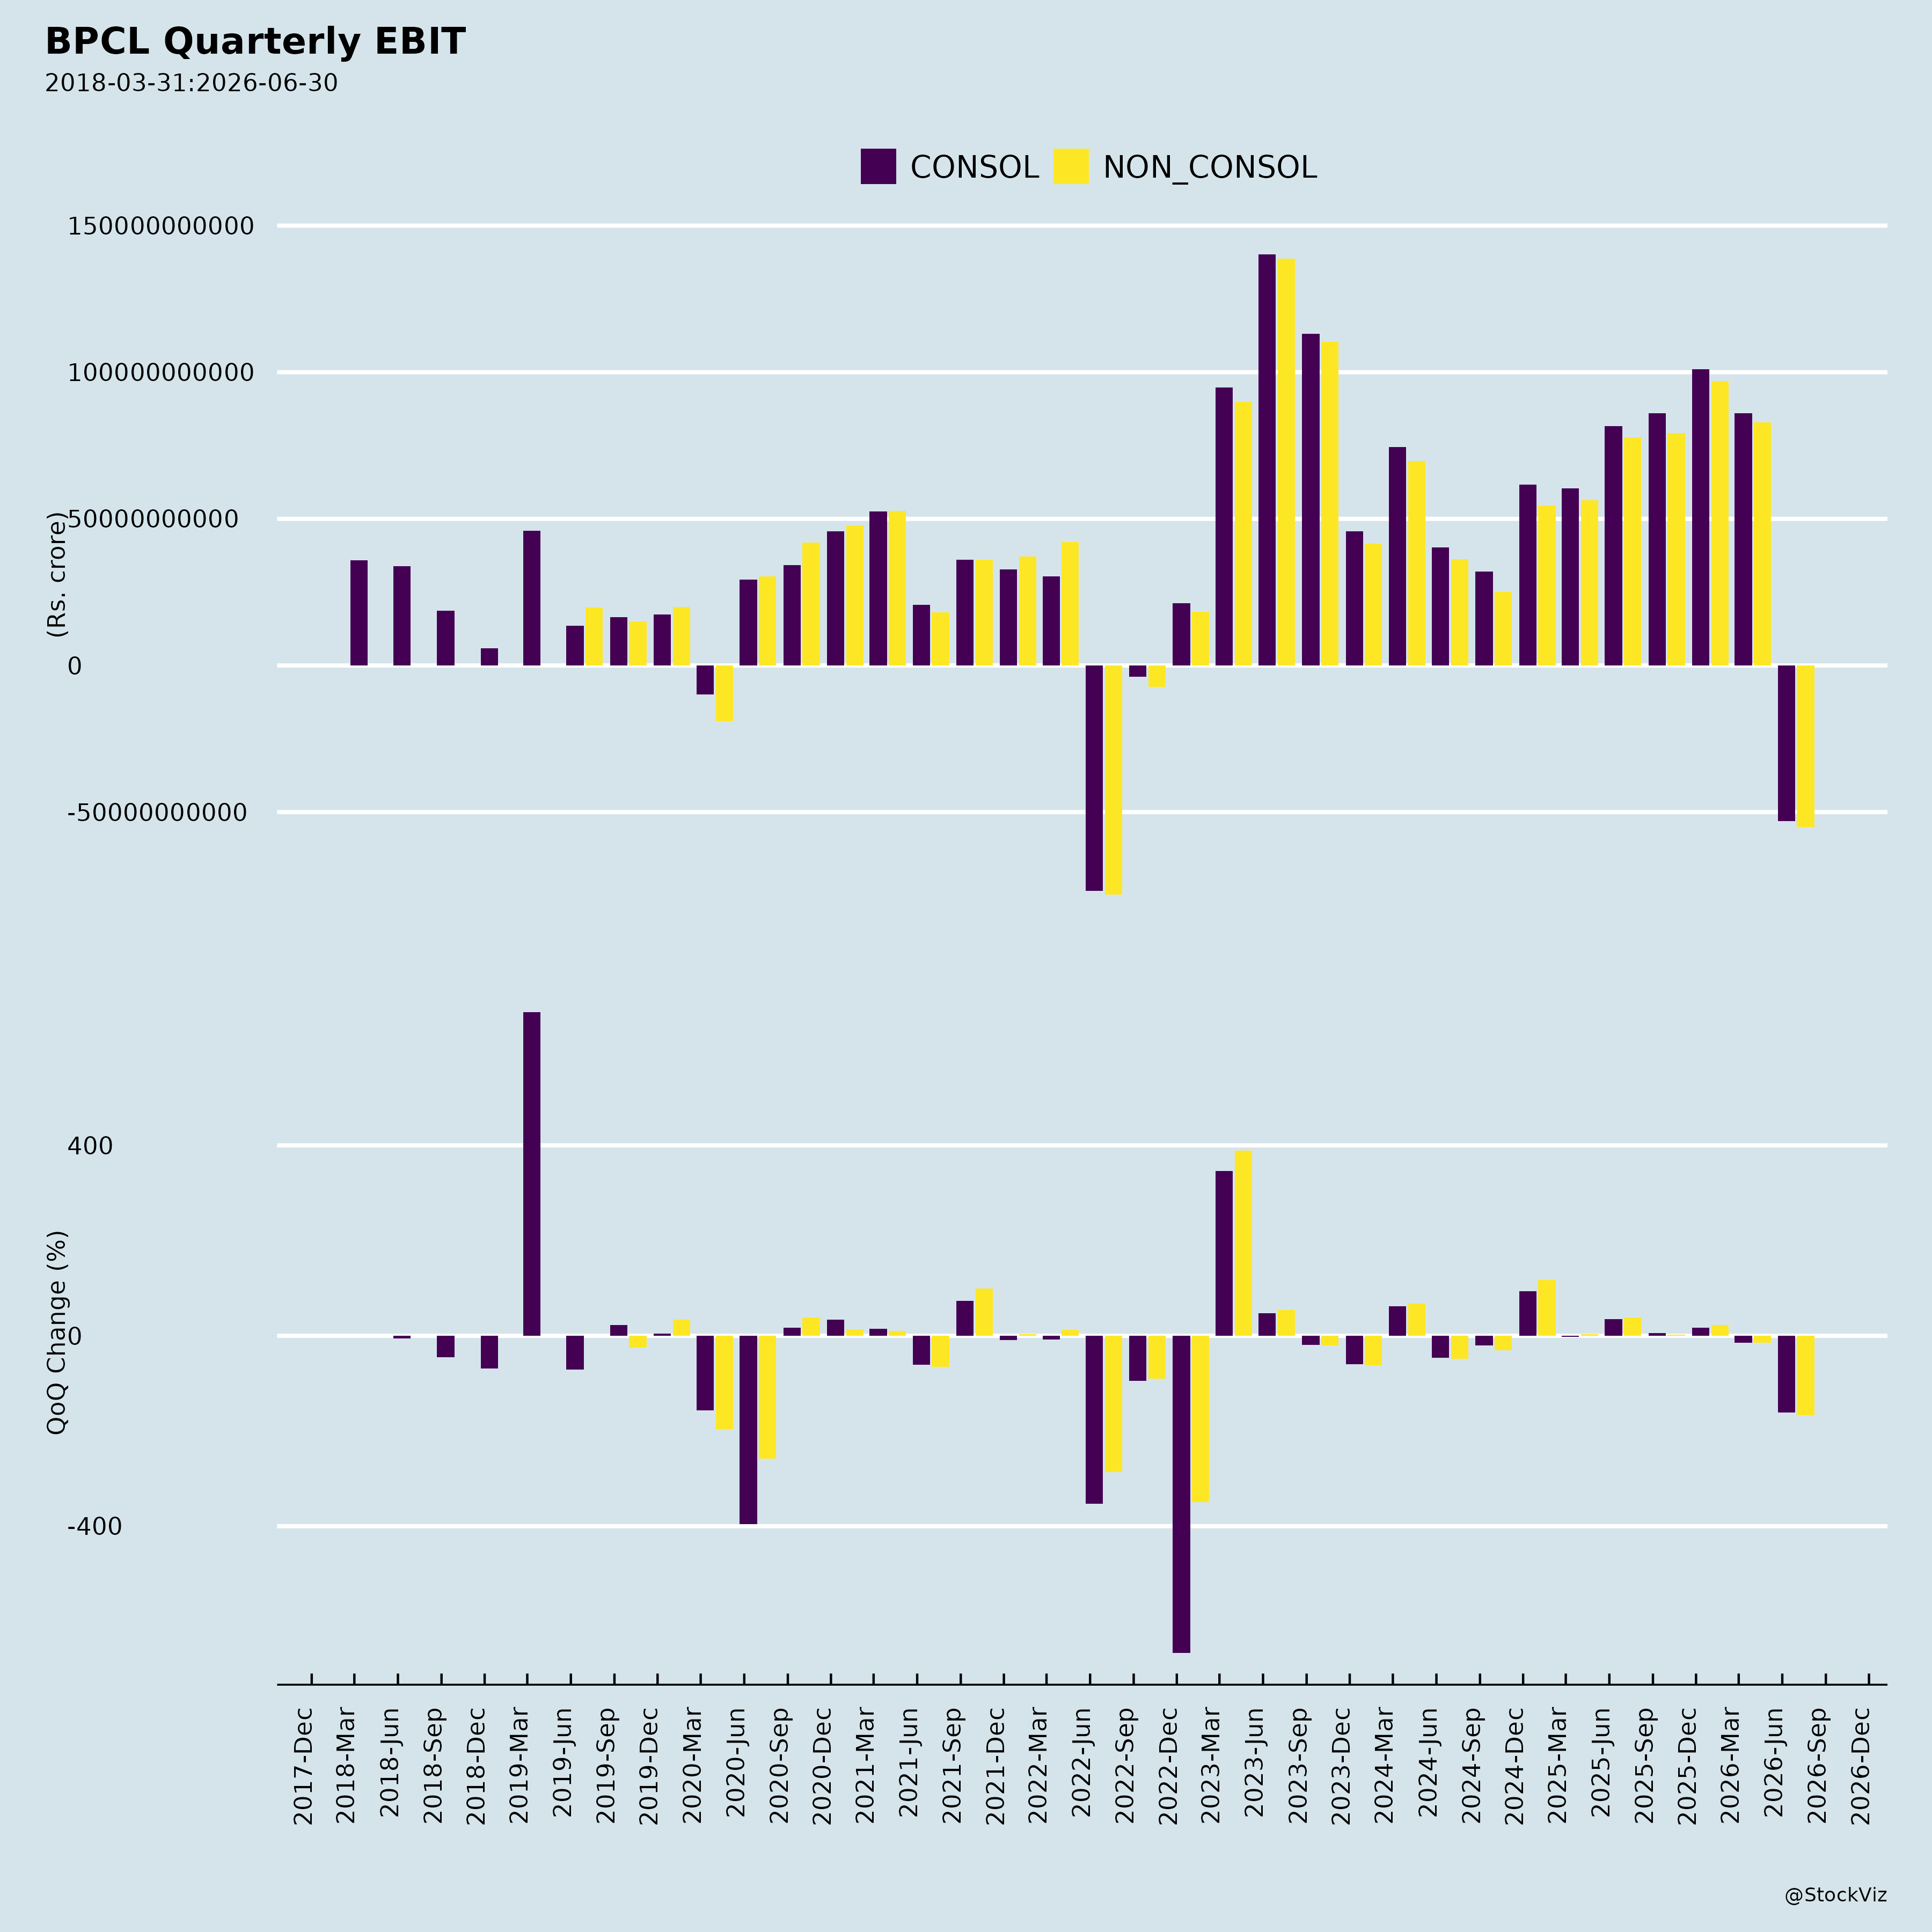
Sharp swing to losses in Q1 FY2026-27. For the quarter ended 30 June 2026, BPCL reported a loss before tax of ₹5,305 crore and a loss after tax of ₹3,962 crore, a steep reversal from the profit before tax of ₹8,157 crore and profit after tax of ₹6,124 crore in the same quarter of the prior year. Sequentially, the result also deteriorated against Q4 FY2025-26 (profit before tax ₹4,258 crore; profit after tax ₹3,191 crore).
Refining margins collapsed. Gross Refining Margin fell to US$41.41/bbl in Q1 FY2026-27 from US$4.88/bbl in Q1 FY2025-26 and US$17.53/bbl in Q4 FY2025-26. The reported GRMs are weighted averages of the three refineries and are stated before factoring the impact of Special Additional Excise Duty and Road & Infrastructure Cess levied with effect from 27 March 2026.
Weaker operational volumes. Refinery throughput declined across all three refineries year-on-year: MR 3.77 MMT (vs 3.94 MMT), KR 4.31 MMT (vs 4.51 MMT), and BR 2.07 MMT (vs 1.97 MMT), with total throughput of 10.15 MMT against 10.42 MMT. Distillate yield slipped to 84.07% from 84.96%, and high sulphur crude as a share of total crude fell to 74% from 76%. Total sales were 14.13 MMT versus 14.03 MMT, with domestic sales at 13.62 MMT against 13.58 MMT and exports at 0.51 MMT against 0.45 MMT.
Rising debt. Debt position (excluding IND AS 116 liabilities) rose to ₹17,396 crore as on 30 June 2026 from ₹10,709 crore a year earlier and ₹10,480 crore as on 31 March 2026. Interest expenditure increased to ₹415 crore from ₹374 crore, including ₹198 crore of interest on lease liability under IND AS 116 (Q1 FY2025-26: ₹189 crore). Lease liability stood at ₹10,799 crore as on 30 June 2026 versus ₹10,942 crore as on 31 March 2026.
Gujarat stamp duty orders. BPCL received two orders dated 08.09.2026 (received 10.09.2026) from the Collector & Additional Superintendent of Stamps, Gujarat, ordering payment of stamp duty of ₹18,56,181 and penalties of ₹18,93,305 and ₹7,37,681, along with rejection of the company’s objections regarding levy of stamp duty, penalty, and impounding of instruments for non-payment of stamp duty. The orders relate to the Scheme of Amalgamation of Bharat Oman Refineries Limited with BPCL, a land allotment order from 2010, and three land awards from 2001, 2003, and 2007.
Tailwinds and Growth Prospects
Inventory gains supported marketing performance. Marketing inventory gain was ₹3,134 crore in Q1 FY2026-27, compared with a loss of ₹835 crore in Q1 FY2025-26 and a gain of ₹1,275 crore in Q4 FY2025-26. Forex fluctuation gain was ₹346 crore, against ₹20 crore a year earlier and a loss of ₹936 crore in Q4 FY2025-26.
Fundraising capacity approved. On 18 August 2026, the Board approved raising funds through secured/unsecured redeemable Non-Convertible Debentures, in one or more series/tranches up to a maximum of 10 tranches, aggregating up to ₹5,000 crore, within one year. Allotment and other details will be decided and informed to the stock exchanges at the time of each issue.
International portfolio reorganization. IBV Brasil Petróleo Limitada, a Brazil-incorporated company in which BPCL holds 100% equity through wholly owned subsidiary Bharat PetroResources Ltd. and step-down subsidiaries, changed its corporate name to “BPRL Brasil Limitada” under applicable Brazilian law, with the certificate received on 19 August 2026.
Stable interest income and government securities holdings. Interest income was ₹367 crore (vs ₹390 crore a year earlier; ₹440 crore in Q4 FY2025-26). Government securities at face value stood at ₹2,827 crore, down from ₹3,590 crore a year earlier but up from ₹2,327 crore as on 31 March 2026.
Key Risks
- Margin and earnings volatility: The swing from profit to loss alongside the GRM decline illustrates exposure to refining margin cycles and inventory valuation movements.
- Regulatory and tax levies: The Special Additional Excise Duty and Road & Infrastructure Cess levied with effect from 27 March 2026 affect reported GRMs, and the Gujarat stamp duty orders show exposure to state-level duty and penalty demands.
- Leverage: The increase in debt to ₹17,396 crore and higher interest expenditure raise financing cost sensitivity.
- Legal/administrative proceedings: The stamp duty orders involve rejection of the company’s objections and impounding of instruments, requiring withdrawal requests or appeals.
Management Guidance Versus Observed Performance
Gujarat stamp duty orders. Management stated that the orders have no material impact on the Company and that it will approach the authorities for withdrawing the orders or file an appeal. The orders themselves direct payment of stamp duty of ₹18,56,181 plus penalties of ₹18,93,305 and ₹7,37,681, and record rejection of the company’s objections and impounding of instruments. No subsequent outcome of the withdrawal request or appeal is disclosed in the material.
Fundraising. The Board approved NCD issuance of up to ₹5,000 crore within one year, with tranche details to be decided and disclosed at the time of each issue. No tranches are reported as issued in the material.
Investor engagement. An institutional investors/analysts meeting (UBS India Summit 2026) was rescheduled to 10 September 2026 from 11 September 2026 due to business exigencies, with no Unpublished Price Sensitive Information intended to be discussed.
Governance. The 73rd Annual General Meeting was held on Thursday, 27 August 2026, where 8 resolutions were passed with the requisite majority through remote e-voting and e-voting during the AGM.
Broker Narrative
The narrative shifted from a 2023 cyclical recovery story—supernormal GRMs backed by Russian crude, LPG over-recoveries, and Bina-led growth offset by heavy capex, rising debt, and margin normalization—to a 2026 story where those tailwinds have reversed: Russian crude discounts have vanished, LPG has swung to under-recoveries with compensation ending, and GRMs have moderated, while the capex/return-ratio concerns persist into FY28/FY29. Broker outcomes corroborate this shift, moving from mostly SUCCESS calls in 2023–2024 to repeated DISAPPOINTMENT and negative actual returns from 2025 through October 2026.
Fears that came true
- Pressure on return ratios from heavy capital expenditure persisted, with the Rs 140bn FY24/Rs 490bn multi-year capex plan flagged in May 2023 still weighing on returns, as the last report cites FY28/FY29 capex as a monitorable amid negative actual returns and DISAPPOINTMENT calls.
- Marketing margins normalized away from supernormal levels, as Q1FY24TD auto fuel GMM of Rs 10.8/lt gave way to margin pressure—even a brief loss of INR-5.4/ltr—before recovering only modestly to INR 5.5/ltr, consistent with later negative-return DISAPPOINTMENT outcomes.
- The Russian crude cost advantage eroded, since the ~30% Russian mix that supported US$20.6/bbl GRMs disappeared, leaving GRMs to moderate on higher freight and absent discounts alongside weaker share-price performance in 2025–2026.
Optimism that failed
- High GRMs sustained by Russian crude failed to last, as the last report attributes GRM moderation to the absence of Russian crude discounts and higher crude freight, while subsequent calls delivered negative actual returns.
- Sustained LPG over-recoveries of roughly Rs 200 per cylinder did not continue, with LPG swinging to INR 328/cylinder under-recoveries by November 2026 and government compensation ceasing after October 2026.
- The Bina refinery expansion as a post-FY25 earnings driver faltered, with planned Bina maintenance shutdowns and FY28/FY29 capex pressures undermining returns even as broker calls turned to DISAPPOINTMENT with negative actual returns.
Broker Timeline
56 broker calls · 2023-05-22 to 2026-10-26
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.