BLUESTARCO
Equity Metrics
September 24, 2026
Blue Star Limited
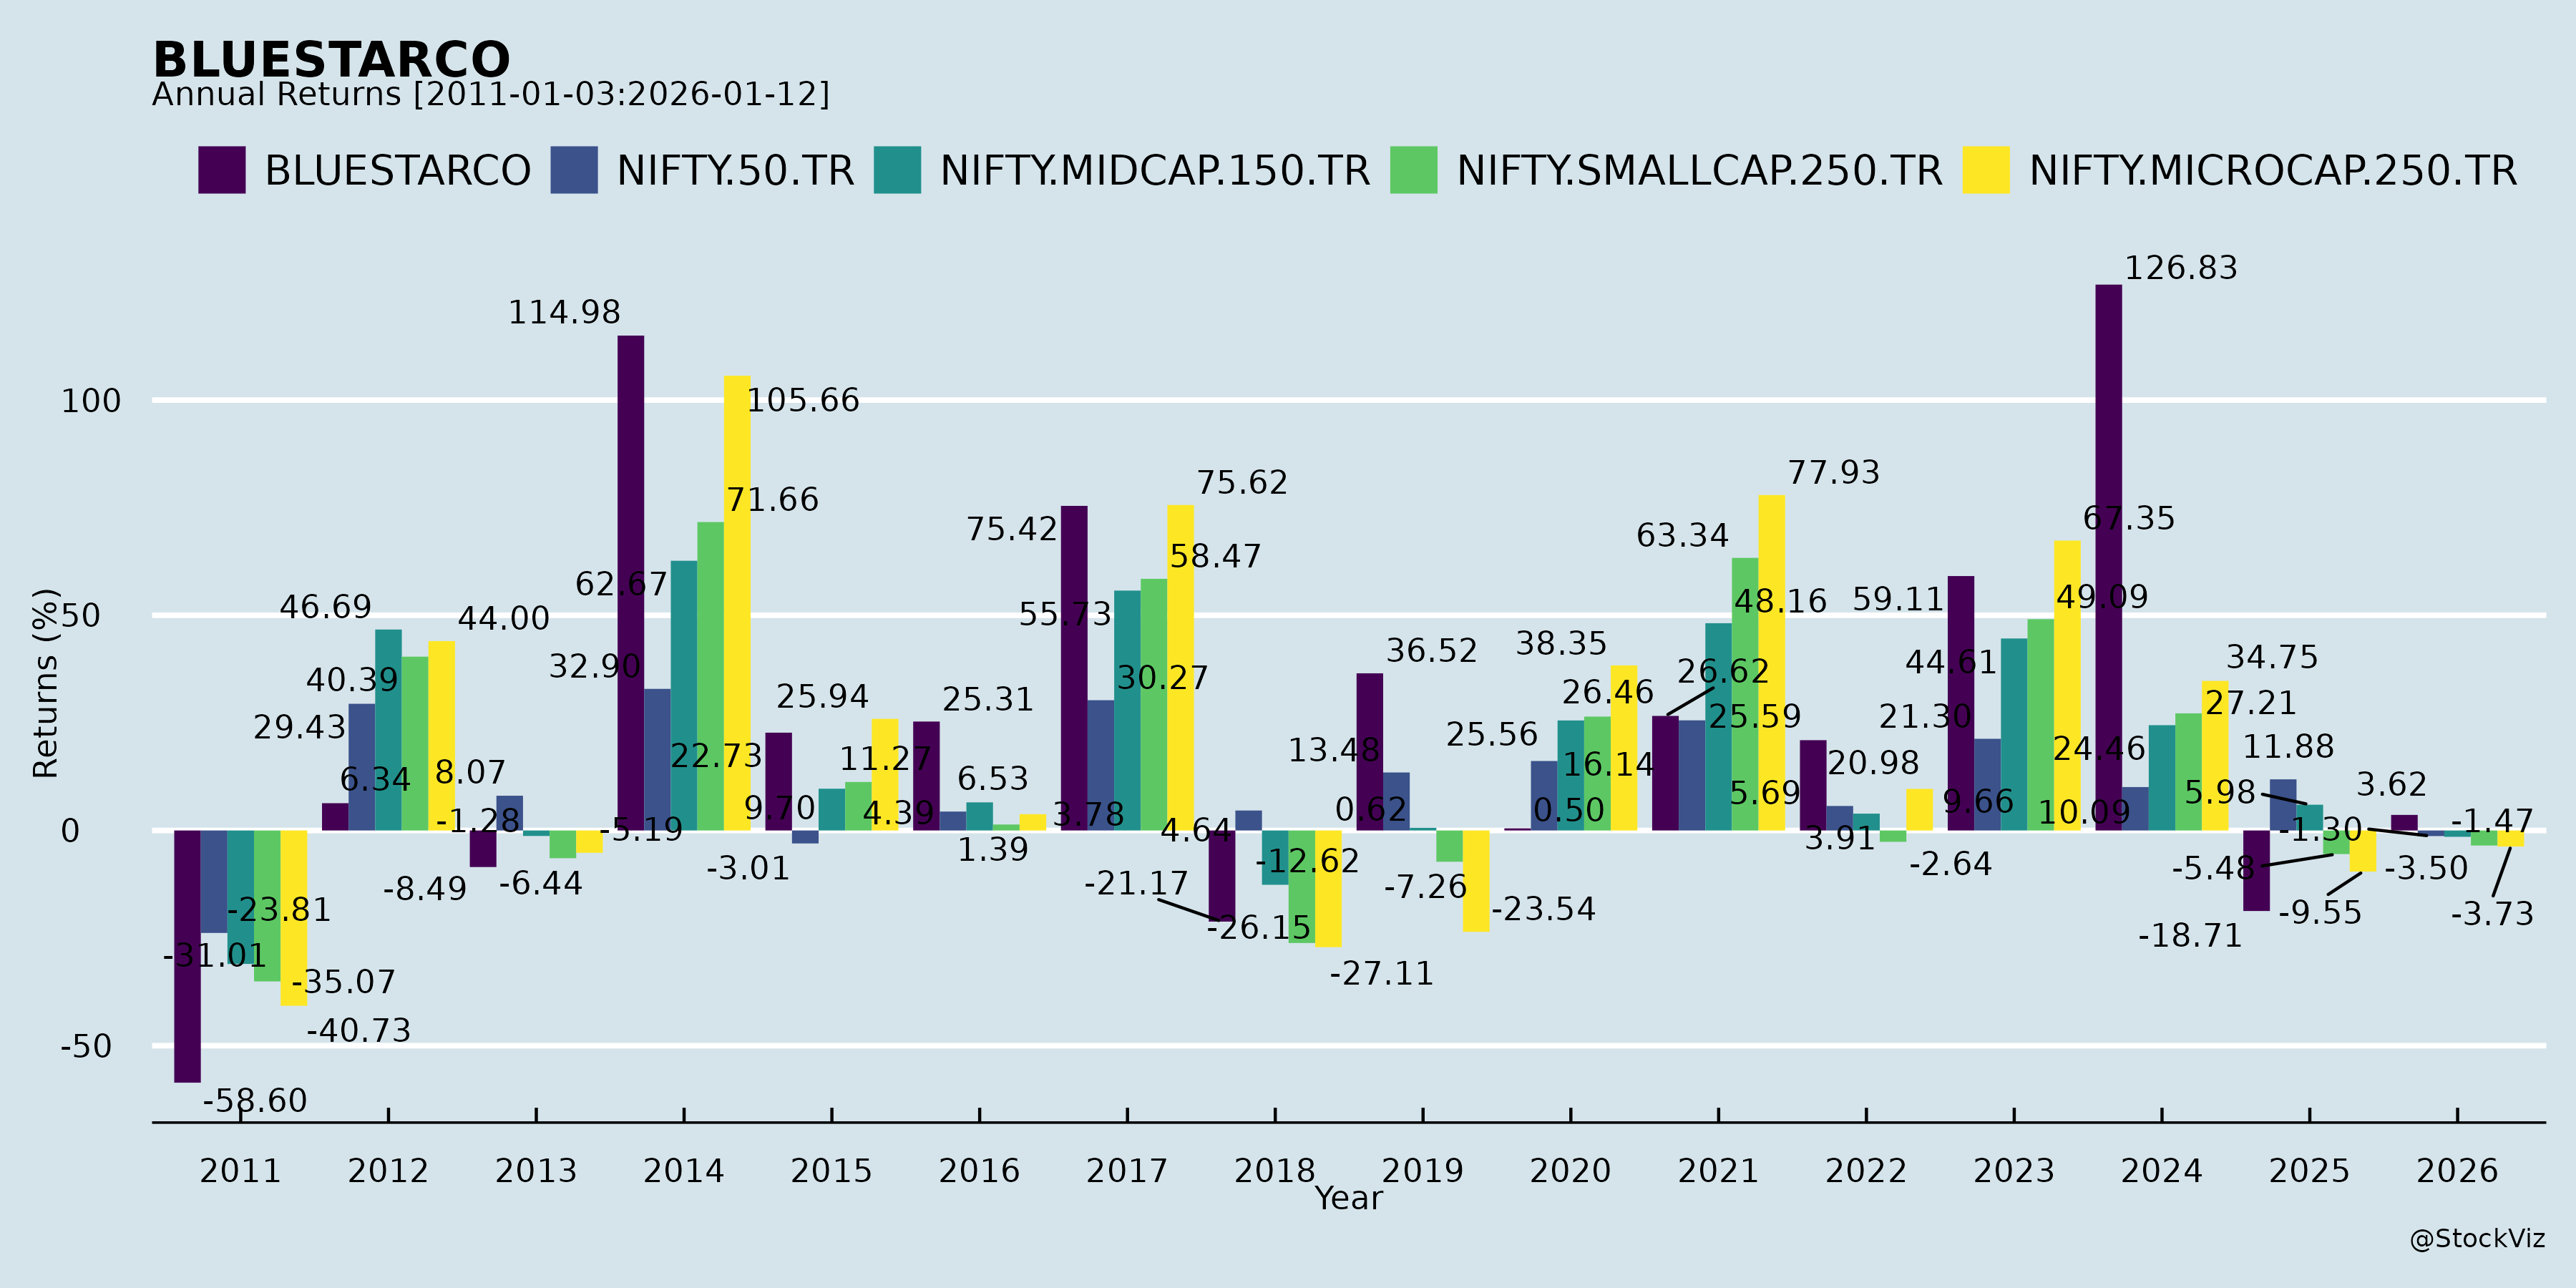
Annual Returns
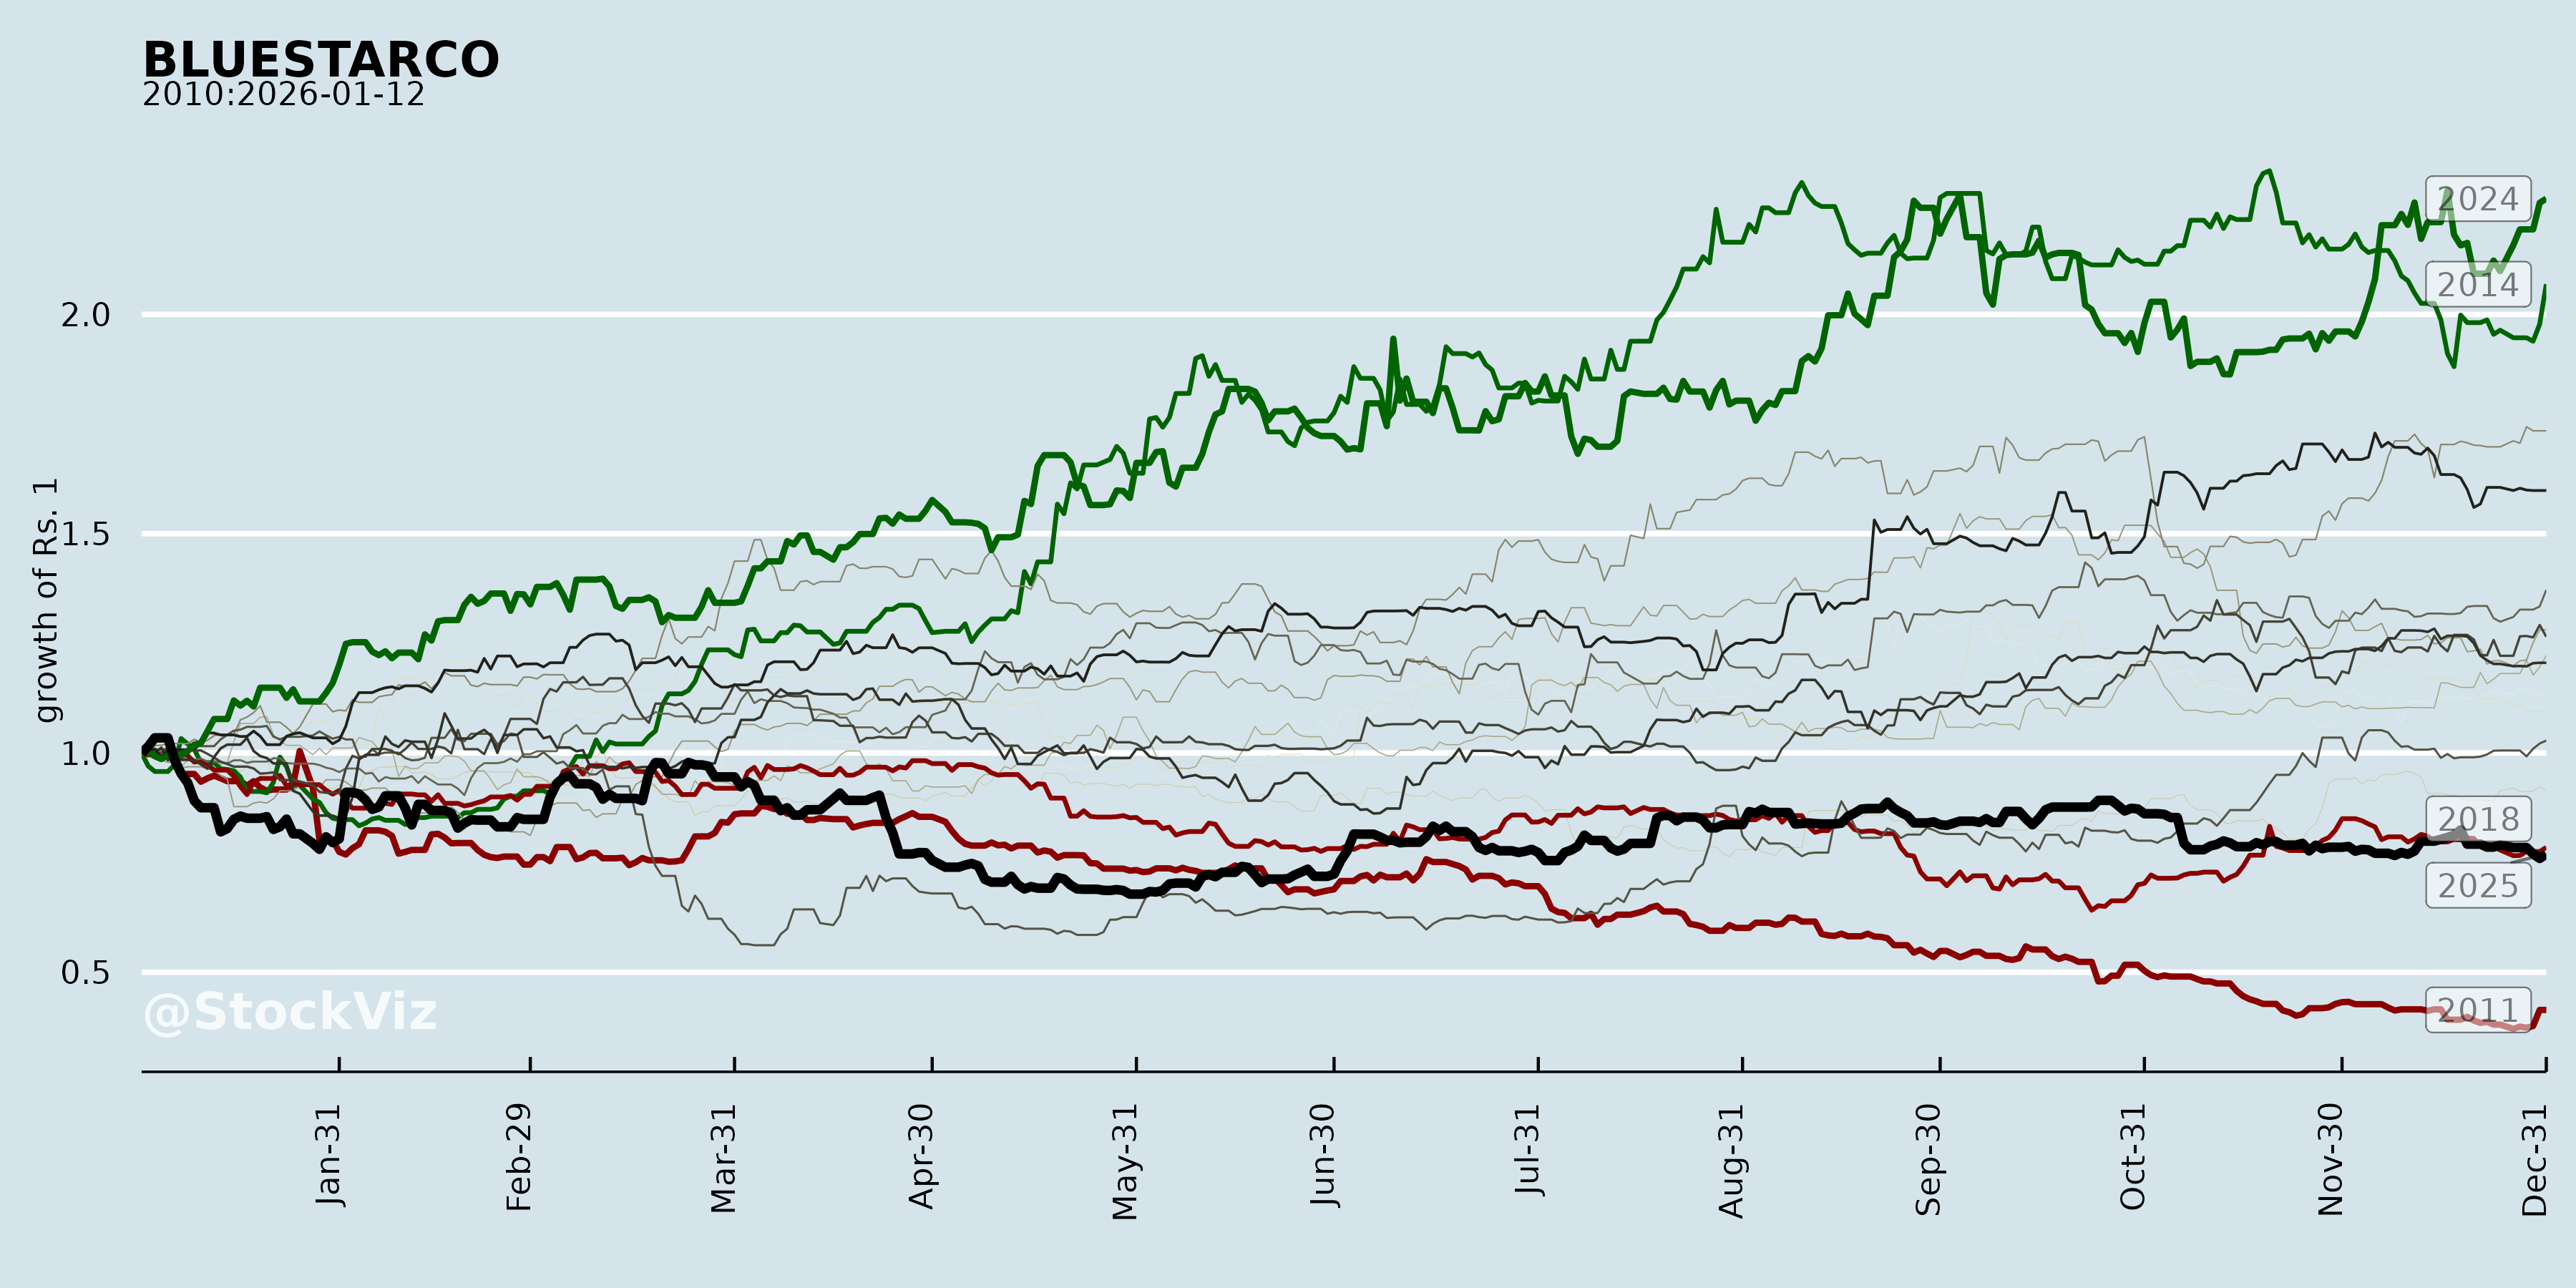
Cumulative Returns and Drawdowns


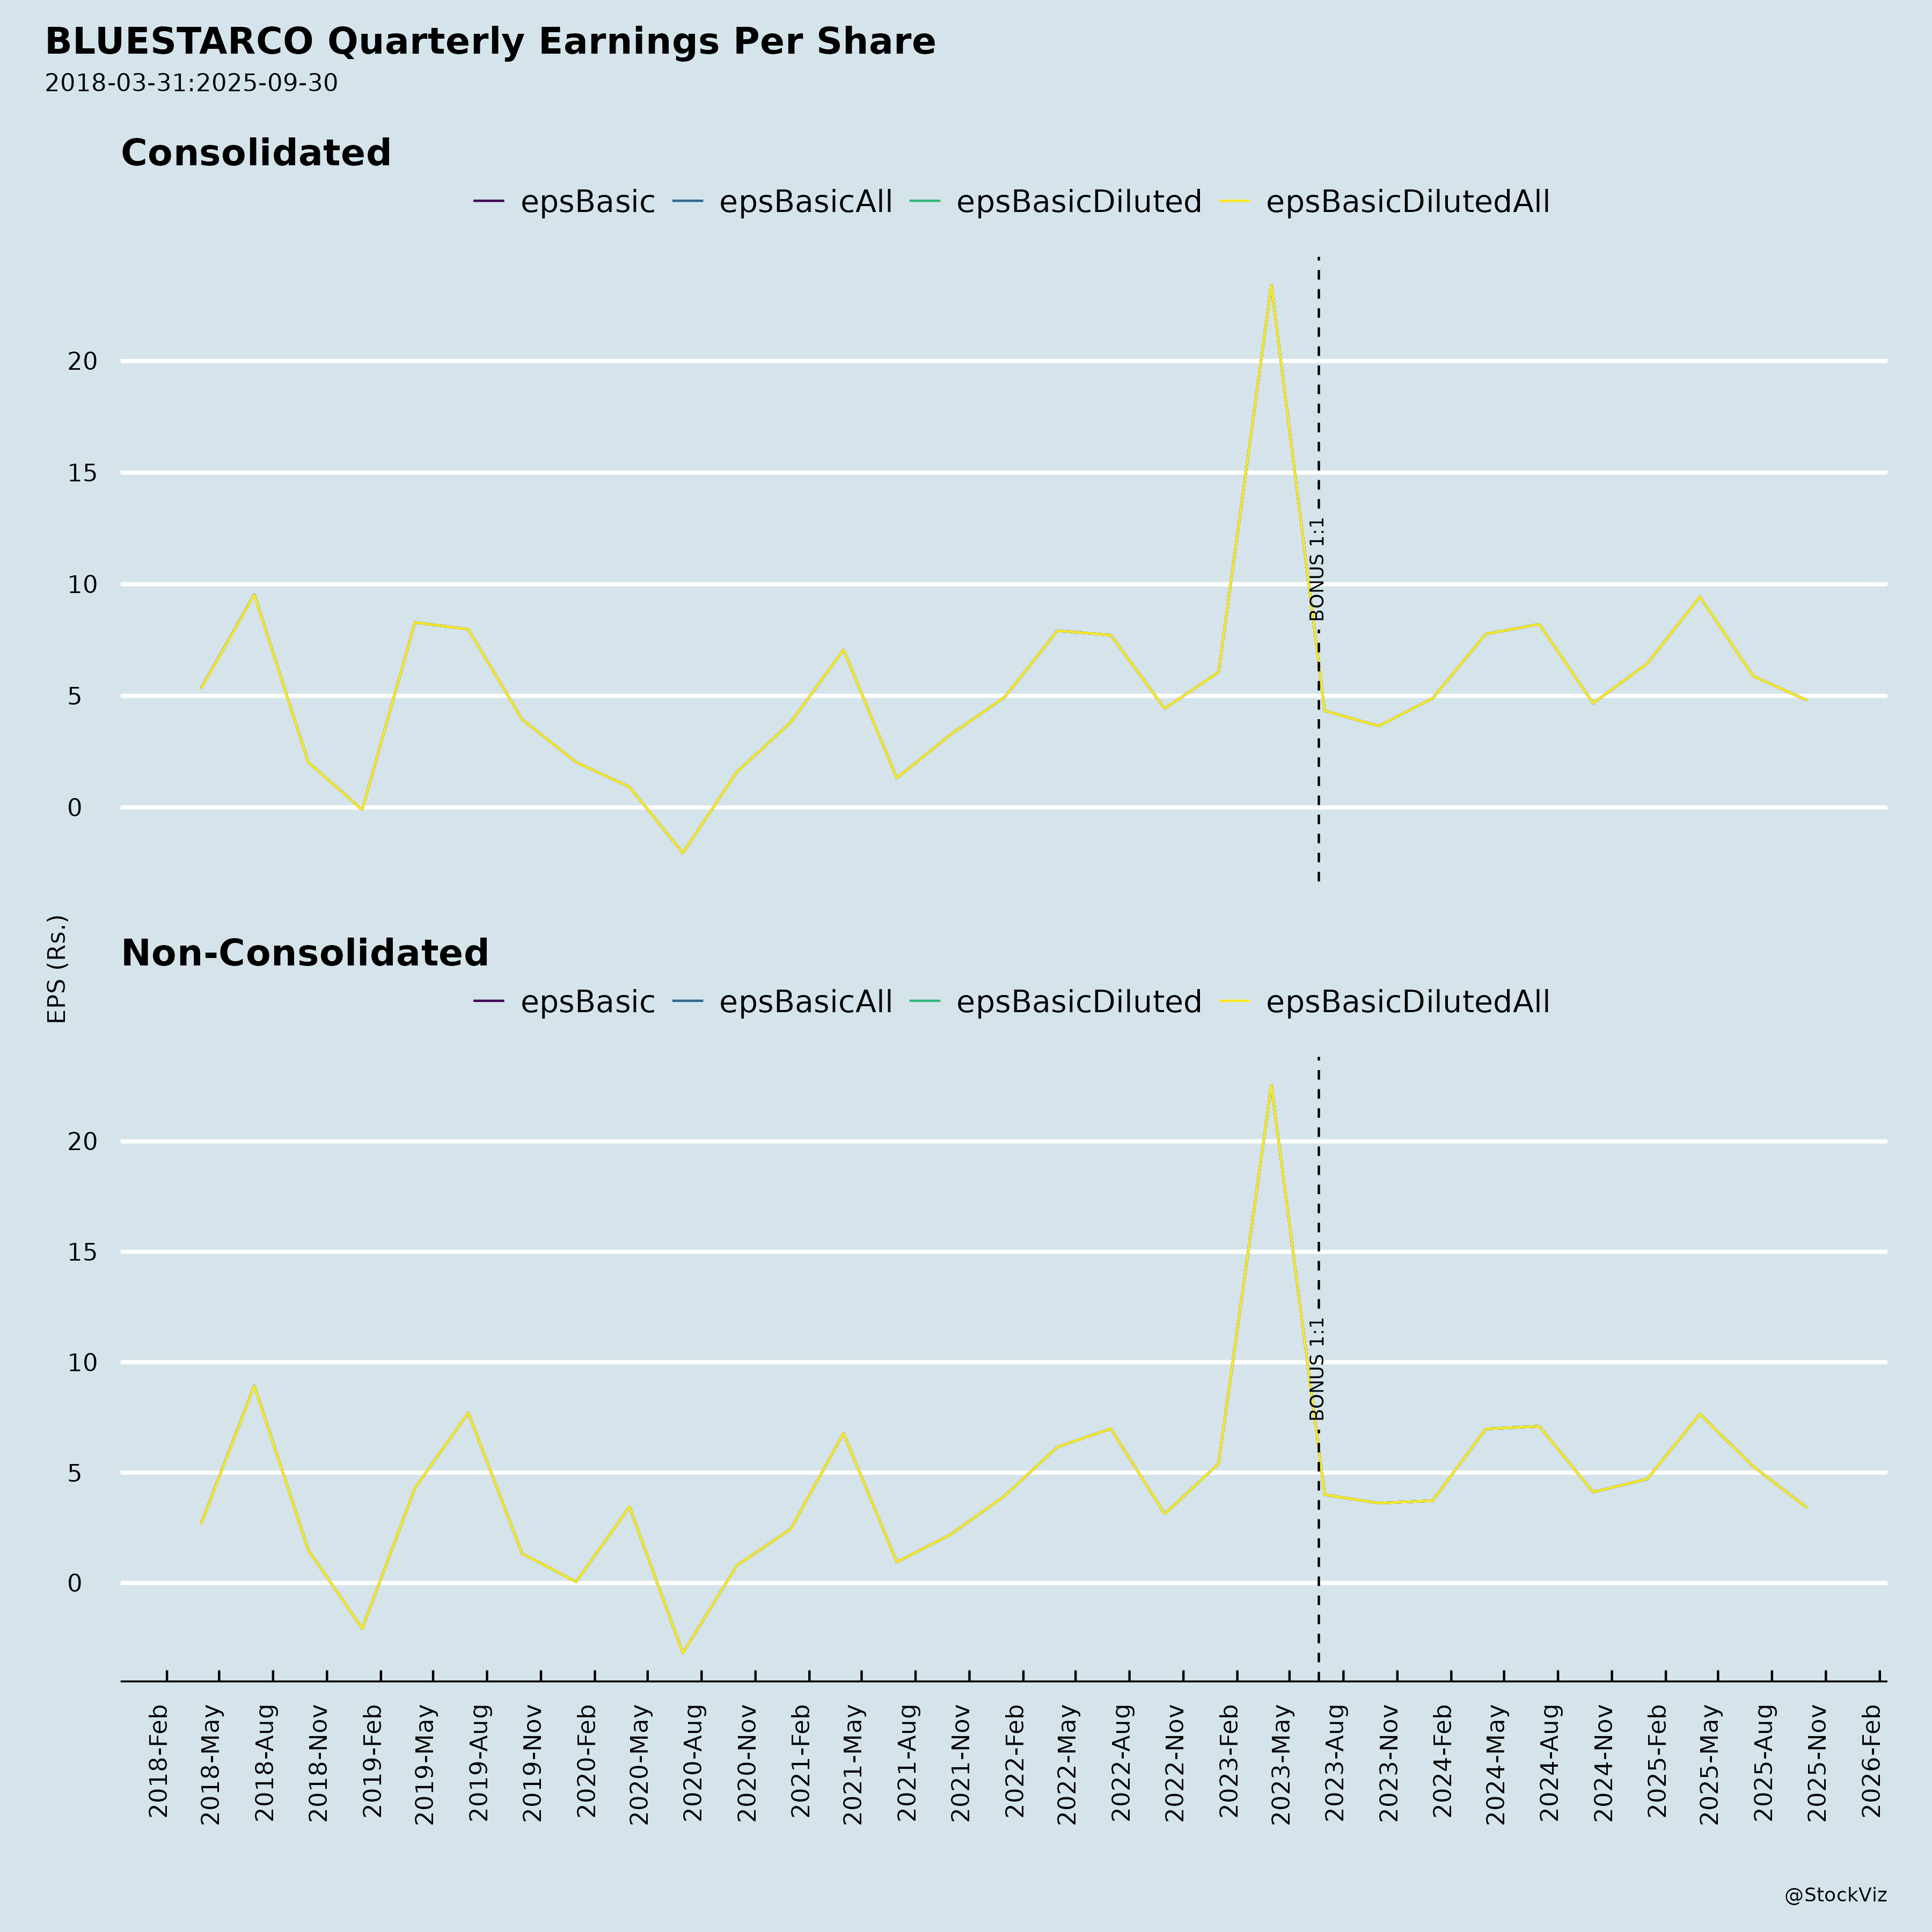
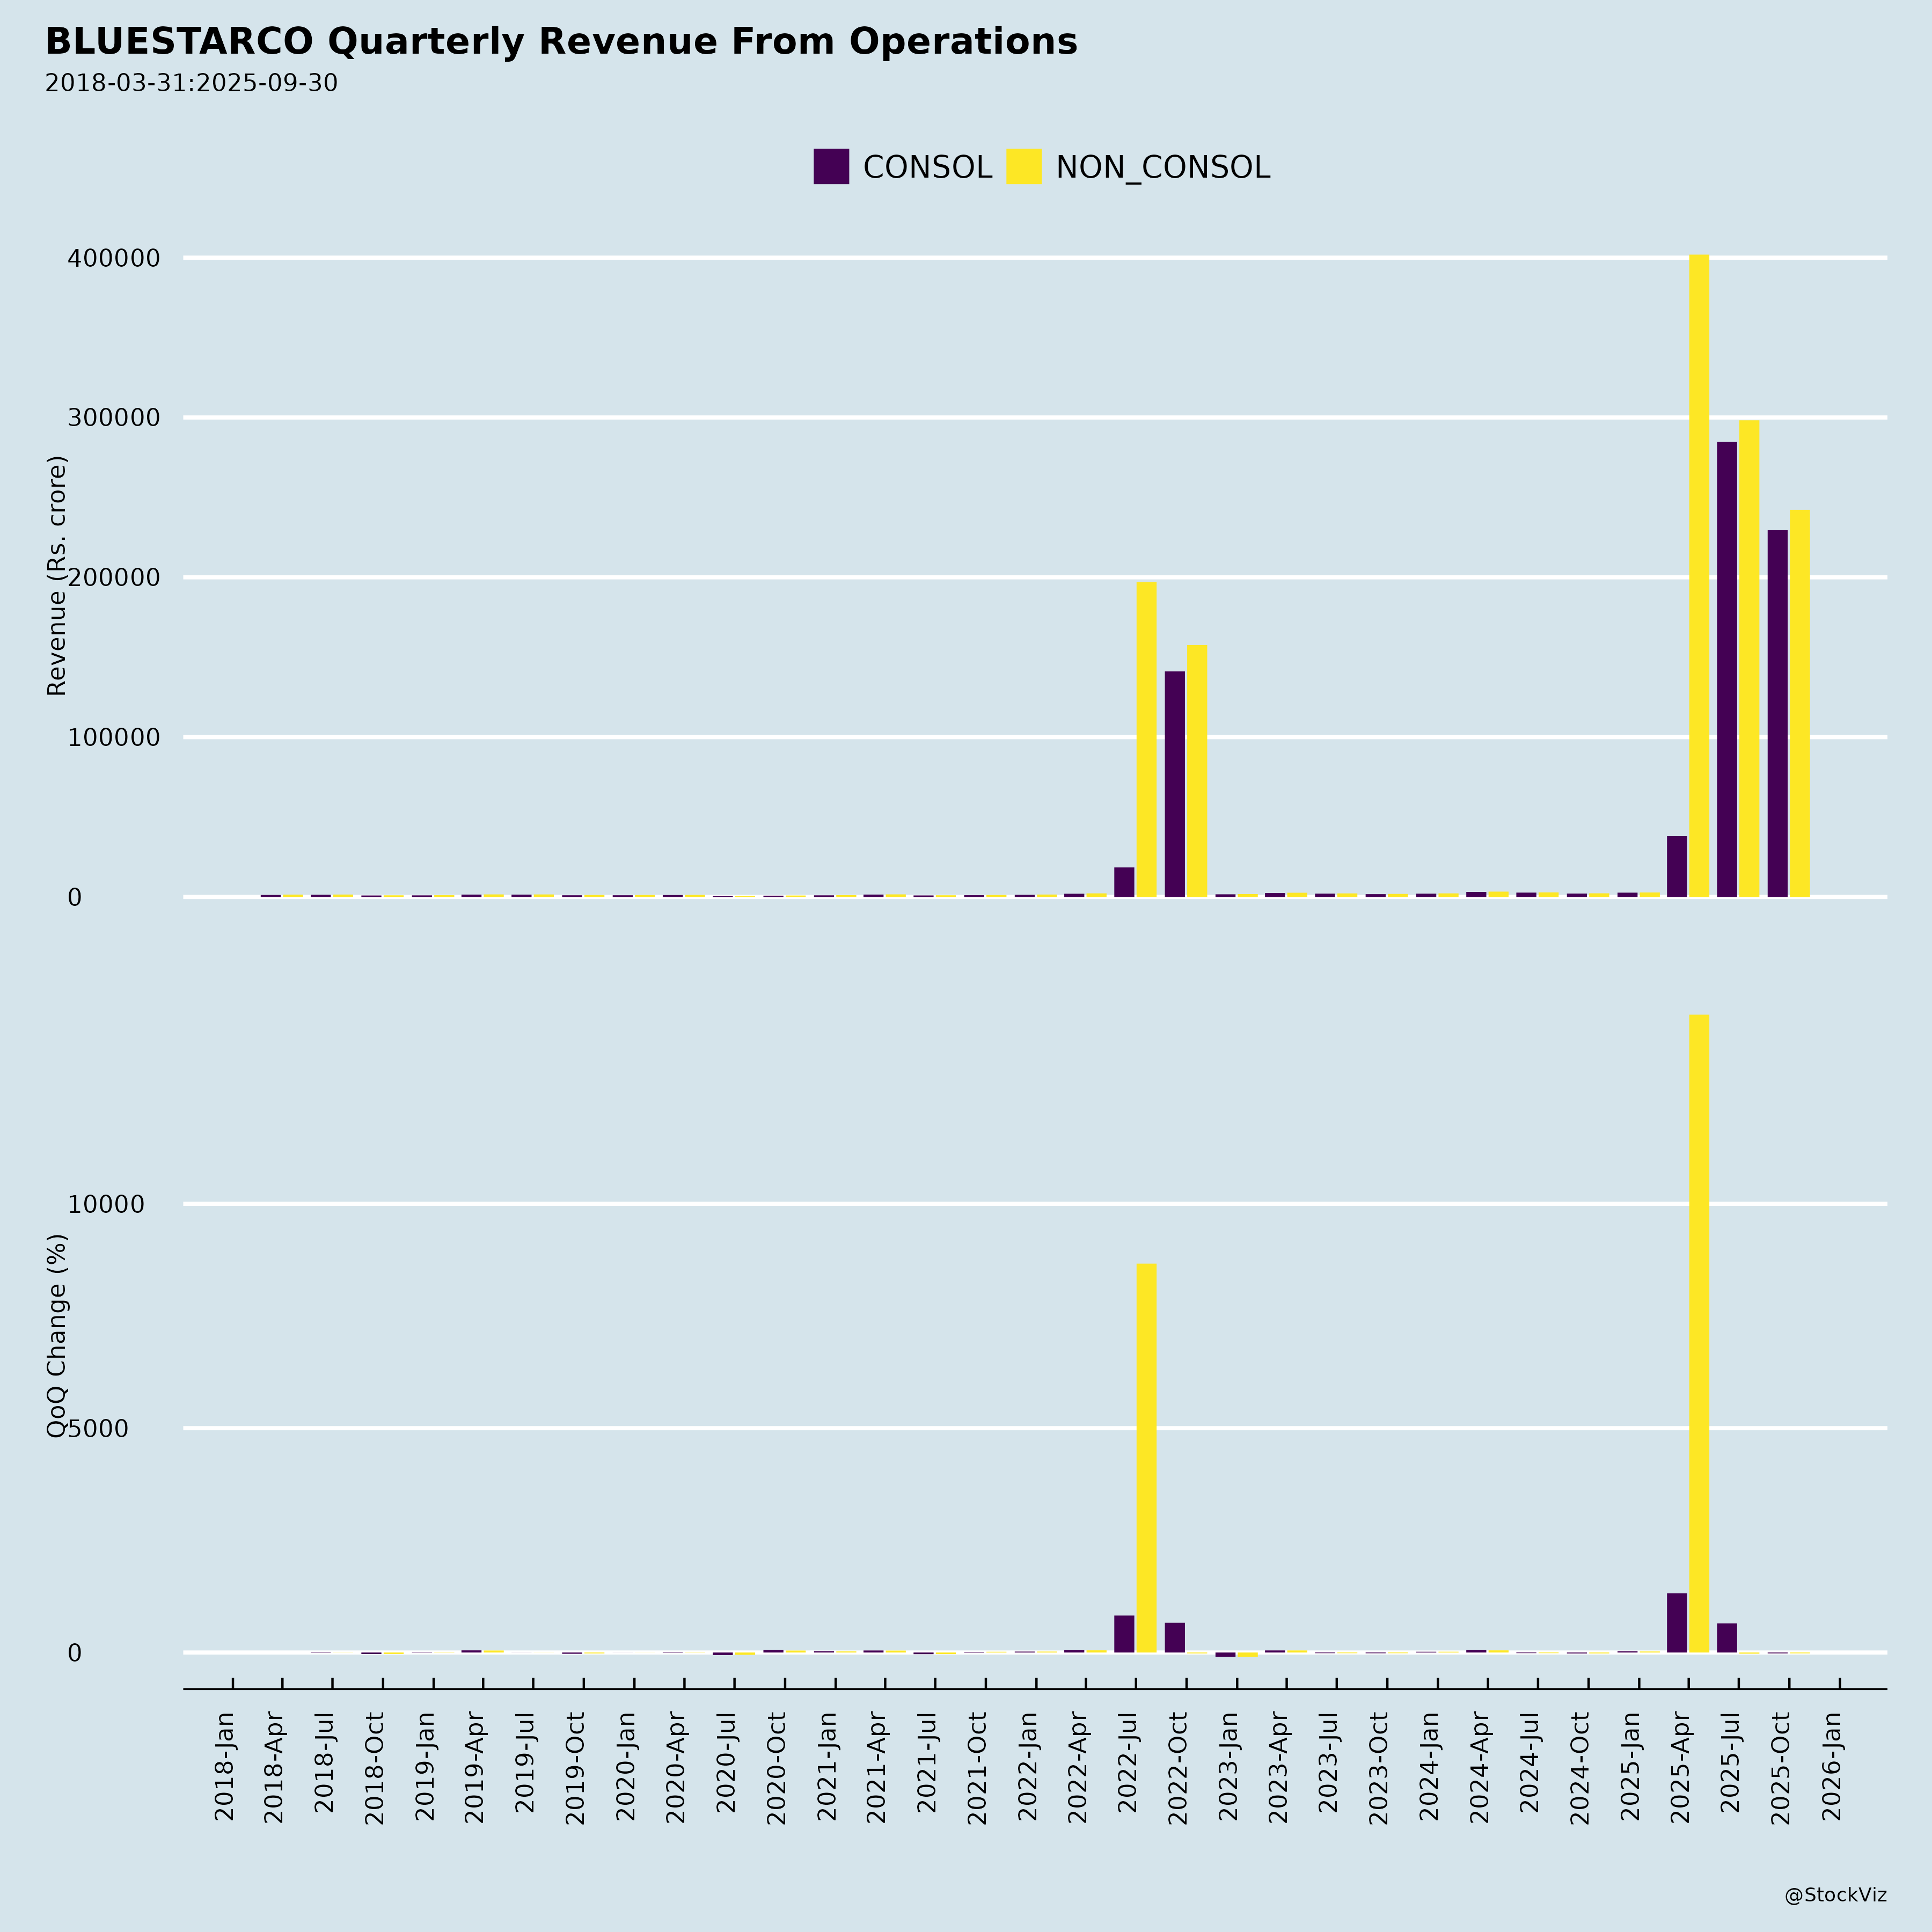
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
Blue Star Limited — Q1FY27 Announcements Review
1. Headwinds and Challenges
- Commodity cost escalation: The quarter saw an unprecedented escalation in commodity prices, which required increases in selling prices. The company also flagged that commodity prices and exchange rates remain highly volatile.
- Summer season disruption: The delayed onset and abrupt end of the summer season compressed the selling window.
- Room AC inventory pile-up: A significant inventory pile-up of old Room ACs in the trade created pressure to liquidate stock during the quarter. While the company attempted to pass on part of the cost escalation through primary sales, market operating prices remained subdued, and the company could not achieve the desired primary sales volume growth, which impacted margins.
- Sluggish non-data-centre project demand: Order inflow from commercial offices, factories and infrastructure remained sluggish, as cost escalations arising from the West Asia crisis led to deferment of order finalisations.
- Commercial Refrigeration weakness: Demand for deep freezers from ice cream manufacturers remained muted, causing a decline in that business.
- MedTech challenges: The Professional Electronics and Industrial Systems segment revenue decline was mainly attributable to continued challenges in the MedTech Solutions business. A separate extract also cites an unclear regulatory policy framework for Med-Tech Solutions.
- Currency and geopolitical uncertainty: Depreciation of the Indian Rupee and the ongoing conflict in West Asia, with resulting market uncertainties, warrant a cautious outlook for the remainder of the financial year.
2. Tailwinds and Growth Prospects
- Data centre MEP orders: A key positive was the strong inflow of Data Centre MEP project orders, reflecting sustained momentum in this high-growth segment. Strong enquiry momentum from the data centre sector provides confidence in the medium-term prospects of the Electro-Mechanical Projects business.
- Commercial Air Conditioning: Robust order bookings during the quarter, driven by demand from industrial, retail and healthcare sectors. Based on the healthy enquiry pipeline and order inflow, growth prospects for the remainder of the year appear positive.
- Order book visibility: Carried-forward order book as of June 30, 2026 grew 13.5% to Rs 7,764.38 crores, compared to Rs 6,843.04 crores as of June 30, 2025.
- Room AC tertiary sales: Despite the short summer window, investments in advertising, trade schemes and consumer finance offers supported healthy tertiary sales.
- Commercial Refrigeration recovery expected: Demand is expected to pick up during the forthcoming festival season.
- Industrial Solutions: Continued steady growth, supported by demand from manufacturing and testing sectors. Expansion in the US and Europe is also cited as an opportunity.
- Balance sheet strength: Net cash position of Rs 900.25 crores as on June 30, 2026, versus Rs 370.92 crores a year earlier, driven by improved working capital levels. Higher surplus funds also yielded higher treasury income.
- Industry fundamentals: Management states the medium-term fundamentals of the HVAC&R industry remain strong.
3. Key Risks
- Volatility in commodity prices and exchange rates, with the endeavour being to prudently balance volume growth and margins across product businesses.
- Geopolitical risk from the ongoing conflict in West Asia and resulting market uncertainties, which management says warrant a cautious outlook for the remainder of the financial year.
- Deferment of order finalisations in commercial offices, factories and infrastructure due to cost escalations.
- Margin pressure in the Unitary Products segment from subdued market operating prices and inability to achieve desired primary sales volume growth.
- Continued challenges and an unclear regulatory policy framework in the MedTech Solutions business.
- Forward-looking statements are based on reasonable assumptions and current expectations, and actual results could differ materially due to various events, risks and uncertainties; the company assumes no obligation to update or revise them.
- The schedule of analyst and institutional investor meetings is subject to changes.
4. Management Guidance Versus Observed Performance
- Revenue growth delivered despite headwinds: Consolidated revenue from operations grew 13.3% to Rs 3,377.92 crores in Q1FY27 from Rs 2,982.25 crores in Q1FY26. Management characterised this as modest growth achieved despite multiple headwinds.
- Margins under pressure: EBITDA (excluding other income) was Rs 174.95 crores (5.2% of revenue) versus Rs 199.99 crores (6.7% of revenue) in Q1FY26. Profit before tax (before exceptional items) declined 23.7% to Rs 125.62 crores from Rs 164.64 crores. Net profit declined to Rs 102.51 crores from Rs 120.82 crores. EPS (not annualised) was Rs 4.99 versus Rs 5.88.
- Segment performance versus commentary:
- Electro-Mechanical Projects and Commercial Air Conditioning Systems revenue grew 15.1% to Rs 1,625.05 crores; segment result was Rs 110.22 crores (6.8% of revenue) versus Rs 111.62 crores (7.9% of revenue). Management continues to exercise caution in project selection given input material cost escalation, while accelerating closure of large infrastructure projects.
- Unitary Products revenue grew 12.7% to Rs 1,689.31 crores; segment result fell to Rs 49.69 crores (2.9% of revenue) from Rs 87.47 crores (5.8% of revenue), reflecting the inventory liquidation pressure and subdued market operating prices.
- Professional Electronics and Industrial Systems revenue declined 9.7% to Rs 63.56 crores; segment result rose to Rs 9.57 crores (15.1% of revenue) from Rs 7.62 crores (10.8% of revenue), with Industrial Solutions growing steadily even as MedTech faced continued challenges.
- Forward-looking stance: Management expects the strong data centre MEP order inflow to support growth in the coming quarters, sees positive growth prospects for Commercial Air Conditioning for the remainder of the year, and expects Commercial Refrigeration demand to pick up in the festival season. At the same time, it flags a cautious outlook for the remainder of the financial year due to West Asia conflict-related uncertainties, and commits to controlling operating costs, investing in R&D with focus on value analysis, value engineering and product optimisation, and maintaining a strong balance sheet.
Other Developments
- The Board approved the standalone and consolidated financial results for the quarter ended June 30, 2026 at its meeting on August 6, 2026.
- The Board approved the appointment of Mr Nikhilesh Panchal (DIN: 00041080) as an Additional Director designated as an Independent Director for a term of five consecutive years commencing from August 14, 2026, subject to shareholder approval via Postal Ballot. Mr Panchal is a practicing lawyer with more than 35 years of experience, a partner at M/s Khaitan & Co since 2005, and is not related to any other Director nor debarred from holding the office of Director.
- All five resolutions set out in the Notice of the 78th Annual General Meeting held on August 6, 2026 were duly transacted and approved by shareholders with the requisite majority.
- The company is scheduled to participate in two investor meetings: an in-person group meeting at Axis Capital’s Consumer & Tech conference in Mumbai on September 10, 2026, and an in-person group meeting at the Jefferies India Forum 2026 in Gurugram on September 16, 2026.
Broker Narrative
The narrative shifted from 2023 cautious optimism—record order books, double-digit growth, and distribution expansion—toward 2025-2026 concerns over execution, margins, and UltraTech’s competitive entry. Early tailwinds proved fleeting, while the latest report still cites W&C sector growth and UltraTech’s UBS network as ramp-up catalysts despite persistent negative returns.
Fears that came true
- Execution pressure on the order book/backlog materialized as the company failed to convert orders, leading to DISAPPOINTMENT outcomes and negative actual returns from 2024 onward.
- Higher other expenses (up 49.6% YoY) capped EBITDA margin expansion persisted, squeezing profitability and correlating with negative actual returns and DISAPPOINTMENT calls.
- EMP and packaged air-conditioner revenue below estimates signaled segment weakness that continued to drag results, contributing to negative actual returns and DISAPPOINTMENT outcomes.
Optimism that failed
- The exceptional gain from Thane land sale and lower depreciation was a one-time tailwind that masked underlying weakness; when it did not repeat, the stock delivered DISAPPOINTMENT and negative returns.
- The expectation that all segments would sustain double-digit revenue growth and the order book would drive outperformance failed, as the stock posted large negative returns from 2025.
- The anticipation that the company would grow faster than the RAC industry’s 20% with 13.5% market share did not materialize, evidenced by negative actual returns and DISAPPOINTMENT outcomes in 2025-2026.
- The latest report’s optimism that UltraTech’s relationships and UBS network would enable a faster ramp-up failed to produce positive returns, as the stock returned -0.5% flat on the Overweight call.
Broker Timeline
27 broker calls · 2023-05-05 to 2026-09-01
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.