BIOCON
Equity Metrics
November 18, 2026
Biocon Limited
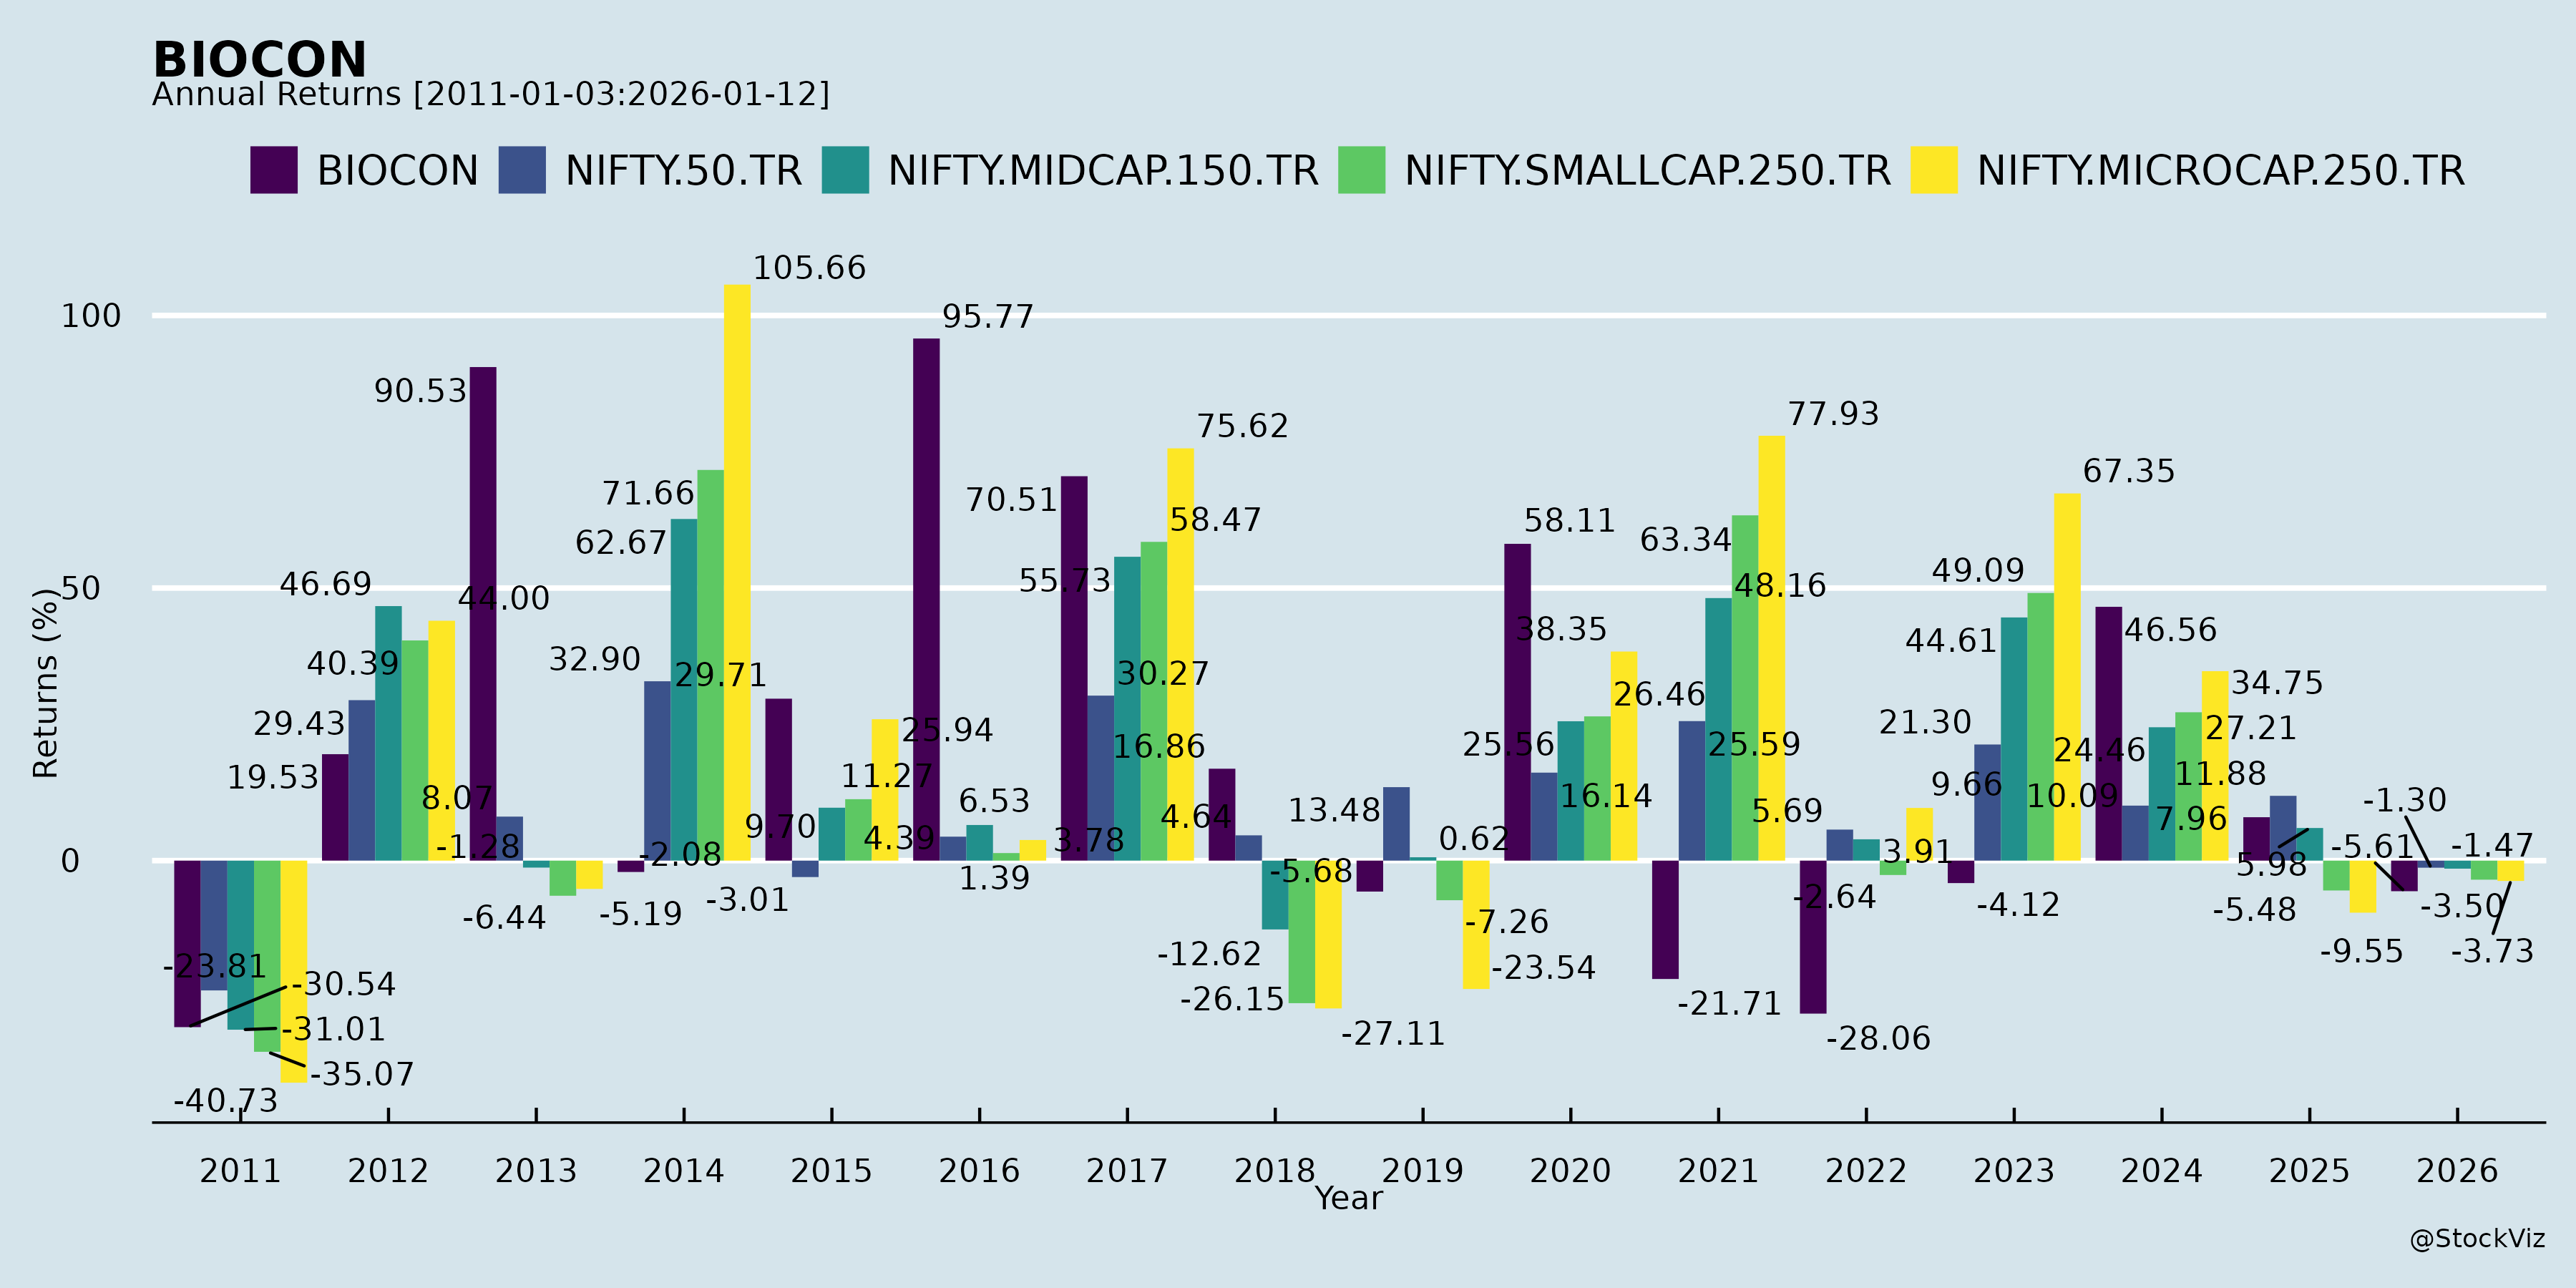
Annual Returns

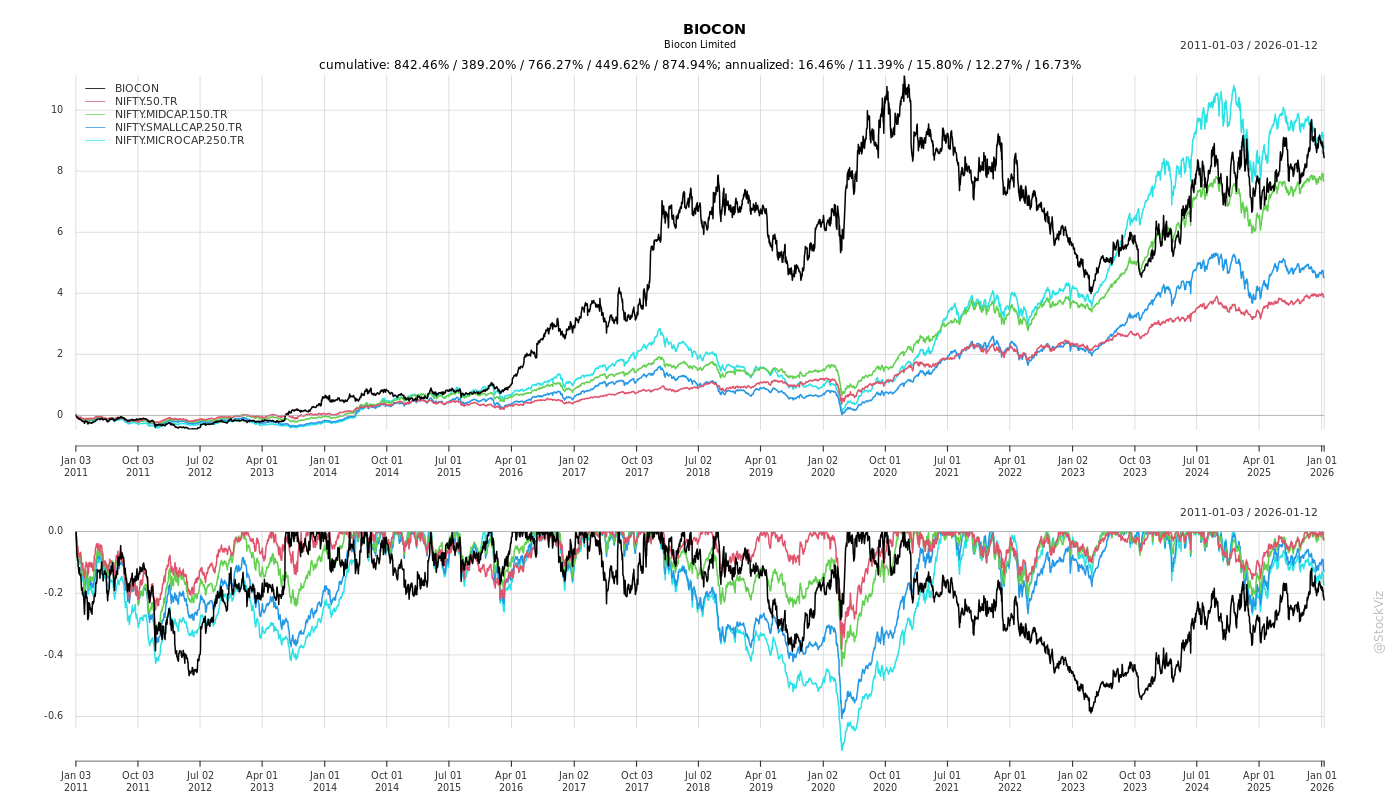
Cumulative Returns and Drawdowns
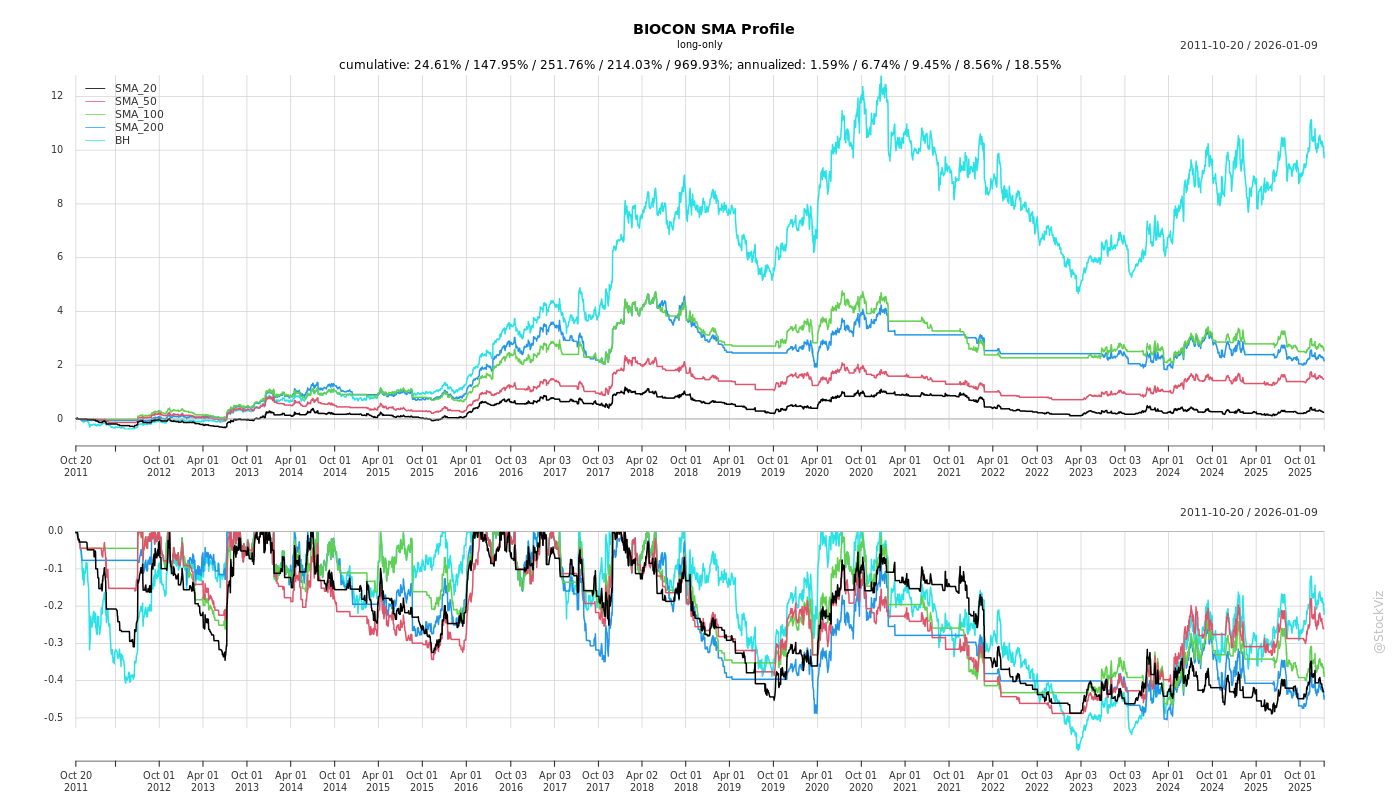
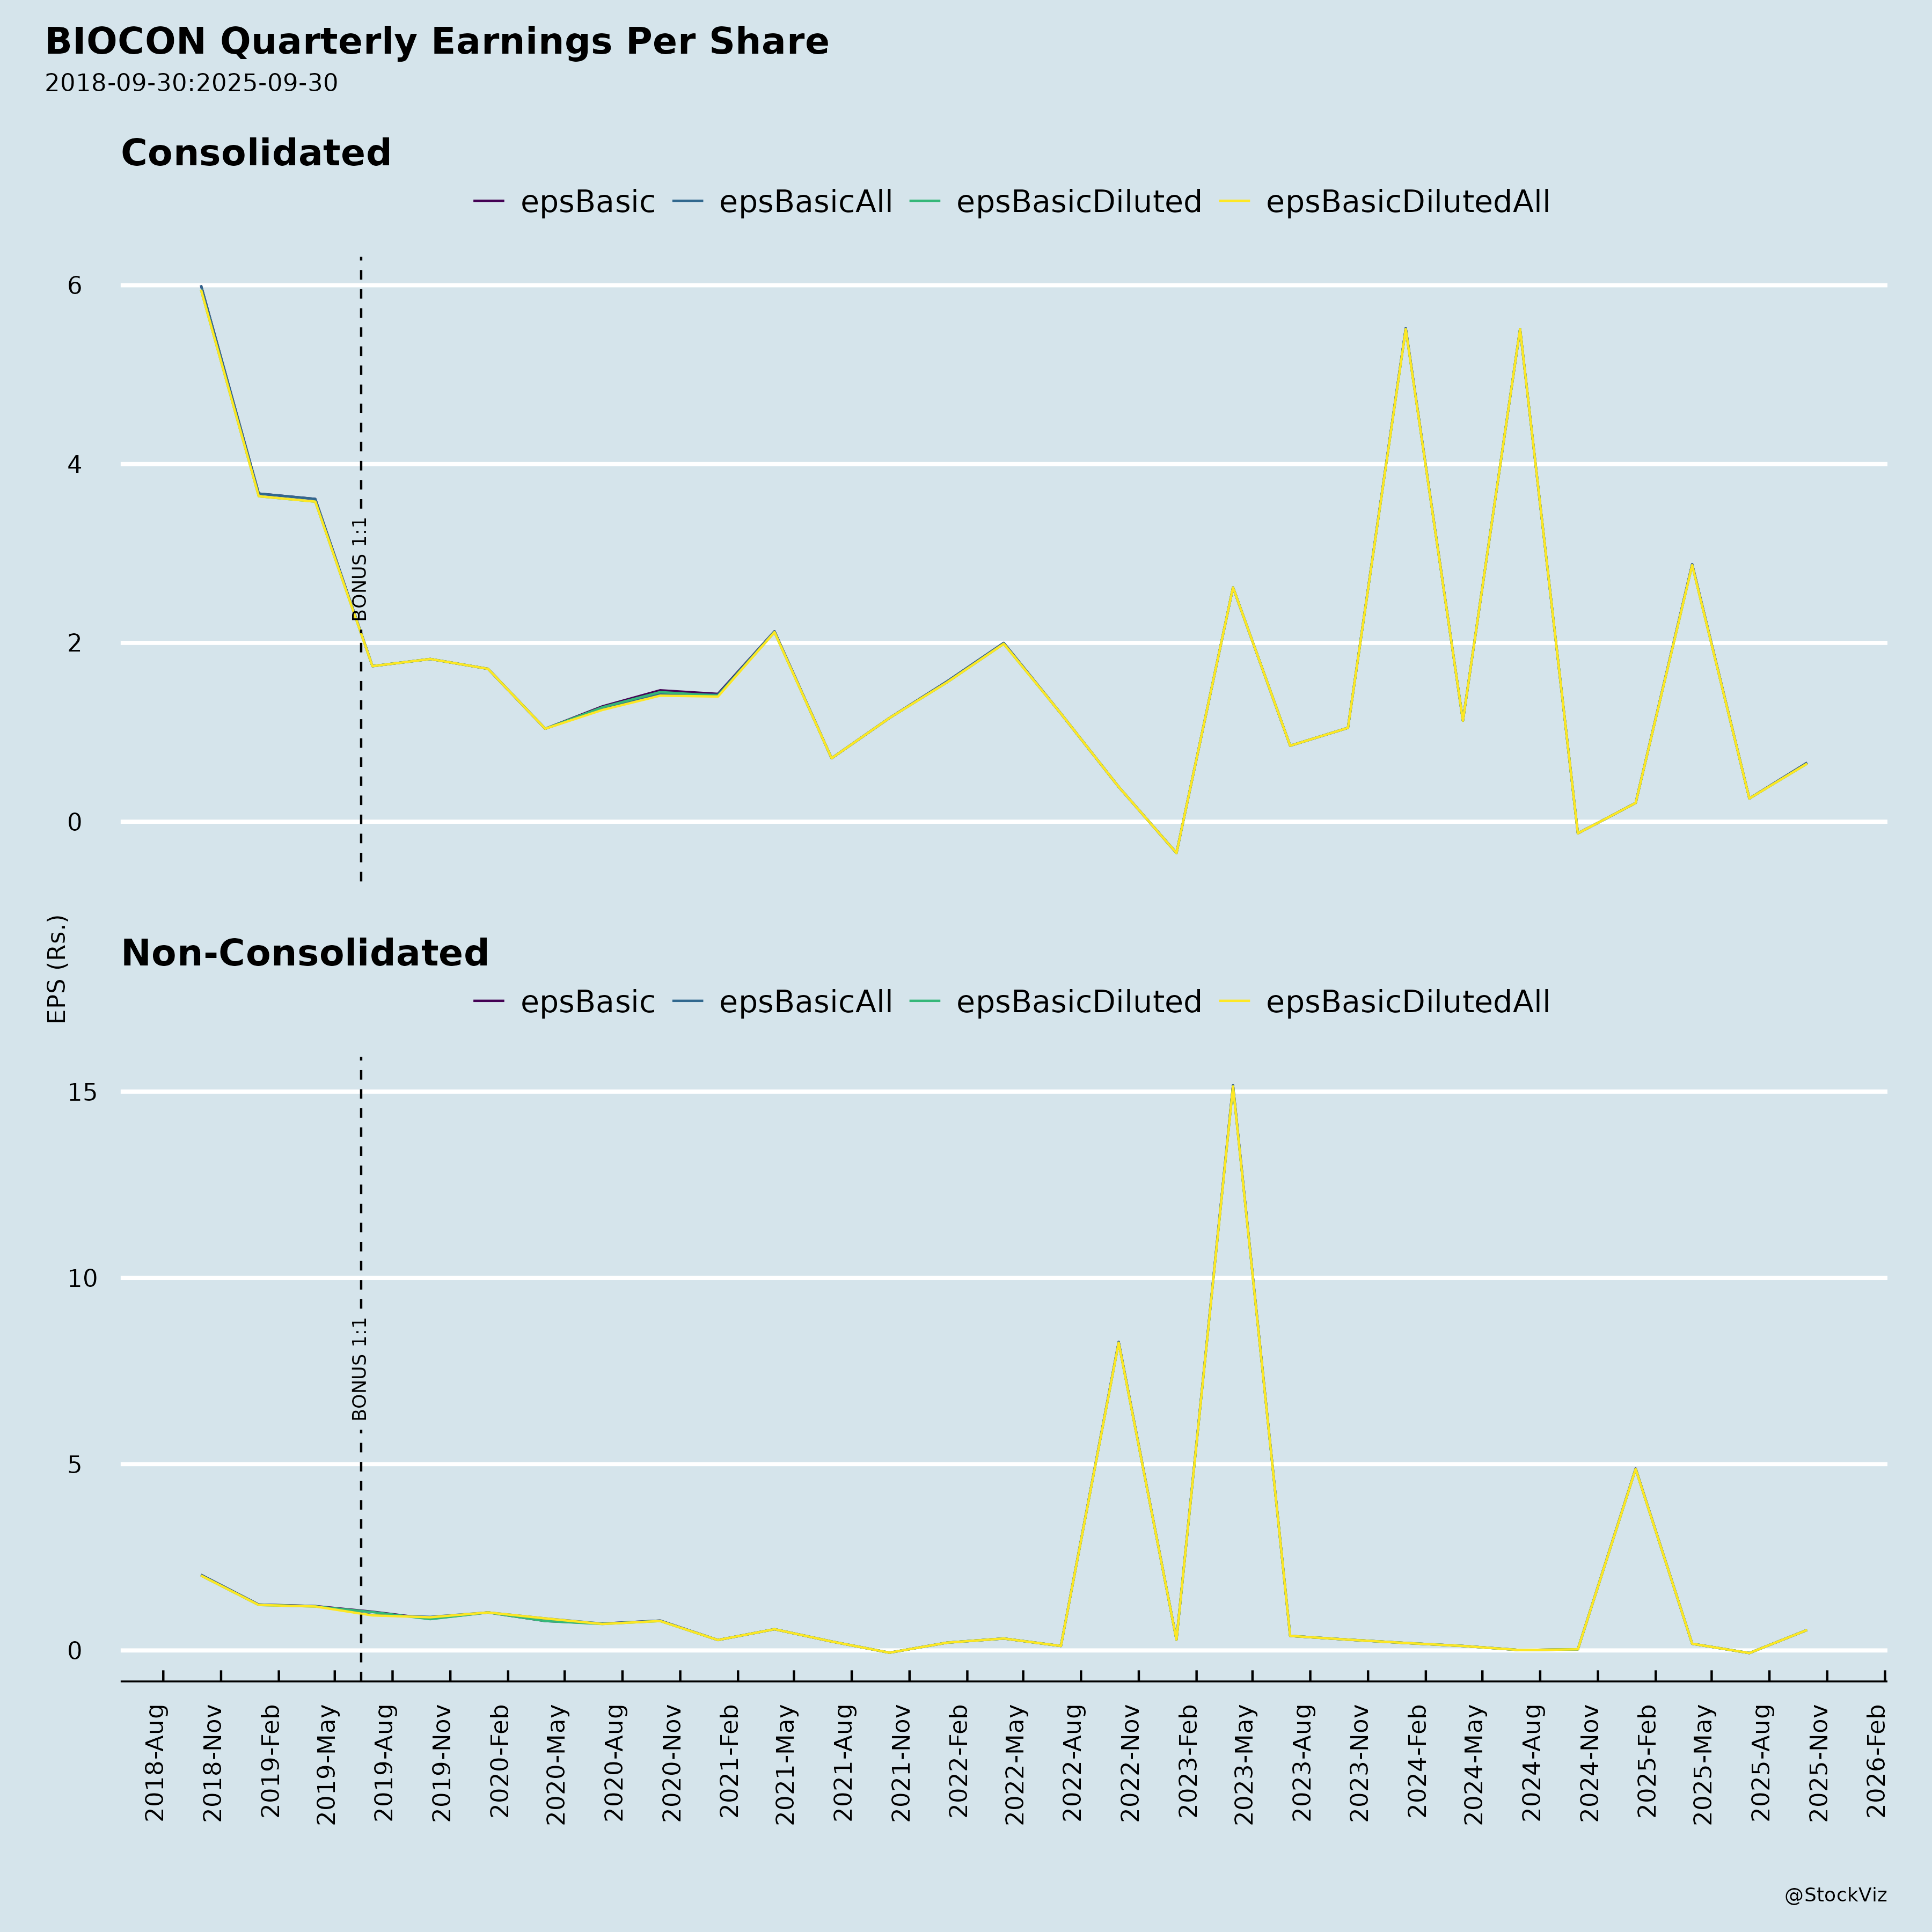
Fundamentals
Ownership

Margined
AI Summary
asof: 2026-09-16
Biocon: Recent Corporate Developments
1. Headwinds and Challenges
Services segment weakness. In Q1 FY27, the Services segment revenue stood at ₹736 Cr, down 16% YoY. Management attributes performance impacts to lower offtake from a key biologics client and forex hedge losses in Services. FY27 is described as a transition year for Services.
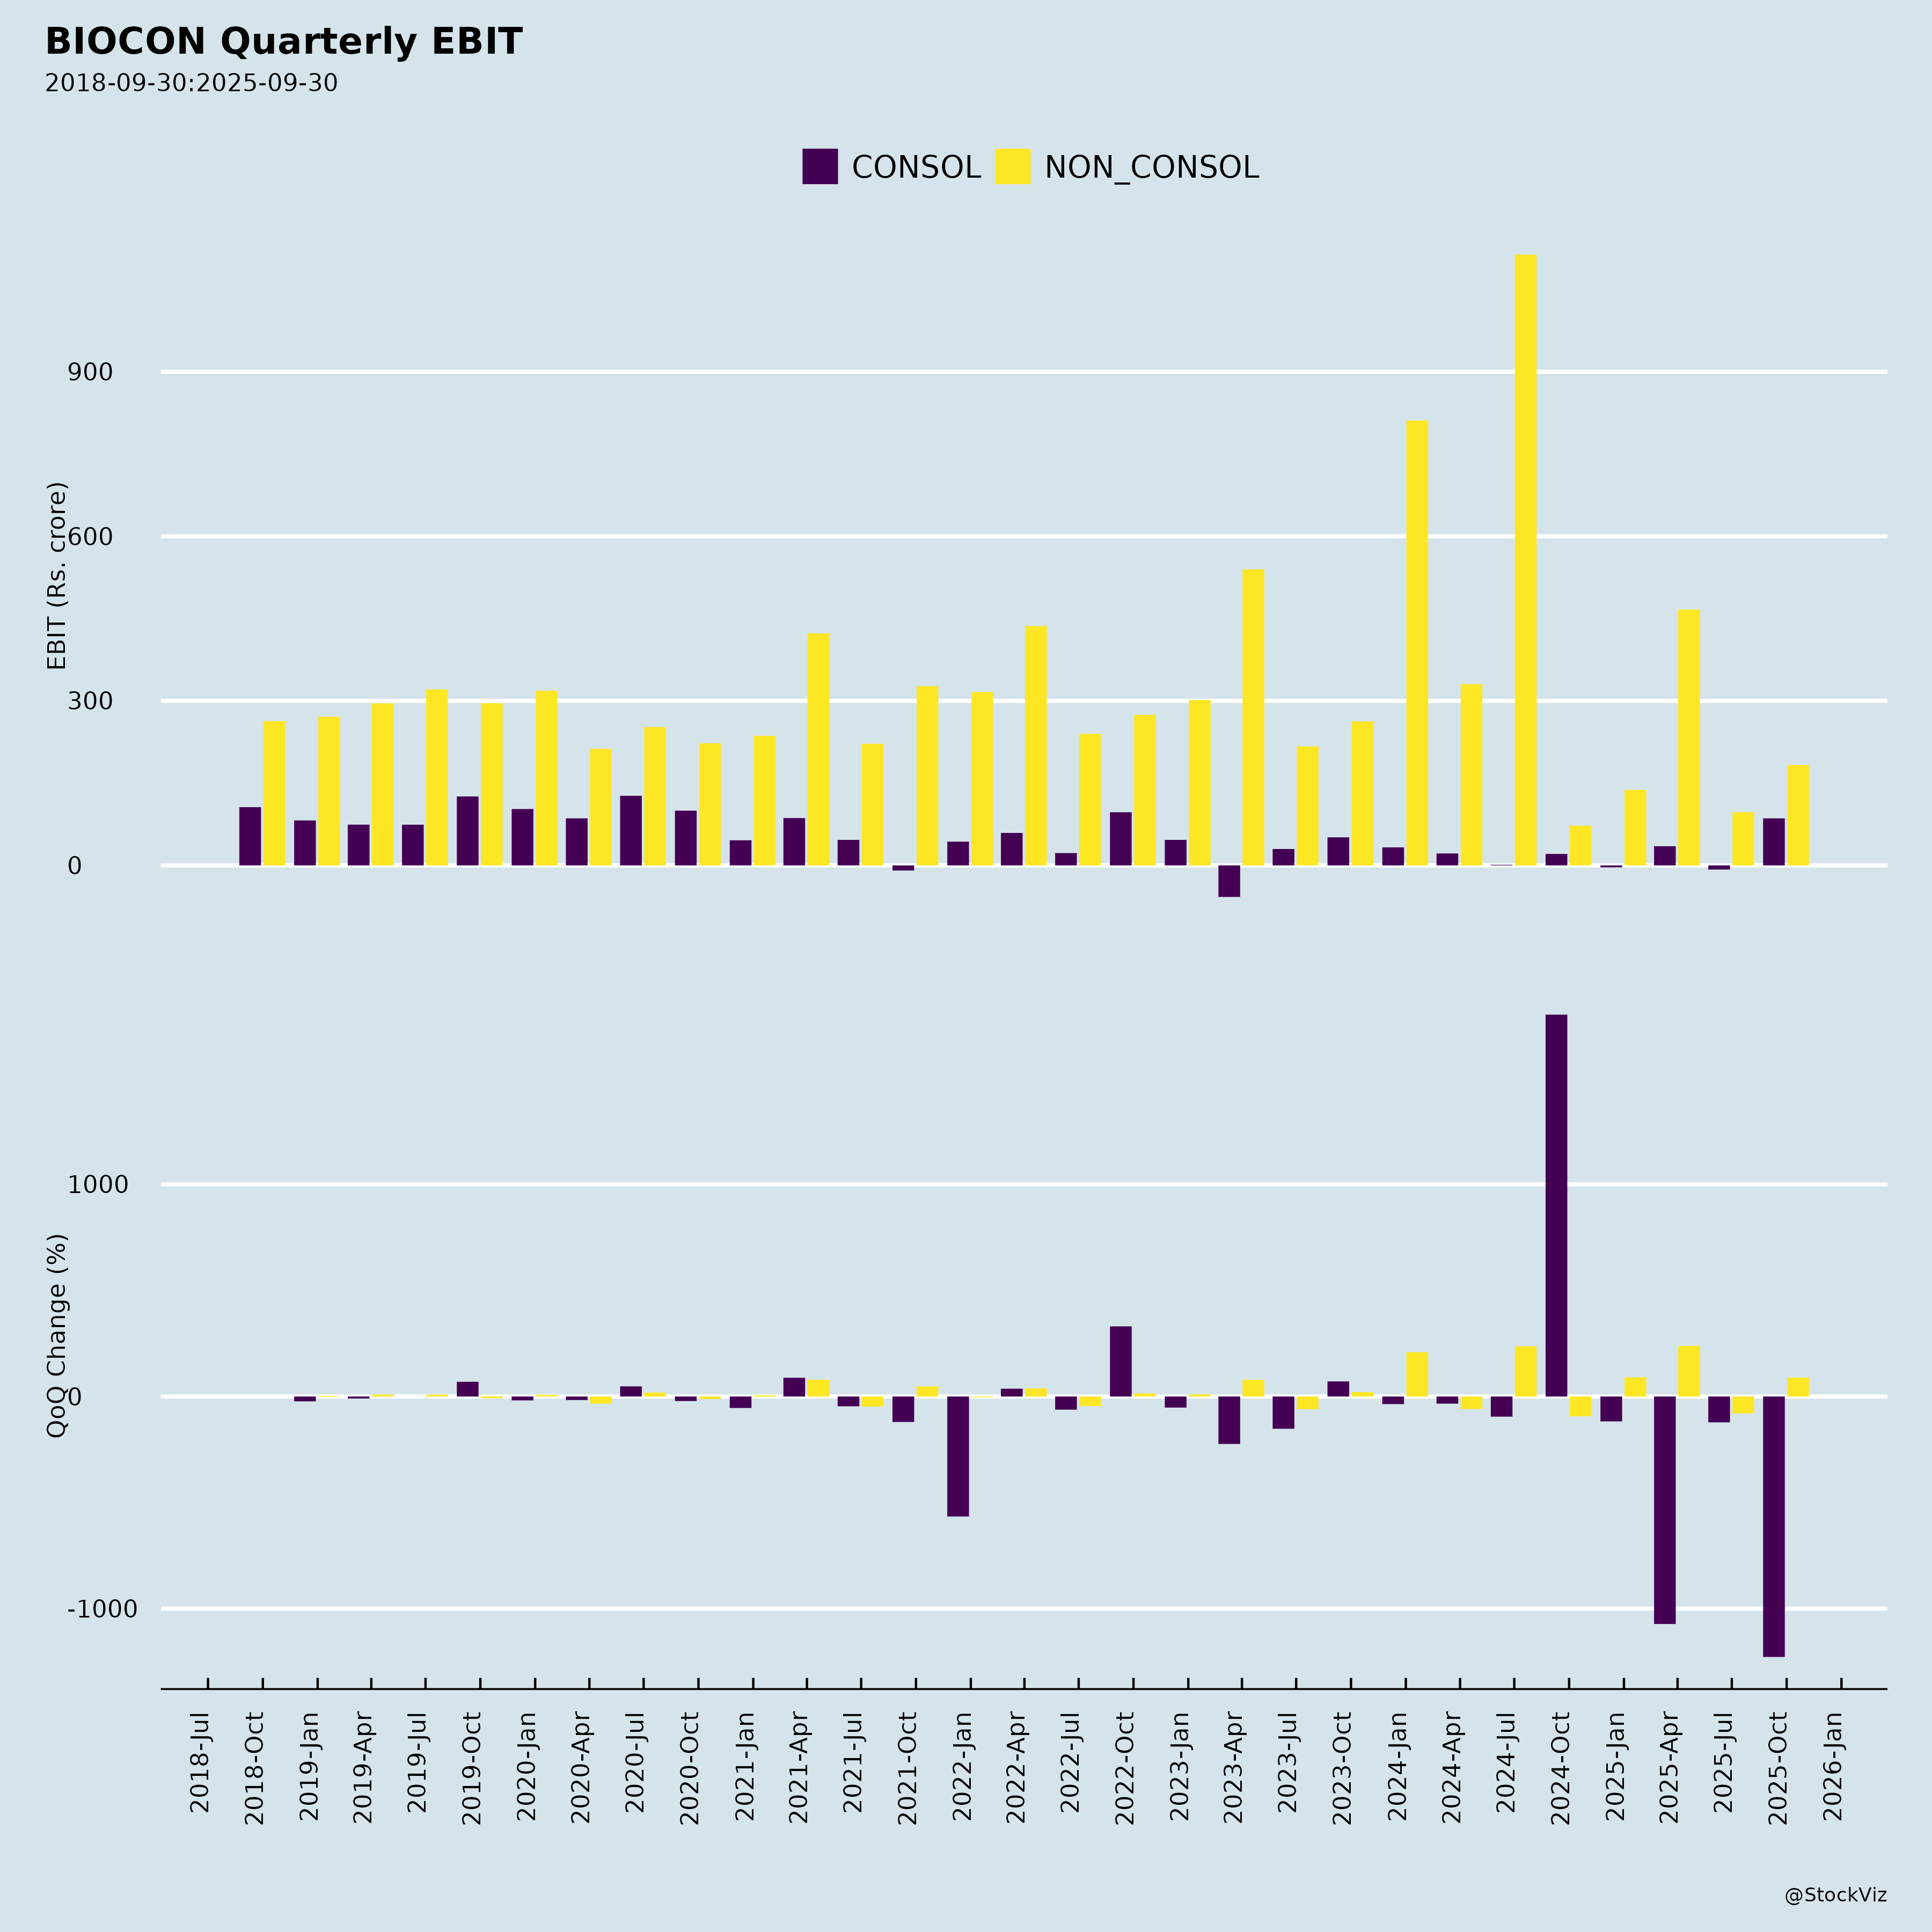
Profitability pressure. Despite revenue growth, Q1 FY27 Profit Before Tax (before exceptional items) and Reported Net Profit were both ₹141 Cr, indicating margin compression relative to the scale of operations. EBITDA margin was 21%.
Broader operating risks. The company identifies general economic and business conditions in India, ability to successfully implement strategy, R&D efforts, growth and expansion plans, technological changes, fluctuations in the value of the Rupee and other currencies, changes in Indian and international interest rates, changes in laws and regulations applying to the Indian and global biotechnology and pharmaceuticals industries, increasing competition, political conditions in India, foreign exchange control regulations as potential risks and headwinds.
2. Tailwinds and Growth Prospects
Biosimilars momentum. Biosimilars revenue was ₹2,855 Cr in Q1 FY27, up 16% YoY. North America is described as the largest strategic market with policy tailwinds and launch execution (Yesafili, Bosaya, Aukelso, and gLiraglutide). Europe features an integrated portfolio of 11 biosimilars and eight generic medicines with tailored retail and tender strategies, plus Evfraxy and Abevmy launches.
Emerging markets. Access-led growth is being pursued through portfolio breadth, local partnerships, CMOs, technology-transfer initiatives, a Yesafili launch in Malaysia, and bevacizumab leadership in Brazil.
Brazil PDP contract. Biocon signed a partnership agreement with Bahiafarma and Bionovis for Pertuzumab in Brazil, securing a 10-year supply contract and 100% allocation under Brazil’s Productive Development Partnership (PDP) program. This grants exclusive access to Brazil’s public healthcare market (representing ~70% of the country’s demand for Pertuzumab), milestone payments, and a share of revenues over a 10-year period, with phased localization of the product in the mid to long term.
Generics growth. Generics revenue was ₹760 Cr in Q1 FY27, up 21% YoY, driven by generic liraglutide, operating leverage, cost efficiency initiatives, and investments in peptides and fermentation. EMA approval for the second insulin drug product line in Malaysia doubles capacity.
Integrated platform. The company cites an integrated platform, global scale, and resilient supply networks as material opportunities.
3. Key Risks
- Dependence on a key biologics client, as evidenced by the Services segment decline linked to lower offtake.
- Foreign exchange exposure, including forex hedge losses in Services and fluctuations in the value of the Rupee and other currencies.
- Regulatory and legal changes across Indian and international biotechnology and pharmaceuticals industries.
- Increasing competition in biosimilars and generics.
- Execution risk on growth and expansion plans, R&D efforts, and technological changes.
- Interest rate changes in Indian and international markets.
- Political conditions in India and foreign exchange control regulations.
- Currency and macro-economic conditions affecting international operations across the group’s many subsidiaries.
4. Management Guidance vs. Observed Performance
Guidance: Management expects growth momentum to build progressively through FY27, with the second half (H2) to be meaningfully better, driven by Biosimilars, recent launches, and market access progress. FY27 is considered a transition year for Services, with performance improving in 2H, a new management team focused on commercial execution and delivery, and positioning for a return to sustainable growth from FY28.
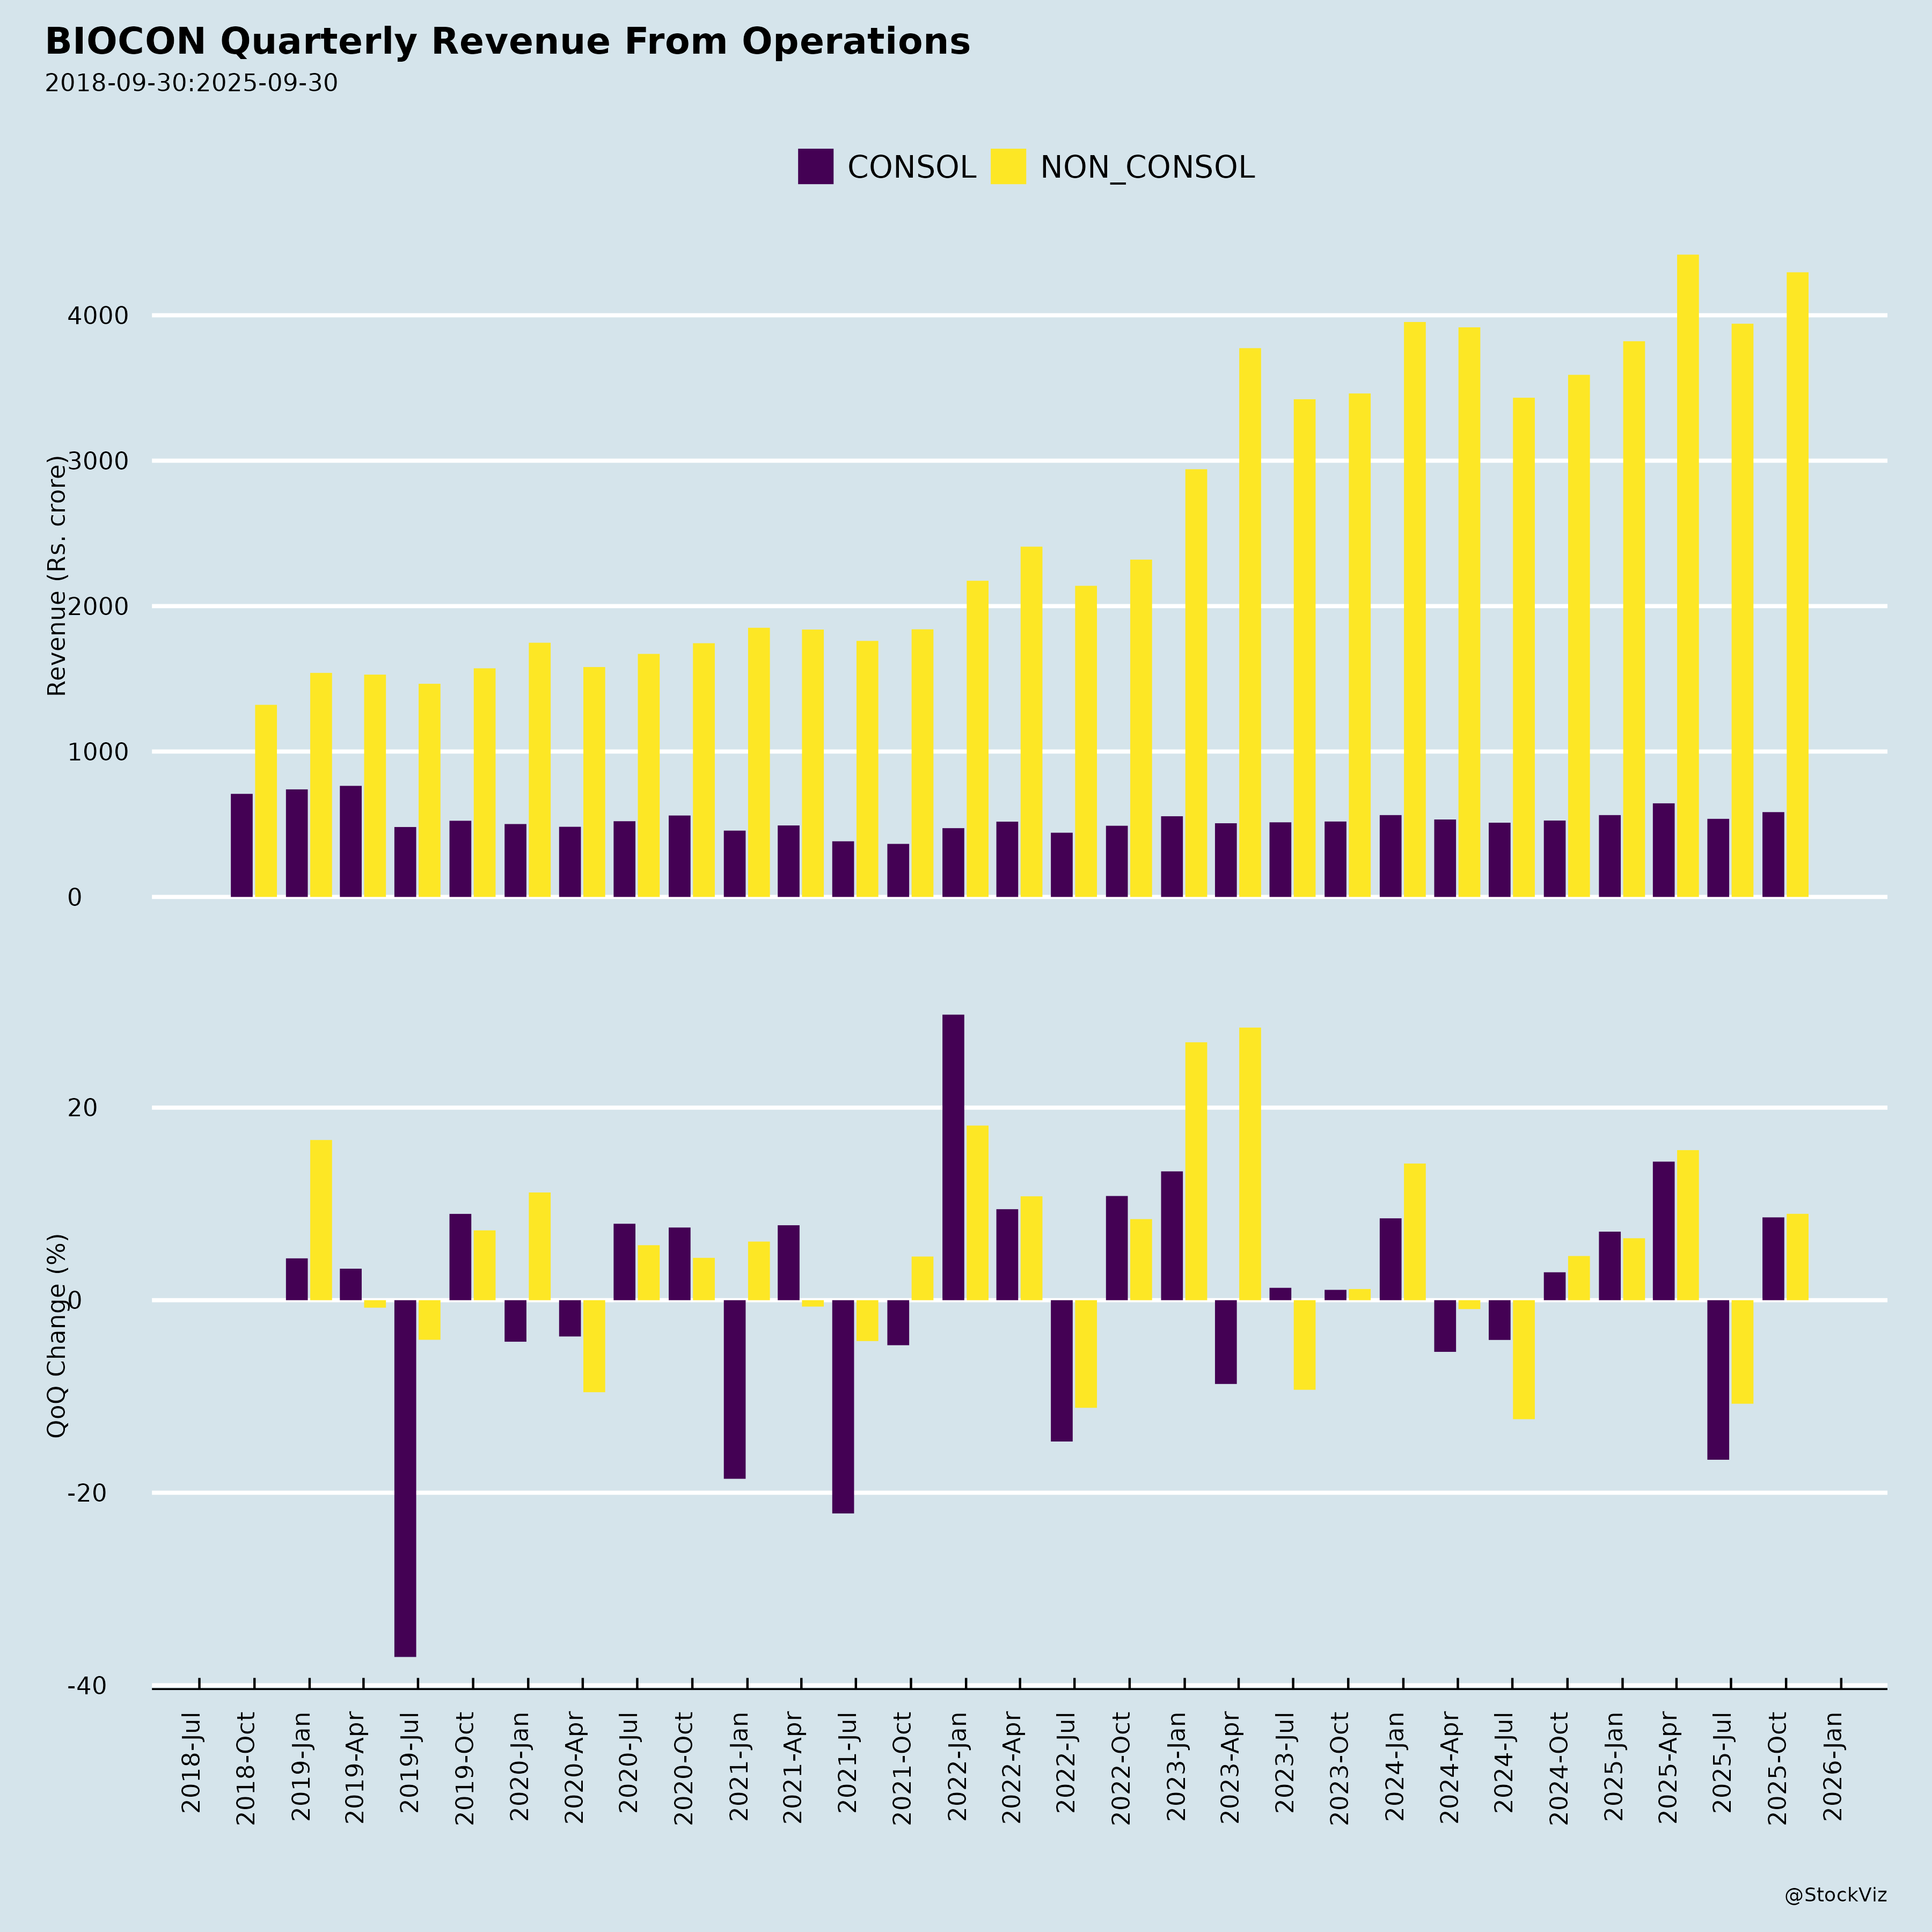
Observed performance (Q1 FY27): Revenue from Operations was ₹4,336 Cr (up 10% YoY); Total Revenue was ₹4,391 Cr (up 9% YoY); EBITDA was ₹902 Cr at a 21% margin; Profit Before Tax (before exceptional items) and Reported Net Profit were both ₹141 Cr. Segment performance was mixed: Biosimilars up 16% YoY and Generics up 21% YoY, while Services declined 16% YoY. R&D (Net) was ₹240 Cr.
The Q1 FY27 results show the growth momentum management refers to in Biosimilars and Generics, while the Services decline is consistent with the characterization of FY27 as a transition year for that segment with improvement expected in H2.
5. Other Key Facts
- The 48th AGM was held on Thursday, August 06, 2026, through video conferencing, transacting businesses set out in the AGM Notice dated July 10, 2026.
- A final dividend of 10% (₹0.50 per equity share) for FY2025-26 was approved and remitted, as approved at the AGM.
- All nine resolutions put to shareholders were passed. Resolutions 1–4 and 9 were ordinary resolutions; Resolutions 5–8 were special resolutions relating to the Biocon Unity Long Term Incentive Plan 2026 (including the Performance Stock Unit Plan 2026, Restricted Stock Unit Plan 2026, Employee Stock Purchase Plan 2026, and Management Stock Unit Plan 2026, also named the Biocon Unity “Growth Accelerator” Plan 2026).
- The equity-based incentive resolutions (5–8) saw significant opposition, with approximately 20% of votes cast against, largely from Public-Institutions (roughly 51% of institutional votes against on Resolutions 5 and 6, and roughly 50.7% against on Resolutions 7 and 8).
- S.R. Batliboi & Associates LLP was approved as Statutory Auditors.
- Eric Vivek Mazumdar (DIN: 09381549) was re-appointed as Director, liable to retire by rotation.
- The Board meeting to approve Q1 FY27 results was held on August 05, 2026, commencing at 2:30 p.m. and concluding at 3:34 p.m.
- B S R & Co. LLP issued limited review reports on both standalone and consolidated unaudited financial results for the quarter ended June 30, 2026, with no material misstatements noted.
- Management is scheduled to meet Analyst(s)/Institutional Investor(s) for an Investor Roadshow on 11-Sep-26 in Mumbai, and will not disclose any Unpublished Price Sensitive Information (UPSI) during these meetings.
Broker Narrative
Broker narrative on BIOCON shifted from broad market technicals to company-specific fundamentals. The 2021 report framed the stock through Nifty momentum—warning of an intermediate top and near-term consolidation while citing an intact uptrend and RSI room for upside. Over the intervening years, Motilal Oswal and others repeatedly issued cautious Neutral/Sell calls predicting declines, yet the stock frequently rallied, producing many DISAPPOINTMENT outcomes for bearish calls. By the 2026 report the narrative had turned constructively on fundamentals—Malaysia insulin capacity doubling, biosimilar margin expansion to the mid-20s, debt retirement and interest savings, and new launches such as Yesafili, Bosaya/Okelso and liraglutide—with no headwinds flagged, even though that latest Buy call itself ended as a DISAPPOINTMENT (-8.6% actual versus +10.1% expected).
Fears that came true
- The inaugural headwind of a Nifty intermediate top triggering near-term correction/consolidation and limited upside was validated by the negative -8.5% actual return on the 2021-06-07 Hold call.
Optimism that failed
- The expected capacity and utilization ramp—EMA approval doubling the Malaysia insulin line with Q2FY27 commercial supply plus fermentation/peptide investment—failed to produce the forecast gains, as the latest Buy target of +10.1% was missed with an -8.6% actual (DISAPPOINTMENT).
- The anticipated margin and cash-flow inflection—biosimilar EBITDA margin of 25% accelerating in H2FY27, retired structured debt, and interest expense down 23% YoY/8% QoQ to Rs 213 Cr—did not drive the predicted upside, ending at -8.6% actual versus +10.1% expected (DISAPPOINTMENT).
- The forecast therapeutic-mix expansion—Yesafili (bAflibercept) in the US/Malaysia, Bosaya/Okelso (bDenosumab) in North America/Europe, Insulin Glargine share gains, Kirsty (Insulin Aspart) payer coverage, and generic Liraglutide GLP-1 growth—did not prevent the downside miss, with the stock at -8.6% against a +10.1% Buy call (DISAPPOINTMENT).
Broker Timeline
28 broker calls · 2021-06-07 to 2026-09-18
CNBC-TV18: ratings, targets and commentary
Extracted from CNBC-TV18 posts; ratings and targets are as published, not current consensus. OCR may contain errors. Speaker attribution is retained; not all speakers are brokers. These statements are separate from the Broker Narrative and Broker Timeline and have no calculated performance or outcomes.
Management comments
Company-related comments from CNBC-TV18 posts in x-stream. Speakers are management of the displayed affiliation, not necessarily management of this company. Only explicit executive designations and affiliations are included; analyst, broker and investment-manager commentary remains separate. OCR may contain errors.
| Published / source (IST) | Speaker / affiliation / designation | Commentary |
|---|---|---|
|
Shreehas Tambe
Biocon
CEO & Managing Director, Biocon
|
|
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.