BBTCL
Equity Metrics
September 24, 2026
B&B Triplewall Containers Limited
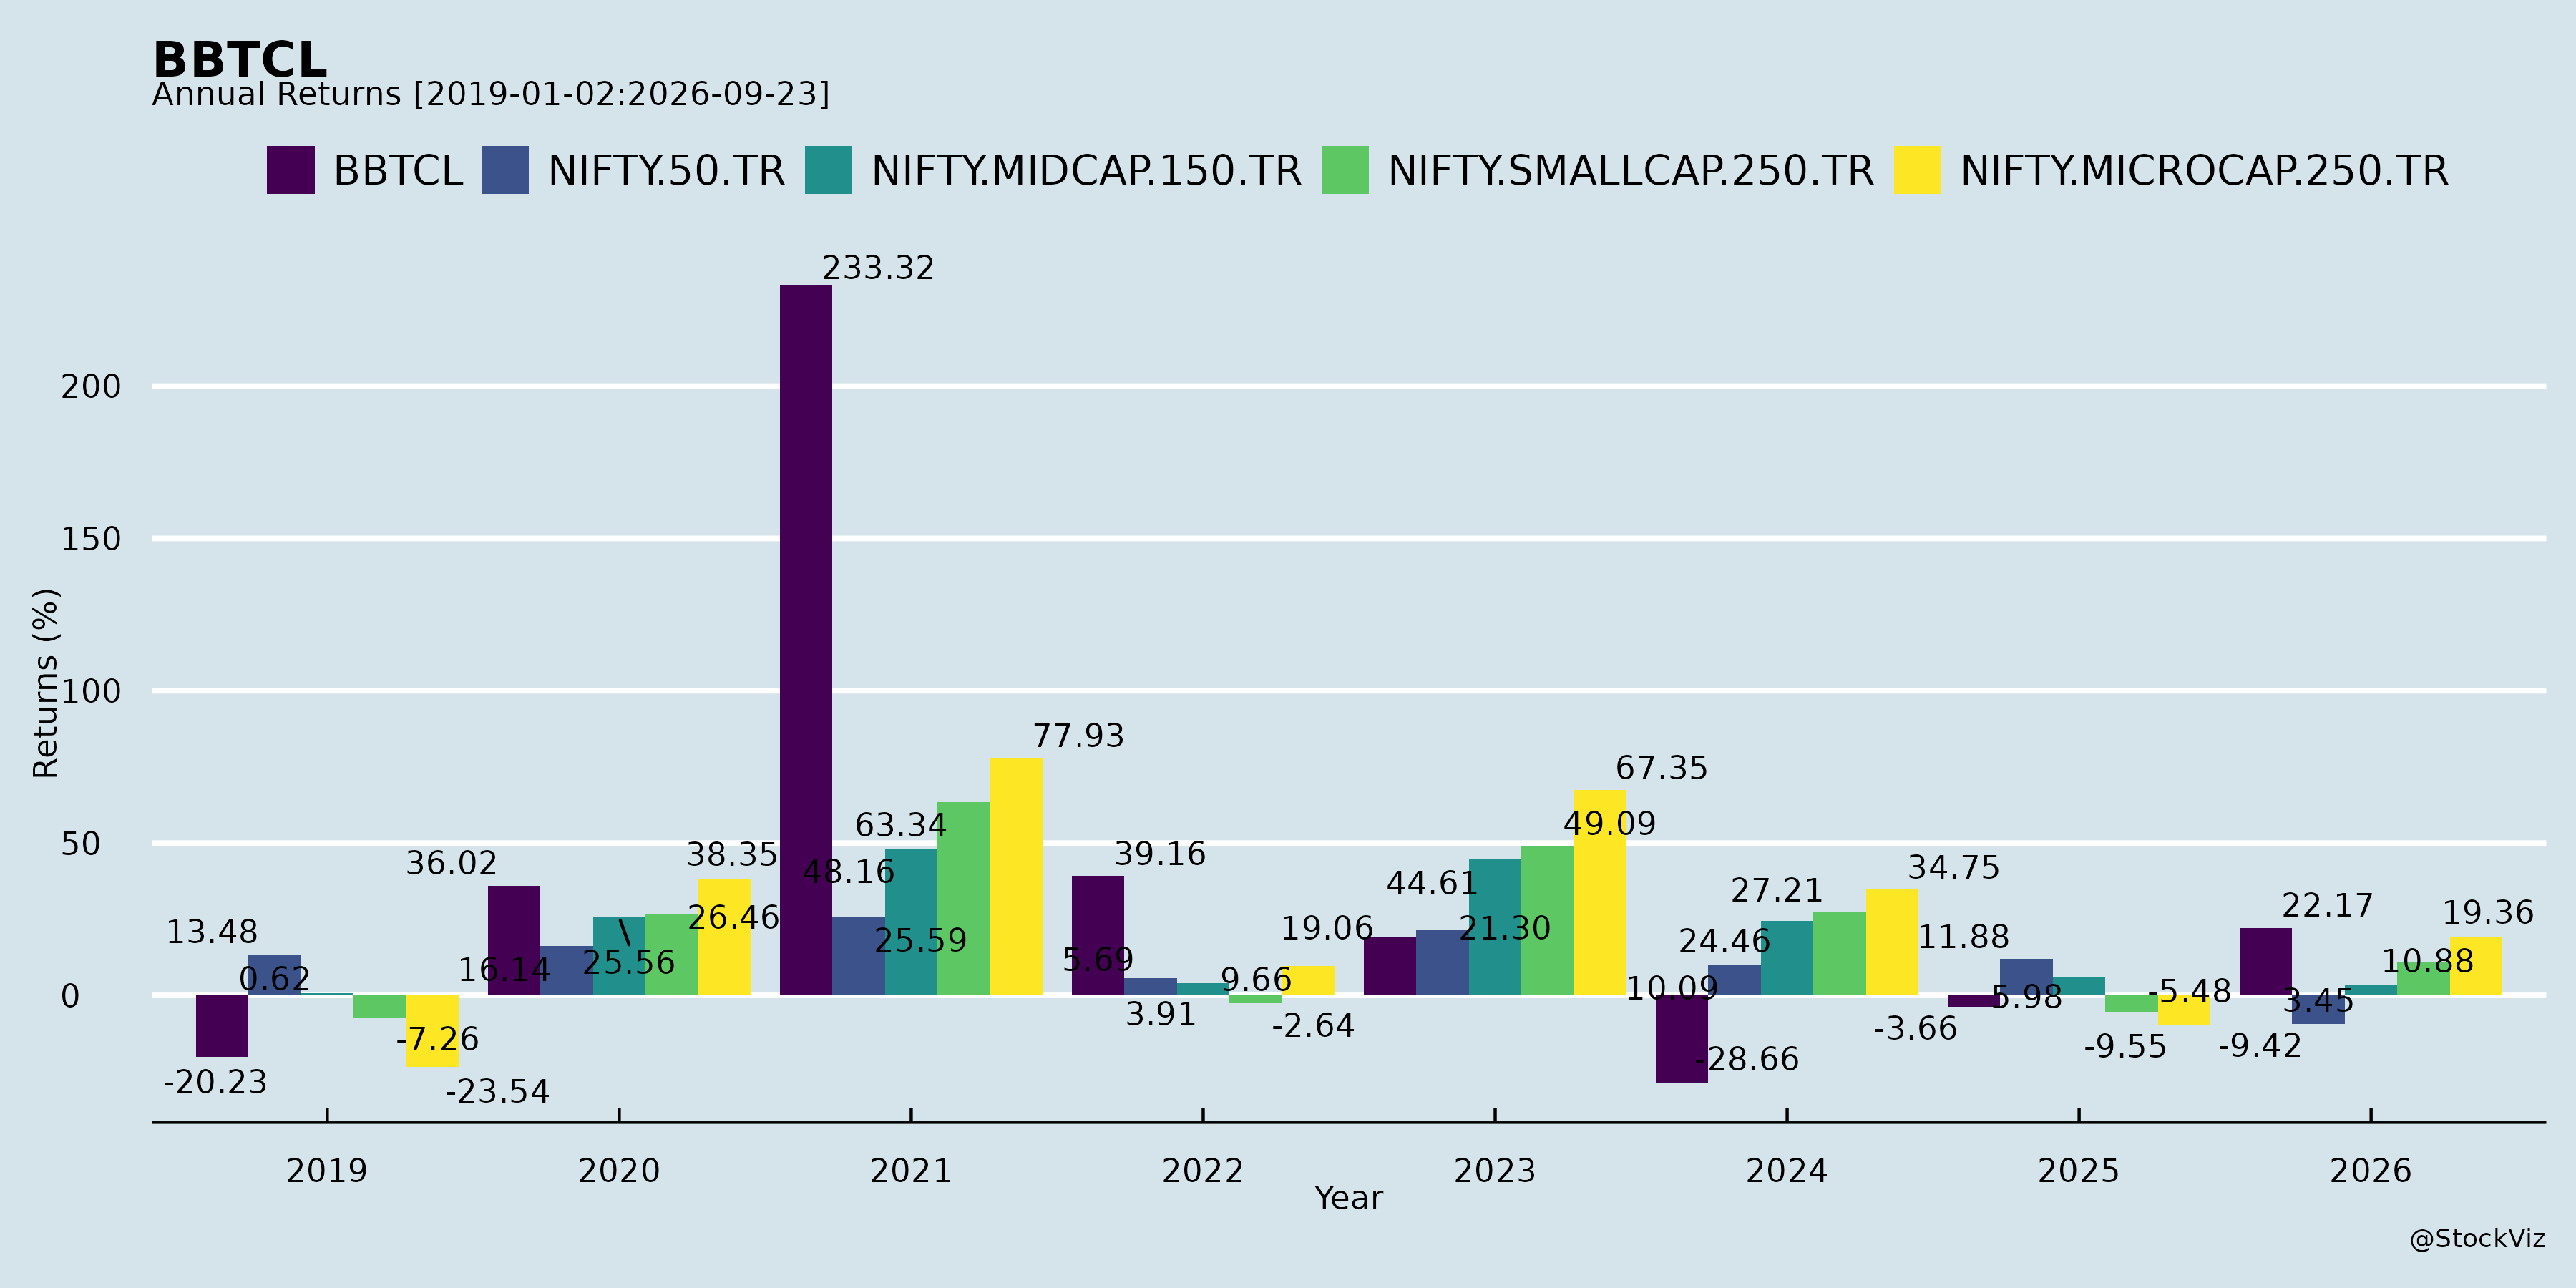
Annual Returns
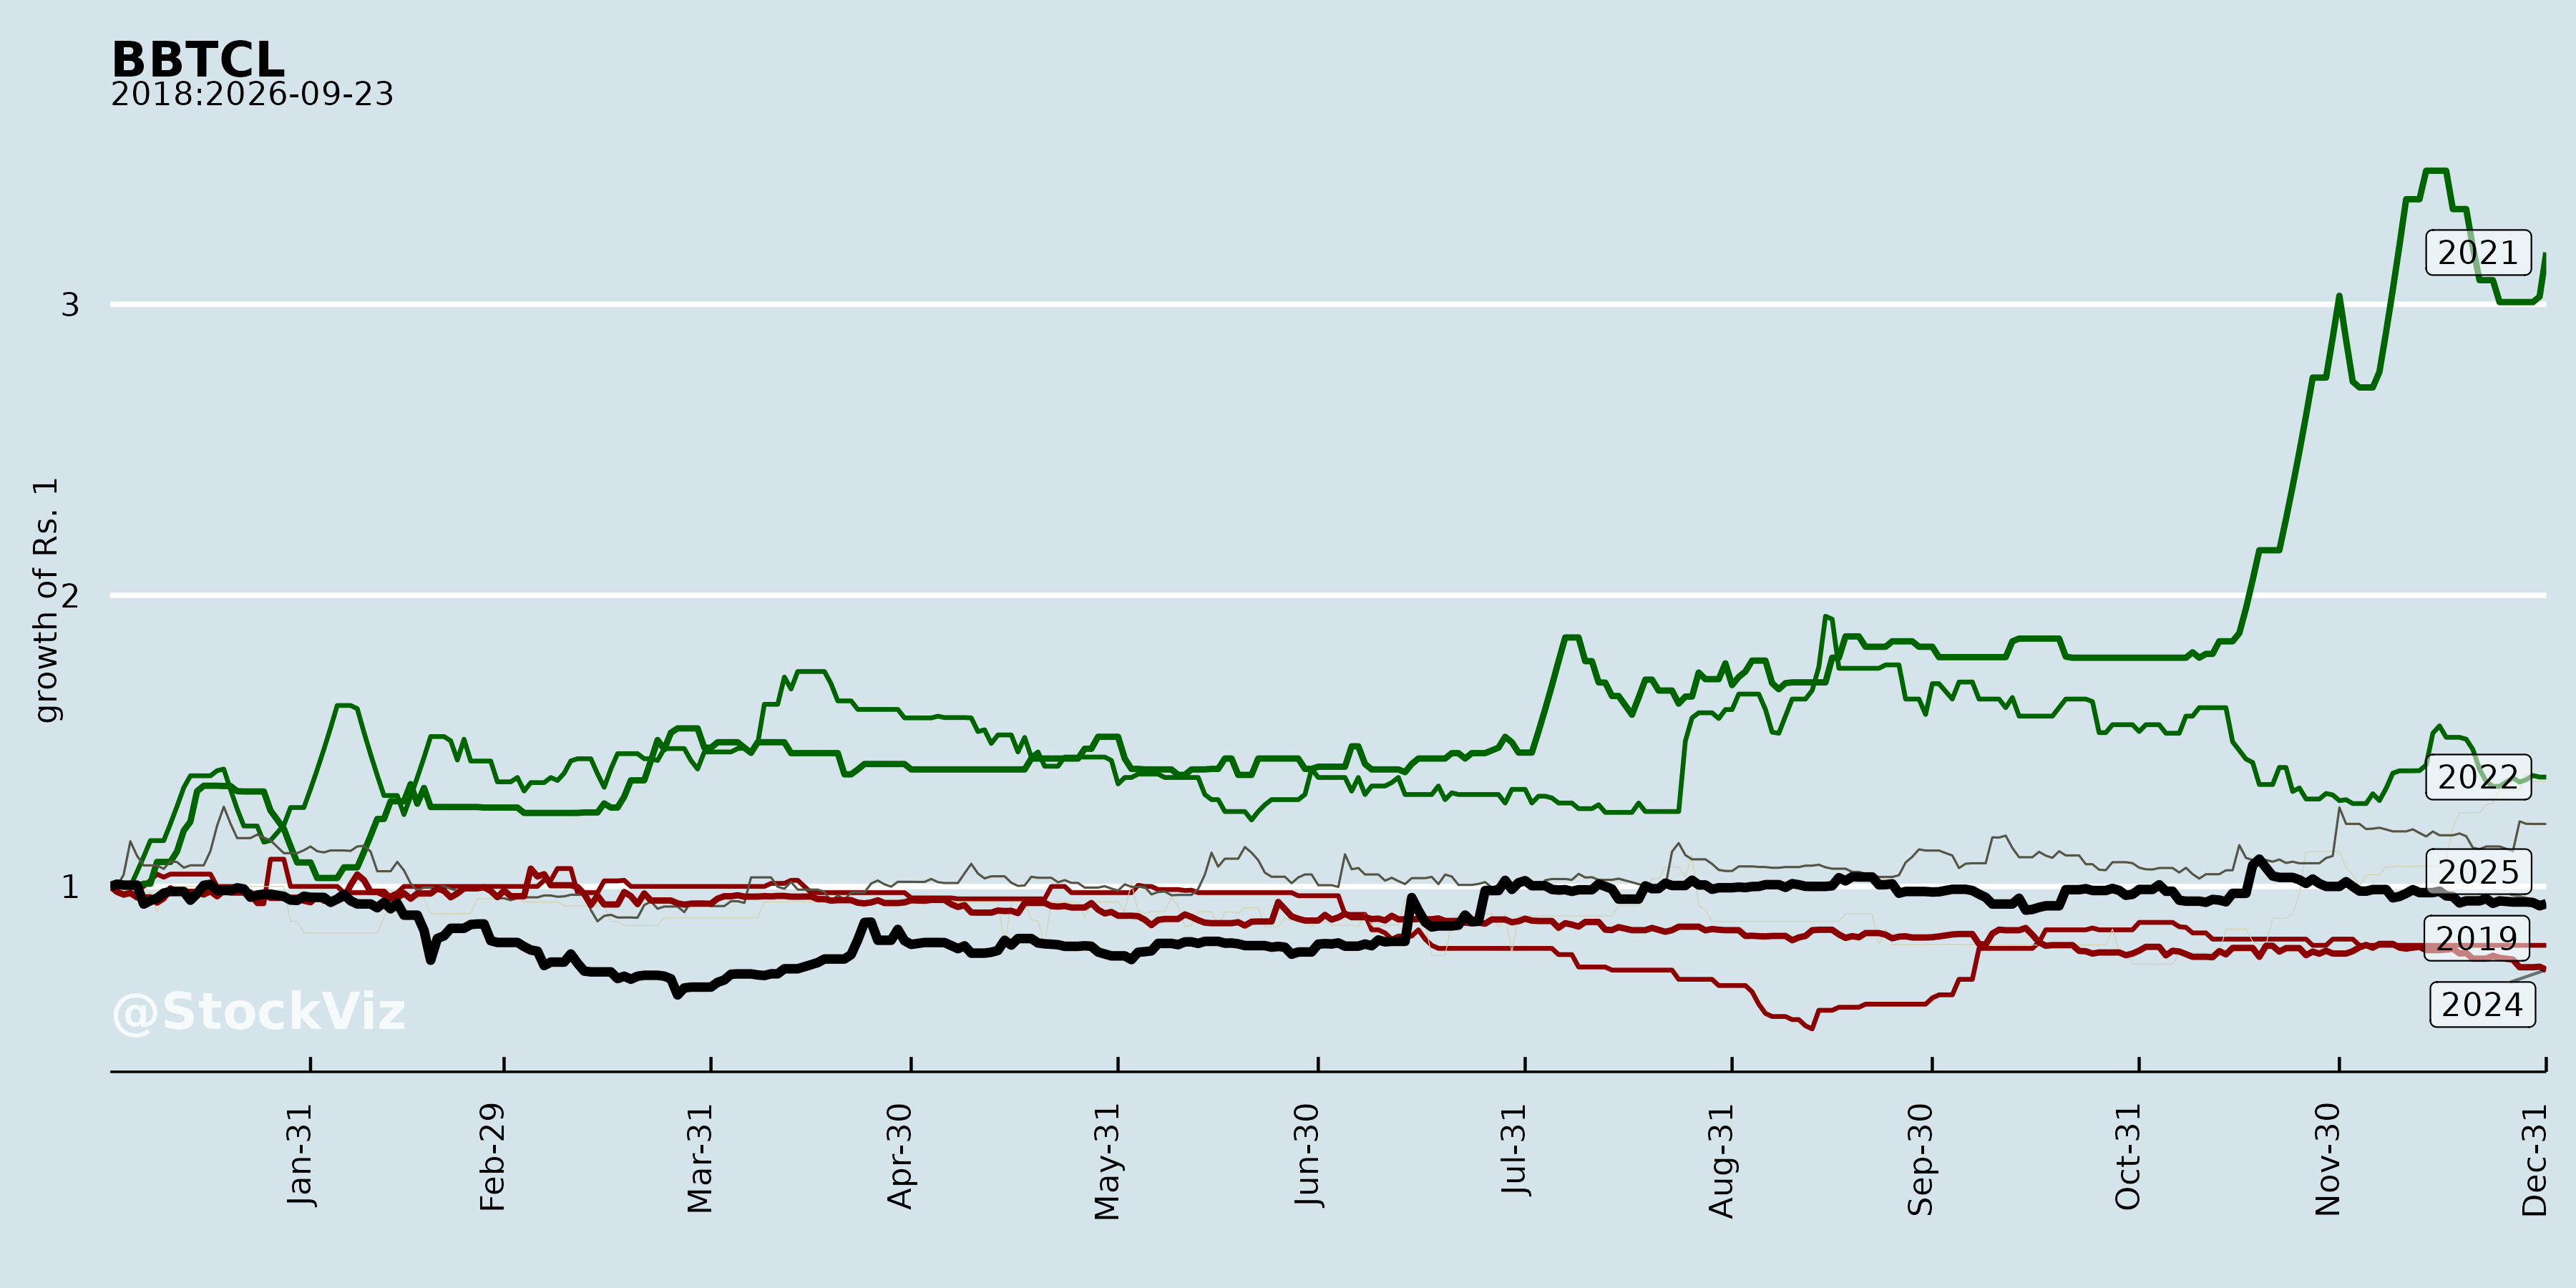
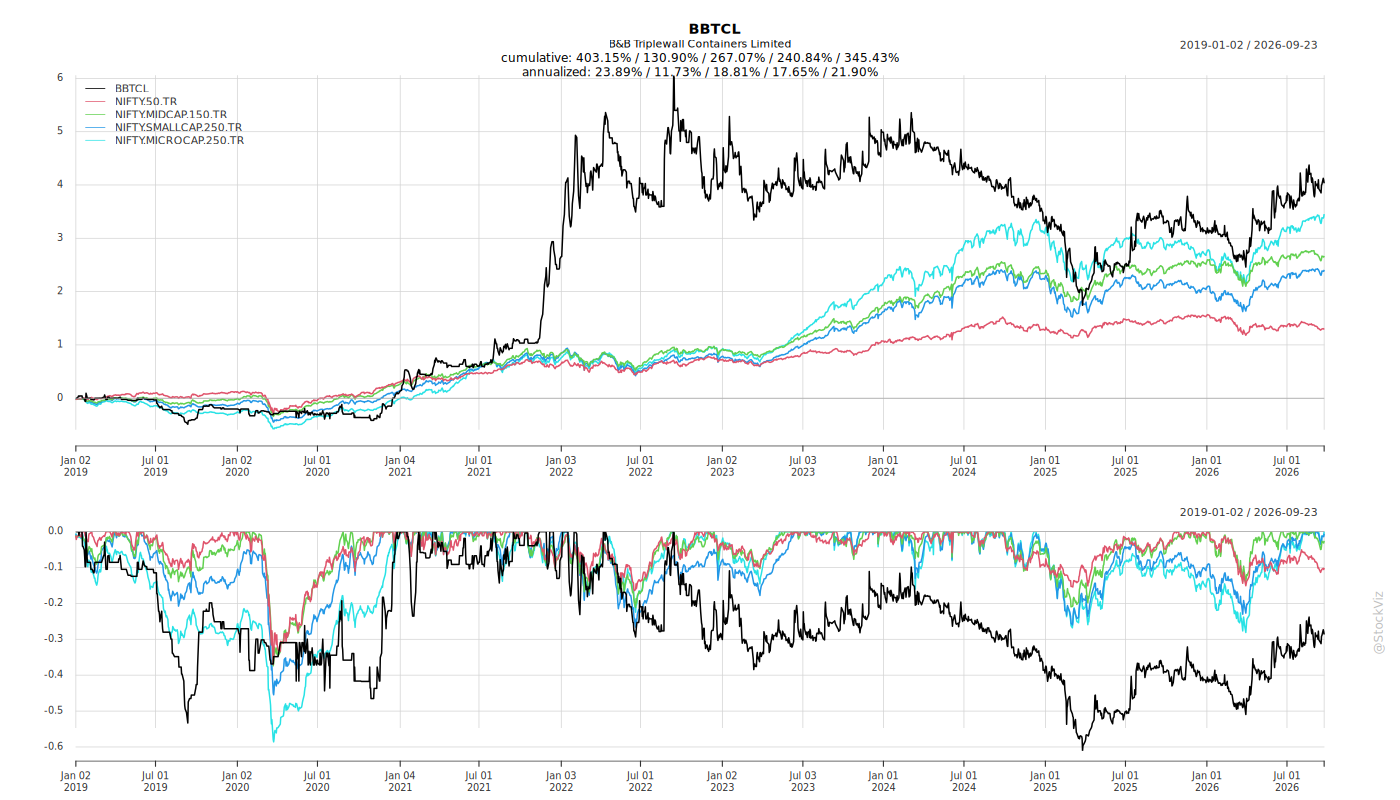
Cumulative Returns and Drawdowns
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-19
BBTCL: Recent Corporate Announcements and Business Developments
1. Headwinds and Challenges
The company operates in an environment shaped by several persistent pressures:
- Raw material price fluctuations and supply chain disruptions affect input costs and production continuity.
- Regulatory compliance costs add to the operating burden.
- Intense industry competition constrains pricing power and margin expansion.
- Fire risks are inherent to operations handling flammable corrugated paper materials.
- Geographical concentration of sales is skewed toward Karnataka, Tamil Nadu, Maharashtra, and Telangana, leaving the business exposed to regional demand and logistical disruptions.
2. Tailwinds and Growth Prospects
Several structural and market factors support the company’s growth trajectory:
- Growing demand for sustainable, recyclable, and biodegradable packaging, driven by environmental awareness and bans on single-use plastics.
- Expansion in the e-commerce sector, which is a significant consumer of corrugated packaging.
- Rising demand across fresh fruits and vegetables, QSR, FMCG, and electronics sectors.
- Backward integration into kraft paper manufacturing, which is intended to improve operational efficiency and cost control. A newly operational kraft paper manufacturing unit supports this effort.
- Established multi-unit footprint across Karnataka, Tamil Nadu, and Telangana provides a base for scaling.
3. Key Risks
- Input cost volatility from raw material price swings.
- Supply chain disruptions that could interrupt production or delivery.
- Regulatory and compliance cost escalation.
- Competitive intensity in the packaging industry.
- Fire-related operational hazards given the flammable nature of corrugated paper materials.
- Regional revenue concentration in four southern and western states.
4. Management Guidance vs. Observed Business Performance
Guidance: - Management’s stated vision is “20 IN 27”, targeting conversion of 20,000 metric tonnes of paper per month by 2027. - The company remains focused on operational excellence, customer responsiveness, expanding manufacturing capabilities, and enhancing shareholder value through sustainable growth.
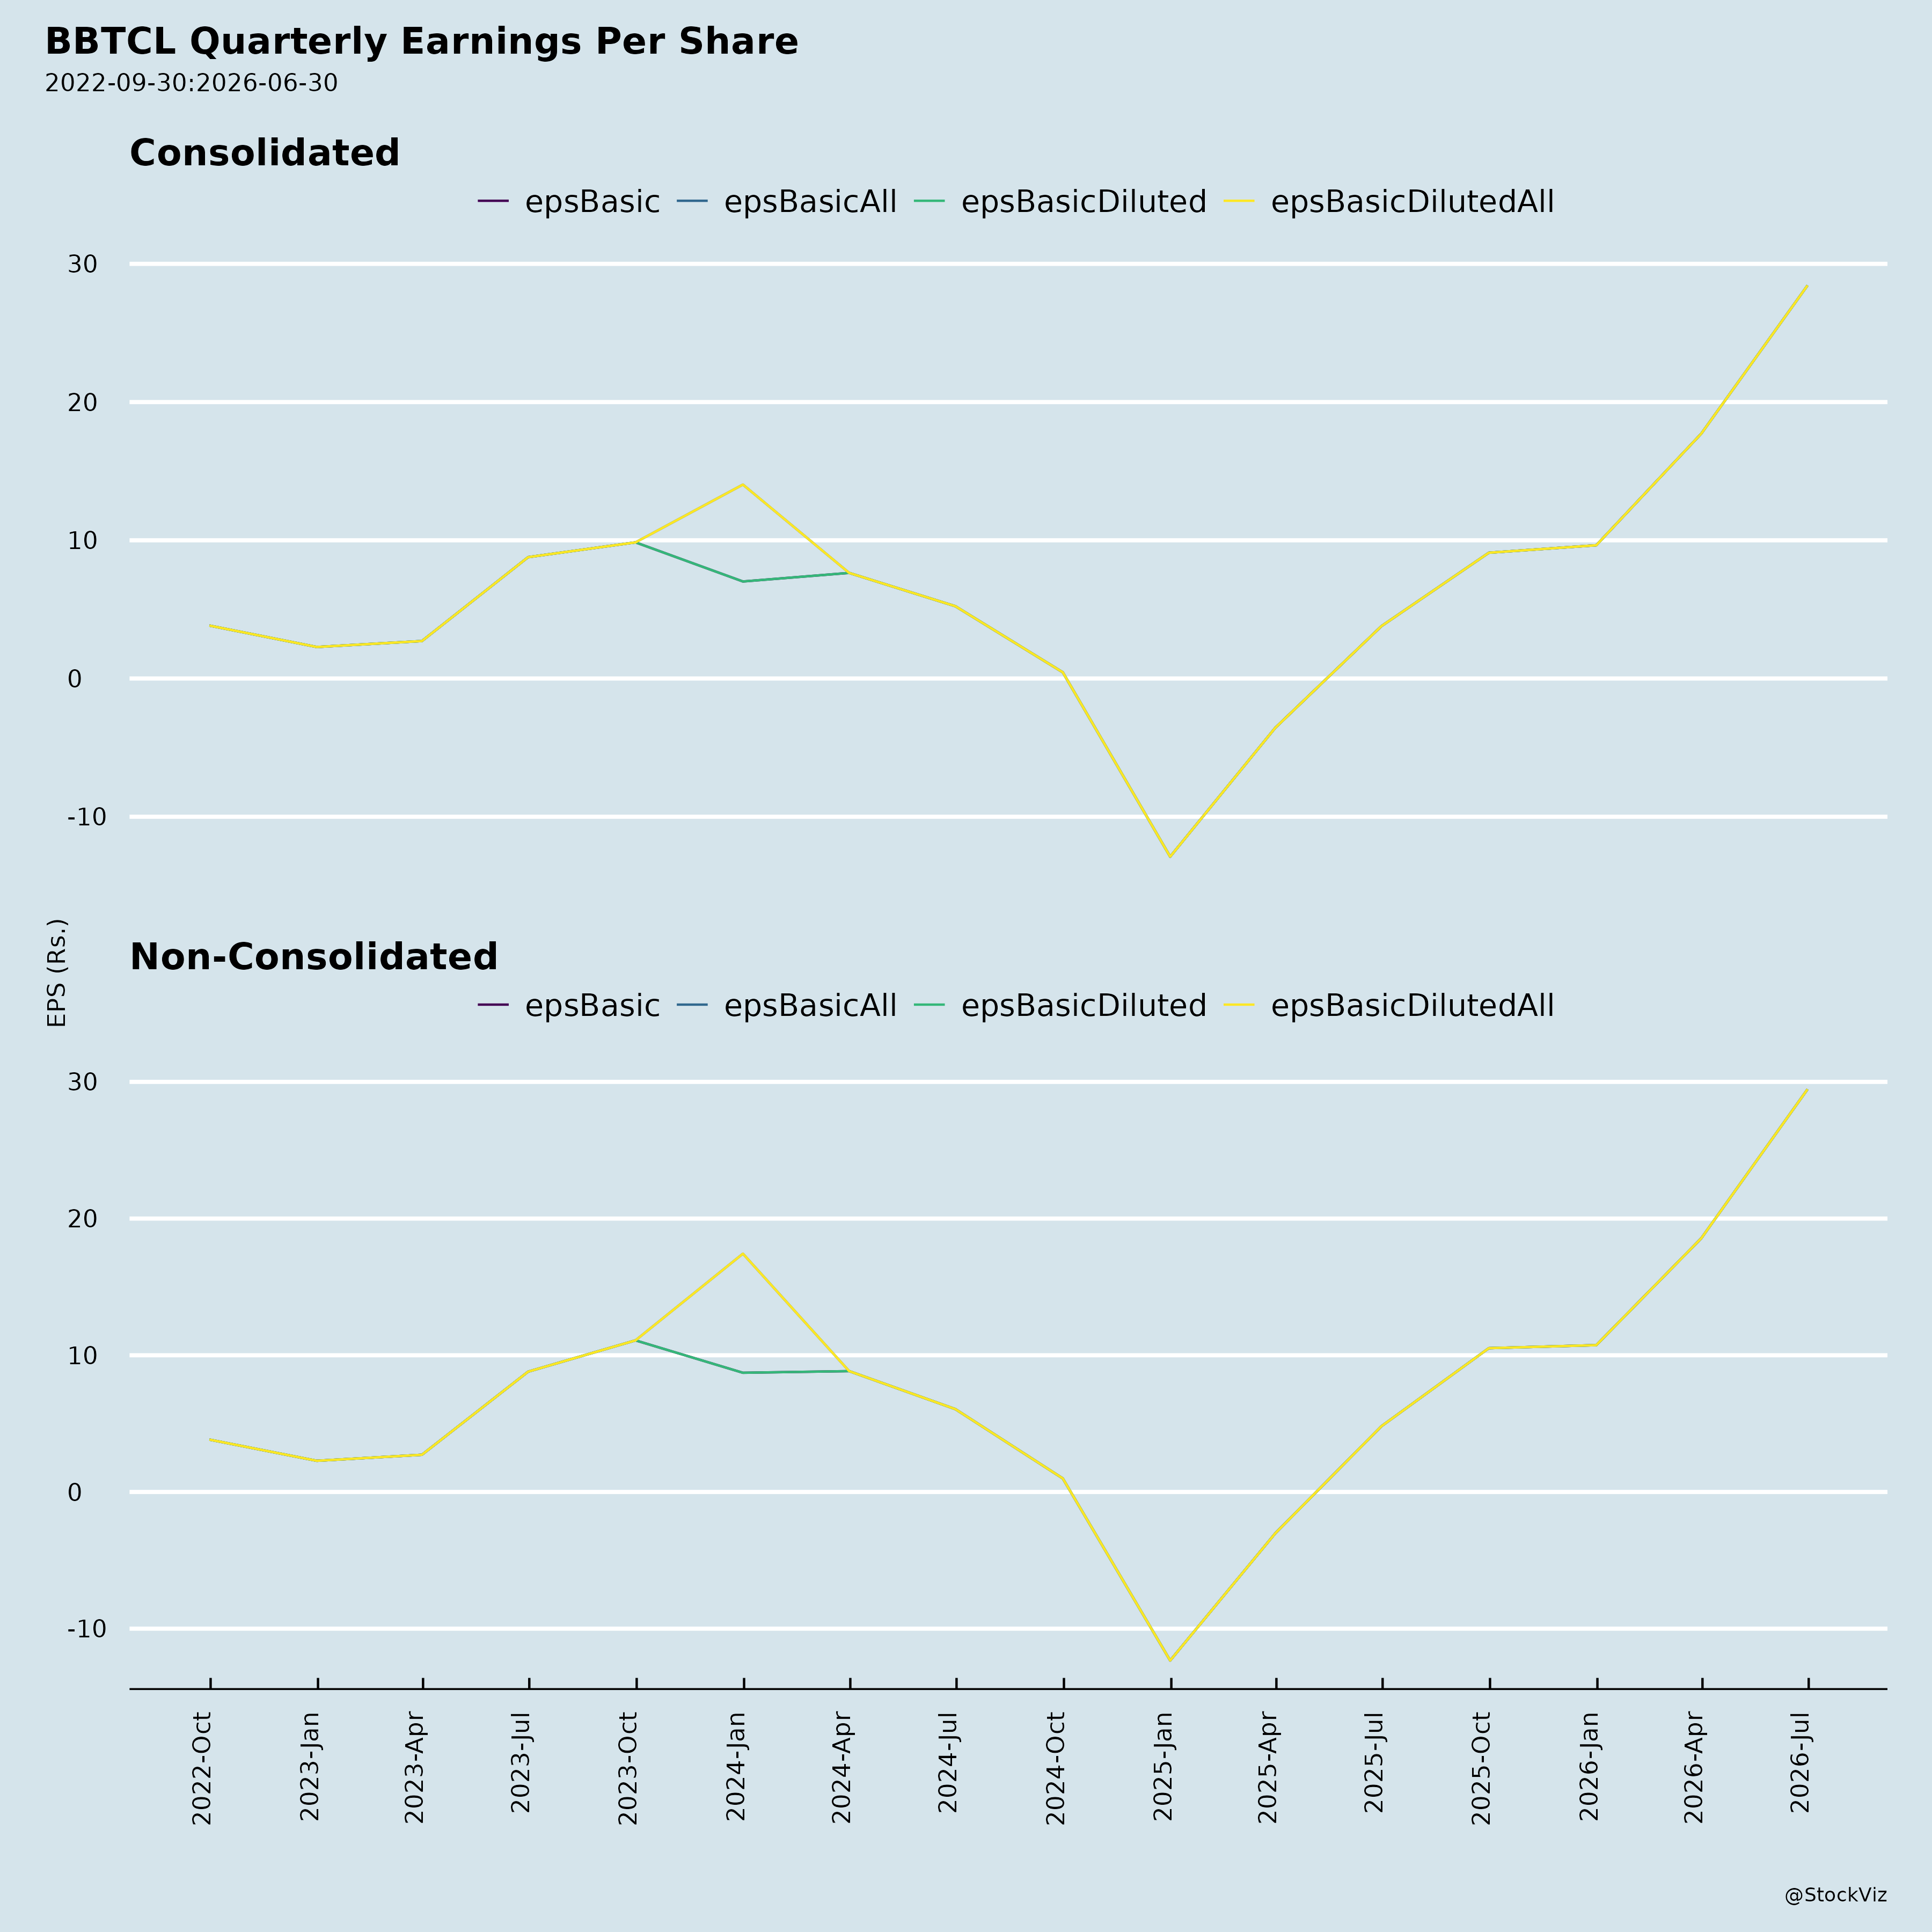
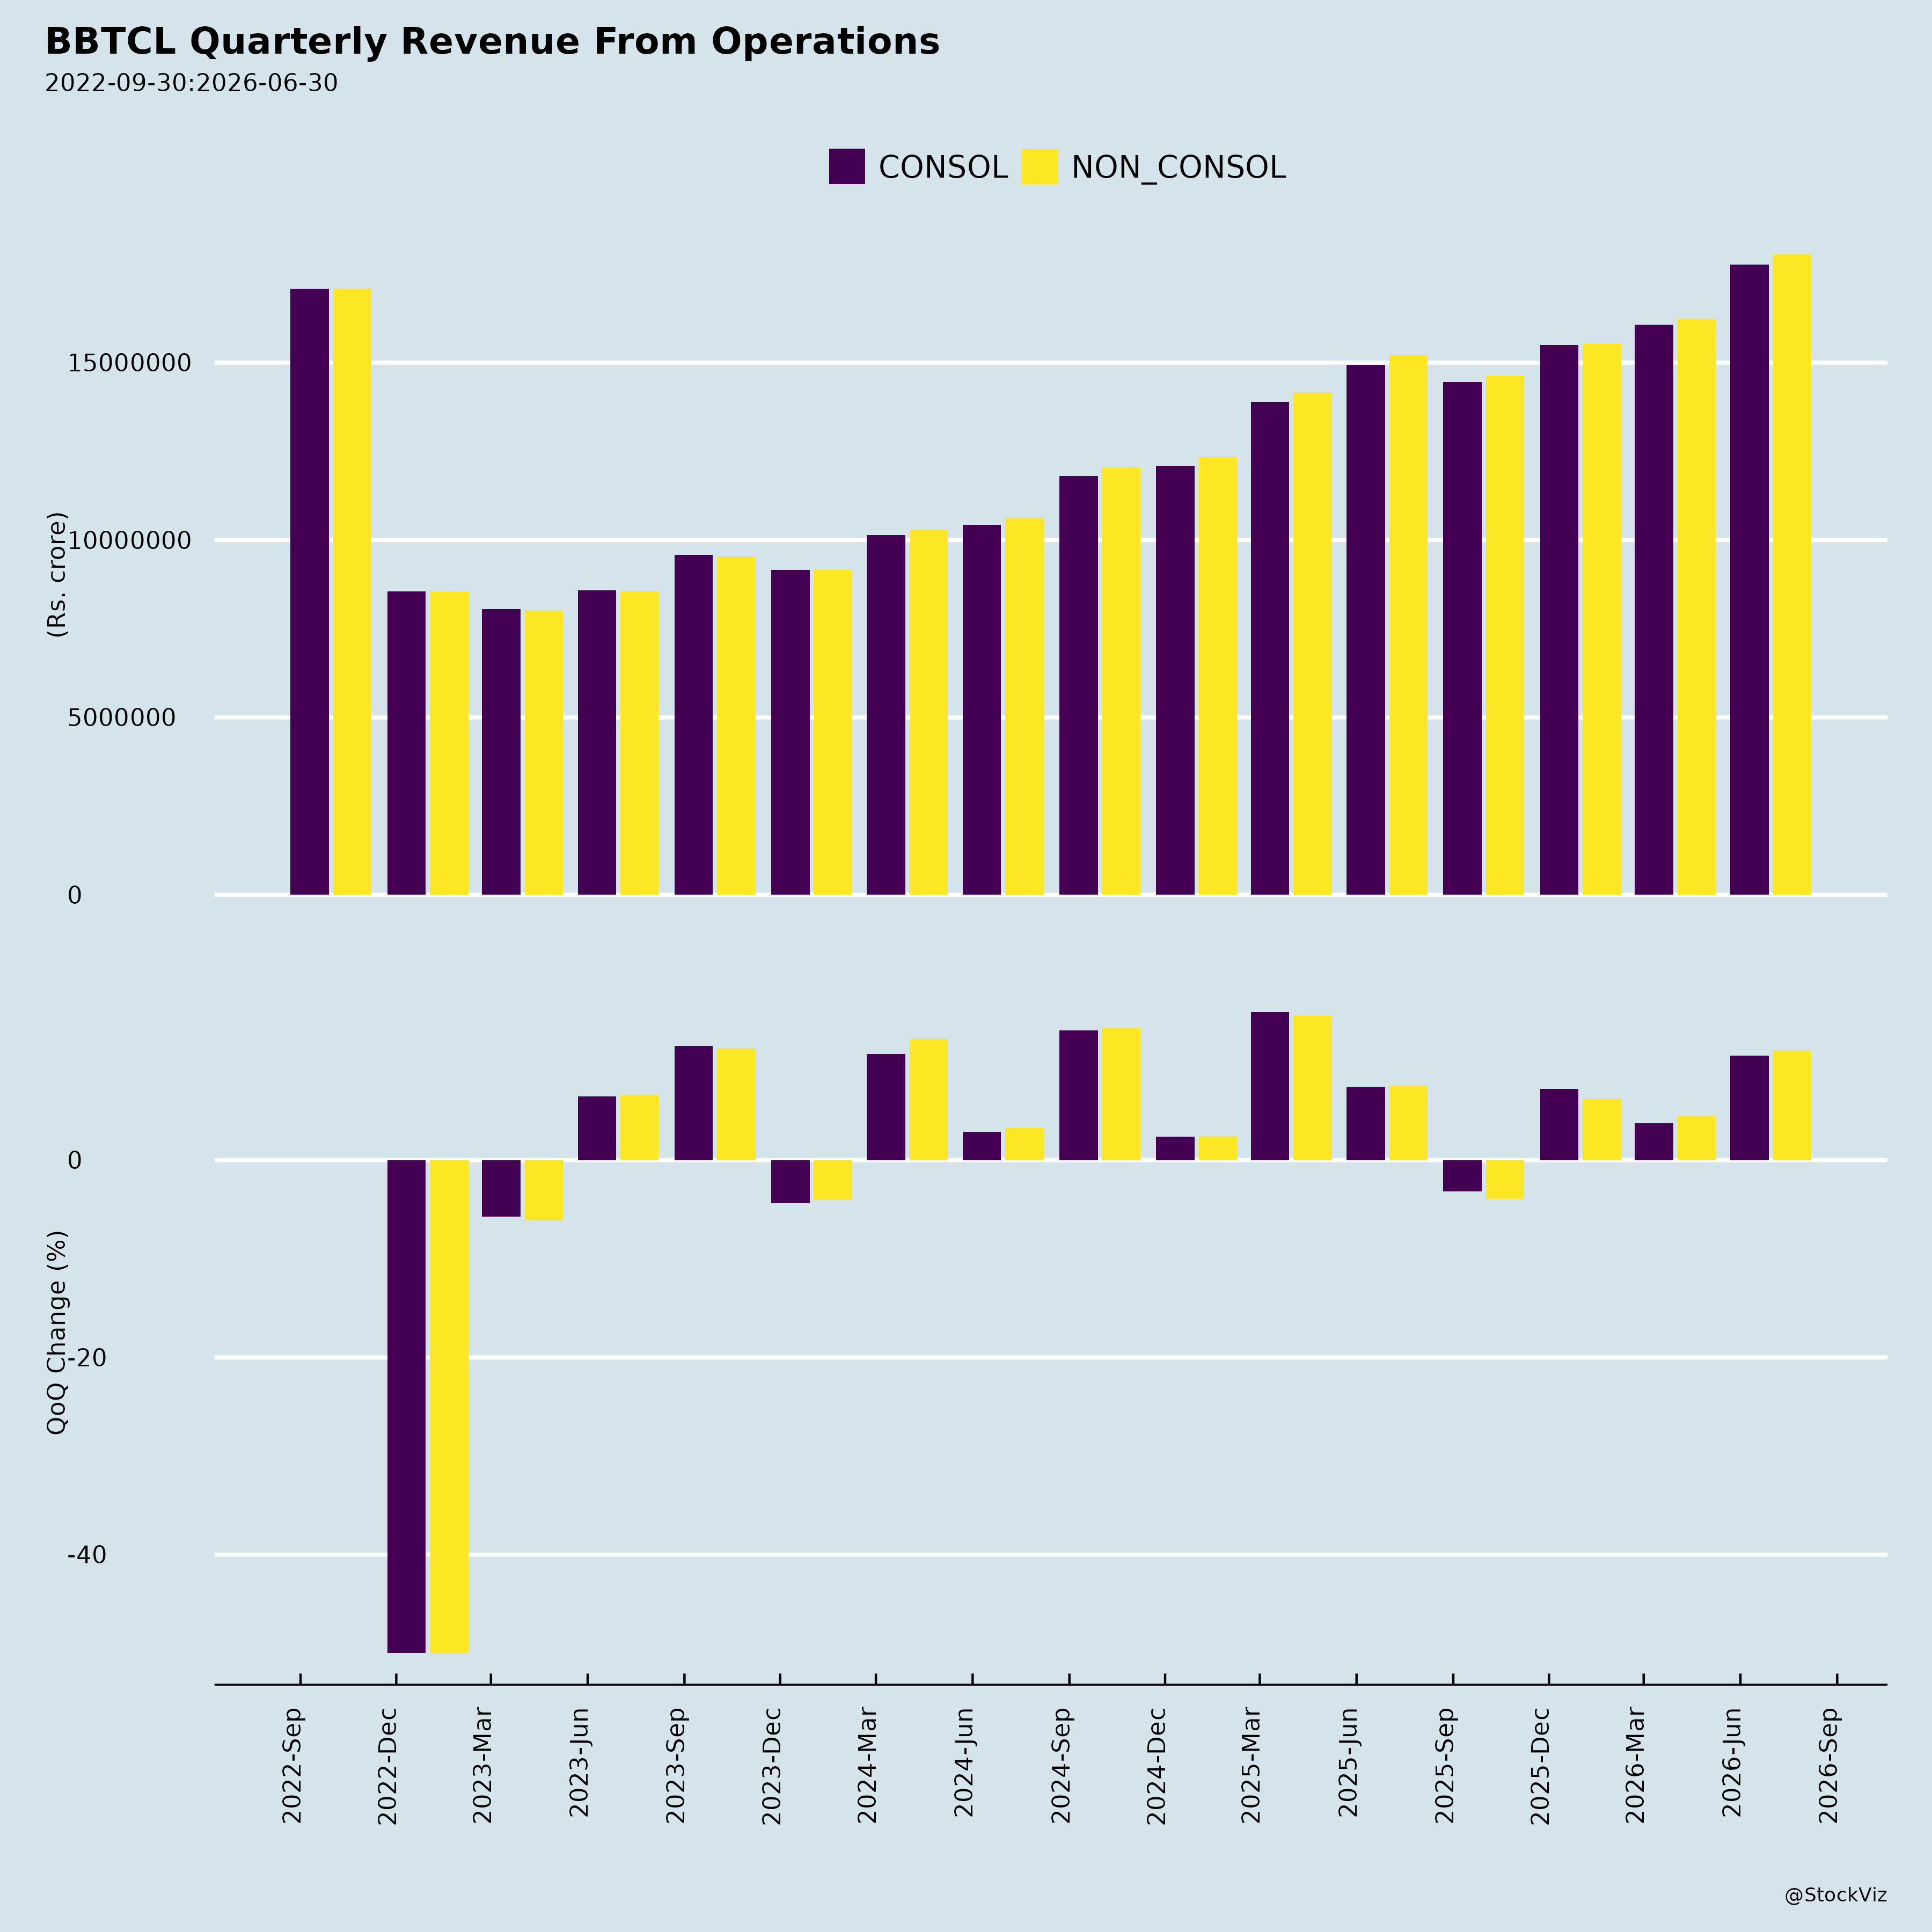
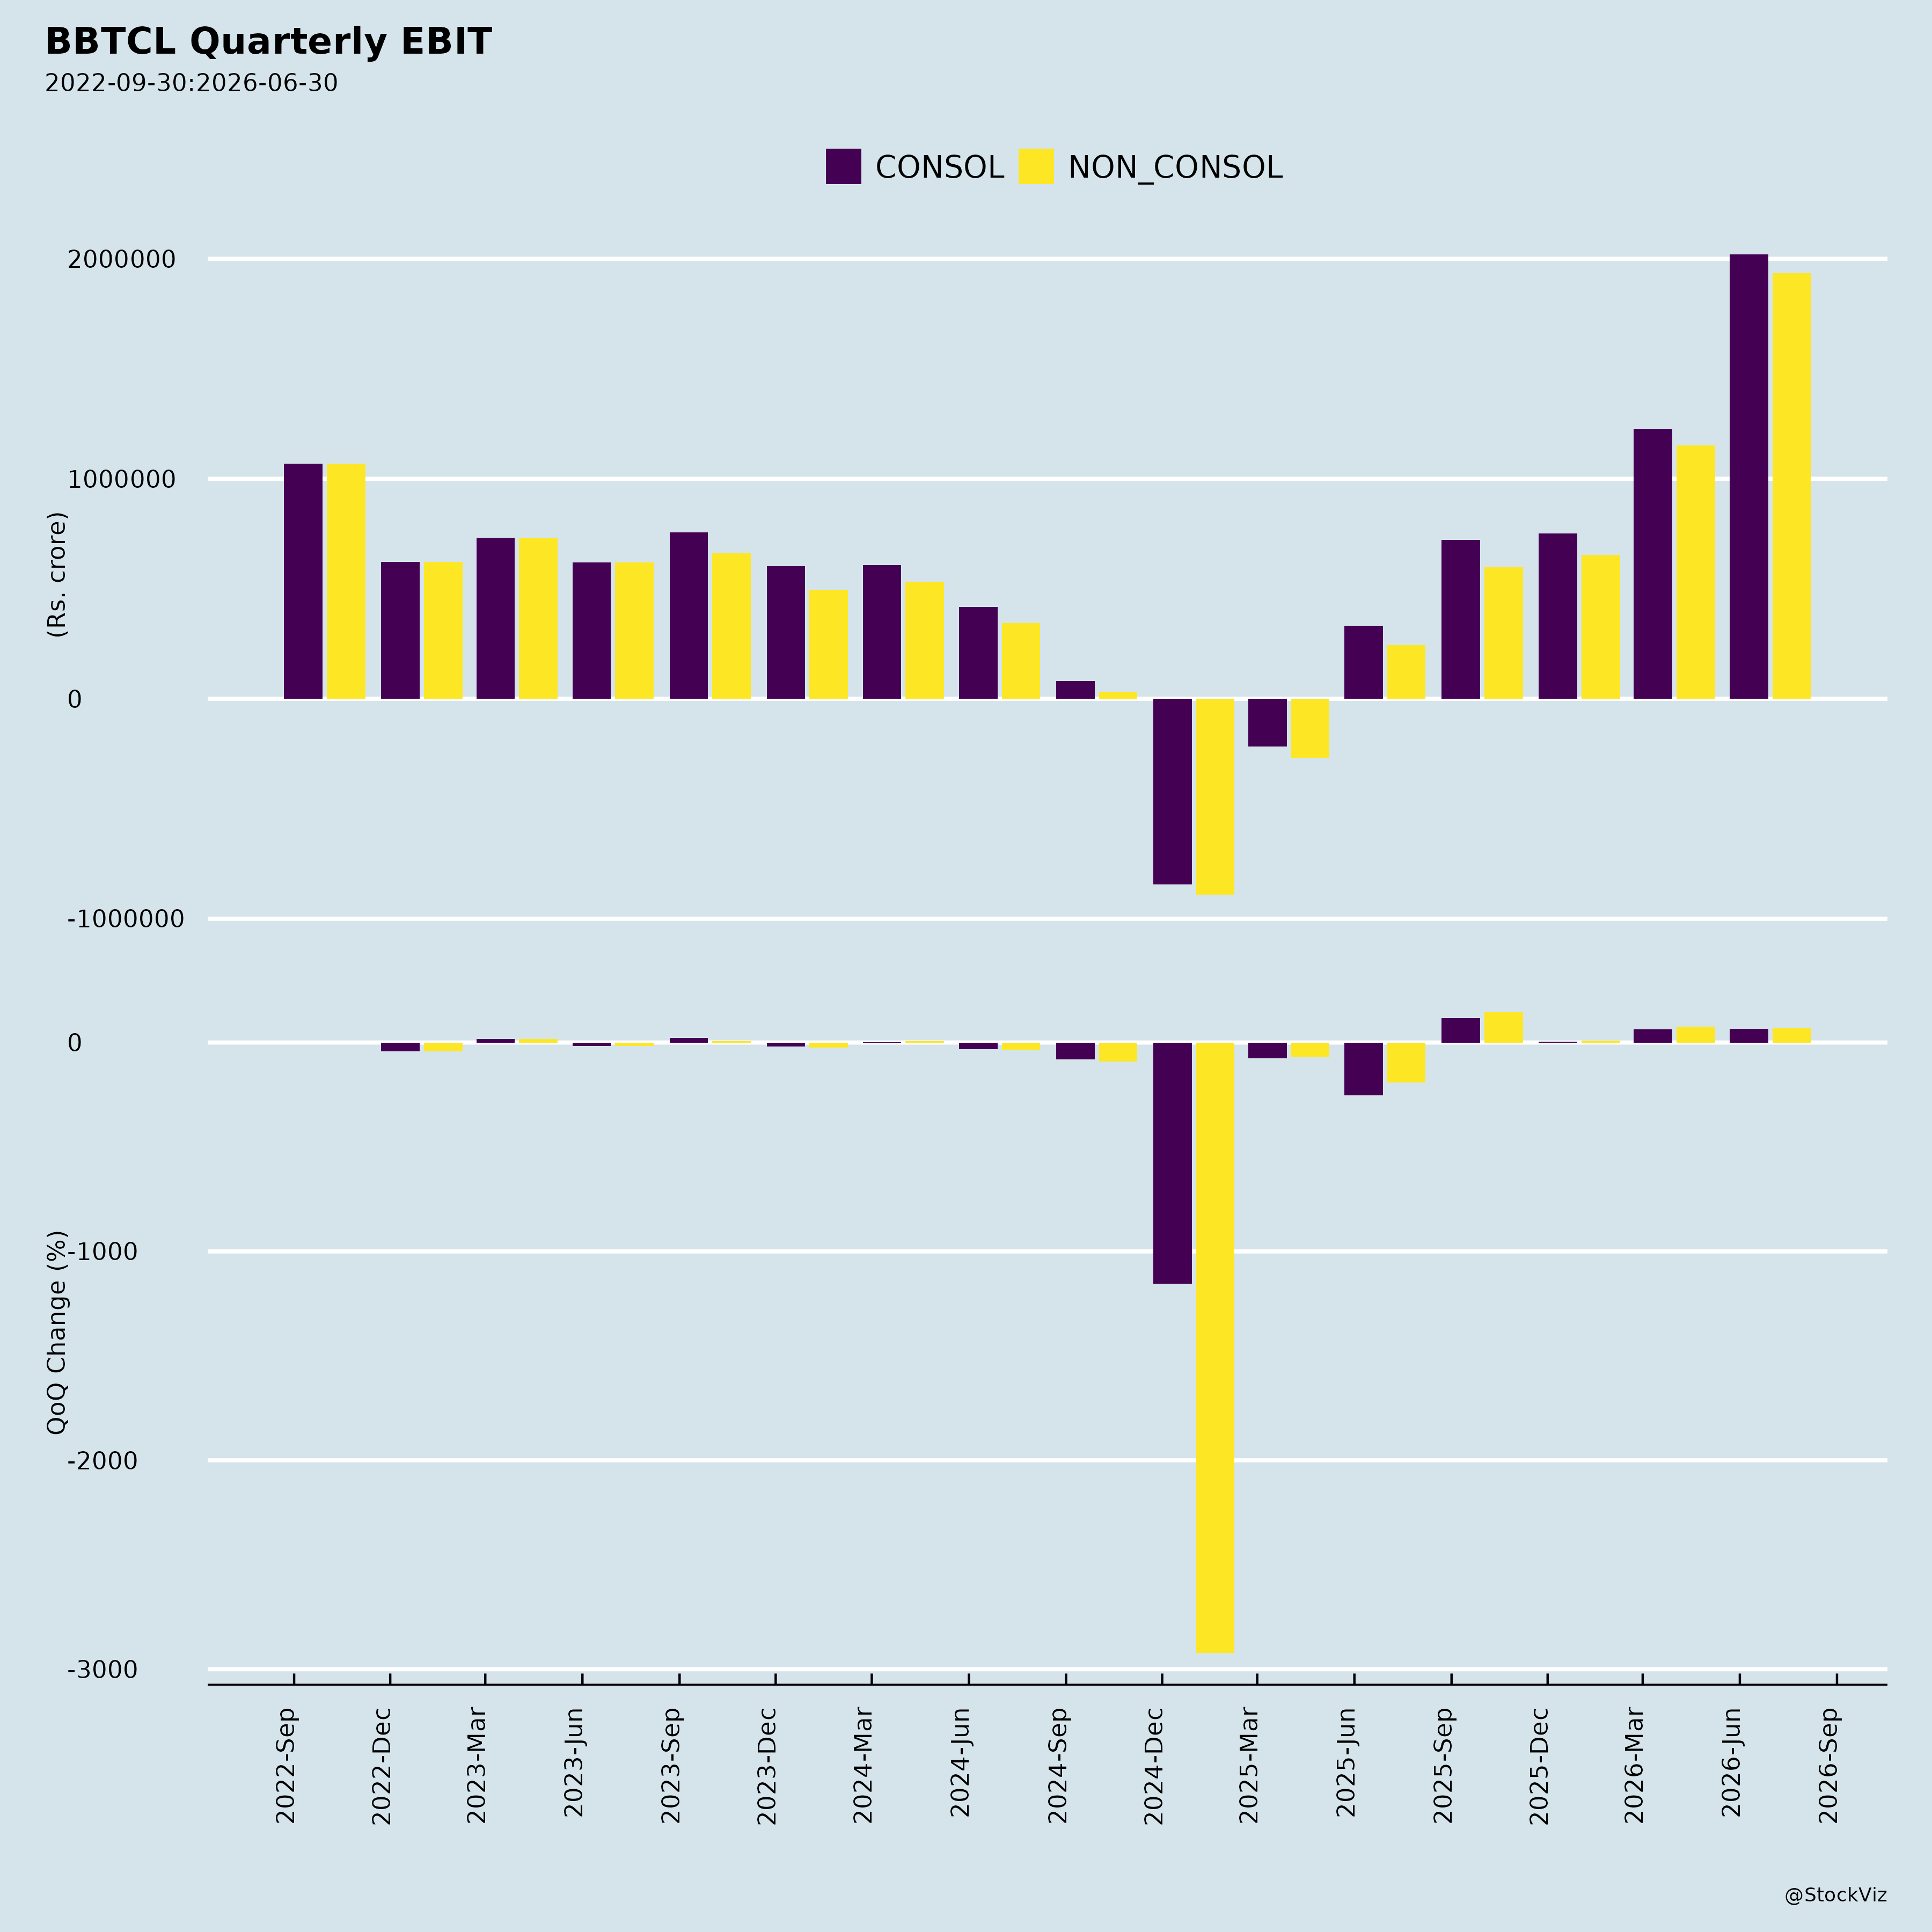
Observed performance (FY 2025-26): - Consolidated revenue from operations: Rs. 61,635.25 lakhs. - Consolidated profit after tax: Rs. 1,969.54 lakhs. - Standalone net profit: Rs. 2,288.81 lakhs, a turnaround from a net loss of Rs. 426.58 lakhs in FY 2024-25.
Dividend and governance actions (August 14, 2026 Board Meeting): - Recommended a final dividend of ₹1.00 per equity share of face value ₹10 each for FY 2025-26, subject to AGM approval. - Recommended a final dividend of 1.5% on preference shares of ₹1,000 each for FY 2025-26. - Record date for dividend entitlement: Friday, September 18, 2026. - 15th AGM scheduled for Wednesday, September 30, 2026 at 3:00 P.M. at the registered office in Anekal Taluk, Bangalore. - Mr. Yuvraj V (Finance and Accounts group head) appointed as Internal Auditor for FY 2026-27. - Ms. Sonali M appointed as General Manager, Unit-I, effective August 14, 2026. - Mr. Deorao Jhadu Pathe appointed as General Manager, Unit-IV, effective August 14, 2026.
The FY 2025-26 results reflect a return to profitability on a standalone basis, while the “20 IN 27” target sets a clear capacity and throughput ambition for the coming years.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.