BANKINDIA
Equity Metrics
November 18, 2026
Bank of India
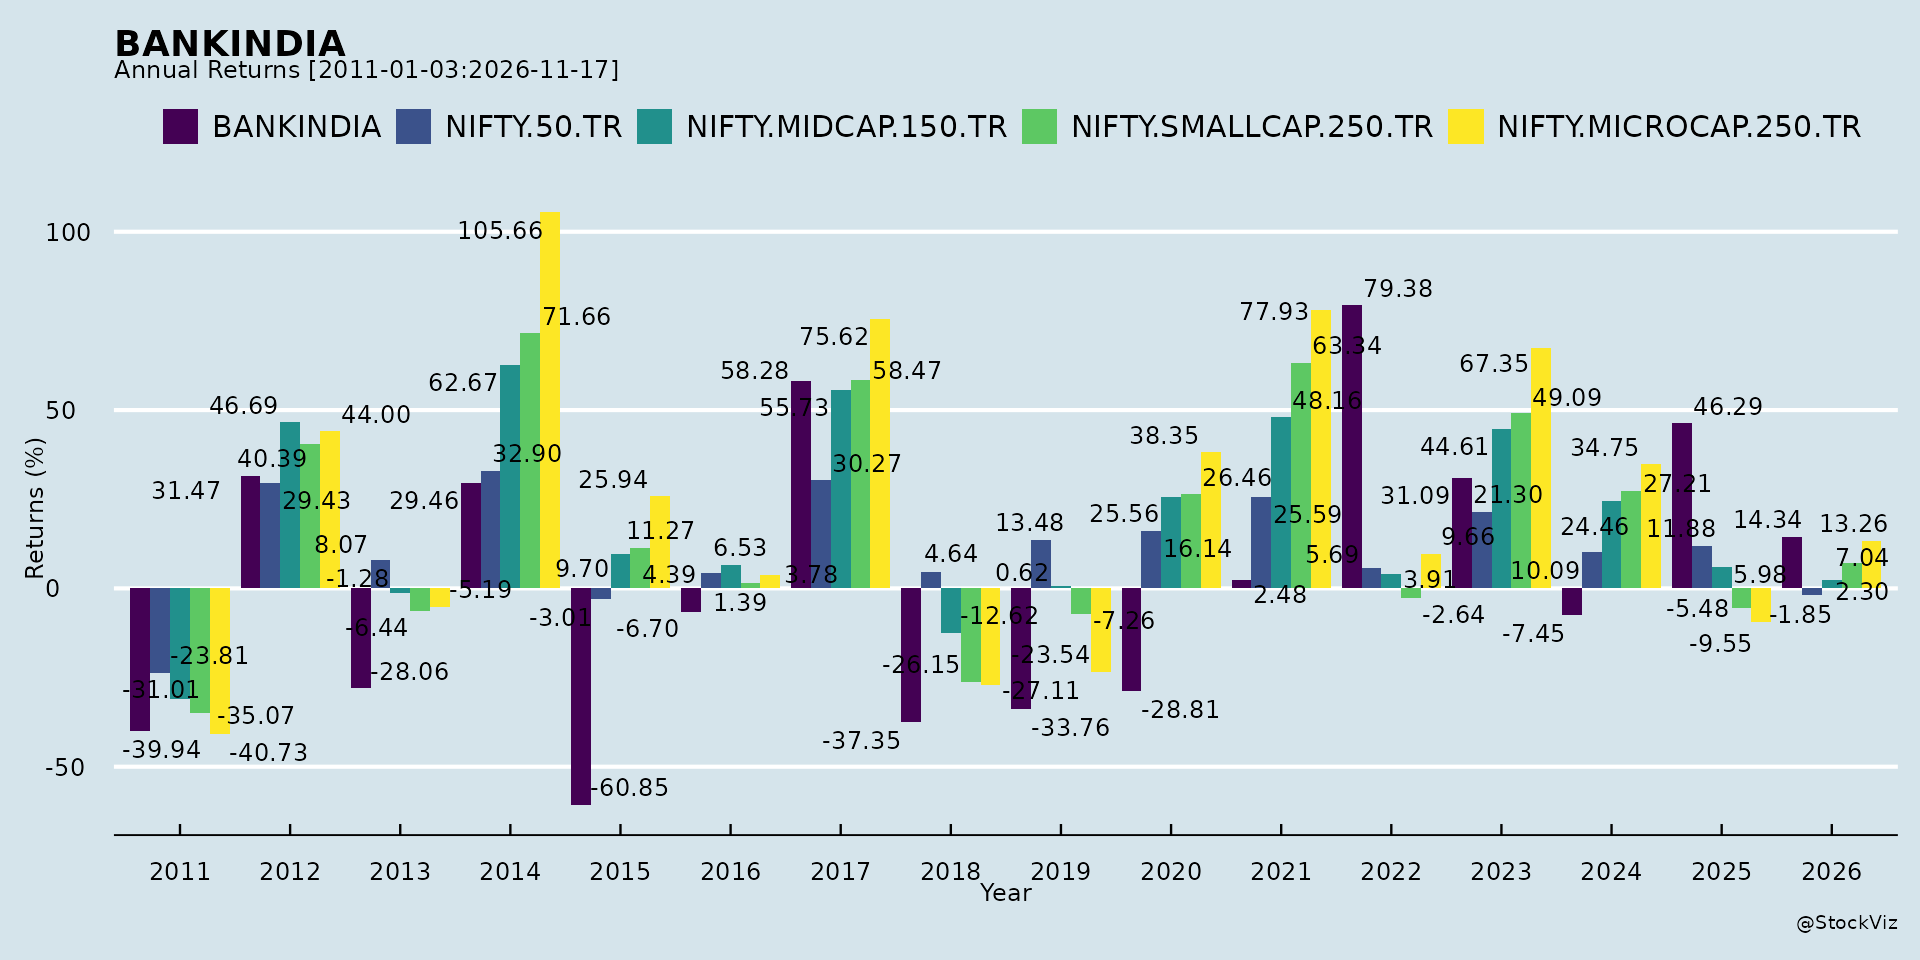
Annual Returns
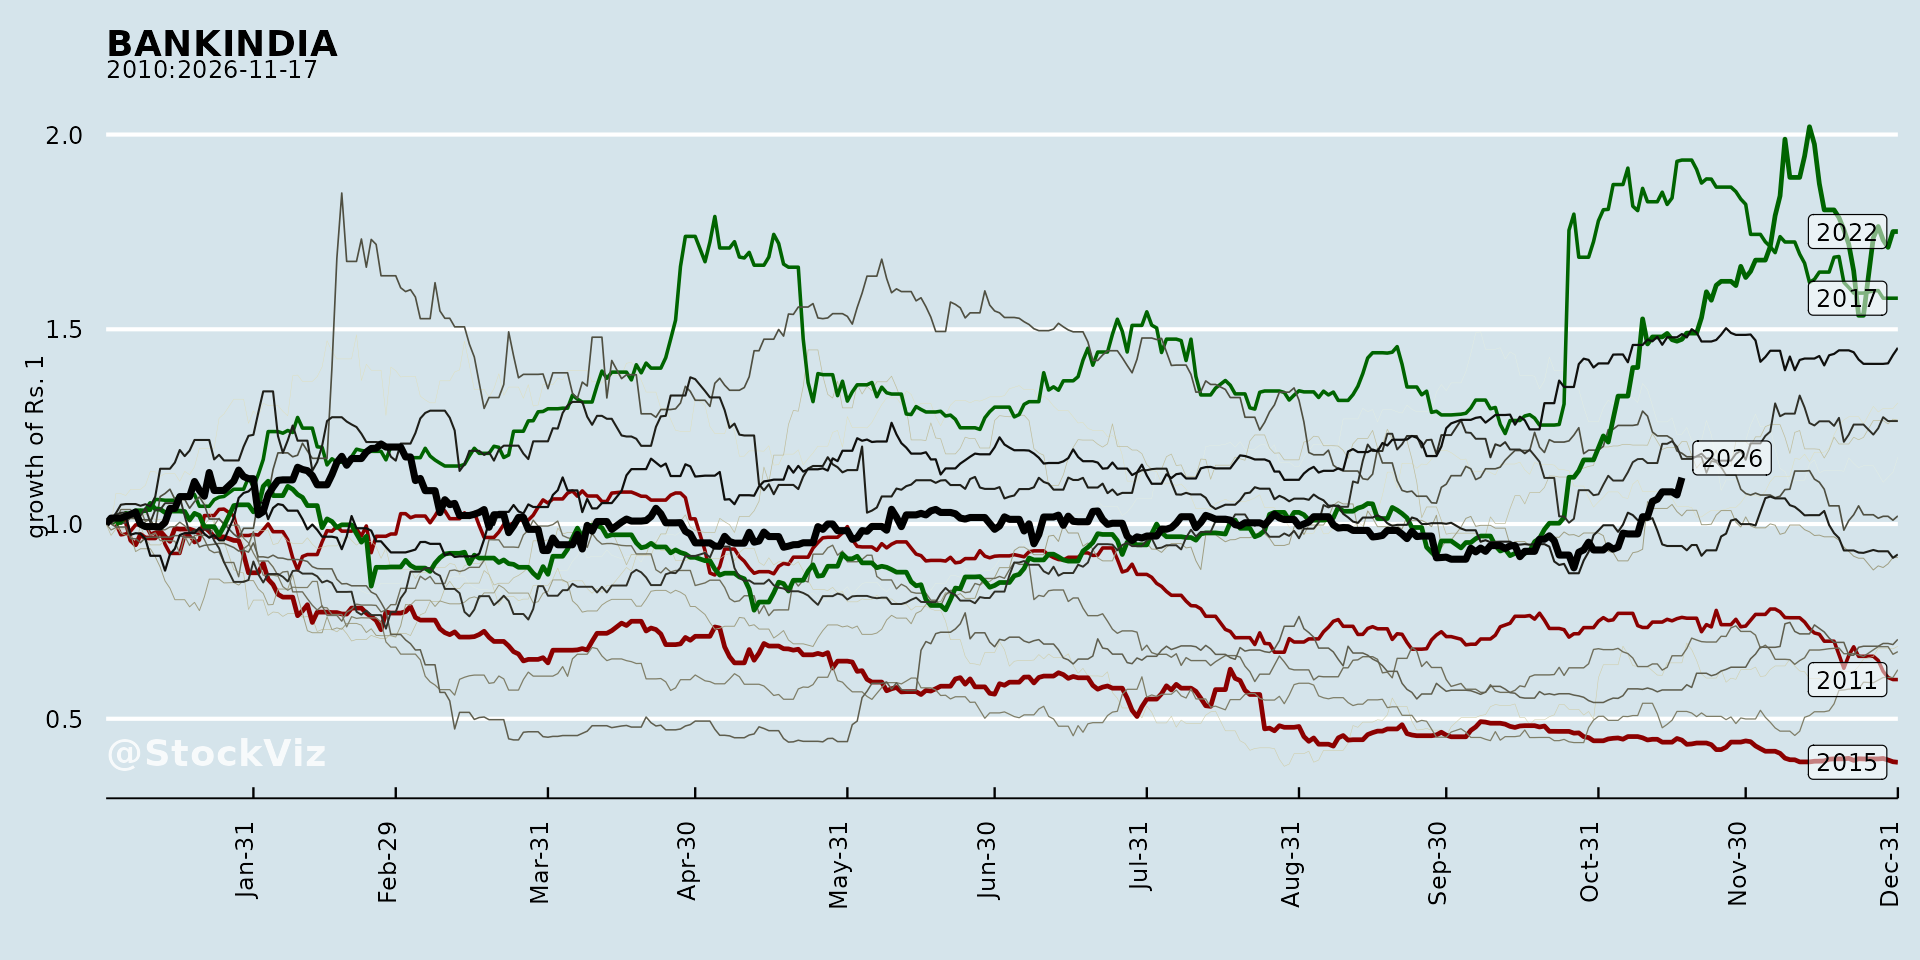
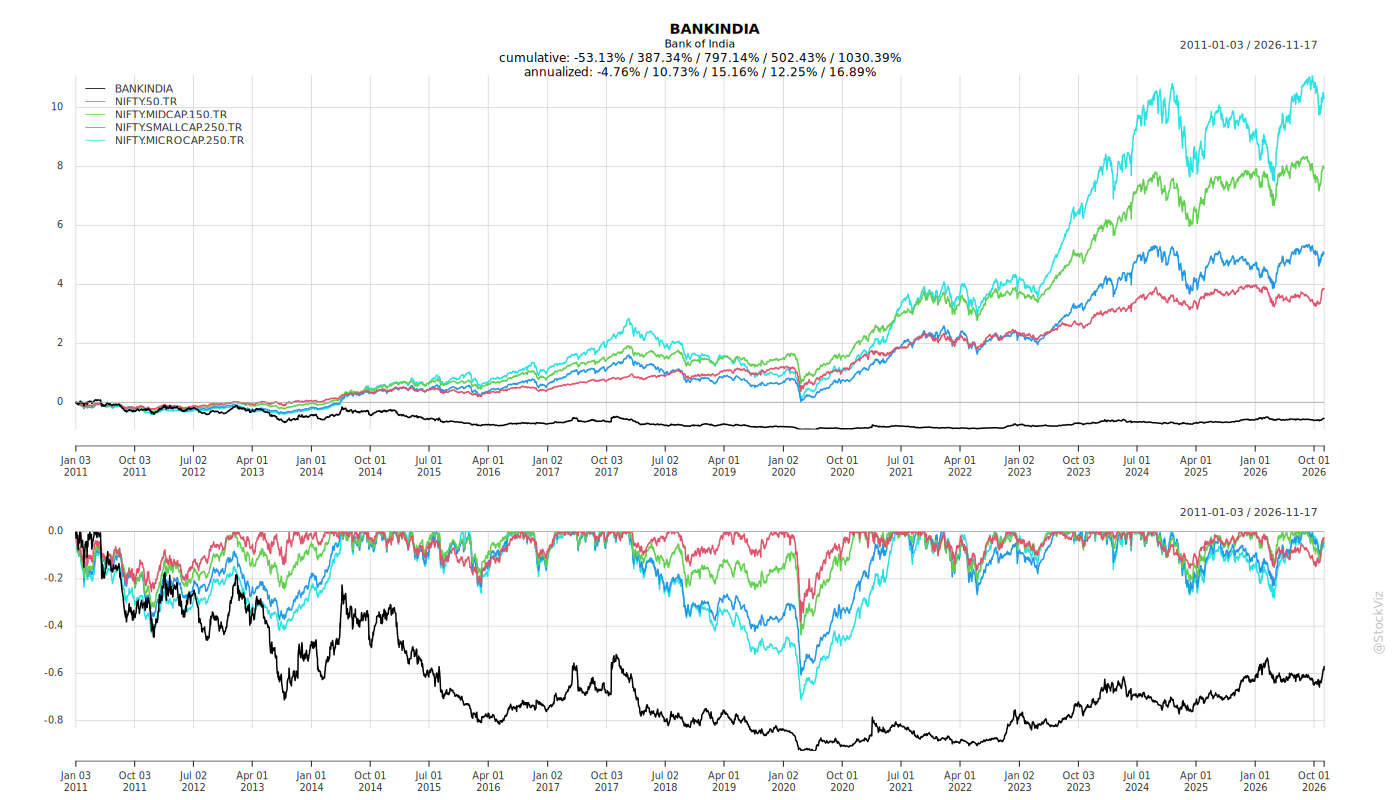
Cumulative Returns and Drawdowns
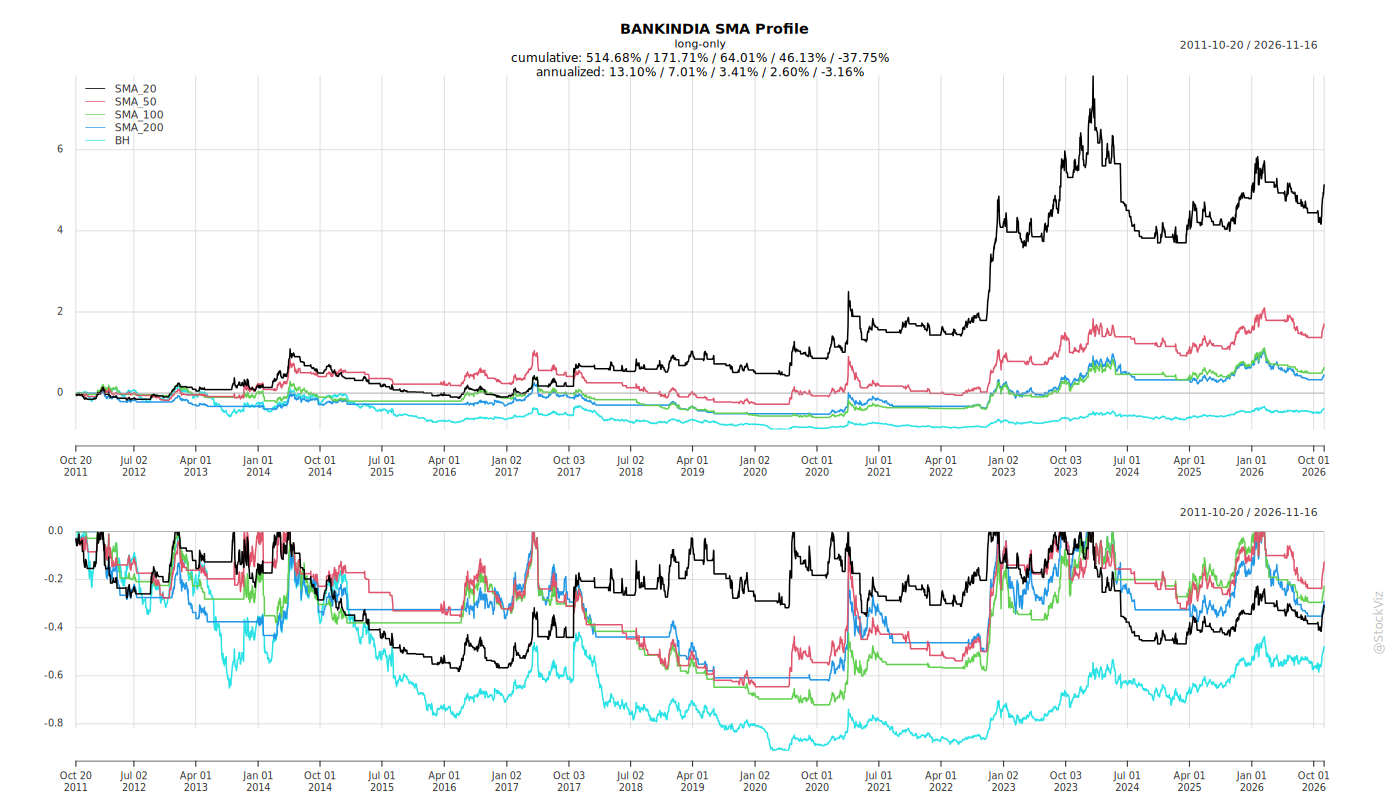
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
BANKINDIA: Recent Corporate Announcements Analysis
Headwinds and Challenges
The bank operates in what its disclosures describe as a dynamic and complex internal and external environment. Forward-looking statements are subject to risks and uncertainties that could cause actual results to differ materially, including market, business, and legal risks; changes in law; future levels of non-performing loans; the impact of acquisitions; allowance for credit losses; provisioning policies; technological implementation and changes; actual growth in demand for banking products and services; investment income; cash flow projections; and exposure to market risks.
Tailwinds and Growth Prospects
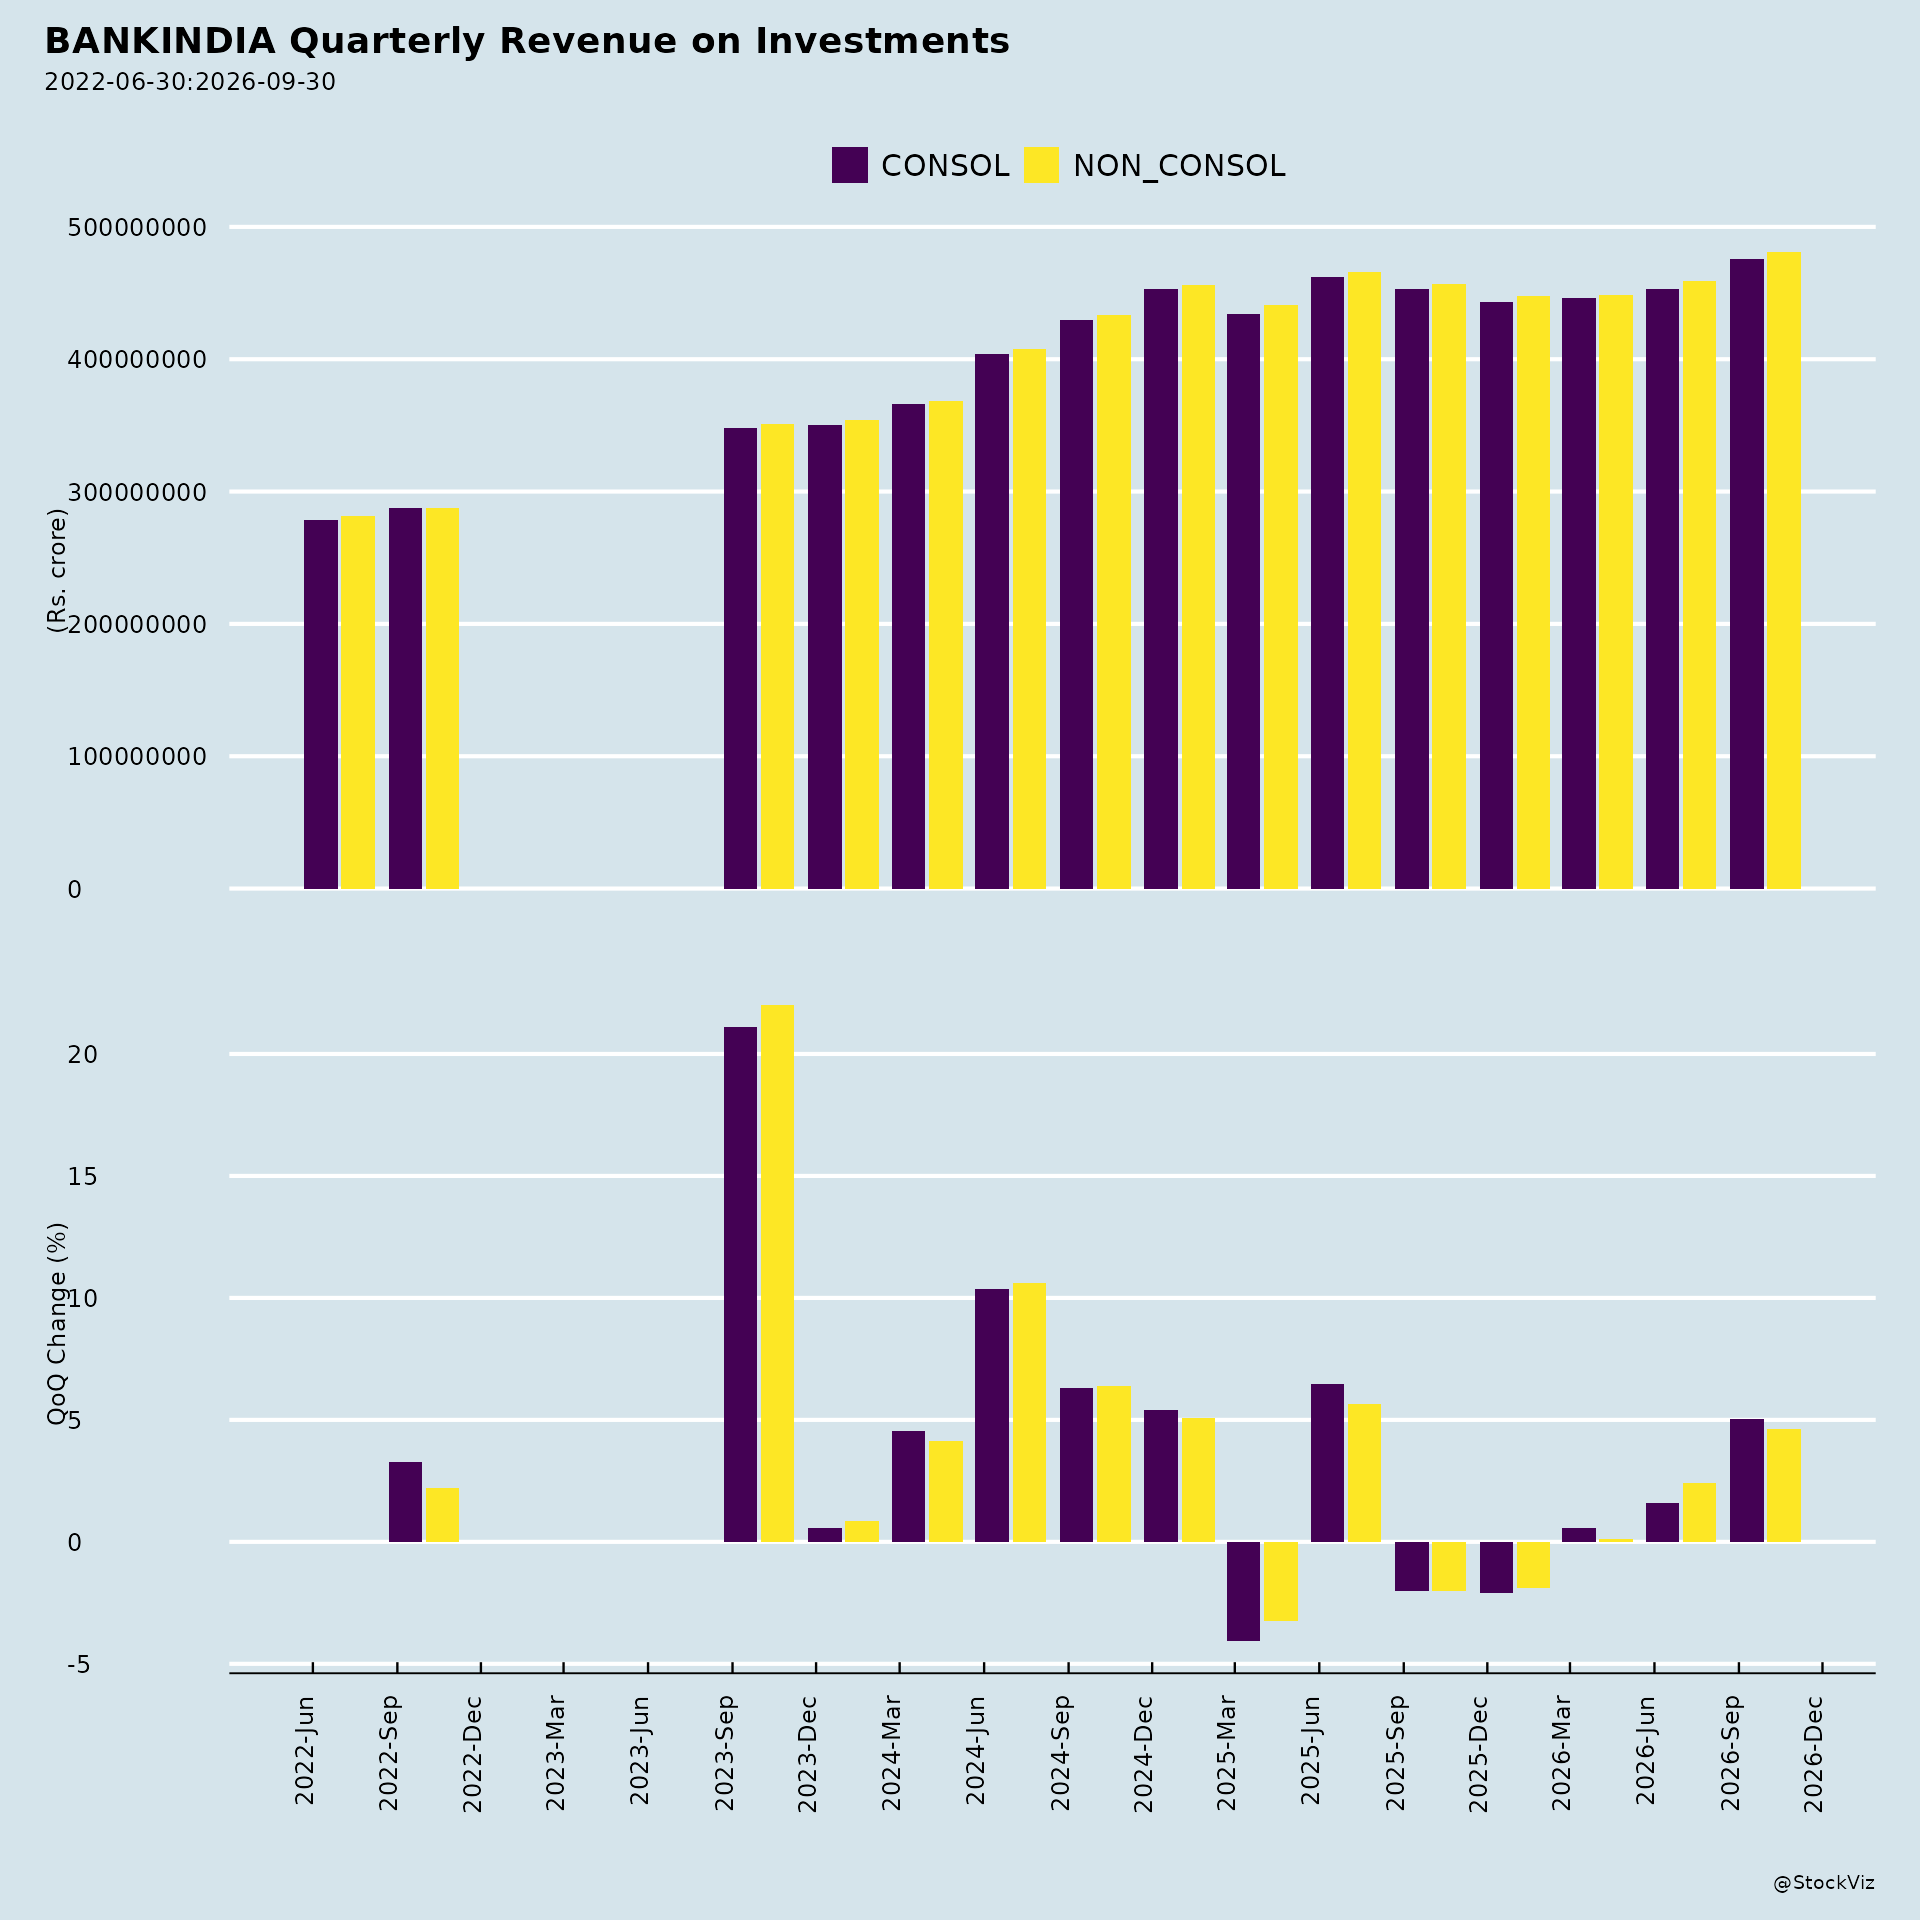
Business expansion (Q1FY27, quarter ended 30.06.2026): - Global Business grew 16.57% YoY to ₹17,55,699 Crore. - Global Deposits grew 14.90% YoY to ₹9,57,924 Crore. - Global Advances grew 18.64% YoY to ₹7,97,775 Crore. - RAM Advances grew 19.75% YoY, constituting 58.30% of advances. - Retail Credit grew 20.60% YoY; MSME Advances grew 19.34% YoY; Agriculture Credit grew 18.92% YoY. - Domestic Deposits grew 16.15% YoY; Domestic Advances grew 19.20% YoY. - Overseas Deposits grew 7.73% YoY; Overseas Advances grew 15.67% YoY.
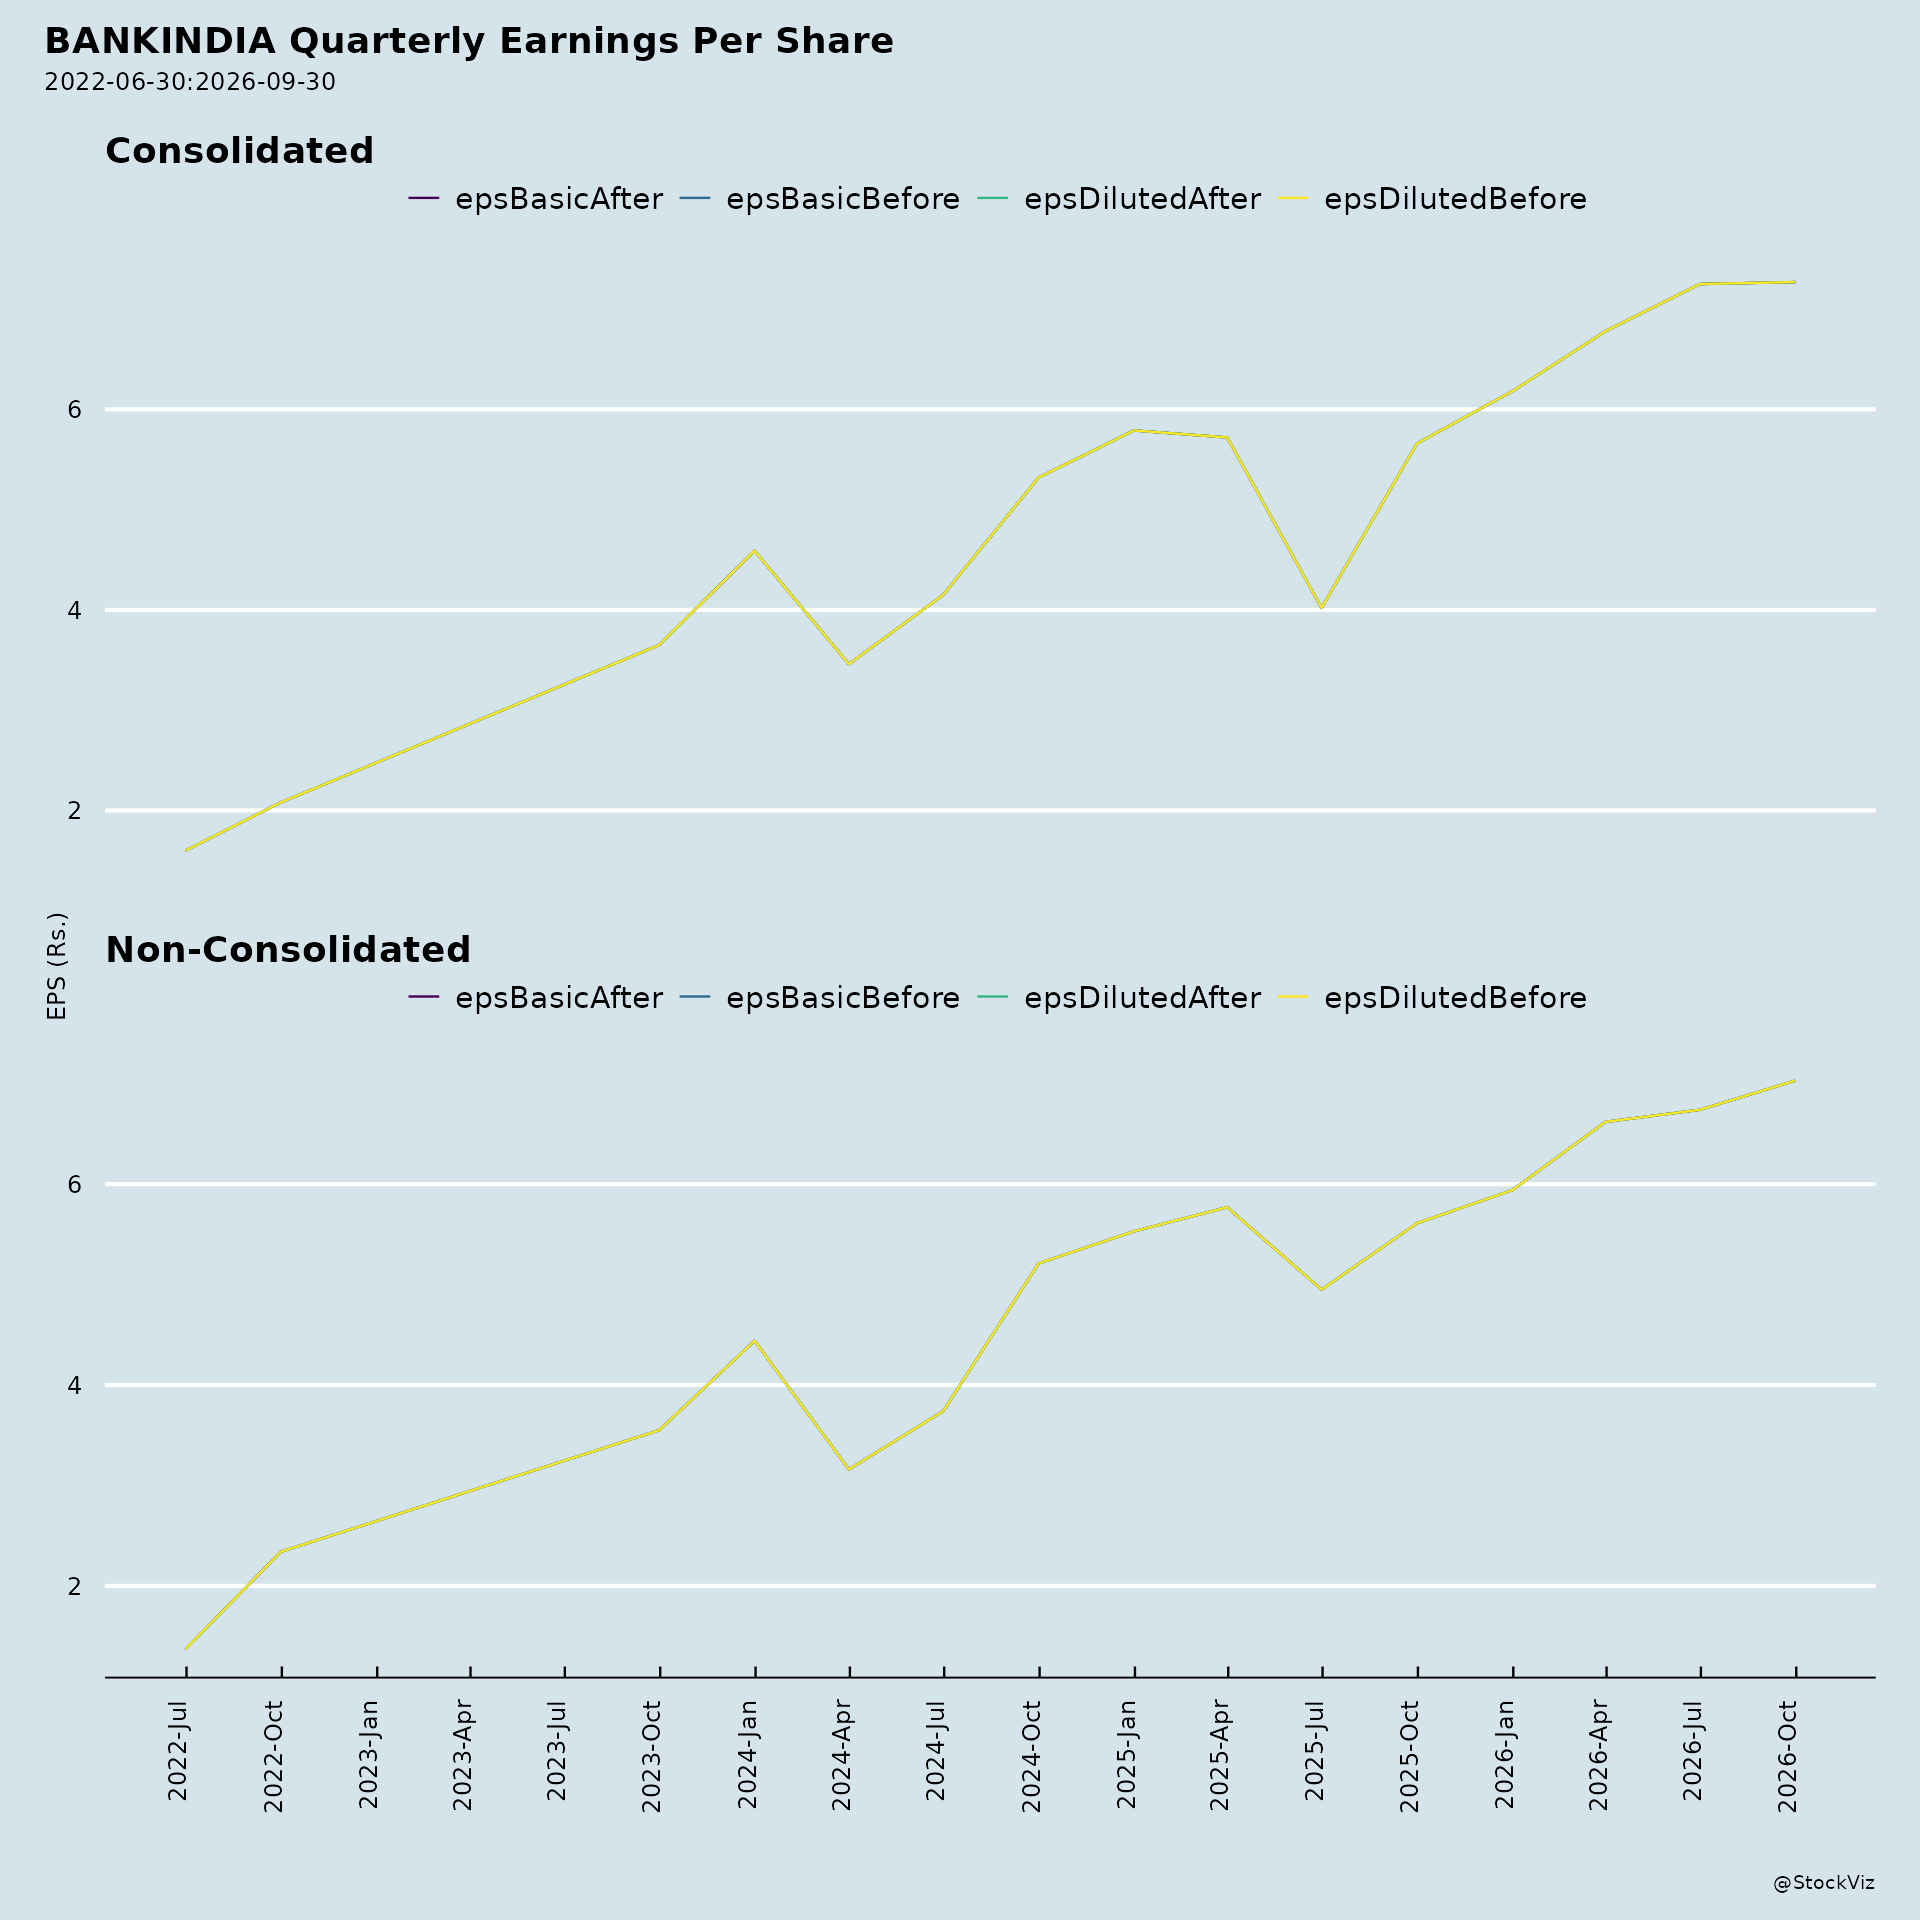
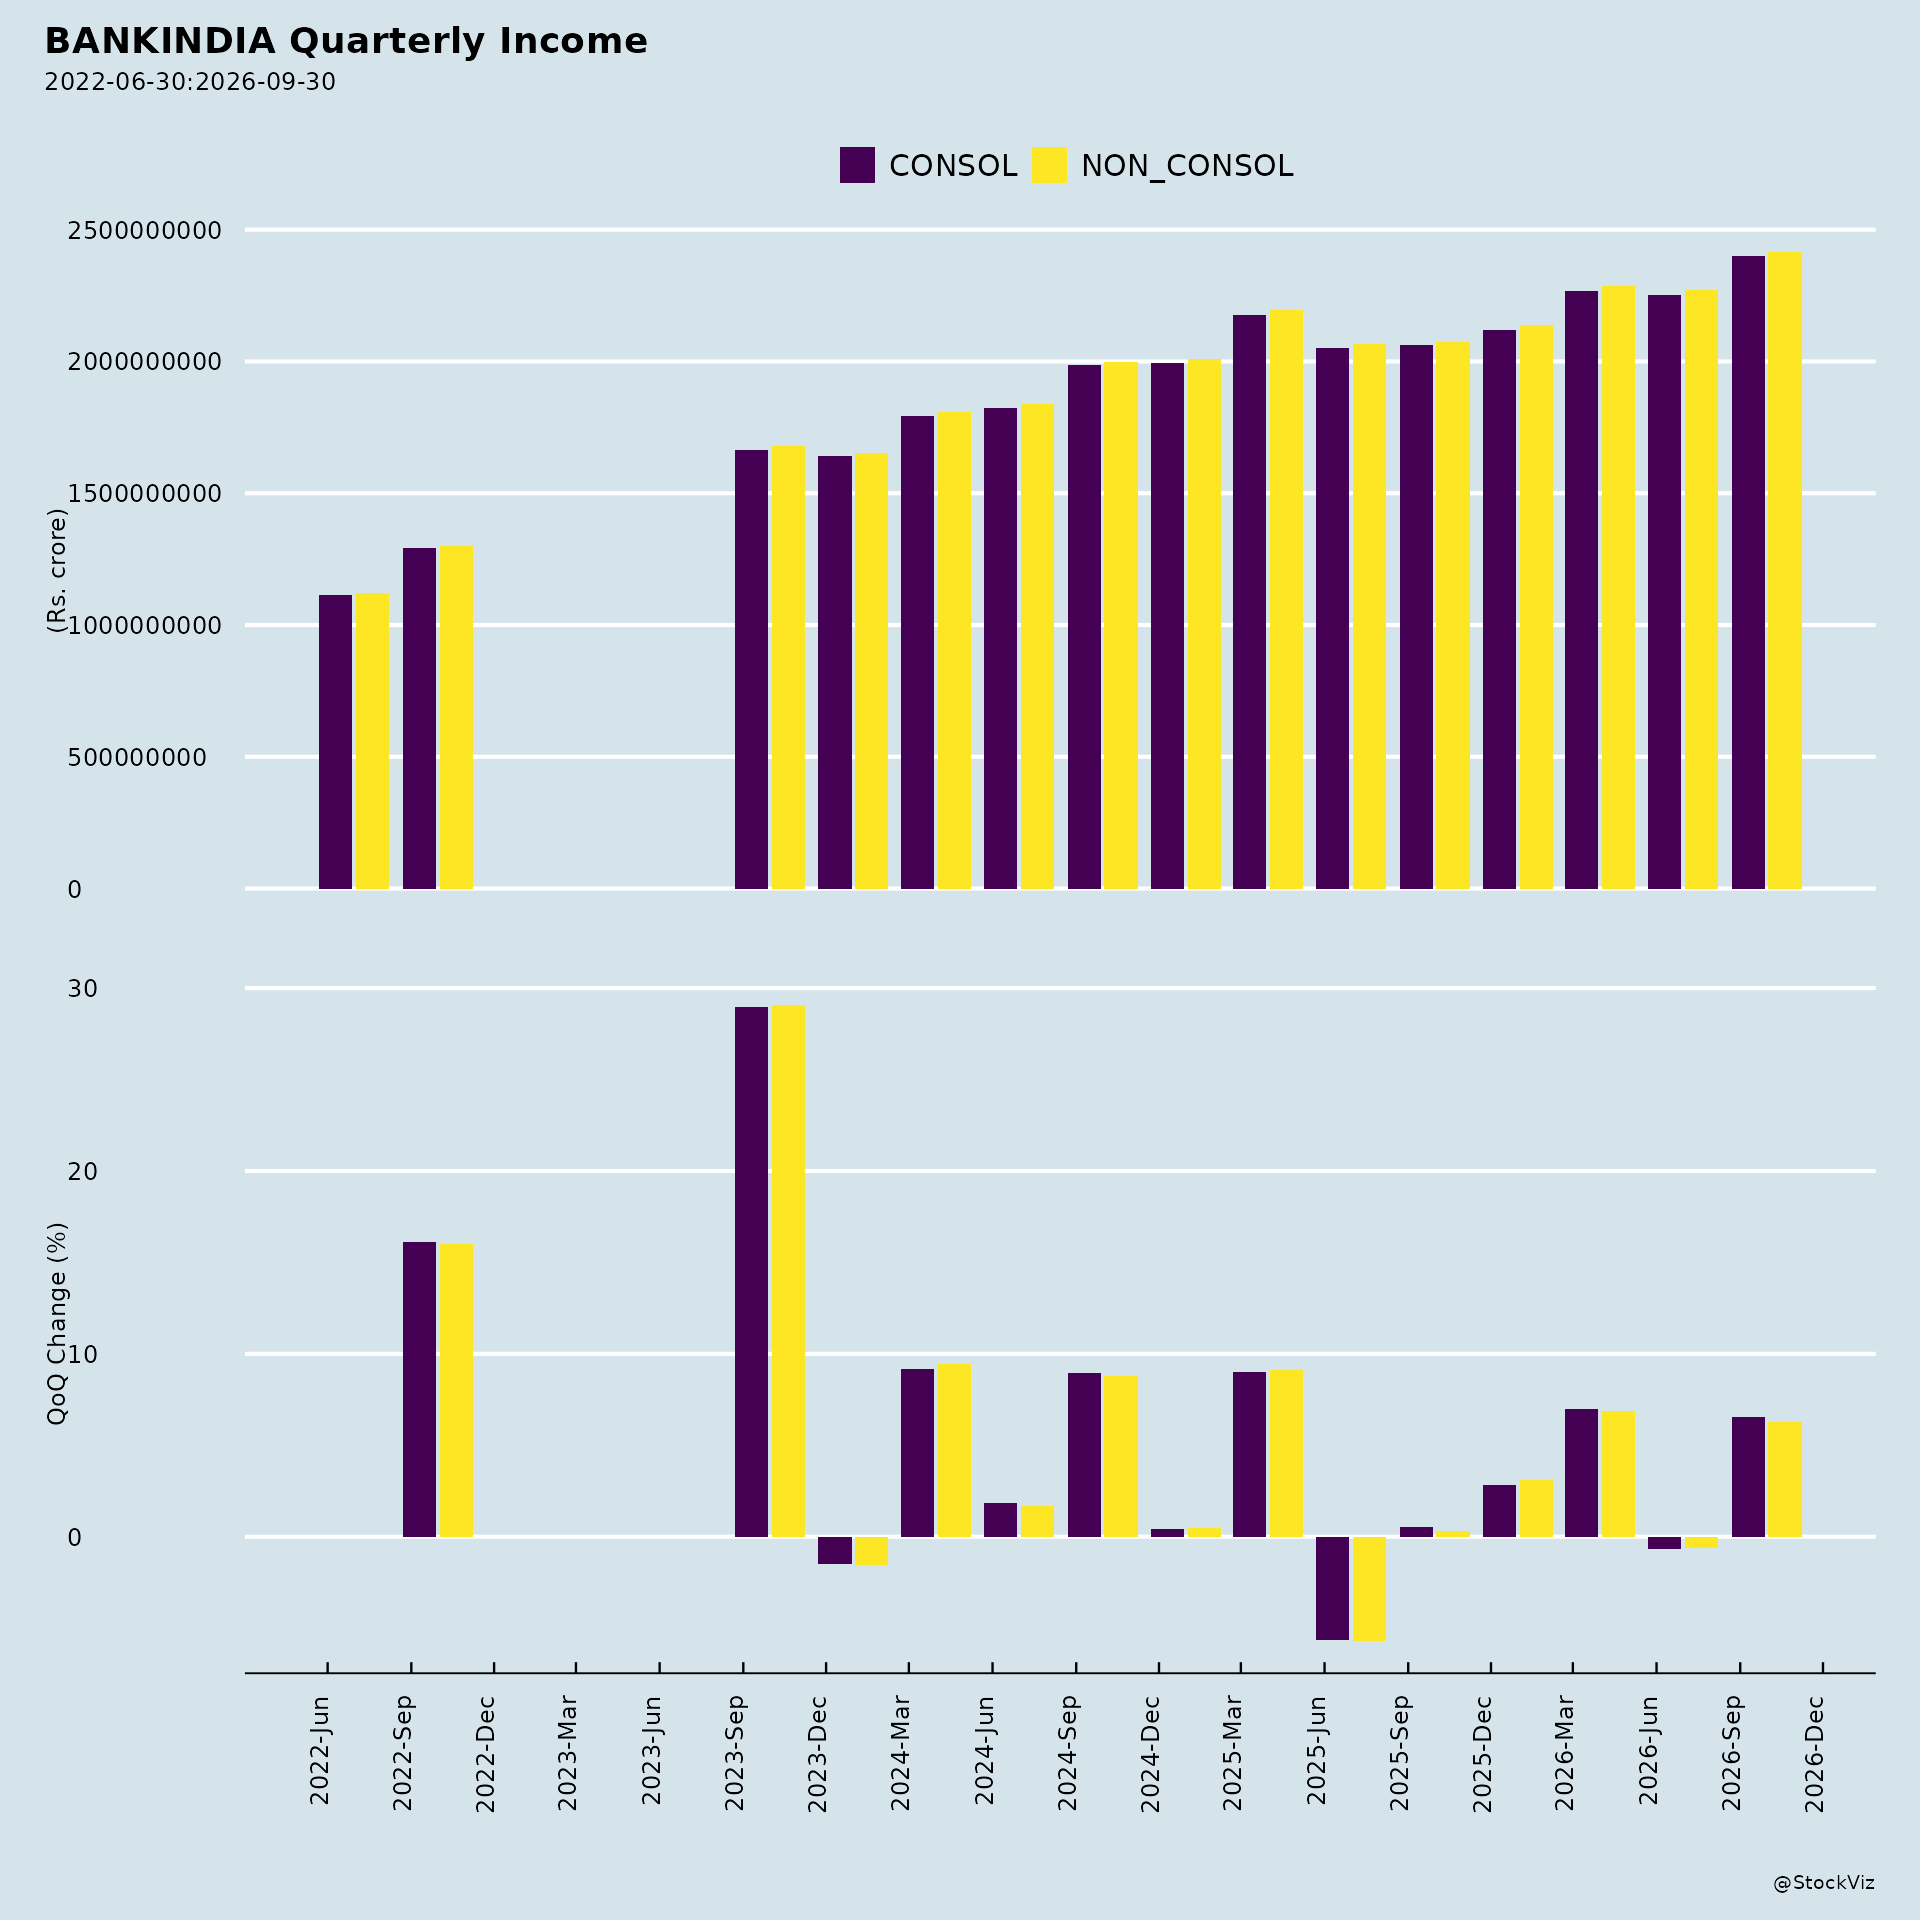
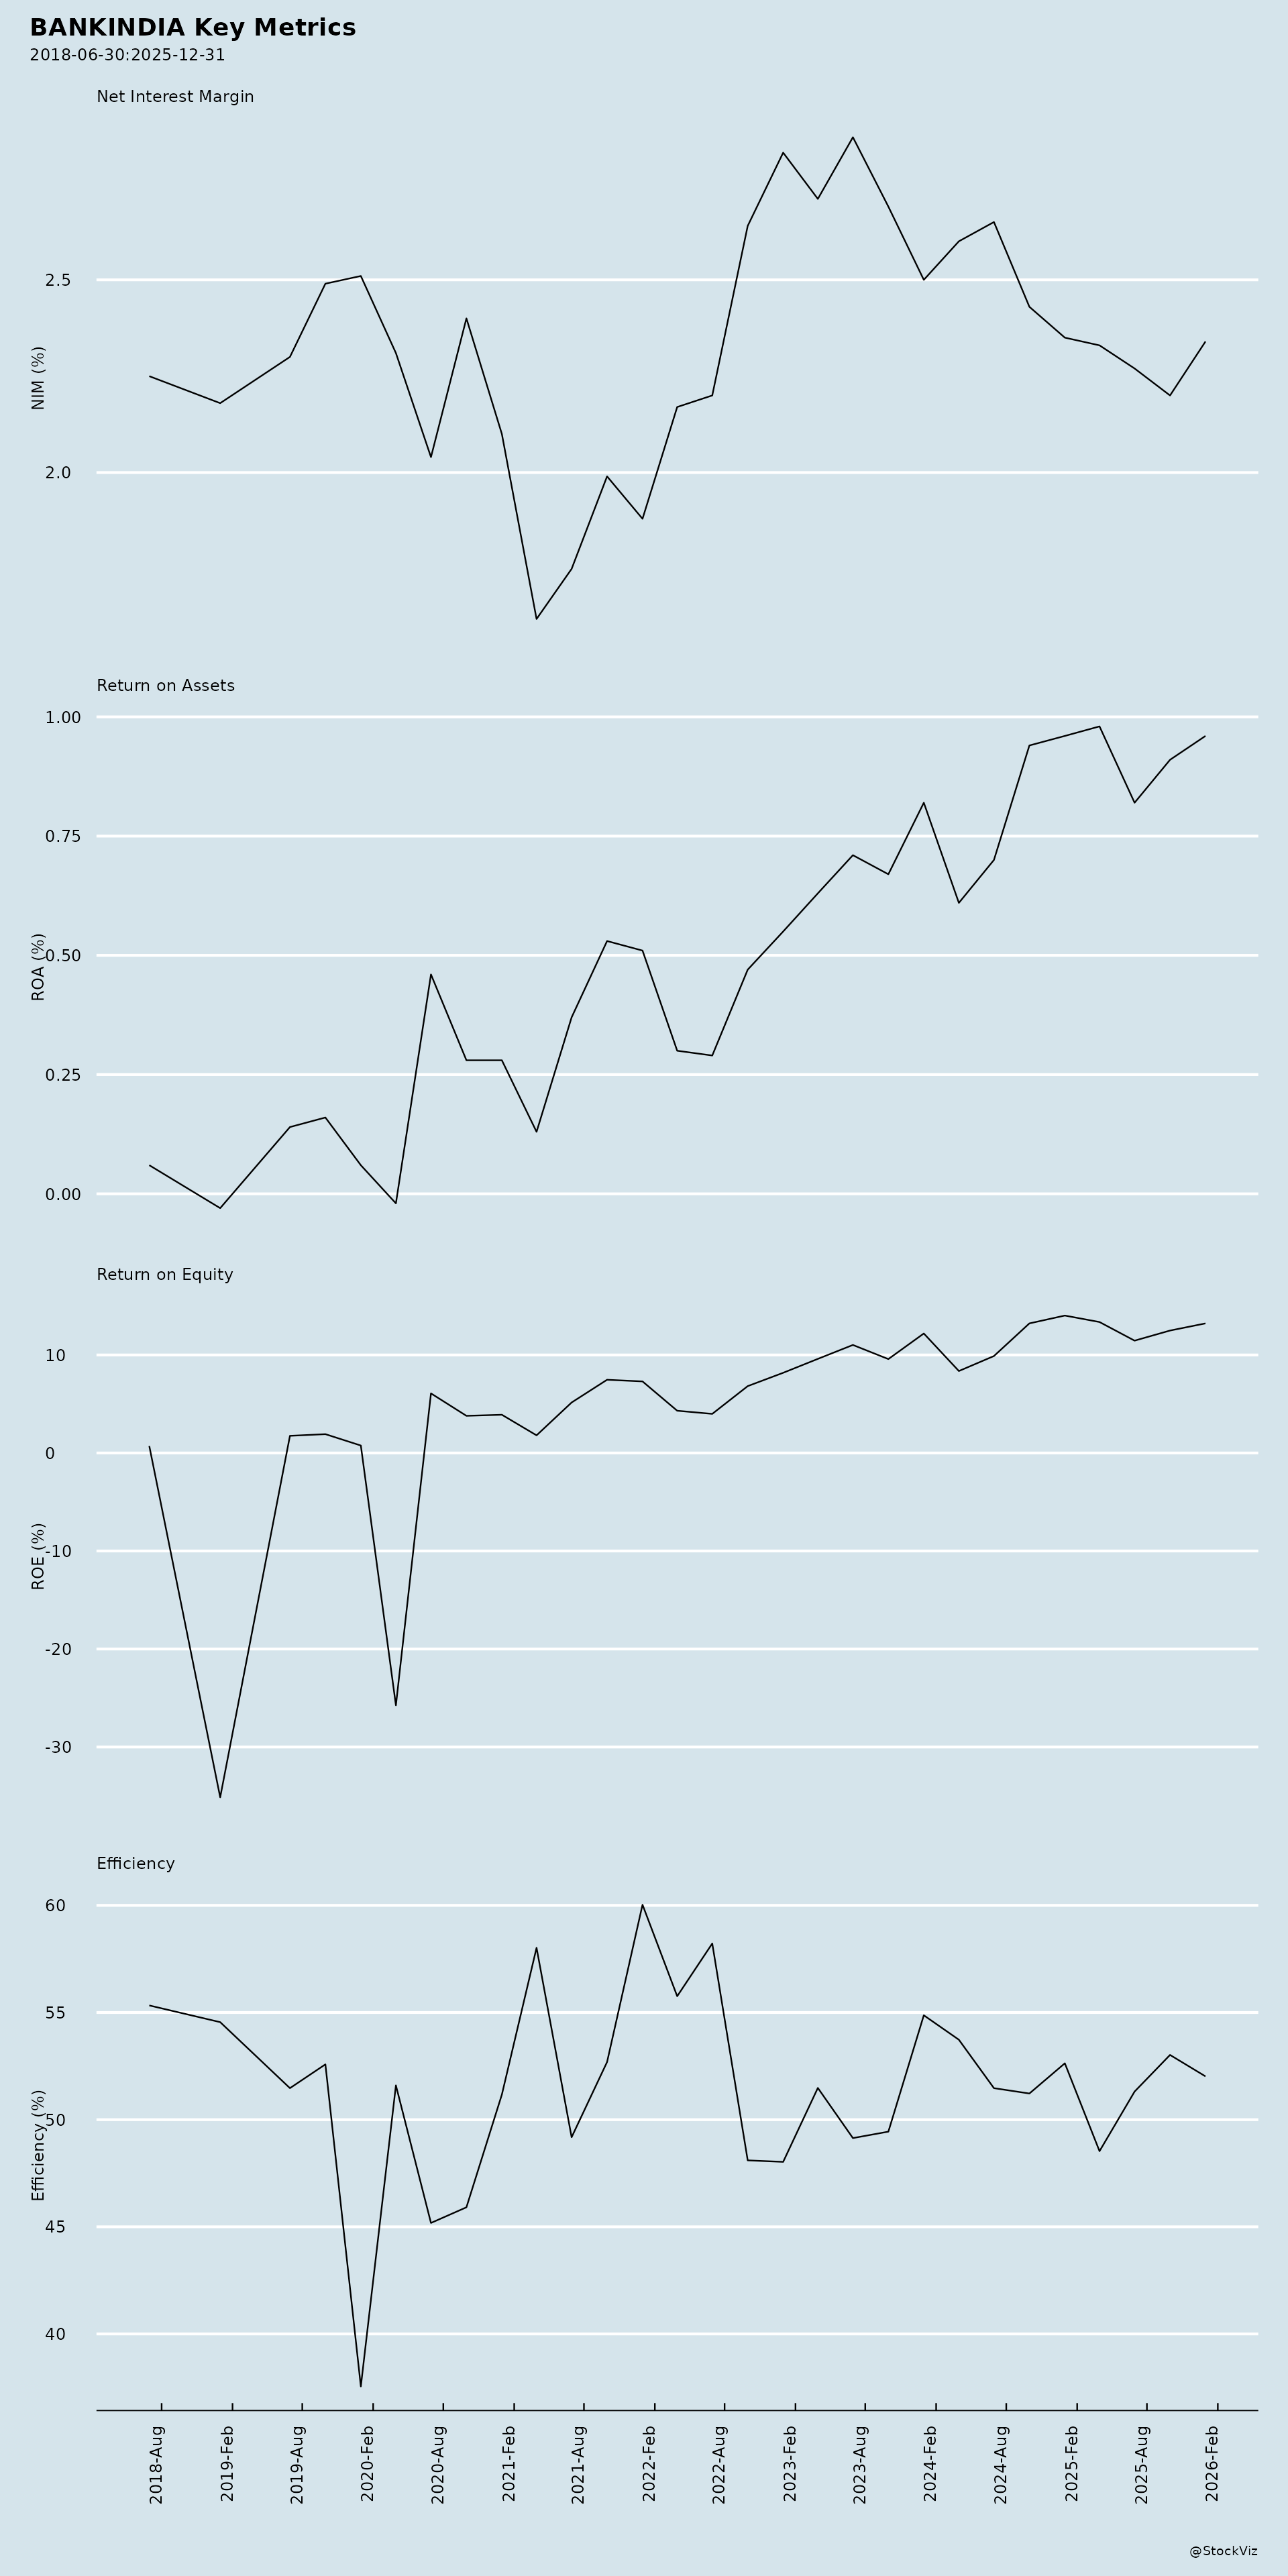
Profitability: - Net Profit grew 36.23% YoY to ₹3,068 Crore. - Operating Profit grew 25.99% YoY to ₹5,051 Crore. - Net Interest Income grew 12.61% YoY to ₹6,833 Crore. - Non-Interest Income grew 19.07% YoY to ₹2,579 Crore. - Cost to Income Ratio improved 498 bps to 46.33%. - ROA rose 19 bps YoY to 1.01%; ROE rose 257 bps to 16.12%.
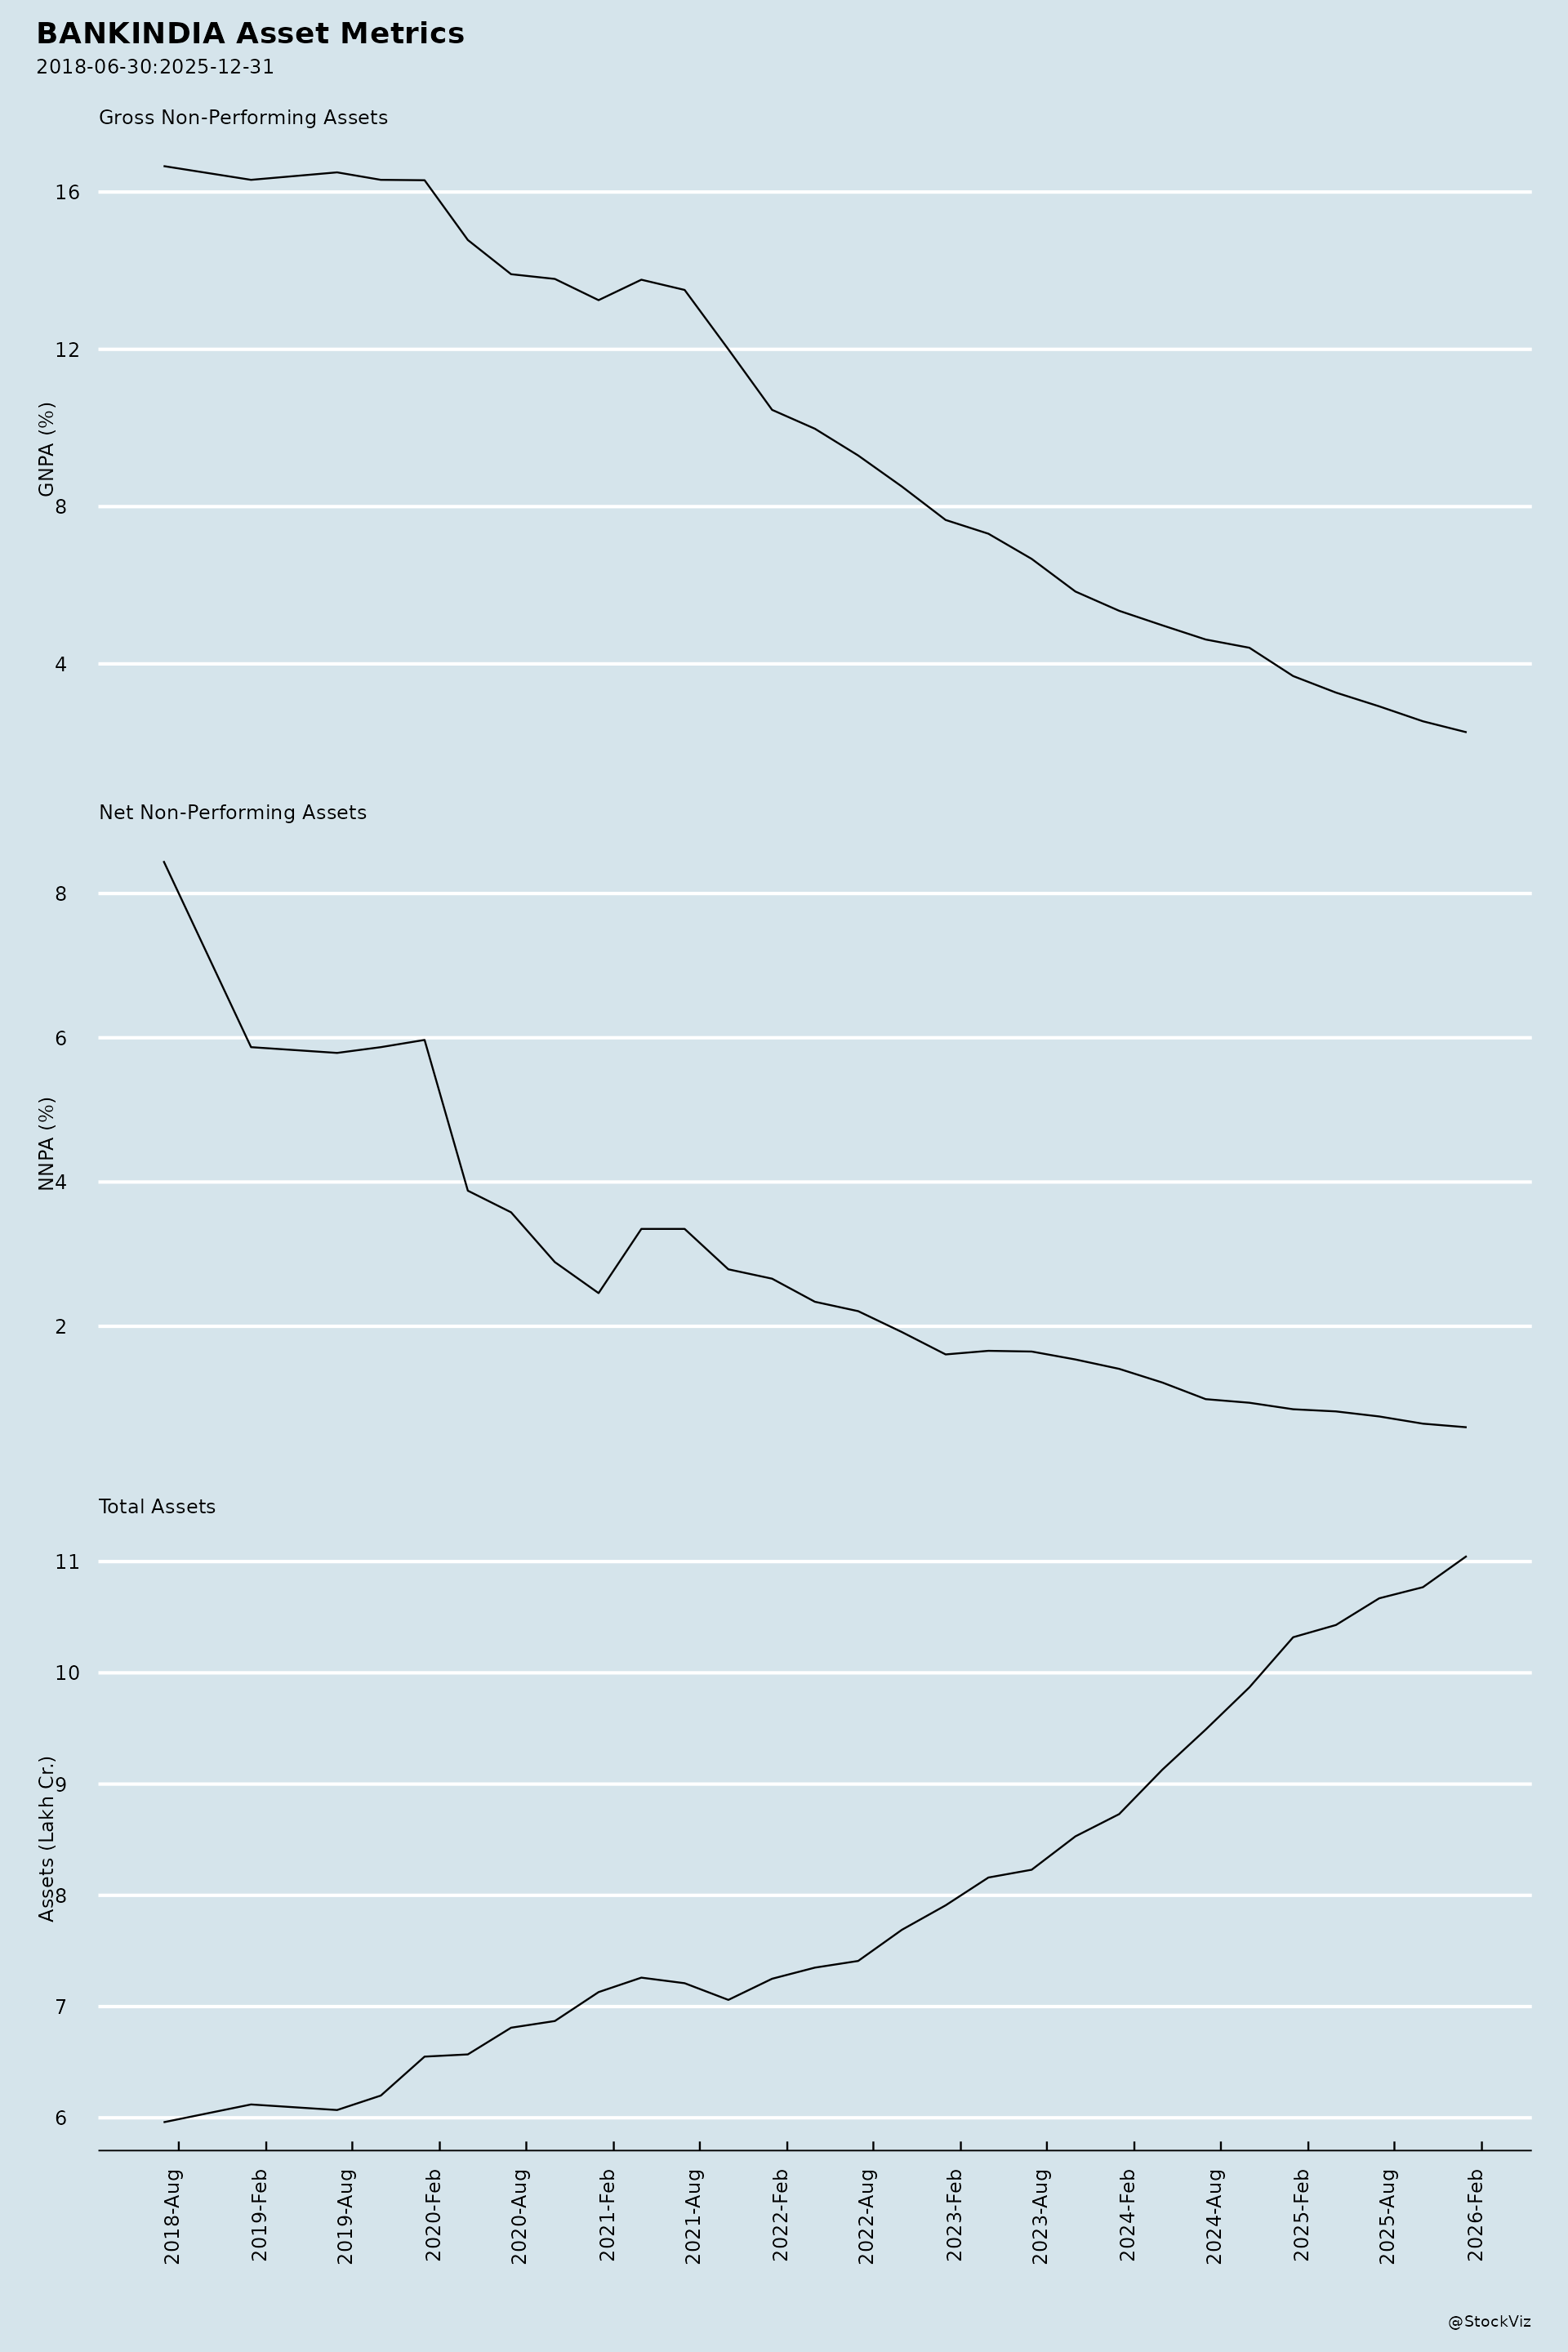
Asset quality: - Gross NPA declined 26.41% YoY to ₹14,454 Crore; GNPA ratio improved 111 bps to 1.81%. - Net NPA declined 18.81% YoY to ₹4,019 Crore; Net NPA ratio improved 24 bps to 0.51%. - Slippage ratio improved 9 bps YoY to 0.24%. - Provision Coverage Ratio stood at 93.83%. - CRAR increased to 18.69%, with CET-1 at 15.97%.
Other developments: - Priority Sector Advances grew 10.93% YoY, achieving 47.11% of ANBC; agricultural advances achieved 19.85% of ANBC; Small & Marginal Farmers achieved 14.22% (norm: 10%); Weaker Sections achieved 17.95% (norm: 12%). - Digital transactions grew 22% YoY to 2.08 billion; Internet Banking users reached 10.1 million and Mobile Banking users 13.9 million. - 3.58 Lakh new PMJDY accounts opened during Q1FY27. - Fund raising through an EMTN Programme. - The bank participated in a Non-deal Roadshow with prospective institutional investors in Hong Kong, Singapore, and London between 09-09-2026 and 16-09-2026, and in London on 15-09-2026.
Key Risks
The disclosed risk factors include market, business, and legal risks; changes in law; future levels of non-performing loans; the impact of acquisitions; allowance for credit losses; provisioning policies; technological implementation and changes; actual growth in demand for banking products and services; investment income; cash flow projections; and exposure to market risks. These are cited as factors that could cause actual results to differ materially from forward-looking statements.
Management Guidance vs. Observed Performance
Capital raising guidance: The bank has approved capital raising in FY27 for Additional Tier-I of ₹2,500 crore and Tier-II Bonds of ₹5,000 crore, totaling ₹7,500 crore. Separately, the Board approved raising foreign currency funds through establishment of a Medium-Term Note (MTN) Programme up to USD 1.00 billion in multiple tranches up to 31-December-2026 in 3/5 year USD Bond (Board meeting held 14.08.2026, following prior intimation dated 10.08.2026).
Observed performance against guidance: The Q1FY27 results (quarter ended 30.06.2026) show capital adequacy already at 18.69% CRAR with CET-1 at 15.97%, alongside improved asset quality (GNPA 1.81%, Net NPA 0.51%) and profitability growth (Net Profit +36.23% YoY). The MTN Programme and domestic capital raising plans indicate continued focus on capital augmentation. The bank notes that the investor presentation for the roadshow shall be shared in due course.
Broker Narrative
The 2023 report framed BANKINDIA as a bank-specific turnaround story: credit revival, asset-quality repair, recoveries, steady NIMs, and efficiency gains were expected to offset ECL, wage, and treasury-income risks. By 2025 the narrative had shifted to a sector-level PSB re-rating story, where PSB advances growth, liability granularity, closing asset-quality gaps, recoveries, and valuation discounts outweighed macro headwinds such as tariffs, deposit-advance mismatches, and rate-cut pressure. Persistent themes were credit growth, recoveries, NIM pressure, asset-quality improvement, efficiency/technology, and re-rating potential; the specific risks changed from idiosyncratic provisioning/wage costs to systemic liquidity and margin issues.
Fears that came true
- The liability-accretion risk materialised as deposit growth lagged advances for three straight years, tightening liquidity and credit-deposit ratios, a likely factor behind the first call’s below-target +15.1% actual return.
- The lower-recoveries risk also appeared, as the last report cautioned that the RoA contribution from recoveries of technically written-off accounts may taper marginally going forward.
Optimism that failed
- The expectation that MCLR repricing and a retail-heavy deposit base would keep NIMs steady near ~3% failed to hold, as the last report noted banking-system NIMs were under downward pressure from RBI repo-rate cuts and stabilisation was only expected from 3QFY26.
Broker Timeline
2 broker calls · 2023-09-11 to 2025-09-18
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.