AVALON
Equity Metrics
November 16, 2026
Avalon Technologies Limited
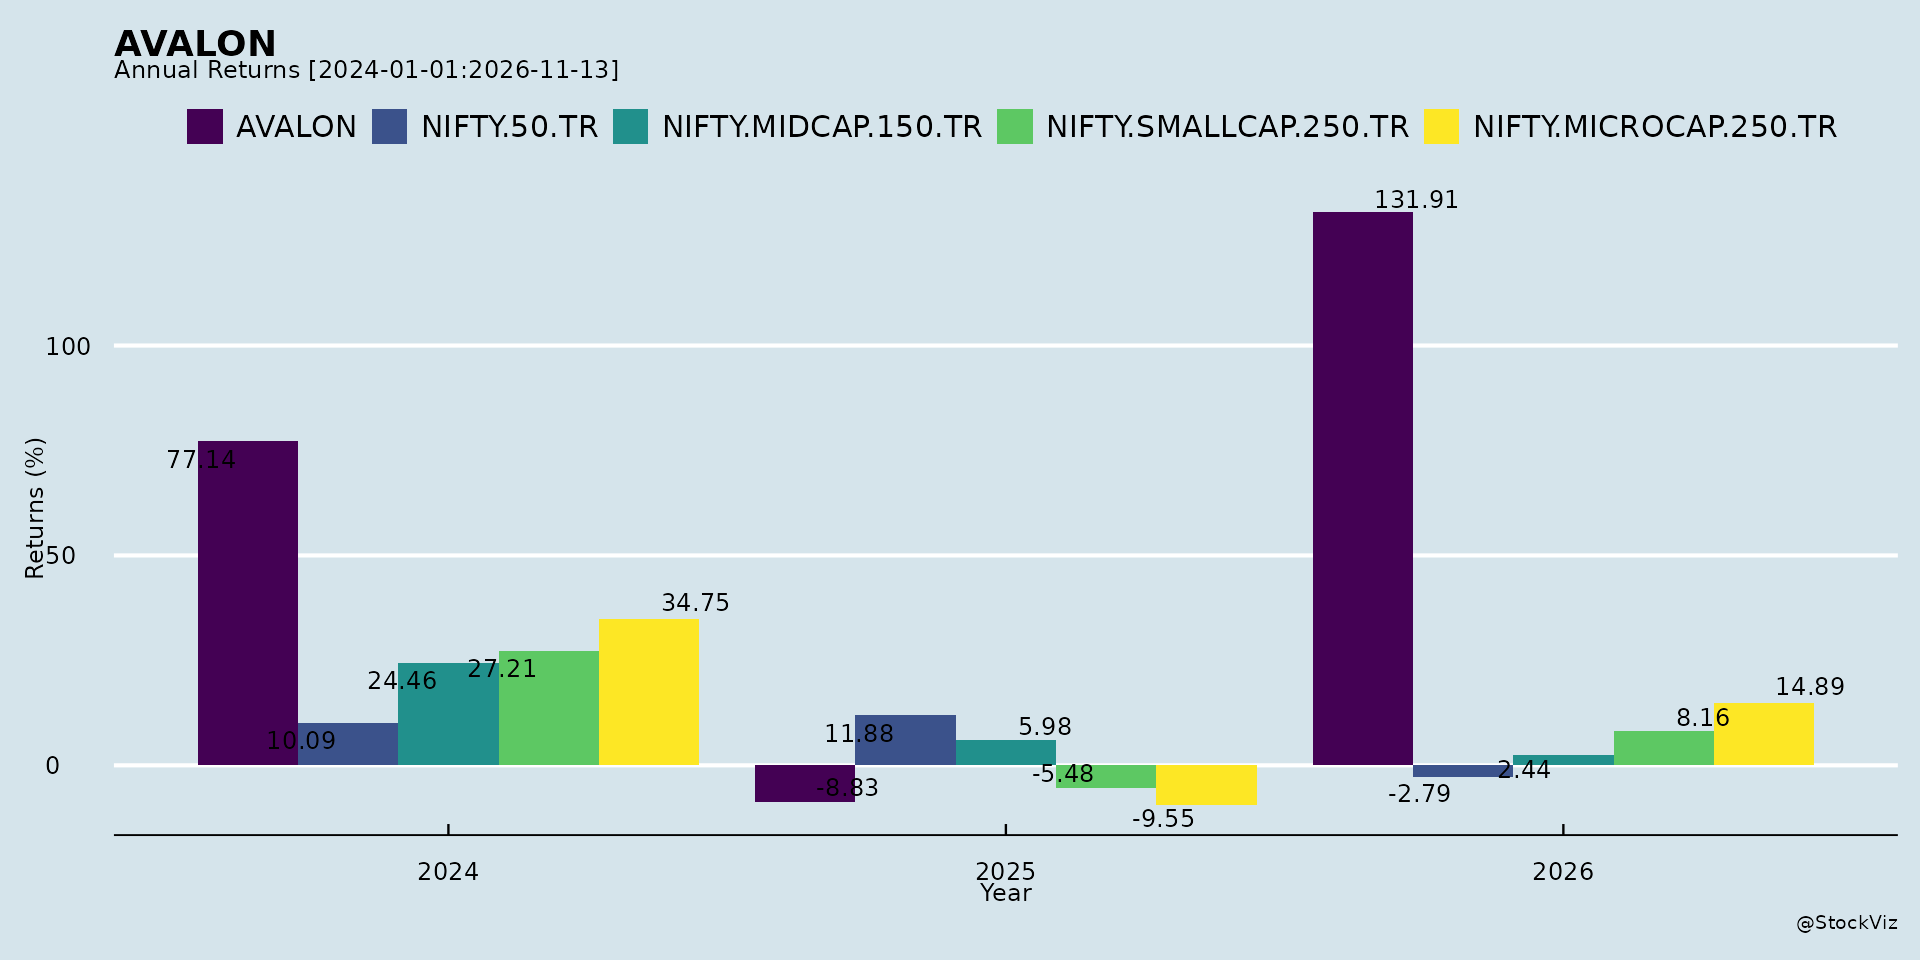
Annual Returns
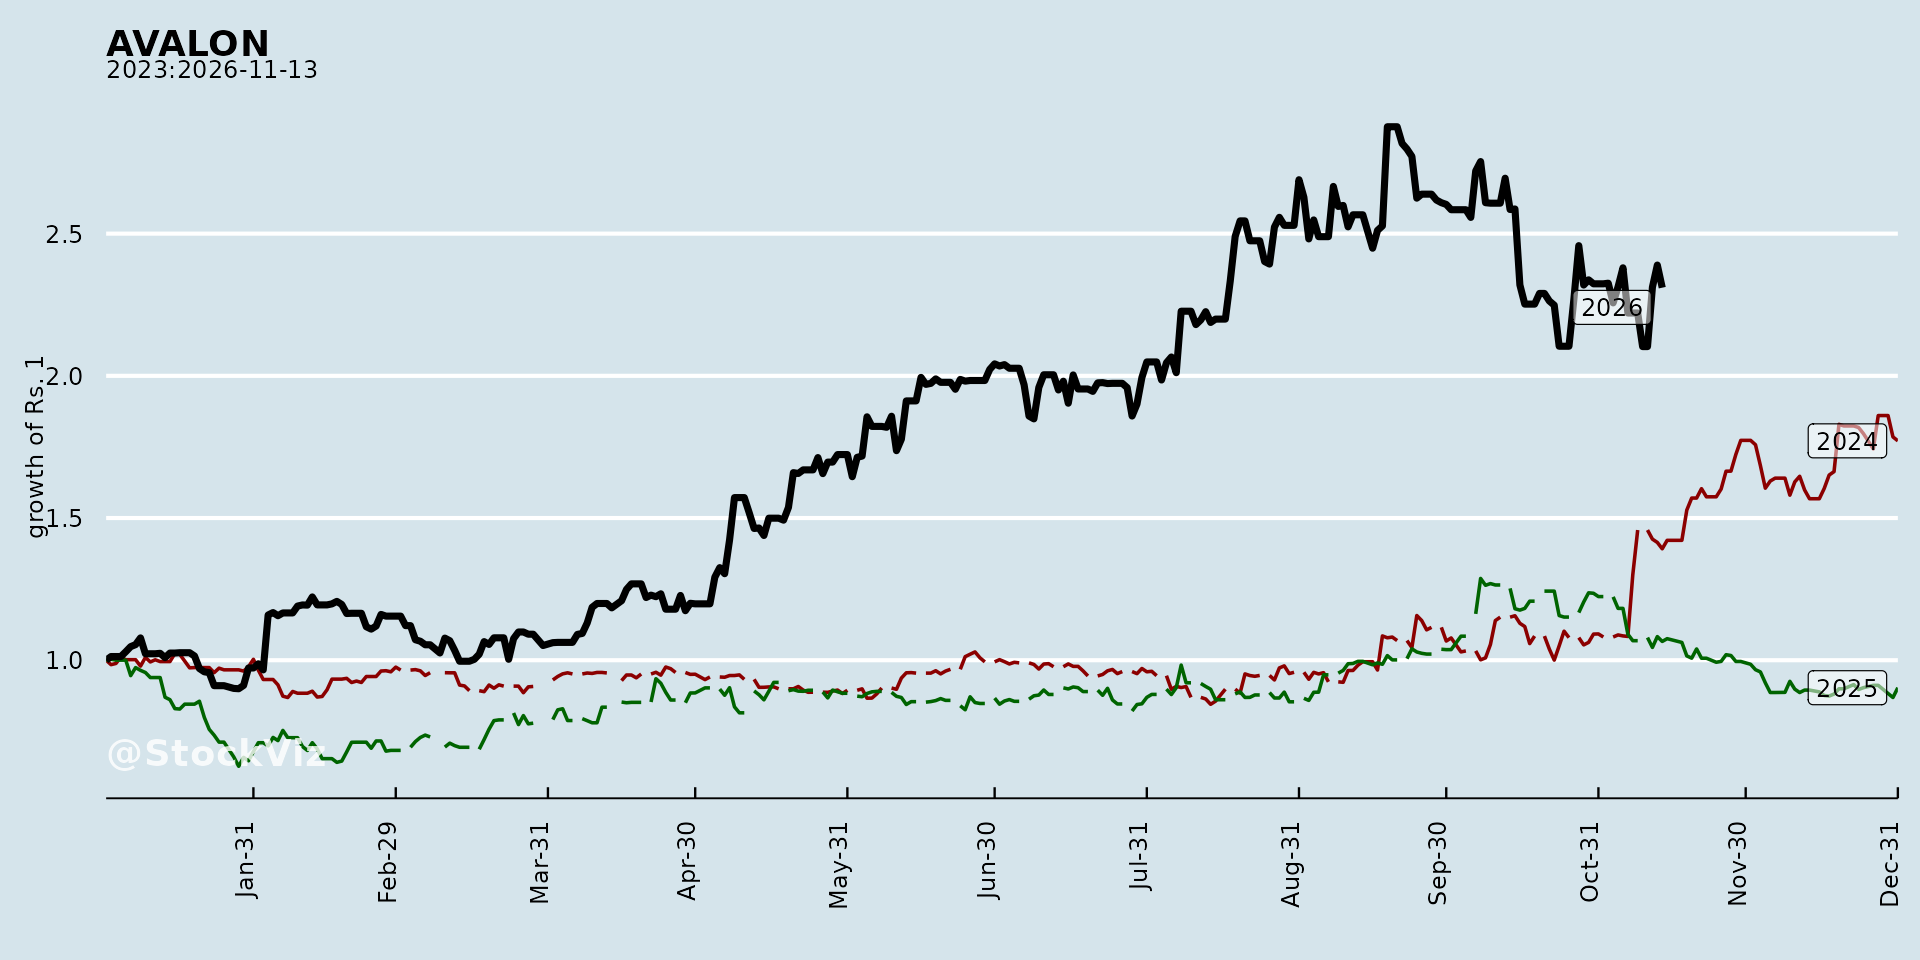
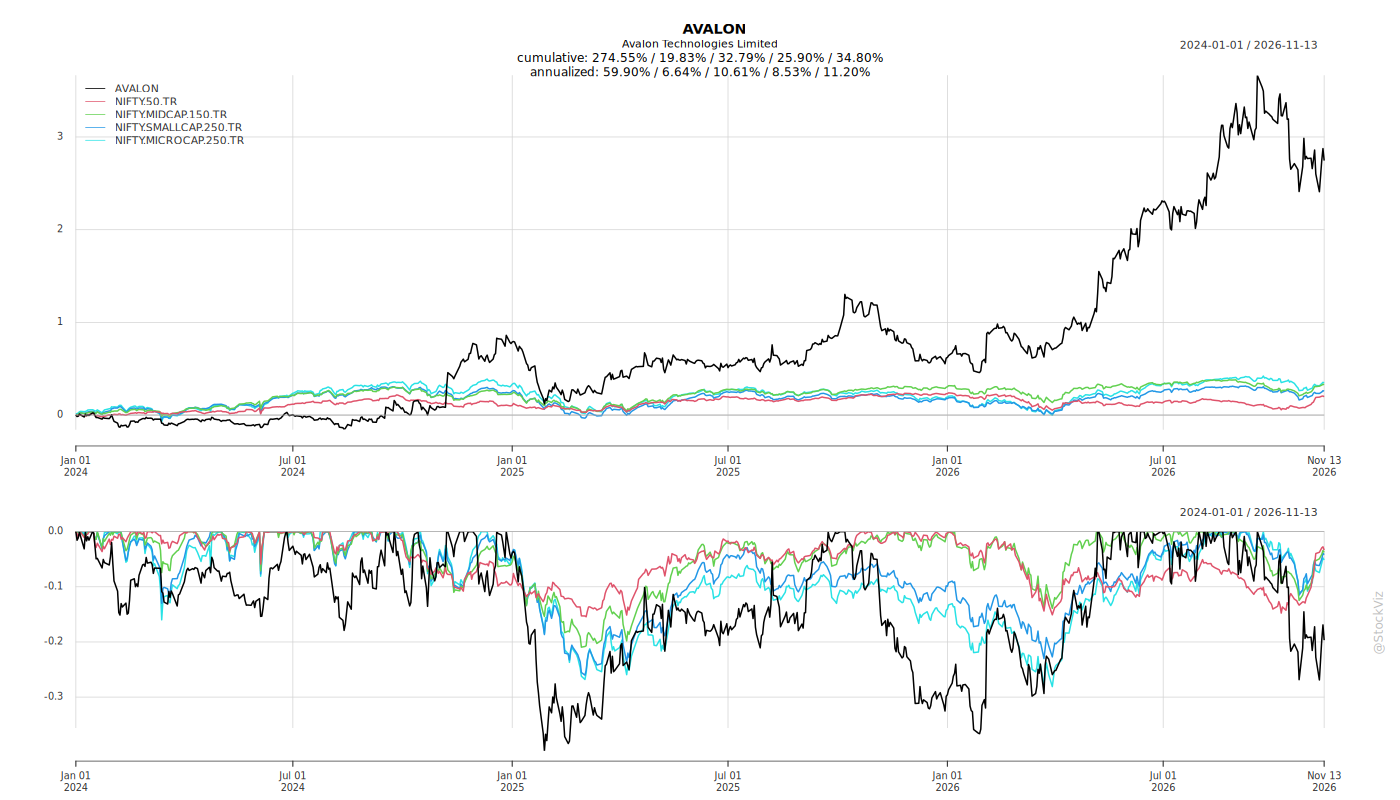
Cumulative Returns and Drawdowns
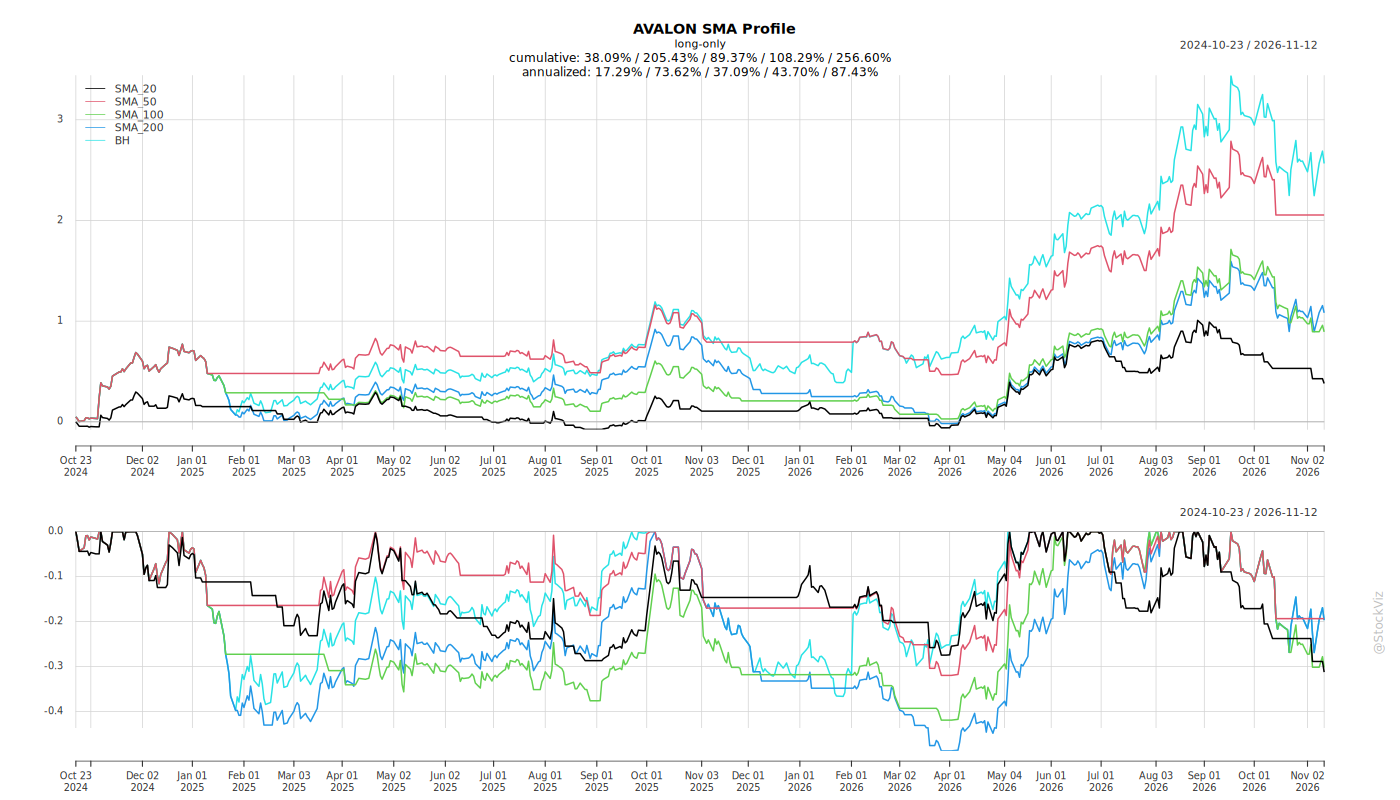
Fundamentals
Ownership
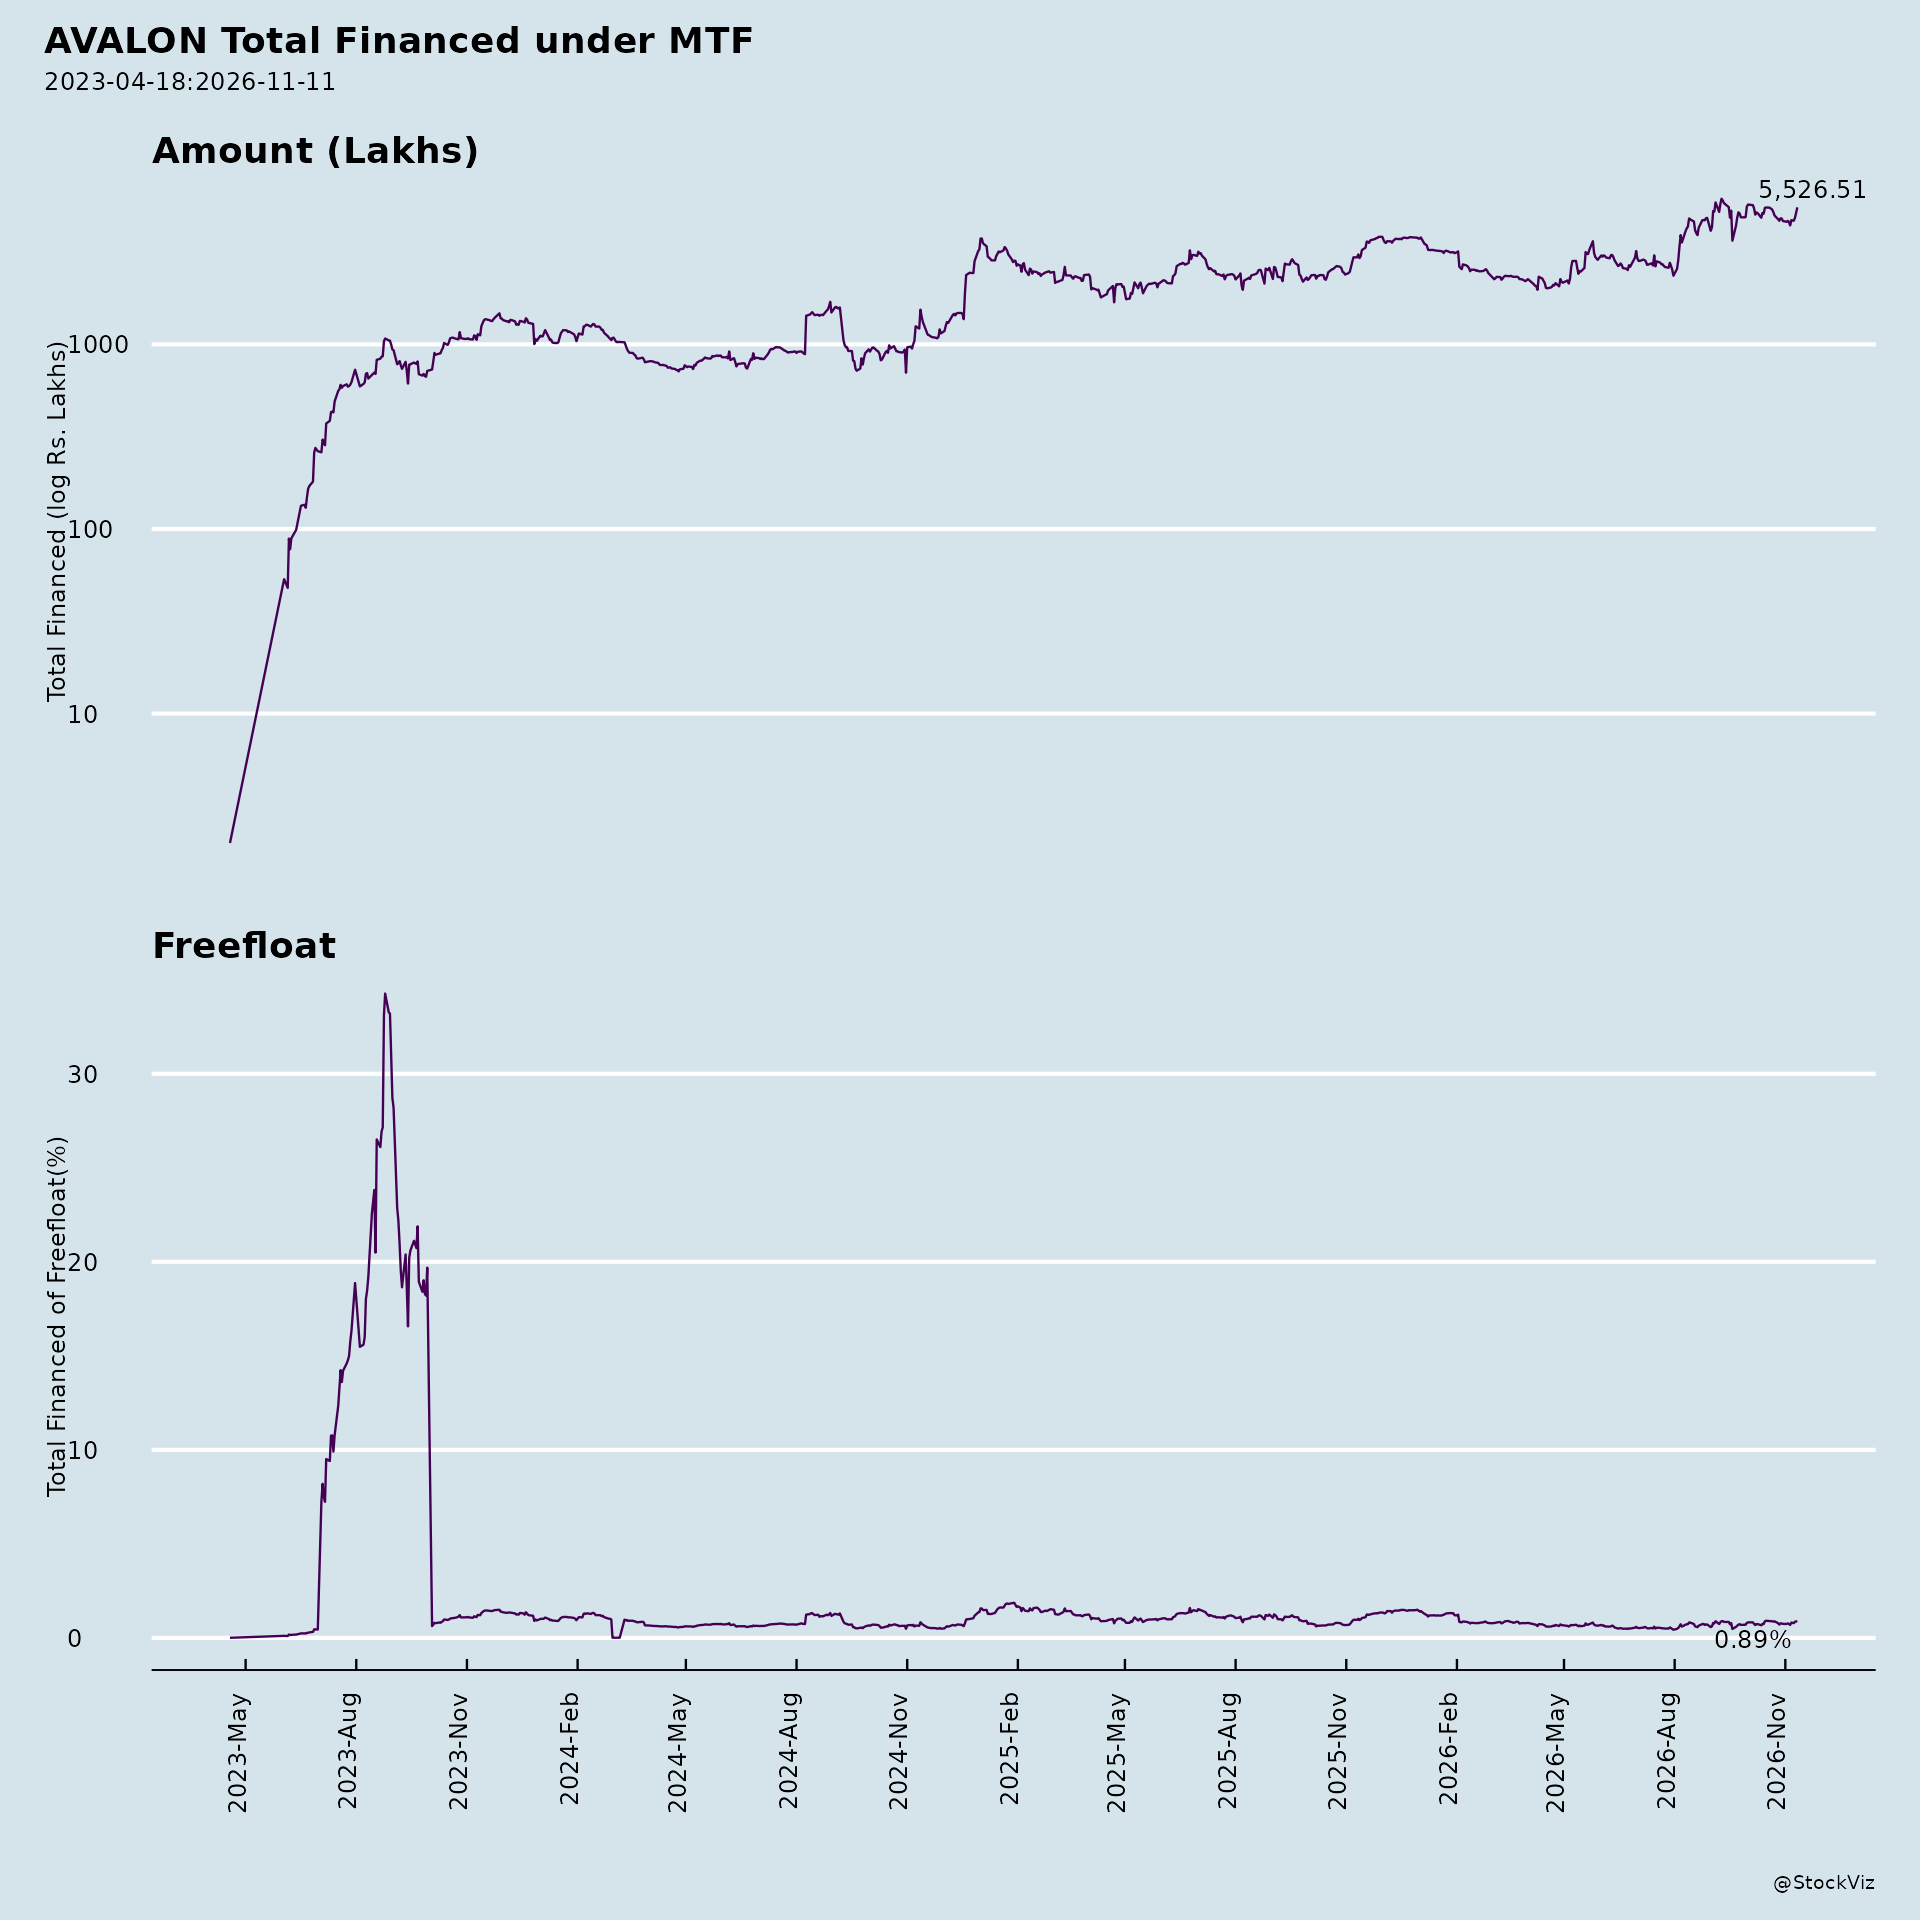
Margined
AI Summary
asof: 2026-09-17
Avalon Technologies: Recent Corporate Developments
1. Headwinds and Challenges
The company operates in an environment shaped by the performance of the Indian economy and various international markets, along with the performance of the electronics manufacturing industry in India and worldwide. Competitive intensity, the ability to successfully implement strategy, future levels of growth and expansion, technological implementation and advancement, changes in revenue, income or cash flows, market preferences, and exposure to market risks are all identified as factors affecting the business. These are described as known and unknown risks, uncertainties and assumptions that are difficult to predict.
2. Tailwinds and Growth Prospects
Several structural drivers support the business outlook:
- Electronification trends: Adoption of Industry 4.0, IoT, Robotics and AI is increasing electronics content across products.
- EMS industry growth: The electronics manufacturing services industry is described as having a CAGR of 27%, with a rising share of EMS manufacturing.
- Supply chain diversification: Manufacturing is moving toward India and the US.
- Indian EMS market expansion: Larger domestic demand, skilled talent, and growing acceptance of India as a manufacturing destination are cited as drivers.
The most significant strategic development is the joint venture with Zollner Elektronik AG. Avalon executed a Joint Venture Agreement to form Zollner Avalon Private Limited, initially set up as a wholly owned subsidiary of Avalon, with Zollner subsequently acquiring a 51% stake and Avalon holding 49%. Avalon holds an option to acquire an additional 2% stake three years after commercial production starts, which would make it the majority shareholder.
The JV is intended to establish a long-term India-based manufacturing and services platform covering PCBA, box-build and system integration, testing, validation, industrialization support, sourcing, supply-chain coordination, logistics, and related after-sales services. It is designed to support domestic business, exports from India, and selected multi-region or global customer programs. Avalon will also supply the JV across several core capabilities, creating additional recurring revenue opportunities. The partnership is expected to expand access to global customers, add new healthcare & life sciences and test & measurement industry verticals, advance high-complexity manufacturing capabilities, and support localization.
3. Key Risks
The principal risks cited include:
- Economic performance in India and international markets
- Industry performance in India and worldwide
- Competition
- Ability to successfully implement strategy
- Future levels of growth and expansion
- Technological implementation, changes and advancements
- Changes in revenue, income or cash flows
- Market preferences
- Exposure to market risks
Management notes that statements regarding market opportunity and business prospects are forward-looking and involve risks and uncertainties, and the company undertakes no obligation to publicly update or revise any forward-looking statements except as required by applicable law.
4. Management Guidance vs. Observed Performance
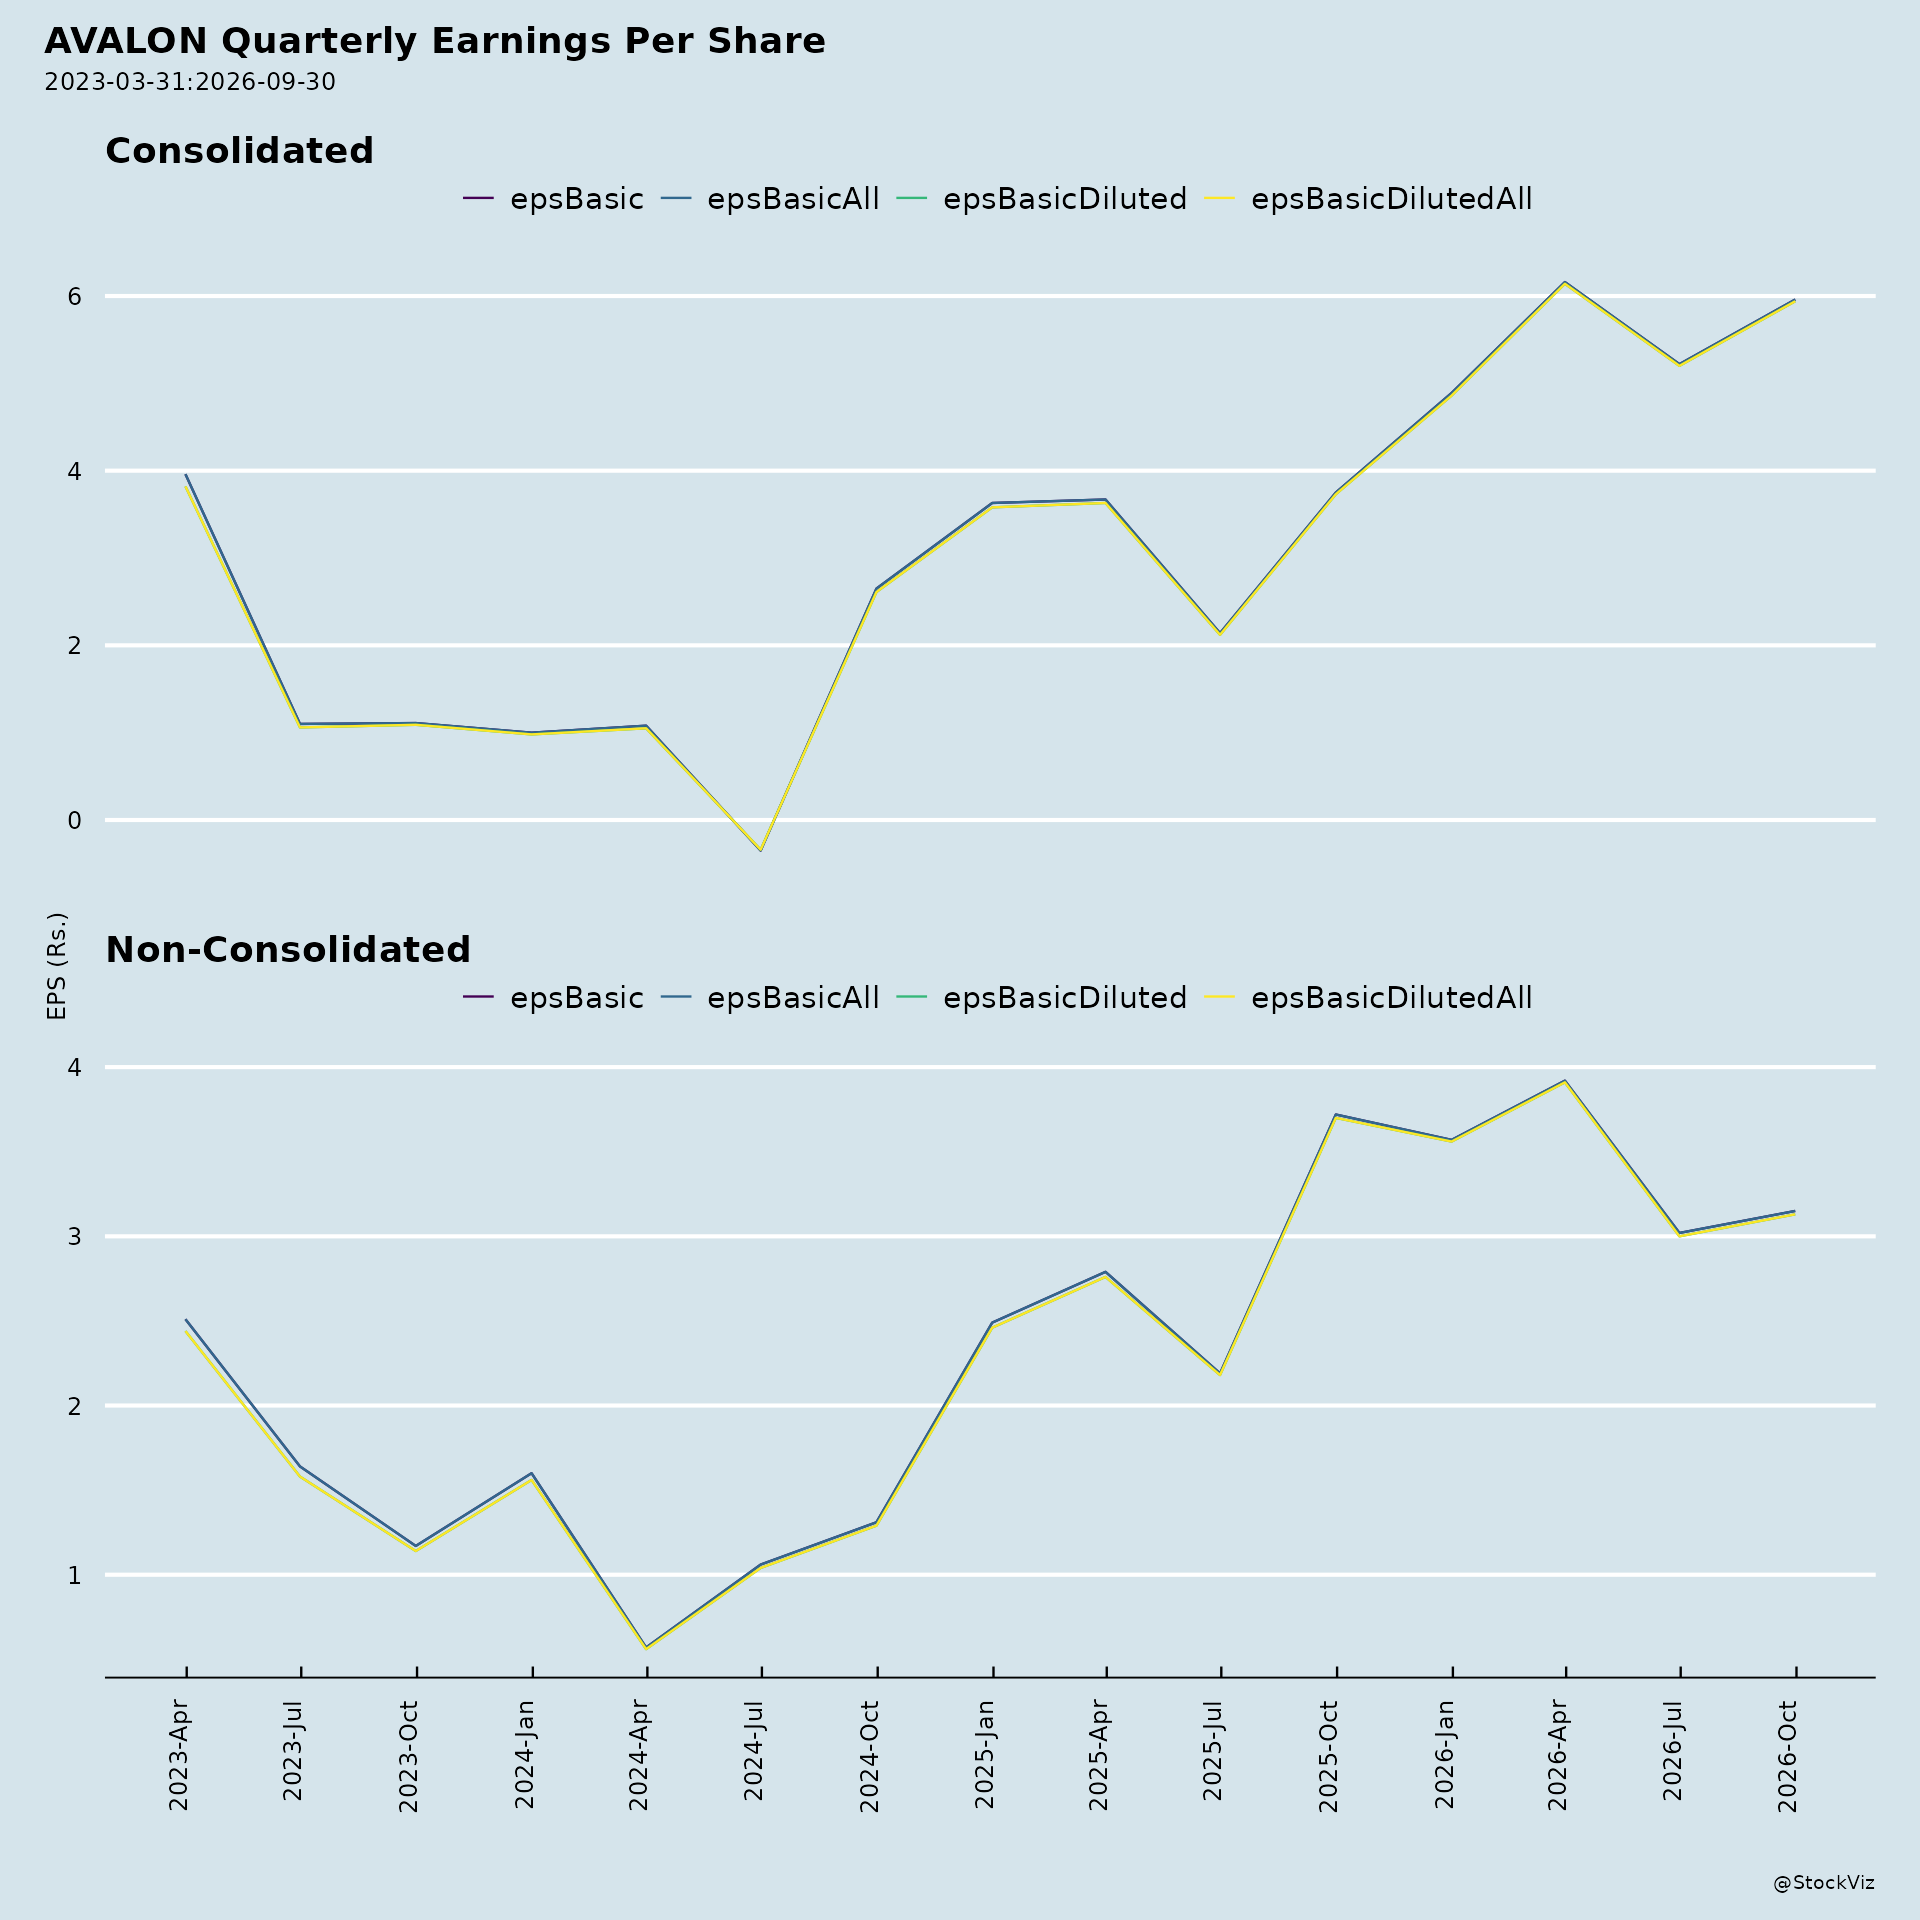
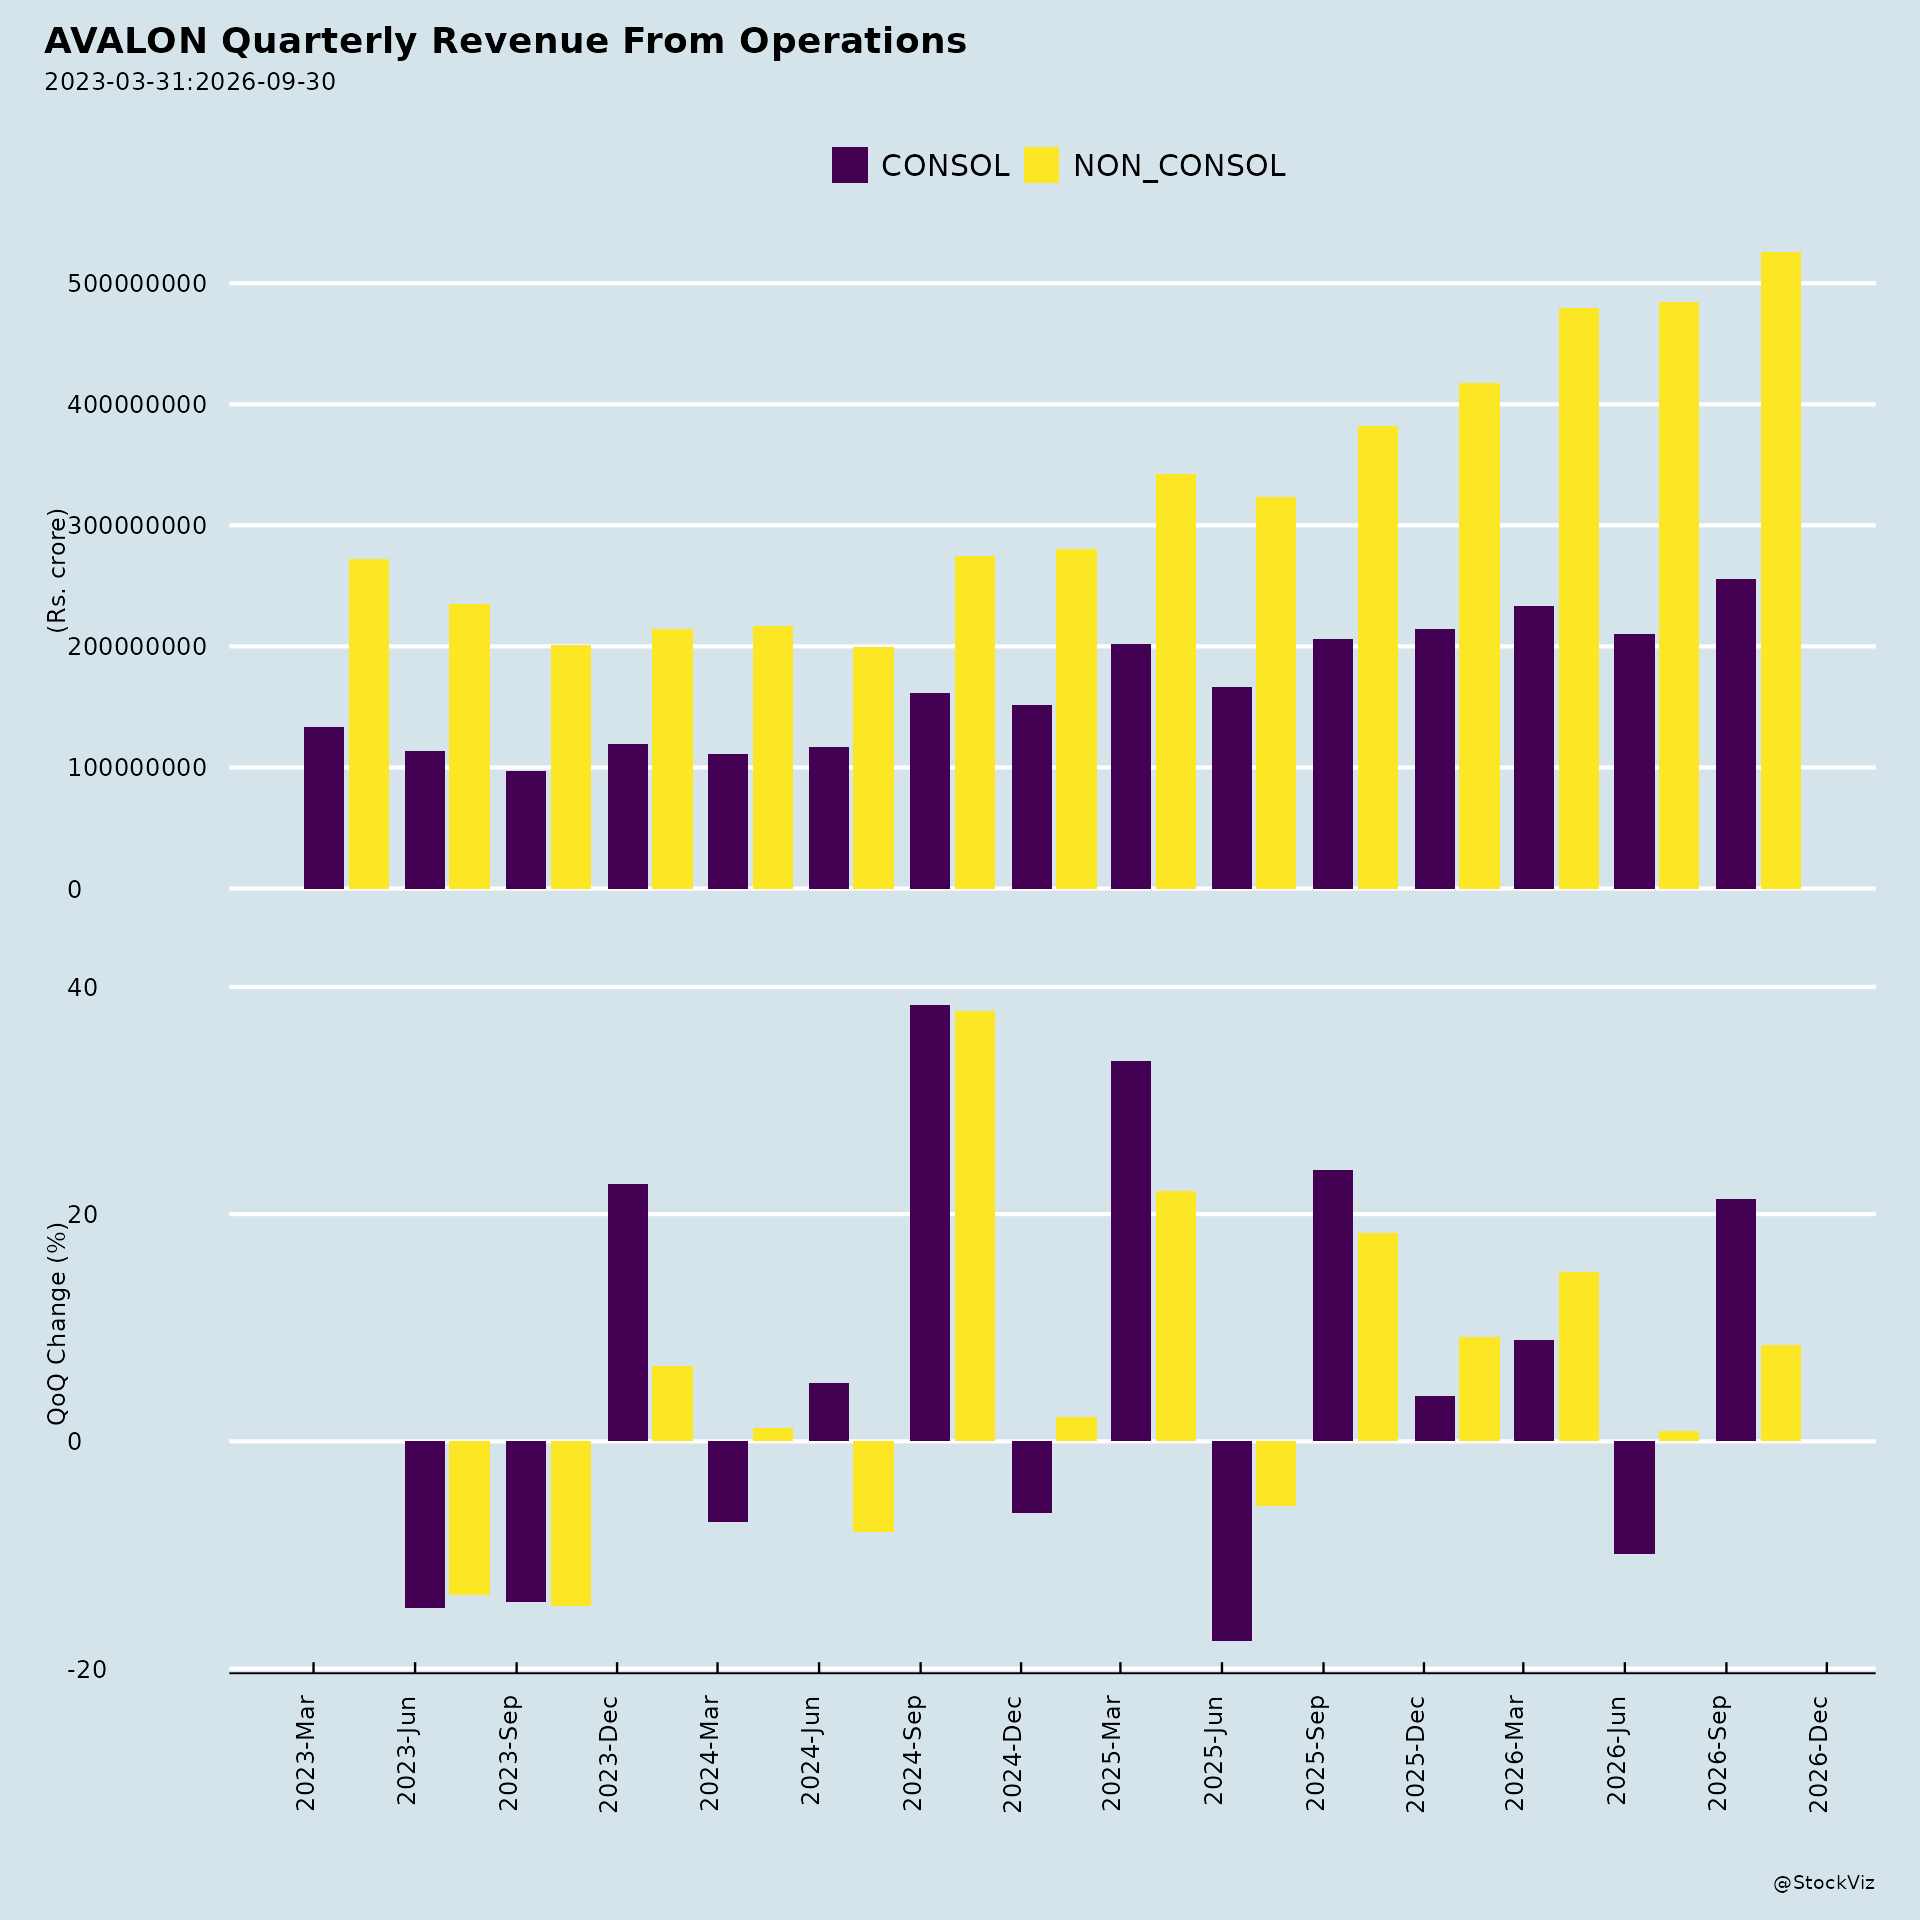
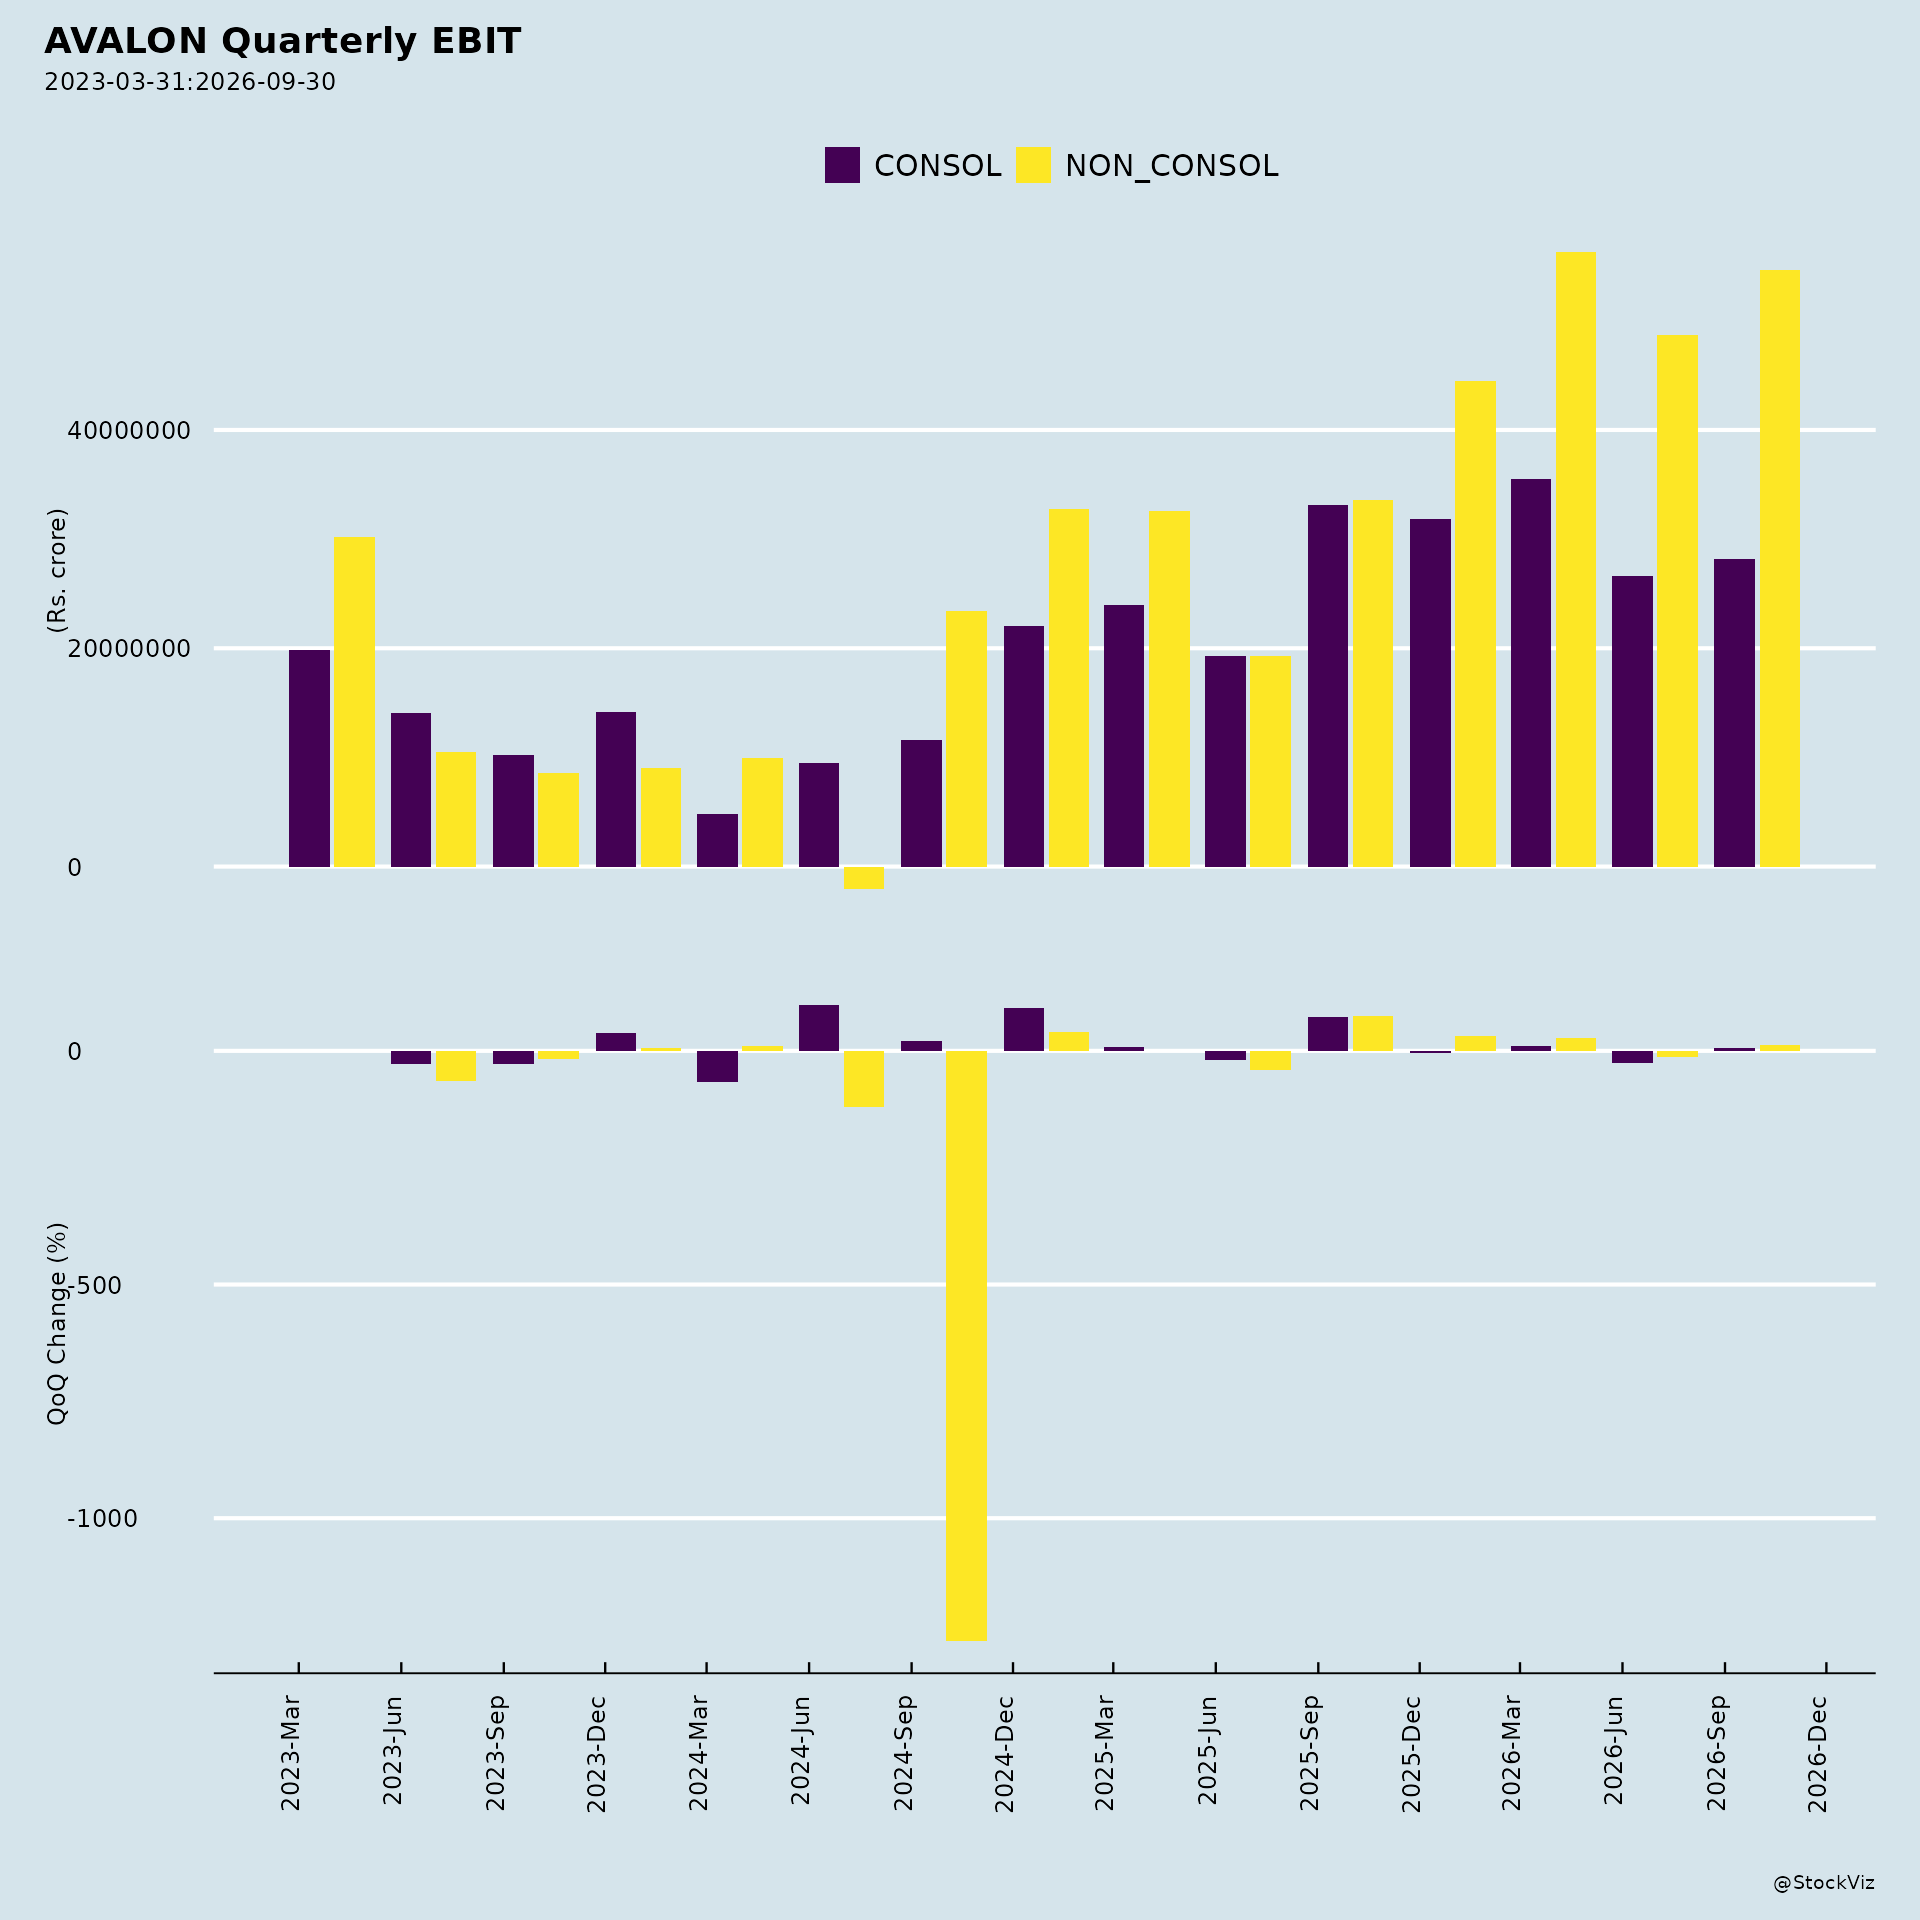
Observed performance (Q1 FY27): The company reported its eighth consecutive quarter of sequential improvement. Revenue stood at INR 484 Cr, gross margin at INR 168 Cr (34.7%), EBITDA at INR 58 Cr (12.0%), and PAT at INR 35 Cr (7.2%). The order book was INR 2,208 Cr, up 23.4% YoY, and Net Working Capital days improved from 142 days in June 2025 to 117 days in June 2026.
Governance and leadership guidance: The Board believes Mr. CG Balaji’s experience and expertise will enhance the Board’s decision-making process and strengthen the governance framework, and that Mr. Kunhamed Bicha’s continued leadership will provide sustainable growth and support implementation of future business plans.
Forward-looking statements: Management characterizes market opportunity and business prospect statements as forward-looking, subject to risks and uncertainties, with no obligation to publicly update or revise them except as required by applicable law.
Key Investor Facts and Dates
- 27th AGM: Scheduled for Monday, September 28, 2026, at 02:30 PM IST via video conferencing. Agenda includes adoption of financial statements, re-appointment of Mr. Kunhamed Bicha as Chairman and Managing Director, appointment of Mr. CG Balaji as Independent Director, and re-appointment of Mr. Venkataramani Anantharamakrishnan and Mr. Byas Unnikrishnan Nambisan as Independent Directors for a second term. Approval is also sought for profit-related commission to Independent Directors up to a maximum of 0.5% of net profits starting from April 1, 2026.
- Investor meet: Avalon will participate in the Motilal Oswal 22nd Annual Global Investor Conference on August 18, 2026, from 9:00 AM to 5:00 PM IST in Mumbai, in physical group format. The schedule is subject to change, and no unpublished price sensitive information is shared at such meetings.
- Board approvals: The board approved the appointment of Mr. CG Balaji as an Independent Additional Director and the re-appointments of Mr. Kunhamed Bicha, Mr. Venkataramani Anantharamakrishnan, and Mr. Byas Unnikrishnan Nambisan.
Broker Narrative
The narrative evolved from a broad EMS growth thesis (import substitution, China+1, consumer/automotive/industrial electronics adoption, 32% CAGR) to a focused high-value engineering thesis (semiconductor equipment, BESS, AI/HBM, advanced packaging, ISM 2.0, aerospace, rail safety, satellites). Persisted themes include manufacturing ecosystem support (PLI→ISM 2.0), outsourcing/export opportunities (China+1→global OEM diversification), and margin expansion. Risk flags disappeared entirely by the last report, replaced by no headwinds.
Broker Timeline
31 broker calls · 2023-07-12 to 2026-09-15
CNBC-TV18: ratings, targets and commentary
Extracted from CNBC-TV18 posts; ratings and targets are as published, not current consensus. OCR may contain errors. Speaker attribution is retained; not all speakers are brokers. These statements are separate from the Broker Narrative and Broker Timeline and have no calculated performance or outcomes.
Ratings and targets
| Published / source (IST) | Speaker / affiliation | Rating / target | Commentary |
|---|---|---|---|
| 2026-11-16 |
Equirus Securities
Manoj Gori
|
top pick
|
Relatively positive in the EMS space, Syrma & Avalon are top picks |
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.