ATGL
Equity Metrics
October 23, 2026
Adani Total Gas Limited
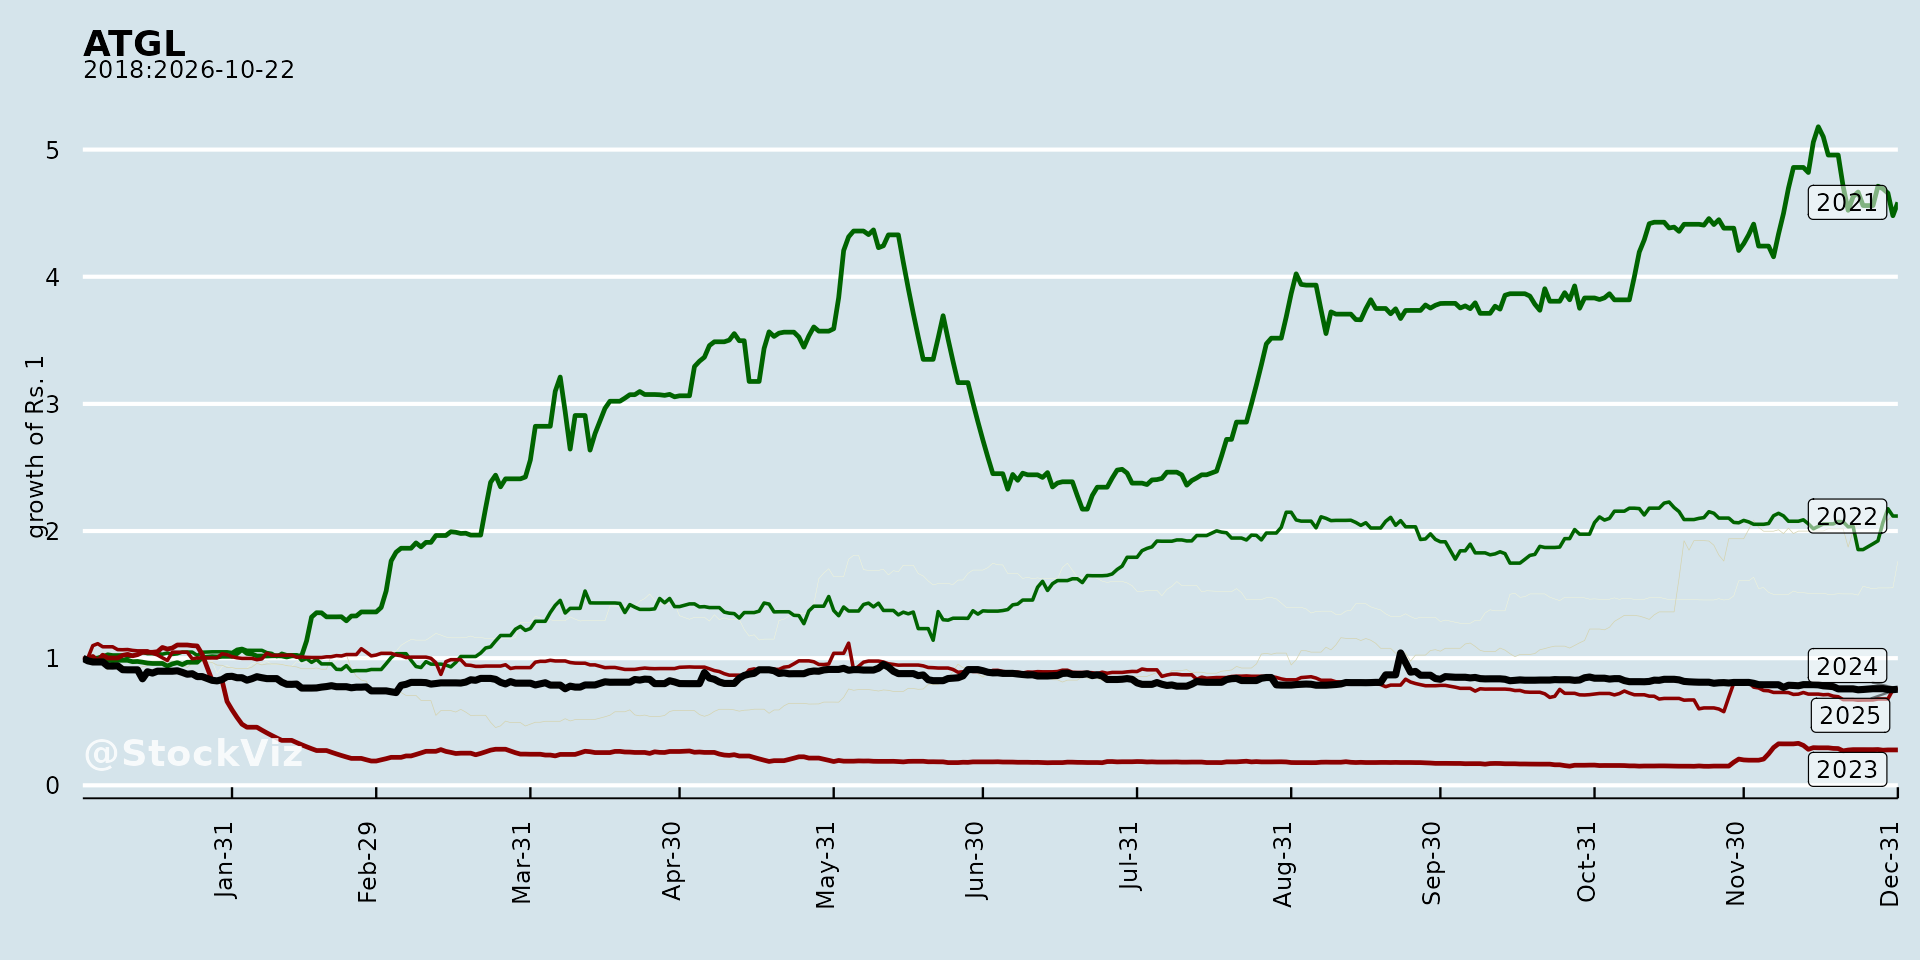
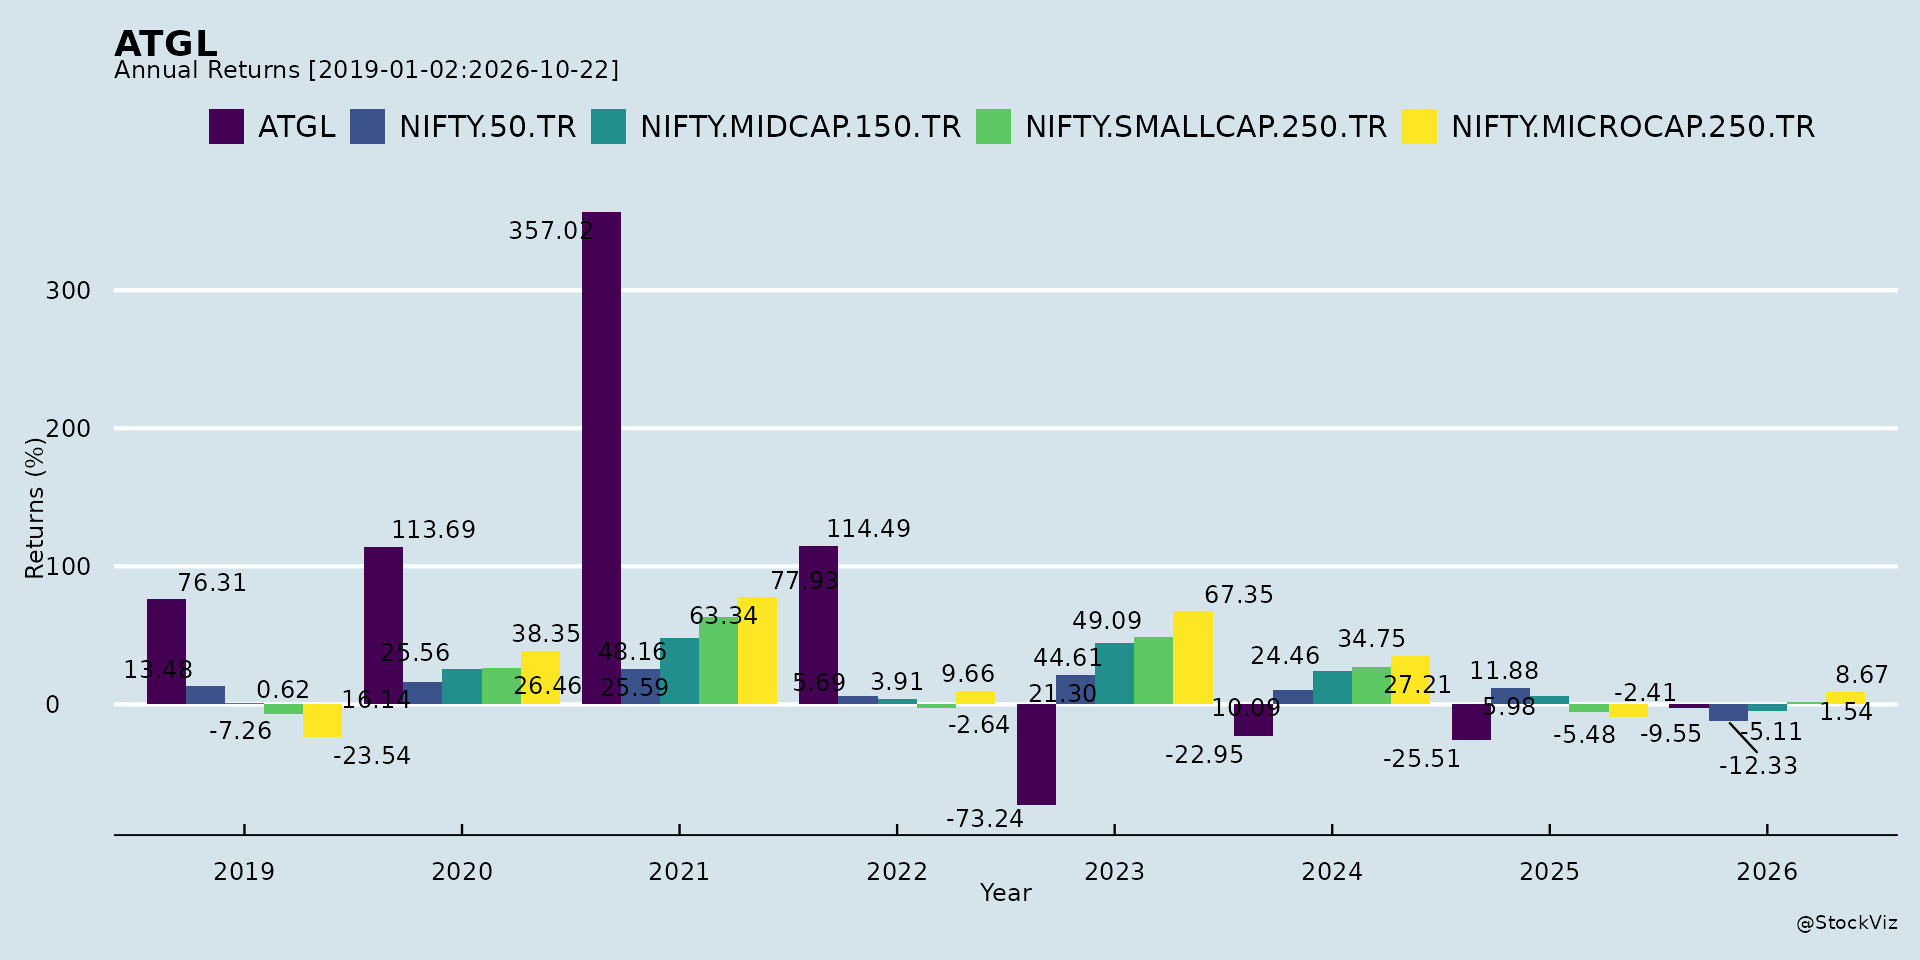
Annual Returns
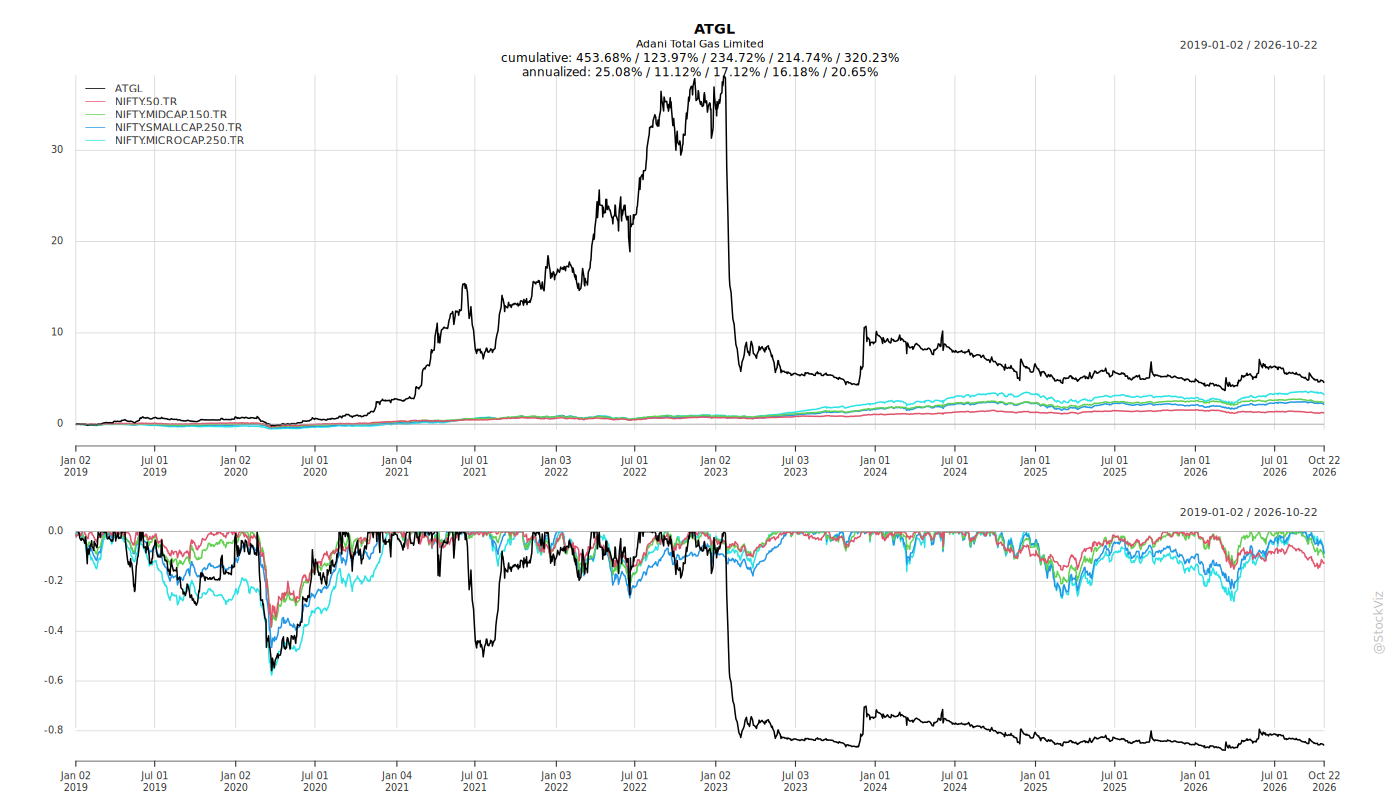
Cumulative Returns and Drawdowns
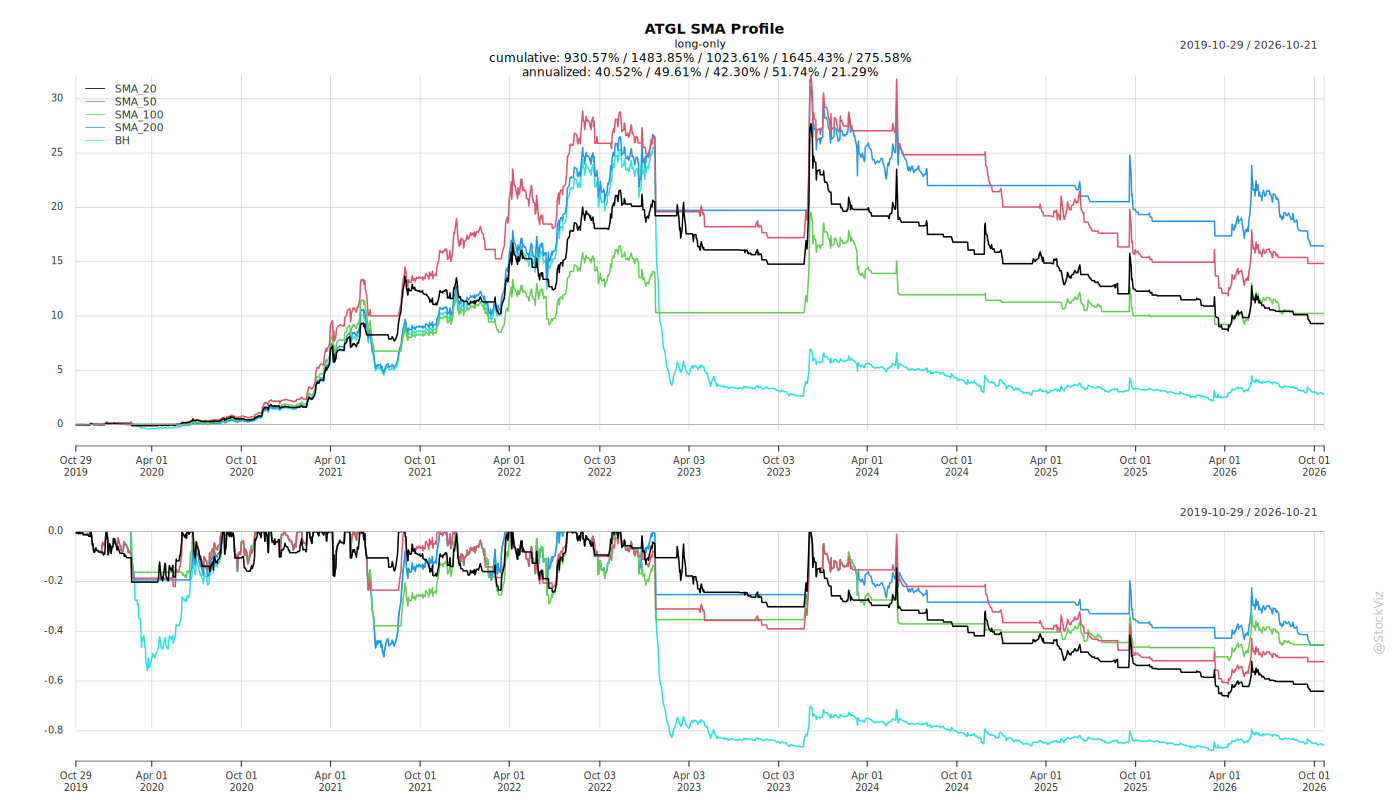
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
ATGL: Recent Corporate Announcements — Headwinds, Tailwinds, Risks, and Guidance vs. Performance
1. Headwinds and Challenges
Elevated gas costs and geopolitical disruption. Q1FY27 (quarter ended June 30, 2026) was marked by the impact of the West Asia crisis. Elevated crude prices drove higher Brent-linked gas costs across New Well Gas, RLNG, and spot LNG. The increase in the APM gas price ceiling, combined with currency depreciation, pushed gas procurement cost up 39% year-on-year. Cost of natural gas rose to INR 1,454 Cr in Q1FY27 from INR 1,049 Cr in Q1FY26.
Reduced APM allocation. During the quarter, APM allocation for the CNG segment fell to approximately 30% from 36% in the prior quarter. The balance was met through existing contracts and higher-priced spot procurement. The presentation notes Q1 APM allocation at 28%, with 72% sourced from other sources (HPHT, NWG, spot gas, and long-term/short-term contracts).
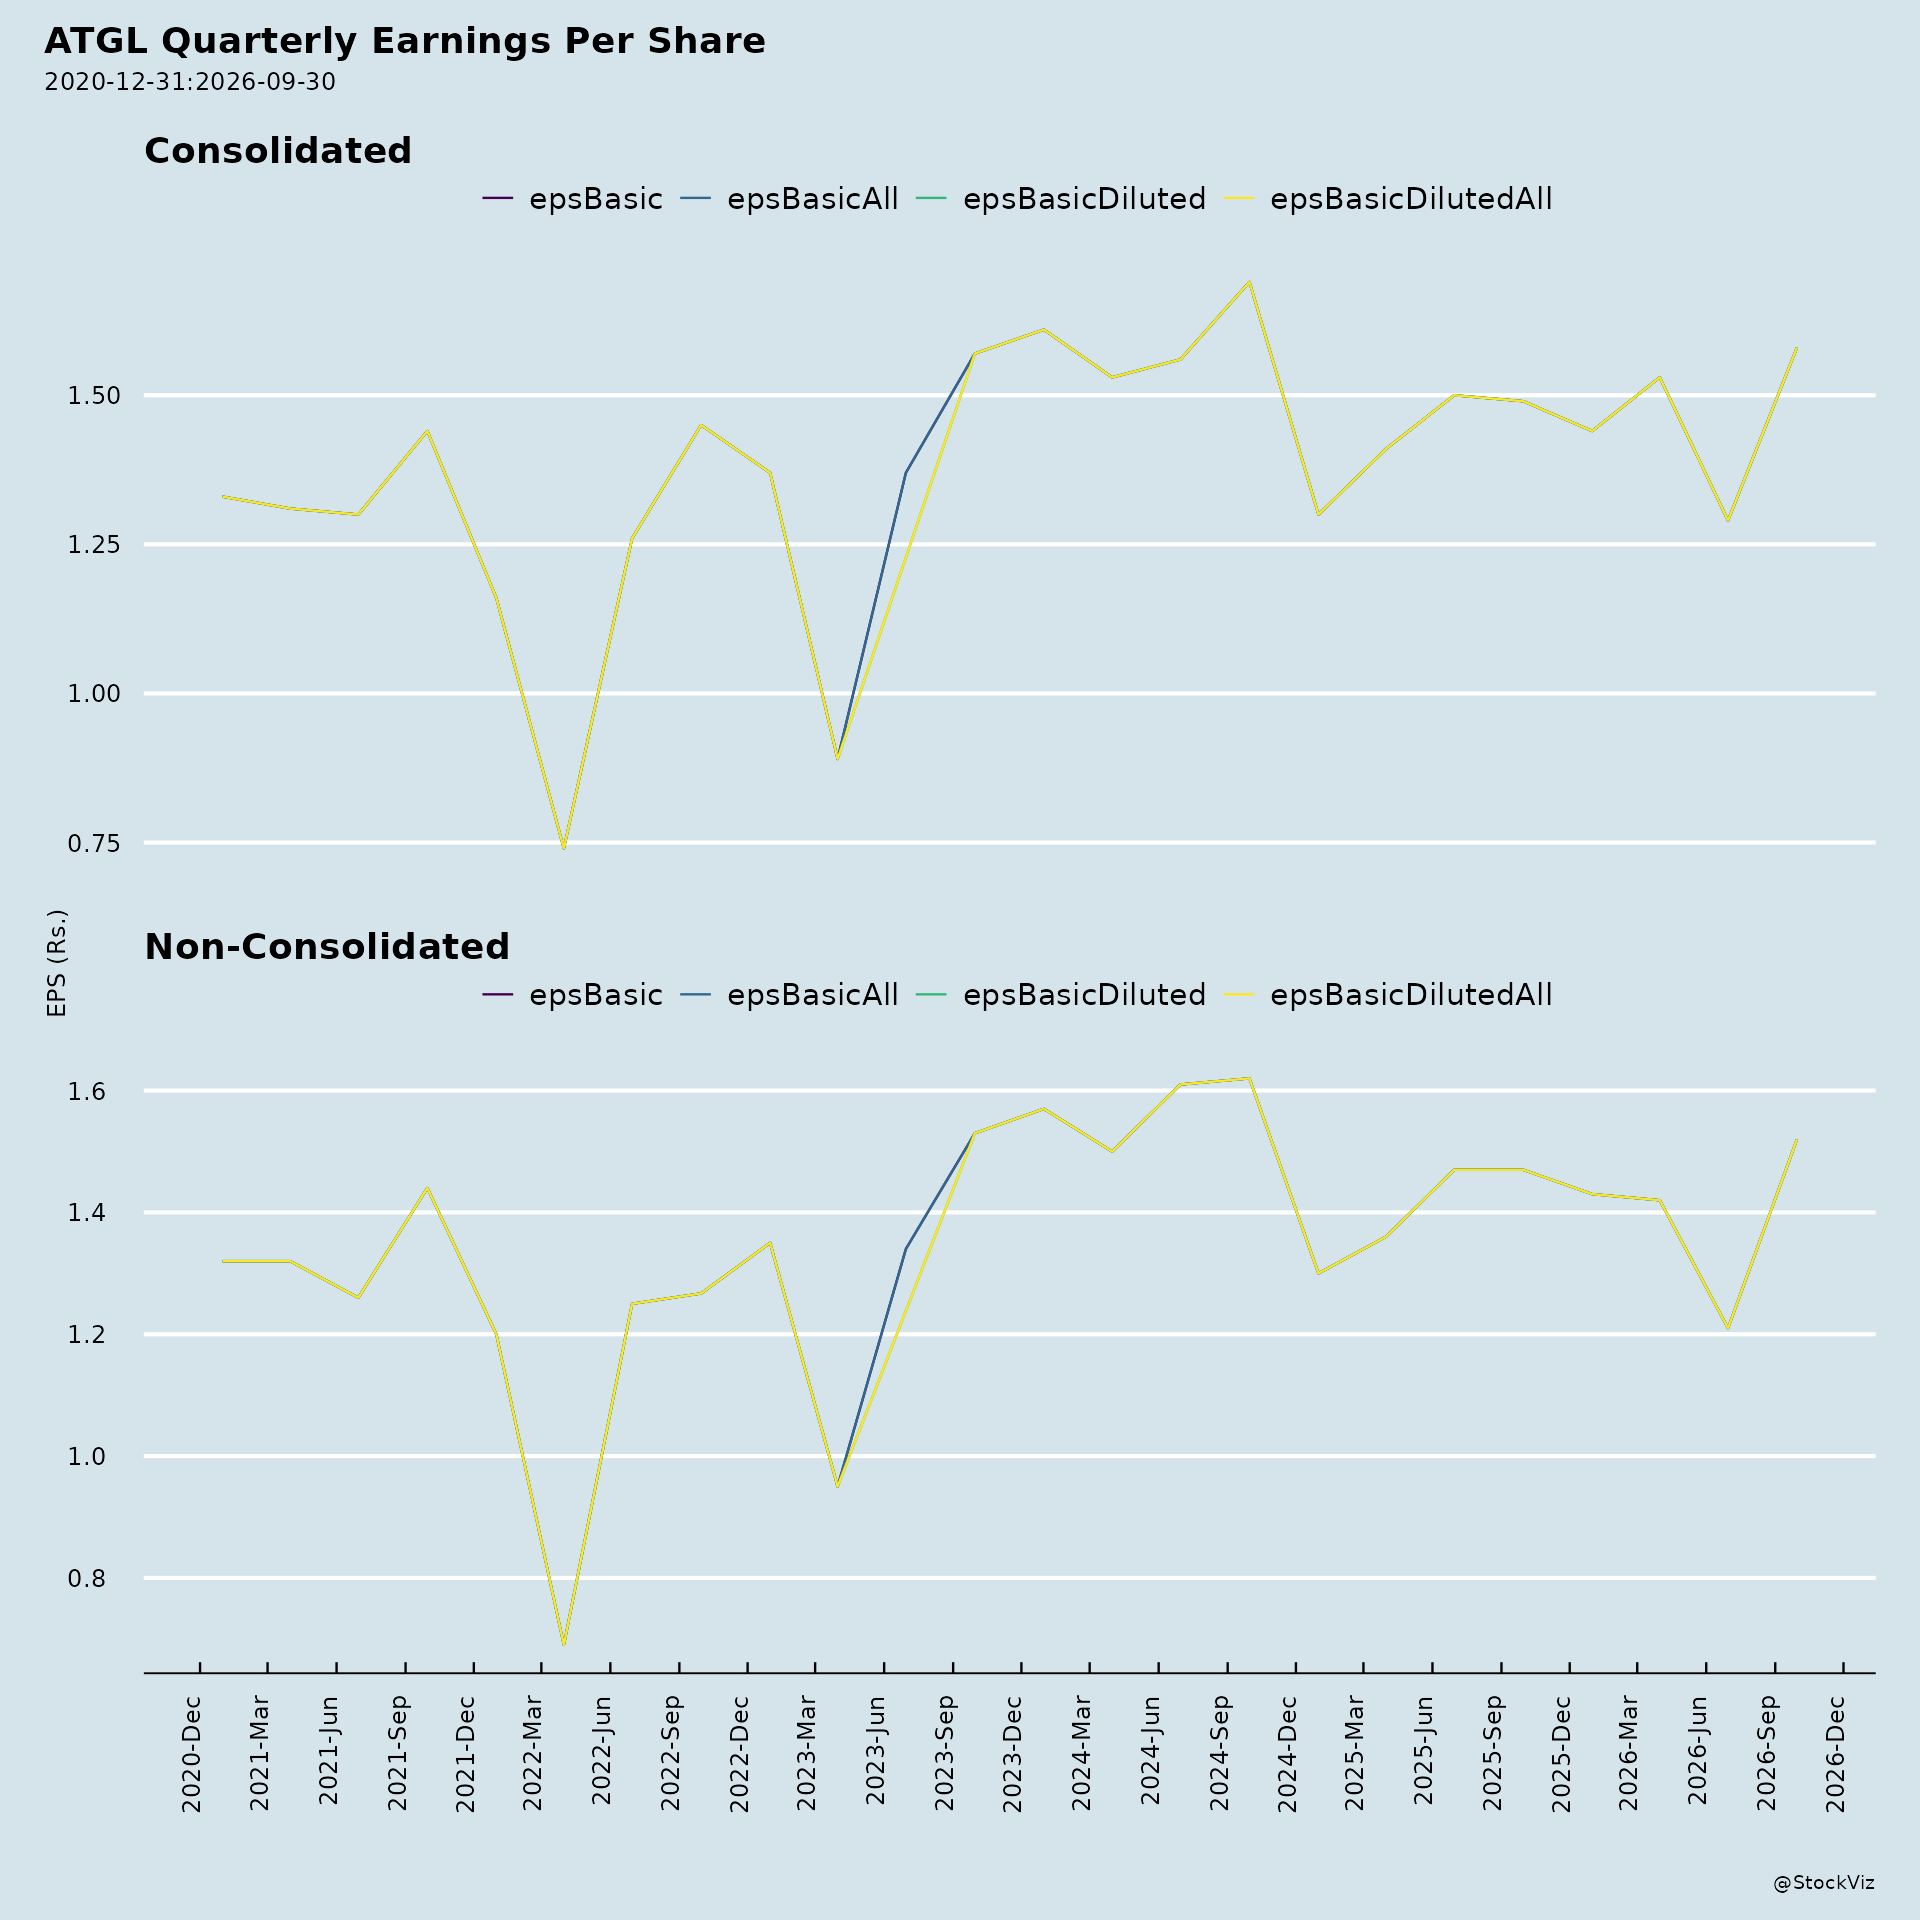
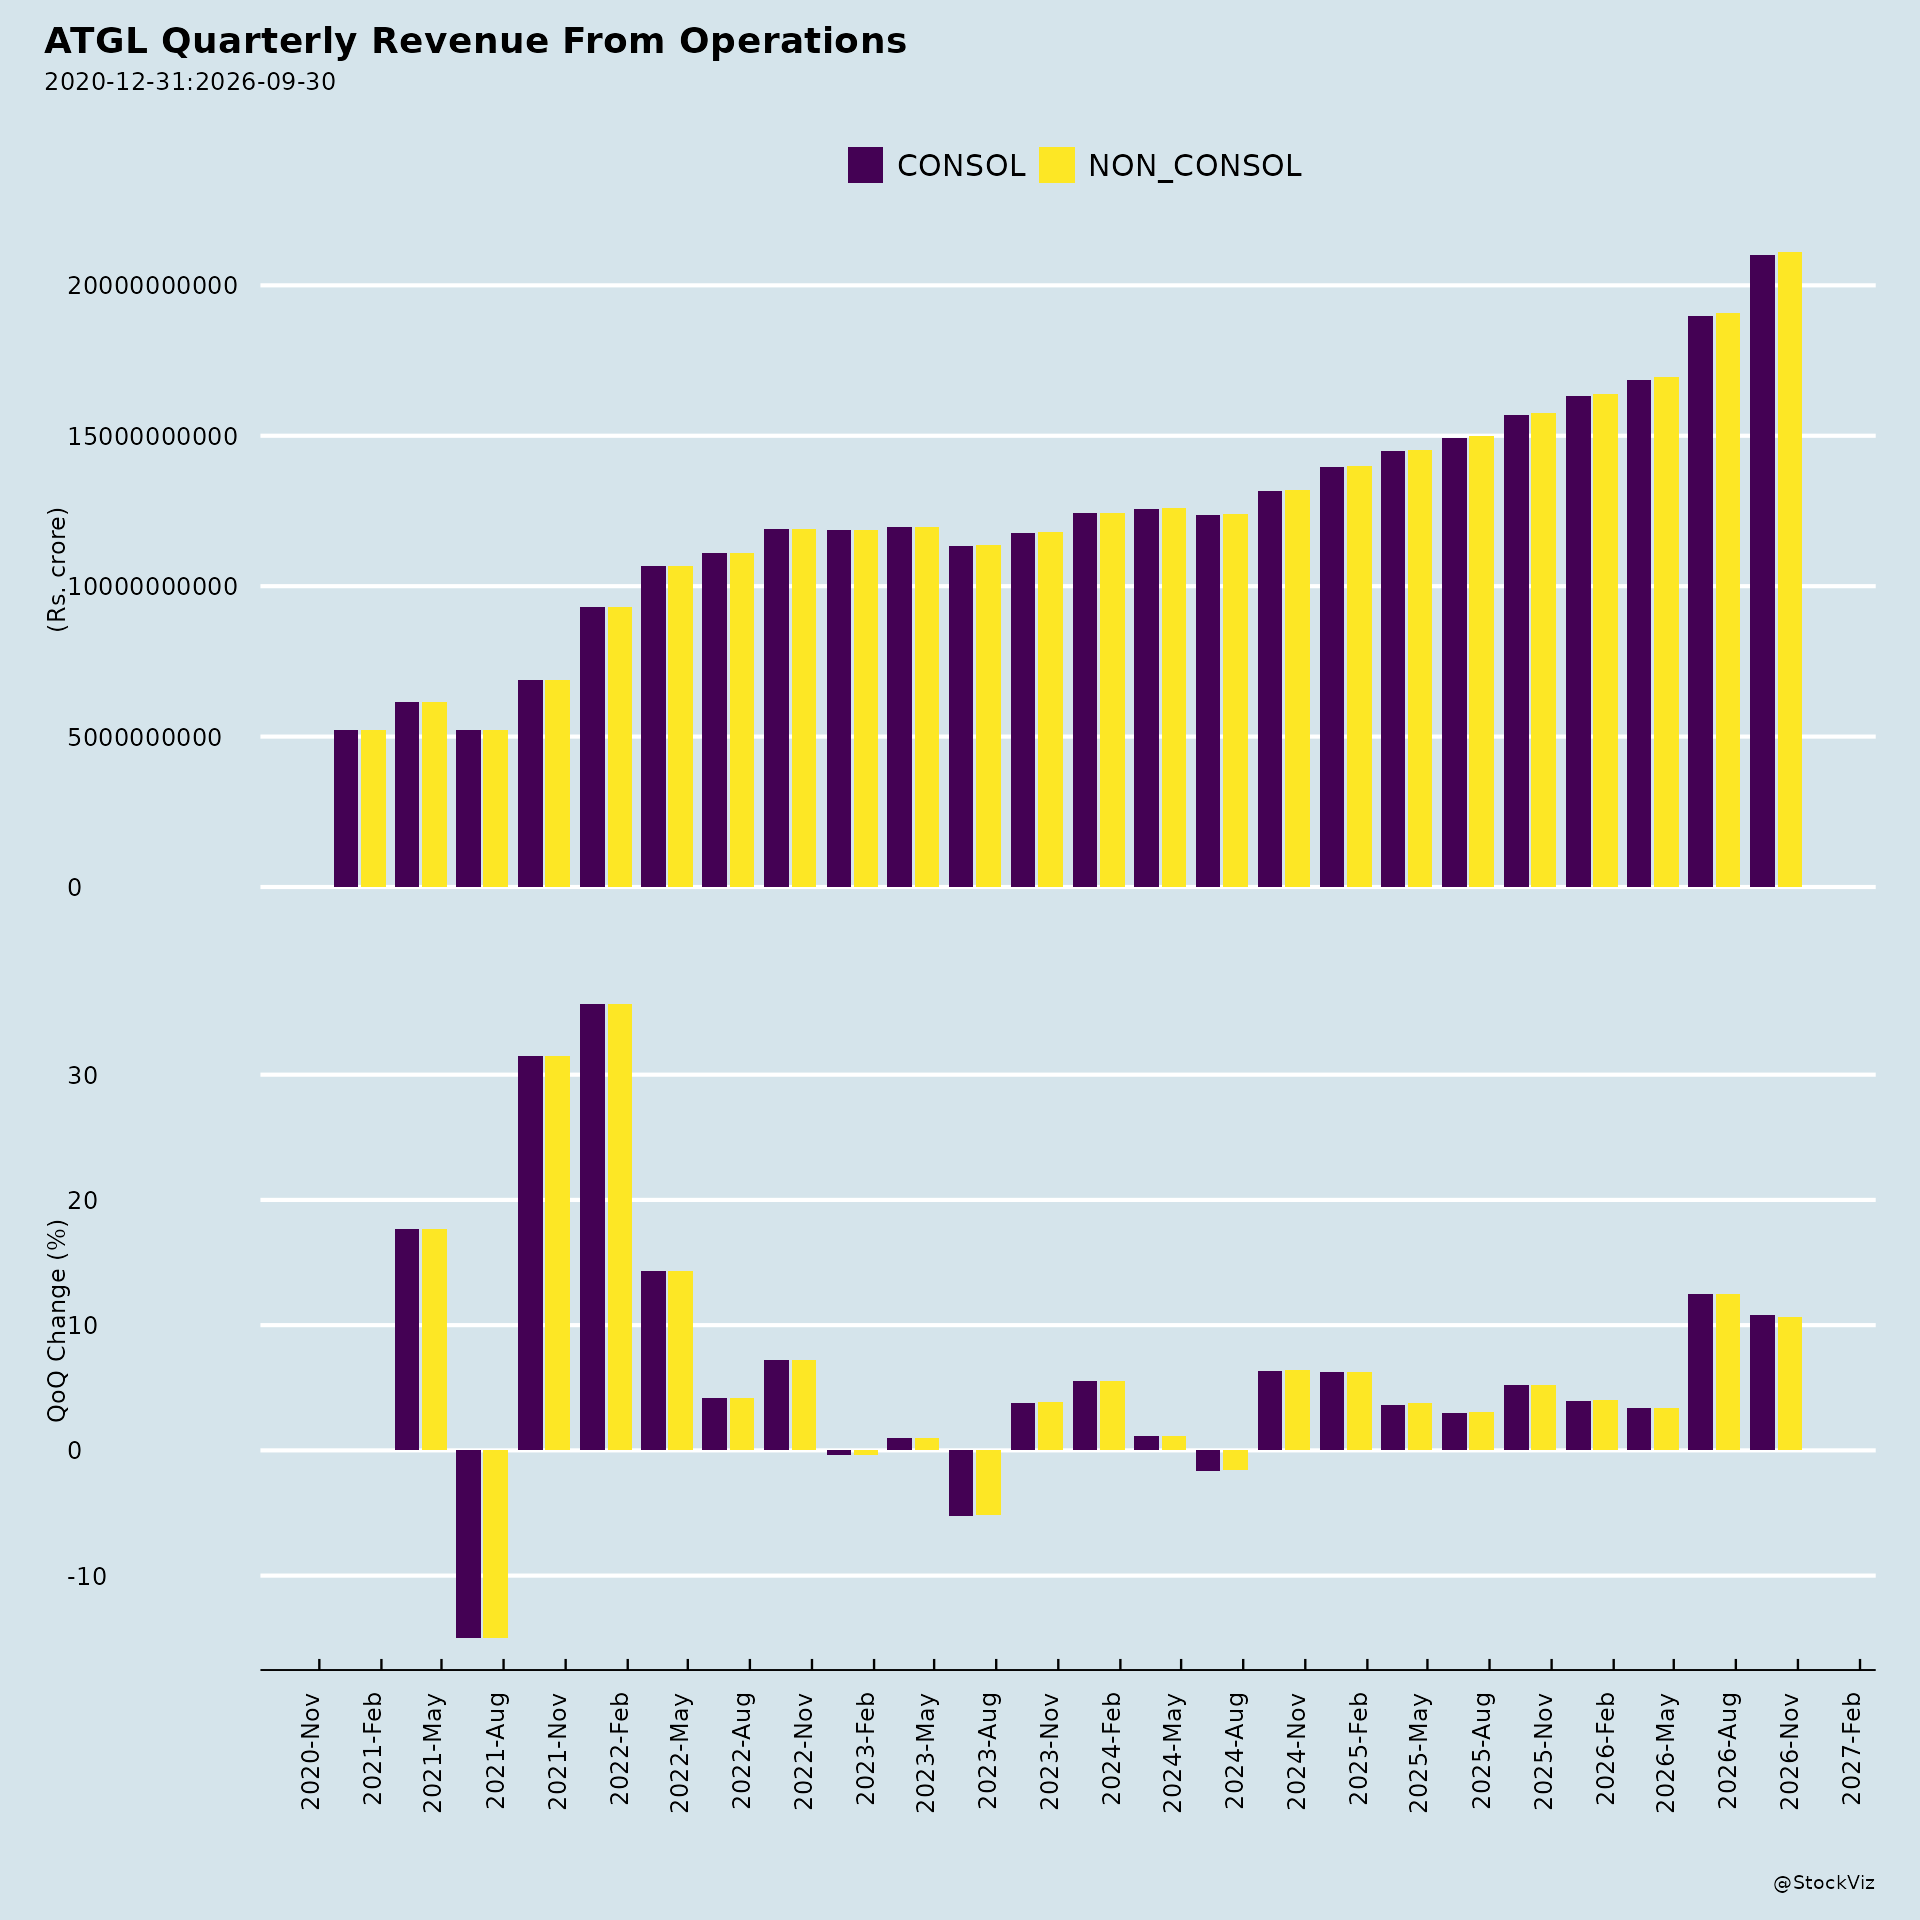
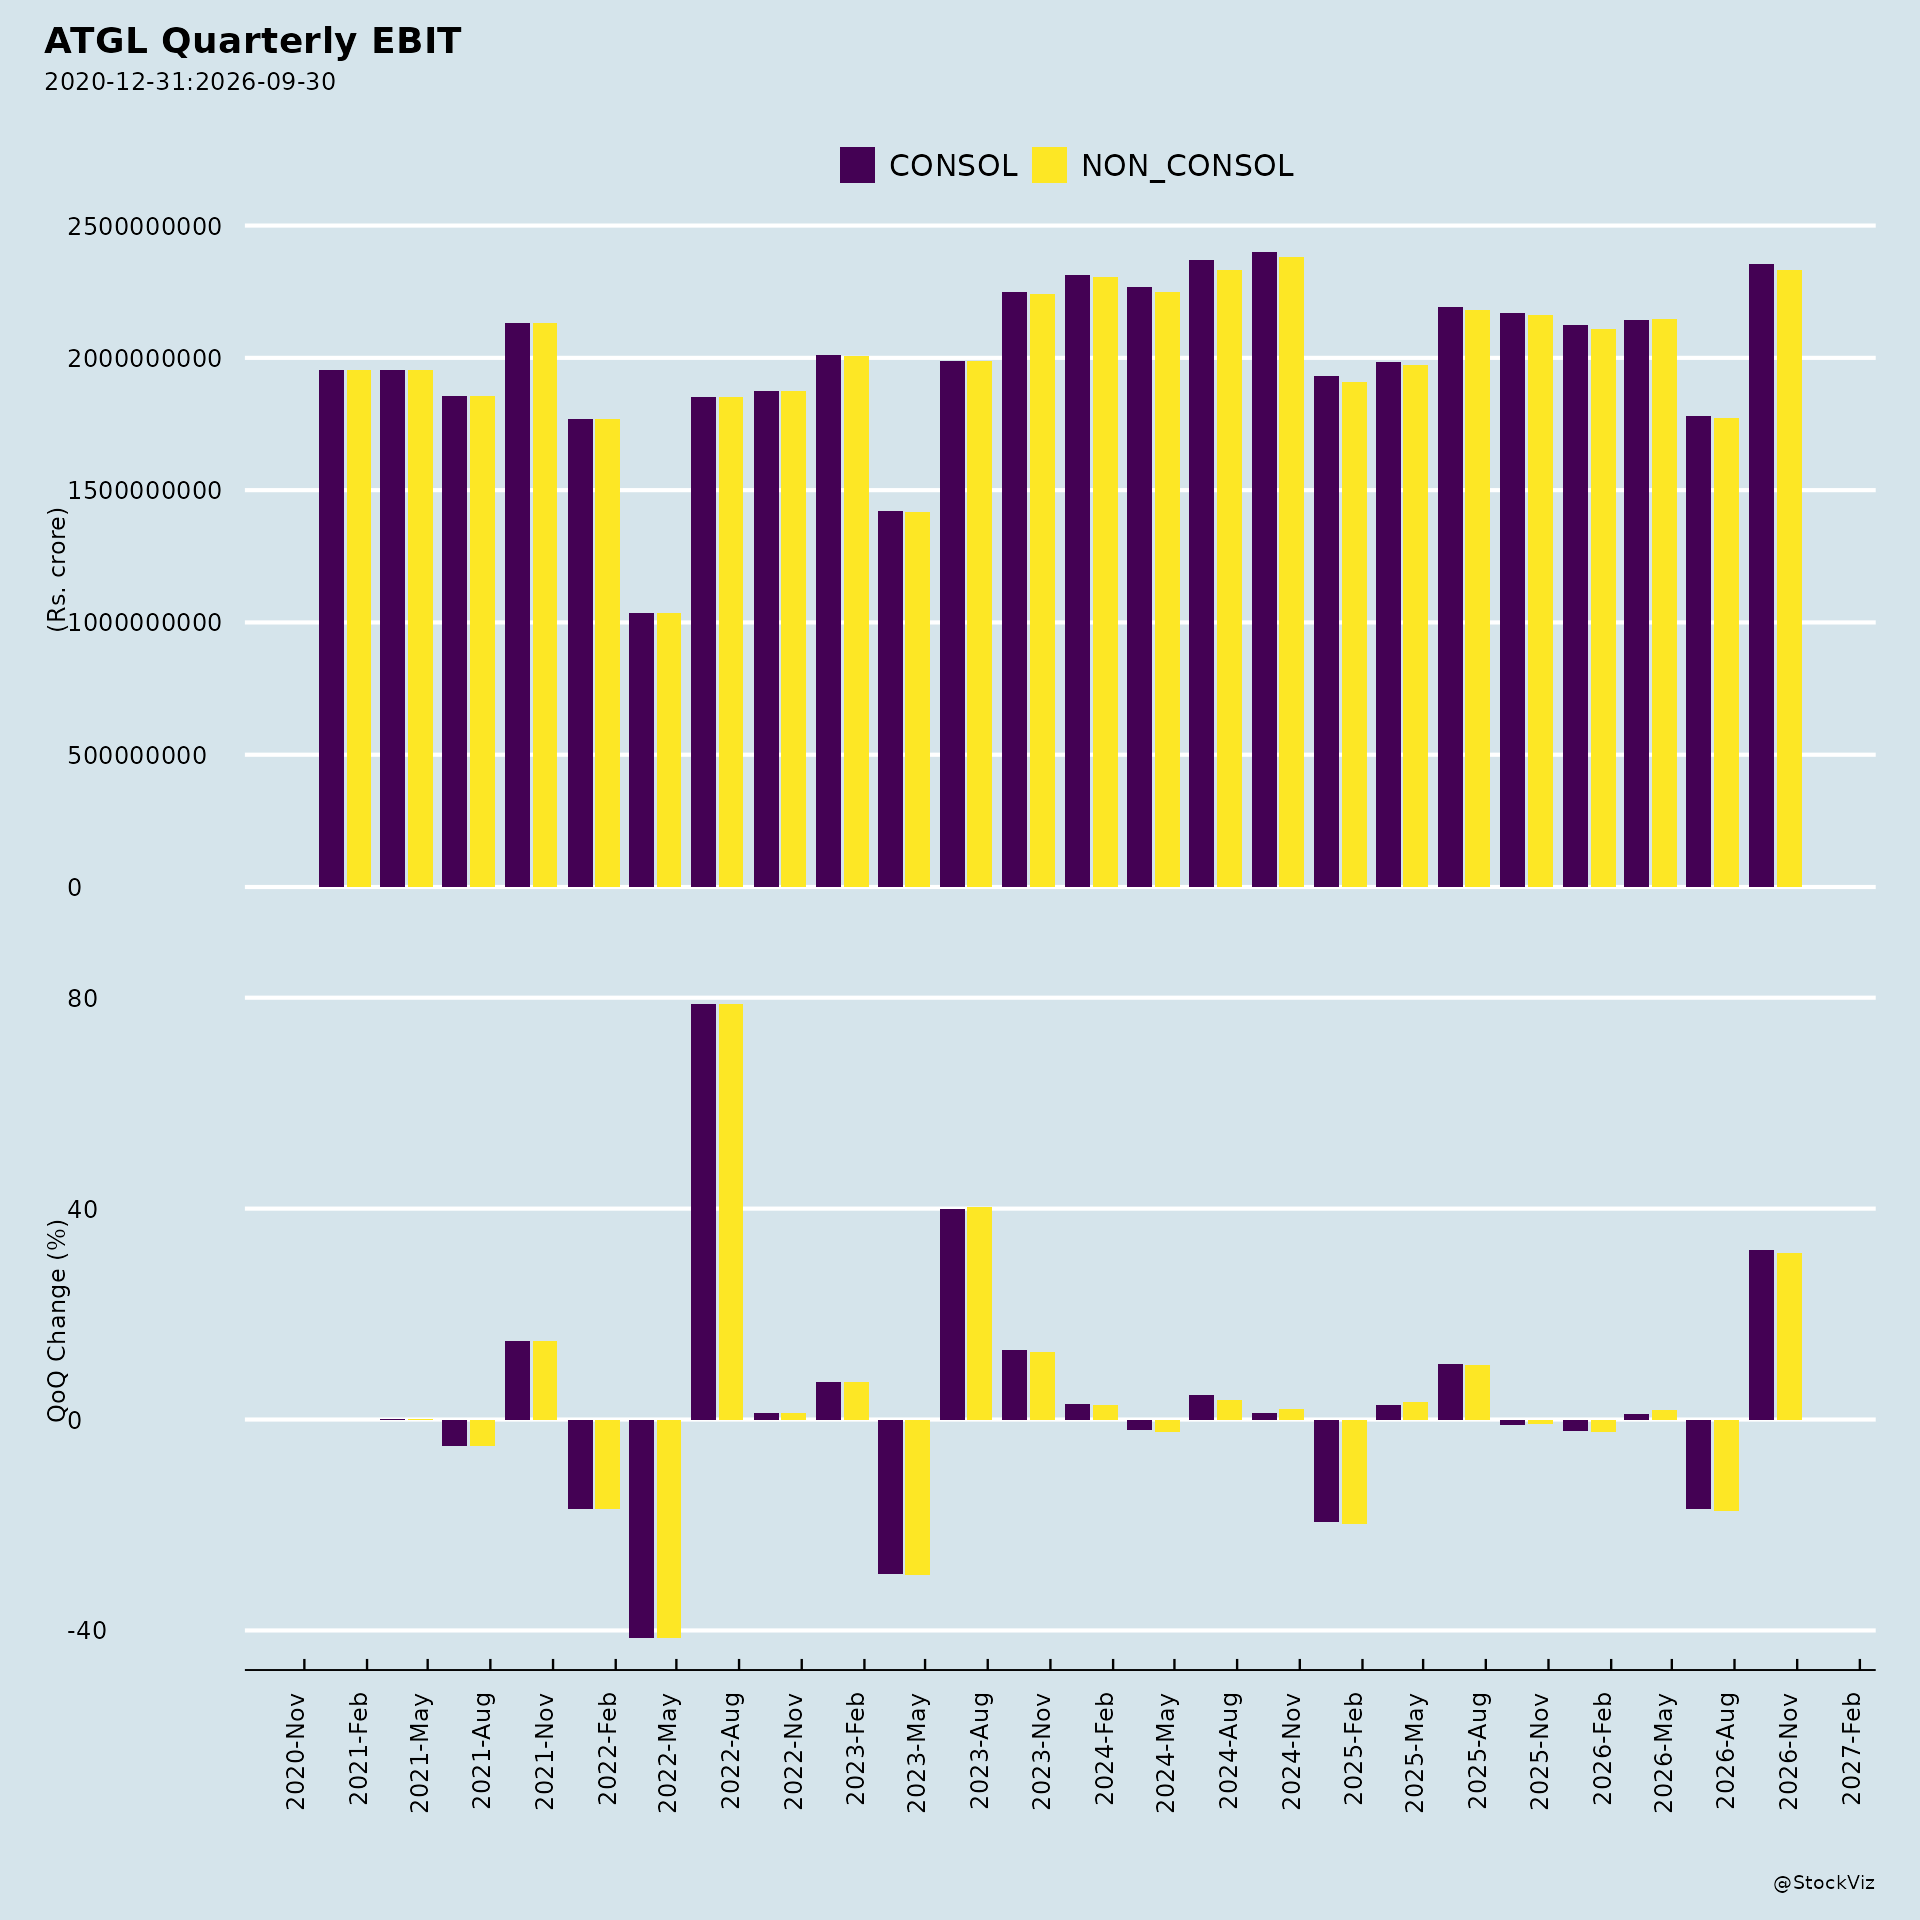
Margin compression despite volume growth. While revenue rose 27% YoY to INR 1,910 Cr and volumes rose 13% YoY to 303 MMSCM, EBITDA declined 7% YoY to INR 281 Cr, PBT fell 19% to INR 178 Cr, and PAT fell 18% to INR 133 Cr. Gross profit was nearly flat at INR 456 Cr (up 1%). The company describes taking a “calibrated approach” in passing on higher gas costs to avoid impacting volume growth.
Sourcing dynamics divergence. HH-indexed contract prices remained lower due to a soft index, while Brent-linked contracts were elevated.
2. Tailwinds and Growth Prospects
Volume and revenue growth. Standalone combined CNG and PNG volume reached 303 MMSCM in Q1FY27, up 13% YoY. CNG volume rose 18% YoY to 218 MMSCM; PNG volume rose 4% YoY to 85 MMSCM. Revenue grew 27% YoY to INR 1,910 Cr. Including the JV IOAGPL, combined volume was 496 MMSCM, up 13% YoY.
Network expansion. CNG stations increased to 707 (5 added in the quarter). PNG home connections reached approximately 11.41 lakh (38,243 added). Industrial and commercial connections reached 10,422 (448 added). Cumulative steel pipeline network reached approximately 15,987 inch-km (415 added). With IOAGPL, the combined network is 1,167 CNG stations and 28,675 inch-km of steel pipeline, with PNG home connections crossing 13.75 lakh.
New GA momentum. Registered 32% YoY growth in new GA volumes at 1.37 mmscmd from 1.04 mmscmd in Q1FY26. Volume mix for new GAs improved to 41% from 35% in Q1FY26.
Government and regulatory support. Timely interventions by the Government of India facilitated continuous gas supply and waiver of imbalance and system disciplinary charges, with supportive state government action on faster turnaround of statutory permissions.
New energy businesses. ATEL expanded to 5,306 installed EV charge points across 26 states/UTs and 226 cities, with installed capacity of approximately 58 MW. ATBL sold 323 MT of CBG in Q1FY27; FOM sales were 5,533 tons, of which 760 tonnes were sold through the Harit Amrit brand, registering 8x YoY growth. Harit Amrit launched organic fertilizer for the nursery segment.
ESG recognition. NSE Sustainability assigned an overall ESG Rating of “75” for FY2026, placing ATGL in the “Leader” category (announced August 11, 2026). CareEdge score rose to 84 from 83; CRISIL ESG score rose to 66 from 61. S&P DJSI score increased to 72 from 62. CDP rating improved to “A” from “B”. ATGL is rated AA+ (stable) by ICRA, CRISIL, and CARE.
Structural opportunity. Natural gas share in India’s fuel mix is projected to increase from 7% currently to 15% by 2030. ATGL is authorised in 34 Geographical Areas; with IOAGPL’s 19 GAs, the footprint covers 53 GAs across 125 districts.
3. Key Risks
Commodity and currency risk. Continued exposure to Brent-linked gas pricing, spot LNG volatility, and USD-INR movements, as evidenced by the 39% YoY rise in gas procurement cost.
Regulatory and allocation risk. APM allocation for the CNG segment declined to approximately 30% from 36% quarter-on-quarter, requiring reliance on higher-priced spot procurement.
Legal and governance matters. The standalone and consolidated financial results notes disclose that during FY2024-25, the company’s management became aware of an indictment filed by the US Department of Justice and a civil complaint by the US SEC against a non-executive director of the company in the United States District Court for the Eastern District of New York (EDNY). The indictment alleges three counts: (i) securities fraud conspiracy, (ii) wire fraud conspiracy, and (iii) securities fraud, for making false and misleading statements and omitting material facts. The director has filed a motion to dismiss the charges, and the US SEC and DOJ have filed motions for entry of final judgement upon consent without admitting or denying the allegations. As of March 31, 2026, various filings had been made by counsel, and the matter remained pending before the court. The company states that the director has not been named in these matters and that the matters do not pertain to the company, with no impact on the company as of the reporting date.
Regulatory proceedings. The company’s application for authorisation to lay, build, operate, and expand a City Gas Distribution network in Noida District (including Greater Noida) and for bifurcating the Faridabad GA into F1 and F2 was rejected by PNGRB through orders dated April 25, 2023, and April 26, 2023. The company filed an appeal before APTEL, which was disposed of with directions to PNGRB to adjudicate the matter. The company has sought suitable directions from PNGRB for compliance with the Hon’ble Supreme Court’s order. Separately, the company filed an appeal claiming deemed authorisation for Sanand, Bavla, and Dholka (Outer Ahmedabad City), which was disposed of by the Hon’ble Supreme Court on September 28, 2021.
Pending acquisition. The intended transaction for acquisition of three Geographical Areas — Jalandhar, Ludhiana, and Kutch (East) — under a Definitive Agreement signed on November 3, 2020, is yet to be consummated. During the year ended March 31, 2025, the authorisation for Jalandhar had been transferred to the company by PNGRB.
4. Management Guidance Versus Observed Business Performance
Management commentary. The CEO, Sanjay Pandita, stated that ATGL delivered robust growth in volumes (up 13% YoY) and revenue (up 27% YoY) in Q1FY27, driven by strong operational performance and increasing consumer preference for cleaner fuels. He noted the operating environment remained dynamic with elevated gas prices, higher Brent crude prices, currency volatility, and geopolitical developments negatively impacting global energy supplies. The company’s stated focus was on ensuring supply continuity, enhancing operational efficiency, safeguarding CNG and PNG consumers from undue risks, and creating long-term value. The company also stated it continues to focus on sustainable growth through disciplined network expansion, digital enablement, and development of its clean energy ecosystem across CNG, PNG, and e-mobility.
Observed performance against stated focus areas. The company’s stated focus on supply continuity and safeguarding consumers is reflected in the volume growth achieved despite cost pressures — CNG volumes rose 18% YoY and PNG volumes rose 4% YoY, while the company absorbed margin compression (EBITDA down 7% YoY, PAT down 18% YoY) rather than passing on the full cost increase. The stated focus on network expansion is evidenced by the addition of 5 CNG stations, 38,243 domestic PNG connections, 448 industrial and commercial connections, and 415 inch-km of steel pipeline during the quarter. The stated focus on the clean energy ecosystem is reflected in the expansion of EV charge points to 5,306 and CBG sales of 323 MT.
ESG targets versus achievements. The presentation lists targets for FY2025-26 including sustaining 100% decarbonization of fleet, 10 MW open access solarization, 50,000 tree plantation, 3,500 km gas grid surveyed, LTIFR below 0.5, and 100% coverage of all plants and offices. Reported achievements include 655+ HCV fleets running on low carbon fuel, cumulative solar capacity increased to 1 MW with 10 MW ongoing captive open access solar projects, 50,000 tree plantation activity in progress at Pusad with an additional 1 lakh trees at Bhilwara under progress, 2,257 km covered for methane leak detection and repair survey, 6 million continuous safe man hours with 0.00 LTIFR, and 5,828 safety training hours in Q4.
Investor interaction. The company will interact with investors and analysts at the Motilal Oswal 2026 Conference in Mumbai on Wednesday, August 19, 2026, in one-on-one and group meeting format (physical), subject to change due to exigencies.
AGM outcomes. The 21st Annual General Meeting was held on June 25, 2026, at 5:00 pm through video conferencing. All six ordinary resolutions — adoption of audited standalone financial statements, adoption of audited consolidated financial statements, declaration of dividend for FY2025-26, re-appointment of Mr. Gautam S. Adani as director, re-appointment of Dr. Sangkaran Ratnam as director, and ratification of remuneration payable to M/s. N D Birla & Co. as cost auditors for FY2026-27 — were passed with the requisite majority.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.