ARKADE
Equity Metrics
November 18, 2026
Arkade Developers Limited
Residential Commercial Projects
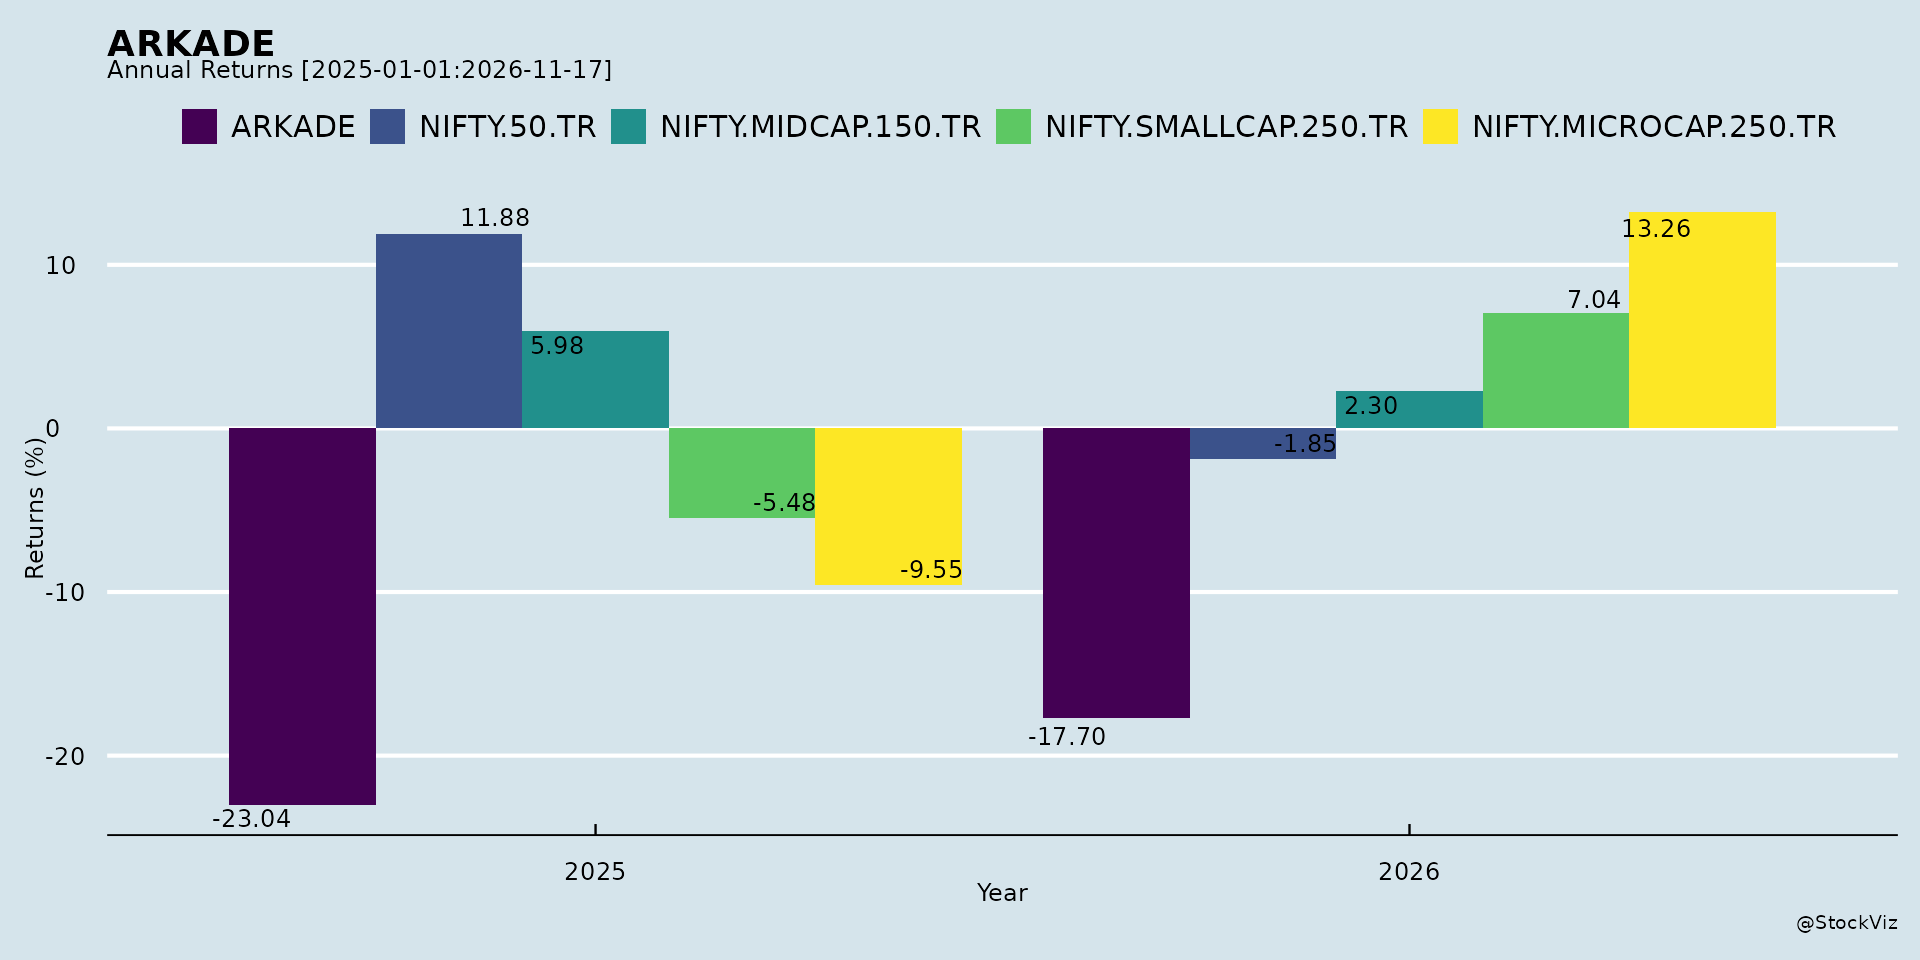
Annual Returns

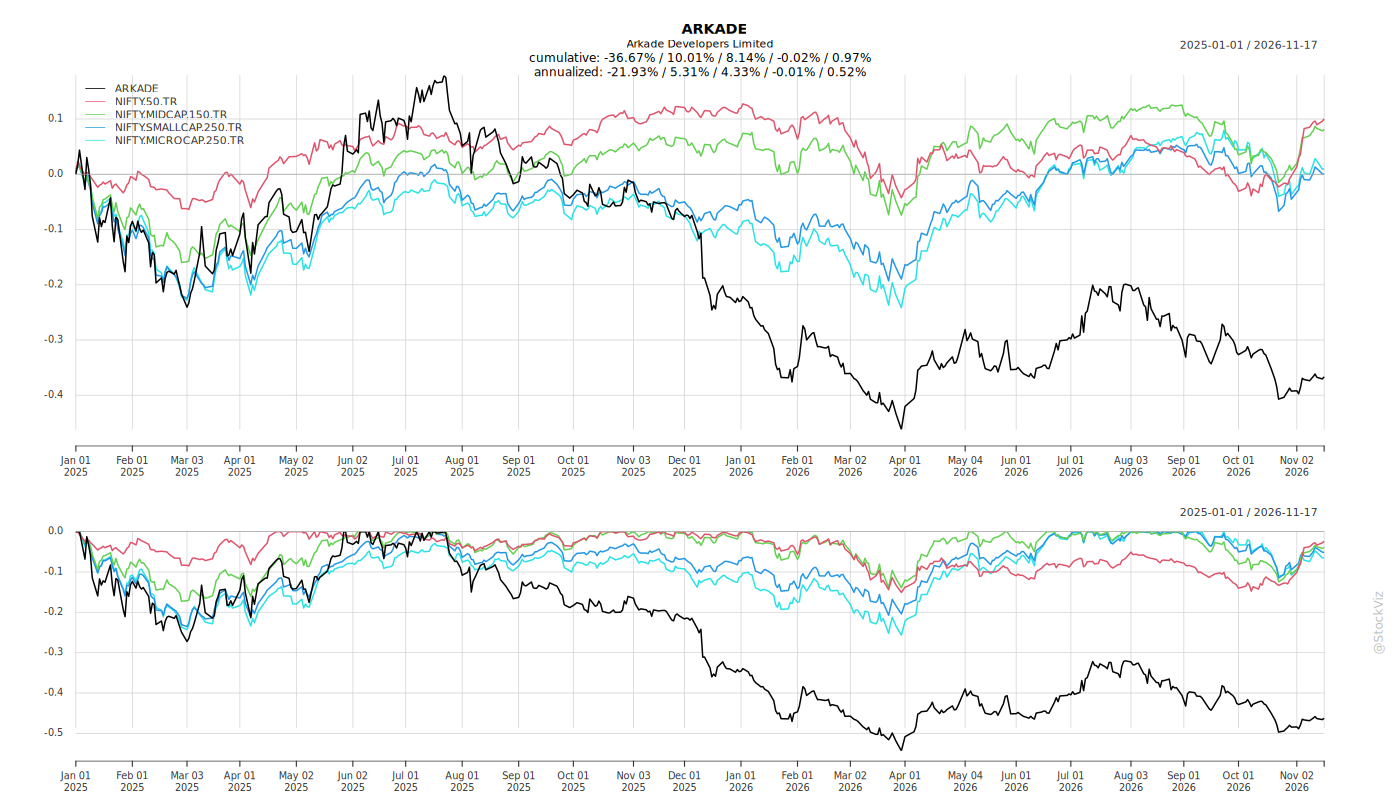
Cumulative Returns and Drawdowns
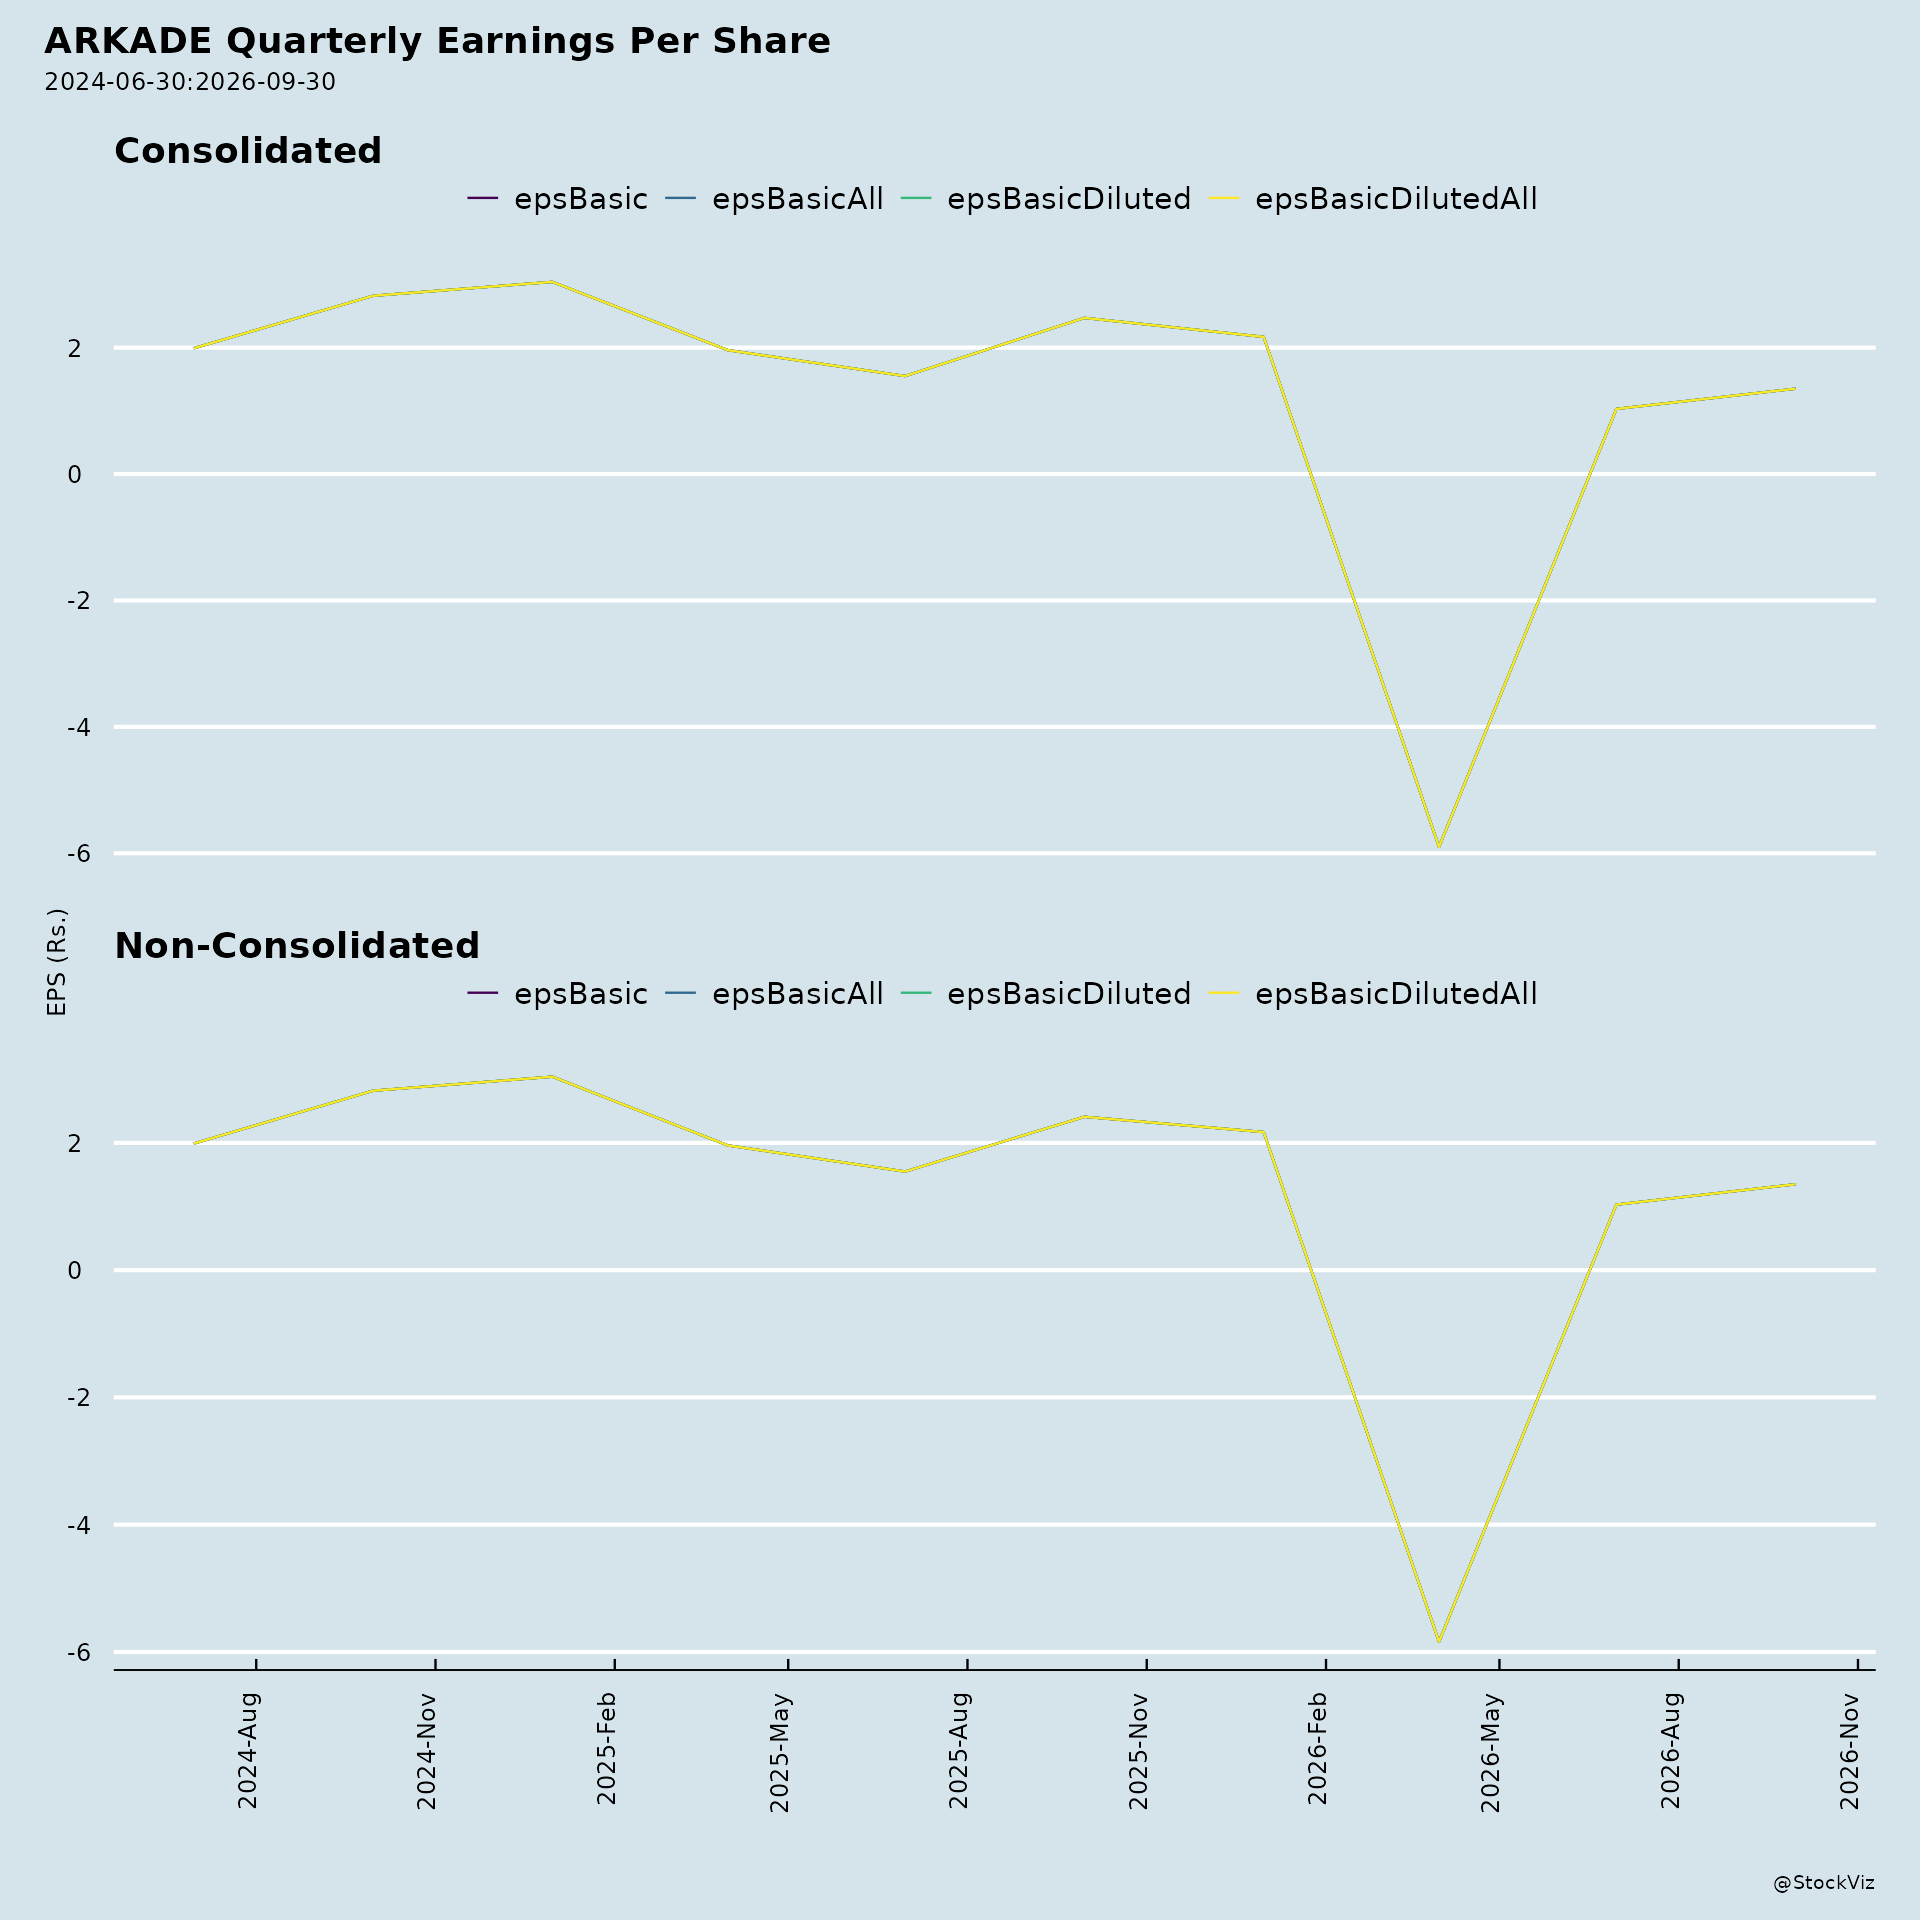
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-18
Arkade Developers — Recent Corporate Developments
1. Headwinds and Challenges
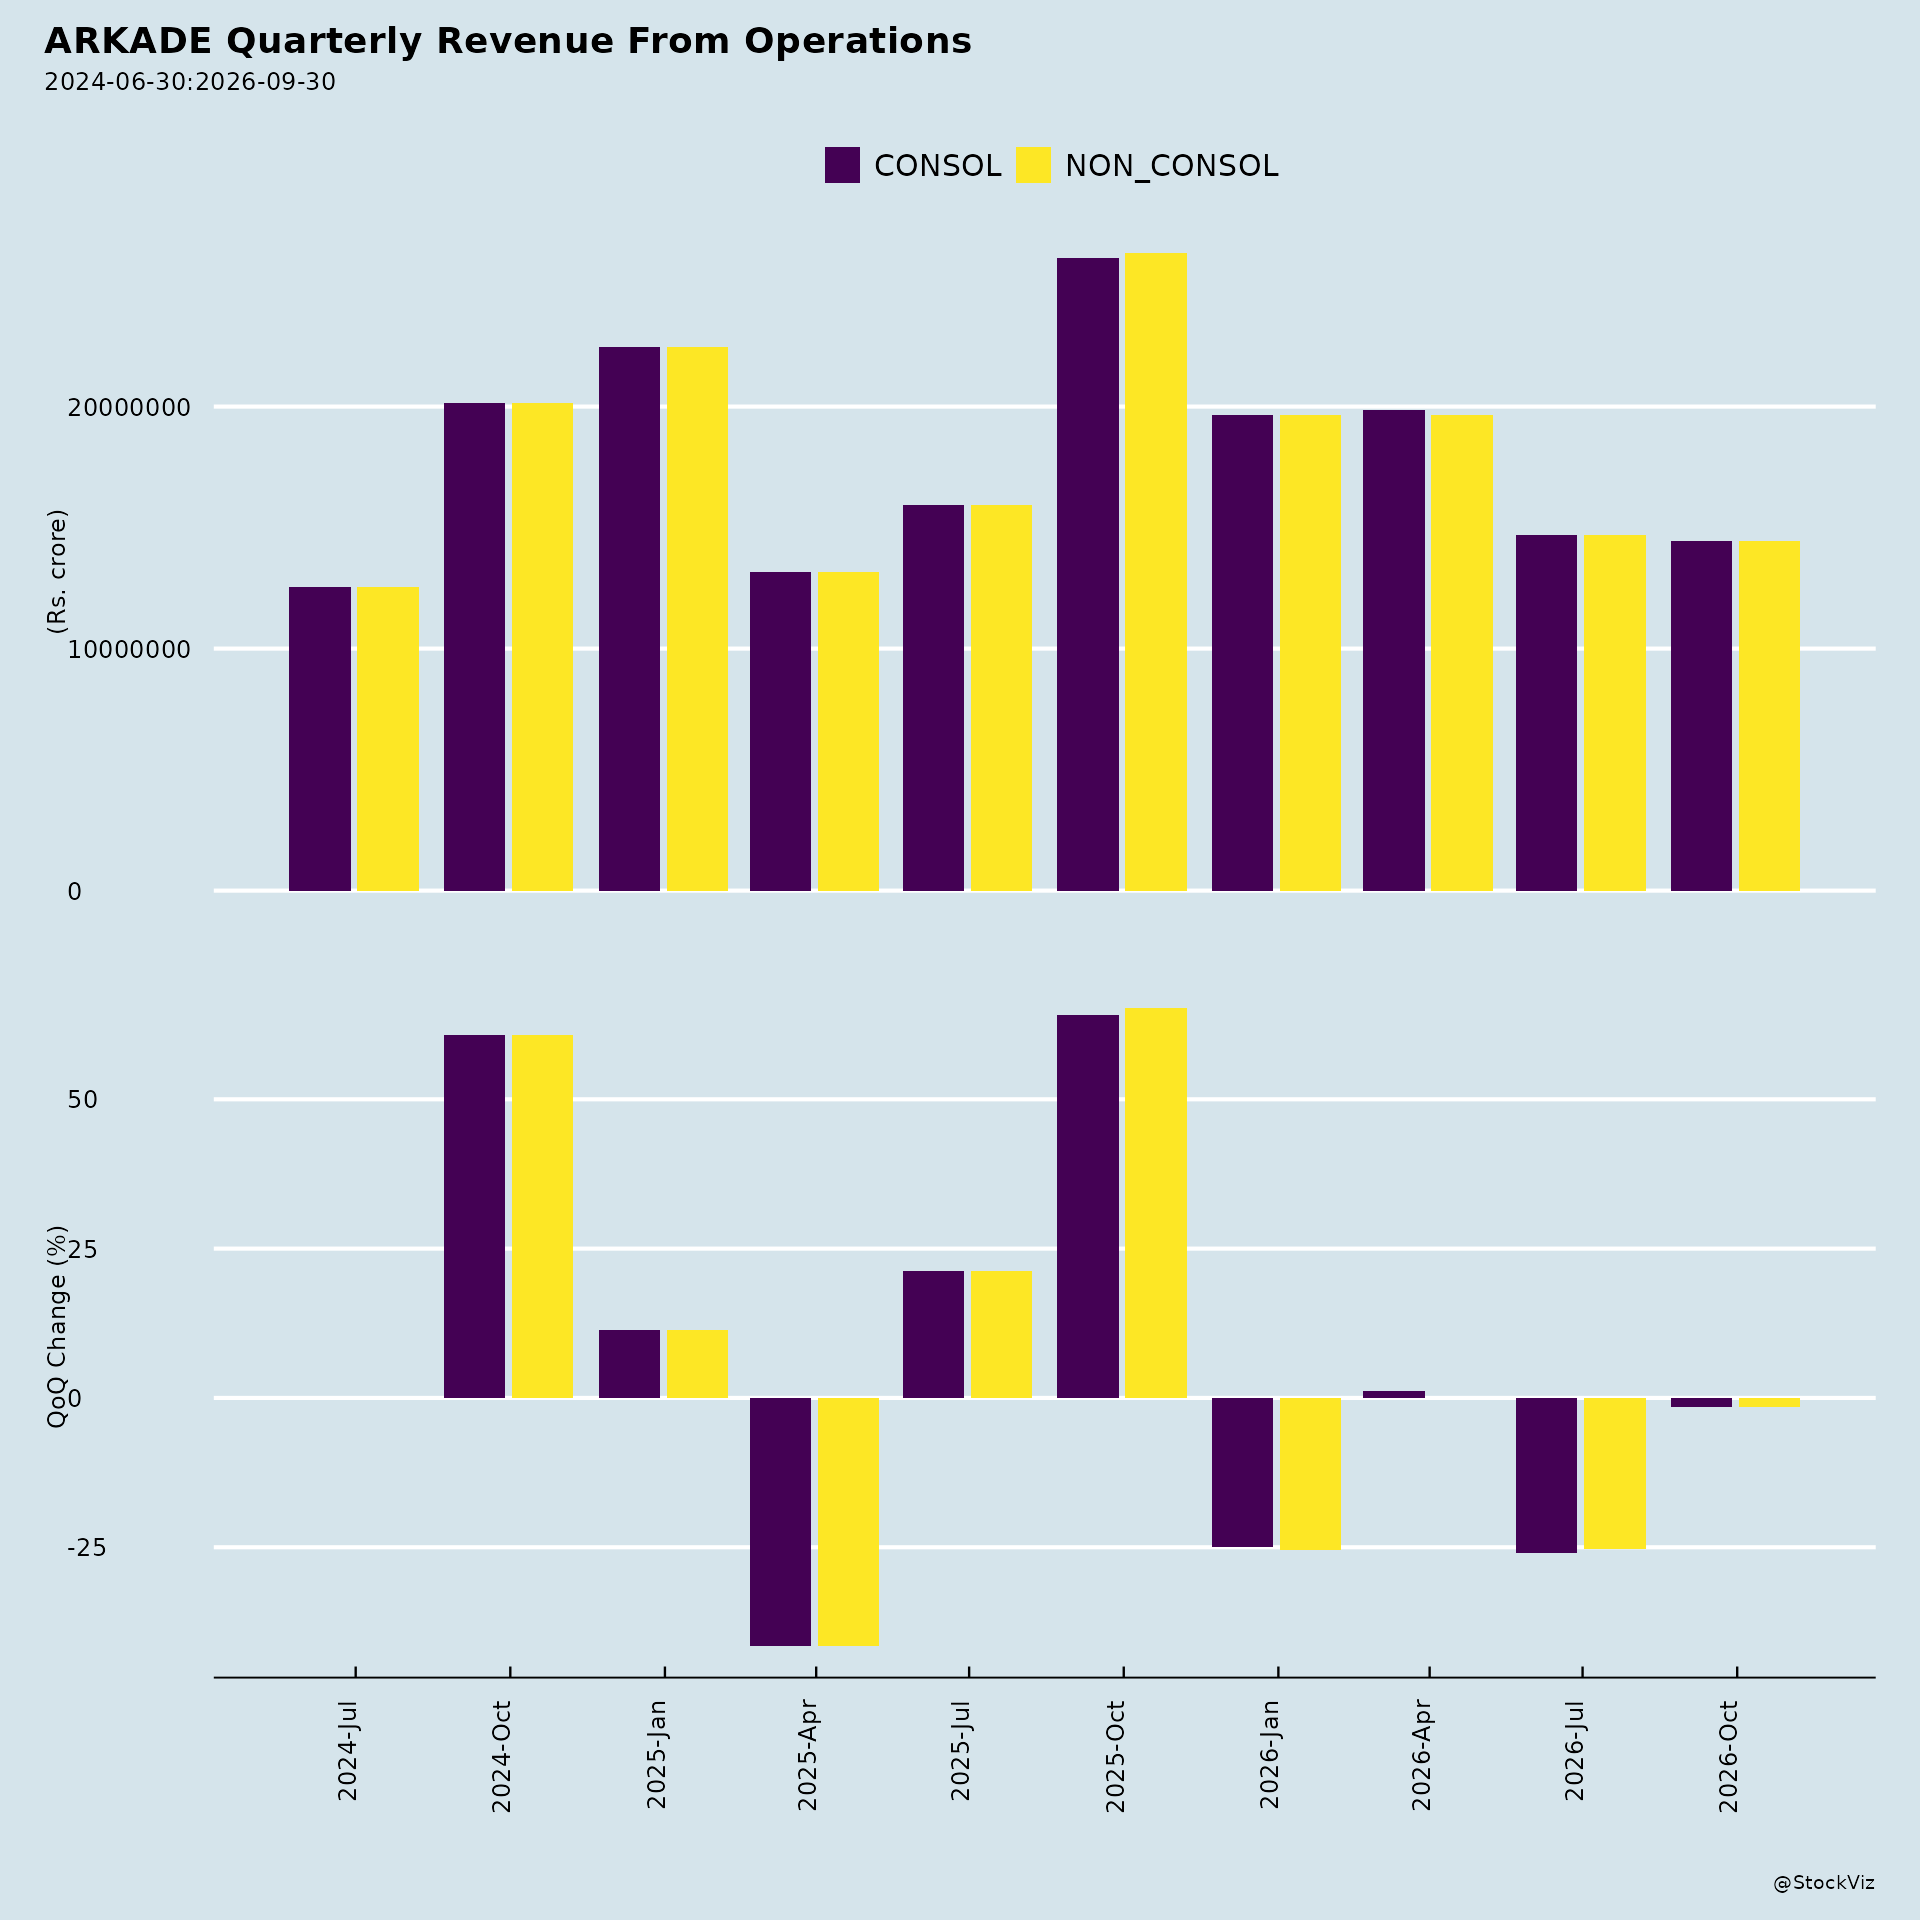
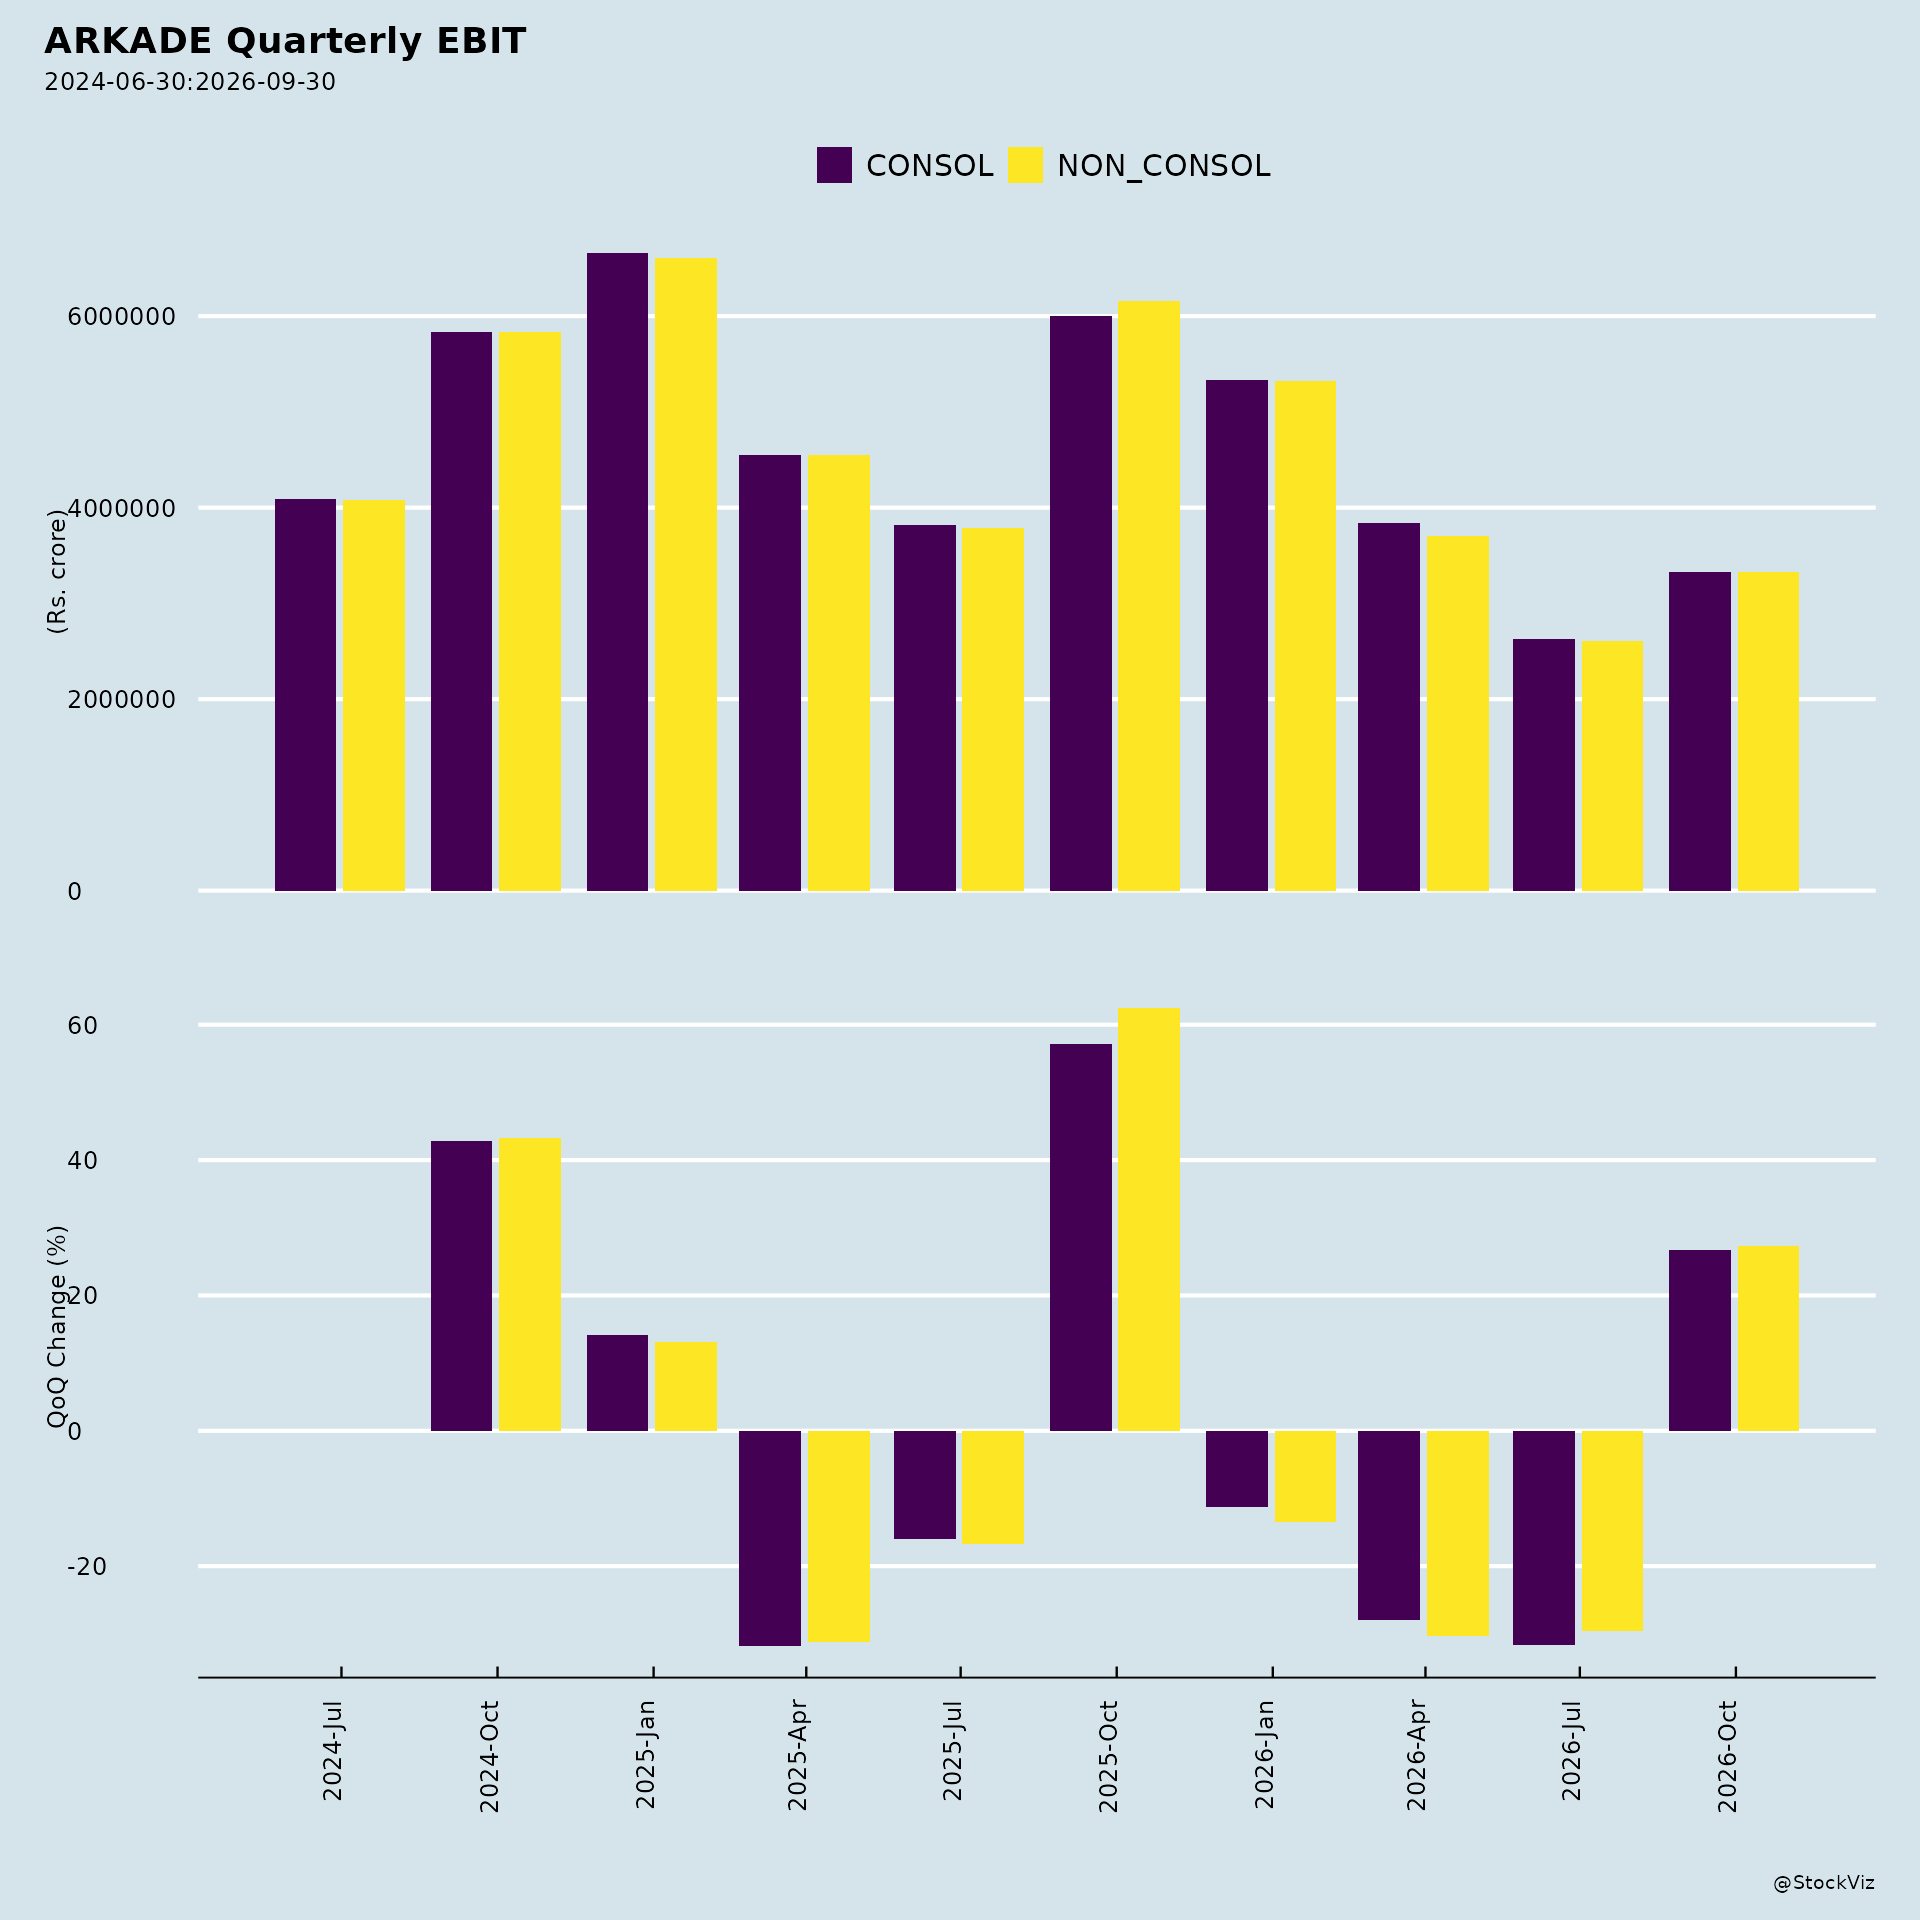
Q1 FY27 earnings decline. For the quarter ended June 30, 2026, revenue from operations was ₹14,697.04 lakhs, down from ₹15,944.58 lakhs in the same quarter a year earlier. Profit for the period fell to ₹1,921.35 lakhs (standalone) from ₹2,875.53 lakhs, and basic/diluted EPS declined to ₹1.03 from ₹1.55. Other income also declined year-on-year, attributed to lower investment income compared to the prior-year period, which had benefited from unutilized IPO proceeds. Employee costs increased as the company strengthened its organizational capabilities.
Impairment charge. An exceptional item of ₹18,217.09 lakhs was recognised as diminution in the value of investment, following the demerger of Filmistan Private Limited’s rental business and Goregaon tenancy rights into Arkade Developers, approved by the NCLT Mumbai Bench by order dated March 16, 2026 with an appointed date of August 1, 2025. Because the economic cost of the tenancy is now embedded in the Goregaon land and the investment in FPL, the component representing extinguished tenancy rights no longer has the potential to produce future economic benefits. This drove a loss for the quarter ended March 31, 2026 (standalone loss of ₹10,834.81 lakhs; consolidated loss of ₹10,956.61 lakhs).
Alleged employee misconduct and ongoing investigation. During the quarter, the company identified alleged acts of misconduct and irregularities involving a former senior employee, including alleged diversion of customer transactions through brokerage entities, alleged wrongful financial gain through brokerage and vendor-related transactions, and alleged preparation and registration of agreements bearing forged signatures relating to additional car parking transactions. An FIR has been registered and the matter is under investigation. The auditors drew attention to this matter by way of an Emphasis of Matter in both the standalone and consolidated limited review reports, noting that the ultimate outcome and any consequential financial impact cannot presently be determined. Management has stated that no material adjustment is considered necessary based on presently available information, and that internal control, compliance and approval processes have been strengthened.
GST demand. The company received an order dated July 9, 2026 (received July 10, 2026) from the Assistant Commissioner, Central GST and Central Excise, Division III, Thane Commissionerate, imposing a tax demand of ₹13,73,857 for FY 2022-23. The alleged contraventions relate to availment of ITC for certain transactions, GST payable on TDRs, and interest on availment of ITC. The company stated there is no material impact on financial and operational activities and is taking legal opinion and considering an appeal.
2. Tailwinds and Growth Prospects
Four new cluster redevelopment projects in Western Mumbai. Announced August 19, 2026, these span approximately 45,204 sq. m. (11.17 acres) across Malad West, Kandivali West, Kandivali East and Borivali West, with aggregate projected saleable carpet area of approximately 15 lakh sq. ft., projected turnover potential of around ₹5,000 crore, and estimated construction area of approximately 51 lakh sq. ft. Breakdown: - Ashok Nagar (Kandivali East) and Shankar Lane (Kandivali West): plot area ~12,611.5 sq. m., projected saleable carpet area 3.5 lakh sq. ft., estimated GDV ₹1,100 crore. - Malad West: ~8,428 sq. m., projected saleable carpet area 2.5 lakh sq. ft., turnover potential ~₹900 crore. - Yogi Nagar – Plot B, Borivali West (largest): ~24,165 sq. m., projected saleable carpet area 9 lakh sq. ft., turnover potential ~₹3,000 crore.
Development pipeline and launch plans. The company reports an estimated GDV of ₹128 billion across nearly 4.25 million sq. ft. of saleable carpet area, with projects estimated at approximately ₹30 billion GDV planned for launch during FY27. Structured growth opportunities in redevelopment are noted as representing 60–65% of Mumbai’s residential pipeline.
New micro-market expansion. Growth prospects cited include a 6.2-acre premium greenfield project in Kasarvadavali, Thane (projected GDV ₹2,000 crore), a 4.1-acre greenfield development at Filmistan, Goregaon West (expected GDV ₹3,500 crore), a Bhandup project (projected GDV ₹760 crore), and Arkade Nest Mulund (projected GDV ₹630 crore). A planned commercial vertical is intended to generate long-term annuity income.
Delivery track record. The company cites the Occupancy Certificate received at Arkade Eden, Malad West, nine months ahead of the committed RERA date, as evidence of execution capability. It reports 32 completed projects, 5,500+ homes delivered, 5.5+ million sq. ft. developed, and 2+ million sq. ft. under development.
Sector outlook. Management cites expectations that real estate’s contribution to GDP will rise from 7.3% to nearly 15% by 2030, alongside continued market expansion, urbanization, technology advancement and evolving consumer preferences.
Employee alignment. The proposed Arkade Employee Stock Option Plan 2026 (covering up to 0.11% of total post-issue capital, not exceeding 2,00,000 equity shares, extendable to subsidiary employees and directors) is intended to attract, retain, reward and motivate talent and align employee interests with shareholders.
3. Key Risks
- The outcome and financial impact of the ongoing investigation into alleged misconduct by a former senior employee cannot presently be determined; the matter is before investigating authorities.
- The GST demand for FY 2022-23, while assessed as not material, remains subject to legal opinion and a potential appeal.
- The impairment of investment in Filmistan Private Limited reflects the loss of future economic benefits from extinguished tenancy rights following the demerger.
- The company operates in a single reportable segment, Real Estate Development, concentrating exposure in one business line.
- Consolidated results include subsidiaries and associates whose interim financial information was not reviewed by the principal auditors in certain cases; the auditors relied on other auditors’ reports and management-provided unaudited results for those entities.
4. Management Guidance Versus Observed Performance
Management expects accelerated growth in the coming quarters, supported by sustained project performance and upcoming launches, with approximately ₹30 billion GDV of projects planned for launch during FY27 to drive near-term growth. The company also points to a strong pipeline of ₹128 billion GDV and a low net debt-to-equity ratio of 0.01x as of June 30, 2026.
Against this, observed Q1 FY27 performance showed revenue from operations of ₹1,470 million, EBITDA of ₹278 million (18.91% margin), and PAT of ₹191 million (12.99%) — with revenue, profit and EPS all lower year-on-year, and other income lower due to the absence of the prior-year benefit from unutilized IPO proceeds. The quarter also carried the ₹18,217.09 lakh exceptional impairment charge and the disclosed investigation. The August 19, 2026 announcement of four new redevelopment projects with ~₹5,000 crore turnover potential represents pipeline additions whose conversion into revenue is yet to be reflected in reported results.
Broker Narrative
Initially, the broker paired a Buy with explicit risks—supply moderation, flattish realizations, weak launches, and booking shortfalls—while leaning on demand, market-share gains, and launch pipelines. By the final report, those headwinds were omitted entirely and the case became unreservedly bullish, citing 20% presales CAGR, low leverage, geographic scaling, commercial expansion, and infrastructure catalysts. The persistent theme was large-developer growth and a strong launch pipeline, but the early caution about launch/bookings weakness was replaced by no-headwind conviction.
Fears that came true
- The flagged absence of new project launches and weak bookings for specific developers correlated with the 2025 DISAPPOINTMENT outcomes, including -36.8% after the final Buy.
- The warning of moderate new launches/lack of significant launches in certain regions was borne out in the stock’s later negative actual returns (-21.6%, -27.8%, -36.8%).
- The concern over supply moderation and flattish realization trends matched the eventual valuation decline, with the last three actual returns deeply negative.
Optimism that failed
- Robust on-ground demand and strong launch pipelines did not produce the expected positive outcome, as the stock delivered DISAPPOINTMENT returns in 2025.
- The assumption that large developers with meager inventory and continued market-share gains would drive gains failed to prevent -36.8% actual return.
- The final report’s confidence in strong presales growth and infrastructure-led visibility did not translate into positive price performance, with all 2025 actuals negative.
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.