APOLLOHOSP
Equity Metrics
September 24, 2026
Apollo Hospitals Enterprise Limited
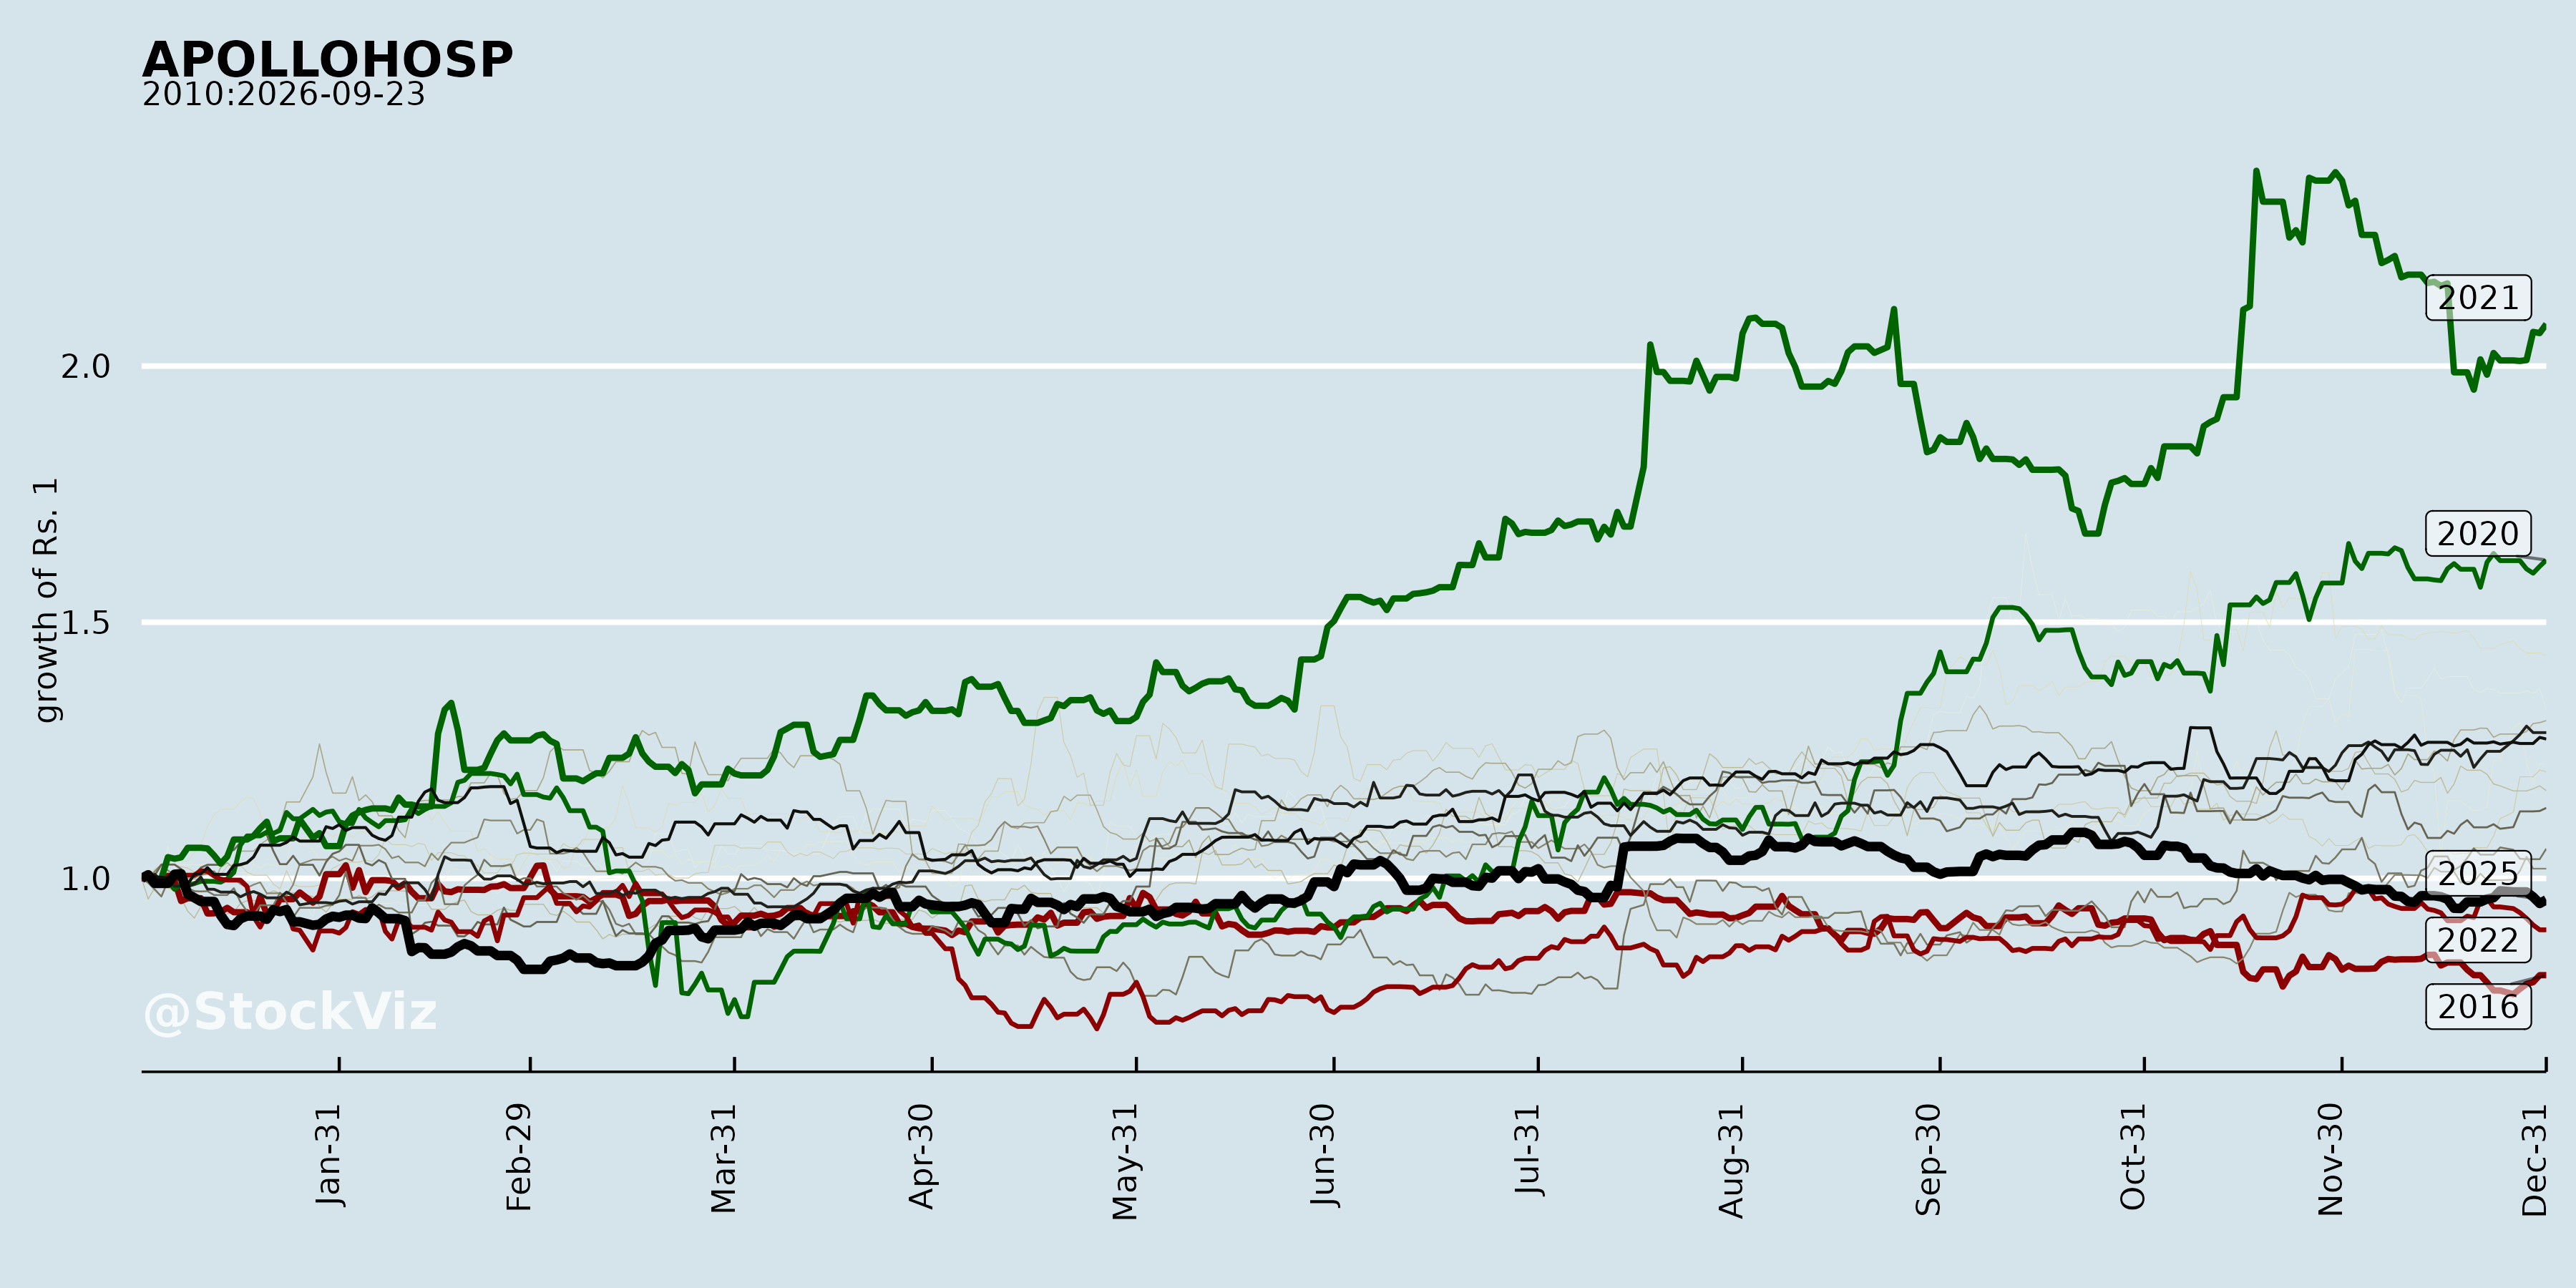
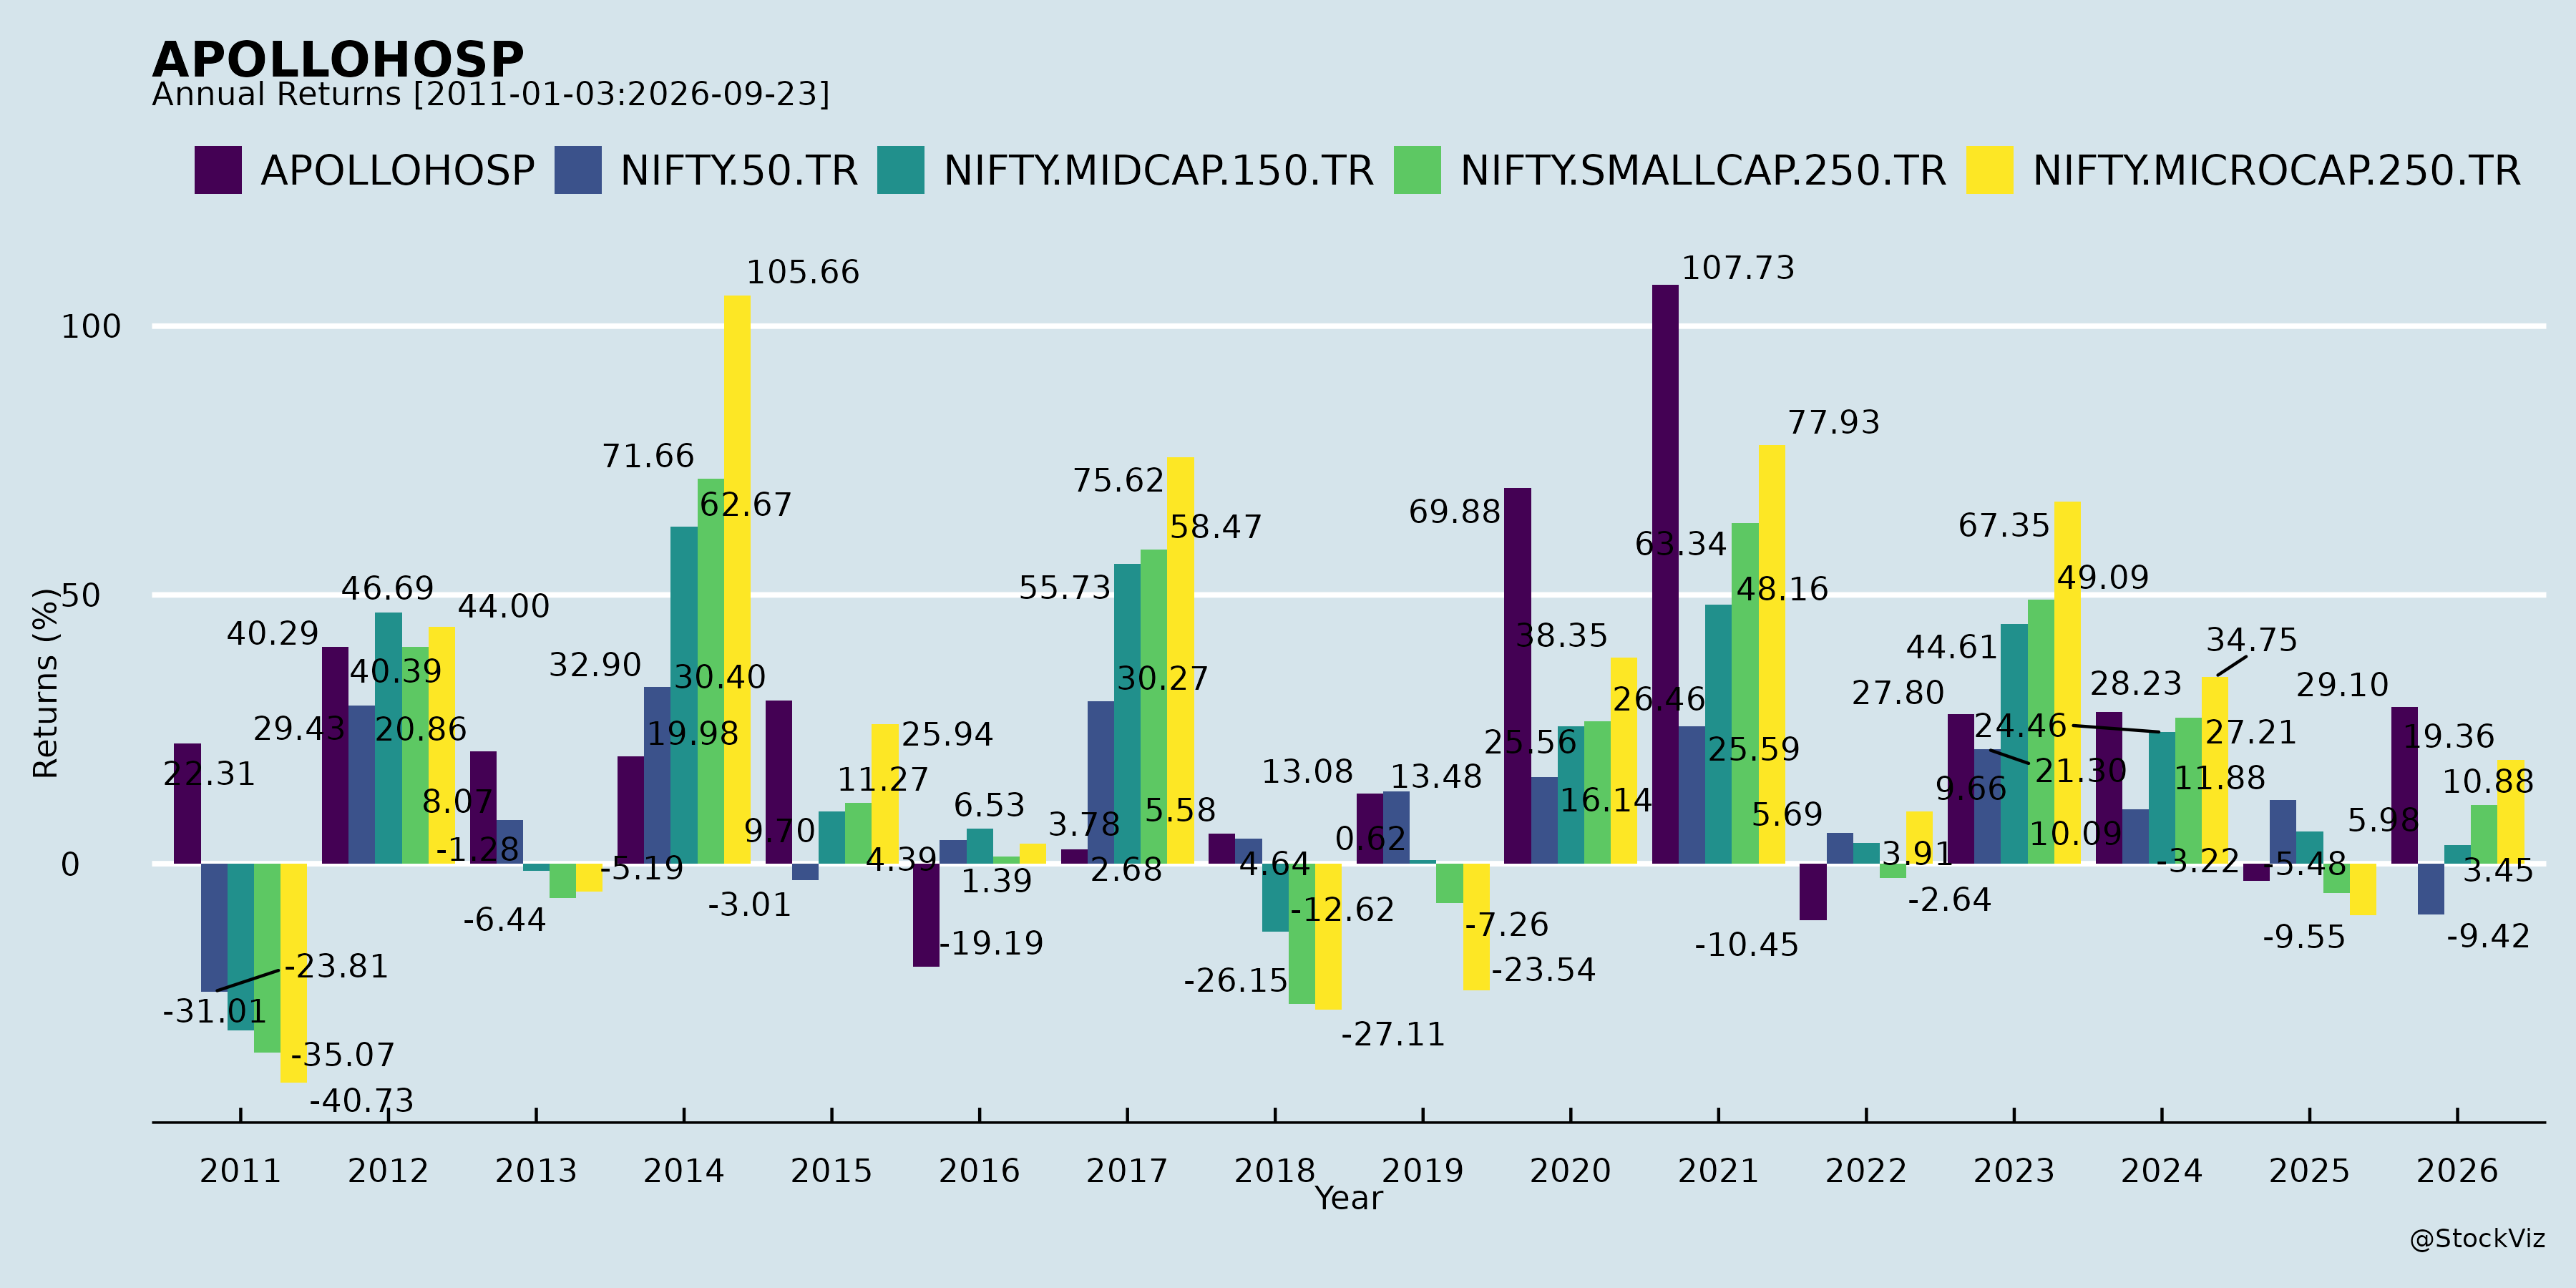
Annual Returns
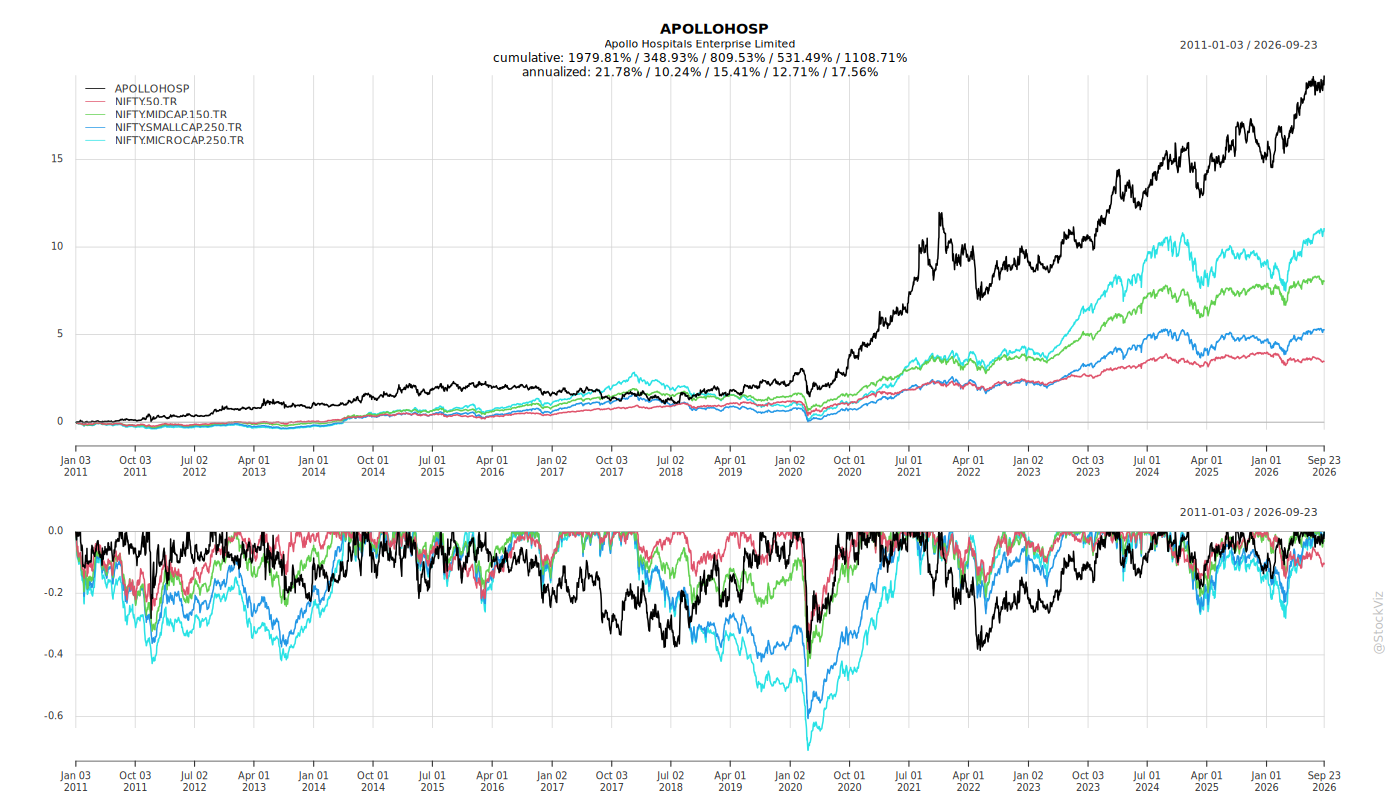
Cumulative Returns and Drawdowns
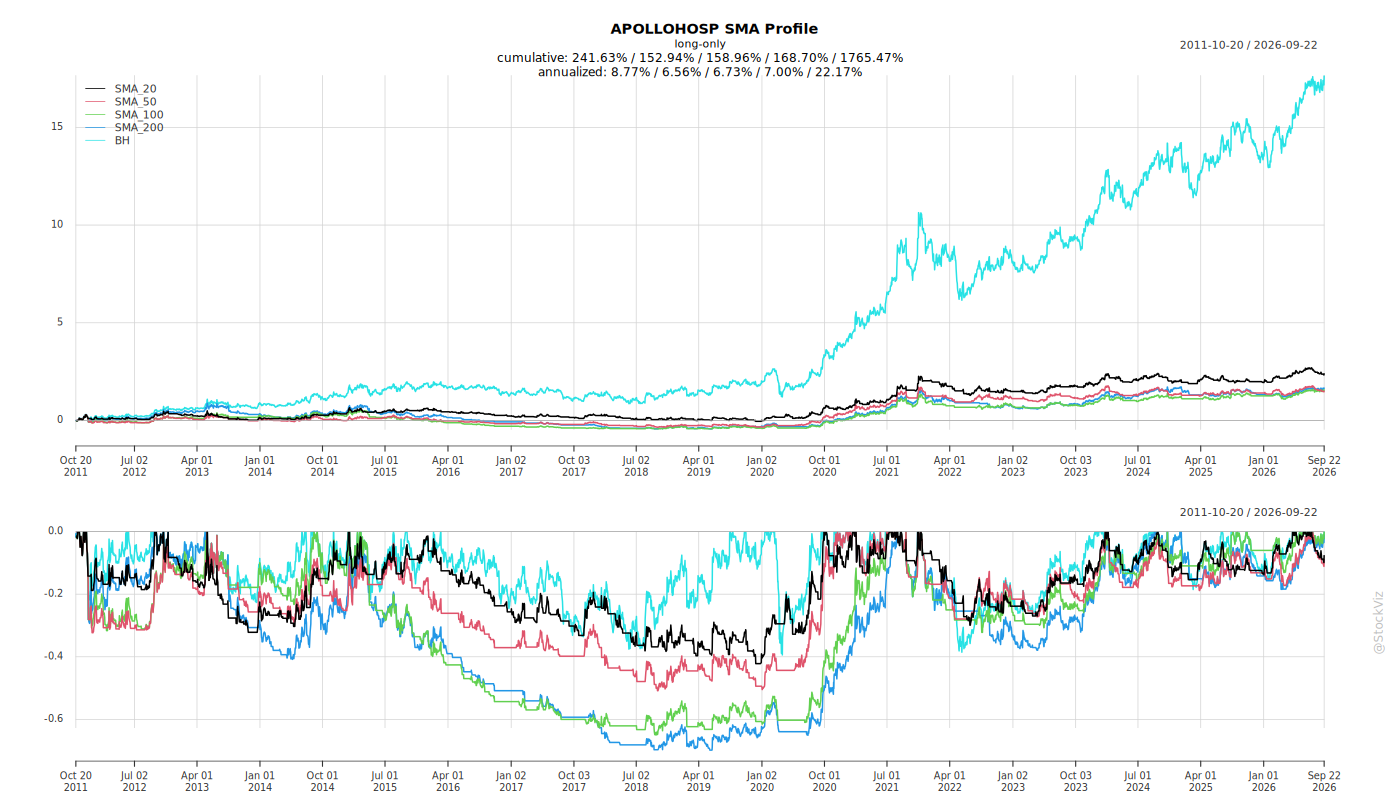
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-14
APOLLOHOSP: Recent Corporate Developments
1. Headwinds and Challenges
New hospital drag on profitability. The newly commissioned hospitals — Financial District, Sonarpur, Pune and Delhi Oncology (commissioned in Q4FY26) and Sarjapur (launched in Q1FY27), with a combined operating capacity of 380 beds — reported an EBITDA loss of Rs. 38 crore in Q1FY27. Separately, new units’ pre-operative expenses/losses in Healthcare Services amounted to Rs. 375 million in Q1FY27.
Margin pressure in offline pharmacy distribution. Offline pharmacy distribution margins saw a reduction of approximately 0.4%, attributed to investment in manpower cost and one-time expenditure in the network.
Labour Codes impact. Following the Government of India’s notification on November 21, 2025 of the Code on Wages, 2019, the Industrial Relations Code, 2020, the Code on Social Security, 2020 and the Occupational Safety, Health and Working Conditions Code, 2020, the Company assessed financial implications resulting in an increase in gratuity liability (past service cost) and leave liability of Rs. 114 million on a standalone basis and Rs. 192 million on a consolidated basis for the year ended March 31, 2026. These were presented as exceptional items. The Company continues to monitor finalisation of Central and State Rules and government clarifications, and will incorporate appropriate accounting treatment as required.
Land grant dispute. The Revenue Department passed an order dated February 13, 2026 cancelling a grant order in respect of a subsidiary (Imperial Hospitals & Research Centre Limited), alleging alienation of land on account of share purchase by its holding company. The subsidiary challenged the order before the Honourable High Court of Karnataka, which granted an interim stay on April 10, 2026 and directed the Revenue Department to file objections. Based on external legal opinions, the group believes it has adequate grounds to demonstrate compliance with the applicable conditions of the land grant. The auditors drew attention to this matter without modifying their conclusion.
Regulatory and approval dependencies. Several initiatives remain subject to approvals: the Composite Scheme of Arrangement awaits sanction by the National Company Law Tribunal; the AHLL–Cloudnine combination is subject to regulatory approvals including the Competition Commission of India; the transfer of the FMCG/wellness undertaking by Apollo Healthco to Apollo Consumer Products Limited is subject to shareholder approval; and the appointment of Price Waterhouse as Statutory Auditors is subject to shareholders’ approval and other statutory requirements.
Forward-looking statement risk. The Company notes that forward-looking statements involve risks and uncertainties, including potential differences in actual results due to market conditions.
2. Tailwinds and Growth Prospects
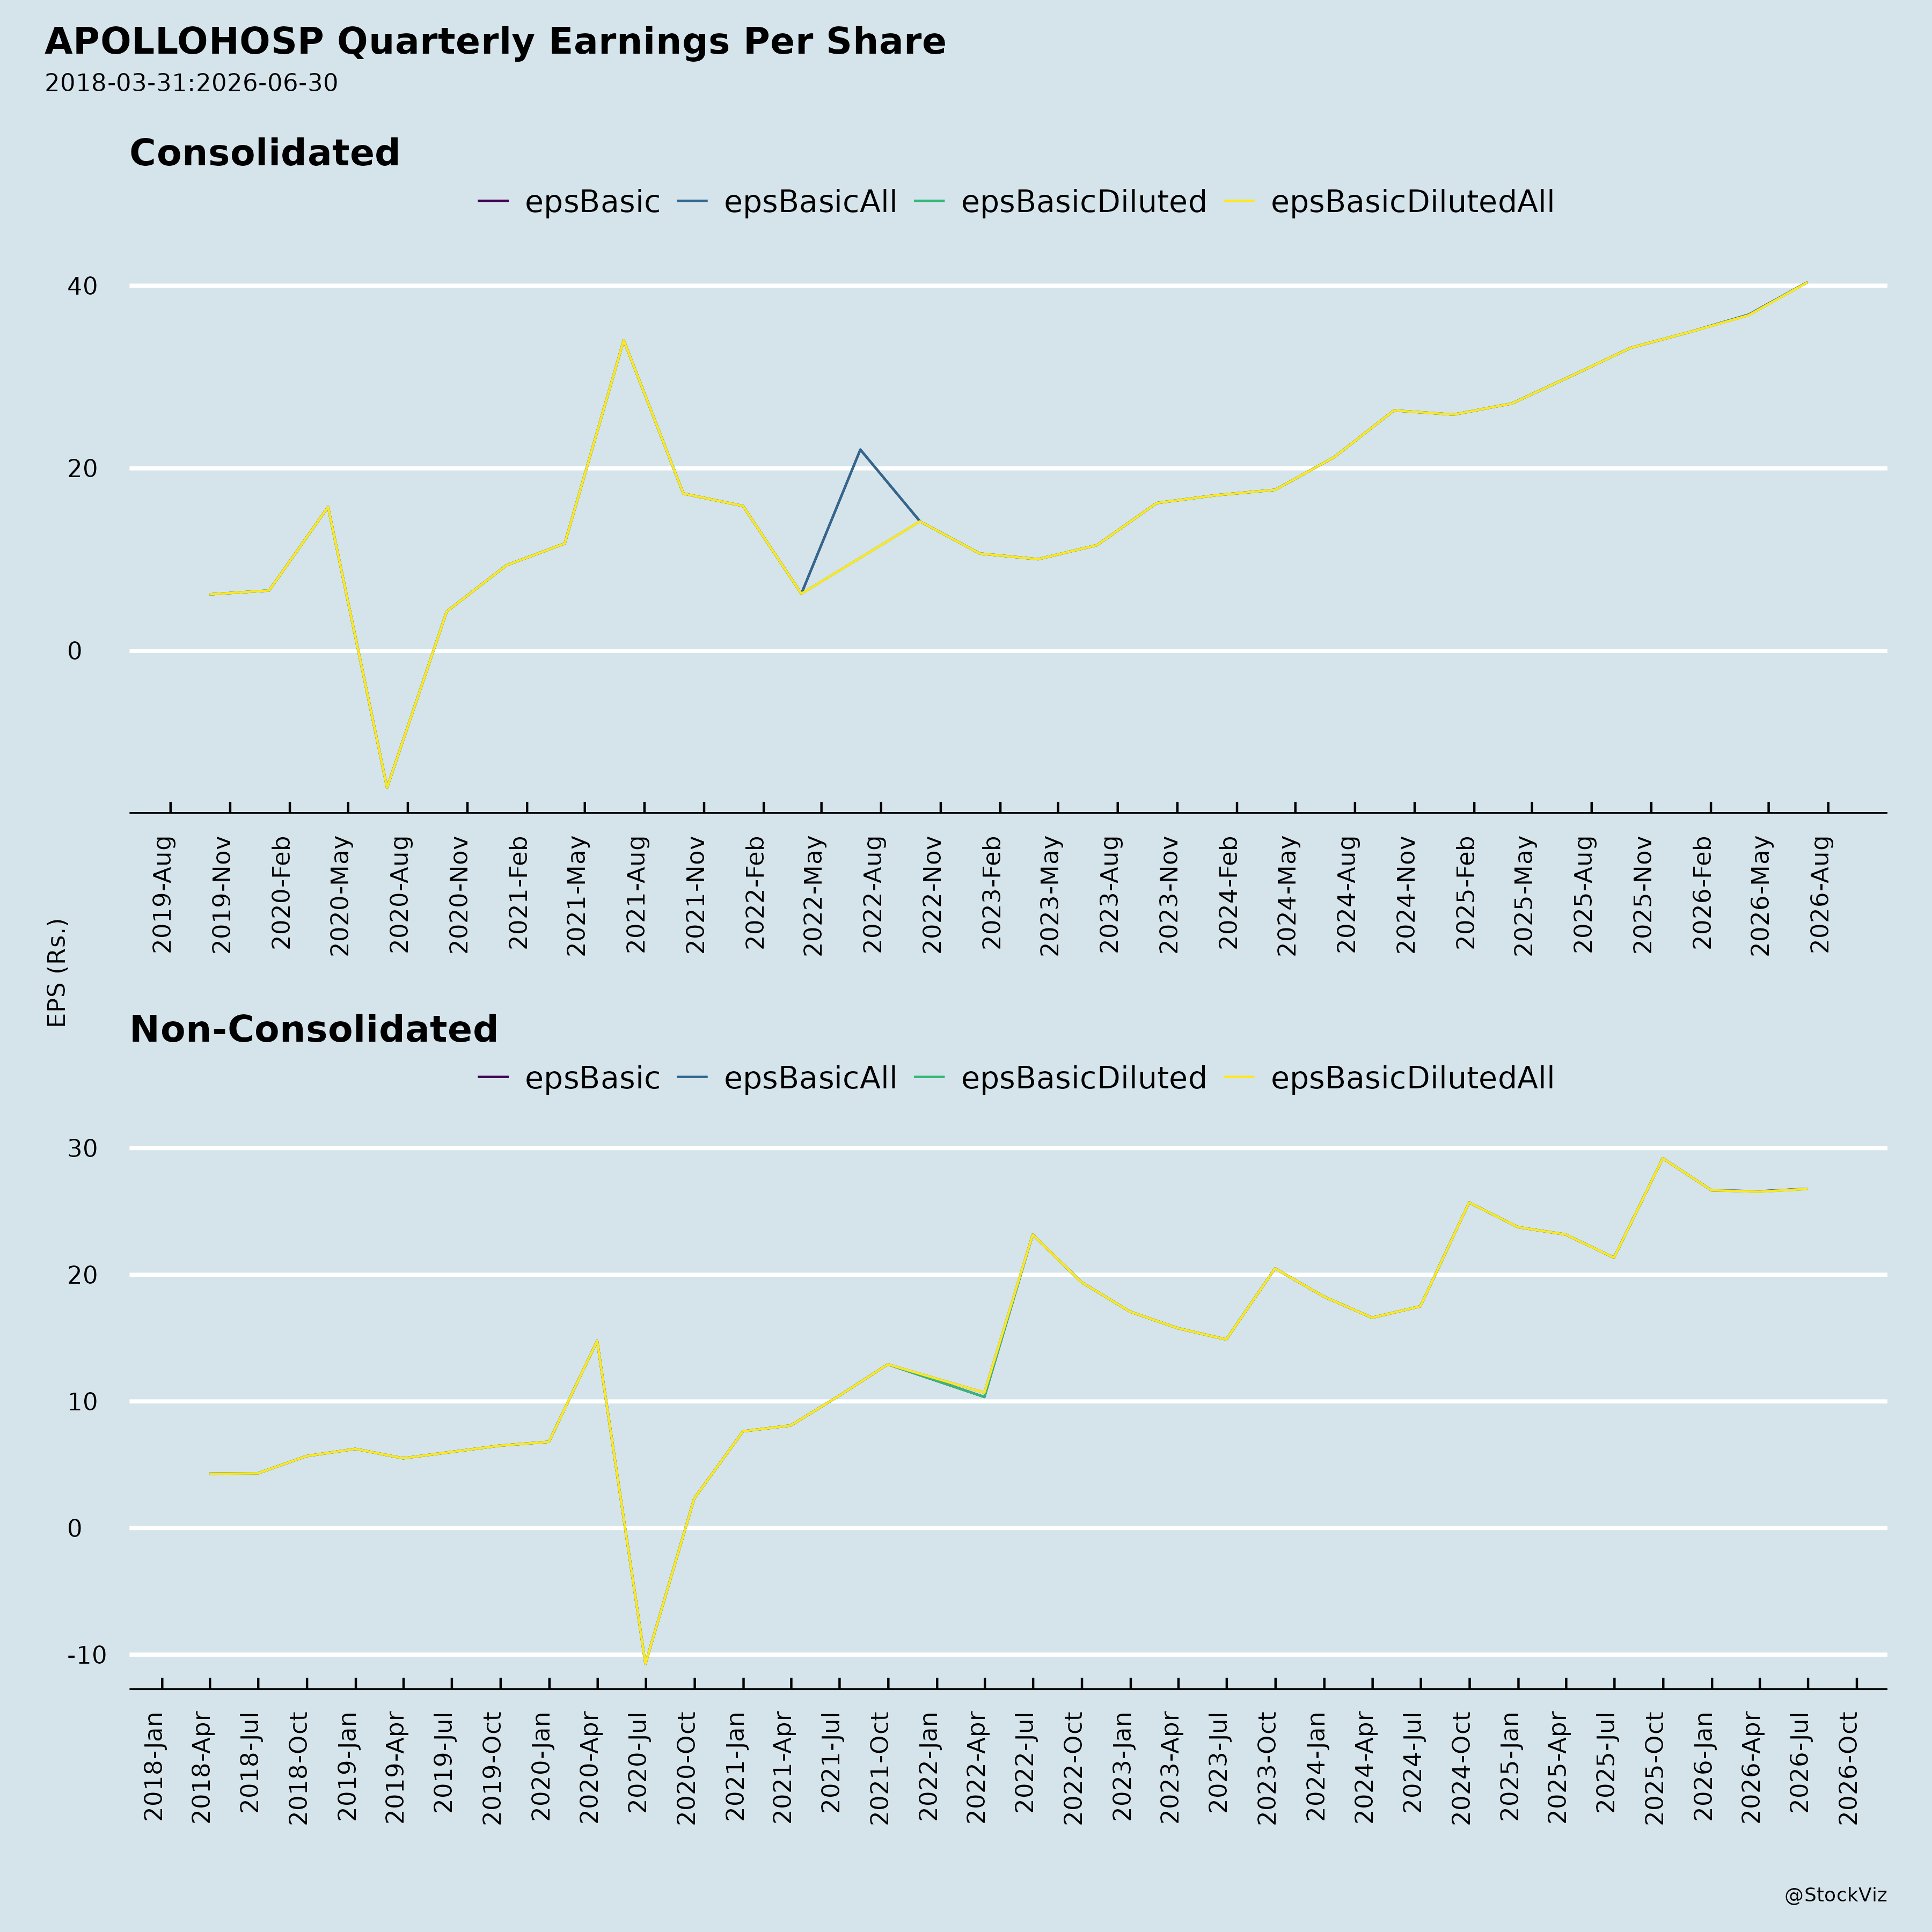
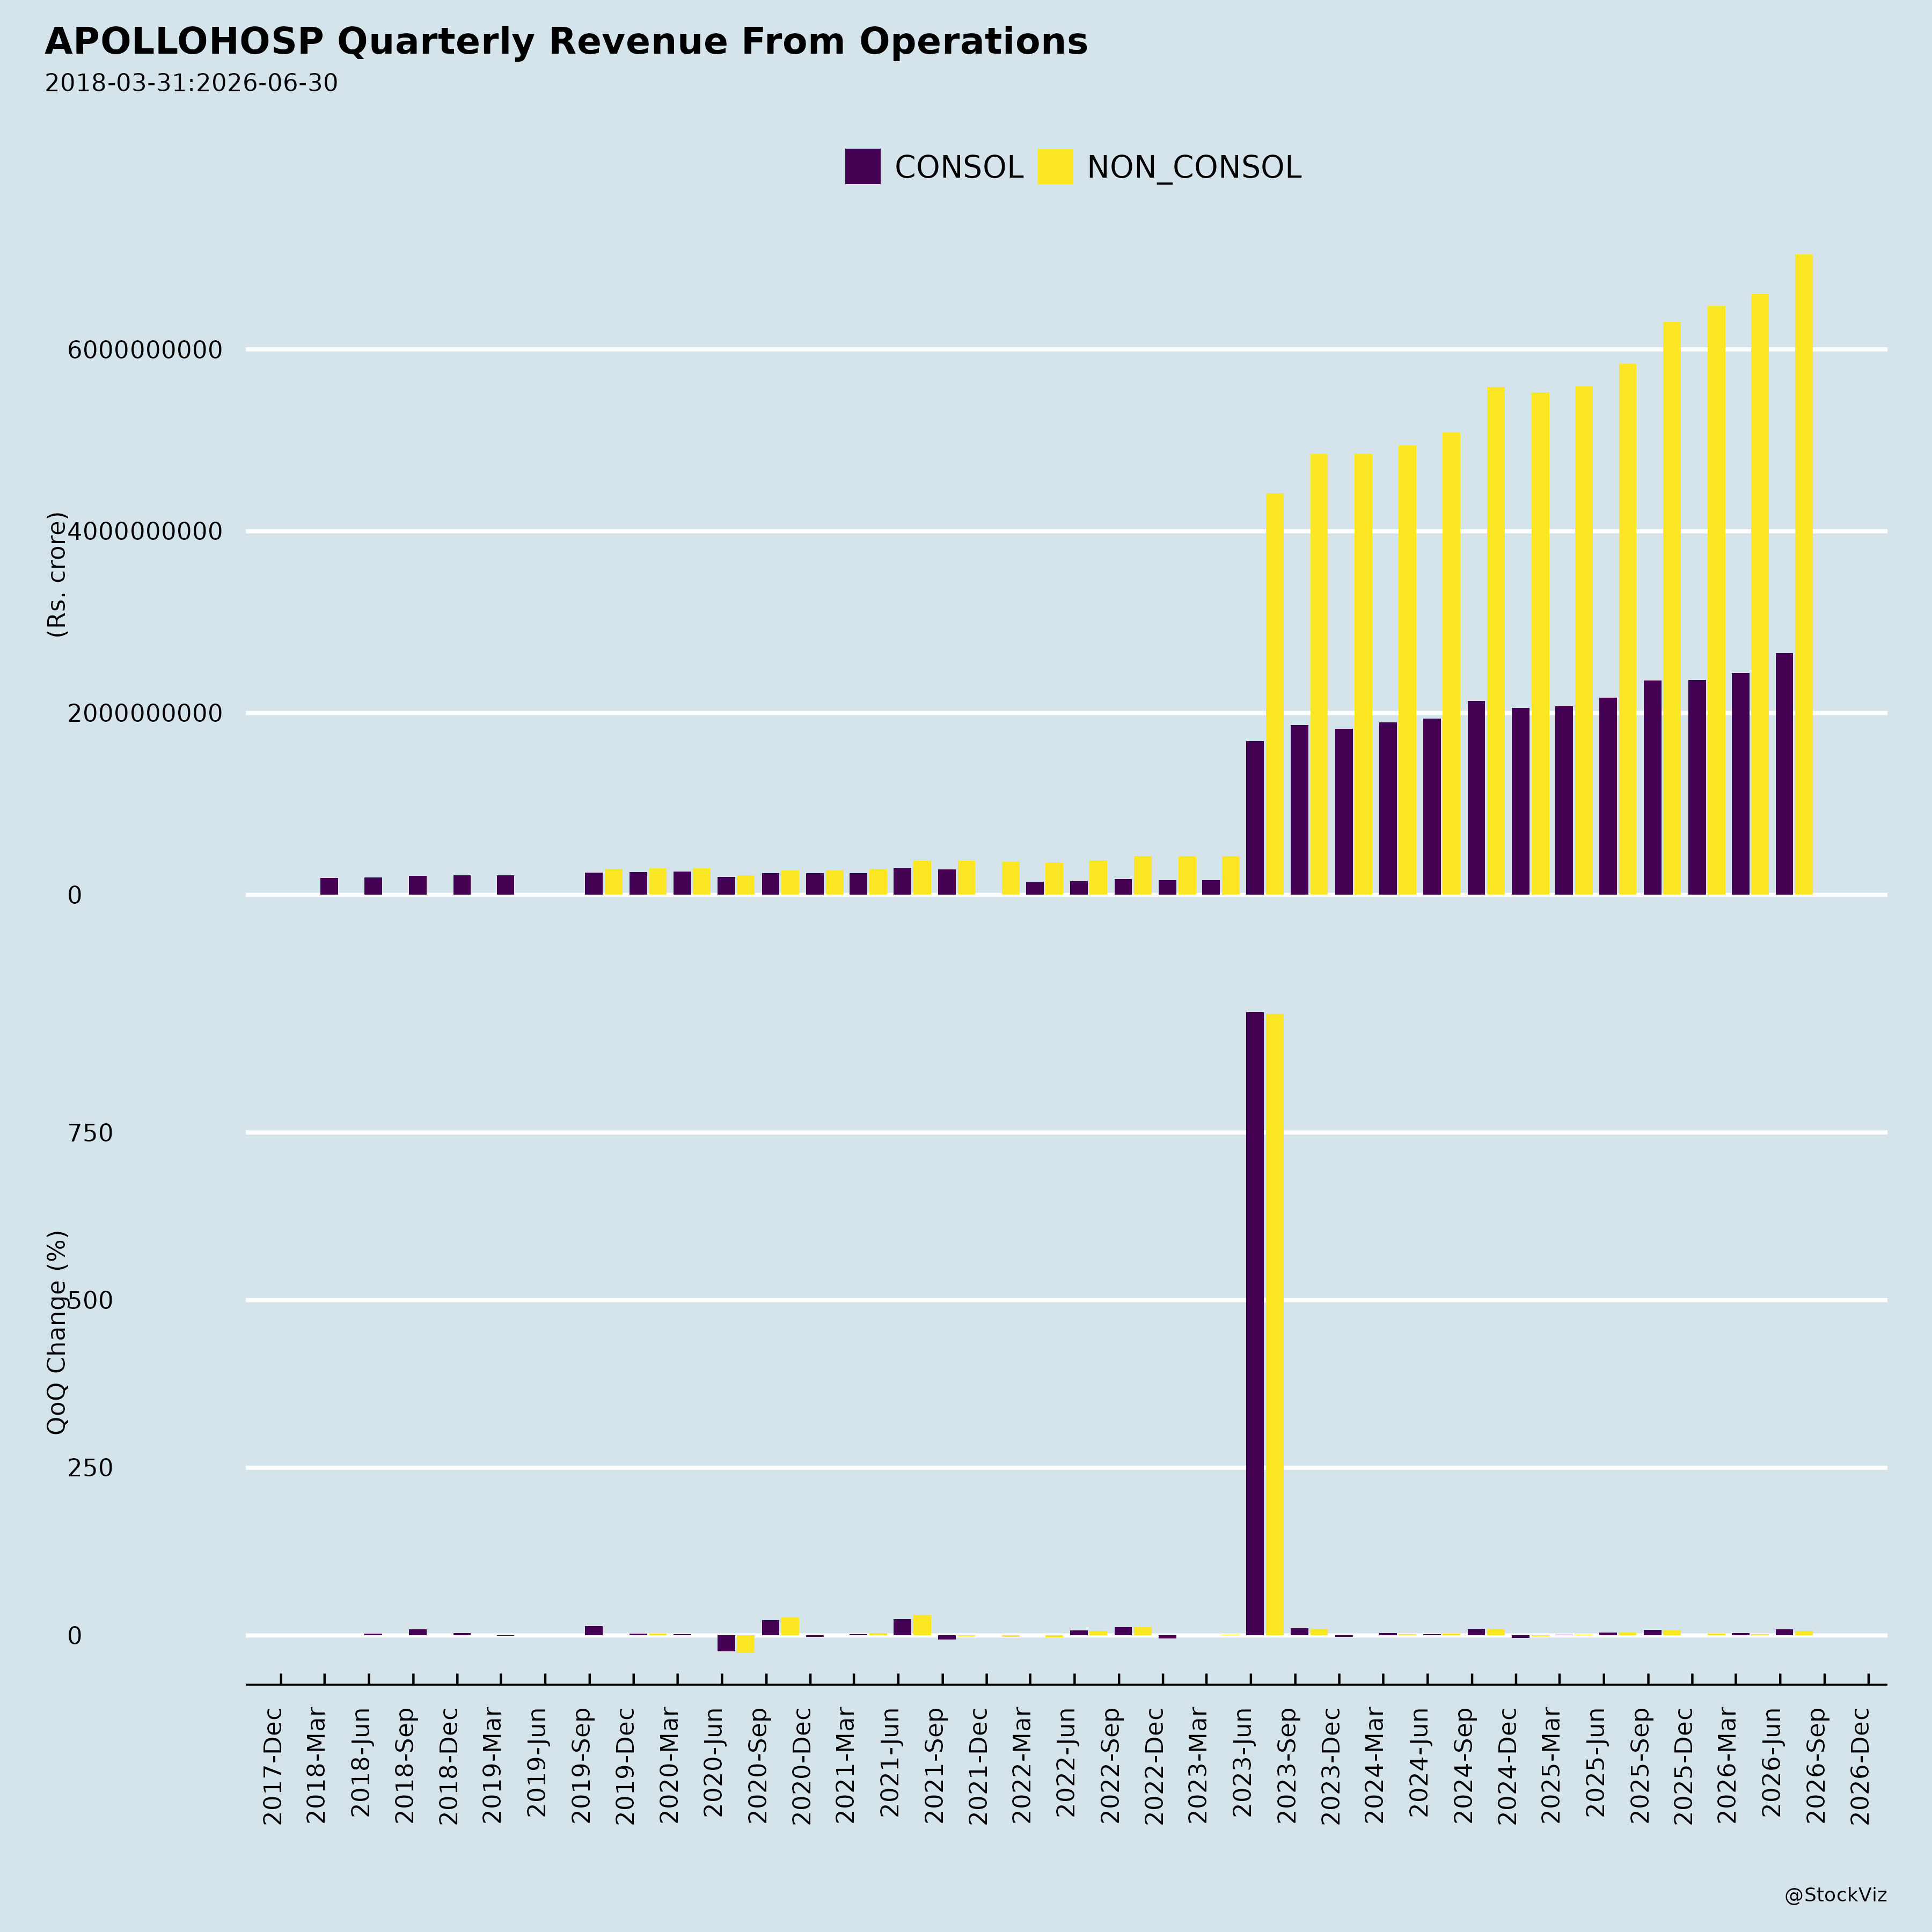
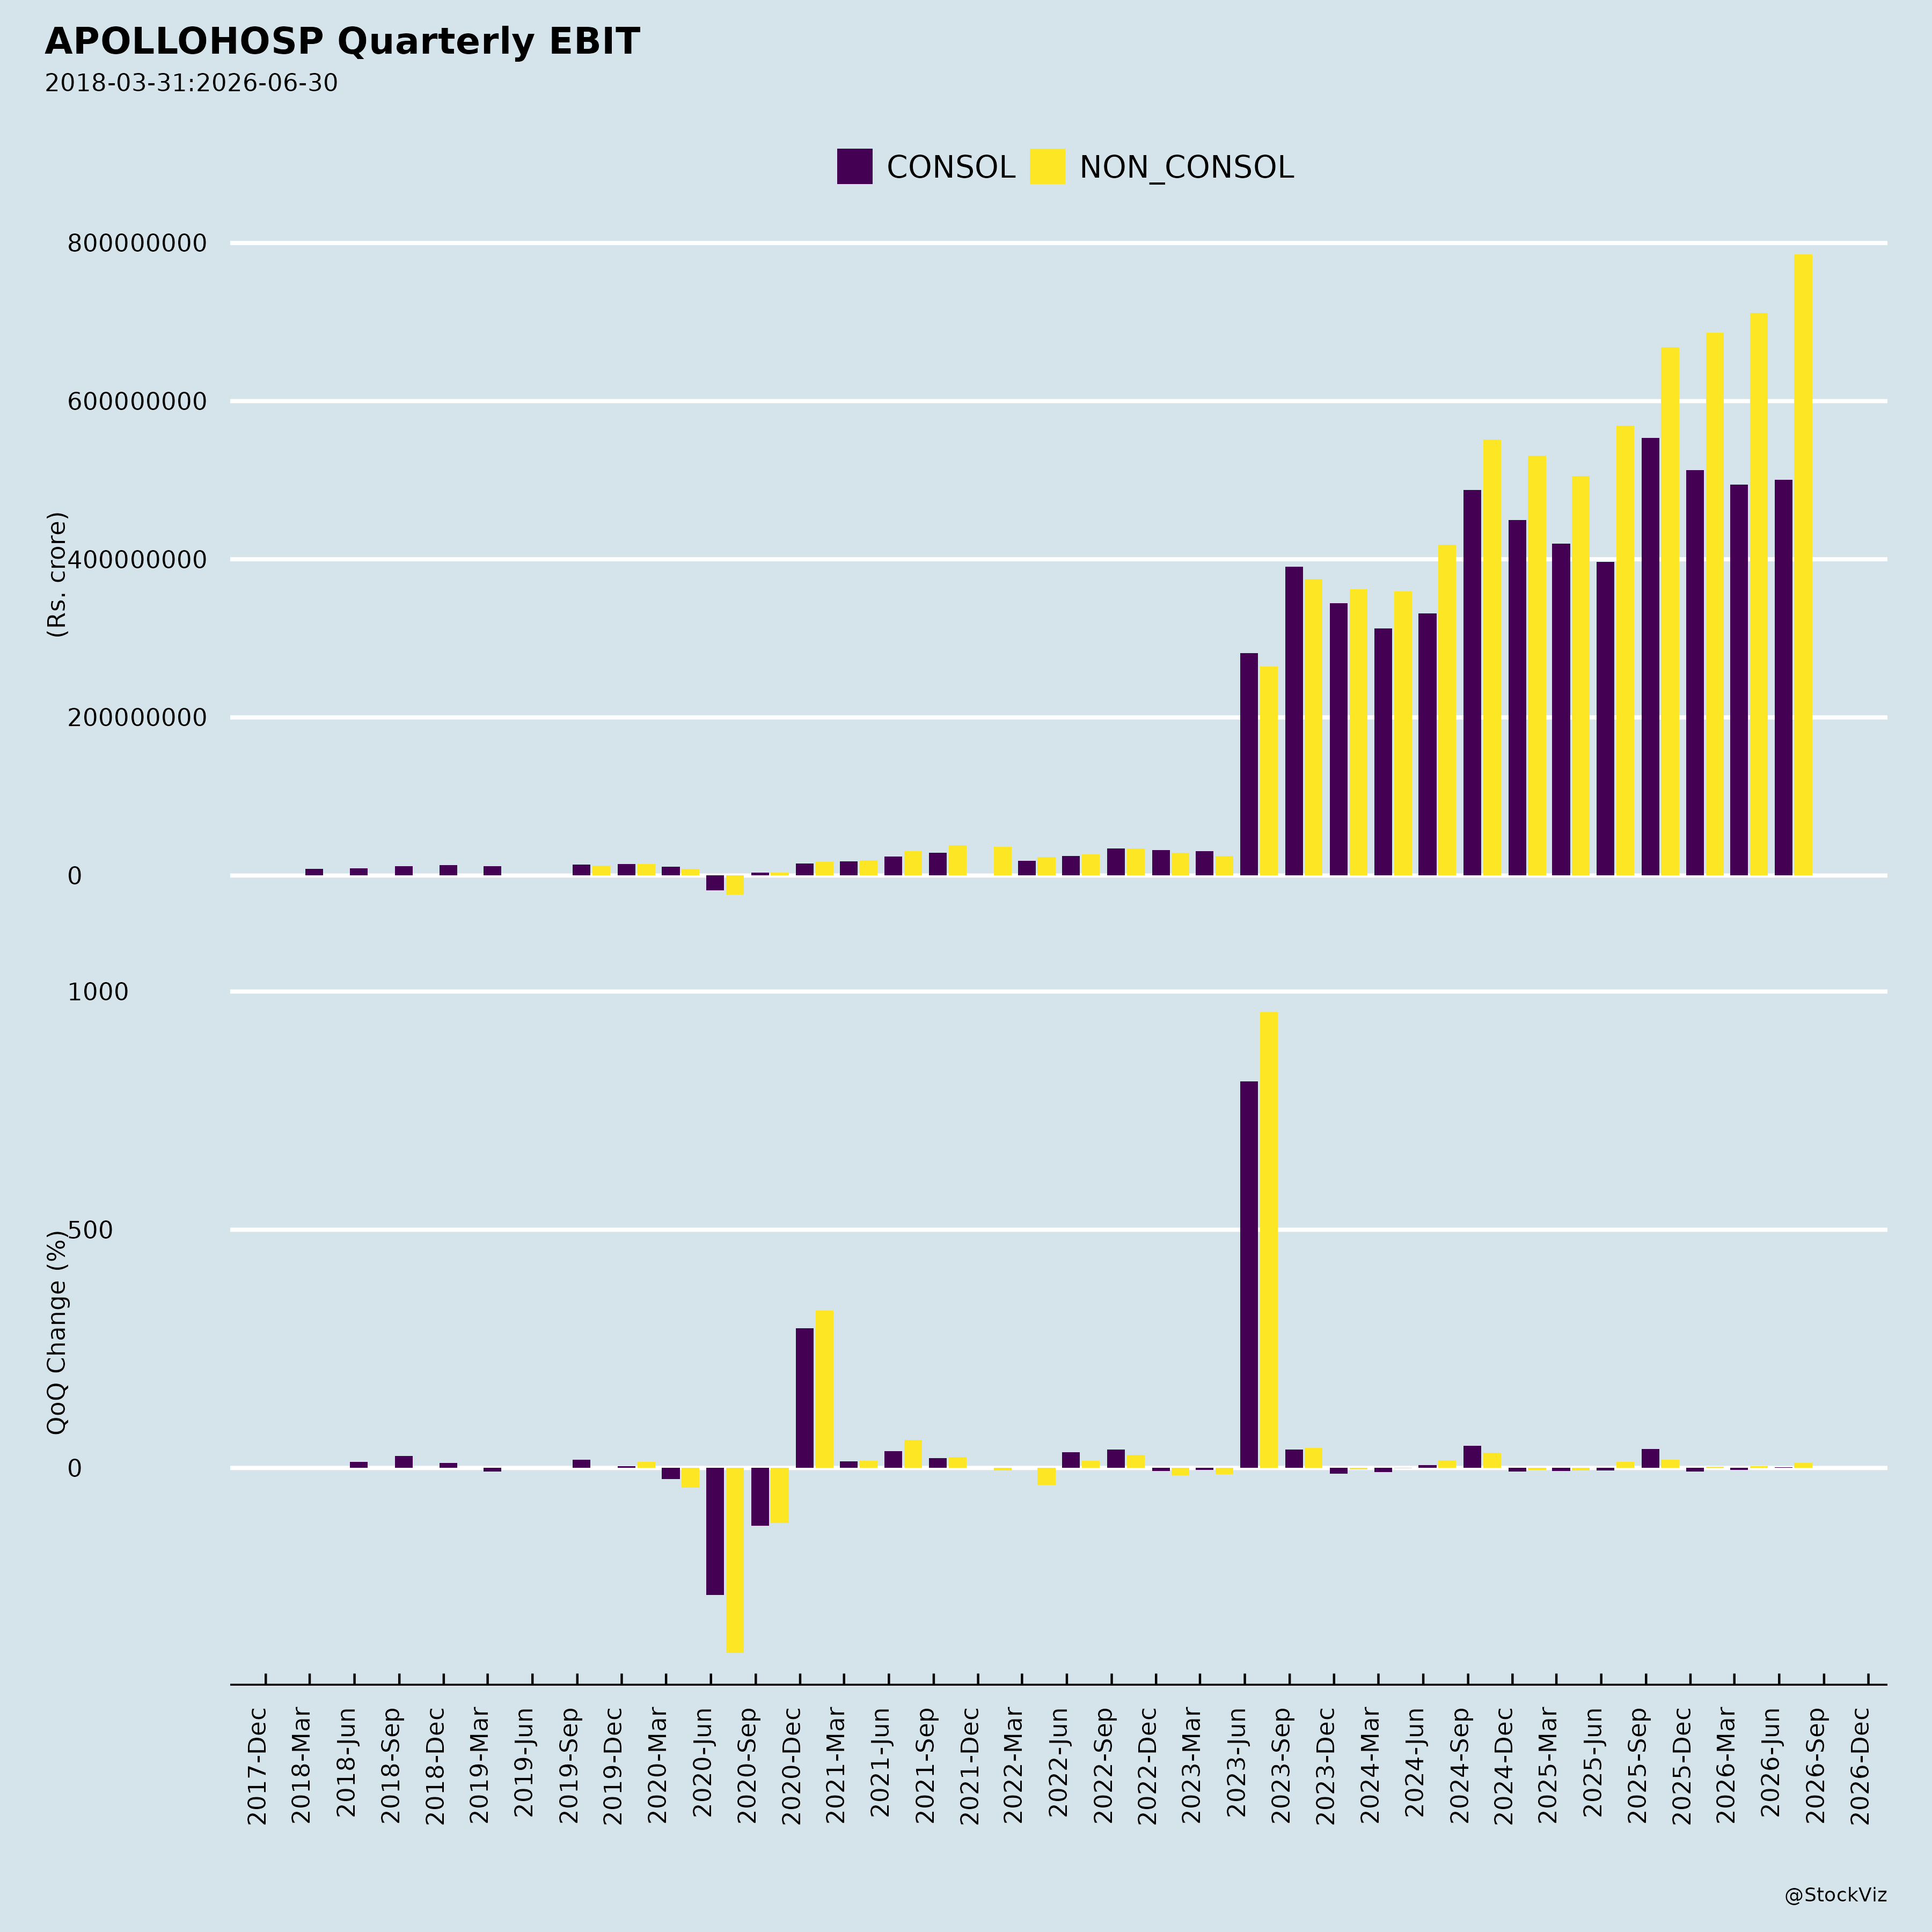
Strong Q1FY27 performance. Consolidated revenue grew 21% YoY to Rs. 7,043 crore (Rs. 70,435 million), consolidated EBITDA grew 28% YoY to Rs. 1,092 crore (Rs. 10,920 million), and consolidated PAT was Rs. 581 crore (Rs. 5,805 million), up 34% YoY. Diluted EPS was Rs. 40.36 per share (not annualised).
Segment momentum. Healthcare Services revenue grew 22% YoY to Rs. 3,567 crore with EBITDA of Rs. 862 crore (up 20% YoY) and PAT of Rs. 480 crore (up 25% YoY). AHLL revenue grew 15% to Rs. 499 crore with EBITDA of Rs. 59 crore and a reduced PAT loss of Rs. 1 crore. Apollo HealthCo reported revenue of Rs. 2,977 crore (up 20% YoY) and EBITDA of Rs. 171 crore.
Volume and occupancy gains. Operating beds stood at 8,352 as on June 30, 2026 (excluding AHLL and managed beds), with overall occupancy at 70% versus 65% in Q1FY26. Regional revenue growth ranged from 16% (Tamil Nadu, Northern) to 31% (AP-Telangana), with occupancy improvements across all regions.
Capacity expansion. Apollo launched a 180-bed hospital in Sarjapur, Bangalore in Q1FY27. The Gurugram facility remains on track for commissioning in Q3FY27. The Company announced expansion of existing facilities in Indore and Guwahati by 148 beds and addition of 4 new hospitals in Indore, Dwarka, Delhi Proton Centre and Ranchi totalling 1,200 beds. Apollo now plans to add over 5,800 total beds (4,700 census beds) over the next 5 years. Management also references commissioning 5 new hospitals totalling approximately 1,000 census beds with ongoing expansion plans.
Digital health and pharmacy scale. Apollo HealthCo added 151 net new stores in the quarter, taking the network to 7,440 stores. Apollo 24/7 GMV stood at Rs. 535 crore, up 23% YoY, with average daily order run rate of 70K versus 64K in Q1FY26. The Apollo 24|7 platform has approximately 49 million+ registrations.
International patient growth. The International Patient Services division saw 26% YoY revenue growth.
Structural opportunities. Management cites opportunities in organising the unorganised primary care and diagnostics sectors. The AHLL combination with Kids Clinic India Limited (Cloudnine) is intended to create one of India’s largest maternity and fertility care platforms, with AHLL divesting stakes in Apollo Specialty Hospitals Private Limited and Apollo Fertility Centre Private Limited at an enterprise value of approximately Rs. 15,500 million (Rs. 1,550 crore), comprising cash and an approximately 9.9% equity stake in Kids Clinic India.
Clinical innovation and partnerships. Apollo Cancer Centres became the first in India to launch Guardant Health’s Shield™ Multi-Cancer Detection Test. Apollo signed an MoU with the ePlane Company to explore electric air ambulances and medical delivery drones.
3. Key Risks
- Execution and ramp-up risk on the significant bed expansion programme, evidenced by the EBITDA losses at newly commissioned hospitals.
- Margin risk in the offline pharmacy distribution business from manpower investment and one-time network expenditure.
- Regulatory/legal risk from the Karnataka land grant cancellation proceedings, currently under interim stay, and from the pending NCLT sanction, CCI approval and other regulatory approvals for announced transactions.
- Accounting and compliance risk arising from the Labour Codes, where final Central and State Rules and government clarifications are still awaited and accounting treatment may need to be revised.
- General forward-looking risk, as the Company notes actual results may differ due to market conditions.
4. Management Guidance Versus Observed Performance
Guidance provided: - Management expects to achieve an INR 250 bn run rate annualised revenue in Q4 FY27 with an EBITDA margin in the range of approximately 6.5%–7.0% for the proposed New Co. - The Gurugram facility remains on track for commissioning in Q3FY27. - Plans to add over 5,800 total beds (4,700 census beds) over the next 5 years.
Observed performance against prior capacity commitments: - The Sarjapur 180-bed hospital was launched in Q1FY27 as part of the capacity growth momentum. - New hospitals with a combined operating capacity of 380 beds in Financial District, Sonarpur, Pune and Delhi Oncology were commissioned in Q4FY26, and Sarjapur in Q1FY27 — these are now in the ramp-up phase and reported an EBITDA loss of Rs. 38 crore in Q1FY27, illustrating the near-term earnings drag associated with the expansion guidance.
Observed performance against growth trajectory: - Q1FY27 consolidated revenue growth of 21% YoY, EBITDA growth of 28% YoY and PAT growth of 34% YoY, with Healthcare Services revenue up 22%, AHLL up 15% and HealthCo up 20%, provide the current run-rate baseline relative to the stated Q4 FY27 New Co revenue and margin ambition.
Other corporate actions: - The Board approved the appointment of M/s Price Waterhouse Chartered Accountants LLP as Statutory Auditors for five years commencing from the conclusion of the 46th AGM (2027) until the conclusion of the 51st AGM (2032), with Deloitte Haskins & Sells LLP continuing until the 46th AGM. - The Board approved grant of additional stock options and RSUs representing 46,798 equity shares of Rs. 5 each to new employees under the Apollo ESOP 2024. - The 45th AGM held on August 25, 2026 passed all eight resolutions, including adoption of financial statements, confirmation of dividends, re-appointments of Dr. Prathap C Reddy and Smt. Sangita Reddy, re-appointment of Smt. Rama Bijapurkar as independent director, approval to offer non-convertible debentures aggregating up to Rs. 7,500 million on a private placement basis, and ratification of the cost auditor’s remuneration. - Unclaimed dividends for seven consecutive years from 2018-2019 onwards, along with corresponding equity shares, are proposed to be transferred to the Investor Education and Protection Fund (IEPF) pursuant to applicable statutory provisions.
Broker Narrative
The narrative shifted from a technically driven Buy in March 2022, based on support bounces, a bullish monthly trend and buying at lower levels, to a fundamental Hold in August 2026, focused on new-hospital EBITDA drags, pharmacy margin pressure and insurance investment costs. The core optimism on hospital growth and margins persisted — established hospital revenue/margins remained healthy and several businesses were approaching break-even — but near-term operational headwinds forced a more cautious rating.
Broker Timeline
41 broker calls · 2022-03-01 to 2026-08-14
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.