APOLLO
Equity Metrics
November 18, 2026
Apollo Micro Systems Limited
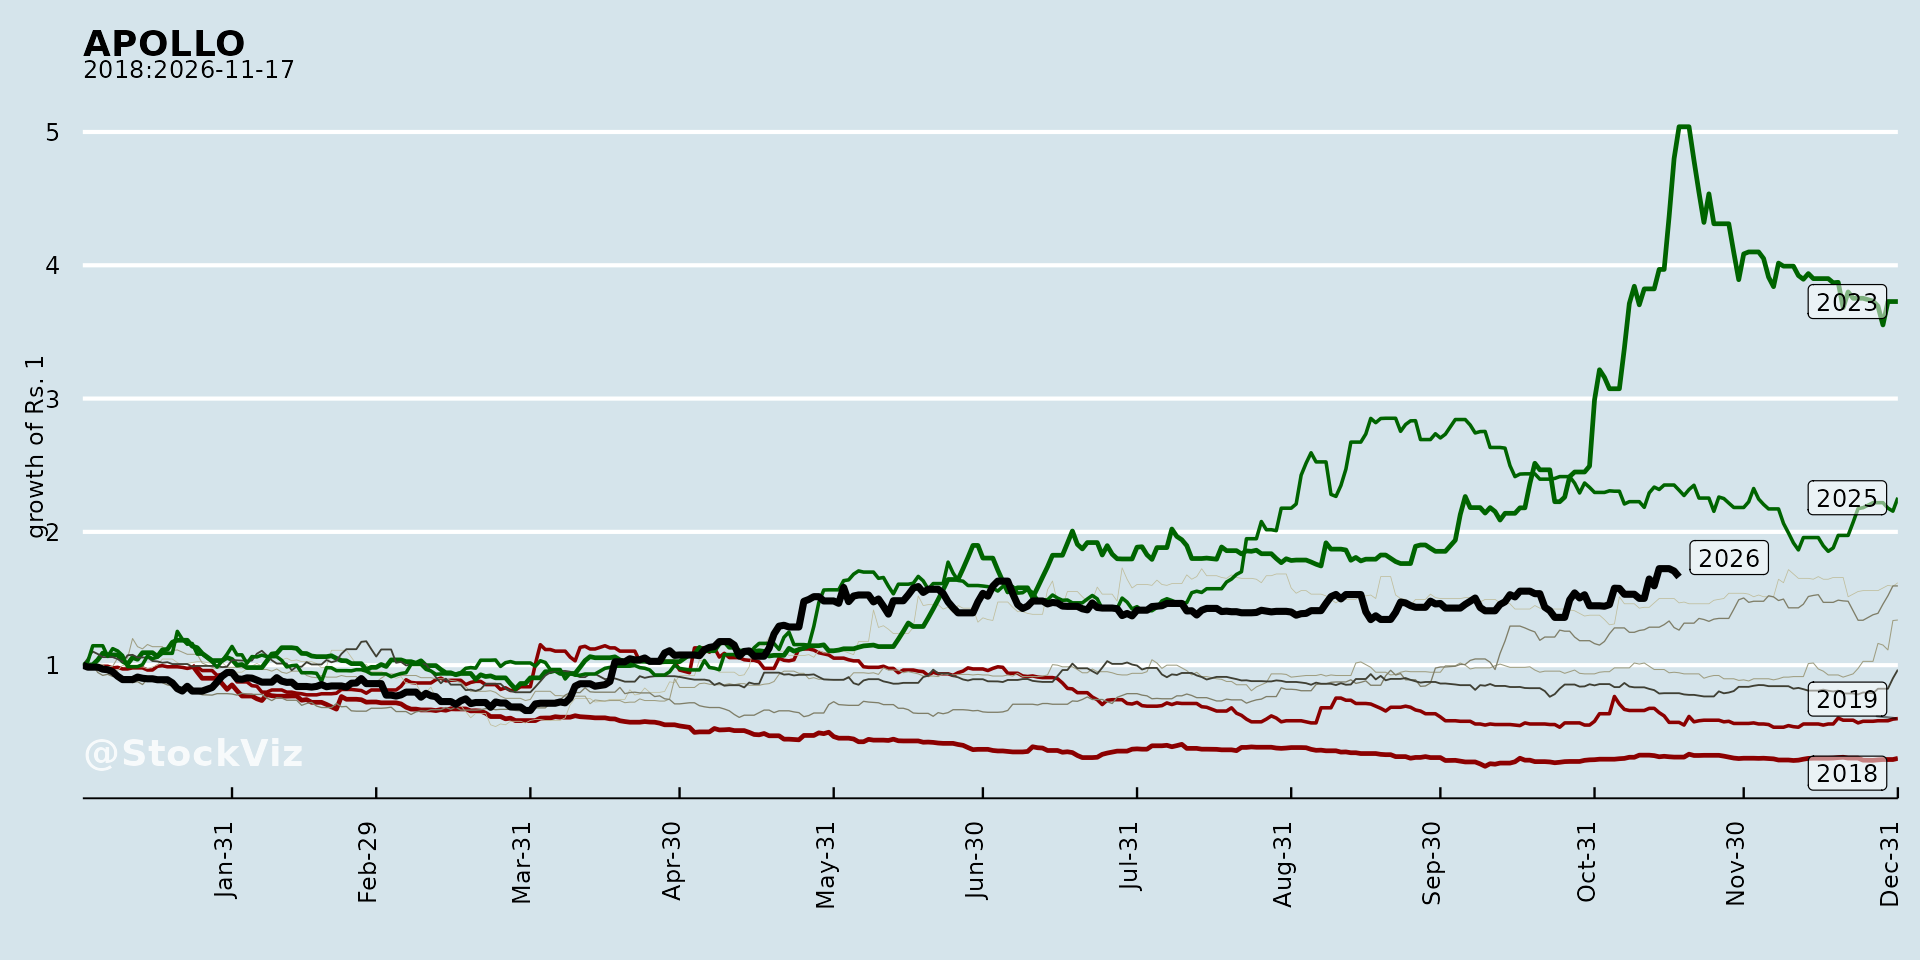
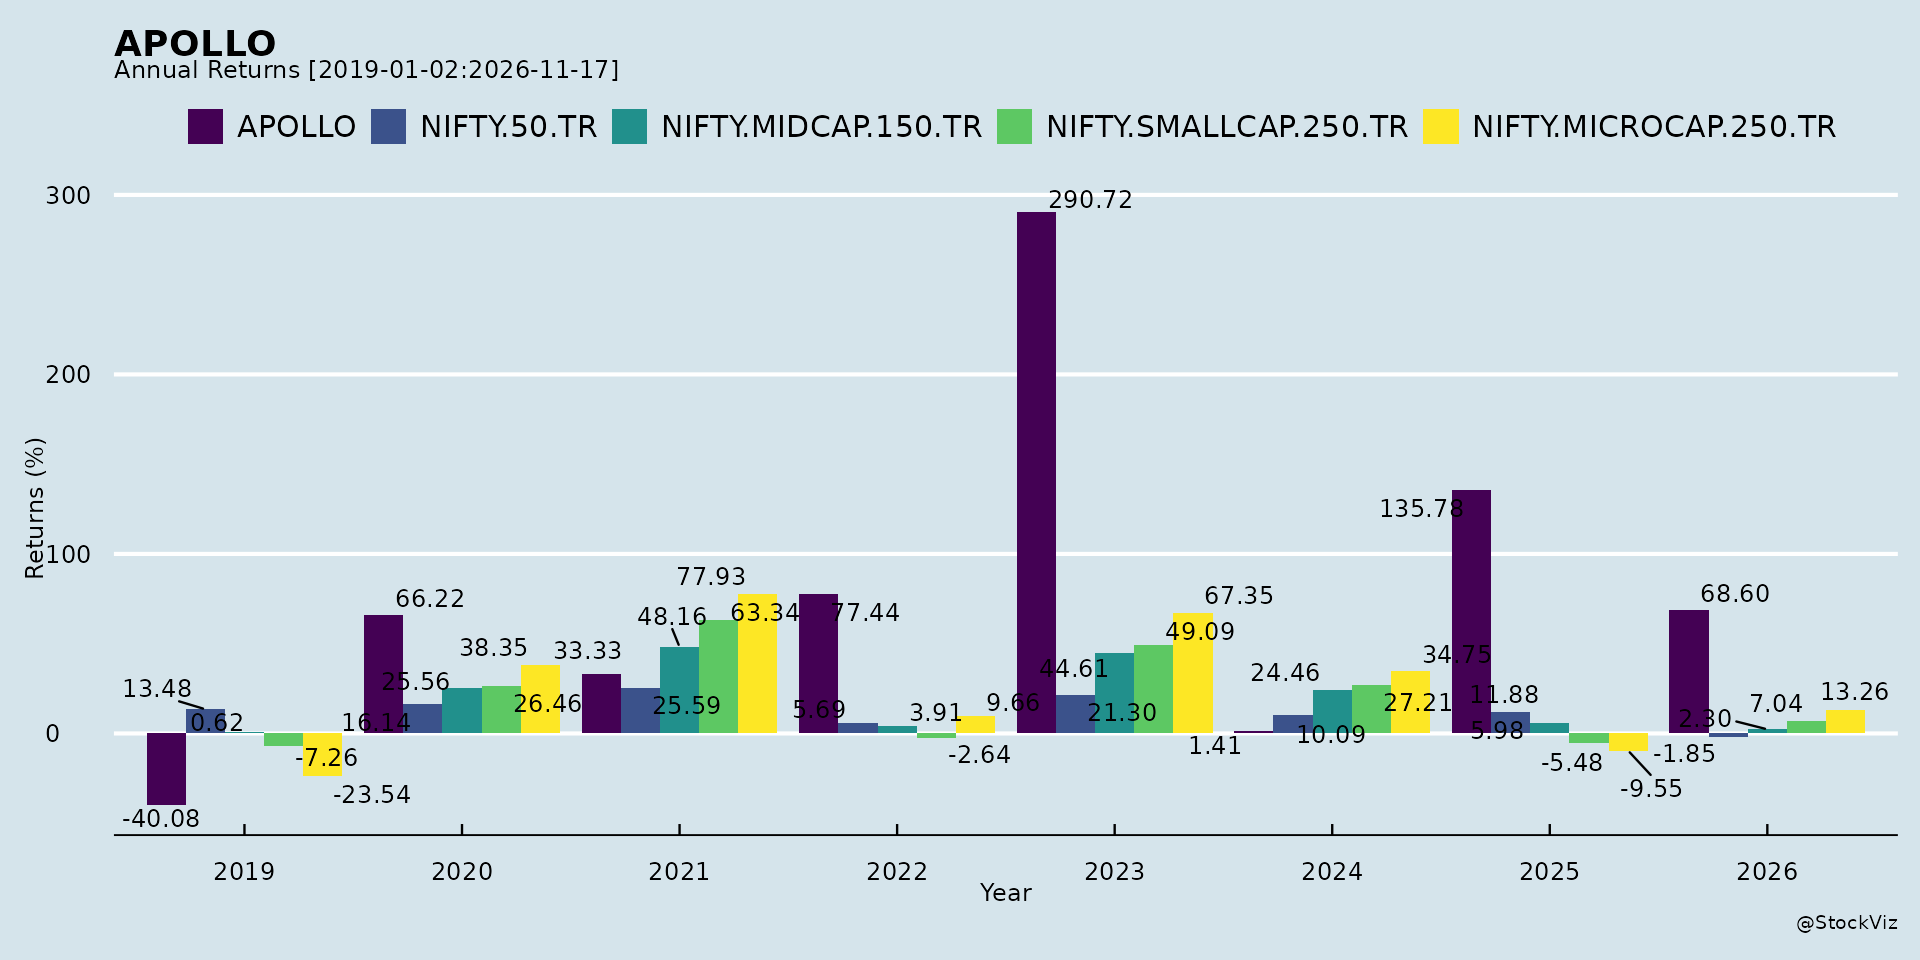
Annual Returns
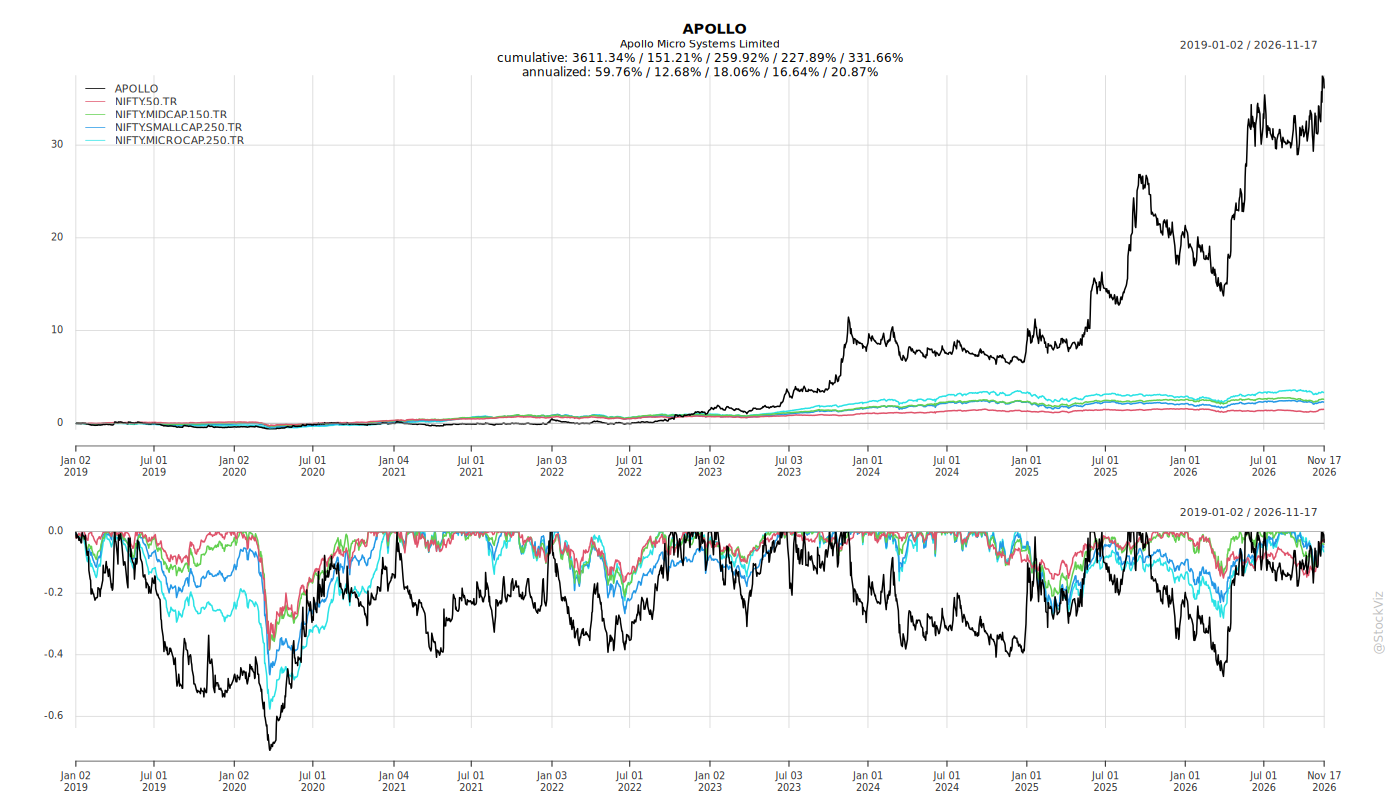
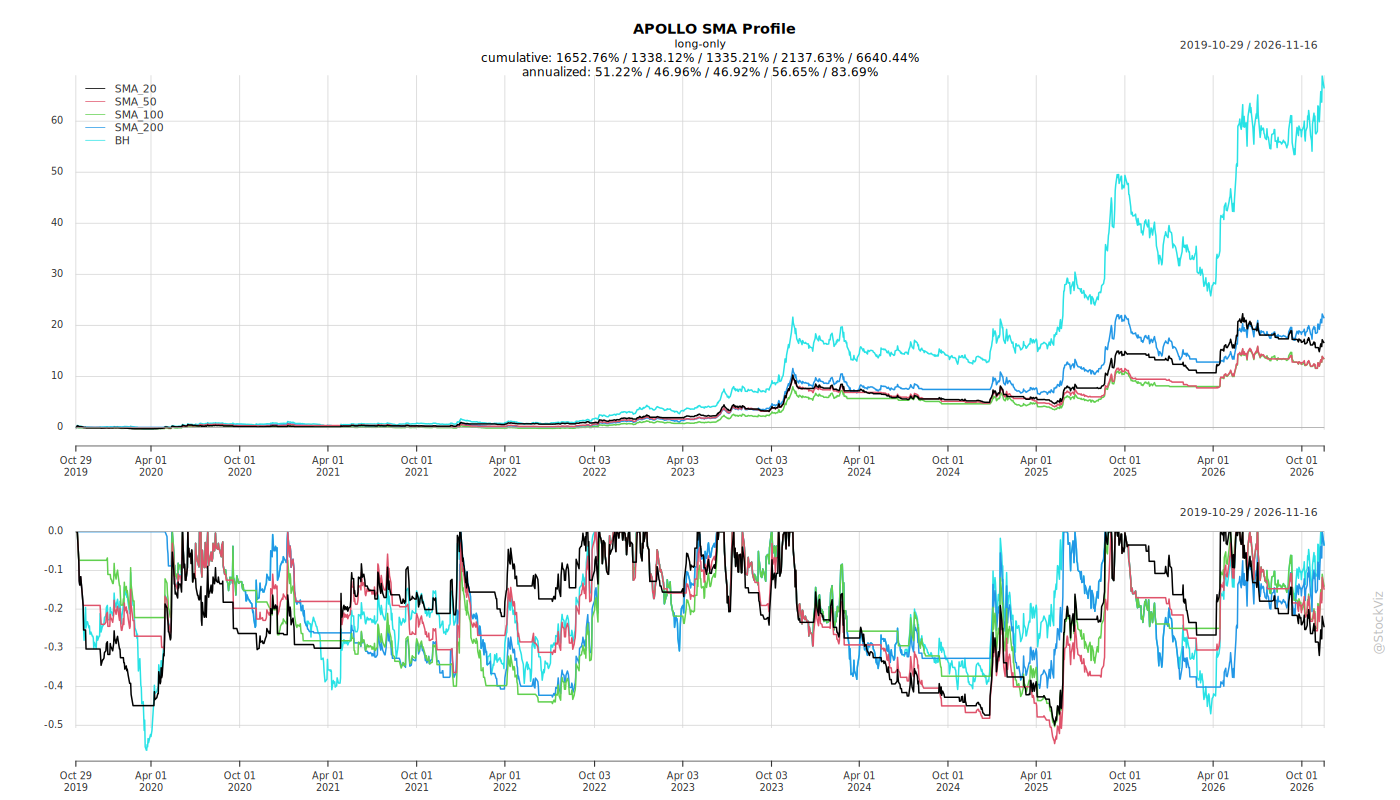
Cumulative Returns and Drawdowns
Fundamentals
Ownership
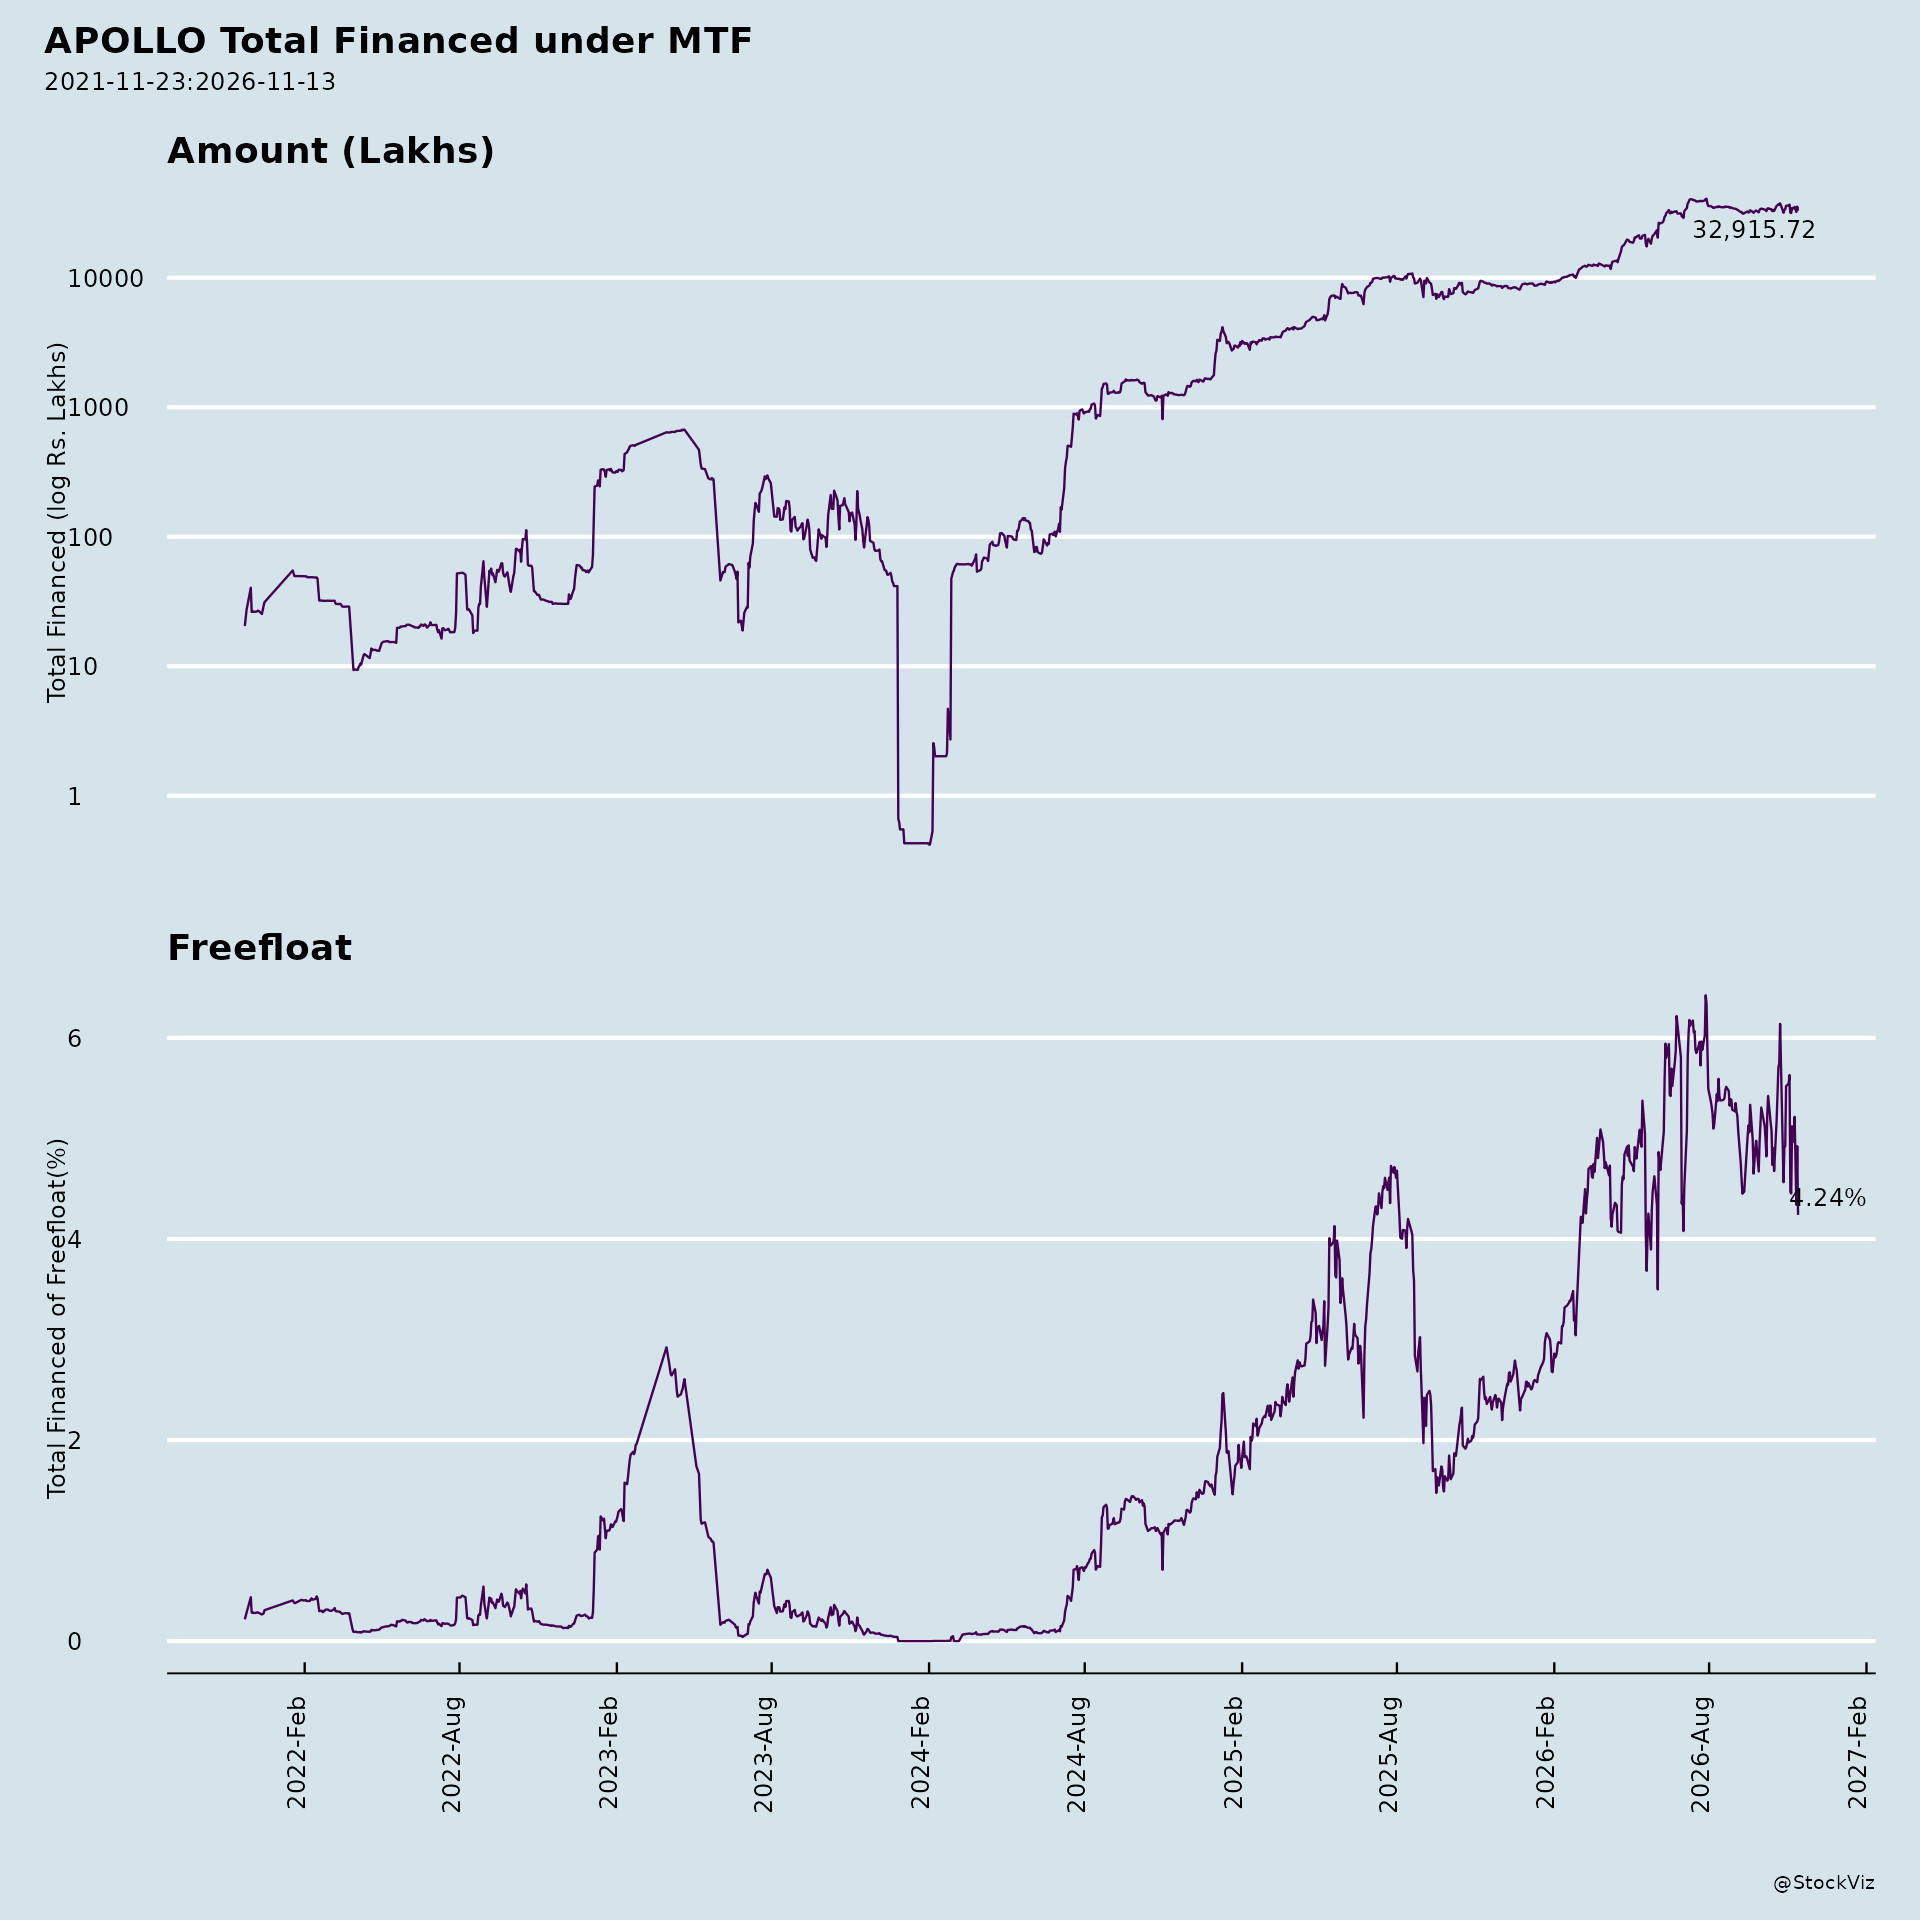
Margined
AI Summary
asof: 2026-09-17
Apollo Micro Systems — Recent Corporate Announcements
Headwinds and Challenges
- Performance in the defence industry is inherently uneven: extended procurement cycles and milestone-linked execution result in revenue recognition that is uneven across quarters, and quarterly variations are not necessarily indicative of underlying business momentum. The company itself notes that performance is best assessed year-on-year rather than quarter-on-quarter.
- Certain subsidiaries and step-down subsidiaries show indicators warranting an assessment of their ability to continue as a going concern, including negative net worth, cash losses for the quarter, losses for the past year, and large borrowings/liabilities.
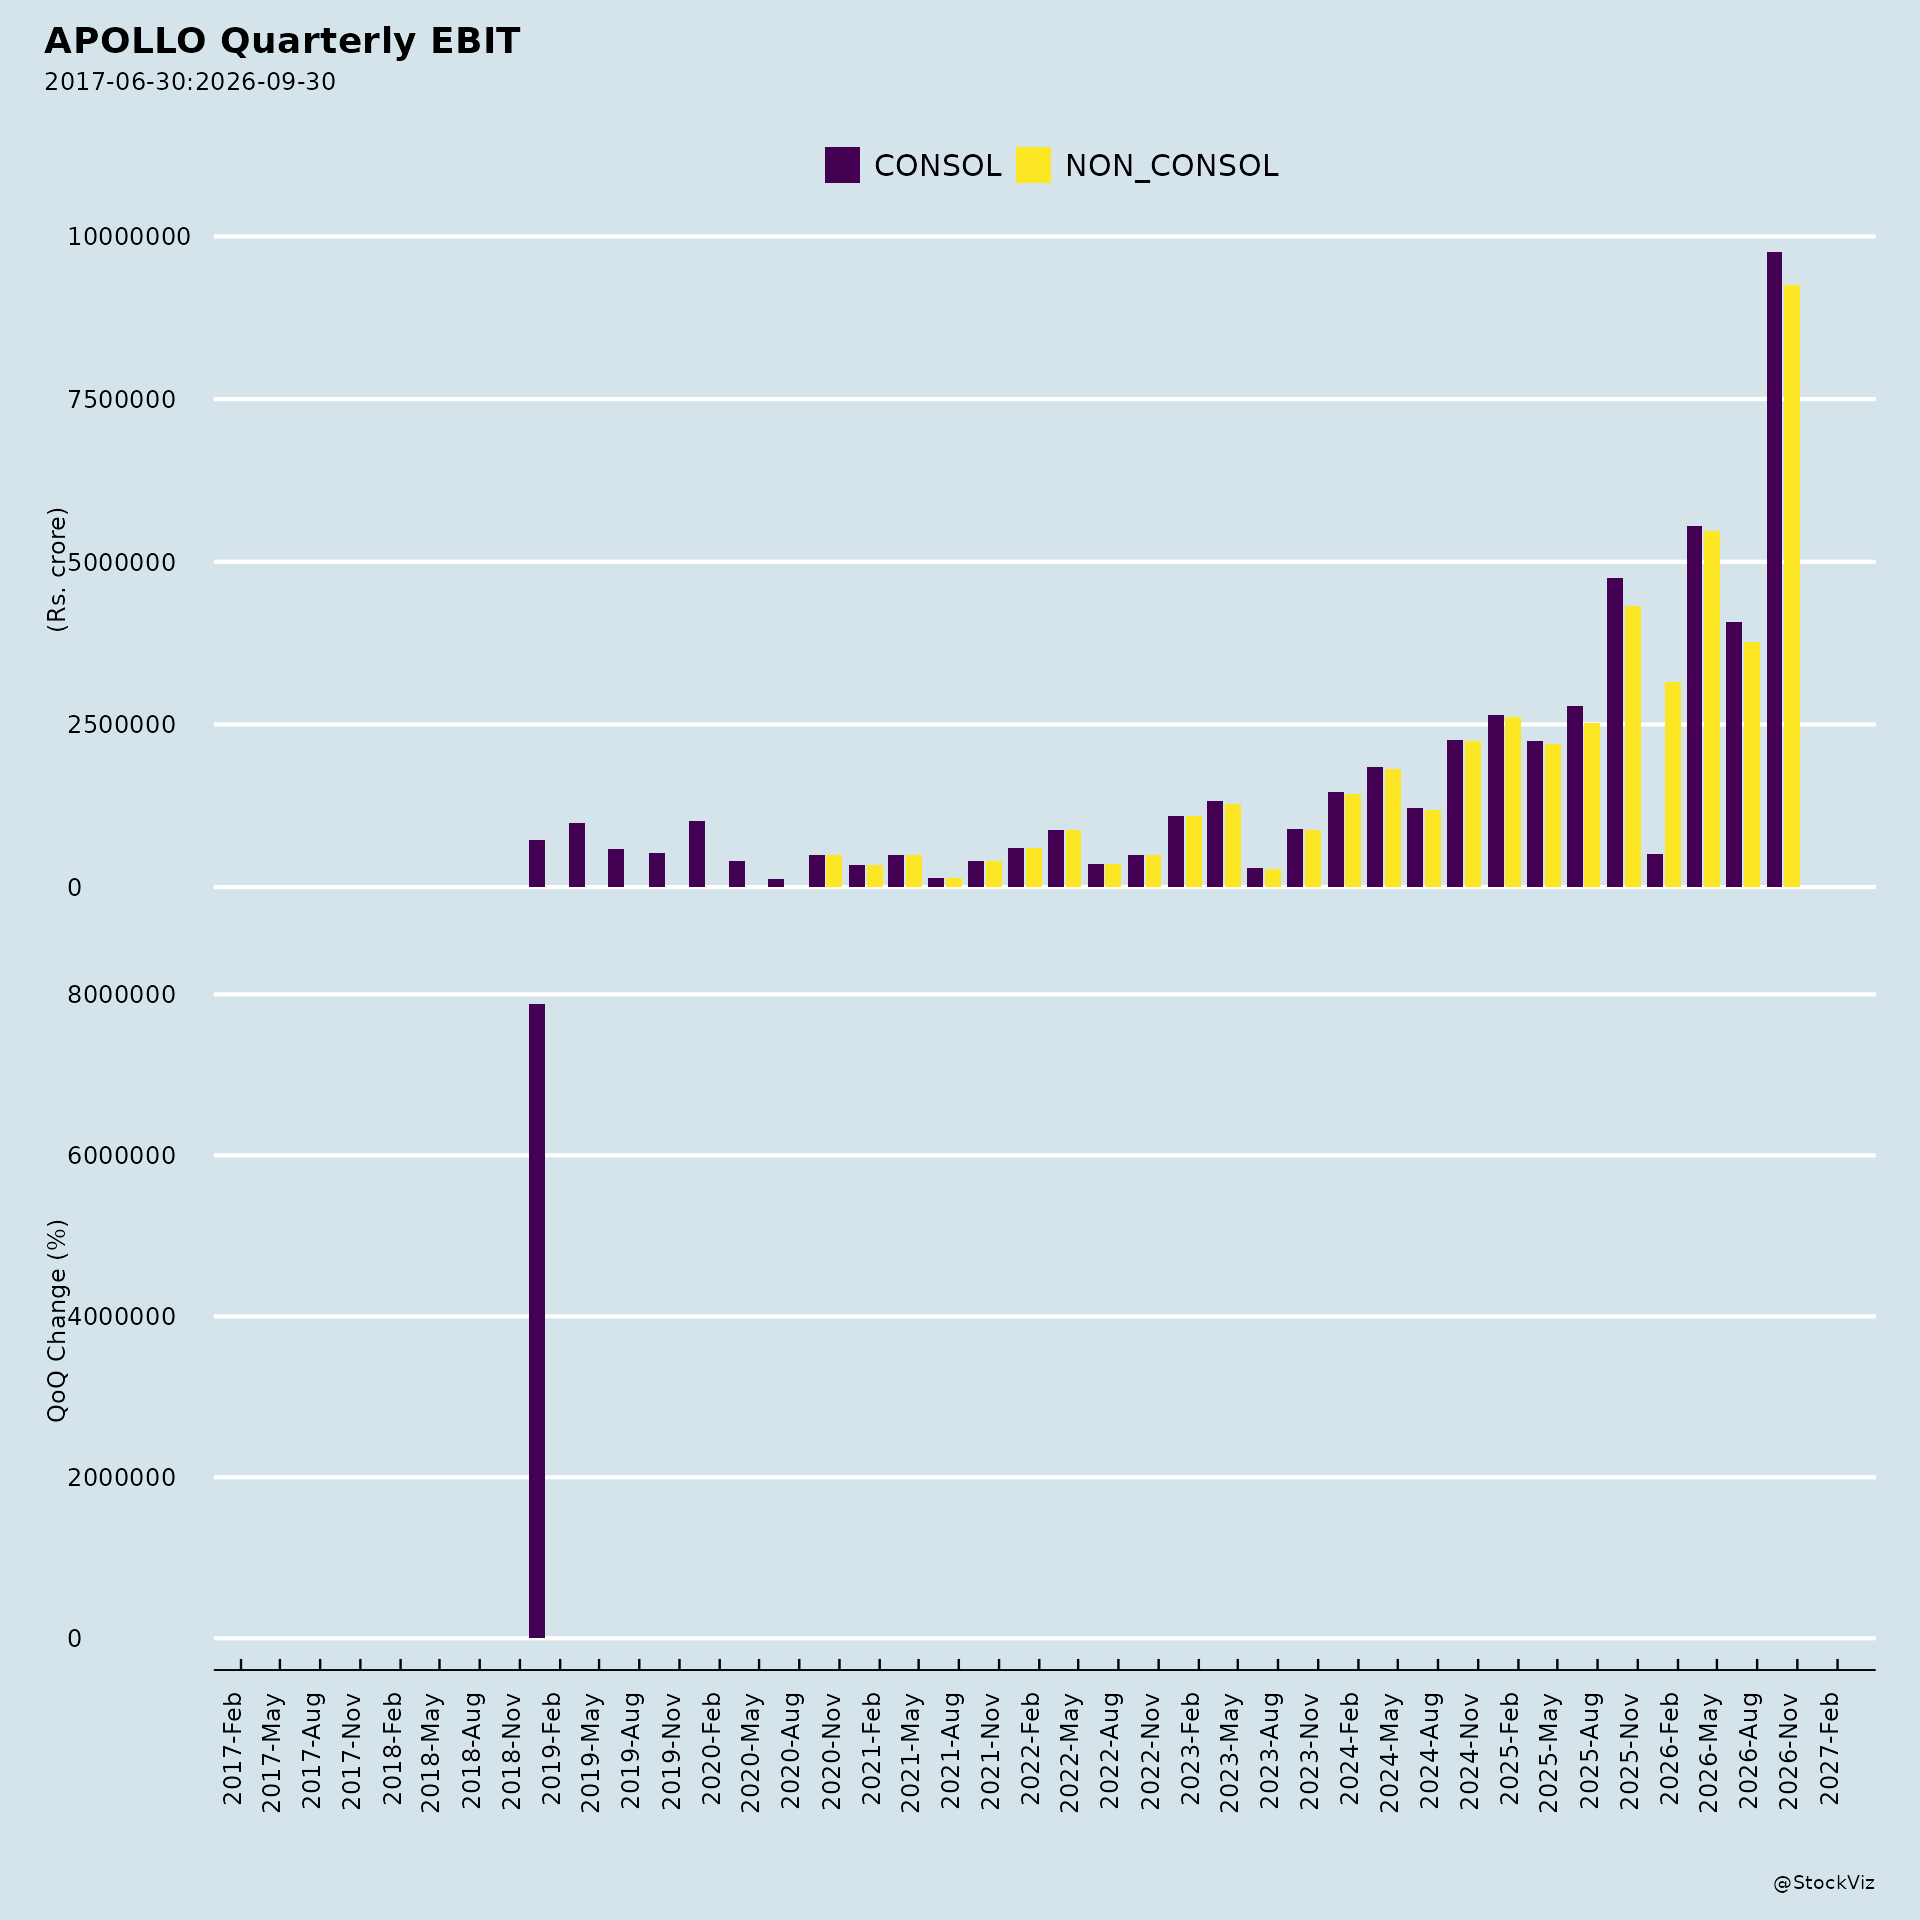
- Margins compressed on a year-on-year basis in Q1FY27: consolidated EBITDA margin stood at 21.4% versus 30.6% in Q1FY26, and PAT margin at 10.0% versus 13.2% in Q1FY26, even as absolute revenue, EBITDA and PAT grew.
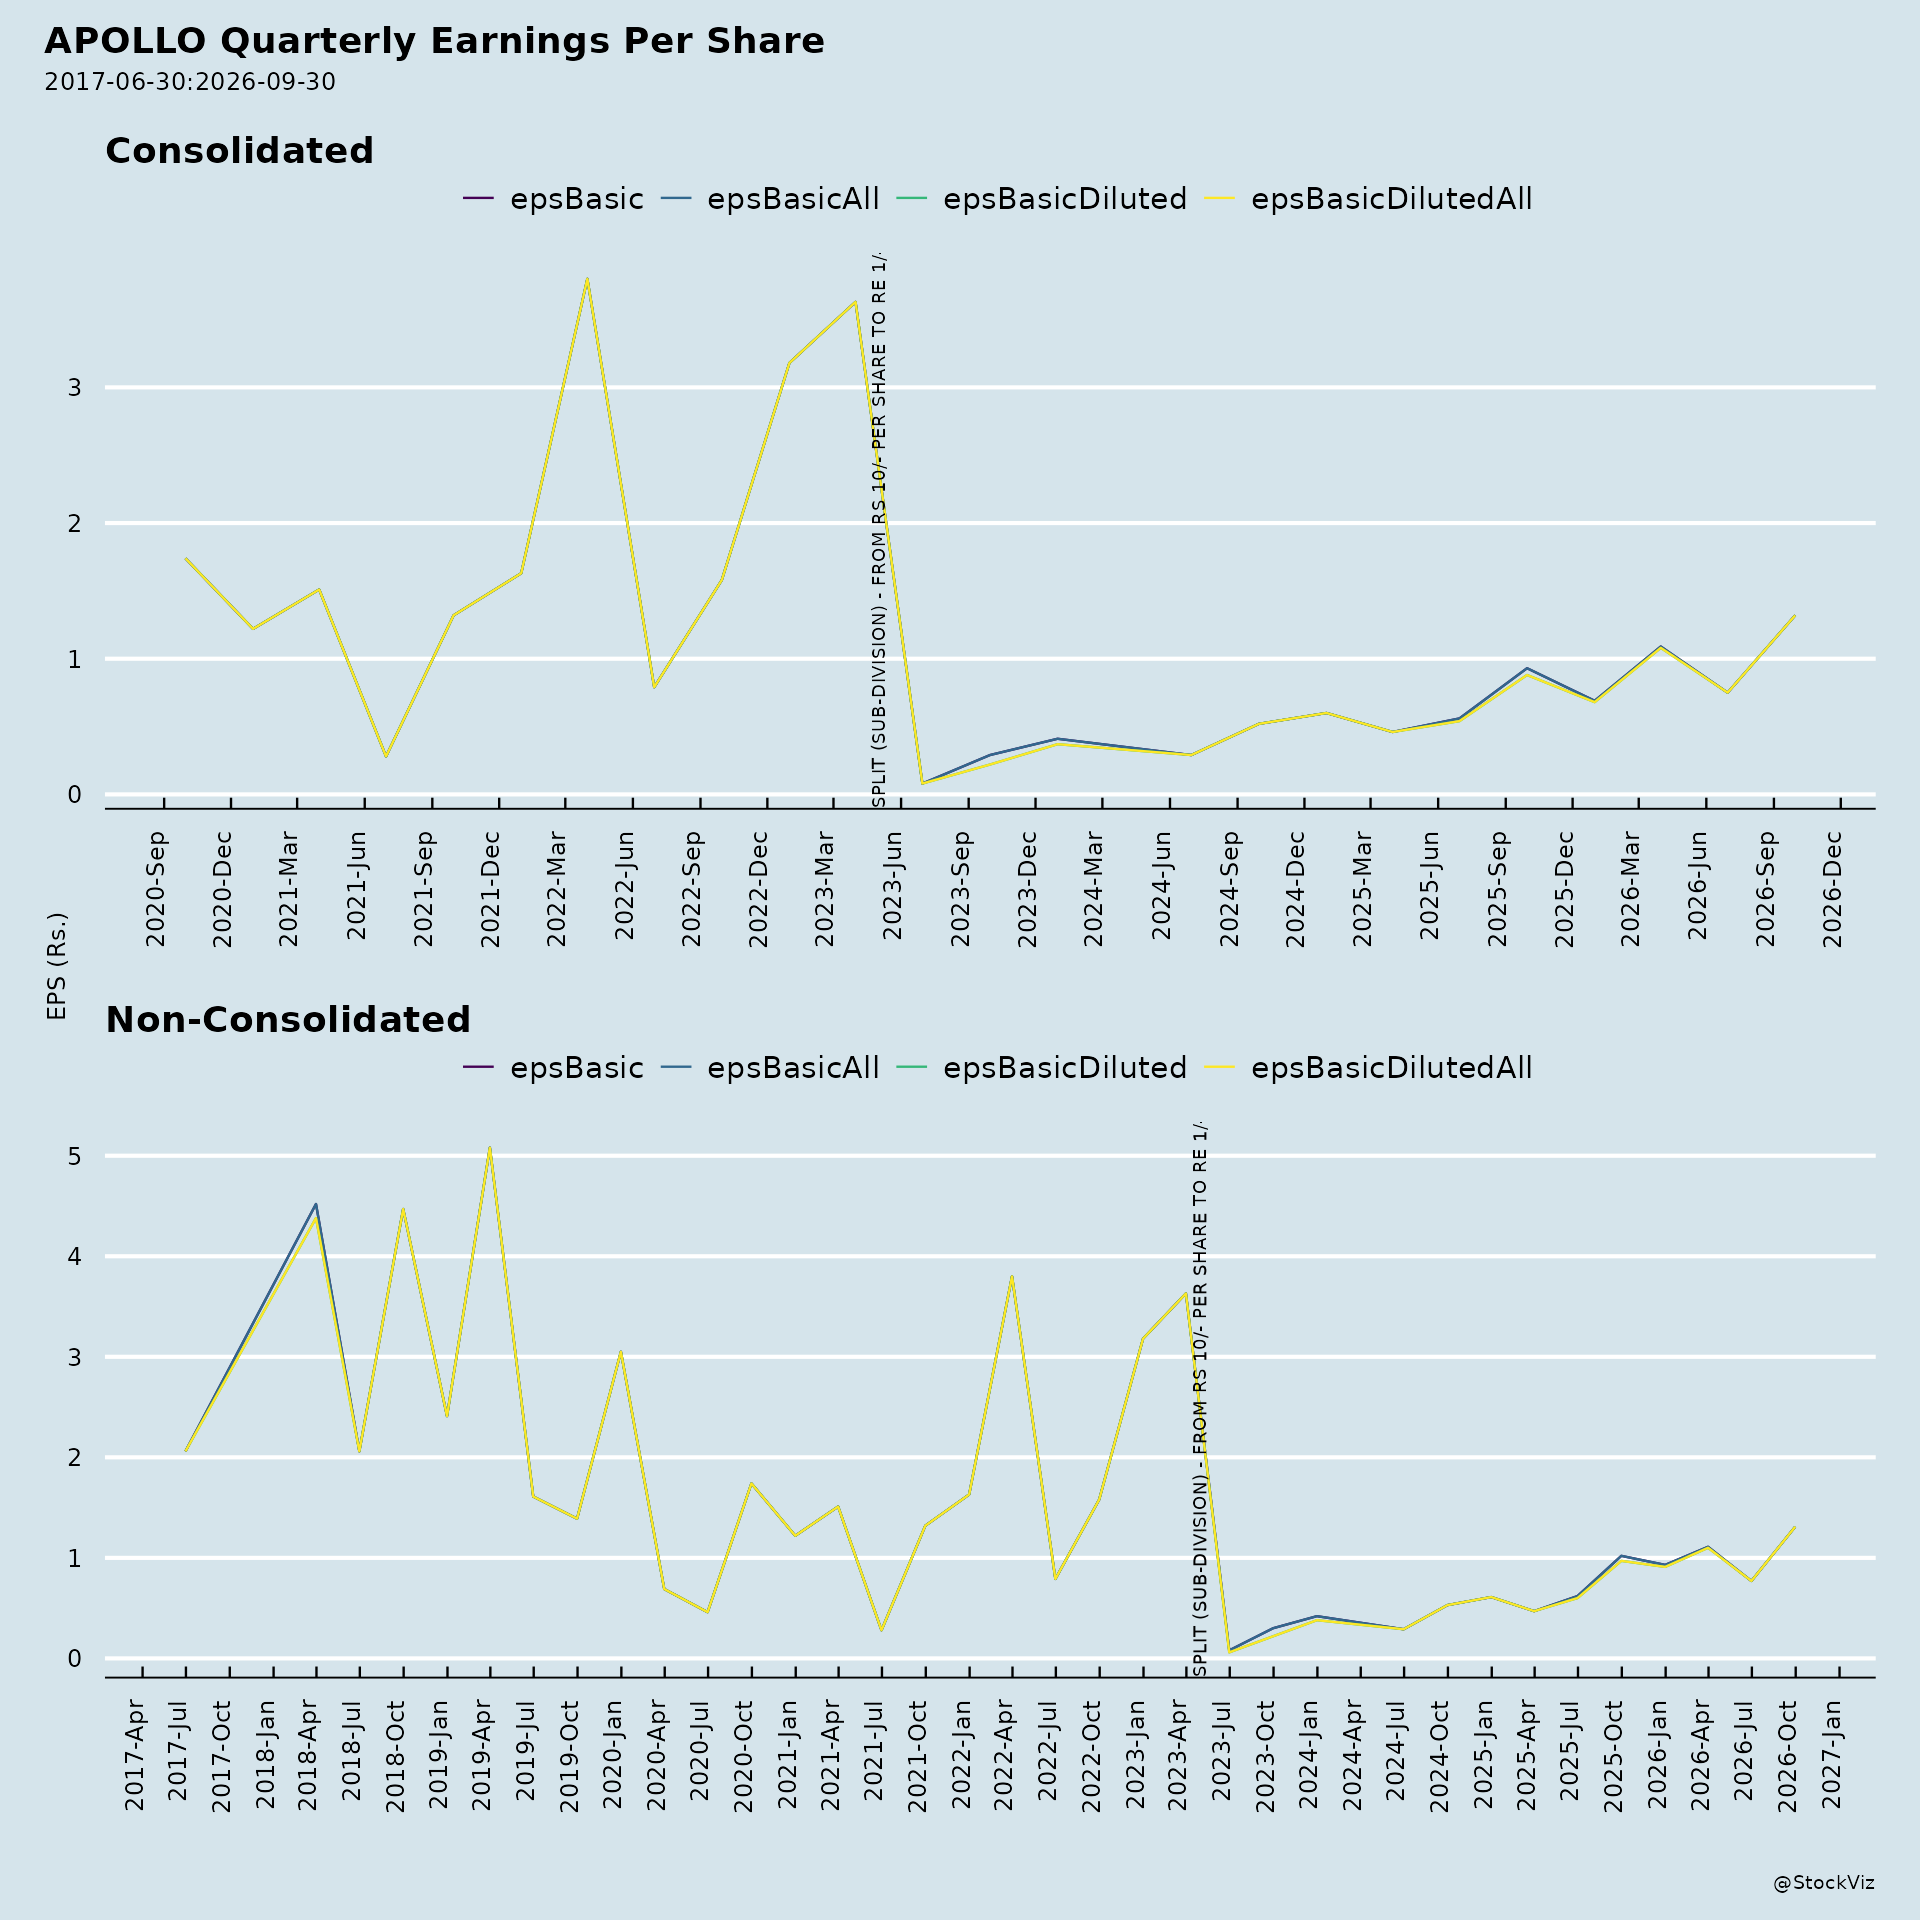
- The equity base expanded following the preferential allotment of shares — from 33,35,32,454 shares as on 30 June 2025 to 37,15,99,512 shares as on 30 June 2026, an increase of over 11% — which the company notes makes quarterly EPS not strictly comparable on a QoQ and YoY basis.
- Statements concerning future plans are forward looking and subject to risks and uncertainties.
Tailwinds and Growth Prospects
- Q1FY27 was described as the highest ever Q1 across revenue, EBITDA, PAT, EBITDA margin and PAT margin, with an all-time high order book.
- Consolidated order book stood at ₹1,704 Cr as on 8 August 2026.
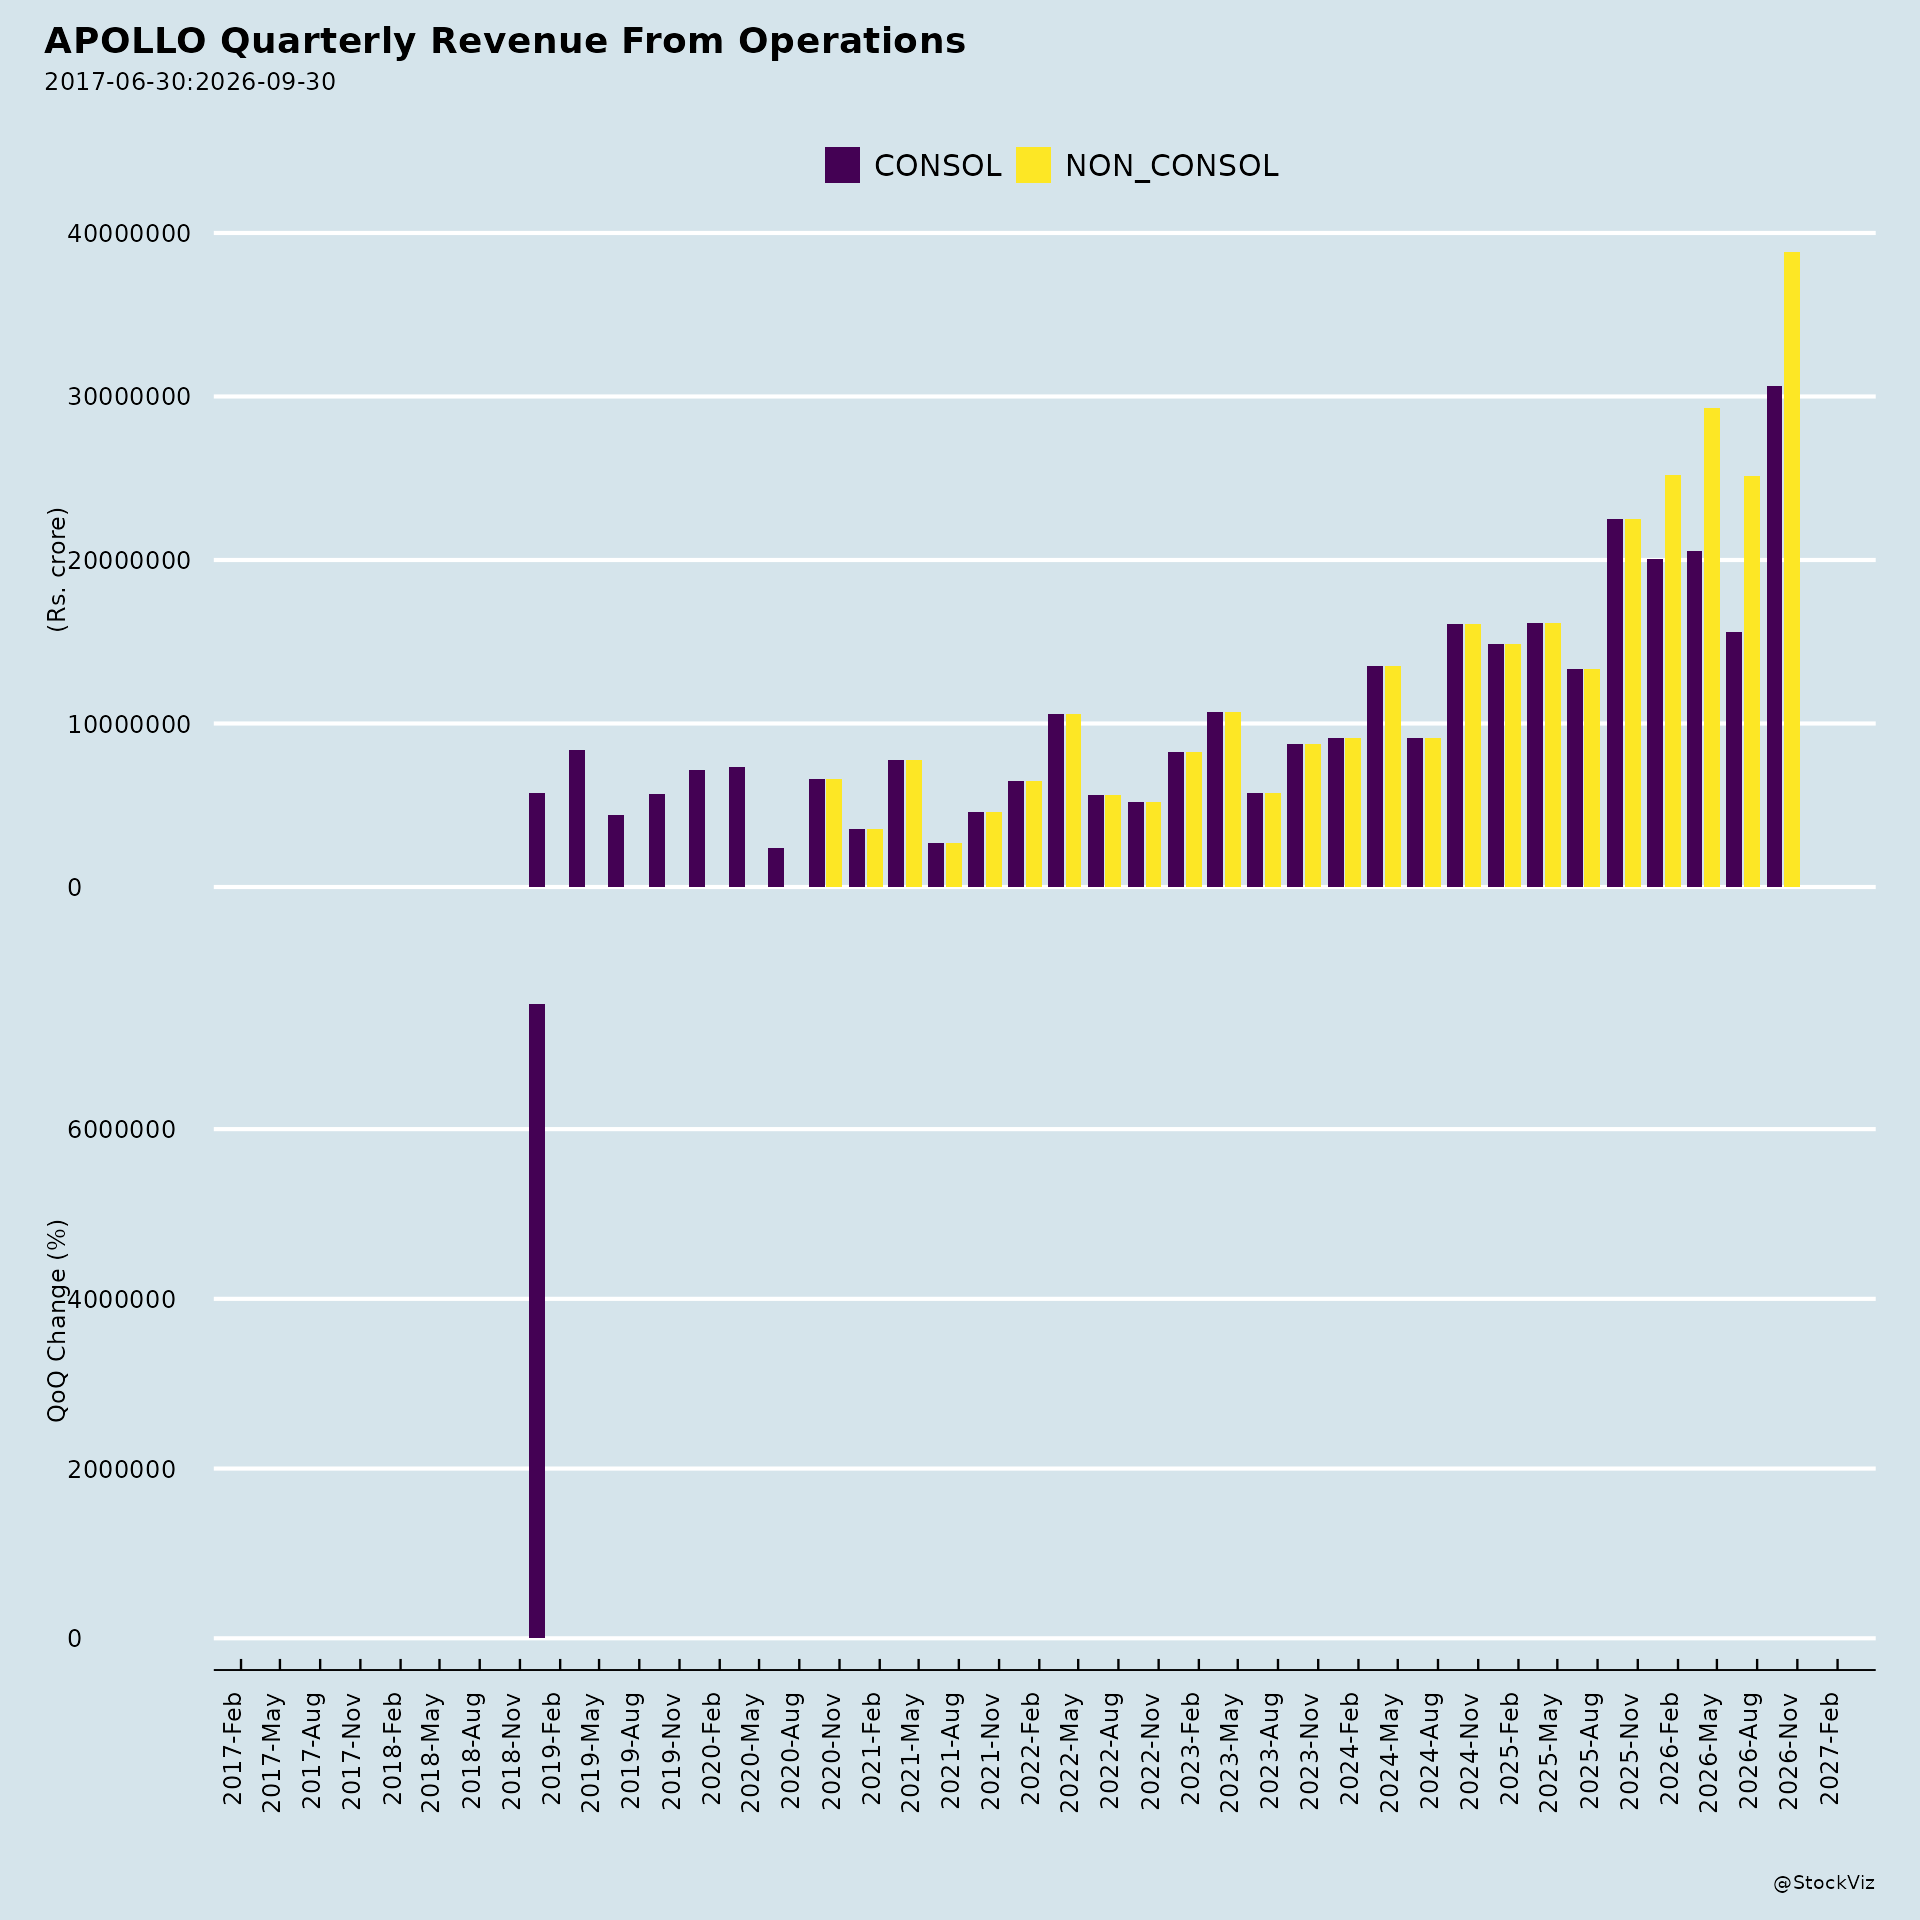
- Consolidated Q1FY27 revenue was ₹251 Cr, up 88% YoY from ₹134 Cr in Q1FY26; EBITDA (ex OI) was ₹54 Cr, up 31% from ₹41 Cr; PAT was ₹25 Cr, up 43% from ₹18 Cr.
- Standalone Q1FY27: revenue ₹156 Cr (+17% YoY), EBITDA ₹48 Cr (+18% YoY), PAT ₹28 Cr (+43% YoY).
- Award of the Transfer of Technology (ToT) for the Semi Active Laser Homing System (SALHS).
- Acceptance of Necessity (AoN) accorded for the Multi Influence Ground Mine (MIGM) – Vighana; the company is an approved production agency for MIGM – Vighana under DcPP by DRDO, with DAC approval accorded on 3rd July 2026.
- Positioning as a Tier-I Original Equipment Design Cum manufacturer with in-house execution capabilities; the company is an established Tier-1 supplier to DRDO, HAL, BEL and the Ministry of Defence, and is licensed to manufacture missile-class weapon systems under the Arms Act, 1959.
- Growth in profitability has more than outpaced the increase in share capital, which the company describes as accretive, earnings-led growth, with EPS improving despite the over 11% increase in equity base.
- Management emphasizes a long-term strategy of developing and manufacturing advanced, mission-critical defence systems and accelerating indigenization.
Key Risks
- Forward-looking statements are subject to risks and uncertainties; actual results may differ materially due to changes in government policy, market conditions, regulatory developments, or other external factors.
- Subsidiary-level going-concern indicators: negative net worth, quarterly cash losses, prior-year losses, and large borrowings/liabilities at certain subsidiaries and step-down subsidiaries.
- Uneven revenue recognition from extended procurement cycles and milestone-linked execution.
- Margin pressure relative to prior-year comparability, as reflected in the Q1FY27 consolidated margin decline versus Q1FY26.
- Dilution-related comparability risk: the increase in the weighted average number of equity shares outstanding affects EPS comparability across periods.
Management Guidance Versus Observed Business Performance
- Management stated that the best ever Q1 performance reflects execution, resilience and focus, and that the company must build on this momentum with greater vigour and sharper execution while remaining aligned with the evolving requirements of the defence sector. Observed Q1FY27 performance is consistent with this: record Q1 revenue, EBITDA, PAT, EBITDA margin and PAT margin, and an all-time high order book of ₹1,704 Cr.
- Management has business plans in place to further improve subsidiaries’ profitability and financial position and, backed by improving performance and committed support from the ultimate parent company and promoters, is confident of meeting all obligations in the ordinary course of business. The subsidiary going-concern indicators noted above are the corresponding observed challenge against this guidance.
- Management notes that statements concerning future plans are forward looking and subject to risks and uncertainties, while emphasizing a long-term strategy of developing and manufacturing advanced, mission-critical defence systems and accelerating indigenization. The SALHS ToT award and the MIGM – Vighana AoN/DAC approval (3rd July 2026) are the observed developments aligned with this strategy.
- On capital structure, all 3,80,67,058 share warrants issued on 2 June 2025 were fully converted into equity shares as of 30 June 2026, with no share warrants outstanding for conversion. The EGM held on August 4, 2026 passed six resolutions, including increase in authorized share capital, issuance of equity shares and convertible equity warrants on a preferential basis, authorization to borrow monies exceeding paid-up share capital, free reserves and securities premium under Section 180(1)(c), authorization to create security under Section 180(1)(a), and authorization to give loans and guarantees under Section 186.
- Governance and investor-engagement events: the Board meeting on 8th September 2026 approved the 29th AGM for 30th September 2026, fixed 23rd September 2026 as the Record Date for the dividend and cut-off date for remote e-voting, appointed Ms. Sridevi Madati as Scrutinizer for e-voting, and appointed CareEdge Ratings as Monitoring Agency in place of Acuite Ratings & Research Limited. Company officials will attend the Anand Rathi Annual Flagship Conference G-200 Summit 2026 in Mumbai on 22nd September 2026, with discussions based strictly on publicly available information and no unpublished price sensitive information intended to be discussed.
Broker Timeline
1 broker calls · 2026-09-21 to 2026-09-21
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.