AMBUJACEM
Equity Metrics
October 23, 2026
Ambuja Cements Limited
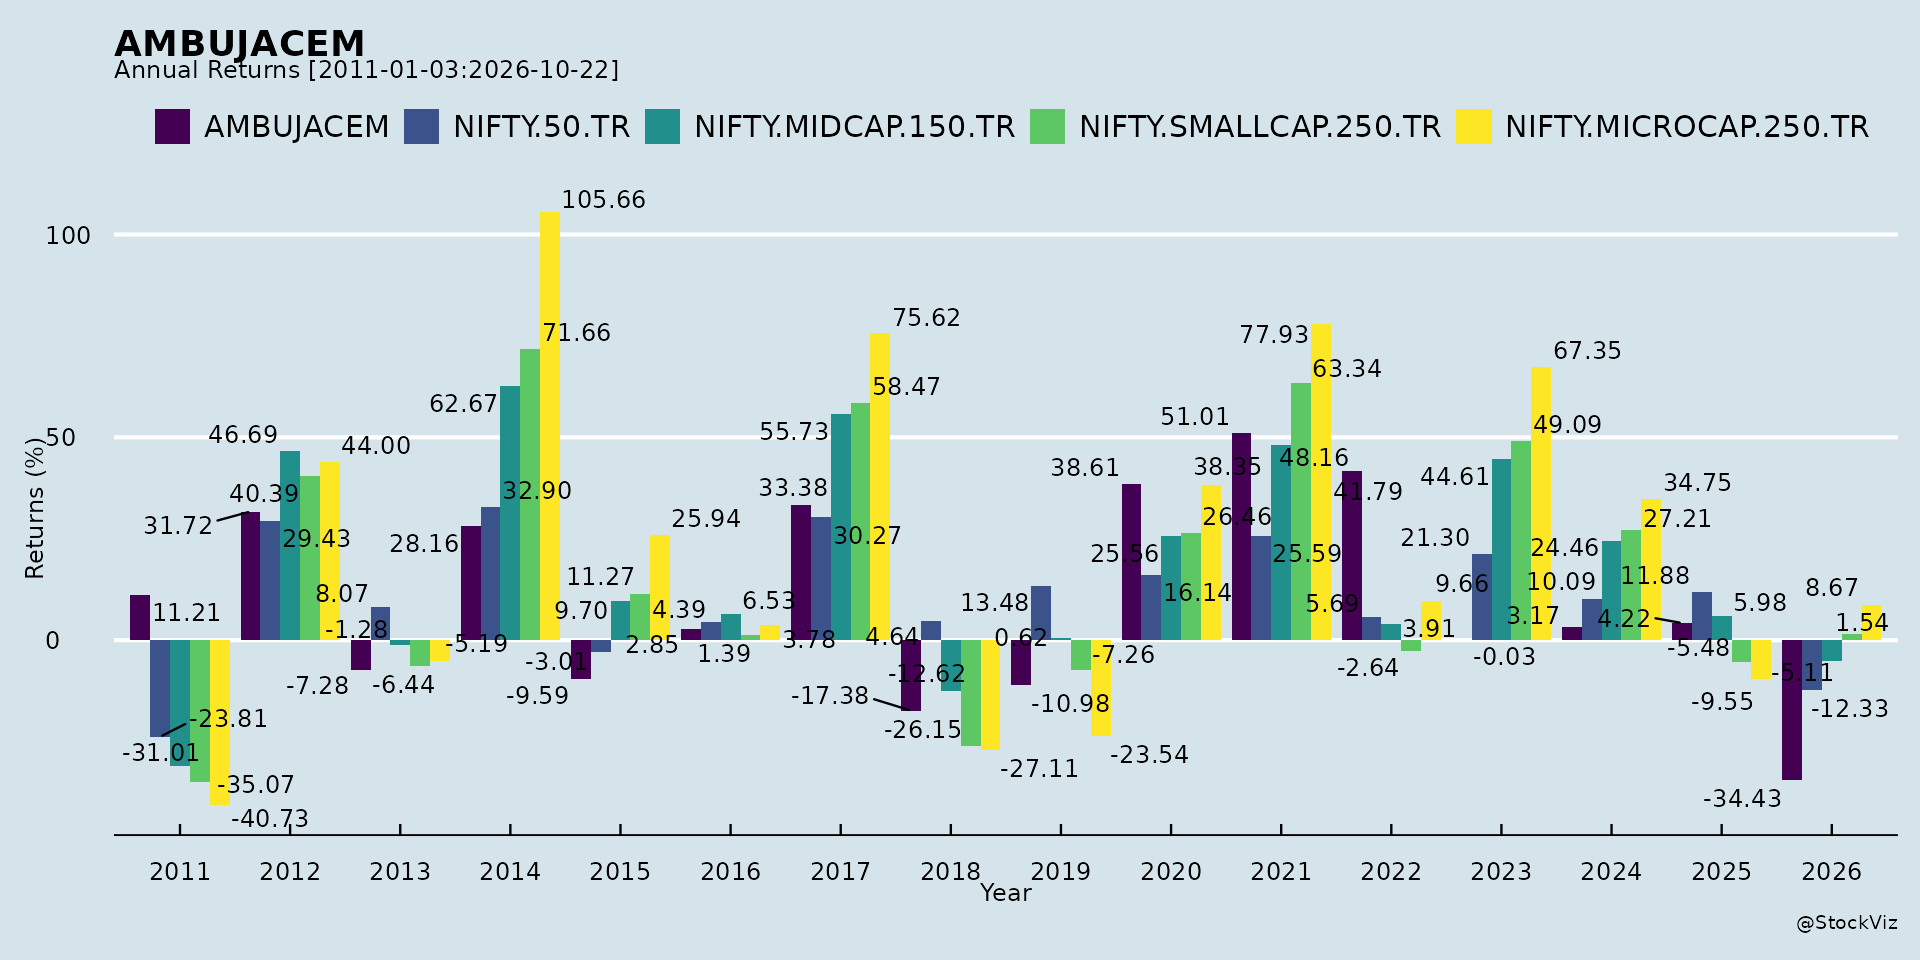
Annual Returns
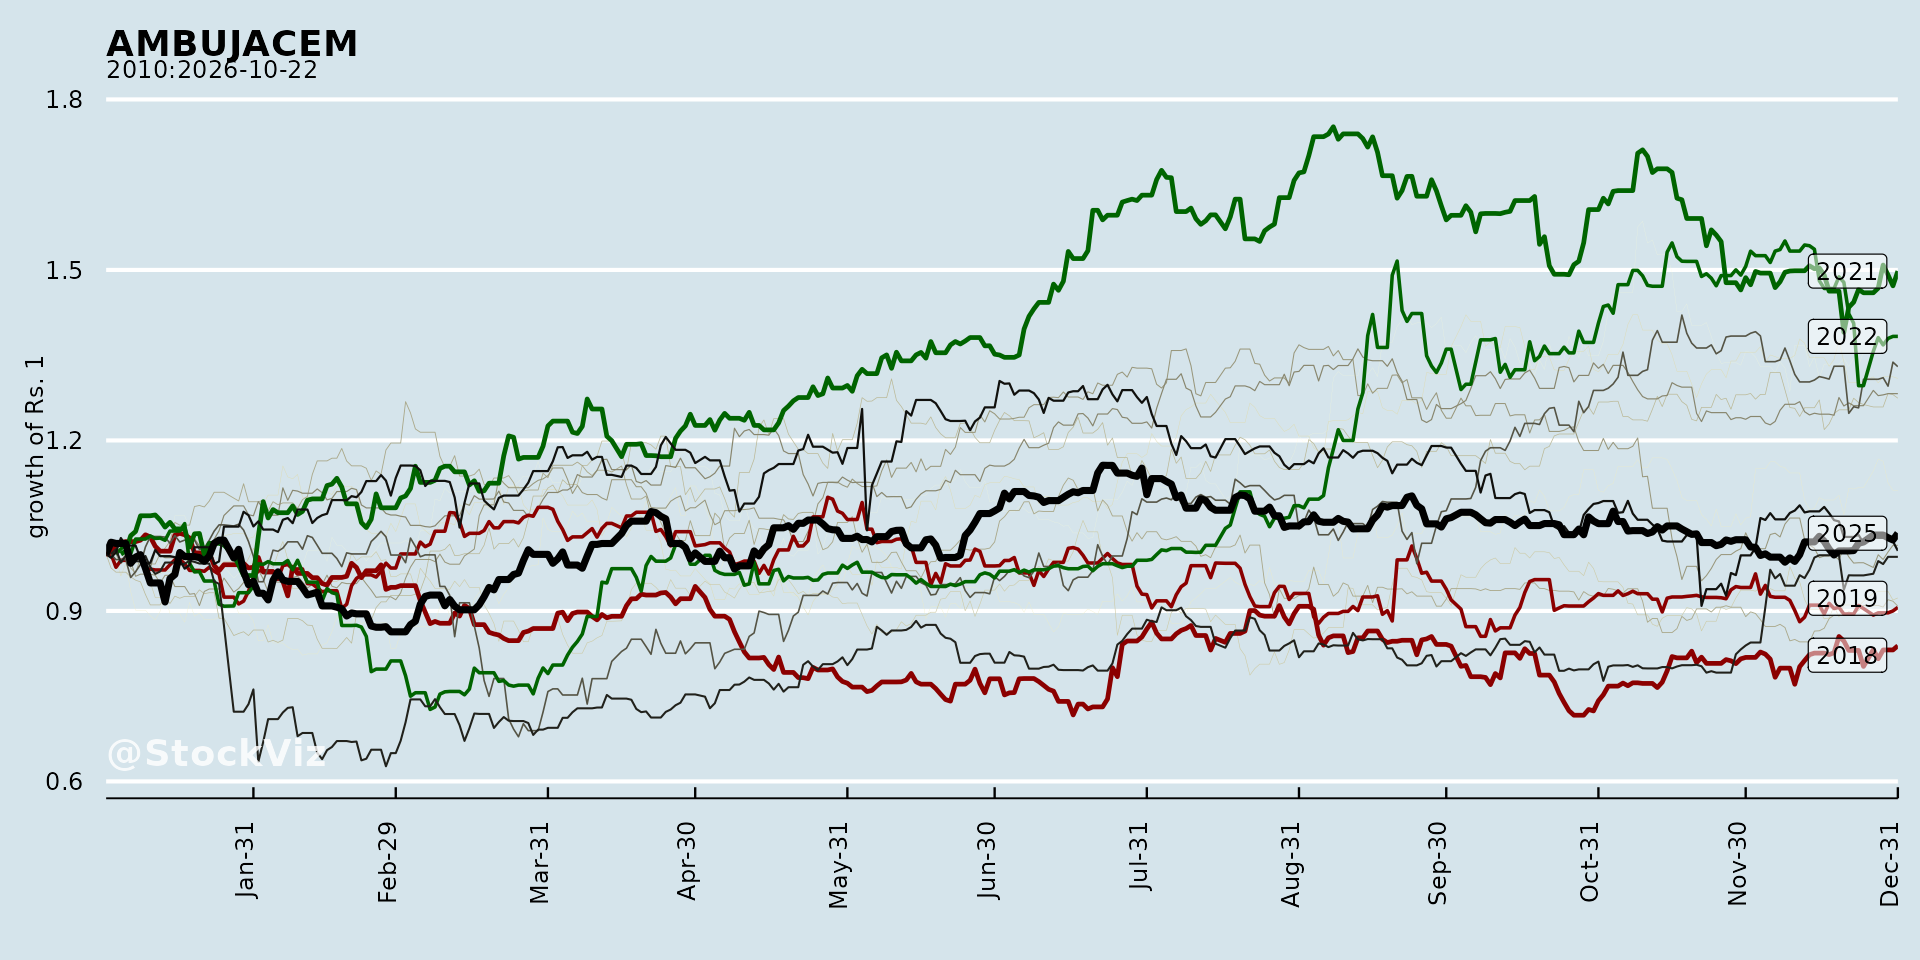
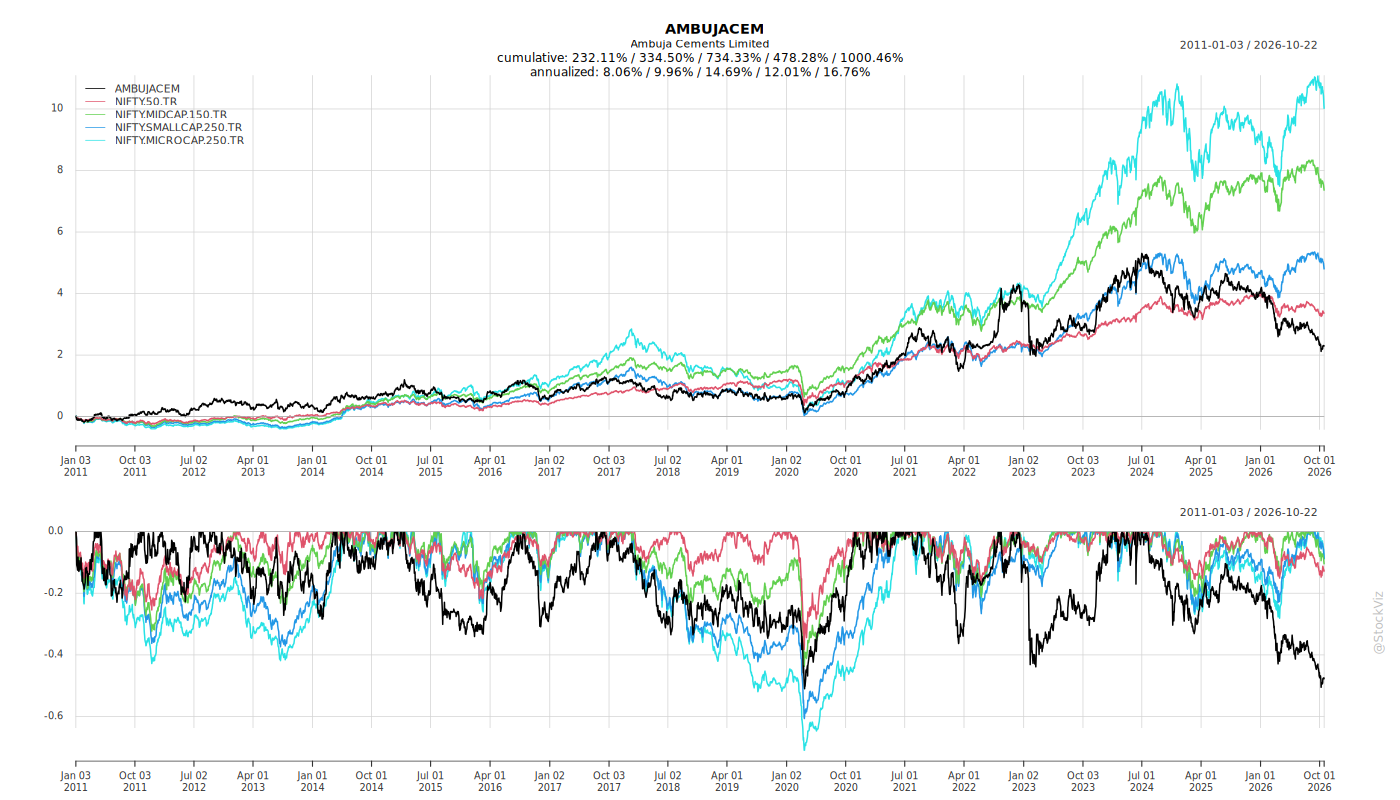
Cumulative Returns and Drawdowns
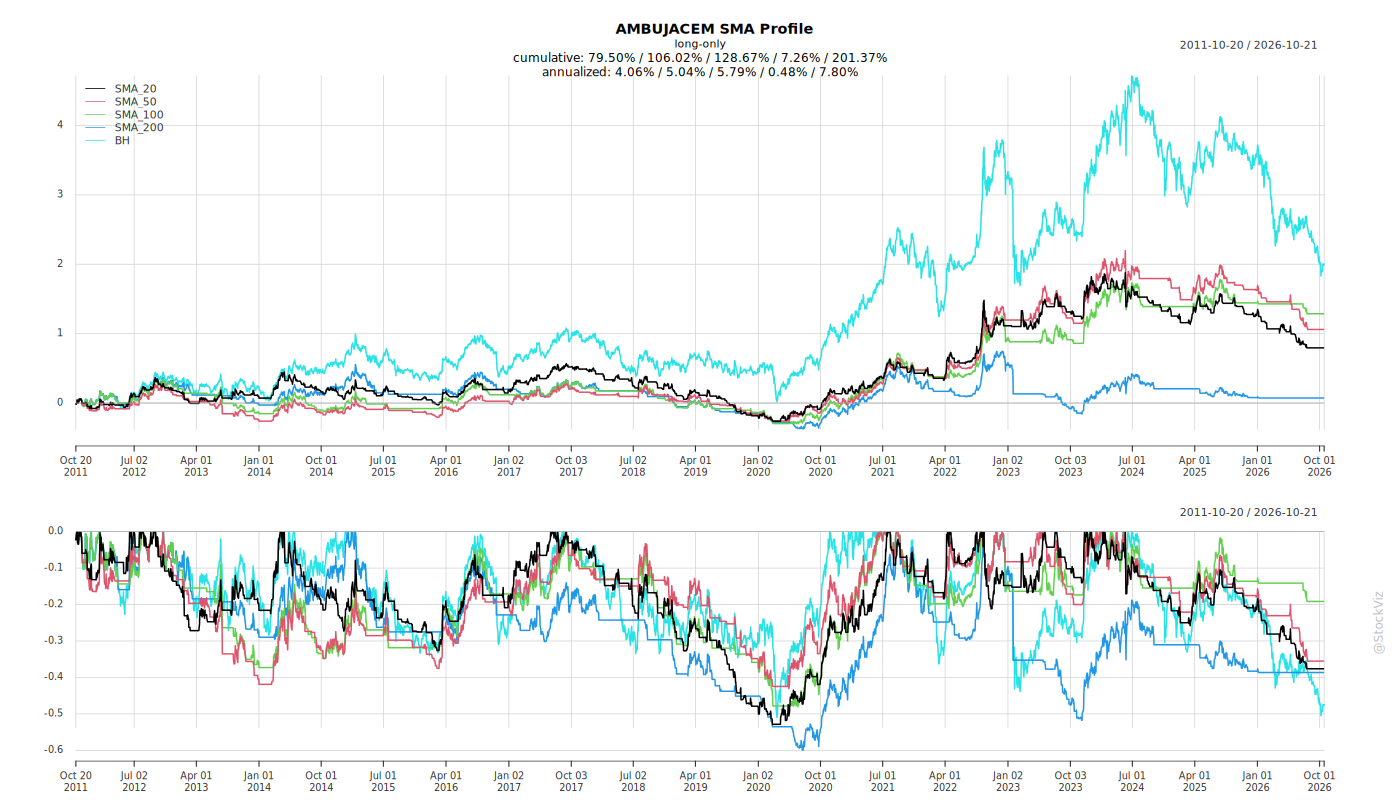
Fundamentals
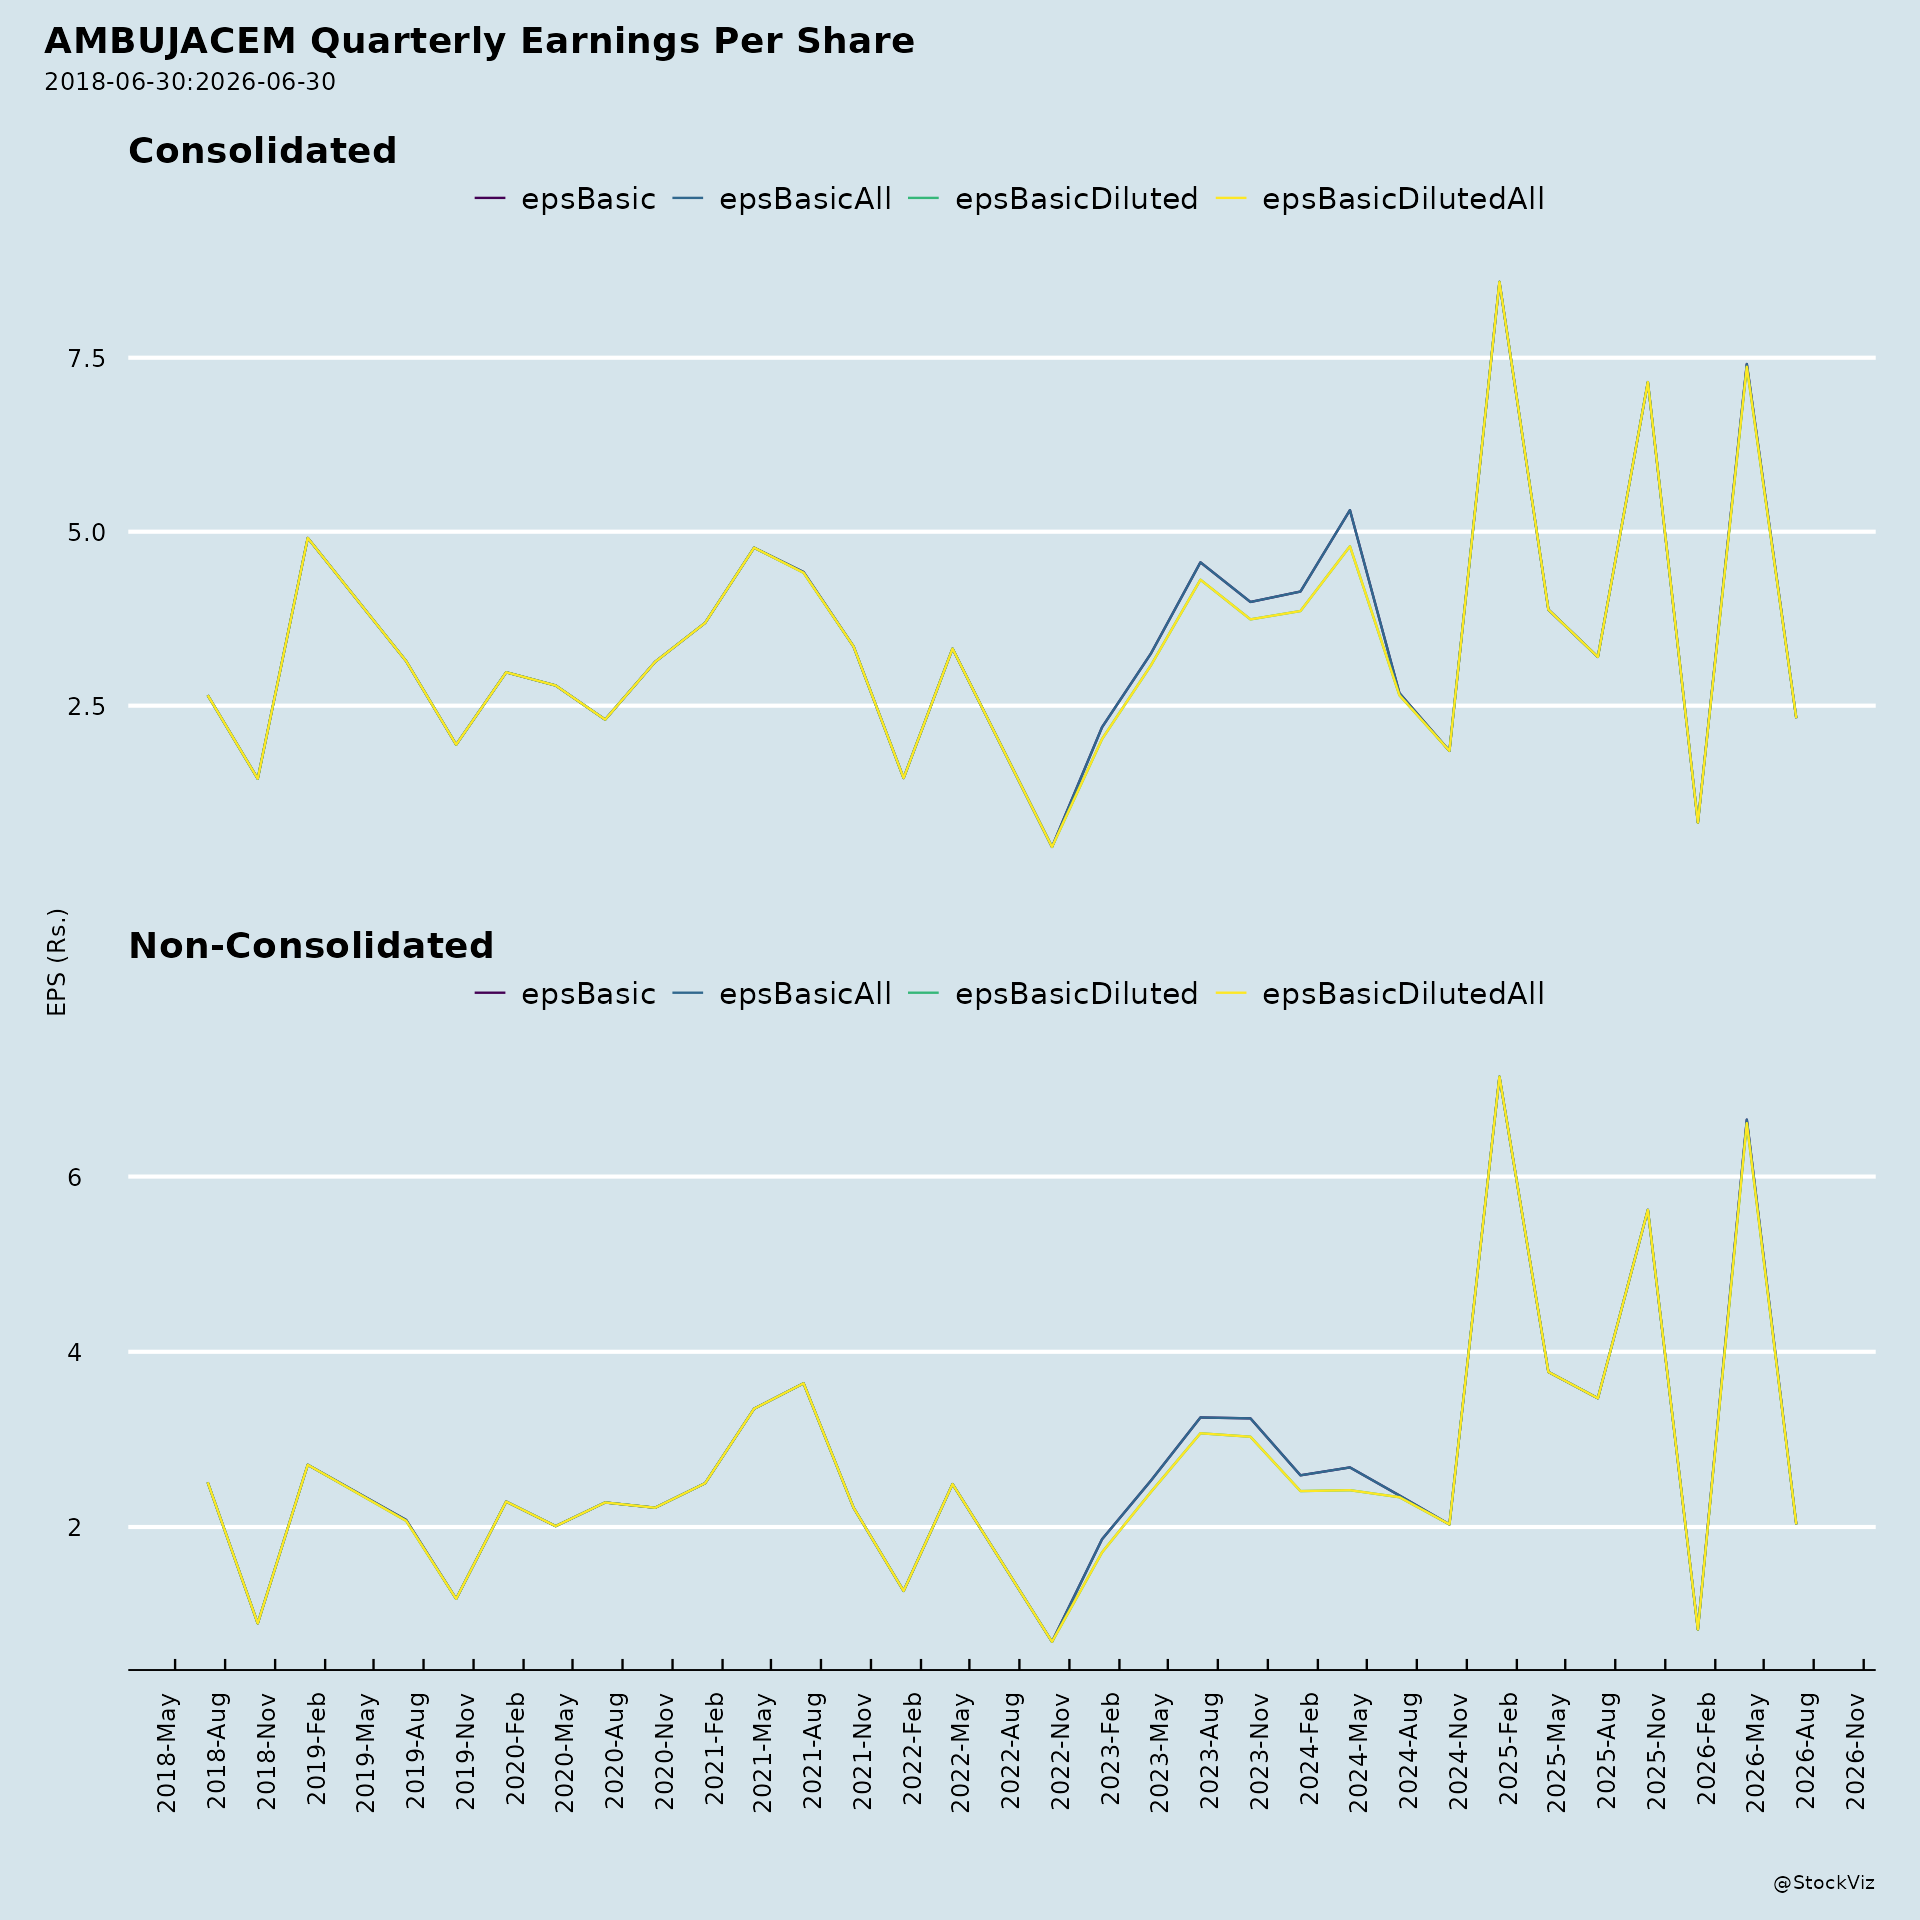
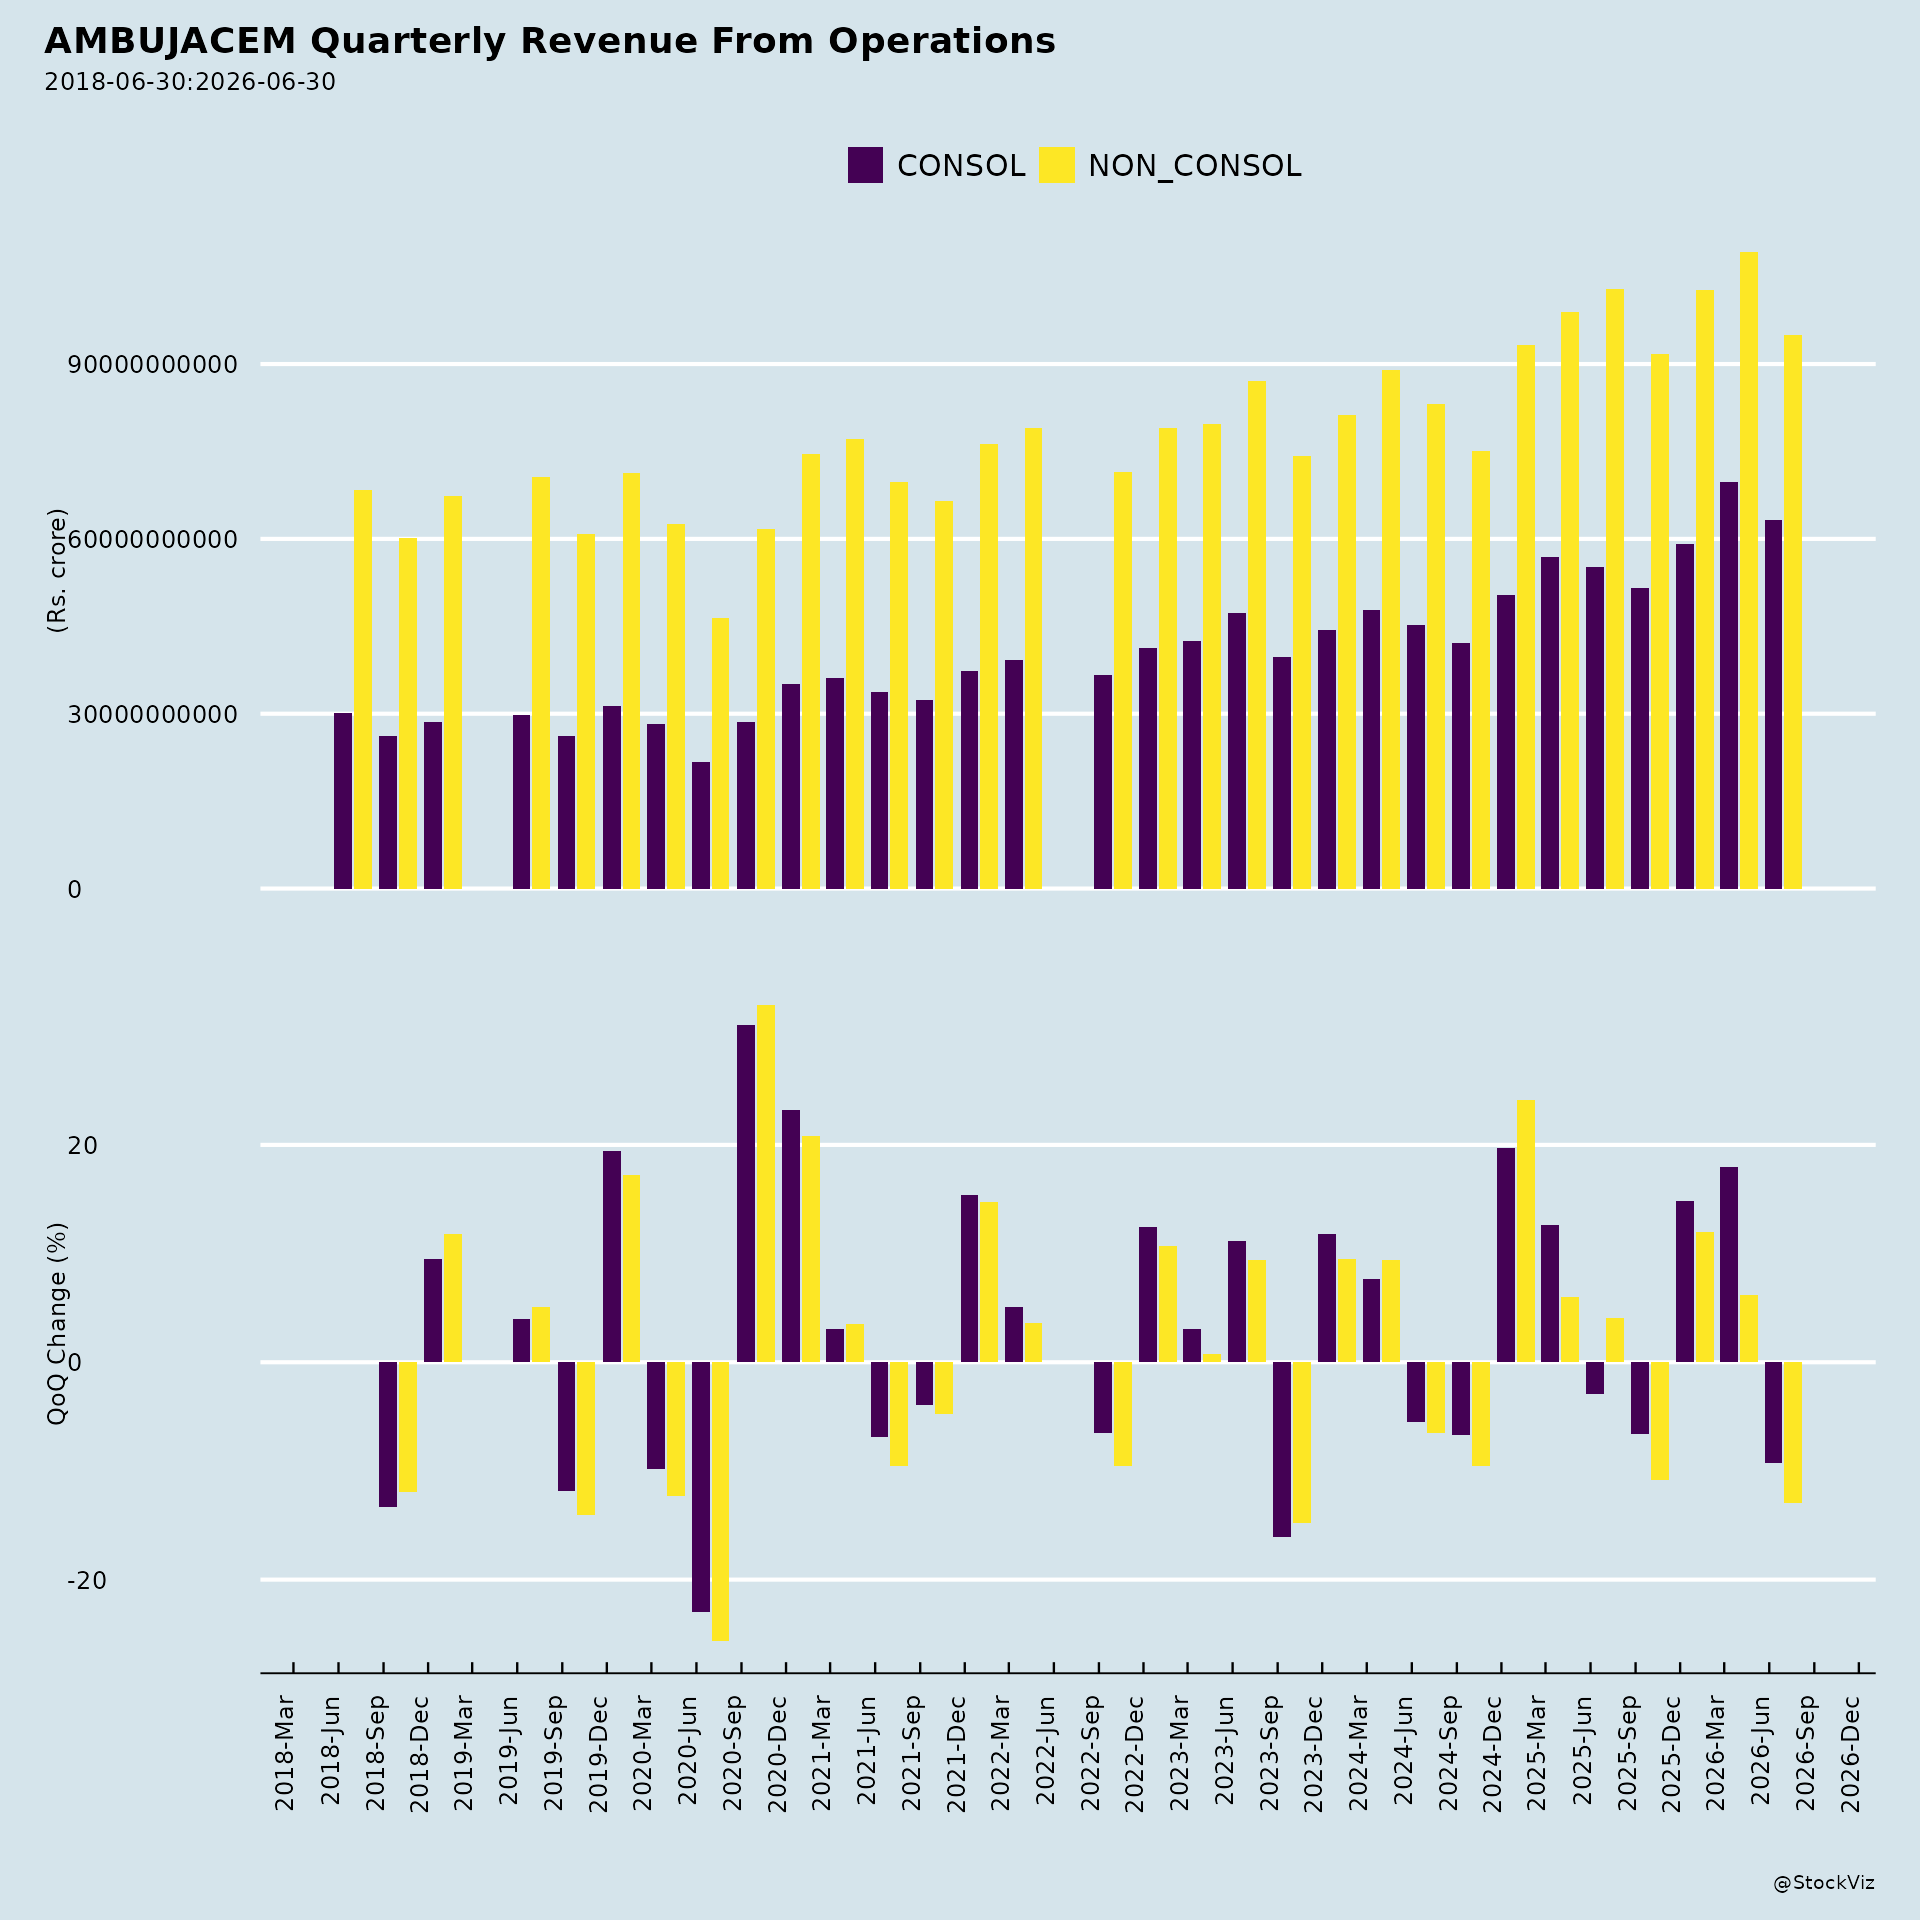
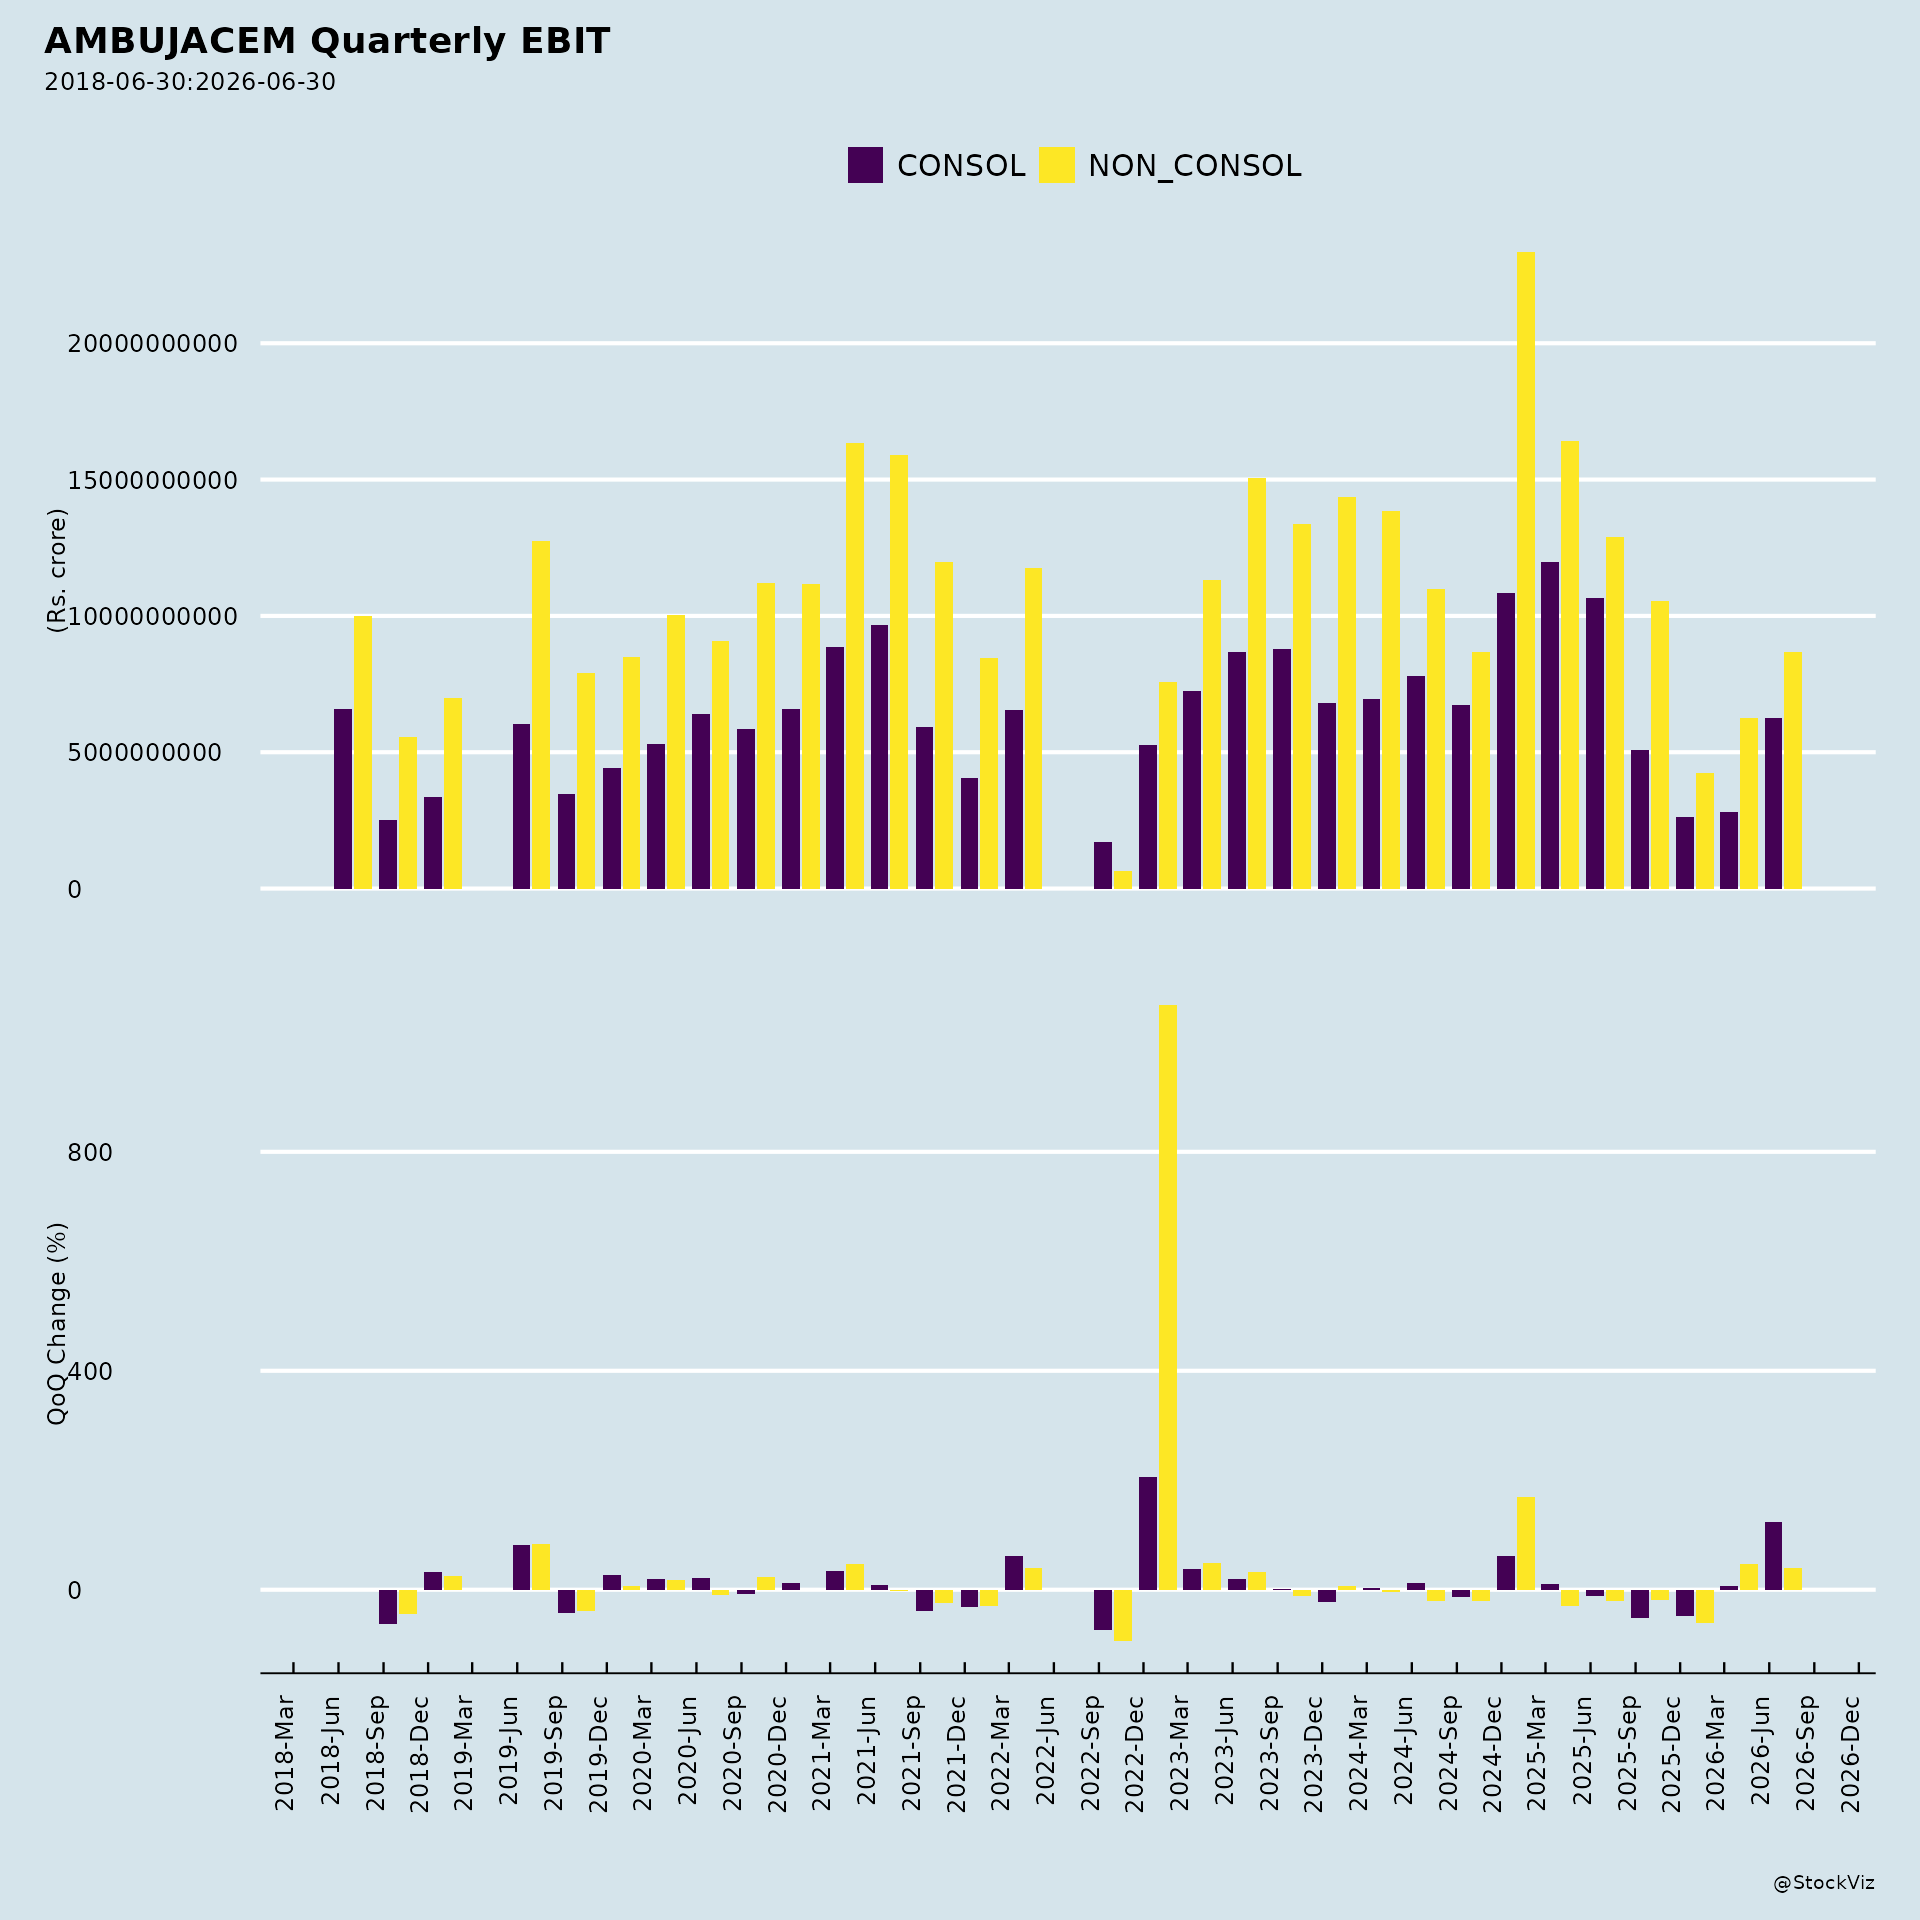
Ownership
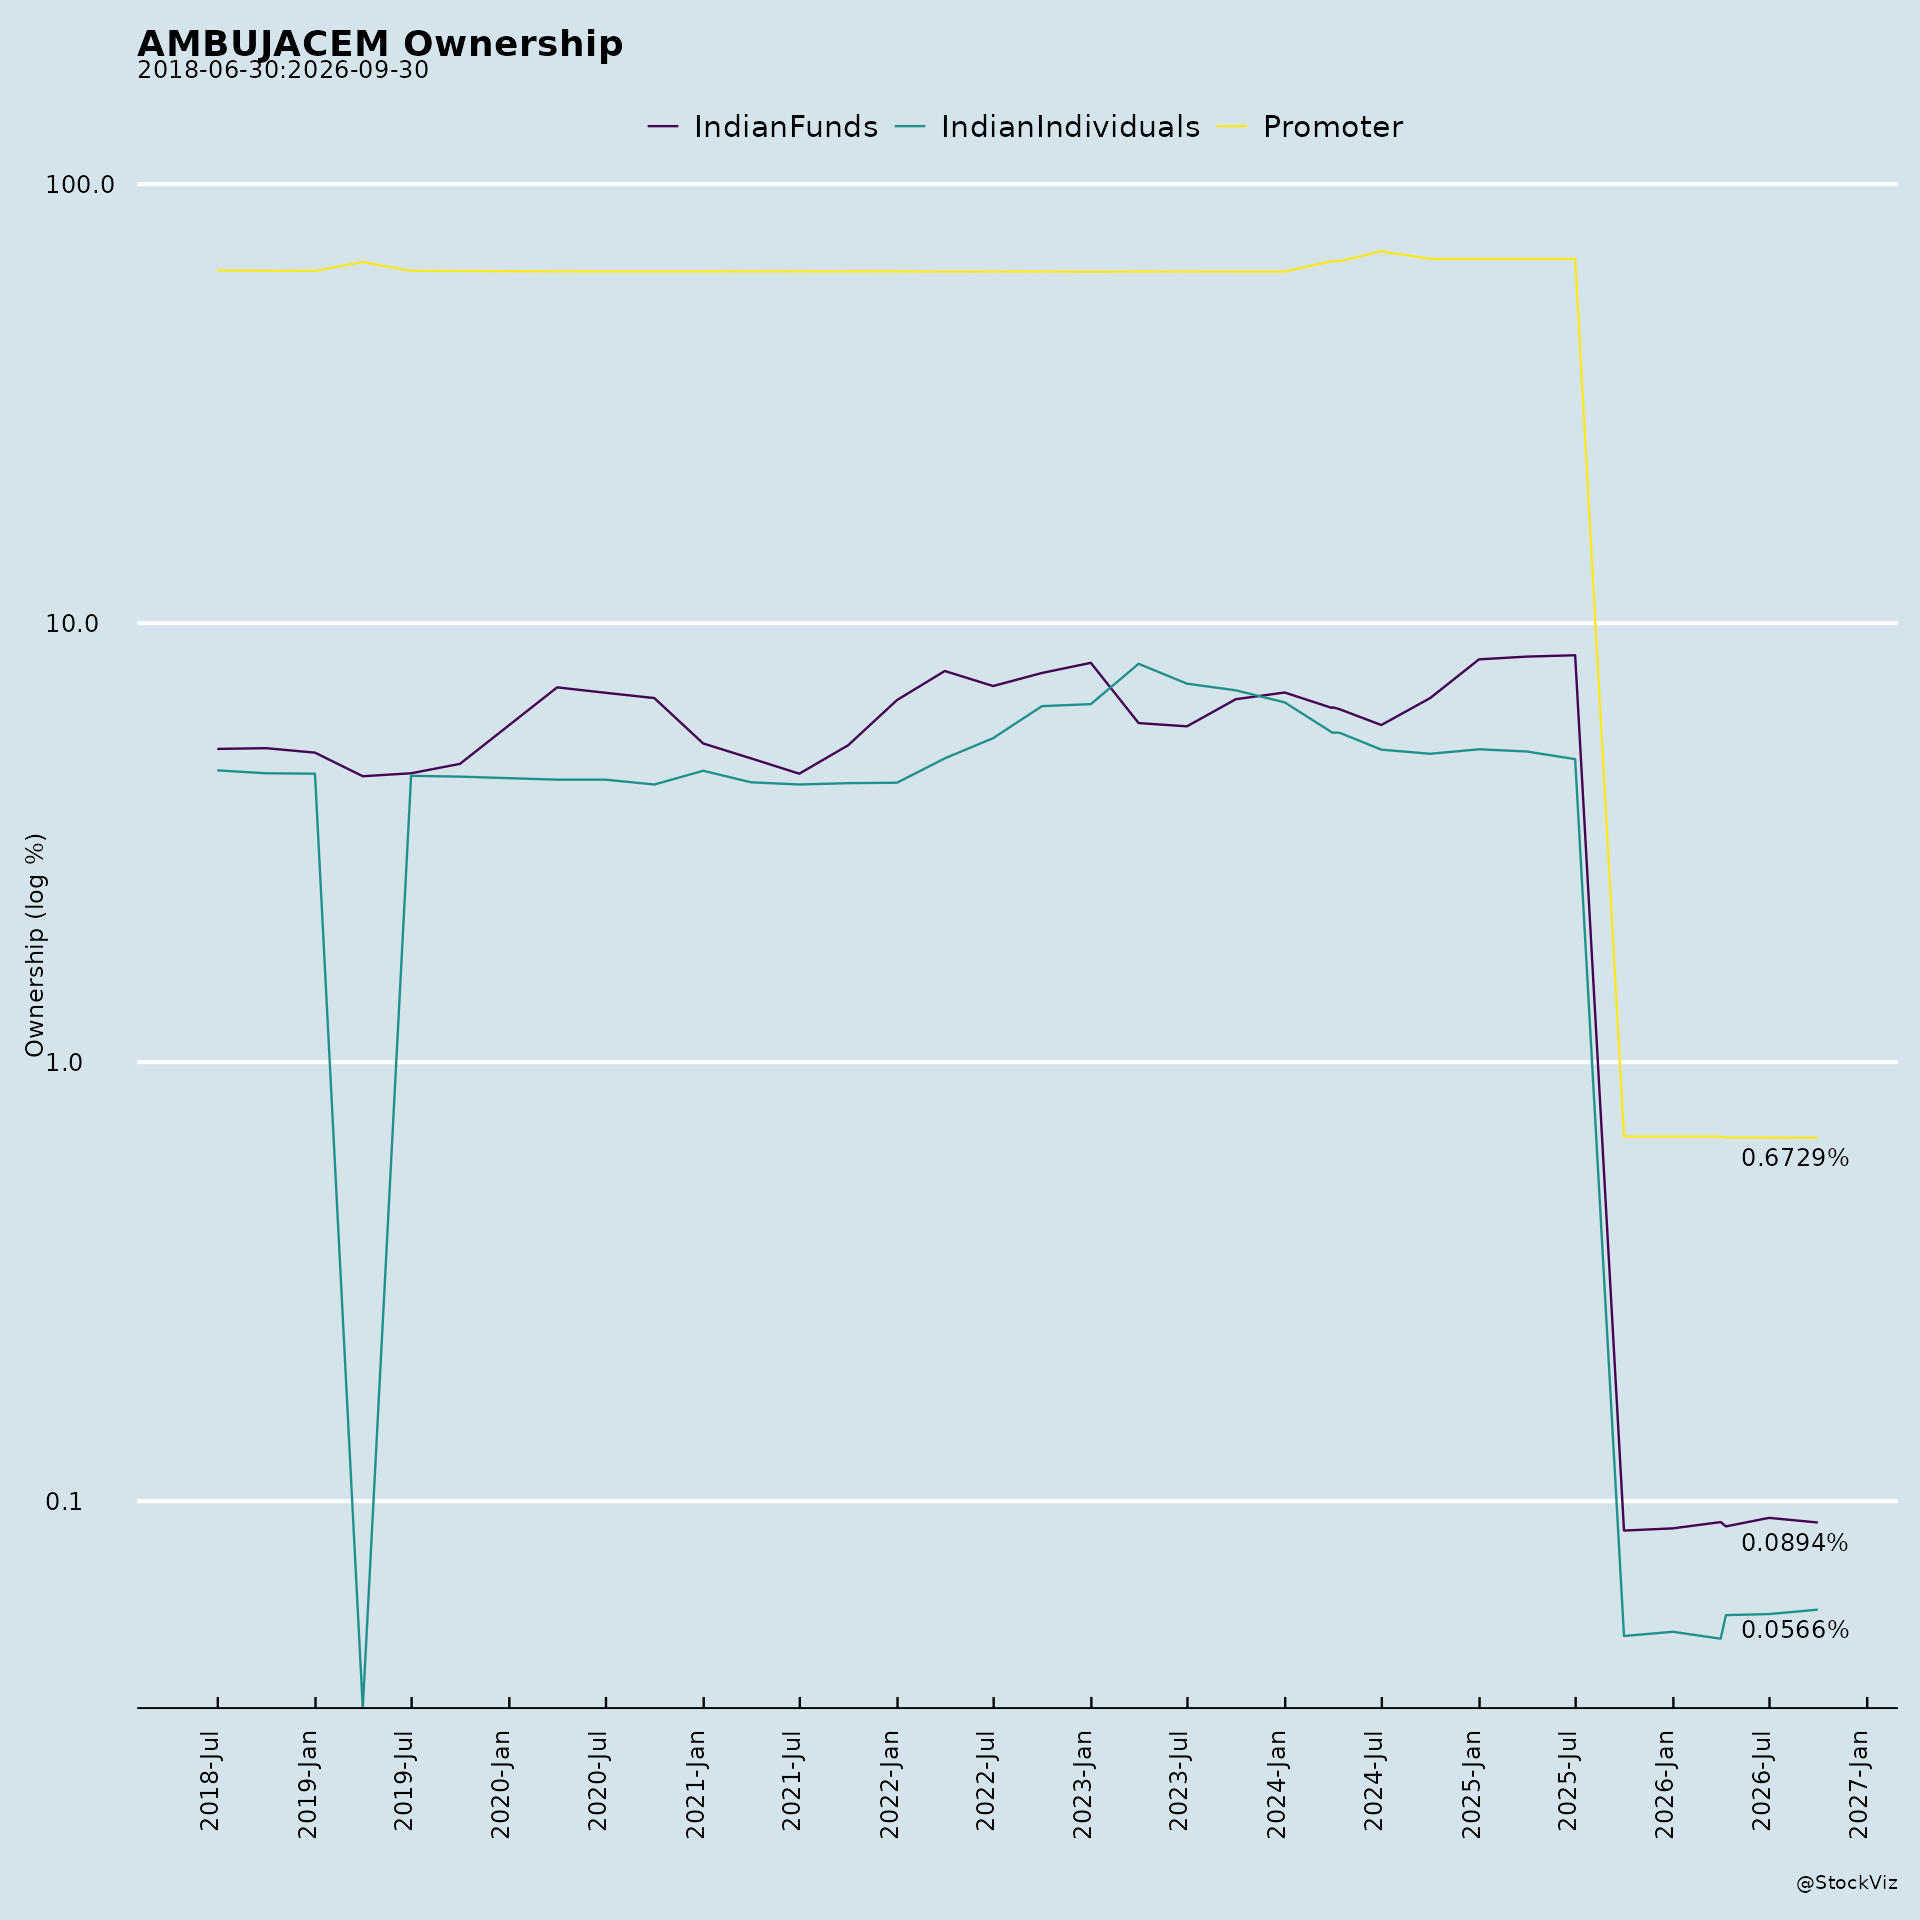
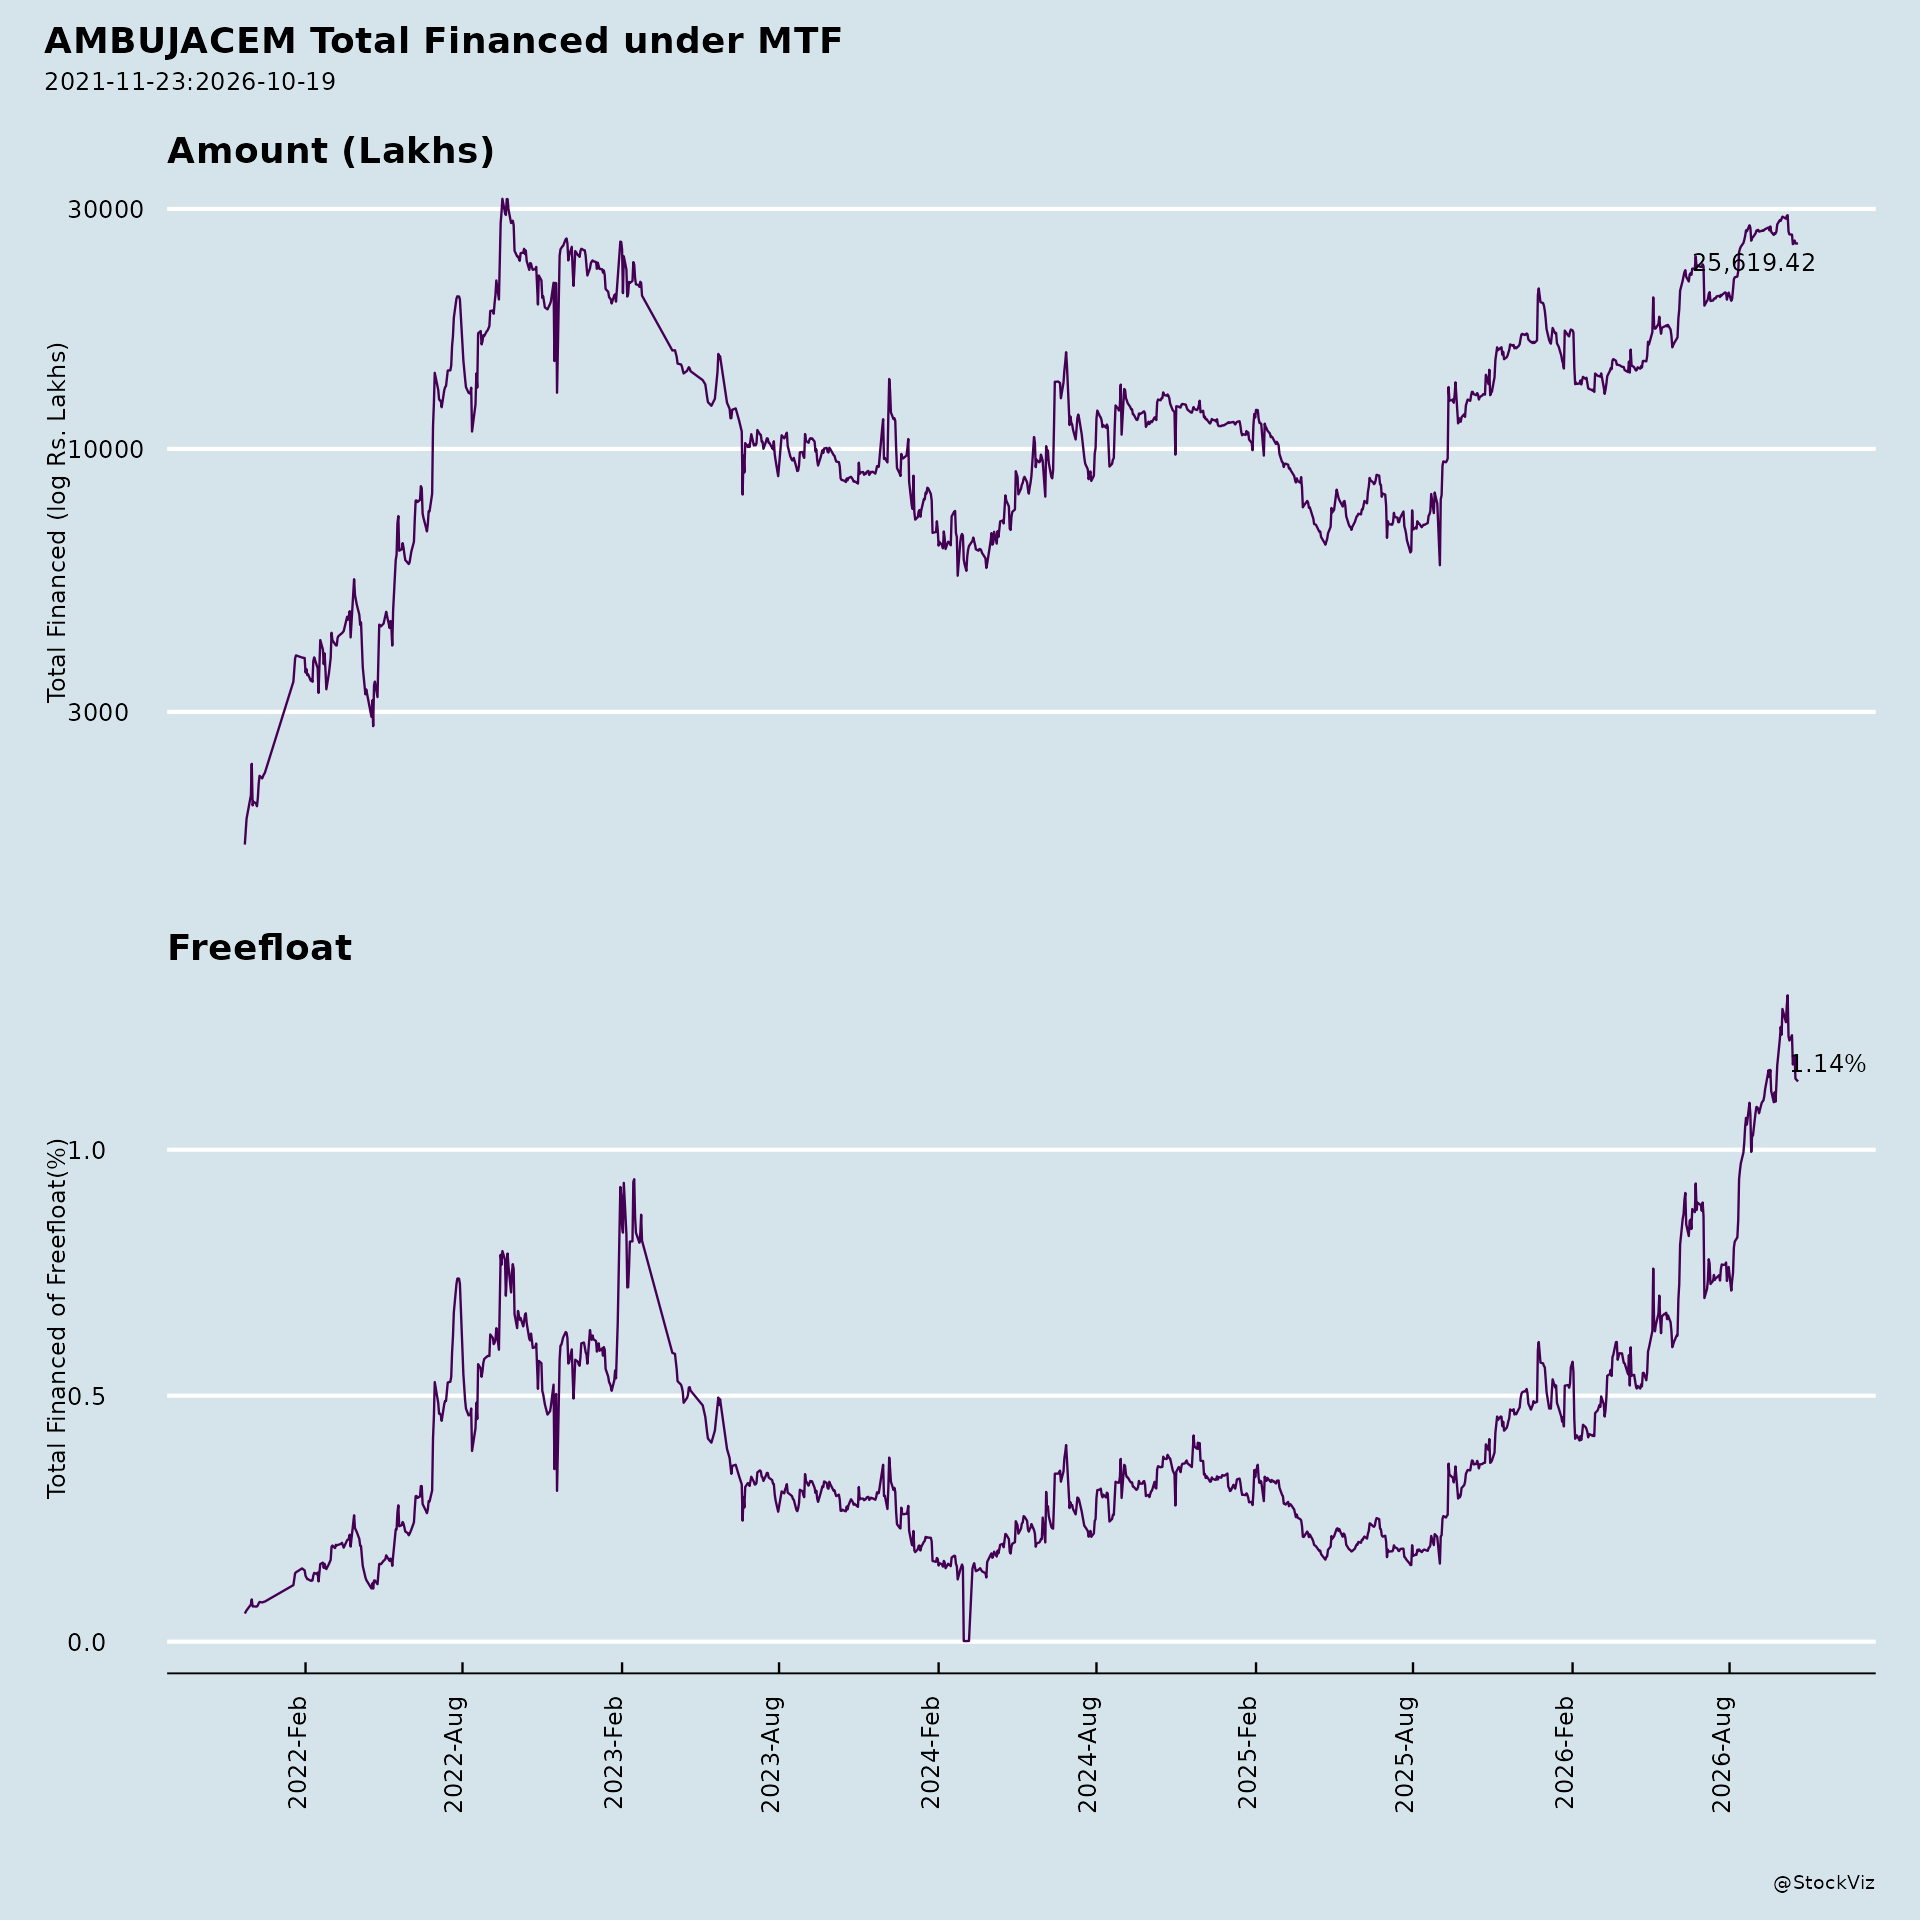
Margined
AI Summary
asof: 2026-09-14
Ambuja Cements: Recent Corporate Developments
1. Headwinds and Challenges
Input cost inflation from West Asia geopolitical tensions. The Indian cement sector witnessed cost pressures during Q1 FY’27 from higher prices of imported fuels such as petcoke and thermal coal, along with elevated freight and logistics costs resulting from geopolitical developments in West Asia. Packaging costs rose significantly by 25–30% during the quarter. Kiln fuel cost increased to Rs 1.66/’000 kCal in Q1 FY’27 from Rs 1.59/’000 kCal in Q1 FY’26, and power cost rose to Rs 6.0/kWh from Rs 5.9/kWh.
Lagging impact of peak fuel costs. Given the 60–90 day fuel inventory cycle, the impact of peak fuel cost inflation is expected to coincide with the seasonally weaker Q2, potentially impacting industry profitability in the near term.
Volume moderation and softer demand. Sales volumes moderated as the Company focused on improving trade mix, rationalizing low-margin volumes and pushing blended cement. Consolidated sales volume fell 7% YoY to 17.1 MnT in Q1 FY’27 from 18.4 MnT, and revenue declined 8% YoY to Rs 9,500 Cr. Cement demand is expected to remain soft at ~5% for FY’27, with near-term demand potentially impacted by seasonal monsoon softness, geopolitical uncertainties, and input cost volatility.
Profitability decline. Consolidated PAT (reported) fell 37% YoY to Rs 660 Cr in Q1 FY’27 from Rs 1,041 Cr, and EBITDA declined 19% YoY to Rs 1,589 Cr. EBITDA margin contracted 2.3 pp YoY to 16.7%.
Litigation and proceedings. An application under Section 9 of the Insolvency and Bankruptcy Code, 2016 has been filed by M/s Kothamangalam Aggregates Prestressed Concrete Industries against ACC Limited, alleging a default of Rs 1,90,80,600; ACC has contested maintainability and the matter is pending. The application also references ongoing adjudication and recovery proceedings, prosecution initiated, and other enforcement actions against the companies, promoters and directors as on 31.03.2026.
2. Tailwinds and Growth Prospects
Capacity expansion roadmap. Cement capacity stood at 109 MTPA as on 30 June 2026 and is expected to reach 119 MTPA by the end of FY’27. Trial production has commenced at Dahej (1.2 MTPA), Salai Banwa (2.4 MTPA), Bathinda (1.2 MTPA) and Jodhpur (2 MTPA). Kalamboli (1 MTPA) and Warisaliganj (2.4 MTPA) will have trials in Q2, and the Maratha clinker line (4 MTPA) will be commissioned in 2027.
Cost reduction trajectory. The Company achieved a sequential cost reduction of Rs 206 PMT in Q1 FY’27 despite the West Asia conflict headwinds, and states it remains on track to deliver approximately Rs 250 PMT cost reduction in FY’27 to achieve a committed cost target of Rs 4,250 PMT.
Value-led growth and premiumisation. Trade share rose 4 pp to 78% YoY; premium products sustained at 34% of trade sales; blended cement share rose 5 pp to 85% YoY; clinker factor improved 2.1 pp to 63.7% YoY. EBITDA PMT surged 27% QoQ to Rs 931 PMT, and EBITDA margin expanded 3.3 pp QoQ.
Green power and sustainability. Renewable energy capacity increased by 75 MW to 973 MW; green power share rose to 34% from 28% YoY. The Company partnered with UK-based Leilac Limited for low-carbon cement production, and its blended cement portfolio received GreenPro certification from CII and GRIHA certification.
Amalgamation of ACC Limited. The Scheme of Amalgamation of ACC Limited into Ambuja Cements, with appointed date 01.01.2026, is expected to combine operations, drive focused growth, operational efficiencies and significant business synergies, unify manufacturing and commercial functions, reduce multiple entities in the same line of business, and unlock economies of scale. Upon effectiveness, the Amalgamated Company is expected to have excess of assets over liabilities of Rs 69,072.53 Cr (based on 31.03.2026).
Macro and policy tailwinds. GDP is projected to grow 6.6%–6.8% in FY2027; the India–US trade agreement reduces policy uncertainty; INR 12 trillion infrastructure spend is expected to deliver long-term growth; RBI maintained the repo rate at 5.25% in June 2026. Demand drivers include urbanisation, housing demand, high-speed rail and expressways, urban and transit infrastructure, and mass housing and rural development.
Balance sheet strength. Debt-free balance sheet with net worth of Rs 71,954 Cr and cash & cash equivalents of Rs 844 Cr; highest AAA/A1+ credit ratings from CRISIL and CARE.
3. Key Risks
- Continued geopolitical uncertainty in West Asia affecting imported fuel, freight and logistics costs, with peak fuel cost inflation expected to coincide with the seasonally weaker Q2.
- Soft cement demand (~5% for FY’27) and monsoon-related seasonality.
- Pending insolvency application against ACC Limited alleging default of Rs 1,90,80,600, currently under consideration before the Tribunal.
- Ongoing adjudication and recovery proceedings, prosecution, and enforcement actions against the companies, promoters and directors.
- Execution risk in stabilising newly commissioned capacities and improving utilisation across the existing asset base.
- Completion of the ACC amalgamation remains subject to shareholder approval at the meetings convened for 29 September 2026 and subsequent regulatory processes.
4. Management Guidance Versus Observed Performance
Cost reduction. Management guides to a ~Rs 250 PMT cost reduction in FY’27 to reach a targeted cost of Rs 4,250 PMT by end of FY’27. Observed: a sequential cost reduction of Rs 206 PMT was achieved in Q1 FY’27 despite West Asia conflict headwinds.
Capacity. Management guides to capacity of 119 MTPA by end of FY’27, from 109 MTPA as on 30 June 2026. Observed: trial production has commenced at Dahej, Salai Banwa, Bathinda and Jodhpur; Kalamboli and Warisaliganj trials are slated for Q2 and the Maratha clinker line for 2027.
Growth positioning. Management states the Company is well positioned to outperform industry growth, leveraging brand portfolio, expanding ready-mix concrete footprint, premiumisation, operational excellence and cost leadership. Observed: trade share up 4 pp YoY to 78%, premium products at 34% of trade sales, blended cement share up 5 pp to 85%, and EBITDA PMT up 27% QoQ — though volumes and revenue declined YoY.
Amalgamation benefits. Management anticipates the unified structure and business synergies from the ACC amalgamation will generate increased shareholder value and support sustainable growth and returns over time. Observed: the NCLT Ahmedabad Bench order dated 29 July 2026 directs equity shareholder meetings on 29 September 2026 (ACC at 10:30 a.m.; Ambuja at 12:30 p.m.) to consider the Scheme; unsecured creditor meetings were dispensed with as no compromise is offered and no liabilities are reduced or extinguished.
Investor interaction. The Company will interact with investors/analysts at the 2026 Jefferies India Forum on September 17, 2026, in Gurugram, via 1x1 and Group Meetings with in-person interaction, with discussions based solely on publicly available information.
Broker Narrative
The narrative moved from a cautious Hold, dominated by sector capacity-race and Adani parent-financial concerns, to a Buy focused on execution: value-over-volume mix, cost reduction, renewable energy, and acquired-asset integration. Capacity expansion, a strong/debt-free balance sheet, and operational efficiency remained central across both reports, while the parent-financial overhang disappeared and the key risks became company-specific volume cuts, fuel/packaging inflation, and ACC/Sanghi/Penna integration.
Fears that came true
- The early fear of capacity competition materialised as subdued pricing (NSR +1% QoQ despite hikes) and a deliberate -21% YoY cut in low-margin non-trade volumes to defend value.
Optimism that failed
- The expected 14 MTPA cement capacity from the 8 MTPA clinker expansion by Q1FY26 failed to materialise on schedule; as of Q1FY27, only smaller units (Kalamboli and Warisaliganj) were still to commission in Q2FY27.
Broker Timeline
68 broker calls · 2023-06-30 to 2026-07-29
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.