ALLDIGI
Equity Metrics
October 23, 2026
Alldigi Tech Limited
Business Process Outsourcing (BPO)/ Knowledge Process Outsourcing (KPO)
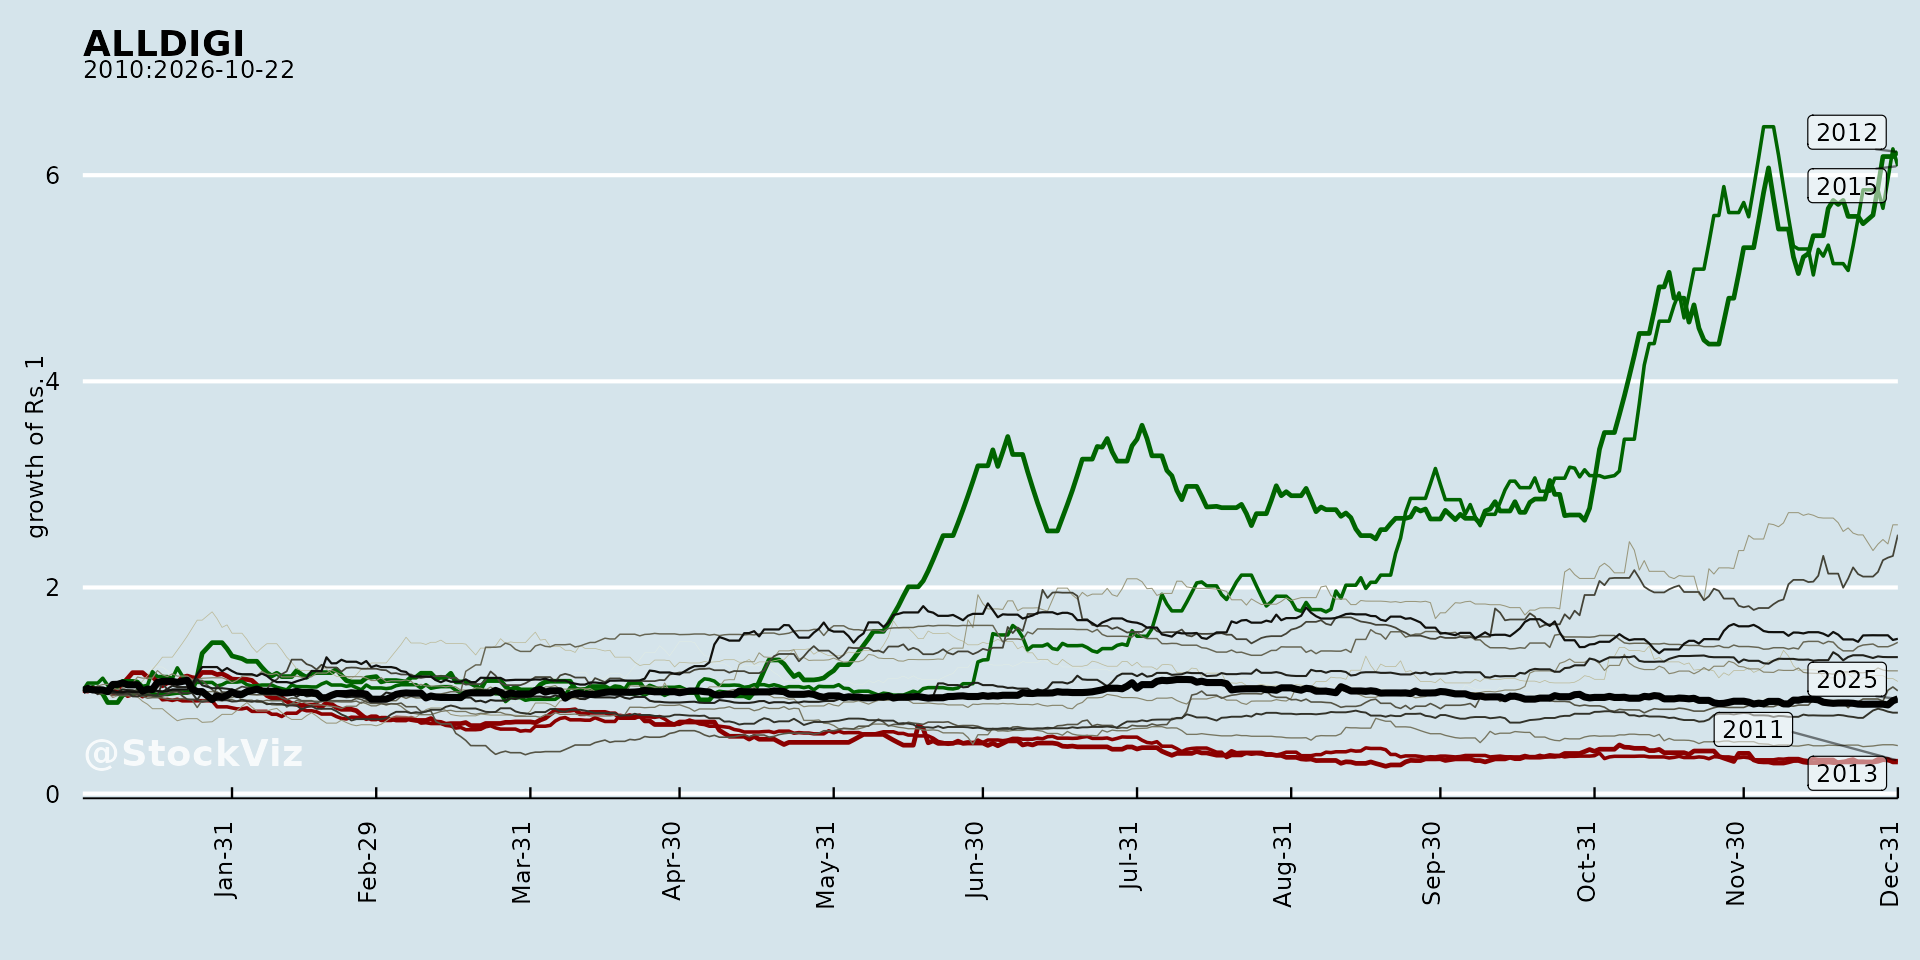
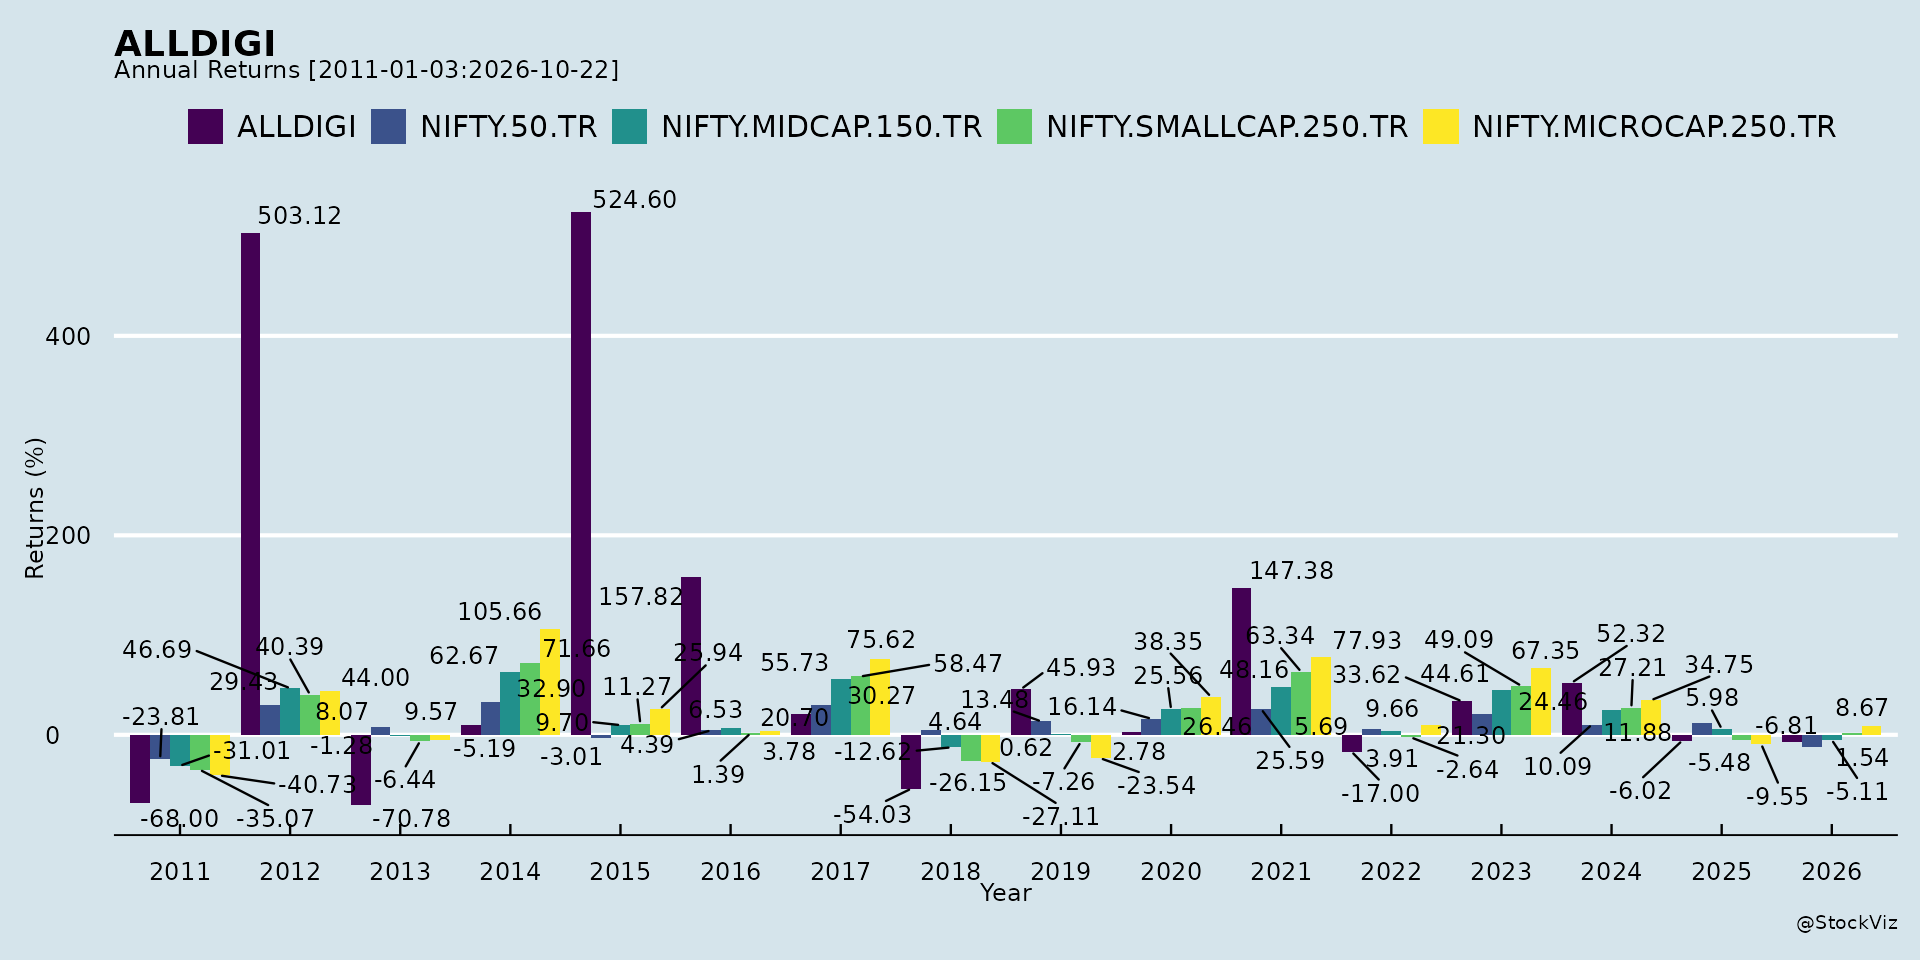
Annual Returns
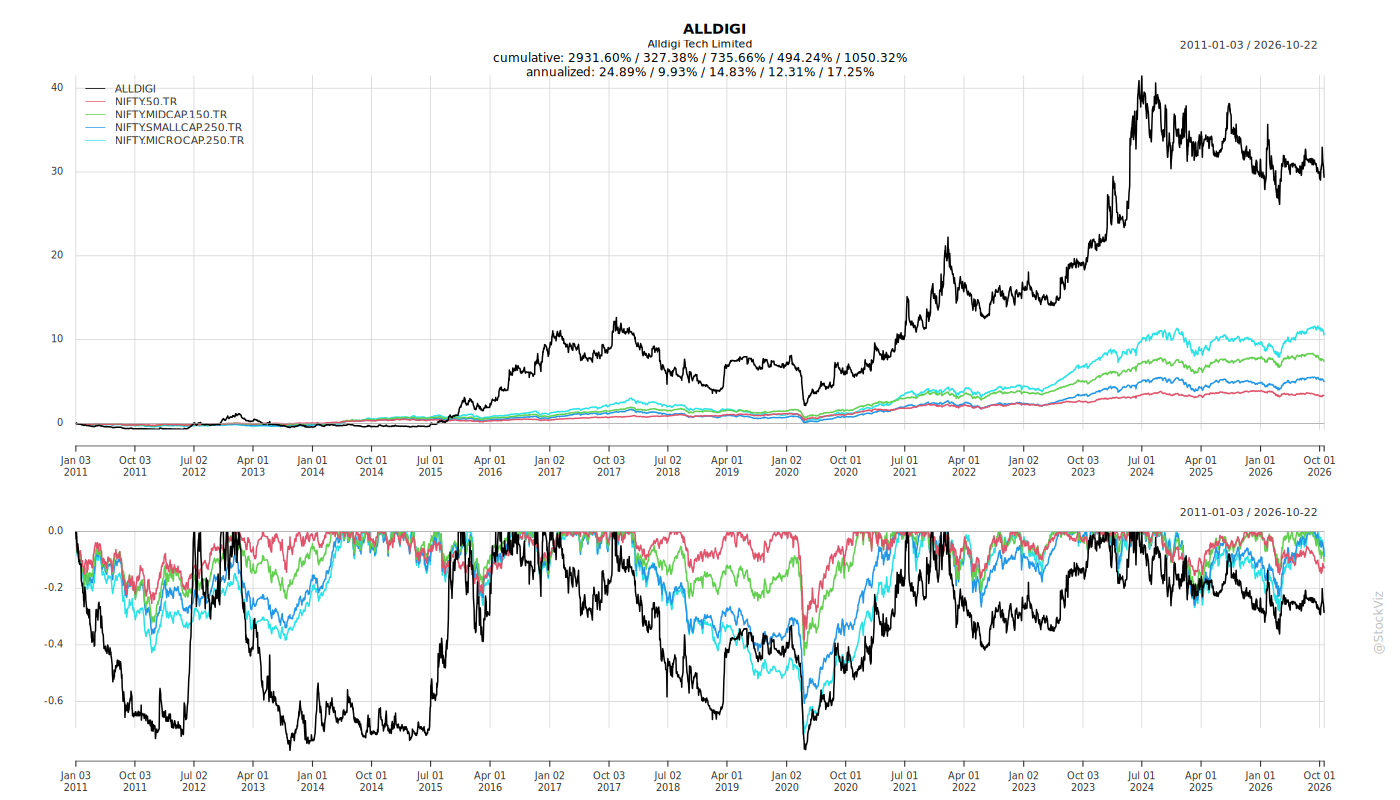
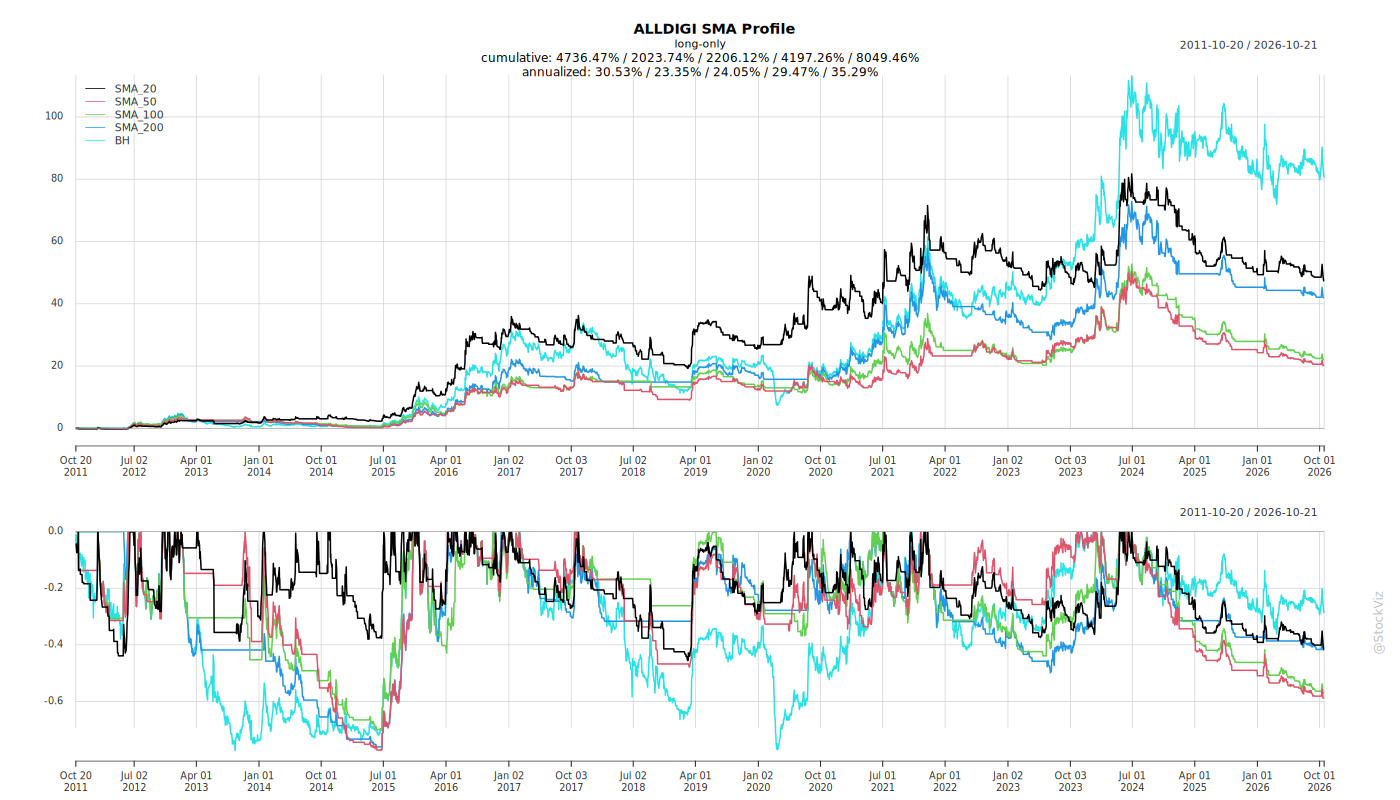
Cumulative Returns and Drawdowns
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-18
Alldigi Tech: AGM and Q1 FY27 Update
1. Headwinds and Challenges
BPM growth moderation. The CEO acknowledged that organic growth in the CXM/BPM business has not sustained at the levels of the previous two years, which he attributed to the large orders received in that period. The CXM business has grown at roughly a 15% CAGR over four years, a figure that includes the deliberate retirement of low-margin accounts.
Margin pressure in BPM. The CEO stated that margin pressure in the CXM business is expected to persist “for some time,” requiring constant monitoring and action. Q1 FY27 segment data shows BPM margin at 11.9%, down from 13.8% a year earlier and 13.6% in the preceding quarter.
Domestic softness. Domestic BPM revenue declined 14.1% year-on-year in Q1 FY27, with international BPM growth of 6.5% offsetting that weakness.
AI-driven pricing pressure. The CEO noted that AI interventions are “constantly creating pressure” in the BPM business, addressed through internal AI adoption and proactive client-level impact assessment.
Payroll growth constraints. The CEO observed that the growth rate seen two to three years ago in organic employee numbers with customers is no longer visible, as customers implement technology and AI. Standalone-country payroll markets typically grow in the single digits.
Headcount reduction. Headcount has declined for three to four quarters, to 4,980 as of end-Q1 FY27. The CEO attributed this to both the retirement of low-margin accounts and AI interventions, and said the number is expected to continue declining for both reasons.
PAT decline in FY26. FY26 PAT of ₹82.2 crores was lower by 1.3% year-on-year, primarily because FY25 had benefited from an exceptional gain of around ₹17 crores on the Labour Law Compliance divestment.
Cash balance reduction. Cash and liquid funds stood at ₹147.7 crores, down ₹17.4 crores year-on-year.
Shareholder concerns raised. Speakers questioned whether 100% of profits being declared as dividends signals an absence of significant acquisition opportunities; asked for stage gates on Buzzily/SmartHR investment rather than open-ended commitment; asked whether the board had formally evaluated separating the T&D and BPM businesses or inducting a strategic/financial partner at the platform level; and asked about US sales and marketing investment consumption and evidence of Digitide synergies.
2. Tailwinds and Growth Prospects
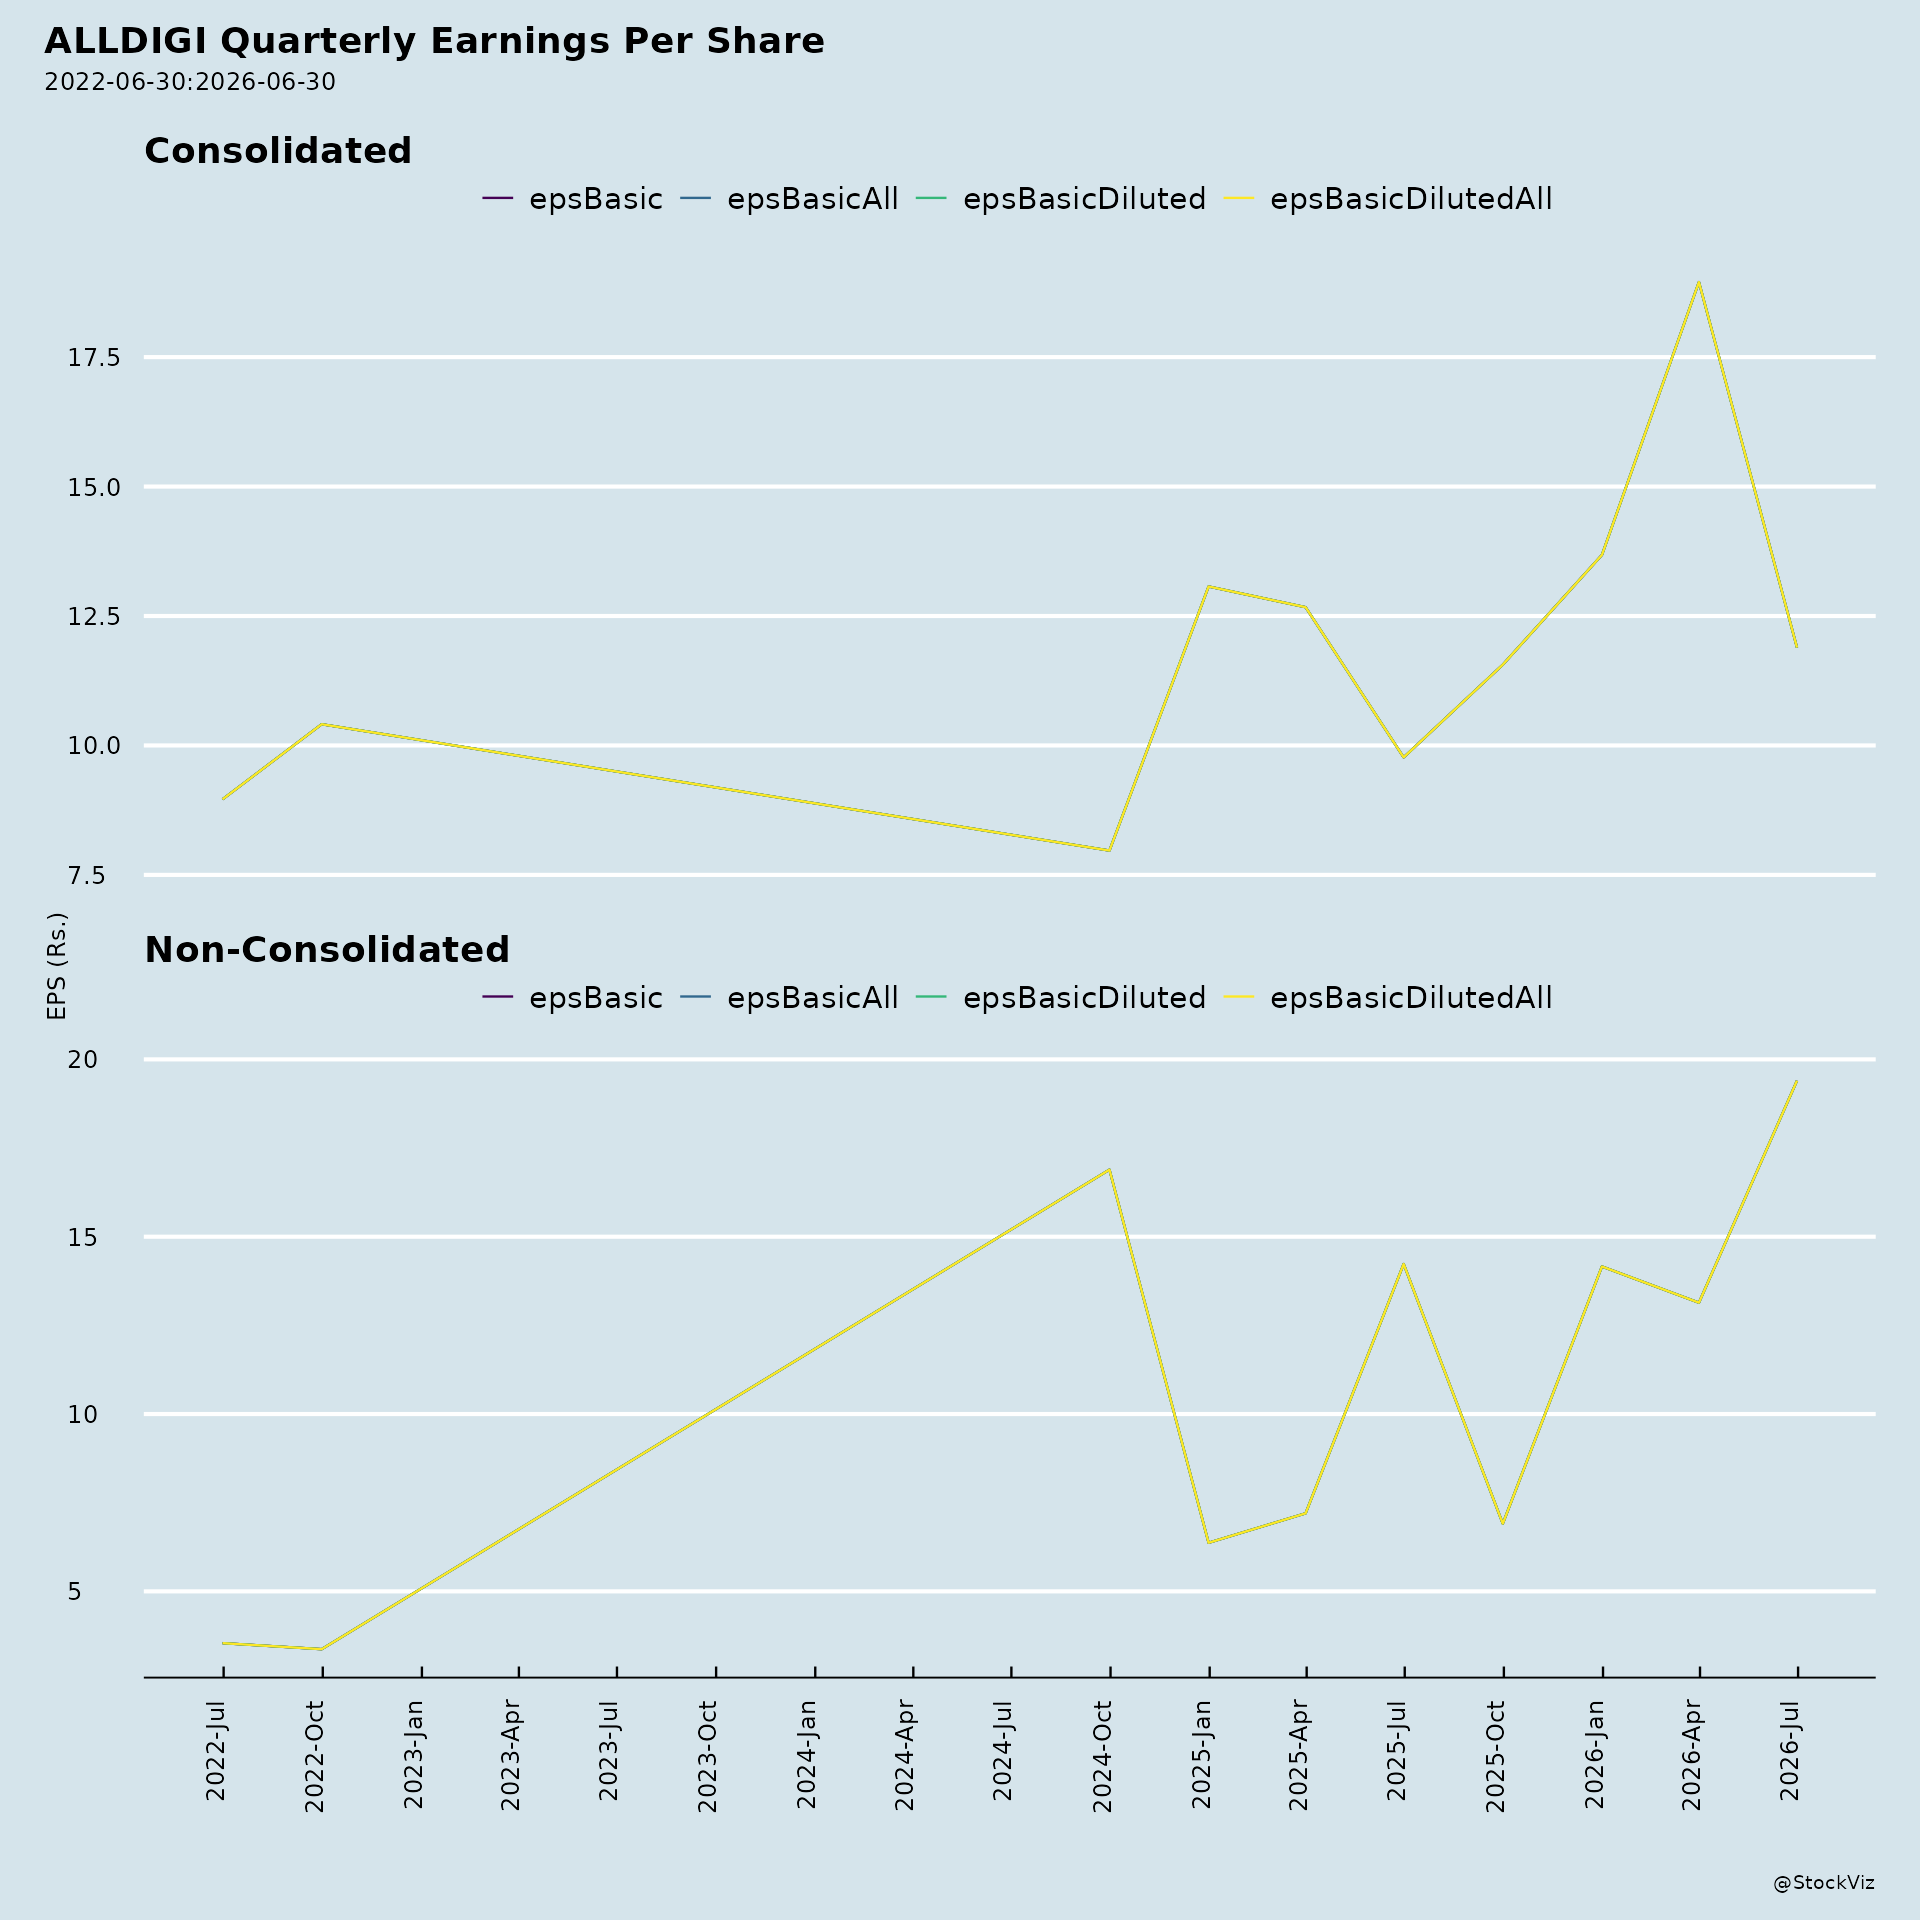
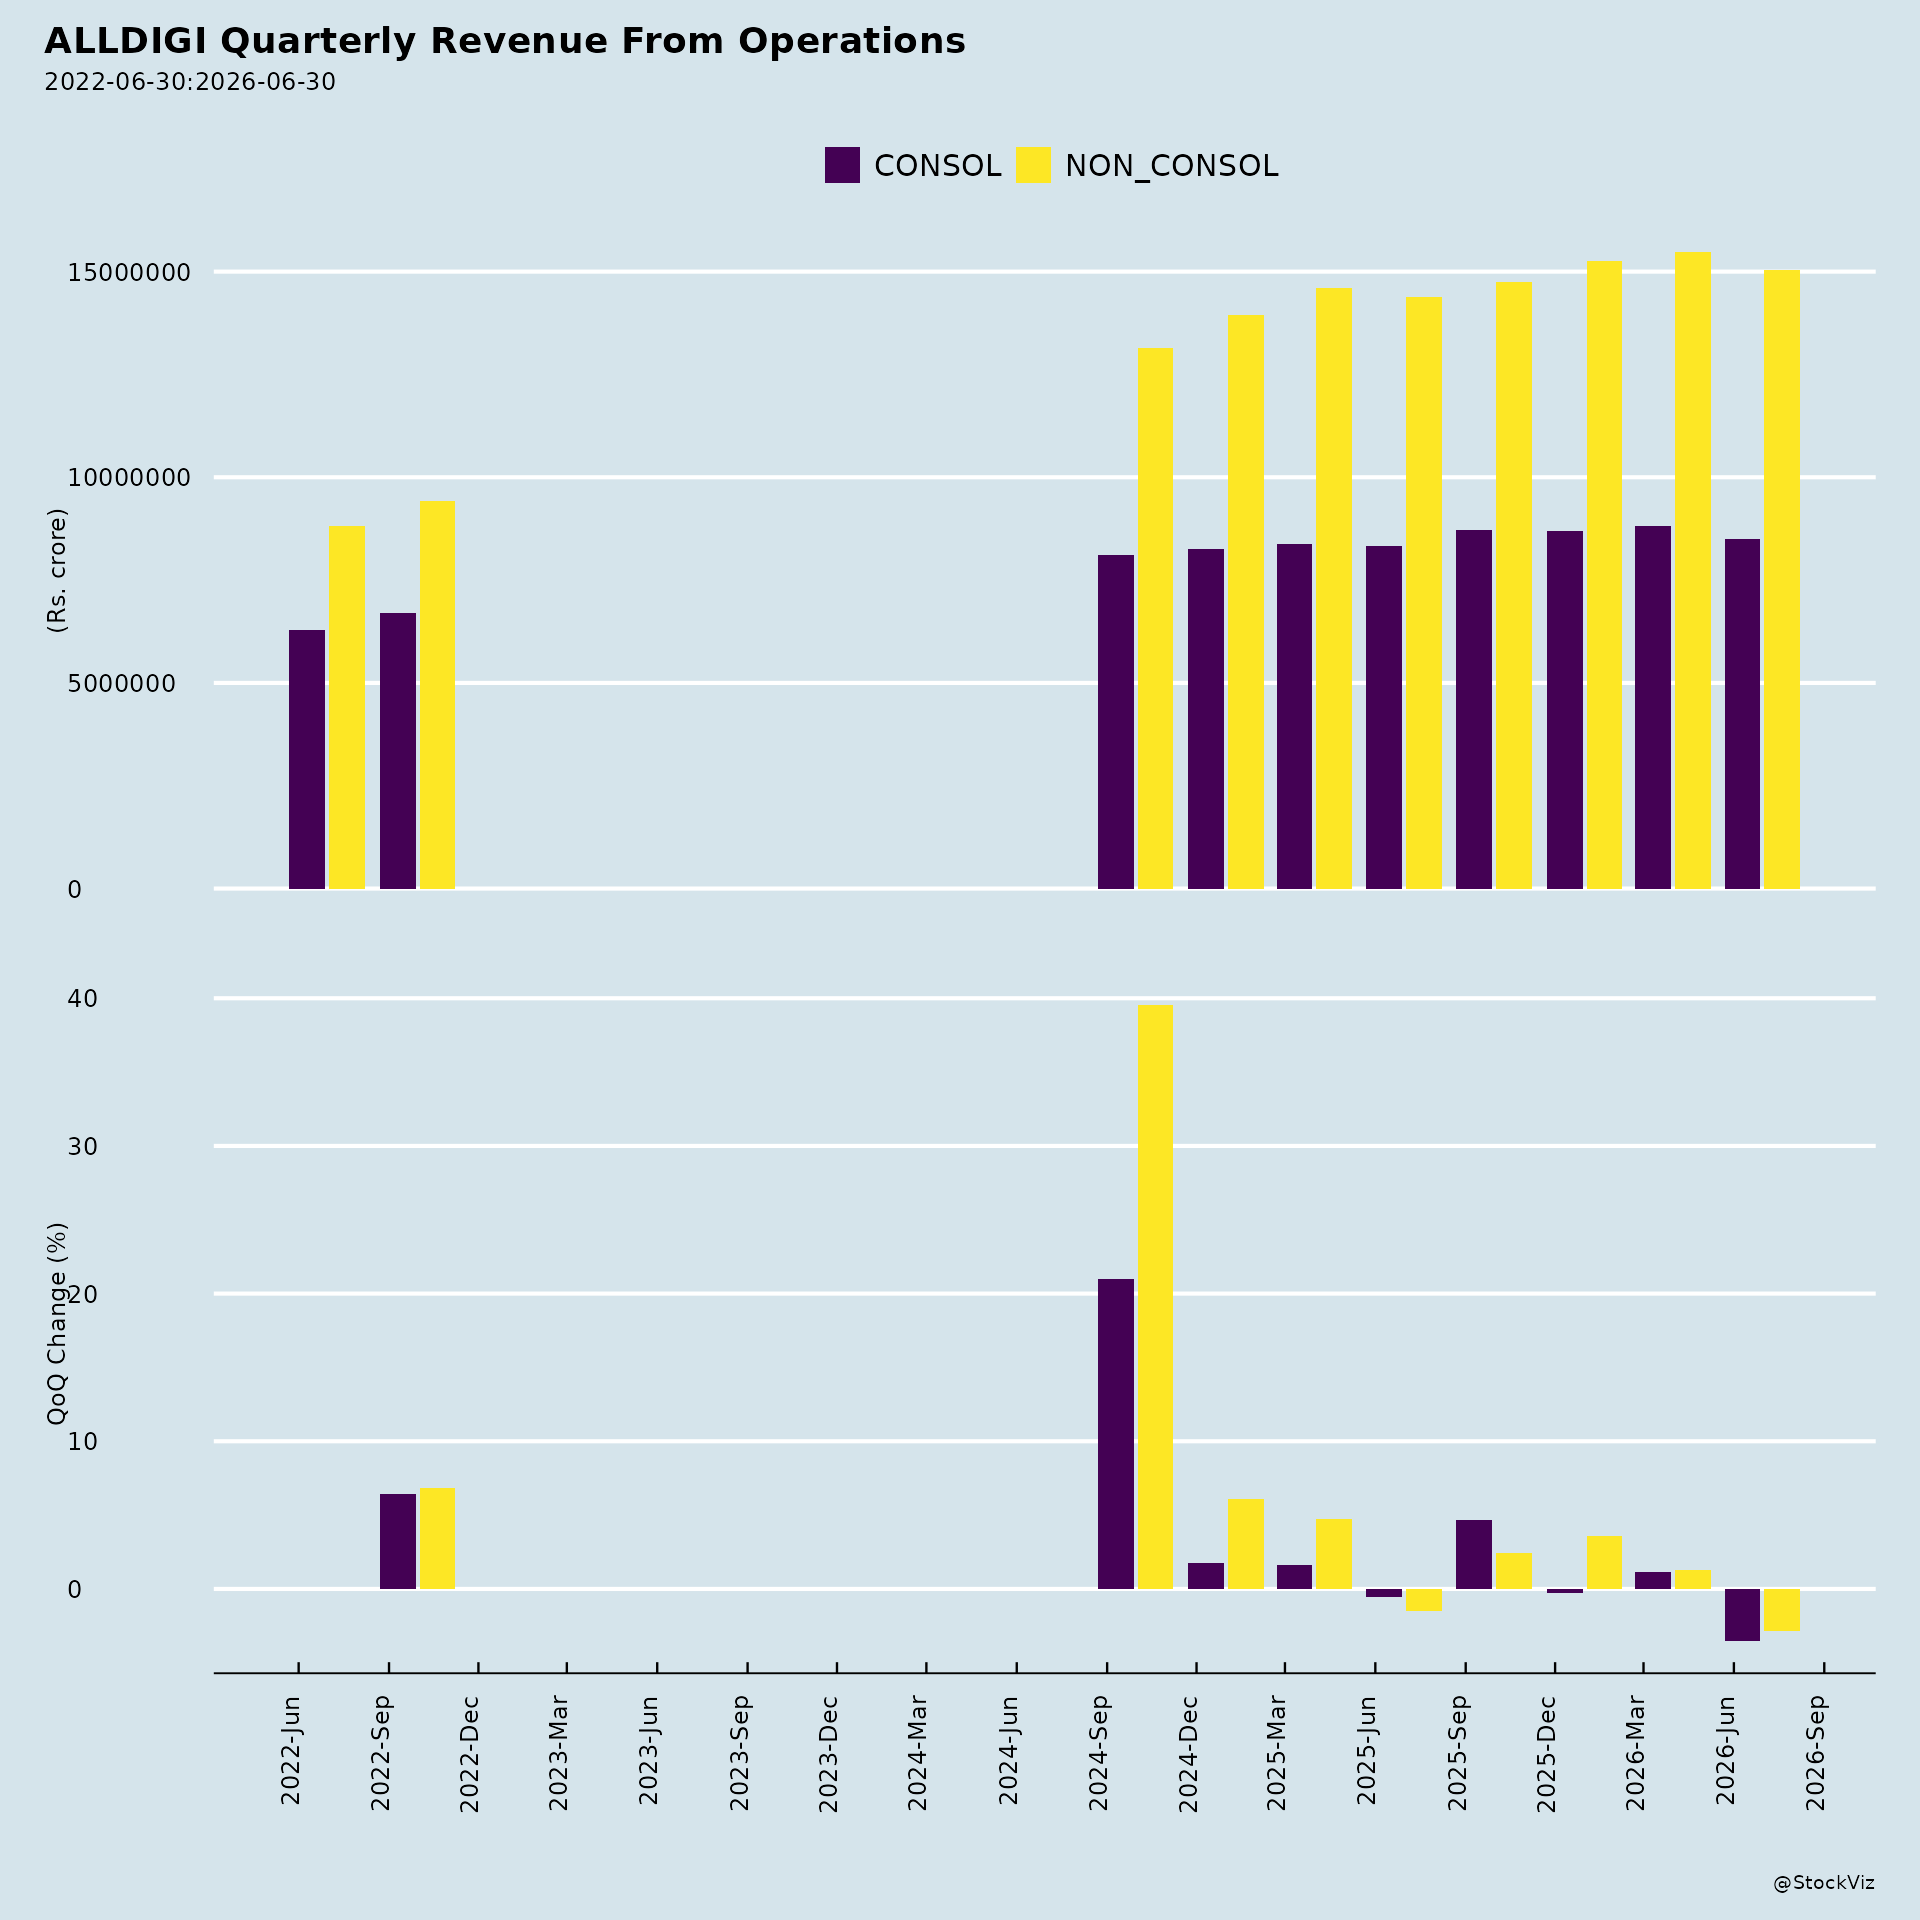
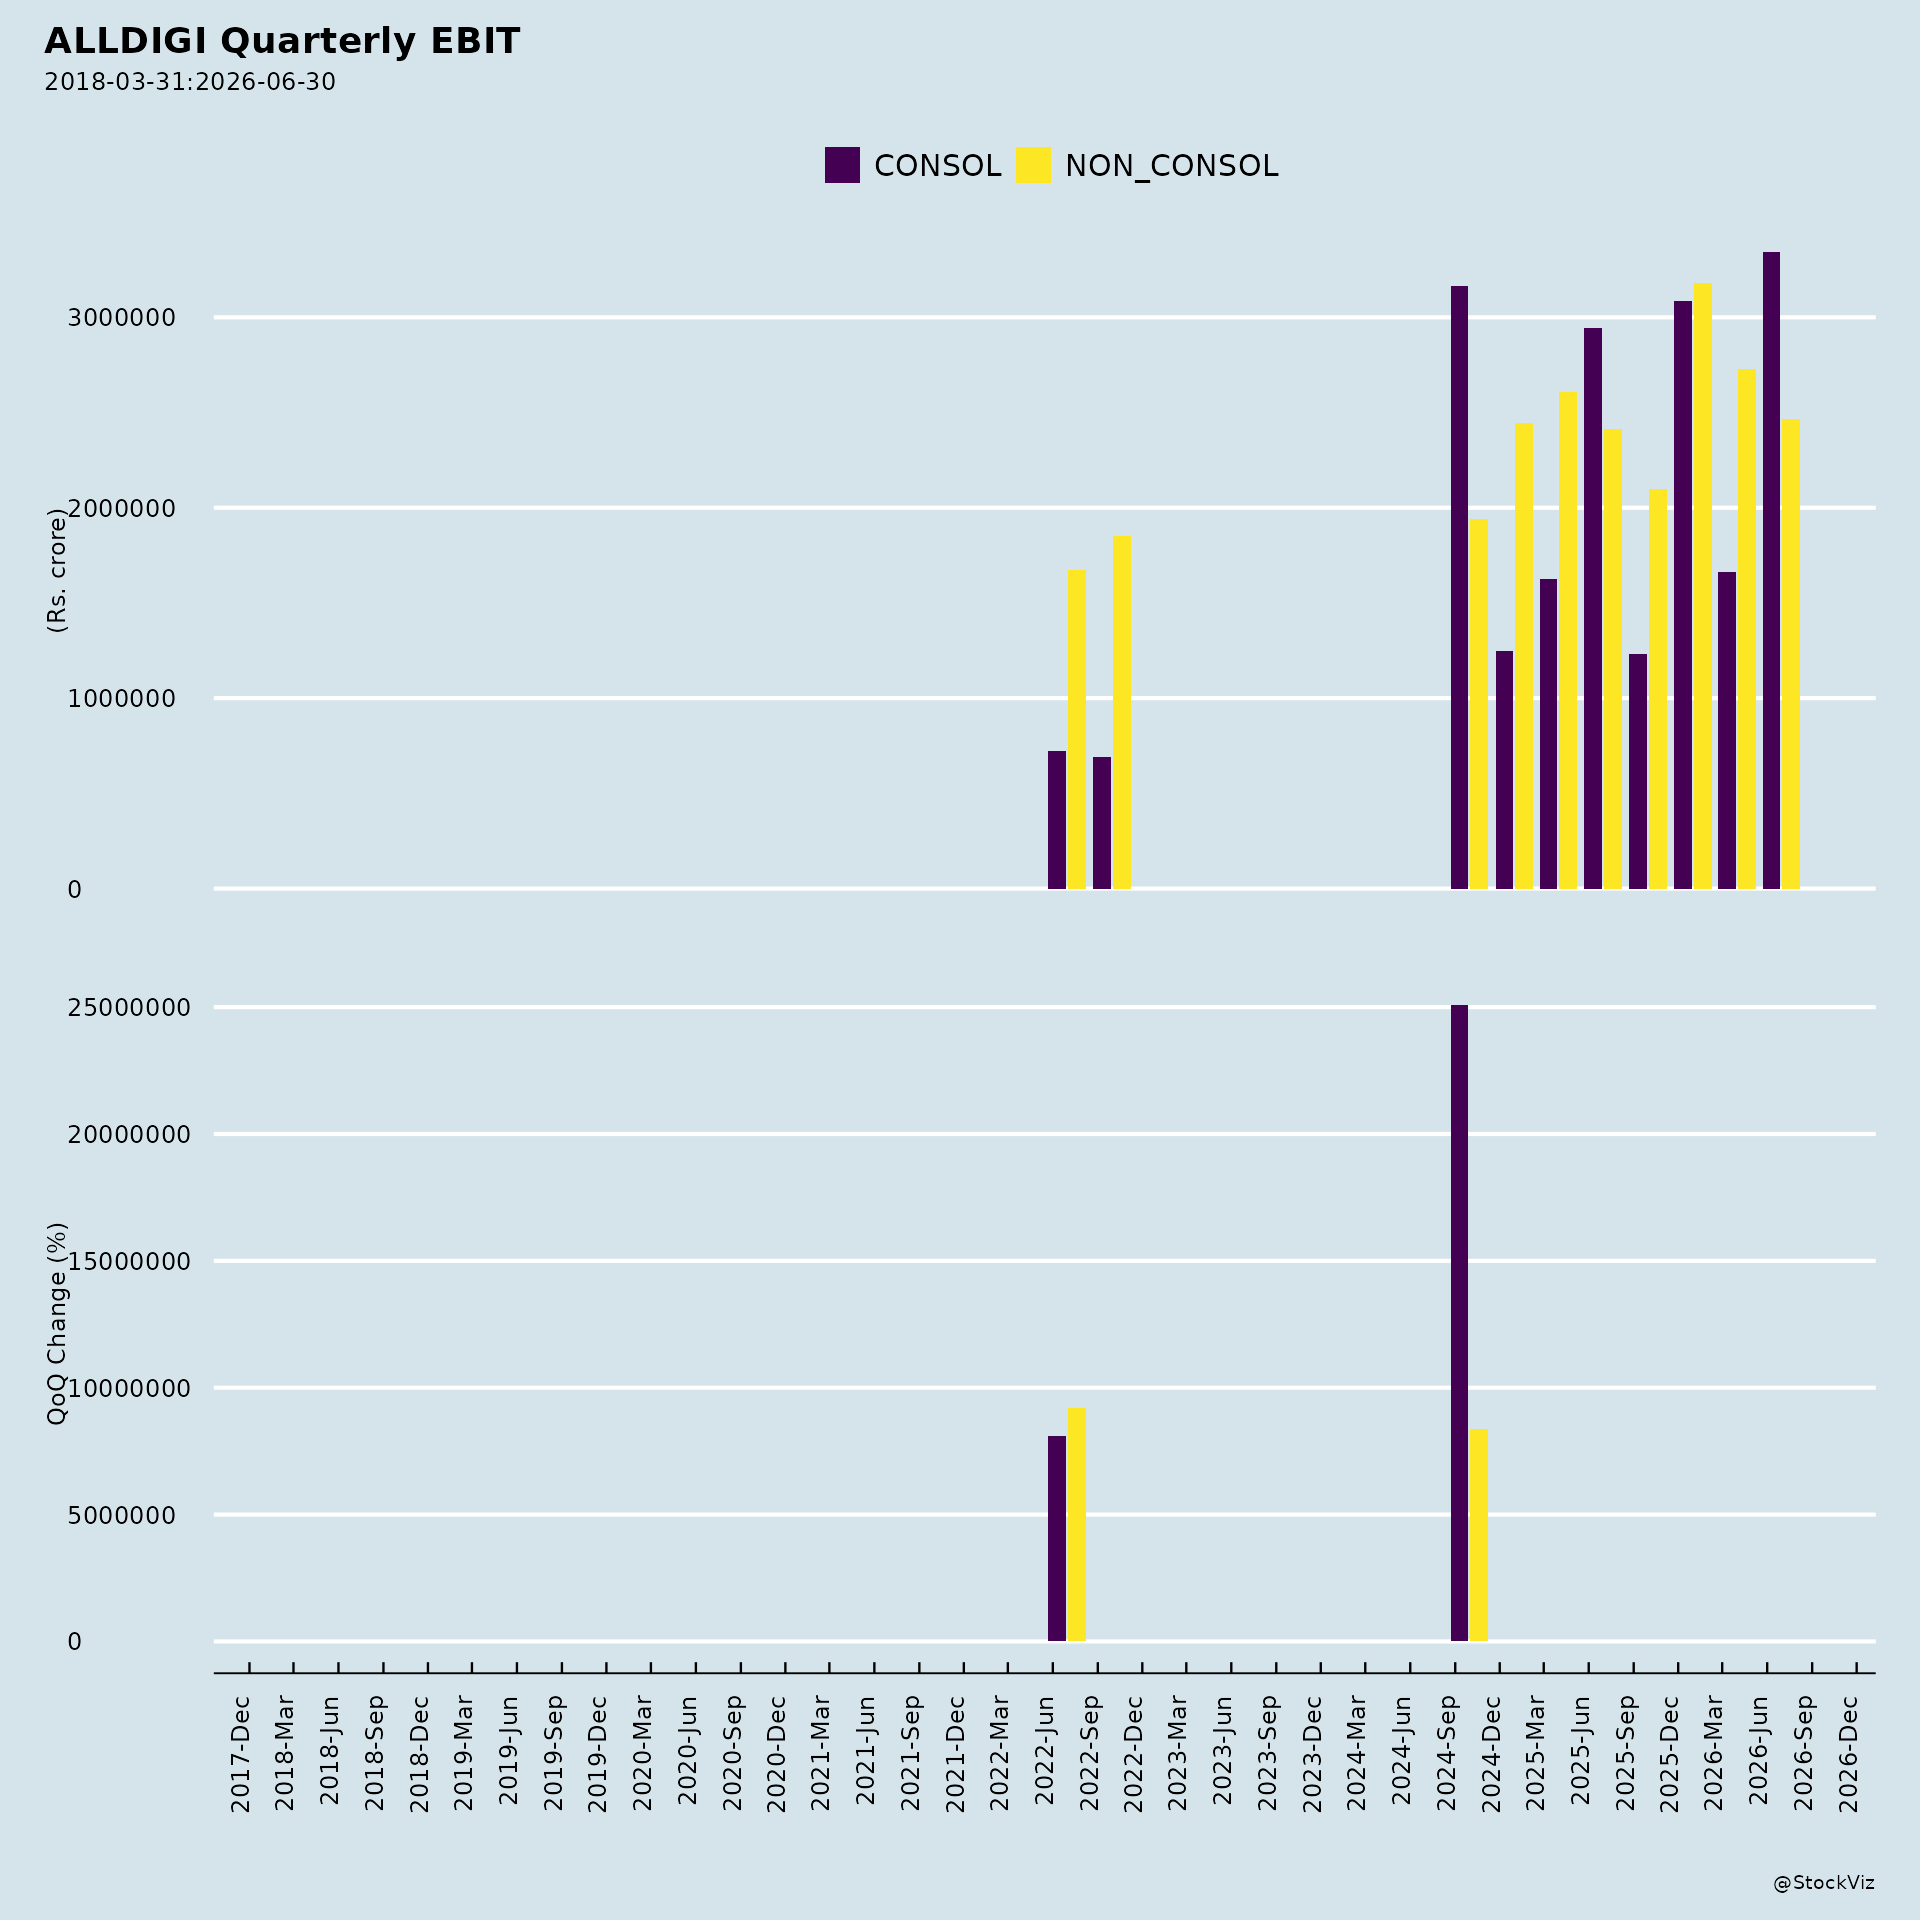
FY26 financial performance. Revenue from operations was ₹598.7 crores, up 9.6% year-on-year, supported by growth across both verticals. EBITDA rose 25.0% to ₹162.0 crores, with margin expanding 333 basis points to 27.1%. Operating cash flow was ₹144.1 crores, up 18.8%, with conversion at 88.9%. Collections were ₹626.1 crores, up 9.0%, and DSO improved by 8 days to 73 days.
Q1 FY27 momentum. Revenue rose 4.4% year-on-year to ₹150.3 crores; EBITDA rose 13.1% to ₹41.4 crores; EBITDA margin expanded 210 basis points to 27.5%; PAT rose 21.7% to ₹18.1 crores; operating cash flow rose 65.1% to ₹33.1 crores. Tech & Digital revenue rose 11.9% year-on-year. Over 50 lakh employee records were processed in a quarter for the first time, up 10.5% year-on-year.
Product roadmap. Aeonox, the next-generation SaaS platform, is progressing with eight modules including AI-powered analytics and performance management, with launch expected in October and individual modules available before year-end. Buzzily 2.0, a unified cloud-based HRMS, ESS and Payroll platform consolidating two applications, is live. Meridian, an analytics module, is expected to launch in September. Partnerships with TaxSpanner and Workday have been strengthened, with additional revenue-sharing partnerships under discussion.
Vertical strategy. Healthcare RCM was added in FY26 and is gaining momentum. International Collections continues to perform strongly. Insurance BPO has gone live with a new US insurance client in FY27, expected to grow significantly over the next 12 months. The FY27 strategy consolidates International Collections, Insurance, Healthcare and Healthcare RCM, with dedicated sales teams per vertical.
Order pipeline. The CEO cited a pipe order booking of about ₹70–75 crores, of which about ₹27 crores is from the EXM business (predominantly rest of world and India) and about ₹50 crores is international revenue.
Geographic expansion. Growth in rest-of-world markets (Philippines, Vietnam, Malaysia, Indonesia, Singapore) is expected to continue. The US is identified as an entry opportunity for T&D, where current US operations are nil, potentially through M&A, partnership or organic product growth. India market share is currently about 2–2.5%, with expectations to grow via the SMB segment.
Customer metrics. Healthy NPS scores, high client retention and renewals, and continued expansion with existing clients were cited.
Capital returns. A dividend of ₹60 per equity share was paid for FY26. An interim dividend of ₹30 per equity share was announced based on Q1 FY27 results, with payment on or before August 20, 2026 to shareholders on record as of July 31, 2026.
Workplace investment. Chennai operations relocated from the long-standing Velachery premises to a Grade-A facility at DLF Cyber City, Manapakkam, effective July 25, 2026, offering scalability for headcount growth.
Productivity. In Tech & Digital, employee records per FTE improved 14.3% year-on-year and 6.9% quarter-on-quarter. Attrition reduced, with continued focus on diversity, equity and inclusion.
CSR. Initiatives reached over 9,000 children across 42 schools and 28 Anganwadis. Alldigi supported CMC Vellore Hospital in building a 350-bed Pediatric Super Specialty Centre, to be inaugurated in a few months.
3. Key Risks
- Continued margin pressure in the CXM/BPM business, which the CEO expects to persist for some time.
- AI-driven disruption to BPM pricing and delivery economics, requiring ongoing client-level impact assessment and alternative new business from existing clients.
- Continued headcount reduction from both low-margin account retirement and AI interventions.
- Payroll business growth dependent on new customer acquisition, given muted organic employee growth at existing customers.
- Execution risk on the product roadmap, including Aeonox, Meridian and Buzzily 2.0 launches and the planned US market entry for T&D.
- M&A execution risk: the CEO said the company is constantly evaluating opportunities and will execute when a right strategic fit is found, with no specific demerger or strategic partner plans currently.
- Regulatory and legislative impacts, including the Labour Codes notified on November 21, 2025, which increased gratuity liability and compensated absences provisions by ₹319 lakhs in the quarter ended March 31, 2026 and ₹781 lakhs for the year ended March 31, 2026, presented as an exceptional item.
- Tax-related items: foreign tax credit charged off against dividend income from the Philippines subsidiary (₹277 lakhs in Q1 FY27, ₹244 lakhs in Q1 FY26, ₹381 lakhs in FY26), and reversals of provisions following expiry of scrutiny assessment timelines (₹264 lakhs reversed in Q1 FY27; ₹1,031 lakhs reversed in the quarter and year ended March 31, 2026).
4. Management Guidance Versus Observed Performance
Revenue growth guidance. Management had guided for roughly 20% revenue growth with 1.5% annual margin improvement, to be funded by a higher international revenue mix. Observed: FY26 revenue grew 9.6% year-on-year; Q1 FY27 revenue grew 4.4% year-on-year. The CEO cited a pipe order booking of ₹70–75 crores with about ₹50 crores from international revenue, and stated the company continues to see a larger international revenue mix.
Margin trajectory. Observed: FY26 EBITDA margin expanded 333 basis points to 27.1%; Q1 FY27 EBITDA margin expanded 210 basis points year-on-year to 27.5%. However, BPM segment margin declined to 11.9% in Q1 FY27 from 13.8% a year earlier, and T&D segment margin declined to 42.9% from 43.5%.
Tech & Digital growth. The CEO said the segment is seeing acceleration, with strategy focused on product play, market segmentation and geographic concentration. Observed: T&D revenue grew 11.9% year-on-year in Q1 FY27, with international T&D revenue up 40.0% year-on-year while domestic T&D grew 0.6%.
Payroll growth. Asked whether ~20% growth is reasonable for the payroll business, the CEO noted 15% CAGR over four years is a good growth rate relative to single-digit standalone-country market norms, and pointed to ₹27 crores of booked orders and a long sales pipeline.
Buzzily/SmartHR scale. The CEO disclosed approximately 100 clients on Buzzily and about 300 clients on SmartHR, with expectations that Buzzily 2.0 will increase this number. No revenue, cumulative investment, budget or stage-gate milestones were disclosed in response to the shareholder request for these.
Dividend policy. The CFO stated the company continues to be guided by its distribution policy, which aims to optimize shareholder returns through distribution, share buyback or long-term capital appreciation, balancing returns against retention for growth. He stated the company currently has sufficient resources for business-as-usual and growth requirements, and will reassess based on business circumstances and new initiative investment needs.
Demerger/strategic partner. The CEO stated there are no specific plans to demerge the T&D and BPM businesses, but that this is something the company can deliberate on. On a strategic partner for the platform business, he said it would be taken under advisement and opportunities explored.
Near-shore centers. The CEO stated the company is constantly evaluating near-shore centers, and could move either organically or through M&A once clear client demand emerges.
Five-year vision. The CEO described AI as a key factor for the next three to five years, with T&D strategy built on product play, US market entry and expansion in India and Southeast Asia, and BPM strategy focused on the three targeted industries with a possible product-wrapper play in one to two years.
AGM outcomes. All four resolutions were passed with requisite majority: adoption of standalone financial statements (99.99997% assent), adoption of consolidated financial statements (99.99988% assent), appointment of Ms. Ruchi Ahluwalia as director liable to retire by rotation (99.99962% assent), and appointment of Mr. Sameer Ahluwalia as director (99.99971% assent). Total votes polled represented 75.8124% of outstanding shares. The statutory auditor’s report contained no qualifications, reservations or adverse remarks.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.