ALIVUS
Equity Metrics
September 24, 2026
Alivus Life Sciences Limited
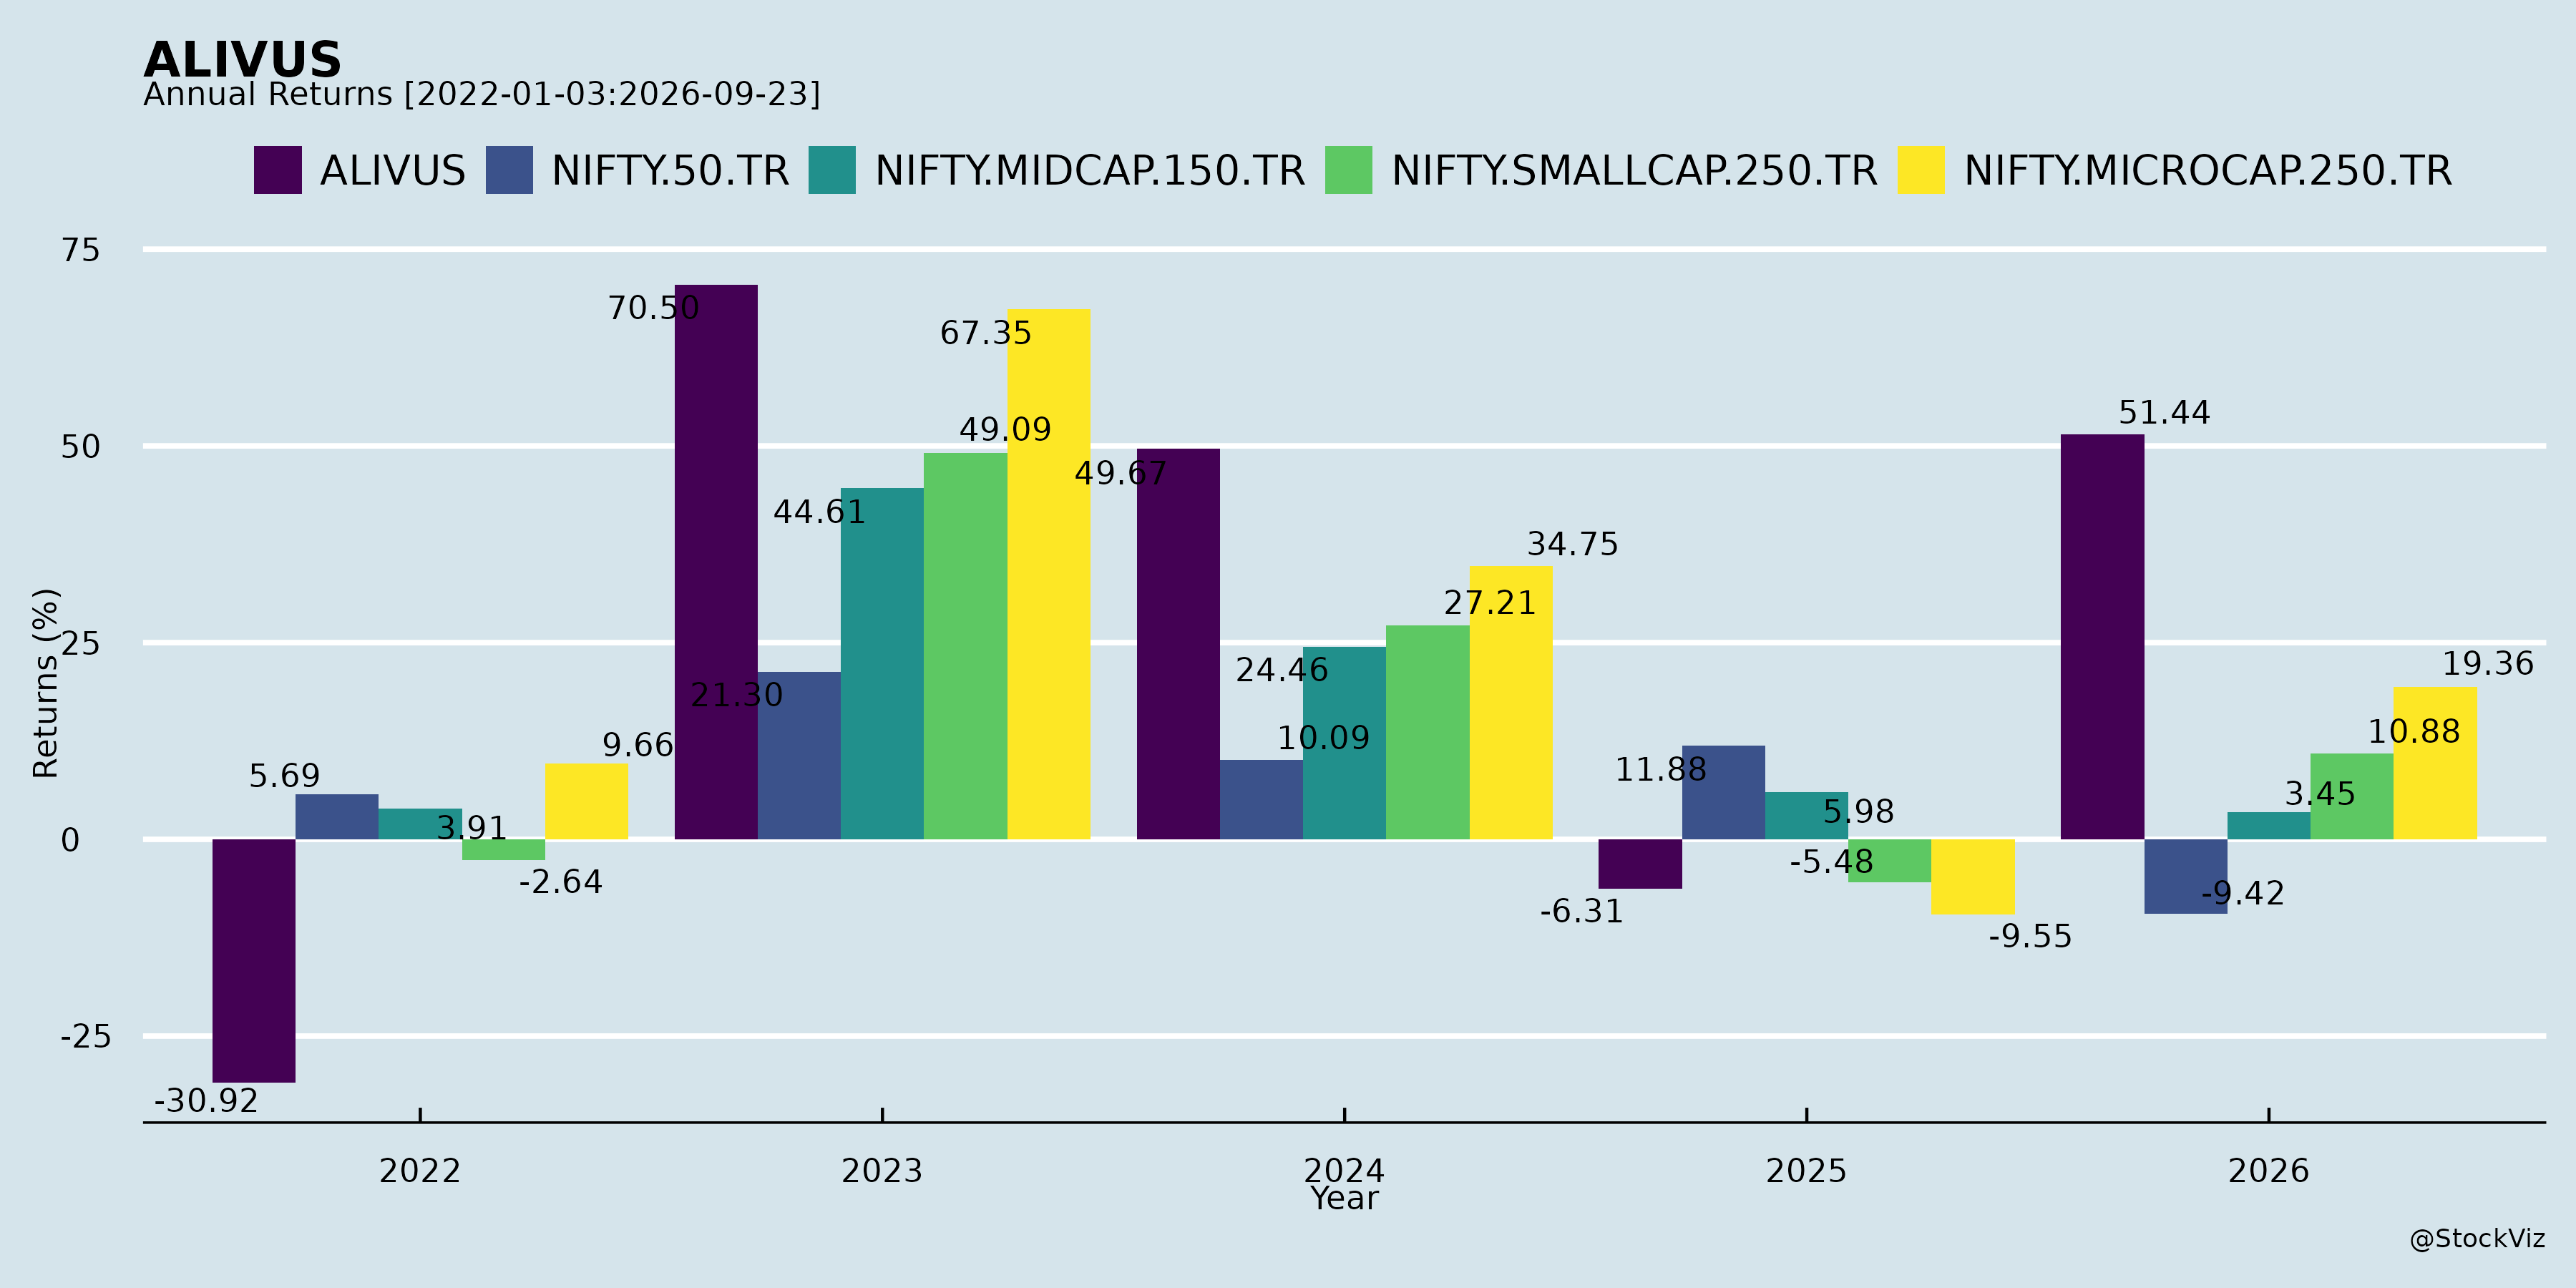
Annual Returns
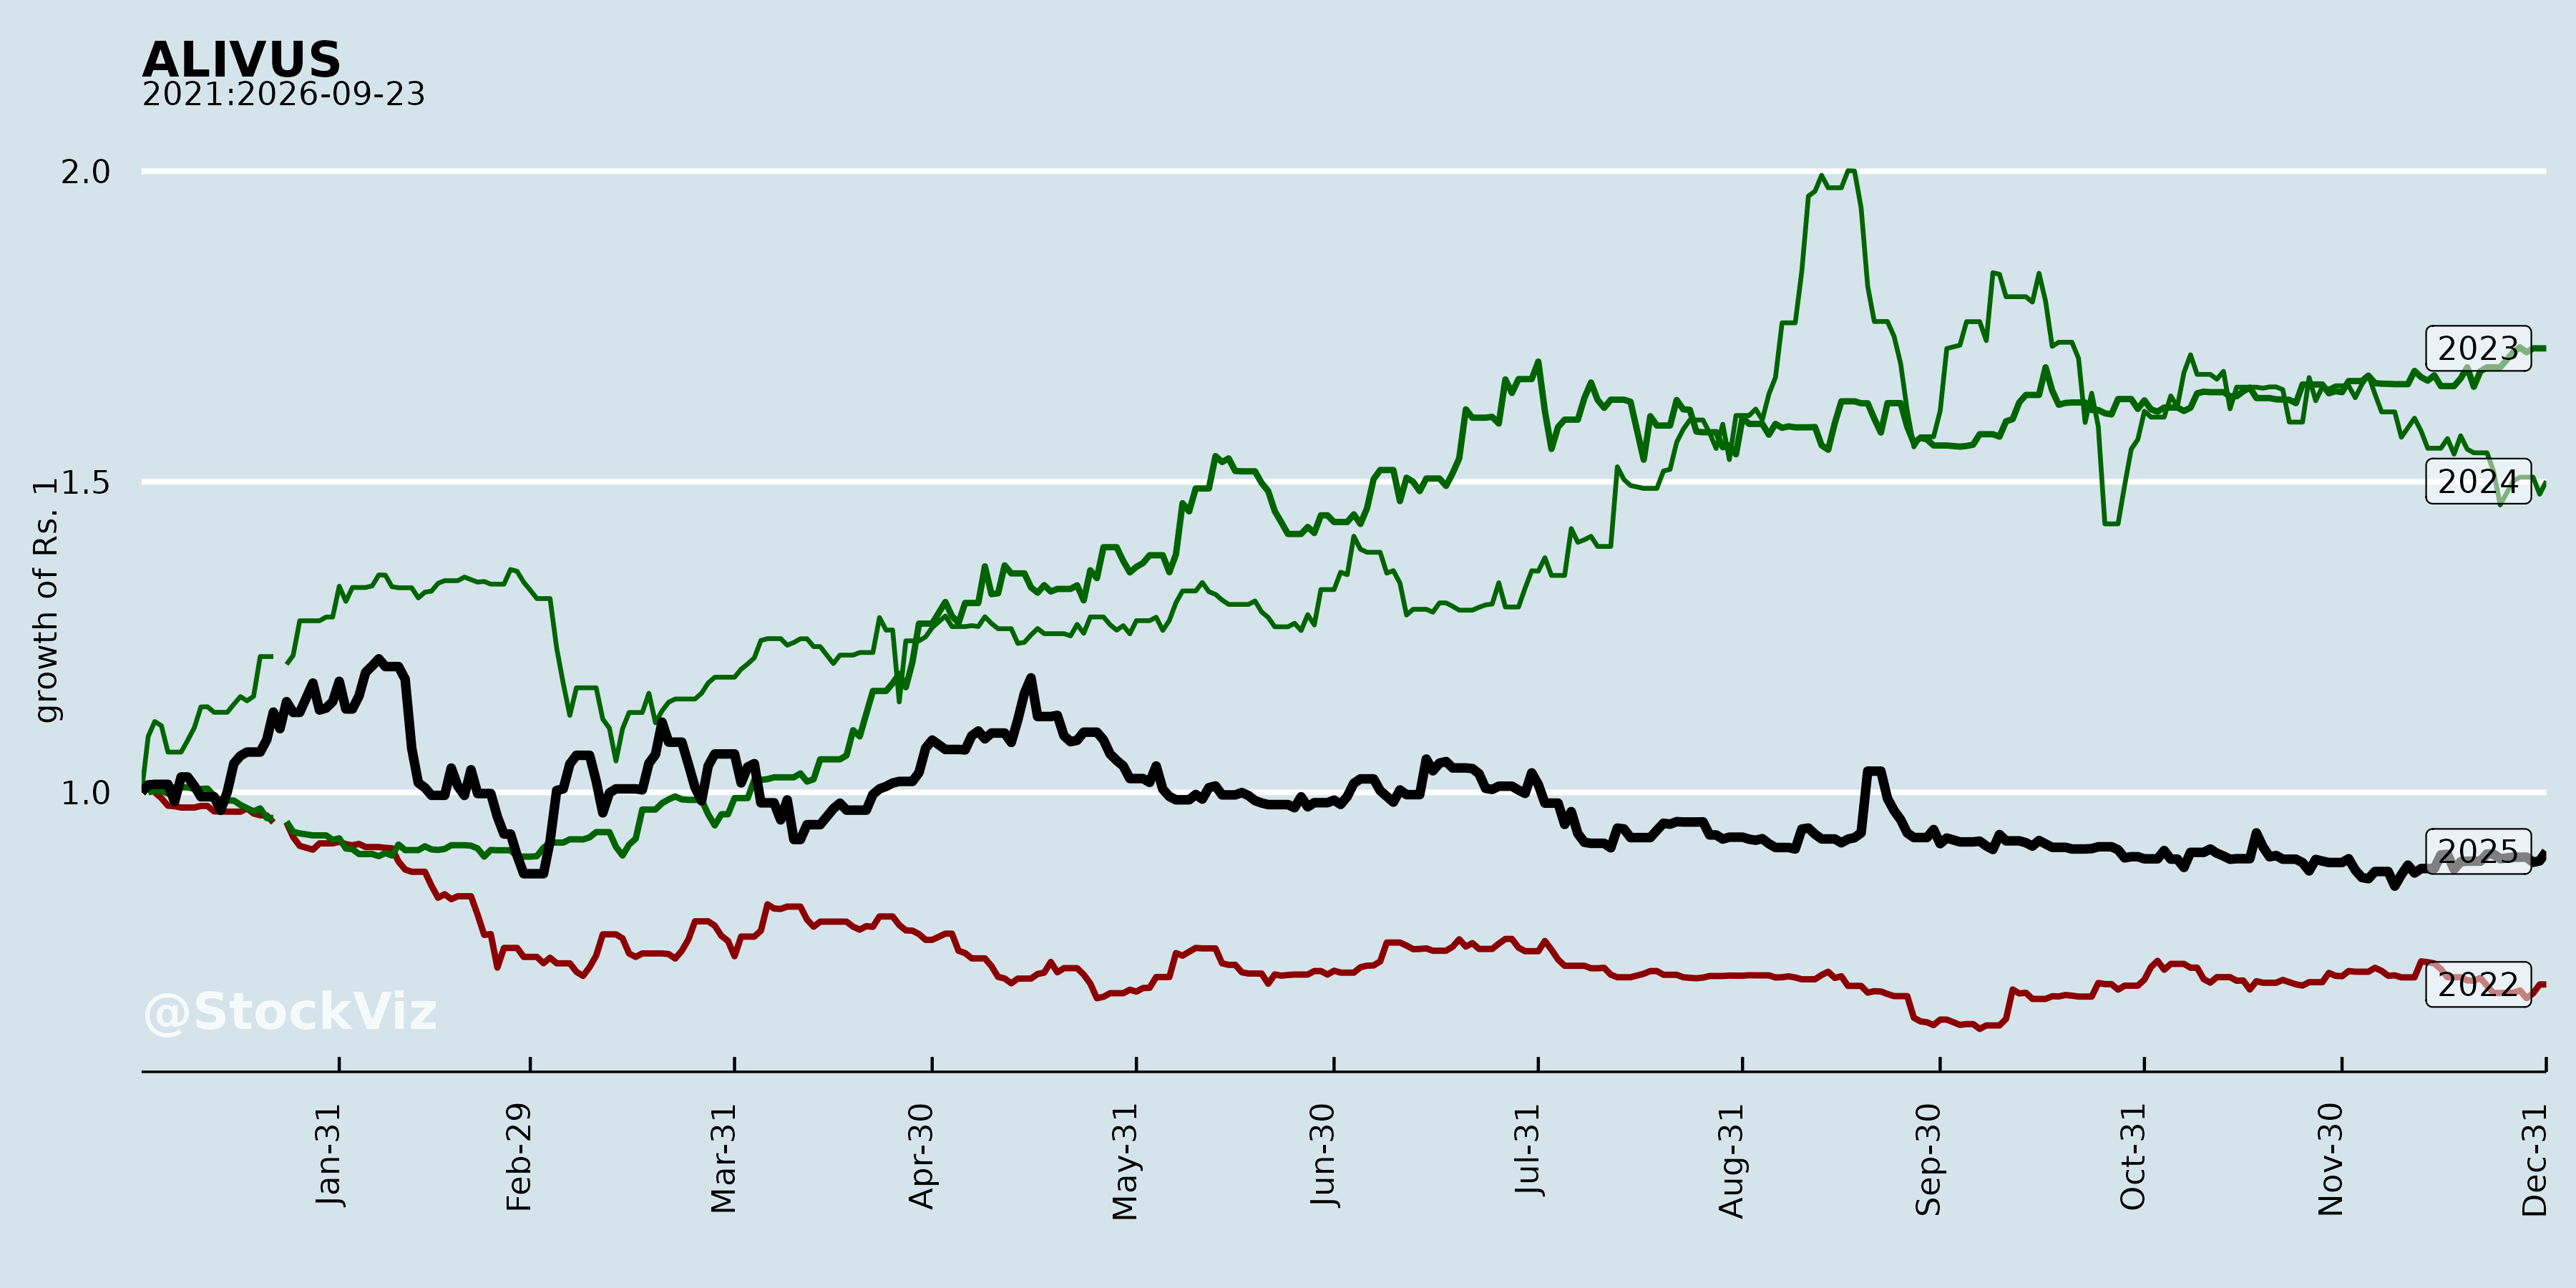
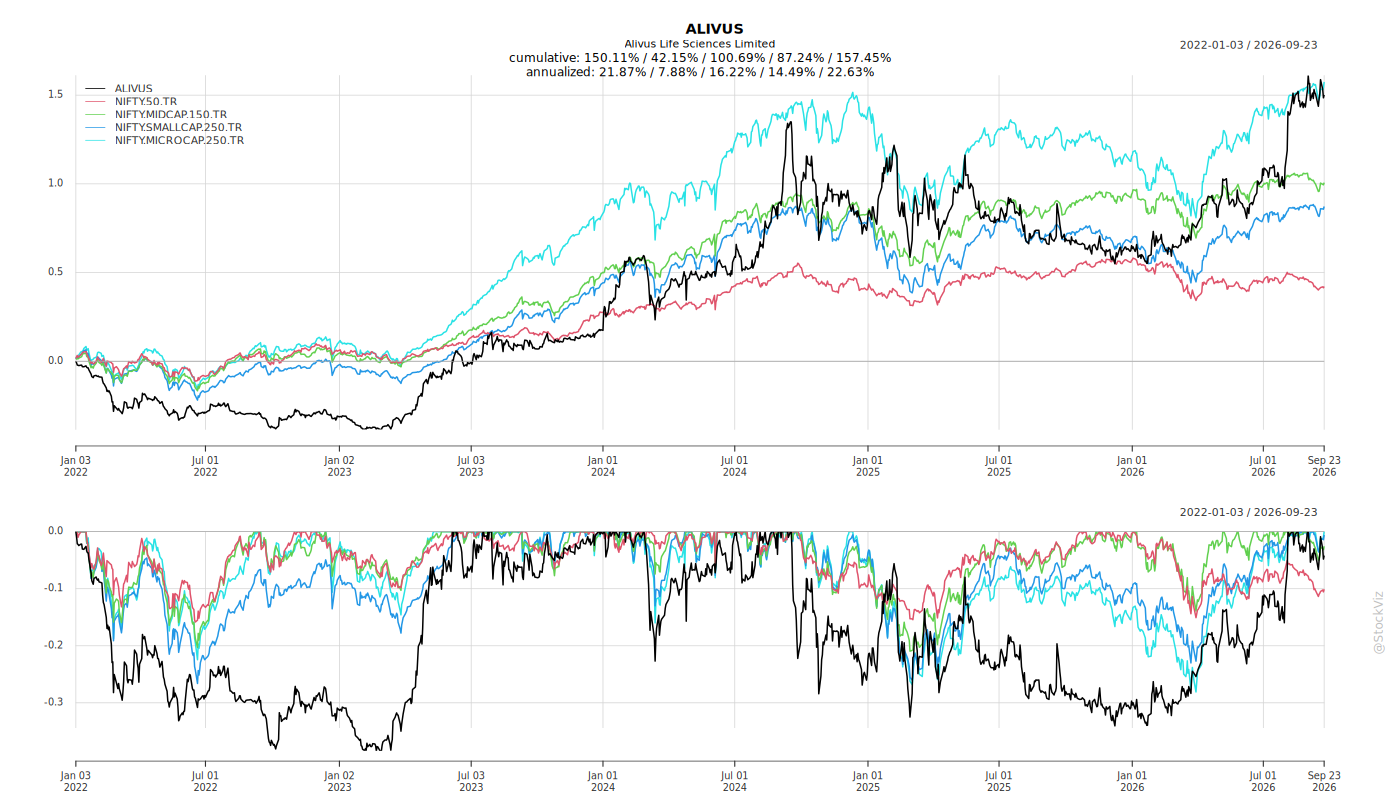
Cumulative Returns and Drawdowns
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
Alivus Life Sciences: Recent Developments and Outlook
1. Headwinds and Challenges
GPL business decline. The GPL business de-grew 52.6% year-on-year in Q1 FY27 due to inventory rationalisation. Management expects this business to recover only in H2 FY27 and to be flattish for the full year, with the historical skew toward H2 expected to repeat.
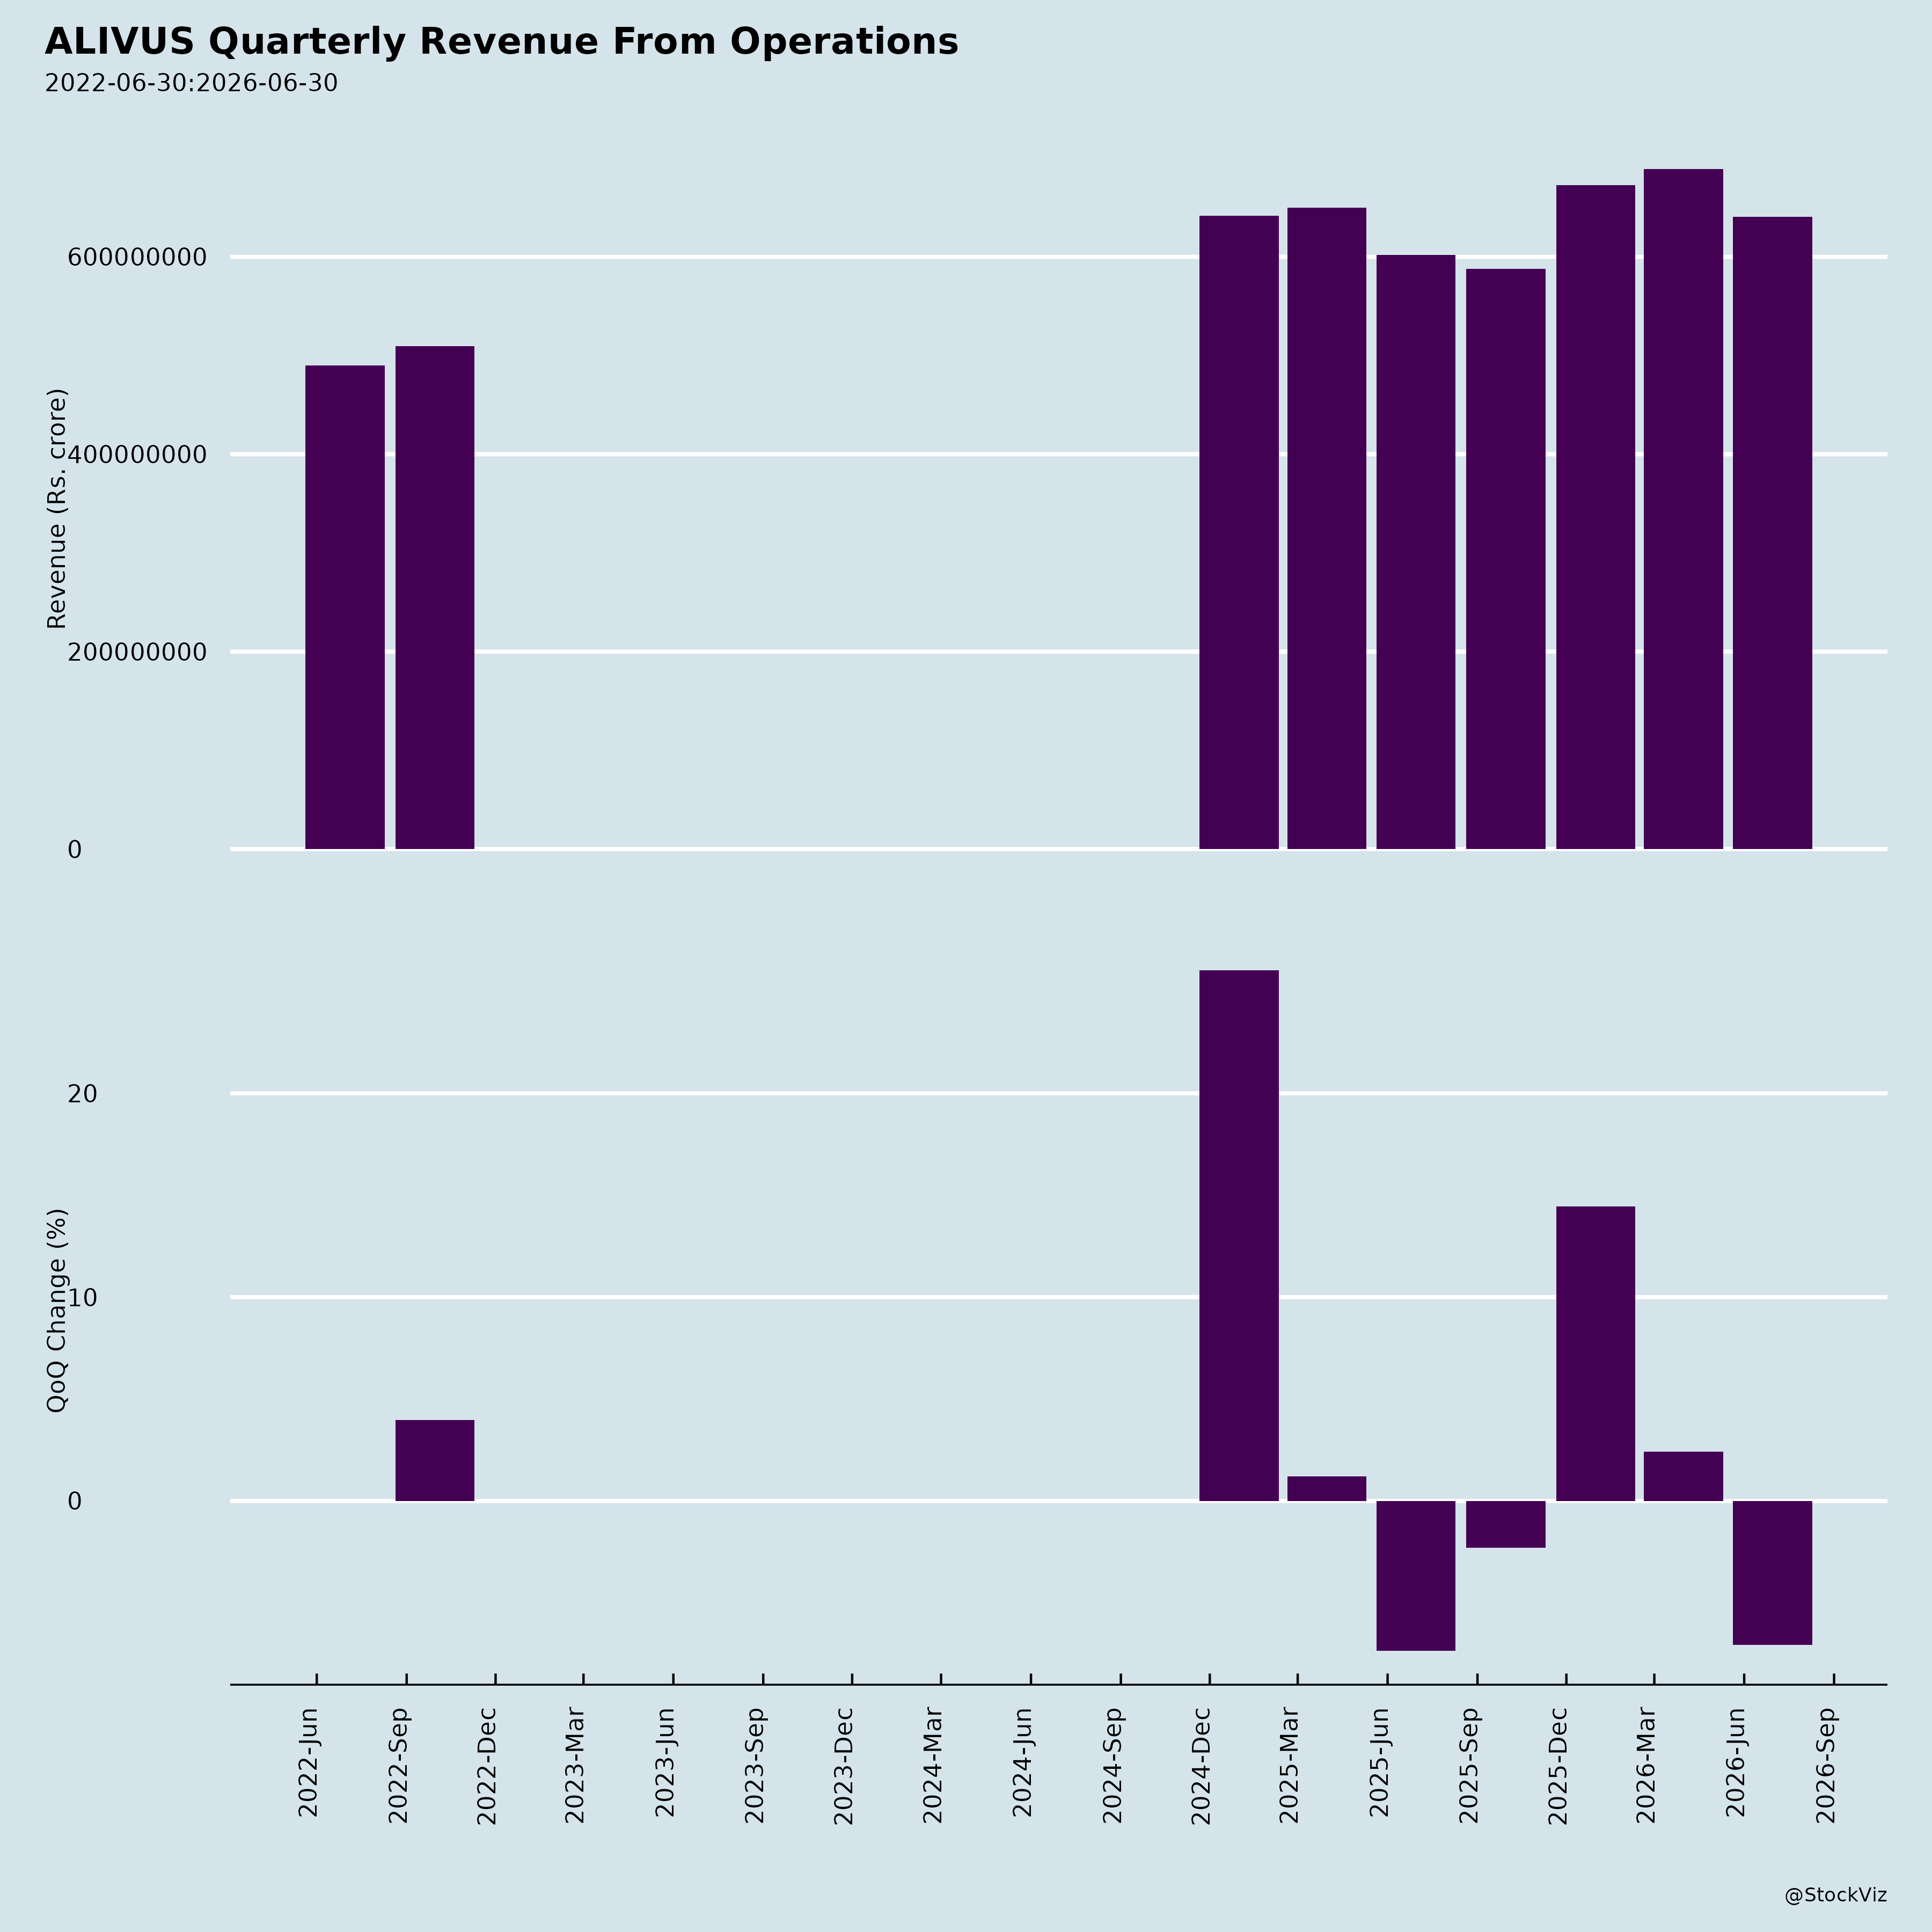
Sequential revenue softness. Revenue from operations declined 7.1% quarter-on-quarter in Q1 FY27 (₹6,404 million versus ₹6,891 million in Q4 FY26), with gross profit down 7.8% QoQ and EBITDA down 1.3% QoQ.
Geopolitical uncertainty. The company notes ongoing geopolitical uncertainties, although it states the product mix remained largely stable despite these conditions.
Asset turn pressure from capex. FATR is at 2.2 times, with asset turns trending slightly lower due to the ongoing capex cycle.
Execution and closing risk on the IQGenX acquisition. The acquisition is subject to customary closing condition precedents and is expected to close by the end of the current calendar year. The indicative completion date is December 6, 2026, or such date as may be agreed, subject to fulfilment of conditions precedent. If conditions precedent are not met within the stated timelines, the sellers will enter into a Business Transfer Agreement with the Company whereby the entire business, including employees and assets, will be acquired.
2. Tailwinds and Growth Prospects
Non-GPL business momentum. The non-GPL business grew 27.6% QoQ and 26.5% YoY in Q1 FY27, driven by healthy demand across all geographies and increasing contributions from new product launches.
Segmental growth. Generic API revenues grew 7.4% YoY in Q1 FY27 despite the significant GPL decline. CDMO revenue grew 3.8% YoY, with new and existing project contributions expected to translate into better growth in H2 FY27; several projects are in advanced stages of discussions.
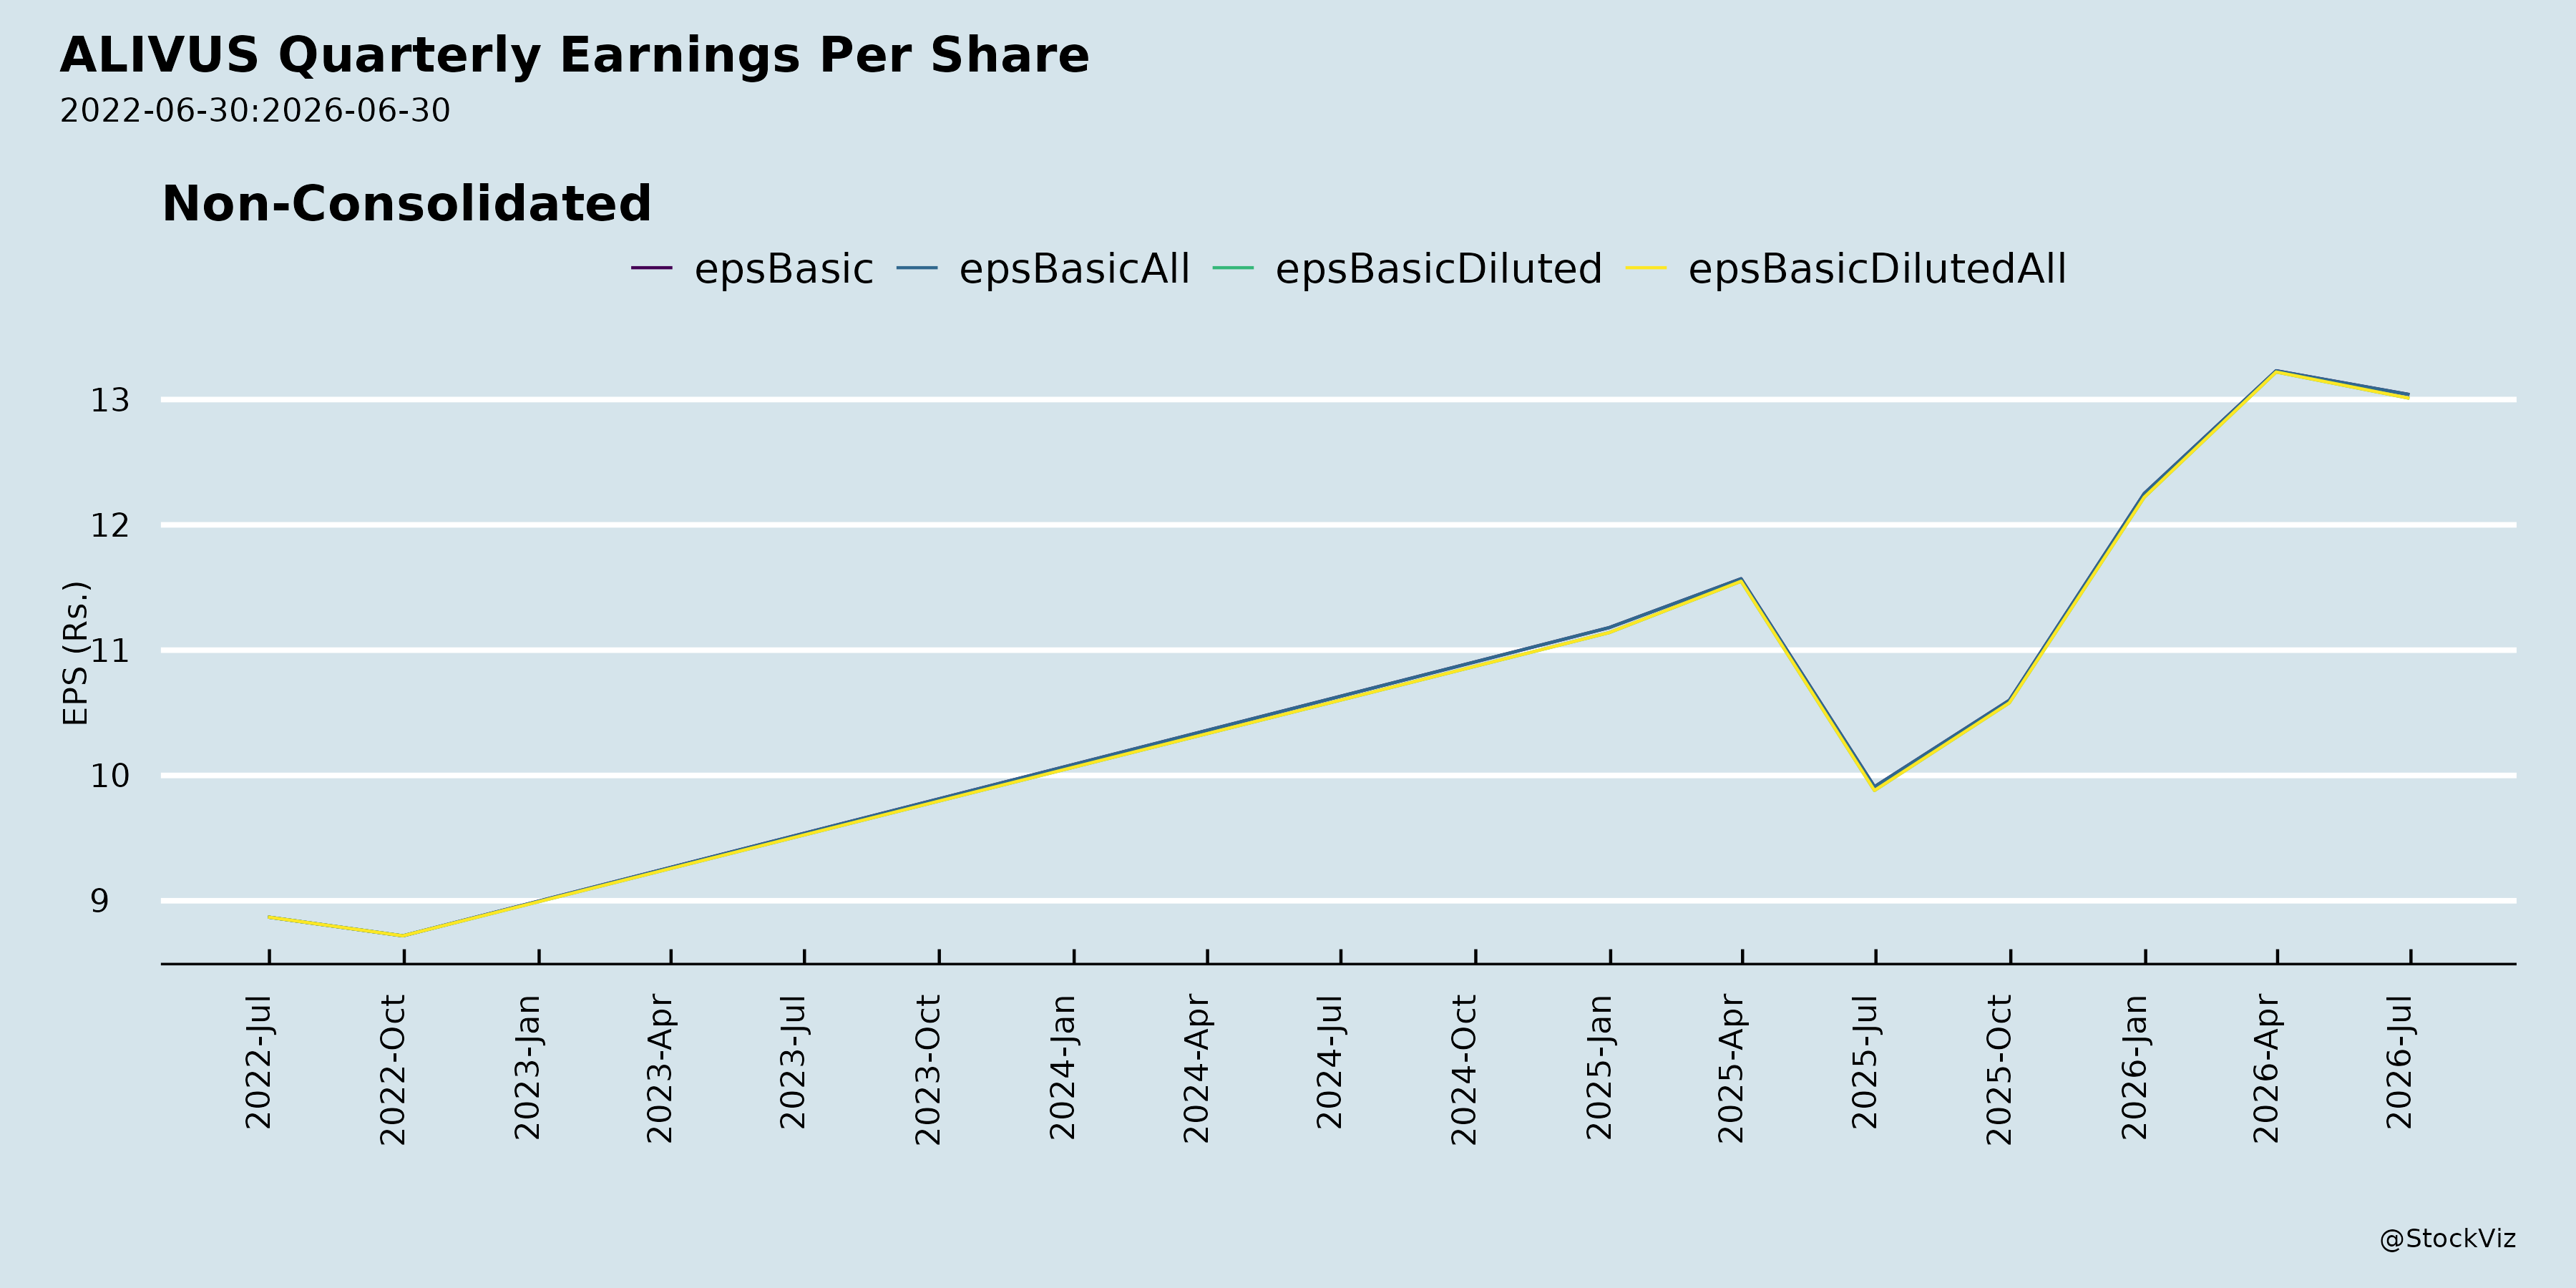
Margin expansion. Gross margins reached 60.2% in Q1 FY27, up 510 bps YoY, on favourable product mix and new launches. EBITDA margins were 36.6%, up 220 bps QoQ and 650 bps YoY. PAT margins were 25.0%, up 140 bps QoQ and 480 bps YoY.
Strong cash position. The company generated free cash flow of ₹901 million in Q1 FY27, with cash and cash equivalents (including short-term investments) of ₹8,802 million as of June 30, 2026.
IQGenX acquisition (announced August 18, 2026). Alivus will acquire 76% of IQGEN-X Pharma Private Limited for approximately INR 9.12 crores (INR 91.2 million) in cash, covering 8,60,589 equity shares of ₹10 each. IQGenX, incorporated in October 2016, is a custom research organisation engaged in formulation development of oral solids, sterile injectables and ophthalmic solutions for US, EU, Latin America, Middle East and other regulated and semi-regulated markets. Its turnover was INR 348.0 lacs in FY2025-26, INR 318.2 lacs in FY2024-25 and INR 267.5 lacs in FY2023-24. The acquisition is not a related party transaction, no promoter has any interest in the target, and no government or regulatory approval is required. The stated rationale is to extend Alivus into advanced formulation development, create an integrated end-to-end platform, add bioequivalence and stability study capabilities, expand the global customer base in generics, scale the CDMO value proposition (pre-formulation through commercial manufacturing, analytical development, regulatory submission support), and build a differentiated niche asset basket with primary focus on Oncology for out-licensing across geographies.
Pipeline and R&D progress. Cumulative DMF/CEP filings reached 617 as of June 30, 2026. Five synthetic small molecules were added to the development grid during the quarter. The HP API portfolio has 29 products in active development with a TAM of ~$82 bn (IQVIA, MAT Mar’26): 13 validated, seven in advanced development, nine in lab development. The iron complexes portfolio has one regulatory filing completed, one product validated, one in advanced development and one under feasibility evaluation, with a collective TAM of ~$2.6 bn (IQVIA, MAT Mar’26).
Capacity expansion. Brownfield addition of ~100 KL at Ankleshwar is planned for Q4 FY27; brownfield addition of ~160 KL at Dahej is planned for Q3 FY27. Greenfield Solapur phases: Phase 1 ~350 KL (Q3 FY27), Phase 2 ~115 KL (Q4 FY27), Phase 3 ~535 KL (FY29). Construction of 465 KL (Phases 1 and 2) at Solapur is in process, and construction of a new R&D facility has commenced. A new Taloja R&D centre will focus on flow chemistry, complex products, particle engineering, oncology research and green chemistry.
Strategic growth levers. CDMO ramp-up, expansion into complex API platforms, iron compounds, oncology and HP API; new product launches, geographic expansion, focus on newly regulated markets and second-source opportunities with top generic players; operational efficiencies including debottlenecking, second/third-generation process adoption, backward integration, carbon footprint reduction, flow chemistry adoption and AVD opportunities.
Other recent developments. The company incorporated a wholly owned subsidiary, Alivus Life Sciences Do Brasil Ltda., in São Paulo, Brazil, on September 15, 2026, with authorised capital of R$ 500,000.00. Representatives attended the Kotak Healthcare Forum 2026 on September 17, 2026 in Mumbai. At the 15th AGM on September 8, 2026, all four ordinary resolutions passed with requisite majority, including approval of audited financial statements for FY ended March 31, 2026, a final dividend of Rs. 5/- per equity share, re-appointment of Mr. Hiren Patel as a Director, and ratification of the cost auditor’s remuneration.
3. Key Risks
- Continued GPL business weakness beyond the expected H2 FY27 recovery, given the 52.6% YoY Q1 decline and dependence on a historically H2-skewed profile.
- Dependence on non-GPL momentum to offset GPL softness; the 10%–12% FY27 revenue growth ambition rests on this balance.
- CDMO growth realisation timing, with better growth currently expected only in H2 FY27.
- Acquisition closing risk on IQGenX if conditions precedent are not met by December 6, 2026, triggering the alternative Business Transfer Agreement route.
- Capex-cycle pressure on asset turns, with FATR at 2.2 times and capacity expansions across Ankleshwar, Dahej and Solapur still to be commissioned.
- Geopolitical uncertainties affecting markets, though the company reports a largely stable product mix.
- Regulatory inspection exposure across four manufacturing facilities; the Mohol site’s last USFDA inspection was March 2018 and Kurkumbh has no listed USFDA inspection, while Ankleshwar (Jan 2025) and Dahej (May 2025) have more recent inspections.
- Forward-looking statements are subject to risks including general economic and business conditions in India and abroad, R&D efforts, currency movements, interest rates, regulatory changes, competition and political conditions.
4. Management Guidance Versus Observed Performance
FY27 revenue growth guidance: 10%–12%. Observed Q1 FY27 revenue grew 6.4% YoY (₹6,404 million versus ₹6,018 million) but declined 7.1% QoQ. Management attributes confidence to continued non-GPL momentum and muted GPL growth.
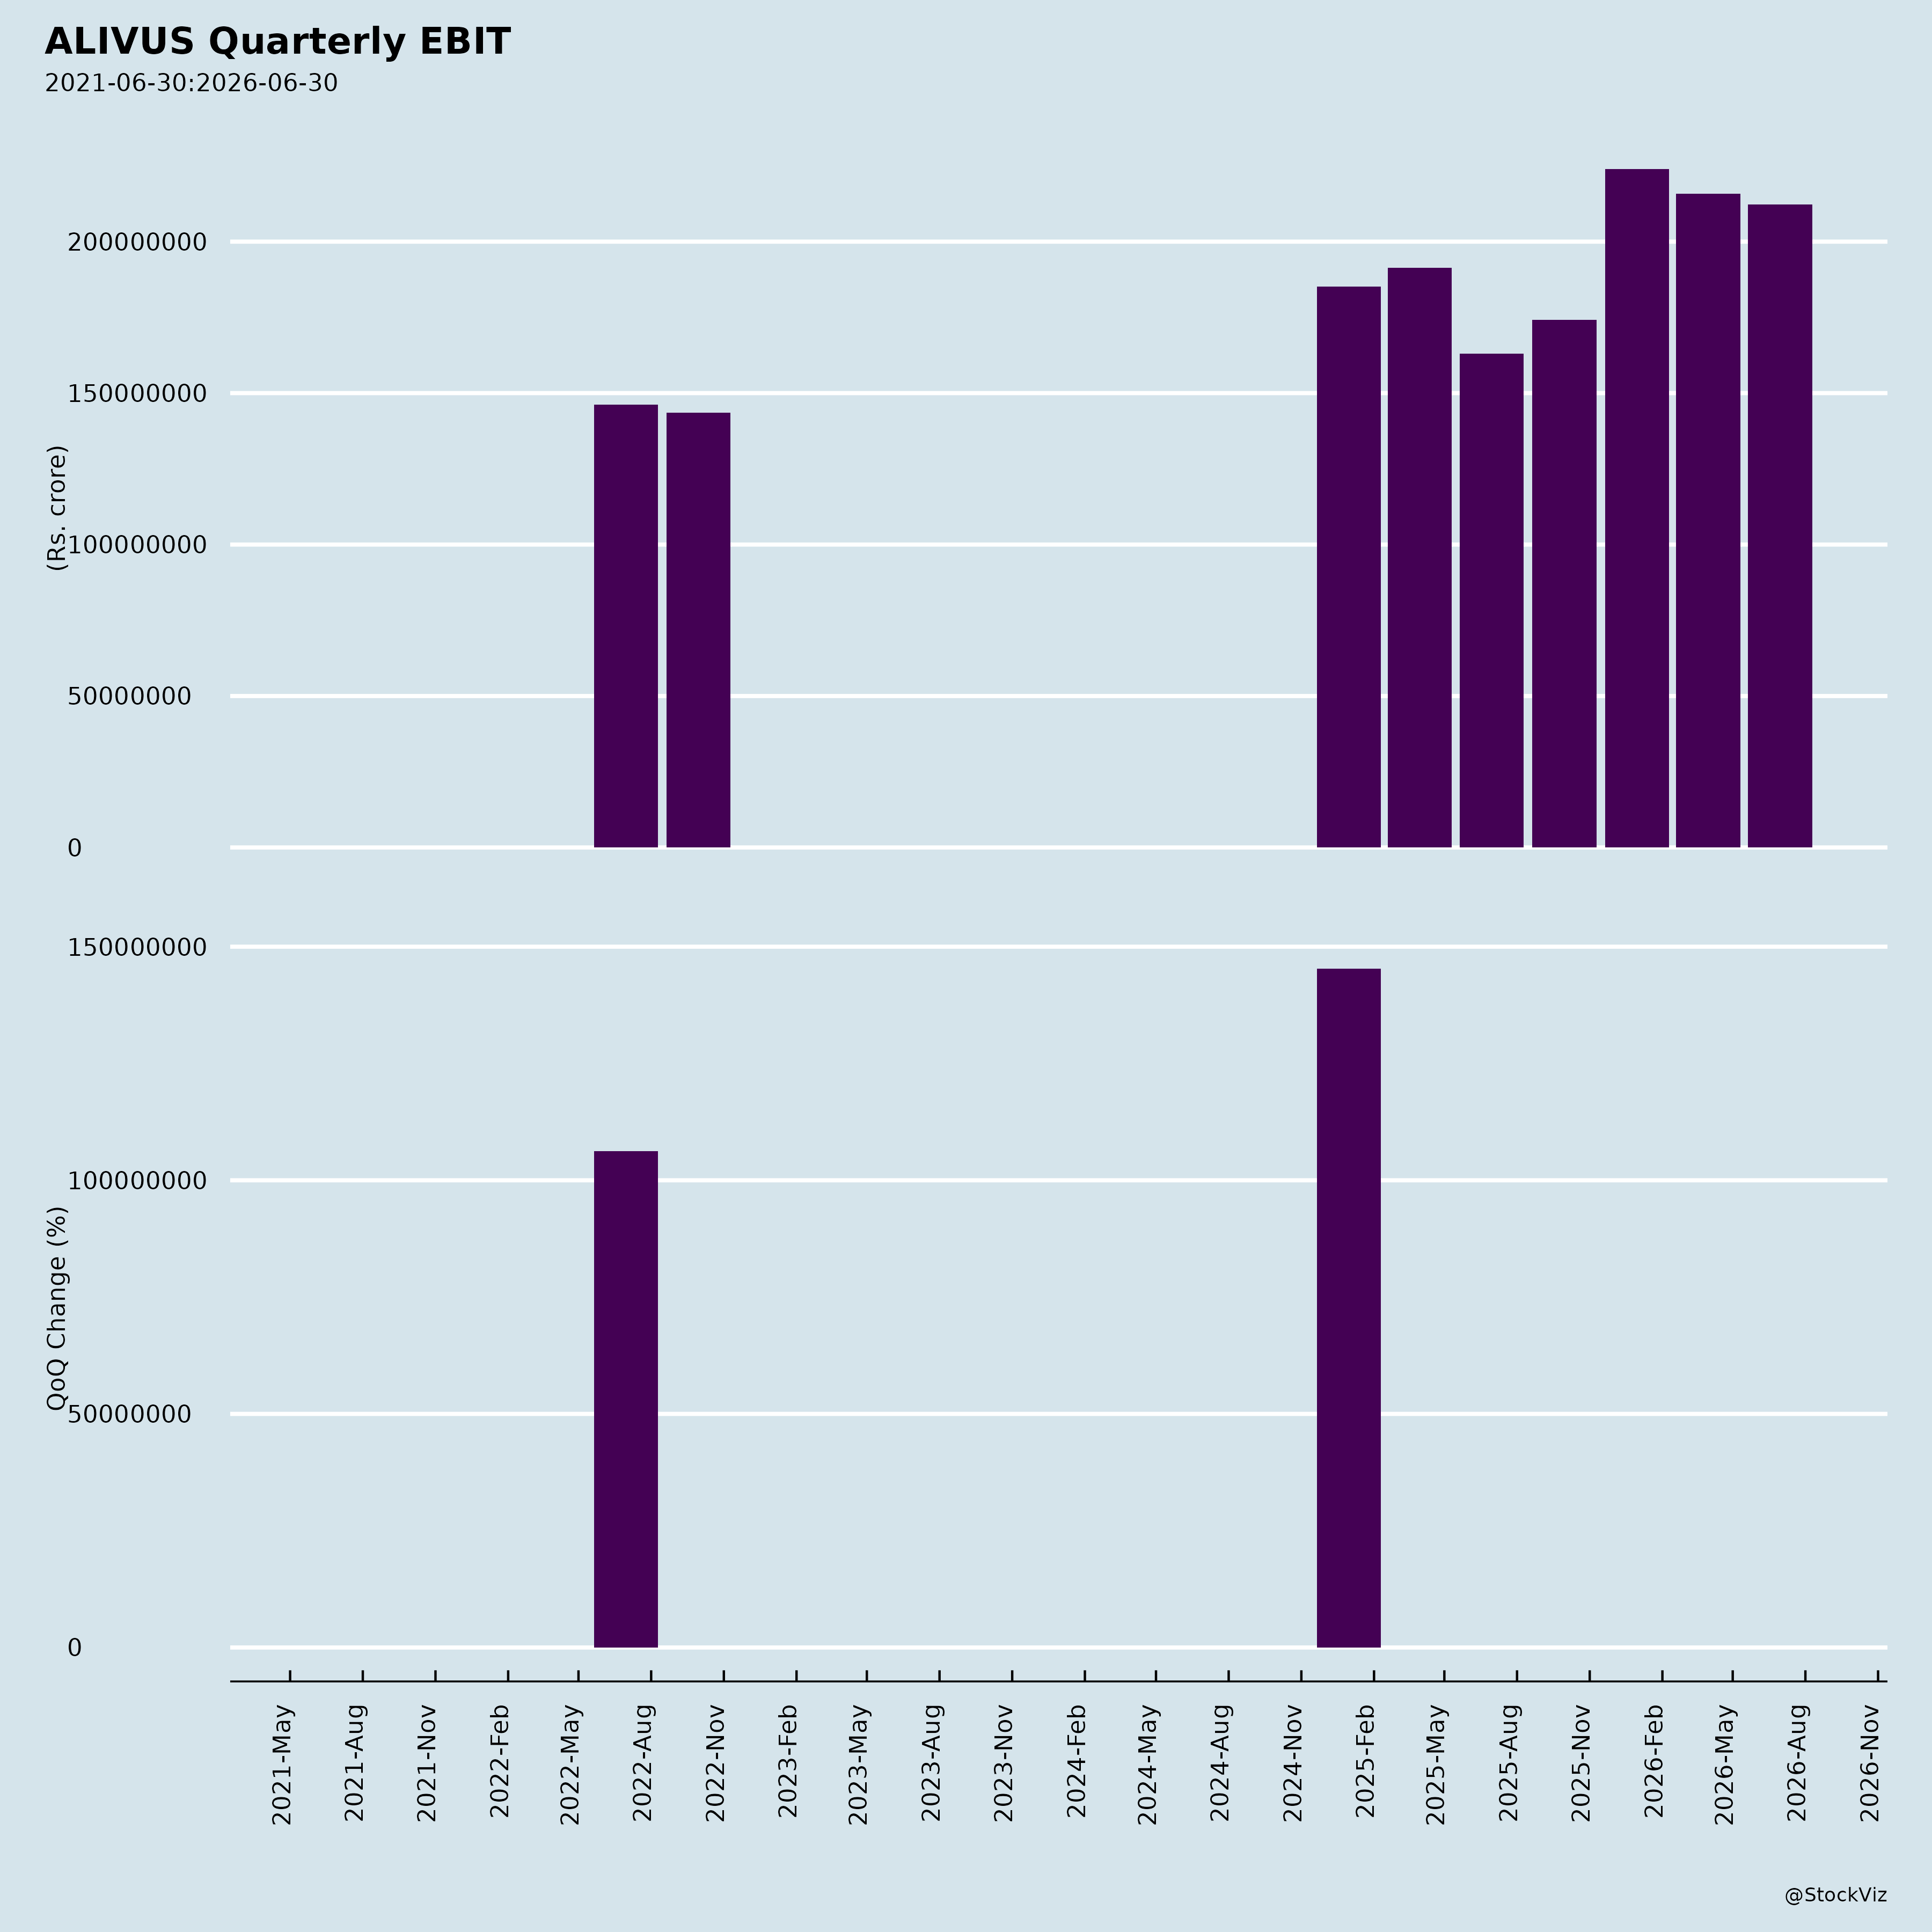
FY27 EBITDA margin guidance: 30%–32%. Observed Q1 FY27 EBITDA margin was 36.6%, above the guided range, up 220 bps QoQ and 650 bps YoY. FY26 full-year EBITDA margin was 33.6%.
GPL business guidance: flattish in FY27, skewed to H2. Observed Q1 FY27 GPL de-growth was 52.6% YoY, which management describes as a significant decline, with recovery expected in H2 FY27.
CDMO guidance: better growth in H2 FY27. Observed Q1 FY27 CDMO growth was 3.8% YoY, with several projects in advanced stages of discussions.
Capacity timelines. Ankleshwar ~100 KL addition guided for Q4 FY27; Dahej ~160 KL guided for Q3 FY27; Solapur Phase 1 (~350 KL) guided for Q3 FY27 and Phase 2 (~115 KL) for Q4 FY27, with construction of 465 KL in process.
IQGenX closing guidance. Expected to close by end of the current calendar year, with an indicative completion date of December 6, 2026, subject to conditions precedent.
AGM outlook. Management expressed confidence in future growth through innovation, disciplined capital allocation, sustainability initiatives, continued value creation for shareholders, and expansion through the “API+” approach and advanced pharmaceutical capabilities.
Broker Narrative
The first report was cautiously Neutral, citing weak seasonality, flat consumer healthcare, and US generics constraints while hoping for launches, innovation, and margin expansion. The last report remained Neutral but was more defensive, flagging margin contraction, higher depreciation/interest/tax, US sales declines, and a modest ~5% earnings CAGR. Domestic formulations shifted from a modest growth concern to a clear outperformer, while cost/R&D pressure and limited valuation upside persisted; earlier optimism on US generics and cost optimization gave way to competitive/pricing pressure.
Fears that came true
- Employee and R&D expense increases flagged in the first report materialized, contributing to 750bp YoY EBITDA margin contraction and 70bp gross margin decline by 1QFY27.
- The early warning of limited valuation upside materialized, with the last report estimating only ~5% earnings CAGR over FY26-28 and limited upside.
- US generics growth constraints from competition and pricing materialized, as US sales fell 2.6% YoY (down 12% in constant currency) and North America sales declined for a second consecutive quarter.
Optimism that failed
- The expectation of sustained double-digit US generics growth from launches and market-share gains failed to hold, as US sales declined and competition/pricing pressure weighed on base/select generics.
- The expectation of cost optimization and delayed competition in a key US product failed, as employee/other expenses and R&D spend rose and margins contracted.
- The expectation that consumer healthcare would benefit from a favourable season failed, as a weaker summer season partly offset domestic consumer growth.
Broker Timeline
3 broker calls · 2026-01-23 to 2026-07-31
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.