ADSL
Equity Metrics
September 24, 2026
Allied Digital Services Limited
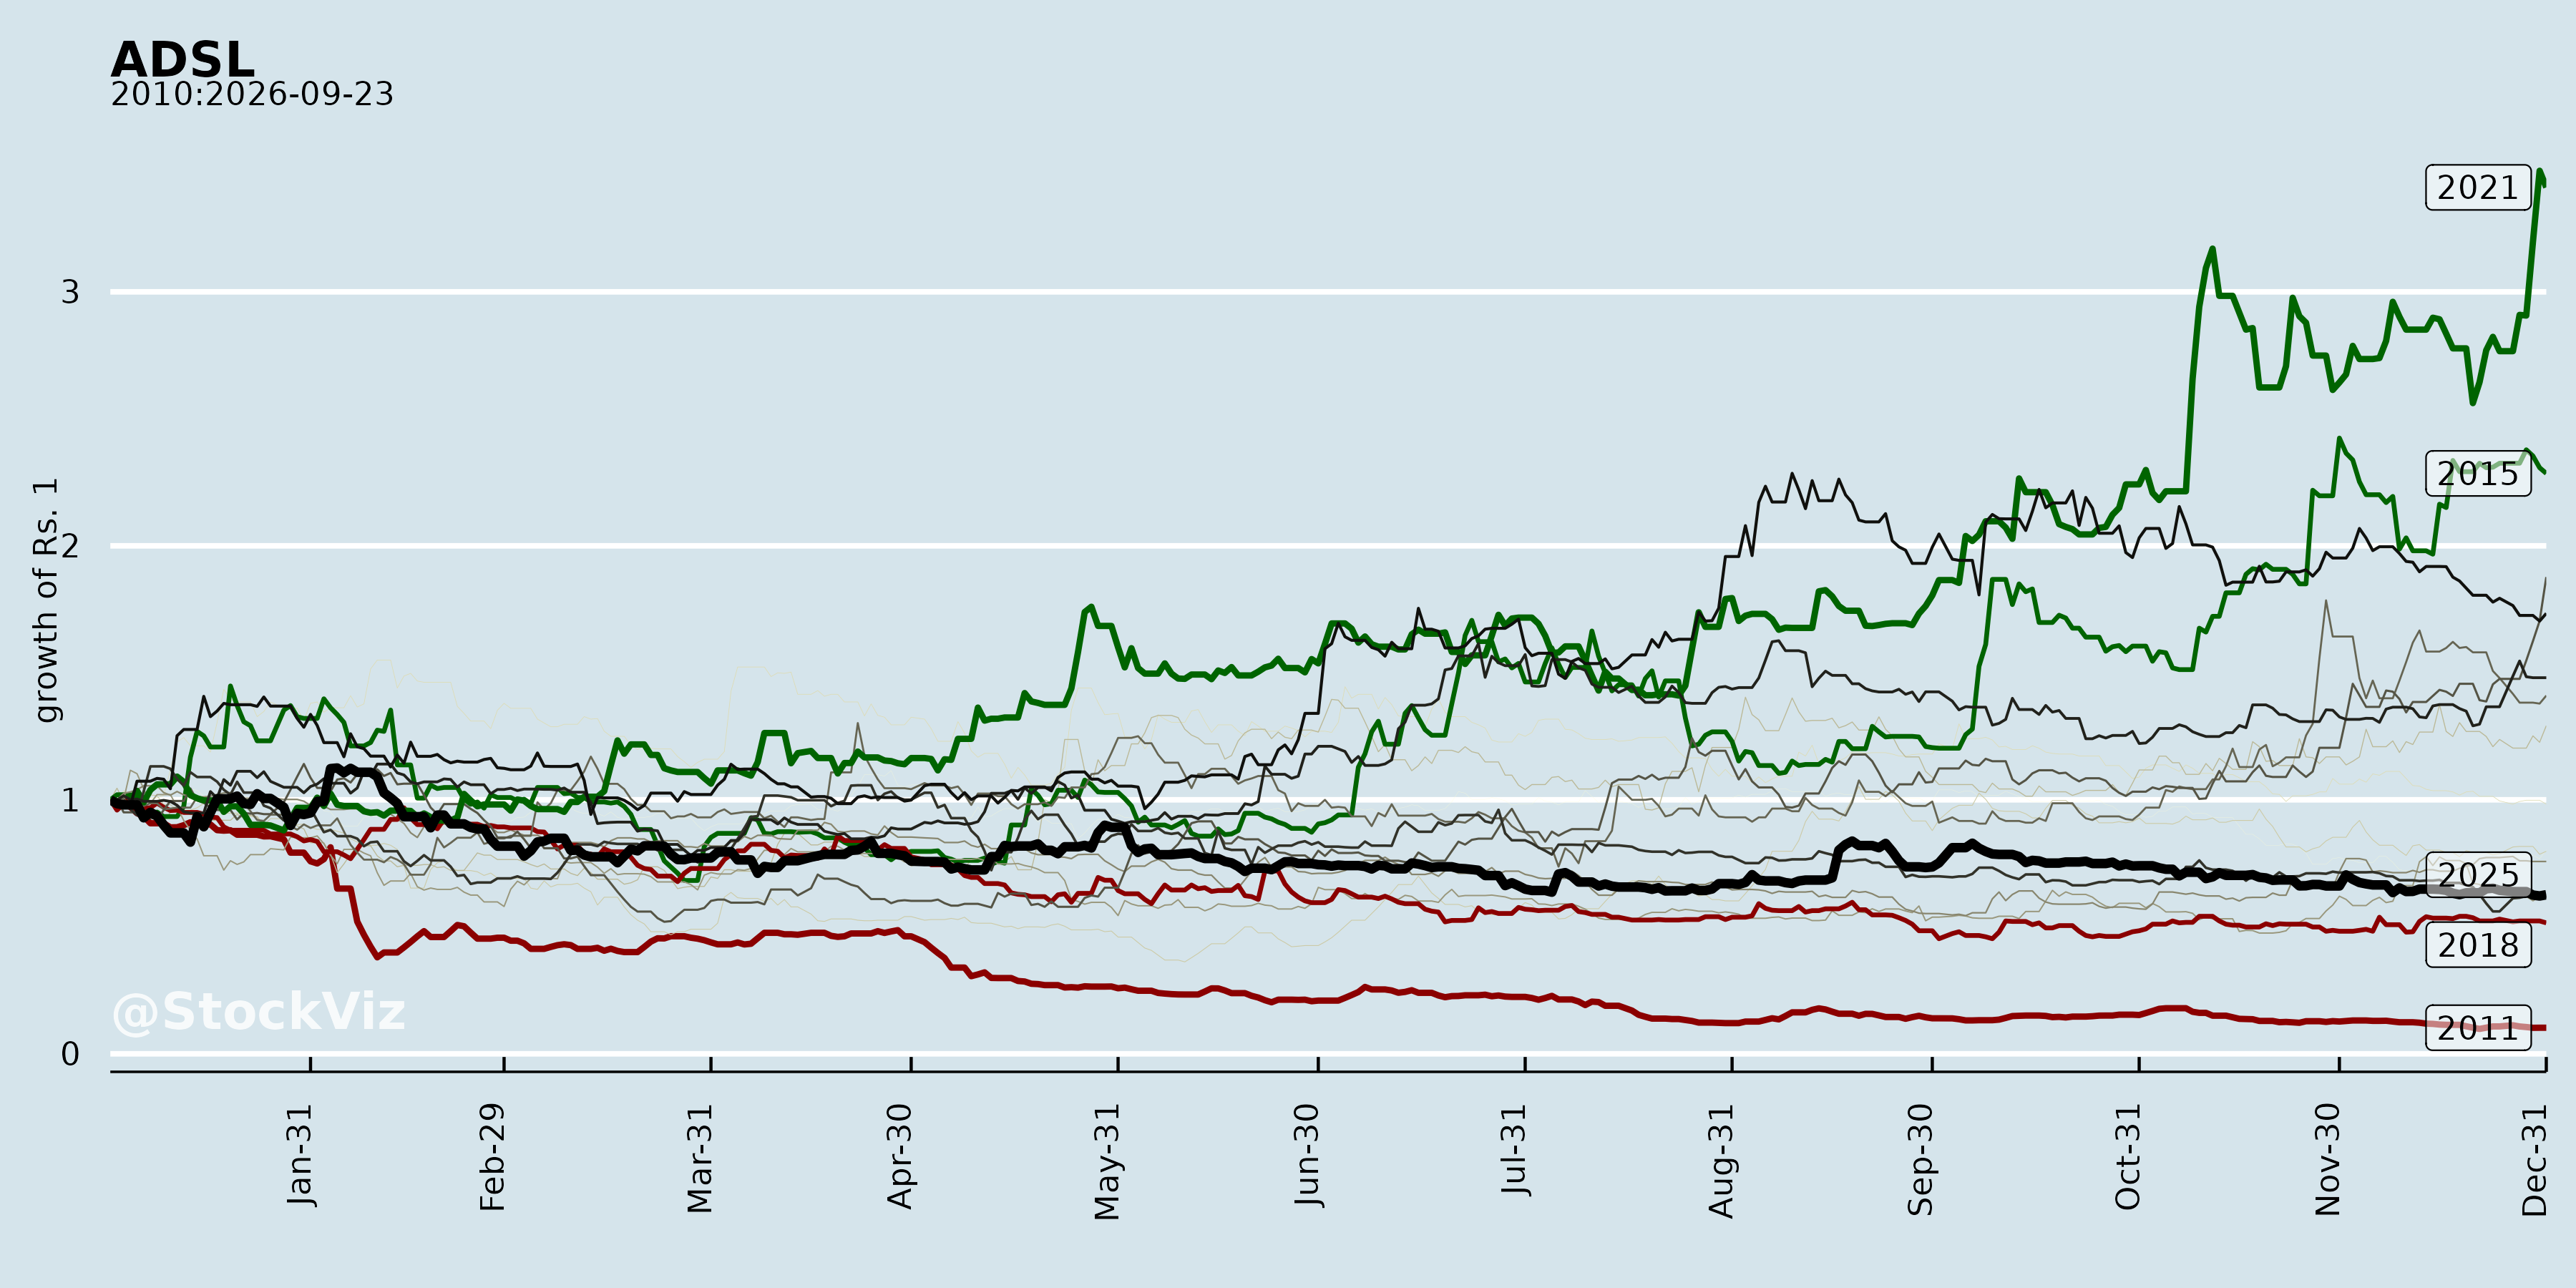
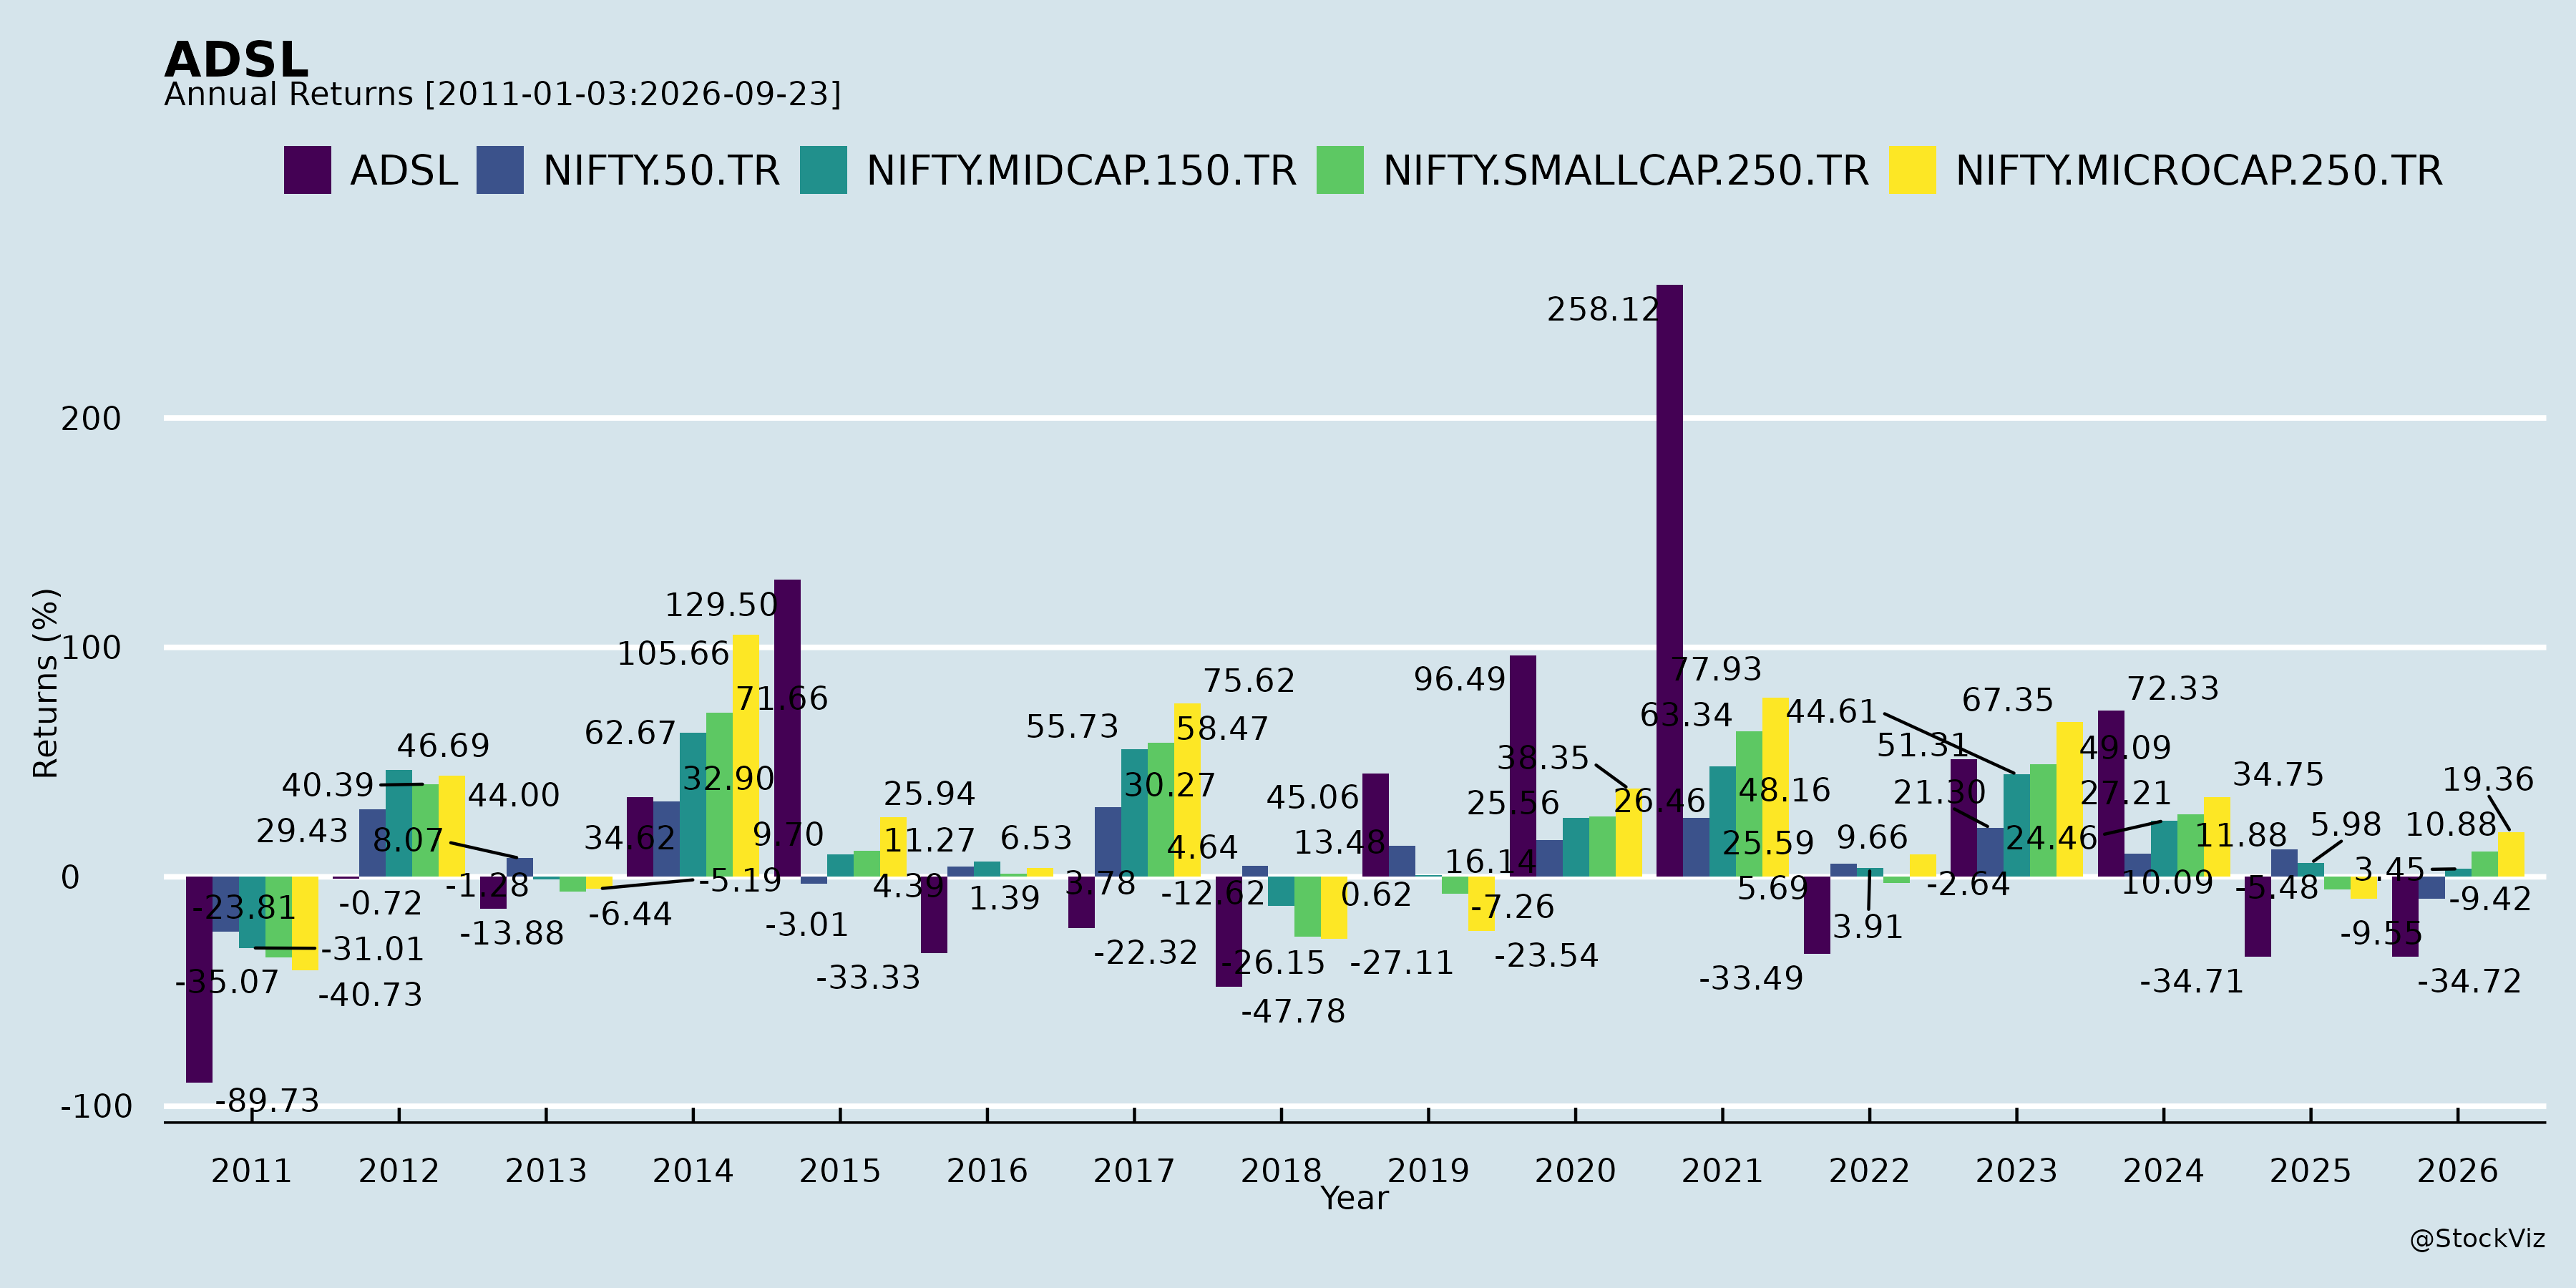
Annual Returns
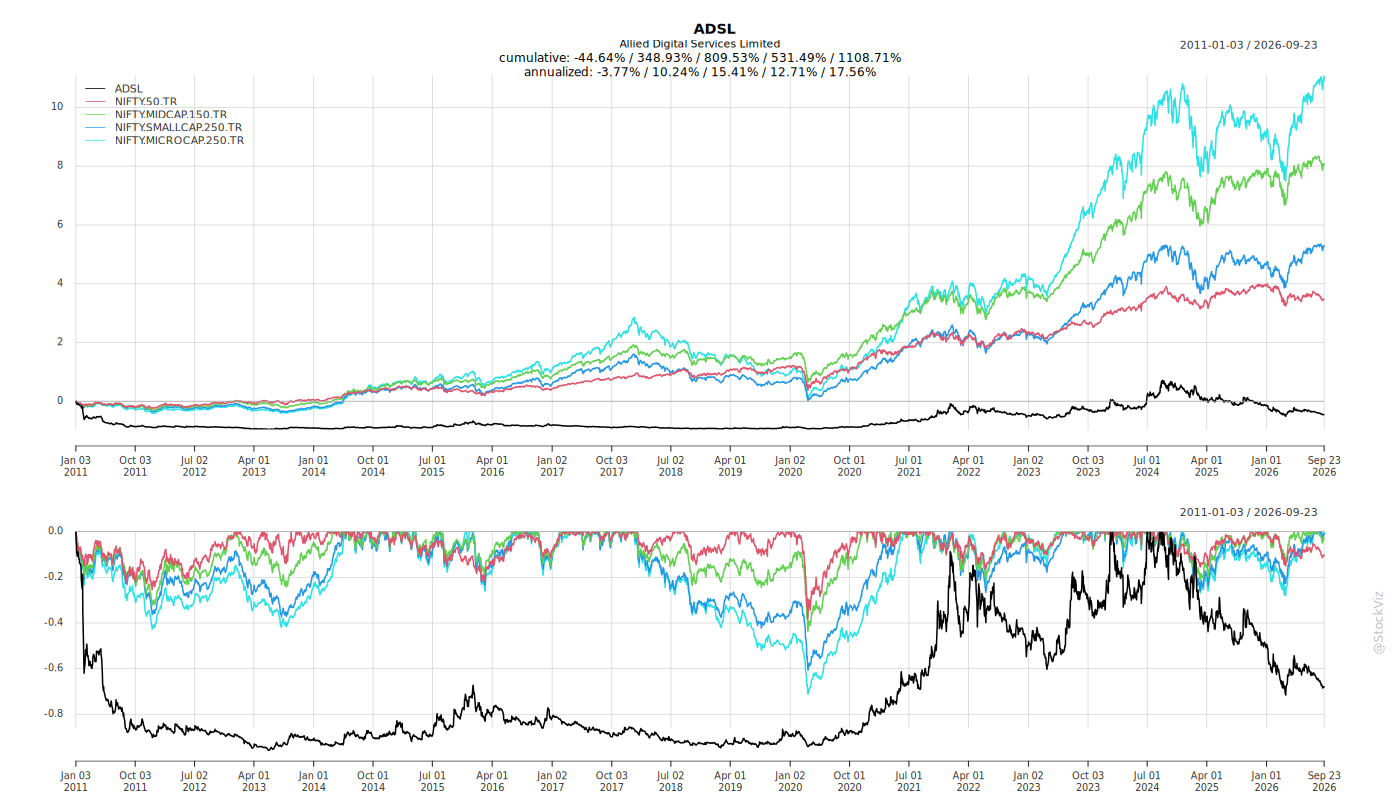
Cumulative Returns and Drawdowns
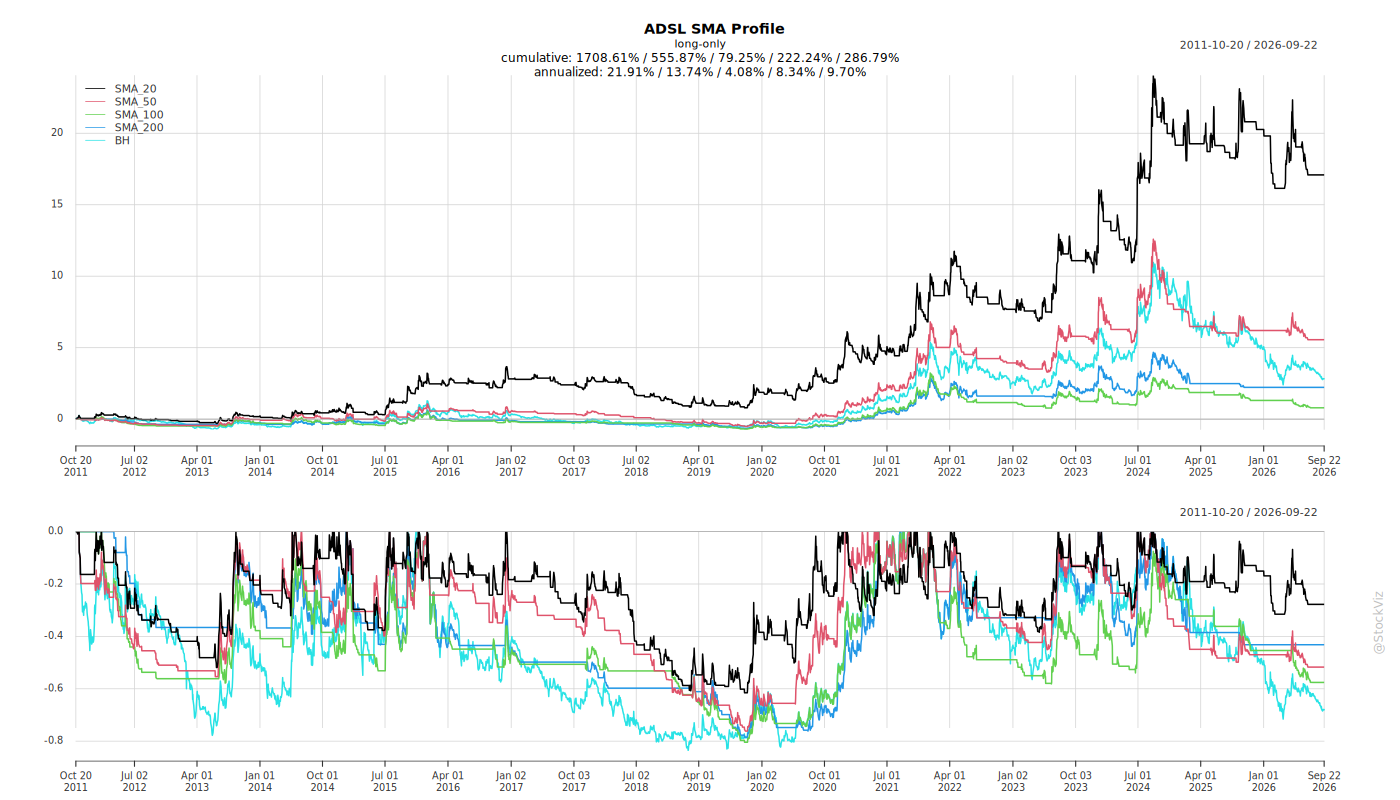
Fundamentals
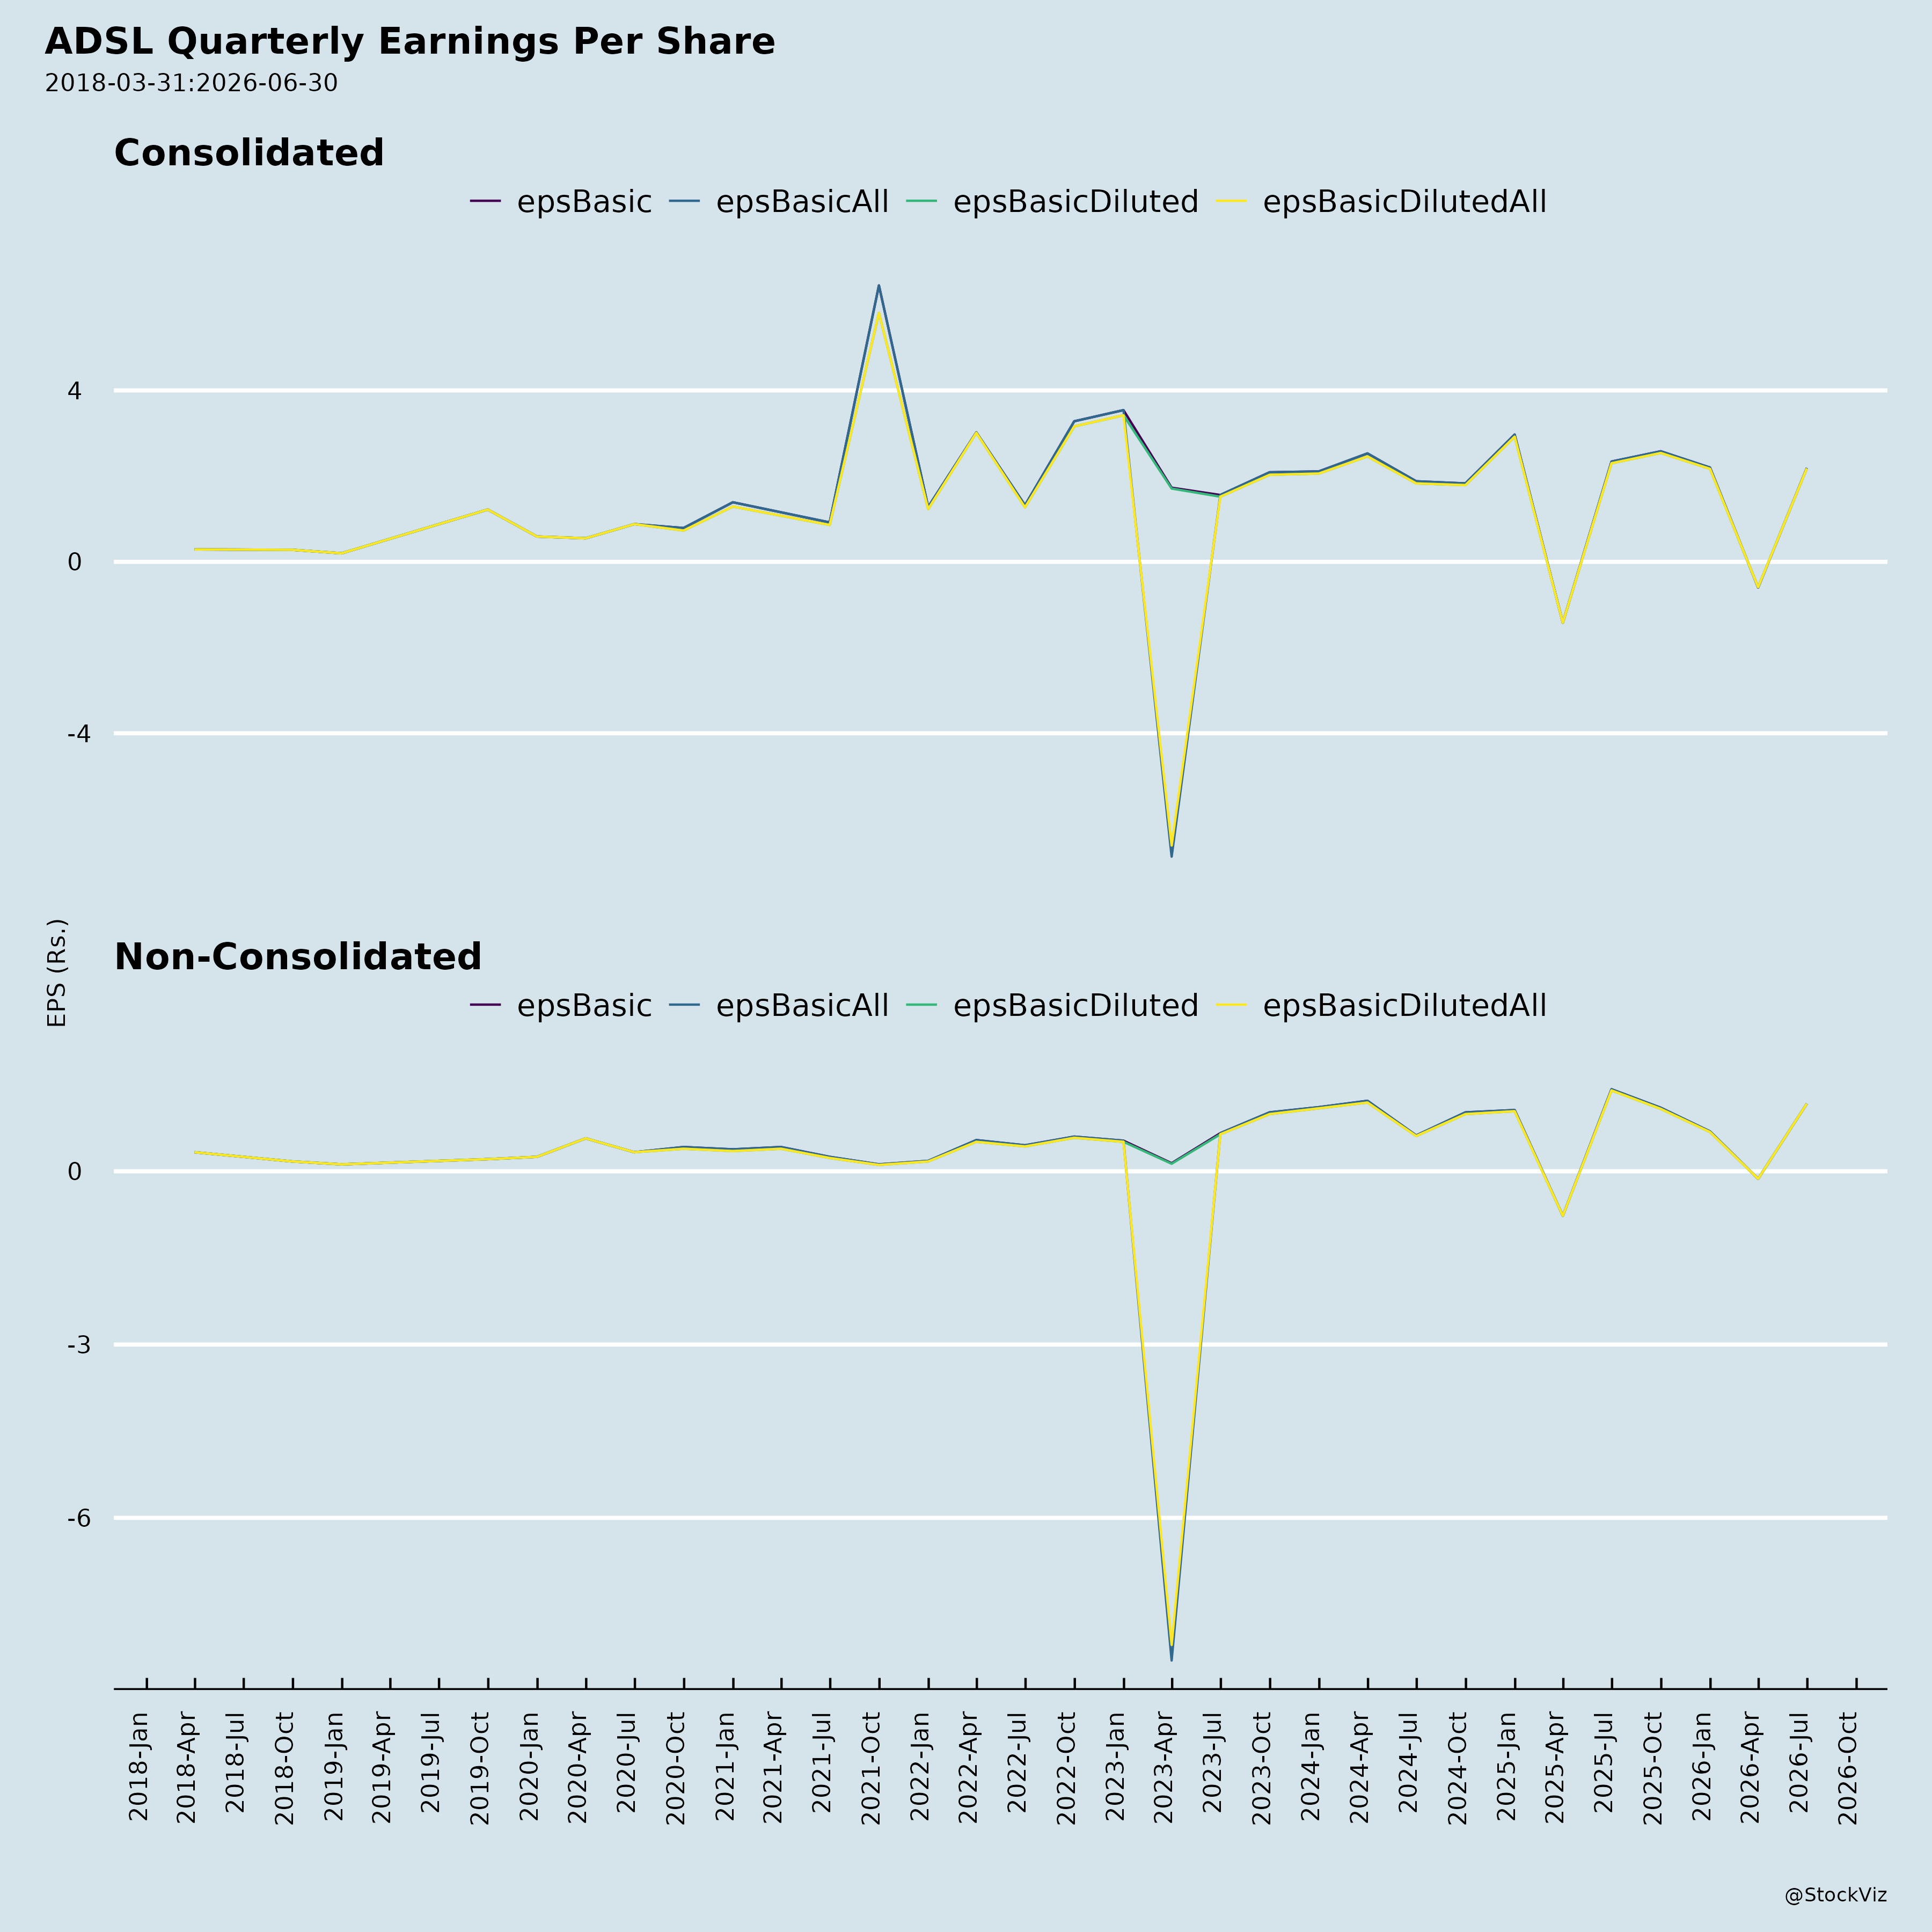
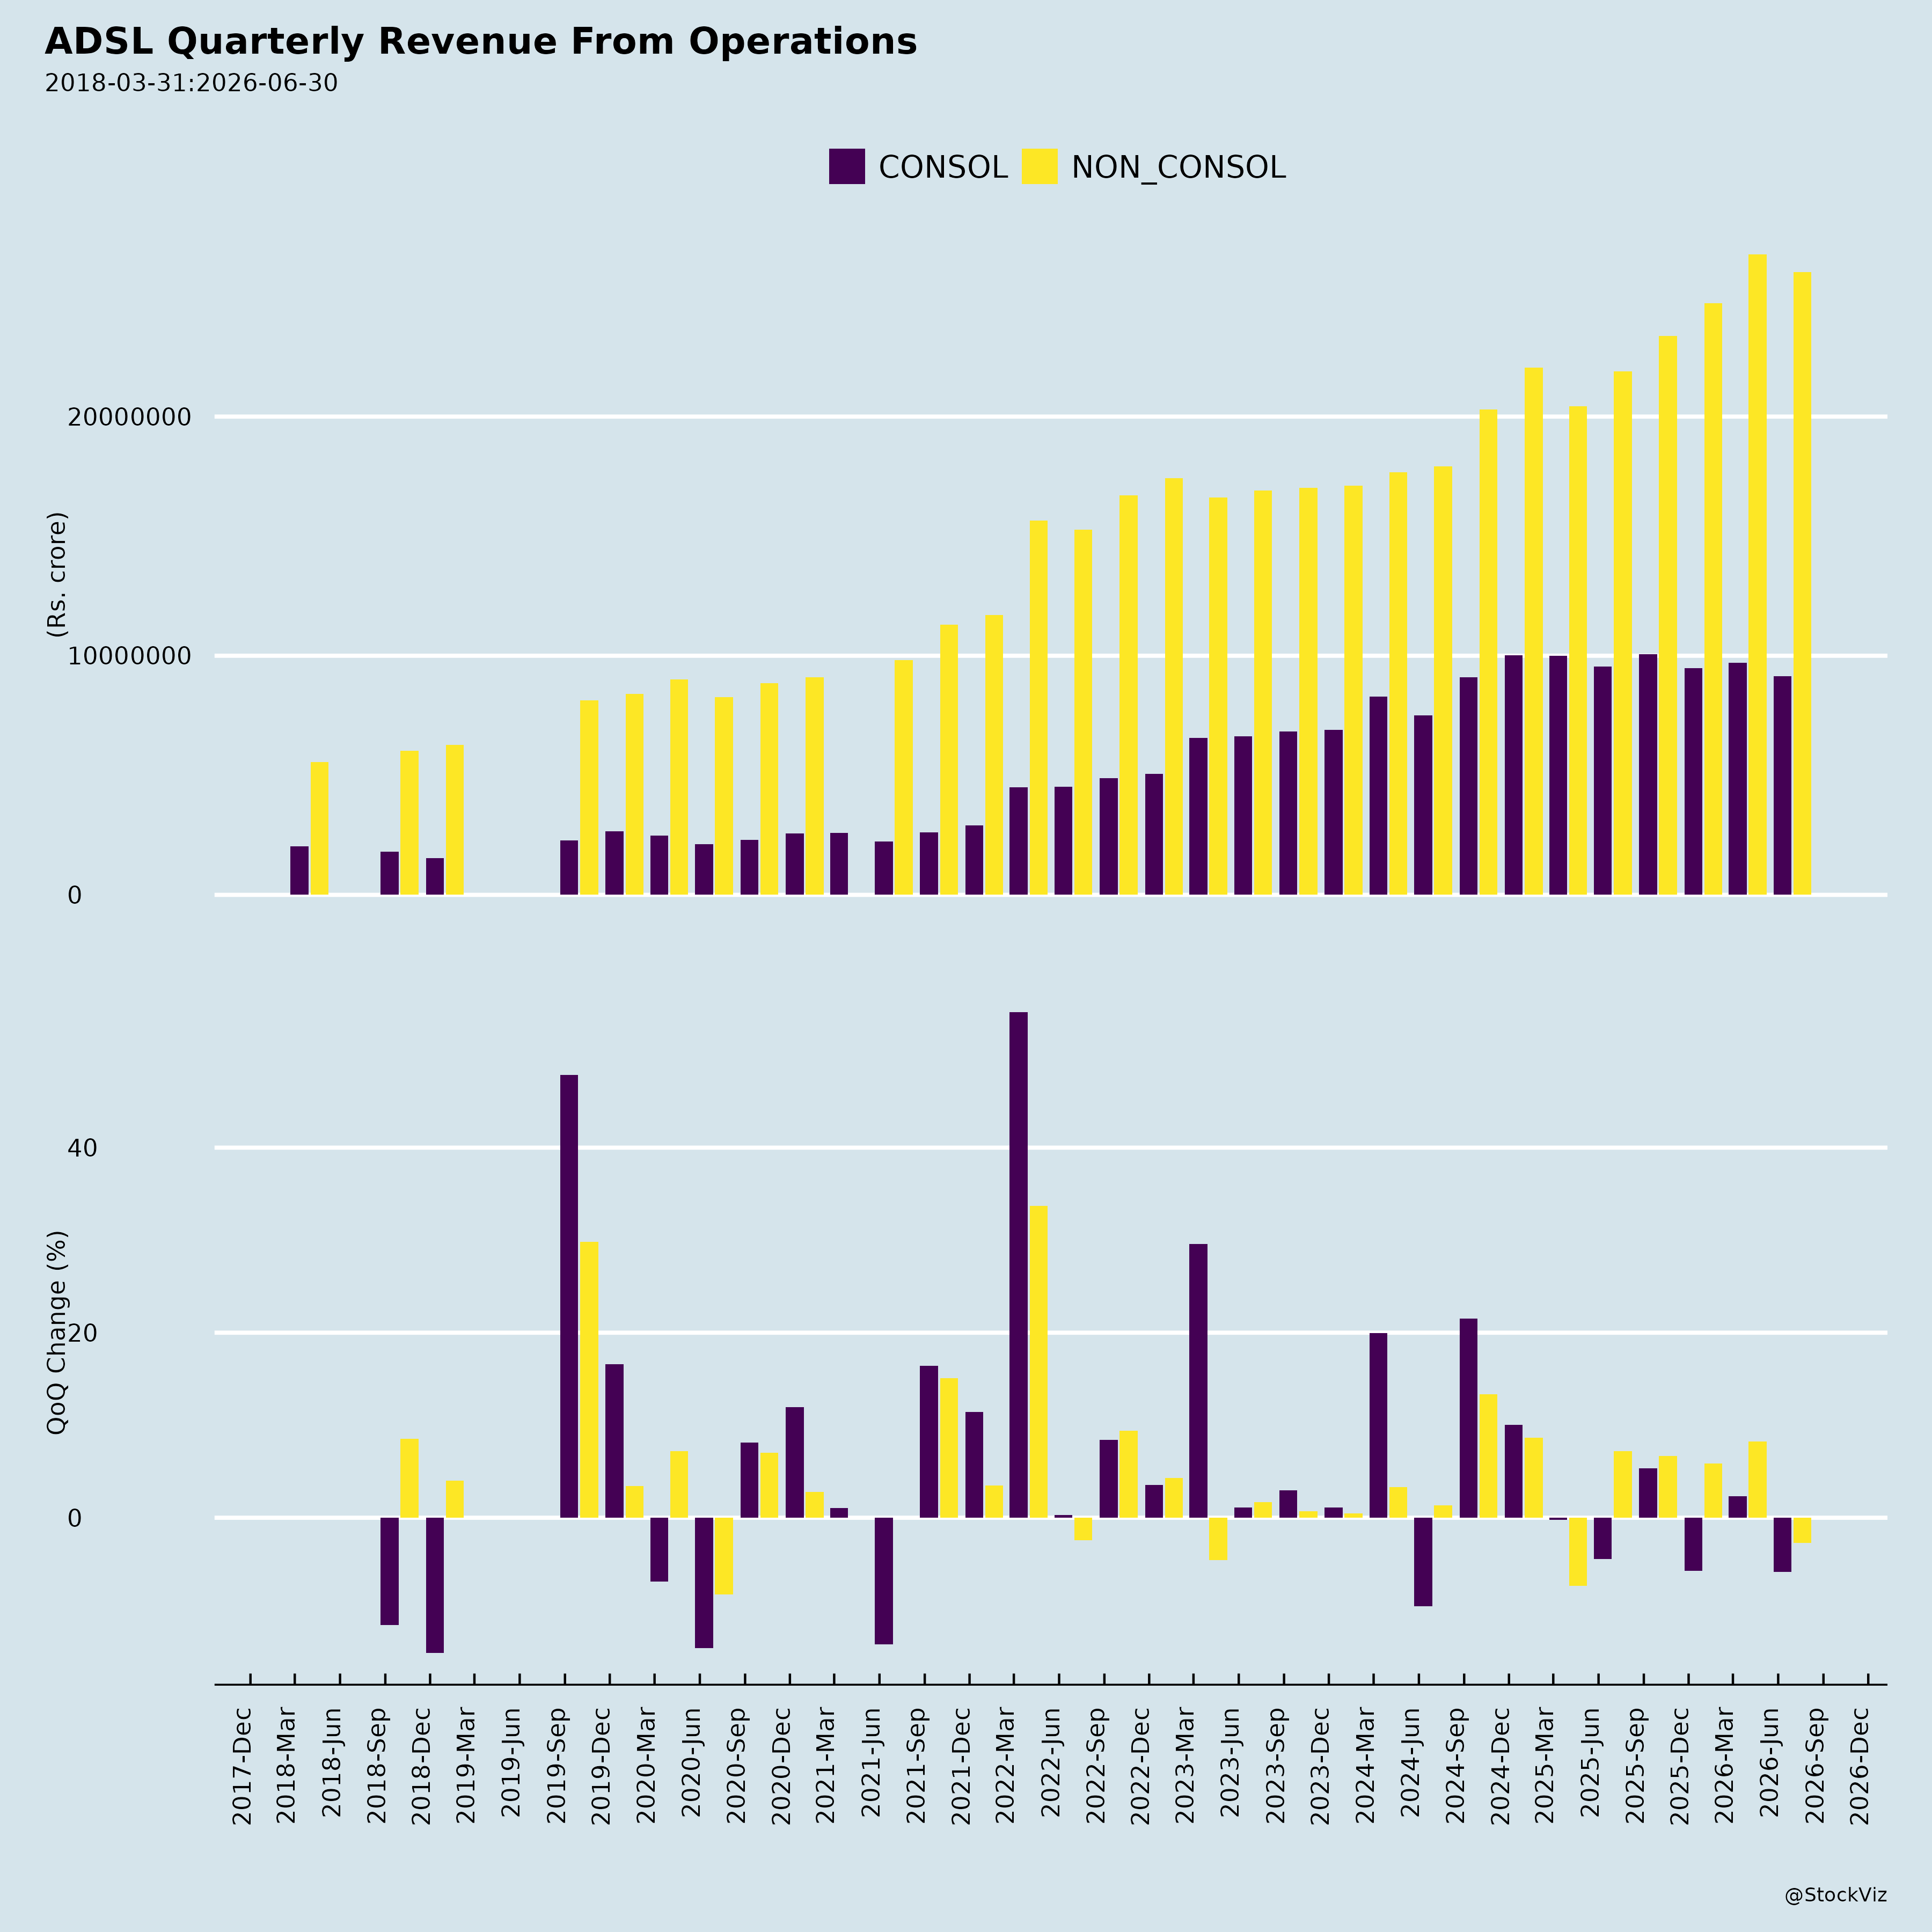
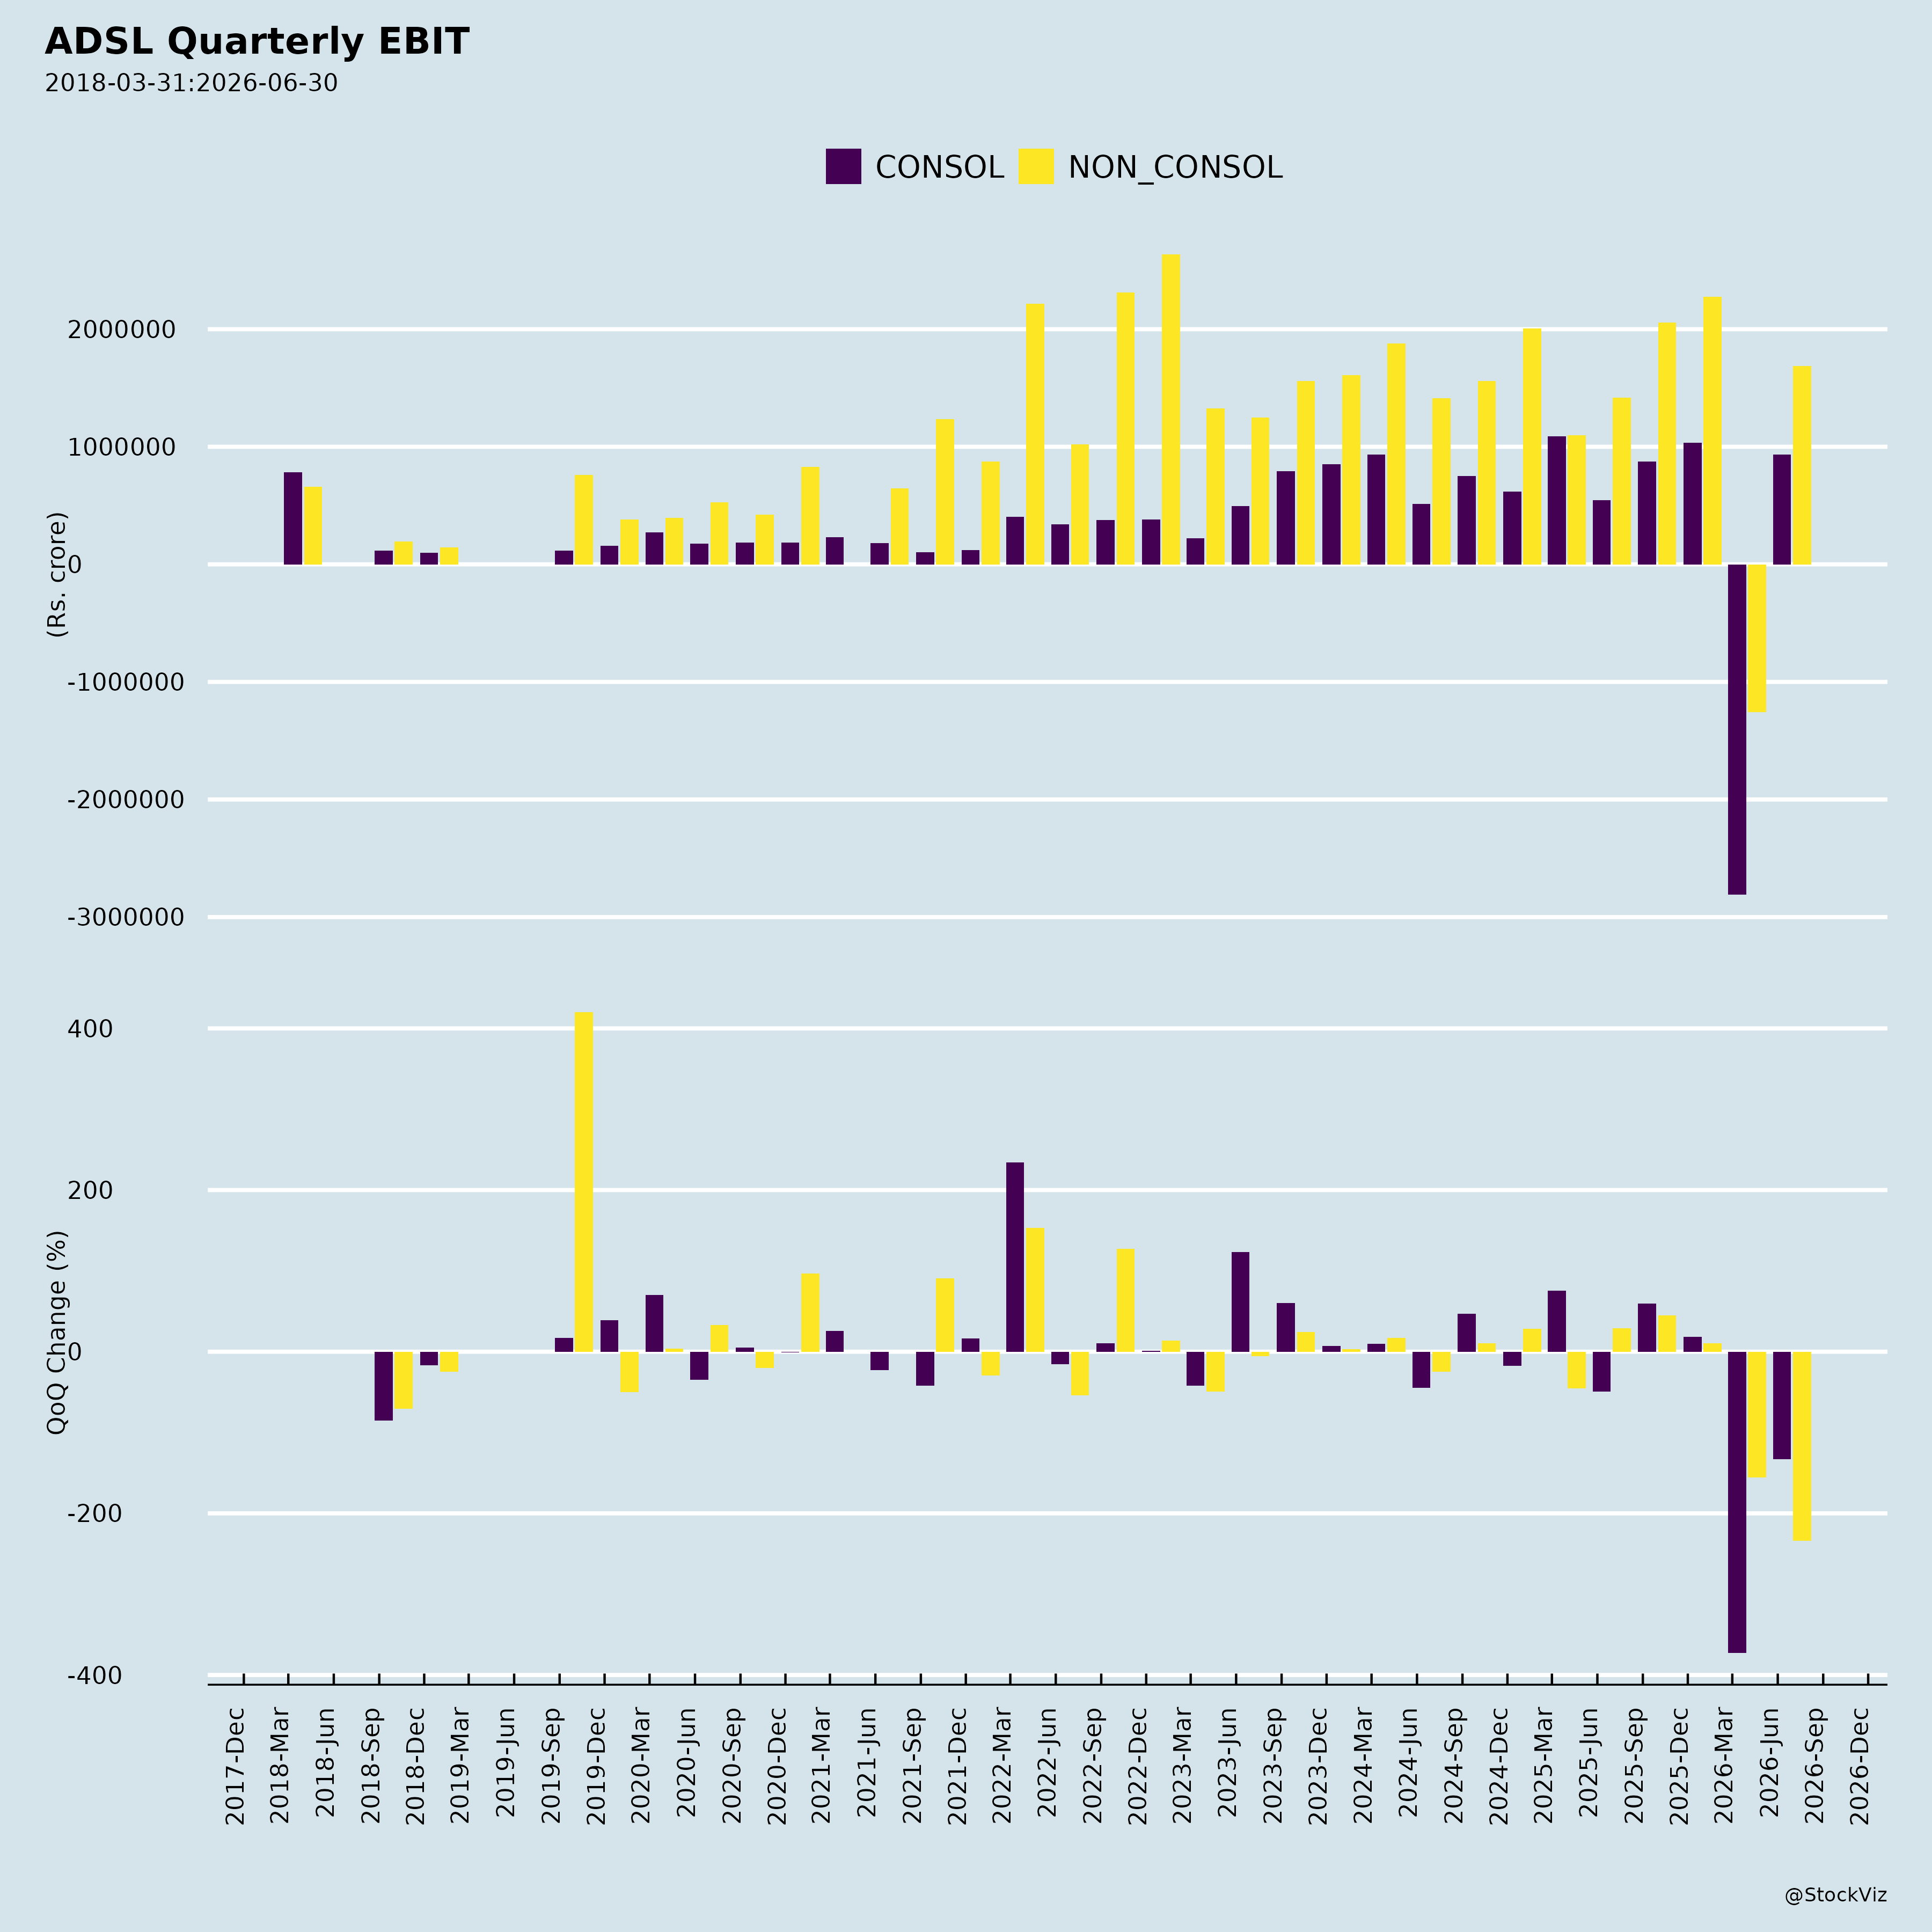
Ownership
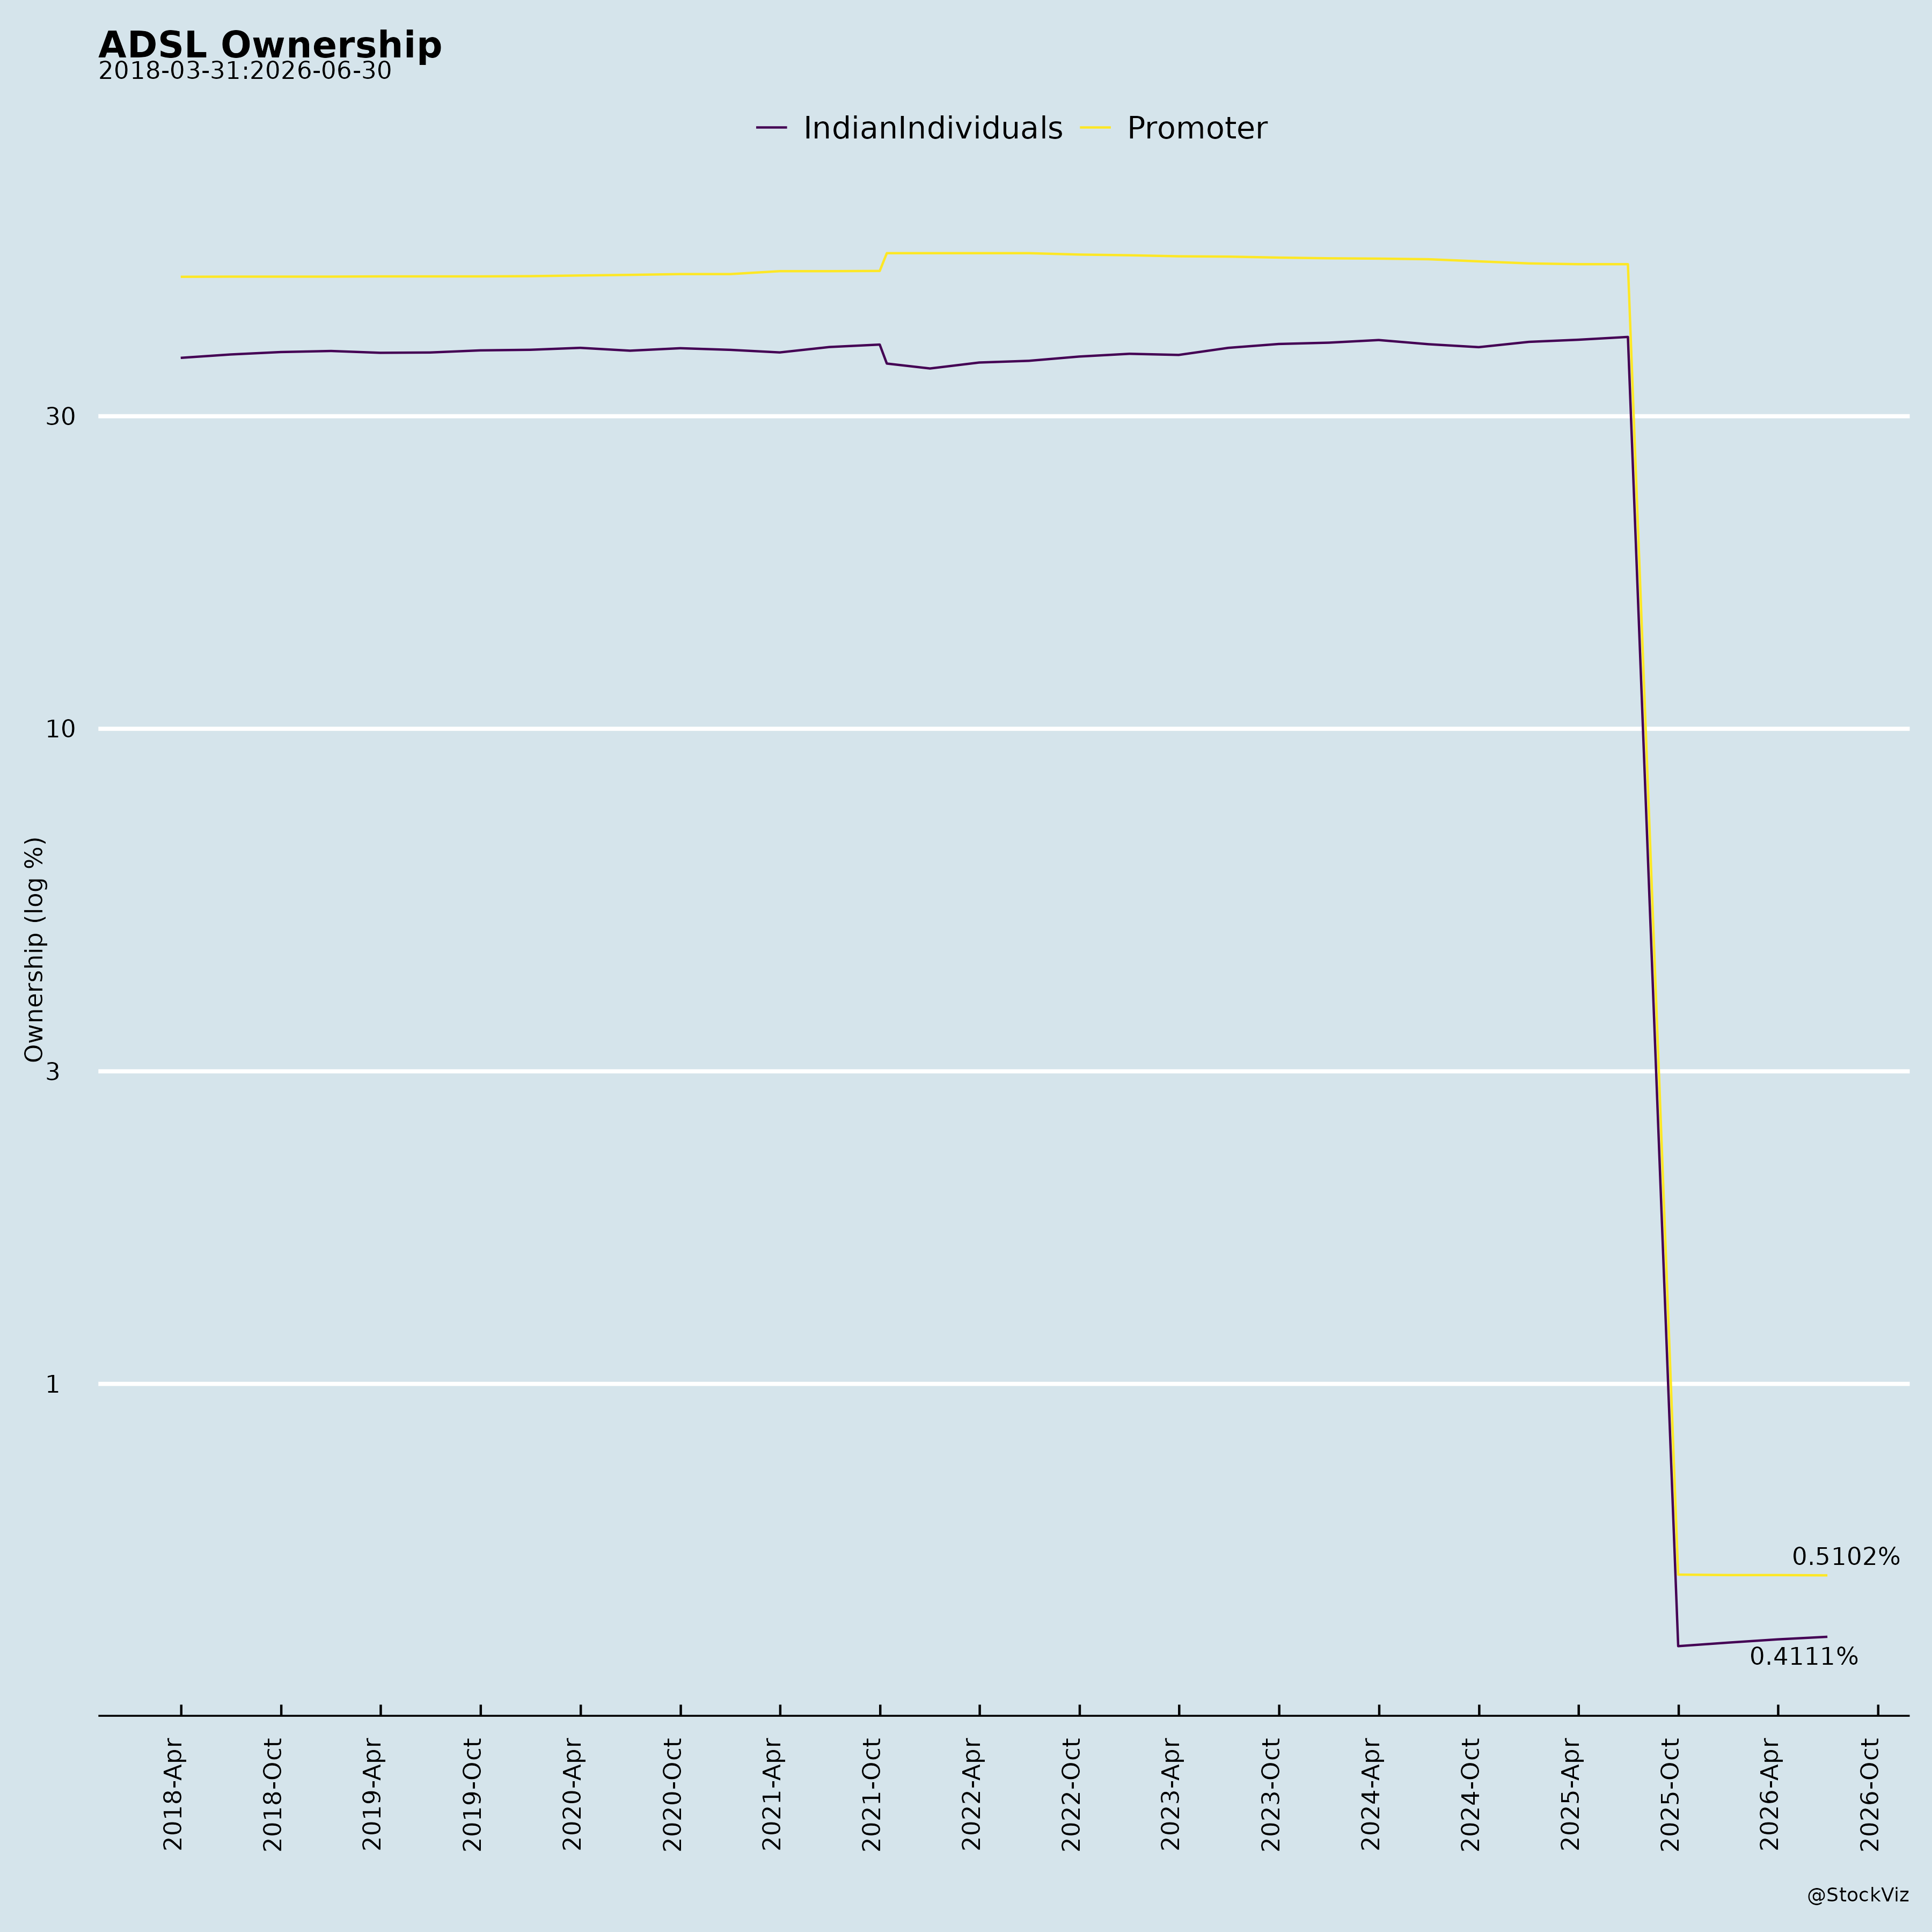
Margined
AI Summary
asof: 2026-09-18
Allied Digital Services Limited — Q1 FY27 Announcements
1. Headwinds and Challenges
- Measured customer spending. Macroeconomic and geopolitical uncertainty has made customers more measured in spending decisions. Procurement cycles have become longer and more rigorous, with greater emphasis on governance, business outcomes and return on investment. Management characterises this as a shift in the timing of decisions rather than a change in underlying demand.
- Margin pressure and competition. Management acknowledged competitive pressure in the business over the last four to eight quarters. Customers are seeking price reductions in anticipation of automation, and competitive intensity has been pronounced in the U.S. market. EBITDA margin was 10% in Q1 FY27, against 12% in Q4 FY26 and 10% in Q1 FY26.
- Cost inflation in the quarter. Employee cost reflected annual wage revisions and continued investment in talent and the leadership team. Finance costs rose modestly on higher working capital deployment as large projects moved into execution. Other income was lower, primarily due to reduced foreign exchange gains.
- India product pricing disruption. Hardware price increases tied to the war situation led the company to refrain from aggressive customer acquisition at lower margins in Q4 FY26 and Q1 FY27. In India, revenue declined 11% year-on-year in Q1 FY27 (Rs. 71 crore versus Rs. 80 crore).
- Withdrawal from railway bids. Orders in the railways worth approximately Rs. 180–200 crore were won, but product pricing rose 25–30% during the bidding phase, and the company bowed out to avoid booking losses. This contributed to caution on similar long-cycle projects.
- Government vertical decline. Government revenue fell 35% year-on-year in Q1 FY27 (Rs. 46 crore versus Rs. 71 crore) and declined 6% for FY26 (Rs. 227 crore versus Rs. 242 crore).
- Solutions segment softness. Solutions revenue declined 17% year-on-year in Q1 FY27 (Rs. 45 crore versus Rs. 54 crore).
- Taxation comparison. Q1 FY26 included a deferred tax asset recognition producing a net tax benefit of Rs. 0.3 crore, while Q1 FY27 carries a tax provision of about Rs. 4.5 crore — a swing of nearly Rs. 5 crore — which weighs on the year-on-year PAT comparison (Rs. 12 crore versus Rs. 14 crore).
- Pending regulatory matter. Conversion of an interest-free loan to equity in wholly-owned subsidiary Allied Digital Inc., USA, remains subject to a pending regulatory compliance process, though management does not expect material adverse consequences.
- Sequential revenue decline. Revenue of Rs. 260 crore in Q1 FY27 was lower than Rs. 268 crore in Q4 FY26, which management attributed in part to the top line declining quarter-over-quarter.
2. Tailwinds and Growth Prospects
- Revenue milestone. Trailing twelve-month revenue crossed Rs. 1,000 crore, reaching Rs. 1,009 crore — an aspiration articulated nearly three years earlier.
- Double-digit growth. Q1 FY27 revenue grew 19% year-on-year to Rs. 260 crore; EBITDA grew 18% to Rs. 25 crore; PBT grew 19% to about Rs. 17 crore.
- International momentum. Rest-of-world revenue grew 36% year-on-year in Q1 FY27 (Rs. 189 crore versus Rs. 139 crore) and 29% for FY26 (Rs. 652 crore versus Rs. 505 crore). Non-government revenue grew 45% year-on-year in Q1 FY27 (Rs. 214 crore versus Rs. 148 crore) and 31% for FY26.
- Services segment strength. Services revenue grew 30% year-on-year in Q1 FY27 (Rs. 215 crore versus Rs. 165 crore) and 21% for FY26.
- Order bookings. Orders of Rs. 120-plus crore were booked during the quarter across new wins and multi-year renewals, spanning workspace services, enterprise applications, managed services, digital infrastructure, IT asset management and integrated command and control solutions.
- New logos and geographies. Wins included an Enterprise Application Services engagement with an NYSE-listed electronics design and testing company (marking entry into that space in the U.S.), a workplace services engagement with an Australian customer-owned mutual bank across Melbourne, Sydney and Adelaide, a turnkey System Integration project for an Integrated Command and Control Centre with the Department of School Education, Government of Punjab, a managed services engagement with a Government of India organisation under the Ministry of Commerce, an IT asset management engagement with an international property consulting firm, and an IT infrastructure support engagement with a leading Indian FMCG company. Multiple renewals spanned pharmaceuticals, chemicals, real estate, BFSI, medical devices and retail design.
- AI as opportunity. Management views AI as an opportunity to acquire more customers and to create differentiated outcome-driven offerings, and is embedding AI across the service portfolio.
- Leadership augmentation. Nehal Shah elevated to Joint Managing Director (subject to shareholder approval at the AGM), Paresh Shah transitioned to Chief Innovation Officer, and Arun Pathak appointed CEO of Cloud & Infrastructure Services for India and the Middle East, bringing over three decades of experience.
- Governance milestone. The audit report for the quarter is unmodified with no qualifications or observations, with all matters identified in earlier periods resolved.
- Balance sheet. Net worth stood at Rs. 671 crore in FY26 versus Rs. 646 crore in FY25 and Rs. 619 crore in FY24. Gross debt was Rs. 134 crore in FY26 versus Rs. 127 crore in FY25 and Rs. 117 crore in FY24. Cash and cash equivalents were Rs. 60 crore in FY26 versus Rs. 72 crore in FY25.
- Addressable opportunity. Integrated capabilities across managed services, cloud, cybersecurity, digital infrastructure and AI-enabled operations position the company for end-to-end transformation programs, including opportunities beyond its traditional partner ecosystem.
- ESOP grant. The Nomination and Remuneration Committee approved the grant of 2,00,000 employee stock options under the ADSL Employees Stock Option Plan 2020 at an exercise price of INR 114 per option, each convertible into one fully paid-up equity share of face value INR 5.
- AGM outcome. All eight resolutions at the 32nd Annual General Meeting held on September 01, 2026, were passed with the requisite majority.
3. Key Risks
- Competitive intensity and customer-driven price deflation, particularly in the U.S. market, with margins under pressure across the industry.
- Elongated and more rigorous procurement cycles, and delayed conversion of pipeline into revenue.
- Volatility in hardware and product pricing, which affected railway bids and India product-led business.
- Concentration effects in the government vertical, which declined 35% year-on-year in Q1 FY27.
- Exposure to foreign exchange movements, with reduced FX gains lowering other income; the reclassification of funds in the U.S. subsidiary from debt to equity removes quarterly revaluation from other income, making reported earnings more reflective of operating performance.
- Higher working capital deployment and finance costs as large projects move into execution.
- Pending regulatory compliance on the loan-to-equity conversion for Allied Digital Inc., USA.
- Forward-looking statements are subject to risks and uncertainties that could cause actual results to differ materially, and the company does not undertake to update them.
4. Management Guidance Versus Observed Performance
- Growth aspiration. Management targets 10x growth over 10 years, translating to about 20% per year, with some quarters varying based on macroeconomics. Observed: Q1 FY27 revenue grew 19% year-on-year; FY26 revenue grew 20% (Rs. 968 crore versus Rs. 807 crore).
- Margin trajectory. Management stated current EBITDA margins are in the 10%–11% range and expects that in a couple of quarters, when large deals kick in, EBITDA margins could improve to 12%–13%, inclusive of AI investment. Observed: Q1 FY27 EBITDA margin was 10%, versus 12% in Q4 FY26 and 10% in Q1 FY26; FY26 margin was 11% versus 12% in FY25.
- Pipeline conversion. Management indicated that if not in Q2, then in Q3, good announcements are expected from the pipeline on hand, with OEM feedback turning positive and product prices bottoming out. Observed: Q1 FY27 revenue of Rs. 260 crore was below Q4 FY26 revenue of Rs. 268 crore.
- Margin bottoming. Management said the situation is in flux and could not specify when margin pressure would bottom out, but expects a change soon and believes the company will fare better than others in a competitive market.
- PAT comparison. Management noted the year-on-year PAT decline to Rs. 12 crore from Rs. 14 crore was influenced by the nearly Rs. 5 crore higher tax outgo, highlighting underlying improvement in operating profitability.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.