ACMESOLAR
Equity Metrics
November 18, 2026
Acme Solar Holdings Limited
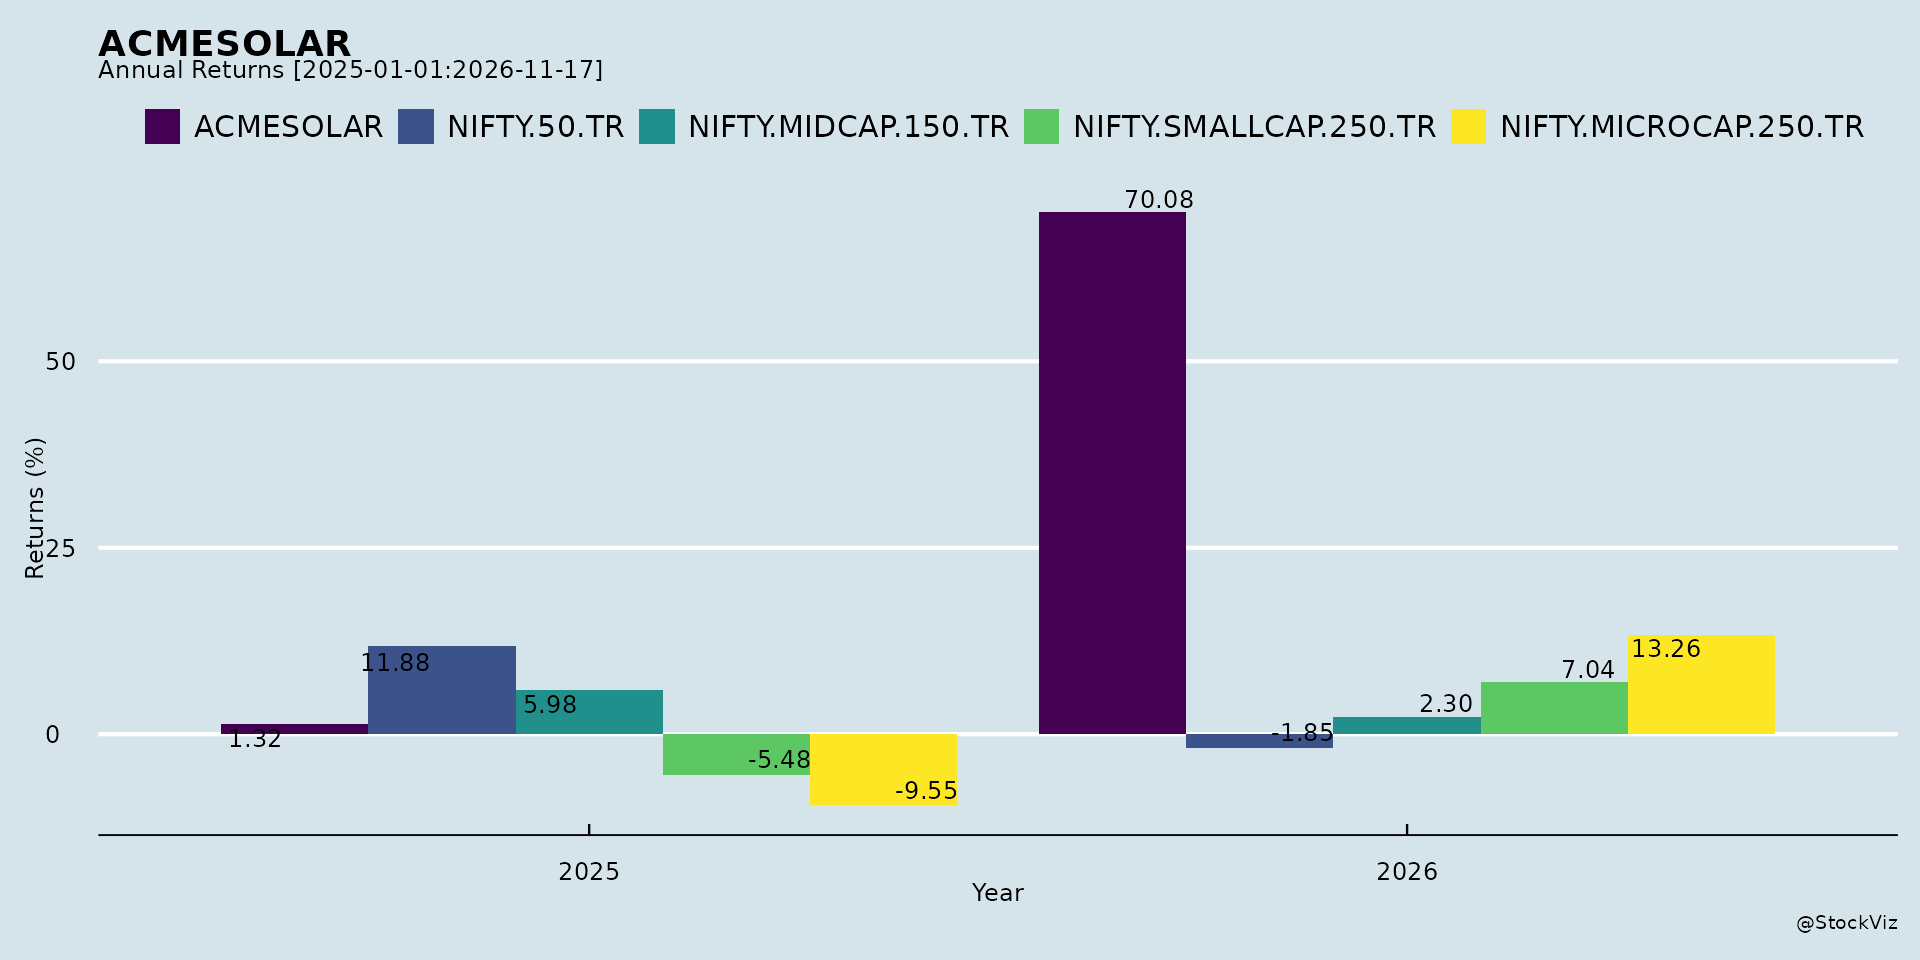
Annual Returns

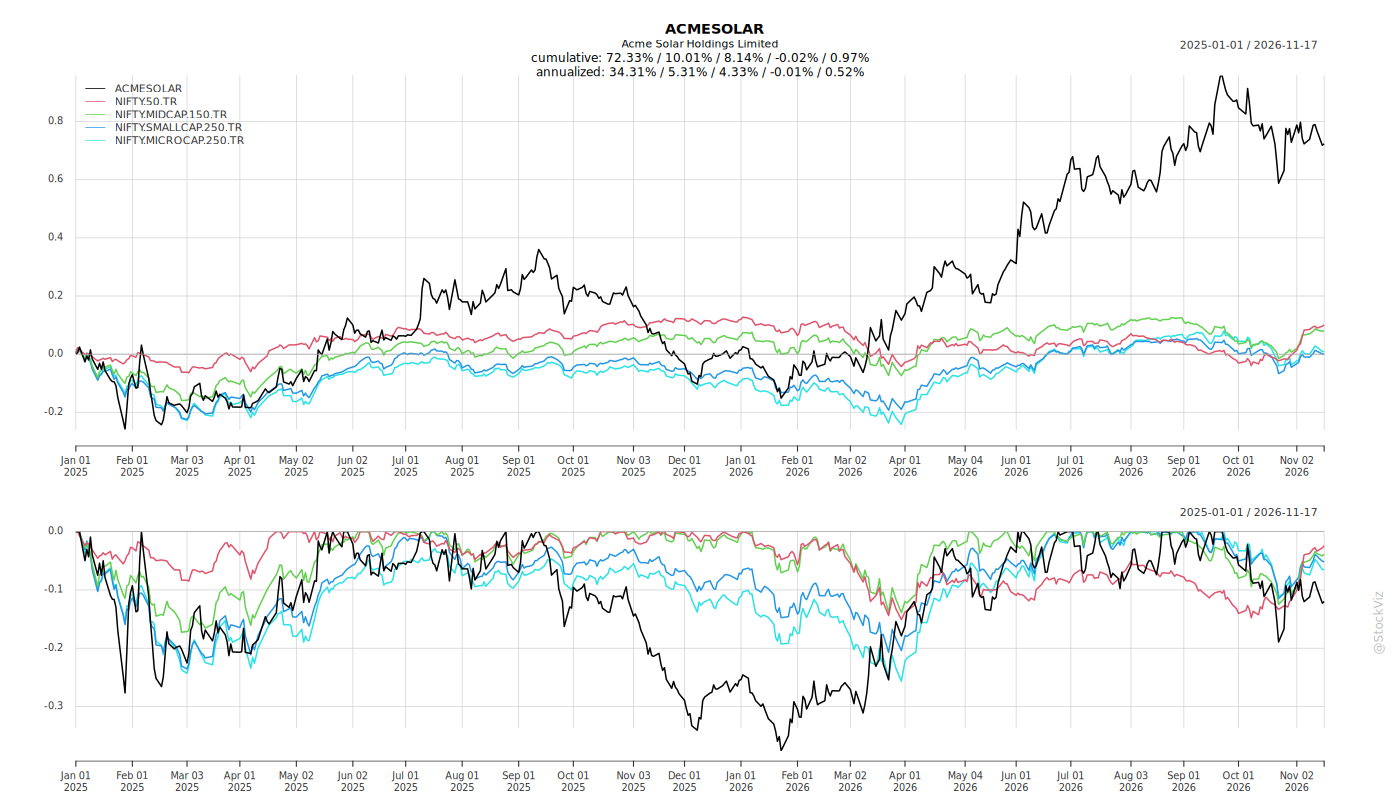
Cumulative Returns and Drawdowns
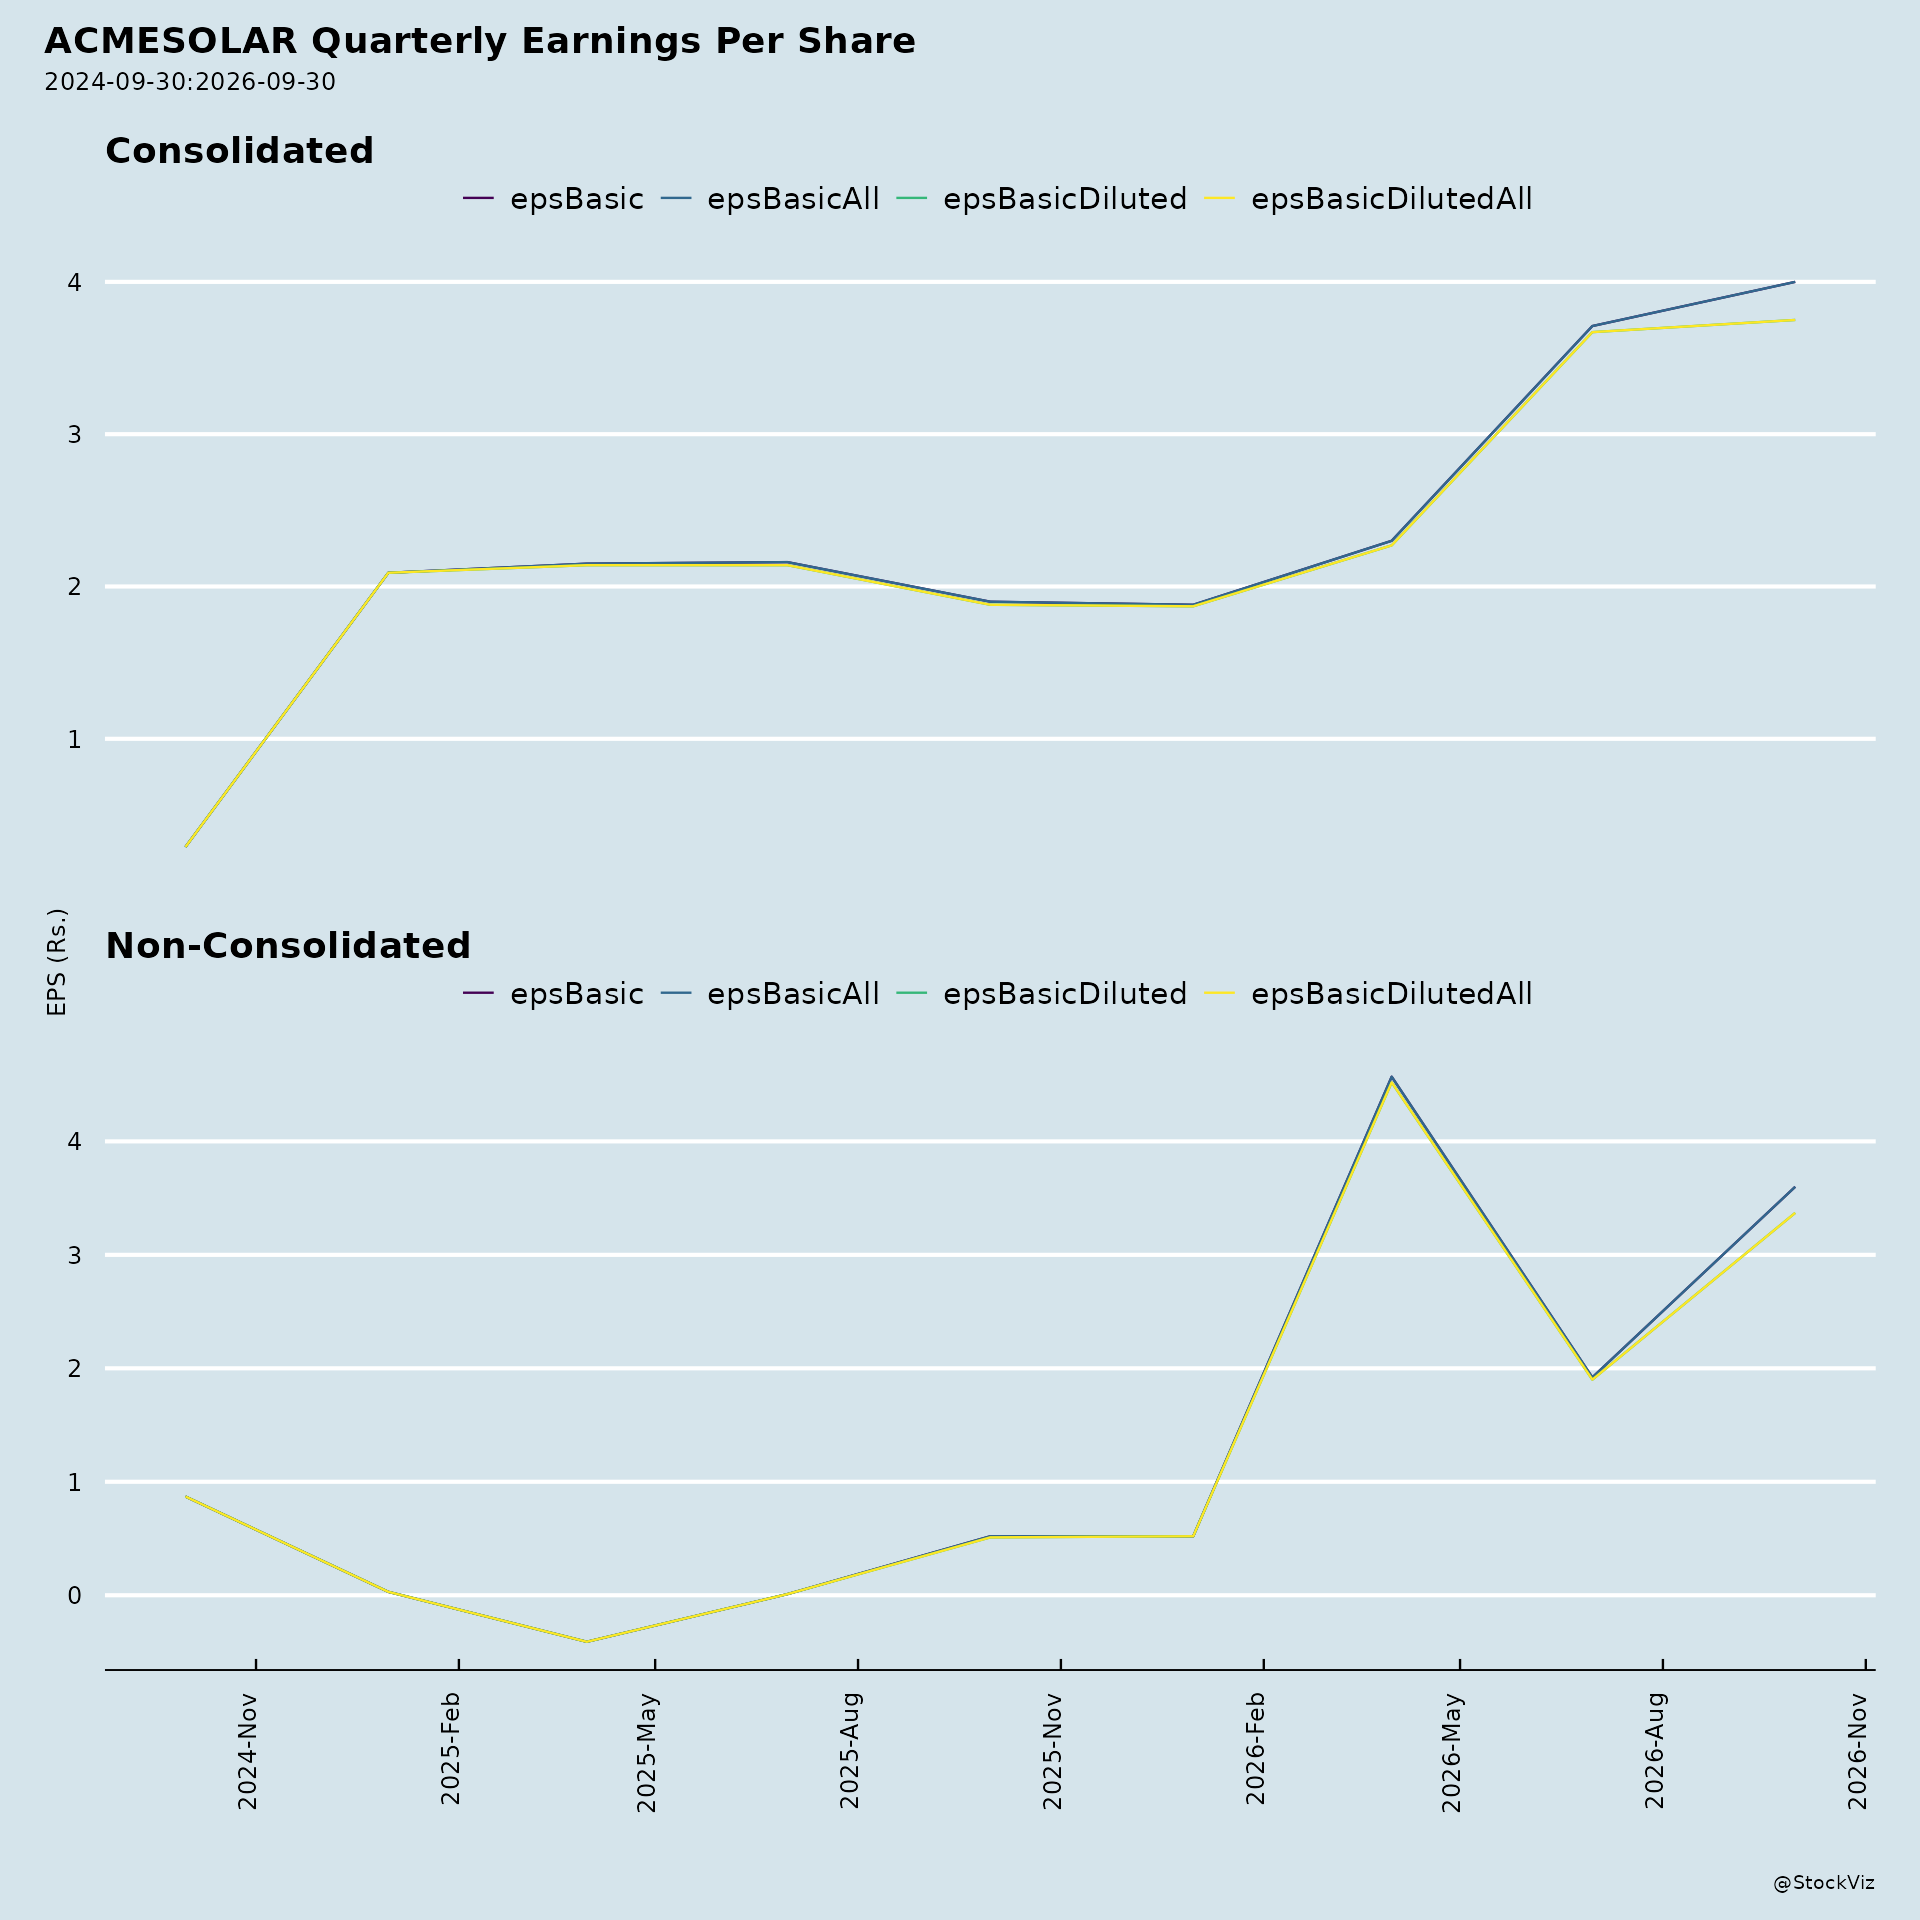
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
ACMESOLAR: Recent Corporate Developments
1. Headwinds and Challenges
- Supply chain and currency exposure: The company depends on global supply chains for cells, turbines, and batteries, and is exposed to adverse currency movements.
- Transmission and evacuation constraints: Non-availability of infrastructure or delays in transmission readiness can cause project delays and revenue loss.
- Project execution risk: Cost escalations and delays are identified risks.
- Capital access risk: Access to capital is flagged as a material risk.
- Cybersecurity and data risk, alongside talent retention risk, are also identified.
- Market competition is a stated material risk.
2. Tailwinds and Growth Prospects
- Policy tailwind: India’s non-fossil fuel capacity target of 500 GW by 2030.
- Demand shift: Increasing demand for Hybrid, FDRE, and Round-the-Clock (RTC) renewable energy.
- Storage economics: Growing commercial viability of Battery Energy Storage Systems (BESS), and expanding opportunities from widening peak and off-peak tariff differentials.
- Investment climate: Rising investments across renewable generation, storage, and transmission infrastructure.
- New business direction: The company is altering its Memorandum of Association Object Clause to expand into generating, storing, transmitting, distributing, and trading electricity from any permitted source or technology, and into data centers, data-centre parks, colocation facilities, cloud infrastructure, and related digital and computing facilities.
- New wins and milestones:
- A Letter of Award from SECI for 300 MW contracted capacity under SECI’s 6,000 MWh Assured Peak Power Tender (FDRE-IX), at a tariff of Rs. 6.00 per kWh, with a project tenure of 25 years from the Scheduled Commencement of Supply Date (SCSD), which is 18 months from PPA signing.
- Commissioning of Phase-I of the first hybrid project: 66.68 MW solar (of 300 MW) at Kelan Village, Bikaner, Rajasthan, tied to an NTPC Limited PPA and PFC project finance.
- Commissioning of Phase-I of the BESS component: 53.63 MW / 300 MWh (of 300 MW / 1,581 MWh), tied to an SJVN Limited PPA and REC project finance, on September 16, 2026.
- These milestones take operational renewable energy capacity to approximately 3,057 MW and operational BESS capacity to 4.16 GWh.
- A diversified contracted portfolio of 8,370 MW spanning solar, wind, storage, FDRE, and hybrid solutions.
- International platform: Approval to incorporate a wholly-owned subsidiary, ACME Renewables FZCO (or as finalized), in the United Arab Emirates with initial capital equivalent to AED 10,000, to support procurement, supply chain management, project support, and ancillary functions including hedging of raw materials such as lithium carbonate and polysilicon available in international markets.
3. Key Risks
- Market competition.
- Supply chain and currency risks.
- Transmission and evacuation risks.
- Capital access risk.
- Project execution risk (cost escalations and delays).
- Cybersecurity and data risk.
- Talent retention risk.
4. Management Guidance vs. Observed Business Performance
- Capacity guidance: Management guides toward 10 GW of operational renewable energy capacity and 25 GWh of BESS capacity by 2030, with ~1.5 GW execution planned by FY 2027, and an upgrade of BESS operationalisation guidance to 10 GWh by FY 2027.
- Observed performance: Operational renewable energy capacity stands at approximately 3,057 MW, and operational BESS capacity at 4.16 GWh, following the September 16, 2026 commissioning milestones.
- Project-level guidance: Management expects to commission the entire 300 MW solar capacity for the first hybrid project by the end of Q3 FY27, and the entire BESS capacity for the FDRE project by Q3 of the current fiscal. Phase-I of both components has been commissioned.
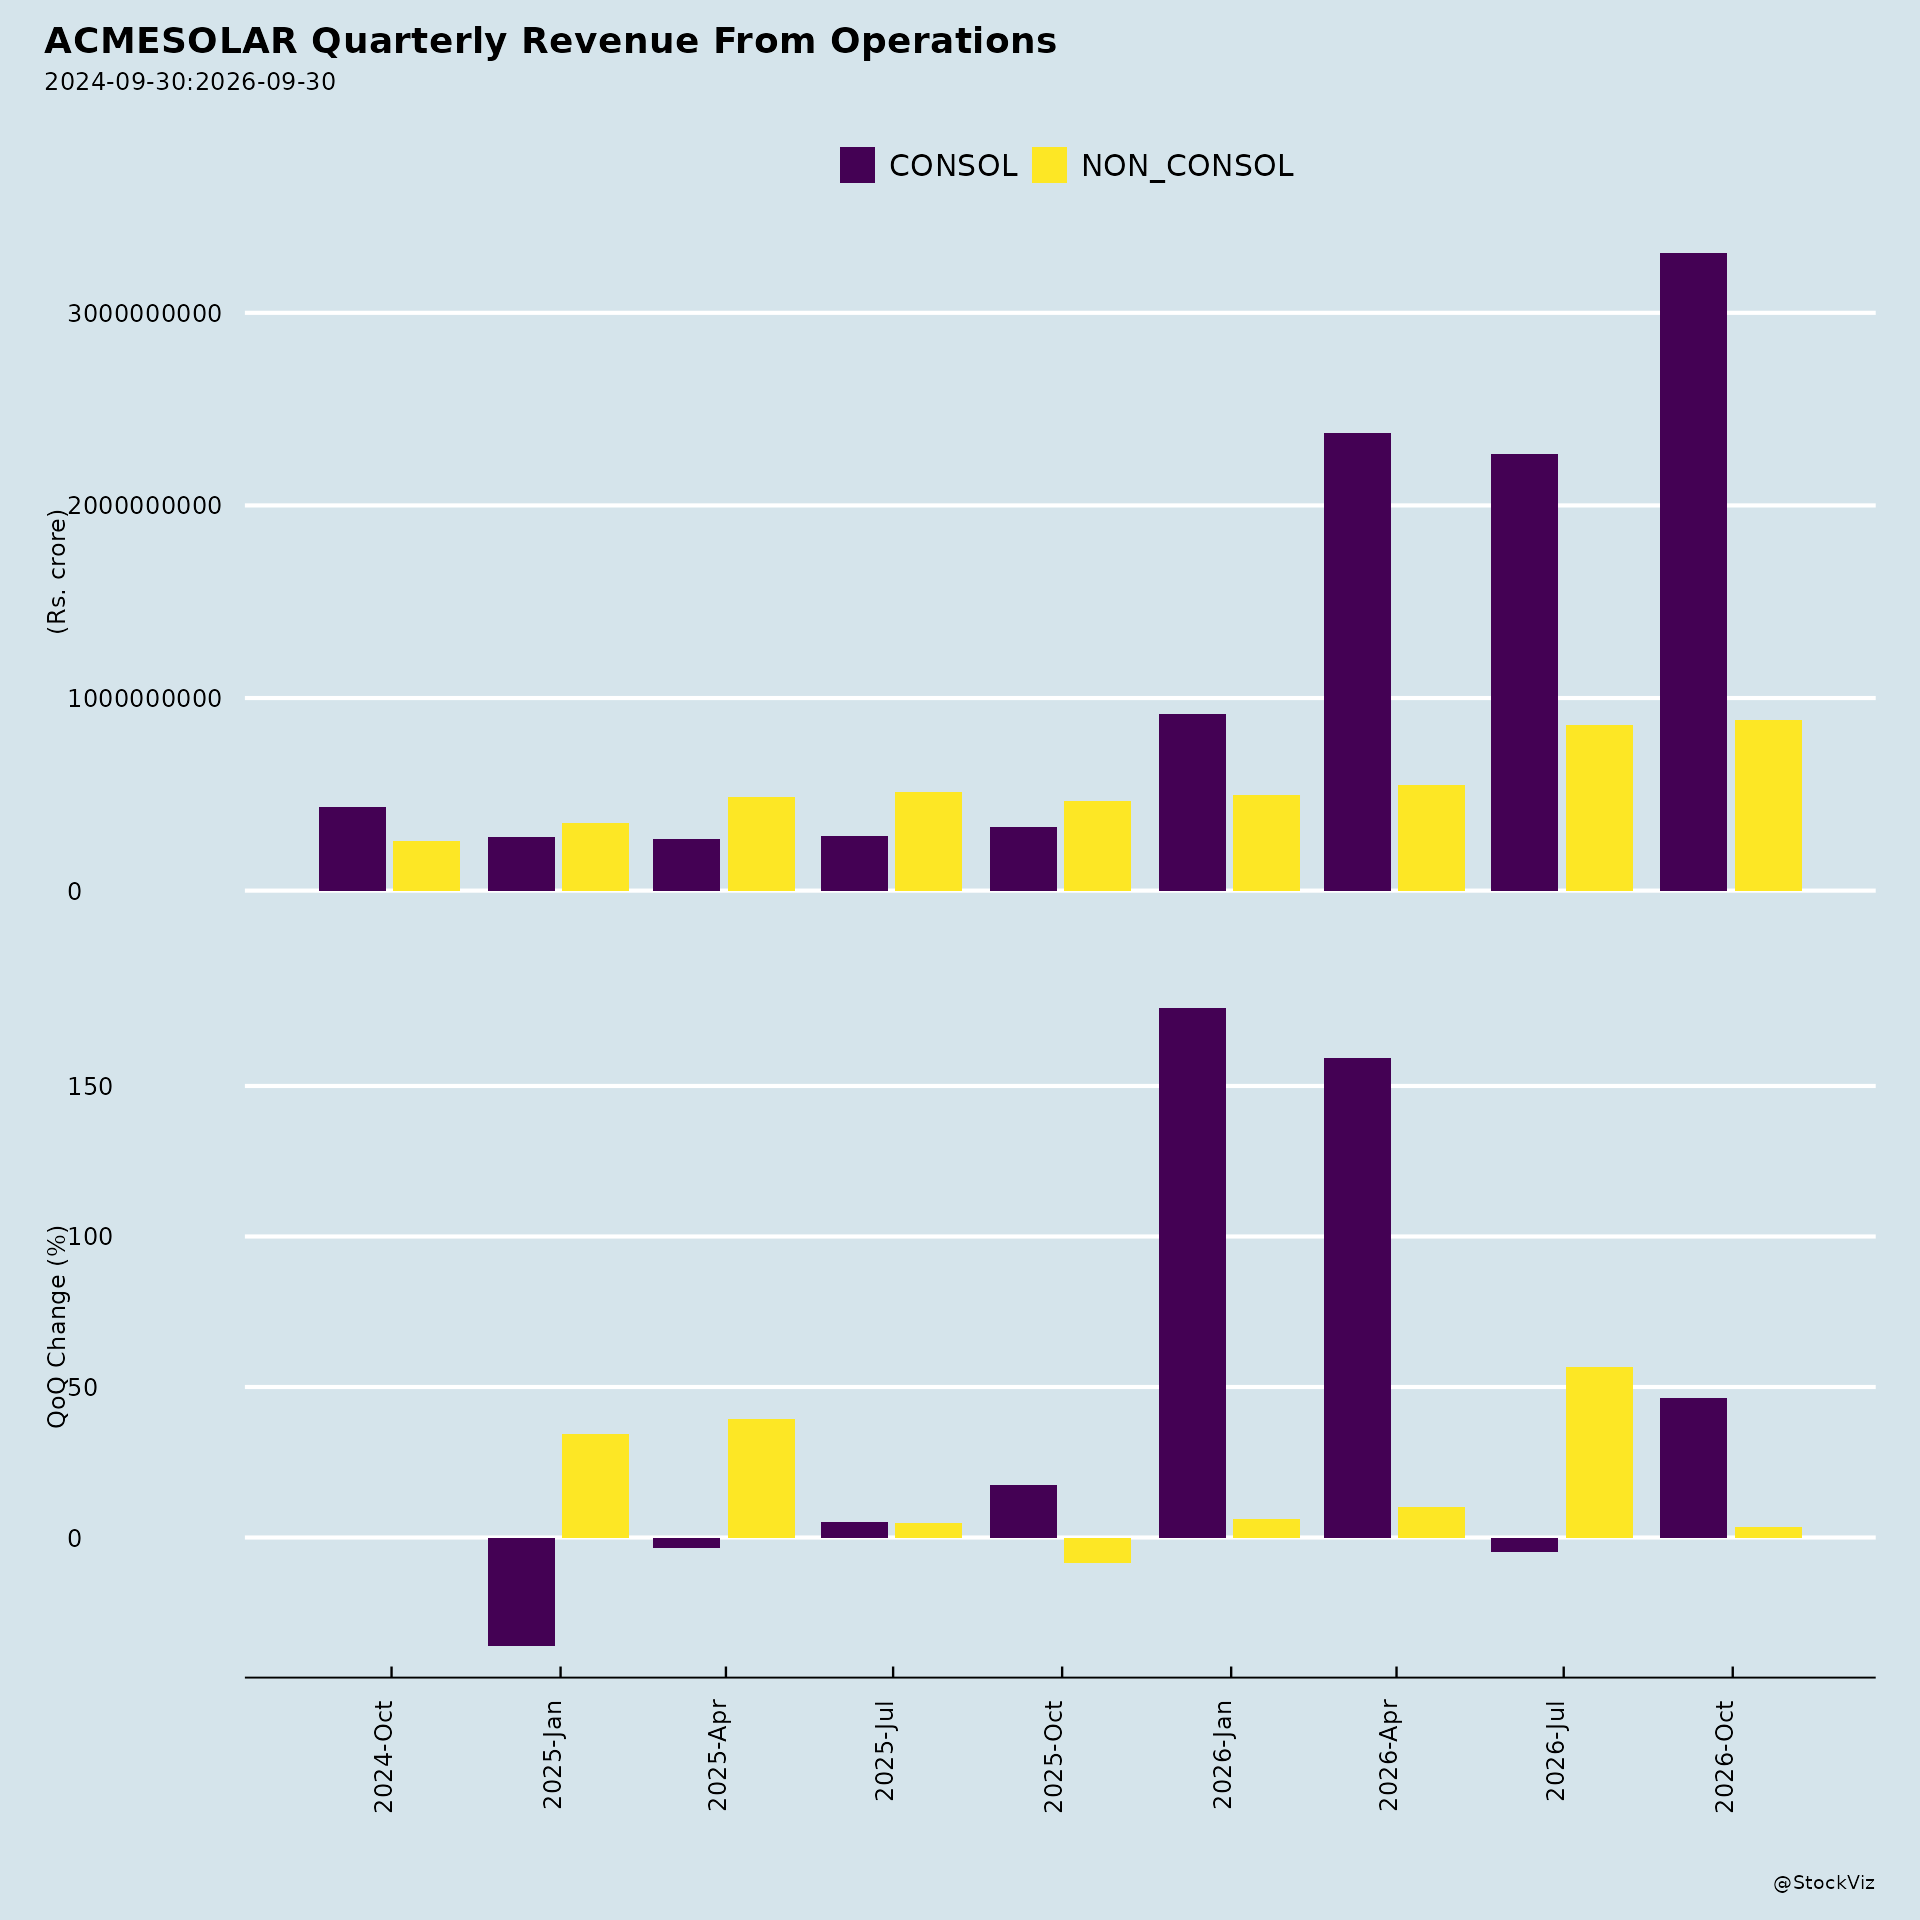
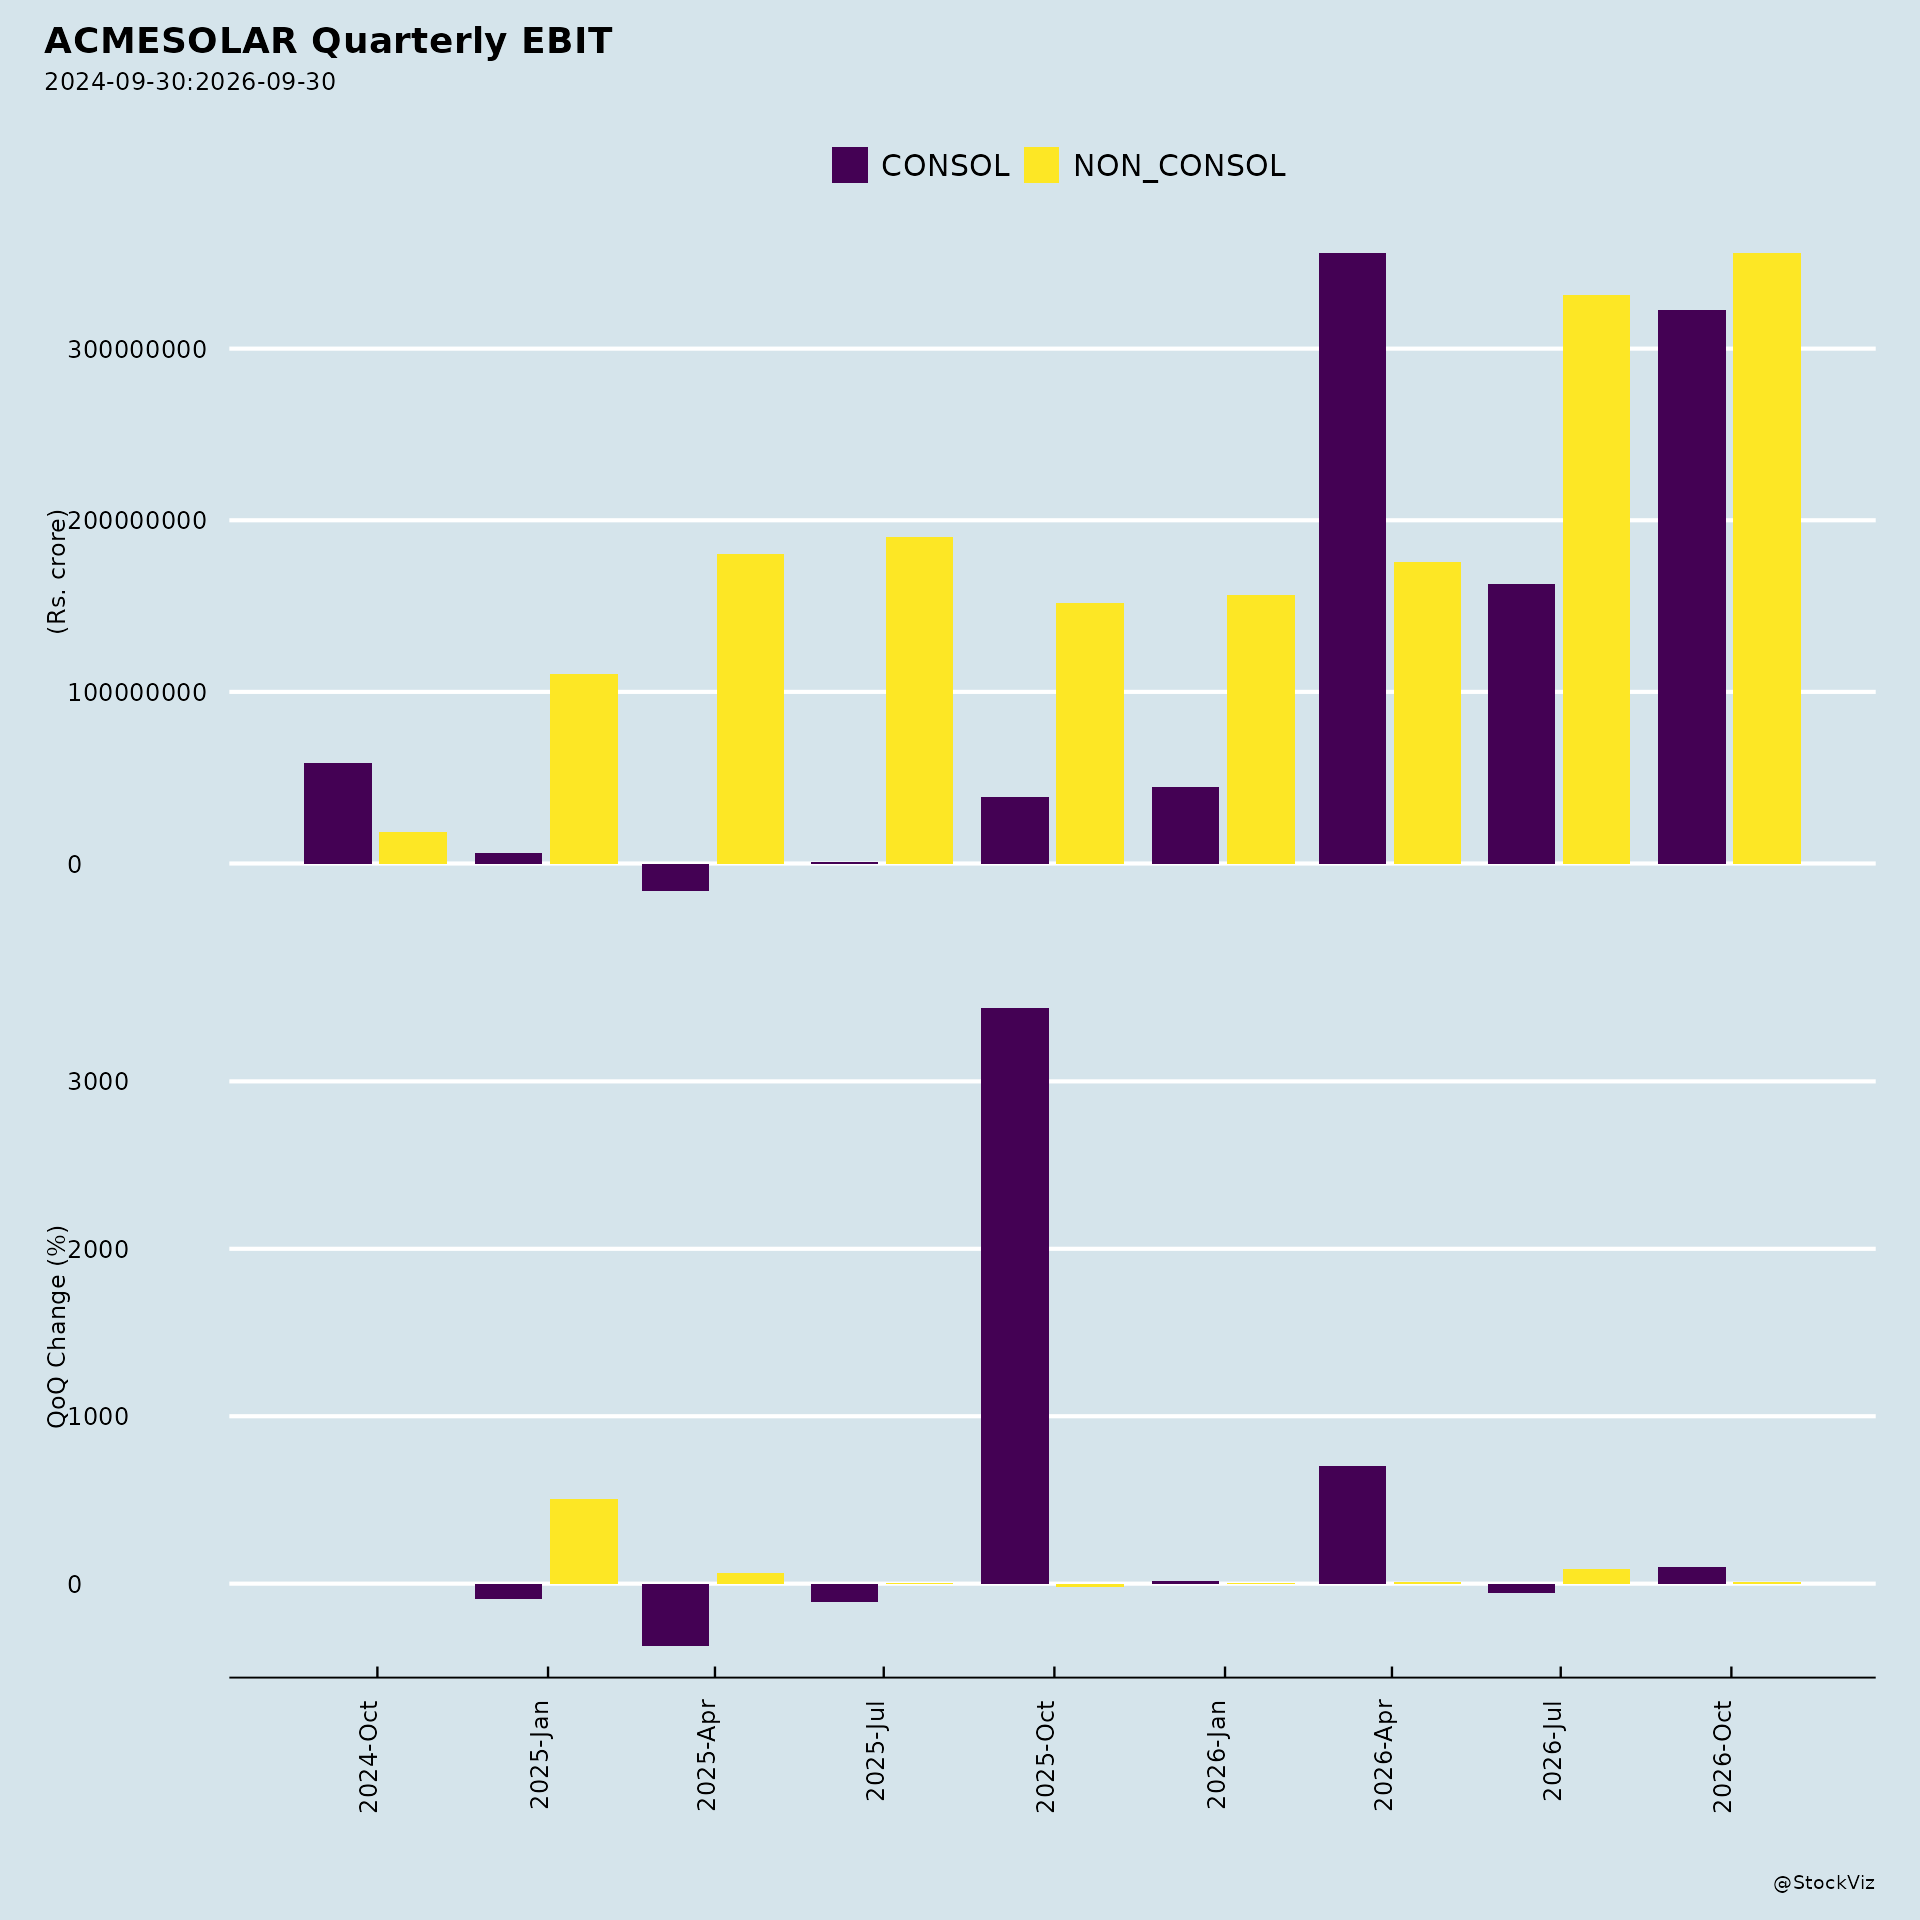
- Financial reference points: Total income of INR 25,071 million, EBITDA of INR 22,650 million (90.3% margin), PAT of INR 4,979 million, and credit ratings reaffirmed at CRISIL and ICRA AA- (Stable).
- Contracted portfolio: Total contracted portfolio capacity of 8,070 MW including 20 GWh BESS, against operational capacity of 2,982 MW plus 3.6 GWh BESS at the time of that disclosure; a later disclosure cites a diversified contracted portfolio of 8,370 MW.
- Governance and disclosure: The Board recommended appointing M/s. BSR & Co. LLP as Joint Statutory Auditors for a five-year term from the conclusion of the 11th AGM until the 16th AGM, replacing retiring auditors M/s. Walker Chandiok & Co. LLP. The 11th AGM is scheduled for Tuesday, September 29, 2026. An earnings call on Q1 FY27 results was held on July 30, 2026, and company officials will participate in an investor/analyst interaction on September 21, 2026 for the MS Energy Security & Powering AI Field Trip in Delhi, with the schedule subject to change and no unpublished price-sensitive information to be disclosed.
Broker Narrative
The narrative shifted from a solar/wind-centric execution story weighed down by high leverage and specific commissioning delays to a BESS-led growth story with rising contracted EBITDA, while execution risk persisted from project-level slippage to broader under-construction and evacuation concerns. Early leverage and capex funding worries receded as BESS capacity scaled and locked-in EBITDA rose, but commissioning timelines remained a recurring weakness.
Fears that came true
- Commissioning delays for the 350MW Sikar Solar and 50MW Pokhran wind projects recurred as broader delays in execution of under-construction capacity, matching the recent period’s disappointing actual returns versus targets.
- Execution risk on the large project pipeline materialized as ongoing under-construction delays, undermining commissioning timelines and contributing to sub-par stock performance in the latest reports.
Optimism that failed
- The optimism around timely commissioning of 450MW in FY26 and 1.9GW in FY27 failed as the latest flagged delays in under-construction execution and potential evacuation infrastructure slippage.
- The expectation that lower battery and solar module prices would ease execution and improve net debt was offset by operational underperformance of BESS projects flagged in the last report.
Broker Timeline
13 broker calls · 2025-06-30 to 2026-10-30
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.