ABCAPITAL
Equity Metrics
November 18, 2026
Aditya Birla Capital Limited
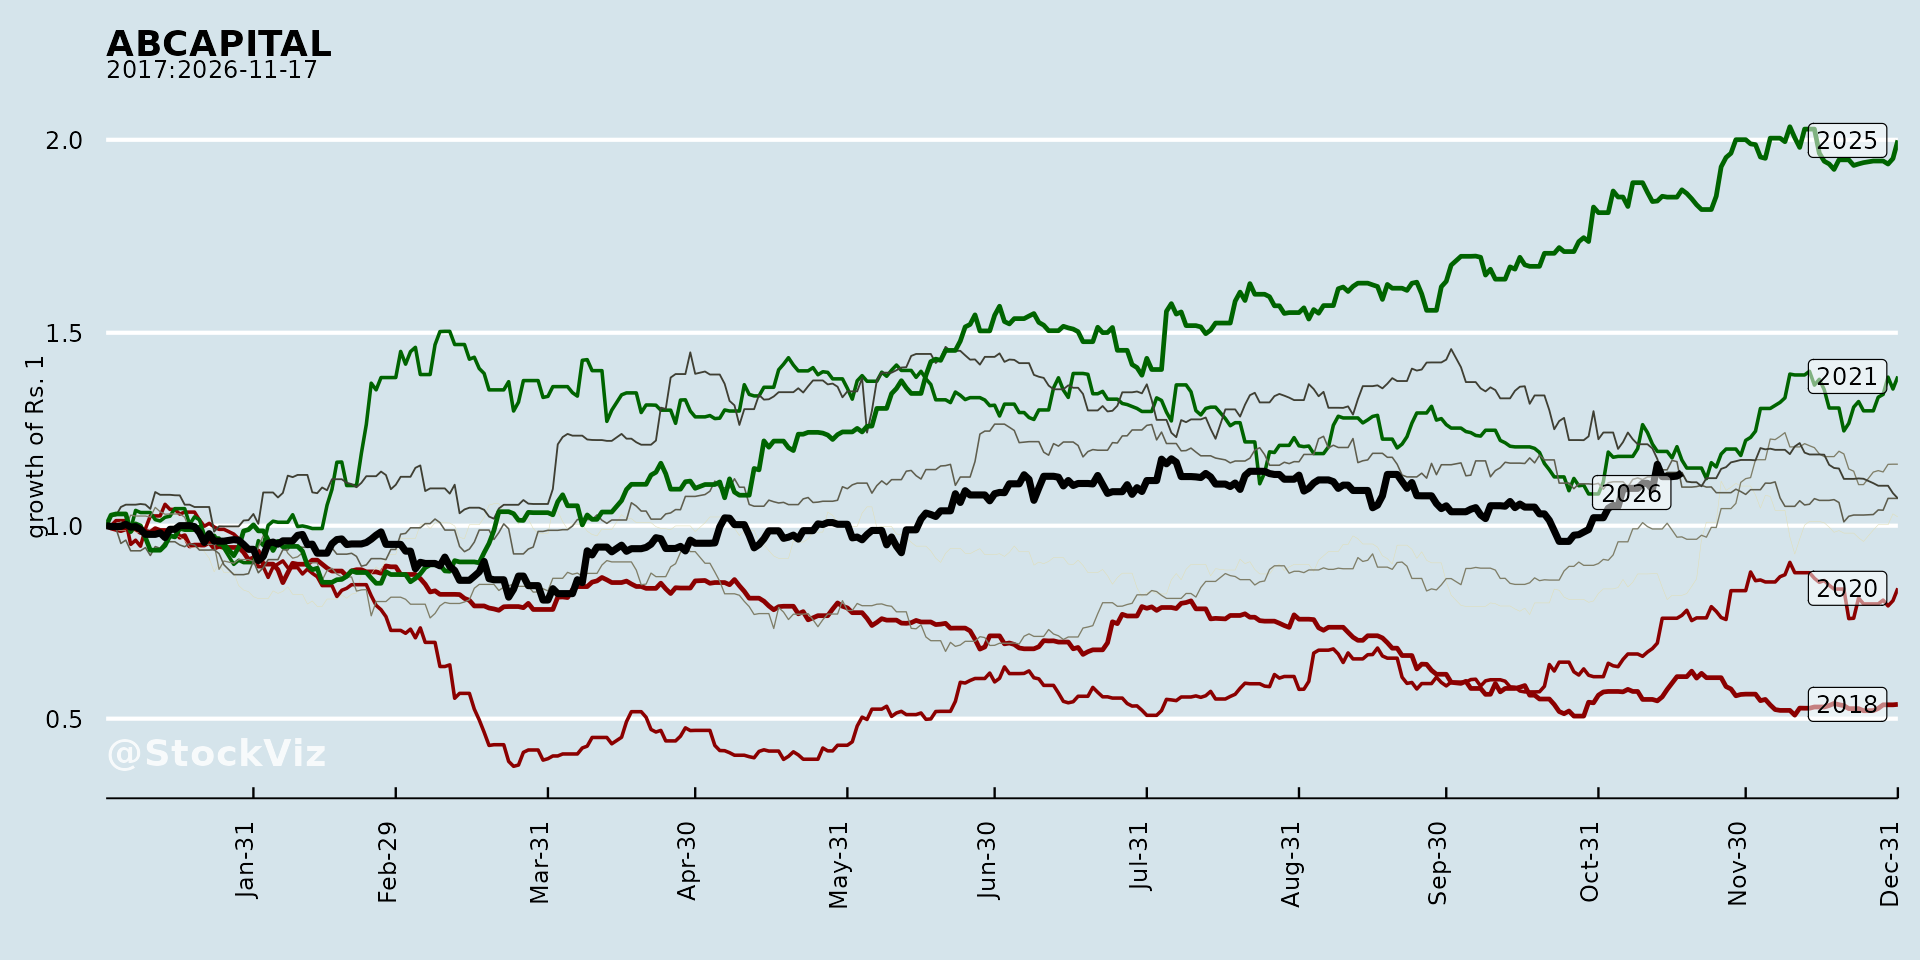
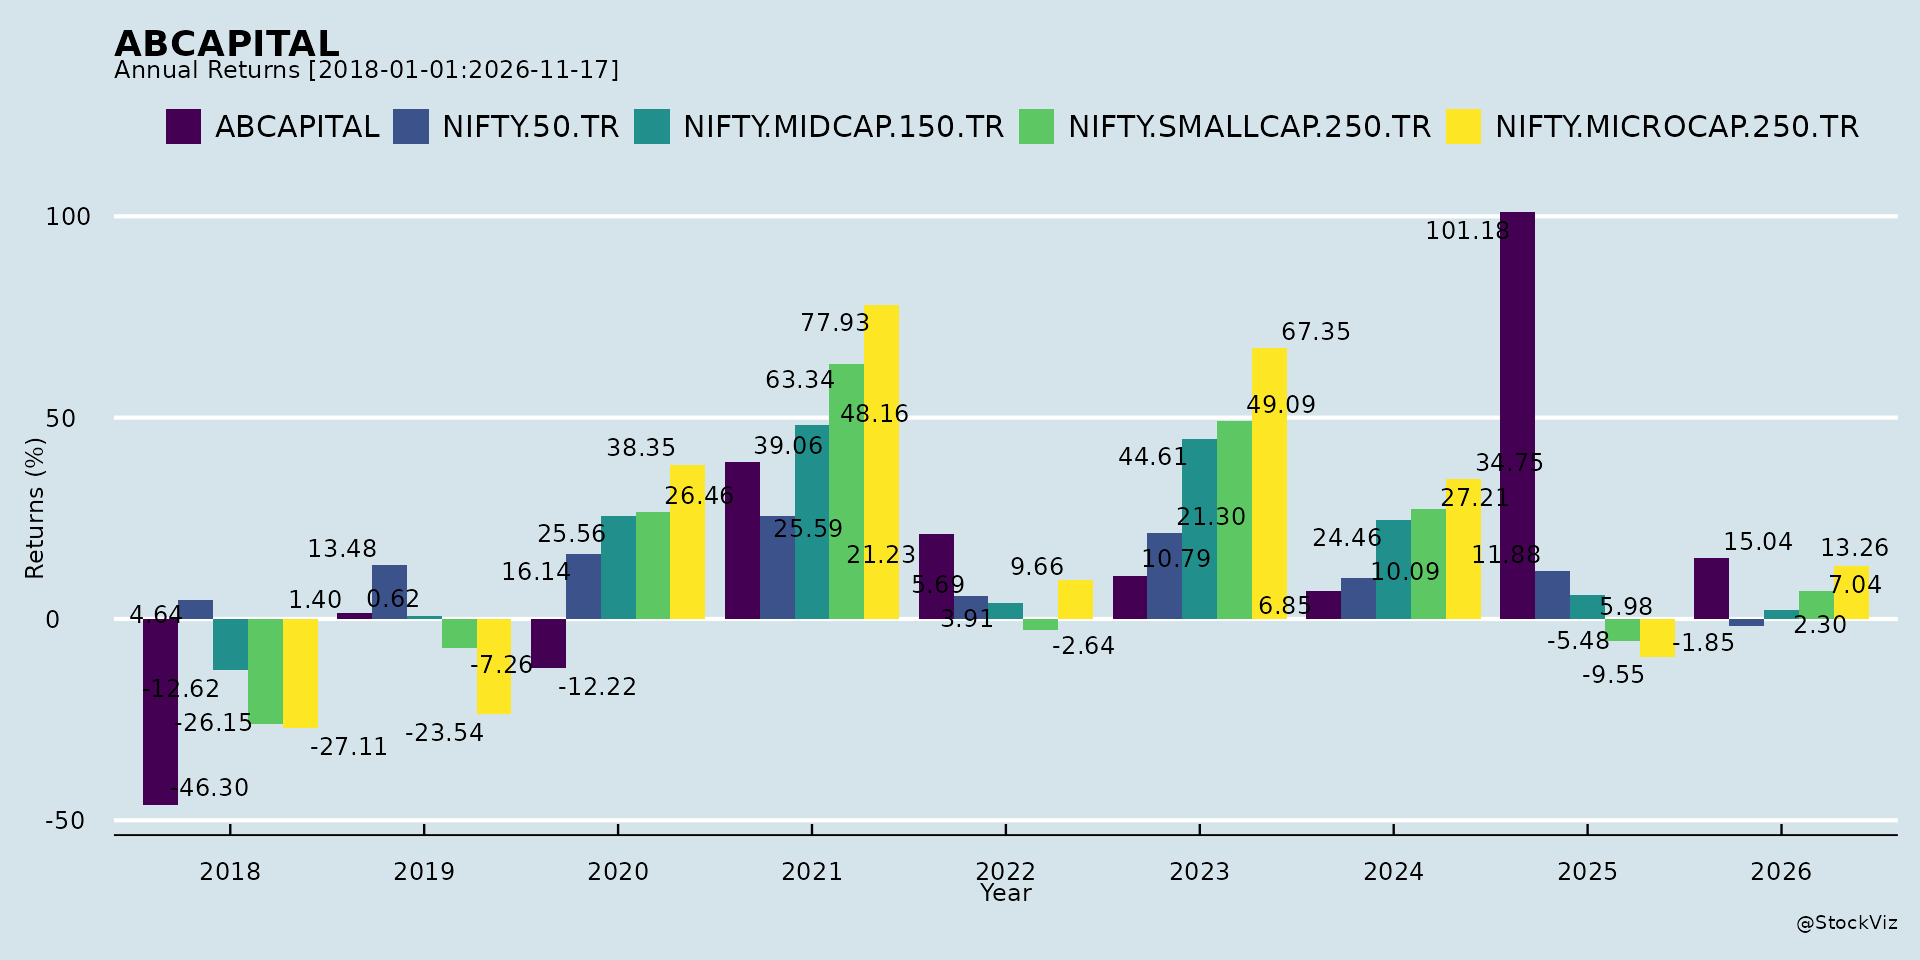
Annual Returns
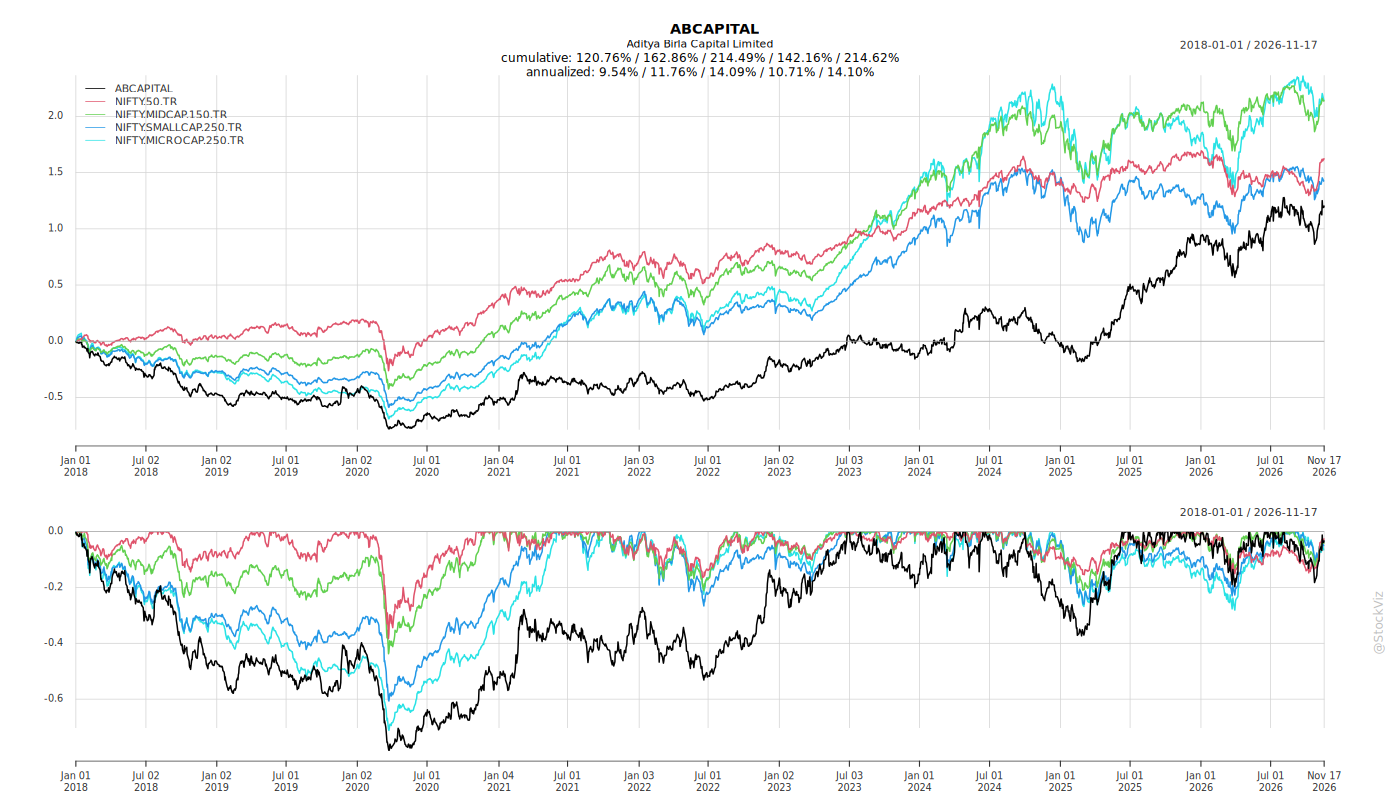
Cumulative Returns and Drawdowns
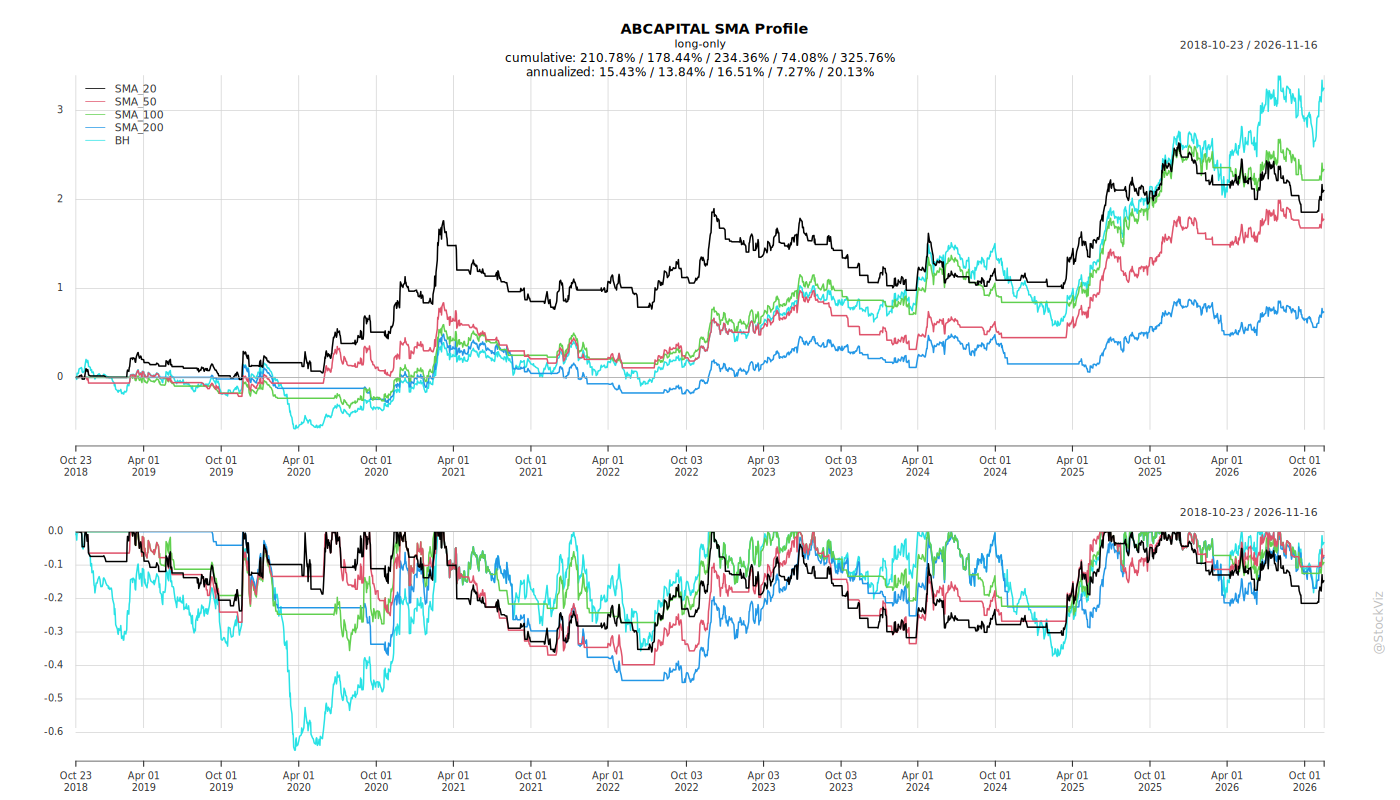
Fundamentals
Ownership
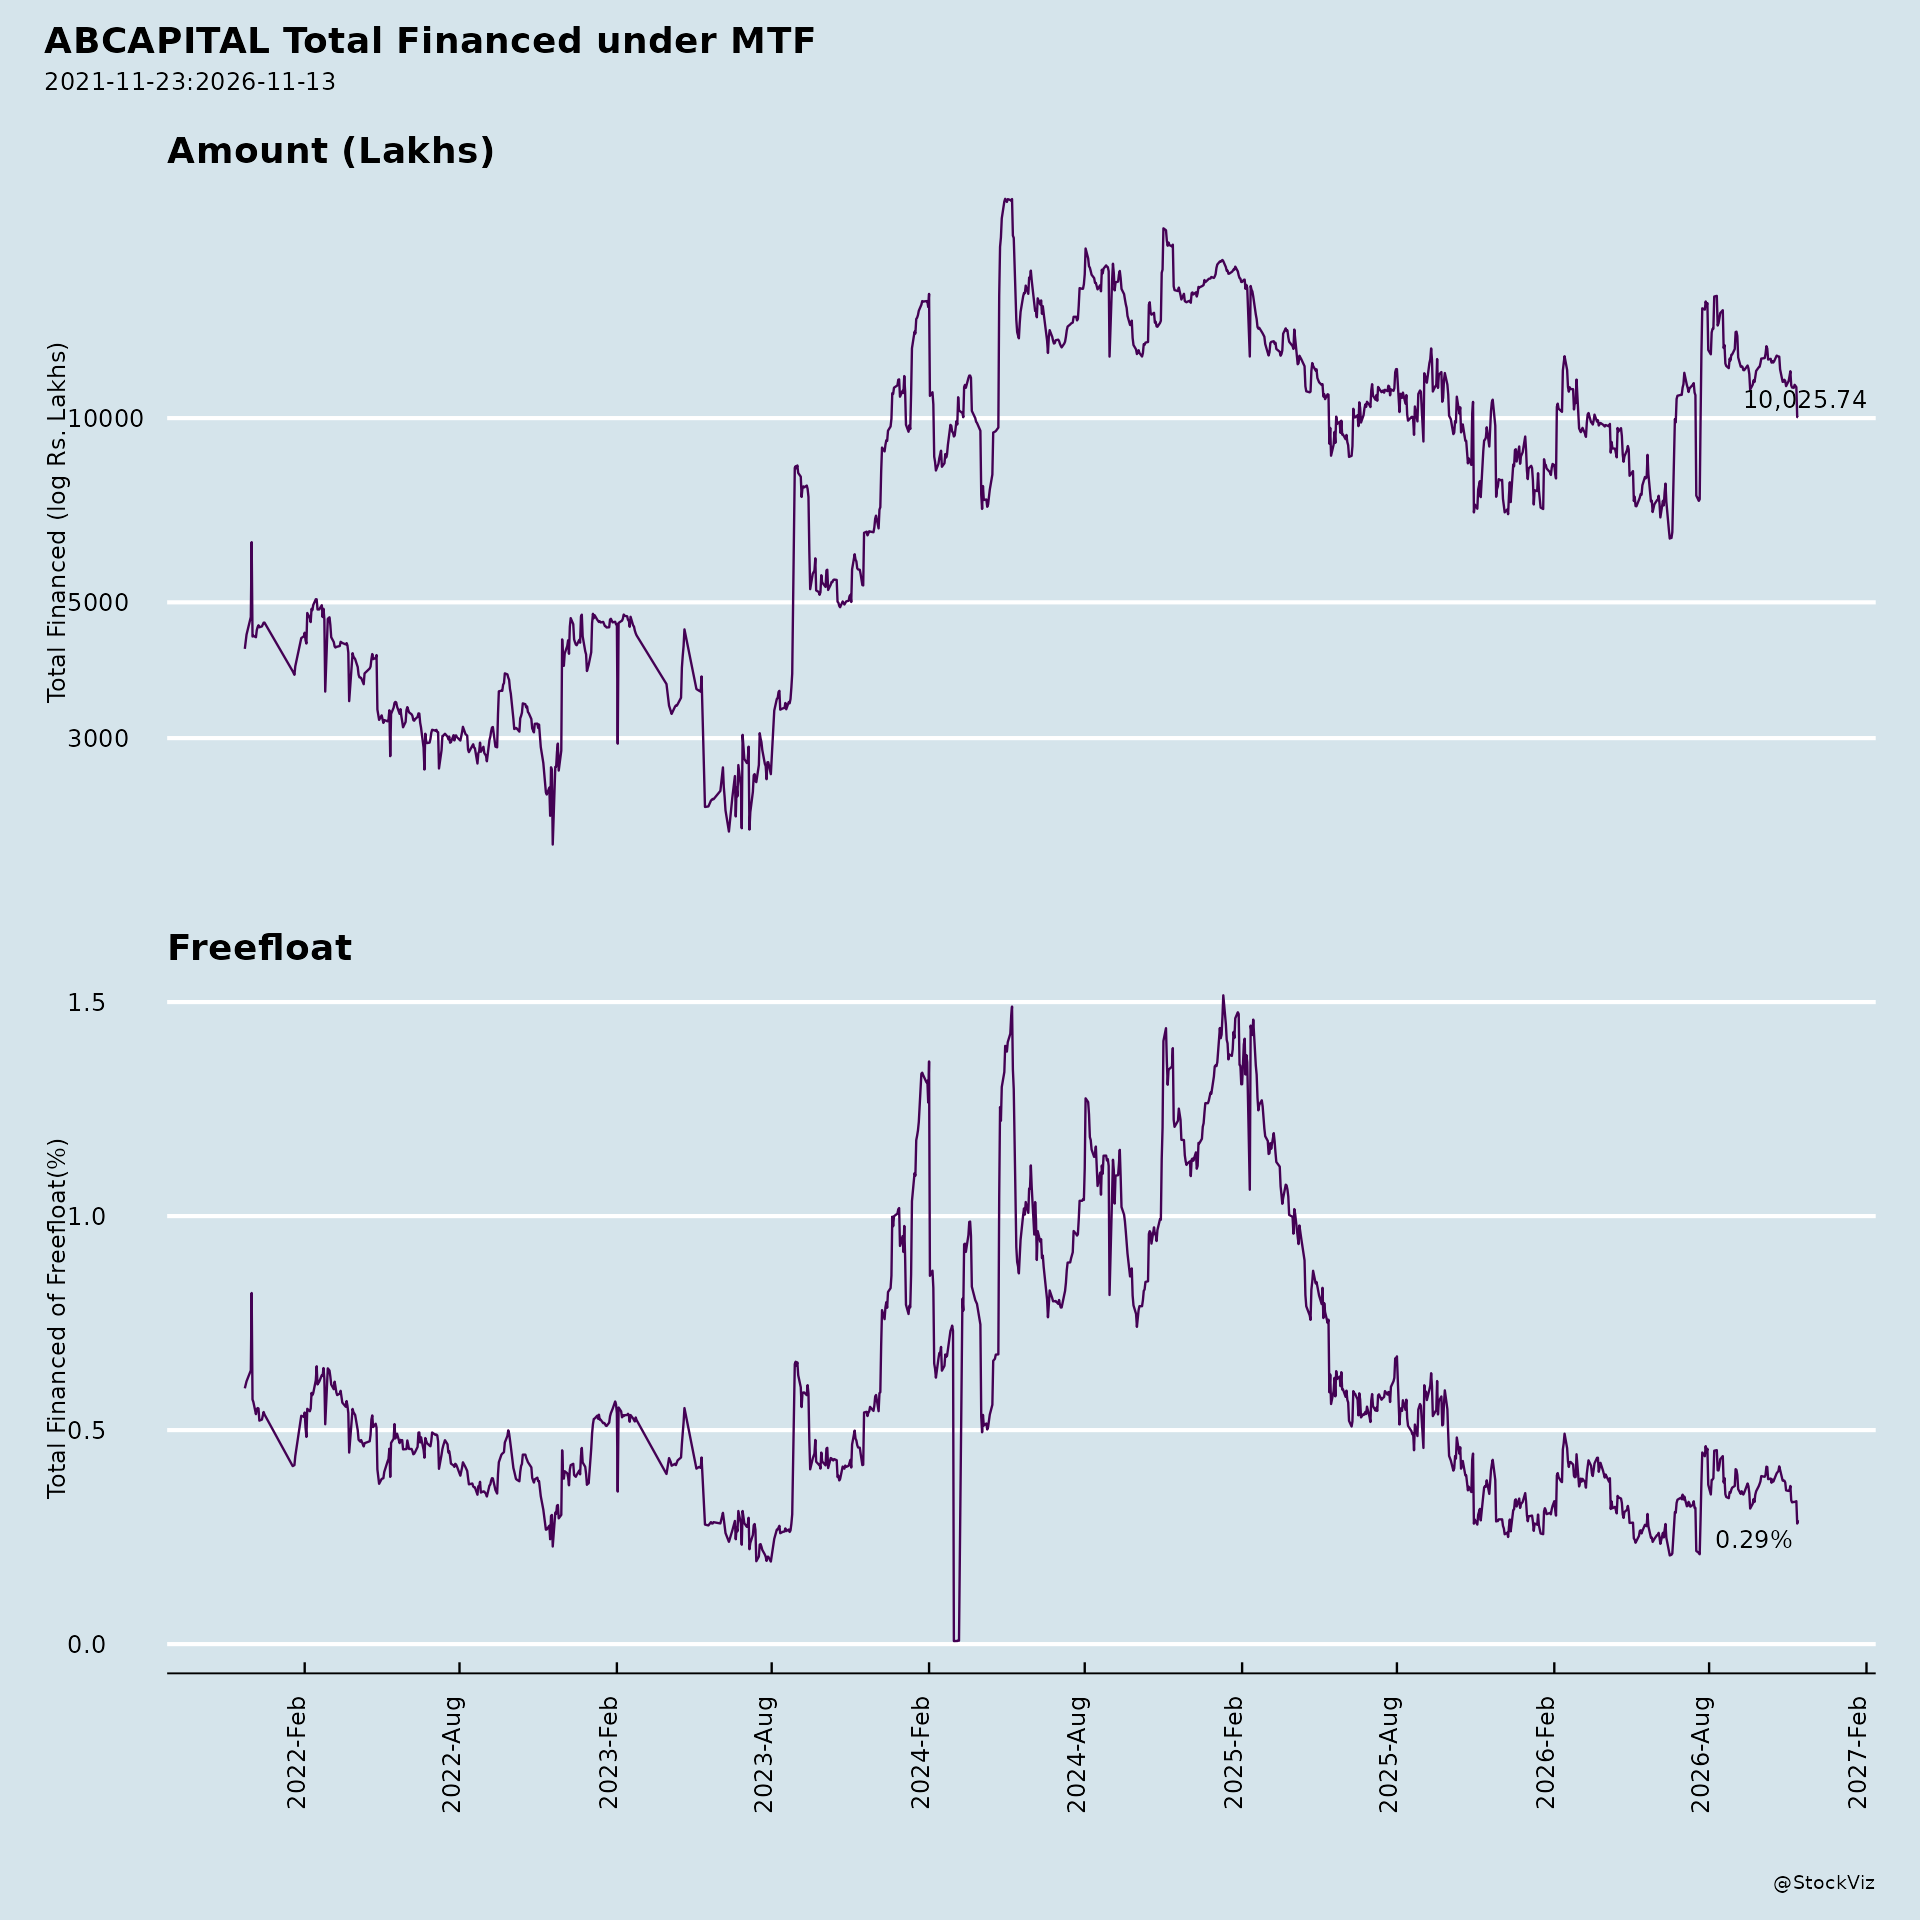
Margined
AI Summary
asof: 2026-09-14
ABCAPITAL: Recent Corporate Announcements — Summary
1. Headwinds and Challenges
The most visible friction point in the supplied material is shareholder dissent at the 19th Annual General Meeting held on 14 August 2026. While all seven resolutions were passed with the requisite majority, two director re-appointment resolutions attracted notable opposition from public institutions:
- Re-appointment of Mr. Kumar Mangalam Birla (Item 3): Public institutions cast 16,53,51,116 votes against, amounting to 31.3125% of institutional votes polled. Across all categories, 6.8852% of votes polled were against.
- Re-appointment of Mr. Sushil Agarwal (Item 4): Public institutions cast 10,23,59,318 votes against, or 19.3838% of institutional votes polled. Across all categories, 4.2652% of votes polled were against.
By contrast, the adoption of standalone and consolidated financial statements (Items 1 and 2) and the borrowing-related special resolutions (Items 5, 6 and 7) saw near-unanimous support, with against-votes of 0.0077% to 0.0084% overall. The dissent is therefore concentrated on board composition rather than on financial or borrowing matters.
A second challenge is execution risk inherent in the gold loan expansion. The company is building the business “from the ground up,” which implies upfront investment in branches, systems, governance and risk processes before revenue scales. The rollout is phased — 200–300 branches by March 2027 and around 1,000 over three years — indicating a measured rather than immediate build-out.
2. Tailwinds and Growth Prospects
The principal growth initiative is the entry into the gold loan business, announced on 20 August 2026. The company describes gold loans as witnessing “strong structural growth in India” and positions the offering as a natural extension of its secured lending strategy. The proposition combines dedicated branch-led service with omnichannel digital capabilities, transparent pricing, secure handling of pledged gold and swift disbursals.
The expansion targets urban and semi-urban markets, serving both existing customers within the Aditya Birla Capital ecosystem and new customers through an integrated physical and digital distribution network. Management intends to leverage the group’s distribution reach and digital capabilities, alongside the Aditya Birla Group’s “generational legacy of trust.”
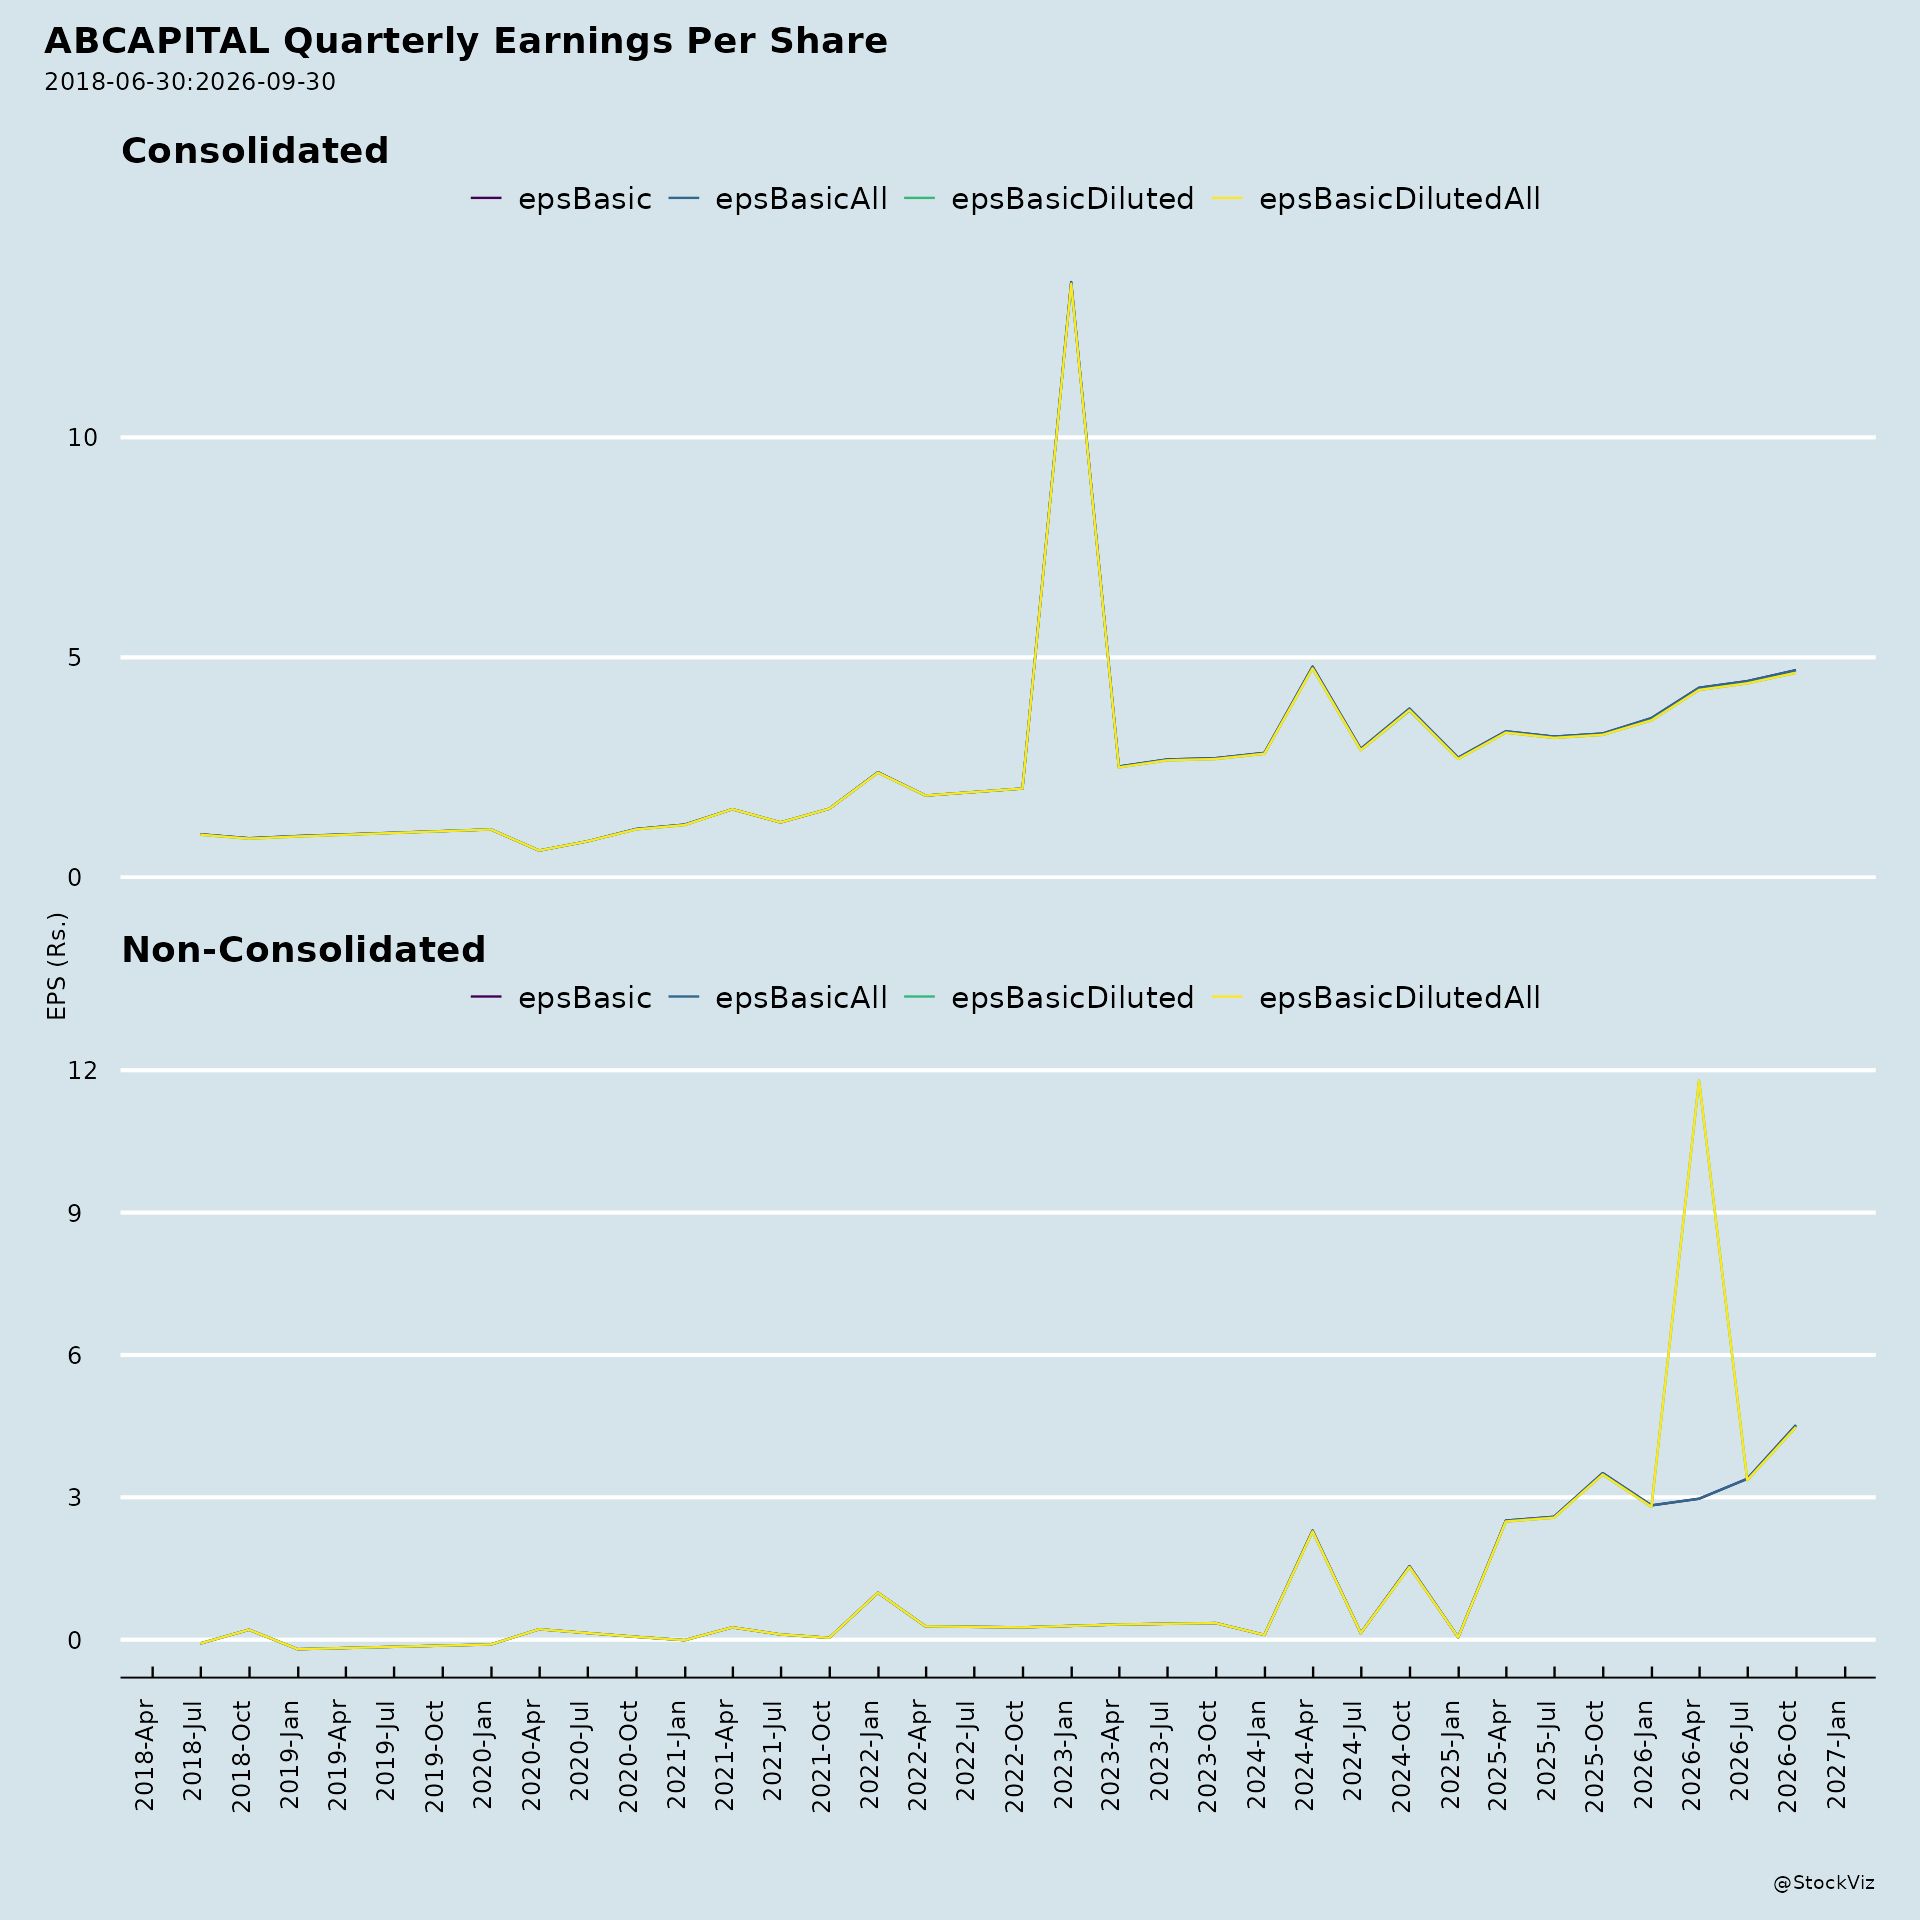
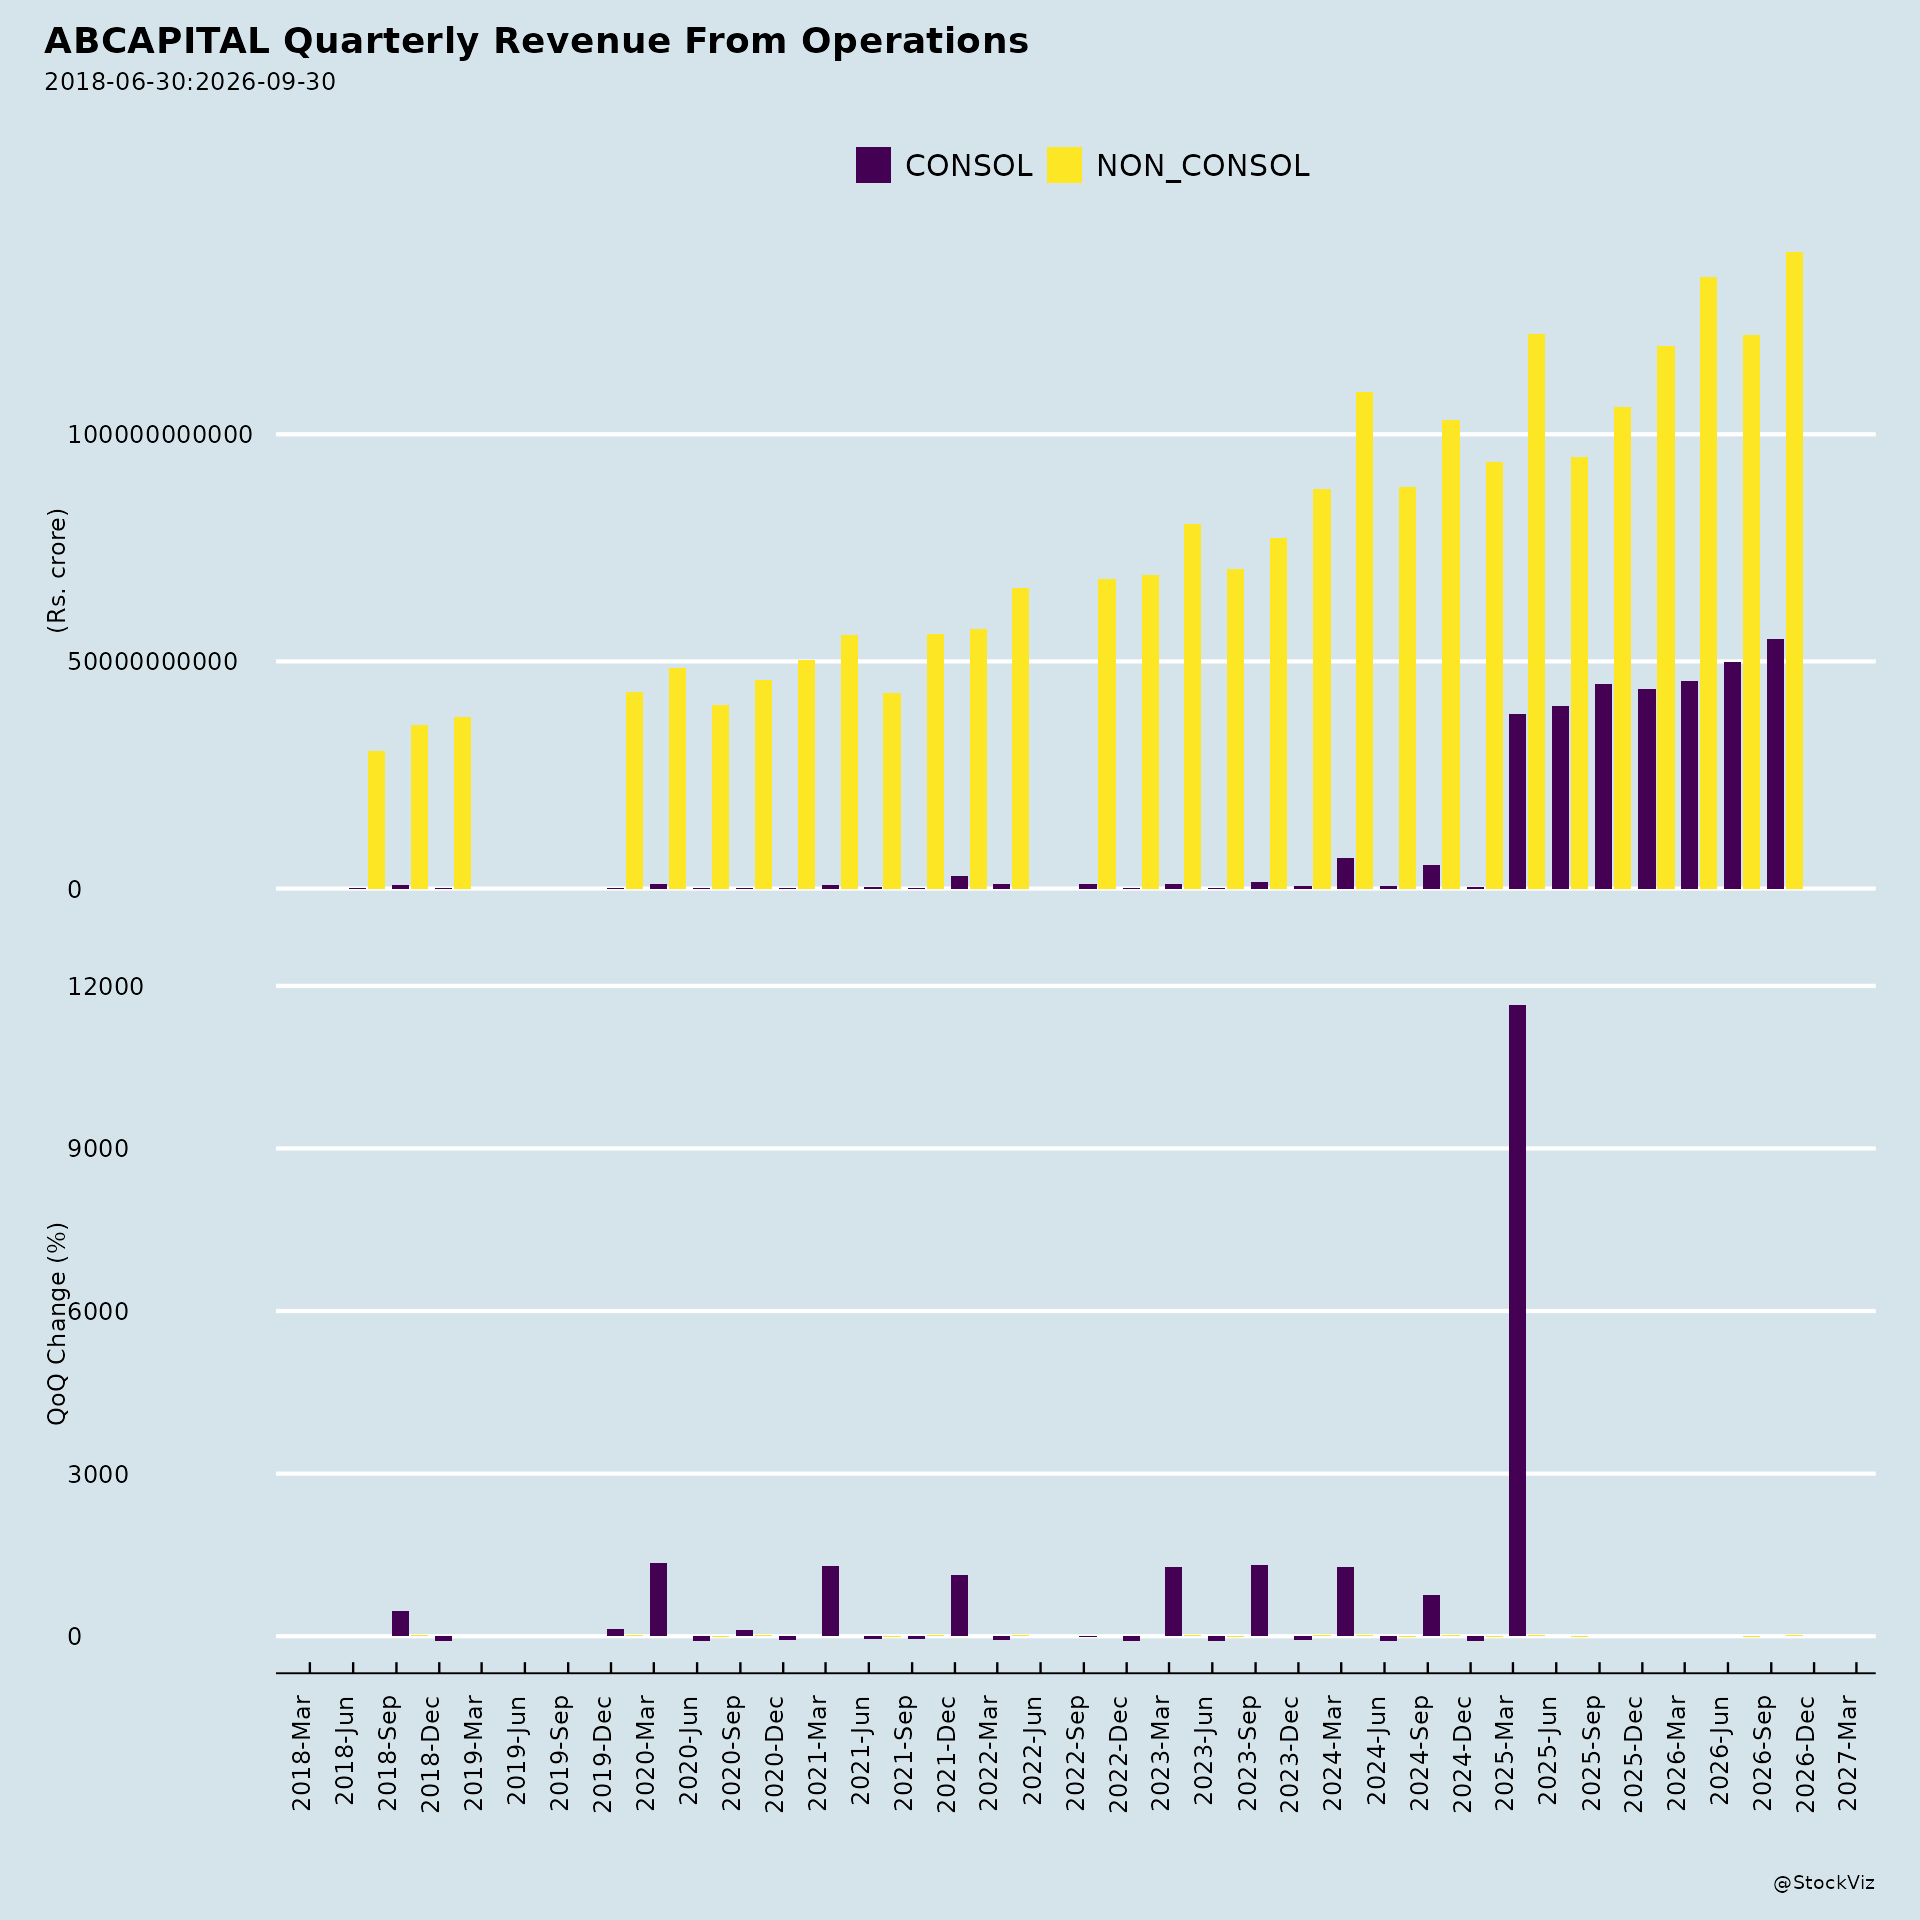
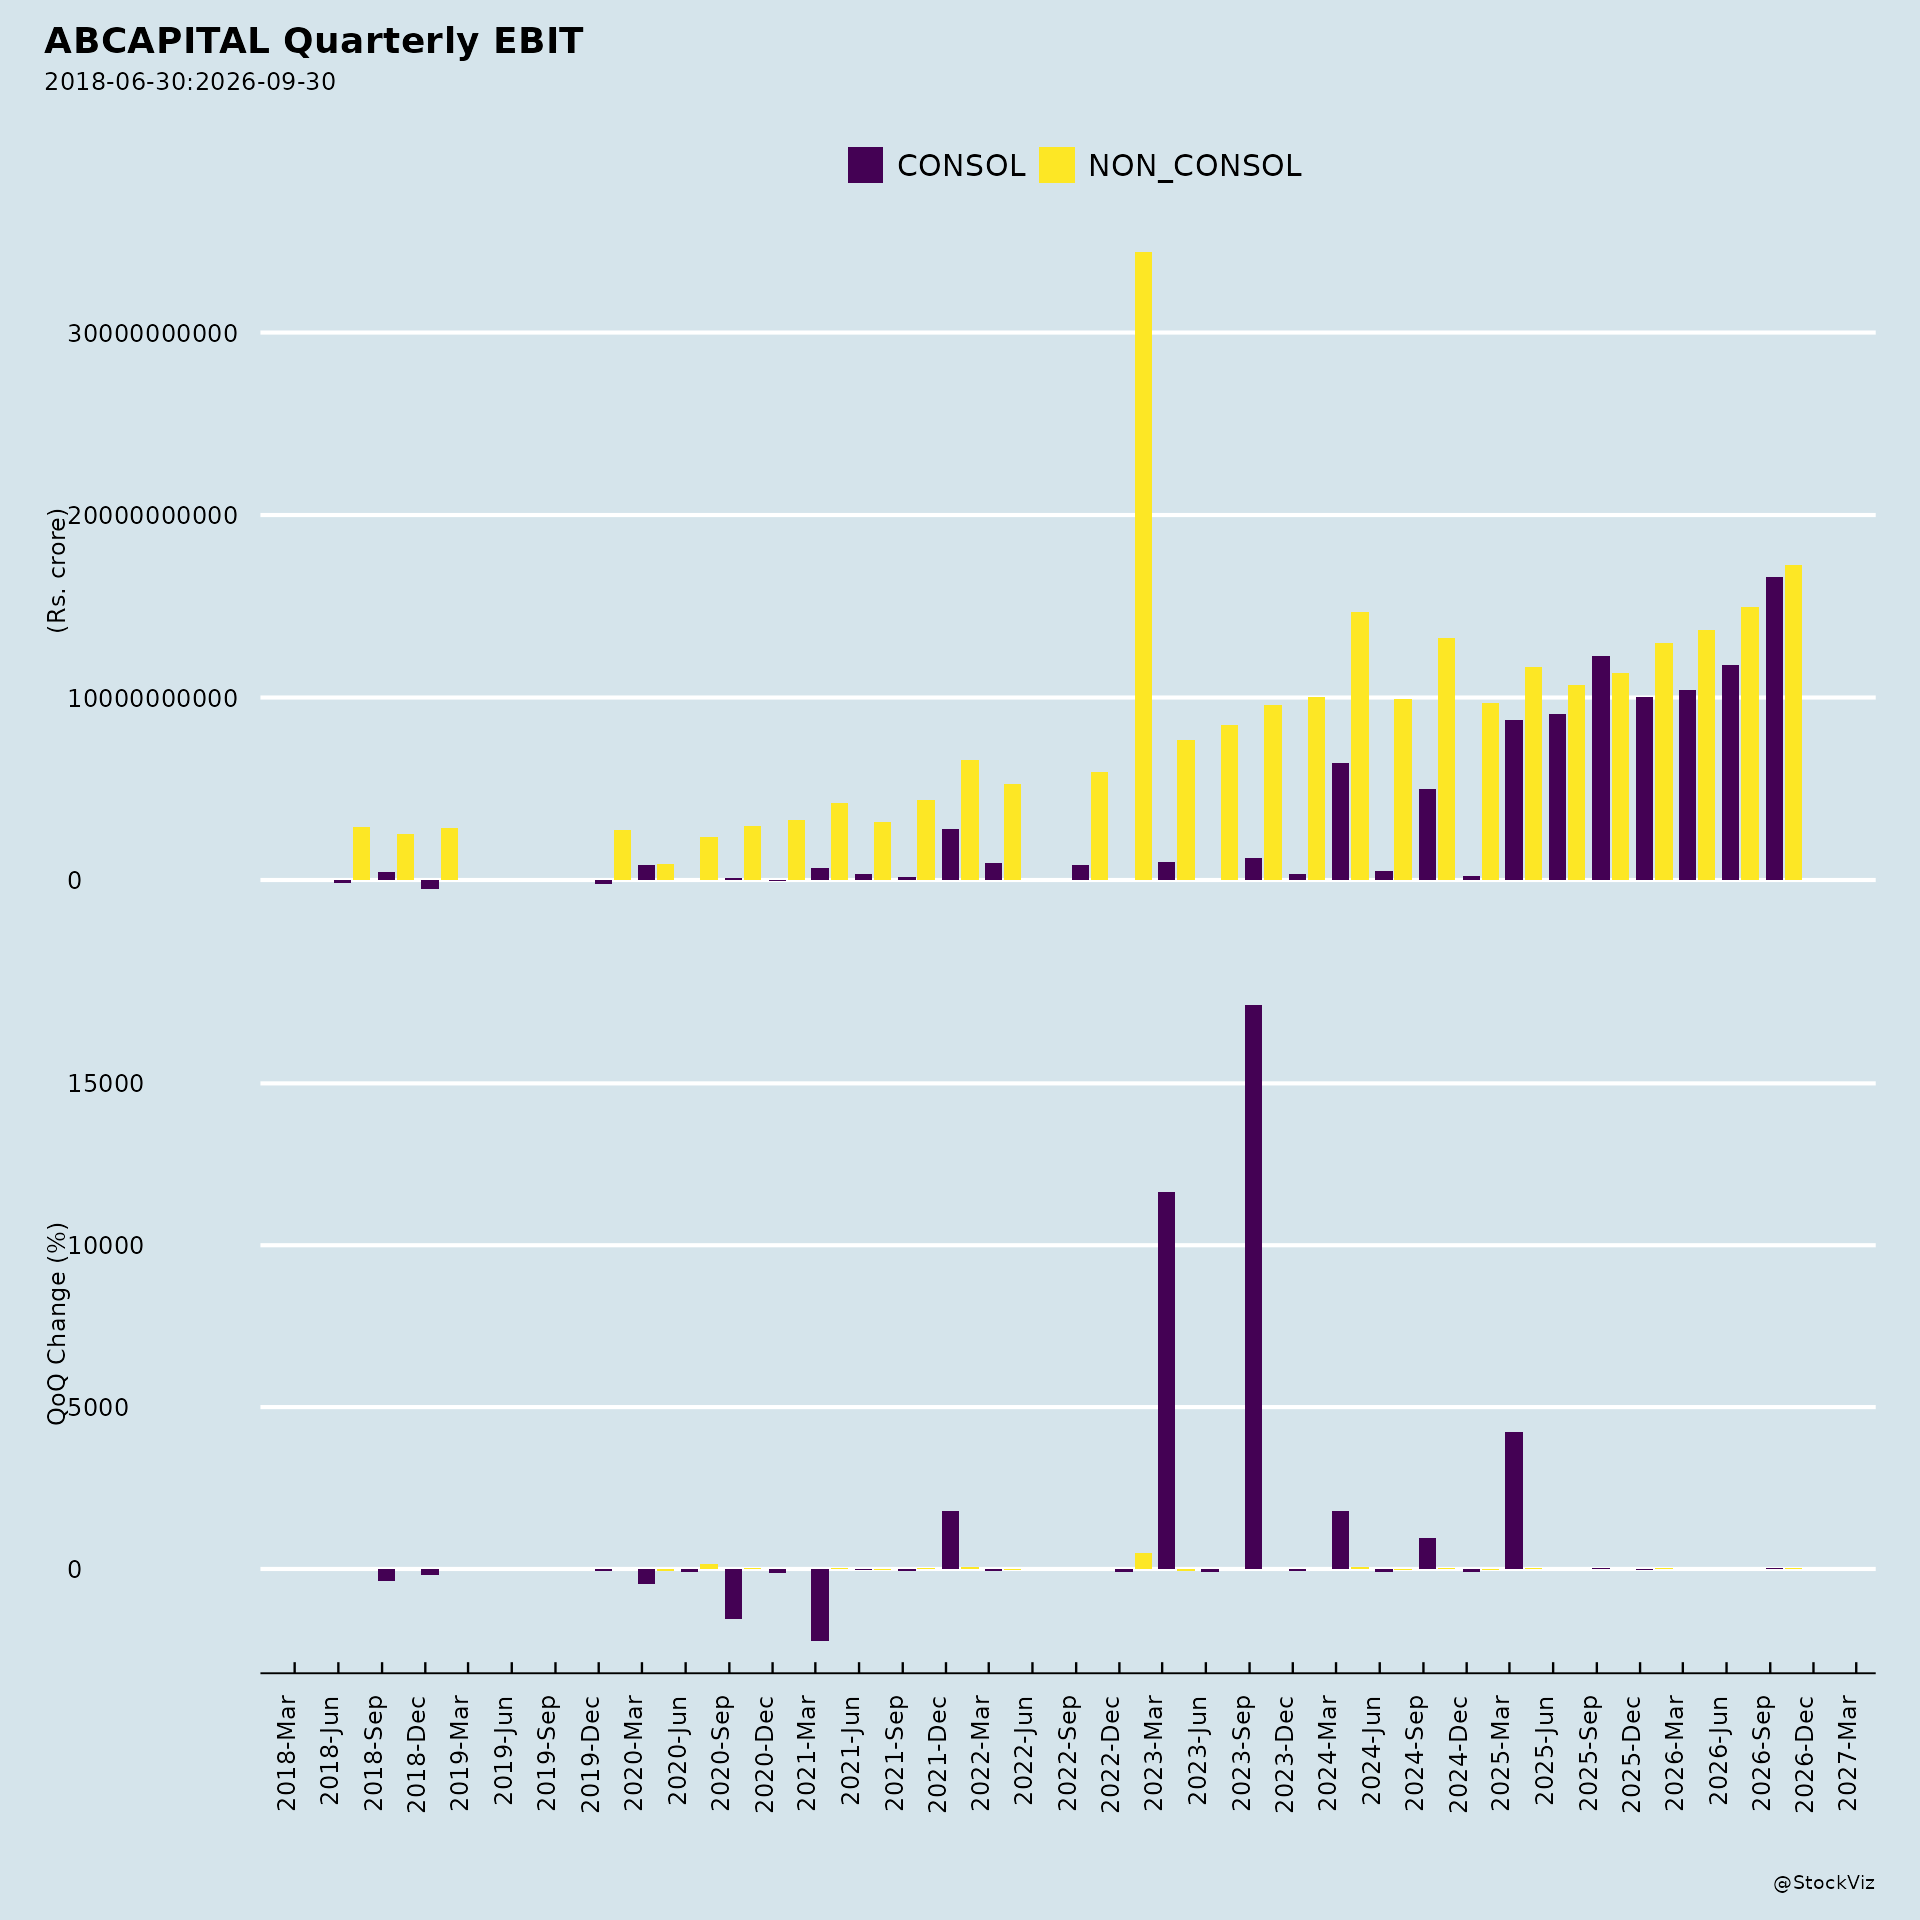
The existing NBFC franchise provides a strong base. In FY26, NBFC AUM grew 27% year-on-year to Rs. 1,59,916 Crore, with retail and SME comprising approximately 68% of AUM; disbursements grew 25% to Rs. 84,204 Crore and profit before tax grew 20% to Rs. 4,023 Crore. Momentum continued in Q1 FY27, with AUM rising 28% year-on-year to Rs. 1,67,456 Crore, disbursements increasing 34% to Rs. 21,201 Crore, and profit before tax growing 32% to Rs. 1,222 Crore.
At the group level, ABCL reports aggregate assets under management of about Rs. 7.53 Lakh Crore and a consolidated lending book exceeding Rs. 2.19 Lakh Crore as of 30 June 2026, with over 1,759 branches, more than 200,000 agents/channel partners and over 66,500 employees.
The AGM also approved special resolutions increasing borrowing powers under Section 180(1)(c) and permitting the creation of charge/security on the company’s assets under Section 180(1)(a), alongside approval for issuing non-convertible debentures on a private placement basis. These approvals provide balance-sheet flexibility to fund expansion.
3. Key Risks
- Governance and board-related dissent: The concentration of against-votes on the two director re-appointment resolutions signals institutional shareholder unease on board matters, even as financial and borrowing resolutions passed overwhelmingly.
- Execution risk in gold loans: Building a new vertical from the ground up, with a target of around 1,000 branches over three years, carries risks around branch ramp-up, staffing, operational processes and customer acquisition.
- Collateral and operational risk: Gold lending requires secure handling of pledged gold, transparent pricing and robust appraisal. The company itself emphasises governance, prudent risk management and operational excellence as foundational to the business.
- Regulatory and disclosure conditions: The scrutinizer’s report notes that voting rights of Foreign Portfolio Investors who had not submitted additional disclosures by the prescribed period were restricted, as provided under the SEBI Master Circular dated 30 May 2024. Shares in the Unclaimed Suspense Account also had frozen voting rights.
- Credit discretion: The company’s own disclaimers state that loans are granted at sole discretion and subject to applicable terms, credit appraisal, eligibility checks and rates.
4. Management Guidance Versus Observed Business Performance
Gold loan rollout guidance: Management has guided a phase-wise rollout of 200–300 dedicated gold loan branches by March 2027, scaling to around 1,000 branches over three years. As the announcement is dated 20 August 2026, this remains forward guidance with no observed branch count yet reported in the supplied material.
NBFC growth trajectory: The guidance-consistent trend is visible in the reported numbers. FY26 NBFC AUM grew 27% year-on-year to Rs. 1,59,916 Crore, and Q1 FY27 AUM rose 28% year-on-year to Rs. 1,67,456 Crore. Disbursements grew 25% in FY26 to Rs. 84,204 Crore and 34% year-on-year in Q1 FY27 to Rs. 21,201 Crore. Profit before tax grew 20% in FY26 to Rs. 4,023 Crore and 32% year-on-year in Q1 FY27 to Rs. 1,222 Crore. The Q1 FY27 acceleration across AUM, disbursements and profit before tax indicates the growth momentum described by management carried into the first quarter of the new fiscal year.
Management commentary: Mr. Rakesh Singh, Executive Director and CEO-NBFC, framed the gold loan entry as a natural extension of the secured lending strategy, citing structural growth in the category and customer demand for transparency, secure handling of gold and trusted stewardship. He stated the business is being built from the ground up with focus on governance, prudent risk management, operational excellence and a customer-first approach, and that the company will leverage its distribution network and digital capabilities as it expands.
Shareholder ratification: The AGM results show that the borrowing-power increase, charge creation and NCD issuance resolutions — all relevant to funding growth — were passed with over 99.99% of votes polled in favour, indicating strong shareholder support for the financing framework underpinning the expansion strategy.
Broker Narrative
The broker maintained a persistent Buy stance and continued to emphasize robust lending growth, improving asset quality, capital raising, and insurance market-share gains. The narrative shifted from early concerns about AMC shrinkage and health underwriting losses to later stress on NBFC margin/yield compression and life-insurance persistency, while margin-expansion expectations became more conditional on the unsecured loan mix. Health-insurance underwriting remained a recurring worry, and the story moved from broad-based growth optimism to a more mixed ‘growth with margin patience’ view.
Fears that came true
- Health insurance underwriting losses persisted: the combined ratio, though improved from 110% to 106%, still indicated a loss-making segment in the last report, coinciding with several FLAT/DISAPPOINTMENT outcomes in the call history.
- Passing on the cost of funds proved difficult: NBFC yield (incl. fees) declined 7bp QoQ and NIM stayed flat at 6.07%, indicating rate pass-through lagged and contributed to disappointing price performance in some windows.
Optimism that failed
- NBFC margin expansion stalled: the early expectation of continued NIM+fee expansion was not sustained, with fee-inclusive NIM flat at 6.07% and yields lower in 1QFY27.
- Life insurance VNB momentum reversed: after doubling to INR8b with ~23% margins in FY23, the 1QFY27 VNB margin was only ~15.1% and 13-month persistency had slipped to 83% from 87%.
- Health insurance turnaround remained incomplete: despite the FY23 near-breakeven and later market-share gains to 16.2%, a 106% combined ratio meant underwriting profitability still had not materialized.
Broker Timeline
19 broker calls · 2023-05-12 to 2026-08-02
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.