AARTIIND
Equity Metrics
November 18, 2026
Aarti Industries Limited
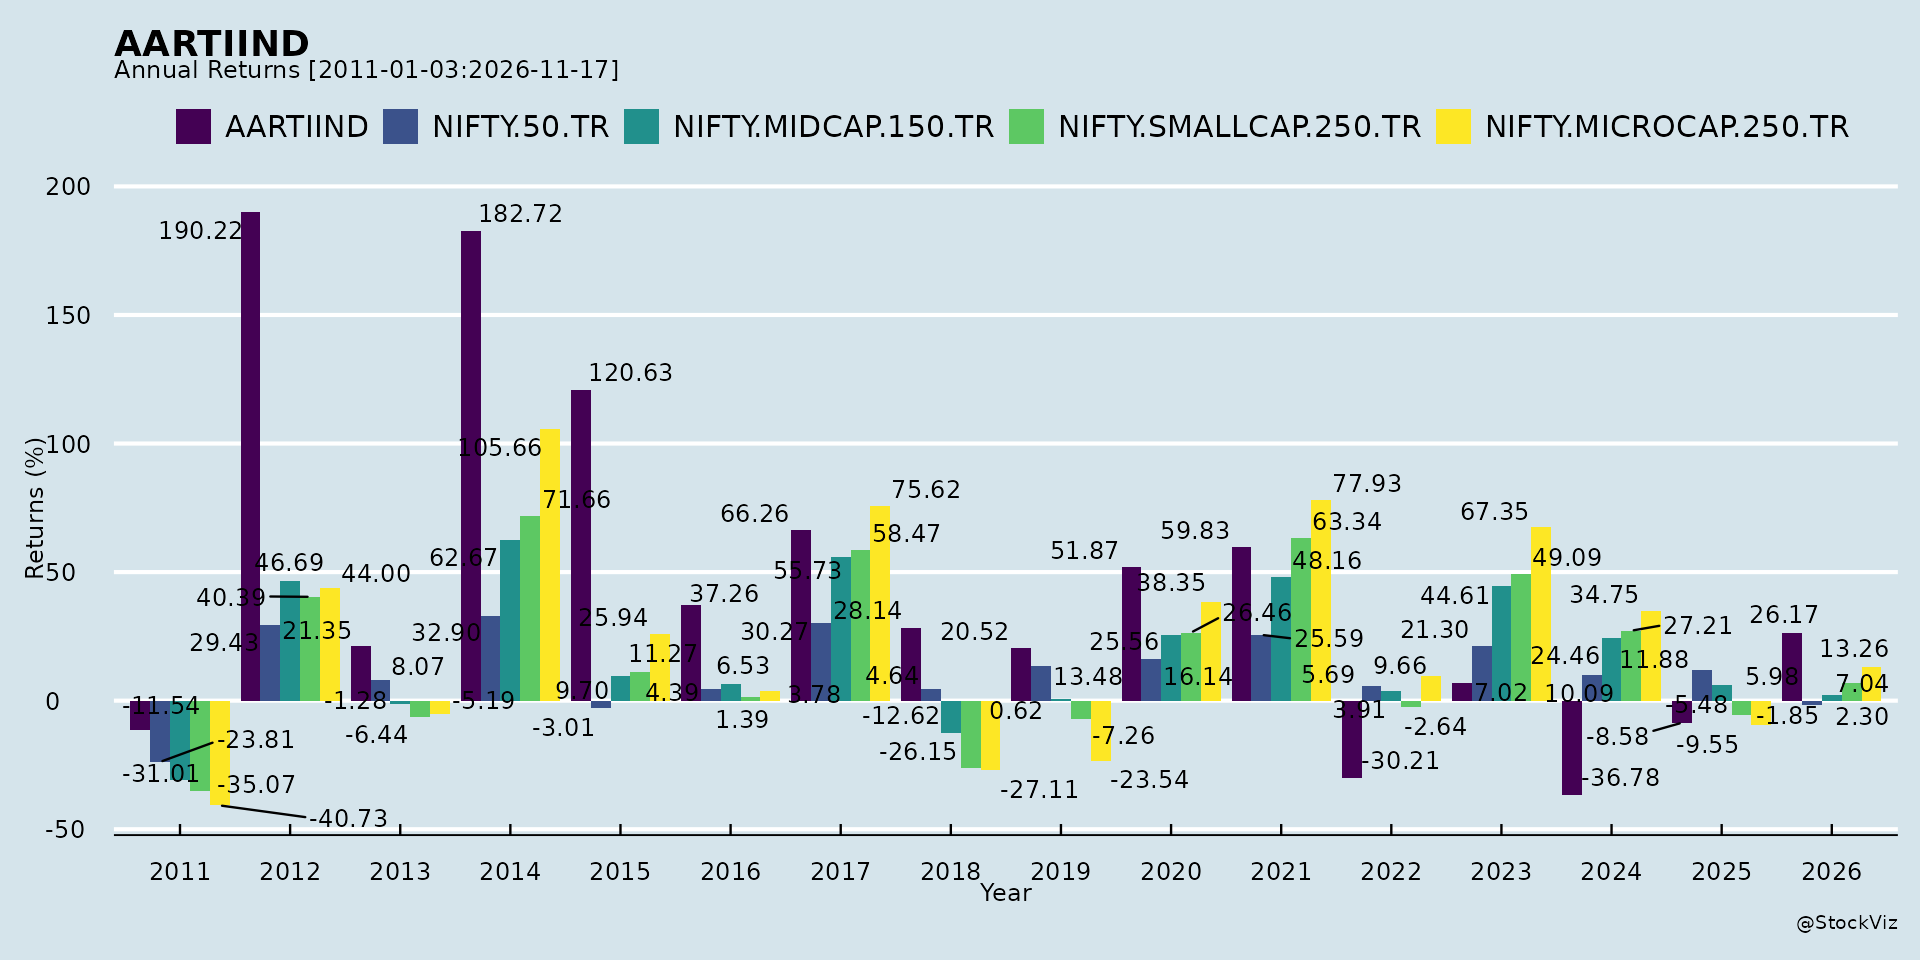
Annual Returns
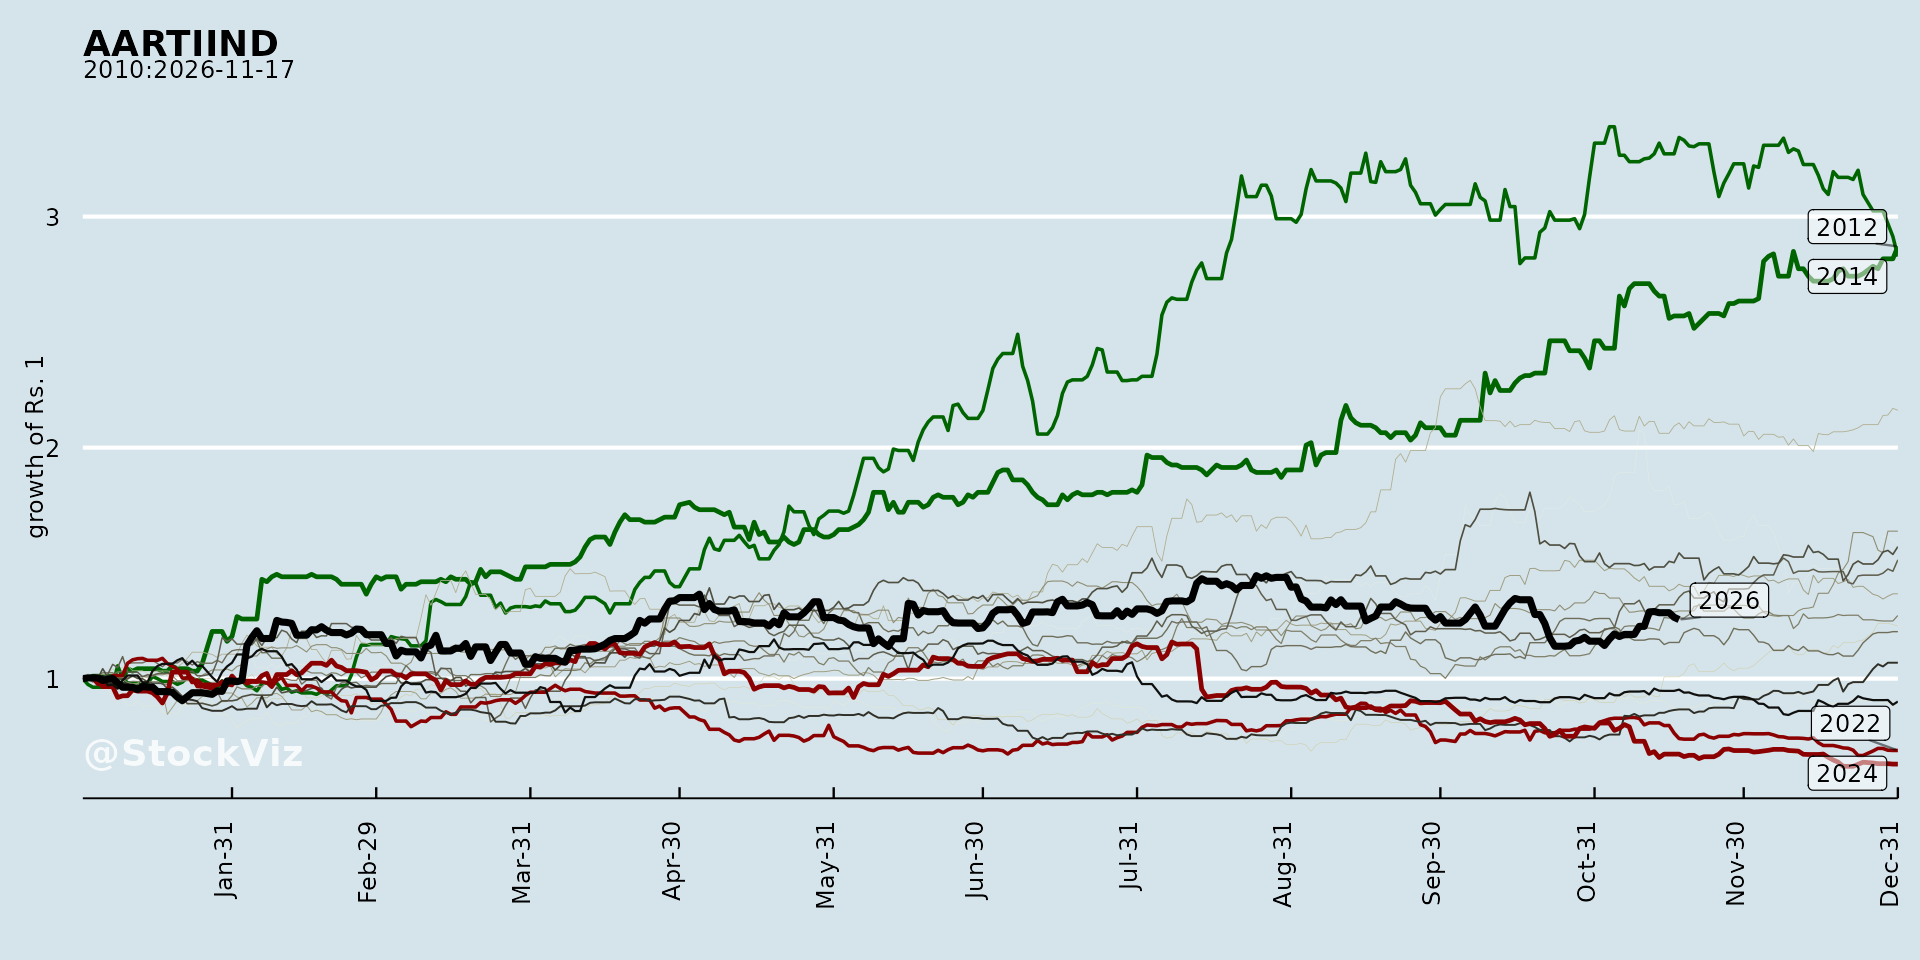
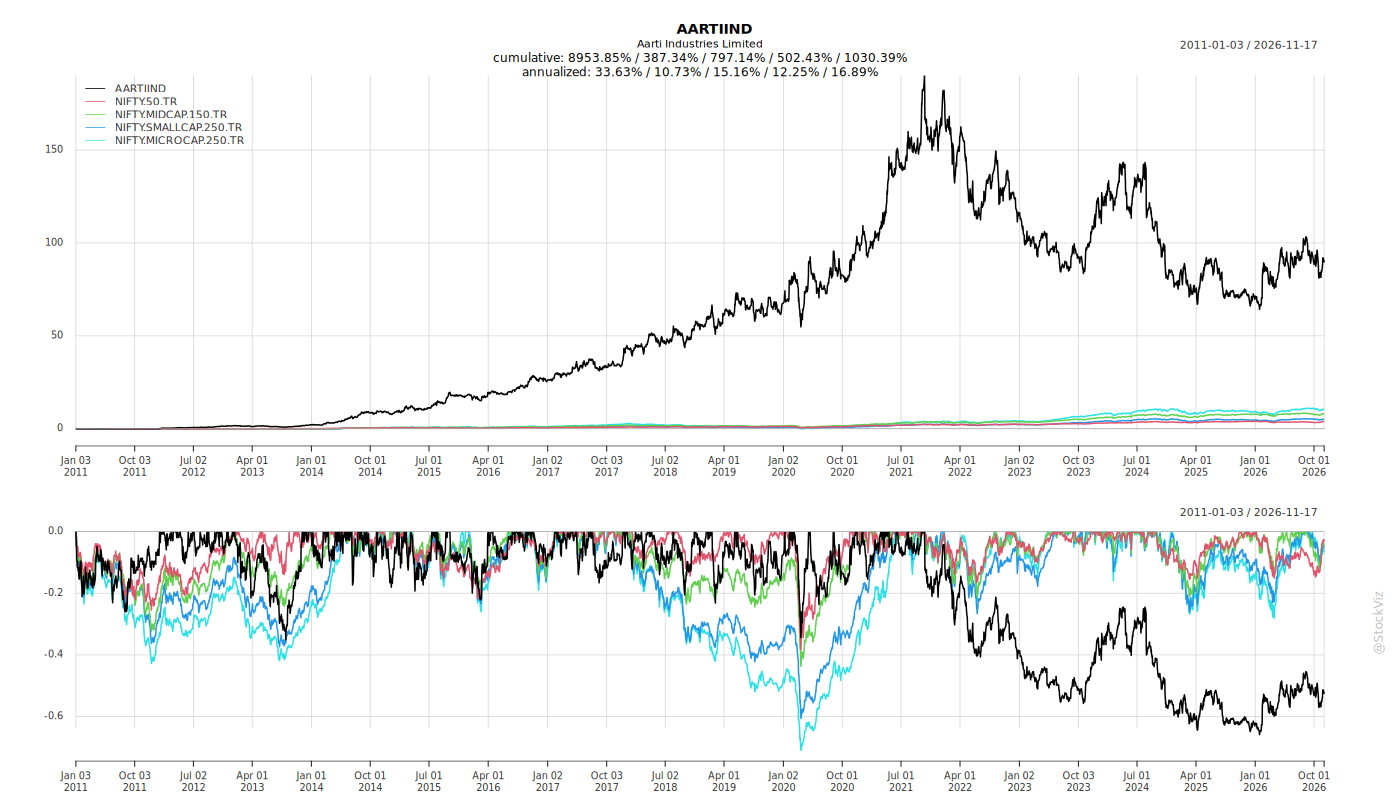
Cumulative Returns and Drawdowns
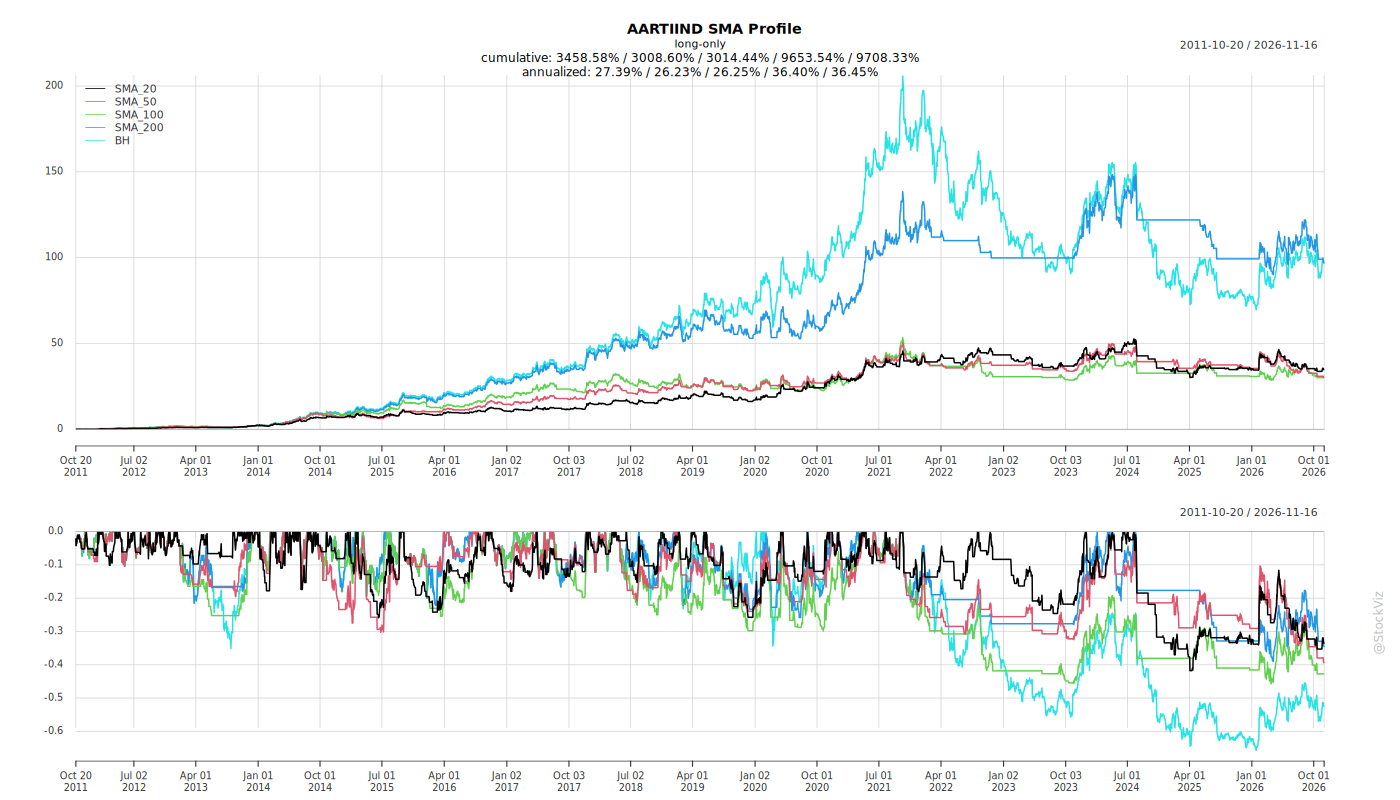
Fundamentals
Ownership
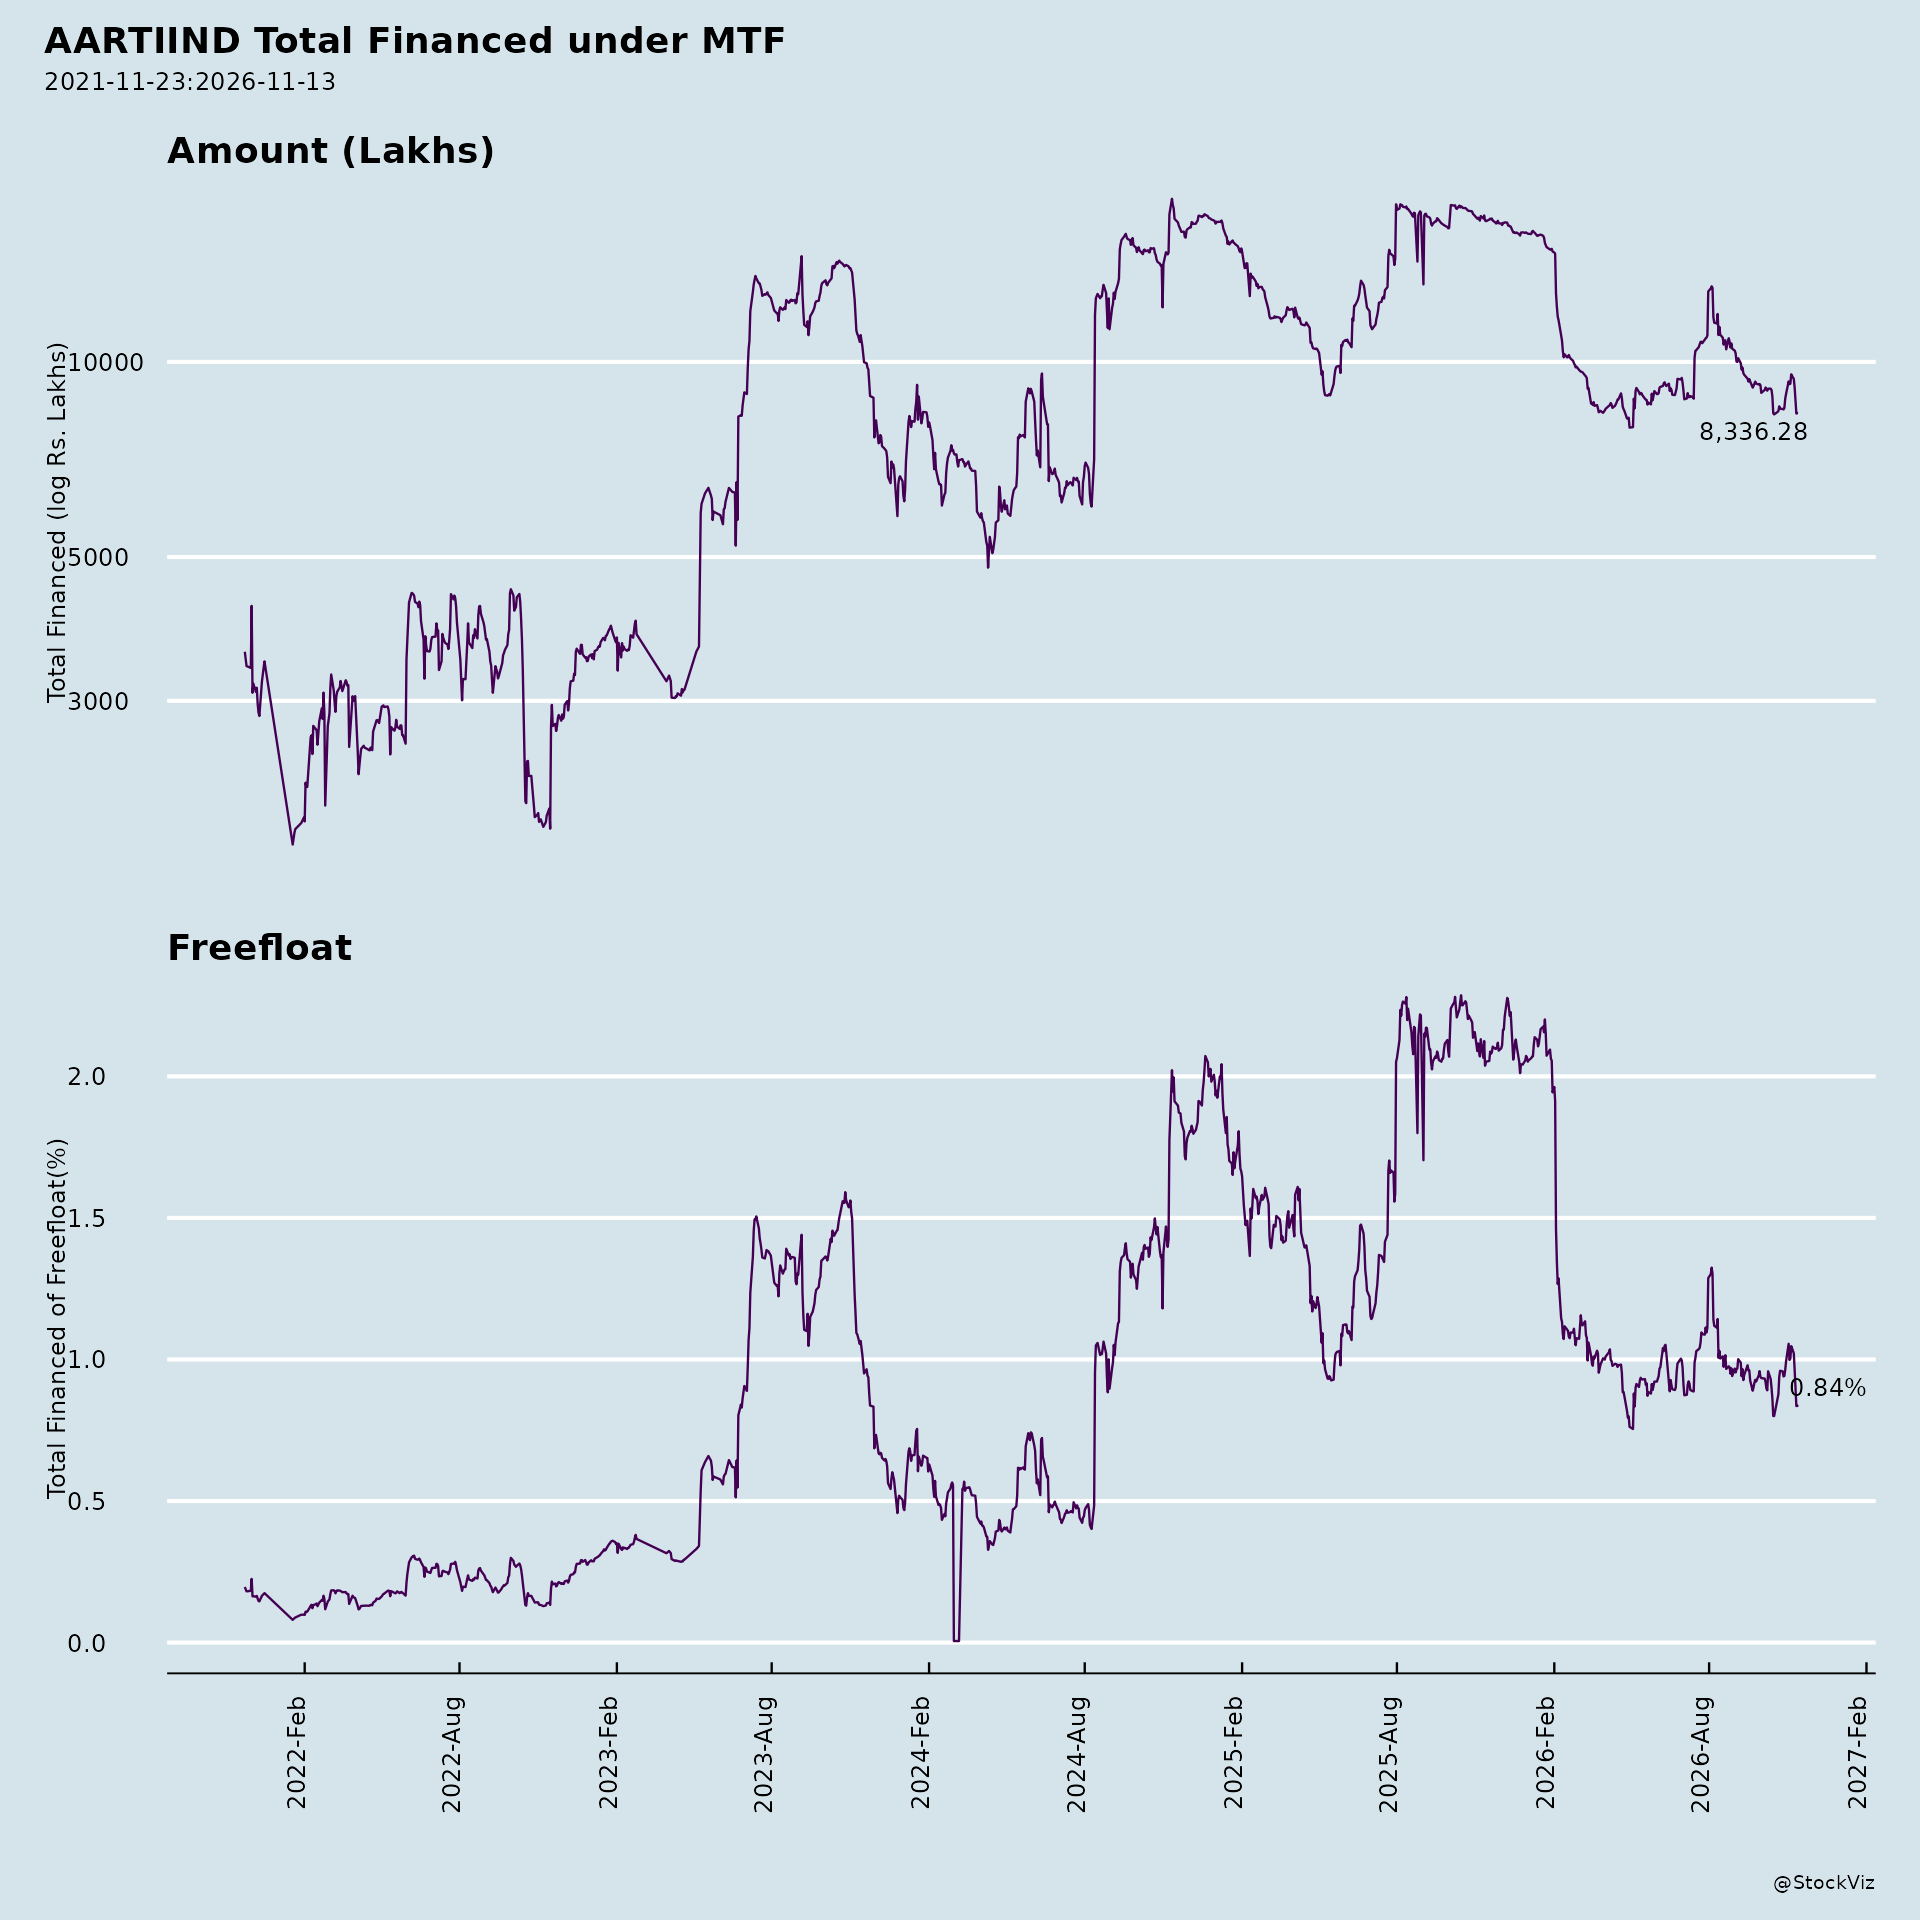
Margined
AI Summary
asof: 2026-09-16
AARTIIND — Recent Corporate Announcements: Summary
1. Headwinds and Challenges
West Asia conflict and supply chain disruption (Q1 FY27) - The West Asia crisis impacted the supply chain, leading to significant volatility in raw material prices. - Volumes of various key products were lower on a quarter-on-quarter basis. - The Middle East, which previously accounted for about 15% of revenues, was significantly impacted; volumes from the region were down to 2% from the earlier ~15% due to the ongoing conflict. - Volumes recovered compared to Q1 FY26 but were sequentially lower in Q1 FY27 on account of supply chain issues linked to the West Asia conflict.
Working capital, debt and finance costs - Working capital increased due to a rise in input prices and exports, leading to higher debt and finance costs. - Net Debt-Equity Ratio (consolidated) rose to 0.80 as of June 30, 2026, from 0.72 as of March 31, 2026 and 0.66 as of June 30, 2025. - Finance costs (consolidated) were ₹83 Crs in Q1 FY27, compared with ₹112 Crs in Q4 FY26 and ₹60 Crs in Q1 FY26.
Segment-specific pressures - PDA: Capacity utilisation impacted by subdued US demand and competition from China. - Polymer & Additives: Softness in the DCB and PDA chains impacted Q1 performance. - Agrochemicals & Fertilizers: Stable demand continues across application segments, though margin and pricing pressure remains persistent in select products; volumes marginally lower due to subdued demand and resistance to source amid elevated RM prices. - Dyes, Pigments & Printing Inks: Segment facing demand headwinds due to soft demand in a high price environment and seasonality. - Pharma: Fluoro products margins continue to remain under pressure driven by high competitive intensity. - Energy & Additives: Feedstock, refining product margins, and Gasoline-Naphtha cracks pose a challenge.
Project execution constraints - Labour constraints impacted the chemical recycling of plastics project timeline by about 3 months; commissioning now expected in H2 FY27. - Zone IV projects were delayed by 2 quarters due to labour constraints and war-related issues.
Other - The company recognised a provision of ₹7 Crs in an earlier period (FY 2025-26) for an advance paid to an Infrastructure NBFC/developer for an industrial land parcel in Gujarat, as the NBFC ran into financial stress and the land parcels are stuck under dispute. - An incremental provision of ₹15 Crs was made in the March 2026 audited results under the statutory impact of new labour codes. - The company’s Long Term Issuers & Bank Facilities credit rating is AA/Negative from CRISIL and India Ratings.
2. Tailwinds and Growth Prospects
Q1 FY27 performance and mix optimisation - AIL took steps to optimise product and geography mix to manage the West Asia situation, resulting in improved EBITDA. - Monetisation of low-cost inventory and FX gains supported EBITDA growth. - Revenue increase was primarily driven by higher input prices passed on to customers. - Alternate markets absorbed part of the volume impact; volume recovery expected in Q2 FY27.
Capacity expansion - Fuel additives capacity expansion from 290 to 360 KTPA completed in July 2026. - DCB volumes increased, supported by PDCB and downstream demand; further capacity debottlenecking to 140 KTPA is underway. - NT and Ethylation capacity utilisation driven by MEA, DEA demand; expected to improve in CY26 with DEA downstream integration investment (PEDA) and increasing demand outlook for MEA.
Partnerships and joint ventures - Existing long-term contracts progressing well and remain stable. - JV with Superform (DCA downstream) at near-commissioning stage, expected commercialisation in Q2 FY27; tailwinds in one end application may support quicker capacity utilisation; marketing efforts initiated. - Re Aarti (chemical recycling of plastics): critical equipment delivered, on-ground execution underway, engagement with potential pyrolysis oil customers continues; expected to commission in H2 FY27.
Cost savings and digital/AI - Successful cost savings drive across all value chains generating ideas on product yield; energy efficiency catalysed through digital and advanced analytics and best-in-class engineering solutions, with 70% of ideas implemented and generating value. - Building in-house digital and analytics capability; 40+ GenAI use cases executed over the last quarter.
Sustainability recognition - Ecovadis Platinum rating with a score of 87 out of 100, placing AIL among the top 1% of companies.
Three-year EBITDA growth drivers (FY25–FY28) - Cost Optimisation (₹150–200 crore): switching to back pressure turbine to improve cogen, renewable power phase 2, waste energy stream utilisation, ETP cost optimisation, fixed cost optimisation, yield improvement, digital and advanced analytics-led cost excellence — majorly completed. - Volume and margin ramp-up (₹350–550 crore): acid, DCB & NCB value chain ramp-up; ethylation & NT volume ramp-up with downstream integration for select ethylation product; MMA capacity expansion completed with volume ramp-up to follow; fluorination and speciality chemicals ramp-up — on track as planned. - CAPEX-led growth (₹300–450 crore): pilot commissioned to fuel new product development; MPP commissioning and ramp-up; Zone 4 commissioning and ramp-up; Augene & Re Aarti JV commissioning and ramp-up — all projects to commission in FY27.
Long-term growth focus areas - MPP and Zone 4 commercialisation: R&D and MPP to support quick development, qualification and commercialisation of new advanced chemistries; chlorotoluene commissioning and ramp-up to open new opportunities in agro and pharma. - Entry into adjacent markets and new platforms: leverage current capabilities into advanced materials, battery materials, defense and coatings; develop newer growth platforms in sustainability/circularity. - Strategic alliances and CDMO: promote India as a manufacturing destination of choice and partner with customers for new India-based investments; leverage R&D strength to provide CDMO services.
Zone IV Phase I commissioning - Phase I of the Zone IV project at Jhagadia, Gujarat, was commissioned, bringing Calcium Chloride, PEDA, and part of the Multipurpose Plant on stream to strengthen downstream integration, application diversification, and flexible manufacturing capabilities. - The project supports commercialisation of high-value and niche products, several expected to be manufactured in India for the first time. - Phase I broadens applications across agrochemicals, pharmaceuticals, coatings, polymers, and energy and additives.
FY2026 context - In FY2026, revenue from operations reached ₹9,018 Crs, EBITDA stood at ₹1,172 Crs, and PAT was ₹419 Crs. - The company completed a peak capital expenditure cycle of ₹1,125 Crs primarily directed toward the Zone IV expansion. - Aarti Industries serves over 1,100 customers across 60+ countries and holds leading market positions, including #1 globally in Di Chloro Benzene (DCB). - The company received the 2026 Gallup Exceptional Workplace Award and achieved an EcoVadis Platinum rating.
Favourable external developments - China’s VAT removal policy from April 2026 improved margins in select value chains; China removed the export VAT rebate for major NCB chain products, supporting improved margins. - Depreciation of ₹ versus ¥ expected to support margin improvement. - Favorable trade agreements (India-EU FTA and US-India trade dynamics) and structural shifts favouring India as a preferred specialty chemicals manufacturing hub. - China’s anti-involution measures improving pricing discipline; expansion into sunrise sectors (EVs, renewable energy, electronics, semiconductors, advanced materials). - Long-term strategic partnerships including a USD 150 million agrochemical supply agreement.
3. Key Risks
- Geopolitical friction and global volatility, including the West Asia conflict, tariff uncertainties and new U.S. tariffs.
- Raw material price volatility (such as price corrections in benzene and anilene) and inventory valuation losses.
- Intense competition and capacity additions, particularly from China.
- Supply chain disruptions, logistics bottlenecks, elevated freight costs, and foreign exchange fluctuations.
- Project execution risk: labour constraints and war-related issues delayed Zone IV projects by 2 quarters; labour constraints impacted the chemical recycling project timeline by about 3 months.
- Demand softness in key end markets (US and China downstream demand softened in Q1; recovery expected in Q2).
- Margin pressure in select products (agrochemicals, fluoro products) and competitive intensity.
- Working capital and leverage risk: higher debt and finance costs; net debt-equity rose to 0.80 (consolidated) as of June 30, 2026.
- Regulatory/statutory risk: impact of new labour codes (₹15 Crs incremental provision in March 2026 results).
- Counterparty risk: provision of ₹7 Crs for advance paid to an Infrastructure NBFC/developer that ran into financial stress.
4. Management Guidance vs. Observed Business Performance
Guidance: Volume recovery expected in Q2 FY27 - Observed: Volumes recovered compared to Q1 FY26 but were sequentially lower in Q1 FY27 due to West Asia conflict-linked supply chain issues. Alternate markets absorbed part of the volume impact. Recovery is expected in Q2 FY27 (stated, not yet observed).
Guidance: JV with Superform commercialisation in Q2 FY27 - Observed: Project at near-commissioning stage; marketing efforts initiated in line with commissioning timelines. Not yet commercialised as of the Q1 FY27 update.
Guidance: Re Aarti (chemical recycling) commissioning in H2 FY27 - Observed: Critical equipment delivered; on-ground execution underway; labour constraints impacted timeline by about 3 months. Commissioning now expected in H2 FY27.
Guidance: Zone IV projects to commission in FY27; Zone IV delayed by 2 quarters - Observed: Zone IV projects delayed by 2 quarters due to labour constraints and war-related issues. Management stated the company remains on track to progressively commercialise all manufacturing blocks within Zone IV during this fiscal year. Phase I of Zone IV at Jhagadia was commissioned (Calcium Chloride, PEDA, and part of the Multipurpose Plant).
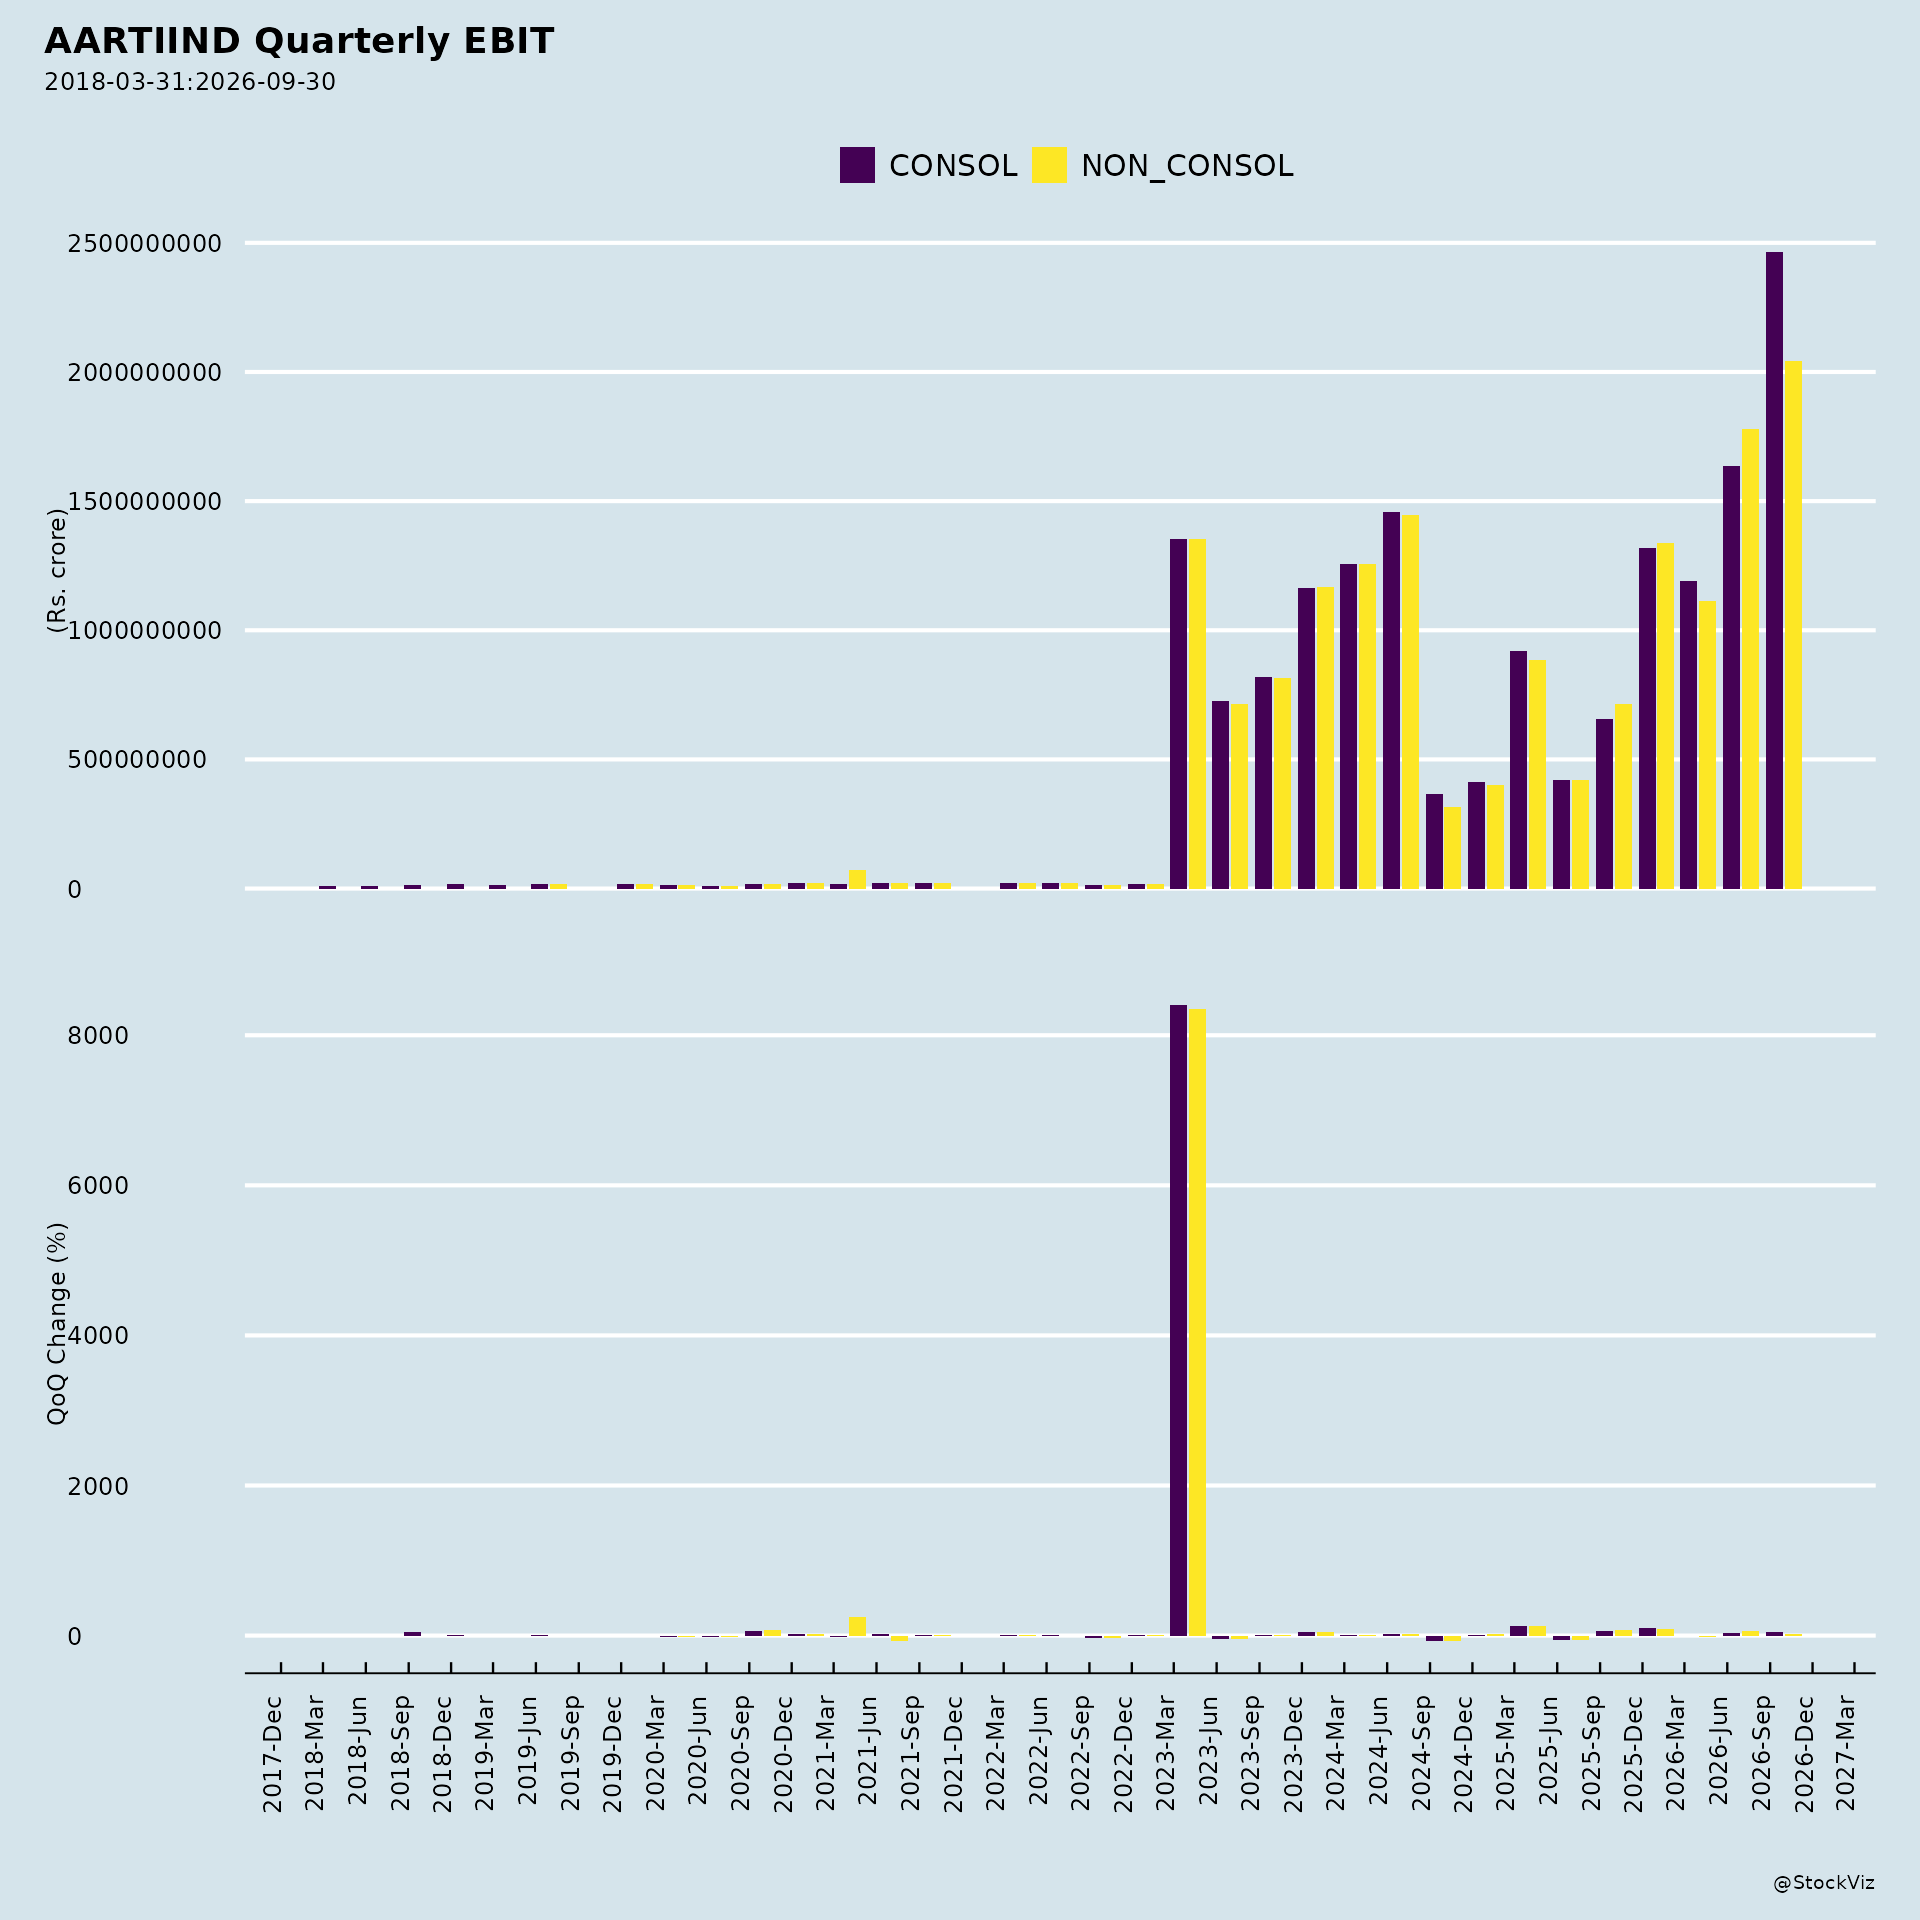
Guidance: Target EBITDA range of ₹1,800–2,200 Crs; Debt/EBITDA of <2.5x - Observed: Q1 FY27 consolidated operating margin was 14.54% (vs 14.15% in Q4 FY26 and 11.35% in Q1 FY26). Net debt-equity was 0.80 as of June 30, 2026. FY2026 EBITDA was ₹1,172 Crs. The target range is a forward-looking statement; observed performance to date is below the lower end of the target range on an annualised basis.
Guidance: Deliver consistent volume growth over 3 years despite margin pressures; operating leverage and cost optimisation to drive EBITDA growth beyond volume growth - Observed: Q1 FY27 volumes were sequentially lower due to West Asia conflict; EBITDA improved on mix optimisation, low-cost inventory monetisation, and FX gains. Cost optimisation initiatives are majorly completed; volume and margin ramp-up is on track as planned.
Guidance: Capex cycle to enter lower-intensity phase in FY2026-27, with capital expenditure moderating to ₹750–800 Crs - Observed: FY2026 peak capex cycle of ₹1,125 Crs was completed. Q1 FY27 results do not provide a capex figure; the moderation guidance is forward-looking.
Guidance: Effective tax rate projected to normalise within 9–15% range - Observed: Q1 FY27 consolidated total tax expense was ₹25 Crs on profit before tax of ₹180 Crs (approximately 13.9%), within the guided range. Standalone total tax expense was ₹19 Crs on profit before tax of ₹163 Crs (approximately 11.7%), also within the range.
Guidance: Gradual deleveraging, improved asset utilisation, margin expansion, and meaningful inflection in free cash flows - Observed: Net debt-equity (consolidated) rose to 0.80 as of June 30, 2026, from 0.72 as of March 31, 2026, indicating leverage increased in Q1 FY27. Working capital increased due to higher input prices and exports, leading to higher debt and finance costs. Margin expansion was observed (consolidated operating margin 14.54% in Q1 FY27 vs 11.35% in Q1 FY26). Deleveraging and free cash flow inflection are forward-looking.
Guidance: Zone IV initial revenue contributions expected in the second half of the year - Observed: Phase I of Zone IV was commissioned; commercialisation of all manufacturing blocks within Zone IV is targeted during the fiscal year. Revenue contribution timing is forward-looking.
Guidance: Commissioning of joint ventures - Observed: Superform JV expected commercialisation in Q2 FY27; Re Aarti expected commissioning in H2 FY27; Augene & Re Aarti JV commissioning and ramp-up included in the CAPEX-led growth driver (all projects to commission in FY27).
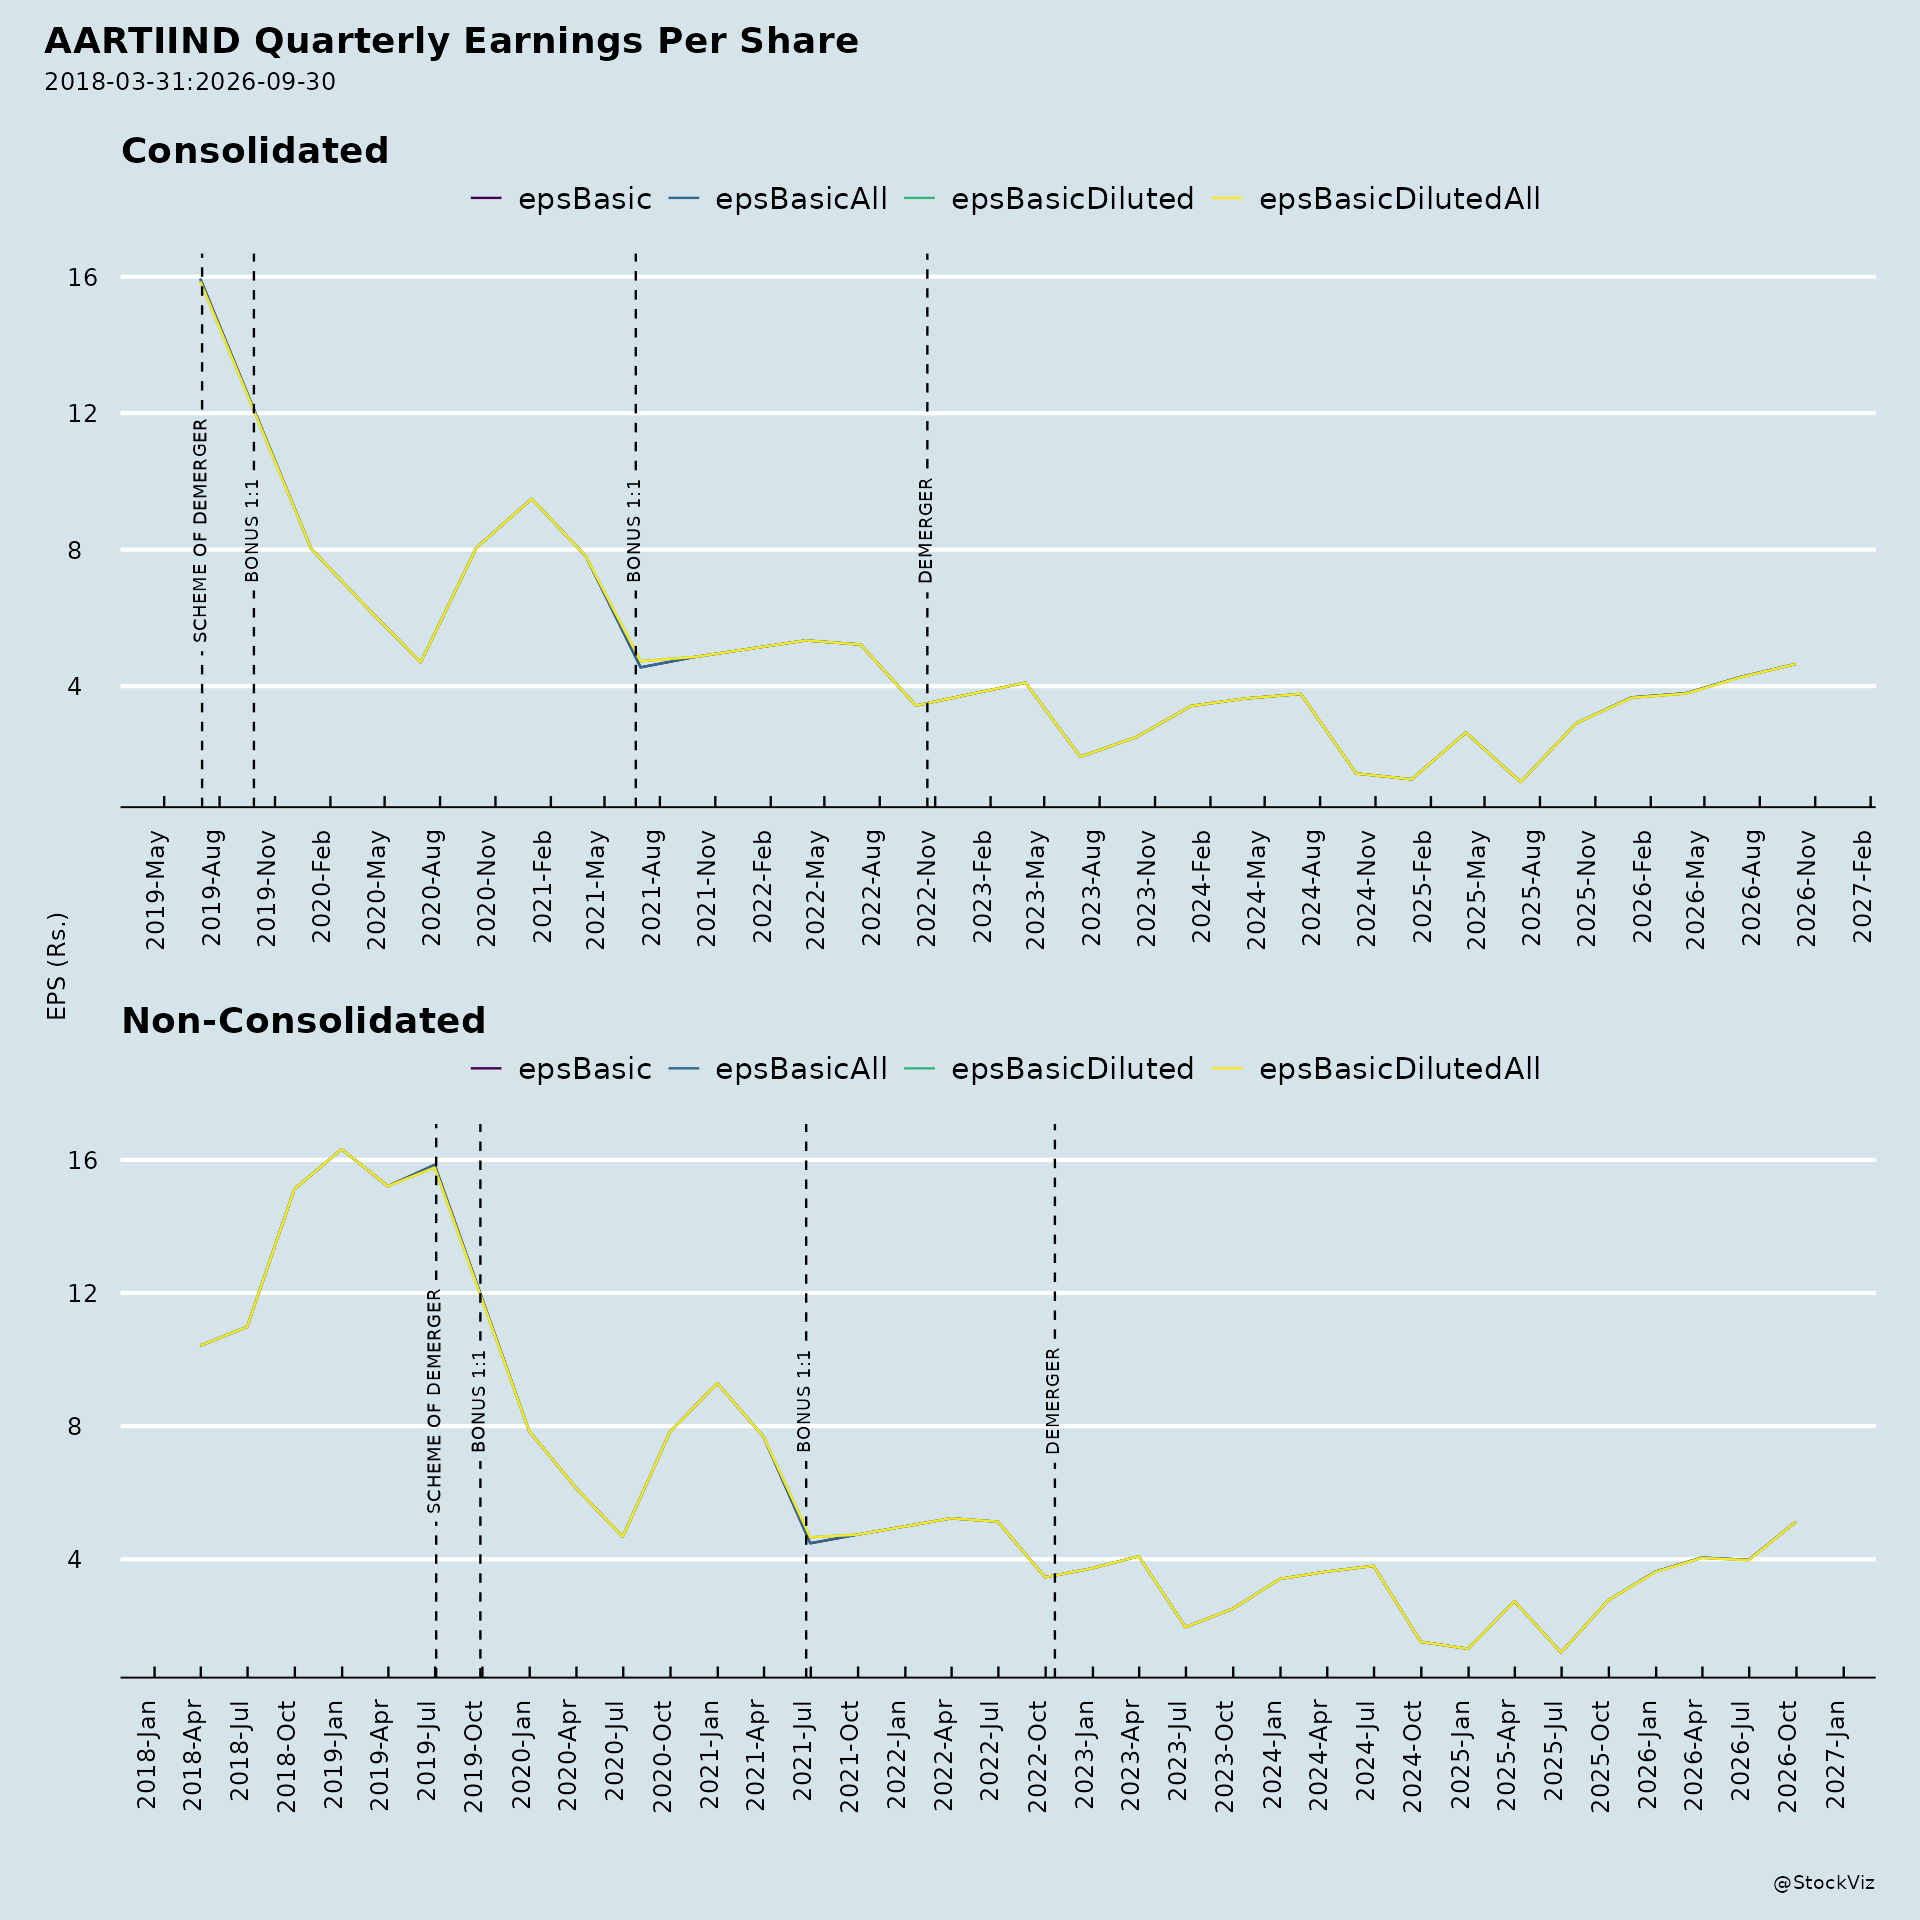
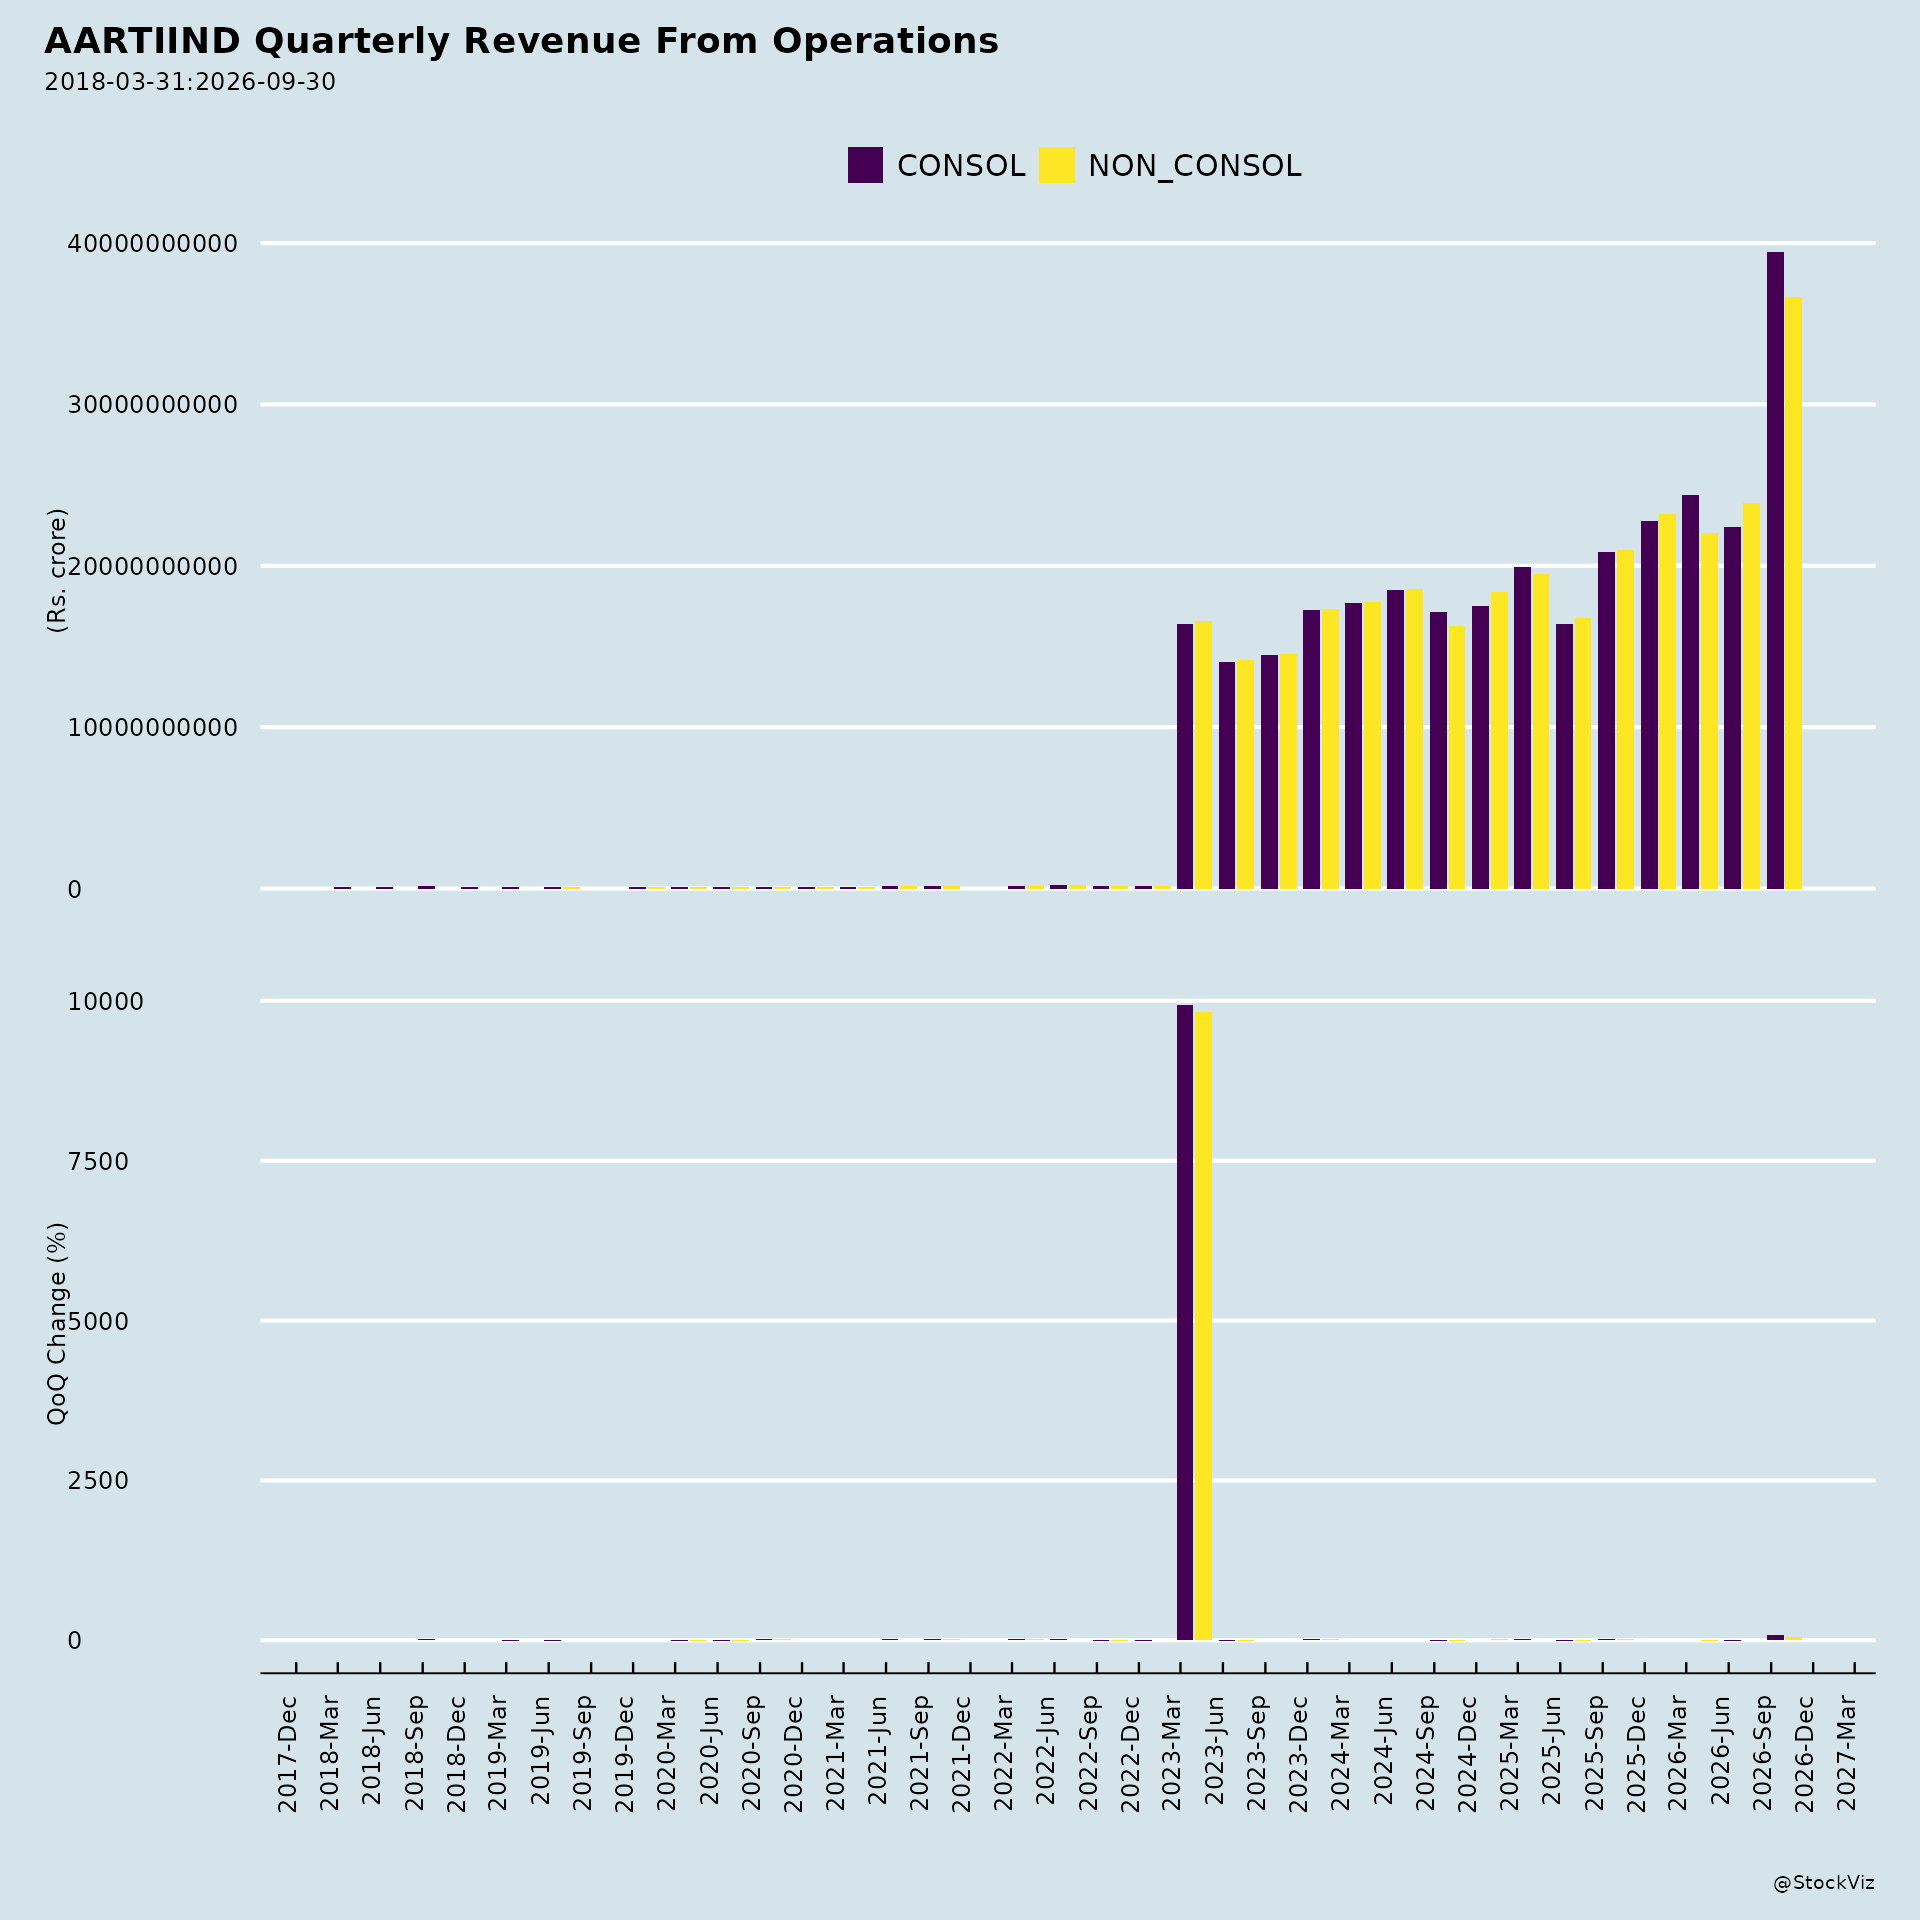
Other observed performance vs. guidance context - Q1 FY27 consolidated revenue from operations (net) was ₹2,387 Crs, up from ₹1,676 Crs in Q1 FY26 and ₹2,206 Crs in Q4 FY26. - Q1 FY27 consolidated PAT was ₹155 Crs, up from ₹43 Crs in Q1 FY26 and ₹137 Crs in Q4 FY26. - Q1 FY27 consolidated EPS (basic) was ₹4.27, vs ₹1.19 in Q1 FY26 and ₹3.79 in Q4 FY26. - The company divested its entire 100% equity stake in Shanti Intermediates Private Limited (through Aarti Corporate Services Limited), effective June 23, 2026; SIPL ceased to be a subsidiary. SIPL’s share of revenue and net profit to AIL had been below 0.1%, so the divestment is not expected to have a material impact. - The company issued 1,32,326 equity shares under the PSOP 2022 during the quarter, increasing paid-up share capital to ₹1,81,36,33,475. - Commercial Papers (listed) outstanding as on June 30, 2026 were ₹600 Crs, rated A1+ by both India Rating and CRISIL. - The company will attend the Anand Rathi Annual Flagship Conference G-200 Summit 2026 on September 22, 2026, in Mumbai for one-on-one and group meetings; these interactions are subject to last-minute changes due to exigencies on the part of the Investor/Company.
Broker Narrative
The broker story moved from a 2023 Hold built on weak end-use demand, slow long-term capacity ramp-up, poor cost absorption, textile/dye-pigment volume weakness, discretionary slowdown, Chinese competition and a stretched balance sheet to a 2026 Buy built on MMA/fuel-additive capacity, Zone IV flexibility, DCB/PPS, NCB spread recovery, ethylation and long-term contracts. The core worries persisted as project ramp-up/commissioning delays, aggressive Chinese pricing/raw-material volatility and operational/environmental risk, while the growth drivers shifted from broad capacity utilisation and 25% FY24 volume growth to fuel additives, geographic diversification and specialty downstream contracts. Early optimism on 20%/12% EBITDA/PAT CAGR and 25% FY24 volume growth was undercut by repeated 2024 negative actual returns and DISAPPOINTMENT outcomes before later fuel-additive/geographic tailwinds supported the Buy.
Fears that came true
- Slower-than-expected ramp-up of capacities meant for long-term projects materialized, since the last report still flags delays in commissioning, customer qualification or product approvals at Zone IV/new ventures and early 2024 Buy/Add calls produced -19.0%, -27.5% and -29.1% actual returns with DISAPPOINTMENT outcomes.
- Competition from Chinese producers in certain segments such as agrochemicals materialized as the last report still cites aggressive Chinese pricing and frames NCB spread recovery only after China’s export-rebate withdrawal, while 2024 actual returns included -43.4%, -37.4% and -34.7%.
- Persisting demand weakness in key end-use segments and the discretionary/textile volume slowdown materialized in the 2024 cluster of negative actual returns and DISAPPOINTMENT outcomes, including 2024-01-08 (-19.0%), 2024-01-18 (-27.5%), 2024-04-02 (-29.1%) and 2024-05-14 (-25.7%).
Optimism that failed
- The expected 20% EBITDA and 12% PAT CAGR over FY23-25E on rising capacity utilisation did not materialize into reliable positive outcomes, as 2024 Buy/Add calls with +11.4%, +11.1% and +6.9% predictions delivered -19.0%, -27.5% and -29.1% actual returns with DISAPPOINTMENT outcomes.
- Management’s guided 25% volume growth for FY24 failed to prevent the 2024 downturn, with actual returns such as -43.4% on 2024-02-09, -37.4% on 2024-08-12 and -34.7% on 2024-08-01.
- The guided FY25 ramp-up of long-term contracts 1, 2 and 3 (~70%, optimal, ~60-70%) was not a clean success, as the last report still flags project ramp-up/returns delays and 2026 Accumulate calls ended DISAPPOINTMENT on -1.0%, -1.3% and -10.4% actual returns.
Broker Timeline
35 broker calls · 2023-05-10 to 2026-11-01
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.