VISL
Equity Metrics
November 18, 2026
Vedanta Iron and Steel Limited
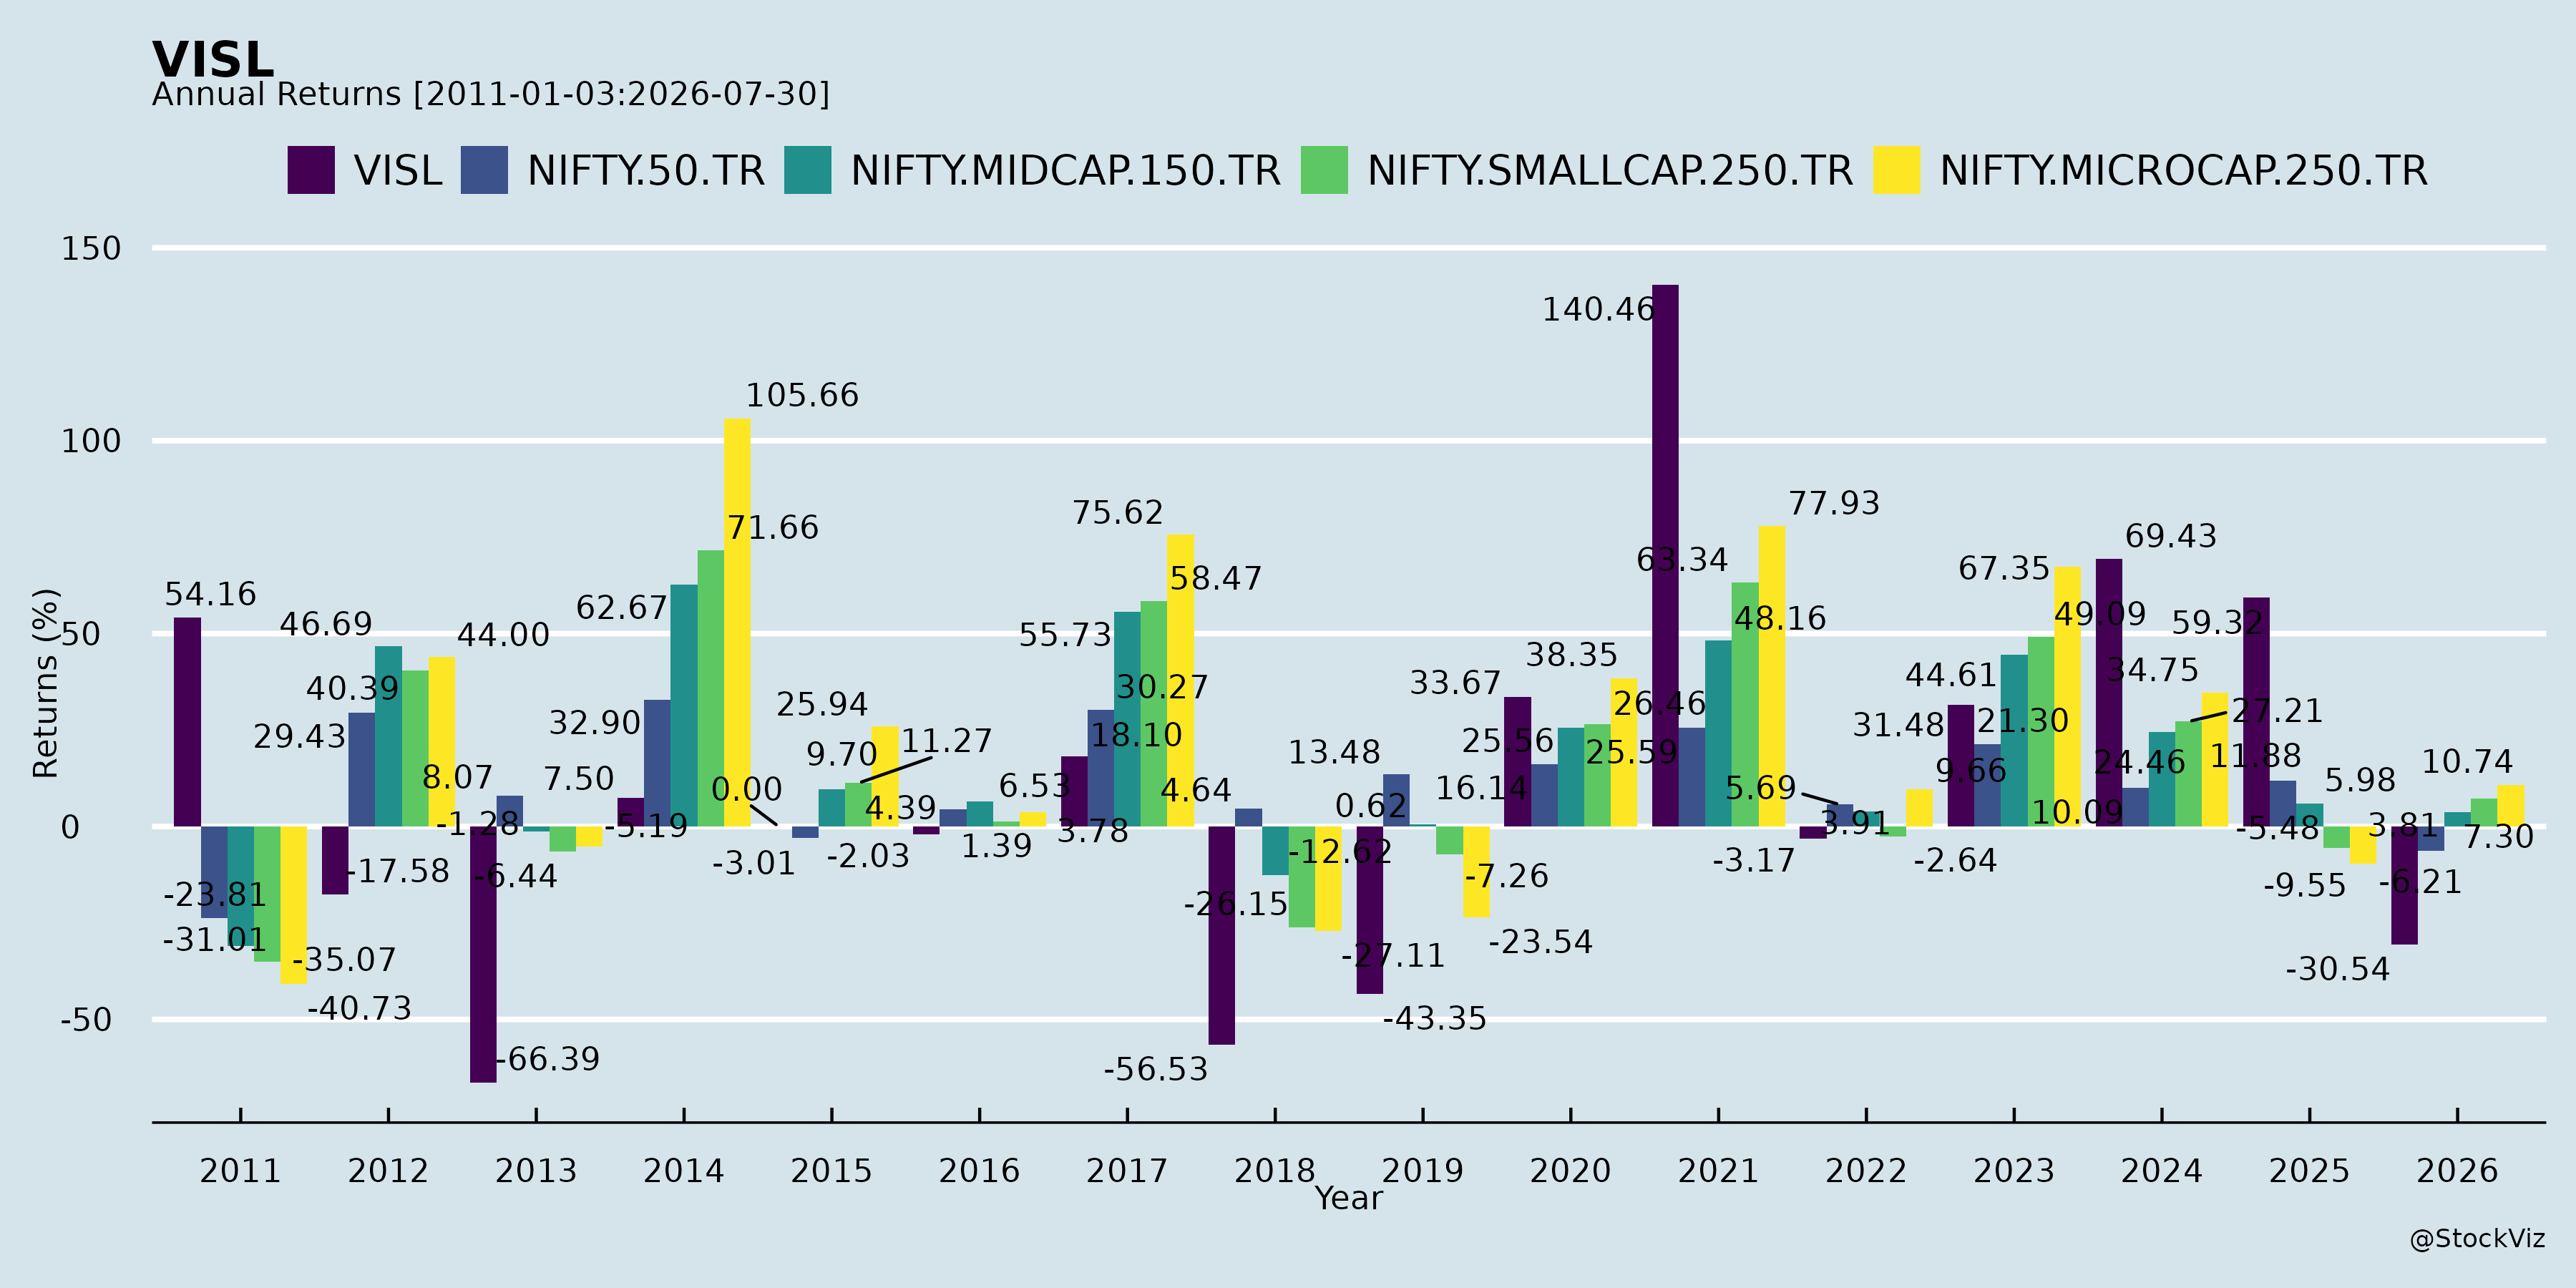
Annual Returns
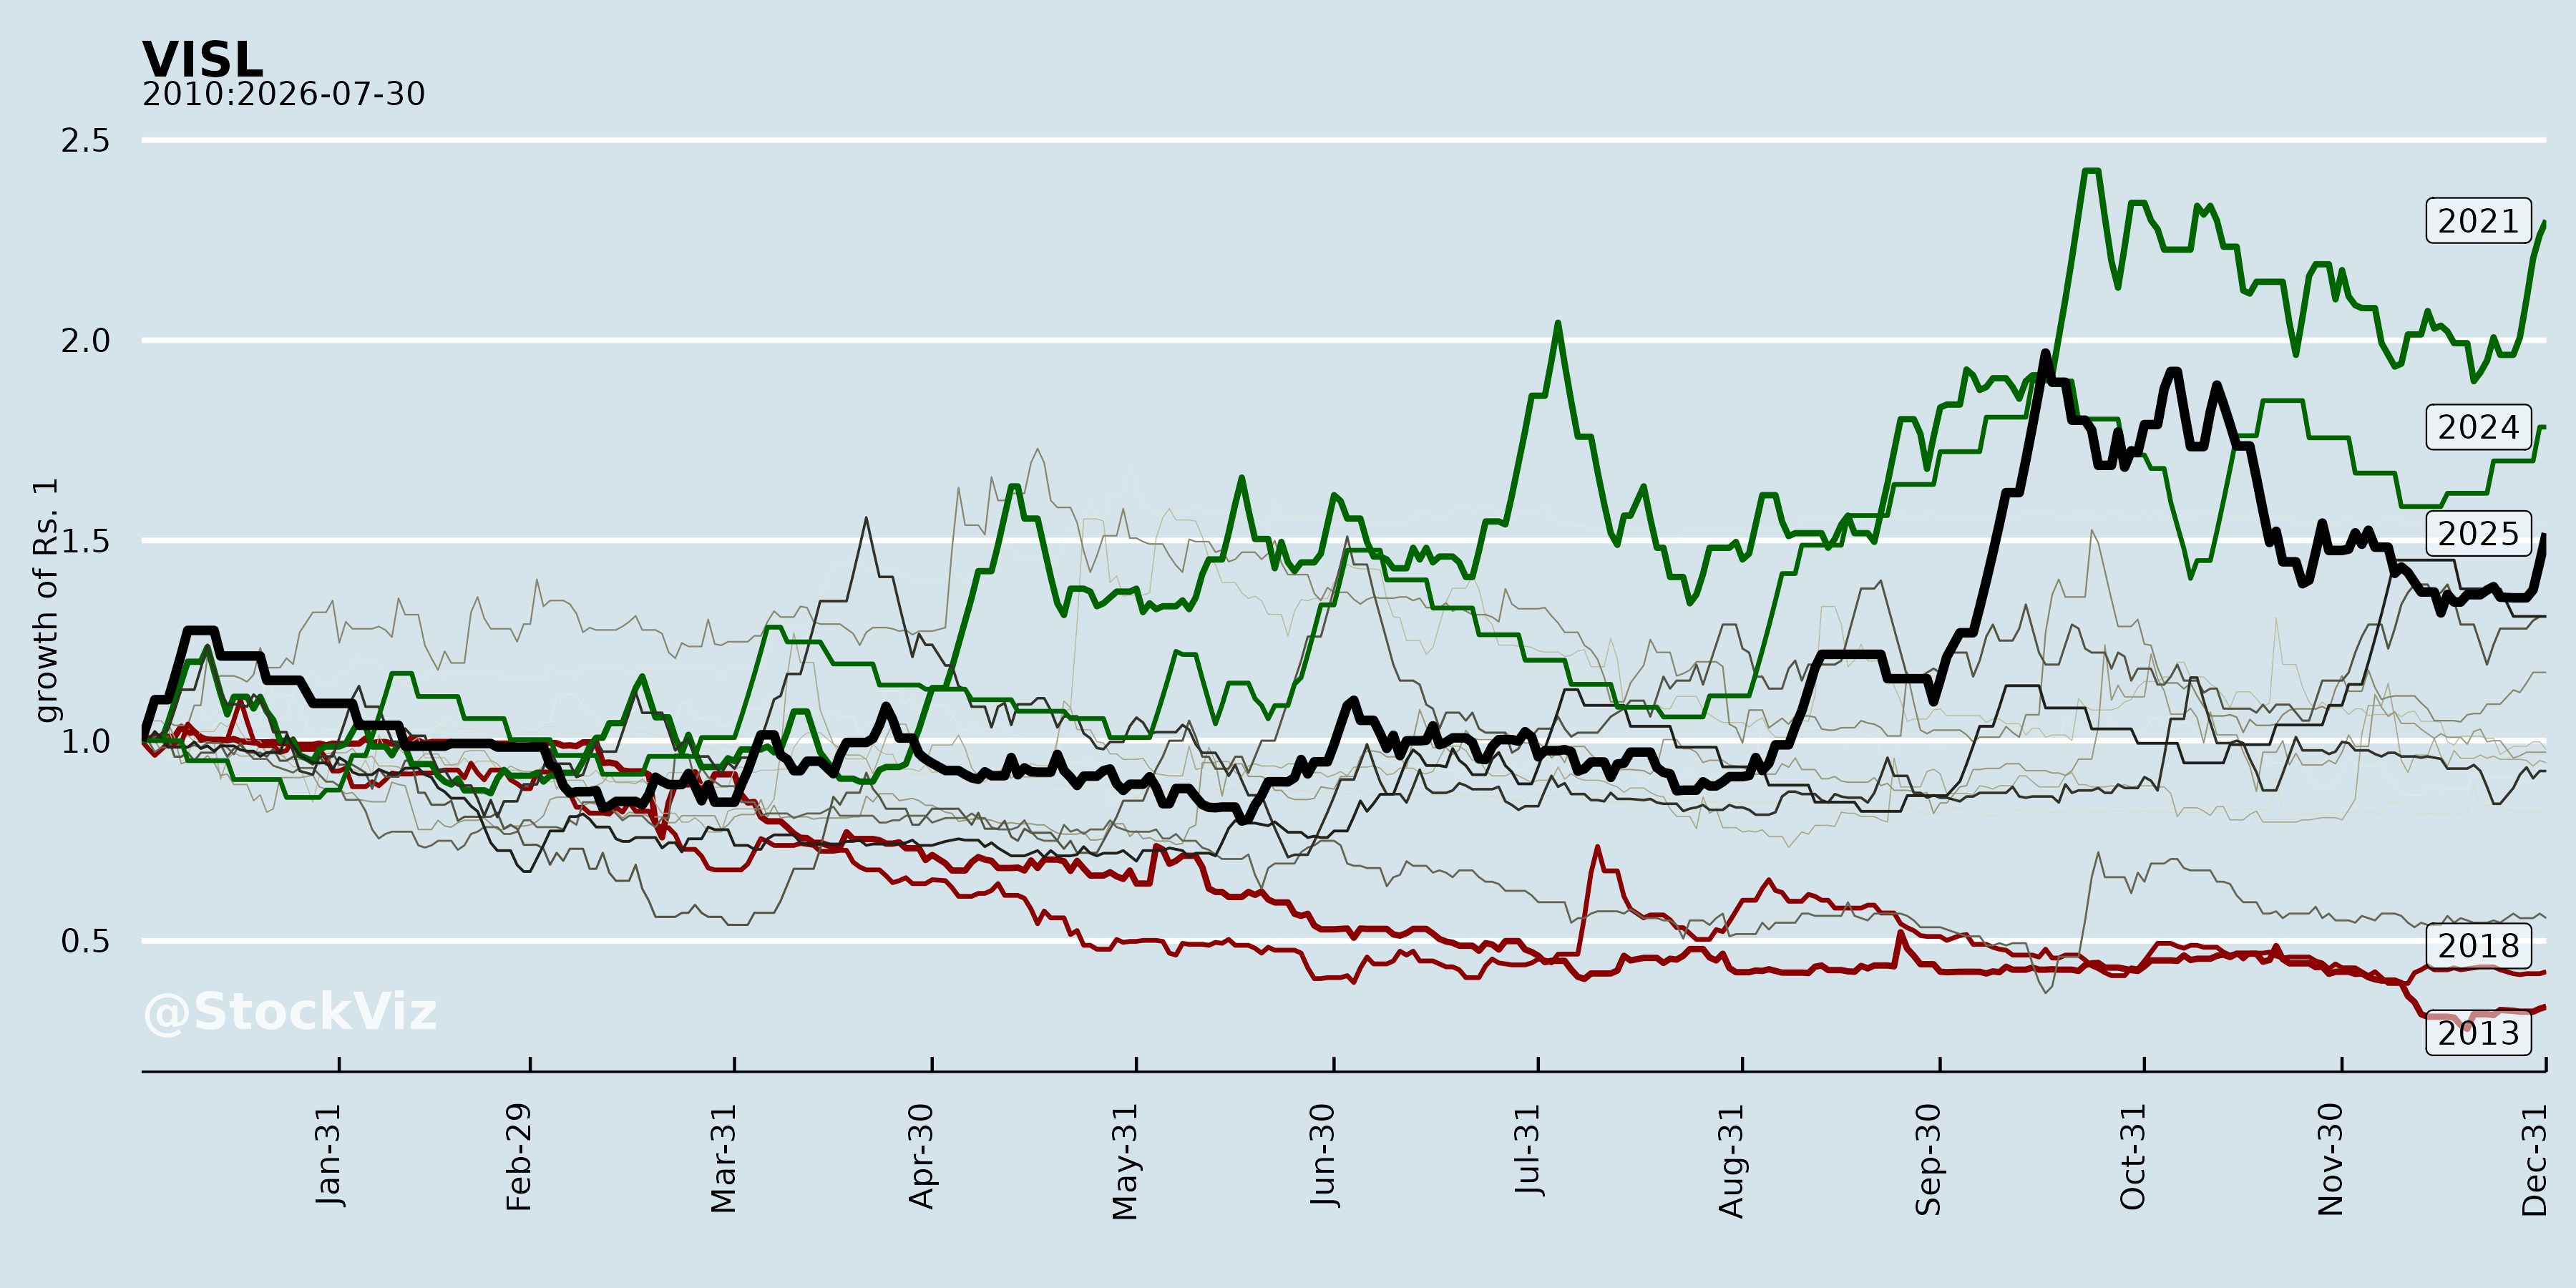
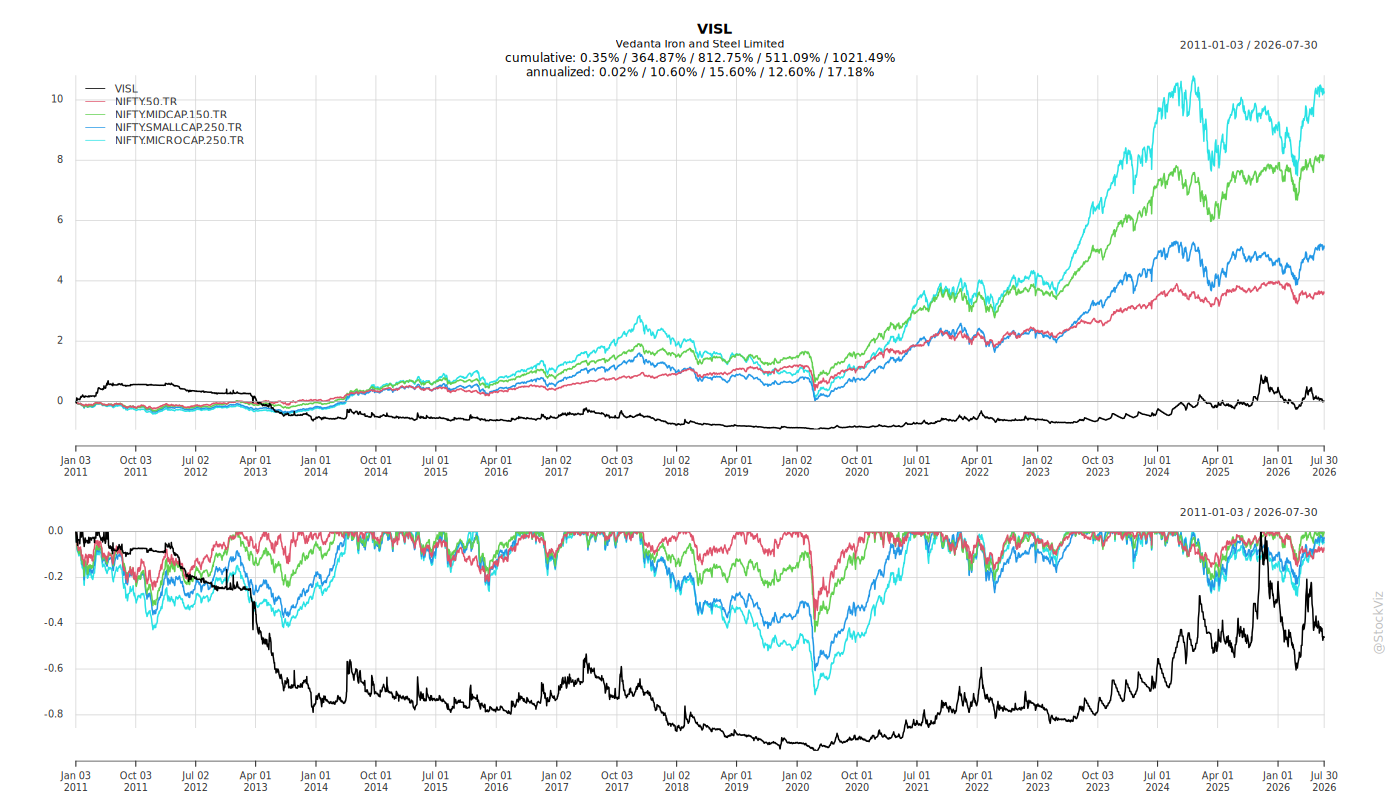
Cumulative Returns and Drawdowns
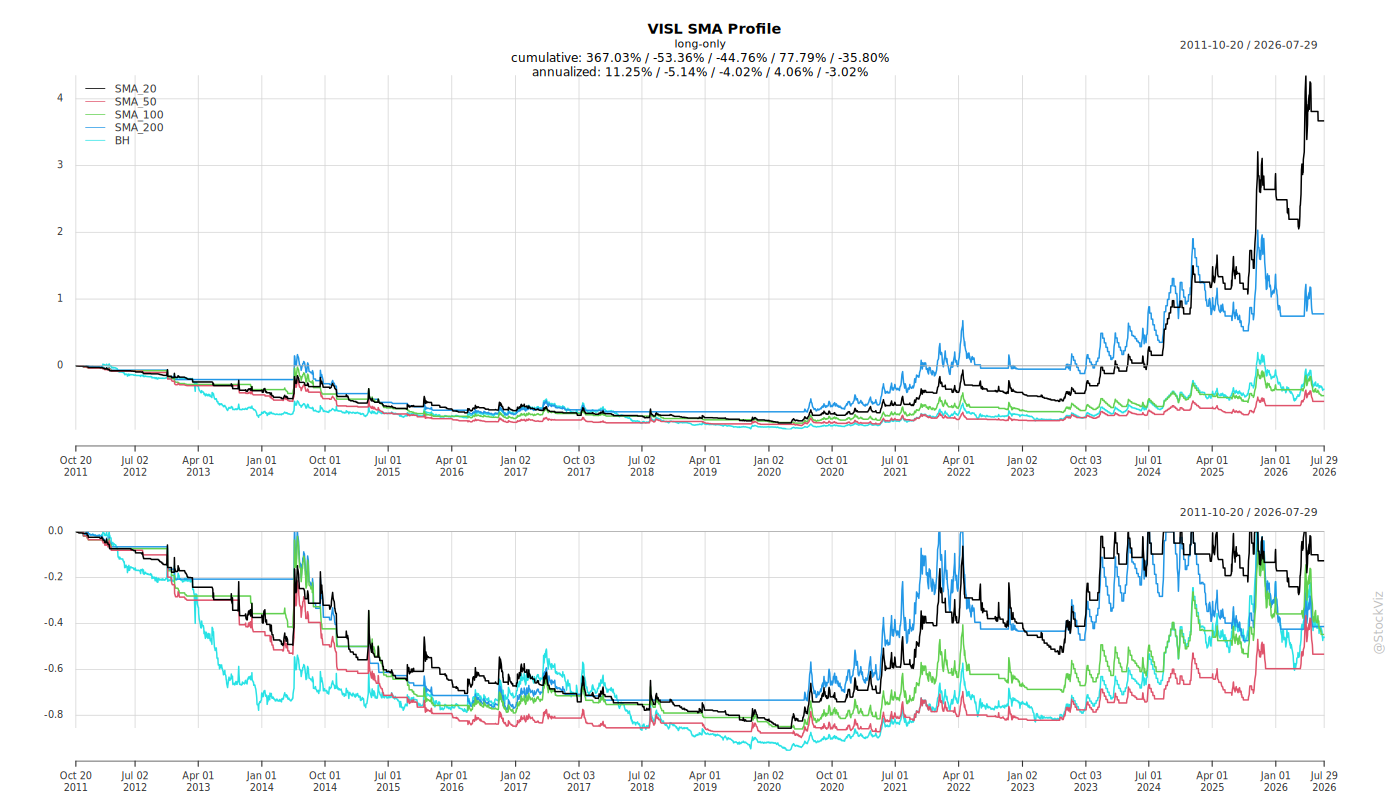
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-17
VISL: Recent Corporate Announcements — Analysis
1. Headwinds and Challenges
GST intimation on input tax credit (ESL Steel Limited). On August 07, 2026, ESL Steel Limited, a subsidiary of VISL, received an intimation in Form GST DRC-01A from the Office of the Principal Commissioner, Central Goods and Services Tax & Central Excise, Ranchi. The intimation alleges excess availment and utilization of Input Tax Credit on imports of goods during FY 2020-21 to FY 2022-23, amounting to Rs. 51,23,19,275 (IGST Rs. 6,73,39,655 and CESS Rs. 44,49,79,620). ESL is examining the intimation and states it will take appropriate steps within prescribed timelines. VISL states this will not have any significant financial and operational impact.
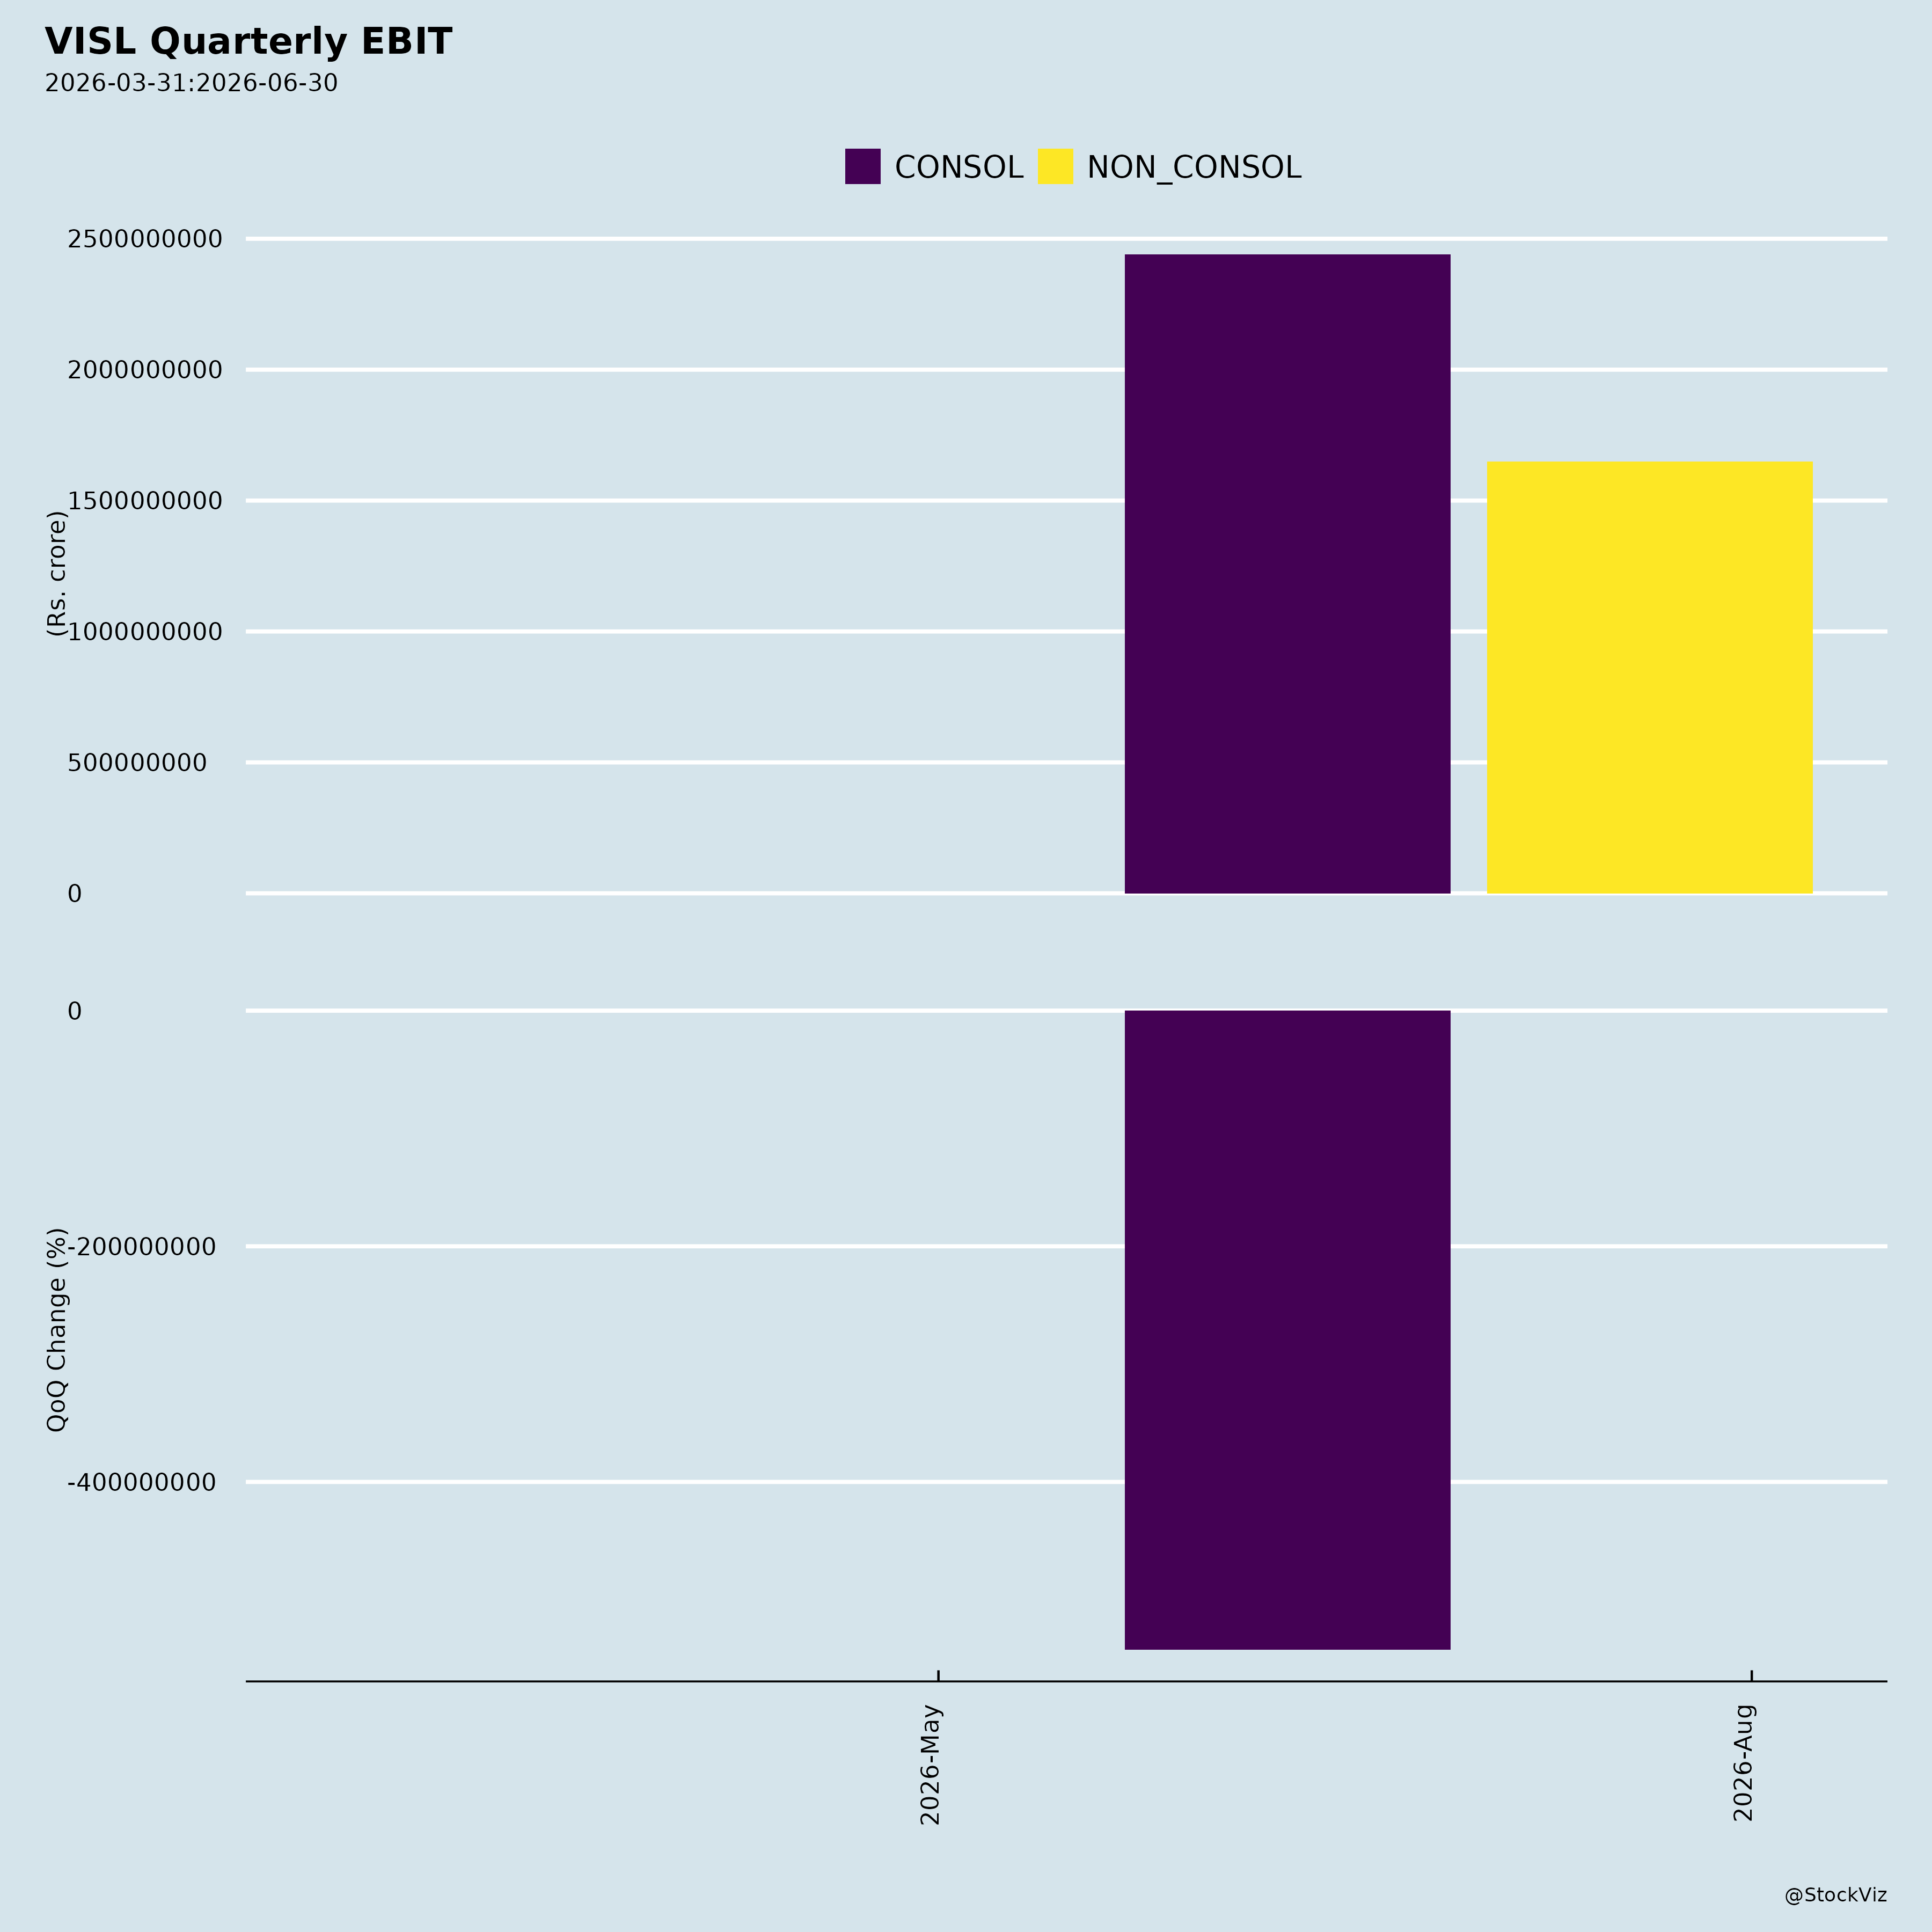
Monsoon-related seasonality. VISL attributes the 10% quarter-on-quarter decline in Q1 FY27 EBITDA to lower production and dispatches in mines due to the monsoon. Working capital increase is described as a strategic inventory build-up ahead of the monsoon season, expected to be released by Q2 FY27.
Environmental clearance and forest clearance matters at ESL Bokaro. ESL Steel Limited’s application for renewal of Consent to Operate (filed August 24, 2017) was denied by the Jharkhand State Pollution Control Board on August 23, 2018. The MoEFCC revoked the Environment Clearance on September 20, 2018. ESL was granted permission by the Hon’ble Supreme Court on September 22, 2020 to run the plant till further orders. Subsequent developments include: Stage I clearance and Terms of Reference approved August 25, 2020; EC rejected “as of now” on August 25, 2021 due to a Madras High Court stay on the MoEFCC Standard Operating Procedure; a Supreme Court order dated December 09, 2021 directing the MoEFCC to process the EC application; MoEFCC deferral of EC grant on February 02, 2022 pending Forest Clearance Stage-II; revocation of FC Stage-I on June 05, 2023; a Jharkhand High Court order dated May 01, 2025 setting aside the EC revocation on natural justice grounds and remanding the matter to MoEFCC for fresh hearing, with ESL permitted to continue operations subject to final decision under JSPCB supervision; a joint inspection on June 12, 2025; a second hearing on August 28, 2025; and a MoEF policy on Compensatory Afforestation penalty issued January 21, 2026 whose implications ESL is examining. Based on FAC recommendation, MoEFCC granted in-principle approval of FC Stage I on April 17, 2026. On receipt of FC and EC, ESL will apply for Consent to Establish and then Consent to Operate.
Western Cluster, Liberia impairment. During the quarter ended March 31, 2026, the Group recognized a provision for impairment of property, plant and equipment and inventory in West Africa (Western Cluster, Liberia) aggregating to Rs. 1,200 crore, and a provision of Rs. 271 crore for contractual obligations arising from cessation of operations. The impairment is attributed to continued uncertainty in project viability due to geopolitical factors including high stripping ratios, lower ore grades, and logistical constraints.
Jharkhand electricity duty matter. The Group filed writ petitions challenging the Jharkhand Electricity Duty (Amendment) Act, 2021. The High Court, by order dated January 05, 2026, upheld the levy for captive power plant generation; the Group has challenged this before the Supreme Court. A differential amount of Rs. 56 crore was provided for during the quarter ended March 31, 2026 as a matter of abundant caution.
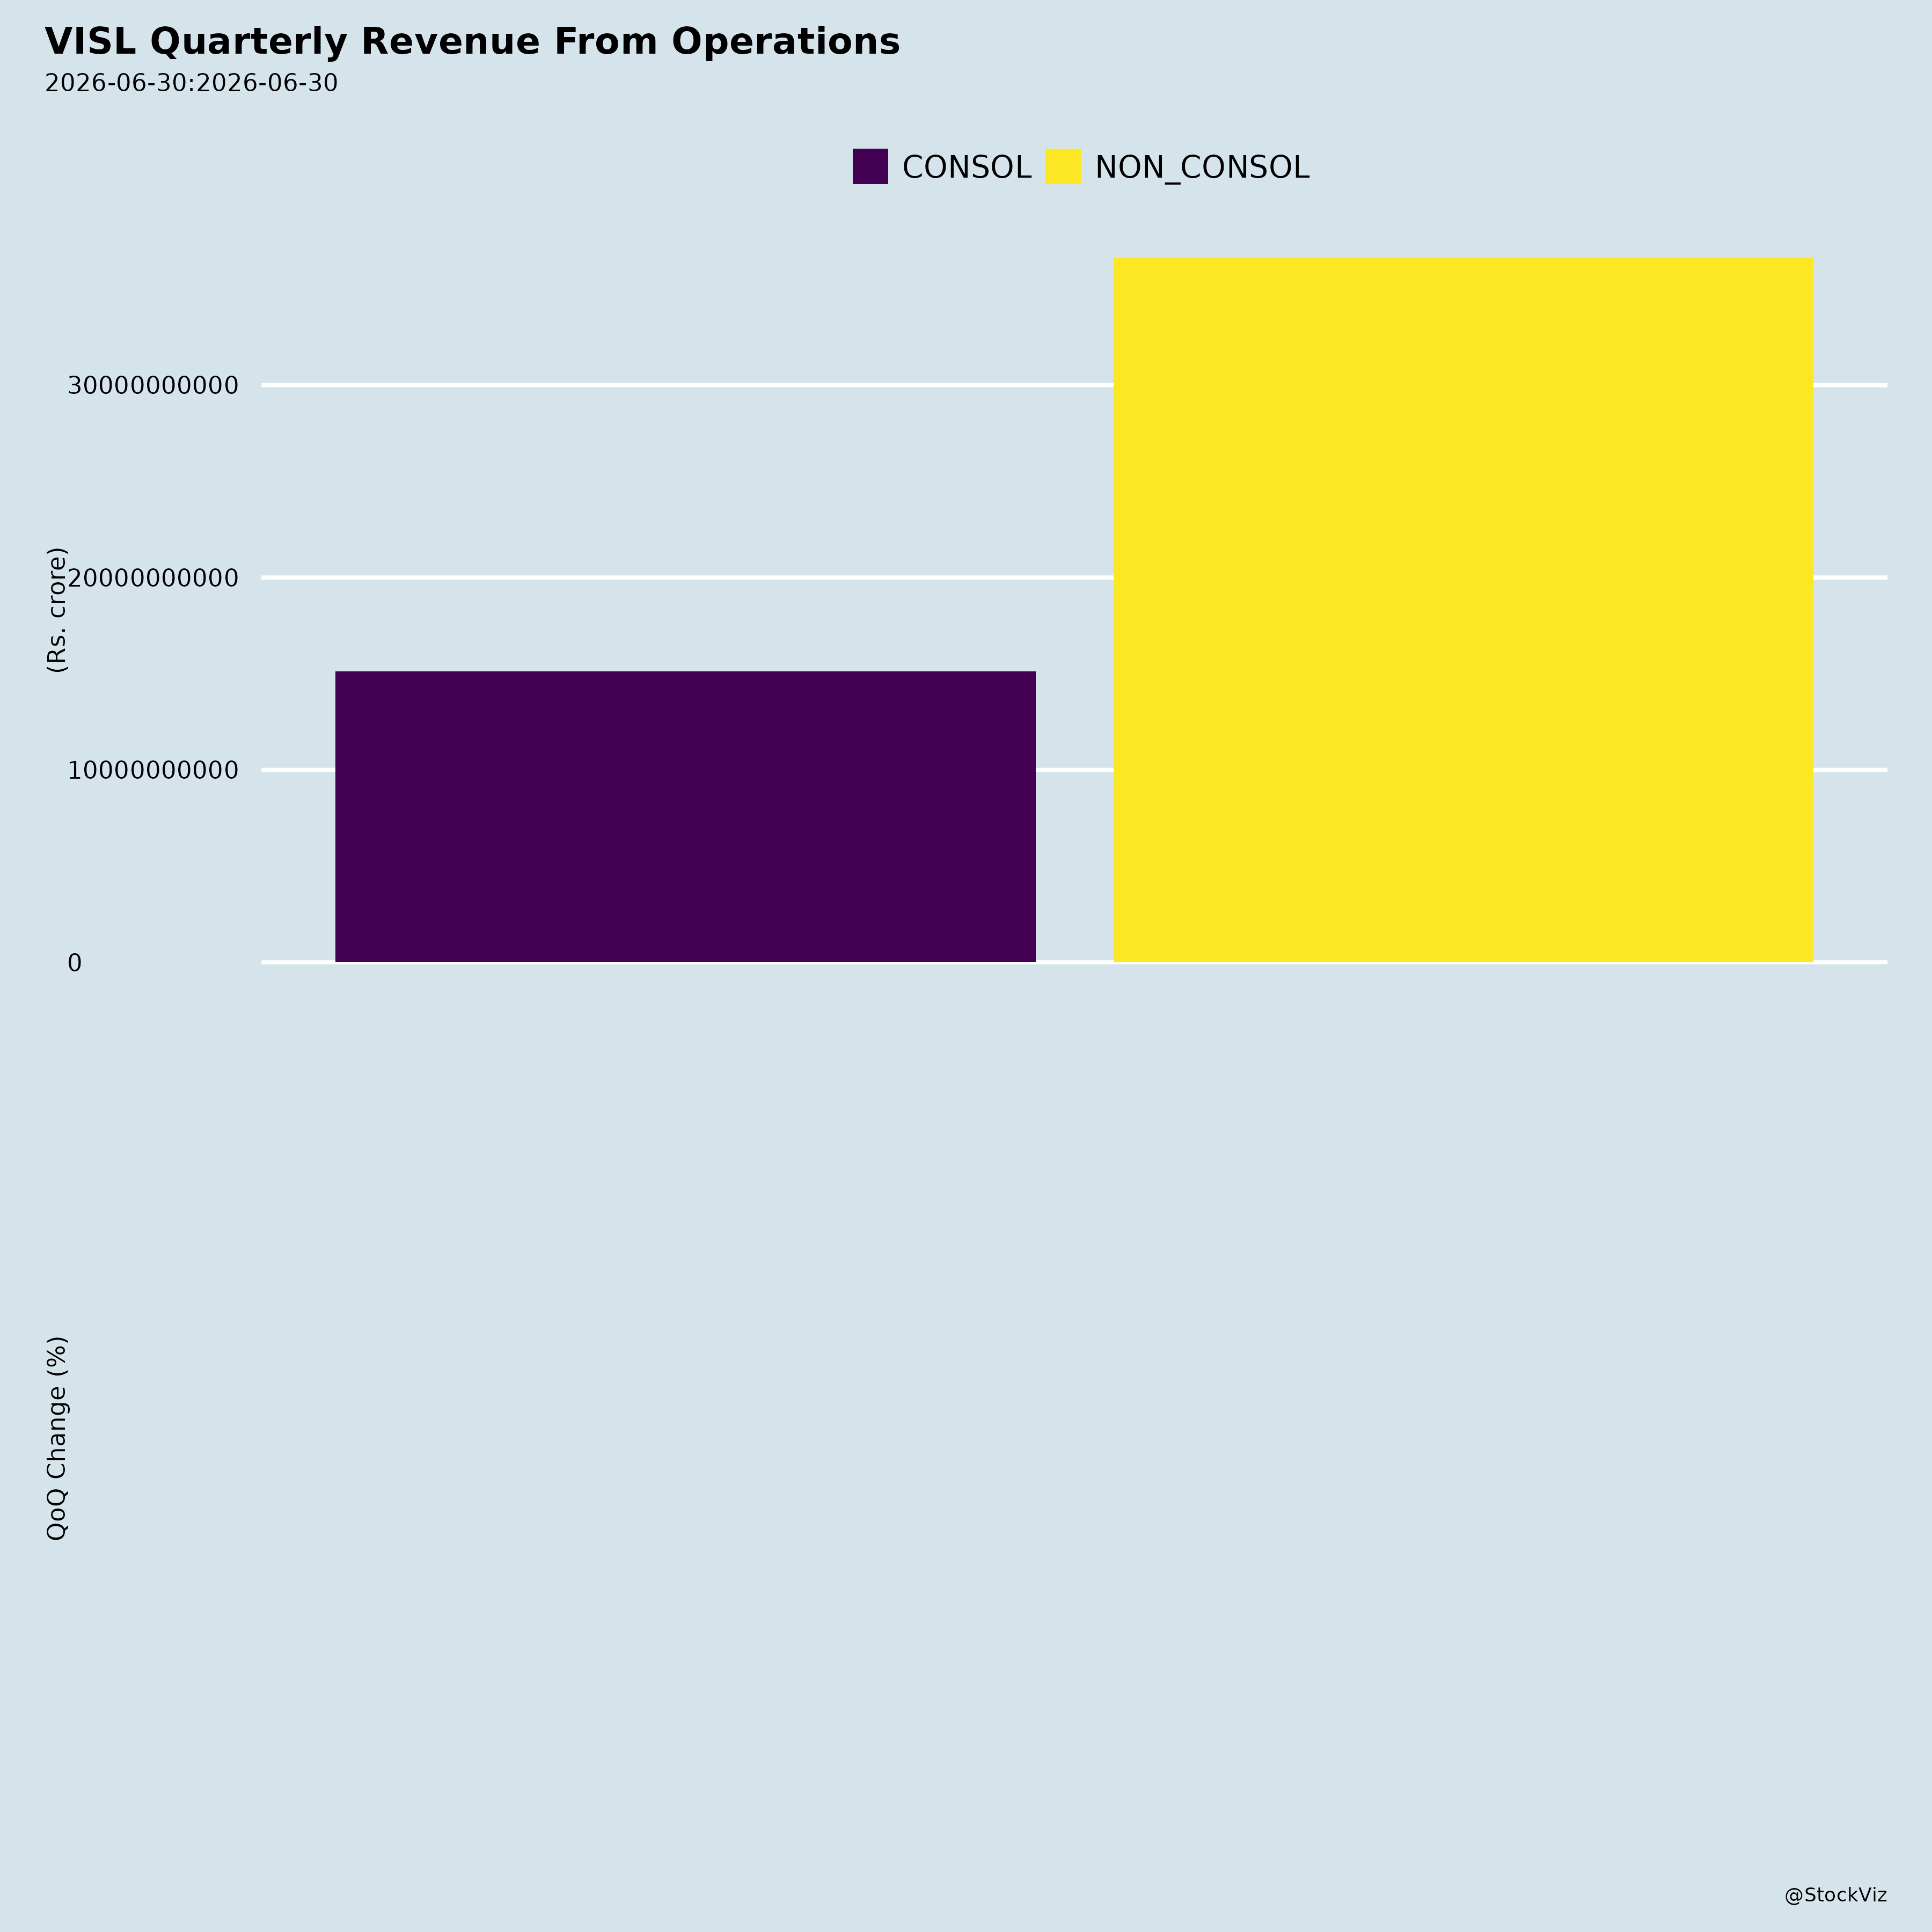
QoQ declines. Revenue from operations declined 5% QoQ (Rs. 3,612 crore in Q1 FY27 vs. Rs. 3,803 crore in Q4 FY26); EBITDA declined 10% QoQ (Rs. 515 crore vs. Rs. 574 crore); other operating income declined 17% QoQ and 20% YoY.
Segment-level production declines. Karnataka iron ore production declined 46% YoY (0.9 Mn DMT vs. 1.6 Mn DMT). Bokaro hot metal declined 2% YoY; Bokaro pig iron declined 6% YoY; TMT Bar production declined 2% YoY; Ductile Iron Pipes production declined 28% YoY (30 KT vs. 41 KT).
2. Tailwinds and Growth Prospects
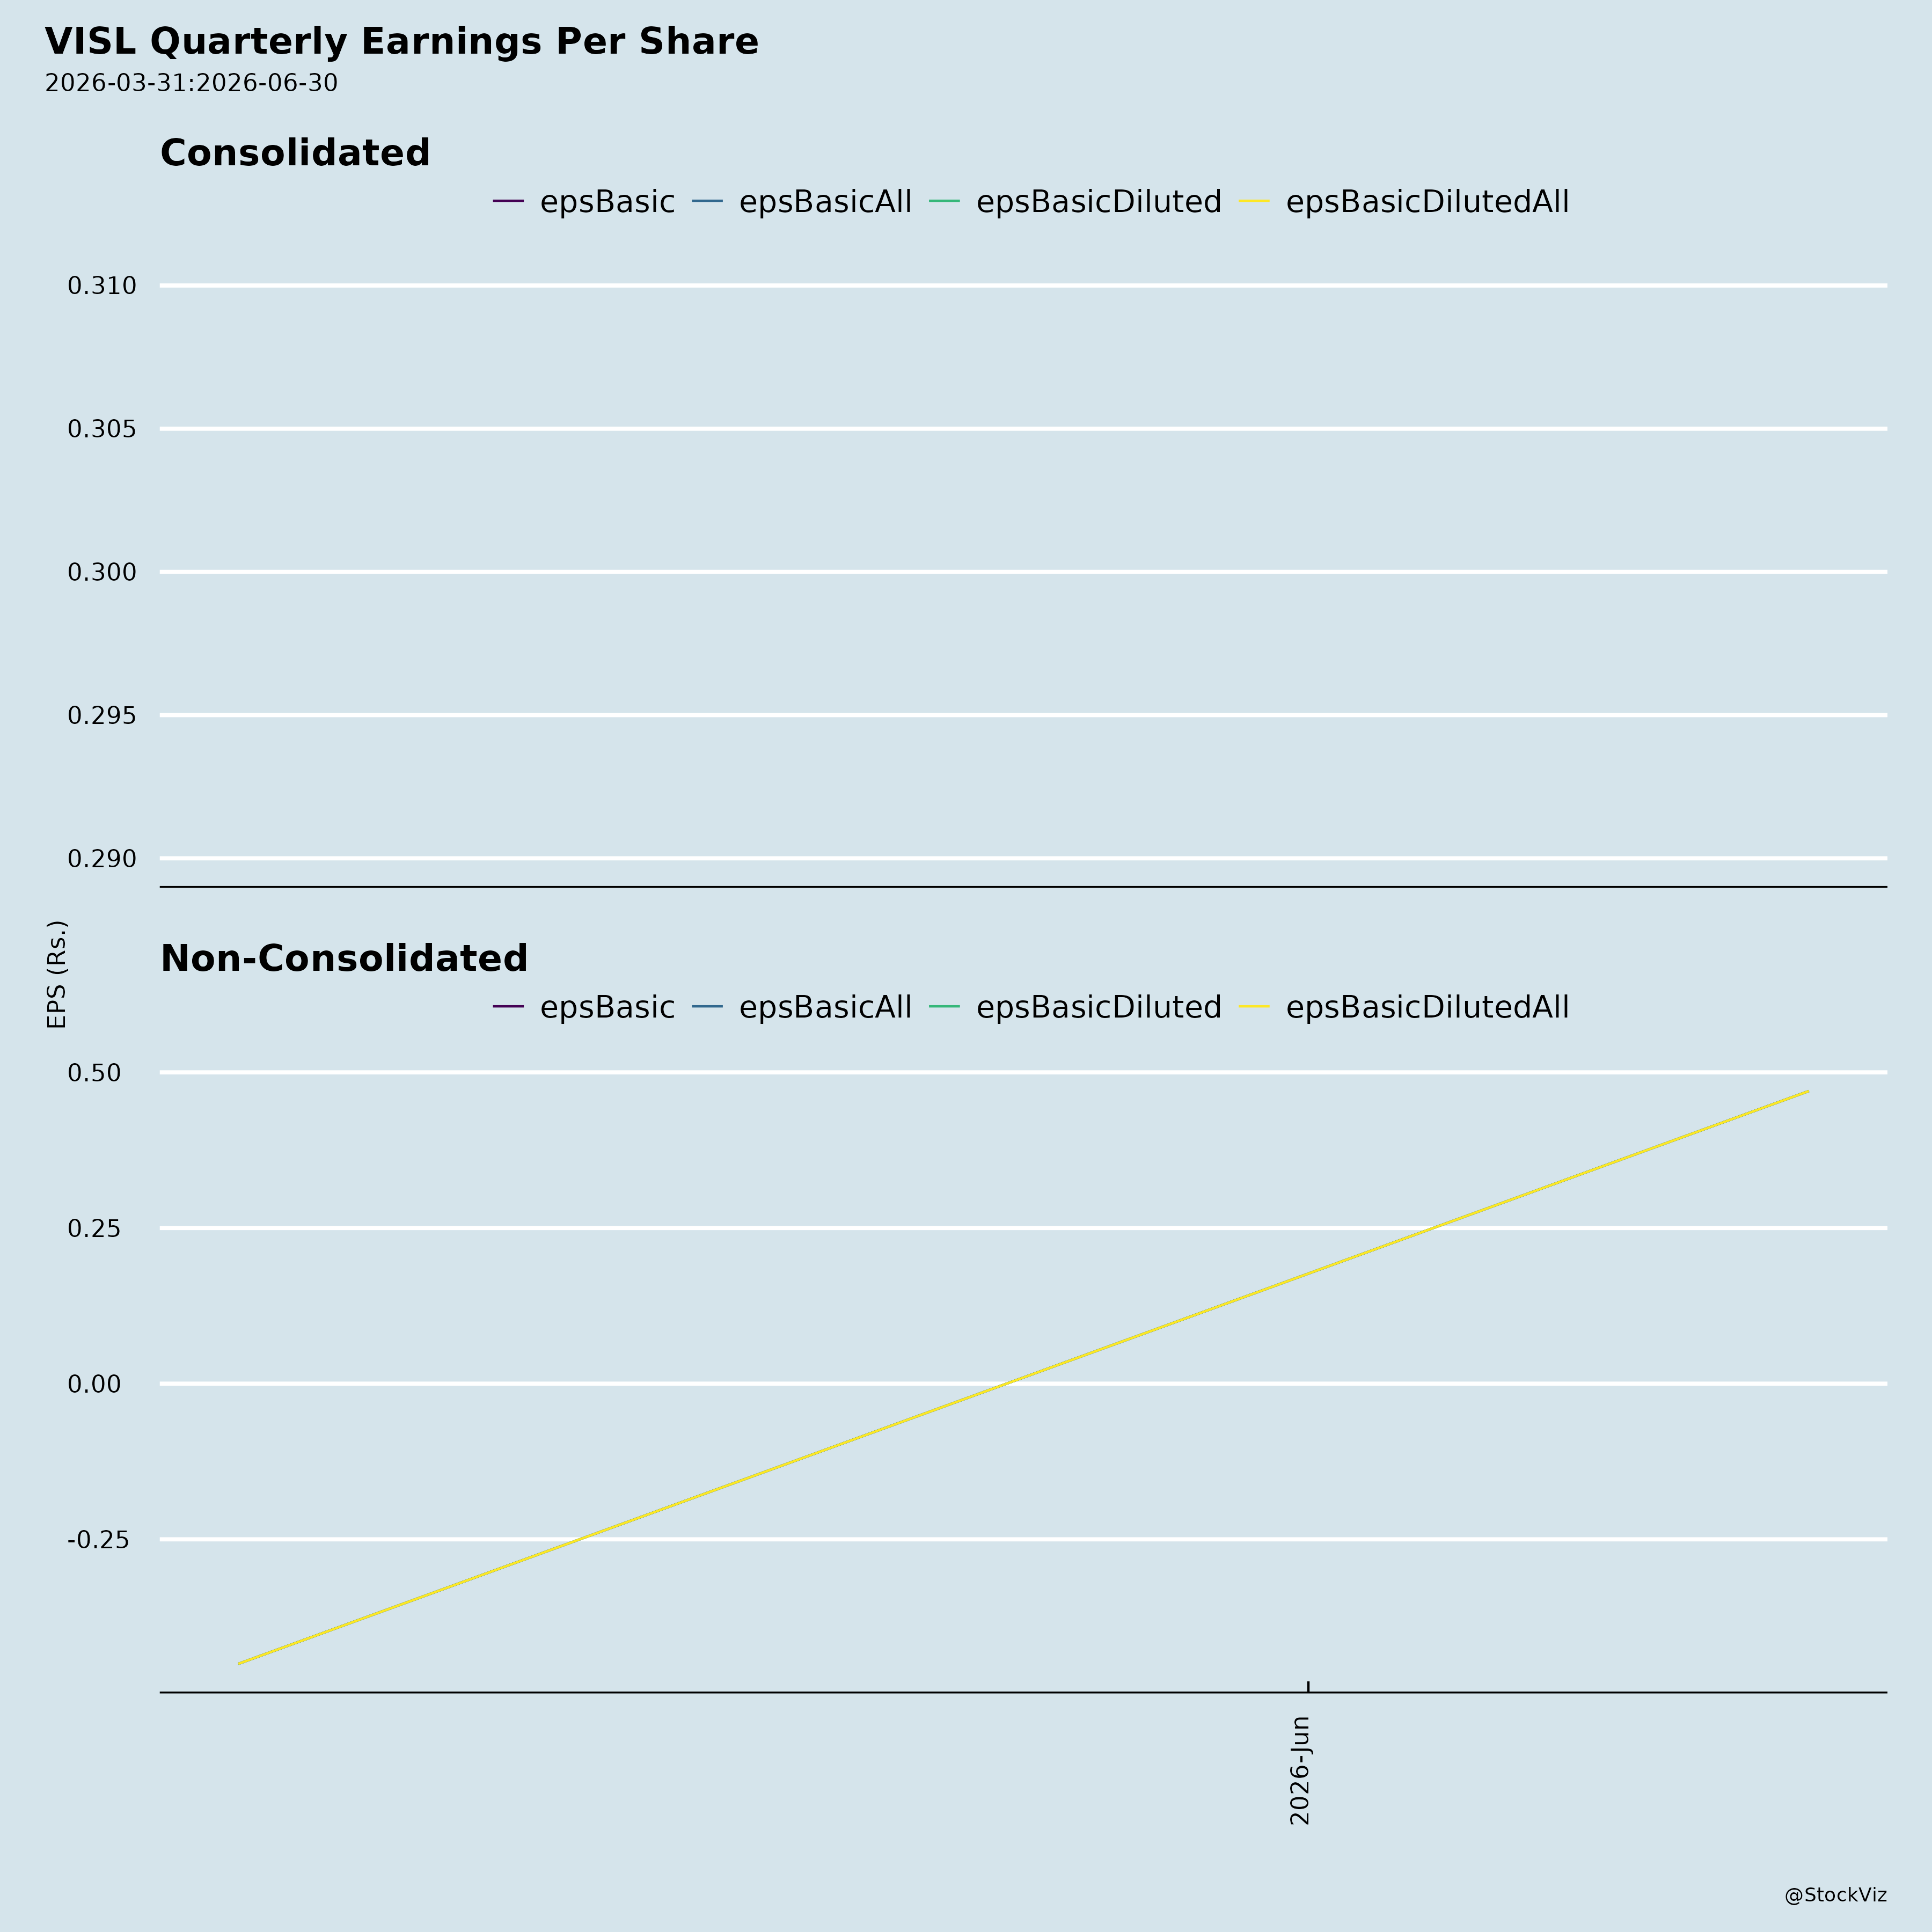
Q1 FY27 financial performance. Revenue from operations for the quarter ended June 30, 2026 stood at Rs. 3,662 crore (including other operating income), up 18% YoY, attributed to increased volumes and higher steel and iron ore prices. EBITDA rose 54% YoY to Rs. 515 crore, with margin improving 322 bps YoY from 11% to 14%. PAT was Rs. 121 crore versus a net loss of Rs. 145 crore in the corresponding quarter last year. Steel business EBITDA margin was Rs. 5,864/ton, up 60% YoY. Iron ore business EBITDA margin was Rs. 1,226/ton, up 24% YoY. Net Debt/EBITDA improved to 1.3x, with cash and cash equivalents at Rs. 1,018 crore.
Operational records. Highest ever quarterly Pig Iron production at 291 kt, up 8% YoY. Goa pig iron plant recorded its highest ever production at 238 kt, up 12% YoY. Iron ore production increased 4% YoY to 2.6 Mn DMT. Steel saleable production increased 4% YoY and 2% QoQ to 582 KT. The DI Pipe Plant at ESL Bokaro delivered best-ever yield of 97.54% and lowest-ever rejection rate of 4.60%. BF#3 at ESL Bokaro achieved a record PCI rate of 187 kg/THM. The New Screening Plant at IOG was commissioned.
Finance cost reduction. Finance cost declined 55% YoY (from Rs. 461 crore in Q1 FY26 to Rs. 207 crore in Q1 FY27) and 53% QoQ, primarily on account of reduced debt pre- and post-demerger. Interest income declined 67% YoY and 64% QoQ due to elimination of inter-division receivables per the demerger scheme.
Debt reduction. Gross debt declined from Rs. 4,678 crore in March 2026 to Rs. 2,792 crore in June 2026. Net external debt reduced to Rs. 1,773 crore in June 2026 from Rs. 2,862 crore in March 2026. Inter-company debt declined from Rs. 9,434 crore to Rs. 960 crore. Total net debt declined from Rs. 12,296 crore to Rs. 2,733 crore. Net external debt/EBITDA stands at 1.3x in Q1 FY27. Credit rating is AA/Stable by CRISIL.
Demerger and listing. The Hon’ble National Company Law Tribunal, Mumbai Bench, approved the Scheme of Arrangement on December 16, 2025, providing for demerger of the Iron Ore Undertaking of Vedanta Limited into the Company. The Scheme became effective on May 1, 2026. VISL issued 1 equity share for every 1 equity share of Vedanta Limited held as on the Record Date of May 1, 2026; allotment of 3,91,03,88,057 equity shares was approved on May 4, 2026, and the Company ceased to be a subsidiary of Vedanta Limited. The equity shares were listed and admitted to trading on BSE Limited and NSE on June 15, 2026.
MetCoke business acquisition. The Group entered into a Business Transfer Agreement dated April 30, 2026 with MALCO Energy Limited for purchase of the MetCoke business on a slump sale basis for a consideration of Rs. 1. The book net worth was Rs. (299) crore (negative), and the difference of Rs. 299 crore was recognized in capital reserve.
Port business divestment. Sesa Mining Corporation Limited entered into a Business Transfer Agreement dated April 30, 2026 with Vedanta Base Metals Limited to hive off the Port Business at Visakhapatnam on a slump sale basis for a consideration of Rs. 452 crore. The book net worth was Rs. 452 crore, and no gain or loss arose. The Port Business is disclosed as discontinued operations.
Debt waiver at Bloom Fountain Limited. Fujairah Gold FZE and THL Zinc Limited irrevocably waived and released BFL from outstanding debts effective April 30, 2026. Total outstanding debt comprising principal, accrued interest and other payables of Rs. 13,138 crore was written back in BFL’s books and transferred to Capital Reserve.
Growth projects. Capex in progress: Ductile Iron Pipe – Goa (approved capex Rs. 722 crore; Rs. 17 crore spent in Q1 FY27; Rs. 342 crore spent up to Q1 FY27; balance Rs. 380 crore) and ESL Phase 1A (approved capex Rs. 2,975 crore; Rs. 64 crore spent in Q1 FY27; Rs. 2,223 crore spent up to Q1 FY27; balance Rs. 752 crore). Total approved capex Rs. 3,697 crore; Rs. 81 crore spent in Q1 FY27; Rs. 2,565 crore spent up to Q1 FY27; balance Rs. 1,132 crore.
Project pipeline. FY27: Bicholim Mine (Goa) expansion from 3 to 3.6 MTPA; 0.5 MTPA Cudnem Mine (Goa); ESL Bokaro coke oven of 0.5 MTPA, hot metal capacity expansion from 1.7 to 3.2 MTPA, DIP of 0.2 MTPA; VAB Goa 0.42 MTPA DI Pipe Plant. FY28: Janthakal Mine (Karnataka). Project timelines are subject to statutory permissions.
India steel demand outlook. India has one of the lowest per capita steel consumption at 102 kg versus a global average of 215 kg. Indian steel production is projected to grow at a CAGR of 8.7%, with a likely supply gap creating headroom for iron ore production expansion. Continued policy support, infrastructure expansion, and investments in green steel technologies are cited as positioning the industry well.
ESG and community initiatives. Programs reached more than 10,000 community members every month. Flagship initiatives include over 100 Nand Ghars, a TACO-supported Animal Birth Control Centre, 20+ Vedanta Computer Centres & Labs, the Sesa Football Academy, and the ESL Archery Academy. Environmental performance included renewable energy, low-carbon power generation, EV induction, and plantation of over 55,000 saplings. Since FY21: ~31 million units RE consumed, 3719 million units WRHB generation, ~5,89,000 trees planted. Workforce: 21% women, 38% in enabling functions, 7 LGBTQ+, 4 specially-abled. Communities: ~5,48,000 women & children, ~38,000 individuals skilled.
Awards and recognition. Recognized by Mormugao Port Authority for highest export cargo tonnage. Best Safety & Health Culture of the Year Award at Minerals & Mining Conclave 2026 and ASSOCHAM Business Excellence Awards. Gold Award at CII IQ National Safety Practice Competition 2026. Platinum Award for Best Kaizen in Large Manufacturing Category. Recognized among India’s Best Workplaces in Basic Metals & Fabricated Metal Products 2026 by Great Place to Work. Recognized by Great Place to Work in Mining & Quarrying category for the seventh consecutive year.
3. Key Risks
GST ITC matter. The alleged excess availment and utilization of ITC of Rs. 51,23,19,275 for FY 2020-21 to FY 2022-23. ESL is evaluating appropriate legal remedy. VISL states there is no material impact on financial, operations and/or other activities.
Environmental and forest clearance uncertainty at ESL Bokaro. The matter remains pending final decision of MoEFCC, with ESL permitted to continue operations subject to that decision under JSPCB supervision. In-principle approval of FC Stage I was granted April 17, 2026; FC and EC are still required before CTE and CTO applications can be made.
Western Cluster, Liberia. Continued uncertainty in project viability due to geopolitical factors including high stripping ratios, lower ore grades, and logistical constraints led to impairment and provisions in Q4 FY26.
Jharkhand electricity duty. The matter is pending before the Hon’ble Supreme Court of India after the High Court upheld the levy for captive power plant generation on January 05, 2026.
Monsoon seasonality. Lower production and dispatches in mines due to monsoon affected Q1 FY27 QoQ performance.
Forward-looking statement uncertainties. The Company cites uncertainties arising from behaviour of financial and metals markets including the London Metal Exchange, fluctuations in interest and/or exchange rates and metal prices, future integration of acquired businesses, and numerous other matters of national, regional, and global scale including political, economic, business, competitive or regulatory nature.
Project execution risk. Project timelines are subject to statutory permissions.
4. Management Guidance Versus Observed Business Performance
Management commentary (Q1 FY27). Pankaj Kumar Sharma, CEO & WTD, stated VISL delivered a resilient operational and financial performance in Q1 FY27 despite a dynamic market environment, with higher iron ore production, record quarterly pig iron output, operational efficiencies across steel businesses, and continued focus on value-added products supporting strong margin improvement. He stated the Company remains focused on executing growth projects, improving cost competitiveness, and building a sustainable platform for long-term value creation. Navin Jaju, CFO, stated VISL reported healthy revenue growth of 18% and EBITDA growth of 54% YoY during the quarter, that the business continues to maintain a strong liquidity position while investing in strategic growth projects, and that disciplined capital allocation, improving operating performance and focus on cash generation position it well for the next phase of expansion.
Observed performance versus commentary. The reported figures align with the commentary: revenue growth of 18% YoY and EBITDA growth of 54% YoY were delivered. Record quarterly pig iron production of 291 kt (up 8% YoY) and highest-ever Goa pig iron production of 238 kt (up 12% YoY) were achieved. Steel EBITDA margin improved 60% YoY to Rs. 5,864/ton. Iron ore EBITDA margin improved 24% YoY to Rs. 1,226/ton. Liquidity position: cash and cash equivalents of Rs. 1,018 crore. Net external debt/EBITDA of 1.3x.
Working capital guidance. The Company states the working capital increase reflects strategic inventory build-up ahead of the monsoon season, which will be released by Q2 FY27.
Project timeline guidance. FY27 and FY28 project timelines are stated subject to statutory permissions. Capex progress: Rs. 81 crore spent in Q1 FY27 against total approved capex of Rs. 3,697 crore; Rs. 2,565 crore spent up to Q1 FY27; balance of Rs. 1,132 crore.
ESL clearance pathway. On receipt of FC and EC, ESL will apply for CTE and then CTO. In-principle approval of FC Stage I was granted April 17, 2026.
Demerger accounting. Comparative periods have been presented as if the Scheme became effective from April 1, 2025. The MetCoke business figures have been re-presented/re-computed as if the transaction occurred from April 1, 2025. The Port Business is disclosed as discontinued operations with prior period figures re-presented/re-computed.
Auditor review. The statutory auditors, S.R. Batliboi & Co. LLP, issued an unmodified conclusion on the consolidated and standalone financial results for the quarter ended June 30, 2026. The report notes reliance on other auditors for 5 subsidiaries (total revenues of Rs. 416 crore, total net loss after tax of Rs. 62 crore for the quarter ended June 30, 2026) and on predecessor auditors for certain comparative periods.
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.