VEDL
Equity Metrics
September 24, 2026
Vedanta Limited
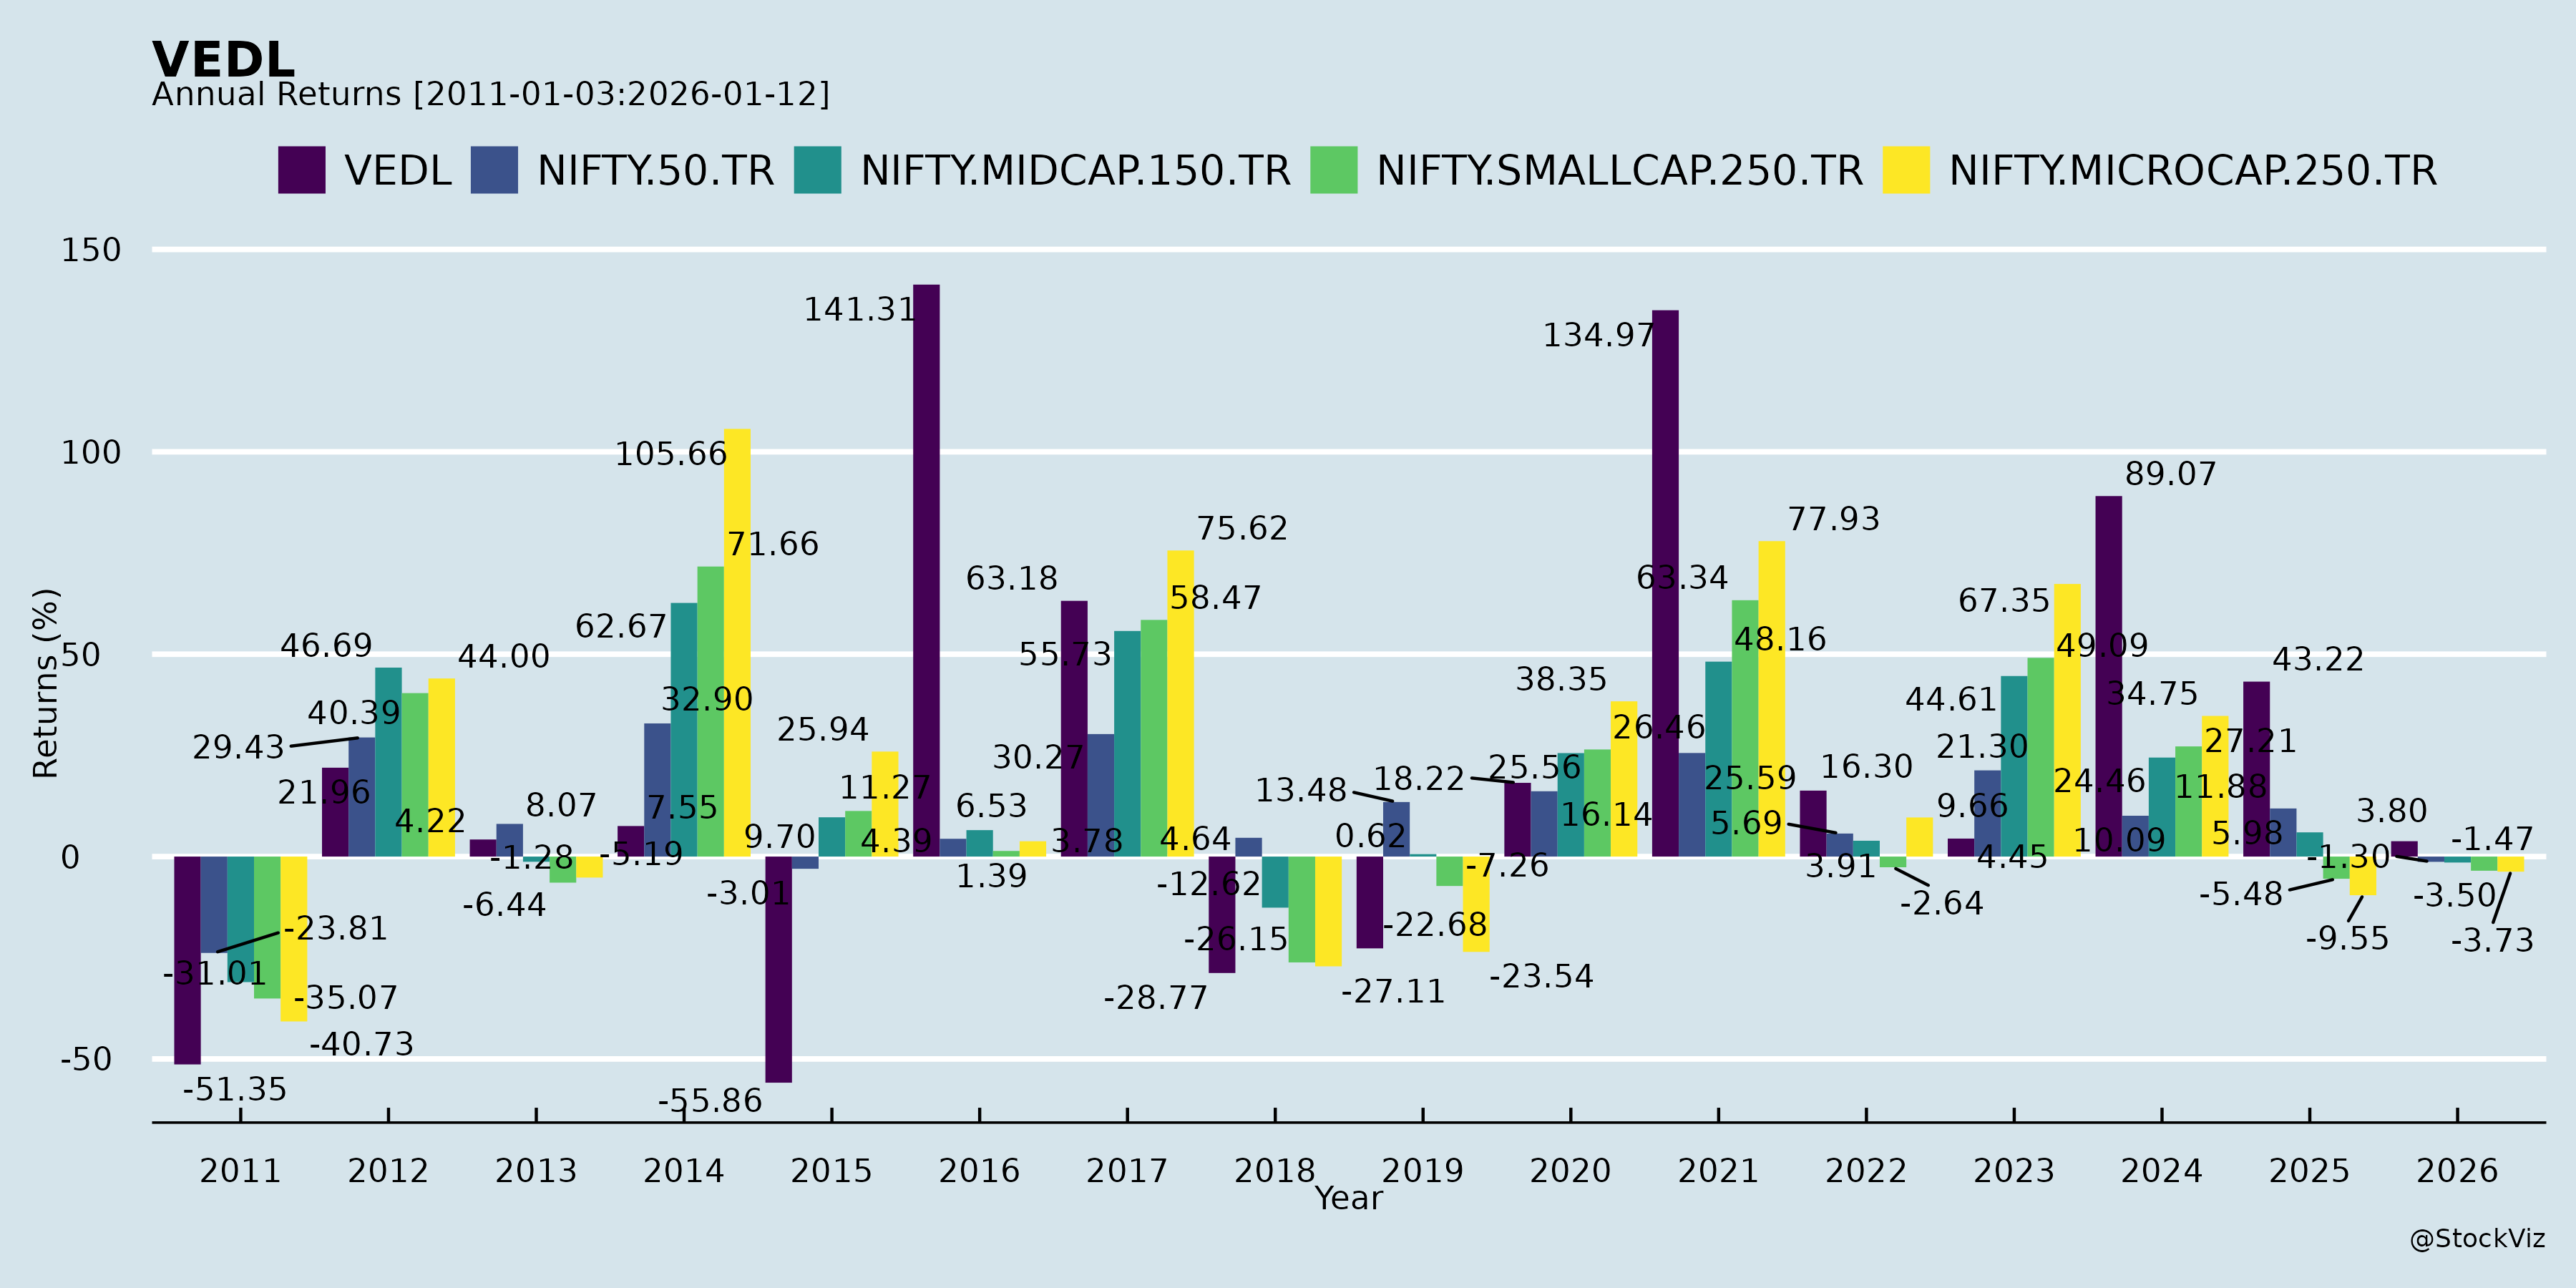
Annual Returns
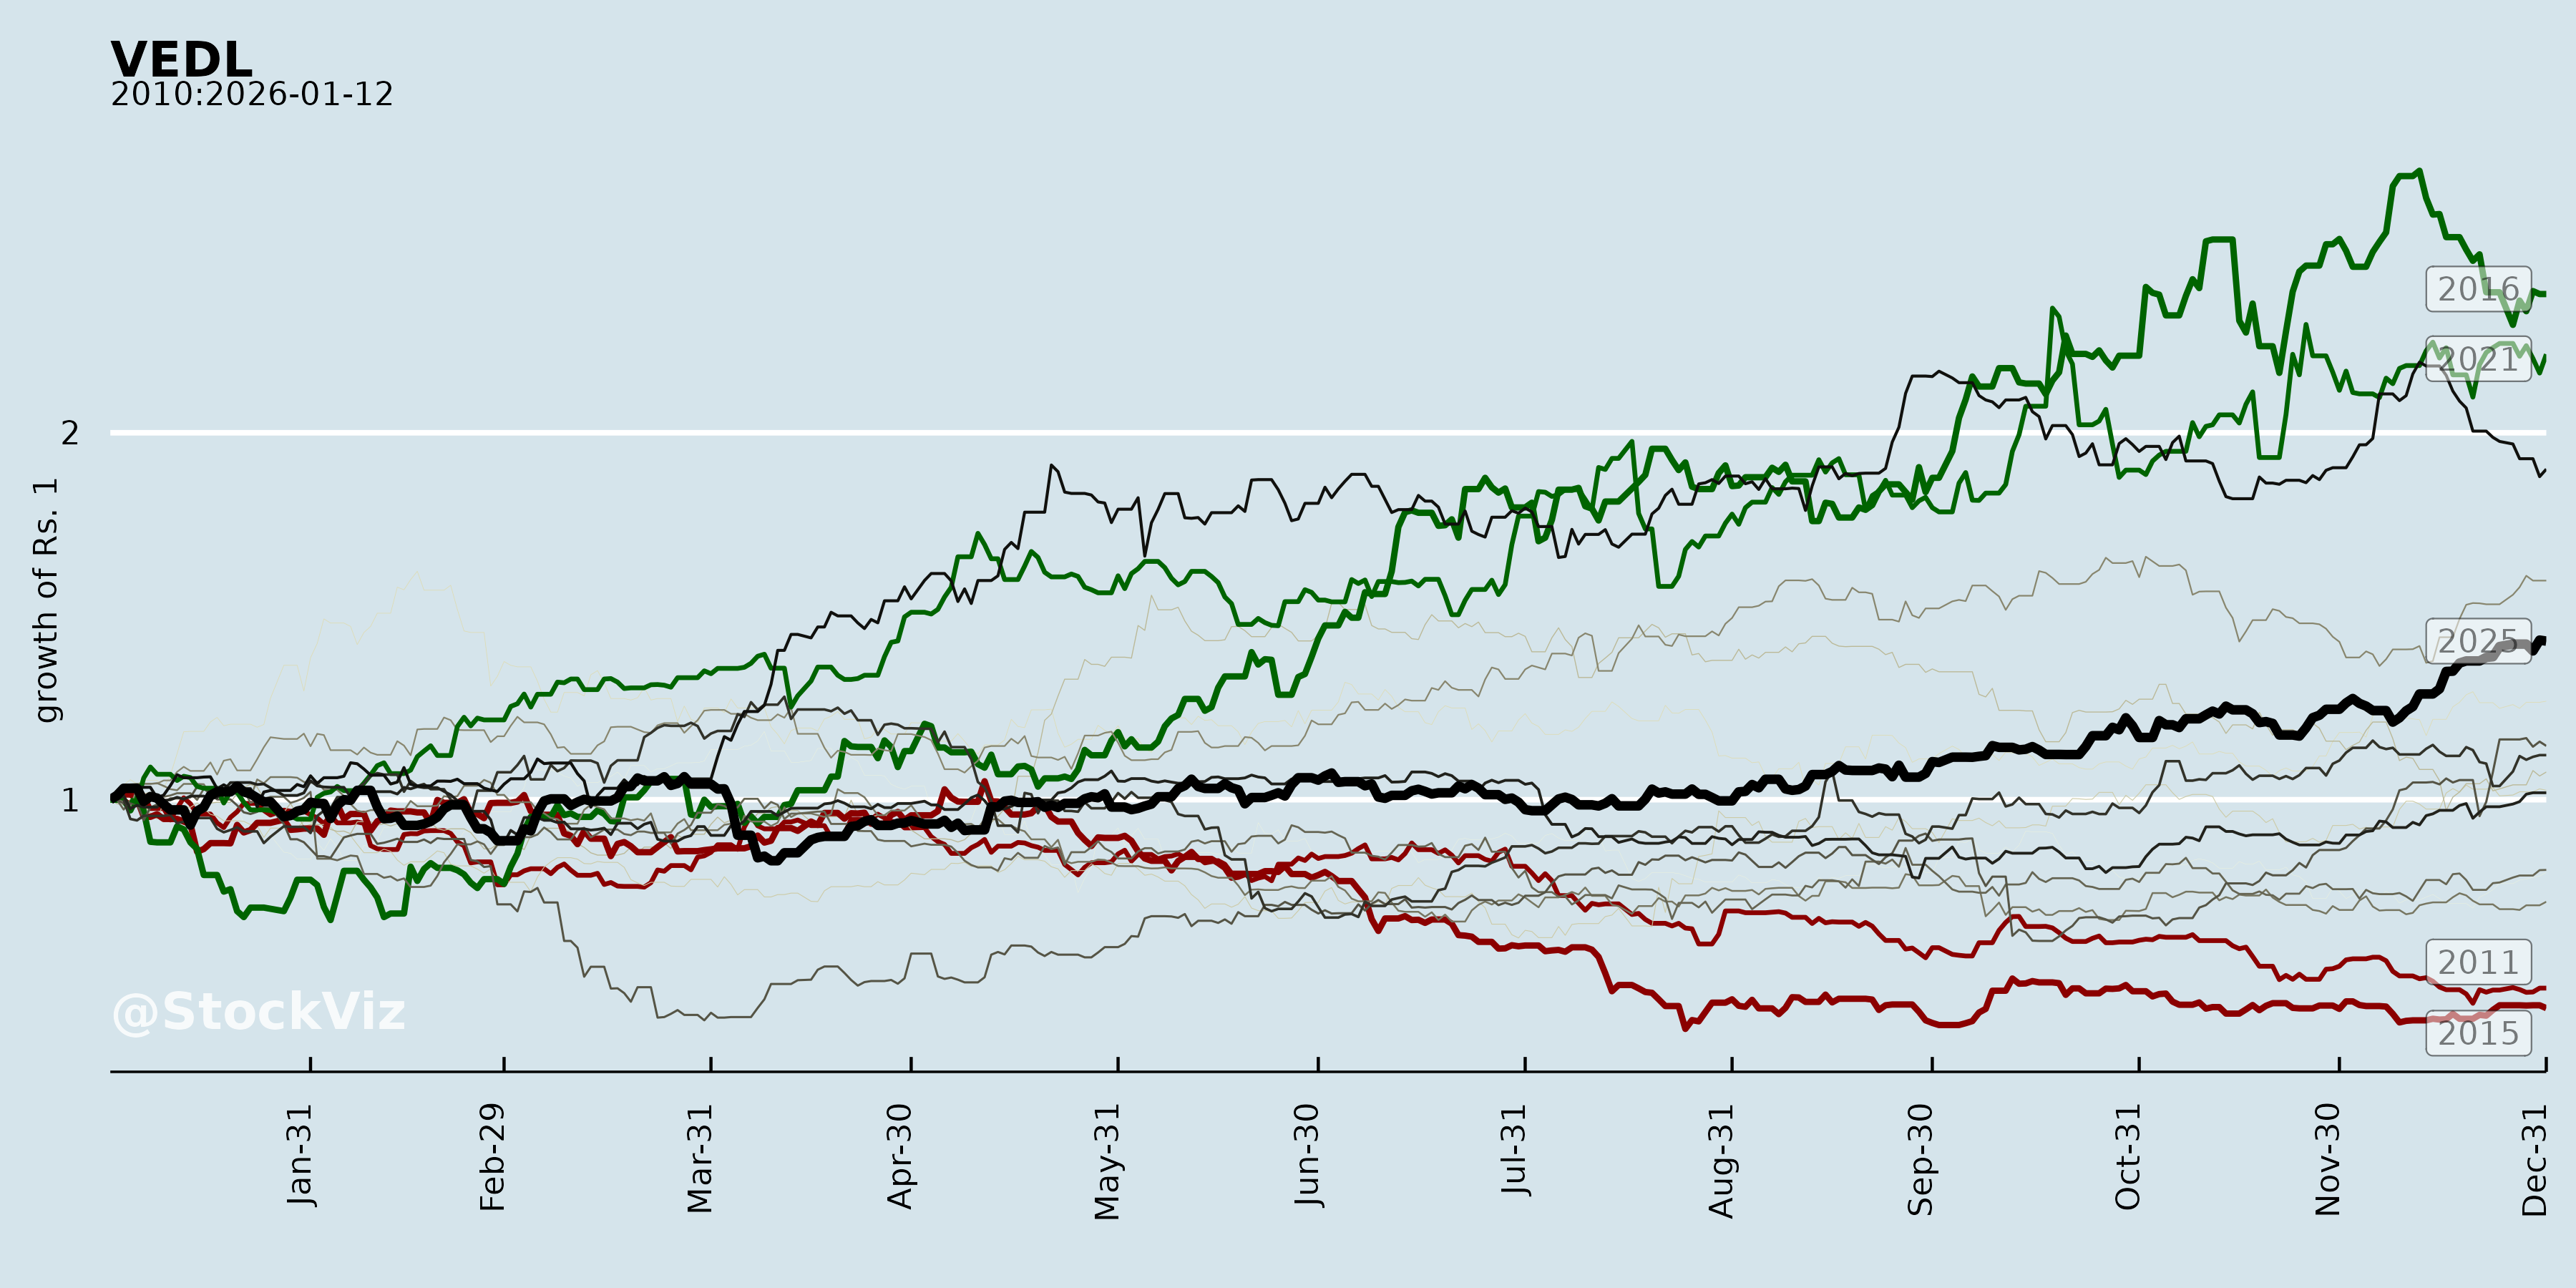
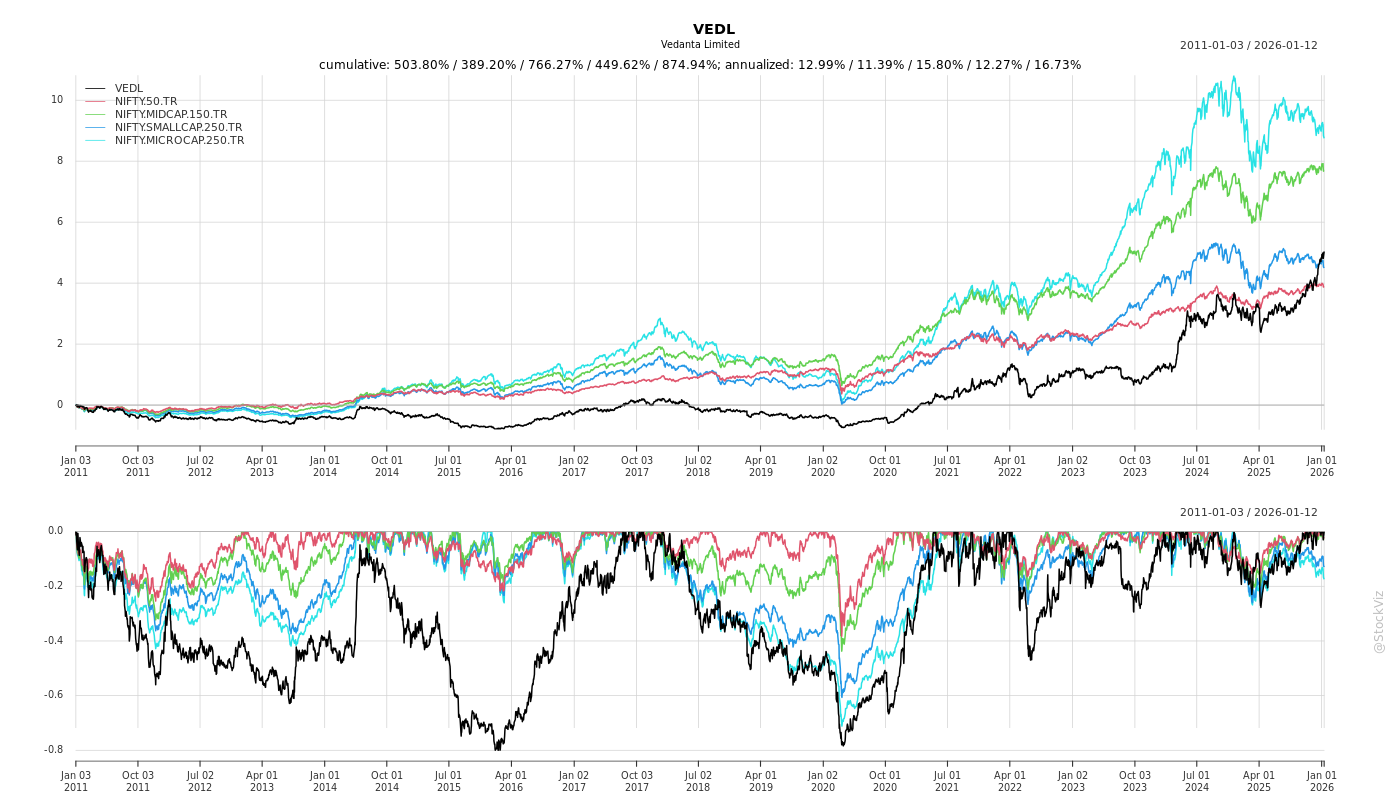
Cumulative Returns and Drawdowns
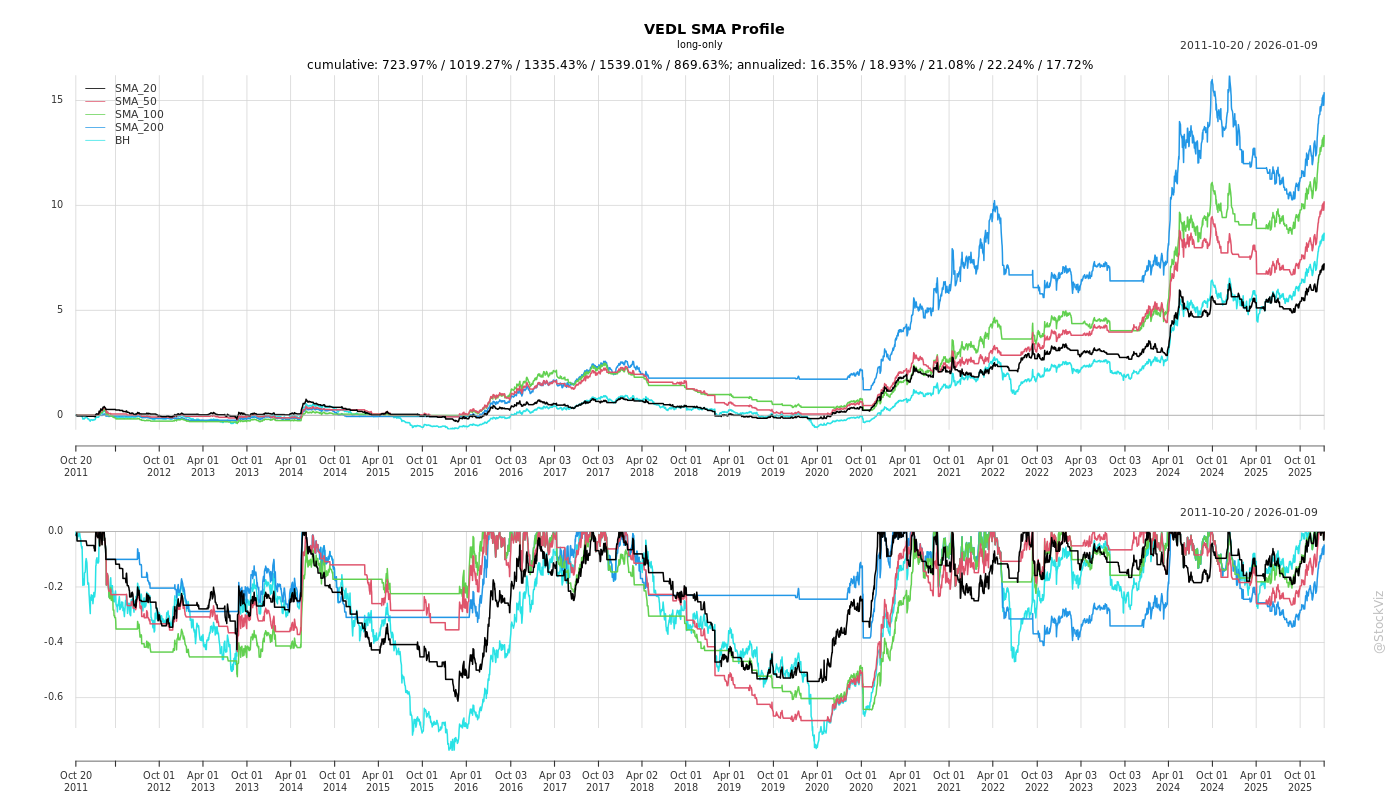
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-14
Vedanta Limited (VEDL): Real Estate Demerger Announcement
Headwinds and Challenges
The real estate business has historically been embedded within Vedanta’s operating businesses, which the company states has resulted in limited focused utilisation and sub-optimal visibility of the real estate segment and value realisation. The portfolio comprises non-core assets accumulated through various acquisitions over the years, and while standalone development options have been assessed periodically over many years, momentum on this exercise has only gained pace in recent months. The demerger itself remains subject to necessary statutory, regulatory and other approvals, including approval of the scheme of arrangement by the National Company Law Tribunal, Mumbai, and no-objection letters from the stock exchanges. Filing with the stock exchanges for their no-objection letter (including SEBI’s comments/approval) is expected in August 2026.
Tailwinds and Growth Prospects
The Board approved the demerger of the Real Estate Business into Vedanta Property Platforms Limited (VPPL) at its meeting on July 30, 2026, with the aim of unlocking significant value. The demerger is planned as a vertical split: for every 20 fully paid-up equity shares of Vedanta Limited of face value INR 1 each, shareholders will receive 1 fully paid-up equity share of VPPL of face value INR 1 each, with no cash consideration payable. The surplus real estate portfolio to be demerged comprises approximately 2,200 acres of industrial land and approximately 55,000 sq feet of residential/commercial properties; the investor presentation describes 22 assets across India, together accounting for approximately 2,264 acres of land (14 land parcels) and approximately 53,185 sq. ft. of residential and office space (8 units).
The rationale centres on creating a pure-play real estate platform: consolidating real estate assets from across Vedanta group companies into a dedicated entity to enable focused management, improved transparency, and more productive deployment of the portfolio. Expected benefits include a centralised platform for leasing, township development, industrial development and infrastructure support services; independent management and governance structures; separate financial and operational disclosures enabling clearer valuation; the ability to attract investors, strategic partners and lenders suited to the real estate sector; and sharper capital market access. The resulting company’s equity shares are proposed to be listed on BSE Limited and the National Stock Exchange of India Limited.
The announcement follows, within three months, the implementation of a five-way demerger culminating in the market debut of four new independent entities on the NSE and BSE. The presentation cites that Vedanta Ltd.’s share price was INR 225.50 on the date of announcement of that demerger (29 September 2023), while the consolidated share value of the four newly listed entities along with Vedanta Ltd. on the listing date (15 June 2026) was INR 932.05, described as over 300% upside. The presentation frames the real estate demerger as having similar potential to create additional shareholder value. It also cites broader market context: an Indian real estate market projected to expand at an estimated CAGR of ~14%, transactions in major cities growing 77% between FY2019 and FY2025, office demand led by GCCs and IT firms with the data center sector growing ~11% annually, and warehousing space additions rising ~11% YoY in FY25. The presentation notes comparable restructuring efforts by companies such as BEML, Raymond, Emami, ITC and Bombay Dyeing.
Key Risks
The scheme requires statutory, regulatory and other approvals, and the timeline for exchange no-objection letters (including SEBI comments/approval) is expected in August 2026, with consummation through NCLT approval. The pre-scheme shareholding pattern of the Resulting Company may vary pursuant to Potential Transactions and Concurrent Schemes, and the post-scheme shareholding pattern would correspondingly change to that extent. Fractional entitlements will not be issued directly; fractional shares will be consolidated, allotted to a nominated trustee, sold in the market, and net sale proceeds distributed to concerned shareholders, subject to withholding tax. The company’s forward-looking statements note uncertainties arising from financial and metals markets including the London Metal Exchange, fluctuations in interest and exchange rates and metal prices, future integration of acquired businesses, and numerous national, regional and global matters of a political, economic, business, competitive or regulatory nature.
Management Guidance Versus Observed Business Performance
The demerged undertaking’s turnover (including other operating income) for the year ended March 31, 2026 was INR 1.26 crore, representing 0.001% of the total standalone turnover of Vedanta Limited for the year ended March 31, 2026. Management characterises the real estate portfolio as historically subject to limited focused utilisation, resulting in sub-optimal visibility and value realisation, and positions the demerger as unlocking embedded value through a focused platform with transparent valuation and dedicated revenue generation avenues. The cited precedent is the prior five-way demerger: the presentation states that the consolidated share value of the four newly listed entities along with Vedanta Ltd. on the listing date (15 June 2026) was INR 932.05, compared with Vedanta Ltd.’s share price of INR 225.50 on the date of announcement of that demerger (29 September 2023). The scheme will not result in any additional or special benefits to the promoter/promoter group/group companies, and the issuance of shares of the Resulting Company to shareholders of the Demerged Company will be on a proportionate basis, with the beneficial economic interest of shareholders in the Demerged Undertaking remaining unchanged and continuing to be held through VPPL. Holders of Listed Debt Securities in the Demerged Company will continue to hold them on the same terms and conditions, with the liability of the Demerged Company neither reduced nor extinguished.
Broker Narrative
The broker narrative evolved from stark technical bearishness in 2020 (bearish engulfing patterns, Nifty trend-line breaks, metal sector divergence, zero tailwinds) to a fundamentally balanced stance in 2026 (operational headwinds like production declines, coal cost pressures, and hedge losses offset by record zinc cost efficiencies, strong FCF, growth projects, and silver-driven earnings). Notably, none of the early fears materialized — the stock returned +1105% after the initial Sell call — while the last report’s tailwinds remain largely intact despite emerging operational risks.
Broker Timeline
45 broker calls · 2020-02-15 to 2026-07-30
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.