TVSMOTOR
Equity Metrics
September 24, 2026
TVS Motor Company Limited
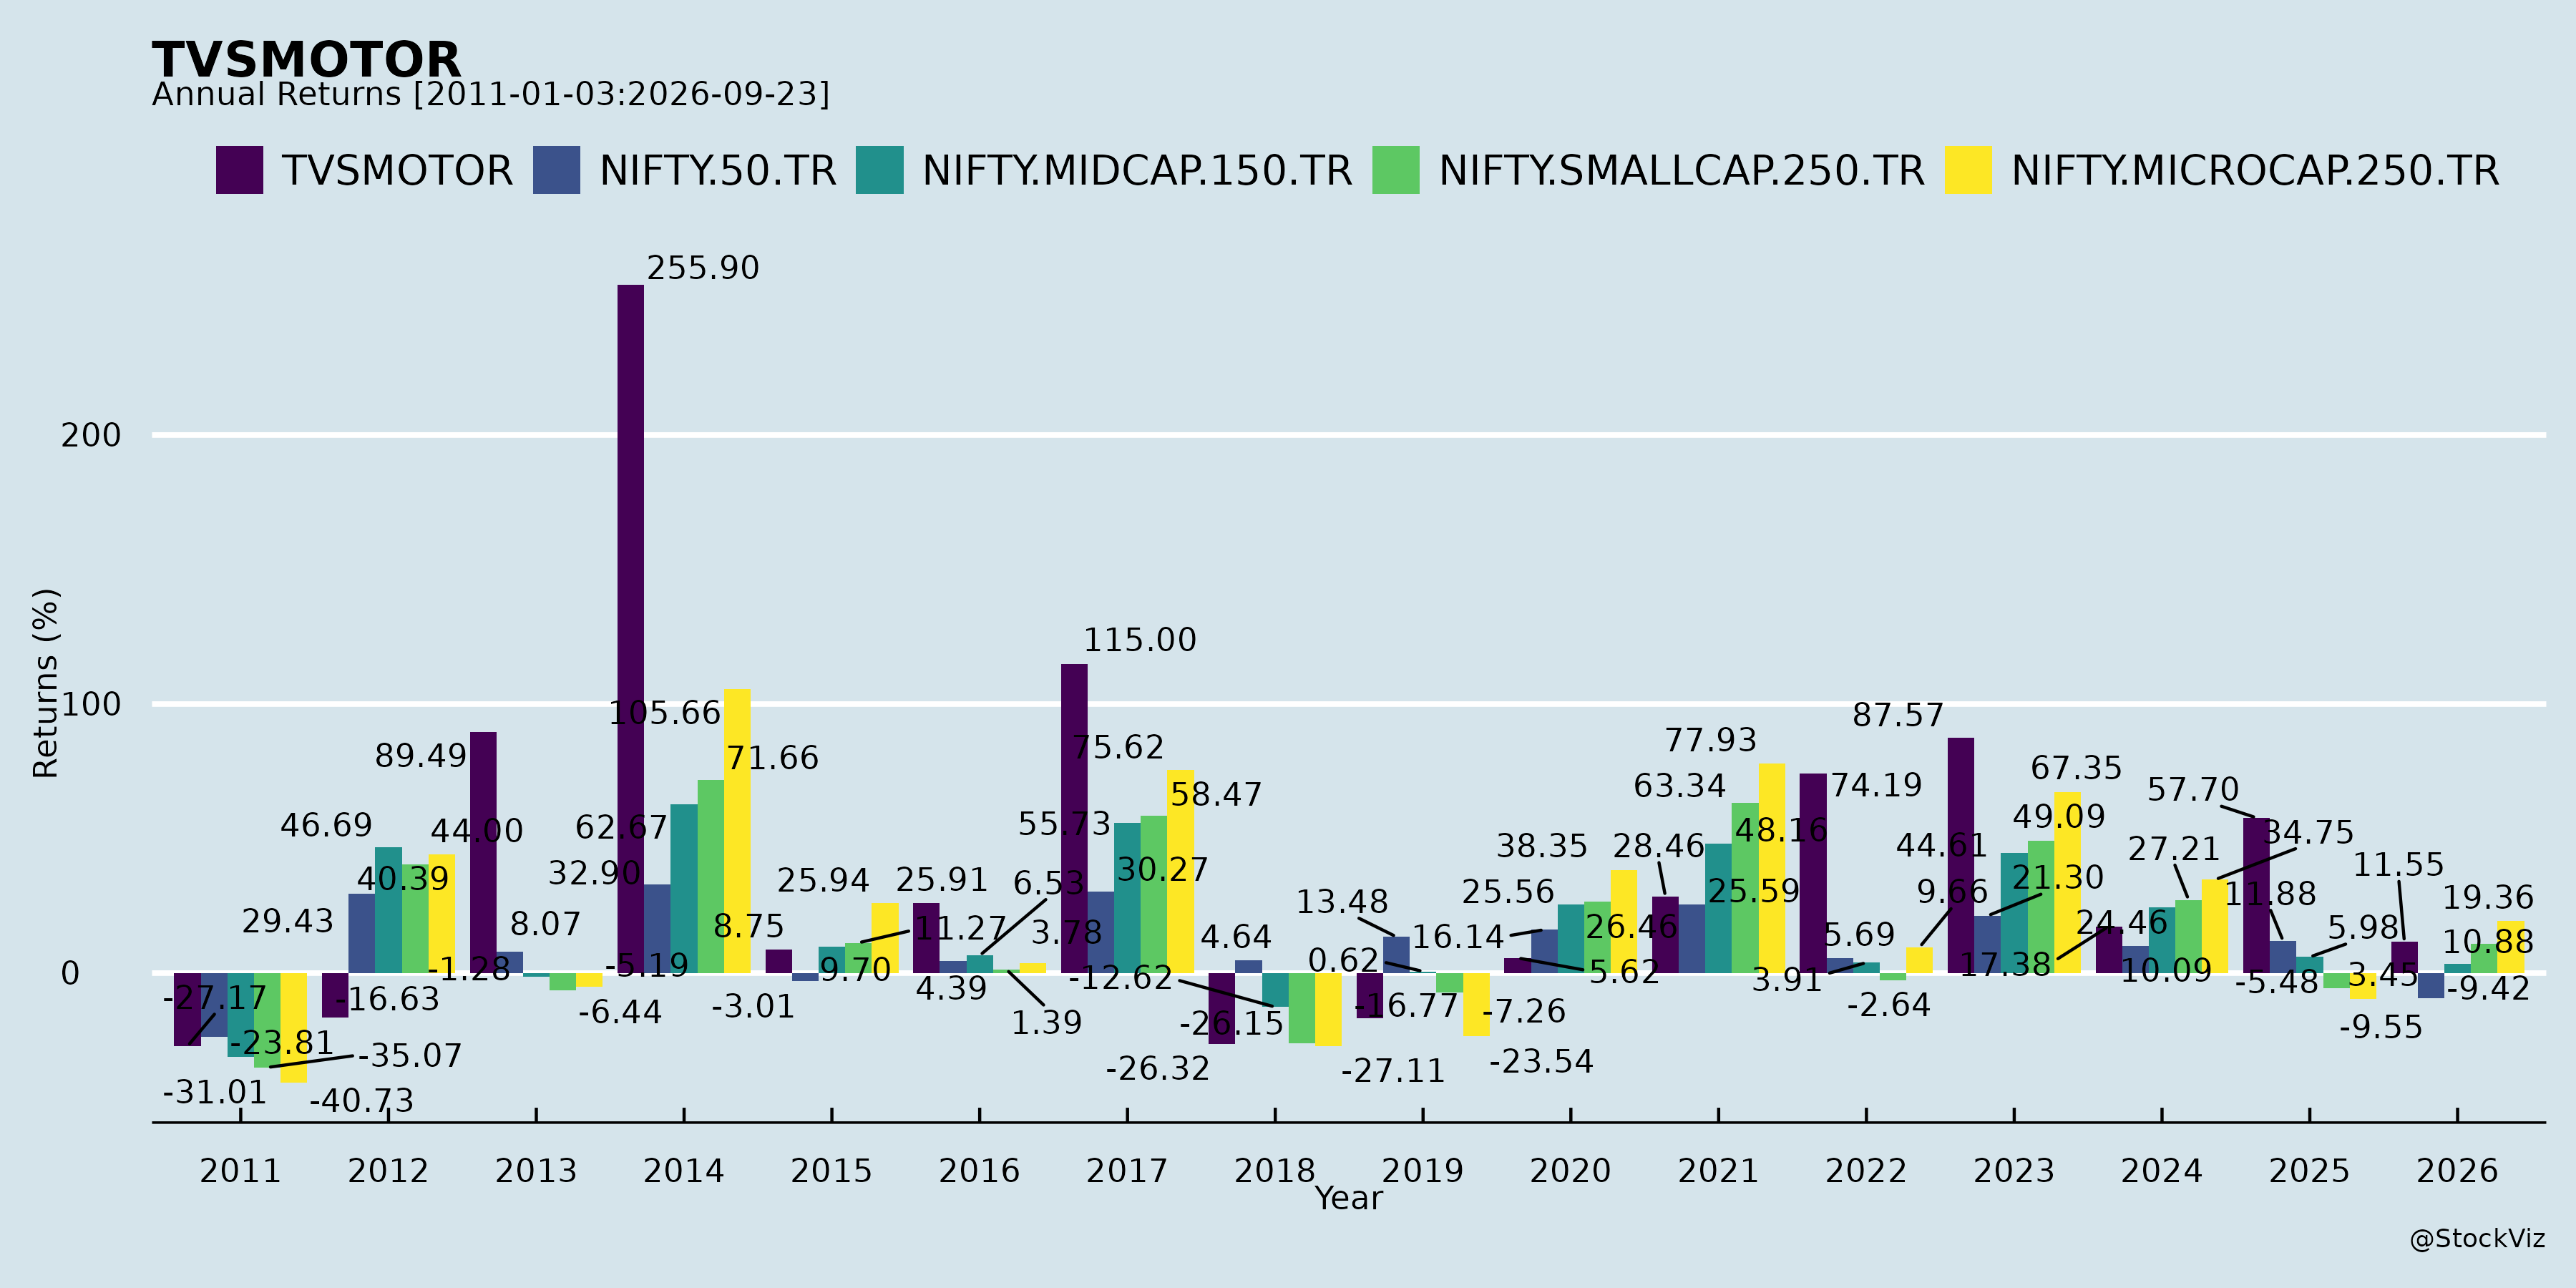
Annual Returns
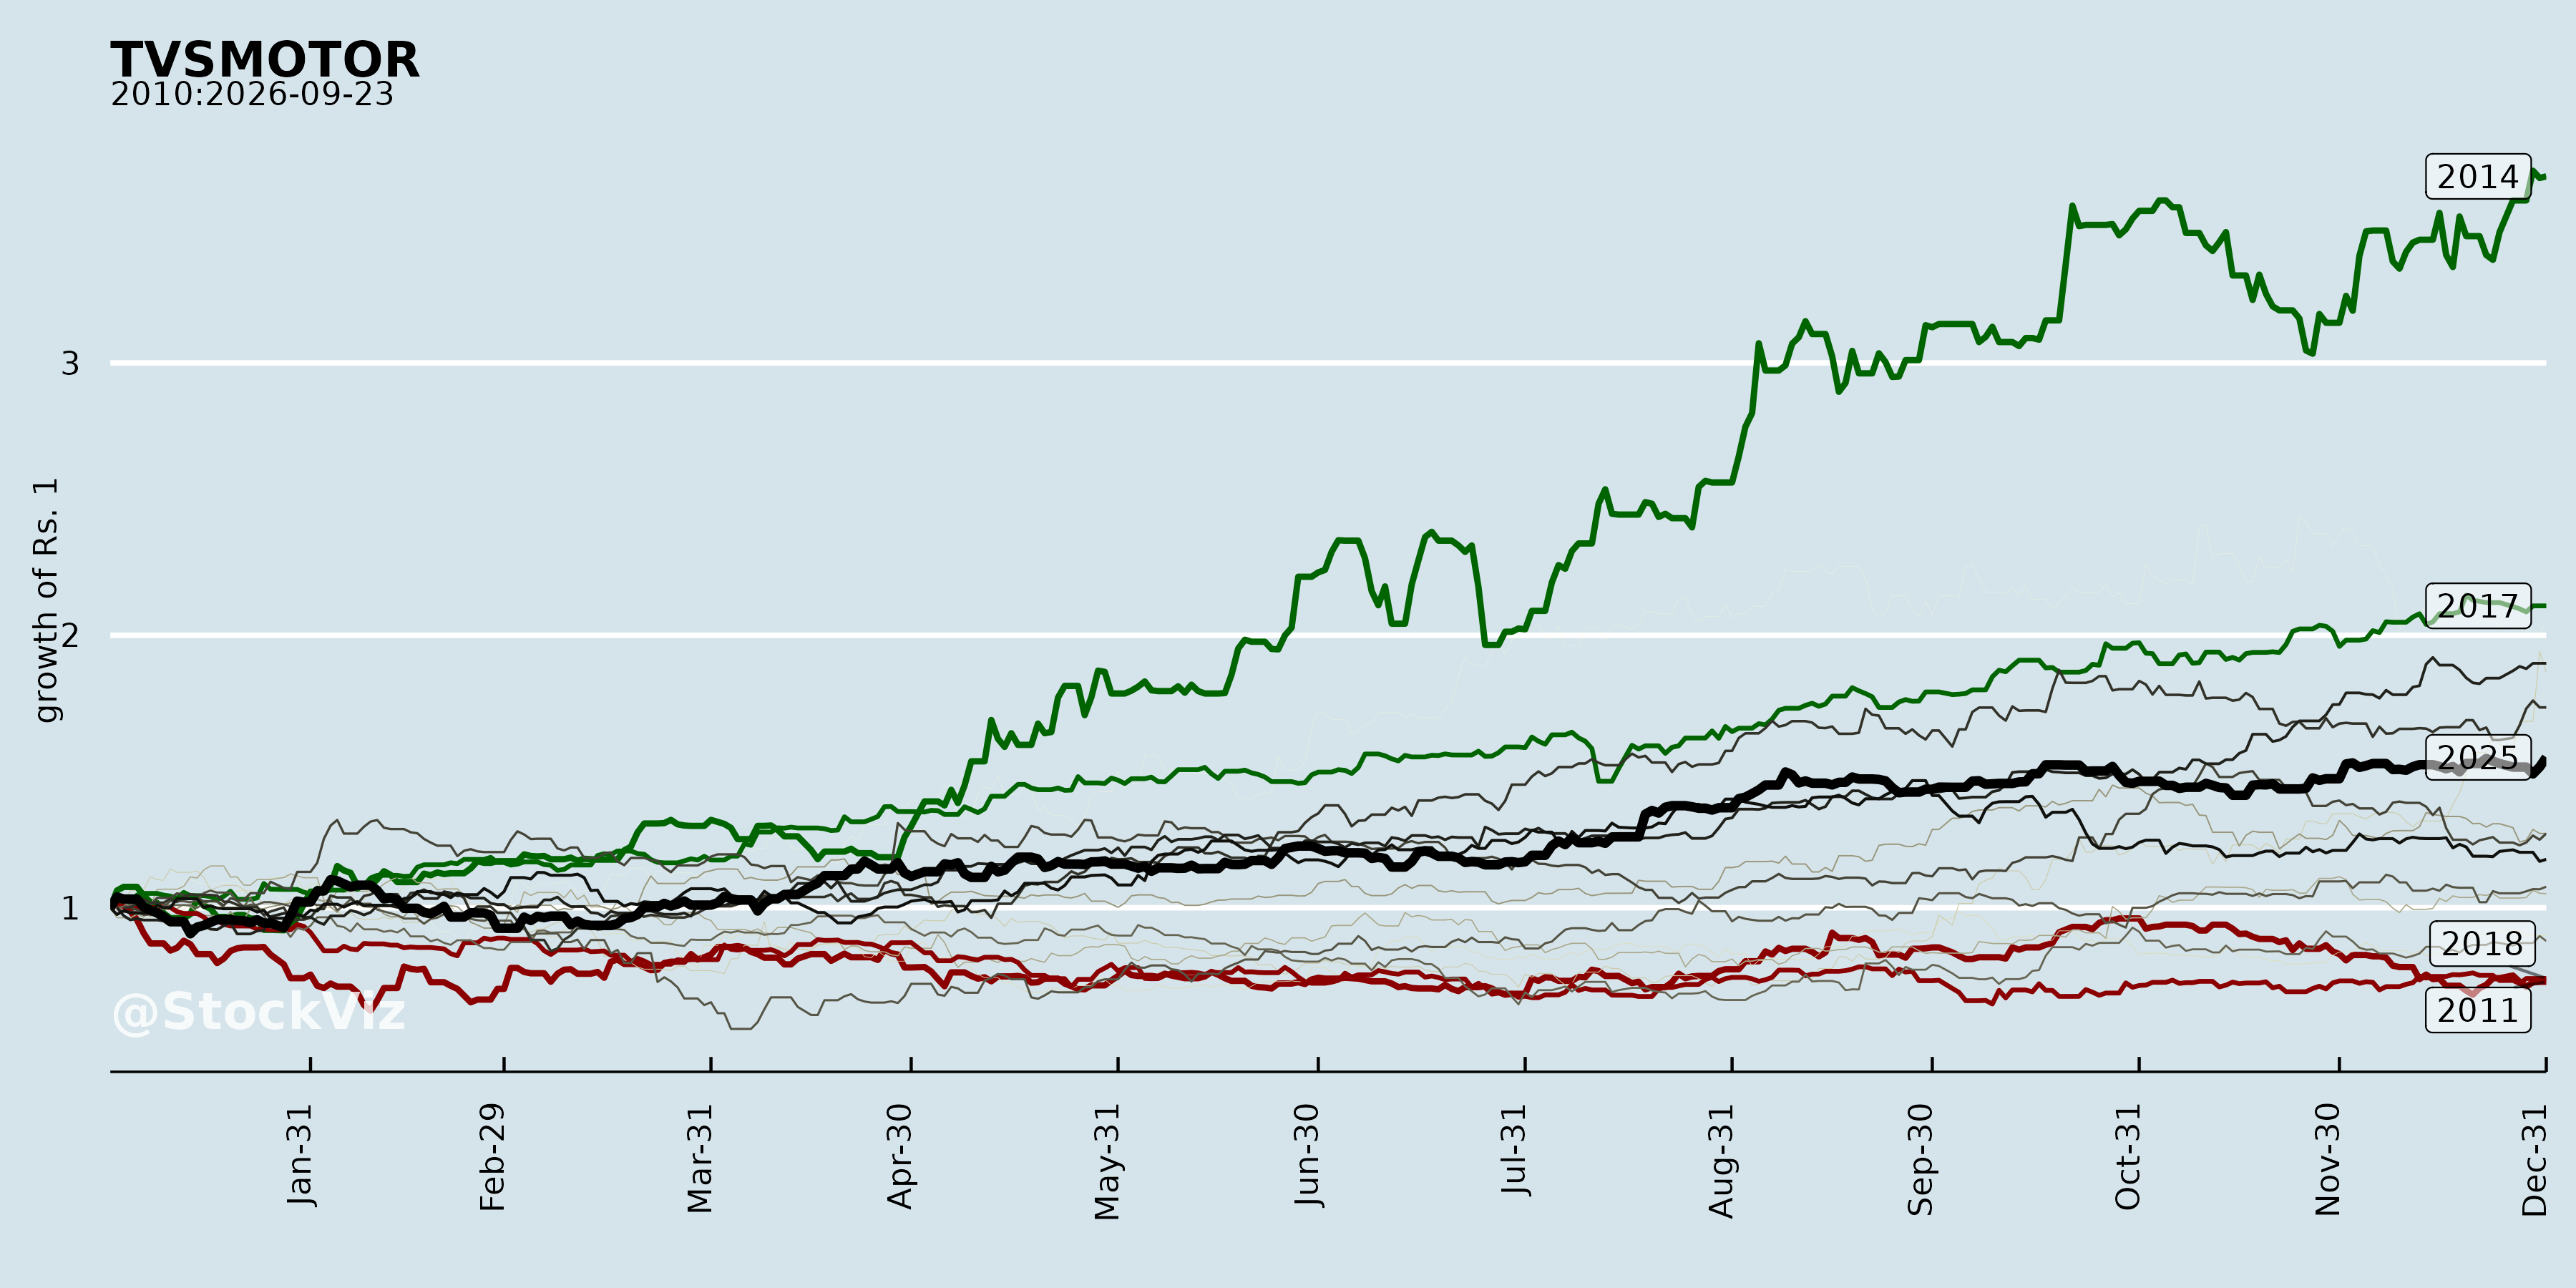
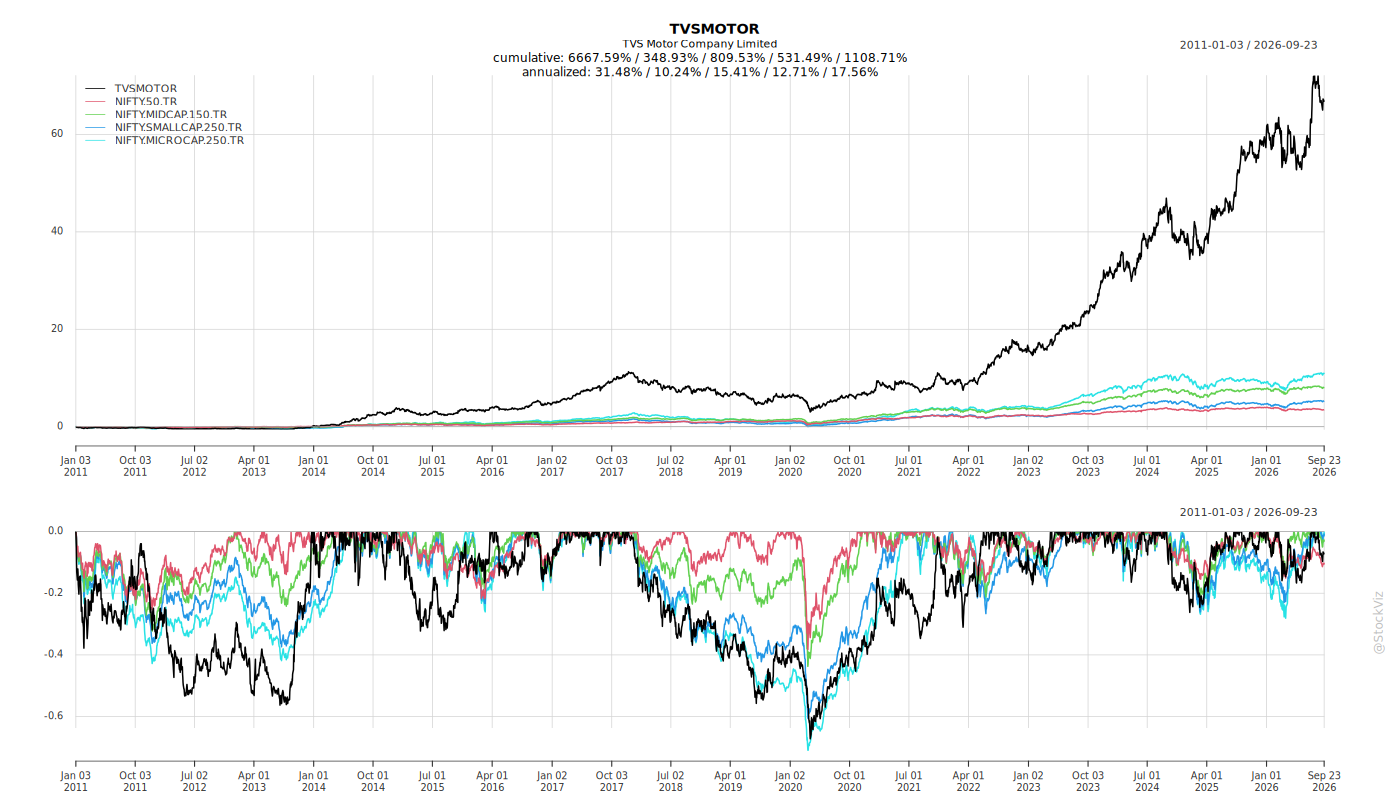
Cumulative Returns and Drawdowns
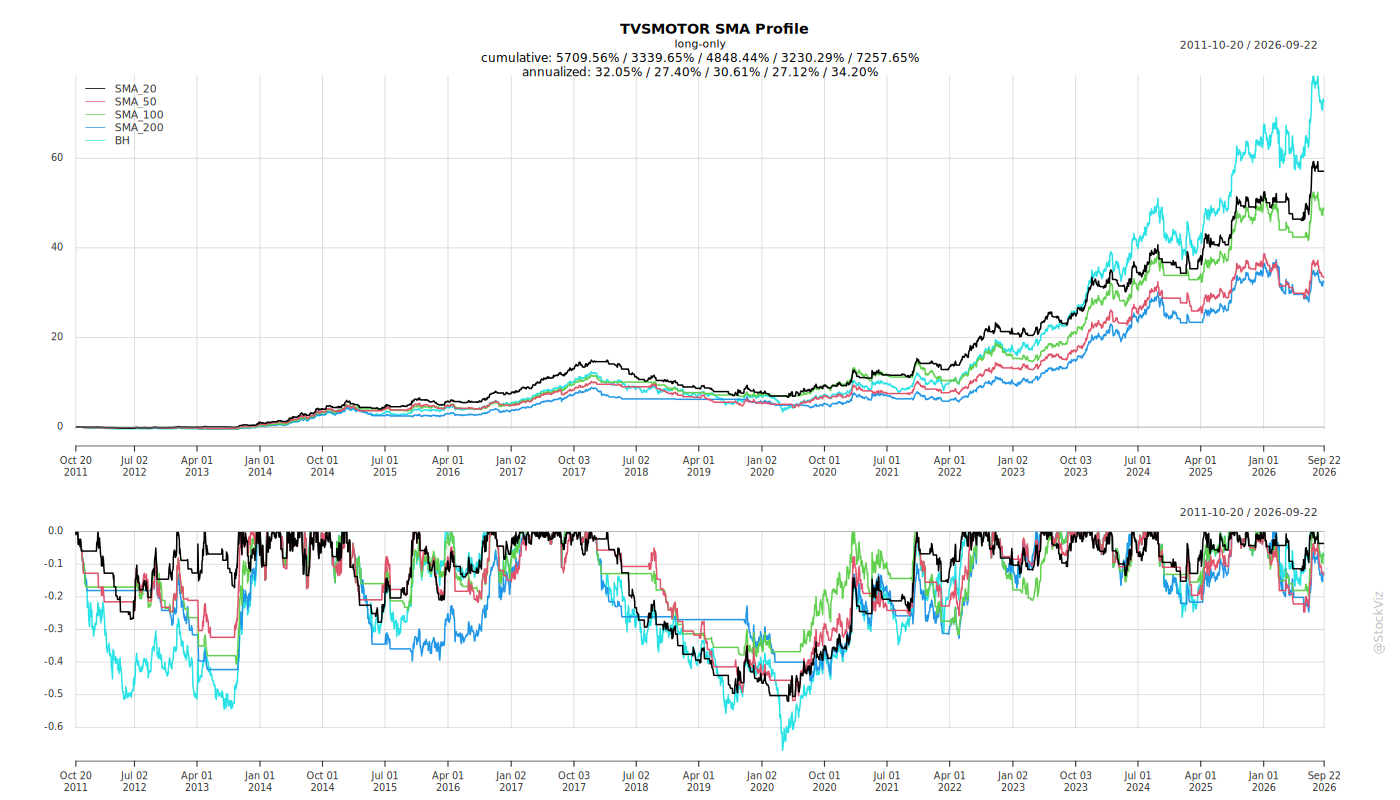
Fundamentals
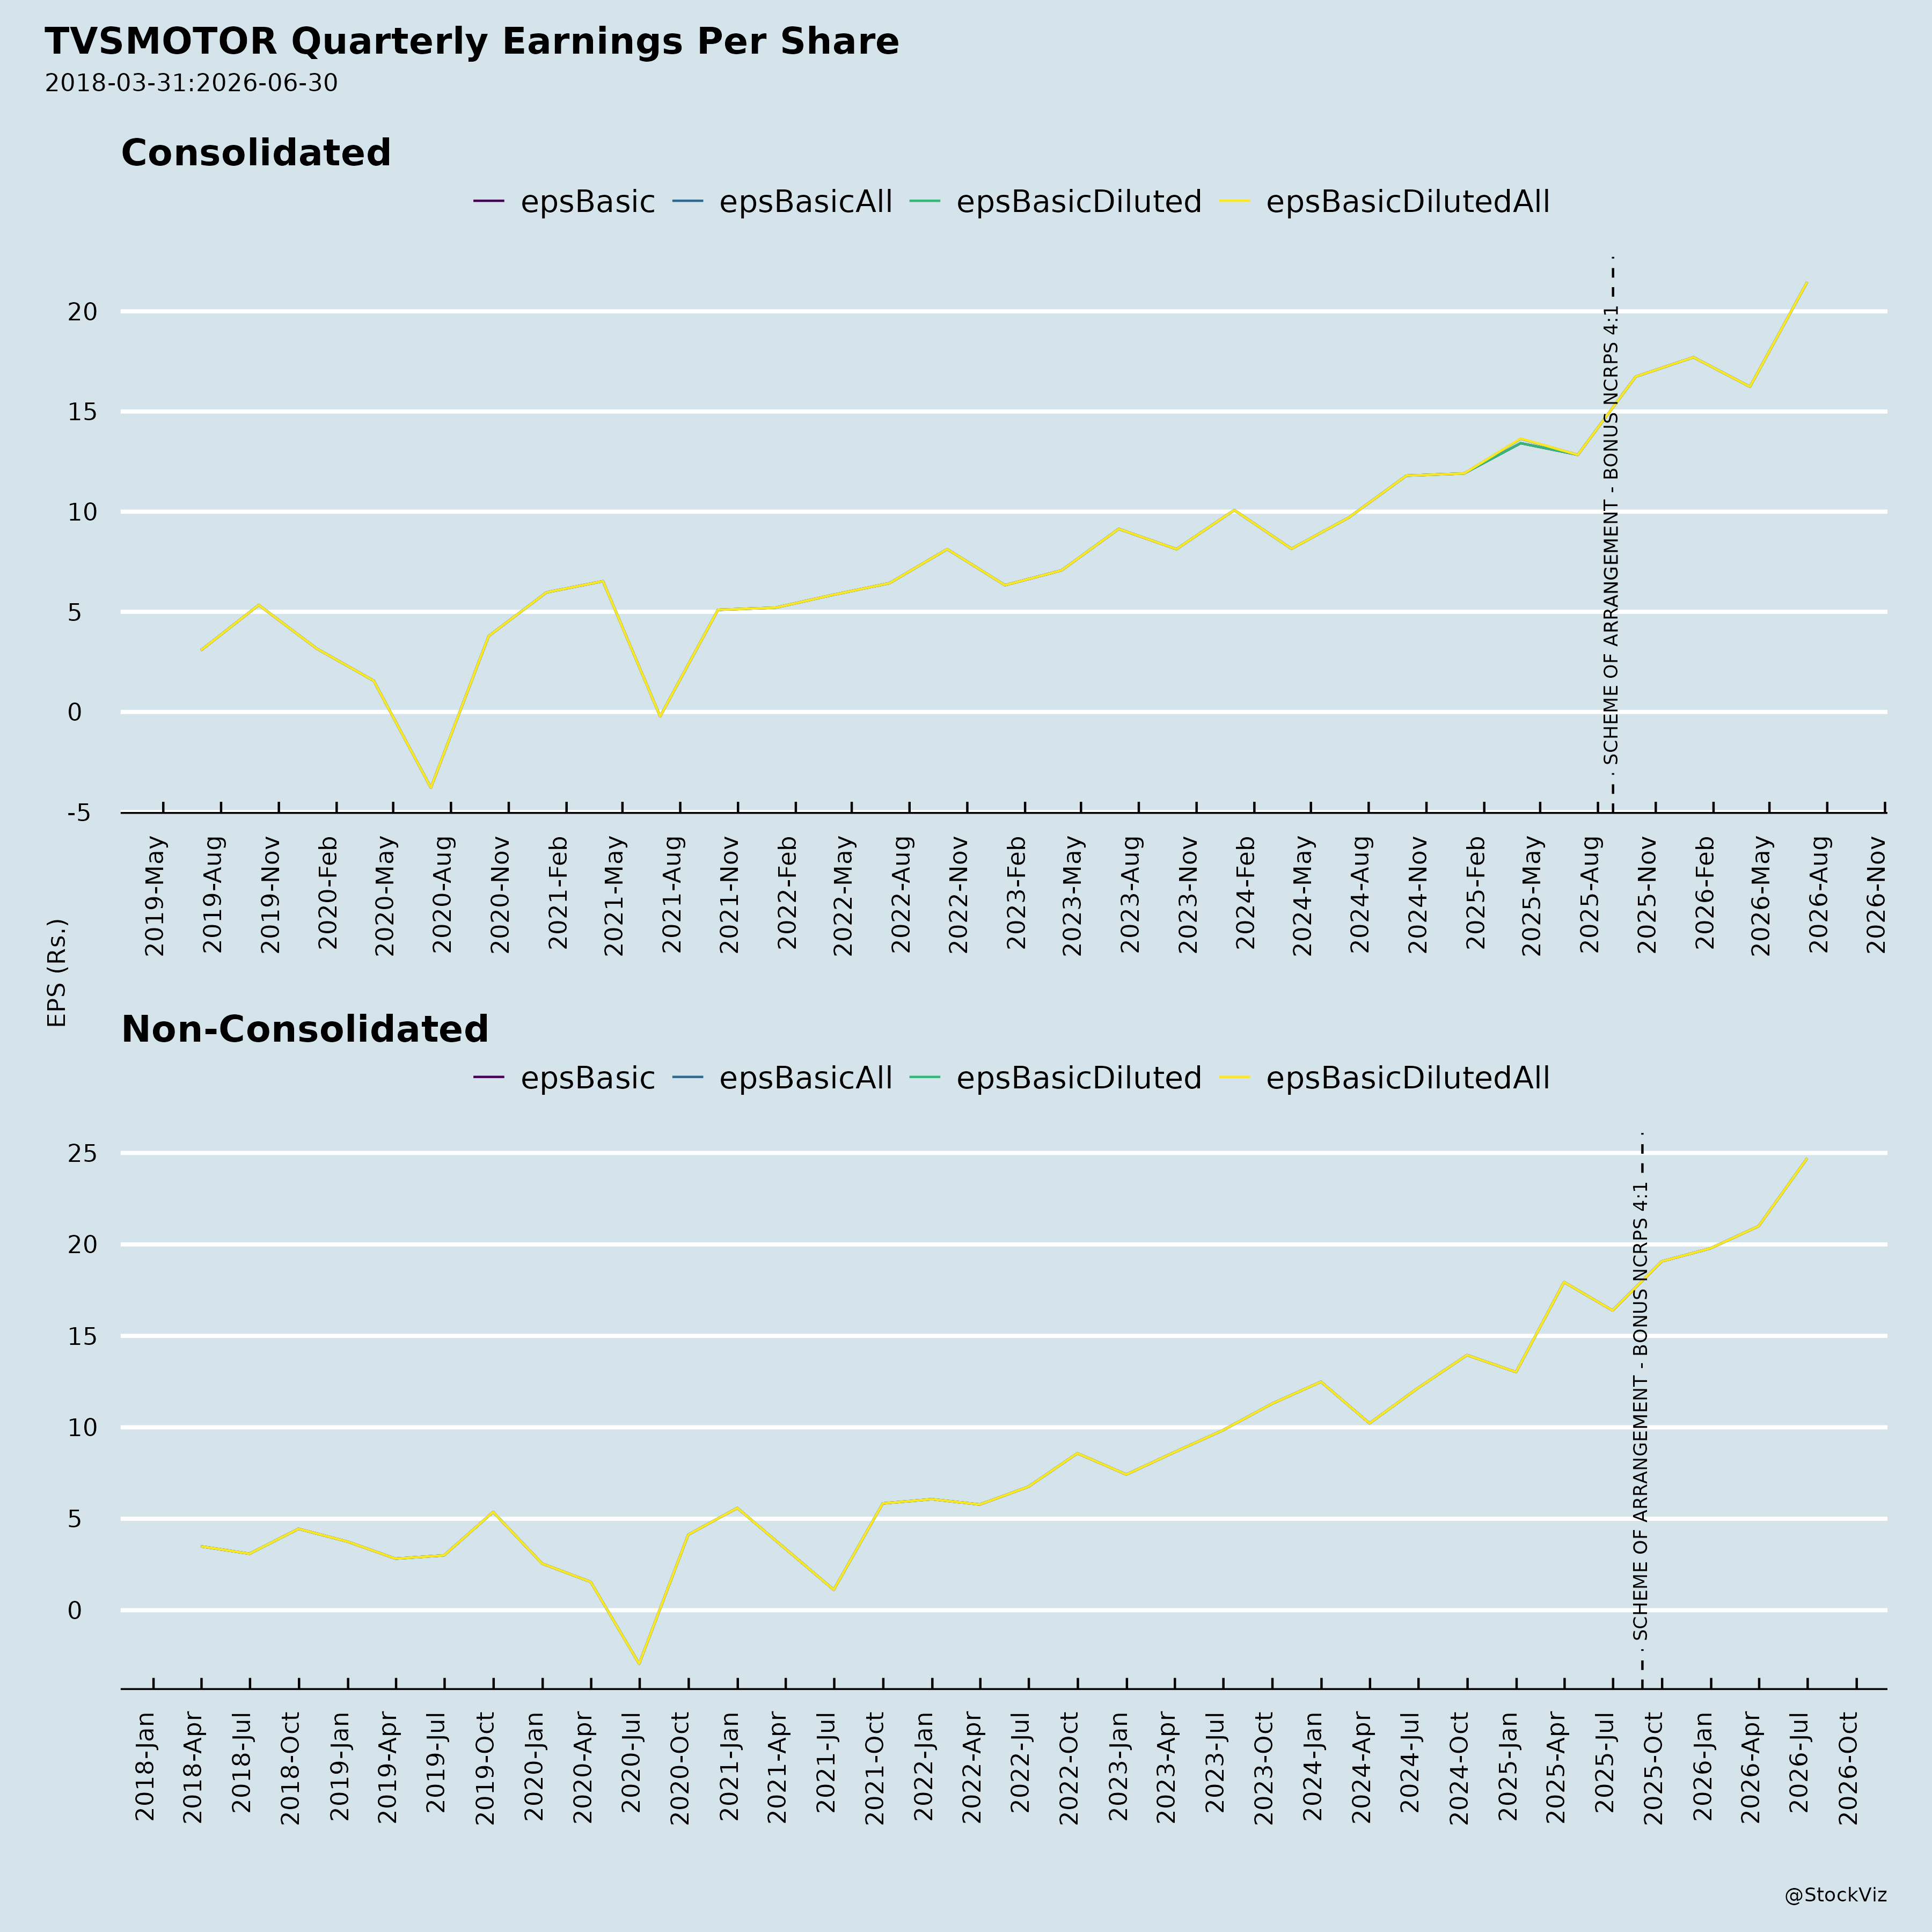
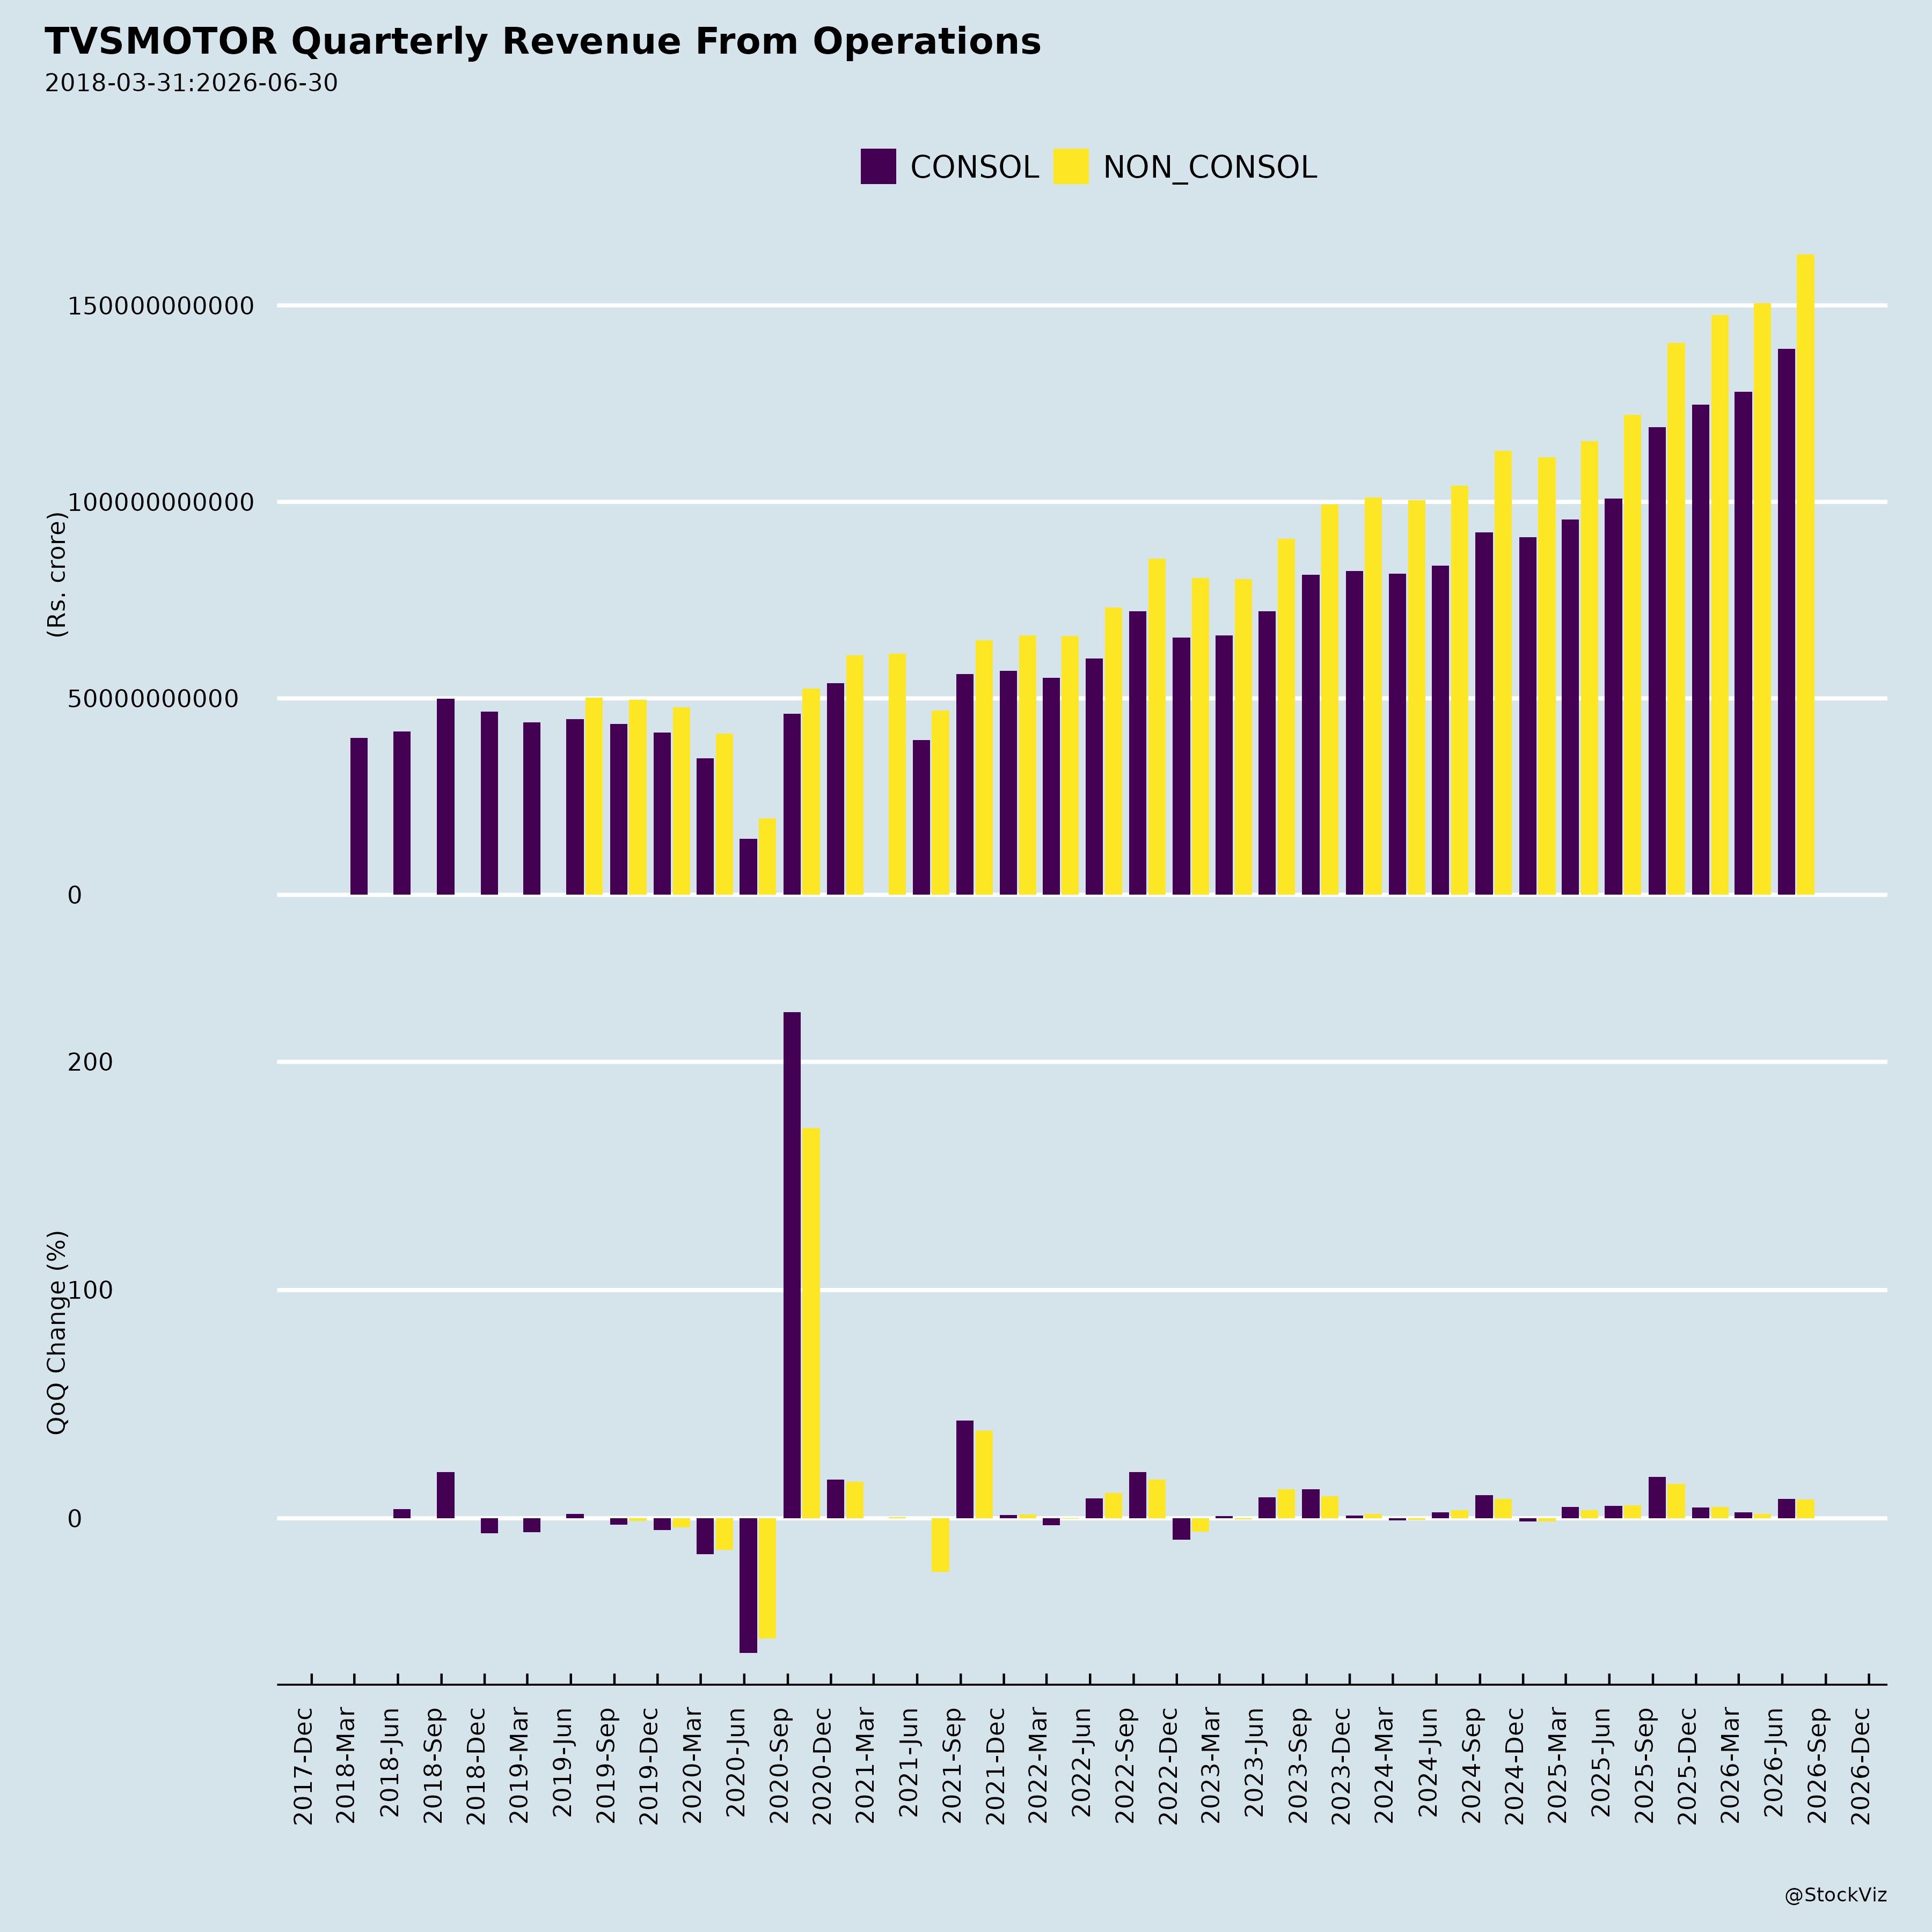
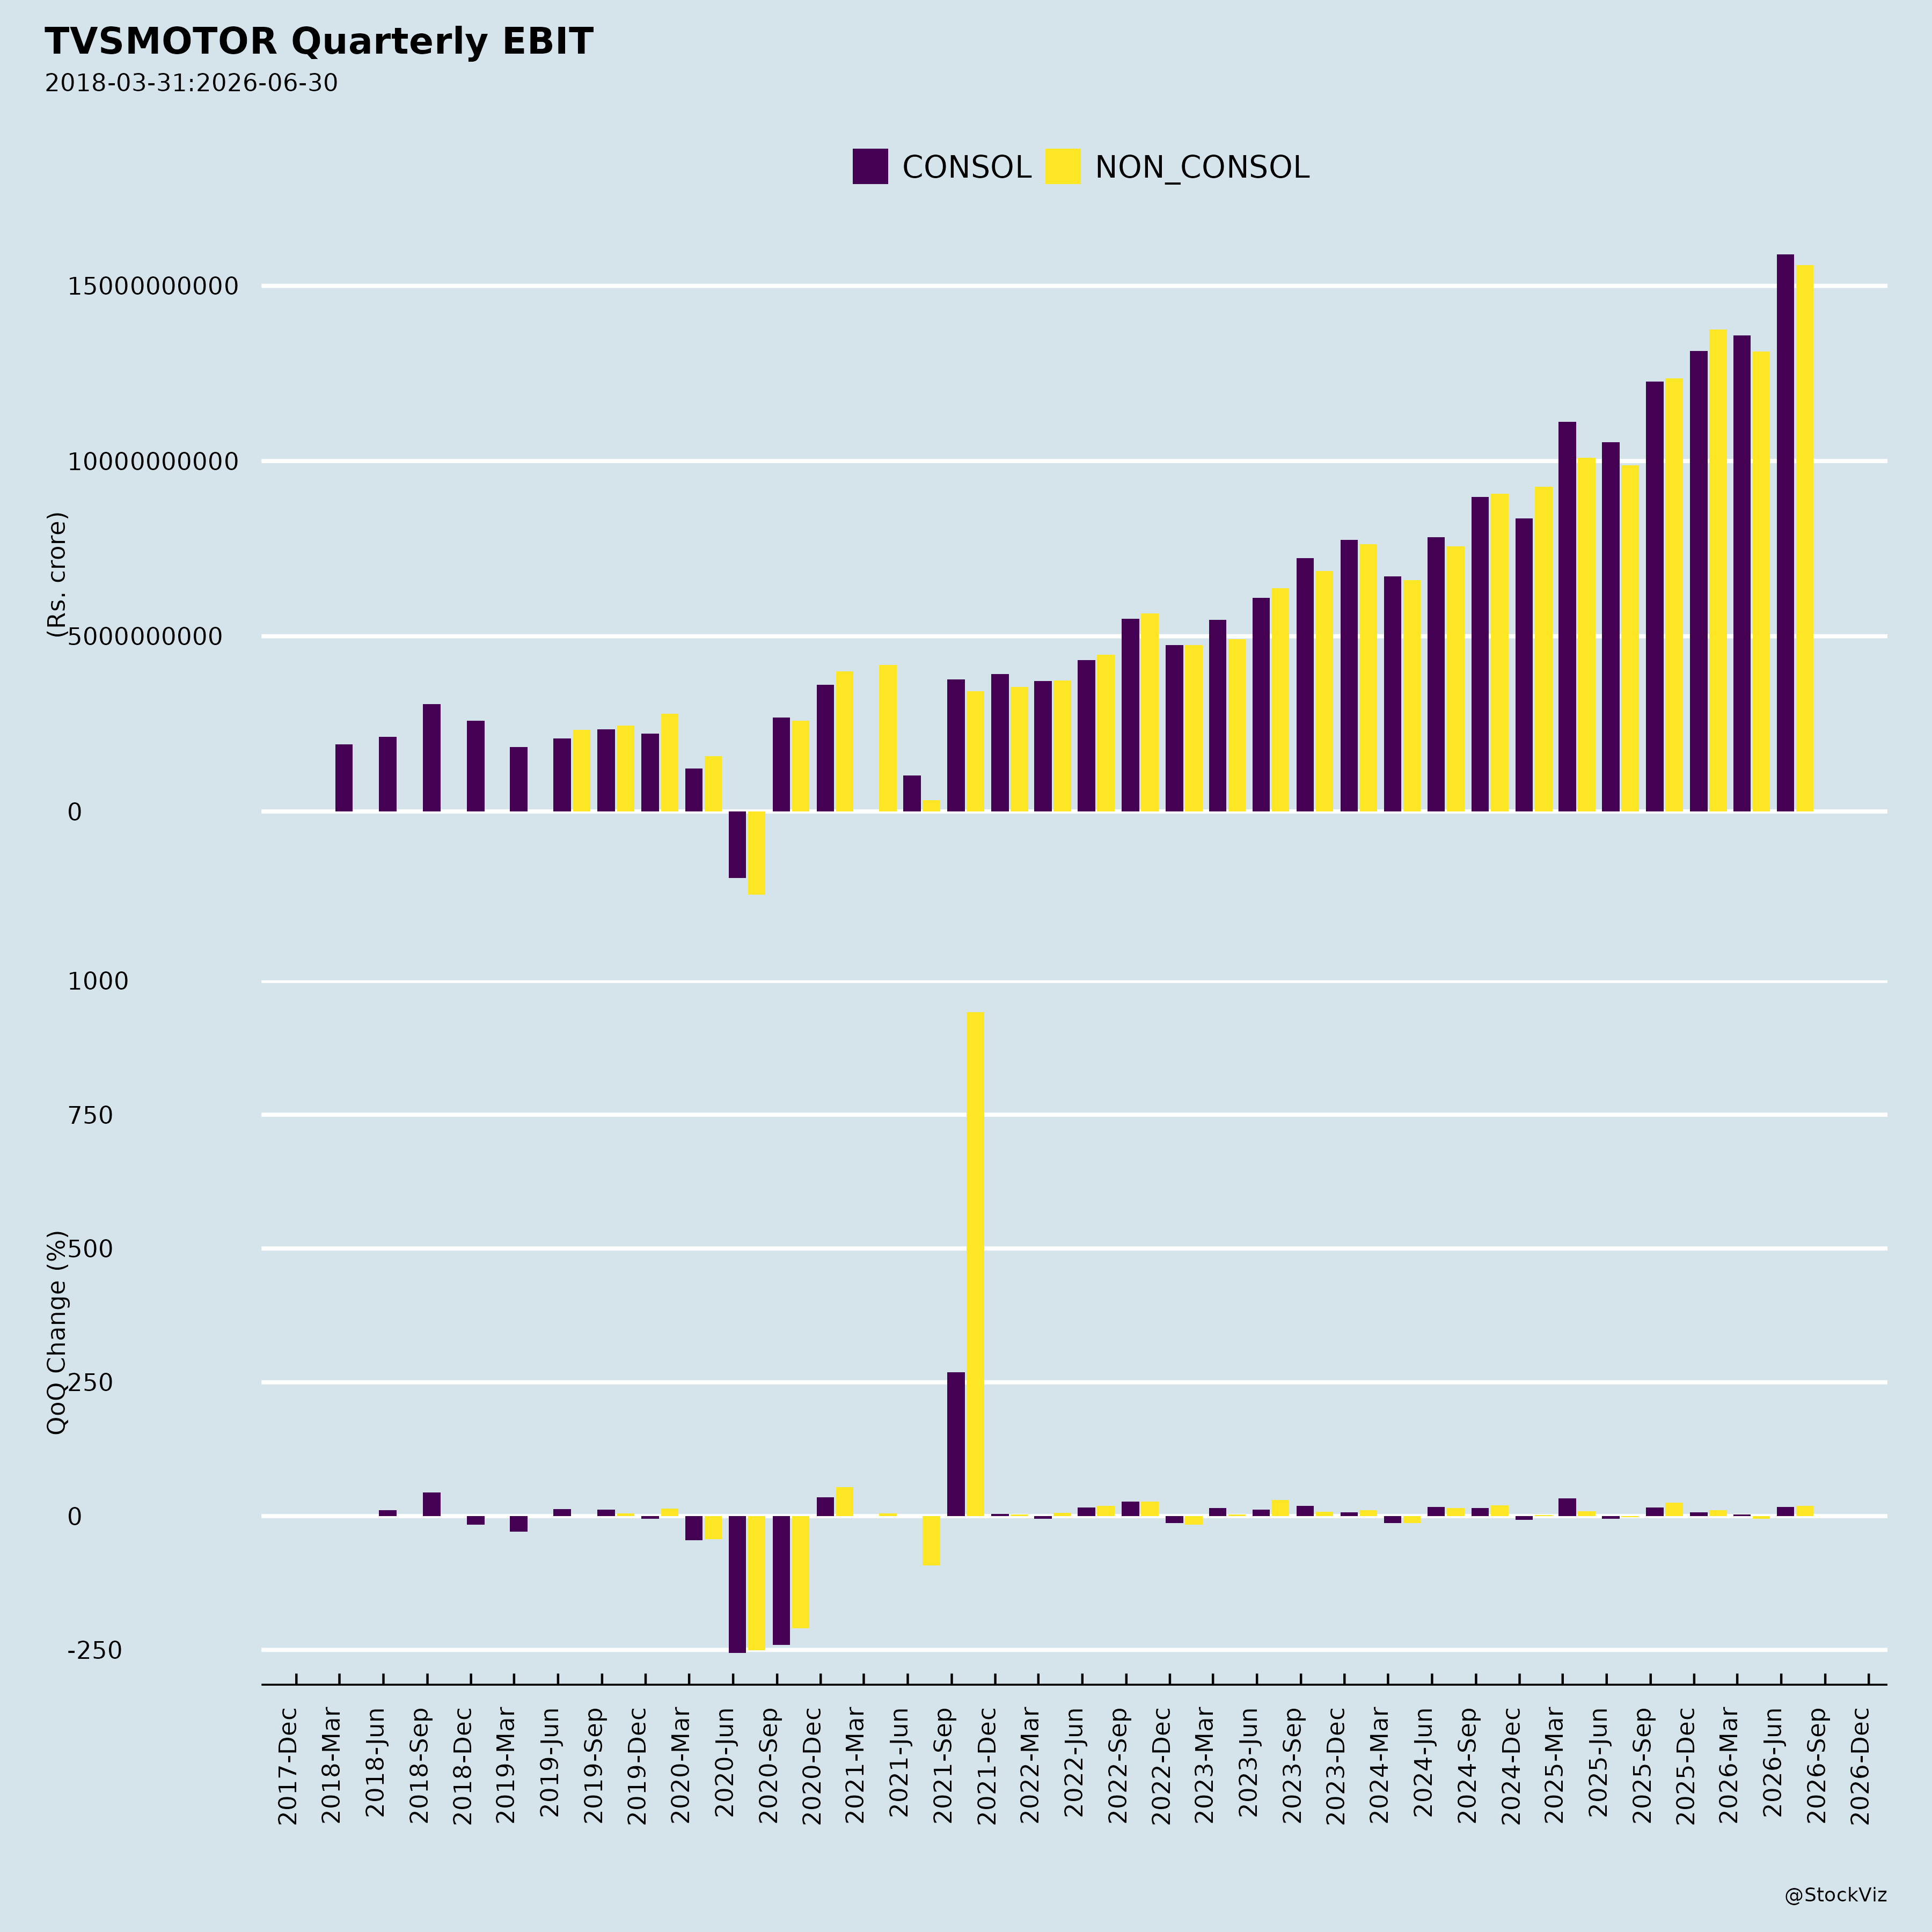
Ownership
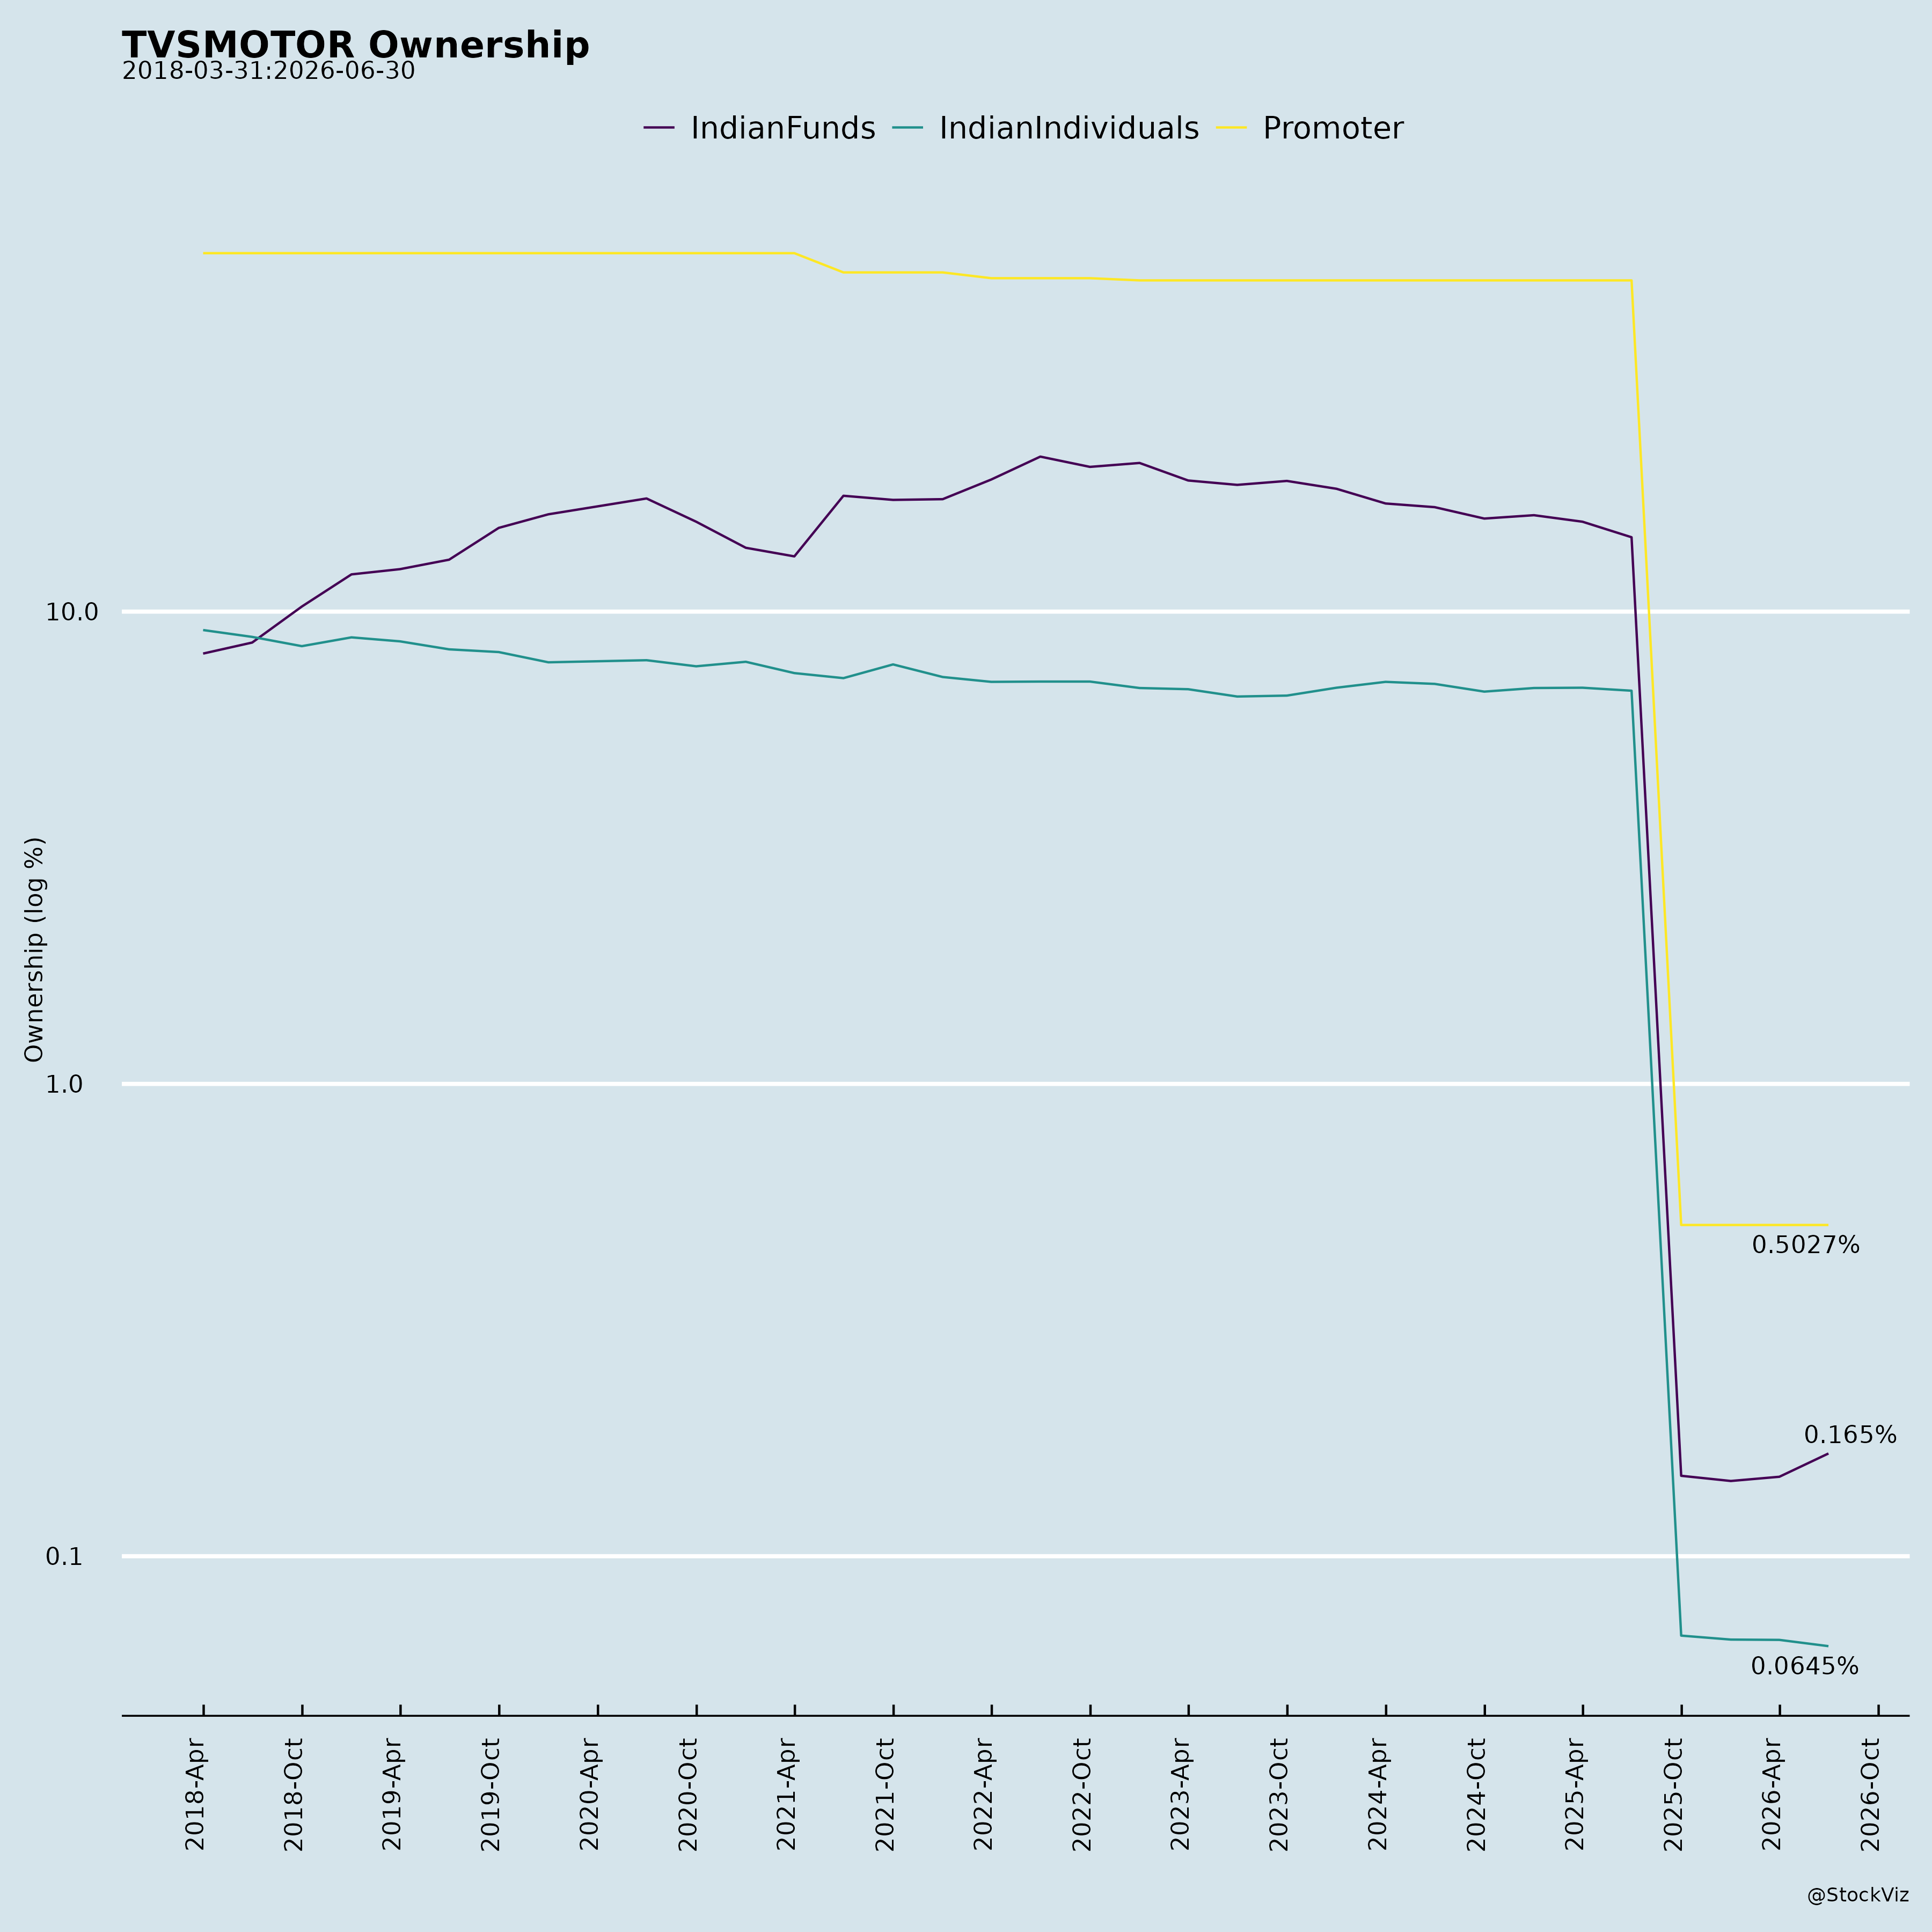
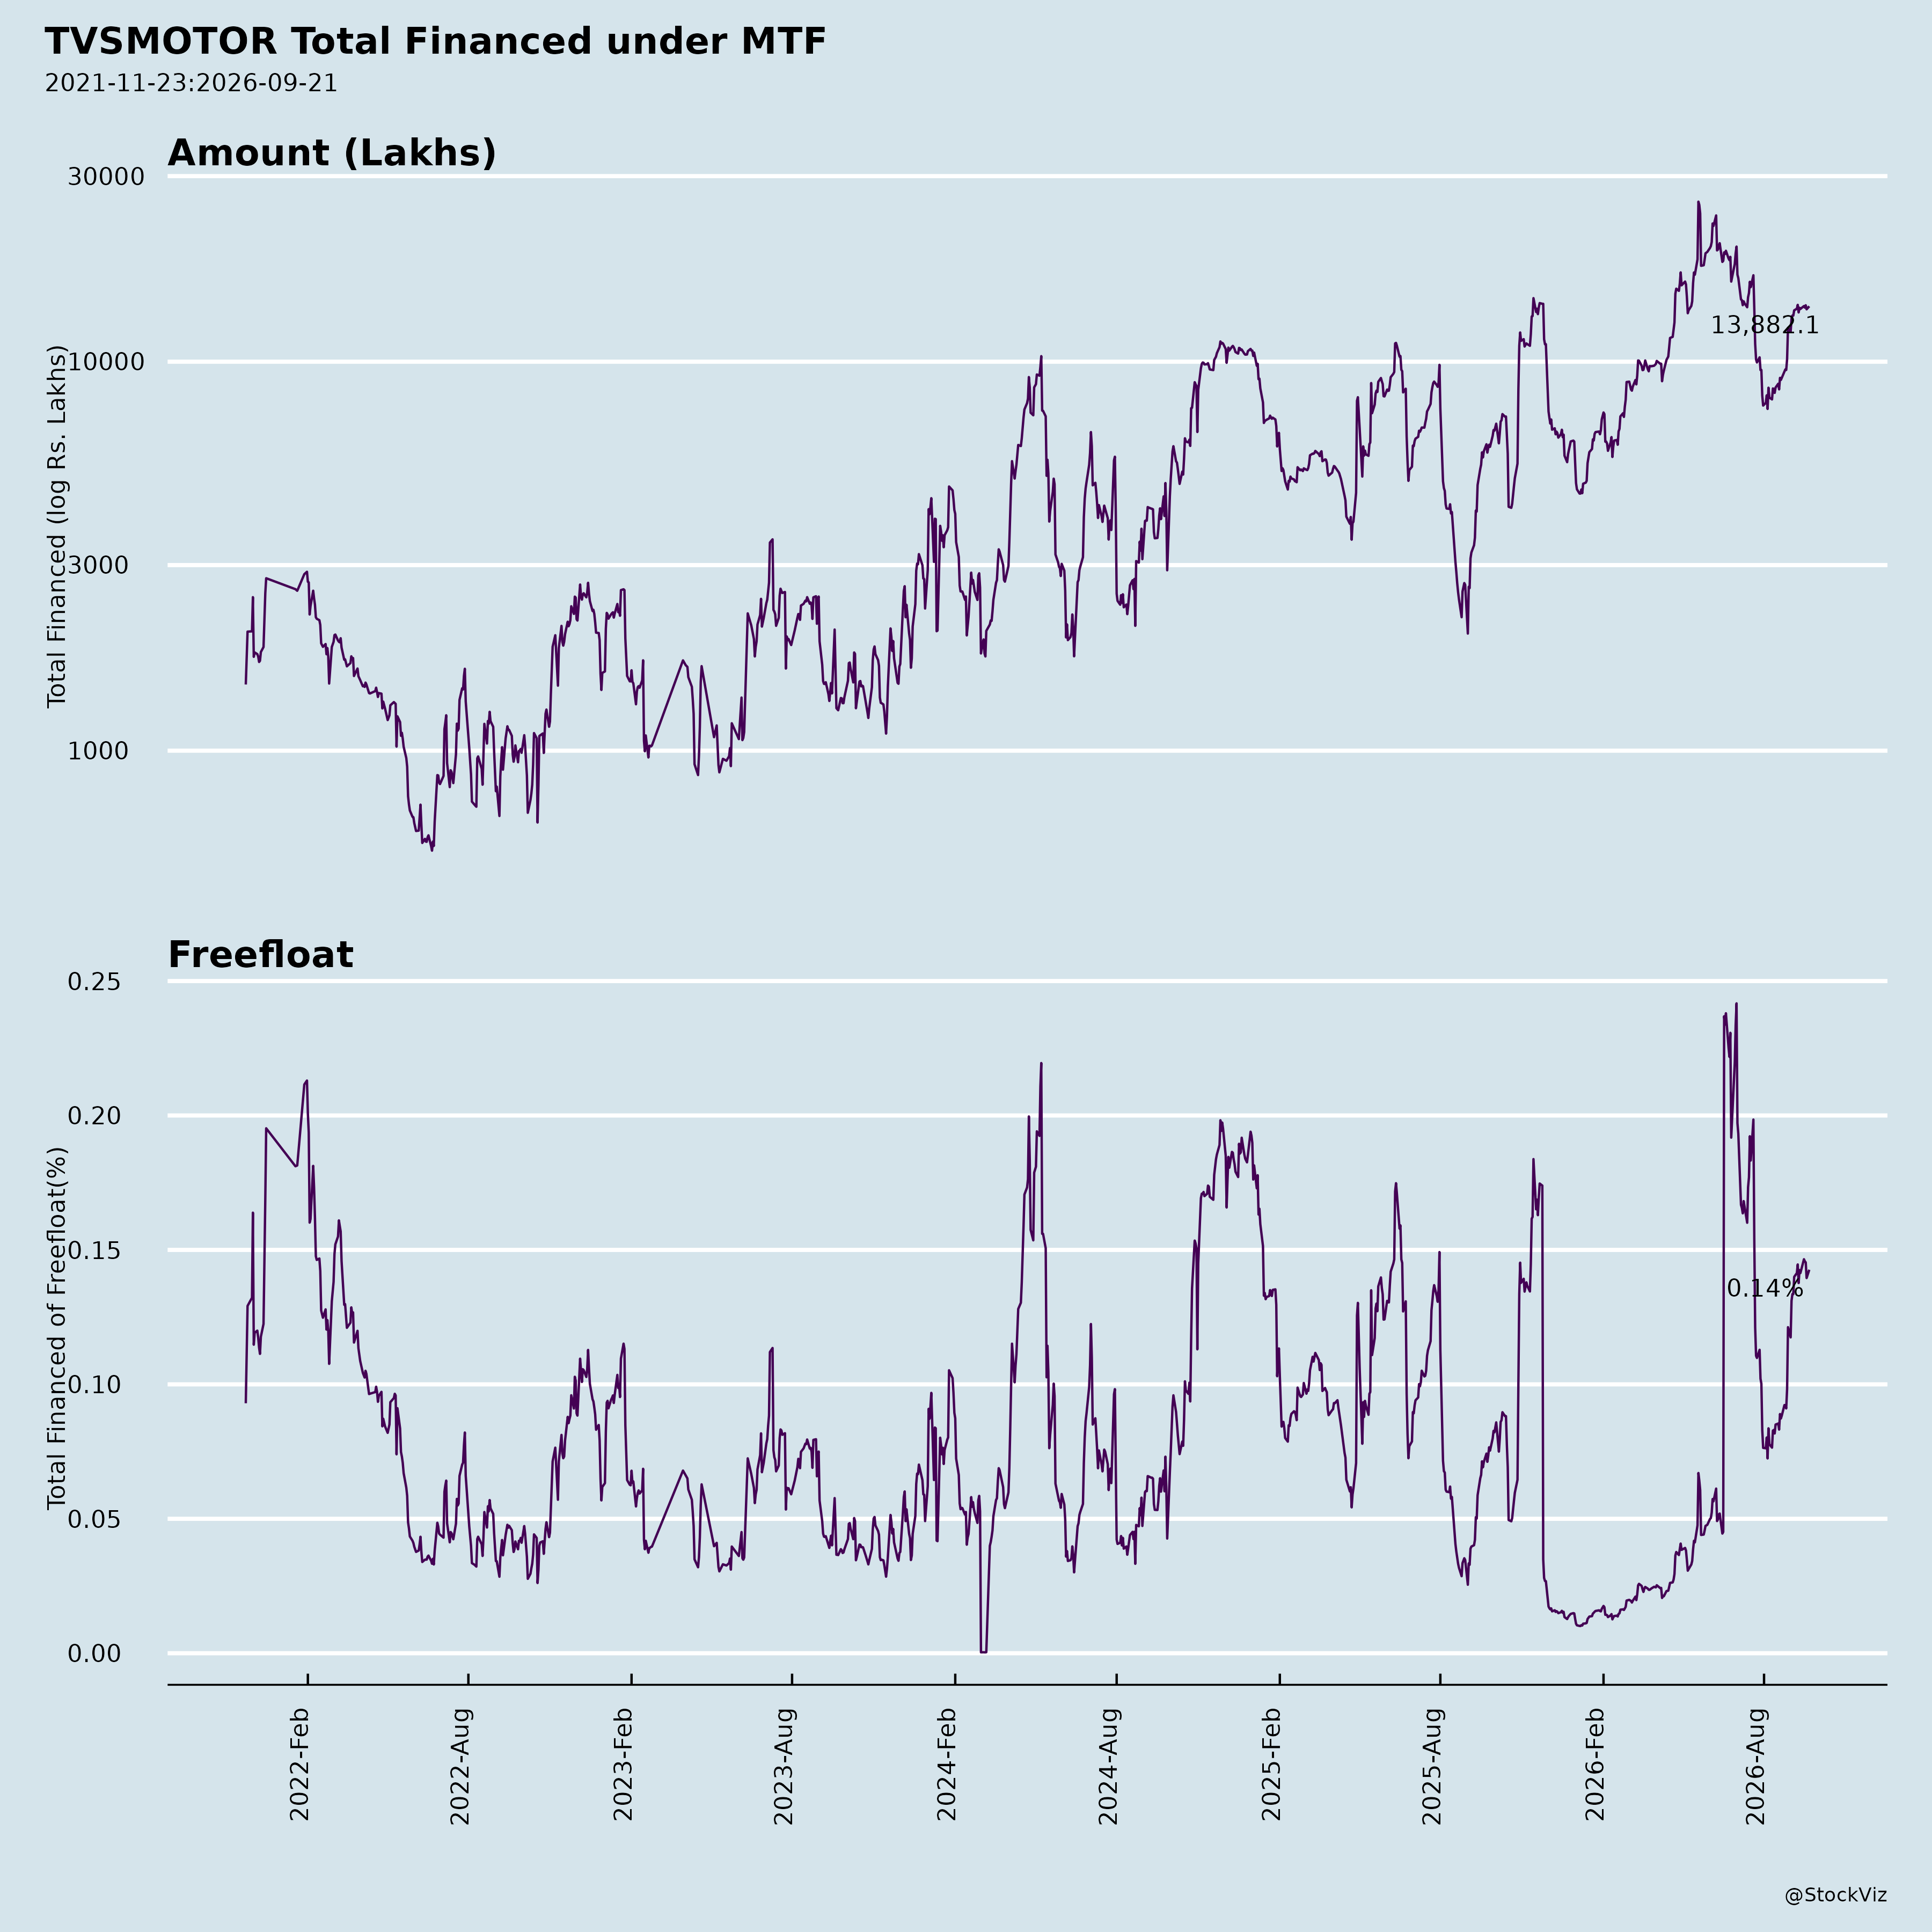
Margined
AI Summary
asof: 2026-09-14
TVS Motor Company — Recent Corporate Announcements
1. Headwinds and Challenges
- Input cost inflation: Commodity prices witnessed a sharp upward trend during the quarter due to global market uncertainties, resulting in increased input costs. The Company partially mitigated the cost increases through price adjustments and focused cost optimisation initiatives, including scale benefits.
- Regulatory cost uncertainty: The Environment Protection (End-of-Life Vehicles) Rules, 2025, notified effective 1 April 2025, impose Extended Producer Responsibility on vehicle manufacturers for scrapping old vehicles. The framework and pricing mechanism for EPR certificates is yet to be notified, and the cost of meeting the obligations under EPR cannot be reliably estimated as at 30 June 2026.
- Rising finance costs: Standalone finance cost rose to Rs. 75.50 crores in Q1 FY2026-27 from Rs. 40.30 crores in Q1 FY2025-26 and Rs. 59.10 crores in Q4 FY2025-26. Consolidated finance cost rose to Rs. 602.17 crores from Rs. 550.56 crores a year earlier.
- Deterioration in some balance-sheet ratios: Standalone net debt to equity increased to 0.26 times as at 30 June 2026 from 0.15 times as at 30 June 2025. Consolidated net debt to equity rose to 2.77 times from 2.61 times. Standalone current ratio was 0.54 times, and consolidated current ratio declined to 0.93 times from 1.11 times a year earlier. Consolidated long-term debt to working capital rose to 2.65 times from 1.85 times.
- Loss-making overseas/step-down operations: The consolidated results include 21 subsidiaries not reviewed by their auditors, reflecting total revenue of Rs. 860.47 crores, total net loss after tax of Rs. 307.41 crores and total comprehensive loss of Rs. 337.23 crores for the quarter ended 30 June 2026. The Group’s share of net loss after tax of associates was Rs. 14.31 crores for the quarter.
- Shareholder dissent on director re-appointment: At the 34th AGM held on 22 July 2026, the resolution re-appointing Mr Sudarshan Venu as Director retiring by rotation passed with 93.9432% votes in favour and 6.0568% against; public institutions recorded 16.0588% of votes polled against.
- Declining asset turnover ratios: Standalone debtors turnover declined to 25.86 times in Q1 FY2026-27 from 30.20 times a year earlier; consolidated debtors turnover declined to 24.47 times from 28.21 times.
2. Tailwinds and Growth Prospects
- Record quarterly sales: The Company registered its highest ever quarterly sales, with overall two- and three-wheelers growing 28% to 1.63 million units in Q1 FY2026-27 from 1.28 million units in Q1 FY2025-26.
- Segment momentum: Motorcycle sales grew 19% to 0.74 million units; scooter sales grew 36% to 0.68 million units; three-wheeler sales grew 48% to 66,697 units; international business grew 33% to 0.47 million units.
- Electric vehicles: Two-wheeler EV sales grew 86% to 129,940 units from 70,060 units. TVS Motor now has more than 1 million EV customers.
- Record financial performance: Highest-ever revenue of Rs. 13,896 crores in Q1 FY2026-27, up 38% from Rs. 10,081 crores. Highest-ever EBITDA of Rs. 1,779 crores, up 41% from Rs. 1,260 crores, with EBITDA margin improving 30 bps to 12.8% from 12.5%. Profit after tax grew 51% to Rs. 1,174 crores from Rs. 776 crores.
- Fair valuation gains: Other income for the quarter included Rs. 149.60 crores gain on fair valuation of investments; PAT for the quarter includes fair valuation gain of Rs. 150 crores versus Rs. 28 crores in Q1 of the prior year.
- Fund-raising capacity: The Board on 21 July 2026 approved raising funds from time to time through Non-Convertible Debentures and/or Commercial Papers and/or other permissible borrowings up to Rs. 1,000 crores, within overall Section 180 borrowing limits.
- Debt issuance completed: The Company allotted 50,000 senior, rated, unsecured, listed, redeemable NCDs of face value INR 1,00,000 each, aggregating to INR 500 crores, on 17 July 2026, with a three-year tenor, to be listed on NSE.
- Investments: During the quarter the Company made investments of Rs. 612.59 crores in TVS Motor (Singapore) Pte Limited and Rs. 193.31 crores in Jana Small Finance Bank Limited.
- Credit quality: CARE credit rating for commercial paper is A1+.
- Improved profitability ratios: Standalone net profit margin improved to 8.4% from 7.7%; consolidated net profit margin improved to 6.5% from 5.3%. Standalone inventory turnover improved to 23.10 times from 17.45 times; consolidated inventory turnover improved to 16.08 times from 12.81 times.
- Financial services segment growth: Segment revenue for financial services rose to Rs. 2,068.41 crores from Rs. 1,724.15 crores; segment profit before tax and interest rose to Rs. 431.57 crores from Rs. 269.97 crores.
- Portfolio actions: TVS EBike Company AG, a wholly owned step-down subsidiary, completed transfer of certain assets and liabilities at book value of CHF 13.8 million on 2 July 2026. Norton USA LLC became a subsidiary with effect from 6 November 2025; Engines Engineering S.P.A. became a subsidiary with effect from 3 October 2025.
3. Key Risks
- Unquantified EPR compliance cost: The EPR framework and pricing mechanism under the ELV Rules is yet to be notified, so the cost of meeting obligations cannot be reliably estimated as at 30 June 2026.
- Commodity price volatility: Sharp upward trends in commodity prices due to global market uncertainties increased input costs; mitigation was only partial.
- Elevated consolidated leverage: Consolidated net debt to equity of 2.77 times and total debts to total assets of 0.54 times, with long-term debt to working capital of 2.65 times.
- Unreviewed subsidiary financials: The consolidated results include 21 subsidiaries whose interim financial information was not reviewed by their auditors and is based solely on management certified accounts, plus 3 associates similarly unreviewed. One subsidiary with total revenues of Rs. 1,918.58 crores and net profit after tax of Rs. 208.68 crores was reviewed by other auditors.
- Dependence on fair valuation gains: Rs. 149.60 crores of other income in the quarter came from fair valuation gains on investments, which contributed to PAT growth.
- Foreign exchange and cross-border operations: The Group operates across multiple jurisdictions including Singapore, the Netherlands, Indonesia, Switzerland, Germany, the UK and the USA, with financial information converted from local accounting principles to Ind AS.
- NCRPS redemption obligation: Outstanding NCRPS of Rs. 1,900.35 crores, with dividend at 6% p.a. payable only at redemption and a tenure of 12 months from allotment date of 1 September 2025.
- Governance dissent: The 6.0568% votes against the director re-appointment resolution, including 16.0588% of public institutional votes polled, indicates shareholder dissent.
4. Management Guidance Versus Observed Business Performance
- Fund-raising approval versus action: On 21 July 2026 the Board approved raising up to Rs. 1,000 crores through NCDs, commercial papers and/or other borrowings. The Company had already allotted Rs. 500 crores of NCDs on 17 July 2026, prior to the Board approval date, indicating partial utilisation of the approved capacity.
- Cost mitigation versus margin outcome: Management stated that commodity cost increases were partially mitigated through price adjustments and cost optimisation including scale benefits. Observed outcome: EBITDA margin improved 30 bps to 12.8% from 12.5%, and standalone operating margin was 12.8% versus 12.5% a year earlier, though it declined from 13.1% in Q4 FY2025-26.
- Amalgamation completion versus accounting: The Scheme of Amalgamation of Sundaram Auto Components Limited with the Company was approved by the NCLT Chennai Bench on 6 May 2026 with an appointed date of 1 April 2025. The amalgamation was accounted for under the pooling of interests method, and Q1 FY2025-26 financials were restated in accordance with Ind AS 103. Restated Q1 FY2025-26 figures: profit before tax Rs. 1,050.13 crores (from Rs. 1,053.07 crores reported), profit after tax Rs. 775.65 crores (from Rs. 778.59 crores), other comprehensive income Rs. 745.42 crores (from Rs. 748.36 crores).
- AGM resolutions versus voting outcome: All three resolutions set out in the Notice were approved by shareholders with requisite majority as ordinary resolutions. Resolution 1 (adoption of audited financial statements for year ended 31 March 2026) passed with 99.9871% in favour; Resolution 2 (re-appointment of Mr Sudarshan Venu as Director) passed with 93.9432% in favour; Resolution 3 (ratification of remuneration to M/s C S Adawadkar & Co as Cost Auditor for FY2026-27) passed with 99.9998% in favour.
- Dividend guidance on NCRPS versus payment timing: The NCRPS carry dividend at 6% p.a. payable at the time of redemption only, with a tenure of 12 months from allotment date of 1 September 2025. No dividend was paid during the quarter.
- Utilisation of issue proceeds: The statement of utilisation of issue proceeds and the statement on deviation/variation in utilisation of funds raised both record “Not Applicable” for the quarter ended 30 June 2026, with no deviation reported.
Broker Narrative
The broker narrative evolved from a purely bearish Sell stance in 2020 — citing technical weakness, sectoral divergence, and Nifty trend-line breaches with zero tailwinds — to overwhelmingly bullish Buy and Accumulate calls through 2023-2025 driven by strong revenue growth and EV/export momentum. By mid-2026, the framing matured into a balanced thesis that pairs robust tailwinds (record exports, 86% EV growth, ₹35B capex expansion) with newly acknowledged headwinds like raw material inflation, gross margin contraction, and heavy Norton pre-launch spending.
Fears that came true
- Raw material cost inflation (steel, aluminum, crude oil derivatives at 3.5-4.0% of revenue) materialized and compressed gross margins by 160 bps YoY, correlating with recent PENDING outcomes where actual returns significantly undershot broker predictions.
- Pre-launch marketing expenses of ~₹600 million for the Norton franchise weighed on short-term profitability as flagged, contributing to 2026 PENDING calls where actual returns (6.7-18.3%) fell well below predicted targets (36.1-39.8%).
Optimism that failed
- The Norton premiumization thesis was optimistic about brand optionality and new product launches, but the associated ₹600M pre-launch spend instead emerged as a near-term margin headwind rather than an immediate growth driver, delaying expected profitability uplift.
Broker Timeline
63 broker calls · 2020-02-15 to 2026-07-24
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.